0000909832-26-000093.txt : 20261007 0000909832-26-000093.hdr.sgml : 20261007 20261006211315 ACCESSION NUMBER: 0000909832-26-000093 CONFORMED SUBMISSION TYPE: 10-K PUBLIC DOCUMENT COUNT: 91 CONFORMED PERIOD OF REPORT: 20260830 FILED AS OF DATE: 20261007 DATE AS OF CHANGE: 20261006 FILER: COMPANY DATA: COMPANY CONFORMED NAME: COSTCO WHOLESALE CORP /NEW CENTRAL INDEX KEY: 0000909832 STANDARD INDUSTRIAL CLASSIFICATION: RETAIL-VARIETY STORES [5331] ORGANIZATION NAME: 07 Trade & Services EIN: 911223280 STATE OF INCORPORATION: WA FISCAL YEAR END: 0830 FILING VALUES: FORM TYPE: 10-K SEC ACT: 1934 Act SEC FILE NUMBER: 000-20355 FILM NUMBER: 261445309 BUSINESS ADDRESS: STREET 1: 999 LAKE DRIVE CITY: ISSAQUAH STATE: WA ZIP: 98027- BUSINESS PHONE: 4253138100 MAIL ADDRESS: STREET 1: 999 LAKE DRIVE CITY: ISSAQUAH STATE: WA ZIP: 98027 FORMER COMPANY: FORMER CONFORMED NAME: COSTCO COMPANIES INC DATE OF NAME CHANGE: 19970401 FORMER COMPANY: FORMER CONFORMED NAME: PRICE/COSTCO INC DATE OF NAME CHANGE: 19930728 10-K 1 cost-20260830.htm 10-K cost-20260830
falseAugust 30, 20262026FYCOSTCO WHOLESALE CORP /NEW000090983208/300.0050.005100,000,000100,000,000————0.0050.005900,000,000900,000,000443,266,000443,237,000443,266,000443,237,000P5YP3YP5Y11953261599495326159949532615994http://fasb.org/us-gaap/2026#OtherAssetsNoncurrenthttp://fasb.org/us-gaap/2026#OtherAssetsNoncurrenthttp://fasb.org/us-gaap/2026#OtherLiabilitiesCurrenthttp://fasb.org/us-gaap/2026#OtherLiabilitiesCurrenthttp://fasb.org/us-gaap/2026#OtherLiabilitiesCurrenthttp://fasb.org/us-gaap/2026#OtherLiabilitiesCurrenthttp://fasb.org/us-gaap/2026#OtherLiabilitiesNoncurrenthttp://fasb.org/us-gaap/2026#OtherLiabilitiesNoncurrenthttp://xbrl.sec.gov/country/2026#US3iso4217:USDxbrli:sharesiso4217:USDxbrli:sharescost:warehousecost:statesxbrli:purecost:Reportable_segment00009098322025-09-012026-08-3000009098322026-02-1500009098322026-09-290000909832us-gaap:ProductMember2025-09-012026-08-300000909832us-gaap:ProductMember2024-09-022025-08-310000909832us-gaap:ProductMember2023-09-042024-09-010000909832us-gaap:MembershipMember2025-09-012026-08-300000909832us-gaap:MembershipMember2024-09-022025-08-310000909832us-gaap:MembershipMember2023-09-042024-09-0100009098322024-09-022025-08-3100009098322023-09-042024-09-0100009098322026-08-3000009098322025-08-310000909832us-gaap:CommonStockMember2023-09-030000909832us-gaap:AdditionalPaidInCapitalMember2023-09-030000909832us-gaap:AccumulatedOtherComprehensiveIncomeMember2023-09-030000909832us-gaap:RetainedEarningsMember2023-09-0300009098322023-09-030000909832us-gaap:RetainedEarningsMember2023-09-042024-09-010000909832us-gaap:AccumulatedOtherComprehensiveIncomeMember2023-09-042024-09-010000909832us-gaap:AdditionalPaidInCapitalMember2023-09-042024-09-010000909832us-gaap:CommonStockMember2023-09-042024-09-010000909832us-gaap:CommonStockMember2024-09-010000909832us-gaap:AdditionalPaidInCapitalMember2024-09-010000909832us-gaap:AccumulatedOtherComprehensiveIncomeMember2024-09-010000909832us-gaap:RetainedEarningsMember2024-09-0100009098322024-09-010000909832us-gaap:RetainedEarningsMember2024-09-022025-08-310000909832us-gaap:AccumulatedOtherComprehensiveIncomeMember2024-09-022025-08-310000909832us-gaap:AdditionalPaidInCapitalMember2024-09-022025-08-310000909832us-gaap:CommonStockMember2024-09-022025-08-310000909832us-gaap:CommonStockMember2025-08-310000909832us-gaap:AdditionalPaidInCapitalMember2025-08-310000909832us-gaap:AccumulatedOtherComprehensiveIncomeMember2025-08-310000909832us-gaap:RetainedEarningsMember2025-08-310000909832us-gaap:RetainedEarningsMember2025-09-012026-08-300000909832us-gaap:AccumulatedOtherComprehensiveIncomeMember2025-09-012026-08-300000909832us-gaap:AdditionalPaidInCapitalMember2025-09-012026-08-300000909832us-gaap:CommonStockMember2025-09-012026-08-300000909832us-gaap:CommonStockMember2026-08-300000909832us-gaap:AdditionalPaidInCapitalMember2026-08-300000909832us-gaap:AccumulatedOtherComprehensiveIncomeMember2026-08-300000909832us-gaap:RetainedEarningsMember2026-08-300000909832country:US2026-08-300000909832country:CA2026-08-300000909832country:MX2026-08-300000909832country:JP2026-08-300000909832country:GB2026-08-300000909832country:KR2026-08-300000909832country:AU2026-08-300000909832country:TW2026-08-300000909832country:CN2026-08-300000909832country:ES2026-08-300000909832country:FR2026-08-300000909832country:SE2026-08-300000909832country:IS2026-08-300000909832country:US2025-08-310000909832country:CA2025-08-310000909832cost:OtherInternationalMember2026-08-300000909832cost:OtherInternationalMember2025-08-310000909832srt:MinimumMemberus-gaap:BuildingAndBuildingImprovementsMember2026-08-300000909832srt:MaximumMemberus-gaap:BuildingAndBuildingImprovementsMember2026-08-300000909832srt:MinimumMemberus-gaap:FurnitureAndFixturesMember2026-08-300000909832srt:MaximumMemberus-gaap:FurnitureAndFixturesMember2026-08-300000909832country:USus-gaap:OperatingSegmentsMember2026-08-300000909832country:CAus-gaap:OperatingSegmentsMember2026-08-300000909832cost:OtherInternationalMemberus-gaap:OperatingSegmentsMember2026-08-300000909832us-gaap:ForeignExchangeForwardMember2026-08-300000909832us-gaap:ForeignExchangeForwardMember2025-08-310000909832srt:MaximumMember2025-09-012026-08-300000909832cost:EmployeesMember2025-09-012026-08-300000909832srt:MinimumMember2025-09-012026-08-300000909832country:NZ2026-08-300000909832country:USus-gaap:OperatingSegmentsMember2024-09-010000909832country:CAus-gaap:OperatingSegmentsMember2024-09-010000909832cost:OtherInternationalMemberus-gaap:OperatingSegmentsMember2024-09-010000909832country:USus-gaap:OperatingSegmentsMember2025-08-310000909832country:CAus-gaap:OperatingSegmentsMember2025-08-310000909832cost:OtherInternationalMemberus-gaap:OperatingSegmentsMember2025-08-310000909832us-gaap:USGovernmentAgenciesDebtSecuritiesMember2026-08-300000909832us-gaap:CertificatesOfDepositMember2026-08-300000909832us-gaap:USGovernmentAgenciesDebtSecuritiesMember2025-08-310000909832us-gaap:CertificatesOfDepositMember2025-08-310000909832us-gaap:USGovernmentAgenciesDebtSecuritiesMemberus-gaap:FairValueMeasurementsRecurringMemberus-gaap:FairValueInputsLevel2Member2026-08-300000909832us-gaap:USGovernmentAgenciesDebtSecuritiesMemberus-gaap:FairValueMeasurementsRecurringMemberus-gaap:FairValueInputsLevel2Member2025-08-310000909832us-gaap:ForeignExchangeForwardMemberus-gaap:FairValueMeasurementsRecurringMemberus-gaap:FairValueInputsLevel2Member2026-08-300000909832us-gaap:ForeignExchangeForwardMemberus-gaap:FairValueMeasurementsRecurringMemberus-gaap:FairValueInputsLevel2Member2025-08-310000909832us-gaap:FairValueMeasurementsRecurringMemberus-gaap:FairValueInputsLevel2Member2026-08-300000909832us-gaap:FairValueMeasurementsRecurringMemberus-gaap:FairValueInputsLevel2Member2025-08-310000909832srt:MinimumMember2026-08-300000909832srt:MaximumMember2026-08-300000909832cost:SeniorNotesZeroPointSixThreePercentDueMarchTwentyTwentySixMember2025-09-012026-08-300000909832cost:SeniorNotesZeroPointSevenNineZeroPercentDueMayTwentyTwentyFiveMember2024-09-022025-08-310000909832cost:SeniorNotesZeroPointNineTwoPercentDueJulyTwentyTwentyFourMember2023-09-042024-09-010000909832cost:SeniorNotesTwoPointSevenFivePercentDueMayEighteenTwentyTwentyFourMemberMember2023-09-042024-09-010000909832cost:SeniorNotesTwoPointSevenFivePercentDueMayEighteenTwentyTwentyFourMemberMember2025-08-310000909832cost:SeniorNotesThreePercentDueMayEighteenTwentyTwentySevenMemberMember2026-08-300000909832cost:SeniorNotesThreePercentDueMayEighteenTwentyTwentySevenMemberMember2025-08-310000909832cost:SeniorNotesOnePointThreeSevenFivePercentDueJuneTwentyTwentySevenMember2026-08-300000909832cost:SeniorNotesOnePointThreeSevenFivePercentDueJuneTwentyTwentySevenMember2025-08-310000909832cost:SeniorNotesOnePointSixZeroPercentDueAprilTwentyThirtyMember2026-08-300000909832cost:SeniorNotesOnePointSixZeroPercentDueAprilTwentyThirtyMember2025-08-310000909832cost:SeniorNotesOnePointSevenFivePercentDueAprilTwentyThirtyTwoMember2026-08-300000909832cost:SeniorNotesOnePointSevenFivePercentDueAprilTwentyThirtyTwoMember2025-08-310000909832cost:OtherLongTermDebtMember2026-08-300000909832cost:OtherLongTermDebtMember2025-08-310000909832cost:S2024Q2DividendsMember2023-09-042024-09-010000909832us-gaap:CommonStockMembercost:S2024Q2DividendsMember2023-09-042024-09-0100009098322026-05-112026-08-300000909832us-gaap:RestrictedStockUnitsRSUMembersrt:MaximumMember2026-08-300000909832us-gaap:RestrictedStockUnitsRSUMember2026-08-300000909832us-gaap:PerformanceSharesMember2026-08-300000909832us-gaap:PerformanceSharesMember2025-09-012026-08-300000909832us-gaap:RestrictedStockUnitsRSUMember2025-09-012026-08-300000909832country:CA2025-09-012026-08-300000909832cost:CanadaOtherMember2025-09-012026-08-300000909832us-gaap:ForeignTaxJurisdictionOtherMember2025-09-012026-08-300000909832us-gaap:RestrictedStockUnitsRSUMember2024-09-022025-08-310000909832us-gaap:RestrictedStockUnitsRSUMember2023-09-042024-09-010000909832stpr:CA2025-09-012026-08-300000909832us-gaap:StateAndLocalTaxJurisdictionOtherMember2025-09-012026-08-300000909832country:MX2025-09-012026-08-300000909832us-gaap:OtherAssetsNoncurrent2026-08-300000909832us-gaap:OtherAssetsNoncurrent2025-08-310000909832us-gaap:OtherLiabilitiesNoncurrent2026-08-300000909832us-gaap:OtherLiabilitiesNoncurrent2025-08-310000909832cost:UnitedStatesMemberus-gaap:OperatingSegmentsMember2025-09-012026-08-300000909832cost:UnitedStatesMemberus-gaap:OperatingSegmentsMember2024-09-022025-08-310000909832cost:UnitedStatesMemberus-gaap:OperatingSegmentsMember2023-09-042024-09-010000909832cost:CanadaMemberus-gaap:OperatingSegmentsMember2025-09-012026-08-300000909832cost:CanadaMemberus-gaap:OperatingSegmentsMember2024-09-022025-08-310000909832cost:CanadaMemberus-gaap:OperatingSegmentsMember2023-09-042024-09-010000909832cost:OtherInternationalMemberus-gaap:OperatingSegmentsMember2025-09-012026-08-300000909832cost:OtherInternationalMemberus-gaap:OperatingSegmentsMember2024-09-022025-08-310000909832cost:OtherInternationalMemberus-gaap:OperatingSegmentsMember2023-09-042024-09-010000909832cost:UnitedStatesMemberus-gaap:OperatingSegmentsMember2026-08-300000909832cost:UnitedStatesMemberus-gaap:OperatingSegmentsMember2025-08-310000909832cost:UnitedStatesMemberus-gaap:OperatingSegmentsMember2024-09-010000909832cost:CanadaMemberus-gaap:OperatingSegmentsMember2026-08-300000909832cost:CanadaMemberus-gaap:OperatingSegmentsMember2025-08-310000909832cost:CanadaMemberus-gaap:OperatingSegmentsMember2024-09-010000909832cost:OtherInternationalMemberus-gaap:OperatingSegmentsMember2026-08-300000909832cost:OtherInternationalMemberus-gaap:OperatingSegmentsMember2025-08-310000909832cost:OtherInternationalMemberus-gaap:OperatingSegmentsMember2024-09-010000909832cost:FoodandSundriesMember2025-09-012026-08-300000909832cost:FoodandSundriesMember2024-09-022025-08-310000909832cost:FoodandSundriesMember2023-09-042024-09-010000909832cost:NonFoodsMember2025-09-012026-08-300000909832cost:NonFoodsMember2024-09-022025-08-310000909832cost:NonFoodsMember2023-09-042024-09-010000909832cost:FreshFoodMember2025-09-012026-08-300000909832cost:FreshFoodMember2024-09-022025-08-310000909832cost:FreshFoodMember2023-09-042024-09-010000909832cost:OtherMember2025-09-012026-08-300000909832cost:OtherMember2024-09-022025-08-310000909832cost:OtherMember2023-09-042024-09-01
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549 
FORM 10-K
☒
ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended August 30, 2026
or
☐
TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
Commission file number 0-20355
Costco Wholesale Corporation
(Exact name of registrant as specified in its charter)
Washington91-1223280
(State or other jurisdiction of
incorporation or organization)
(I.R.S. Employer Identification No.)
999 Lake Drive, Issaquah, WA 98027
(Address of principal executive offices) (Zip Code)
Registrant’s telephone number, including area code: (425) 313-8100
Securities registered pursuant to Section 12(b) of the Act:
Title of each classTrading SymbolName of each exchange on
which registered
Common Stock, $.005 Par ValueCOSTThe NASDAQ Global Select Market
Securities registered pursuant to Section 12(g) of the Act: None 
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒   No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐   No ☒ 
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒   No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files).
Yes ☒   No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
Large accelerated filer ☒Accelerated filer ☐
Non-accelerated filer ☐Smaller reporting company ☐
Emerging growth company☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements. ☐
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant's executive officers during the relevant recovery period pursuant to §240.10D-1(b). ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ☐   No ☒
The aggregate market value of the voting stock held by non-affiliates of the registrant as of February 15, 2026 was $451.6 billion.
The number of shares outstanding of the registrant’s common stock as of September 29, 2026, was 443,129,349.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the registrant's Proxy Statement for the Annual Meeting of Shareholders to be held on January 21, 2027, are incorporated by reference into Part III of this Form 10-K.


COSTCO WHOLESALE CORPORATION
ANNUAL REPORT ON FORM 10-K FOR THE FISCAL YEAR ENDED AUGUST 30, 2026
TABLE OF CONTENTS
 
Page
Item 1.
Item 1A.
Item 1B.
Item 1C.
Item 2.
Item 3.
Item 4.
Item 5.
Item 6.
Item 7.
Item 7A.
Item 8.
Item 9.
Item 9A.
Item 9B.
Item 9C.
Item 10.
Item 11.
Item 12.
Item 13.
Item 14.
Item 15.
Item 16.
2

INFORMATION RELATING TO FORWARD LOOKING STATEMENTS
Certain statements contained in this document constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. For these purposes, forward-looking statements are statements that address activities, events, conditions or developments that the Company expects or anticipates may occur in the future and may relate to such matters as net sales growth, changes in comparable sales, cannibalization of existing locations by new openings, price or fee changes, earnings performance, earnings per share, stock-based compensation expense, warehouse openings and closures, capital spending, the effect of adopting certain accounting standards, future financial reporting, financing, margins, return on invested capital, investments in technology, strategic direction, expense controls, membership fee changes, signups, and renewal rates, shopping frequency, litigation, including self-insured general liability claims, attainment of sustainability goals, and the demand for our products and services. In some cases, forward-looking statements can be identified because they contain words such as “anticipate,” “believe,” “continue,” “could,” “estimate,” “expect,” “intend,” “likely,” “may,” “might,” “plan,” “potential,” “predict,” “project,” “seek,” “should,” “target,” “will,” “would,” or similar expressions and the negatives of those terms. Such forward-looking statements involve risks and uncertainties that may cause actual events, results, or performance to differ materially from those indicated by such statements, including, without limitation, the factors set forth in the section titled “Item 1A-Risk Factors”, and other factors noted in the section titled “Item 7-Management's Discussion and Analysis of Financial Condition and Results of Operations” and in the consolidated financial statements and related notes in Item 8 of this Report. Forward-looking statements speak only as of the date they are made, and we do not undertake to update these statements, except as required by law.
PART I
Item 1—Business
Costco Wholesale Corporation and its subsidiaries (Costco or the Company) began operations in 1983, in Seattle, Washington. We are principally engaged in the operation of membership warehouses in the United States (U.S.) and Puerto Rico, Canada, Mexico, Japan, the United Kingdom (U.K.), Korea, Australia, Taiwan, China, Spain, France, Sweden, Iceland, and New Zealand. Costco operated 939, 914, and 890 warehouses worldwide at August 30, 2026, August 31, 2025, and September 1, 2024. The Company operates e-commerce sites in the U.S., Canada, Mexico, the U.K., Korea, Taiwan, Japan, Australia, and China. Our common stock trades on the NASDAQ Global Select Market, under the symbol “COST.”
We report on a 52/53-week fiscal year, consisting of thirteen four-week periods and ending on the Sunday nearest the end of August. The first three quarters consist of three periods each, and the fourth quarter consists of four periods (five weeks in the thirteenth period in a 53-week year). The material seasonal impact in our operations is increased net sales and earnings during the winter holiday season. References to 2026, 2025, and 2024 relate to the 52-week fiscal years ended August 30, 2026, August 31, 2025, and September 1, 2024.
General
We operate membership warehouses and e-commerce sites based on the concept that offering low prices on a limited selection of nationally-branded and private-label products in a wide range of categories will produce high sales volumes and rapid inventory turnover. When combined with the operating efficiencies achieved by volume purchasing, efficient distribution and reduced handling of merchandise in no-frills, self-service warehouse facilities, these volumes and turnover enable us to operate profitably at significantly lower gross margins (net sales less merchandise costs) than most other retailers. We often sell inventory before we are required to pay for it, even while taking advantage of early payment discounts.
We buy most of our merchandise directly from suppliers and route it to cross-docking consolidation points (depots) or directly to our warehouses. Our depots receive large shipments from suppliers and quickly
3

ship these goods to warehouses. This process creates freight volume and handling efficiencies, lowering costs associated with traditional multiple-step distribution channels. Our e-commerce operations ship merchandise through our depots and logistics operations, as well as through drop-ship and other delivery arrangements with our suppliers.
Our average warehouse space is approximately 148,000 square feet, with newer units being slightly larger. Floor plans are designed for efficiency in the use of selling space, the handling of merchandise, and the control of inventory. Because shoppers are attracted principally by the quality of merchandise and low prices, our warehouses are not elaborate. By strictly controlling the entrances and exits and using a membership format, we believe our inventory losses (shrinkage) are well below those of typical retail operations.
Our operating hours are shorter than many other retailers, and due to other efficiencies inherent in a warehouse club operation, we believe labor costs are lower relative to the volume of sales. In the U.S., we offer exclusive shopping hours for our Executive members and our gasoline operations generally have extended hours. Merchandise is generally stored on racks above the sales floor and displayed on pallets containing large quantities, reducing labor required. In general, with variations by country, our warehouses accept certain credit cards, including Costco co-branded cards, debit cards, cash and checks, Executive member reward certificates, co-brand cardholder rebates, and our proprietary stored-value card (shop card).
Our strategy is to provide our members with a broad range of high-quality merchandise at prices we believe are consistently lower than elsewhere. We seek to limit most items to fast-selling models, sizes, and colors. We carry less than 4,000 active stock keeping units (SKUs) per warehouse in our core warehouse business, significantly less than other broadline retailers. We average from 9,000 to 11,000 SKUs online, some of which are available in our warehouses. Many consumable products are offered for sale in case, carton, or multiple-pack quantities only.
To promote member satisfaction, we generally accept returns of merchandise. On certain electronic items, we have a 90-day return policy and provide, free of charge, technical support services, as well as an extended warranty. Additional third-party warranty coverage is sold on certain electronic items and major appliances.
We offer merchandise and services in the following categories:
■Core Merchandise Categories:
•Foods and Sundries (including sundries, dry grocery, candy, cooler, freezer, liquor, and tobacco)
•Non-Foods (including consumer electronics, appliances, small electrics, health and beauty aids, hardware, lawn and garden, sporting goods, tires, toys and seasonal, automotive, stamps, tickets, apparel, furniture, domestics, housewares, special order kiosk, and jewelry)
•Fresh Foods (including meat, produce, deli, and bakery)
■Warehouse Ancillary (includes gasoline, pharmacy, food court, optical, hearing aids, and tire installation)
■Other Businesses (includes e-commerce, business centers, travel, and other)
Warehouse ancillary operate primarily within, next to or near our warehouses, encouraging more frequent shopping. The number of warehouses with gas stations varies significantly by country. We operated 774 gas stations at the end of 2026. Our gasoline business represented 11% of total net sales in 2026.
4

Our other businesses sell products and services that largely complement our warehouse operations. Our business centers carry items tailored for food services, convenience stores, and offices, and offer walk-in shopping and deliveries. Business centers are included in our total warehouse count. Our e-commerce operations give members convenience and a broader selection of goods and services. Costco Travel offers vacation packages, car rentals, cruises and other travel products exclusively for Costco members in varying degrees in the U.S., Canada, the U.K., and Australia. Digitally-enabled sales, which represents sales that are initiated through a digital device, whether fulfilled through a warehouse or distribution center, as well as Costco Travel, represented 11% of total net sales in 2026.
We have direct relationships with many producers of brand-name merchandise. We do not obtain a significant portion of merchandise from any one supplier. When sources of supply become unavailable, we seek alternative sources or items. We pursue diversification in our supply-chain and seek to expand in-country production. We also purchase and manufacture private-label merchandise, where quality and member demand are high and the value to our members is significant.
Certain financial information for our segments and geographic areas is included in Note 11 to the consolidated financial statements included in Item 8 of this Report.
Membership
Our members may utilize their memberships at all of our warehouses and e-commerce sites. Our annual fee for memberships is $65 in the U.S., varies in other countries and includes a free household card.
Membership at the end of 2026, 2025, and 2024 was made up of the following (in thousands):
202620252024
Paid members1
84,100 81,000 76,200 
Household cards66,300 64,200 60,600 
Total cardholders150,400 145,200 136,800 
_______________
(1)These membership counts include active memberships as well as memberships that have expired and not renewed within the 12 months prior to the reporting date. These expired memberships make up a small percentage of membership counts, and many of them are subsequently renewed.
Paid members, in most countries, are eligible to upgrade to an Executive membership for an additional annual fee. These members earn an Executive reward, generally 2% on qualified purchases, subject to an annual maximum value, redeemable at Costco warehouses. Executive members represented 42,300, 38,700, and 35,400 of total paid members in 2026, 2025, and 2024. The penetration of sales to Executive members represented approximately 75.2% of worldwide net sales in 2026.
Our member renewal rate was 92.3% in the U.S. and Canada and 89.8% worldwide at the end of 2026. This rate is a trailing calculation that captures renewals during the period seven to eighteen months prior to the reporting date. Memberships that have an expiration date in the six months prior to the end of our reporting period are excluded from this calculation, regardless of whether or not they have been renewed. Although most members renew prior to expiration, the vast majority of those who renew late do so within six months of expiration. The timing of renewal after expiration is impacted by a variety of factors, such as warehouse openings and promotional activity.
5

Human Capital
“Take Care of Our Employees,” is a key component of our code of ethics and is fundamental to our commitment to “Take Care of Our Members.” Compensation and benefits for employees is our largest expense after the cost of merchandise and is carefully monitored.
Employee Base
At the end of 2026, we employed 355,000 employees worldwide. Approximately 95% are employed in our membership warehouses and distribution channels. Around 5% are represented by unions. We also utilize seasonal employees.
The total number of employees by segment was:
202620252024
United States232,000 223,000 219,000 
Canada58,000 55,000 53,000 
Other International65,000 63,000 61,000 
Total employees355,000 341,000 333,000 
Growth and Engagement
We believe that our warehouses are among the most productive in the retail industry, owing largely to the commitment and efficiency of our employees. We seek to provide them not merely with employment but careers. Many attributes of our business contribute to this objective. The more significant include: competitive compensation and benefits; a commitment to employee development and promoting from within; and a target ratio of at least 50% of our base being full-time employees. These attributes contribute to what we consider, especially for the industry, a high retention rate. In 2026, in the U.S. and Canada that rate was approximately 94% for employees who have been with us for at least one year.
Inclusion
The commitment to “Take Care of Our Employees” includes promoting an inclusive and respectful workplace. We strive for an environment where all employees feel that they belong, are accepted, included, respected, and supported. We demonstrate leadership commitment to inclusion through consistent communication, employee development and education, support of diversity and inclusion within the organization, community involvement, and supplier inclusion. Listening to our employees is one of the ways Costco takes care of its workforce. Costco continues its efforts to develop future leaders, including through our supervisor in training (SIT) programs in the U.S. and Canada. In 2026, over 8,100 hourly employees completed the six-week course.
Well Being
We strive to provide our employees with competitive wages and excellent benefits. In March 2026, we increased the top of wage scales by $1.00 per hour in the U.S. and Canada, bringing our average rate at the end of 2026 for hourly employees in the U.S. to approximately $33.00. We continue to offer expansive benefits in the U.S. that provide physical, emotional, mental, and financial well-being support for employees and their dependents at low cost to our employees. Globally, our policies and practices are designed to mirror our practices in the U.S. regarding compensation leadership, subject to local regulations, customs, and market conditions.
For more detailed information regarding our programs, see “Employees” within our Sustainability Commitment (located on our website). The Sustainability Commitment and other information on our website are not incorporated by reference into and do not form any part of this Annual Report.
6

Competition
Our industry is highly competitive, based on factors such as price, merchandise quality and selection, location, convenience, distribution strategy, and customer service. We compete on a worldwide basis with global, national, and regional wholesalers and retailers, including supermarkets, supercenters, online retailers, gasoline stations, hard discounters, department and specialty stores, and operators selling a single category or narrow range of merchandise. Walmart, Target, Kroger, and Amazon are among our significant general merchandise retail competitors in the U.S. We also compete with other warehouse clubs, including Walmart’s Sam’s Club and BJ’s Wholesale Club in the U.S. Many of the metropolitan areas in the U.S. and certain of our Other International locations have multiple competing clubs.
Intellectual Property
We believe that, to varying degrees, our trademarks, trade names, copyrights, proprietary processes, trade secrets, trade dress, domain names, and similar intellectual property add significant value to our business and are important to our success. We have invested significantly in the development and protection of our well-recognized brands, including the Costco Wholesale trademarks and our private-label brand, Kirkland Signature. We believe that Kirkland Signature products are high quality, offered at prices that are generally lower than national brands, and help lower costs, differentiate our merchandise offerings, and generally earn higher margins. We expect to continue to increase the sales penetration of our private-label items.
We rely on trademark and copyright laws, trade-secret protection, and confidentiality, license and other agreements with our suppliers, employees and others to protect our intellectual property. The availability and duration of trademark registrations vary by country; however, trademarks are generally valid and may be renewed indefinitely as long as they are in use and registrations are maintained.
Available Information
Our U.S. website is www.costco.com. We make available through the Investor Relations section of that site, free of charge, our Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K, Proxy Statements and Forms 3, 4 and 5, and any amendments to those reports, as soon as reasonably practicable after filing such materials with or furnishing such documents to the Securities and Exchange Commission (SEC). The information found on our website is not part of this or any other report filed with or furnished to the SEC. The SEC maintains a site that contains reports, proxy and information statements, and other information regarding issuers, such as the Company, that file electronically with the SEC at www.sec.gov.
We have a code of ethics for senior financial officers, pursuant to Section 406 of the Sarbanes-Oxley Act. Copies of the code are available free of charge by writing to Secretary, Costco Wholesale Corporation, 999 Lake Drive, Issaquah, WA 98027. If the Company makes any amendments to this code (other than technical, administrative, or non-substantive amendments) or grants any waivers, including implicit waivers, to the Chief Executive Officer, Chief Financial Officer or principal accounting officer and controller, we will disclose (on our website or in a Form 8-K report filed with the SEC) the nature of the amendment or waiver, its effective date, and to whom it applies.
7

Information about our Executive Officers
The executive officers of Costco, their position, and ages are listed below. Most officers have over 25 years of service with the Company.
NamePositionExecutive
Officer
Since
Age
Ron M. VachrisPresident and Chief Executive Officer. Mr. Vachris has been a director since February 2022. Mr. Vachris was previously President and Chief Operating Officer from February 2022 to December 2023. He was Executive Vice President of Merchandising from June 2016 to January 2022, Senior Vice President, Real Estate Development, from August 2015 to June 2016, and Senior Vice President, General Manager, Northwest Region, from 2010 to July 2015.201661
Gary MillerchipExecutive Vice President and Chief Financial Officer. Mr. Millerchip previously served as Senior Vice President and Chief Financial Officer of The Kroger Co. from April 2019 to February 2024 and, prior to that, as Chief Executive Officer of Kroger Personal Finance since July 2010.202455
Caton FratesSenior Executive Vice President, Chief Operating Officer - Warehouse Operations, U.S. and Mexico. Mr. Frates was Executive Vice President, Chief Operating Officer, Southwest Division from 2022 to February 2026, and Senior Vice President, Los Angeles Region, from 2015 to May 2022.202258
Jim C. KlauerExecutive Vice President. Mr. Klauer was Executive Vice President, Chief Operating Officer - Northern Division from 2018 to August 2026 and Senior Vice President, Non-Foods and E-commerce Merchandise, from 2013 to January 2018. Mr. Klauer will be retiring from the Company effective October 30, 2026.201864
Yoram RubanenkoExecutive Vice President, Chief Operating Officer - Eastern Division. Mr. Rubanenko was Senior Vice President and General Manager, Southeast Region, from 2013 to September 2021, and Vice President, Regional Operations Manager for the Northeast Region, from 1998 to 2013.202162
John SullivanExecutive Vice President, General Counsel & Corporate Secretary. Mr. Sullivan has been General Counsel since 2016 and Corporate Secretary since 2010.202166
Claudine AdamoExecutive Vice President, Administration. Ms. Adamo was Executive Vice President, Chief Operating Officer - Merchandising from 2022 to March 2026, Senior Vice President, Non-Foods, from 2018 to February 2022, and Vice President, Non-Foods, from 2013 to 2018.202256
Pierre RielExecutive Vice President, Chief Operating Officer, International Division. Mr. Riel was Senior Vice President, Country Manager, Canada, from 2019 to March 2022, and Senior Vice President, Eastern Canada Region, from 2001 to 2019.202263
Javier PolitExecutive Vice President, Chief Information and Digital Officer. Mr. Polit previously served as Chief Information Officer for Mondelez International (formerly Kraft Foods) from 2022 to 2024. From 2017 to 2022, he was Chief Information Officer for The Procter & Gamble Company. Prior to that role, he served as Group Chief Information Officer for The Coca-Cola Company from 2007 to 2017.202362
Teresa JonesExecutive Vice President, Chief Operating Officer - Global Depots and Traffic. Ms. Jones was Senior Vice President, Depot Operations from August 2022 to July 2024, and Vice President, Depot Operations, from 2018 to 2022.202457
W. Richard WilcoxExecutive Vice President, Chief Operating Officer, Southwest Division. Mr. Wilcox was Senior Vice President, General Manager - San Diego Region from 2016 to October 2025.202560
Sarah GeorgeExecutive Vice President, Chief Operating Officer - Merchandising. Ms. George was Senior Vice President, Merchandising - Foods and Sundries, from 2023 to March 2026, and Senior Vice President, Fresh Foods, from 2019 to 2023.202650
Adam SelfExecutive Vice President, Chief Operating Officer, Northern Division. Mr. Self was Senior Vice President, General Manager, Northeast Region from 2020 to August 2026, and Vice President, Regional Operations Manager for the Northeast Region from 2013 to March 2020. 202656
8

Item 1A—Risk Factors
The risks described below could materially and adversely affect our business, financial condition and results of operations. We could also be affected by additional risks that apply to all companies operating in the U.S. and globally, as well as other risks that are not presently known to us or that we currently consider to be immaterial. These Risk Factors should be carefully reviewed in conjunction with Management's Discussion and Analysis of Financial Condition and Results of Operations in Item 7 and our consolidated financial statements and related notes in Item 8 of this Report.
Business and Operating Risks
We are highly dependent on the financial performance of our U.S. and Canadian operations.
Our financial and operational performance is highly dependent on our U.S. and Canadian operations, which comprised 86% and 83% of net sales and operating income in 2026. Within the U.S., we are highly dependent on our California operations, which comprised 26% of U.S. net sales in 2026. Our California market, in general, has a larger percentage of higher volume warehouses as compared to our other domestic markets. Any substantial slowing or sustained decline in these operations could materially adversely affect our business and financial results. Declines in financial performance of our U.S. operations, particularly in California, and our Canadian operations could arise from, among other things: slow growth or declines in comparable warehouse sales (comparable sales); negative trends in operating expenses, including increased labor, healthcare, and energy costs; failing to meet targets for warehouse openings; cannibalizing existing locations with new warehouses; shifts in sales mix toward lower gross margin products; changes or uncertainties in economic conditions in our markets, including higher levels of unemployment and depressed home values; and failing to consistently provide high quality and innovative new products.
We may be unsuccessful implementing our growth strategy, including expanding our business in existing markets and new markets, and integrating acquisitions, which could have an adverse impact on our business, financial condition and results of operations.
Our growth is dependent, in part, on our ability to acquire property and build or lease new warehouses and depots. We compete with other retailers and businesses for suitable locations. Local land use and other regulations restricting the construction and operation of our warehouses and depots, as well as local community actions opposed to the location of our warehouses or depots at specific sites and the adoption of local laws restricting our operations and environmental regulations, may impact our ability to find suitable locations and increase the cost of sites and of constructing, leasing and operating warehouses and depots. We also may have difficulty negotiating leases or purchase agreements on acceptable terms. With continued growth in global demand for electricity and water stress in certain regions, we may have difficulty securing long-term utility contracts for new buildings or incur additional costs due to onsite generation and storage requirements. In addition, certain jurisdictions have enacted or proposed laws and regulations that would prevent or restrict the operation or expansion plans of certain large retailers and warehouse clubs, including us. Failure to effectively manage these and other similar factors may affect our ability to timely build or lease and operate new warehouses and depots, which could have a material adverse effect on our future growth and profitability.
We seek to expand in existing markets to attain a greater overall market share. A new warehouse may draw members away from our existing warehouses and adversely affect their comparable sales performance, member traffic, and profitability.
We intend to continue to open warehouses in new markets. Associated risks include difficulties in attracting members due to a lack of familiarity with us, attracting members of other wholesale club operators, our lesser familiarity with local member preferences, and seasonal differences in the market. Entry into new markets may bring us into competition with new competitors or with existing competitors with a large, established market presence. We cannot ensure that new warehouses and new e-commerce sites will be profitable and future profitability could be delayed or otherwise materially adversely affected.
9

We have made and may continue to make investments and acquisitions to improve the speed, accuracy and efficiency of our supply chains and delivery channels. The effectiveness of these investments can be less predictable than opening new locations and might not provide the anticipated benefits or desired rates of return.
Our failure to maintain membership growth, loyalty, brand recognition, and our culture could adversely affect our results of operations.
Membership loyalty and growth are essential to our business. The extent to which we achieve growth in our membership base, increase the penetration of Executive membership, and sustain high renewal rates materially influences our profitability. Achieving these metrics relies heavily on member trust and our long-standing culture focused on value, integrity, member service, and always striving to do what is right. Damage to our brands, reputation, or culture may negatively impact comparable sales, diminish member trust, and reduce renewal rates and, accordingly, net sales and membership fee revenue, negatively impacting our results of operations.
We sell many products under our Kirkland Signature brand. Maintaining consistent product quality, competitive pricing, and availability of these products is essential to developing and maintaining member loyalty. These products also generally carry higher margins than national brand products and represent a growing portion of our overall sales. If the Kirkland Signature brand experiences a loss of member acceptance or confidence, our sales and gross margin results could be adversely affected.
Disruptions in merchandise distribution or processing, packaging, manufacturing, and other facilities could adversely affect sales and member satisfaction.
We depend on the orderly operation of the merchandise receiving and distribution process, primarily through our depots. We also rely upon processing, packaging, manufacturing and other facilities to support our business, which includes the production of certain private-label items. Although we believe that our operations are efficient, disruptions due to extreme weather, pandemics or other catastrophic events, labor issues, work stoppage, or other shipping problems may result in delays in the production and delivery of merchandise to and the operation of our warehouses, which could adversely affect sales and the satisfaction of our members. Our e-commerce operations depend heavily on logistics providers, both internal and external, and are negatively affected when services are unable to be provided in a timely fashion.
We may not timely identify or effectively respond to consumer tastes and preferences, which could negatively affect our relationship with our members, the demand for our products and services, and our market share.
It is difficult to consistently and successfully predict the products and services that our members will desire. Our success depends, in part, on our ability to identify and respond to trends in demographics and consumer preferences. Failure to identify timely or effectively respond to changing consumer tastes, preferences and spending patterns including those related to resource efficiency, environmental protection, human rights, and the transition to a low-carbon economy could negatively affect our relationship with our members, the demand for our products and services, and our market share. We sell a substantial amount of gasoline, the demand for which could be impacted by concerns and regulation about climate change.
If we are not successful at predicting our sales trends and adjusting our purchases accordingly, we may have excess inventory, which could result in additional markdowns, or we may experience out-of-stock positions and delivery delays, which could result in higher costs, both of which would reduce our operating performance. This could have an adverse effect on net sales, gross margin and operating income.
10

Availability and performance of our IT systems are vital to our business. Failure to successfully execute IT projects and have IT systems available to our business would adversely impact our operations.
IT systems play a crucial role in conducting our business. These systems are utilized to, among other things, process a very high volume of transactions, conduct payment transactions, track and value our inventory, and produce reports critical for making business decisions. Failure or disruption of these systems could have an adverse impact on our ability to buy products and services from our suppliers, produce goods in our manufacturing plants, move products in an efficient manner to our warehouses, and sell products to our members. Given the high volume of transactions we process, it is important that we build strong resiliency to lessen disruption from events such as power outages, computer and telecommunications failures, viruses, internal or external security breaches and other cybersecurity incidents, errors by employees, extreme weather, and catastrophic events. Any debilitating failure of our critical IT systems, data centers, and backup systems would require significant investments in resources to restore services and may cause serious impairment in our business operations, including loss of business services, increased cost of moving merchandise and failure to provide service to our members. We are currently making substantial investments in technology and IT projects, including maintaining and enhancing our digital resiliency, and failure or delay in these projects could be costly and harmful to our business. We must also effectively monitor competitive technology trends, including the evolution of artificial intelligence (AI). Any failure to effectively incorporate these technologies could adversely affect our ability to compete. Additionally, the autonomous nature of AI presents unique challenges, particularly regarding third-party systems which may operate in ways that are difficult to monitor. There is a risk that these autonomous systems could bypass internal controls, lack adequate third-party governance, or result in unauthorized access to data, data leakage, and non-compliance with applicable data privacy laws. These systems may also produce inaccurate outputs, leading to unintended operational decisions. Failure to deliver IT projects efficiently and effectively could result in the loss of our competitive position and adversely impact our financial condition and results of operations. Insufficient IT capacity could also impact our capacity for timely, complete and accurate financial and non-financial reporting required by law.
We are required to maintain the privacy and security of personal and business information amidst multiplying threat landscapes and in compliance with increasing privacy and data protection regulations globally. Failure to do so could damage our business, including our reputation with members, suppliers and employees, cause us to incur substantial additional costs, and become subject to litigation and regulatory action.
Increased security threats and more sophisticated cyber misconduct pose a risk to our systems, networks, products and services. We rely upon IT systems and networks, some of which are managed by or belong to third parties, including suppliers, partners, vendors, and service providers. Additionally, we collect, store, and process sensitive information relating to our business, members, employees, and other third parties. Operating these IT systems and networks and processing and maintaining this data in a secure manner are critical to our business operations and strategy. Remote work has also expanded possible attack surfaces. Attempts to gain unauthorized access to systems, networks, and data, both ours and third parties with whom we work, are increasing in frequency and sophistication, and in some cases, these attempts are successful. Cybersecurity attacks may range from random attempts to coordinated and targeted attacks, including sophisticated computer crimes and advanced persistent threats. Phishing attacks are particularly prominent, including as vectors for ransomware attacks, which have increased in breadth and frequency. While we train our employees as part of our security efforts, that training cannot be completely effective. The rapid evolution of AI has automated and accelerated the scale of cybersecurity threats, potentially reducing the time for us to detect and mitigate potential information security incidents. If our security infrastructure fails to keep pace with these evolving threats, it could lead to more frequent or sophisticated compromises of our systems, networks, or data, adversely affecting our operations and member confidence. These threats pose a risk to the security of our systems and networks and the confidentiality, integrity, and availability of our data. Our IT systems and networks, or
11

those managed by third parties such as cloud providers or suppliers that otherwise host or have access to confidential information, periodically have vulnerabilities, which may go unnoticed for a period of time. Our logging capabilities, or the logging capabilities of third parties, are also not always complete or sufficiently detailed, affecting our ability to fully investigate and understand the scope of security events. While our cybersecurity and compliance efforts seek to mitigate such risks, there can be no guarantee that the actions and controls we and our third-party service providers have implemented and are implementing will be sufficient to protect our systems, information, or other property.
The potential impacts of a cybersecurity attack include reputational damage, litigation, government enforcement actions, penalties, disruption to systems and operations, unauthorized release of confidential or otherwise protected information, corruption of data, diminution in the value of our investment in IT systems, and increased cybersecurity protection and remediation costs. This could adversely affect our competitiveness, results of operations and financial condition and, critically in light of our business model, loss of member confidence. Further, the insurance coverage we maintain and indemnification arrangements with third parties may be inadequate to cover claims, costs, and liabilities relating to cybersecurity incidents. In addition, data we collect, store, and process is subject to a variety of U.S. and international laws and regulations (such as the European Union General Data Protection Regulation, California Consumer Privacy Act, Health Insurance Portability and Accountability Act, and China's Personal Information Protection Act), evolving rules concerning AI, and other privacy and cybersecurity laws. The use of AI carries risks related to the accuracy and reliability of its outputs. If these tools provide incorrect information to our members or our employees, or if the content generated inadvertently infringes upon the intellectual property rights of third parties, it could lead to reputational damage, legal claims, and increased regulatory scrutiny. Laws and restrictions on use of member information may also impair our ability to utilize data, consistent with member consents and preferences, which may carry significant potential penalties for noncompliance.
We are subject to payment-related risks.
We accept payments using a variety of methods, including select credit and debit cards, cash and checks, co-brand cardholder rebates, Executive member reward certificates, and our shop card. As we offer new payment options to our members, we may be subject to additional rules, regulations, compliance requirements, and higher fraud losses. For certain payment methods, we pay interchange and other related acceptance fees, along with additional transaction processing fees. We rely on third parties to provide payment transaction processing services for credit and debit cards and our shop card. It could disrupt our business if these parties become unwilling or unable to provide these services to us. We are also subject to fee increases by these service providers.
We must comply with evolving payment card association and network operating rules, including data security rules, certification requirements, and rules governing electronic funds transfers. For example, we are subject to Payment Card Industry Data Security Standards, which contain compliance guidelines and standards with regard to our security surrounding the physical and electronic storage, processing, and transmission of individual cardholder data. If our internal systems are breached or compromised, we may be liable for card re-issuance costs, subject to fines and higher transaction fees, and lose our ability to accept card payments from our members, and our business and operating results could be adversely affected. Our failure to offer payment methods desired by our members could create a competitive disadvantage.
We might sell products that cause illness or injury to our members, harm to our reputation, and expose us to litigation.
If our merchandise, including food and prepared food products for human consumption, drugs, children's products, pet products, and durable goods, do not meet or are perceived not to meet applicable safety or labeling standards or our members' expectations, we could experience lost sales, increased costs, litigation, or reputational harm. The sale of these items involves the risk of illness or injury to our members. Such illnesses or injuries could result from tampering by unauthorized third parties, product
12

contamination or spoilage, including the presence of foreign objects, substances, chemicals, other agents, or residues introduced during the growing, manufacturing, storage, handling, and transportation phases, or faulty design. Our suppliers are generally contractually required to comply with product safety laws, and we are dependent on them to ensure that the products we buy comply with safety and other standards. While we are subject to governmental inspection and regulations and work to comply in all material respects with applicable laws and regulations, we cannot be sure that consumption or use of our products will not cause illness or injury or that we will not be subject to claims, lawsuits, or government investigations relating to such matters, resulting in costly product recalls and other liabilities that could adversely affect our business and results of operations. Even if a product liability claim is unsuccessful or is not fully pursued, negative publicity could adversely affect our reputation with existing and potential members and our corporate and brand image, and these effects could be long-term.
If we do not successfully develop and maintain a relevant and comprehensive digital experience for our members, our results of operations could be adversely impacted.
We must keep pace with changing member expectations and new developments by our competitors. Our members are increasingly using mobile phones, tablets, computers, and other devices to shop and otherwise interact with us. We are making investments in our websites and mobile applications. If we are unable to make, improve, or develop relevant member-facing technology in a timely manner, our ability to compete and our results of operations could be adversely affected.
Inability to attract, train and retain qualified employees could adversely impact our business, financial condition and results of operations.
Our success depends on the continued contributions of our employees, including members of our senior management and other key operations, IT, merchandising, and administrative personnel. Failure to identify and implement a succession plan for senior management could negatively impact our business. We must attract, train, and retain a large and growing number of qualified employees, while controlling related labor costs, preserving our culture, and maintaining our core values. Our ability to control labor and benefit costs is subject to numerous internal and external factors, including regulatory changes, prevailing wage rates, union relations, and healthcare and other insurance costs. We compete with other retail and non-retail businesses for these employees and invest significant resources in training and motivating them. There is no assurance that we will be able to attract or retain highly qualified employees in the future, which could have a material adverse effect on our business, financial condition and results of operations.
We may incur property, casualty or other losses not covered by our insurance.
Claims for employee health care benefits, workers’ compensation, general liability, property damage, directors’ and officers’ liability, vehicle liability, inventory loss, and other exposures are funded predominantly through self-insurance. Insurance coverage is maintained for certain risks to limit exposures arising from very large losses. The types and amounts of insurance may vary from time to time based on our decisions with respect to risk retention and regulatory requirements. Significant claims or events, regulatory changes, a substantial rise in costs of health care or costs to maintain our insurance or the failure to maintain adequate insurance coverage could have an adverse impact on our financial condition and results of operations.
Although we maintain specific coverages for catastrophic property losses, we still bear a significant portion of the risk of losses incurred as a result of any physical damage to, or the destruction of, any warehouses, depots, manufacturing or home office facilities, loss or spoilage of inventory, and business interruption. Such losses could materially impact our cash flows and results of operations.
13

Market and Other External Risks
We face strong competition from other retailers and warehouse club operators, which could adversely affect our business, financial condition and results of operations.
The retail business is highly competitive. We compete for members, employees, sites, products and services, and in other important respects with a wide range of local, regional and national wholesalers and retailers, both in the United States and in foreign countries, including other warehouse-club operators, supermarkets, supercenters, online retailers, gasoline stations, pharmacies, hard discounters, department and specialty stores and operators selling a single category or narrow range of merchandise or services. Such retailers and warehouse club operators compete vigorously and in a variety of ways, including pricing, selection and availability, services, location, convenience, store hours, and the attractiveness, and ease of use of websites and mobile applications. The evolution of retailing in online and mobile channels has improved the ability of customers to comparison shop, which has enhanced competition. Additionally, the emergence of AI tools may change consumer shopping habits and increase the competition we face. AI may also present inaccurate pricing or product data, or fail to capture the full value of our membership offering, impacting member purchasing decisions by prioritizing immediate or inaccurate price comparison or logistics over member loyalty. Some competitors have greater technology capabilities, including the faster adoption of AI technologies, and greater market penetration than we do. Our inability to respond effectively to competitive pressures, changes in the retail markets or customer expectations could result in lost market share and negatively affect our financial results.
General economic factors, domestically and internationally, may adversely affect our business, financial condition, and results of operations.
Higher energy and gasoline costs, inflation, levels of unemployment, healthcare costs, consumer debt levels, foreign-currency exchange rates, unsettled financial markets, weaknesses in housing and real estate markets, reduced consumer confidence, changes and uncertainties related to government fiscal, monetary, and tax policies including changes in interest rates, tax rates, duties, tariffs, or other restrictions, sovereign debt crises, pandemics and other health crises, and other economic factors could adversely affect demand for our products and services, require a change in product mix, or impact the cost of or ability to purchase inventory. Additionally, trade-related actions in various countries have adversely affected the costs of some of our merchandise. The degree of our exposure is dependent on (among other things) the type of goods, rates imposed, and timing of the tariffs and policy changes. The impact to our net sales and gross margin is influenced in part by our merchandising and pricing strategies in response to potential cost increases. Higher tariffs could adversely impact our results.
Prices of certain commodities, including gasoline and consumable goods used in manufacturing and our warehouse retail operations, are historically volatile and are subject to fluctuations arising from changes in domestic and international supply and demand, inflationary pressures, labor costs, competition, market speculation, government regulations, taxes, and periodic delays in delivery. Rapid and significant changes in commodity prices and our ability and desire to pass them through to our members may affect our sales and profit margins. These factors could also increase our merchandise costs and selling, general and administrative expenses, and otherwise adversely affect our operations and financial results. General economic conditions can also be affected by events like the outbreak of hostilities or acts of terrorism.
Inflationary factors, such as increases in merchandise costs, may adversely affect our business, financial condition and results of operations. We may not be able to adjust prices to sufficiently offset the effect of cost increases without negatively impacting consumer demand.
14

Suppliers may be unable to timely provide us with quality merchandise at competitive prices or may fail to adhere to our high standards, resulting in adverse effects on our business, merchandise inventories, sales, and profits.
We depend heavily on our ability to purchase quality merchandise in sufficient quantities at competitive prices. As the quantities we require continue to grow, we have no assurances of continued supply, appropriate pricing or access to new products, and any supplier has the ability to change the terms upon which they sell to us or discontinue selling to us. Member demands may lead to out-of-stock positions causing a loss of sales and profits.
We buy from numerous domestic and foreign suppliers and importers. Our inability to acquire suitable merchandise on acceptable terms or the loss of key suppliers could negatively affect us. We may not be able to develop relationships with new suppliers, and products from alternative sources, if any, may be of a lesser quality or more expensive. Because of our efforts to adhere to high-quality standards for which available supply may be limited, particularly for certain food items, the large volumes we demand may not be consistently available. Our efforts to secure supply could lead to commitments that prove to be unsuccessful in the short and long-term.
Our suppliers (and those they depend upon for materials and services) are subject to risks, including labor disputes, union organizing activities, human rights violations, animal welfare violations, financial liquidity, climate change, natural disasters, extreme weather conditions, environmental degradation, public health emergencies, supply constraints, and general economic and political conditions and other risks similar to those we face that could limit their ability to timely provide us with acceptable merchandise. One or more of our suppliers might not adhere to our quality control, packaging, legal, regulatory, labor, human rights, environmental, or animal welfare standards. These deficiencies may delay or preclude delivery of merchandise to us and might not be identified before we sell such merchandise to our members. This failure could lead to recalls and litigation and otherwise damage our reputation and our brands, increase costs, and otherwise adversely impact our business.
Fluctuations in foreign-exchange rates may adversely affect our results of operations.
During 2026, our international operations, including Canada, generated 27% and 35% of our net sales and operating income. Our international operations have accounted for an increasing portion of our warehouses, and we plan to continue international growth. To prepare our consolidated financial statements, we translate the financial statements of our international operations from local currencies into U.S. dollars using current exchange rates. Future fluctuations in exchange rates that are unfavorable to us may adversely affect the financial performance of our Canadian and Other International operations and have a corresponding adverse effect on our results of operations. As we continue to expand internationally, our exposure to fluctuations in foreign-exchange rates may increase.
A portion of the products we purchase is paid for in a currency other than the local currency of the country in which the goods are sold. Currency fluctuations may increase our merchandise costs and may not be passed on to members and thus may adversely affect our results of operations.
Natural disasters, extreme weather conditions, or other catastrophic events could negatively affect our business, financial condition, and results of operations.
Natural disasters, extreme weather conditions, and other catastrophic events, including those impacted by climate change, such as extreme temperatures, hurricanes, typhoons, floods, earthquakes, wildfires, droughts; acts of terrorism or violence, including active shooter situations; and energy shortages; particularly in California or Washington state, where our centralized operating systems and administrative personnel are located, could negatively affect our operations and financial performance. Such events could result in physical damage to our properties or inventory, additional heating, cooling, and refrigeration costs, limitations on store operating hours, less frequent visits by members to physical locations, the temporary closure of warehouses, depots, manufacturing, or home office facilities, the temporary lack of an adequate work force, disruptions to our IT systems, the temporary or long-term
15

disruption in the supply of products from some local or overseas suppliers, the temporary disruption in the transport of goods to or from overseas, delays in the delivery of goods to our warehouses or depots, delays in online merchandise delivery, the temporary reduction in the availability of products in our warehouses, and long-term disruption or threats to the habitability of key markets in which we operate. These events could also reduce demand for our products or make it difficult or impossible to procure products. We may be required to suspend operations in some or all of our locations, which could have a material adverse effect on our business, financial condition and results of operations.
Pandemics and other health crises could affect our business, financial condition and results of operations in many respects.
The emergence, severity, magnitude, and duration of global or regional health crises are uncertain and difficult to predict. A pandemic could affect certain business operations, demand for our products and services, in-stock positions, costs of doing business, availability of labor, access to inventory, supply chain operations, our ability to predict future performance, exposure to litigation, and our financial performance, among other things. Other factors and uncertainties include, but are not limited to: the severity and duration of pandemics; evolving macroeconomic factors including general economic uncertainty, unemployment rates, and recessionary pressures; changes in labor markets affecting us and our suppliers; unknown consequences on our business performance and initiatives stemming from the substantial investment of time and other resources to the pandemic response; the pace of post-pandemic recovery; the long-term impact of the pandemic on our business, including consumer behaviors; and disruption and volatility within the financial and credit markets.
Failure to meet financial market expectations could adversely affect the market price and volatility of our stock.
We believe that the price of our stock currently reflects high market expectations for our future operating results. Any failure to meet or delay in meeting these expectations, including our comparable sales growth rates, membership fee revenue, including new member sign-ups and renewal rates, gross margin, earnings, earnings per share, new warehouse openings, or dividend or stock repurchase policies could cause the price of our stock to decline.
Legal and Regulatory Risks
Changes in or failure to comply with laws and regulations could adversely impact our business, financial condition and results of operations.
We are subject to a wide and growing array of federal, state, local, and international laws and regulations relating to (among other things), product and food safety, marketing, information security and privacy, pricing, AI, labor and employment, imports and customs, transportation, intellectual property, anti-corruption, and environmental or social matters. These laws and regulations may expand mandatory reporting, increase the scope and complexity of matters that we are required to regulate, assess, and disclose, potentially limit our sourcing flexibility, or require extensive system or other changes that could increase the cost of doing business. Failure to comply could result in harm to our members, employees, workers in the value chain, or others, significant costs to satisfy environmental compliance, remediation or compensatory requirements, or the imposition of severe penalties or restrictions on operations by governmental agencies or courts that could adversely affect our business, financial condition and results of operations.
The impact of changes to or the introduction of new laws, regulations, and policies and enforcement practices, can be unpredictable. These may require extensive system and operational changes, be difficult to implement, increase the cost of doing business, require significant capital expenditures, adversely impact the products or services we offer, or result in adverse publicity and harm to our reputation. If we fail to comply or respond adequately to changes in laws and regulations, our business, operations and financial performance may be adversely affected.
16

We are subject to risks associated with the legislative, judicial, accounting, regulatory, political and economic factors specific to the places where we operate, which could adversely affect our business, financial condition and results of operations.
At the end of 2026, we operated 292 warehouses outside of the U.S. (31% of all warehouse locations), and we plan to continue expanding our international operations. Future operating results internationally could be negatively affected by a variety of factors, many similar to those we face in the U.S., certain of which are beyond our control. These factors include political and economic conditions, regulatory constraints, currency regulations, policy changes, and other matters where we operate, now or in the future. Other factors that may impact international operations include foreign trade (including tariffs and trade sanctions), monetary and fiscal policies, and the laws and regulations of the U.S. and foreign governments, agencies and similar organizations, international conflicts, and risks associated with having major facilities in locations which have been historically less stable than the U.S. Risks inherent in international operations also include, among others, the costs and difficulties of managing international operations, adverse tax consequences, and difficulty in enforcing intellectual property rights. New reporting obligations globally are increasing the cost and complexity of doing business.
Changes in accounting standards and subjective assumptions, estimates and judgments by management related to complex accounting matters could significantly affect our financial condition and results of operations.
Accounting principles and related pronouncements, implementation guidelines, and interpretations we apply to a wide range of matters that are relevant to our business, including self-insurance liabilities, are highly complex and involve subjective assumptions, estimates, and judgments by our management. Changes in rules or interpretation or changes in underlying assumptions, estimates, or judgments by our management could significantly change our reported or expected financial performance and have a material impact on our consolidated financial statements.
We are exposed to risks relating to evaluations of controls required by Section 404 of the Sarbanes-Oxley Act and otherwise.
Section 404 of the Sarbanes-Oxley Act of 2002 requires management assessments of the effectiveness of internal control over financial reporting and disclosure controls and procedures. If we are unable to maintain effective internal control over financial reporting or disclosure controls and procedures, our ability to record, process, and report financial information accurately and to prepare financial statements within required time periods could be adversely affected, which could subject us to litigation or investigations requiring management resources and payment of legal and other expenses, negatively affect investor confidence in our financial statements, and adversely impact our stock price. Uncertainties around our developing systems concerning controls for non-financial reporting also create risks.
Changes in federal, state and foreign tax rates and legislation, could adversely affect our financial condition and results of operations.
We are subject to a variety of taxes and tax collection and remittance obligations related to federal, state, and foreign jurisdictions. At any point in time, we are generally under examination for value added, sales-based, payroll, product, import, or other non-income taxes. We may recognize additional tax expense, be subject to additional tax liabilities, or incur losses and penalties, due to changes in laws, regulations, administrative practices, principles, assessments by authorities, and interpretations related to tax, including tax rules in various jurisdictions. We compute our income-tax provision based on enacted tax rates in the countries in which we operate. As tax rates vary among countries, a change in earnings attributable to the various jurisdictions in which we operate could result in an unfavorable change in our overall tax provision. Additionally, changes in the enacted tax rates or adverse outcomes in tax audits, including transfer pricing disputes, could have a material adverse effect on our financial condition and results of operations.
17

Failure or perceived failure to meet our environmental, social or governance (ESG) goals or expectations set by changing public interest and government regulation of ESG topics could result in reputational harm or adversely affect our business.
We are committed to doing what is right for the business, our members, employees, and shareholders over the long-term. Costco has set public targets and disclosed intentions for future action regarding sustainability. There are dependencies outside of our control impacting our ability to meet our goals, including but not limited to: economic conditions, ability to access technology at an appropriate cost or scale, the ability to procure sufficient clean energy at competitive market rates to meet future operational and supplier needs, unforeseen operational and implementation challenges, termination or contraction of policies or systems which support our capital investments, and collaboration with third parties. We may not make adequate and timely investments or successfully implement strategies that will effectively achieve our sustainability-related goals. Furthermore, international, federal, state, and local regulatory authorities, private organizations and individuals may challenge our approach to ESG issues, including allegations that we failed in our efforts, should not have undertaken such efforts, or that we improperly engaged other entities in our approach to ESG issues. A failure or perceived failure to meet our goals or otherwise meet evolving and diverse stakeholder expectations could lead to reputational harm. Multiple states have enacted or proposed extended producer responsibility laws requiring us to enact policies and processes and will increase expenses in the form of fees paid to the state governments, or subject us to fines and penalties, among other effects.
Our operations require the treatment and disposal of wastewater, stormwater, and agricultural and food processing wastes, the use and maintenance of refrigeration systems, noise, odor, and dust management, the operation of mechanized processing equipment, and other operations that potentially could affect the environment and public health and safety. Failure to comply with current and future environmental, health and safety standards could result in the imposition of fines and penalties, illness or injury of our employees, and claims or lawsuits related to such illnesses or injuries, and temporary closures or limits on the operations of facilities.
Natural gas, diesel fuel, gasoline, and electricity are used in our operations, distribution channels, and value chain. Government regulations limiting carbon dioxide and other greenhouse gas emissions and other environmental restrictions may increase compliance, operations, and merchandise costs, and other regulations affecting energy inputs could materially affect our profitability.
More stringent fuel economy standards, changing public policies aimed at increasing the adoption of zero-emission and alternative fuel vehicles, and other regulations related to climate change may affect our future operations, adversely impact certain elements of our profitability, and require significant capital expenditures.
We are involved in a number of legal proceedings and audits and some of these outcomes could adversely affect our business, financial condition and results of operations.
Our business requires compliance with many laws and regulations. Failure to achieve compliance could subject us to lawsuits and other proceedings and lead to damage awards, fines, penalties, and remediation costs. We are or may become involved in a number of legal proceedings and audits, including grand jury investigations, government and agency investigations, and consumer, employment, tort, unclaimed property laws, and other litigation. We cannot predict with certainty the outcomes of these proceedings and other contingencies, including environmental remediation and other proceedings commenced by governmental authorities. The outcome of some of these proceedings, audits, unclaimed property laws, and other contingencies could require us to take, or refrain from taking, actions which could negatively affect our operations or could require us to pay substantial amounts of money, adversely affecting our financial condition and results of operations. Additionally, defending against these lawsuits and proceedings may involve significant expense and diversion of management's attention and resources.
18

Item 1B—Unresolved Staff Comments
None.
Item 1C—Cybersecurity
Risk Management and Global Strategy
We have implemented processes, technologies, and controls to seek to assess, identify, and manage risks associated with cybersecurity threats. Management considers cybersecurity risks within our overall approach to enterprise risk management. We evaluate these risks based on several frameworks, including the National Institute of Standards and Technology (NIST) Cybersecurity Framework (CSF), Center for Internet Security (CIS) 18 Critical Security Controls, and the Payment Card Industry Data Security Standard. Our governance policies, including our Information Security Policy, outline high-level objectives designed to meet compliance and regulatory requirements.
We undertake regular NIST CSF and CIS 18 Critical Security Controls assessments, conducted by a third-party, to measure program maturity. We have implemented a variety of technologies, leveraging third-party security providers for some, and engage in multiple activities to seek to identify and mitigate vulnerabilities and risks. These include, among other activities, scanning for common vulnerabilities and exposures, penetration tests on internal and external networks, code scans on applications, allowed application listing, configuration management tools, employee awareness and training, and internal and external audits. We also review with various frequencies and on a risk-based priority select third parties with whom we do business, in an effort to reduce the likelihood of security incidents or business interruptions. We maintain cybersecurity insurance that would apply to certain losses arising from significant security incidents.
We maintain a security operations center, supported by external providers and our employees, which provides threat detection and incident response capabilities. We maintain cyber incident response plans and related playbooks in coordination with stakeholders (including legal counsel). Significant incidents are prescribed to be escalated to a Cybersecurity Materiality Committee to assess materiality based on qualitative and quantitative factors and evaluate disclosure and corrective action. The Committee is composed of a cross-divisional group of executives representing the core business functions of Information Technology and Security, Operations, Administration, Finance and Accounting, and Legal. We conduct periodic tabletop exercises, including at the executive level, to review our response processes and incident management procedures.
Governance
Our Board of Directors has delegated certain responsibilities to the Audit Committee of the Board. The Audit Committee reviews and discusses with management the identification and mitigation of cybersecurity risks, including (among other things) the effectiveness of risk-management policies and practices designed to help safeguard our operations, financial systems, and data. Our Chief Information and Digital Officer (CIDO) and his executive team, including the Vice President of Information Security and Chief Information Security Officer (CISO), present cybersecurity-related topics, including program maturity progress, regularly to the Audit Committee. The Internal Audit team, in its periodic compliance and risk assessment updates to the Audit Committee, also reports on its reviews of certain of our cybersecurity risk exposures, controls, and management actions. The full Board also receives cybersecurity evaluations from time to time.
19

Our information security organization is led by our CISO, who joined us in December 2025 and brings over 20 years of relevant cybersecurity and leadership experiences across various industries, primarily pharmacy, finance, and consulting. The CISO is responsible for cybersecurity engineering and architecture, cybersecurity operations, incident response, threat intelligence, identity and access management, cybersecurity risk and compliance, and vulnerability management. Our CISO reports to our CIDO, who has more than 30 years of experience in which he has led global digital responsibilities, including leading global cyber teams. Our CIDO reports to the Chief Executive Officer.
Risks from Material Cybersecurity Threats
We and our third-party service and merchandise providers have experienced cybersecurity incidents and threats. Based on the information available as of the date of this Form 10-K, we are not aware of any risks from actual cybersecurity incidents that have materially affected us or are reasonably likely to materially affect us, including our business strategy, results of operations, or financial condition. It is possible that there have been intrusions into our systems that have not been identified by our controls and procedures and that might manifest in significant events at a later time. There can be no guarantee that the actions and controls we and our third-party service providers have implemented and are implementing will be sufficient to protect our systems, information, or other property. See “Risk Factors” in Item 1A of this Form 10-K for more information on our cybersecurity-related risks.
Item 2—Properties
Warehouse Properties
At August 30, 2026, we operated 939 membership warehouses:
Own Land
and Building
Lease Land
and/or
Building(1)
Total
United States and Puerto Rico536 111 647 
Canada96 19 115 
Other International123 54 177 
Total755 184 939 
_______________
(1)136 of the 184 leases are land-only leases, where Costco owns the building.
At the end of 2026, our warehouses contained 138.7 million square feet of operating floor space: 96.6 million in the U.S.; 16.6 million in Canada; and 25.5 million in Other International. Total square feet associated with distribution and logistics facilities were 33.6 million. Additionally, we operate various processing, packaging, manufacturing, and other facilities to support our business, which includes the production of certain private-label items.
Item 3—Legal Proceedings
See discussion of Legal Proceedings in Note 10 to the consolidated financial statements included in Item 8 of this Report.
Item 4—Mine Safety Disclosures
Not applicable.
20

PART II
Item 5—Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Market Information and Dividend Policy
Our common stock is traded on the NASDAQ Global Select Market under the symbol “COST.” On September 29, 2026, we had 10,703 stockholders of record.
Payment of dividends is subject to declaration by the Board of Directors. Factors considered in determining dividends include our profitability and expected capital needs. Subject to these qualifications, we presently expect to continue to pay dividends on a quarterly basis.
Issuer Purchases of Equity Securities
The following table sets forth information on our common stock repurchase activity for the fourth quarter of 2026 (dollars in millions, except per share data):
PeriodTotal Number of Shares PurchasedAverage Price Paid per Share
Total Number of Shares Purchased as Part of Publicly Announced Program(1)
Maximum Dollar Value of Shares that May Yet be Purchased under the Program
May 11—June 7, 202660,000 $1,010.13 60,000 $1,298 
June 8—July 5, 202664,000 961.15 64,000 1,237 
July 6—August 2, 202665,000 939.11 65,000 1,176 
August 3—August 30, 202664,000 951.03 64,000 1,115 
Total fourth quarter253,000 $964.62 253,000 
_______________
(1)Our share repurchase program is conducted under a $4,000 authorization approved by our Board of Directors in January 2023, which expires in January 2027.
21

Performance Graph
The following graph compares the cumulative total shareholder return assuming reinvestment of dividends on an investment of $100 in Costco common stock, S&P 500 Index, and the S&P Retail Select Index over the five years from August 29, 2021, through August 30, 2026. The S&P Retail Select Index comprises stocks in the S&P Total Market Index that are classified in the GICS Apparel Retail, Automotive Retail, Broadline Retail, Computer & Electronic Retail, Consumer Staples Merchandise Retail, Drug Retail, Food Retailers, and Other Specialty Retail sub-industries.
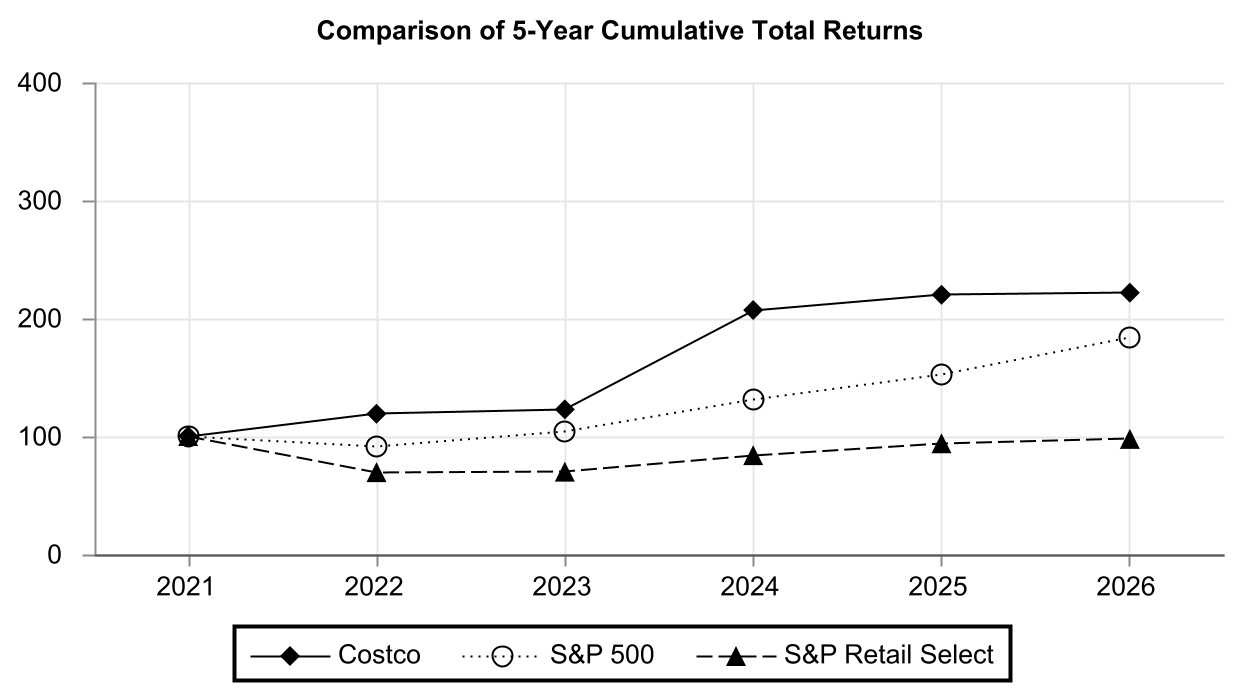
561
The following graph provides information concerning average sales per warehouse over a 10-year period.
Average Sales Per Warehouse*
(Sales In Millions)
Year Opened# of Whses
202625$187 
202524$192 219 
202429$170 192 217 
202323$151 166 186 209 
202223$150 158 179 201 226 
202120$140 158 172 187 210 234 
202013$132 152 184 193 215 240 268 
201920$129 138 172 208 216 226 242 262 
201821$116 119 141 172 202 214 231 245 264 
2017 & Before741$163 178 185 196 223 254 263 274 286 306 
Totals939$163 $176 $182 $192 $217 $245 $252 $260 $272 $292 
2017201820192020202120222023202420252026
Fiscal Year
*First year sales annualized.
2017 and 2023 were 53-week fiscal years but have been normalized for purposes of comparability.
Item 6—Reserved
22

Item 7—Management's Discussion and Analysis of Financial Condition and Results of Operations (amounts in millions, except per share, share, percentages and warehouse count data)
OVERVIEW
Management's Discussion and Analysis of Financial Condition and Results of Operations (MD&A) is intended to promote understanding of the results of operations and financial condition. MD&A is provided as a supplement to, and should be read in conjunction with our consolidated financial statements and the accompanying Notes to Financial Statements (Part II, Item 8 of this Form 10-K). This section generally discusses the results of operations for 2026 compared to 2025. For discussion related to the results of operations and changes in financial condition for 2025 compared to 2024 refer to Part II, Item 7, Management's Discussion and Analysis of Financial Condition and Results of Operations in our fiscal year 2025 Form 10-K, which was filed with the Securities and Exchange Commission on October 8, 2025.
We believe that the most important driver of our profitability is increasing net sales, particularly comparable sales. Net sales includes our core merchandise categories (foods and sundries, non-foods, and fresh foods), warehouse ancillary (gasoline, pharmacy, food court, optical, hearing aids, and tire installation), and other businesses (e-commerce, business centers, travel, and other). E-commerce and business center sales are allocated to the appropriate merchandise categories in the Net Sales discussion. The Executive reward earned by our Executive members reduces net sales and is allocated to the category in which the reward is generated (core merchandise categories, warehouse ancillary, and other businesses). Comparable sales is defined as net sales from warehouses operating for more than one year, including remodels, relocations, and expansions. Digitally-enabled comparable sales is defined as sales initiated through a digital device, whether fulfilled through a warehouse, distribution center, or Costco Travel, operating for more than one year. Comparable sales metrics are intended as supplemental information and are not a substitute for net sales presented in accordance with U.S. generally accepted accounting principles (U.S. GAAP) and should be reviewed in conjunction with results reported in accordance with U.S. GAAP. Comparable sales growth is achieved through increasing shopping frequency from new and existing members and the amount they spend on each visit (average ticket). Sales comparisons can also be particularly influenced by certain factors that are beyond our control: fluctuations in currency exchange rates (with respect to our international operations) and inflation or deflation in the cost of gasoline and associated competitive conditions. The higher our comparable sales exclusive of these items, the more we can leverage our selling, general and administrative (SG&A) expenses, reducing them as a percentage of sales and enhancing profitability. Generating comparable sales growth is foremost a question of making available the right merchandise at the right prices, a skill that we believe we have repeatedly demonstrated over the long-term. Another substantial factor in net sales growth is the health of the economies in which we do business, including the effects of inflation or deflation, especially the United States. Net sales growth and gross margins are also impacted by competition, which is vigorous and widespread, across a wide range of global, national, and regional wholesalers and retailers, including those with e-commerce operations. While we cannot control or reliably predict general economic health or changes in competition, we believe that we have been successful, historically, in adapting our business to these changes, such as through adjustments to our pricing and merchandise mix, including increasing the penetration of our private-label items, and through online offerings.
Our philosophy is to provide our members with quality goods and services at competitive prices. We do not focus in the short-term on maximizing prices charged, but instead seek to maintain what we believe is a perception among our members of our “pricing authority” – consistently providing the most competitive values. Our net sales and gross margin are influenced in part by our merchandising and pricing strategies in response to cost increases. Those strategies can include, but are not limited to, working with our suppliers to share in absorbing cost increases, earlier-than-usual purchasing and in greater volumes, sourcing in the countries and regions where items are sold, as well as passing cost increases on to our members. Our investments in merchandise pricing may include reducing prices on merchandise to drive sales or meet competition and holding prices steady despite cost increases instead of passing the increases on to our members, negatively impacting gross margin and gross margin as a percentage of
23

net sales (gross margin percentage) in the near term. Gross margin is also impacted by our digitally-enabled businesses, domestically and internationally, some of which have a lower gross-margin percentage than our warehouse operations.
Government actions in various countries relating to tariffs affect the costs of some of our merchandise. The degree of our exposure is dependent on (among other things) the type of goods, rates imposed, and timing of the tariffs. Higher tariffs are more likely to adversely impact rather than improve our results.
We believe our gasoline business enhances traffic in our warehouses; it generally has a lower gross margin percentage and lower SG&A expense relative to our non-gasoline businesses. A higher penetration of gasoline sales will generally lower our gross margin percentage. Generally, rising gasoline prices benefit net sales growth which, given the higher sales base, negatively impacts our gross margin percentage but decreases our SG&A expenses as a percentage of net sales. A decline in gasoline prices has the inverse effect.
We also achieve net sales growth by opening new warehouses. As our warehouse base grows and available and desirable sites become more difficult to secure, square footage growth becomes a comparatively less substantial component of growth. Negative aspects of such growth include lower initial operating profitability relative to existing warehouses and cannibalization of sales at existing warehouses when openings occur in existing markets. Our rate of square footage growth is generally higher in many of our international markets, due to the smaller base in those markets, and we expect that to continue.
The membership format is integral to our business and profitability. This format is designed to reinforce member loyalty and provide continuing fee revenue. The extent to which we achieve growth in our membership base, increase the penetration of Executive memberships, and sustain high renewal rates materially influences our profitability. Our renewal rate, which excludes affiliates of Business members, is a trailing calculation that captures renewals during the period seven to eighteen months prior to the reporting date. Our paid-membership growth rate may be adversely impacted when warehouse openings occur in existing markets as compared to new markets. Our worldwide renewal rate is adversely impacted by membership growth in certain international markets and a higher penetration of memberships sold online, including through digital membership promotions, which renew at a slightly lower rate on average.
Our financial performance depends heavily on controlling costs. While we believe that we have achieved successes in this area, some significant costs are partially outside our control, particularly health care and utility expenses. With respect to the compensation of our employees, our philosophy is not to seek to minimize their wages and benefits. Rather, we believe that achieving our longer-term objectives of reducing employee turnover, increasing productivity, and enhancing employee satisfaction requires maintaining compensation levels that are better than the industry average for much of our workforce. This may cause us, for example, to absorb costs that other employers might seek to pass through to their workforces. Because our business operates on very low margins, modest changes in various items in the consolidated statements of income, particularly merchandise costs and SG&A expenses, can have substantial impacts on net income.
Our operating models are generally the same across our U.S., Canadian, and Other International operating segments (see Note 11 to the consolidated financial statements included in Item 8 of this Report). Certain operations in the Other International segment have relatively higher rates of square footage growth, lower wage and benefit costs as a percentage of sales, less or no direct membership warehouse competition, or lack business delivery or Costco operated e-commerce sites.
In discussions of our consolidated operating results, we refer to the impact of changes in foreign currencies relative to the U.S. dollar, which are differences between the foreign-exchange rates we use to convert the financial results of our international operations from local currencies into U.S. dollars. This impact is calculated based on the difference between the current and prior period's exchange rates. The impact of changes in gasoline prices on net sales is calculated based on the difference between the current and prior period's average price per gallon. Results expressed excluding the impacts of foreign-
24

exchange and gasoline prices are intended as supplemental information and are not a substitute for net sales presented in accordance with U.S. GAAP and should be reviewed in conjunction with results reported in accordance with U.S. GAAP.
Our fiscal year ends on the Sunday closest to August 31. References to 2026, 2025, and 2024 relate to the 52-week fiscal years ended August 30, 2026, August 31, 2025, and September 1, 2024. Certain percentages presented are calculated using actual results prior to rounding.
Highlights for 2026 include:
•We opened 28 new warehouses, including three relocations, for a total of 25 net new warehouses: 18 in the U.S., five in our Canadian segment, and two in our Other International segment, compared to 27 new warehouses, including three relocations, in 2025;
•Net sales increased 10% to $297,247, driven by an increase in comparable sales and sales at new warehouses;
•Higher gasoline prices positively impacted net sales by $3,501, or 130 basis points, and changes in foreign currencies positively impacted net sales by $1,332, or 49 basis points;
•Membership fee revenue increased 11% to $5,907, driven by new member sign-ups, membership fee increases, and upgrades to Executive membership;
•Gross margin percentage decreased three basis points; it increased 10 basis points excluding the impact of gasoline price inflation;
•SG&A expenses as a percentage of net sales decreased 10 basis points; it increased one basis point excluding the impact of gasoline price inflation;
•The effective tax rate in 2026 was 24.7%, compared to 25.1% in 2025;
•Net income increased 14% to $9,226, $20.76 per diluted share, compared to $8,099, $18.21 per diluted share in 2025; and
•In April, the Board of Directors approved a 13% increase in the quarterly cash dividend.
Tariff Impacts
Beginning in February 2025, the United States imposed tariffs under the International Emergency Economic Powers Act (IEEPA) on certain goods, materials, and products imported into the United States. We paid the government approximately $500 in IEEPA tariffs. In February 2026, the U.S. Supreme Court ruled that the IEEPA tariffs were unlawful. Following this ruling, the government launched a program to administer IEEPA refunds.
We applied the gain contingency model, in accordance with Accounting Standards Codification (ASC) 450-30, “Gain Contingencies,” recognizing recoveries in our consolidated statements of operations only as they were realized. During 2026, we began filing for refunds and received $184, made up of $174 in refunds, recorded as a reduction to merchandise costs, and $10 recorded as interest income. A portion of these refunds was invested in reducing prices for members. Subsequent to 2026, we received $155 in additional refunds and we intend to continue to invest the majority of the refunds in increased value for the member. For a small percentage of transactions where corrections are required, refunds may be delayed as the government continues to implement the IEEPA refund process.
25

RESULTS OF OPERATIONS
Net Sales
202620252024
Net Sales
$297,247$269,912$249,625
Increases in net sales:
U.S.10 %9 %4 %
Canada10 %6 %6 %
Other International12 %8 %9 %
Total Company10 %8 %5 %
Increases in comparable sales(1):
U.S.8 %6 %4 %
Canada8 %5 %7 %
Other International10 %5 %8 %
Total Company8 %6 %5 %
Increases in comparable sales excluding the impact of changes in foreign-currency and gasoline prices(1):
U.S.7 %7 %5 %
Canada7 %8 %8 %
Other International6 %8 %8 %
Total Company7 %8 %6 %
_______________
(1)Comparable sales for 2024 were calculated using comparable retail weeks.

Net sales increased $27,335 or 10% during 2026. The improvement was primarily attributable to an increase in comparable sales of $22,457 or 8%. Comparable sales were positively impacted by increases of 5% in average ticket and 3% in shopping frequency. The remaining increase in net sales was driven by sales at the 25 net new warehouses opened since the end of 2025.
Digitally-enabled comparable sales increased 21% during 2026, both as reported and excluding the impact of changes in foreign currencies.
Sales increased $17,136 or 8% in core merchandise categories, increasing in all categories. Sales in warehouse ancillary and other businesses increased $10,199, or 20%, led by gasoline and pharmacy.
Higher gasoline prices positively impacted net sales by $3,501, or 130 basis points, with a 12% increase in the average price per gallon. The volume of gasoline sold increased 7%, positively impacting net sales by $1,913, or 71 basis points.
Changes in foreign currencies relative to the U.S. dollar positively impacted net sales by $1,332, or 49 basis points, attributable to our Other International and Canadian operations.
Membership Fees
202620252024
Membership fees$5,907$5,323$4,828
Membership fee revenue increased 11% in 2026, driven by new member sign-ups, membership fee increases, and upgrades to Executive memberships. At the end of 2026, member renewal rates were 92.3% in the U.S. and Canada and 89.8% worldwide.
26

As previously reported, we increased annual membership fees in the U.S. and Canada, effective September 1, 2024. We account for membership fee revenue on a deferred basis, recognized ratably over the one-year membership period. The fee income increase accounted for approximately 30% and 40% of membership income growth during 2026 and 2025.
Gross Margin
202620252024
Net sales$297,247$269,912$249,625
Less merchandise costs264,279239,886222,358
Gross margin$32,968$30,026$27,267
Gross margin percentage11.09 %11.12 %10.92 %
Gross margin percentage decreased three basis points. Excluding the impact of gasoline price inflation on net sales, gross margin percentage was 11.22%, an increase of 10 basis points. This increase was positively impacted by 19 basis points in warehouse ancillary and other businesses, primarily gasoline and pharmacy, offset by an 11 basis point decrease in core merchandise categories. The majority of the increase in warehouse ancillary and other businesses and the decrease in core merchandise categories was due to the change in sales mix as warehouse ancillary and other businesses sales grew at a faster rate than core merchandise categories. Core merchandise categories were also negatively impacted by our co-branded credit card program as a result of reward costs associated with higher gasoline sales. IEEPA tariff refunds, net of investment in price reductions for members, positively impacted gross margin by three basis points.
The gross margin in core merchandise categories when expressed as a percentage of their own sales increased 15 basis points. The increase was across all categories. Gross margin in warehouse ancillary and other businesses when expressed as a percentage of their own sales decreased 14 basis points, primarily due to gasoline and pharmacy.
Changes in foreign currencies relative to the U.S. dollar positively impacted gross margin by $137, attributable to our Other International and Canadian operations.
Selling, General and Administrative Expenses
202620252024
SG&A expenses$27,190$24,966$22,810
SG&A expenses as a percentage of net sales9.15 %9.25 %9.14 %
SG&A expenses as a percentage of net sales decreased 10 basis points compared to 2025. SG&A expenses as a percentage of net sales excluding the impact of gasoline price inflation was 9.26%, an increase of one basis point. Changes in foreign currencies relative to the U.S. dollar increased SG&A expenses by $126, attributable to our Other International and Canadian operations. SG&A expenses as a percentage of net sales increased in our Canadian and Other International segments and were flat in our U.S. segment compared to 2025.
Interest Expense
202620252024
Interest expense$145 $154 $169 
Interest expense is primarily related to Senior Notes and financing leases. For more information on our debt arrangements, refer to the consolidated financial statements included in Item 8 of this Report.
27

Interest Income and Other, Net
202620252024
Interest income$601 $469 $533 
Foreign-currency transaction gains, net69 84 26 
Other, net41 36 65 
Interest income and other, net$711 $589 $624 
The increase in interest income in 2026 was due to higher cash balances, partially offset by lower interest rates. Foreign-currency transaction gains, net, include revaluation or settlement of monetary assets and liabilities by our Canadian and Other International operations and mark-to-market adjustments for forward foreign-exchange contracts. See Derivatives and Foreign-Currency sections in Note 1 to the consolidated financial statements included in Item 8 of this Report.
Provision for Income Taxes
202620252024
Provision for income taxes$3,025 $2,719 $2,373 
Effective tax rate24.7 %25.1 %24.4 %
The effective tax rate for 2026 was favorably impacted by net discrete tax benefits of $83 and $72 related to research and development credits and stock compensation. The effective tax rate for 2025 was favorably impacted by discrete tax benefits of $100 related to stock compensation
The Organization of Economic Cooperation and Development (OECD) introduced a framework to implement a global minimum corporate tax of 15% (referred to as Pillar 2), which was effective for fiscal 2025. Pillar 2 did not have a material impact on our consolidated financial statements.
LIQUIDITY AND CAPITAL RESOURCES
The following table summarizes our significant sources and uses of cash and cash equivalents:
202620252024
Net cash provided by operating activities$15,817 $13,335 $11,339 
Net cash used in investing activities(6,378)(5,311)(4,409)
Net cash used in financing activities(3,355)(3,775)(10,764)
Our primary sources of liquidity are cash flows from operations, cash and cash equivalents, and short-term investments. Cash and cash equivalents and short-term investments were $21,301 and $15,284 at August 30, 2026, and August 31, 2025. Of these balances, unsettled credit and debit card receivables represented $2,842 and $2,670. These receivables generally settle within four days.
Material contractual obligations arising in the normal course of business primarily consist of purchase obligations, long-term debt and related interest payments, leases, and construction and land purchase obligations. See Notes 4 and 5 to the consolidated financial statements included in Item 8 of this Report for amounts outstanding on August 30, 2026, related to debt and leases.
Purchase obligations consist of contracts primarily related to merchandise, equipment, and third-party services, the majority of which are due in the next 12 months. Construction and land-purchase obligations consist of contracts primarily related to the development and opening of new and relocated warehouses, the majority of which (other than leases) are due in the next 12 months.
28

We believe that our cash and investment positions and operating cash flow, with capacity under existing and available credit agreements, will be sufficient to meet our liquidity and capital requirements for the foreseeable future and that our U.S. current and projected asset position is sufficient to meet our U.S. liquidity requirements.
Cash Flows from Operating Activities
Our cash flow provided by operations is primarily from net sales and membership fees. Cash flow used in operations generally consists of payments to merchandise suppliers, warehouse operating costs, including wages and employee benefits, utilities, credit and debit card processing fees, and operating leases. Cash used in operations also includes payments for income taxes. Changes in our net investment in merchandise inventories (the difference between merchandise inventories and accounts payable) is impacted by several factors, including inventory levels and turnover, payment terms with suppliers, and early payments to obtain discounts. Net cash provided by operating activities totaled $15,817 in 2026, compared to $13,335 in 2025. The increase was primarily due to higher operating income, as well as reduced net investment in merchandise inventories. The latter was a result of faster inventory turns and improved payment terms with suppliers.
Cash Flows from Investing Activities
Net cash used in investing activities totaled $6,378 in 2026, compared to $5,311 in 2025, and is primarily related to capital expenditures. Net cash from investing activities also includes purchases and maturities of short-term investments.
Capital Expenditure Plans
Our primary requirements for capital are acquiring land, buildings, and equipment for new and remodeled warehouses, information systems, and manufacturing and distribution facilities. In 2026, we spent $6,435 on capital expenditures, and it is our current intention to spend approximately $7,500 during fiscal 2027. These expenditures are expected to be financed with cash from operations, cash and cash equivalents, and short-term investments. We opened 28 new warehouses, including three relocations, in 2026, and plan to open up to 33 new warehouses, including five relocations, in 2027. There can be no assurance that current expectations will be realized, and plans are subject to change upon further review of our capital expenditure needs and the economic environment.
Cash Flows from Financing Activities
Net cash used in financing activities totaled $3,355 in 2026, compared to $3,775 in 2025. Cash flow used in financing activities primarily related to the payment of dividends, repurchases of common stock, repayments of short-term borrowings and long-term debt, and withholding taxes on stock-based awards. Cash flow provided by financing activities included proceeds from short-term borrowings and issuance of long-term debt.
Long-term Debt
Proceeds from long-term debt in 2026 included three series of Guaranteed Senior Notes totaling approximately $500, at fixed interest rates ranging from 2.620% to 3.680%, issued by our Japan subsidiary, as compared to no proceeds in 2025. Repayments of long-term debt in 2026 totaled $69, as compared to $103 in 2025.
Dividends
Cash dividends declared in 2026 totaled $2,458, $5.54 per share, as compared to $2,183, $4.92 per share, in 2025. In April 2026, the Board of Directors increased our quarterly cash dividend from $1.30 to $1.47 per share.
29

Share Repurchase Program
On January 19, 2023, the Board of Directors authorized a share repurchase program in the amount of $4,000, which expires in January 2027. During 2026 and 2025, we repurchased 891,000 and 943,000 shares of common stock, at an average price per share of $950.90 and $957.66, totaling $847 and $903. These amounts may differ from the accompanying consolidated statements of cash flows due to changes in unsettled repurchases at the end of each fiscal year. Purchases are made from time to time, as conditions warrant, in the open market or in block purchases, pursuant to plans under SEC Rule 10b5-1. Repurchased shares are retired, in accordance with the Washington Business Corporation Act. The remaining amount available to be purchased under our approved plan was $1,115 at the end of 2026.
Bank Credit Facilities and Commercial Paper Programs
We maintain bank credit facilities for working capital and general corporate purposes. At August 30, 2026, we had borrowing capacity under these facilities of $2,118, compared to $1,220 at the end of 2025. This increase was primarily driven by the renewal and expansion of our U.S. revolving credit facility in August 2026, which increased total borrowing capacity from $400 to $1,000 and extended the maturity date to August 2027, as well as credit facility expansions in our Japan and Mexico subsidiaries. Our Canadian and Other International operations maintain $1,012 of this capacity under bank credit facilities, of which $333 is guaranteed by the Company. There were no short-term borrowings outstanding under the bank credit facilities at the end of 2026. Short-term borrowings were immaterial at the end of 2025 and were included in other current liabilities on the consolidated balance sheets.
We have letter of credit facilities, for commercial and standby letters of credit, totaling $232. The outstanding commitments under these facilities at the end of 2026 totaled $210, most of which were standby letters of credit that do not expire or have expiration dates within one year. The bank credit facilities have various expiration dates, most within one year, and we generally intend to renew these facilities. The amount of borrowings available at any time under our bank credit facilities is reduced by the amount of standby and commercial letters of credit outstanding.
Off-Balance Sheet Arrangements
In the opinion of management, we have no off-balance sheet arrangements that have had or are reasonably likely to have a material current or future effect on our financial condition or financial statements.
Critical Accounting Estimates
The preparation of our consolidated financial statements in accordance with U.S. GAAP requires that we make estimates and assumptions that affect the reported amounts of assets and liabilities and the disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. We base our estimates on historical experience and on assumptions that we believe to be reasonable, and we continue to review and evaluate these estimates. For further information on significant accounting policies, see discussion in Note 1 to the consolidated financial statements included in Item 8 of this Report.
Insurance/Self-insurance Liabilities
Claims for employee health-care benefits, workers’ compensation, general liability, property damage, directors’ and officers’ liability, vehicle liability, inventory loss, and other exposures are funded predominantly through self-insurance. Insurance coverage is maintained for certain risks to limit exposures to very large losses. We use various risk management mechanisms, including a wholly-owned captive insurance subsidiary and a reinsurance program. Liabilities associated with the risks that we retain are not discounted and are estimated using historical claims experience, demographic factors, severity factors, and other actuarial assumptions. The costs of claims are highly unpredictable and can fluctuate as a result of inflation rates, regulatory or legal changes, and developments in claim frequency
30

and amounts. While we believe our estimates are reasonable, actual claims and costs could differ significantly from recorded liabilities. Historically, adjustments to our estimates have been immaterial.
Recent Accounting Pronouncements
See discussion of Recent Accounting Pronouncements in Note 1 to the consolidated financial statements included in Item 8 of this Report.
Item 7A—Quantitative and Qualitative Disclosures About Market Risk (amounts in millions)
Our exposure to financial market risk results from fluctuations in interest rates and foreign-currency exchange rates. We do not engage in speculative or leveraged transactions or hold or issue financial instruments for trading purposes.
Interest Rate Risk
Our exposure to market risk for changes in interest rates relates primarily to our investment holdings, which are diversified among various instruments considered to be cash equivalents, as defined in Note 1 to the consolidated financial statements included in Item 8 of this Report, as well as short-term investments in government and agency securities with effective maturities of generally three months to ten years at the date of purchase. The primary objective of our investment activities is to preserve principal and secondarily to generate yields. The majority of our short-term investments are in fixed interest-rate securities. These securities are subject to changes in fair value due to interest rate fluctuations.
Our policy limits investments in the U.S. to direct U.S. government and government agency obligations, repurchase agreements collateralized by U.S. government and government agency obligations, U.S. government and government agency money market funds, and insured bank balances. Our Canadian and Other International subsidiaries’ investments are primarily in money market funds and bank certificates of deposit, generally denominated in local currencies.
A 100 basis point change in interest rates as of the end of 2026 would have had an immaterial incremental change in fair market value. For those investments that are classified as available-for-sale, the unrealized gains or losses related to fluctuations in market volatility and interest rates are reflected within stockholders’ equity in accumulated other comprehensive income in the consolidated balance sheets.
The nature and amount of our long-term debt may vary as a result of business requirements, market conditions, and other factors. As of the end of 2026, long-term debt with fixed interest rates was $6,175. Fluctuations in interest rates may affect the fair value of the fixed-rate debt. See Note 4 to the consolidated financial statements included in Item 8 of this Report for more information on our long-term debt.
Foreign-Currency Risk
Our foreign subsidiaries conduct certain transactions in non-functional currencies, which exposes us to fluctuations in exchange rates. We manage these fluctuations, in part, through the use of forward foreign-exchange contracts, seeking to economically hedge the impact of these fluctuations on known future expenditures denominated in a non-functional foreign-currency. The contracts are intended primarily to economically hedge exposure to U.S. dollar merchandise inventory expenditures made by our international subsidiaries. We seek to mitigate risk with the use of these contracts and do not intend to engage in speculative transactions. For additional information related to the Company's forward foreign-exchange contracts, see Notes 1 and 3 to the consolidated financial statements included in Item 8 of this Report. A hypothetical 10% strengthening of the functional currencies compared to the non-functional currency exchange rates at August 30, 2026, would have decreased the fair value of the contracts by
31

approximately $55 and resulted in an unrealized loss in the consolidated statements of income for the same amount.
Commodity Price Risk
We are exposed to fluctuations in prices for energy, particularly electricity and natural gas, and other commodities used in retail and manufacturing operations. We seek to partially mitigate these through fixed-price contracts for certain of our warehouses and other facilities, predominantly in the U.S. and Canada. We also enter into variable-priced contracts for some purchases of electricity and natural gas, in addition to some of the fuel for our gas stations, on an index basis. These contracts meet the characteristics of derivative instruments, but generally qualify for the “normal purchases and normal sales” exception under authoritative guidance and require no mark-to-market adjustment.
32

Item 8—Financial Statements and Supplementary Data
COSTCO WHOLESALE CORPORATION
INDEX TO CONSOLIDATED FINANCIAL STATEMENTS
33

REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the Stockholders and Board of Directors
Costco Wholesale Corporation:
Opinion on the Consolidated Financial Statements
We have audited the accompanying consolidated balance sheets of Costco Wholesale Corporation and subsidiaries (the Company) as of August 30, 2026 and August 31, 2025, the related consolidated statements of income, comprehensive income, equity, and cash flows for each of the fiscal years in the three-year period ended August 30, 2026, and the related notes (collectively, the consolidated financial statements). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company as of August 30, 2026 and August 31, 2025, and the results of its operations and its cash flows for each of the fiscal years in the three-year period ended August 30, 2026, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of August 30, 2026, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission, and our report dated October 6, 2026 expressed an unqualified opinion on the effectiveness of the Company’s internal control over financial reporting.
Basis for Opinion
These consolidated financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on these consolidated financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. We believe that our audits provide a reasonable basis for our opinion.
Critical Audit Matter
The critical audit matter communicated below is a matter arising from the current period audit of the consolidated financial statements that was communicated or required to be communicated to the audit committee and that: (1) relates to accounts or disclosures that are material to the consolidated financial statements and (2) involved our especially challenging, subjective, or complex judgments. The communication of a critical audit matter does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
34

Sufficiency of audit evidence over United States and Canada revenue
As discussed in Note 11 to the consolidated financial statements, the Company generated $219,823 million and $40,561 million of total revenue in the United States (U.S.) and Canada, respectively, for the year ended August 30, 2026, which included revenue from membership fees, merchandise sales, and gasoline sales (U.S. and Canada revenue). The processing and recording of U.S. and Canada revenue is dependent upon the use of multiple information technology (IT) systems.
We identified the evaluation of the sufficiency of audit evidence over U.S. and Canada revenue as a critical audit matter. Evaluating the sufficiency of audit evidence required subjective auditor judgment due to the highly automated nature of certain processes to record U.S. and Canada revenue, which involves interfacing significant volumes of data across multiple IT systems. The complexity of the IT environment required the involvement of IT professionals with specialized skills and knowledge.
The following are the primary procedures we performed to address this critical audit matter. We applied auditor judgment to determine the nature and extent of procedures to be performed over the processing and recording of U.S. and Canada revenue, including the IT systems tested. We involved IT professionals with specialized skills and knowledge, who assisted in evaluating the design and testing the operating effectiveness of certain internal controls over the Company's revenue process, including general IT and application controls related to the IT systems used for the processing and recording of U.S. and Canada revenue. We performed a software-assisted data analysis to test the relationships among certain revenue journal entries. We evaluated the sufficiency of audit evidence obtained over U.S. and Canada revenue by assessing the results of procedures performed, including the appropriateness of nature and extent of such evidence.
/s/ KPMG LLP
We have served as the Company’s auditor since 2002.
Seattle, Washington
October 6, 2026
35

REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the Stockholders and Board of Directors
Costco Wholesale Corporation:
Opinion on Internal Control Over Financial Reporting
We have audited Costco Wholesale Corporation and subsidiaries’ (the Company) internal control over financial reporting as of August 30, 2026, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission. In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of August 30, 2026, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Company as of August 30, 2026 and August 31, 2025, the related consolidated statements of income, comprehensive income, equity, and cash flows for each of the fiscal years in the three-year period ended August 30, 2026, and the related notes (collectively, the consolidated financial statements), and our report dated October 6, 2026 expressed an unqualified opinion on those consolidated financial statements.
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Annual Report on Internal Control Over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audit also included performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control Over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ KPMG LLP
Seattle, Washington
October 6, 2026
36

COSTCO WHOLESALE CORPORATION
CONSOLIDATED STATEMENTS OF INCOME
(amounts in millions, except per share data)
52 Weeks Ended
August 30,
2026
August 31,
2025
September 1,
2024
REVENUE
Net sales$297,247 $269,912 $249,625 
Membership fees5,907 5,323 4,828 
Total revenue303,154 275,235 254,453 
OPERATING EXPENSES
Merchandise costs264,279 239,886 222,358 
Selling, general and administrative27,190 24,966 22,810 
Operating income11,685 10,383 9,285 
OTHER INCOME (EXPENSE)
Interest expense(145)(154)(169)
Interest income and other, net711 589 624 
INCOME BEFORE INCOME TAXES12,251 10,818 9,740 
Provision for income taxes3,025 2,719 2,373 
NET INCOME$9,226 $8,099 $7,367 
NET INCOME PER COMMON SHARE:
Basic$20.78 $18.24 $16.59 
Diluted$20.76 $18.21 $16.56 
Shares used in calculation (000’s)
Basic443,953 443,985 443,914 
Diluted444,427 444,803 444,759 

The accompanying notes are an integral part of these consolidated financial statements.
37

COSTCO WHOLESALE CORPORATION
CONSOLIDATED STATEMENTS OF COMPREHENSIVE INCOME
(amounts in millions)
52 Weeks Ended
August 30,
2026
August 31,
2025
September 1,
2024
NET INCOME
$9,226 $8,099 $7,367 
Foreign-currency translation adjustment and other, net
150 58 (23)
COMPREHENSIVE INCOME
$9,376 $8,157 $7,344 


The accompanying notes are an integral part of these consolidated financial statements.
38

COSTCO WHOLESALE CORPORATION
CONSOLIDATED BALANCE SHEETS
(amounts in millions, except par value and share data)
August 30,
2026
August 31,
2025
ASSETS
CURRENT ASSETS
Cash and cash equivalents$20,207 $14,161 
Short-term investments1,094 1,123 
Receivables, net3,959 3,203 
Merchandise inventories19,324 18,116 
Other current assets1,998 1,777 
Total current assets46,582 38,380 
OTHER ASSETS
Property and equipment, net35,633 31,909 
Operating lease right-of-use assets2,697 2,725 
Other long-term assets4,133 4,085 
TOTAL ASSETS$89,045 $77,099 
LIABILITIES AND EQUITY
CURRENT LIABILITIES
Accounts payable$22,591 $19,783 
Accrued salaries and benefits5,641 5,205 
Accrued member rewards3,037 2,677 
Deferred membership fees3,006 2,854 
Current portion of long-term debt2,248 75 
Other current liabilities7,429 6,514 
Total current liabilities43,952 37,108 
OTHER LIABILITIES
Long-term debt, excluding current portion3,914 5,713 
Long-term operating lease liabilities2,414 2,460 
Other long-term liabilities2,962 2,654 
TOTAL LIABILITIES53,242 47,935 
COMMITMENTS AND CONTINGENCIES
EQUITY
Preferred stock $0.005 par value; 100,000,000 shares authorized; no shares issued and outstanding
— — 
Common stock $0.005 par value; 900,000,000 shares authorized; 443,266,000 and 443,237,000 shares issued and outstanding
2 2 
Additional paid-in capital8,830 8,282 
Accumulated other comprehensive loss(1,620)(1,770)
Retained earnings28,591 22,650 
TOTAL EQUITY35,803 29,164 
TOTAL LIABILITIES AND EQUITY$89,045 $77,099 
The accompanying notes are an integral part of these consolidated financial statements.


39

COSTCO WHOLESALE CORPORATION
CONSOLIDATED STATEMENTS OF EQUITY
(amounts in millions)
Common StockAdditional
Paid-in
Capital
Accumulated
Other
Comprehensive
Income (Loss)
Retained
Earnings
Total
Equity
Shares (000’s)Amount
BALANCE AT SEPTEMBER 3, 2023442,793 $2 $7,340 $(1,805)$19,521 $25,058 
Net income— — — — 7,367 7,367 
Foreign-currency translation adjustment and other, net— — — (23)— (23)
Stock-based compensation— — 822 — — 822 
Release of vested restricted stock units (RSUs), including tax effects1,337 — (315)— — (315)
Repurchases of common stock(1,004)— (18)— (680)(698)
Cash dividends declared— — — — (8,589)(8,589)
BALANCE AT SEPTEMBER 1, 2024443,126 2 7,829 (1,828)17,619 23,622 
Net income— — — — 8,099 8,099 
Foreign-currency translation adjustment and other, net— — — 58 — 58 
Stock-based compensation— — 864 — — 864 
Release of vested RSUs, including tax effects1,054 — (393)— — (393)
Repurchases of common stock(943)— (18)— (885)(903)
Cash dividend declared— — — — (2,183)(2,183)
BALANCE AT AUGUST 31, 2025443,237 2 8,282 (1,770)22,650 29,164 
Net income— — — — 9,226 9,226 
Foreign-currency translation adjustment and other, net— — — 150 — 150 
Stock-based compensation— — 929 — — 929 
Release of vested RSUs, including tax effects920 — (361)— — (361)
Repurchases of common stock(891)— (20)— (827)(847)
Cash dividend declared— — — — (2,458)(2,458)
BALANCE AT AUGUST 30, 2026443,266 $2 $8,830 $(1,620)$28,591 $35,803 
The accompanying notes are an integral part of these consolidated financial statements.


40

COSTCO WHOLESALE CORPORATION
CONSOLIDATED STATEMENTS OF CASH FLOWS
(amounts in millions)
52 Weeks Ended
August 30,
2026
August 31,
2025
September 1,
2024
CASH FLOWS FROM OPERATING ACTIVITIES
Net income$9,226 $8,099 $7,367 
Adjustments to reconcile net income to net cash provided by operating activities:
Depreciation and amortization2,674 2,426 2,237 
Non-cash lease expense318 303 315 
Stock-based compensation924 860 818 
Deferred income taxes306 (108)(60)
Other non-cash operating activities, net49 (9)51 
Changes in operating assets and liabilities:
Merchandise inventories(1,153)559 (2,068)
Accounts payable2,755 404 1,938 
Other operating assets and liabilities, net718 801 741 
Net cash provided by operating activities15,817 13,335 11,339 
CASH FLOWS FROM INVESTING ACTIVITIES
Additions to property and equipment(6,435)(5,498)(4,710)
Purchases of short-term investments(788)(1,028)(1,470)
Maturities of short-term investments811 1,141 1,790 
Other investing activities, net34 74 (19)
Net cash used in investing activities(6,378)(5,311)(4,409)
CASH FLOWS FROM FINANCING ACTIVITIES
Repayments of short-term borrowings(577)(862)(920)
Proceeds from short-term borrowings553 816 928 
Repayments of long-term debt(69)(103)(1,077)
Proceeds from issuance of long-term debt496 — 498 
Tax withholdings on stock-based awards(361)(393)(315)
Repurchases of common stock(848)(903)(700)
Cash dividend payments(2,458)(2,183)(9,041)
Financing lease payments and other financing activities, net(91)(147)(137)
Net cash used in financing activities(3,355)(3,775)(10,764)
EFFECT OF EXCHANGE RATE CHANGES ON CASH AND CASH EQUIVALENTS(38)6 40 
Net change in cash and cash equivalents6,046 4,255 (3,794)
CASH AND CASH EQUIVALENTS BEGINNING OF YEAR14,161 9,906 13,700 
CASH AND CASH EQUIVALENTS END OF YEAR$20,207 $14,161 $9,906 
SUPPLEMENTAL DISCLOSURE OF CASH FLOW INFORMATION:
Cash paid during the year for:
Interest$103 $106 $129 
Income taxes, net$2,839 $2,917 $2,319 
SUPPLEMENTAL DISCLOSURE OF NON-CASH ACTIVITIES:
Capital expenditures included in liabilities$220 $193 $203 
The accompanying notes are an integral part of these consolidated financial statements.


41

COSTCO WHOLESALE CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
(amounts in millions, except share, per share, and warehouse count data)
Note 1—Summary of Significant Accounting Policies
Description of Business
Costco Wholesale Corporation (Costco or the Company), a Washington corporation, and its subsidiaries operate membership warehouses and e-commerce sites based on the concept that offering members low prices on a limited selection of nationally-branded and private-label products in a wide range of merchandise categories will produce high sales volumes and rapid inventory turnover. At August 30, 2026, Costco operated 939 warehouses worldwide: 647 in the United States (U.S.) located in 47 states, Washington, D.C., and Puerto Rico, 115 in Canada, 43 in Mexico, 37 in Japan, 29 in the U.K., 20 in Korea, 15 in Australia, 14 in Taiwan, seven in China, five in Spain, three in France, two in Sweden, and one each in Iceland and New Zealand. The Company operates e-commerce sites in the U.S., Canada, the U.K., Mexico, Korea, Taiwan, Japan, Australia, and China.
Basis of Presentation
The consolidated financial statements include the accounts of Costco and its wholly-owned subsidiaries. All material inter-company transactions among the Company and its consolidated subsidiaries have been eliminated in consolidation.
Fiscal Year End
The Company operates on a 52/53-week fiscal year basis with the year ending on the Sunday closest to August 31. References to 2026, 2025, and 2024 relate to the 52-week fiscal years ended August 30, 2026, August 31, 2025, and September 1, 2024.
Use of Estimates
The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and the disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. These estimates and assumptions take into account historical and forward-looking factors that the Company believes are reasonable. Actual results could differ from those estimates and assumptions.
Reclassification
Reclassifications were made to the 2025 consolidated balance sheet and the 2025 and 2024 consolidated statements of cash flows to conform with current year presentation.
Cash and Cash Equivalents
The Company considers as cash and cash equivalents all cash on deposit, highly liquid investments with a maturity of three months or less at the date of purchase, and proceeds due from credit and debit card transactions with settlement terms of up to four days. Credit and debit card receivables were $2,842 and $2,670 at the end of 2026 and 2025.
Short-Term Investments
Short-term investments generally consist of debt securities (U.S. government and agency securities), with maturities at the date of purchase of three months to ten years. Investments with maturities beyond five years may be classified, based on the Company’s determination, as short-term based on their highly liquid nature and because they represent the investment of cash that is available for current operations.
42

Short-term investments classified as available-for-sale are recorded at fair value using the specific identification method with the unrealized gains and losses reflected in accumulated other comprehensive income (loss) until realized. Realized gains and losses from the sale of available-for-sale securities, if any, are determined on a specific identification basis and are recorded in interest income and other, net in the consolidated statements of income. These available-for-sale investments have a low level of inherent credit risk given they are issued by the U.S. government and agencies. Changes in their fair value are primarily attributable to changes in interest rates and market liquidity. Short-term investments classified as held-to-maturity are financial instruments that the Company has the intent and ability to hold to maturity and are reported net of any related amortization and are not remeasured to fair value on a recurring basis.
The Company periodically evaluates unrealized losses in its investment securities for credit impairment, using both qualitative and quantitative criteria. In the event a security is deemed to be impaired as the result of a credit loss, the Company recognizes the loss in interest income and other, net in the consolidated statements of income.
Fair Value of Financial Instruments
The Company accounts for certain assets and liabilities at fair value. The carrying value of the Company’s financial instruments, including cash and cash equivalents, receivables, and accounts payable, approximate fair value due to their short-term nature or variable interest rates. See Notes 2, 3, and 4 for the carrying value and fair value of the Company’s investments, derivative instruments, and fixed-rate debt.
Fair value is defined as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. Fair value is estimated by applying a fair value hierarchy, which requires maximizing the use of observable inputs when measuring fair value. The three levels of inputs are:
Level 1: Quoted market prices in active markets for identical assets or liabilities.
Level 2: Observable market-based inputs or unobservable inputs that are corroborated by market
data.
Level 3: Significant unobservable inputs that are not corroborated by market data.
The Company’s valuation techniques used to measure the fair value of money market mutual funds, which are included in cash and cash equivalents, are based on quoted market prices, such as quoted net asset values published by the fund as supported in an active market. Valuation methodologies used to measure the fair value of all other non-derivative financial instruments are based on independent external valuation information. The pricing process uses data from a variety of independent external valuation information providers, including trades, bid price or spread, two-sided markets, quotes, benchmark curves including but not limited to treasury benchmarks, Secured Overnight Financing Rate and swap curves, discount rates, and market data feeds. All are observable in the market or can be derived principally from or corroborated by observable market data. The Company reports transfers in and out of Levels 1, 2, and 3, as applicable, using the fair value of the individual securities as of the beginning of the reporting period in which the transfer(s) occurred.
Current financial liabilities have fair values that approximate their carrying values. Long-term financial liabilities include the Company's long-term debt, which are recorded on the balance sheet at issuance price and adjusted for unamortized discounts or premiums and debt issuance costs. Discounts, premiums, and debt issuance costs are amortized to interest expense over the term of the loan. The estimated fair value of the Company's long-term debt is based primarily on reported market values, recently completed market transactions, and estimates based upon interest rates, maturities, and credit.
43

Receivables, Net
Receivables consist primarily of vendor, third-party pharmacy, credit card incentive, reinsurance, and other receivables. Vendor receivables include discounts, volume rebates, and a variety of other programs. Balances are generally presented on a gross basis, separate from any related payable due. In certain circumstances, these receivables may be settled against the related payable to that vendor, in which case the receivables are presented on a net basis. Third-party pharmacy receivables generally relate to amounts due from insurance providers. Credit card incentive receivables primarily represent amounts earned under co-branded credit card arrangements. Reinsurance receivables are held by the Company’s wholly-owned captive insurance subsidiary and primarily represent amounts ceded through reinsurance arrangements gross of the amounts assumed under reinsurance, which are presented within other current liabilities in the consolidated balance sheets. Other receivables primarily consist of amounts due from governmental entities, mostly tax-related items.
The valuation allowance related to receivables was immaterial to the Company's consolidated financial statements at the end of 2026 and 2025.
Merchandise Inventories
Merchandise inventories consist of the following:
20262025
United States $13,707 $12,868 
Canada2,188 1,907 
Other International3,429 3,341 
Merchandise inventories$19,324 $18,116 
Merchandise inventories are stated at the lower of cost or market. U.S. merchandise inventories are valued by the cost method of accounting, using the last-in, first-out (LIFO) basis. The Company believes the LIFO method more fairly presents the results of operations by more closely matching current costs with current revenues. The Company records an adjustment each quarter, if necessary, for the projected annual effect of inflation or deflation, and these estimates are adjusted to actual results determined at year-end, after actual inflation or deflation rates and inventory levels have been determined. Due to higher merchandise costs in 2026, a $206 charge was recorded to merchandise costs to increase the cumulative LIFO valuation on merchandise inventories at August 30, 2026. A charge of $142 was recorded in 2025 and an immaterial LIFO benefit was recorded in 2024. Canadian and Other International merchandise inventories are predominantly valued using the cost and retail inventory methods, respectively, using the first-in, first-out (FIFO) basis.
The Company initially provides for estimated inventory losses between physical inventory counts using estimates based on experience. The provision is adjusted to reflect physical inventory counts, which generally occur in the second and fourth fiscal quarters. Inventory cost where appropriate is reduced by estimates of vendor rebates when earned or as the Company progresses towards earning those rebates, provided that they are probable and reasonably estimable.
Property and Equipment, Net
Property and equipment are stated at cost. Depreciation and amortization expense is computed primarily using the straight-line method over estimated useful lives. Leasehold improvements made after the beginning of the initial lease term are depreciated over the shorter of the estimated useful life of the asset or the remaining term of the initial lease plus any renewals that are reasonably certain at the date of the leasehold improvements.
The Company capitalizes certain computer software and costs incurred in developing or obtaining software for internal use. During development, these costs are included in construction in progress. To the
44

extent that the assets become ready for their intended use, these costs are included in equipment and fixtures and amortized on a straight-line basis over estimated useful lives.
Repair and maintenance costs are expensed when incurred. Expenditures for remodels, refurbishments, and improvements that add to or change asset function or useful life are capitalized. Assets removed during the remodel, refurbishment, or improvement are retired. Assets classified as held-for-sale at the end of 2026 and 2025 were immaterial.
The following table summarizes the Company's property and equipment balances at the end of 2026 and 2025:
Estimated Useful Lives20262025
LandN/A$11,265 $10,323 
Buildings and improvements
5-50 years
27,775 25,508 
Equipment and fixtures
3-20 years
14,850 13,127 
Construction in progressN/A2,722 1,882 
56,612 50,840 
Accumulated depreciation and amortization(20,979)(18,931)
Property and equipment, net$35,633 $31,909 
The Company evaluates long-lived assets for impairment on an annual basis, when relocating or closing a facility, or when events or changes in circumstances may indicate that the carrying amount of the asset group, generally an individual warehouse, may not be fully recoverable. For asset groups held and used, including warehouses to be relocated, the carrying value of the asset group is considered recoverable when the estimated future undiscounted cash flows generated from the use and eventual disposition of the asset group exceed the respective carrying value. In the event that the carrying value is not considered recoverable, an impairment loss is recognized for the asset group to be held and used equal to the excess of the carrying value above the estimated fair value of the asset group. For asset groups classified as held-for-sale (disposal group), the carrying value is compared to the disposal group’s fair value less costs to sell. The Company estimates fair value by obtaining market appraisals from third party brokers or using other valuation techniques. There were no impairment charges recognized in 2026, and impairment charges in 2025 and 2024 were immaterial.
Leases
The Company leases land, buildings, and/or equipment at warehouses and certain other office and distribution facilities. Leases generally contain one or more of the following options, which the Company can exercise at the end of the initial term: (a) renew the lease for a defined number of years at the then-fair market rental rate or rate stipulated in the lease agreement; (b) purchase the property at the then-fair market value or purchase price stated in the agreement; (c) a right of first refusal in the event of a third-party offer; or (d) a right of first offer if the landlord intends to sell.
Some leases include free-rent periods and step-rent provisions, which are recognized on a straight-line basis over the original term of the lease and any extension options that the Company is reasonably certain to exercise from the date the Company has control of the property. Certain leases provide for periodic rent increases based on price indices or the greater of minimum guaranteed amounts or sales volume, which are recognized as variable lease payments. The Company's leases do not contain any material residual value guarantees or material restrictive covenants.
The Company determines at inception whether a contract is or contains a lease. Non-lease components and the lease components to which they relate are accounted for together as a single lease component for all asset classes. The Company initially records right-of-use (ROU) assets and lease obligations for its finance and operating leases based on the discounted future minimum lease payments over the term.
45

The lease term is defined as the noncancelable period of the lease plus any options to extend when it is reasonably certain that the Company will exercise the option. As the rate implicit in the Company's leases is not easily determinable, the present value of the sum of the lease payments is calculated using the Company's incremental borrowing rate. The rate is determined using a portfolio approach based on the rate of interest the Company would pay to borrow an amount equal to the lease payments on a collateralized basis over a similar term. The Company uses quoted interest rates from financial institutions to derive the incremental borrowing rate. Impairment of ROU assets is evaluated in a similar manner as described in Property and Equipment, Net above.
The Company's asset retirement obligations (ARO) primarily relate to leasehold improvements that must be removed at the end of a lease. These obligations are recorded as a discounted liability, with an offsetting asset, based upon the estimated fair value of the costs to remove the improvements. These liabilities are accreted over time to the projected future value of the obligation. The ARO assets are depreciated using the same depreciation method as the leasehold improvement assets and are included in buildings and improvements. Estimated ARO liabilities associated with these leases are included in other long-term liabilities in the consolidated balance sheet.
Goodwill and Acquired Intangible Assets
Goodwill represents the excess of acquisition cost over the fair value of the net assets acquired and is not subject to amortization. The Company reviews goodwill annually in the fourth quarter for impairment or when circumstances indicate carrying value may exceed the fair value. This evaluation is performed at the reporting unit level. If a qualitative assessment indicates that it is more likely than not that the fair value is less than carrying value, a quantitative analysis is completed using either the income or market approach, or a combination of both. The income approach estimates fair value based on expected discounted future cash flows, while the market approach uses comparable public companies and transactions to develop metrics to be applied to historical and expected future operating results.
Goodwill is included in other long-term assets in the consolidated balance sheets. At the end of 2026, 2025, and 2024 goodwill balances in the Company's U.S., Canadian, and Other International operations were $953, $26, and $15, respectively. No impairment charges were recorded in 2026, 2025, or 2024.
Definite-lived intangible assets, which are immaterial, are included in other long-term assets on the consolidated balance sheets and are amortized on a straight-line basis over their estimated lives, which approximates the pattern of expected economic benefit.
Insurance/Self-insurance Liabilities
Claims for employee health-care benefits, workers’ compensation, general liability, property damage, directors’ and officers’ liability, vehicle liability, inventory loss, and other exposures are funded predominantly through self-insurance. Insurance coverage is maintained for certain risks to limit exposures to very large losses. The Company uses various risk management mechanisms, including a wholly-owned captive insurance subsidiary and participates in a reinsurance program. Liabilities associated with the risks that are retained by the Company are not discounted and are estimated using historical claims experience, demographic factors, severity factors, and other actuarial assumptions. The estimated accruals for these liabilities could be significantly affected if future occurrences, claims, or expenses differ from these assumptions and historical trends. At the end of 2026 and 2025, these insurance liabilities were $2,157 and $1,878 in the aggregate, and were included in accrued salaries and benefits and other current liabilities in the consolidated balance sheets, classified based on their nature.
The captive receives direct premiums, which are netted against the Company’s premium costs in SG&A expenses in the consolidated statements of income. The captive participates in a reinsurance program that includes third-party participants. The participant agreements and practices of the reinsurance program are designed to limit participating members’ individual risk. Income statement adjustments related to the reinsurance program and related impacts to the consolidated balance sheets are
46

recognized as information becomes known. In the event the Company leaves the reinsurance program, the Company retains its primary obligation to the participants for prior activity.
Derivatives
The Company is exposed to foreign-currency exchange-rate fluctuations in the normal course of business. It manages these fluctuations, in part, through the use of forward foreign-exchange contracts, seeking to economically hedge the impact of fluctuations of foreign-exchange on known future expenditures denominated in a non-functional foreign-currency. The contracts relate primarily to U.S. dollar merchandise inventory expenditures made by the Company’s international subsidiaries with functional currencies other than the U.S. dollar. These contracts either do not qualify for or the Company has not elected derivative hedge accounting. The Company seeks to mitigate risk with the use of these contracts and does not intend to engage in speculative transactions. Some of these contracts contain credit-risk-related contingent features that require settlement of outstanding contracts upon certain triggering events. The aggregate fair value amounts of derivative instruments in a net liability position and the amount needed to settle the instruments immediately if the credit-risk-related contingent features were triggered were immaterial at the end of 2026 and 2025. The aggregate notional amounts of open, unsettled forward foreign-exchange contracts were $541 and $1,184 at the end of 2026 and 2025. See Note 3 for information on the fair value of unsettled forward foreign-exchange contracts at the end of 2026 and 2025.
The unrealized gains or losses recognized in interest income and other, net in the consolidated statements of income relating to the net changes in the fair value of unsettled forward foreign-exchange contracts were immaterial in 2026, 2025, and 2024.
The Company is exposed to fluctuations in prices for energy, particularly electricity and natural gas, and other commodities used in retail and manufacturing operations, which it seeks to partially mitigate through the use of fixed-price contracts for certain of its warehouses and other facilities, primarily in the U.S. and Canada. The Company also enters into variable-priced contracts for some purchases of natural gas, in addition to fuel for its gas stations, on an index basis. These contracts meet the characteristics of derivative instruments, but generally qualify for the “normal purchases and normal sales” exception under authoritative guidance and require no mark-to-market adjustment.
Foreign-Currency
The functional currencies of the Company’s international subsidiaries are their local currencies. Assets and liabilities recorded in foreign currencies are translated at the exchange rate on the balance sheet date. Translation adjustments are recorded in accumulated other comprehensive loss. Revenues and expenses of the Company’s consolidated foreign operations are translated at average exchange rates prevailing during the year.
The Company recognizes foreign-currency transaction gains and losses related to revaluing or settling monetary assets and liabilities denominated in currencies other than the functional currency in interest income and other, net in the consolidated statements of income. Generally, these include the U.S. dollar cash and cash equivalents and the U.S. dollar payables of consolidated subsidiaries revalued to their functional currency. Also included are realized foreign-currency gains or losses from settlements of forward foreign-exchange contracts. These items were immaterial in 2026, 2025, and 2024.
Revenue Recognition
The Company recognizes sales for the amount of consideration collected from the member, which includes gross shipping fees where applicable, and is net of sales taxes collected and remitted to government agencies and member returns. The Company reserves for estimated returns based on historical trends and reduces sales and merchandise costs accordingly. The Company records on a gross basis a refund liability and an asset for recovery, which are included in other current liabilities and other current assets, respectively, in the consolidated balance sheets.
47

The Company offers merchandise in the following core merchandise categories: foods and sundries, non-foods, and fresh foods. The Company also provides expanded products and services through warehouse ancillary and other businesses. The Company is the principal for the majority of its transactions and recognizes revenue on a gross basis. The Company is the principal when it has control of the merchandise or service before it is transferred to the member. The majority of revenue from merchandise sales is recognized at the point of sale. Revenue generated through e-commerce or special orders is generally recognized upon shipment to the member. For merchandise shipped directly to the member, shipping and handling costs are expensed as incurred as fulfillment costs and included in merchandise costs in the consolidated statements of income. In certain ancillary businesses, revenue is deferred until the member picks up merchandise at the warehouse. Deferred sales are included in other current liabilities in the consolidated balance sheets.
The Company accounts for membership fee revenue, net of refunds, on a deferred basis, ratably over the one-year membership period. Deferred membership fees at the end of 2026 and 2025 were $3,006 and $2,854.
In most countries, the Company's Executive members qualify for an Executive reward, generally 2% on qualified purchases, subject to an annual maximum value, which does not expire and is redeemable at Costco warehouses. The Company accounts for this reward as a reduction in sales, net of the estimated impact of non-redemptions (breakage), with the corresponding liability classified as accrued member rewards in the consolidated balance sheets. Estimated breakage is computed based on redemption data. For 2026, 2025, and 2024, the net reduction in sales was $3,383, $3,007, and $2,804.
The Company sells and otherwise provides proprietary shop cards that do not expire and are redeemable at the warehouse or online for merchandise or membership. Revenue from shop cards is recognized upon redemption, and estimated breakage is recognized based on redemption data. The Company accounts for outstanding shop card balances as a liability, net of estimated breakage. Shop card liabilities are included in other current liabilities in the consolidated balance sheets.
Citibank, N.A. is the exclusive issuer of co-branded credit cards to U.S. members. The Company receives various forms of consideration from Citibank, including a royalty on purchases made on the card outside of Costco. A portion of the royalty is used to fund the rebate that cardholders receive, after taking into consideration breakage, which is calculated based on rebate redemption data. The rebates are issued in February and expire on December 31. The Company also maintains varying co-branded credit card arrangements in Canada and certain Other International subsidiaries.
Merchandise Costs
Merchandise costs consist of the purchase price or manufacturing costs of inventory sold, inbound and outbound shipping charges, and all costs related to the Company’s depot, fulfillment, and manufacturing operations, and are reduced by vendor consideration. Merchandise costs also include salaries, benefits, depreciation, and utilities in fresh foods departments and certain ancillary businesses.
Vendor Consideration
The Company receives funds from vendors for discounts and a variety of other programs. These programs are evidenced by agreements that are reflected in the carrying value of the inventory when earned or as the Company progresses towards earning the rebate or discount, and as a component of merchandise costs as the merchandise is sold. Other vendor consideration is generally recorded as a reduction of merchandise costs upon completion of contractual milestones, agreement terms, or other systematic approaches.
Selling, General and Administrative Expenses
Selling, general and administrative expenses consist primarily of salaries, benefits and workers’ compensation costs for warehouse employees (other than fresh foods departments and certain ancillary
48

businesses, which are reflected in merchandise costs), as well as all regional and home office employees, including buying personnel. Selling, general and administrative expenses also include substantially all building and equipment depreciation, stock compensation expense, credit and debit card processing fees, utilities, preopening, as well as other operating costs incurred to support warehouse and e-commerce operations.
Retirement Plans
The Company's 401(k) retirement plan is available to all U.S. employees over the age of 18 who have completed 90 days of employment. The plan allows participants to make wage deferral contributions, a portion of which the Company matches. In addition, the Company provides each eligible participant an annual discretionary contribution. The Company also has a defined contribution plan for employees in Canada and contributes a percentage of each employee's wages. Certain subsidiaries in the Company's Other International operations have defined benefit and defined contribution plans, which are immaterial. Amounts expensed under all plans were $1,174, $1,061, and $963 for 2026, 2025, and 2024, and are predominantly included in SG&A expenses in the consolidated statements of income.
Stock-Based Compensation
The Company grants stock-based compensation, primarily to employees and non-employee directors. Grants to executive officers are generally performance-based. Through a series of shareholder approvals, there have been amended and restated plans and new provisions implemented by the Company. Restricted Stock Units (RSUs) are subject to quarterly vesting in the event of retirement or voluntary termination. Recipients are not entitled to vote or receive dividends on unvested and undelivered shares.
For grants issued prior to October 2025, RSUs generally vest over five years, with accelerated vesting provisions for participants reaching specified long-service milestones (25 years of service for employees; five years for non-employee directors). For grants issued in October 2025 and thereafter, RSUs vest over either a three-year schedule with no accelerated vesting or a five-year schedule with long-service acceleration, based on a one-time election made by eligible participants in 2025. RSUs granted to new participants vest over a three-year term with no such acceleration.
Compensation expense for awards is predominantly recognized using the straight-line method over the requisite service period for the entire award and forfeitures are recognized as they occur. Under accelerated vesting provisions, compensation expense is recognized upon achievement of the long-service term. The cumulative amount of compensation cost recognized at any point in time equals at least the portion of the grant-date fair value of the award that is vested at that date. The fair value of RSUs is calculated as the market value of the common stock on the measurement date less the present value of the expected dividends forgone during the vesting period.
Stock-based compensation expense is predominantly included in SG&A expenses in the consolidated statements of income. Certain stock-based compensation costs are capitalized or included in the cost of merchandise. See Note 7 for additional information.
Income Taxes
The Company accounts for income taxes using the asset and liability method. Deferred tax assets and liabilities are recognized for the future tax consequences attributed to differences between the financial statement carrying amounts of existing assets and liabilities and their tax bases, credits and loss carry-forwards. Deferred tax assets and liabilities are measured using tax rates expected to apply to taxable income in the years in which those temporary differences and carry-forwards are expected to be recovered or settled. The effect on deferred tax assets and liabilities of a change in tax rates is recognized in income in the period that includes the enactment date. A valuation allowance is established when necessary to reduce deferred tax assets to amounts that are more likely than not expected to be realized.
49

The timing and amounts of deductible and taxable items and the probability of sustaining uncertain tax positions requires significant judgment. The benefits of uncertain tax positions are recorded in the Company’s consolidated financial statements only after determining a more-likely-than-not probability that the uncertain tax positions will withstand challenge from tax authorities. When facts and circumstances change, the Company reassesses these probabilities and records changes as appropriate.
Net Income per Common Share
The computation of basic net income per share uses the weighted average number of shares that were outstanding during the period. The computation of diluted net income per share uses the weighted average number of shares in the basic net income per share calculation plus the number of common shares that would be issued assuming vesting of all potentially dilutive common shares outstanding using the treasury stock method for shares subject to RSUs.
Stock Repurchase Programs
Repurchased shares of common stock are retired, in accordance with the Washington Business Corporation Act. The par value of repurchased shares is deducted from common stock and the excess repurchase price over par value is deducted by allocation to additional paid-in capital and retained earnings. The amount allocated to additional paid-in capital is the current value of additional paid-in capital per share outstanding and is applied to the number of shares repurchased. Any remaining amount is allocated to retained earnings. See Note 6 for additional information.
Recent Accounting Pronouncements Adopted
In December 2023, the FASB issued ASU 2023-09, which requires public business entities on an annual basis to disclose specific categories in the income-tax rate reconciliation, provide information for reconciling items that meet a quantitative threshold, and disclose certain information about income taxes paid. The standard is effective for annual periods beginning after December 15, 2024, with early adoption permitted. The Company adopted the ASU for the fiscal year ended August 30, 2026, on a prospective basis. See Note 8 for additional information.
Recent Accounting Pronouncements Not Yet Adopted
In November 2024, the FASB issued 2024-03, which requires disaggregated disclosures of certain costs and expenses on the income statement on an annual and interim basis. The standard is effective for fiscal years beginning after December 15, 2026, and interim periods within fiscal years beginning after December 15, 2027, with early adoption permitted. The amendments should be applied on a prospective basis. Retrospective application is permitted. The Company is evaluating the standard.
Note 2—Investments
The Company’s investments were as follows:
2026:Cost
Basis
Unrealized
Losses, Net
Recorded
Basis
Available-for-sale:
Government and agency securities$810 $(14)$796 
Held-to-maturity:
Certificates of deposit298 — 298 
Total short-term investments$1,108 $(14)$1,094 
50

2025:Cost
Basis
Unrealized
Gains, Net
Recorded
Basis
Available-for-sale:
Government and agency securities$783 $3 $786 
Held-to-maturity:
Certificates of deposit337 — 337 
Total short-term investments$1,120 $3 $1,123 
Gross unrecognized holding gains and losses on available-for-sale securities were not material for the years ended August 30, 2026, and August 31, 2025. At those dates, there were no available-for-sale securities in a material continuous unrealized-loss position. There were no sales of available-for-sale securities during 2026 or 2025.
The maturities of available-for-sale and held-to-maturity securities at the end of 2026 are as follows:
Available-For-SaleHeld-To-Maturity
Cost BasisFair Value
Due in one year or less$126 $126 $298 
Due after one year through five years411 405 — 
Due after five years273 265 — 
Total$810 $796 $298 
Note 3—Fair Value Measurement
Assets and Liabilities Measured at Fair Value on a Recurring Basis
The following table presents information regarding the Company’s financial assets and liabilities that are measured at fair value on a recurring basis and indicates the level within the hierarchy reflecting the valuation techniques utilized to determine such fair value:
Level 2
20262025
Investment in government and agency securities$796 $786 
Forward foreign-exchange contracts, in asset position(1)
1 6 
Forward foreign-exchange contracts, in (liability) position(1)
(3)(14)
Total$794 $778 
 ____________
(1)The asset and liability values are included in other current assets and other current liabilities, respectively, in the consolidated balance sheets.
At August 30, 2026, and August 31, 2025, the Company did not hold any Level 1 or 3 financial assets or liabilities that were measured at fair value on a recurring basis. There were no transfers between levels during 2026 or 2025.
Assets and Liabilities Measured at Fair Value on a Nonrecurring Basis
Assets and liabilities recognized and disclosed at fair value on a nonrecurring basis include items such as financial assets measured at amortized cost and long-lived nonfinancial assets. These assets are measured at fair value if determined to be impaired. There were no material fair value adjustments to these items during 2026 and 2025. Please see Note 1 for additional information.
51

Note 4—Debt
Short-Term Borrowings
The Company maintains various short-term bank credit facilities, with a borrowing capacity of $2,118 and $1,220, in 2026 and 2025. This increase was primarily driven by the renewal and expansion of the Company's U.S. revolving credit facility in August 2026, which increased total borrowing capacity from $400 to $1,000 and extended the maturity date to August 2027, as well as credit facility expansions in the Japan and Mexico subsidiaries. There were no short-term borrowings outstanding at the end of 2026, and short-term borrowings were immaterial at the end of 2025.
Long-Term Debt
The Company's long-term debt consists primarily of Senior Notes, described below. The Company at its option may redeem the Senior Notes at any time, in whole or in part, at a redemption price plus accrued interest. The redemption price is equal to the greater of 100% of the principal amount or the sum of the present value of the remaining scheduled payments of principal and interest to maturity. Additionally, upon certain events, a holder has the right to require a repurchase at a price of 101% of the principal amount plus accrued and unpaid interest. Interest on all outstanding long-term debt is payable semi-annually. The estimated fair value of Senior Notes is valued using Level 2 inputs.
Other long-term debt consists of Guaranteed Senior Notes issued by the Company's Japanese subsidiary, valued using Level 3 inputs. In 2026, the Company’s Japan subsidiary issued three series of Guaranteed Senior Notes, totaling approximately $500, at fixed interest rates ranging from 2.620% to 3.680%. Interest is payable semi-annually, and maturity dates range from June 2031 to June 2041. In 2026, 2025, and 2024 the Japanese subsidiary repaid $69, $103, and $77 of its Guaranteed Senior Notes.
In 2024, the Company repaid the $1,000 outstanding principal balance on its 2.750% Senior Notes.
At the end of 2026 and 2025, the fair value of the Company's long-term debt, including the current portion, was $5,689 and $5,370. The carrying value of long-term debt consisted of the following:
20262025
3.000% Senior Notes due May 2027
$1,000 $1,000 
1.375% Senior Notes due June 2027
1,250 1,250 
1.600% Senior Notes due April 2030
1,750 1,750 
1.750% Senior Notes due April 2032
1,000 1,000 
Other long-term debt1,175 805 
Total long-term debt6,175 5,805 
Less unamortized debt discounts and issuance costs13 17 
Less current portion(1)
2,248 75 
Long-term debt, excluding current portion$3,914 $5,713 
_____________
(1)Net of unamortized debt discounts and issuance costs.
52

Maturities of long-term debt during the next five fiscal years and thereafter are as follows:
2027$2,250 
2028— 
2029136 
20301,750 
2031161 
Thereafter
1,878 
Total
$6,175 
Note 5—Leases
Information regarding the Company's lease assets and liabilities were as follows:
20262025
Assets
Operating lease right-of-use assets$2,697 $2,725 
Finance lease assets(1)
1,413 1,488 
Total lease assets$4,110 $4,213 
Liabilities
Current
Operating lease liabilities(2)
$192 $208 
Finance lease liabilities(2)
94 78 
Long-term
Operating lease liabilities2,414 2,460 
Finance lease liabilities(3)
1,319 1,401 
Total lease liabilities$4,019 $4,147 
 _______________
(1)Included in other long-term assets in the consolidated balance sheets.
(2)Included in other current liabilities in the consolidated balance sheets.
(3)Included in other long-term liabilities in the consolidated balance sheets.
20262025
Weighted-average remaining lease term (years)
Operating leases
1920
Finance leases
2325
Weighted-average discount rate
Operating leases
3.20 %3.05 %
Finance leases
4.72 %4.63 %
53

The components of lease expense, excluding short-term lease costs and sublease income (which were immaterial), were as follows:
202620252024
Operating lease costs(1)
$282 $271 $284 
Finance lease costs:
Amortization of lease assets(1)
106 102 97 
Interest on lease liabilities(2)
64 63 58 
Variable lease costs(1)
195 182 163 
Total lease costs$647 $618 $602 
 _______________
(1)Included in selling, general and administrative expenses and merchandise costs in the consolidated statements of income.
(2)Included in interest expense and merchandise costs in the consolidated statements of income.
Supplemental cash flow information related to leases were as follows:
202620252024
Cash paid for amounts included in the measurement of lease liabilities:
Operating cash flows — operating leases$312 $255 $274 
Operating cash flows — finance leases
62 58 58 
Financing cash flows — finance leases
89 147 136 
Operating lease assets obtained in exchange for new or modified leases238 294 125 
Finance lease assets obtained in exchange for new or modified leases122 131 200 
As of August 30, 2026, future minimum payments during the next five fiscal years and thereafter are as follows:
Operating Leases(1)
Finance Leases
2027$252 $146 
2028258 142 
2029226 130 
2030204 118 
2031186 97 
Thereafter2,399 1,657 
Total(2)
3,525 2,290 
Less amount representing interest919 877 
Present value of lease liabilities$2,606 $1,413 
 _______________
(1)Operating lease payments have not been reduced by expected future sublease income of $90.
(2)Excludes $1,667 of lease payments for leases that have been signed but not commenced.
54

Note 6—Equity
Dividends
Cash dividends declared in 2026 totaled $2,458 or $5.54 per share, as compared to $2,183 or $4.92 per share in 2025. Dividends in 2024 included a special dividend of $15 per share, resulting in a payment of $6,655. The Company's current quarterly dividend rate is $1.47 per share.
Stock Repurchase Programs
The Company's stock repurchase program is conducted under a $4,000 authorization by the Board of Directors, which expires in January 2027. As of the end of 2026, the remaining amount available under the authorization was $1,115. The following table summarizes the Company’s stock repurchase activity:
Shares
Repurchased
(000’s)
Average
Price per
Share
Total Cost
2026891 $950.90 $847 
2025943 957.66 903 
20241,004 695.29 698 
These amounts may differ from repurchases of common stock in the consolidated statements of cash flows due to changes in unsettled stock repurchases at the end of each fiscal year. Purchases are made from time to time, as conditions warrant, in the open market or in block purchases and pursuant to plans under SEC Rule 10b5-1.
Note 7—Stock-Based Compensation
The 2019 Incentive Plan authorizes the issuance of up to 15,885,000 RSUs. The number of RSUs that may be granted under this Plan is subject to adjustments for changes in capital structure. The Company issues new shares of common stock upon vesting and settlement of RSUs. Shares for vested RSUs are generally delivered to participants annually, net of shares withheld for taxes.
Summary of Restricted Stock Unit Activity
At the end of 2026, 5,280,000 shares were available to be granted as RSUs, and the following awards were outstanding:
•1,877,000 time-based RSUs, which vest upon continued employment or service over specified periods of time; and
•123,000 performance-based RSUs, of which 67,000 were granted to executive officers subject to the determination of the attainment of performance targets for 2026, which occurred in September 2026. At that time, a portion vested as a result of executive officers who met accelerated vesting provisions. The remaining awards vest upon continued employment over specified periods of time. Please refer to Note 1 for accelerated vesting requirements.
55

The following table summarizes RSU transactions during 2026:
Number of
Units
(in 000’s)
Weighted-Average
Grant Date Fair
Value
Outstanding at the end of 20252,308 $597.00 
Granted1,088 933.56 
Vested and delivered(1,303)669.59 
Forfeited(93)696.05 
Outstanding at the end of 20262,000 $728.17 
The weighted-average grant date fair value of RSUs granted was $933.56, $883.46, and $547.26 in 2026, 2025, and 2024. The remaining unrecognized compensation cost related to non-vested RSUs at the end of 2026 was $922 and the weighted-average period of time over which this cost will be recognized is 1.5 years. Included in the outstanding balance at the end of 2026 were approximately 704,000 RSUs vested but not yet delivered.
Summary of Stock-Based Compensation
The following table summarizes stock-based compensation expense and the related tax benefits:
202620252024
Stock-based compensation expense$924 $860 $818 
Less recognized income tax benefit
212 183 173 
Stock-based compensation expense, net$712 $677 $645 
Note 8—Taxes
Income Taxes
Income before income taxes is comprised of the following:
202620252024
Domestic$9,070 $8,324 $7,255 
Foreign3,181 2,494 2,485 
Total$12,251 $10,818 $9,740 
56

The provisions for income taxes are as follows:
202620252024
Federal:
Current$1,206 $1,395 $1,245 
Deferred328 (42)48 
Total federal1,534 1,353 1,293 
State:
Current472 449 431 
Deferred21 (18)(77)
Total state493 431 354 
Foreign:
Current1,041 955 798 
Deferred(43)(20)(72)
Total foreign998 935 726 
Total provision for income taxes$3,025 $2,719 $2,373 
The reconciliation between the statutory tax rate and the effective rate for 2026 is as follows:
2026
Federal taxes at statutory rate$2,573 21.0 %
State and local income taxes, net of federal income tax effect(1)
402 3.3 
Foreign tax effects:
Canada - subnational taxes185 1.5 
Canada - other(12)(0.1)
Other foreign jurisdictions117 1.0 
Effect of cross-border tax laws(46)(0.4)
Tax credits:
Research and development(134)(1.1)
Other tax credits(99)(0.8)
Changes in valuation allowance62 0.5 
Nontaxable or nondeductible items(75)(0.6)
Changes in unrecognized tax benefits50 0.4 
Other adjustments2 — 
Total$3,025 24.7 %
 _______________
(1)State taxes in California, New York, New Jersey, and Oregon make up the majority (greater than 50%) of the tax effect in this category.
57

The reconciliation between the statutory tax rate and the effective rate for 2025 and 2024 is as follows:
20252024
Federal taxes at statutory rate$2,272 21.0 %$2,045 21.0 %
State taxes, net338 3.1 288 3.0 
Foreign taxes, net222 2.1 109 1.1 
Employee stock ownership plan (ESOP)(28)(0.3)(120)(1.2)
Other(85)(0.8)51 0.5 
Total$2,719 25.1 %$2,373 24.4 %
The Company's effective tax rate in 2026, 2025, and 2024 included tax benefits of $72, $100, and $45, related to stock compensation. In 2024, tax benefits also included $94 related to the portion of the special dividend payable through the Company's 401(k) plan and a net non-recurring tax benefit of $63 related to a transfer pricing settlement and certain true-ups of tax reserves.
The following is a supplemental schedule of cash paid for income taxes, net of refunds:
2026
U.S. federal$1,377 
U.S. state and local:
California209 
Other322 
Foreign:
Canada430 
Mexico185 
Other316 
Total$2,839 
58

The components of the deferred tax assets (liabilities) are as follows:
20262025
Deferred tax assets:
Equity compensation$122 $100 
Deferred income/membership fees398 369 
Foreign tax credit carry forward470 390 
Operating lease liabilities710 699 
Accrued liabilities and reserves1,041 917 
Total deferred tax assets2,741 2,475 
Valuation allowance(641)(554)
Total net deferred tax assets2,100 1,921 
Deferred tax liabilities:
Property and equipment(1,372)(944)
Merchandise inventories(344)(305)
Operating lease right-of-use assets(675)(670)
Foreign branch deferreds(107)(103)
Other(33)(31)
Total deferred tax liabilities(2,531)(2,053)
Net deferred tax liabilities$(431)$(132)
The deferred tax accounts at the end of 2026 and 2025 include deferred income tax assets of $635 and $592, included in other long-term assets; and deferred income tax liabilities of $1,066 and $724, included in other long-term liabilities.
In 2026 and 2025, the Company had valuation allowances of $641 and $554, primarily related to foreign tax credits that the Company believes will not be realized due to carry forward limitations. The foreign tax credit carry forwards are set to expire beginning in fiscal 2030.
The Company generally no longer considers fiscal year earnings of non-U.S. consolidated subsidiaries (other than China) indefinitely reinvested after 2023, in the case of Taiwan, and after 2017, in the case of all other subsidiaries, and has recorded the estimated incremental foreign withholding taxes (net of available foreign tax credits) and state income taxes payable assuming a hypothetical repatriation to the U.S. The Company considers undistributed earnings of certain non-U.S. consolidated subsidiaries, which totaled $3,230, to be indefinitely reinvested and has not provided for withholding or state taxes.
A reconciliation of the beginning and ending amount of gross unrecognized tax benefits for 2026 and 2025 is as follows:
20262025
Gross unrecognized tax benefit at beginning of year$65 $81 
Gross increases—current year tax positions18 9 
Gross increases—tax positions in prior years25 14 
Gross decreases—tax positions in prior years(6)(38)
Gross decreases—settlements(8)(1)
Gross unrecognized tax benefit at end of year$94 $65 
At the end of 2026 and 2025, there were $94 and $65 of unrecognized tax benefits that if recognized would affect the annual effective tax rate.
59

Accrued interest and penalties related to income tax matters are classified as a component of income tax expense. Accrued interest and penalties recognized during 2026 and 2025, and accrued at the end of each respective period were immaterial.
The Company files income tax returns in the U.S., various state and local jurisdictions, and in several foreign jurisdictions. With few exceptions, the Company is no longer subject to U.S. federal, state or local examination for years before fiscal 2018.
Other Taxes
The Company is subject to multiple examinations for value added, sales-based, payroll, product, import, or other non-income taxes in various jurisdictions. In certain cases, the Company has received assessments from the authorities. Possible losses or range of possible losses associated with these matters are either immaterial or an estimate of the possible loss or range of loss cannot be made at this time. If certain matters or a group of matters were to be decided adversely to the Company, it could result in a charge that might be material to the results of an individual fiscal quarter or year.
Note 9—Net Income per Common and Common Equivalent Share
The following table shows the amounts used in computing net income per share and the weighted average number of shares of basic and of potentially dilutive common shares outstanding (shares in 000’s):
202620252024
Net income
$9,226 $8,099 $7,367 
Weighted average basic shares
443,953 443,985 443,914 
RSUs474 818 845 
Weighted average diluted shares
444,427 444,803 444,759 
Basic earnings per share is calculated by dividing net income by the weighted average number of shares of common stock outstanding during the period. Diluted earnings per share is calculated based on the dilutive effect of RSUs using the treasury stock method.
Note 10—Commitments and Contingencies
Legal Proceedings
The Company is involved in many claims, proceedings, and litigations arising from its business and property ownership. In accordance with accounting guidance, the Company establishes an accrual for legal proceedings if and when those matters present loss contingencies that are both probable and reasonably estimable. There may be actual losses in excess of amounts accrued. The Company monitors those matters for developments that would affect the likelihood of a loss (considering where applicable indemnification arrangements concerning suppliers and insurers) and the accrued amount, if any, thereof, and adjusts the amount as appropriate. The Company has recorded an immaterial accrual with respect to some matters described below, in addition to other immaterial accruals for matters not described below. If the loss contingency at issue is not both probable and reasonably estimable, the Company does not establish an accrual, but monitors for developments that make the contingency both probable and reasonably estimable. In each case, there is a reasonable possibility that a loss may be incurred, including a loss in excess of the applicable accrual. For matters where no accrual has been recorded, the possible loss or range of loss (including any loss in excess of the accrual) cannot, in the Company's view, be reasonably estimated because, among other things: the remedies or penalties sought are indeterminate or unspecified; the legal and/or factual theories are not well developed; and/or the matters involve complex or novel legal theories or a large number of parties.
In November 2023, a former employee filed a class action against the Company alleging claims under California law for failure to pay minimum wage, failure to pay overtime, failure to provide meal and rest
60

breaks, failure to provide accurate wage statements, failure to reimburse expenses, failure to pay wages when due, and failure to pay sick pay. Martin Reyes v. Costco Wholesale Corp. (No. 23cv011351; Sacramento County Superior Court), removed to federal court (No. 2:24-cv-00300; E.D. Cal.). A second amended complaint was filed, which the Company has moved to dismiss. In January 2024, the same plaintiff filed a related Private Attorneys General Act (PAGA) representative action, seeking civil penalties and asserting the same alleged underlying Labor Code violations and an additional suitable seating claim. In May 2024, the plaintiff filed an amended PAGA complaint; the Company has denied the material allegations of the complaint and filed a motion to stay the action. The motion was granted on December 18, 2024.
In August 2024, an employee filed an action under PAGA against the Company, alleging claims for penalties for various alleged violations of the California Labor Code. Nader v. Costco (No. CV-24-006198; Stanislaus County Superior Court). An amended complaint was filed in November 2024. In February 2025 the court granted the Company’s motion to strike portions of the complaint. The plaintiff filed a further amended complaint; the Company's motion to strike a portion of this complaint was granted on May 13, 2025. The Company's motion to stay the action was granted on November 13, 2025.
In January 2026, a class action on behalf of Washington employees was filed against the Company alleging failure to provide meal periods and rest breaks and to compensate for violations, wage theft, and failure to furnish accurate wage statements. The complaint seeks compensatory and exemplary damages, interest, and attorneys' fees. Madera v. Costco Wholesale Corp. (No. 26-2-02879-6; King County Superior Court). A similar class action was filed in March 2026. Howell v. Costco Wholesale Corp. (No. 26-2-09459-5; King County Superior Court). Howell was subsequently dismissed. The Company has reached an agreement to resolve Madera for an immaterial amount, subject to court approval.
Beginning in December 2017, the United States Judicial Panel on Multidistrict Litigation consolidated numerous cases concerning the impacts of opioid abuses filed against various defendants by counties, cities, hospitals, Native American tribes, third-party payors, and others. In re National Prescription Opiate Litigation (MDL No. 2804) (N.D. Ohio). Cases filed against the Company by counties and cities in Michigan, New Jersey, Oregon, Virginia, and South Carolina, a hospital in Texas, and class actions and individual actions filed on behalf of individuals seeking to recover alleged increased insurance costs associated with opioid abuse in 43 states and American Samoa have been resolved or dismissed. A claim by a third-party payor in Ohio and actions filed on behalf of infants born with opioid-related medical conditions in 40 states remain in the MDL. A claim against the Company filed in federal court outside the MDL by one county in Georgia is pending, and claims filed by certain cities and counties in New York are pending in state court, as are claims by certain county district attorneys in Pennsylvania. Claims against the Company in state courts in New Jersey, Oklahoma, Utah, and Arizona have been dismissed. Claims against the Company in federal court in Georgia and Florida have been dismissed. The Company is defending all of the pending matters remaining.
In June 2025, a former employee filed a class action alleging that the Company restricted workers earning less than twice the minimum wage from having a second job in violation of the Washington law. Gray, et al., v. Costco Wholesale Corp. (No. 25-2-17717-3; King County Superior Court). In October 2025 the court denied the Company’s motion to dismiss. The court certified a class on December 12, 2025. Trial is set for March 1, 2027.
Between September 25 and October 31, 2023, five class action suits were filed against the Company alleging privacy law violations stemming from pixel trackers on Costco.com: Birdwell v. Costco Wholesale Corp., No. C23-02416, Contra Costa County Superior Court; and Scott v. Costco Wholesale Corp., No. 2:23-cv-08808 (C.D. Cal.), now consolidated with R.S. v. Costco Wholesale Corp., No. 2:23-cv-01628 (W.D. Wash.); Groves, et ano., v. Costco Wholesale Corp., No. 2:23-cv-01662 (W.D. Wash.), and Castillo v. Costco Wholesale Corp., under No. 2:34-cv-01548 (W.D. Wash.). The Castillo plaintiffs filed a consolidated complaint on January 26, 2024, which seeks damages, equitable relief, and attorneys’ fees under various statutes, including the Washington Consumer Protection Act, Washington Privacy Act, Washington Uniform Health Care Information Act, Electronic Communications Privacy Act, California
61

Invasion of Privacy Act, and California Confidentiality of Medical Information Act. The consolidated complaint also alleges breach of implied contract, invasion of privacy, conversion, and unjust enrichment. The Company filed a motion to dismiss the Castillo complaint on March 11, 2024. In November 2024 the court denied the motion to dismiss in substantial part. On May 16, 2024, the parties stipulated to stay Birdwell pending resolution of Castillo. On January 2, and August 22, 2024, the Company received related civil investigative demands from the Washington Attorney General's Office. On January 3, 2024, the Company received a related pre-litigation letter from the Los Angeles Office of the County Counsel. The Company is in the process of responding to both agencies. The Birdwell case was dismissed with prejudice in March 2026.
In October and November 2025, two class actions were filed against the Company alleging violations of consumer protection and other laws arising from the Company's sale of Kirkland Signature tequila products in the United States: Glazer v. Costco Wholesale Corp., Case No. 1:25-cv-25057 (S.D. Fla.); and Salisbury, et al. v. Costco Wholesale Corp., Case No. 2:25-cv-02277 (W.D. Wash.). Plaintiffs allege that the Company's Kirkland Signature tequilas are labeled “100% de Agave” but contain alcohol derived from non-agave sugars. They seek damages, statutory penalties, punitive and treble damages, and disgorgement. The Glazer action was subsequently dismissed without prejudice. An amended complaint was filed in the Salisbury case on March 9, 2026, adding Glazer as an additional named plaintiff. The Company filed a motion to dismiss Salisbury in April 2026.
In March 2026, four class actions were filed against the Company seeking a refund of tariffs paid by the Company under IEEPA that were passed on to members through higher prices. The complaints allege violations of state consumer protection laws and equitable doctrines: Stockov, et al., v. Costco Wholesale Corp. (Case No. 26-cv-02734; N.D. Ill.); Gower, et al., v. Costco Wholesale Corp. (Case No. 26-2-08898-5SEA; King County Superior Court); Ortiz, et al., v. Costco Wholesale Corp. (Case No. 3:26-cv-01164-CVR; D.P.R.); and Briggs, et al., v. Costco Wholesale Corp. (Case No. 2:26-cv-01064; W.D. Wash.). The Company has filed motions to dismiss in Stockov and Gower. The Gower court denied the motion to dismiss on July 17, 2026. A motion seeking discretionary appellate review of that decision is pending.
In June of 2025, a class action was filed related to promotional emails. Zydel v. Costco Wholesale Corp. (Case No. 25-1-16392-0; King County Superior Court). The complaint alleges the emails include “misleading subject lines that encourage recipients to open e-mails on misleading pretenses” and that the subject lines advertised promotional sales with specific time limitations that were misleading, in violation of the Washington Commercial Electronic Mail Act. The Company filed a motion to dismiss the case in August 2025, which was granted in part and denied in part in October 2025. The Company subsequently agreed to a class-wide settlement for an immaterial amount, which is currently in the process of administration. In July 2026, a class action complaint was filed by plaintiff Tracy Jay, alleging deceptive email marketing practices. Jay v. Costco Wholesale Corp. (Case No. 26-2-22333-5SEA; King County Superior Court). Specifically, that Costco sent commercial emails to consumers utilizing false or misleading “limited-time” subject lines, in violation of the Washington Commercial Electronic Mail Act, as well as Indiana’s Deceptive Commercial Electronic Mail Act and Maryland’s Commercial Electronic Mail Act.
The Company does not believe that any pending claim, proceeding, or litigation, either alone or in the aggregate, will have a material adverse effect on the Company’s financial position, results of operations, or cash flows; it is possible that an unfavorable outcome of some or all of the matters, however unlikely, could result in a charge that might be material to the results of an individual fiscal quarter or year.
62

Note 11—Segment Reporting
The Company is principally engaged in the operation of membership warehouses through wholly owned subsidiaries in the U.S., Canada, Mexico, Japan, the U.K., Korea, Australia, Taiwan, China, Spain, France, Sweden, Iceland, and New Zealand. Reportable segments are largely based on management’s organization of the operating segments for operational decisions and assessments of financial performance, which considers geographic locations. The material accounting policies of the segments are as described in Note 1. Inter-segment net sales and expenses, including royalties, have been eliminated in computing total revenue and operating income.
The chief operating decision maker (CODM) is the Company's Chief Executive Officer, President, and Director. The CODM uses the metrics outlined in the table below, along with internal management reports, to evaluate performance, monitor actual results versus budget and prior year results, and make strategic and operational resource allocation decisions.
The following table provides the revenue, significant expenses, and operating income for the Company's reportable segments:
202620252024
United States
Total revenue$219,823 $200,046 $184,143 
Merchandise costs191,440 174,021 160,573 
Selling, general and administrative expenses20,736 19,147 17,353 
Operating income$7,647 $6,878 $6,217 
Canada
Total revenue$40,561 $36,923 $34,874 
Merchandise costs35,287 32,204 30,543 
Selling, general and administrative expenses3,167 2,870 2,683 
Operating income$2,107 $1,849 $1,648 
Other International
Total revenue$42,770 $38,266 $35,436 
Merchandise costs37,552 33,661 31,242 
Selling, general and administrative expenses3,287 2,949 2,774 
Operating income$1,931 $1,656 $1,420 
Total
Total revenue$303,154 $275,235 $254,453 
Merchandise costs264,279 239,886 222,358 
Selling, general and administrative expenses27,190 24,966 22,810 
Operating income11,685 10,383 9,285 
Other income(1)
566 435 455 
Income before income taxes$12,251 $10,818 $9,740 
 ____________
(1)Other income consists of interest expense and interest income and other, net.
63

The following table provides depreciation and amortization and other asset related information for the Company's reportable segments:
202620252024
United States
Depreciation and amortization$2,082 $1,895 $1,730 
Additions to property and equipment5,122 4,215 3,725 
Property and equipment, net25,714 22,790 20,638 
Total assets65,090 54,862 48,816 
Canada
Depreciation and amortization$219 $196 $192 
Additions to property and equipment673 580 351 
Property and equipment, net3,395 2,930 2,602 
Total assets8,026 7,304 6,915 
Other International
Depreciation and amortization$373 $335 $315 
Additions to property and equipment640 703 634 
Property and equipment, net6,524 6,189 5,792 
Total assets15,929 14,933 14,100 
Total
Depreciation and amortization$2,674 $2,426 $2,237 
Additions to property and equipment6,435 5,498 4,710 
Property and equipment, net35,633 31,909 29,032 
Total assets89,045 77,099 69,831 
Disaggregated Revenue
The following table summarizes net sales by merchandise category; sales from e-commerce sites and business centers have been allocated to the applicable merchandise categories:
202620252024
Foods and Sundries
$116,788 $109,564 $101,463 
Non-Foods
77,375 71,190 63,973 
Fresh Foods
41,715 37,988 34,220 
Warehouse Ancillary and Other Businesses
61,369 51,170 49,969 
Total net sales
$297,247 $269,912 $249,625 

64

Item 9—Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
None.
Item 9A—Controls and Procedures
Evaluation of Disclosure Controls and Procedures
Our disclosure controls and procedures (as defined in Rules 13a-15(e) or 15d-15(e) under the Securities Exchange Act of 1934, as amended) are designed to ensure that information required to be disclosed in the reports that we file or submit under the Exchange Act is recorded, processed, summarized, and reported within the time periods specified in the rules and forms of the SEC and to ensure that information required to be disclosed is accumulated and communicated to management, including our principal executive and financial officers, to allow timely decisions regarding disclosure. The Chief Executive Officer and the Chief Financial Officer, with assistance from other members of management, have reviewed the effectiveness of our disclosure controls and procedures as of August 30, 2026, and, based on their evaluation, have concluded that the disclosure controls and procedures were effective as of such date.
Management's Annual Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting as defined in Rule 13a-15(f) under the Exchange Act. Our internal control over financial reporting is designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with U.S. GAAP and includes those policies and procedures that: (1) pertain to the maintenance of records that in reasonable detail accurately and fairly reflect our transactions and the dispositions of our assets; (2) provide reasonable assurance that our transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles and that our receipts and expenditures are being made only in accordance with appropriate authorizations; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of our assets that could have a material effect on our financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Projections of any evaluation of effectiveness for future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Under the supervision of and with the participation of our management, we assessed the effectiveness of our internal control over financial reporting as of August 30, 2026, using the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission in Internal Control—Integrated Framework (2013).
Based on its assessment, management has concluded that our internal control over financial reporting was effective as of August 30, 2026. The attestation of KPMG LLP, our independent registered public accounting firm, on the effectiveness of our internal control over financial reporting is included with the consolidated financial statements in Item 8 of this Report.
Changes in Internal Control Over Financial Reporting
There have been no changes in our internal control over financial reporting (as defined in Rules 13a-15(f) or 15d-15(f) of the Exchange Act) that occurred during the fourth quarter of 2026 that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.

65

Item 9B—Other Information
During the fiscal quarter ended August 30, 2026, no director or officer of the Company adopted or terminated a Rule 10b5-1 trading arrangement or a non-Rule 10b5-1 trading arrangement, as each term is defined in Item 408(a) of Regulation S-K.
Item 9C—Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
Not Applicable.
PART III
Item 10—Directors, Executive Officers, and Corporate Governance
Information relating to the availability of our code of ethics for senior financial officers and a list of our executive officers appear in Part I, Item 1 of this Report. The information required by this Item concerning our directors and nominees for director is incorporated herein by reference to the sections entitled “Proposal 1: Election of Directors,” “Directors,” “Director Biographies,” and “Committees of the Board” in Costco’s Proxy Statement for its 2027 annual meeting of shareholders, which will be filed with the SEC within 120 days of the end of our fiscal year (“Proxy Statement”). We have adopted an Insider Trading Policy governing the purchase, sale, and other dispositions of our securities by directors, officers, and employees that is reasonably designed to promote compliance with insider trading laws, rules, and regulations and any applicable listing standards. A copy of our policy is incorporated herein by reference to Exhibit 19.1 to our Annual Report on Form 10-K for the fiscal year ended September 1, 2024.
Item 11—Executive Compensation
The information required by this Item is incorporated herein by reference to the sections entitled “Compensation of Directors” and “Executive Compensation” in Costco’s Proxy Statement.
Item 12—Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
The information required by this Item is incorporated herein by reference to the section entitled “Principal Shareholders” and “Equity Compensation Plan Information” in Costco’s Proxy Statement.
Item 13—Certain Relationships and Related Transactions, and Director Independence
The information required by this Item is incorporated herein by reference to the sections entitled “Certain Relationships and Transactions” and "Committees of the Board" in Costco’s Proxy Statement.
Item 14—Principal Accounting Fees and Services
Our independent registered public accounting firm is KPMG LLP, Seattle, WA, Auditor Firm ID: 185.
The information required by this Item is incorporated herein by reference to the sections entitled “Independent Public Accountants” in Costco’s Proxy Statement.
66

PART IV
Item 15—Exhibits, Financial Statement Schedules
(a)Documents filed as part of this report are as follows:
1.Financial Statements:
See the listing of Financial Statements included as a part of this Form 10-K in Item 8 of Part II.
2.Financial Statement Schedules:
All schedules have been omitted because the required information is not present or is not present in amounts sufficient to require submission of the schedule, or because the information required is included in the consolidated financial statements, including the notes thereto.
(b)Exhibits: The required exhibits are filed or furnished as part of this Annual Report on Form 10-K or are incorporated herein by reference.
Incorporated by Reference
Exhibit
Number
Exhibit DescriptionFiled
Herewith
FormPeriod EndedFiling Date
3.110-K8/28/202210/5/2022
3.28-K9/20/2024
4.1
First Supplemental Indenture between Costco Wholesale Corporation and U.S. Bank National Association, as Trustee, dated as of March 20, 2002 (incorporated by reference to Exhibits 4.1 and 4.2 to the Company's Current Report on the Form 8-K filed on March 25, 2002)
8-K3/25/2002
4.28-K4/17/2020
4.38-K4/17/2020
4.48-K4/17/2020
4.58-K5/16/2017
4.68-K5/16/2017
4.710-K8/28/202210/5/2022
10.1*10-K9/2/201210/19/2012
10.2*DEF 1412/17/2019
10.3*DEF 14A12/19/2014
67

Incorporated by Reference
Exhibit
Number
Exhibit DescriptionFiled
Herewith
FormPeriod EndedFiling Date
10.3.1*10-Q11/24/201912/23/2019
10.3.2*10-Q11/24/201912/23/2019
10.3.3*10-Q11/24/201912/23/2019
10.3.4*10-Q11/24/201912/23/2019
10.3.5*10-Q11/23/202512/17/2025
10.3.6*10-Q11/23/202512/17/2025
10.4*8-K10/20/2025
10.5*10-Q11/26/202312/20/2023
10.5.1*10-Q11/24/202412/19/2024
10.5.2*10-Q11/23/202512/17/2025
10.614A12/13/1999
10.7*10-K9/1/201310/16/2013
10.8#
10-Q2/16/20253/13/2025
19.110-K9/1/202410/9/2024
21.1x
23.1x
68

Incorporated by Reference
Exhibit
Number
Exhibit DescriptionFiled
Herewith
FormPeriod EndedFiling Date
31.1x
32.1**
97.110-K9/1/202410/9/2024
101.INSInline XBRL Instance Documentx
101.SCHInline XBRL Taxonomy Extension Schema Documentx
101.CALInline XBRL Taxonomy Extension Calculation Linkbase Documentx
101.DEFInline XBRL Taxonomy Extension Definition Linkbase Documentx
101.LABInline XBRL Taxonomy Extension Label Linkbase Documentx
101.PREInline XBRL Taxonomy Extension Presentation Linkbase Documentx
104Cover Page Interactive Data File (formatted as inline XBRL and contained in Exhibit 101)x
 _____________________
* Management contract, compensatory plan or arrangement.
** Furnished herewith
# Certain information in this exhibit has been omitted because it is (i) immaterial and (ii) customarily and actually treated by the registrant as private or confidential.
(c)Financial Statement Schedules—None.
Item 16—Form 10-K Summary
None.
69

SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
October 6, 2026
COSTCO WHOLESALE CORPORATION
(Registrant)
By
/s/ GARY MILLERCHIP
Gary Millerchip
Executive Vice President and Chief Financial Officer
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
October 6, 2026
By
/s/ RON M. VACHRIS
By
/s/ HAMILTON E. JAMES
Ron M. Vachris
Chief Executive Officer, President, and Director
Hamilton E. James
Chairman of the Board
By
/s/ GARY MILLERCHIP
By
/s/ TIFFANY M. BARBRE
Gary Millerchip
Executive Vice President and Chief Financial Officer
(Principal Financial Officer)
Tiffany M. Barbre
Senior Vice President and Corporate Controller
(Principal Accounting Officer)
By
/s/ SUSAN L. DECKER
By
/s/ KENNETH D. DENMAN
Susan L. Decker
Director
Kenneth D. Denman
Director
By
/s/ HELENA B. FOULKES
By
/s/ SALLY JEWELL
Helena B. Foulkes
Director
Sally Jewell
Director
By
/s/ JEFFREY S. RAIKES
By
/s/ GINA M. RAIMONDO
Jeffrey S. Raikes
Director
Gina M. Raimondo
Director
By
/s/ JOHN W. STANTON
By
/s/ MARY (MAGGIE) A. WILDEROTTER
John W. Stanton
Director
Mary (Maggie) A. Wilderotter
Director
70
EX-21.1 2 costex21110k83026.htm EX-21.1 Document

Exhibit 21.1
SUBSIDIARIES OF THE COMPANY

The following is a list of subsidiaries of the Company as of August 30, 2026, omitting subsidiaries which, considered in the aggregate, would not constitute a significant subsidiary.
Subsidiaries
State or Other Jurisdiction of Incorporation or Organization
Name under Which Subsidiary Does Business
Costco Wholesale Membership, Inc.
California
Costco Wholesale Membership, Inc.
Costco Wholesale Canada Ltd.
Canadian Federal
Costco Wholesale Canada, Ltd.
NW Re Limited
Arizona
NW Re Limited
Costco Insurance Agency, Inc.
Washington
Costco Insurance Agency, Inc.
Price Costco International, Inc.
Nevada
Price Costco International, Inc.
Costco Wholesale Korea, Ltd.
Korea
Costco Wholesale Korea, Ltd.
Costco Wholesale Japan, Ltd.
Japan
Costco Wholesale Japan, Ltd.
Costco de Mexico, S.A. de C.V.
Mexico
Costco de Mexico, S.A. de C.V.
Costco Wholesale UK Limited
United Kingdom
Costco Wholesale UK Limited
Costco Wholesale Taiwan, Inc.
Taiwan
Costco Wholesale Taiwan, Inc.
Costco Wholesale Australia, Pty. Ltd.AustraliaCostco Wholesale Australia, Pty. Ltd.

EX-23.1 3 costex23110k83026.htm EX-23.1 Document

Exhibit 23.1
Consent of Independent Registered Public Accounting Firm

We consent to the incorporation by reference in the registration statements (Nos. 333-82782, 333-120523, 333-129172, 333-135052, 333-150014, 333-151748, 333-165550, 333-180163, 333-187418, 333-202673, 333-204739, 333-218397, 333-230253, 333-251396, and 333-276624) on Form S-8 and the registration statement (No. 333-296468) on Form S-3 of our reports dated October 6, 2026, with respect to the consolidated financial statements of Costco Wholesale Corporation and the effectiveness of internal control over financial reporting.

/s/ KPMG LLP
Seattle, Washington
October 6, 2026


EX-31.1 4 costex31110k83026.htm EX-31.1 Document

Exhibit 31.1
CERTIFICATIONS
I, Ron M. Vachris, certify that:
1)I have reviewed this Annual Report on Form 10-K of Costco Wholesale Corporation (“the registrant”);
2)Based on my knowledge, this report does not contain any untrue statement of a material fact or omit to state a material fact necessary to make the statements made, in light of the circumstances under which such statements were made, not misleading with respect to the period covered by this report;
3)Based on my knowledge, the financial statements, and other financial information included in this report, fairly present in all material respects the financial condition, results of operations and cash flows of the registrant as of, and for, the periods presented in this report;
4)The registrant’s other certifying officer(s) and I are responsible for establishing and maintaining disclosure controls and procedures (as defined in Exchange Act Rules 13a-15(e) and 15d-15(e)) and internal control over financial reporting (as defined in Exchange Act Rules 13a-15(f) and 15d-15(f)) for the registrant and have:
a.Designed such disclosure controls and procedures, or caused such disclosure controls and procedures to be designed under our supervision, to ensure that material information relating to the registrant, including its consolidated subsidiaries, is made known to us by others within those entities, particularly during the period in which this report is being prepared;
b.Designed such internal control over financial reporting, or caused such internal control over financial reporting to be designed under our supervision, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles;
c.Evaluated the effectiveness of the registrant’s disclosure controls and procedures and presented in this report our conclusions about the effectiveness of the disclosure controls and procedures, as of the end of the period covered by this report based on such evaluation; and
d.Disclosed in this report any change in the registrant’s internal control over financial reporting that occurred during the registrant’s most recent fiscal quarter (the registrant’s fourth fiscal quarter in the case of an annual report) that has materially affected, or is reasonably likely to materially affect, the registrant’s internal control over financial reporting; and
5)The registrant’s other certifying officer(s) and I have disclosed, based on our most recent evaluation of internal control over financial reporting, to the registrant’s auditors and the audit committee of the registrant’s board of directors (or persons performing the equivalent functions):
a.All significant deficiencies and material weaknesses in the design or operation of internal control over financial reporting which are reasonably likely to adversely affect the registrant’s ability to record, process, summarize and report financial information; and
b.Any fraud, whether or not material, that involves management or other employees who have a significant role in the registrant’s internal control over financial reporting.

October 6, 2026
 
/s/ RON M. VACHRIS
Ron M. Vachris
President and Chief Executive Officer


CERTIFICATIONS
I, Gary Millerchip, certify that:
1)I have reviewed this Annual Report on Form 10-K of Costco Wholesale Corporation (“the registrant”);
2)Based on my knowledge, this report does not contain any untrue statement of a material fact or omit to state a material fact necessary to make the statements made, in light of the circumstances under which such statements were made, not misleading with respect to the period covered by this report;
3)Based on my knowledge, the financial statements, and other financial information included in this report, fairly present in all material respects the financial condition, results of operations and cash flows of the registrant as of, and for, the periods presented in this report;
4)The registrant’s other certifying officer(s) and I are responsible for establishing and maintaining disclosure controls and procedures (as defined in Exchange Act Rules 13a-15(e) and 15d-15(e)) and internal control over financial reporting (as defined in Exchange Act Rules 13a-15(f) and 15d-15(f)) for the registrant and have:
a.Designed such disclosure controls and procedures, or caused such disclosure controls and procedures to be designed under our supervision, to ensure that material information relating to the registrant, including its consolidated subsidiaries, is made known to us by others within those entities, particularly during the period in which this report is being prepared;
b.Designed such internal control over financial reporting, or caused such internal control over financial reporting to be designed under our supervision, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles;
c.Evaluated the effectiveness of the registrant’s disclosure controls and procedures and presented in this report our conclusions about the effectiveness of the disclosure controls and procedures, as of the end of the period covered by this report based on such evaluation; and
d.Disclosed in this report any change in the registrant’s internal control over financial reporting that occurred during the registrant’s most recent fiscal quarter (the registrant’s fourth fiscal quarter in the case of an annual report) that has materially affected, or is reasonably likely to materially affect, the registrant’s internal control over financial reporting; and
5)The registrant’s other certifying officer(s) and I have disclosed, based on our most recent evaluation of internal control over financial reporting, to the registrant’s auditors and the audit committee of the registrant’s board of directors (or persons performing the equivalent functions):
a.All significant deficiencies and material weaknesses in the design or operation of internal control over financial reporting which are reasonably likely to adversely affect the registrant’s ability to record, process, summarize and report financial information; and
b.Any fraud, whether or not material, that involves management or other employees who have a significant role in the registrant’s internal control over financial reporting.

October 6, 2026
 
/s/ GARY MILLERCHIP
Gary Millerchip
Executive Vice President and Chief Financial Officer


EX-32.1 5 costex32110k83026.htm EX-32.1 Document

Exhibit 32.1
CERTIFICATION PURSUANT TO
18 U.S.C. SECTION 1350, AS ADOPTED PURSUANT TO
SECTION 906 OF THE SARBANES-OXLEY ACT OF 2002
In connection with the Annual Report of Costco Wholesale Corporation (the Company) on Form 10-K for the year ended August 30, 2026, as filed with the Securities and Exchange Commission (the Report), I, Ron M. Vachris, President and Chief Executive Officer of the Company, certify, pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002, that:
(1)The Report fully complies with the requirements of Section 13(a) or 15(d) of the Securities Exchange Act of 1934; and
(2)The information contained in the Report fairly presents, in all material respects, the financial condition and results of operations of the Company.
/s/ RON M. VACHRIS
Date: October 6, 2026
Ron M. Vachris
President and Chief Executive Officer
A signed original of this written statement has been provided to and will be retained by Costco Wholesale Corporation and furnished to the Securities and Exchange Commission or its staff upon request.


CERTIFICATION PURSUANT TO
18 U.S.C. SECTION 1350, AS ADOPTED PURSUANT TO
SECTION 906 OF THE SARBANES-OXLEY ACT OF 2002
In connection with the Annual Report of Costco Wholesale Corporation (the Company) on Form 10-K for the year ended August 30, 2026, as filed with the Securities and Exchange Commission (the Report), I, Gary Millerchip, Executive Vice President and Chief Financial Officer of the Company, certify, pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002, that:
(1)The Report fully complies with the requirements of Section 13(a) or 15(d) of the Securities Exchange Act of 1934; and
(2)The information contained in the Report fairly presents, in all material respects, the financial condition and results of operations of the Company.
/s/ GARY MILLERCHIP
Date: October 6, 2026
Gary Millerchip
Executive Vice President and Chief Financial Officer
A signed original of this written statement has been provided to and will be retained by Costco Wholesale Corporation and furnished to the Securities and Exchange Commission or its staff upon request.

EX-101.SCH 6 cost-20260830.xsd XBRL TAXONOMY EXTENSION SCHEMA DOCUMENT 0000001 - Document - Cover link:presentationLink link:calculationLink link:definitionLink 0000002 - Document - Audit Information link:presentationLink link:calculationLink link:definitionLink 9952151 - Statement - Consolidated Statements Of Income link:presentationLink link:calculationLink link:definitionLink 9952152 - Statement - Consolidated Statements Of Comprehensive Income link:presentationLink link:calculationLink link:definitionLink 9952153 - Statement - Consolidated Balance Sheets link:presentationLink link:calculationLink link:definitionLink 9952154 - Statement - Consolidated Balance Sheets (Parenthetical) link:presentationLink link:calculationLink link:definitionLink 9952155 - Statement - Consolidated Statements of Equity link:presentationLink link:calculationLink link:definitionLink 9952156 - Statement - Consolidated Statements Of Cash Flows link:presentationLink link:calculationLink link:definitionLink 9952157 - Disclosure - Summary of Significant Accounting Policies link:presentationLink link:calculationLink link:definitionLink 9952158 - Disclosure - Investments link:presentationLink link:calculationLink link:definitionLink 9952159 - Disclosure - Fair Value Measurement link:presentationLink link:calculationLink link:definitionLink 9952160 - Disclosure - Debt link:presentationLink link:calculationLink link:definitionLink 9952161 - Disclosure - Leases link:presentationLink link:calculationLink link:definitionLink 9952162 - Disclosure - Stockholders' Equity link:presentationLink link:calculationLink link:definitionLink 9952163 - Disclosure - Stock-Based Compensation Plans link:presentationLink link:calculationLink link:definitionLink 9952164 - Disclosure - Income Taxes link:presentationLink link:calculationLink link:definitionLink 9952165 - Disclosure - Net Income per Common and Common Equivalent Share link:presentationLink link:calculationLink link:definitionLink 9952166 - Disclosure - Commitment and Contingencies link:presentationLink link:calculationLink link:definitionLink 9952167 - Disclosure - Segment Reporting link:presentationLink link:calculationLink link:definitionLink 9955511 - Disclosure - Summary of Significant Accounting Policies (Policies) link:presentationLink link:calculationLink link:definitionLink 9955512 - Disclosure - Summary of Significant Accounting Policies (Tables) link:presentationLink link:calculationLink link:definitionLink 9955513 - Disclosure - Investments (Tables) link:presentationLink link:calculationLink link:definitionLink 9955514 - Disclosure - Fair Value Measurement (Tables) link:presentationLink link:calculationLink link:definitionLink 9955515 - Disclosure - Debt (Tables) link:presentationLink link:calculationLink link:definitionLink 9955516 - Disclosure - Leases (Tables) link:presentationLink link:calculationLink link:definitionLink 9955517 - Disclosure - Stockholders' Equity (Tables) link:presentationLink link:calculationLink link:definitionLink 9955518 - Disclosure - Stock-Based Compensation Plans (Tables) link:presentationLink link:calculationLink link:definitionLink 9955519 - Disclosure - Income Taxes (Tables) link:presentationLink link:calculationLink link:definitionLink 9955520 - Disclosure - Net Income per Common and Common Equivalent Share Net Income per Common and Common Equivalent Share (Tables) link:presentationLink link:calculationLink link:definitionLink 9955521 - Disclosure - Commitment and Contingencies (Tables) link:presentationLink link:calculationLink link:definitionLink 9955522 - Disclosure - Segment Reporting (Tables) link:presentationLink link:calculationLink link:definitionLink 9955523 - Disclosure - Accounting Policies - Additional Information (Details) link:presentationLink link:calculationLink link:definitionLink 9955524 - Disclosure - Accounting Policies - Basis of Presentation (Details) link:presentationLink link:calculationLink link:definitionLink 9955525 - Disclosure - Accounting Policies - Cash and Cash Equivalents (Details) link:presentationLink link:calculationLink link:definitionLink 9955526 - Disclosure - Accounting Policies - Merchandise Inventories (Details) link:presentationLink link:calculationLink link:definitionLink 9955527 - Disclosure - Accounting Policies - Property and Equipment, Net (Details) link:presentationLink link:calculationLink link:definitionLink 9955528 - Disclosure - Accounting Policies - Leases (Details) link:presentationLink link:calculationLink link:definitionLink 9955529 - Disclosure - Accounting Policies - Goodwill and Acquired Intangible Assets (Details) link:presentationLink link:calculationLink link:definitionLink 9955530 - Disclosure - Accounting Policies - Insurance/Self-Insurance Liabilities (Details) link:presentationLink link:calculationLink link:definitionLink 9955531 - Disclosure - Accounting Policies - Derivatives (Details) link:presentationLink link:calculationLink link:definitionLink 9955532 - Disclosure - Accounting Policies - Foreign Currency (Details) link:presentationLink link:calculationLink link:definitionLink 9955533 - Disclosure - Accounting Policies - Revenue Recognition (Details) link:presentationLink link:calculationLink link:definitionLink 9955534 - Disclosure - Accounting Policies - Retirement Plans (Details) link:presentationLink link:calculationLink link:definitionLink 9955535 - Disclosure - Accounting Policies - Stock-Based Compensation (Details) link:presentationLink link:calculationLink link:definitionLink 9955536 - Disclosure - Investments - Available for Sale and Held to Maturity Investments (Details) link:presentationLink link:calculationLink link:definitionLink 9955537 - Disclosure - Investments - Maturities of Available for Sale and Held to Maturity Securities (Details) link:presentationLink link:calculationLink link:definitionLink 9955538 - Disclosure - Fair Value Measurement - Fair Value of Financial Assets and Financial Liabilities Measured on Recurring Basis (Details) link:presentationLink link:calculationLink link:definitionLink 9955539 - Disclosure - Debt, Schedule Of Short-Term Debt (Details) link:presentationLink link:calculationLink link:definitionLink 9955540 - Disclosure - Debt, Schedule of Long-Term Debt (Details) link:presentationLink link:calculationLink link:definitionLink 9955541 - Disclosure - Debt, Carrying Value of Long-Term Debt (Details) link:presentationLink link:calculationLink link:definitionLink 9955542 - Disclosure - Debt, Schedule Of Long-Term Debt Maturities (Details) link:presentationLink link:calculationLink link:definitionLink 9955543 - Disclosure - Leases, Supplemental Balance Sheet Information (Details) link:presentationLink link:calculationLink link:definitionLink 9955544 - Disclosure - Leases, Components of Lease Expense (Details) link:presentationLink link:calculationLink link:definitionLink 9955545 - Disclosure - Leases, Supplemental Cash Flow Information (Details) link:presentationLink link:calculationLink link:definitionLink 9955546 - Disclosure - Leases, Future Minimum Payments (Details) link:presentationLink link:calculationLink link:definitionLink 9955547 - Disclosure - Stockholders' Equity - Additional Information (Details) link:presentationLink link:calculationLink link:definitionLink 9955548 - Disclosure - Equity - Additional Information - Stock Repurchase Programs (Details) link:presentationLink link:calculationLink link:definitionLink 9955549 - Disclosure - Stockholders' Equity (Stock Repurchased During Period) (Details) link:presentationLink link:calculationLink link:definitionLink 9955550 - Disclosure - Stock-Based Compensation Plans - Additional Information (Details) link:presentationLink link:calculationLink link:definitionLink 9955551 - Disclosure - Stock-Based Compensation Plans - Summary of RSU Transactions (Details) link:presentationLink link:calculationLink link:definitionLink 9955552 - Disclosure - Stock-Based Compensation Plans - Summary of Stock-Based Compensation Expense (Details) link:presentationLink link:calculationLink link:definitionLink 9955553 - Disclosure - Income Taxes (Income Before Income Taxes) (Details) link:presentationLink link:calculationLink link:definitionLink 9955554 - Disclosure - Income Taxes (Schedule of Foreign And Domestic Income Taxes) (Details) link:presentationLink link:calculationLink link:definitionLink 9955555 - Disclosure - Income Taxes (Reconciliation Between Statutory And Effective Rates) (Details) link:presentationLink link:calculationLink link:definitionLink 9955556 - Disclosure - Income Taxes (Reconciliation Between Statutory and Effective Rates FY25 and FY24) (Details) link:presentationLink link:calculationLink link:definitionLink 9955557 - Disclosure - Income Taxes (Reconciliation Between Statutory and Effective Rates Narrative) (Details) link:presentationLink link:calculationLink link:definitionLink 9955558 - Disclosure - Income Taxes Cash Paid for Income Taxes (Details) link:presentationLink link:calculationLink link:definitionLink 9955559 - Disclosure - Income Taxes (Components of Deferred Tax Assets And Liabilities) (Details) link:presentationLink link:calculationLink link:definitionLink 9955560 - Disclosure - Income Taxes (Deferred Tax Assets and Liabilities Narrative) (Details) link:presentationLink link:calculationLink link:definitionLink 9955560 - Disclosure - Income Taxes (Deferred Tax Assets and Liabilities Narrative) (Details) link:presentationLink link:calculationLink link:definitionLink 9955561 - Disclosure - Income Taxes (Gross Unrecognized Tax Benefits) (Details) link:presentationLink link:calculationLink link:definitionLink 9955562 - Disclosure - Net Income per Common and Common Equivalent Share - Schedule of Earnings per Share Effect on Net Income and Weighted Averegae Number of Dilutive Potential Common Stock (Details) link:presentationLink link:calculationLink link:definitionLink 9955563 - Disclosure - Commitment and Contingencies (Details) link:presentationLink link:calculationLink link:definitionLink 9955564 - Disclosure - Segment Reporting - Narrative (Details) link:presentationLink link:calculationLink link:definitionLink 9955565 - Disclosure - Segment Reporting Information by Segment (Details) link:presentationLink link:calculationLink link:definitionLink 9955566 - Disclosure - Segment Reporting Information by Segment (Details) link:presentationLink link:calculationLink link:definitionLink 9955567 - Disclosure - Segment Reporting Information by Item Category (Details) link:presentationLink link:calculationLink link:definitionLink EX-101.CAL 7 cost-20260830_cal.xml XBRL TAXONOMY EXTENSION CALCULATION LINKBASE DOCUMENT EX-101.DEF 8 cost-20260830_def.xml XBRL TAXONOMY EXTENSION DEFINITION LINKBASE DOCUMENT EX-101.LAB 9 cost-20260830_lab.xml XBRL TAXONOMY EXTENSION LABEL LINKBASE DOCUMENT Trading Arrangements, by Individual Trading Arrangements, by Individual [Table] Shares used in calculation (000's) Weighted Average Number of Shares Outstanding, Diluted [Abstract] Trading Arrangement: Trading Arrangement [Axis] Maximum [Member] Maximum [Member] Statistical Measurement [Domain] Statistical Measurement [Domain] Title of 12(b) Security Title of 12(b) Security Document Fiscal Year Focus Document Fiscal Year Focus Stock-based compensation expense, net Share-Based Payment Arrangement, Expense, after Tax Adjustment to Compensation, Amount Adjustment to Compensation Amount Major Types of Debt and Equity Securities Financial Instrument [Axis] Number of units Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Nonvested, Number of Shares [Roll Forward] Schedule Of Gross Unrecognized Tax Benefits Table Schedule of Unrecognized Tax Benefits Roll Forward [Table Text Block] Segment Reporting [Abstract] Segment Reporting [Abstract] Common Stock $.005 par value; 900,000,000 shares authorized; 443,266,000 and 442,237,000 shares issued and outstanding Common Stock, Value, Issued 2027 Lessee, Operating Lease, Liability, to be Paid, Year One Tax withholdings on stock-based awards Payment, Tax Withholding, Share-Based Payment Arrangement Interest expense Interest Expense, Operating and Nonoperating Revenue from External Customers by Products and Services [Table] Segment Reporting, Entity-Wide Information Not Provided as Part of Reportable Segment, Product and Service, Revenue [Table] Accrued salaries and benefits Employee-related Liabilities, Current Gross decreases—settlements Unrecognized Tax Benefits, Decrease Resulting from Settlements with Taxing Authorities State taxes, net Effective Income Tax Rate Reconciliation, State and Local Income Taxes, Percent Restatement Determination Date Restatement Determination Date Tax Jurisdiction of Domicile [Extensible Enumeration] Tax Jurisdiction of Domicile [Extensible Enumeration] Changes in valuation allowance Effective Income Tax Rate Reconciliation, Change in Deferred Tax Assets Valuation Allowance, Amount Food and Sundries [Member] Food and Sundries [Member] Food and Sundries [Member] 2027 Finance Lease, Liability, to be Paid, Year One Derivative, by Nature Derivative Instrument [Axis] Schedule of Effective Income Tax Rate Reconciliation Schedule of Effective Income Tax Rate Reconciliation [Table Text Block] Measurement Frequency [Axis] Measurement Frequency [Axis] Amendment Flag Amendment Flag Goodwill [Line Items] Goodwill [Line Items] CURRENT LIABILITIES Liabilities, Current [Abstract] Average price per share Shares Acquired, Average Cost Per Share Entity Common Stock, Shares Outstanding Entity Common Stock, Shares Outstanding Financing cash flows - finance leases Finance Lease, Principal Payments Stock compensation tax benefits Effective Income Tax Rate Reconciliation, Tax Expense (Benefit), Share-Based Payment Arrangement, Amount Thereafter Lessee, Operating Lease, Liability, to be Paid, after Year Five Effective Income Tax Rate Reconciliation, Percent [Abstract] Effective Income Tax Rate Reconciliation, Percent [Abstract] Unrealized Losses, Net Debt Securities, Available-for-Sale, Accumulated Gross Unrealized Loss, before Tax Investments [Domain] Investments [Domain] Other Deferred Tax Liabilities, Other Tax credits: Effective Income Tax Rate Reconciliation, Tax Credit, Percent [Abstract] Leases [Abstract] Leases [Abstract] Foreign taxes, net Effective Income Tax Rate Reconciliation, Foreign Income Tax Rate Differential, Amount Deferred income taxes Increase (Decrease) in Deferred Income Taxes Income Tax Paid, by Individual Jurisdiction [Line Items] Income Tax Paid, by Individual Jurisdiction [Line Items] Adjustment to Non-PEO NEO Compensation Footnote Adjustment to Non-PEO NEO Compensation Footnote [Text Block] Entity Address, State or Province Entity Address, State or Province PEO Total Compensation Amount PEO Total Compensation Amount Tax credits: Effective Income Tax Rate Reconciliation, Tax Credit, Amount [Abstract] Common stock, par value (in dollars per share) Common Stock, Par or Stated Value Per Share Foreign-currency translation adjustment and other, net Other Comprehensive Income (Loss), Foreign Currency Transaction and Translation Adjustment, Net of Tax Additions to property and equipment Segment Reporting, Long-Lived Asset, Expenditure for Addition Outstanding at the end of 2025 Outstanding at the end of 2026 Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Nonvested, Number Gross increases—tax positions in prior years Unrecognized Tax Benefits, Increase Resulting from Prior Period Tax Positions Derivative, Notional Amount Derivative, Notional Amount Basic Weighted average basic shares Weighted Average Number of Shares Outstanding, Basic Accrued insurance Accrued Insurance Deferred Deferred Foreign Income Tax Expense (Benefit) Outstanding Aggregate Erroneous Compensation Amount Outstanding Aggregate Erroneous Compensation Amount Number of Reportable Segments Number of Reportable Segments Total current liabilities Liabilities, Current INCOME BEFORE INCOME TAXES Income before Income Taxes Income (Loss) Attributable to Parent, before Tax 2030 Lessee, Operating Lease, Liability, to be Paid, Year Four U.S. state and local, Other Income Tax Jurisdiction, Domestic State and Local, Other [Member] Due after five years Debt Securities, Available-for-Sale, Fair Value, Maturity, Allocated and Single Maturity Date, after Year 5 Through 10 Interest income and other, net Interest and Other Income United States United States [Member] United States Inventory, LIFO Reserve, Period Charge Inventory, LIFO Reserve, Period Charge Lease, Cost [Abstract] Lease, Cost [Abstract] Entity Address, City or Town Entity Address, City or Town Schedule of Cash Flow, Supplemental Disclosures Schedule of Cash Flow, Supplemental Disclosures [Table Text Block] Effect of cross-border tax laws Effective Income Tax Rate Reconciliation, Cross-Border Tax Effect, Percent Granted Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Grants in Period Available-For-Sale, Cost Basis Debt Securities, Available-for-Sale, Amortized Cost, Fiscal Year Maturity [Abstract] Share-based Compensation Arrangement by Share-based Payment Award [Line Items] Share-Based Compensation Arrangement by Share-Based Payment Award [Line Items] ICFR Auditor Attestation Flag ICFR Auditor Attestation Flag Segment Reporting, Descriptive Information [Abstract] Segment Reporting, Descriptive Information [Abstract] Statement of Financial Position [Abstract] Statement of Financial Position [Abstract] Title of Individual [Domain] Title and Position [Domain] Award Timing MNPI Disclosure Award Timing MNPI Disclosure [Text Block] RSUs vested, but not yet delivered (shares) Vested and delivered Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Vested in Period Class of Stock [Axis] Class of Stock [Axis] Basis of Presentation Basis of Accounting, Policy [Policy Text Block] Net sales Net Sales Product [Member] Non-Foods [Member] Non-Foods [Member] Non-Foods [Member] Peer Group Total Shareholder Return Amount Peer Group Total Shareholder Return Amount NEW ZEALAND NEW ZEALAND Fair Value, Inputs, Level 2 [Member] Fair Value, Inputs, Level 2 [Member] Total Shareholder Return Vs Peer Group Total Shareholder Return Vs Peer Group [Text Block] Entity Well-known Seasoned Issuer Entity Well-known Seasoned Issuer Non-Rule 10b5-1 Arrangement Terminated Non-Rule 10b5-1 Arrangement Terminated [Flag] Current portion of long-term debt Long-Term Debt, Current Maturities UNITED STATES UNITED STATES Dividends [Domain] Dividends [Domain] Release of vested RSUs, including tax effects (shares) Stock Issued During Period, Shares, Restricted Stock Award, Gross Schedule of Long-term Debt Instruments [Table] Schedule of Long-Term Debt Instruments [Table] Recent Accounting Pronouncements Adopted and Not Yet Adopted New Accounting Pronouncements, Policy [Policy Text Block] Net Income per Common Share Earnings Per Share, Policy [Policy Text Block] Capital expenditures included in liabilities Capital Expenditures Incurred but Not yet Paid Segment Reporting Information, by Segment Segment Reporting [Table Text Block] 1.600% Senior Notes due April 2030 SeniorNotesOnePointSixZeroPercentDueAprilTwentyThirty [Member] SeniorNotesOnePointSixZeroPercentDueAprilTwentyThirty Use of Estimates Use of Estimates, Policy [Policy Text Block] Other Long Term Debt Other Long Term Debt [Member] Other Long Term Debt [Member] Employee stock ownership plan (ESOP) (percent) Effective Income Tax Rate Reconciliation, Deduction, Employee Stock Ownership Plan Dividend, Percent Due after one year through five years Debt Securities, Available-for-Sale, Fair Value, Maturity, Allocated and Single Maturity Date, after Year One Through Five Schedule of Future Minimum Payments Under Operating Leases Lessee, Operating Lease, Liability, to be Paid, Maturity [Table Text Block] SUPPLEMENTAL DISCLOSURE OF NON-CASH ACTIVITIES: Cash Flow, Noncash Investing and Financing Activities Disclosure [Abstract] Document Period End Date Document Period End Date Warehouse ancillary and other businesses Other [Member] Other [Member] Changes in operating assets and liabilities: Adjustment to Reconcile Net Income to Cash Provided by (Used in) Operating Activity, Increase (Decrease) in Operating Capital [Abstract] Net cash used in investing activities Cash Provided by (Used in) Investing Activity, Including Discontinued Operation Equity Awards Adjustments, Excluding Value Reported in Compensation Table Equity Awards Adjustments, Excluding Value Reported in the Compensation Table [Member] Gross unrecognized tax benefit at beginning of year Gross unrecognized tax benefit at end of year Unrecognized Tax Benefits Preferred stock, shares outstanding Preferred Stock, Shares Outstanding 2028 Lessee, Operating Lease, Liability, to be Paid, Year Two Stockholders' Equity Equity [Text Block] Security Exchange Name Security Exchange Name TAIWAN TAIWAN Fiscal Year End Fiscal Period, Policy [Policy Text Block] SWEDEN SWEDEN Income Tax Paid, Federal, after Refund Received Income Tax Paid, Federal, after Refund Received Finance Lease, Weighted Average Remaining Lease Term Finance Lease, Weighted Average Remaining Lease Term Fair value of liabilities measured on recurring basis Liabilities, Fair Value Disclosure Accumulated other comprehensive loss Accumulated Other Comprehensive Income (Loss), Net of Tax Entity Shell Company Entity Shell Company Consolidation Items [Domain] Consolidation Items [Domain] Due after one year through five years Debt Securities, Held-to-Maturity, Amortized Cost, after Allowance for Credit Loss, Maturity, Allocated and Single Maturity Date, after Year One through Five Auditor Information [Abstract] Auditor Information [Abstract] Auditor Information Other Effective Income Tax Rate Reconciliation, Other Adjustments, Amount Current operating lease liabilities Operating Lease, Liability, Current Transfer pricing settlement and certain true-ups of tax reserves tax benefit Effective Income Tax Rate Reconciliation, Tax Settlement, Amount Finance lease assets Finance Lease, Right-of-Use Asset, after Accumulated Amortization Property, Plant, and Equipment Property, Plant, and Equipment [Table Text Block] Statement of Comprehensive Income [Abstract] Statement of Comprehensive Income [Abstract] Net Income Per Common and Common Equivalent Share Earnings Per Share [Text Block] Name Outstanding Recovery, Individual Name Maturities of short-term investments Proceeds from Sale and Maturity of Marketable Securities NET INCOME PER COMMON SHARE: Earnings Per Share [Abstract] Award Timing, How MNPI Considered Award Timing, How MNPI Considered [Text Block] Deferred Deferred State and Local Income Tax Expense (Benefit) Document Fiscal Period Focus Document Fiscal Period Focus Revenue from External Customer Segment Reporting, Entity-Wide Information Not Provided as Part of Reportable Segment, Product and Service, Revenue [Line Items] Peer Group Issuers, Footnote Peer Group Issuers, Footnote [Text Block] Due in one year or less Debt Securities, Held-to-Maturity, Amortized Cost, after Allowance for Credit Loss, Maturity, Allocated and Single Maturity Date, Year One TOTAL LIABILITIES Liabilities Trading Symbol Trading Symbol 0.630% Senior Notes Due March 2026 Senior Notes Zero Point Six Three Percent Due March Twenty Twenty Six [Member] Senior Notes Zero Point Six Three Percent Due March Twenty Twenty Six Held-To-Maturity Debt Securities, Held-to-Maturity, Amortized Cost, after Allowance for Credit Loss, Maturity [Abstract] Segment, Geographical [Domain] Geographical [Domain] Additions to property and equipment Payments to Acquire Property, Plant, and Equipment Reconciliation of Unrecognized Tax Benefits, Excluding Amounts Pertaining to Examined Tax Returns [Roll Forward] Unrecognized Tax Benefits [Roll Forward] Prior Year End Fair Value of Equity Awards Granted in Any Prior Year that Fail to Meet Applicable Vesting Conditions During Covered Year Prior Year End Fair Value of Equity Awards Granted in Any Prior Year that Fail to Meet Applicable Vesting Conditions During Covered Year [Member] Pension Adjustments Prior Service Cost Pension Adjustments Prior Service Cost [Member] Company Selected Measure Name Company Selected Measure Name Income Tax Disclosure [Abstract] Income Tax Disclosure [Abstract] Tax credits - Other tax credits Effective Income Tax Rate Reconciliation, Tax Credit, Other, Amount Long-Term Debt, Gross Long-Term Debt, Gross Changes in unrecognized tax benefits Effective Income Tax Rate Reconciliation, Tax Contingency, Percent CASH FLOWS FROM OPERATING ACTIVITIES Cash Provided by (Used in) Operating Activity, Including Discontinued Operation [Abstract] Foreign Income (Loss) from Continuing Operations before Income Taxes, Foreign Compensation Amount Outstanding Recovery Compensation Amount Individual: Individual [Axis] Diluted Weighted average diluted shares Weighted Average Number of Shares Outstanding, Diluted Entity Emerging Growth Company Entity Emerging Growth Company Equity Valuation Assumption Difference, Footnote Equity Valuation Assumption Difference, Footnote [Text Block] Property, plant and equipment, useful life Property, Plant, and Equipment, Useful Life 2028 Finance Lease, Liability, to be Paid, Year Two Derivatives Derivatives, Policy [Policy Text Block] Line of Credit Facility [Table] Line of Credit Facility [Table] Underlying Security Market Price Change Underlying Security Market Price Change, Percent Dividends Dividends 2030 Finance Lease, Liability, to be Paid, Year Four Less amount representing interest Lessee, Operating Lease, Liability, Undiscounted Excess Amount Schedule of Share-based Compensation Arrangements by Share-based Payment Award [Table] Schedule of Share-Based Compensation Arrangements by Share-Based Payment Award [Table] Line of credit facility, current borrowing capacity Line of Credit Facility, Current Borrowing Capacity Less amount representing interest Finance Lease, Liability, Undiscounted Excess Amount Other operating assets and liabilities, net Increase (Decrease) in Other Operating Assets and Liabilities, Net Operating cash flows - operating leases Operating Lease, Payments Deferred Tax Assets: Components of Deferred Tax Assets [Abstract] Award Timing Predetermined Award Timing Predetermined [Flag] Deferred Deferred Federal Income Tax Expense (Benefit) Canada Canada [Member] Canada Adjustment To PEO Compensation, Footnote Adjustment To PEO Compensation, Footnote [Text Block] Stock-based compensation APIC, Share-Based Payment Arrangement, Increase for Cost Recognition Total state State and Local Income Tax Expense (Benefit), Continuing Operations Total Effective Income Tax Rate Reconciliation, Percent Total Lessee, Operating Lease, Liability, to be Paid Operating lease right-of-use assets DeferredTaxLiabilitiesRightOfUseAssets DeferredTaxLiabilitiesRightOfUseAssets Fair Value of Financial Instruments Fair Value of Financial Instruments, Policy [Policy Text Block] RSUs and other Incremental Common Shares Attributable to Dilutive Effect of Share-Based Payment Arrangements Outstanding at the end of 2025 Outstanding at the end of 2026 Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Nonvested, Weighted Average Grant Date Fair Value Inventory, Current [Table] Inventory, Current [Table] All Executive Categories All Executive Categories [Member] Number of states in country Number of States in which Entity Operates Repurchases of common stock, value Repurchases of common stock, value Stock Repurchased and Retired During Period, Value Pension Adjustments Service Cost Pension Adjustments Service Cost [Member] Preferred stock, par value (in dollars per share) Preferred Stock, Par or Stated Value Per Share Long-term Debt, Fair Value Long-Term Debt, Fair Value Equity compensation Deferred Tax Assets, Tax Deferred Expense, Compensation and Benefits Plan Name [Domain] Plan Name [Domain] LesseeOperatingandFinancingLeasesNotYetCommenced LesseeOperatingandFinancingLeasesNotYetCommenced LesseeOperatingandFinancingLeasesNotYetCommenced Operating lease right-of-use assets Operating Lease, Right-of-Use Asset Due in one year or less Debt Securities, Available-for-Sale, Amortized Cost, Maturity, Allocated and Single Maturity Date, Year One Schedule of Earnings Per Share, Basic and Diluted Schedule of Earnings Per Share, Basic and Diluted [Table Text Block] Fair Value Disclosures [Abstract] Fair Value Disclosures [Abstract] Debt Disclosure [Abstract] Debt Disclosure [Abstract] Segment Reporting Segment Reporting [Text Block] Investments Investment in Debt and Equity Securities and Other Trading Assets [Text Block] Minimum [Member] Minimum [Member] Investment Type [Axis] Investment Type [Axis] Retirement Plans Pension and Other Postretirement Plans, Nonpension Benefits, Policy [Policy Text Block] Cash dividend payments Payments of Ordinary Dividends, Common Stock Expiration Date Trading Arrangement Expiration Date Current Current Foreign Tax Expense (Benefit) 2030 Long-Term Debt, Maturity, Year Four Auditor Name Auditor Name Revenue from External Customers by Products and Services Disaggregation of Revenue [Table Text Block] Current Current State and Local Tax Expense (Benefit) Available For Sale And Held To Maturity [Line Items] Available For Sale And Held To Maturity [Line Items] Available For Sale And Held To Maturity [Line Items] EFFECT OF EXCHANGE RATE CHANGES ON CASH AND CASH EQUIVALENTS Effect of Exchange Rate on Cash, Cash Equivalent, Restricted Cash, and Restricted Cash Equivalent, Continuing Operation Non-Rule 10b5-1 Arrangement Adopted Non-Rule 10b5-1 Arrangement Adopted [Flag] Goodwill and Intangible Assets, Goodwill, Policy Goodwill and Intangible Assets, Goodwill, Policy [Policy Text Block] Aggregate Grant Date Fair Value of Equity Award Amounts Reported in Summary Compensation Table Aggregate Grant Date Fair Value of Equity Award Amounts Reported in Summary Compensation Table [Member] OperatingLeaseandFinanceLeaseLiabilities OperatingLeaseandFinanceLeaseLiabilities OperatingLeaseandFinanceLeaseLiabilities Building and improvements [Member] Building and Building Improvements [Member] Aggregate Pension Adjustments Service Cost Aggregate Pension Adjustments Service Cost [Member] Derivative [Table] Derivative [Table] Common stock, shares authorized Common Stock, Shares Authorized Carrying Value of Company's Long-Term Debt Schedule of Carrying Values and Estimated Fair Values of Debt Instruments [Table Text Block] Exercise Price Award Exercise Price CASH FLOWS FROM INVESTING ACTIVITIES Cash Provided by (Used in) Investing Activity, Including Discontinued Operation [Abstract] Entity Voluntary Filers Entity Voluntary Filers Fair Value, Recurring [Member] Fair Value, Recurring [Member] Segment Reporting [Line Items] Segment Reporting [Line Items] Stock Repurchase Program, Authorized Amount Share Repurchase Program, Authorized, Amount Unrecognized compensation cost Share-Based Payment Arrangement, Nonvested Award, Cost Not yet Recognized, Amount Document Financial Statement Error Correction [Flag] Document Financial Statement Error Correction [Flag] Year-over-Year Change in Fair Value of Equity Awards Granted in Prior Years That are Outstanding and Unvested Year-over-Year Change in Fair Value of Equity Awards Granted in Prior Years That are Outstanding and Unvested [Member] Segments [Domain] Segments [Domain] Property and Equipment, Net Property, Plant, and Equipment [Policy Text Block] Long-Term Operating and Finance Lease Liabilities [Abstract] Long-Term Operating and Finance Lease Liabilities [Abstract] Long-Term Operating and Finance Lease Liabilities Debt Debt Disclosure [Text Block] Repayments of long-term debt Repayments of Long-Term Debt Less unamortized debt discounts and issuance costs Debt Issuance Costs, Net Awards Close in Time to MNPI Disclosures, Table Awards Close in Time to MNPI Disclosures [Table Text Block] Income Tax Paid, by Individual Jurisdiction [Table] Income Tax Paid, by Individual Jurisdiction [Table] Equity Component [Domain] Equity Component [Domain] PEO Actually Paid Compensation Amount PEO Actually Paid Compensation Amount 0.790% Senior Notes Due May 2025 SeniorNotesZeroPointSevenNineZeroPercentDueMayTwentyTwentyFive [Member] SeniorNotesZeroPointSevenNineZeroPercentDueMayTwentyTwentyFive Available-For-Sale, Fair Value Debt Securities, Available-for-Sale, Fair Value, Fiscal Year Maturity [Abstract] Buildings and improvements Buildings and Improvements, Gross Adoption Date Trading Arrangement Adoption Date Thereafter Long-Term Debt, Maturity, after Year Five Credit and debit card receivables, at carrying value Cash Equivalent, Credit and Debit Card Receivables, Carrying Value Merchandise Inventories Inventory, Policy [Policy Text Block] Income Tax Paid, by Individual Jurisdiction [Abstract] Income Tax Paid, by Individual Jurisdiction [Abstract] Finance Lease, Weighted Average Discount Rate, Percent Finance Lease, Weighted Average Discount Rate, Percent Dividends, Common Stock, Cash Dividends, Common Stock, Cash Debt instrument, interest rate, stated percentage Debt Instrument, Interest Rate, Stated Percentage TOTAL EQUITY Equity at beginning of period Equity at end of period Equity, Attributable to Parent Foreign tax credit carry forward Deferred Tax Assets, Tax Credit Carryforwards, Foreign ASSETS Assets [Abstract] Title Trading Arrangement, Individual Title Forgone Recovery due to Disqualification of Tax Benefits, Amount Forgone Recovery due to Disqualification of Tax Benefits, Amount Available-for-sale, cost basis Available-for-sale, cost basis, total Debt Securities, Available-for-Sale, Amortized Cost Accounting Policies [Abstract] Accounting Policies [Abstract] Restatement does not require Recovery Restatement Does Not Require Recovery [Text Block] Tax credits - Research and development Effective Income Tax Rate Reconciliation, Tax Credit, Research, Amount Present value of lease liabilities Operating Lease, Liability Insider Trading Policies and Procedures [Line Items] Present value of lease liabilities Finance Lease, Liability Held-to-maturity, recorded basis Debt Securities, Held-to-Maturity, Fair Value Insider Trading Policies and Procedures Adopted Insider Trading Policies and Procedures Adopted [Flag] Performance Shares [Member] Performance Shares [Member] Selling, general and administrative Selling, General and Administrative Expense Repayments of Debt Repayments of Debt Commitments and Contingencies Commitments and Contingencies Disclosure [Text Block] Compensation Actually Paid vs. Net Income Compensation Actually Paid vs. Net Income [Text Block] Construction in progress Construction in Progress, Gross Restricted Stock Units (RSUs) Restricted Stock Units (RSUs) [Member] Auditor Location Auditor Location Entity Central Index Key Entity Central Index Key Accumulated depreciation and amortization Property, Plant, and Equipment, Accumulated Depreciation, Depletion, and Amortization Additional paid-in capital Additional Paid in Capital, Common Stock All Adjustments to Compensation All Adjustments to Compensation [Member] Equity [Abstract] Dividends or Other Earnings Paid on Equity Awards not Otherwise Reflected in Total Compensation for Covered Year Dividends or Other Earnings Paid on Equity Awards not Otherwise Reflected in Total Compensation for Covered Year [Member] Effect of cross-border tax laws Effective Income Tax Rate Reconciliation, Cross-Border Tax Effect, Amount Income Taxes Income Tax, Policy [Policy Text Block] Net cash provided by operating activities Cash Provided by (Used in) Operating Activity, Including Discontinued Operation Federal taxes at statutory rate Effective Income Tax Rate Reconciliation at Federal Statutory Income Tax Rate, Amount Total foreign Foreign Income Tax Expense (Benefit), Continuing Operations Income Statement [Abstract] Income Statement [Abstract] Document Transition Report Document Transition Report Fair Value Hierarchy and NAV [Axis] Fair Value Hierarchy and NAV [Axis] OPERATING EXPENSES Operating Expenses [Abstract] Long-term finance lease liabilities Finance Lease, Liability, Noncurrent Finance lease assets Finance Lease, Right-of-Use Asset, Statement of Financial Position [Extensible Enumeration] Schedule of Components of Income Tax Expense (Benefit) Schedule of Components of Income Tax Expense (Benefit) [Table Text Block] Stock Appreciation Rights (SARs) Stock Appreciation Rights (SARs) [Member] Income Tax Expense (Benefit), Effective Income Tax Rate Reconciliation, Amount [Abstract] Income Tax Expense (Benefit), Effective Income Tax Rate Reconciliation, Amount [Abstract] Employees [Member] Employees [Member] Employees [Member] Deferred membership fees Deferred Revenue, Current City Area Code City Area Code Total Finance Lease, Liability, to be Paid Accumulated Other Comprehensive Income (Loss) AOCI Attributable to Parent [Member] All Individuals All Individuals [Member] Name Forgone Recovery, Individual Name Weighted-average recognition period Share-Based Payment Arrangement, Nonvested Award, Cost Not yet Recognized, Period for Recognition Share-based compensation arrangement by share-based payment number of years of service Share Based Compensation Arrangement By Share Based Payment Number Of Years Of Service The number of years of service completed by an employee with the Company at which accelerated vesting occurs. Non-GAAP Measure Description Non-GAAP Measure Description [Text Block] Statement [Line Items] Statement [Line Items] Undistributed Earnings of Foreign Subsidiaries Undistributed Earnings of Foreign Subsidiaries Total assets Assets Lessee, Operating Lease, Liability, to be Paid, Fiscal Year Maturity [Abstract] Lessee, Operating Lease, Liability, to be Paid, Fiscal Year Maturity [Abstract] Schedule of Deferred Tax Assets and Liabilities Schedule of Deferred Tax Assets and Liabilities [Table Text Block] Effective Income Tax Rate Reconciliation [Line Items] Effective Income Tax Rate Reconciliation [Line Items] Weighted average grant date fair value Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Additional Disclosures [Abstract] Preferred stock, shares issued Preferred Stock, Shares Issued State [Abstract] State and Local Income Tax Expense (Benefit), Continuing Operations [Abstract] Operating Segments Operating Segments [Member] Stock-Based Compensation Share-Based Payment Arrangement [Policy Text Block] 2.750% Senior Notes due May 2024 SeniorNotesTwoPointSevenFivePercentDueMayEighteenTwentyTwentyFour [Member] [Member] SeniorNotesTwoPointSevenFivePercentDueMayEighteenTwentyTwentyFour [Member] [Member] Unrealized Gains, Net Debt Securities, Available-for-Sale, Accumulated Gross Unrealized Gain, before Tax Stock-Based Compensation Plans Share-Based Payment Arrangement [Text Block] Foreign taxes, net Effective Income Tax Rate Reconciliation, Foreign Income Tax Rate Differential, Percent Non-cash lease expense OperatingandFinancingLeaseRightofUseAssetAmortization Amount of Amortization expense attributable to right-of-use asset from operating and finance lease. Net deferred tax liabilities Deferred Tax Liabilities, Net PEO PEO [Member] 2028 Long-Term Debt, Maturity, Year Two Repurchases of common stock, shares Repurchases of common stock, shares Stock Repurchased and Retired During Period, Shares Other long-term liabilities Other Liabilities, Noncurrent Goodwill Goodwill Forgone Recovery due to Violation of Home Country Law, Amount Forgone Recovery due to Violation of Home Country Law, Amount Cash and Cash Equivalents Cash and Cash Equivalents, Policy [Policy Text Block] Foreign, Other Income Tax Jurisdiction, Foreign, Other [Member] Weighted-average grant date fair value Granted Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Grants in Period, Weighted Average Grant Date Fair Value Foreign [Abstract] Foreign Income Tax Expense (Benefit), Continuing Operations [Abstract] Thereafter Finance Lease, Liability, to be Paid, after Year Five Changes in unrecognized tax benefits Effective Income Tax Rate Reconciliation, Tax Contingency, Amount Other Supplemental Balance Sheet Information [Abstract] Other Supplemental Balance Sheet Information [Abstract] Other Supplemental Balance Sheet Information Due in one year or less Debt Securities, Available-for-Sale, Fair Value, Maturity, Allocated and Single Maturity Date, Year One Redemption Price Certain Events Redemption Price Certain Events The redemption price, as a percentage of the principal amount, that the Company, upon certain events defined by the terms of the outstanding notes, will be required to make a purchase offer to redeem notes outstanding. Retained Earnings Retained Earnings [Member] Long-term operating lease liabilities Operating Lease, Liability, Noncurrent Foreign branch deferreds Deferred Tax Liabilities, Undistributed Foreign Earnings Forfeited Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Forfeitures, Weighted Average Grant Date Fair Value Stock Repurchase Programs Stockholders' Equity, Policy [Policy Text Block] Tax credits - Other tax credits Effective Income Tax Rate Reconciliation, Tax Credit, Other, Percent Erroneously Awarded Compensation Recovery Erroneously Awarded Compensation Recovery [Table] Increase (Decrease) in Stockholders' Equity [Roll Forward] Increase (Decrease) in Stockholders' Equity [Roll Forward] Common stock, shares outstanding Common stock at beginning of period (shares) Common stock at end of period (shares) Common Stock, Shares, Outstanding Award Timing Disclosures [Line Items] Diluted Earnings Per Share, Diluted Entity Current Reporting Status Entity Current Reporting Status Net cash used in financing activities Cash Provided by (Used in) Financing Activity, Including Discontinued Operation Total Shareholder Return Amount Total Shareholder Return Amount Line of Credit Facility [Line Items] Line of Credit Facility [Line Items] Stockholders' Equity Note [Abstract] Stockholders' Equity Note [Abstract] Total short-term investments, cost basis Debt Securities, Available-for-Sale and Held-to-Maturity, Amortized Cost, before Allowance for Credit Loss Adjustments to reconcile net income including noncontrolling interests to net cash provided by operating activities: Adjustment to Reconcile Net Income to Cash Provided by (Used in) Operating Activity [Abstract] 2029 Long-Term Debt, Maturity, Year Three Available For Sale And Held To Maturity [Table] Available For Sale And Held To Maturity [Table] Available For Sale And Held To Maturity [Table] Share-based Payment Arrangement [Abstract] Share-Based Payment Arrangement [Abstract] CASH FLOWS FROM FINANCING ACTIVITIES Cash Provided by (Used in) Financing Activity, Including Discontinued Operation [Abstract] Property and equipment, net Property, Plant, and Equipment, after Accumulated Depreciation, Depletion, and Amortization Total revenue Total Revenue Revenue from Contract with Customer, Excluding Assessed Tax Operating Lease and Finance Lease Right-of-Use-Assets [Abstract] Operating Lease anf Finance Lease Right-of-Use-Assets [Abstract] Operating Lease and Finance Lease Right-of-Use-Assets Other Effective Income Tax Rate Reconciliation, Other Adjustments, Percent Property and equipment Deferred Tax Liabilities, Property, Plant and Equipment Income Tax Paid, State and Local, after Refund Received Income Tax Paid, State and Local, after Refund Received Financial Instruments [Domain] Financial Instruments [Domain] Special Dividend [Member] S2024Q2Dividends [Member] Special Dividend [Member] Other Income Other Income LIFO Inventory Amount LIFO Inventory Amount Equity Awards Adjustments, Footnote Equity Awards Adjustments, Footnote [Text Block] Underlying Securities Award Underlying Securities Amount Purchases of short-term investments Payments to Acquire Short-Term Investments Operating Lease and Finance Lease Liabilities [Abstract] Operating Lease and Finance Lease Liabilities [Abstract] Operating Lease and Finance Lease Liabilities Finance Lease, Liability, Payment, Due, Rolling Maturity [Abstract] Finance Lease, Liability, to be Paid, Rolling Maturity [Abstract] Schedule of Income before Income Tax, Domestic and Foreign Schedule of Income before Income Tax, Domestic and Foreign [Table Text Block] Tax Credit Carryforward [Line Items] Tax Credit Carryforward [Line Items] Other investing activities, net Payment for (Proceeds from) Other Investing Activity Merchandise inventories Increase (Decrease) in Inventories Operating Lease, Weighted Average Discount Rate, Percent Operating Lease, Weighted Average Discount Rate, Percent State taxes, net Effective Income Tax Rate Reconciliation, State and Local Income Taxes, Amount Segment Reporting [Table] Segment Reporting [Table] Number of shares available to be granted as RSUs Share-Based Compensation Arrangement by Share-Based Payment Award, Number of Shares Available for Grant Schedule of Maturities of Long-term Debt Schedule of Maturities of Long-Term Debt [Table Text Block] Finance lease liabilities Finance Lease, Liability, Current, Statement of Financial Position [Extensible Enumeration] Title of Individual [Axis] Title and Position [Axis] Lease, Cost Lease, Cost [Table Text Block] Other current assets Other Assets, Current Commitments and Contingencies Disclosure [Abstract] Commitments and Contingencies Disclosure [Abstract] OTHER INCOME (EXPENSE) Other Nonoperating Income (Expense) [Abstract] All Trading Arrangements All Trading Arrangements [Member] Auditor Firm ID Auditor Firm ID Other Performance Measure, Amount Other Performance Measure, Amount Award Timing MNPI Considered Award Timing MNPI Considered [Flag] Operating income Operating income Operating Income (Loss) OperatingLeaseandFinanceLeaserightofuseassets OperatingLeaseandFinanceLeaserightofuseassets OperatingLeaseandFinanceLeaserightofuseassets Current Fiscal Year End Date Current Fiscal Year End Date Income Tax Paid, Foreign, after Refund Received Income Tax Paid, Foreign, after Refund Received Schedule of Future Minimum Payments under Financing Leases Finance Lease, Liability, to be Paid, Maturity [Table Text Block] Held-to-maturity, cost basis Held-to-maturity, cost basis, total Debt Securities, Held-to-Maturity, Amortized Cost, before Allowance for Credit Loss Non-PEO NEO Average Total Compensation Amount Non-PEO NEO Average Total Compensation Amount Derivative [Line Items] Derivative [Line Items] Change in Fair Value as of Vesting Date of Prior Year Equity Awards Vested in Covered Year Change in Fair Value as of Vesting Date of Prior Year Equity Awards Vested in Covered Year [Member] Common Stock, Dividends, Per Share, Declared Common Stock, Dividends, Per Share, Declared Entity File Number Entity File Number Rule 10b5-1 Arrangement Adopted Rule 10b5-1 Arrangement Adopted [Flag] Maturities of Available for Sale and Held to Maturity Securities Investments Classified by Contractual Maturity Date [Table Text Block] Recovery of Erroneously Awarded Compensation Disclosure [Line Items] Common stock, shares issued Common Stock, Shares, Issued Measure: Measure [Axis] Federal [Abstract] Federal Income Tax Expense (Benefit), Continuing Operations [Abstract] SPAIN SPAIN Equity Components [Axis] Equity Components [Axis] Product and Service [Domain] Product and Service [Domain] Income Tax Paid, after Refund Received, Total Income Tax Paid, after Refund Received CALIFORNIA CALIFORNIA Disaggregation of Revenue [Table] Disaggregation of Revenue [Table] Entity Interactive Data Current Entity Interactive Data Current Current finance lease liabilities Finance Lease, Liability, Current Number of warehouses operated Number of Stores Deferred Tax Liabilities Deferred Income Tax Liabilities, Net Compensation Actually Paid vs. Other Measure Compensation Actually Paid vs. Other Measure [Text Block] Due after one year through five years Debt Securities, Available-for-Sale, Amortized Cost, Maturity, Allocated and Single Maturity Date, after Year One Through Five Defined contribution plan, cost recognized Defined Contribution Plan, Cost Entity Small Business Entity Small Business 0.920% Senior Notes Due July 2024 Senior Notes Zero Point Nine Two Percent Due July Twenty Twenty Four [Member] Senior Notes Zero Point Nine Two Percent Due July Twenty Twenty Four COMPREHENSIVE INCOME Comprehensive Income (Loss), Net of Tax, Attributable to Parent Balance Sheet Location[Table] Balance Sheet Location [Table] Balance Sheet Location 2029 Lessee, Operating Lease, Liability, to be Paid, Year Three FIFO Inventory Amount FIFO Inventory Amount Termination Date Trading Arrangement Termination Date Property and Equipment, Net [Line Items] Property, Plant, and Equipment [Line Items] Effective Income Tax Rate Reconciliation [Table] Effective Income Tax Rate Reconciliation [Table] Fair Value, Recurring and Nonrecurring [Table] Fair Value, Recurring and Nonrecurring [Table] Federal taxes at statutory rate Effective Income Tax Rate Reconciliation, at Federal Statutory Income Tax Rate, Percent Compensation Actually Paid vs. Total Shareholder Return Compensation Actually Paid vs. Total Shareholder Return [Text Block] MNPI Disclosure Timed for Compensation Value MNPI Disclosure Timed for Compensation Value [Flag] Other current liabilities Other Liabilities, Current Nontaxable or nondeductible Effective Income Tax Rate Reconciliation, Nondeductible Expense, Amount Other long-term assets Other Assets, Noncurrent 2029 Finance Lease, Liability, to be Paid, Year Three Document Type Document Type Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items] Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items] Accrued member rewards Accrued Liabilities, Current Entity Public Float Entity Public Float OTHER LIABILITIES Other Liabilities [Abstract] Fair Value as of Grant Date Award Grant Date Fair Value 1.750% Senior Notes due April 2032 SeniorNotesOnePointSevenFivePercentDueAprilTwentyThirtyTwo [Member] SeniorNotesOnePointSevenFivePercentDueAprilTwentyThirtyTwo Gross decreases—tax positions in prior years Unrecognized Tax Benefits, Decrease Resulting from Prior Period Tax Positions Debt Instrument, Redemption Price, Percentage Debt Instrument, Redemption Price, Percentage Significant Accounting Policies Significant Accounting Policies [Text Block] Entity Location [Table] Entity Location [Table] Schedule of Goodwill [Table] Goodwill [Table] Pay vs Performance Disclosure, Table Pay vs Performance [Table Text Block] Stock Repurchase Program, Remaining Authorized Repurchase Amount Share Repurchase Program, Remaining Authorized, Amount Arrangement Duration Trading Arrangement Duration Summary of RSU Transactions Share-Based Compensation Arrangements by Share-Based Payment Award, Restricted Stock Units, Vested and Expected to Vest [Table Text Block] Statement of Stockholders' Equity [Abstract] Statement of Stockholders' Equity [Abstract] Proceeds from issuance of long-term debt Proceeds from Issuance of Long-Term Debt Local Phone Number Local Phone Number CANADA CANADA Total deferred tax liabilities Deferred Tax Liabilities, Gross Consolidation Items [Axis] Consolidation Items [Axis] Entity Address, Postal Zip Code Entity Address, Postal Zip Code Entity Registrant Name Entity Registrant Name Gross increases—current year tax positions Unrecognized Tax Benefits, Increase Resulting from Current Period Tax Positions INCOME BEFORE INCOME TAXES Income (Loss) from Continuing Operations before Income Taxes, Noncontrolling Interest Insider Trading Policies and Procedures Not Adopted Insider Trading Policies and Procedures Not Adopted [Text Block] Summary Of Significant Accounting Policies [Line Items] Summary Of Significant Accounting Policies [Line Items] Summary Of Significant Accounting Policies [Line Items] COMMITMENTS AND CONTINGENCIES Commitments and Contingencies Long-term finance lease liabilities Finance Lease, Liability, Noncurrent, Statement of Financial Position [Extensible Enumeration] Gross property and equipment Property, Plant, and Equipment, before Accumulated Depreciation, Depletion, and Amortization Changed Peer Group, Footnote Changed Peer Group, Footnote [Text Block] 1.375% Senior Notes due June 2027 SeniorNotesOnePointThreeSevenFivePercentDueJuneTwentyTwentySeven [Member] SeniorNotesOnePointThreeSevenFivePercentDueJuneTwentyTwentySeven Equipment and fixtures Fixtures and Equipment, Gross OTHER ASSETS Other Assets [Abstract] Forgone Recovery due to Expense of Enforcement, Amount Forgone Recovery due to Expense of Enforcement, Amount Executive Category: Executive Category [Axis] CHINA CHINA Finance Lease, Right-of-Use Asset, Amortization Finance Lease, Right-of-Use Asset, Amortization Share-based compensation arrangement by share-based payment award, award vesting period Share-Based Compensation Arrangement by Share-Based Payment Award, Award Vesting Period Equipment and Fixtures [Member] Furniture and Fixtures [Member] LIABILITIES AND EQUITY Liabilities and Equity [Abstract] AUSTRALIA AUSTRALIA Fair Value of Financial Assets and Liabilities Measured on Recurring Basis Schedule of Fair Value, Assets and Liabilities Measured on Recurring Basis [Table Text Block] Merchandise inventories Inventory, Net Award Type [Domain] Award Type [Domain] Non-PEO NEO Average Compensation Actually Paid Amount Non-PEO NEO Average Compensation Actually Paid Amount Finance Lease, Interest Expense Finance Lease, Interest Expense Fair Value Measurement Fair Value Disclosures [Text Block] US Government Agencies Debt Securities [Member] Government and Agency Securities [Member] US Government Agencies Debt Securities [Member] SUPPLEMENTAL DISCLOSURE OF CASH FLOW INFORMATION: Supplemental Cash Flow Information [Abstract] PEO Name PEO Name Geographical [Axis] Geographical [Axis] Lessor, Operating Lease, Payments to be Received Lessor, Operating Lease, Payment to be Received Income taxes paid, net Income Tax Paid, before Refund Received Property, Plant and Equipment, Type [Axis] Long-Lived Asset, Class [Axis] Tax credits - Research and development Effective Income Tax Rate Reconciliation, Tax Credit, Research, Percent Stock Price or TSR Estimation Method Stock Price or TSR Estimation Method [Text Block] Entity Tax Identification Number Entity Tax Identification Number Less income tax benefit Share-Based Payment Arrangement, Expense, Tax Benefit Revenue Recognition Revenue [Policy Text Block] CASH AND CASH EQUIVALENTS BEGINNING OF YEAR CASH AND CASH EQUIVALENTS END OF YEAR Cash, Cash Equivalent, Restricted Cash, and Restricted Cash Equivalent, Continuing Operation Accounts payable Increase (Decrease) in Accounts Payable Entity Incorporation, State or Country Code Entity Incorporation, State or Country Code Aggregate Erroneous Compensation Not Yet Determined Aggregate Erroneous Compensation Not Yet Determined [Text Block] Material Terms of Trading Arrangement Material Terms of Trading Arrangement [Text Block] Non-NEOs Non-NEOs [Member] Vesting Date Fair Value of Equity Awards Granted and Vested in Covered Year Vesting Date Fair Value of Equity Awards Granted and Vested in Covered Year [Member] ICELAND ICELAND Measurement Frequency [Domain] Measurement Frequency [Domain] Stock-based compensation Total stock-based compensation expense before income taxes Share-Based Payment Arrangement, Noncash Expense Cash dividends declared Dividends, Cash Total lease costs Lease, Cost Land Land DisclosureofSupplementalBalanceSheetInformationRelatedtoLeases DisclosureofSupplementalBalanceSheetInformationRelatedtoLeases [Table Text Block] DisclosureofSupplementalBalanceSheetInformationRelatedtoLeases Schedule of Merchandise Inventories Schedule of Inventory, Current [Table Text Block] Lessee, Operating Leases Lessee, Operating Leases [Text Block] 2027 Long-Term Debt, Maturity, Year One Long-term Debt, Type [Domain] Long-Term Debt, Type [Domain] Due after five years Debt Securities, Available-for-Sale, Amortized Cost, Maturity, Allocated and Single Maturity Date, after Year 5 Through 10 Basic Earnings Per Share, Basic Repurchases of common stock Payments for Repurchase of Common Stock Valuation allowance Valuation Allowances Tax Credit Carryforward, Valuation Allowance Total current assets Assets, Current Statistical Measurement [Axis] Statistical Measurement [Axis] Insider Trading Arrangements [Line Items] Long-term debt, excluding current portion Long-Term Debt, Excluding Current Maturities Other International Other International [Member] Other International [Member] Changes in valuation allowance Effective Income Tax Rate Reconciliation, Change in Deferred Tax Assets Valuation Allowance, Percent Award Type [Axis] Award Type [Axis] Document Annual Report Document Annual Report Named Executive Officers, Footnote Named Executive Officers, Footnote [Text Block] Operating lease liabilities DeferredTaxAssetsOperatingLeaseLiabilities DeferredTaxAssetsOperatingLeaseLiabilities Stock repurchase activity Class of Treasury Stock [Table Text Block] Retained earnings Retained Earnings (Accumulated Deficit) Product and Service [Axis] Product and Service [Axis] Financing lease payments and other financing activities, net Financing lease payments and other financing activities, net Financing lease payments and other financing activities, net Aggregate Change in Present Value of Accumulated Benefit for All Pension Plans Reported in Summary Compensation Table Aggregate Change in Present Value of Accumulated Benefit for All Pension Plans Reported in Summary Compensation Table [Member] Vendor Consideration Cost of Sales, Vendor Allowances, Policy [Policy Text Block] Awards Close in Time to MNPI Disclosures Awards Close in Time to MNPI Disclosures [Table] Common Stock Common Stock [Member] Available-for-sale, recorded basis, total Available-for-sale, recorded basis, total Debt Securities, Available-for-Sale 3.000% Senior Notes due May 2027 SeniorNotesThreePercentDueMayEighteenTwentyTwentySeven[Member] [Member] SeniorNotesThreePercentDueMayEighteenTwentyTwentySeven[Member] Changes in valuation allowance Effective Income Tax Rate Reconciliation, Nondeductible Expense, Percent Operating Lease, Cost Operating Lease, Cost Compensation Actually Paid vs. Company Selected Measure Compensation Actually Paid vs. Company Selected Measure [Text Block] Cover [Abstract] Reclassification Reclassification, Comparability Adjustment [Policy Text Block] Documents Incorporated by Reference Documents Incorporated by Reference [Text Block] UNITED KINGDOM UNITED KINGDOM Derivative, Name [Domain] Derivative Contract [Domain] Receivables, Net Receivable [Policy Text Block] Equity Awards Adjustments Equity Awards Adjustments [Member] TOTAL LIABILITIES AND EQUITY Liabilities and Equity Variable Lease, Cost Variable Lease, Cost Deferred Tax Assets, Net Deferred Tax Assets, Net Employee Stock Option Share-Based Payment Arrangement, Option [Member] Segments [Axis] Segments [Axis] Additional 402(v) Disclosure Additional 402(v) Disclosure [Text Block] Plan Name [Axis] Plan Name [Axis] Income Tax Jurisdiction [Domain] Income Tax Jurisdiction [Domain] Tabular List, Table Tabular List [Table Text Block] Available for Sale and Held to Maturity Investments Unrealized Gain (Loss) on Investments [Table Text Block] Summary of Stock-Based Compensation Expense and Related Tax Benefits Share-Based Payment Arrangement, Cost by Plan [Table Text Block] Name Awards Close in Time to MNPI Disclosures, Individual Name EQUITY Equity, Including Portion Attributable to Noncontrolling Interest [Abstract] Due after five years Debt Securities, Held-to-Maturity, Amortized Cost, after Allowance for Credit Loss, Maturity, Allocated and Single Maturity Date, after Year 5 through 10 Year-end Fair Value of Equity Awards Granted in Covered Year that are Outstanding and Unvested Year-end Fair Value of Equity Awards Granted in Covered Year that are Outstanding and Unvested [Member] Forfeited Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Forfeited in Period Property, Plant and Equipment, Type [Domain] Long-Lived Asset, Class [Domain] Fresh Foods [Member] Fresh Food [Member] Fresh Food [Member] Preferred stock, shares authorized Preferred Stock, Shares Authorized Employee stock ownership plan (ESOP) Effective Income Tax Rate Reconciliation, Deduction, Employee Stock Ownership Plan Dividend, Amount FRANCE FRANCE Receivables, net Receivables, Net, Current Property and Equipment, Net [Table] Property, Plant, and Equipment [Table] Preferred stock $.005 par value; 100,000,000 shares authorized; no shares issued and outstanding Preferred Stock, Value, Issued Adjustment to Compensation: Adjustment to Compensation [Axis] Merchandise Costs Cost of Goods and Service [Policy Text Block] Dividends Payable [Line Items] Dividends Payable [Line Items] Class of Stock [Domain] Class of Stock [Domain] Dividends Payable [Table] Dividends Payable [Table] Rule 10b5-1 Arrangement Terminated Rule 10b5-1 Arrangement Terminated [Flag] Aggregate Erroneous Compensation Amount Aggregate Erroneous Compensation Amount Operating cash flows - finance leases Finance Lease, Interest Payment on Liability Interest Interest Paid, Excluding Capitalized Interest, Operating Activity Statement of Cash Flows [Abstract] Statement of Cash Flows [Abstract] Selling, General and Administrative Expenses Selling, General and Administrative Expenses, Policy [Policy Text Block] Forward foreign exchange contracts Foreign Exchange Forward [Member] Foreign Exchange Forward [Member] Schedule of Inventory [Line Items] Inventory [Line Items] Aggregate Available Trading Arrangement, Securities Aggregate Available Amount Fair value of assets measured on recurring basis Assets, Fair Value Disclosure Short-Term Investments Investment, Policy [Policy Text Block] Income Tax Jurisdiction [Axis] Income Tax Jurisdiction [Axis] 2031 Finance Lease, Liability, to be Paid, Year Five Name Measure Name Income Taxes Income Tax Disclosure [Text Block] Minimum number of days of employment to qualify for retirement plan Minimum Number Of Days Of Employment To Qualify For Retirement Plan Minimum number of days of employment to qualify for 401(k) Retirement Plan Accounts payable Accounts Payable, Current Pay vs Performance Disclosure [Line Items] Fair Value, Measurements, Fair Value Hierarchy [Domain] Fair Value Hierarchy and NAV [Domain] Other Noncash Income (Expense) Other Noncash Income (Expense) 2031 Lessee, Operating Lease, Liability, to be Paid, Year Five MEXICO MEXICO Deferred Tax Liabilities: Components of Deferred Tax Liabilities [Abstract] Debt Instrument [Line Items] Debt Instrument [Line Items] Pay vs Performance Disclosure Pay vs Performance Disclosure [Table] Domestic Income (Loss) from Continuing Operations before Income Taxes, Domestic Additional Paid-in Capital Additional Paid-in Capital [Member] Entity Filer Category Entity Filer Category Short-term investments Total investments, recorded basis Short-Term Investments Repayments of short-term borrowings Repayments of Short-Term Debt Dividends [Axis] Dividends [Axis] Name Trading Arrangement, Individual Name Accrued liabilities and reserves Deferred Tax Assets, Tax Deferred Expense, Reserves and Accruals, Accrued Liabilities Cash and cash equivalents Cash and Cash Equivalent Operating lease liabilities Operating Lease, Liability, Current, Statement of Financial Position [Extensible Enumeration] Company Selected Measure Amount Company Selected Measure Amount Canada Other Canada Other [Member] Canada Other Share-Based Compensation Arrangement by Share-Based Payment Award, Non-Option Equity Instruments, Outstanding, Number Share-Based Compensation Arrangement by Share-Based Payment Award, Non-Option Equity Instruments, Outstanding, Number Investments, Debt and Equity Securities [Abstract] Investments, Debt and Equity Securities [Abstract] Depreciation and amortization Depreciation, Depletion and Amortization Total federal Federal Income Tax Expense (Benefit), Continuing Operations Reduction in sales Reduction In Sales The entity's rewards members receive a cash back reward. These rewards are accounted for as a reduction to sales revenue for this revenue stream. Finance lease assets obtained in exchange for new or modified leases Right-of-Use Asset Obtained in Exchange for Finance Lease Liability Unrecognized tax benefits that would impact effective tax rate Unrecognized Tax Benefits that Would Impact Effective Tax Rate 2031 Long-Term Debt, Maturity, Year Five CURRENT ASSETS Assets, Current [Abstract] Operating Lease, Weighted Average Remaining Lease Term Operating Lease, Weighted Average Remaining Lease Term Non-PEO NEO Non-PEO NEO [Member] Foreign Currency Foreign Currency Transactions and Translations Policy [Policy Text Block] Entity Address, Address Line One Entity Address, Address Line One Operating lease assets obtained in exchange for new or modified leases Right-of-Use Asset Obtained in Exchange for Operating Lease Liability Vested and delivered Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Vested in Period, Weighted Average Grant Date Fair Value Provision for income taxes Total provision for income taxes Income Tax Expense (Benefit) Deferred Income/membership fees Deferred Tax Assets, Deferred Income Merchandise costs Cost of Product and Service Sold Award Timing Method Award Timing Method [Text Block] Net change in cash and cash equivalents Cash, Cash Equivalent, Restricted Cash, and Restricted Cash Equivalent, Period Increase (Decrease), Including Exchange Rate Effect and Discontinued Operation Forgone Recovery, Explanation of Impracticability Forgone Recovery, Explanation of Impracticability [Text Block] Total net deferred tax assets Deferred Tax Assets, Net of Valuation Allowance Total deferred tax assets Deferred Tax Assets, Gross Current Operating and Finance Lease Liabilities [Abstract] Current Operating and Finance Lease Liabilities [Abstract] Current Operating and Finance Lease Liabilities KOREA KOREA, REPUBLIC OF NET INCOME NET INCOME Net Income (Loss) Attributable to Parent Long-term Debt, Type [Axis] Long-Term Debt, Type [Axis] Erroneous Compensation Analysis Erroneous Compensation Analysis [Text Block] Balance Sheet Location [Axis] Location, Statement of Financial Position, Balance [Axis] Statement [Table] Statement [Table] Restatement Determination Date: Restatement Determination Date [Axis] Certificates of Deposit [Member] Certificates of Deposit [Member] Release of vested RSUs, including tax effects Stock Issued During Period, Value, Restricted Stock Award, Gross Insurance / Self-Insurance Liabilities Self Insurance Reserve [Policy Text Block] Merchandise inventories Deferred Tax Liabilities, Inventory Leases Lessee, Leases [Policy Text Block] Membership fees Membership [Member] Membership [Member] JAPAN JAPAN Proceeds from short-term borrowings Proceeds from Short-Term Debt REVENUE Revenues [Abstract] Current Current Federal Tax Expense (Benefit) Pension Benefits Adjustments, Footnote Pension Benefits Adjustments, Footnote [Text Block] EX-101.PRE 10 cost-20260830_pre.xml XBRL TAXONOMY EXTENSION PRESENTATION LINKBASE DOCUMENT GRAPHIC 11 cost-20260830_g1.jpg begin 644 cost-20260830_g1.jpg M_]C_X 02D9)1@ ! @$ 8 !@ #_[@ .061O8F4 90 !_]L 0P " 0$! M 0$" 0$! @(" @($ P(" @(%! 0#! 8%!@8&!08&!@<)" 8'"0<&!@@+" D* M"@H*"@8("PP+"@P)"@H*_]L 0P$" @(" @(% P,%"@<&!PH*"@H*"@H*"@H* M"@H*"@H*"@H*"@H*"@H*"@H*"@H*"@H*"@H*"@H*"@H*"@H*"@H*_\ $0@" MO 3< P$B (1 0,1 ?_$ !\ $% 0$! 0$! ! @,$!08'" D* M"__$ +40 (! P,"! ,%!00$ !?0$" P $$042(3%!!A-180'EZ@X2%AH>(B8J2DY25EI>8F9JBHZ2EIJ>H MJ:JRL[2UMK>XN;K"P\3%QL?(R;GZ.GJ\?+S]/7V M]_CY^O_$ !\! ,! 0$! 0$! 0$ ! @,$!08'" D*"__$ +41 (! M @0$ P0'!00$ $"=P ! @,1! 4A,08205$'87$3(C*!"!1"D:&QP0DC,U+P M%6)RT0H6)#3A)?$7&!D:)BH*#A(6&AXB)BI*3E)66EYB9FJ*CI*6FIZBIJK*SM+6V MM[BYNL+#Q,7&Q\C)RM+3U-76U]C9VN+CY.7FY^CIZO+S]/7V]_CY^O_: P# M 0 "$0,1 #\ _?RBBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *** M* "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH M **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ MHHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "B MBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *** M* "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH M **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ MHHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "B MBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ J#5-4TS0 M],N-:UK48+.SLX'GN[NZF6.*")%+,[LQ 50 223@ $FIZ^#_ /@YA^*WBWX0 M_P#!%+XTZUX*OIK6\U:QTS0YKF%B"EI?:G:VUTIQV>WDEB/_ %TH ^;OCK_P M=T_"6+XOZM\*_P!@;]A/Q]^T!;Z"[#4O$.CWLEA;2HK$-/;I%9W?$[1[-[N[\#>))DE^U0 M1L%EDM+A HG\LLH='2.1,_!^A6D6K^/; MC5=:\4ZG%$!+?7*ZE=6T6]NI$<$$48&<#:Q&"QKZ)T?_ ()._L&:#^W/>?\ M!2#2O@@D'Q>O)#(?$EMK%W#%%*UH;265;6*5;=I)8699'>-BQ9F)RQ) /HRB MOQ"_:)_;Q_X*A_\ !7C_ (*S>/?^"9W_ 31_:)A^"_P^^$;7L'C/QS;6^;V MZFLYTM+J8RJIE_X^W,,,$+QAU1I'S6X%[;37L\EM:2"0J)6"9I"FY)( MWV\2 '[;45^$7CO]L[_@L)^T'_P<$_&G_@FE^RC^V,GA#PW<6LUM97^N:)!? M0>#[".UL+J:]M(=@,ER2&@0.Q4?;&.4(61/.O@_^TW_P7L^$/_!5OQQ_P0P\ M._\ !0"T\8:[K6UIJ.OZ5!=6_@O3(19337MK&(]SW!/^CIN+#-XQRA DC / MWJHK\-OV?/VS_P#@J/\ \$A_^"R_@+_@FY_P4#_:IF^.'P^^,ILHO#7B?4X# M]IMYKZ>2UM9XF?,D+"\C\F2W:22,1N'7!(KV?_@J+X&_X*^_%+]L?58=:_X* M;>!/V1/V;-.THGPOXM3Q59PWNI3HL0)M3DU>[M;ZX8M"KA9!$%&-IV*N?FR3YY_P5N_X*G_ +36O?\ M!97Q'_P3\\;_ /!1S5OV1?A!X1TFT^P^,M#\(37]QJUW/96UR))GMRDRK(T\ MD:N)%AC6 %AO+&@#][Z*_,C_ ((>ZA_P4@/QD\8Z9\1/^"EGPK_:F^ $-H%\ M.^-],\213^(;>]*QO&SPP)*T*L#+')!:@\-PUK]H,J#SG>:9)3 M%#&\*"&,LY+CD _$/& M.FSS6VM:W:_O8RVE3ZA;74.\M+;L'@:!X?->/#%ADA"/W)H **_"[Q%^VQ_P M5;_X+H_\%)_BA^R3_P $[/VJ$^!?P=^$%S/:ZIXMTVV)O-0:*X>U2X:2,"=W MGECF:*%)(8UAC) MB3W$"2O93Y1#YL1>^:_J*\*6&LZ7X7TW3/$6J M"^U"VL(8K^]"X^T3*@#R8[;F!/XT ? G_!6;_@XG_9M_X))_M Z+^SI\3_@K MXN\7:QK'A*'7VG\-W%JD5K!+HO^"3?_ <5_L]_ M\%;?VC]7_9M^%'P"\9>%M1T?P9<^(YM1\0W-H\$D,-U:6QB A=FWEKM&&1C" M-[5\1?ML_L[_ /!9WQ9_P<>^)?VQ_P!B']C,ZJ/"'AV+3/ /BWXB636_AU+; M^QUL[B=9WFA263S;J\V1J[-E]Q0JK$?4O_!'_P#X+=_M2?'O]M7QC_P2T_X* M<_ W1/ _QL\+6T]QI]UX<#)::D(4262!XS-,OF&"1;B.:*0Q2Q;B F%,@!^H MLYF6%VMHU>0*?+5W*J6QP"0#@>^#]#7P%^P7_P %\/AO^U[^WEXO_P""+[3P#H?[>WPWNM:O]2CT^STV'7U,LUT\@C2%5QRQ_\ MP=&_\$_?B%\-?$/A+_@N!^QDSZ1\0_A5J-@_CJ6PC^>XM(956SU)E'^L,+%8 M)@<[[>1 V$A;(!]@_P#!7+_@N7\&?^"4OC'P#\(KWX1:W\2O'OQ D9]-\&^& M;Z.*ZAMO,$,4S;D'\,UI#?PQB-7A5\Y@L82J(V/GN9'ER)(FSZ? M_P %O?\ @J=^UOJ__!27P'_P1Y_8A_:*T+X,3ZQ8P7OQ"^*^N7$,!L!+!+=" M!)IOE@2.UB$N5*R3231Q*Z '> ?LA17X9_LJ_P#!17]M;_@FM_P5>^&G[ /[ M2_\ P4/\/?M2_"OXR?9+'1/&MG!/V2?V:-/TT42PW'+O#)%<.'1WE"R1+Y; M[=Q?PW]G?]I__@O'_P %-OV]OVC?V$/V9_V[V\):-X8\::M>MXHUI1%)H>FV M.J75K;Z?:2VT!E7SFFAW$#=MM/O@;DD /Z+J^7/^"I'_ 5S_9-_X),?"FQ^ M('[1.JW]_K&O22Q>%/!>@1I)J.KO&!YCJ'94BA3$O%6F)?Z'J]IN"3PMD,M+_P"":MS??"]/"&JZ2?#LNGZC-?2V9O-:M5NBKWS3,?,$ MTN[)(S(Q&": /TBHK\Z? G[77[2&J?\ !LW/^V9?_%C4)?B>O[/^HZXOC!HX MOM(U&.*&=&LY-,^'7AS15@FU6R2_CTY]2O;D?)-,&CB^TC44BE* MW&-FS<"H_AQQTH ^K/\ @HE^V=H7_!/7]C3QO^V-XE\#7?B6Q\%6UI-/HEC> M+;RW0GO8+4!9'5@N#.&Y!R%([TO_ 3Q_;+T/_@H/^QKX(_;$\->![OPW8^- M;2ZG@T2^O%N);40WD]J0TB*H;)@+< <,!VK\B]7_ &HOC[^V%_P9X_%3XW_M M+_$R^\7>*[S4S;76M:BD:RR10^)[!(U(C55PJC XKW3_ ()S7/[?<7_!L)\) M+/\ X)JVWAM?BA=Z9J,-GJGB>_A@ATNT_MK4FGNHA.K0R3@*JHLN(P9"[9"; M6 /UIKP?_@H/_P %(OV4O^"8_P %E^-_[5?C2YT^QN[EK30]*TRQ:ZO]8NPA M?[/;QC"[MH)+2,D:\;G7(K\&/VW_ -J'_@IK_P $M?!_@[X]Z3_P<*^'_B]\ M2;W6K:+QA\&=+U:VU:/1RT$DLN^/SIHI(%=/)8^5;L?,5D]5Z;_@[4NOV@OC M3\!OV^$=,GT_X:Q6Y_P");K<]C)>7%Z)",LK0SQ0A2Q_U M.<\>V^J:]8:;'X?T.Y6*YC%U! M-,)2Q1QA1%@C'5AS7MO[/'QONFL1> M6D=P()#@9=/,VDX'*G@5^1G_ 4T^)W_ 5'_P""5_\ P0GT'Q=XJ_;NN_$? MQ2O/BWIT=OX[T?38H7BT2YL)FCT_9+$5(5H:31[A8X;%,2HX5+J>[5@X&0+-^0"<\?_P61_X*5?MG?"[] MJKX*?\$6?V2?VJ=.\$>*=7\+Z8_Q.^._BN:W@FW/&ZF1I9!LMB8[>2ZD9 '= MIHHXVCPP8 _:&BOPG^ W_!0_]MW_ ()8_P#!4/X3_L<_M%_\%(_#O[5/PC^- M%U:Z9!XHMKJWFO=!O[BX%K&[/'+-)"4G> LDDLD;PR,RA'!V_NQ0!^.7Q7_X M.WU^#E]K;>,_^"4WQ;LM*T/49+6XUR^OOL]J=LWDJYDDM JAV*A2F0*TB)'V$MU<_9(Y_,8>:"EQL6:&5Y5$4BR( MP.00#]0/B#_P4X_9,^'W[=_@C_@FY<^,+O4?BSXXCN)X="TRP9X]*MHM/N+\ M3WDS%4C#Q6SA$4O(2R$HJ'?7T%7\PO[2?[,7_!0G6_\ @Z+A^"/A']MJ#3/B M[KTM]?\ @WXF'2]R:)IDFC7UU#9F+9\Y2Q5[7.TY+9SWK]1_^"K'@'_@LSXD MU[X7_"[X'_MK^"/@A\(-/\-VL/Q5^-VHZ_:VFH3:JL3^=,4G\MUB/EKY<<,B M%Y)F,C*B@H ?IG7Q9X-_X+->!O&/_!8OQ)_P1_@^!NK0:WX+()([M+>Z^PW,Z&&X$DS)+'- JNJSRQ/')G ?&SJ?@C M_P KM'Q/_P"Q3_\ =3TR@#]TJ_'?Q]_P=R>%/#7QZ\9]ENI+8S^7';,T:,R9&>F<9K]B*_EE_P"">?\ P5!E M_P""6O\ P5=_:R^*H_9?\5_$^'7O%GB"QN;/PK+L;34CUV>8W$S>5( GRXR< M#/>@#])_@1_P=Z?LH>+OCEH_P4_:@_94^(GP<.N7L=K!KWB)HIK6S:1]BR72 ME8I8H=V09%1PN,L Q'ZY@@C(-?S0?MF?M'_ +1G_!VE\:?AK\&?V/?V+W\' M:'\-KVY;Q3XYU[78;K^SH;\P*TD[B.+RXD6V9EA0R23-T V\_=/_ 7\_P"" MH?[2_P"RG\7?@G_P2G_8:^*>E>!?&7Q&L+ ZY\3?$D\*C1=,ENFL+=O-F5D@ M#-!&O"VE6#2R16\\LD2WMQ(2L<,&^*1>6+L4;:C88C\C[;_@H%^W=_P1C_;B M^#O@GXX_\%3O#7[5_P '/BUJHT[Q--%>6]Q>^'I//@BEG4I--+!Y8N8Y$S+Y MF!XYVSAL^=U.* /Z8**_%K_@K)^V/_ ,%$?V&/VP?V#_V6 MM._:WU.>Y\31:)I7Q:U#3;2!(?%=XNIV%K=7#K)$602AY>%VX$G:O0/^#L7] MN[]KC]A/]GWX2^*_V2/CAJO@?4=>\97UIJ]UI44+-=0I:!U1O-1Q@-SQB@#] M9:*_%[_@Y8_X*5_MY?L-_&+]EV']C_XMW^F2^*K2\N=:\.QV\,EOXAN(KC3O M*@G#+NV.97C(1D.)3R#@C2^+/PR_X+:?\$V/^":7[3_[5G[7'_!2%_&/BV?P MOH=UX%3P_)YD7AR_?4XUOV1)[5$C&R2.*-8AY94R$HI"4 ?L?17\_?PEO_\ M@X!_;R_X)#2_\%)K'_@IQ)X&TKP+X2UG4O#WA?0])\K4/%T.E27)O+N^O8BF MR9WMYXHHMCQ$0QY5-S.?:OV:/^"X7[:GBO\ X-I_B%_P4 O;:T\1_%[X=Z]) MX5_X2"32H_+E+7-@BZI/;QJ(R\,&H!F 4(SP!G7:7H _9JBOYK_V:?VFOVY? MVF_A#X?^.?P!_P"#FW2U^.NH7%M)J/P1^)UK'H&G0323 /;137K&TNV0$MMB MMBD@^5<%0#_0_P#L^3?'"?X'^%9/VEH?#:>/_P"P[<>+O^$/NI9M+>^" 2O; M-,B/Y;'Y@K+\N[;E@-Q .QHHHH **** "BBB@ HHHH **** "BBB@ HHHH * M*** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HH MHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB M@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ KQC_@HA^QU MX:_;_P#V*?B+^R!XIU06$/C;0&MK/4FCWBROHI$N+.X*]66.YAA)? M#L\L=LT=Q.TLD4%R+>6&[MY)I'F5E*R1M,ZNA)"I[S_P1HB_X*^?\%"_^"H/ MB7_@J!^TNOC_ .#OP5>T=-(^&%WJE[:Z=KI%L;:SMTLYMGVB.$$W$EX8U$DP MPG#.L?[244 ?@)X[T/\ :V_X-XO^"T?Q=_;=C_9,\5_%'X#_ !MN-1N[O5_! M]H\SZ;]NO5OVC9E5E@G@N/,C5)BB30ON5]P.RY\(O"/[6'_!P?\ \%J_A;_P M4"UO]E;Q/\*?@1\#7TZYTJ_\7VKQ3:K+87DE_#&A956>::[9!(L6Z.&&/YG+ ME1)^]]% 'XH_L4?!KXOZ-_P=R_'CXL:Q\*?$EIX6OO"^H)8^);G0KB/3[AC: M:4 J7#((W)*L,!C]T^AH\%_!GXOP_P#!YUXN^,4WPI\2IX1E\+Q)%XI;0K@: M:[?\(991;1<[/*)\Q2F-WW@5ZC%?M=10!^*7Q"^#7Q?N/^#S?P+\8;?X4^)7 M\(P>%I4G\4IH5P=-C;_A#=0BVMIQ7RS%^U#\=?V-O^#I# M]HG]H7X*_LYZ]\4[30AJ1\>^%/"R!]2.@O'IZ37-LF"9'AG-K(4 .45\[%W2 M)_2G7YY?LJ_\$;?B_P# #_@M[\6_^"INO?%OPW?>&/B)HU_9:?X9LX+@7]JT M[V+*TC,HC('V1\X)^\/>@#X+^'-[^T=_P<'_ /!=GX1_MI>'/V5?&'PY^"_P M';3+E]8\8V#0O/+I][+J"1EL>6]S-=O%&88F?RXH]['J#YA^T+I6C_ /_@OM M\9?BM_P6>_8/^*?QQ\':_?Z@GP;AT'0I=4M#:-=*^EK! TL4%S&EF# T7F$1 MRERT;/EE_I0HH _ '_@A/\-/C%\/?^#AWXF_$_Q_^P;XC^!GACQW\.-3'@_P MI)X3:TT_1[>>33+VTM"\,2V\4OV2 EXAM*2AT95=2H]0_P"#7WX+?%WX:?\ M!03]M#Q'\2/A/XD\/V>K^*(FT>^US0KBTBO4_M;56)A>5%$HPR'*D\,I[BOV MNHH _%+_ (++?!KXO^,/^#E_]CCXD>$OA3XEU3P[H]EX8&K:]IVA7$]E9%/$ M6H.XFG1#''M1E8[B,!@3P:9_P6B^.$_AG]NN?P7_ ,%7?^"-^F?%G]G(:1)% MX,^+7PR\-7TOB:W5PDD<;ZA'=Q+#Y;^>DEH7A+$B9&*C:_[844 ?SK?\$%?V M/O$NO_\ !;8?M4L"N[ABBG=\)S?M7_ /!M+_P54^-?QC\4_L@^,/B7\ OC)?W%Y9>) M?!EFTQLXGNY;NV#2!3&D\'GSP/#,8O,'[U&V@!OZ#** /PA_9#^%_P"UO_P7 M+_X+D>$O^"KOQ,_9A\1?"CX,?"+3[2'PJ/%EL\-UJILVN)K2&(NB>>[7EU)/ M(\:F*)%\K>S[2W8_\$^_@S\7]!_X.S/VC/BKKOPI\267A?4/"VK)I_B2[T*X MCL+EF.D;5CN&01N3L? #'.T^AK]K:* /Q1_:0^#/Q@U'_@\-^$WQ"[)IC:Q?:YKJT#2;3&D\(N) MX)()C$7_ -:C;0-W:_L6?"?]KG_@MO\ \%R?#?\ P5M^*O[,?B'X4?!OX5:? M;P^$H?%5L\-UJIM5N&M(8BZ)Y[&ZN9;B21%,4:KY6]FPS?NW10!^*/PG^#7Q M@M/^#ROXA?&"Z^%/B6/PE<>%U2#Q3)H5PNG2-_PB>G1[5N2GE,?,5DP&^\I' M48K]KJ** /R#_;)_X*R?\%5?^"5'_!2[Q-=?M5_ 'Q!\4OV7M=M9V\"7W@#P MG LFGB1HY(A)=+'\UQ"5EMVAGDC\Q6$RYP,^=_\ !'SX!_M1_P#!1?\ X+@> M.?\ @N?\8?V>]=^%G@&+3Y+3P+I7B2V>&ZU60Z7'I,.Q753)&MHDDDLP&SSG M5$+X8I^X%% 'YW^$O^#7'_@D-X)^*.F?&'0/A/XKCUS2-?AUFRGD\%O$WC;_@DA\>_"G@SPY?ZOJE_P" ;B*QTW3+ M-[BXN'+QX1(XP6=O8 FOJVB@#\Z?^#6'X>^/OAA_P1\\(^$?B7X'UCP[JT7B MO77ETS7=,EM+A%:]"O@QX4FL]7U7XK?$CP]>V&J: M3J%M*TXFMI(;J2U:7>L"0VZ^:^Y6E=E3(3R#]KG1M.^!7_!P3\4_C#_P62_8 M<^*/QO\ ASK7VJ+X06WAW19=2LQ;M+"VFB"%I8H+A([=989(/,PLTCNT;-S7 M](]% '\^_P#P18^&_P 6_!O_ <:>+?B_P"*OV /$OP)\'>._ .HCP9X4D\( M-9V.D6LEO93VD#F");>WF:WM6=XOE*RLZ$;LBO6?^#;KX*_%SX=_\%9?VU_% M_P 0OA/XDT+3=8\3WK:-J>LZ%<6L%\C:]?/F&21%64%2K94G@@]#7[7T4 %? MC#_P7[_X)P?MI?#']O/X?_\ !;K_ ()Q?#^?QAXI\&+9CQMX.TZS>YNYS:!H MTN4MX_WEU#+:N;6:.+]XB(K*"&=H_P!GJ* /Y^?VQ?\ @X:_X*#?\%)?@%>_ ML/?L1?\ !,KXG>#OB'XS6+3O$.MVEQ=75QI<)93-';%+6$V^_&UKF9D$49K/?ZO+J=W=W% MOJUO?R:=!-(6>X,-M$T,?+&62/Y?]8 /U3HH _G2^"?_ 4I_:7^*?\ P0PU M[_@DI\(O^";7Q>U#XD^&?AGJVB^*O$-QH30Z-IND0^?//.S.!-]J-L&B2U*! MGF90C.2$.WX#^ 7QV@_X,V_&GP@G^"OBU/%LWCR*6'PN_ARZ&HNG_"4V$FX6 MWE^:1L5GR%QM!/05_0E10!^/?B[X1_%:7_@SSB^$<7PQ\0MXK'PMLH3X8719 MSJ/FC78G*?9MGF;@H+8VYQSTJ/\ 9O\ A%\5]._X,[]1^$6H?##Q#!XL;X8^ M*X5\,3:+.NHF1]?U!T3[,4\W.1HT S(VU5 M!+"O+/@[_P %*?VE_BU_P0NUW_@DO\(?^";7Q>U#XD>&/AEJFB^*_$5SH30Z M-IND0>=/-.S,!,;MK93%':E SS,H1G)"'^BVB@#\#O@7\"OC=8_\&<'Q$^$- M[\'/%4/BRXUN=K?PO+X>N5U&4'Q-92 K;%/-8;%+<+]T$]!7,?M5?L]_M\:M M_P &G'P"^&_P0^'7C2)M'U^]G^*WA#3=,N8M3?2O[0U5HS-;!1*]NLKP22)M M/!CD(VH67^ABB@#^5G]M71?V??VH?^":'ACX=?\ !+W_ ((F?$CPI?\ A'4= M*O\ XK?%+5_ HFNVF6"2T-A;7H:6YOEEN;@2N!Y>U848P@+] N+/_2& M>YALK>-9T42+;QRWTF5SL<0'@D&O4_\ @XS_ &!OB%\/?^"GGPZ_X*H7'['] M]\=?@^VE6>G?%3P5IUE+> M$-4U[6+W_A'/L>DZ+I\EU/O">IZ'J]EIVL"\TK6+"2VN8"VMZ@ZAXI &7*LK#(&0P/0U M]M44 ?@A^T-X)_:\_P"""7_!^$[5YIM M.^WSP7ES'(45A;3Q7L&]/- CFA?:'#%O+IZ=I?[57_!R!_P5X^#_ .U+;_LG M>+/A=\ /@C,[1H9-4-O>"]>)&*A99IY$AA,<)=88T,C/E@I_?NB@# M\ /^"N7B_P"+O_!._P#X.9/ O_!2;Q!^S-XU\9^!H_"(974PRR(JR90AAM)R.>E?N)10 M!_/]_P %%2V0P)_> MFB@#^>?]GG4_V1?V\_VUOA]\+?\ @G3_ ,&\.BV/@%9H9/B5XX^+?AJ]L6T- MA,IDEAFM;MH%\I%DV(Y:6>0J D>TY[/_ (.*H_C!^RM_P72_9N_X*0Q?L_\ MBSQAX"\*>%M(AO)_#>FR2^;=V>K:C+-:"0*4CF,5W"R!R-^X@?=8C]Y:* /P M4_X.(K#]H_X_V'[&O_!83X+_ ++OC&^T+PQ!!K/B7PFVF2OJ&@2_:[+4+>&\ M2-"T2N8Y8C+MV*R#.-Z!O%/^#@/]LC]IS_@LQ^SY\,O'O[/'_!.3XR>'OASX M3\1W*3:SXF\,NUWJVJ75MPEM;VWF%K:&.WD#7&2I>9%(0@!OZ5J* /P^_P"# MEGX(_?ME?L.:GX!^$?B;7[+1M5_XG=SHV@W%U%8+_:.D',[1HPB&U'/S M8X5O0U]Z_P#!PCX/\6^/O^"-_P /^"%/A?]O7]G+_ (-\ MOBL/@7^R18^)OB-%\6-5N8?AE\4= NH(]=TR33M+CN$6W=H6G)C$FU"=LOEM M&,LP%?N-10!_*3^U-+_P3R_:B_9RE\$>#_\ @BA\;/AI^U_=P16USI7PV\+7 MMIX:&I"91(Z:?+<2R10LH77GS:;;RWD\UI8N^3EH+:2&$J"0GE[ 2$!KZMHH M **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ MHHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "B MBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *** M* "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH M **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ MHHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "B MBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *** M* "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH M **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **\H_;;_;$^ M$O[!O[,_B?\ :>^,UY)_9?A^T'V33+4@W6KWTAV6UA;+_'--*511T&2S856( M_-#_ ((7>,?VV?$G_!9/]IR3]NWQ#.OC;4_AQX:UV]\)17DC6?AE+](KJWTR M*-CM1K:WFB@<@9+QN2SDEV /V&HK\KOB1X)UK_@M#_P6 ^,/[(OQ9^*OB_2O MV?\ ]FCP]HUKJ?@[P=XBGTI?%/B/4XFG\Z]F@99'CA6.>,1@C:T"LI7?)OUO MV-$\;_\ !+K_ (+'G_@EE8_&'Q7XM^#'Q:^%\OC#X5V'C/6I-1N_"NJ6DTJW M>G0W$I+M;-##-+M).,Q=6\UW /T[HK\B/V4OV<-+_P""_GQW^/'[5O[8GQ5\ M>3?"[P/\5;_P%\&/AWX6\8W>D:?90:>L9EU:1;9U:6YF\Z)@Y/RGS%.Y5C"> MQ?\ !&_XK?&3X&?MA?M$?\$@OC=\8=>\?V_P8NM*UOX7>+?%5X;G4Y_#FI6Z MS+9W,YP9C;&2! Y')DD VHB(H!^BM%%% !1110 4444 %%%% !1110 4444 M%%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4 M444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !11 M10 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% M !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 M%%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4 M444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !11 M10 4444 ?D%_P4.^/7[2^L_\%AM)UGXV?\$S/V@_BG\$O@'#;ZA\+=+^&?@& M6_TW7_%4]M%*VMW4KE(Y/L@E:&"-=^R6-GW*2Z-YE^P=_P %&_'FN_\ !PK\ M@:CX=O/!X6_P#!<0BL[?\ M+5X]_\ HUF1^^$F M3^[^;%?N57@/PG_X)^^ OA+_ ,% OBM_P4(TKQUJ]UK_ ,6/#ND:1JN@W$<0 ML[*/3X(H8WB(7>681 MN)&2<4 ?)O_!)=!\//^"VG_!0OX4^)6$&KZMXD\(> M(]-ADX:YL9;.\1G]@_X)X_\ !.KX,?\ !.7X5:MX M$^&NO:]XFU_Q7KLNN^/?'WB^^%UJ_B75)?OW-S+@<#)"H!A;_&"_ M_;P^#7PPUSXH:U\:O!E[;:+I[W$EK:^&&220C@ %B0.2#SV!KZ8KRC]N?_DT M?Q[_ -@%_P#T-: .L\%W/C_7_!VDZ[>:W9>;>Z9!/+BT(&YXU8\9]36G]B\; M_P#0;LO_ &/^-1?"[_DF?AW_L!6G_HE*W: ,?[%XW_Z#=E_X#'_ !H^Q>-_ M^@W9?^ Q_P :V** ,?[%XW_Z#=E_X#'_ !H^Q>-_^@W9?^ Q_P :V** ,?[% MXW_Z#=E_X#'_ !H^Q>-_^@W9?^ Q_P :V** ,?[%XW_Z#=E_X#'_ !H^Q>-_ M^@W9?^ Q_P :V** ,?[%XW_Z#=E_X#'_ !JGJ,_C2PN[2V;6+4FZF**5MN!Q MGFNDK'\2_P#(7T?_ *_3_P"@F@ ^Q>-_^@W9?^ Q_P :/L7C?_H-V7_@,?\ M&MBB@#'^Q>-_^@W9?^ Q_P :/L7C?_H-V7_@,?\ &MBB@#'^Q>-_^@W9?^ Q M_P :/L7C?_H-V7_@,?\ &MBB@#'^Q>-_^@W9?^ Q_P :/L7C?_H-V7_@,?\ M&MBB@#'^Q>-_^@W9?^ Q_P :/L7C?_H-V7_@,?\ &MBB@#'^Q>-_^@W9?^ Q M_P :/L7C?_H-V7_@,?\ &MBB@#'^Q>-_^@W9?^ Q_P :/L7C?_H-V7_@,?\ M&MBB@#'^Q>-_^@W9?^ Q_P :/L7C?_H-V7_@,?\ &MBB@#'^Q>-_^@W9?^ Q M_P :/L7C?_H-V7_@,?\ &MBB@#'^Q>-_^@W9?^ Q_P :/L7C?_H-V7_@,?\ M&MBB@#'^Q>-_^@W9?^ Q_P :/L7C?_H-V7_@,?\ &MBB@#'^Q>-_^@W9?^ Q M_P :IZ+/XTU>T:YCUBU4+,Z8>VY^4X[5TE8_@?\ Y!$O_7[-_P"A4 'V+QO_ M -!NR_\ 8_XT?8O&_\ T&[+_P !C_C6Q10!C_8O&_\ T&[+_P !C_C1]B\; M_P#0;LO_ &/^-;%% &/]B\;_P#0;LO_ &/^-'V+QO_ -!NR_\ 8_XUL44 M 8_V+QO_ -!NR_\ 8_XT?8O&_\ T&[+_P !C_C6Q10!C_8O&_\ T&[+_P ! MC_C1]B\;_P#0;LO_ &/^-;%% &/]B\;_P#0;LO_ &/^-'V+QO_ -!NR_\ M 8_XUL44 8_V+QO_ -!NR_\ 8_XT?8O&_\ T&[+_P !C_C6Q10!C_8O&_\ MT&[+_P !C_C1]B\;_P#0;LO_ &/^-;%% &/]B\;_P#0;LO_ &/^-'V+QO_ M -!NR_\ 8_XUL44 8_V+QO_ -!NR_\ 8_XT?8O&_\ T&[+_P !C_C6Q10! MC_8O&_\ T&[+_P !C_C1]B\;_P#0;LO_ &/^-;%% '-ZC/XTL+NTMFUBU)N MIBBE;;@<9YJY]B\;_P#0;LO_ &/^-'B7_D+Z/\ ]?I_]!-;% &/]B\;_P#0 M;LO_ &/^-'V+QO_ -!NR_\ 8_XUL44 8_V+QO_ -!NR_\ 8_XT?8O&_\ MT&[+_P !C_C6Q10!C_8O&_\ T&[+_P !C_C1]B\;_P#0;LO_ &/^-;%% &/ M]B\;_P#0;LO_ &/^-'V+QO_ -!NR_\ 8_XUL44 8_V+QO_ -!NR_\ 8_X MT?8O&_\ T&[+_P !C_C6Q10!C_8O&_\ T&[+_P !C_C1]B\;_P#0;LO_ &/ M^-;%% &/]B\;_P#0;LO_ &/^-'V+QO_ -!NR_\ 8_XUL44 8_V+QO_ -!N MR_\ 8_XT?8O&_\ T&[+_P !C_C6Q10!C_8O&_\ T&[+_P !C_C1]B\;_P#0 M;LO_ &/^-;%% &/]B\;_P#0;LO_ &/^-'V+QO_ -!NR_\ 8_XUL44 8_V M+QO_ -!NR_\ 8_XT?8O&_\ T&[+_P !C_C6Q10!S>BS^--7M&N8]8M5"S.F M'MN?E..U7/L7C?\ Z#=E_P" Q_QH\#_\@B7_ *_9O_0JV* ,?[%XW_Z#=E_X M#'_&C[%XW_Z#=E_X#'_&MBB@#'^Q>-_^@W9?^ Q_QH^Q>-_^@W9?^ Q_QK8H MH Q_L7C?_H-V7_@,?\:/L7C?_H-V7_@,?\:V** ,?[%XW_Z#=E_X#'_&C[%X MW_Z#=E_X#'_&MBB@#'^Q>-_^@W9?^ Q_QH^Q>-_^@W9?^ Q_QK8HH Q_L7C? M_H-V7_@,?\:/L7C?_H-V7_@,?\:V** ,?[%XW_Z#=E_X#'_&C[%XW_Z#=E_X M#'_&MBB@#'^Q>-_^@W9?^ Q_QH^Q>-_^@W9?^ Q_QK8HH Q_L7C?_H-V7_@, M?\:/L7C?_H-V7_@,?\:V** ,?[%XW_Z#=E_X#'_&C[%XW_Z#=E_X#'_&MBB@ M#'^Q>-_^@W9?^ Q_QJGJ,_C2PN[2V;6+4FZF**5MN!QGFNDK'\2_\A?1_P#K M]/\ Z": #[%XW_Z#=E_X#'_&C[%XW_Z#=E_X#'_&MBB@#'^Q>-_^@W9?^ Q_ MQH^Q>-_^@W9?^ Q_QK8HH Q_L7C?_H-V7_@,?\:/L7C?_H-V7_@,?\:V** , M?[%XW_Z#=E_X#'_&C[%XW_Z#=E_X#'_&MBB@#'^Q>-_^@W9?^ Q_QH^Q>-_^ M@W9?^ Q_QK8HH Q_L7C?_H-V7_@,?\:/L7C?_H-V7_@,?\:V** ,?[%XW_Z# M=E_X#'_&C[%XW_Z#=E_X#'_&MBB@#'^Q>-_^@W9?^ Q_QH^Q>-_^@W9?^ Q_ MQK8HH Q_L7C?_H-V7_@,?\:/L7C?_H-V7_@,?\:V** ,?[%XW_Z#=E_X#'_& MC[%XW_Z#=E_X#'_&MBB@#'^Q>-_^@W9?^ Q_QH^Q>-_^@W9?^ Q_QK8HH Q_ ML7C?_H-V7_@,?\:IZ+/XTU>T:YCUBU4+,Z8>VY^4X[5TE8_@?_D$2_\ 7[-_ MZ%0 ?8O&_P#T&[+_ ,!C_C1]B\;_ /0;LO\ P&/^-;%% &/]B\;_ /0;LO\ MP&/^-'V+QO\ ]!NR_P# 8_XUL44 8_V+QO\ ]!NR_P# 8_XT?8O&_P#T&[+_ M ,!C_C6Q10!C_8O&_P#T&[+_ ,!C_C1]B\;_ /0;LO\ P&/^-;%% &/]B\;_ M /0;LO\ P&/^-'V+QO\ ]!NR_P# 8_XUL44 8_V+QO\ ]!NR_P# 8_XUKQAQ M&HE8%MHW$#@FEHH **** "BBB@ HHHH **** "BBB@ HHHH *\H_;G_Y-'\> M_P#8!?\ ]#6O5Z\H_;G_ .31_'O_ & 7_P#0UH [KX7?\DS\._\ 8"M/_1*5 MNUA?"[_DF?AW_L!6G_HE*W: "BBB@ HHHH **** "BBB@ K'\2_\A?1_^OT_ M^@FMBL?Q+_R%]'_Z_3_Z": -BBBB@ HHHH **** "BBB@ HHHH **** "BBB M@ HHHH **** "BBB@ HHHH *Q_ __((E_P"OV;_T*MBL?P/_ ,@B7_K]F_\ M0J -BBBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HH MHH Q_$O_ "%]'_Z_3_Z":V*Q_$O_ "%]'_Z_3_Z":V* "BBB@ HHHH **** M"BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH Q_ __ "")?^OV;_T* MMBL?P/\ \@B7_K]F_P#0JV* "BBB@ HHHH **** "BBB@ HHHH **** "BBB M@ HHHH **** "BBB@ K'\2_\A?1_^OT_^@FMBL?Q+_R%]'_Z_3_Z": -BBBB M@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *Q_ _ M_((E_P"OV;_T*MBL?P/_ ,@B7_K]F_\ 0J -BBBB@ HHHH **** "BBB@ HH MHH **** "BBB@ HHHH **** "BBB@ HHHH **** "O*/VY_^31_'O_8!?_T- M:]7KRC]N?_DT?Q[_ -@%_P#T-: .Z^%W_),_#O\ V K3_P!$I6[6%\+O^29^ M'?\ L!6G_HE*W: "BBB@ HHHH **** "BBB@ K'\2_\ (7T?_K]/_H)K8K'\ M2_\ (7T?_K]/_H)H V**** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ M HHHH **** "BBB@ K'\#_\ ((E_Z_9O_0JV*Q_ _P#R")?^OV;_ -"H V** M** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@#'\2 M_P#(7T?_ *_3_P"@FMBL?Q+_ ,A?1_\ K]/_ *":V* "BBB@ HHHH **** " MBBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH Q_ _\ R")?^OV;_P!" MK8K'\#_\@B7_ *_9O_0JV* "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ M HHHH **** "BBB@ K'\2_\ (7T?_K]/_H)K8K'\2_\ (7T?_K]/_H)H V** M** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ K'\ M#_\ ((E_Z_9O_0JV*Q_ _P#R")?^OV;_ -"H V**** "BBB@ HHHH **** " MBBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *\H_;G_P"31_'O_8!? M_P!#6O5Z\H_;G_Y-'\>_]@%__0UH [KX7?\ ),_#O_8"M/\ T2E;M87PN_Y) MGX=_[ 5I_P"B4K=H **** "BBB@ HHHH **** "L?Q+_ ,A?1_\ K]/_ *": MV*Q_$O\ R%]'_P"OT_\ H)H V**** "BBB@ HHHH **** "BBB@ HHHH *** M* "BBB@ HHHH **** "BBB@ K'\#_P#((E_Z_9O_ $*MBL?P/_R")?\ K]F_ M]"H V**** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "B MBB@#'\2_\A?1_P#K]/\ Z":V*Q_$O_(7T?\ Z_3_ .@FMB@ HHHH **** "B MBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** ,?P/\ \@B7_K]F M_P#0JV*Q_ __ "")?^OV;_T*MB@ HHHH **** "BBB@ HHHH **** "BBB@ MHHHH **** "BBB@ HHHH *Q_$O\ R%]'_P"OT_\ H)K8K'\2_P#(7T?_ *_3 M_P"@F@#8HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH M **** "L?P/_ ,@B7_K]F_\ 0JV*Q_ __((E_P"OV;_T*@#8HHHH **** "B MBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ KRC]N?\ MY-'\>_\ 8!?_ -#6O5Z\H_;G_P"31_'O_8!?_P!#6@#NOA=_R3/P[_V K3_T M2E;M87PN_P"29^'?^P%:?^B4K=H **** "BBB@ HHHH **** "L?Q+_R%]'_ M .OT_P#H)K8K'\2_\A?1_P#K]/\ Z": -BBBB@ HHHH **** "BBB@ HHHH M**** "BBB@ HHHH **** "BBB@ HHHH *Q_ _P#R")?^OV;_ -"K8K'\#_\ M((E_Z_9O_0J -BBBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** M "BBB@ HHHH Q_$O_(7T?_K]/_H)K8K'\2_\A?1_^OT_^@FMB@ HHHH **** M "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** ,?P/_R")?\ MK]F_]"K8K'\#_P#((E_Z_9O_ $*MB@ HHHH **** "BBB@ HHHH **** "BB MB@ HHHH **** "BBB@ HHHH *Q_$O_(7T?\ Z_3_ .@FMBL?Q+_R%]'_ .OT M_P#H)H V**** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** M "BBB@ K'\#_ /((E_Z_9O\ T*MBL?P/_P @B7_K]F_]"H V**** "BBB@ H MHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *\H_;G_Y M-'\>_P#8!?\ ]#6O5Z\H_;G_ .31_'O_ & 7_P#0UH [KX7?\DS\._\ 8"M/ M_1*5NUA?"[_DF?AW_L!6G_HE*W: "BBB@ HHHH **** "BBB@ K'\2_\A?1_ M^OT_^@FMBL?Q+_R%]'_Z_3_Z": -BBBB@ HHHH **** "BBB@ HHHH **** M"BBB@ HHHH **** "BBB@ HHHH *Q_ __((E_P"OV;_T*MBL?P/_ ,@B7_K] MF_\ 0J -BBBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB M@ HHHH Q_$O_ "%]'_Z_3_Z":V*Q_$O_ "%]'_Z_3_Z":V* "BBB@ HHHH * M*** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH Q_ __ "")?^OV M;_T*MBL?P/\ \@B7_K]F_P#0JV* "BBB@ HHHH **** "BBB@ HHHH **** M"BBB@ HHHH **** "BBB@ K'\2_\A?1_^OT_^@FMBL?Q+_R%]'_Z_3_Z": - MBBBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH * MQ_ __((E_P"OV;_T*MBL?P/_ ,@B7_K]F_\ 0J -BBBB@ HHHH **** "BBB M@ HHHH **** "BBB@ HHHH **\]_:6_:P_9M_8Y^'3?%G]J+XU>'_ _A\3B" M/4=?OUB%Q,02(84Y>:0@,=D:LV%)Q@$USO[)7_!0G]BC]NW3[_4/V1_VDO#' MC@Z6JMJ=EI5X5O+-&.%>6VE"31H3D!V0*2" 20: /9**\E_:S_;M_8__ &%? M"]EXP_:W_:"\.^!K+4Y7CTM=8NB;B^9 "_D6\8:6;;N7<40A=RYQD9T_V8_V MO/V9/VS_ (?'XI_LL?&[P_XYT*.X-O<7N@WPD-M, #Y4T9P\#X(;9(JM@@XP M0: /1Z*\&_:T_P""GW[ /["VOZ?X2_:P_:H\+>#=8U2$366C7MQ)->-"6*B9 MH($DDCB)# 2.H0E6 /!QZC\&_C7\(OVA_AQIOQ>^!7Q)T7Q;X7UB(R:;KN@: M@ES;3@$JP#H2-RL"K*<,K @@$$4 =11110 5Y1^W/_R:/X]_[ +_ /H:UZO7 ME'[<_P#R:/X]_P"P"_\ Z&M '=?"[_DF?AW_ + 5I_Z)2MVL+X7?\DS\._\ M8"M/_1*5NT %%%% !1110 4444 %%%% !6/XE_Y"^C_]?I_]!-;%8_B7_D+Z M/_U^G_T$T ;%%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 % M%%% !1110 5C^!_^01+_ -?LW_H5;%8_@?\ Y!$O_7[-_P"A4 ;%%%% !111 M0 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110!C^)?\ D+Z/ M_P!?I_\ 036Q6/XE_P"0OH__ %^G_P!!-;% !1110 4444 %%%% !1110 44 M44 %%%% !1110 4444 %%%% !1110 4444 8_@?_ )!$O_7[-_Z%6Q6/X'_Y M!$O_ %^S?^A5L4 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 44 M44 %%%% !6/XE_Y"^C_]?I_]!-;%8_B7_D+Z/_U^G_T$T ;%%%% !1110 44 M44 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 5C^!_^01+_ -?L MW_H5;%8_@?\ Y!$O_7[-_P"A4 ;%%%% !1110 4444 %%%% !1110 4444 % M%%% !1110!\M_M6_\$[OV??C7^V'X(_X*%?M->-;C4]#^"W@_4?[+\#:[9PW M&A6<[;Y9M8=&4DSI&%Z[@/L\+ !D!/PM\%OCO^R[_P %$O\ @X>^%_Q[_P"" M7M%.T;&7RRH 0[B(DK M[@^/_P#P5&^&?[./_!1/P3^P'^T-\/H_#GAWXF^";G4?"WQ1US6HXM*O]2CF M,;Z,TOC=X3PI("J2M-;S'S -P M6Z=0<$T^;PIX5_8A_P"#FWP9X5^!?AZT\.^&OVE_@EJ+^-/#VE0+!9W.MZ6] MSQ\.)\?=/ M\,^-_AC?:USMM;U1[FV33_.0E&E$,X[T[0?B)X4\-6B[+71KJ[MH%OUMXQ\L222W" (H"JEO$J@!:SO\ @WW^)7PY M_9'U;]I7_@FU\;/&^E^&O&_P\^/FN:WI^F:Y?1VCZCX>ODMVM+^ 2E?-C81E MR5SL6:$MC>,W_P#@E3K>C?M>_P#!:_\ ;"_X*#?"K4(]4^&]IIV@?#OPIXFM M6WVNLW5I;0-?M;R#Y94CEMT(=259+B)@2&H _3RBBB@ KRC]N?\ Y-'\>_\ M8!?_ -#6I_BM^R5\-?C%XN?QIXHU_P 46]V\"0F/2?$^* /I; MX7?\DS\._P#8"M/_ $2E;M<7\,_!>E2_#?P_(US>9;0[0G%TV/\ 4I6Y_P ( M/I'_ #\WO_@6U &Q16/_ ,(/I'_/S>_^!;4?\(/I'_/S>_\ @6U &Q16/_P@ M^D?\_-[_ .!;4?\ "#Z1_P _-[_X%M0!L45C_P#"#Z1_S\WO_@6U'_"#Z1_S M\WO_ (%M0!L45C_\(/I'_/S>_P#@6U'_ @^D?\ /S>_^!;4 ;%8_B7_ )"^ MC_\ 7Z?_ $$T?\(/I'_/S>_^!;5F:YX5TZUU'388Y[DB>Y*N6N&) V]O2@#J MZ*Q_^$'TC_GYO?\ P+:C_A!](_Y^;W_P+:@#8HK'_P"$'TC_ )^;W_P+:C_A M!](_Y^;W_P "VH V**Q_^$'TC_GYO?\ P+:C_A!](_Y^;W_P+:@#8HK'_P"$ M'TC_ )^;W_P+:C_A!](_Y^;W_P "VH V**Q_^$'TC_GYO?\ P+:C_A!](_Y^ M;W_P+:@#8HK'_P"$'TC_ )^;W_P+:C_A!](_Y^;W_P "VH V**Q_^$'TC_GY MO?\ P+:C_A!](_Y^;W_P+:@#8HK'_P"$'TC_ )^;W_P+:C_A!](_Y^;W_P " MVH V**Q_^$'TC_GYO?\ P+:C_A!](_Y^;W_P+:@#8HK'_P"$'TC_ )^;W_P+ M:C_A!](_Y^;W_P "VH V**Q_^$'TC_GYO?\ P+:C_A!](_Y^;W_P+:@#8K'\ M#_\ ((E_Z_9O_0J/^$'TC_GYO?\ P+:LSPKX5T[4-.DFFGN01_P#@6U &Q16/_P (/I'_ #\WO_@6U'_"#Z1_S\WO_@6U &Q16/\ \(/I M'_/S>_\ @6U'_"#Z1_S\WO\ X%M0!L45C_\ "#Z1_P _-[_X%M1_P@^D?\_- M[_X%M0!L45C_ /"#Z1_S\WO_ (%M1_P@^D?\_-[_ .!;4 ;%%8__ @^D?\ M/S>_^!;4?\(/I'_/S>_^!;4 ;%%8_P#P@^D?\_-[_P"!;4?\(/I'_/S>_P#@ M6U &Q16/_P (/I'_ #\WO_@6U'_"#Z1_S\WO_@6U &Q16/\ \(/I'_/S>_\ M@6U'_"#Z1_S\WO\ X%M0!L45C_\ "#Z1_P _-[_X%M1_P@^D?\_-[_X%M0!L M45C_ /"#Z1_S\WO_ (%M1_P@^D?\_-[_ .!;4 ;%%8__ @^D?\ /S>_^!;4 M?\(/I'_/S>_^!;4 '@?_ )!$O_7[-_Z%6Q7*>%?"NG:AITDTT]R"+F10$N&4 M8#5I_P#"#Z1_S\WO_@6U &Q16/\ \(/I'_/S>_\ @6U'_"#Z1_S\WO\ X%M0 M!L45C_\ "#Z1_P _-[_X%M1_P@^D?\_-[_X%M0!L45C_ /"#Z1_S\WO_ (%M M1_P@^D?\_-[_ .!;4 ;%%8__ @^D?\ /S>_^!;4?\(/I'_/S>_^!;4 ;%%8 M_P#P@^D?\_-[_P"!;4?\(/I'_/S>_P#@6U &Q16/_P (/I'_ #\WO_@6U'_" M#Z1_S\WO_@6U &Q16/\ \(/I'_/S>_\ @6U'_"#Z1_S\WO\ X%M0!L45C_\ M"#Z1_P _-[_X%M1_P@^D?\_-[_X%M0!L45C_ /"#Z1_S\WO_ (%M1_P@^D?\ M_-[_ .!;4 ;%%8__ @^D?\ /S>_^!;4?\(/I'_/S>_^!;4 ;%8_B7_D+Z/_ M -?I_P#031_P@^D?\_-[_P"!;5F:YX5TZUU'388Y[DB>Y*N6N&) V]O2@#JZ M*Q_^$'TC_GYO?_ MJ/\ A!](_P"?F]_\"VH V**Q_P#A!](_Y^;W_P "VH_X M0?2/^?F]_P# MJ -BBL?_A!](_Y^;W_P+:C_ (0?2/\ GYO?_ MJ -BBL?\ MX0?2/^?F]_\ MJ/^$'TC_GYO?\ P+:@#8HK'_X0?2/^?F]_\"VH_P"$'TC_ M )^;W_P+:@#8HK'_ .$'TC_GYO?_ +:C_A!](_Y^;W_ ,"VH V**Q_^$'TC M_GYO?_ MJ/\ A!](_P"?F]_\"VH V**Q_P#A!](_Y^;W_P "VH_X0?2/^?F] M_P# MJ -BBL?_A!](_Y^;W_P+:C_ (0?2/\ GYO?_ MJ -BBL?\ X0?2/^?F M]_\ MJ/^$'TC_GYO?\ P+:@#8HK'_X0?2/^?F]_\"VH_P"$'TC_ )^;W_P+ M:@#8K'\#_P#((E_Z_9O_ $*C_A!](_Y^;W_P+:LSPKX5T[4-.DFFGN01\<: )Q/#I_B#3UF^SS $"6%_ MOPR8)&^-E;!(S@D5RG[)/_!.#]A?]A$WT_[)/[,7A?P3=ZG$(M0U33;1I+VX MB!#")[J9GF:/< =A?;D9QFO;:* /)_VL/V%?V0?VY_"]EX/_ &MOV?/#GCJR MTR5Y-+;6;,^?8LX 3: N^1F; S@ 5Z/10!X/^UI_P $ MP_V OVZ=(,6(C9BH+-@ M?,<^H?!KX)_"+]G?X<:;\(/@5\-M%\)>%]'B,>FZ%H&GI;6T )+,0B LS$L MS'+,Q+$DDFNHHH **** "O*/VY_^31_'O_8!?_T-:]7KRC]N?_DT?Q[_ -@% M_P#T-: .Z^%W_),_#O\ V K3_P!$I6[6%\+O^29^'?\ L!6G_HE*W: "BBB@ M HHHH **** "BBB@ K'\2_\ (7T?_K]/_H)K8K'\2_\ (7T?_K]/_H)H V** M** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ K'\ M#_\ ((E_Z_9O_0JV*Q_ _P#R")?^OV;_ -"H V**** "BBB@ HHHH **** " MBBB@ HHHH **** "BBB@ HHHH **** "BBB@#'\2_P#(7T?_ *_3_P"@FMBL M?Q+_ ,A?1_\ K]/_ *":V* "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ M HHHH **** "BBB@ HHHH Q_ _\ R")?^OV;_P!"K8K'\#_\@B7_ *_9O_0J MV* "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ K'\ M2_\ (7T?_K]/_H)K8K'\2_\ (7T?_K]/_H)H V**** "BBB@ HHHH **** " MBBB@ HHHH **** "BBB@ HHHH **** "BBB@ K'\#_\ ((E_Z_9O_0JV*Q_ M_P#R")?^OV;_ -"H V**** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ M HHHH **** "BBB@ HHHH *\H_;G_P"31_'O_8!?_P!#6O5Z\H_;G_Y-'\>_ M]@%__0UH [KX7?\ ),_#O_8"M/\ T2E;M87PN_Y)GX=_[ 5I_P"B4K=H *** M* "BBB@ HHHH **** "L?Q+_ ,A?1_\ K]/_ *":V*Q_$O\ R%]'_P"OT_\ MH)H V**** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "B MBB@ K'\#_P#((E_Z_9O_ $*MBL?P/_R")?\ K]F_]"H V**** "BBB@ HHHH M **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@#'\2_\A?1_P#K]/\ MZ":V*Q_$O_(7T?\ Z_3_ .@FMB@ HHHH **** "BBB@ HHHH **** "BBB@ MHHHH **** "BBB@ HHHH **** ,?P/\ \@B7_K]F_P#0JV*Q_ __ "")?^OV M;_T*MB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH M *Q_$O\ R%]'_P"OT_\ H)K8K'\2_P#(7T?_ *_3_P"@F@#8HHHH **** "B MBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "L?P/_ ,@B7_K] MF_\ 0JV*Q_ __((E_P"OV;_T*@#8HHHH **** "BBB@ HHHH **** "BBB@ MHHHH **** "BBB@ HHHH **** "BBB@ KRC]N?\ Y-'\>_\ 8!?_ -#6O5Z\ MH_;G_P"31_'O_8!?_P!#6@#NOA=_R3/P[_V K3_T2E;M87PN_P"29^'?^P%: M?^B4K=H **** "BBB@ HHHH **** "L?Q+_R%]'_ .OT_P#H)K8K'\2_\A?1 M_P#K]/\ Z": -BBBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** M "BBB@ HHHH *Q_ _P#R")?^OV;_ -"K8K'\#_\ ((E_Z_9O_0J -BBBB@ H MHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH Q_$O_(7T M?_K]/_H)K8K'\2_\A?1_^OT_^@FMB@ HHHH **** "BBB@ HHHH **** "BB MB@ HHHH **** "BBB@ HHHH **** ,?P/_R")?\ K]F_]"K8K'\#_P#((E_Z M_9O_ $*MB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ H MHHH *Q_$O_(7T?\ Z_3_ .@FMBL?Q+_R%]'_ .OT_P#H)H V**** "BBB@ H MHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ K'\#_ /((E_Z_ M9O\ T*MBL?P/_P @B7_K]F_]"H V**** "BBB@ HHHH **** "BBB@ HHHH M**** "BBB@ HHHH **** "BBB@ HHHH *\H_;G_Y-'\>_P#8!?\ ]#6O5Z\H M_;G_ .31_'O_ & 7_P#0UH [KX7?\DS\._\ 8"M/_1*5NUA?"[_DF?AW_L!6 MG_HE*W: "BBB@ HHHH **** "BBB@ K'\2_\A?1_^OT_^@FMBL?Q+_R%]'_Z M_3_Z": -BBBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB M@ HHHH *Q_ __((E_P"OV;_T*MBL?P/_ ,@B7_K]F_\ 0J -BBBB@ HHHH * M*** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH Q_$O_ "%]'_Z_ M3_Z":V*Q_$O_ "%]'_Z_3_Z":V* "BBB@ HHHH **** "BBB@ HHHH **** M"BBB@ HHHH **** "BBB@ HHHH Q_ __ "")?^OV;_T*MBL?P/\ \@B7_K]F M_P#0JV* "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB M@ K'\2_\A?1_^OT_^@FMBL?Q+_R%]'_Z_3_Z": -BBBB@ HHHH **** "BBB M@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *Q_ __((E_P"OV;_T*MBL M?P/_ ,@B7_K]F_\ 0J -BBBB@ HHHH **** "BBB@ HHHH **** "BBB@ HH MHH **** "BBB@ HHHH **** "O*/VY_^31_'O_8!?_T-:]7KRC]N?_DT?Q[_ M -@%_P#T-: .Z^%W_),_#O\ V K3_P!$I6[6%\+O^29^'?\ L!6G_HE*W: " MBBB@ HHHH **** "BBB@ K'\2_\ (7T?_K]/_H)K8K'\2_\ (7T?_K]/_H)H M V**** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ M K'\#_\ ((E_Z_9O_0JV*Q_ _P#R")?^OV;_ -"H V**** "BBB@ HHHH ** M** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@#'\2_P#(7T?_ *_3_P"@ MFMBL?Q+_ ,A?1_\ K]/_ *":V* "BBB@ HHHH **** "BBB@ HHHH **** " MBBB@ HHHH **** "BBB@ HHHH Q_ _\ R")?^OV;_P!"K8K'\#_\@B7_ *_9 MO_0JV* "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ M K'\2_\ (7T?_K]/_H)K8KY._;N_X*[?L(?L&?'SX:? ?]I'XQV^D>(?&>J@ M+#$@ECT6U965+[4&!_T6V>4"-9&!R2S8\N.1T /K&BH[2[M+^UBO["YCG@GC M62&:%PR2(1D,I'!!!R"*DH **** "BBB@ HHHH **** "BBB@ HHHH **** M"BBB@ HHHH **** "L?P/_R")?\ K]F_]"KS?]N?]N?]G;_@G=^SMK'[2W[2 MWC!=,T33%\NRLH=KWFKWC*3%96D1(\V9]IP,A54,[E41F'YZ?\$0_P#@YG^% M?_!07XPZS^S!^T9X2TOX<>,M7UZYG^&@BOF>SUBT=RT>GO+)TOT7H<*D_.Q4 M8!& /UKHHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH M**** "BBB@ KRC]N?_DT?Q[_ -@%_P#T-:]7KRC]N?\ Y-'\>_\ 8!?_ -#6 M@#NOA=_R3/P[_P!@*T_]$I6[6%\+O^29^'?^P%:?^B4K=H **** "BBB@ HH MHH **** "L?Q+_R%]'_Z_3_Z":V*Q_$O_(7T?_K]/_H)H V**** "BBB@ HH MHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ K'\#_\@B7_ *_9 MO_0JV*Q_ _\ R")?^OV;_P!"H V**** "BBB@ HHHH **** "BBB@ HHHH * M*** "BBB@ HHHH **** "BBB@#'\2_\ (7T?_K]/_H)K8K'\2_\ (7T?_K]/ M_H)K8H **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** M"BBN!_:>_:>^!W[''P.U[]HK]HKQ[:>'/"?ART,^H:A=-EG;HD,2#YI9I&PB M1J"S,0 * .F\#_\ ((E_Z_9O_0JV*^-?^"/?_!8K]EC_ (*M_#?7+_X.3W.@ M^*O#VI3MK?@779H_[0M[1I2(+Q=A*RPR+MRR9\N0E&_@9_LJ@ HHHH **** M"BBB@ HK'\5?$+P#X%@-SXW\<:/HT87<9-5U.*W7'KF1AQ7EGC'_ (*4?\$Z M_AX63QW^WI\&='=#AHM1^)VE0OGT"MEFN$VCWQW%'_ ]T_P""A7BW_DD?_! WXWWN[_5?\)EXKTGP M_G/W=WG,^WW]* /T HK\_P#_ (;-_P"#@;QJ/^*7_P"",'@'P8'^XWC']HFP MU#;[L+&('GKCM0=4_P"#GGQJ<67A;]BWP3;/]XZC?>)M2NXP?[OE 1$CWX- M'Z 45^?_ /PRW_P<3>->?$W_ 5/^#7@G?RP\'? ]=2\L^B_;Y!D=^:/^'5O M_!4_Q9Q\6_\ @X%^)5Z&_P!;_P (=\)-#\/Y'?;Y+/M/OVH _0"BOS__ .'" MVH>)OWOQ;_X+%?MJ>(BW,EG;_&@:?9N?7R8;7CTX;N?6C_B&E_X)EZ]Q\6U^ M+/C\'B0>,?C'K,WF#T;R9XN.] 'VMXQ^.OP1^'9OVNYDS^/6O5_!W_!*3_@ MF)X */X1_P"">?P5LY4^[(]"TQY!XF#.%2!8UW&.\4NBR09)4L&4LC([ 'V;_P;[_\ !RIXN_8\ MT*R_8I_;$\/^+O'O@9$6W^'=_P"&=/.HZUHTF0$TX0EU:YM6Z1JI,D)^10T9 M58OUH_XB*_V57^2V_9#_ &HYI#Q'#%\";XL[=E&6ZGI7!_\ !OS_ ,&_/@C_ M ()B^"+;]H?]H?3;#7?COKMAB>=2LUOX1MY%^:RM&Y#3L#MFN%Z\QQGR]S2_ MIW0!\ ?\1#?P)_Z1]_M?_P#A@KK_ ./4?\1!WPON/GT?_@F-^VIJ,70SV7[/ MD[(&_N_-<@YZ=NXK[_HH ^ /^(@3P=)^[L?^"3?[([>#]GB0O(?0 W8 M&?QH_P"'^G_6%?\ ;_\ _$*KK]]I7_ 1+_;I>$]&N M_@BW<&GP)COES*0/ZT? M\/@?VZ_^D"W[0'_@VTO_ .+K[^HH ^ ?^'M/_!1R?][8_P#! GXRM"W,;3^. M-'BG'U]*^ M_P"B@#X _P"'I'_!6'_I7V^('_AY]"_^)H_X>7_\%EI/WEM_P;S^)#&W,9E_ M:,\.HQ7ME3%\IQU':OO^B@#X _X>/_\ !;6\^31?^#=[4Y''+B^_:A\-VR@> MQ:$Y/M1_P\/_ ."Z_P#TKJ_^;<^&/_D>OO\ HH ^ /\ AN[_ (+WM\R_\$%] M 4'D*W[4>ADCV.(*/^&W/^"_E_Q:?\$//!^G[/O&^_:7TJ7?G^[Y!_P1A^'P]S^T58?_&:7_AJG_@X?_P"D4OP?_P##Z1__ M !JOOZB@#^.;_@OQ^U'_ ,%)?V@/VXM2\*_\%'/!$W@?5?"L7E>&/AY93E]* MTJQEP1/:2!F2[\[:&>Z#,9&3;\@C6-/B+3]0O](OX-5TJ^FM;JUF66VN;>4I M)%(I!5U88*L" 01R"*_LZ_X+!?\ !'WX ?\ !6_X /X"\>Q0Z'XZT.&67P%X M]@M@UQI5PPR890,&:TD( DB)]&4JZ@U^57_!#S_@U8\;:5\==1^/O_!3_P ( M:>VA^"/$,MKX5\ 1W275OXDNH),"_N2O#6 (#1PL TY_UBK&-DH!^E/_ ;S M_M&?M\_M.?\ !.KP[\1/V^O K66J;EA\'^*+Z4IJ'BG2 B^5J%U;E1Y;'E5E M)S<*!+M 822_=%-AAAMX4M[>)8XXU"HB+@*!P .@IU !1110 4444 %%%% M!1110 4444 %%%% !1110!\O?\%!/^"I7PV_86\7^"_@;H?PB\7?%3XM_$=Y MO^$)^%W@.U22^NX8@3+=SR2,$MK9<-F1L_<-7^D]0_9&_9RO\ ]JBS_;?U/X<0R?$_3/![^&++Q7+J-SNM]):9IVMU@\WR M!^\=VW^7O^=ANP2*_.?XW?$ZR_X+1_\ !8+X+?#_ /9(A&K?"C]DGQJ_BOXE M?%NU7=87FN*8FM]'L)A\L_SP*)&4E65Y&&5B4R@'U5^W!_P5AT;]F#X_:'^Q MM\ /V:?%_P <_C3KNAOK9\!>"YX+=-*TM6V"[O[R<^7:HS_*F0?QY\!_$NA^(S M#\OVJUM%OKV$28^]B9$(S_<7T% 'J?[0W_!935?#7[3OB?\ 9$_8A_8>\>_M M#>+_ (?002?$F?PGJ-II^E^'7F!:.U>\N25ENBH)\E0/NLH8LDBI[!_P3S_X M*)_!G_@HQ\*M6\=_#70-?\,Z]X4UZ;0O'O@+Q?8BUU?PUJD7W[:YBR>O)5P< M-A@=KHZ+\E_\&NV/%?[*?QN^.6MKYWB+QW^T[XKU+7KZ3F663%KA&;J0"TC M=C(WK2_L52-X"_X.8_VP/A[X:_T?2?%?PL\)^(]4LX>(VOX;>T@60J.-Q%Q, MQ/4F1CWH _3&BBB@ KRC]N?_ )-'\>_]@%__ $-:V_B#^T]\ /A5XC;PE\1/ MBII>D:DD*2M9W,O!W@OXOZ1J.J7VBR) M:65O(Q>5@0Q ROH"?PH ]_\ A=_R3/P[_P!@*T_]$I6[7(_#+Q=X:C^&WAZ- M]9A#+H=H"">A\E*W/^$Q\,?]!J#_ +ZH TJ*S?\ A,?#'_0:@_[ZH_X3'PQ_ MT&H/^^J -*BLW_A,?#'_ $&H/^^J/^$Q\,?]!J#_ +ZH TJ*S?\ A,?#'_0: M@_[ZH_X3'PQ_T&H/^^J -*BLW_A,?#'_ $&H/^^J/^$Q\,?]!J#_ +ZH TJQ M_$O_ "%]'_Z_3_Z":F_X3'PQ_P!!J#_OJLO7O$N@W.IZ9-!JD3+#=%I6!^Z- MO4T =-16;_PF/AC_ *#4'_?5'_"8^&/^@U!_WU0!I45F_P#"8^&/^@U!_P!] M4?\ "8^&/^@U!_WU0!I45F_\)CX8_P"@U!_WU1_PF/AC_H-0?]]4 :5%9O\ MPF/AC_H-0?\ ?5'_ F/AC_H-0?]]4 :5%9O_"8^&/\ H-0?]]4?\)CX8_Z# M4'_?5 &E16;_ ,)CX8_Z#4'_ 'U1_P )CX8_Z#4'_?5 &E16;_PF/AC_ *#4 M'_?5'_"8^&/^@U!_WU0!I45F_P#"8^&/^@U!_P!]4?\ "8^&/^@U!_WU0!I4 M5F_\)CX8_P"@U!_WU1_PF/AC_H-0?]]4 :5%9O\ PF/AC_H-0?\ ?5'_ F/ MAC_H-0?]]4 :5%9O_"8^&/\ H-0?]]4?\)CX8_Z#4'_?5 &E6/X'_P"01+_U M^S?^A5-_PF/AC_H-0?\ ?59?A+Q+H-CIDD-WJD4;&ZE8*Q[%N#0!TU%9O_"8 M^&/^@U!_WU1_PF/AC_H-0?\ ?5 &E16;_P )CX8_Z#4'_?5'_"8^&/\ H-0? M]]4 :5%9O_"8^&/^@U!_WU1_PF/AC_H-0?\ ?5 &E16;_P )CX8_Z#4'_?5' M_"8^&/\ H-0?]]4 :5%9O_"8^&/^@U!_WU1_PF/AC_H-0?\ ?5 &E16;_P ) MCX8_Z#4'_?5'_"8^&/\ H-0?]]4 :5%9O_"8^&/^@U!_WU1_PF/AC_H-0?\ M?5 &E16;_P )CX8_Z#4'_?5'_"8^&/\ H-0?]]4 :5%9O_"8^&/^@U!_WU1_ MPF/AC_H-0?\ ?5 &E16;_P )CX8_Z#4'_?5'_"8^&/\ H-0?]]4 :5%9O_"8 M^&/^@U!_WU1_PF/AC_H-0?\ ?5 $/B7_ )"^C_\ 7Z?_ $$UL5S.O>)=!N=3 MTR:#5(F6&Z+2L#]T;>IK4_X3'PQ_T&H/^^J -*BLW_A,?#'_ $&H/^^J/^$Q M\,?]!J#_ +ZH TJ*S?\ A,?#'_0:@_[ZH_X3'PQ_T&H/^^J -*BLW_A,?#'_ M $&H/^^J/^$Q\,?]!J#_ +ZH TJ*S?\ A,?#'_0:@_[ZH_X3'PQ_T&H/^^J M-*BLW_A,?#'_ $&H/^^J/^$Q\,?]!J#_ +ZH TJ*S?\ A,?#'_0:@_[ZH_X3 M'PQ_T&H/^^J -*BLW_A,?#'_ $&H/^^J/^$Q\,?]!J#_ +ZH TJ*S?\ A,?# M'_0:@_[ZH_X3'PQ_T&H/^^J -*BLW_A,?#'_ $&H/^^J/^$Q\,?]!J#_ +ZH M TJ*S?\ A,?#'_0:@_[ZK!^)?[0/P0^#/@F_^)/Q;^*V@^&?#^EQ>;J&M:[J M4=K;6Z^K22$*,] ,Y)X'- '2Z_JPT#0KW76TZ[O!96DDYM+" RSS[%+;(T'W MW;&%7N2!7\>'_!*/^"R_[17[<6MW/PP_X(M?LY)XFTU9 MVMM0_:&^*\$^E>#].(.UVM(647.INI[(J[6 )1T.:^*?^"GG_!KY\3?C'\%? M$/[6OAK]K^^^+'[2][>/K'C.&]T>RTG3/$J")5-K86\"+]FG14 C+N5EQM(C M+ J ?A[^RS^U-\=/V,/CIH/[1O[.7CRZ\.^*_#MT);*]MSE)4/#P3(?EFAD7 M*O&V5920:_IW_92_X+_?M@_M4_L_>&/BG\,/^")GQF\47FJZ/AR^ M\-_"CPYJCQVGA/5(9+6^\67L$A5X&4@/#9QR*4E?AG96B3&'=/Z<_#^H_#KP MGH-EX6\+?V=INF:;:1VNG:=80+#!:P1J$CBCC0!415 4* !0!\.C]OG_@ MNQXR./ __!"#3/#\#?ZJ_P#&7[2.C'(/0M!;P^8F.X)H/Q"_X.:O&H_XIS]G MC]D'P2'Z?\);XMU_4FC^OV%0"?3M7W=_PF/AC_H-0?\ ?5'_ F/AC_H-0?] M]4 ?"/\ PHG_ (.1O&O_ ",W[>7[-_@G?][_ (0WX7WVI>7GKM^WN,X[9Z]Z M/^':W_!9CQ?\WQ/_ .#@/7HXG^]9^#OV?M!TOR_99A(SM]2,\^U?=W_"8^&/ M^@U!_P!]4?\ "8^&/^@U!_WU0!\(G_@AS\7_ !9S\7/^"W?[8NI!O];%X7^( M]OH<<@/52L-L_P I],].*/\ B' _8>U[_DK?QQ_:%\?EO]:?&/QNU*;S#ZMY M)BYQQ7W=_P )CX8_Z#4'_?5'_"8^&/\ H-0?]]4 ?%/A7_@VK_X(E^$I_MEM M^PWIM_<%MTD^N>+M:OS(WJPN+UU/TQBO5/!W_!&W_@D_X$"?\(__ ,$YO@TS M1@;)-1^'UA>NON&N(G;/OG-?07_"8^&/^@U!_P!]4?\ "8^&/^@U!_WU0!RG M@W]E7]E_X=%#\/OV;_ 6A&,Y0Z-X/LK7:?;RXEQ7=Q1101+!!&J(BA41%P% MZ #L*S_^$Q\,?]!J#_OJC_A,?#'_ $&H/^^J -*BLW_A,?#'_0:@_P"^J/\ MA,?#'_0:@_[ZH TJ*S?^$Q\,?]!J#_OJC_A,?#'_ $&H/^^J -*BLW_A,?#' M_0:@_P"^J/\ A,?#'_0:@_[ZH TJ*S?^$Q\,?]!J#_OJC_A,?#'_ $&H/^^J M -*BLW_A,?#'_0:@_P"^J/\ A,?#'_0:@_[ZH TJY[QGHVD:GX@\.7NI:5;7 M$VGZHT]A+/ KM;2F%XS)&2,HQ21TW#!VNPZ$BK__ F/AC_H-0?]]5EZ]XET M&YU/3)H-4B98;HM*P/W1MZF@#IJ*S?\ A,?#'_0:@_[ZH_X3'PQ_T&H/^^J M-*BLW_A,?#'_ $&H/^^J/^$Q\,?]!J#_ +ZH TJ*S?\ A,?#'_0:@_[ZH_X3 M'PQ_T&H/^^J -*BLW_A,?#'_ $&H/^^J/^$Q\,?]!J#_ +ZH TJ*S?\ A,?# M'_0:@_[ZH_X3'PQ_T&H/^^J -*BLW_A,?#'_ $&H/^^J/^$Q\,?]!J#_ +ZH M TJ*S?\ A,?#'_0:@_[ZH_X3'PQ_T&H/^^J -*BLW_A,?#'_ $&H/^^J/^$Q M\,?]!J#_ +ZH TJ*S?\ A,?#'_0:@_[ZH_X3'PQ_T&H/^^J -*BLW_A,?#'_ M $&H/^^J/^$Q\,?]!J#_ +ZH TJ*S?\ A,?#'_0:@_[ZH_X3'PQ_T&H/^^J M-*L?P/\ \@B7_K]F_P#0JF_X3'PQ_P!!J#_OJLOPEXET&QTR2&[U2*-C=2L% M8]BW!H Z:BLW_A,?#'_0:@_[ZH_X3'PQ_P!!J#_OJ@#2HK-_X3'PQ_T&H/\ MOJC_ (3'PQ_T&H/^^J -*BLW_A,?#'_0:@_[ZH_X3'PQ_P!!J#_OJ@#2HK-_ MX3'PQ_T&H/\ OJC_ (3'PQ_T&H/^^J -*BLW_A,?#'_0:@_[ZH_X3'PQ_P!! MJ#_OJ@#2HK-_X3'PQ_T&H/\ OJM%'61!(C95AD$=Q0 M%%% !1110!^._P#P M<0?MQ_'K5?V@_"__ 3H\*?#SXV:9\&K_3HM0^.?CCX/^!I]1U;5;28.4T6Q MD.R%%=%7SG+\B<*598Y(IO4?^"?O_!7']@WX3VWP\_87_95_X)G_ +2_P^\/ MW^MV6AZ/)JGP=%KI]I/=3I";R^N3=NY&YQ)-#/#T^JCPKXBTR%X/*O88%: M1(IEDGE$@!RTZA0VR39I_L8S>.O^"HW_ 6/;_@J=I_P?\5>$O@M\)_A?+X. M^%FH>,]%DTZ[\5:G=S2M=:C#;R@.MLL4TT6X]<1=&\U(_P!/:* /R(_96_:1 ML?\ @@)\=?CO^RK^V'\(?'L7PL\;_%74/'WP:^(_A7P?=:OI]W!J*Q"3293; M*S0W$)BB4*P^9O,8[5:)G]@_X(V?"OXS_'3]L']HG_@KY\;_ (/:[X MOC1= M:5HOPN\)>*K,VVJ0>'--MUA6\N8#DPFY,<#A">LWTV)'0[E&0P4$<5[=7E'[<__ ":/X]_[ +_^AK0!VGPOT^P/PT\. MDV4))T*TR3&/^>*5N_V=I_\ SXP_]^A61\+O^29^'?\ L!6G_HE*W: (?[.T M_P#Y\8?^_0H_L[3_ /GQA_[]"IJ* (?[.T__ )\8?^_0H_L[3_\ GQA_[]"I MJ* (?[.T_P#Y\8?^_0H_L[3_ /GQA_[]"IJ* (?[.T__ )\8?^_0H_L[3_\ MGQA_[]"IJ* (?[.T_P#Y\8?^_0K(\1V5FFJZ2J6D0#7A# 1CD;36[6/XE_Y" M^C_]?I_]!- &E_9VG_\ /C#_ -^A1_9VG_\ /C#_ -^A4U% $/\ 9VG_ //C M#_WZ%']G:?\ \^,/_?H5-10!#_9VG_\ /C#_ -^A1_9VG_\ /C#_ -^A4U% M$/\ 9VG_ //C#_WZ%']G:?\ \^,/_?H5-10!#_9VG_\ /C#_ -^A1_9VG_\ M/C#_ -^A4U% $/\ 9VG_ //C#_WZ%']G:?\ \^,/_?H5-10!#_9VG_\ /C#_ M -^A1_9VG_\ /C#_ -^A4U% $/\ 9VG_ //C#_WZ%']G:?\ \^,/_?H5-10! M#_9VG_\ /C#_ -^A1_9VG_\ /C#_ -^A4U% $/\ 9VG_ //C#_WZ%']G:?\ M\^,/_?H5-10!#_9VG_\ /C#_ -^A1_9VG_\ /C#_ -^A4U% $/\ 9VG_ //C M#_WZ%9'@NRLY=*D:6TB8_;)1EHP>-U;M8_@?_D$2_P#7[-_Z%0!I?V=I_P#S MXP_]^A1_9VG_ //C#_WZ%344 0_V=I__ #XP_P#?H4?V=I__ #XP_P#?H5-1 M0!#_ &=I_P#SXP_]^A1_9VG_ //C#_WZ%344 0_V=I__ #XP_P#?H4?V=I__ M #XP_P#?H5-10!#_ &=I_P#SXP_]^A1_9VG_ //C#_WZ%344 0_V=I__ #XP M_P#?H4?V=I__ #XP_P#?H5-10!#_ &=I_P#SXP_]^A1_9VG_ //C#_WZ%344 M 0_V=I__ #XP_P#?H4?V=I__ #XP_P#?H5-10!#_ &=I_P#SXP_]^A1_9VG_ M //C#_WZ%344 0_V=I__ #XP_P#?H4?V=I__ #XP_P#?H5-10!#_ &=I_P#S MXP_]^A1_9VG_ //C#_WZ%344 87B.RLTU7252TB :\(8",/M'O#=A86%E L-G96=FD4,$2C"HB* JJ !5 MG^SM/_Y\8?\ OT*FHH PO!=E9RZ5(TMI$Q^V2C+1@\;JU_[.T_\ Y\8?^_0K M-\#_ /((E_Z_9O\ T*MB@"'^SM/_ .?&'_OT*/[.T_\ Y\8?^_0J:B@"'^SM M/_Y\8?\ OT*/[.T__GQA_P"_0J:B@"'^SM/_ .?&'_OT*/[.T_\ Y\8?^_0J M:B@"'^SM/_Y\8?\ OT*/[.T__GQA_P"_0J:B@"'^SM/_ .?&'_OT*/[.T_\ MY\8?^_0J:B@"'^SM/_Y\8?\ OT*/[.T__GQA_P"_0J:B@"'^SM/_ .?&'_OT M*/[.T_\ Y\8?^_0J:B@"'^SM/_Y\8?\ OT*/[.T__GQA_P"_0J:B@"'^SM/_ M .?&'_OT*/[.T_\ Y\8?^_0J:B@"'^SM/_Y\8?\ OT*/[.T__GQA_P"_0J:B M@"'^SM/_ .?&'_OT*R/$=E9IJNDJEI$ UX0P$8Y&TUNUC^)?^0OH_P#U^G_T M$T :7]G:?_SXP_\ ?H4?V=I__/C#_P!^A4U% $/]G:?_ ,^,/_?H4?V=I_\ MSXP_]^A4U% $/]G:?_SXP_\ ?H4?V=I__/C#_P!^A4U% $/]G:?_ ,^,/_?H M4?V=I_\ SXP_]^A4U% $/]G:?_SXP_\ ?H4?V=I__/C#_P!^A4U% $/]G:?_ M ,^,/_?H4?V=I_\ SXP_]^A4U% $/]G:?_SXP_\ ?H4?V=I__/C#_P!^A4U% M $/]G:?_ ,^,/_?H4?V=I_\ SXP_]^A4U% $/]G:?_SXP_\ ?H4?V=I__/C# M_P!^A4U% $/]G:?_ ,^,/_?H4?V=I_\ SXP_]^A4U% $/]G:?_SXP_\ ?H4? MV=I__/C#_P!^A4U<7^T?\=/!W[,/[/\ XV_:,^(+/_8G@;PM?Z[J:0D"22&U M@>9HTSP7;9M4=V8#O0!#\=/C]^S?^S#X./Q!_:,^+OA#P-HF\QIJ?BO6+:PA MDDQGRT:9E\QR.B+ECV%>4?LJ_P#!2O\ X)T_M/:X?AY\#/VO_AOXG\12WDOV M;0;+Q';_ &ZX 8\Q0.5DE )RBD 8/0BOF?_ ()L_P#!-G0/VU= T?\ X*K_ M /!5;PAI_P 3/BE\3-/CUOP?X/\ %%O]LT#P!H%Q^^L=/LK&;,7F>2T%--O%GE&C^+/".C6^E:SH\ MJG]W-:WENBR(R,%8(VZ,E%#(P&* /JG^SM/_ .?&'_OT*/[.T_\ Y\8?^_0K MXE_X(\_M"_M P>)?B]_P37_;#\KUY1^W/_ ,FC^/?^P"__ *&M '=?"[_DF?AW_L!6G_HE M*W:POA=_R3/P[_V K3_T2E;M !1110 4444 %%%% !1110 5C^)?^0OH_P#U M^G_T$UL5C^)?^0OH_P#U^G_T$T ;%%%% !1110 4444 %%%% !1110 4444 M%%%% !1110 4444 %%%% !1110 5C^!_^01+_P!?LW_H5;%8_@?_ )!$O_7[ M-_Z%0!L4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 M%%%% &/XE_Y"^C_]?I_]!-;%8_B7_D+Z/_U^G_T$UL4 %%%% !1110 4444 M%%%% !1110 4444 %)))'#&TLLBJBJ2S,< =237QE^UE_P6X_9J^"'Q(D_9 ME_9I\)Z]^T'\;'+1P?##X41"]>SD!P6U&]4-!I\:GB0L6>/JT8'->7Q_\$X/ M^"BW_!3*1?$?_!77]HL^ _AU=,'C_9I^".JO;6T\1_Y8ZUJZGS;TD8#Q1,8B M0&C>,\4 =Q^T-_P7)^$-G\2;O]F'_@G;\)M;_:=^+\/[N?0/AW,G]AZ(Y)42 M:GK+ VUK&&!!VER&&UO+)S7&Z7_P26_:[_X*":G;_$'_ (+6_M/MJ_A_STN; M']G#X17D^E^%+3!#(FH7*L+G4W7OE@$8'9(R'%?;_P"SS^S-^S]^R;\-K3X0 M?LU_!_0?!7ANRYBTK0-/2!'? !ED8?--*<#=)(6=CR6)KN: .:^$?P;^$WP" M\ 6'PJ^"'PVT3PEX;TN/9I^A^'M,BM+6 =R(XP!D]2W5CR22"/ D=A+XX\8Z5HRZKJD&F:6VJZC%;B\O9FVPVL7F,/,FD((6-#$^+6L7UF?'_CNP\'^&?L>CW%V)]5O/,,$%-76VM/$:&)H_L6HHR,)[;)#;!M.0"&!YH [34?$. M@:/?66EZMKEG:W.I3-%IUO;'&T<)6+YAYK(&/RKN M;BK/Q(_9X^"OQ>\>>#/B?\2?A[9:OK_P\U.;4/!>J7)<2:35)+'M8#+) M\IW C%=DT,+RK.\*ET!".5&5!QD ]LX'Y4 <#\2/C#XY\$?&SX>?"WP_\!?$ M7B/1O&!)?#'Q" M^%=AY2V=WKD5G#9S0ZA&R^;%):RQO+$OREEFB3$DG MI\U?''[0O_!'GQ)!^T#KG[8G_!-?]KS7OV=OB3XKE$_CBTT[1(-7\,^*YP6/ MGWNE3E8Q)M._:T_P"" MJG[7'[?/PUF6Z^'&_P /_#CP?K]N=T&O7.E6[MJ-Q$P^62))I(T21=RNK@@\ M$5^B%4?MS_P#)H_CW_L O_P"AK7J]>4?MS_\ )H_CW_L O_Z& MM '=?"[_ ))GX=_[ 5I_Z)2MVL+X7?\ ),_#O_8"M/\ T2E;M !1110 4444 M %%%% !1110 5C^)?^0OH_\ U^G_ -!-;%8_B7_D+Z/_ -?I_P#030!L4444 M %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !6/X'_ M .01+_U^S?\ H5;%8_@?_D$2_P#7[-_Z%0!L4444 %%%% !1110 4444 %%% M% !1110 4444 %%%% !1110 4444 %%%% &/XE_Y"^C_ /7Z?_036Q6/XE_Y M"^C_ /7Z?_036Q0 4444 %%%% !1110 4444 %%?,O[<7_!6[]C#]@O4+;P% M\2?&UYXF^(NJ%4\/?"7P!8'5_$NJRN,QHEG"G@3P+J*7?C[7+8_PWFI8\O2PZD'9$OF+EHY( MVZT >U_MI_\ !9?]D7]D#QJGP&T.?6?BO\8[YS#I'P=^%5@=6UN6;'"W"Q92 MS4<%C,RN$)94<"O%/^&/_P#@K)_P5*_XFG_!0CXTO^SG\([WYE^!/P[O92TTY+9;:S;%).U5'%>V4 >6_LG?L4_LJ_L,_#>/ MX3_LH? _0O!>C*%-RFEVV;B^=1@2W-PY::YDQQOE=FQQG'%>I444 %%%% !1 M110 4444 %%%% &/X'_Y!$O_ %^S?^A5L5C^!_\ D$2_]?LW_H5;% !1110 M4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 5C^)?^0OH_\ MU^G_ -!-VTW7-4B*G:TEFD9-@Y!'[N8DC!Y((- 'Z-T5\?_L7?\%;=!^/WQSF M_8R_:J_9V\3? 'X[06#7UM\/?&-U%=6VNVJ;B]QI.HP@0ZBB!&+;0IPKE0XC M=E^P* "BBL3XC_$CX?\ P?\ NJ?$_XJ^--,\.^'-#LVNM8US6;U+>ULH%^] M))(Y"HH]2: -NBN"^+W[0_@[X3?L\:G^TO::#KWC#0M/T)-7MK+P-IAU*_U2 MV<*R&TA5AY[,KJR@$9'-0?&+XC_&J#]FR_\ BA^S)\'8_%'C2?1;>]\,^#/% M.I?V-]HDE,9\FYDD4_9G1'8LK#.Y-G!.0 >B45YW\>O"/[0OQ1_9TU/PK\"_ MB[;?"SXB:IIUM_9WBN708-;CT2X\R)YO]&F(BN?D$L8W$#Y@W84O[1_[.7AS M]JGX :K^S[\3O&'B+3K+7(;5=3UCP7K$ND7X:&>*X4HQAC+2>5\IDV[002*/VCO#'[1?BSP9 MING_ +,OQ1T/PEKD7B6PN-3U'7]#_M"&?2TES=VRQ[AMDDC^59,_*>:] HH MX#]H?]GZQ_:*\/:#X>O_ (K^.?"*Z!XOT_Q!'=>!/$3:;-?/:.76SNF"L)[. M0D>9 PP^U>1@5J?%?X&_!_XZVFB6'QC^'&D^)8/#?B2U\0:##J]FLRV.J6V[ M[/>1AN%ECWMM;J,UU=% !1110 4444 %%%% !1110 5C^!_^01+_ -?LW_H5 M;%8_@?\ Y!$O_7[-_P"A4 ;%%%% !1110 4444 %%%% !1110 4444 %%%% M!1110 4444 %%%% !1110 4444 %>4?MS_\ )H_CW_L O_Z&M>KUY1^W/_R: M/X]_[ +_ /H:T =U\+O^29^'?^P%:?\ HE*W:POA=_R3/P[_ -@*T_\ 1*5N MT %%%% !1110 4444 %%%% !6/XE_P"0OH__ %^G_P!!-;%8_B7_ )"^C_\ M7Z?_ $$T ;%%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %% M%% !1110 5C^!_\ D$2_]?LW_H5;%8_@?_D$2_\ 7[-_Z%0!L4444 %%%% ! M1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% &/XE_Y"^C_P#7 MZ?\ T$UL5C^)?^0OH_\ U^G_ -!-;% !1110 4444 %%>-?MF?\ !03]C[_@ MG_X#'Q _:O\ CAI'A:&X5O[+TN20SZEJCCCR[2SB#37#9P"44JN06*CFOD3_ M (7K_P %C/\ @JG_ *'^RU\.9_V2/@O>\'XE_$C2TNO&^M6Q_CL-*W>7IX93 MQ),V[!62.3(VT ?4/[<'_!3W]B[_ ()ZZ+;S_M'_ !=M[?7M2 'A_P #:'"; M_7]9D8[42VL8N)XFY!E4U] ?L/_ /!(;]C3]A76KCXG>#?"FH^,OB=J M9,GB#XO_ !'U ZQXDU*9AAW-U,/W 8<%85C# #=N(S7U!0!\\_L.?\$M?V+/ M^">^GW-S^S[\*D;Q/J88^(?B%XEN#J7B'69&.9'N+Z4%_G;YC''LCW?A!\? M/A)9?';X(>/=/\6>$M3@N)=,UW09?M$%XL,LD4GE%?OXDBD3CNI% '745Y[^ MS]^TEX(_:?\ V>])_:0^$6C:Y+HVNV-Q!?%TR?:]/G5Y$BBN& MB)4;]B/\N<+(.XH ]"HKSWX*:G^TGXN_9TTW4?CWX9\/>$/B;>Z3.-4T[0+U MM0T[3;PM(L1CD< S*%\MB#U)84?"#P/\>;7]G'3_ !^T+\7;/6?'\FB3VNO M>,_"VE#3XGN7WA;BW@)(B**R8!S\R9[XH ]"J#5-4TS0],N-:UK48+.SLX'G MN[NZF6.*")%+,[LQ 50 223@ $FN$^%?P&NO!?[-MC^SO\2/BQXE\?-'H$VE M:QXM\2W8_M354E5U>662(+B3:Y4,H!&!W&:G^$?[-_PG^"W[/FE_LO\ A/1; MBY\&Z3H3:/#I^N7\M^\UFRLKQS2SLSRAE=@=Q/!QTH ^!OB%XX^#O[7/_!=; M3_&_Q,\9Z5KGPF_9D_9S_P"%A>%7M9UOM.FUB_NV#ZRGE;UN!#:0CRR@Z!-X@T%/#.G.]YK5LML\J1VL$W MELTT@78D;["78*=O;XQ_;R^ .N?\$Q?VF_AO_P %0/V0/V>3JWPT\(_#V7X< M_&_X8>!]*030>$?M!NK?4K&U4!9&M)B[2+U,0495/,D3Z0^%_P#P4^_X)P_' MGP/X?^)?P>_;*^&EQH(82R+/XIM;&:P39]VXMKAXY;4C(^61$(R..10!\[?\ M%R+.U^./_!)/3O\ @HKX8\!Z_P##[XG?!]M&^(WPZ/BW2?L.M^&[Q;JV-Q87 M<624+Q,T++/X&_^"X?C&R_X)4? M\$_]KJ9C M%^H]A866E6,.EZ;:QP6UM"L5O!$H58T4 *H Z 4 >?ZO\ !\2OV5F_9E^ M/_CS4?%3ZMX(3P_XO\468_LN[U:1K407%Z@MV_T661MTH$;8C9L*< 5MZ/\ M!7X9:7\&+#]GR]\*6VL>$+#P[!H0T;Q$O]HQW5C%"L*Q7'VC?]HRB@,9-Q?D MMDDUU5% %?2=)TK0-*MM"T+3+>RL;*W2"SL[2%8XH(D4*D:(H 554 !0 M*L444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 5C^!_\ D$2_ M]?LW_H5;%8_@?_D$2_\ 7[-_Z%0!L4444 %%%% !1110 4444 %%%% !1110 M 4444 %%%% !1110 4444 %%%% !1110 5Y1^W/_ ,FC^/?^P"__ *&M>KUY M1^W/_P FC^/?^P"__H:T =U\+O\ DF?AW_L!6G_HE*W:POA=_P DS\._]@*T M_P#1*5NT %%%% !1110 4444 %%%% !6/XE_Y"^C_P#7Z?\ T$UL5C^)?^0O MH_\ U^G_ -!- &Q1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%% M% !1110 4444 %8_@?\ Y!$O_7[-_P"A5L5C^!_^01+_ -?LW_H5 &Q1110 M4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 8_B7_D+ MZ/\ ]?I_]!-;%8/BJ_L(?$>A:=->PI<3W4CP0-( \BJHW%5ZD#M;U M !17%_'O]HOX$_LM?#>\^+W[1?Q:T'P9X:L!_I&L>(-12WBW8)$:;CF21L$+ M&@9V/"@GBOA:?_@IG_P4 _X*43OX6_X([_LW?\(QX"N',T63 M,=BBY(01*'5#L,C 5]=444 %%%% !1110 4444 %%%% !1110 4444 %%%% M!7R9^V/_ ,%COV8OV3?BY%^S)X8\'^.?C#\7Y[87'_"K/@]X;;6-5M(F *RW M9#+%:)@JQ\Q]X1@^PJ03ZC_P4(_:3OOV/?V'/BO^T]I%I%<:AX(\":CJFDP3 MKF.2]2!OLRN.Z&8QAO8FO'O^"(W[(/@3]F/]B;P_XTGU"#Q!\4/B98V_BOXQ M^-[J9;C4=6UR^B6[EBN)N6VP?:/+2,X &7VAI7+ 'EWA3_@O;X3^#!M_^&[_ M -@/X^? KPUJ&IF*'XA>*?!XO= M7D?")=W-F[M;L25&"C<[LD!2:_0/PCXN M\*>/_"VG>./ OB6PUG1=7LX[O2M6TN[2>VO+>10R2Q2(2KHRD$,"00>*\Z^" MOQ0_9Y_:Q\ >-_"/A76]$\:Z-HWBO5?!_CC3)K43VT5_"%%WIUQ'*NURJS*' M4@J0^.>:^&/^"#?Q0T?X2_M;_M4?\$PO $7B6#X<_"SQJFL_"G3O%5E-!<:3 M8W?_ +/?Q7^)_P 6M(\2W_Q2 M_9_U7X>SZ+XTU'1](M-6U."Z;6;"W95AU6(P_P"KBGRQ5&^HH_9XU/\ M:9U30-?D_:B\,^$-+U.+Q?J$7AF/P=>SSQ3Z&K@6-O'KZEXFO]735/'>K+>7-D MES)O6QA<(NVVA'RQHS6< MFI^'=7AOK=;B%RDT)DA9E$B."K)G*D$$ USO[.'[,'P6_9,\#WWPZ^!7AB?2 M=)U+Q%?:Y>P7&K7-X9+Z\E,MQ*&N)'*!G.0BD(O\*BM[X9?"+X5?!;P_-X3^ M#_PUT'PKI=QJ$]_<:=X=TB&RAENYW+S7#)$JAI9&)9G(W,>230!A?LV_M0? M[]KKX<2?%K]GOQL=?\/QZS>Z2]^=-N;0B[M)F@N(C'IOVD?A>GQ-G^"GCSX?L^JWED?#GQ'T#^S=306\[Q"8PAW'E2A1)&X8 MAD93QTKOT1(U"(H55& , "EH \__9E\>_'OXE?"6V\5_M*_ *#X9^+);^\C MN?"5OXJ@UI(+=+ATMY1=P*J.9(0DA7:"IL;;]L35?!-] MX]%W=G4[GX>0746E- ;B0VPB2[)E5A 8E?<3EU8@X(KT"B@#S_\ 9A^%WQ<^ M#GP4TOX=_'7]H2^^*?B:SFNWU#QQJ6A6^FS7ZRW,LL:M;VQ\M!%&ZPC;U6($ M\DT?LQ?L[>'OV6?@;I'P%\.>//%WBG3]':Z,>M>/=?;5=4N?M%S+@44 <5^SS^SM\%OV4?@[H_[/\ ^SUX!M?#'@[P^LZZ/H5G M+(\5L)IY+B7!E9G.Z661SDGES71>#?!/@SX<^&;7P7\/?".EZ#HUBK+8Z3HU MA':VUN&8NP2*)51 69F. ,EB>IK3HH **** "BBB@ HHHH *^7OCG_P20_X) MC_&3XE6/Q#^)/["7PQU+6K[46DU'43X3MXI+UR"2\_E*HG8DY+2;B>,]!7U# M6/XE_P"0OH__ %^G_P!!- %?X8_"?X6_!/P9:?#GX-?#?0?"?AZP!%EH?AK2 M(;&SM\\G9#"JHN>^!S70444 %%%% !1110 4444 %%%% !1110 4444 %%%% M !1110 4444 %%%% !6/X'_Y!$O_ %^S?^A5L5C^!_\ D$2_]?LW_H5 &Q11 M10 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% M !7E'[<__)H_CW_L O\ ^AK7J]>4?MS_ /)H_CW_ + +_P#H:T =U\+O^29^ M'?\ L!6G_HE*W:POA=_R3/P[_P!@*T_]$I6[0 4444 %%%% !1110 4444 % M8_B7_D+Z/_U^G_T$UL5C^)?^0OH__7Z?_030!L4444 %%%% !1110 4444 % M%%% !1110 4444 %%%% !1110 445G>)O%_A/P5IQUCQCXHT[2;1?O76IWL< M$8_X$Y H T:*\ ^(_P#P5;_X)E?"3S(_B%^W]\']/GBSYEE_PL+3Y;D?]L8Y M6D_\=KY_^*G_ O!FJ7=QJ$J@ M[8HYFMEMU+-@;FD &K+>:+-(248, OGV[X/ESA0&P5(1U9!_*I_P5'_ M ."G7[2?_!4O]I.]^-OQ]OWL;*Q>6U\(^"[:9C9>'++=_J(U;&Z5L RS, TC M#D*JHB<#^QA^V?\ M!_L"?M!Z)^TM^S3XVDT;Q'HTF'1LO:ZC:L1YMG=19 F M@D 9#@@A64JZJR@']T]%?FM\#_^"S/_ 5(^.7PB\._%;P;_P $!?'M[9>( M=*AN["\?XL:98172NORRI'>0I-'$_P!Y&=1E&5AD$$]5_P /(?\ @ME>?NM' M_P"#=_5'E'+"]_:?\-VZ;?9FA()Z2]]\:C*&]@( MXL@_6C_A>'_!R3>?O[;]AK]FFR0\""\^)NH2./?=&F,4 ??]%? '_"??\'-U MY^YMO@#^QU9L_P!V:[\5>(I$C_W@BY/IQWH_M'_@Z.O_ /CT\.?L(:?L^]]N MO/&,OF9_N^7TQWSZB@#[_HKX _L3_@Z'O/W]QXV_89LV;[T%IIOBZ1$[?*SG M)]>>YH_X5C_PRA_U 'W_17P!_PZ'_;^N_WVK?\ !>[XZO-T MW6?AS2K=,=OD5",^]'_#EW]J>Z'EZI_P76_:D>-_]<+36K&!C_NL(#LY_P * M /O^BO@#_AQO\6KWC6O^"X/[9T@7_5_8?B?!;$>N[;:G=V^GXT?\.$K^Z_?: MI_P6L_;W>9OOFU_:#$$9],(+(@<8^IY[T ??]>&_\%"?^"A/[.7_ 32_9RU M/]H_]H_Q/]FLK;,&B:):LK7VNWQ4F.SM8R1OD;&2QPJ*&=R%4FOG+_B'R^&D M_P"[U3_@J!^VM?0G[UM=_M!S&-O3(%L#P>>O:OE?_@K#_P &JEO\9OV?I_'/ M[*?[3_Q=\:_$SPM%)/HVA?%_Q^=9M]4MR,RV<$LL:&TG8JI1RWELR[7"AA)& M ?C7^UO_ ,%P/V\/VI_V\M+_ &]X?BC>^$M>\(7[-\.=%T6Z)L_#5GN_X]D1 MAMG\Q>)VD4_:,D,NS;&O[4_L;?\ !Q9^VC_P5:\):+^SE_P3[_9-\*:=\:XO M#XN?B1XN^(/B>*#PWX>02>2U]9V<;M>WZ,2C; N87D5&$R_.W\TWB[PCXI\ M^*=1\#^./#E]H^LZ/?2V>JZ5J5JT%Q9W$;%)(I8W 9'5@05(!!!%?OA_P:X_ M\$#_ (F^#_%WAS_@J-^U7+K7A=K>!KGX7>#;>ZEL[J]CFB9/[0OMA5EMWC<^ M7;G_ %P;?(/+VK* ?H?\ _\ @AK\,KWXD6?[3G_!2WXQZU^T]\6;<^;::AX[ M@5/#NA.2&,>FZ*F;:% P'+A\LH=5C:ONF"""U@2VMH4CCC0+''&H"JH& !T M ':GT4 %%%% !1110 4444 %%%0IJ6G27[Z5'?PM=11K));+*#(B$D!BN<@$ M@X/M0!-17'>&OV@O@QXQ^,_B?]GCPQ\0["\\:^#+"RO?%'AV)F^T:=;WBLUM M(X(QB15)&"??&15#P/\ M!67CGX_^.OV?X?A/XYTR;P+::9/+XMUCPZ8="UO M[;"THCT^\WD7,D 4+,A52C.H&[)( /0**\_\ >-?V@=:^/'Q \'?$'X)V.B> M M%CTK_A7WC*W\2QW4_B1I;=GO\ SK15#V7D3;(EW%O-&YP0,"E^'/AG]HO2 MOC?\0_$'Q-^)NA:KX"U-]+_X5KX>T_13!>Z(L=LRW_VNXR1+<,KN .5R <9ZUPWPR^!%[\./C)\ M0_B[)/B7J-K?^.-3AN9F.JW%M!Y$,C([E(RL M?R_NU4'J.?&/PT^&WQ"L-7U[X?:G#IWC/3+4MYFDW4L M7FQQ2Y &63YA@D8JC\'_ -H&S^,/COQ]X#MOA-XY\//X!\0)I,VK>*O#IL[' M76:(2_:=,FWL+N 9VLXVE6&"!QGLM,\,^&]$O[[5=&\/V-I=:G,LVI7-K:)' M)=R!=H>5E ,C!0 "V3@8J]0!Y_\ !CQI^T#XJ\7>/--^-/P4L/">D:/XH:T\ M!:E9>)([]O$.EB-2+V6-%!M'+EE\ELD #D]:7X)>&/VB_#WB#QU=?'?XGZ'X MBTW4O%\UUX M='T0VDFCZ,4016=P^X_:)58.QEP,[L=ACOZ* /G7XK?\$_+3 MXH?LP_'[]G'Q+\?O'/B2W^.3ZY/#+XTUD7T7A1[ZV$45KIJ!%,%E;NB2);DL M V\Y^8BOF;_@WS^,W[/7PN^$>M?\$_\ QGX+L/A?^T;X0\0SO\7_ +J&H2+ M<>)M4$<<3>(K,3.1=17<$,$K- BMR%6-HF?](Z\#_;4_P""87[#'_!0>WL9 M/VK/@!IGB#5-)0+HWB:UGFL-6T\!BRB*]M7CF"!B6$98Q[N2I- '0>-?C=^S M/^Q;\%/$/QJ^-GC;PUX!\+V^IW=_K.JWICM4N;ER6=@JC=<7,A'"J&ED; 8 MX%?+G_!&?PS\2?VCOC9\=/\ @KQ\4O VH^&+/X\:EI>G?"GPYK$/E7=MX0TJ M!H;2\E3/[M[QG,Q0YQL#*2CJ3I_L\?\ !OO_ ,$N_AWXPM/BSXB^">J>/]=T M>]?^QI_B=XMOM>@L0K?+LMKJ5H&QA<%XV(V*001FONM$2-!'&@55&%4# ]* M %HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *Q_$O M_(7T?_K]/_H)K8K'\2_\A?1_^OT_^@F@#8HHHH **** "BBB@ HHHH **** M"BBB@ HHHH **** "BBB@ HHHH **** "L?P/_R")?\ K]F_]"K8K'\#_P#( M(E_Z_9O_ $*@#8HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BO$ M/V\O^"AO[+__ 3B^$2?%W]ICQG+9I?SM:>&_#^EVC76IZ_>A'? TVG MB&Z\.6HM\FRN6*+)+.K ^8T@!W[@%084 'Z T5^?7[4O[:G[=G[2W_!1/6O^ M"8W_ 3.\6^$/ T_PX\*6FN?&'XM>+M".K?V5+>*KV>FV=GN$$_VZ_%7_!*S_@I//X3U;Q_8>#8_&/PW^(_@[3WL;/Q M=H9F,$HEM6)$%U%*&!5,*1%+QB,22 'W?17YJ6_[77_!3S_@IO\ M3_%WX>_ M\$V_C'X#^$?PH^"'BI_"5]X]\3^$/[=OO%?B& 9NX(8F810VL1PN\?.0\;@L M)-L7L7_!*']OWXZ?M)^(_BQ^R!^VKX1T#1/CI\!O$-MIOC+_ (1=I!IFN6-U M$TMCJMJDIWHLT:DLAZ9C;">8(T /LFBBB@ KRC]N?_DT?Q[_ -@%_P#T-:]7 MKRC]N?\ Y-'\>_\ 8!?_ -#6@#NOA=_R3/P[_P!@*T_]$I6[6%\+O^29^'?^ MP%:?^B4K=H **** "BBB@ HHHH **** "L?Q+_R%]'_Z_3_Z":^)/^"FW_!4 MKXM?"'XPR_L3_L0Z?X//Q#T_PBWBKXF?$CXBWC1>&/ACX>!P+Z_*'=+<2=8K M<<_-&Q5U8*?P7\2?\' O_!0+4OVMH4U'_@J7\2+KP';:R(&\;Z3\/-(MF$>X M*;^'1"@B:)>JV\DJR2(N6:-G** ?UMT5^;_[!_\ P5)_:*\)?&;X=?LS_M[> M,O!/Q!\-_&C3GN?@#^TK\.;%U09=O$7B6UL@H]_.D7% '7T5\J?$?\ MX+C?\$A?A7Y@\5?\%$/A;.T6=Z>'_$L>K,".V+'SCGVZUY9+_P '+7_!,+Q# M*]M\"-1^*/Q5F5BJP_#OX0:S=%V'&U3/!""<\=<>] 'W]17Y_?\ #[/]HKQ] MQ^SW_P $.OVJ]9W_ .HF\=>&+3PO#+Z,'N9Y,*>S$=.<4?\ #8W_ <$?$OC MX?\ _!'KX=?#V.3_ %-U\1_CU:ZCQV9HM-B#+_N]10!^@-%?G]_PKS_@YB^) MG_(S_M%?LG?#&&3[O_"&>$M:UFYB7_:_M!A&S#VXH_X=>?\ !67XA?-\=_\ M@OMXZ:*3[]E\./A%HWA[RA_=6>-G<_[Q&: /T!K!\\#_\ !MW_ ,$7/ UY_:R_L4:=K=^[;KB^\5^*-6U5 MYV_O.MU=NA/T4#VH ].^(_\ P62_X)2?"CS$\9_\%#?A$LL6?-MM,\<6=_,A M]#%:O(X/L1FO&]5_X.7_ /@D?/?2:-\*_C+XL^(FHQG:VG^ OAAK=[(6[ ,] MK'&V?9B*^COAQ_P38_X)X_"#RW^&'["_PBT*6/&VZT[X=:;'.2.YE$.]C[DD MU['I6D:5H5C'I>B:9;V=M$,16UK"L<:#T"J !0!\#?\ #];QSXZ_=?L]_P#! M&O\ :]\4[O\ 4:AK?PTCT.PF]"MQ/(TQ_$<8]Z_0"B@#\_O\ AP5IWC7][^T+_P %6_VP?'>__7Z;'[!_@R.#XFP1O=^.? VG0A4\6HHR]W;(.!J MRR#_ (^>H_??ZWP3_@V]_P"#;Q_'ESI'[?O_ 4,\ /'HMK.MS\/?AEK5H5; M4)%(*:AJ,+C(@!P8K=A^](#N/+VK+_0_6/X'_P"01+_U^S?^A4 ; 4!5 MX HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *\P_: MX_;*_9K_ &%?@[>?'?\ :F^*EAX5\.6LBPQSW0:2>]N&!*6]M!&&DN)FP2(X MU8X5F.%5B/2)M4TRWOX=*GU&!+JX5FM[9YE$DH7&XJI.6 R,XZ9K\S_A5-\( M_P!O7_@OO\3M?_:,\7Z%?6?[-=K8>&_@1\.M9U*$FYUJ6T6]UC7(K-VS-/;D MPQ"1581J8G.QXT8 'SA^TMXB_9*_;#_;1\%?\%*/$'_! /\ :I\0VV@,);K4 ME\"VMO'XO6-5-K=W.D/*9+XPJA:,[E\Q/+63>@1%_53]AK_@HK^RC_P4-\#7 M_B[]FOQY)A7(M/%/A/6K%[#6?#]SR/(O+.7#Q'*LH8;HV*,%=MK8ZOXA_ M'GX/^&/CUX)_9]U_Q_86OC3Q1#=ZAX?\.RLWVB^MK91Y\J#&"$R,Y/>OSS_X M+ ^+?"O["?\ P5"_9P_;A^#'PO\ %.E>*/$7B:T\+?&'Q'H^@E?#_B#PQ?74 M5EY&HW*,%.H02O%+;JZY=8\E\01J #]4Z*X#7/&_Q_L_VDM"\ :)\#K*\^&U MYX9NKO7/B"WB:))]/U-) L-BM@5\R173+F96PIX('4IJGAO]HV7]IC2_%>D_ M$G0(?A7#X2GMM7\)RZ,S:E<:RTX:*[2ZSA(5B!0QXY+$^E 'H%0G4=/74%TE MKZ$73PF9;8RCS#&"%+A>NT%@">F2/6N%O/@3?WG[3UE^TDOQO\<0VUGX*D\/ M'X=P:RH\.W#/="X_M&6T*$M>K@1+,&4B/*X()J>3]FKX'R_M))^UZ_@&#_A8 M\?@L^$E\4"ZF$O\ 8OVHW?V,QA_**^>?,W%-VGGXA+X2_X2AO"FYOM0T?[2+7[;C&/+\\^7G.=V>.#5"U_:"L+K]J"Z_9;' MPI\<)=6G@B/Q,?&LGAUO^$Z-L+%;\-M^V[@TGV) MCXT'AVP_MDV(LCJWV1/M)M@Y<0>;C?Y8:NUP4DT]K#:)(E2("3SB2K;@HPU5CQP>? MKW]% 'G_ (>^!-]H/[1_B+]H63XW^.;ZWU_P]9Z5'X O=:#^']-:!V8WEM:[ M,QW,F=KN'PP'*YP1/X:_9K^"'@[X]>)OVGO#7@&WM/'?C+2;+3/$WB%+F8R7 M]K: BWC:,N8QL#$!E4,>Y-=S10!1M/#'AJPUV[\46/AZQAU._CC2^U&*T19[ ME4&$620#? M2I9%"R26[NI:%V4!2R$$CC.":_/+_@@=_P G4_M_?]G;:U_Z-GK]*J^-_P#@ MEC^PW\M1\7>#_P"R]0,[G3IWD9//4JOE2889 M7G'K0!XO_P $=58?\%C/^"C9UG_D)_\ ">^#\>9]_P"R?9-2\G&?X=FW_P = M]J3]KT,?^#H+]DDZ1_KQ\&?%AU?9U^R_9M0\K=_L^=T]ZZS]J;]BK]O']FS_ M (*):U_P4W_X)E^&O!WC:;XC^%;31/C#\)?&.MMI7]K2V:JEGJ-G>;3'',D2 M)$1)@ !B YE/EZG[ _[#7[8WBS]NSQ5_P55_X*40>%-(\?W_ (-C\'?#CX;^ M#M0:^L_".AB8SRF6Z8 3W4LA8EDRH$LO.)%CB //_P#@U@5U_87^*?\ :'_( M4_X:6\6?VWN^_P#:]MENW?[6W9^E)^R4&/\ P=$?M7'2?^/8?!+PJ-6V=/M7 MDZ=Y6[_:\K./:IX?V1/^"H/_ 3*_:F^+OQ%_P"";7PE\ _%SX3_ !M\5R^+ MK_X?^*?%AT*^\+>(IP!=SP3,IBEMI2 Q0?, D: )Y>^7V#_@D]_P3_\ CK^S M5XD^+/[8'[:OB_0=<^.GQY\0VVI>,AX7#G3-#L;6-HK'2[5Y1O=88V*LYZ[8 MUR_EB1P#[+HHHH \O^*WQY^)7P^\7/X<\+_LR^*/%-HL"2#5M)GA6%F8_\ 8!?_ -#6@#H_AGXCU5/AOX?1?"5XP&AV@#!EP?W* M _DX_-BOZ(_\ @YT_X)%_\%$/^"B/[9GA MSXB_L9?L1?VUHVA>!8-/UWQJGC?1;%];N1/-*D1MKJ^CD(MTD*K(T89C,Z\J MB&OQ&\1_\$W/^"A'A/X@CX5>(/V'_BQ!XB:X,,.DCX?Z@\L[9 _=A82)5.1A MD)4@@@D&@#I/V7D5NJRSJF[8KN! ME@NYL GC<<=30!^6'Q1_X(V?LT:'\0_!G@#XX>)_VU/V@CXOUUM-U?4M:^,= MUJ-GX?Q#YPN-3-L;/_ 7@.V_X).WO MB.\\>:Y)IMCJ,ECJ'B.UT^1(C*T^H2WMU*MM"0,!V!!8X KVS]K'_@B!^P%^ MV#\;-2_:;\=>$O%WAWXF:M%;QWOCWP+X_P!3TJ_=8(8X(0%CF, V1Q1J#Y6? ME&WP9^?\ 8Z_X+J?&[28H>;?3?C'H^G^.(2H_Y9;[I8F1,< @ M$J.G2@#U?4O _P#P3H_8S\?^ /AMH'["7@OPKJOQ"UN32?"K>$_A59(ANHXC M*WG2VUOB ;1]^0@$]\UZO\4/VN/A!\"O'/@/X3_$JXFT;6_B/J\ND>!=+^QR MR'4KJ*+S7A0Q(R1;8QG,A1<=ZT?@!HO[27@/]G72])_:0\:Z-X\^)&GV%R=7 MU?P[I@TRTU6<2RM L<+'$.8S$A).-P9N :^/)O\ @LC^UK\)'0_MJ?\ !#/X M_P#AO[*V9=3^&'V#QS9VQP093+9M$43')8 D ]Z /L#XA_M0?#/X3^,O"/P] M^(^J1:/K?CS5)=.\':;>SA9=6NHXS*\,([L$&X].*N^+_P!H'P#\/O$OA_P; MX]UO3=$U?Q;>O9^%M,U?6;>VN-8N43>\%K'(X:XD"?,40,P'.,5\H_#7_@O7 M_P $<_C_ /$/1/!/B;XS0>'/'-KJ*)HV@?$WP+?:7?V-W*1&HCDNK?RHY&)" M?)+D]*^RO%GPK^%_CWQ#H/B[QS\.- UK5O"MZ]YX7U/5M'@N;C1[ET,;S6LD MBEK>1D)4O&5)4X)Q0!1UWXN:%X7U73-"\3"#3K[6[EK?1K.^U*&&6_F5=QCA M1V!E8+R54$@FBFN6*V\4DZ*TI R0H)RQ YXJEX^^!7P? M^*7C+PI\0_B)\.M+UC6_ NHRW_@_4[ZV#RZ1!OBG\3_ 4.K:_P##;5YM4\$:C+=31MI=W+%Y,DJK&ZJY,?RXD# = M0 >: .A_X275_P#H4+W_ +Z6C_A)=7_Z%"]_[Z6N7^+/[,OPE^-GQ*\ ?%GQ M_IE_/K7PSUBXU/PG+:ZO<6\4-Q-#Y,AEBC<)<+LZ+(& /( -'Q8_9U\*_&#X ME^ /BEKOC#Q3IU[\.M7N-1TJQT+7I+2SOY)H?)9+V%1BZC"\JCYO9?#WA?71:Z;XD6:'ROL^IP[";F)#B1%#+M?)YS1\5_@_P"._B%\3OA_ MXZ\,?'KQ!X5TSP?JUS=Z]X9TF*)K;Q3')#Y:6]VS@LJ1M^\&S!+=>* .H_X2 M75_^A0O?^^EH_P"$EU?_ *%"]_[Z6N7^*WPW^-OC#XG_ _\6_#3]HB7PAX> M\-ZK=7'C?PLGA>VOE\6VLD&R*V:XE(>R\N3]YYD0+-]TX%+\5O"G[0^N_%#X M?ZW\)/BSI&@^%-)U2ZE^(FAW^@BZN-=M&@VP0V\Q(^RLDOSLP!W XH Z?_A) M=7_Z%"]_[Z6C_A)=7_Z%"]_[Z6N7^*MA^TW=?%+X?W7P7\0>#K3P;;ZI=M\3 MK7Q#:7$E_=V9@Q;+I[1?)'()N7,O!7@_P#?2UR_Q4\5?M$:)\5/A]H7PE^%&CZYX2U;4KR/XBZ]J&NB MVGT*U2#=;R6\&";II)?D*C&T%8X8!+'-=ASN996S&NS)W#GBOCO_ (.0?VK/B7\!/V![GX,? M"?PGXHCU?XT:C!X-7QWI-AOTWPO!=75K!<->S;@8&GMYYH8<&=0?3_$/Q1UCQ1!H7A.VNTQO@MKJ5 M6.HNN0&$6,;E=2Z$,<&S_P""PG[:7[%MK#K'_!4G_@FEJ7@OX?7&H^3=_%[X M8^*H_$>DZ1))($!O[9$%Q:0AB!YQ+9+*JHS5]9?#^3X"_P#!/C0O@I^PE\+? MA-XEAT35[:XT/PK/X>\.M<6&GFRMA/)-J5PF%@>;+OYK@F:4R$_,3F_\0OBQ MX,T;7_"?[-OCSX%>+/&&F_%J]UG2;V[TOPJ-1T33;>*V,DJZO(6VV\$R,8D+ M*PD8E3CK0!WWA'XIZ;X_\*Z;XY\#V/\ :^C:S817NDZKIUW'-;WEM*@>.:.1 M25=&5@P8'!!!K1_X275_^A0O?^^EK\UO^"*WQ@^)_P"S3XW^(7_!,7PK\&_% M'C7P'\-?VC/$_AK0/&EM>QM;^"_#QMH]1L;>\,AWRYEFFA4J20S8(4 "OT!^ M)OCGX^^'/C'\//"?PS^!5KXC\':]=ZBGQ"\6S>)X;.3PO%%;A[22.U=2]]Y\ MQ,9"$&,#<<@T =1_PDNK_P#0H7O_ 'TM'_"2ZO\ ]"A>_P#?2UR_Q,OOVG+? MXR_#RT^$6A>#+GP#/._#6G> ]/N-2/Q-T?5=+DFO]5C>V"V*V4RG; 8Y]SR%@ M=RX4=Z .H_X275_^A0O?^^EH_P"$EU?_ *%"]_[Z6N7^)/PX^-_BGXU_#OQY MX _:)D\,>$/#,VIOXZ\"KX5MKQ?&"SVRQ6BM>2,);'[++OF'E9\TL%?A11\1 M_@IXD\>?&[X=_%W2_CIXL\/:?X%DU1]2\&Z-=(FF>*?MELL$:Z@C*3(MN0TL M04C$C;CG&* .H_X275_^A0O?^^EH_P"$EU?_ *%"]_[Z6N7^(W[.WAGXF?'' MX=_'K5?&OBNQU'X:OJK:3I&D:\]OIFI&_MEMI/M]L!MN_+1^#'OO&?PH.K'P%JZZIDQ12+%/YD*A, M3*X7DKM8YH U=3^+.B:)XCTOP=K*0VFKZWYW]BZ5=:C#'$/#M[J44=YK LXA- M=&VB)W2B*,AWV@[5()K2\8? CX.^/_BEX/\ C;XT^'>F:EXM\ ?VA_PA>OW4 M&ZYT?[="L%WY#?P>;$JHWJHQ6KK7P\\ >)/%NB^/O$7@;1[_ %WPV+G_ (1W M6KW3(I;O2_M"".X^S3,I>#S454?81O4 -D"@#A/'?[7GPF^&?QN\!_LX^.;V M?3_&OQ.35&\"Z');2NVK#3K=;F]VR(AC3RH65SYC+D'Y=QXIOCO]J[P[\//C MIX#_ &?-<^'/BN76_B+%JDFA7=CH[S6,(L(%GG^U7"_);$HZA ^-[<#FO49+ M2UEN([N6VC:6(,(I60%D!ZX/49P,_2I* /*_''[2/B;P9\.X=>MH8?#+6\*O;));./,N#<2-Y:^6?DVEFXKU2 MB@#RKQM\2/VF]/\ COX(\-^!/@/8:A\/M0MM2;QYXDO-;$5[I,L<*FR2WM\? MOQ+*2KG(V*N>XIOC;Q#^UNWQ\\$2?#OPUX17X7K9ZE_PL:+6%NCKSW'E+_9_ M]G-&?LXC\PN9O.&[:%V')->KT4 >3^-;7]IK5/C_ ."?%_@CQC!I?P]TNQU) M/'/@^XT"*>ZUR>2)5LI(;LL&M1"^YV !\P8''6CQIX.^,WB/]H'P5\5_#_Q1 M\0Z+X6\-V&I0>(?A];Z;;26GB.6XC5;>:6=CYD)MV#.H3ABW/2O6** /)_&7 MPIUOQC^T'X,^/J^//B5I*>#=.U&T;P1HWB)(= UW[7&J"74;0H?M,D&W="P9 M=C,3\W2CQA\$/"'CC]H3P;^TSK7ACQ,OB3P+INHV.B1VNN2163Q7J*DWGVRM MY<[ *-K."4/(KUBB@#R[Q3\$OA1XU^.WA7]IGQ/\$I;OQUX)TV^L/"_B%KN1 M9+"VO%"W,817$;APH!WJQ&.,5^>7Q"U3X4_\$J_^"VGB3]K?]J'X1:=:?#+] MHFSLAX2^+.K:;"X\!>+(;46=W927; FR@U"W1)&E+*K,B@X2*5D_5ZN?^*7P MH^&7QP\ :G\*OC'\/]'\4^&M9M_(U70M>TZ.ZM+J/(.'BD!5L$ @XR" 1@@& M@#G-0U#PEXPUCPY\3[3PC8WLT$;/HVNQK!,S6\J MY$XSA' !.UMK #K7Y^_ MMF_M Z)_P5Q_;C^%/[ /[+-L?%'@CX._$G3OB%\?_&NCS)/IMDVG%VL="2X0 MF.6>>8GS%1LQA 028YE3M_%/_!M9_P $HXMY5VB MW9V[@"2N<'&>N* *7_"2ZO\ ]"A>_P#?2T?\)+J__0H7O_?2UPOQ9_;D_8I^ M GB.X\'_ !T_;!^%O@O5[14-UI7BSX@:;IUS"'570O%<3(R[E=&&1R'4C@BO M*?$G_!<+_@D+X5S_ &G_ ,%%?A1+MZ_V;XKAO/3_ )]R^>O\_0T ?2'_ DN MK_\ 0H7O_?2T?\)+J_\ T*%[_P!]+7/_ +.?[27P._:V^$>F_'C]G+XBV7BO MPCK$EQ'INN:>DBQ3M!,\$H D56^62-UY ^[QD8-?'EY_P[EL? S M_%?Q;+%(T93PW\'=9EW,"00/,@C[@B@#[C_X275_^A0O?^^EH_X275_^A0O? M^^EKX8/_ <%_#G5^/AU_P $O?VU/%F[_5OH/[/\S(WH2TMRF!TYQQFOK_\ M:5^+_P 0/@M\!-:^+?PK^ >N_$K7].AMGTWP)H-Q%;WVI-+<11,JO-\B>6DC M2MN_AB;O0!U'_"2ZO_T*%[_WTM'_ DNK_\ 0H7O_?2U\,?\/+/^"R_B3CX? M?\&^'B%D?[L_B;]H?P_IFP'^)D:-F.,J2HY^\.U=]^R_^T9_P64^)?QTT+1_ MVF_^"<'@+X9?#RX:X/B#6;;XP0:UJ5H!;2M (H8(U20M/Y*-V"EV':@#ZI_X M275_^A0O?^^EK\IO^"X'_!P"W_!//]NOX$_ /PG8F2QTG6X_$'QIM5"RR_V+ M<(]K%:KC.)0CS7FWY6W06O.V1@?KW_@KO\?OV^/V6O@#-^T/^QWK_P "M*\- M>#M#U75?B9J'QGBU>25((DA-I'IL>G,HDGD;ST*2D!G:!5.2:_CV_:G_ &F? MBS^V1^T-XM_:>^.>MQW_ (J\9ZN]_JLT$92*,D!8X8E))2**-4B12252-1DX MS0!_^(L7BW0+'Q5X8T:6_P!-U.SBN].OK2='BN8)$#QR(P.&5E(8$<$$ M5<_X275_^A0O?^^EK\>_^#/']OSXN_M(_ 3QM^R]\:OC;;:U_P *IT[1[3P# MX9GTJ.*[L-'/VI7D-P#NNHPQ@@"L/W"PQ#)$H ^W?VI?V1?^"MGQ7^.NN>+_ M -F?_@K[8?";P'?BV_L;P?\ \* T?7I]+V6T23?Z7=2JT_FSI++\P&P3;1P@ MH ^I_P#A)=7_ .A0O?\ OI:/^$EU?_H4+W_OI:^&/^';?_!:N^^;7?\ @X>U MB1C\KG3_ -F7PY:@KZ +,<'K\W^%?7_[+?PL^+/P6^!6A_#/XY?M!ZA\5/%. MF_:O[3\>:IHL&G3ZGYEU++'NM[/VW;\[==_X+R?M#R(WS.-/L],M3N]BL9VC_ M &:3_AR1\?;\[M?_ ."Y7[7?VY]F_ MXK'X7>)/[(UW3_)NHKC_ $:[V/Y6_P KRG^4[HI)%XW9'R!_Q#X_"^Y^76_^ M"G/[:FIIU$5_^T'.RAO[WRVPYZ_F: /N?_A)=7_Z%"]_[Z6C_A)=7_Z%"]_[ MZ6OEC]EO_@C%\!_V4?CKH?[0GA;]ICX_>)]:T'[3Y-GX[^+5UJEA=&>UEMF, M]LZA)=J3,RYQM=4;JM>@?MS_ /!-3]FG_@H=_P (O_PT1+XO4>$/MO\ 9(\* M^,KS2-PNO(\T2_9G7S?^/:/;NSM^;&-QH ]G_P"$EU?_ *%"]_[Z6C_A)=7_ M .A0O?\ OI:^&/\ B&/_ ."0EQQK7P9\9:DH^XE]\6=?8(?4;;P&KJ2R\175G831)NEAO=5@B9%QG)#,"!CG-8%_\ MM?\ P$TO;_:?Q3\*6V_.SS_%UBF['7&9>>H_.O*/VB/^")O_ 2W_:Q^-FL_ MM%_M$?LBZ-XH\:>('MFUG7+W5]01KDV]M%;0YCBN%C 6&"),!0#MRU 'TYX2^+.B^/_ [!XO\ M D<.MZ3=;_LVJ:1J,-S;3;':-]LD;%6VNK*<'AE(/(->2:C_ ,%5O^">VCM( MNK?MI_!ZU,2YE%S\6=%38,9R=UR,<$=#69=)T#2(/+M[42S23R[5YQNEED<^K.3WKQO3O^".G_!)_2Q&MM_P3=^" M+>6V5^T_#/39L\YY\R$[OHYX M&Z62-!ZLX'>N.L?^"6__ 3*TM633/\ @G3\";=6.6$'PBT5 3ZG%M7L7C/P M1X+^(_AJY\&?$/PAI>O:/>;/MFDZUI\=U;3['5TWQ2JRMM=589'#*".0* /C M[4?^#A;_ ()#:8)#<_MM^"6\O[WV?4FFS]/+0[OPS6_^S]_P6_\ ^";7[5/Q MIT?]G?\ 9Z_:.TKQ5XSU]+AM(T/3;:ZWW(@@EN)<.\*Q@K%#(Y!8'"^XS[OI MW[*'[+6C^6=)_9J\ 6OD_P"J^S>#;%-GTVQ#%=#X=^%OPQ\(W27OA/X$?MP_P#!6;]BS_@F\?#(_;2^(USX*/C' M[9_PC8?P_J%_]L^R>1]HQ]BMYMFS[3#]_;G?QG!QX(O_ =&?\$A[SC0?C!X MJU0MS"NG_#/76,R_WEW60R,<\XXK]#]JE@Y49 P#BEH _)C_ (*+?\'+?[-5 ME_P3K^)WQ _9"U/Q/'XUF%KX8\*76N^&;O2FBO\ 48[G%W!]IC1I/LT%M:N?RR_X-4_^"EMU^QE^WL?V>O'FK.?!7QM,&D2I-/A+77E9O[/N M,MP#(TDEL<8W&XC).(Q7,_\ !T!_P4B_X;R_X*+:G\// NO?:OA_\'//\->' M/)EW0W=^)!_:5ZO8[YT6%6!(:.TB8?>-?G'I^H7^D7\&JZ5>S6UU:S++;7-O M(4DBD4@JZL.58$ @CD$4 ?WO?\)+J_\ T*%[_P!]+1_PDNK_ /0H7O\ WTM? M,'_!$/\ X*)6'_!3+_@GEX-^/>I:C#)XPTV'^P?B';1X!BUFU1!+(5'"K.C1 M7*@_\ ?2UL44 8_P#PDNK_ /0H7O\ WTM'_"2Z MO_T*%[_WTM;%% &/_P )+J__ $*%[_WTM'_"2ZO_ -"A>_\ ?2UL44 8_P#P MDNK_ /0H7O\ WTM:\;%XU=D*DJ"5/4>U+10 4444 %%%% !1110 4444 %%% M% !1110 5Y1^W/\ \FC^/?\ L O_ .AK7J]>4?MS_P#)H_CW_L O_P"AK0!W M7PN_Y)GX=_[ 5I_Z)2MVL+X7?\DS\._]@*T_]$I6[0 4444 %%%% !1110 4 M444 %8_B7_D+Z/\ ]?I_]!-;%8_B7_D+Z/\ ]?I_]!- &Q1110 4444 %%%% M &-XN^'/P]^( M1X]\!Z-K8L;A+BR&KZ7%<_9YD8,LB>8IV,& (88((!K@OV MR/V*_P!G[]O3X/CX&_M(^'-2U'08]6@U2U72?$%WIL]O>0AQ%,LMK)&Q*B1_ ME8E,D$J2 1ZM10!^?G_#C?XM_"3]]^Q?_P %C/VF/A^$_P"/71_%?B6#Q9I% MKZ".SO8UPOJ"YSZU[!^Q3\'/^"L?PD^*M]IG[:O[97PY^+G@ :%*NFZGI?P\ M.@Z\VI>=#Y321P.;40>5Y^X+EM_EXXW&OJ.B@#Y;_;5_;_\ VBOV0_BO9:%X M5_X)D?%KXN^!9M"BN[WQI\+9+2_N;>[::99+,:8SK-(4C2*3S-P#&;:!\I)\ MM\._\')'_!,:WU>'PO\ M Z_\1/@KK^&&J:7,&[JSQQ30ICN6D ] MZ^]JI>(O#7ASQ?I$WA_Q9X?LM4L+@8GL=1M$GAD'HR."I_$4 ,/^"$7A?3/%NJ_$+]EG_@HO\ M-?"+5=5U&>_N-/\/_$^2]T9[B61 MI'9[&[1PXWL2%W@#)% 'WE17Y^#]E?\ X.&/@4=WP;_X*:**86PF;&$#O+ACDK&1R: /1**_/V'_@XY_8S\!3+9?MA_ + MX_\ P!G#!)I/BK\'K^&W#=,K+9BXWH3T; R"#Q7T;^S5_P %.O\ @GK^V#K- MKX7_ &:_VQOA_P"+-;O4=[3P[8^(H4U2941I'9;*4I<$*BLS'R^ I)QB@#W6 MBBB@ KP/_@I[^Q7;?\%"/V&/B!^RG'KB:3JGB#3(Y_#.LN6 T_5K6:.ZLIBR M@LJ">&,.5^;RV<#DU[Y10!\*?L$?\%H?@]XZTB+]F/\ X*#>*-,^"G[1G@V" M/3_'?@WQ]>Q:7#JES&H7^T=-N)BL-U;W !E18W+*&. R!97V?VH/^"TO[%7[ M)/@.70_!_P 2=,^*?Q0UB]EM? _PD^&^HQZMK&N:@[%8(3':F0VT;-UED ^5 M6V"1@$/T+^TI^Q]^R-^UAH,6G_M5_L\^"?'%GIL;/:S>+= M[I[%?O,T4TBE MX!QR49,B[VF5XF4J0I;'/3.: .:_X(X_L>_$GXV?"KPA\;/ /P0\2^-[&S\5^,CJ-UX8T2>3$VHQ64<;731COY:S1 ML1UP21G:<>A4 %%%% !1110 4444 %%%% !1577-=T3PQH]SXA\2:Q:Z?I]E M"TUY?7UPL4,$:C)=WO^*?$ M^K1:9H.E:)/-=&\NY6VQQ+)%&T8+$@ LP&3UKN_VV_V\/@S^P-X$TCX@?&?P M]XRU2VUS5O[-TVS\$^$KG5[J2X\IY<&. $H-B,=S8'&,YQ0![317Y_\ _#_K M0O$?[OX1_P#!)S]M/Q;N_P!5>6/P,:"S.?NEIIKE=H/8E>F:]K_8C_;E_: _ M:Q\;:QH?Q0_X)R?$_P"#.BV&E"ZT[7OB'-:)_:$WFJAMU@B9G1@I+Y8XPIH M^E:*^5/VQ/C7_P %<_"/Q@/@S]B']B3X<>+_ D=+@E7QIXV^)/V#%TQ;S(3 M9QH9=J84[@<-OXZ&O*OM/_!SWXTYATW]BOP5;/SBXF\3ZE>1^WRXA/\ ^KWH M _0"BO+?V/O#?[7OA7X.II?[;WQ*\'^*_')U*>275/ VCRV-@+4[?*C6.4EM MR_-ECUR*^8_&/_!+?_@H[\1?%^JZQXM_X+M_%2QTF]U*>:PT;P?\/='TDV-N M\C,D FCW,^Q"J!R 3MR1DT ?=U%?G_\ \.#QXE&_XM_\%?/VU/$V[_6V1^-O MV.S?_MC#:C!_X%7U_P#%3]F'X/\ QT_9POOV4?C-HEYXD\%ZMH$6C:S97VJS MQSW]JBH,27$#QRAVV LZLK$Y.1F@#3\8_'_X$?#LN/B!\;/".A&,XD_MGQ): MVNWZ^9(N*_-C_@X:_P""W_[-OP+_ .">OBCX9?LE?M0^"/%OQ)^(H;PU9P>" MO%]GJ-SHEE.C"\OI1;2LT&( \,;':WFS(RY\ML?07A#_ (-W?^"*W@) VD?L M!^$95C7[VM7]_J/'7)-W\/:S-87-W'INLQA(IHO+MHY) MQ $.X* M0&M%''F$U^P#?\'.7_!'O4V,?@#XZ>+/%C X"^'/A1X@ER?;S+),]_R-?R0? M"WXE^,_@Q\2_#_Q=^'.L/I^O^&-9MM5T6^0 F"Z@E66-\'@@,HR#P1P>#7]N MG_!.W]L[P'_P4$_8Q\ _M:?#]888/%>B))J>FQ/N_LS48R8KNS/?]U.DB G& MY0K=&% '/?L/?\%-O@=^W[KVOZ'\&_AI\3M'3P]9P7%QJ'CKP#=:/;72RLRA M;=Y_]:P*'< !C@]ZY;]K;_@IM\6OV;OC5>_!?X=_\$NOVA/BI]CL[><>+/!/ MAFW;1+@RQA_+CNI)AN=/F5QM&UACG(-?6E% 'P ?^"J?_!4OQ!_R3S_@W[^) MESG[G_"2?%C1-(S]?-#XZ']/6OK7]DOXF?M%?%WX*6'CC]J?]F-?A!XRN+JX M2]\"KXTM/$'V.))2L3_;;15BD\Q 'P -N[!Z5Z510!\%:Y\1?^#D_7]:O+?P M+^SE^R7X?L1=2+8W'BOQ?KMV[1!B$=ULU&"5P2![U5_X5_\ \'-OBC_D._M! M?L>>%M_WO^$9\*>(;[9_N_;&&<9[^@]37W_10!Y_\=_ ?Q\^(G[/>J^ O@I\ M>X/AU\0+_3H(M.\?Q>%X-7CTNY#QF69;&Y(BG#*LBA'( W@]17R!_P .M?\ M@J_XBY^(_P#P<$_$&ZW?ZW_A&?@SH6CY]=OE,^WJV/3*_P!VOO\ HH ^./V; M?^"5WQM^"?QNT#XV?$C_ (*T_M&?$;^PYY)9/"/B'Q';1:)J1>%XMMS:Q0_O M$4R%U&X89$.?EY]/_;C_ .">GPB_;]TWPYH_Q=^(_P 1M!M?#4]S+;P^ /&U MQHPO#.(PRW)AYF5?*&T$C;N;'6O>** /@#_B&2_X)&:M_P E$^$OC?Q?G[__ M DOQ:U^7?\ 7RKR.OH7]BO_ ()A_L*_\$[9M=N?V-?@#:>"9/$T-O%KTMOK M-_>->) 9#"&-W/*?E,LF,8^^:]ZHH \7^*G_ 3C_8!^.OQ-O?C/\@>'?#_ (4TJ/0O"^A6>FV,.?)L M["U2&),DDX1 ,DDG ZFKE%% !1110 4444 ?GK_ ,'$'["/_!0;_@I-^S9X M<_93_8QU3P?IOAV]US^T_B%=>)_$$UF]XMOM-G:(L<$N^/S2TS[MN'@@QGFO MQCO?^#.__@K/87%O;3^(_A%NN9-D>WQC=XSC//\ H5?U35C^)?\ D+Z/_P!? MI_\ 030!^"7_ 2(_P"#>3_@LA_P3'_;R\%_M2V?B'X5W&@VMPVF^.-*LO&= MT7U#1+@A;F-5-F [IA)XU) ,L$>2!FOZ!:** "BBB@ HHHH **** "BBB@ H MHHH **** "BBB@ HHHH **** "@@$8(R#U!HHH \1?\ X)F_\$WY7,DG_!/S MX(LS'+,WPHTQOM+_9_P#@1X-\"VVI MRI+J5OX.\+VFF1W4?MS_\FC^/?^P"_P#Z M&M>KUY1^W/\ \FC^/?\ L O_ .AK0!W7PN_Y)GX=_P"P%:?^B4K=K"^%W_), M_#O_ & K3_T2E;M !1110 4444 %%%% !1110 5C^)?^0OH__7Z?_036Q6/X ME_Y"^C_]?I_]!- &Q1110 4444 %%%% !1110 4444 %%%% !1110 4444 - MFAAN(7M[B)9(Y%*NCKD,#P00>HKSG1OV./V2/#GQ:LOCYX;_ &8?A_IOCC3A M,++QAIO@^RM]3B$L;12J+F.,2X9'=2"V"&->D44 ?.O[* MC^U=\;/A5KGA2WN8M(U7X/\ CUM&9Q.T;.+A/+=9QF)!AATR 1DUX-_P[_\ M^"VWP/\ WG[./_!:&T\:V$7_ ![^&_C?\)K.ZW8Z>9J5HPN6SW^4>O>OT#HH M \/_ &'K[_@HK<>$=]?:],N;FWL[>2[NYTBBB0O++(P544#)))X M[T ?B[_P7-_X./\ ]BWQE_P34\0_#G_@GY^T?:^*O&GQ,8^')A9:?>65UHNE MRHQOKB2.ZAB>,M%FW7@'=<%E_P!6:Q/^#.[_ (*8Z1XS_9T\7?\ !/[XP^+K M>VU#X9Q3^)/"%WJ-TL:MH$LF;N,LQP%MKA_,))X2[ &%C./R!_X+G_M]:1_P M46_X*/>.?C;X'CMD\&Z9<_V#X)-K J"YTZU9E%XV "[W$AEGW-\P65$)^05X MI^Q=^TM>?LD_M)>'/C6V@KK6D6DLUCXN\-3.1%KVAW<+VNI:=)R/EGM)IHLG M[I<,.5% ']L5]^V+^R+I85M3_:G^'%N')V&?QQ8)NQZ9FYI=&_;#_9'\1ZQ: M>'O#W[4WPYO]0O[F.WL;&R\;V$LUQ,[!4CC19BSNS$ * 220!7S;\%O^"-O_ M 0[^,/PO\/_ !H^%'["'PSU;PYXMT2UU;1-1.DM*MQ:3Q++$X#N=I*N,C@@ M\'I7>^!_^",?_!*KX:^-='^(W@+]@WX<:3KN@:I;ZEHNJV6@JDUG=P2++#-& MV?E='56![$"@#W[X@_%'X9_"31(_$OQ5^(FA>&=-EN5MXM0\0ZO#90/,RLRQ MB29E4N51B%SDA2>QKA+[]O3]AG2RJZG^V?\ ">W+@[!/\1=,3=CTS/S6Q^TA M^RK^SG^U_P"!+?X8?M/?!O0O''AZTU2/4K;2/$-D)X([M(Y(TF"GHX2650?1 MSZUXQ8_\$0?^"0^GAA;_ /!.GX3MOQGS_",$OY;P+M5AM&NIM,\,>,+*_N(X%95:5HX)68(&=%+$8!=1GD4[XH_ MM1_LR_ _78/"_P :?VBO GA#4[FT%U;:=XH\766GSRP%F02K'/*K,A9'4,!C M*,,Y!KE?V?/^"=W["O[)_C:?XD?LT?LF> O NOW6FOI]SK'ACPW!:7$EH[QR M/"7C4$H7BC8KTRBGM3_VA_\ @GQ^P[^UKXPM/B!^TW^REX$\>:W8::NGV6J^ M*/#L%Y/!:+))(L*O(I(0/+(VWIEV/>@""^_X*1_\$[=,D$6I?M[_ 6MW9-])M+UK.ZU3PAXBMM2M MX;@(CF%Y+=W59 DB,4)R ZG&"*\4L?\ @C1_P29T^,Q0?\$W_@LP9LDS_#K3 MY3^;Q$CZ5Z_\!OV:/V>/V6O"EUX$_9K^!_A3P%HM]J#7]YI/A#08-/MY[IHT MC:=XX%56D*11J6(SA%'0"@#EO%/_ 4,_8#\#>)M0\%^-OVX_@_H^LZ3>RV> MJZ3JOQ,TJWN;*XC8I)#+%)_\ !5/_ ()@:;-]GU'_ M (*/_ 6"3;G9-\8-%4X]<&ZIOC;_ ()6_P#!-#XD^,=5^(7Q!_8#^#^MZ]KF MH37^LZSJOP\TZ>YOKJ5R\L\LCPEI)'=F9F8DDDDU6LO^"2'_ 2LL(?(@_X) MK? 5EW9S-\(M&D/YO;$_A0![+!\6/A9<_"X?'&V^)?A^3P4VA?VVOC!-9@.E MG3/)\_[=]K#^3]G\G]YYV[9L^;..:\@_X>Q?\$LO^DEG[/\ _P"'DT/_ .2J M]?@^$_PLM?AFC0#2QIGD^1]A^R!/*^S^3^[\G;L MV?+C'%>0?\.G?^"67_2-/]G_ /\ #-Z'_P#(M $OAS_@JA_P3.\9>,M-^'G@ MW_@H)\&-9US6=0@L-(TK2/B7IEU/>W4SK'%!$L4[&21W9555R2S 8S7HWQV_ M:/\ V?\ ]E[P=!\0OVD/C5X6\!Z#K>0 M:3XN\/VVI6T=PJNBS+%<(Z"0+(ZAP,@.PS@F@#QG_A\/_P $H/\ I)'\#_\ MPYVF?_'JZWX"_P#!0C]AG]J;Q[=?"_\ 9M_:U^'_ ([\0V>FOJ%UI'A/Q1;7 M\T=JCQQO.5A=OD#RQ*6Z NH[U2_X=E?\$W/^D?/P/_\ #3Z/_P#(U=?\)_V3 M?V5_@-K3^(_@;^S1\/\ P9J+VC6CW_A/P;8Z=,T#,KM$7MXD8H61&*YP2JG& M0* .=_:'_P""A'[#O[)7C"T^'_[3?[5W@3P)KE_IJZA9:5XH\106<\]HTDD: MS*DC E"\4B[NF48=JX+_ (?6_P#!(_\ Z2-?!_\ \+BT_P#BZ]D^*/[+G[,W MQPUV#Q1\:?V=? GB_4[:T%K;:CXH\(V6H3Q0!F<1+)/$S*@9W;:#C+L<9)KF M_P#AWM^P+_T8]\'_ /PVFE?_ "/0!O?LY?M7?LW?M>^$+[X@?LP?&OP]X[T3 M3=6?3+[5?#6HKO*?B#_P63_X)9?"GQWK/PP^( M_P"W;\.M&\0>'=4GTW7-(O\ 7E2>RNX)&CEAD7'RNCJRD=B#7NWPU^$?PH^# M.@OX6^#_ ,,?#WA33);@SR:=X:T6"Q@>4JJF0QP(JEMJ*N[&<*!V%0/,SC[M<]_PQ%^Q?_P!&B?"__P ('3O_ (S7PM_P M<]?M_>'?^"?7_!,NX_9^^%7V+2O%/QG[/'B>0Z#\(M?MK+ MX41R%TANM-LY6,LCH<'9>NT[." WDSK&WW*_?SX ?\'(?_!*S]I/Q/X(^'/P MN^+?B/4?%?C:]TS3X] M?A]K#?V9?WCQ1BWN;DVJVZB.24*\JNT8"E@Q'-?Q MYU^_O_!F5_P4CP?%?_!,7XF:]U\[Q1\,OM$OT_M&P3/_ "Z1!_T],: /V@_ M;4_:WF_8S^%=C\3;;]F+XL_%F74=?BTJ'PU\'/"(UG4X6DAGE%S-"98_+ME\ MG8TN3M:6,8^;(^7O^'PO[<_BP9^$G_!!?]H.]W?ZK_A,=2TS0,_[WG.^VOT MHH ^8/V*?VHO^"D?QX^*&H:1^UU_P3!B^!OA"#09;C3->G^,FE^(KF]OA/"J M6S6UE&IA5HGFW-?4G[%_P@_:K^"OPGNO"W[87[7Z?&OQ70^*XO -GX<2ULVBA5+%;6T=D<(Z2OYI(9O.P1\HSZY10!\-_$W_@BGXD^, MOQ(\0^.O'?\ P5S_ &O[*PUO7+N^MO"G@_XLII.FZ?#-,\B6D<<=LS&&)6"* M"V<(N36'_P 0VG_!/K7O^2M^/OCEX_W?ZT>,?C3JLWFYZAO)DBZ]^E?H!10! MQ,W[.?P8O/V>(_V4M7\#P:CX 3PE'X9?P[J<\MQ'-I26XMA;R/(QDD'E*%+, MQ8]223FO*O!W_!(3_@E=X"*R>&O^"=7P6CD0YCN+KX;Z=?AE+%/\-O@/X,\// 087T/PO:6AC(Z;3%&N,>U=G110 44 M44 %%%% !1110 4444 5M:T;2?$>CW?A[7M.AO+&_MI+>]M+F,/'/$ZE71E/ M#*RD@@]0:^>?^'/'_!*#_I&Y\#__ V.F?\ QFOH^B@#Y;\'_P#!('_@E3=Z M7))=?\$X_@E(PNY5#/\ #/3"Y=41YC%"JKO98T!;&2$7TK;\#_ /((E_Z_9O\ T*MB M@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *Q_$O M_(7T?_K]/_H)K8K'\2_\A?1_^OT_^@F@#8HHHH **** "BBB@ HHHH **** M"BBB@ HHHH **** "BBB@ HHHH **** "L?P/_R")?\ K]F_]"K8K'\#_P#( M(E_Z_9O_ $*@#8HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB M@ HHHH **** "BBB@ KRC]N?_DT?Q[_V 7_]#6O5Z\H_;G_Y-'\>_P#8!?\ M]#6@#NOA=_R3/P[_ -@*T_\ 1*5NUA?"[_DF?AW_ + 5I_Z)2MV@ HHHH ** M** "BBB@ HHHH *Q_$O_ "%]'_Z_3_Z":V*Q_$O_ "%]'_Z_3_Z": -BBBB@ M HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ KGOBU\+_"/Q MM^%_B'X.^/X+N;0O%.C7.E:S#8ZC-:32VL\;12HLT#))$61F&Y&5AG@BNAHH M _/#_B%8_P""'/\ T:-J'_AR-?\ _DVLWPM_P:T_\$1-3TZ2XO/V2M09UN9$ M!'Q'UXU^D-8_@?_D$2_P#7[-_Z%0!RG[*_[+7P8_8O^!FB_LW?L]Z# M>Z5X/\.B9=%TR^UJZOVM4EF>9T6:ZDDD*;Y'(4L0H.!@ "O0Z** "BBB@ HH MHH **** "BBB@ HHHH **** "BBB@ HHHH **** "O!/VL?^"7_[!7[<_C+3 MOB!^UI^S=H_CC5](TS^S],N]6N[H?9K;S&D*(D_X-[_^",UKJ6F0V_[ OA!5FNBLH%U??,-N_!/_ ((G_P#!+/\ M9Q^*FB_&[X'?L<^'O#/BSP[=_:=%US3;Z]6:UD*LA*YG((*LRE2"&5B"""17 MT=XE_P"0OH__ %^G_P!!-;% !1110 4444 %%%% !1110 4444 %%%% !111 M0 4444 %%%% !1110 4444 8_@?_ )!$O_7[-_Z%6Q6/X'_Y!$O_ %^S?^A5 ML4 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !6/X ME_Y"^C_]?I_]!-;%8_B7_D+Z/_U^G_T$T ;%%%% !1110 4444 %%%% !111 M0 4444 %%%% !1110 4444 %%%% !1110 5C^!_^01+_ -?LW_H5;%8_@?\ MY!$O_7[-_P"A4 ;%%%% !1110 4444 %%%% !1110 4444 %%%% !1110 44 M44 %%%% !1110 4444 %>4?MS_\ )H_CW_L O_Z&M>KUY1^W/_R:/X]_[ +_ M /H:T =U\+O^29^'?^P%:?\ HE*W:POA=_R3/P[_ -@*T_\ 1*5NT %%%% ! M1110 4444 %%%% !6/XE_P"0OH__ %^G_P!!-;%8_B7_ )"^C_\ 7Z?_ $$T M ;%%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 M 5C^!_\ D$2_]?LW_H5;%8_@?_D$2_\ 7[-_Z%0!L4444 %%%% !1110 444 M4 %%%% !1110 4444 %%%% !1110 4444 %%%% &/XE_Y"^C_P#7Z?\ T$UL M5C^)?^0OH_\ U^G_ -!-;% !1110 4444 %%%% !1110 4444 %%%% !1110 M 4444 %%%% !1110 4444 8_@?\ Y!$O_7[-_P"A5L5C^!_^01+_ -?LW_H5 M;% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 5C^ M)?\ D+Z/_P!?I_\ 036Q6/XE_P"0OH__ %^G_P!!- &Q1110 4444 %%%% ! M1110 4444 %%%% !1110 4444 %%%% !1110 4444 %8_@?_ )!$O_7[-_Z% M6Q6/X'_Y!$O_ %^S?^A4 ;%%%% !1110 4444 %%%% !1110 4444 %%%% ! M1110 4444 %%%% !1110 4444 %>4?MS_P#)H_CW_L O_P"AK7J]>4?MS_\ M)H_CW_L O_Z&M '=?"[_ ))GX=_[ 5I_Z)2MVL+X7?\ ),_#O_8"M/\ T2E; MM !1110 4444 %%%% !1110 5C^)?^0OH_\ U^G_ -!-;%8_B7_D+Z/_ -?I M_P#030!L4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 M %%%% !6/X'_ .01+_U^S?\ H5;%8_@?_D$2_P#7[-_Z%0!L4444 %%%% !1 M110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% &/XE_Y"^C_ /7Z M?_036Q6/XE_Y"^C_ /7Z?_036Q0 4444 %%%% !1110 4444 %%%% !1110 M4444 %%%% !1110 4444 %%%% &/X'_Y!$O_ %^S?^A5L5C^!_\ D$2_]?LW M_H5;% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 M5C^)?^0OH_\ U^G_ -!-;%8_B7_D+Z/_ -?I_P#030!L4444 %%%% !1110 M4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !6/X'_ .01+_U^S?\ MH5;%8_@?_D$2_P#7[-_Z%0!L4444 %%%% !1110 4444 %%%% !1110 4444 M %%%% !1110 4444 %%%% !1110 5Y1^W/\ \FC^/?\ L O_ .AK7J]>4?MS M_P#)H_CW_L O_P"AK0!W7PN_Y)GX=_[ 5I_Z)2MVL+X7?\DS\._]@*T_]$I6 M[0 4444 %%%% !1110 4444 %8_B7_D+Z/\ ]?I_]!-;%8_B7_D+Z/\ ]?I_ M]!- &Q1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4 M444 %8_@?_D$2_\ 7[-_Z%6Q6/X'_P"01+_U^S?^A4 ;%%%% !1110 4444 M%%%% !1110 4444 %%%% !1110 4444 %%%% !1110!C^)?^0OH__7Z?_036 MQ6/XE_Y"^C_]?I_]!-;% !1110 4444 %%%% !1110 4444 %%%% !1110 4 M444 %%%% !1110 4444 8_@?_D$2_P#7[-_Z%6Q6/X'_ .01+_U^S?\ H5;% M !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 5C^)? M^0OH_P#U^G_T$UL5C^)?^0OH_P#U^G_T$T ;%%%% !1110 4444 %%%% !11 M10 4444 %%%% !1110 4444 %%%% !1110 5C^!_^01+_P!?LW_H5;%8_@?_ M )!$O_7[-_Z%0!L4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !11 M10 4444 ?D1^RE^SAI?_ 7\^._QX_:M_;$^*OCR;X7>!_BK?^ O@Q\._"WC M&[TC3[*#3UC,NK2+;.K2W,WG1,')^4^8IW*L83V+_@C?\5OC)\#/VPOVB/\ M@D%\;OC#KWC^W^#%UI6M_"[Q;XJO#*],UZQDXEBD M<,R]0"0Z@]S&P[4 MG[%*?\)__P ',?[8'Q"\-,+C2O"GPL\)^'-4NX>8UOIK>TG$9(XW 6\RD=08 MV':@#],:*** "O*/VY_^31_'O_8!?_T-:G^*WA3]K/5_%SWGP?\ BOX7TC13 M @2RU;0GN)A(!\[%P1P3T%>:_&/]G_\ ;Z^*_P +];^'5[\>_ 31:O8M ROX M;FC!R01EE)(&1V% 'OOPN_Y)GX=_[ 5I_P"B4K=KXQTKX!_\%H=$TNVT;3?V MPOA9';VEND-NA\)D[410JC)MLG@#DU8_X4O_ ,%K?^CR/A9_X2/_ -S4 ?8U M%?'/_"E_^"UO_1Y'PL_\)'_[FH_X4O\ \%K?^CR/A9_X2/\ ]S4 ?8U%?'/_ M I?_@M;_P!'D?"S_P )'_[FH_X4O_P6M_Z/(^%G_A(__1\+/\ PD?_ +FH_P"%+_\ !:W_ */(^%G_ (2/_P!S4 ?8U%?' M/_"E_P#@M;_T>1\+/_"1_P#N:C_A2_\ P6M_Z/(^%G_A(_\ W-0!]C5C^)?^ M0OH__7Z?_037RC_PI?\ X+6_]'D?"S_PD?\ [FKB/BGH_P#P6'\!>,_!7AK7 M?VM/AS<7/B?7&L=,EM?"2[(91&7+2;K<';@8XR1\+/\ MPD?_ +FH_P"%+_\ !:W_ */(^%G_ (2/_P!S4 ?8U%?'/_"E_P#@M;_T>1\+ M/_"1_P#N:C_A2_\ P6M_Z/(^%G_A(_\ W-0!]C45\<_\*7_X+6_]'D?"S_PD M?_N:C_A2_P#P6M_Z/(^%G_A(_P#W-0!]C45\<_\ "E_^"UO_ $>1\+/_ D? M_N:C_A2__!:W_H\CX6?^$C_]S4 ?8U%?'/\ PI?_ (+6_P#1Y'PL_P#"1_\ MN:C_ (4O_P %K?\ H\CX6?\ A(__ '-0!]C45\<_\*7_ ."UO_1Y'PL_\)'_ M .YJ/^%+_P#!:W_H\CX6?^$C_P#1\+/_"1_^YJ/ M^%+_ /!:W_H\CX6?^$C_ /C_\%A_BYX,N_$OA/]K3X6,D5_X27>989"CL M-MN1M)Y'?% 'W[17QS_PI?\ X+6_]'D?"S_PD?\ [FH_X4O_ ,%K?^CR/A9_ MX2/_ -S4 ?8U%?'/_"E_^"UO_1Y'PL_\)'_[FH_X4O\ \%K?^CR/A9_X2/\ M]S4 ?8U%?'/_ I?_@M;_P!'D?"S_P )'_[FH_X4O_P6M_Z/(^%G_A(__1\+/\ PD?_ +FH_P"%+_\ !:W_ */(^%G_ (2/ M_P!S4 ?8U%?'/_"E_P#@M;_T>1\+/_"1_P#N:C_A2_\ P6M_Z/(^%G_A(_\ MW-0!]C45\<_\*7_X+6_]'D?"S_PD?_N:C_A2_P#P6M_Z/(^%G_A(_P#W-0!] MC45\<_\ "E_^"UO_ $>1\+/_ D?_N:C_A2__!:W_H\CX6?^$C_]S4 ?8U%? M'/\ PI?_ (+6_P#1Y'PL_P#"1_\ N:C_ (4O_P %K?\ H\CX6?\ A(__ '-0 M!]C45\<_\*7_ ."UO_1Y'PL_\)'_ .YJ/^%+_P#!:W_H\CX6?^$C_P#1\+/_"1_^YJ/^%+_ /!:W_H\CX6?^$C_ /)?^0OH_ M_7Z?_036Q7P%\4]'_P""P_@+QGX*\-:[^UI\.;BY\3ZXUCIDMKX279#*(RY: M3=;@[<#'&3FNW_X4O_P6M_Z/(^%G_A(__1\ M+/\ PD?_ +FH_P"%+_\ !:W_ */(^%G_ (2/_P!S4 ?8U%?'/_"E_P#@M;_T M>1\+/_"1_P#N:C_A2_\ P6M_Z/(^%G_A(_\ W-0!]C45\<_\*7_X+6_]'D?" MS_PD?_N:C_A2_P#P6M_Z/(^%G_A(_P#W-0!]C45\<_\ "E_^"UO_ $>1\+/_ M D?_N:C_A2__!:W_H\CX6?^$C_]S4 ?8U%?'/\ PI?_ (+6_P#1Y'PL_P#" M1_\ N:C_ (4O_P %K?\ H\CX6?\ A(__ '-0!]C45\<_\*7_ ."UO_1Y'PL_ M\)'_ .YJ/^%+_P#!:W_H\CX6?^$C_P#1\+/_"1_ M^YJ/^%+_ /!:W_H\CX6?^$C_ /1\+/\ PD?_ +FH_P"%+_\ !:W_ */(^%G_ M (2/_P!S4 ?8U%?'/_"E_P#@M;_T>1\+/_"1_P#N:C_A2_\ P6M_Z/(^%G_A M(_\ W-0!]C45\<_\*7_X+6_]'D?"S_PD?_N:C_A2_P#P6M_Z/(^%G_A(_P#W M-0!]C45\<_\ "E_^"UO_ $>1\+/_ D?_N:C_A2__!:W_H\CX6?^$C_]S4 ? M8U%?'/\ PI?_ (+6_P#1Y'PL_P#"1_\ N:C_ (4O_P %K?\ H\CX6?\ A(__ M '-0!]C5C^)?^0OH_P#U^G_T$U\H_P#"E_\ @M;_ -'D?"S_ ,)'_P"YJXCX MIZ/_ ,%A_ 7C/P5X:UW]K3X1\+/\ PD?_ +FH_P"%+_\ !:W_ */(^%G_ (2/_P!S4 ?8U%?' M/_"E_P#@M;_T>1\+/_"1_P#N:C_A2_\ P6M_Z/(^%G_A(_\ W-0!]C45\<_\ M*7_X+6_]'D?"S_PD?_N:C_A2_P#P6M_Z/(^%G_A(_P#W-0!]C45\<_\ "E_^ M"UO_ $>1\+/_ D?_N:C_A2__!:W_H\CX6?^$C_]S4 ?8U%?'/\ PI?_ (+6 M_P#1Y'PL_P#"1_\ N:C_ (4O_P %K?\ H\CX6?\ A(__ '-0!]C45\<_\*7_ M ."UO_1Y'PL_\)'_ .YJ/^%+_P#!:W_H\CX6?^$C_P#1\+/_"1_^YJ/^%+_ /!:W_H\CX6?^$C_ /6,D5_X27>989"CL-MN1M)Y'?% 'W[17QS_ ,*7_P""UO\ T>1\+/\ PD?_ M +FH_P"%+_\ !:W_ */(^%G_ (2/_P!S4 ?8U%?'/_"E_P#@M;_T>1\+/_"1 M_P#N:C_A2_\ P6M_Z/(^%G_A(_\ W-0!]C45\<_\*7_X+6_]'D?"S_PD?_N: MC_A2_P#P6M_Z/(^%G_A(_P#W-0!]C45\<_\ "E_^"UO_ $>1\+/_ D?_N:C M_A2__!:W_H\CX6?^$C_]S4 ?8U%?'/\ PI?_ (+6_P#1Y'PL_P#"1_\ N:C_ M (4O_P %K?\ H\CX6?\ A(__ '-0!]C45\<_\*7_ ."UO_1Y'PL_\)'_ .YJ M^MO"EOXBM/"VFVGC#4(+O5HM/A35+NUBV137(0"1T7^%2^X@=@10!H4444 % M%%% !1110 4444 ?$'[0_P#P1FO_ !-^TYXG_:]_8B_;>\??L\>,_B!;PQ?$ M>+PE86NH:7XB>(;4NI+.Y 6.Z"EAYRGJS,%#/(S^P?\ !/'_ ()U?!C_ ()R M_"K5O GPUU[7O$VO^*]=EUWQ[X^\7WPNM7\2ZI+]^YN9<#@9(5 ,+EB=SN[M M[_10 4444 %%%% !1110 4444 %%%% !1110 4444 %>0?M'^!?%WBSXL?"3 M6_#F@SW=IH?C"2ZU:>$ K:PF!E#MSTSQ7K]% !1110 4444 %%%% !1110 4 M444 %%%% !1110 4444 %%%% !1110 4444 %>0?L4^!?%WP^^$^I:)XTT&? M3KN;QAJEU'!< !FADG+(_!Z$OT44 %%%% !1110 4444 %%%% !1110 4444 %%%% !111 M0 4444 %%%% !7D'[1_@7Q=XL^+'PDUOPYH,]W::'XPDNM6GA *VL)@90[<] M,\5Z_10 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 M %%%% !7D'[%/@7Q=\/OA/J6B>--!GTZ[F\8:I=1P7 9H9)RR/P>A'(KU^B M@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** M"BBB@ HHHH **** "BBB@ HHHH *\%_X*<7?[;4'[$'CJR_X)U^%8M5^,%_8 MQ67A-9M1M+7[&99D2>Z5[R1(?,B@,KQAVQY@3((!!]ZK&^(?Q"\#_"7P)K'Q M/^)GBJQT/P]X?TV:_P!:UC4K@16]G;1(7DED<\*JJ"30!^6?[3O_ 0G^#?[ M+_["OC+]JFP_;0^-.E_'CP#X!O/$UW\:KSXJ:@TUYJMI:OW"X\IY%6%P4V[%NF:,H50C0U*7]HK_@Y3\7PZ98Z?KOPQ_89T M36EDN;VX5[36_C#/;2Y"QKPUMIJR)U/)9<_-*-MKTW_!<7P9X5^!GQ__ ."> MGC/0]!M-#\">!?VC=+\.K#:PB*STJ&X2VCM4 'RQQI':/CL%C/I0!Y[_ ,%$ MO^"=MM_P1-_9J@_X*:?\$^OCK\4(_%7PNUS2KKXC:+XL\>W>J6/Q TNXO(+2 MZCOH9B4$I:99-\:J$&\JH<1LGTE_P4!^"W[97_!2;XF? ?X6? _QQXF\%?LQ M^*-(E\1_&'QMX-\3V^G:QJ$3VWFV&EI^\%PL4O D,:LI%P"W^KQ4G_!R_P", M=$\'?\$3/C>([7P1H?AOPUX%T:'S=7\2:U'801"QMHNI;>/G<_* M@(SEF16 /C3]M#]F/0/^"&'[2?[-/QD_X)]?&7Q]96WQ/^-6F^!?&_P:Q8>)["\)$EY'%=.[)<1':HD!.U[B$@*-PD^X/^"D_[3'[>?PXE\.?L\_\ M!.O]E*X\9_$#Q[:7?E^/]?E$'ACP1#&T:&\OY"#YLO[PM%;CE_+8@2;3&WB? M[!O[ '[4G[4'[46F?\%:/^"M%K;V?CG3K21/@M\$K.7S-.^'%C*/]=/GB;4G M4@LQY0_,WSK'';?HO0!^:7_!K%X@^)WB7]@;XAZA\9?'M[XG\3K^T-XGCUO7 M;^Y>62\N0EEYLN7YPTF]LZ"OTMK\U?^#6[_DQ[XJ?]G,>+O\ VSK]*J " MBBB@ HHHH **** "BBB@ HHHH **** "BBB@ K\\/CO_ ,$Y/VH/^"D?_!1+ MQZ?VY?%'C+PY^S%X+T/3;7X4>"_!GCU=/@\87\T1:]OM0%E-]H!AD#(J2B,[ M9(MAP)@_Z'U\;_\ !3G_ (*KO^R#XDT#]DS]EGX63?%?]I'XAP'_ (03X;Z> MW[JSB.Y?[3U.0$"WLT*NQRREQ&_S1HKRH ?.'[*&@>)O^"9G_!=;2O\ @FC\ M!/CAXO\ %WP;^(_P=N/%=QX'\8>(9M6?P/?P33JDEO/,6DBAE$&W8Q^8W +; MBL;5S_[*7[.&E_\ !?SX[_'C]JW]L3XJ^/)OA=X'^*M_X"^#'P[\+>,;O2-/ MLH-/6,RZM(MLZM+=$PK^+/VM?VM/ MB$ MOV4OC=\#]:80^(? G[3WBO3->L9.)8I +7#,O4 D.H/1+:WTR.PF:U55B$&F%QI7A3X6>$_#FJ792.H,;#M57]JO\ ;H_:;_X* MJ?&;Q-_P3<_X)&:TVB^%M&NFTKXY?M-,C-8Z#&/\ M7-0MT?Q%#"T*6]Y/<73B*:6!)FN TKD.GE(Q8Y+6K_\ X-__ (<>'?V-;SX^ M_M _MA?&G3OVB-/\#R^(/$?QFE^+-\)-&UB.U-S-M1)O(^R0RJR8'S&)#B0' M##[Q_9%_91_9M_X)G?LE:7\!OA)'!H'@KP5I:U\-_P!B_2M7-KX[^*;P MM;ZK\3V@D_>:?I:.,Q619%])@TW0M(LE(CM;:) B(,Y)X'+$EF.2222:Z*@ MHHHH **** "BBB@ HHHH **** "BBB@ HHHH \%_X*<7?[;4'[$'CJR_X)U^ M%8M5^,%_8Q67A-9M1M+7[&99D2>Z5[R1(?,B@,KQAVQY@3((!!^%/VG?^"$_ MP;_9?_85\9?M4V'[:'QITOX\> ? -YXFN_C5>?%34&FO-5M+5[EQ+"\GE_9I M94,>P#?L<#>[9+?J9\0_B%X'^$O@36/B?\3/%5CH?A[P_ILU_K6L:E<"*WL[ M:)"\DLCGA5502:_+#4I?VBO^#E/Q?#IECI^N_#']AG1-:62YO;A7M-;^,,]M M+D+&O#6VFK(G4\EES\THVVH!G_M$?\%-OVQ?C)_P1W_9-T?P%XNE\'?&S]K; MQ3HG@JY\8:?!Y$VF02RM#>:O;A<>4\BK"X*;=BW3-&4*H13_ ."B7_!.VV_X M(F_LU0?\%-/^"?7QU^*$?BKX7:YI5U\1M%\6>/;O5+'X@:7<7D%I=1WT,Q*" M4M,LF^-5"#>54.(V3T+_ (+B^#/"OP,^/_\ P3T\9Z'H-IH?@3P+^T;I?AU8 M;6$16>E0W"6T=J@ ^6.-([1\=@L9]*]4_P"#E_QCHG@[_@B9\;FUBZ1'U2PT MK3;"%C\T]Q-J]FJH@_B(&Y\#LC'M0!'_ ,% ?@M^V5_P4F^)GP'^%GP/\<>) MO!7[,?BC2)?$?QA\;>#?$]OIVL:A$]MYMAI:?O!<+%+P)#&K*1< M_J\5\S? MMH?LQZ!_P0P_:3_9I^,G_!/KXR^/K*V^)_QJTWP+XW^#FO\ C6\UBP\3V%X2 M)+R.*Z=V2XB.U1("=KW$) 4;A)]E_%G]N/X/?\$CO^";GPOUS]HU-0O/$=KX M(T/PWX:\"Z-#YNK^)-:CL((A8VT74MO'SN?E0$9RS(K>4?L&_L ?M2?M0?M1 M:9_P5H_X*T6MO9^.=.M)$^"WP2LY?,T[X<6,H_UT^>)M2=2"S'E#\S?.L<=L M =7^VA_P3M_:<_X*(?MWV?AW]HCXJZQH/[*7ACP8);+PCX$\8S:=>>*_$+R+ MO.I& )(+=(V8(JN0#$"I4R/7C7[!UOJO[#G_ 70\4?\$S?V9OCAXK\<_!6[ M^"J^+-:\*^)?$LNL_P#"O=;6\\E;>*XF9Y(4DB,;F%FRWVM&.=@)^X_'?Q<_ M9!_:U\??$O\ X)K:U\2WOO%FG^%(G\?^$--N+VPO;72[V.,K(EU&J8#I-&"T M,A9/,&2I(K\[?"7[/GA;_@A]_P %K/@=^SO^Q!K=_P#\*O\ VI+768O'?PXU M:Z_M"?3;S3K?S(=2@NY@UR$S)G;([C$=SDGFVOPH\%^#/'JZ?!XPOYHBU[?:@+*;[0##(&14E$9VR1;#@3!_-_P!E M#0/$W_!,S_@NMI7_ 31^ GQP\7^+O@W\1_@[<>*[CP/XP\0S:L_@>_@FG5) M+>>8M)%#*(-NQC\QN 6W%8VKZ/\ ^"G/_!5=_P!D'Q)H'[)G[+/PLF^*_P"T MC\0X#_P@GPWT]OW5G$=R_P!IZG("!;V:%78Y92XC?YHT5Y49_P $KO\ @E_X MF_9#U?Q9^UK^UI\3A\2/VD/BN$E^(GC@KBWL8 59-)TY2H\JTBV1CA5W^3'\ MJ+'&B@'RG^RE^SAI?_!?SX[_ !X_:M_;$^*OCR;X7>!_BK?^ O@Q\._"WC&[ MTC3[*#3UC,NK2+;.K2W,WG1,')^4^8IW*L83T[_@E/\ &;]HO]G3]H[]J#_@ MDQXY^(&N?%;4?@=:V7B'X+ZQXNU0/J6J:-J%F)X--NKN0@,89)+:(2M@ RR# MY$1%6#_@UX0>$OV4OC=\#]:80^(? G[3WBO3->L9.)8I +7#,O4 D.H/"D, M\B6UOID=A,UJJK$(Y1_K$#/MV_*<^A?\&Z_[2OQU^-?[//Q7^#WQL^+5[\2( M_@I\;M:\"^%?B;J$ADG\1Z7:>6899I229I 'W>826*2Q DD%FXS]JO\ ;H_: M;_X*J?&;Q-_P3<_X)&:TVB^%M&NFTKXY?M-,C-8Z#&20_\)/XON)\#2;>2,CS(;&(.TW./.D0%3MC M8_N]7\X7_!2?]I?2OAI_P1Z\%_L)?#;_ ()2_M*_"SP[X6\/XR^)W@5; M*WU6]2=Y9Y9Y@YWWEU*SN!T+':,*J@?O;^Q]^T=KW[5?P/LOC'XD_9U\>_"R MZO+RY@?P?\2M'^P:K;B*0H)'AW'".!N4YY!!H ]0HHHH **** "BBB@ HHHH M **** "BBB@ HHHH *\%_P""G%W^VU!^Q!XZLO\ @G7X5BU7XP7]C%9>$UFU M&TM?L9EF1)[I7O)$A\R* RO&';'F!,@@$'WJL;XA_$+P/\)? FL?$_XF>*K' M0_#WA_39K_6M8U*X$5O9VT2%Y)9'/"JJ@DT ?EG^T[_P0G^#?[+_ .PKXR_: MIL/VT/C3I?QX\ ^ ;SQ-=_&J\^*FH-->:K:6KW+B6%Y/+^S2RH8]@&_8X&]V MR6S/VB/^"FW[8OQD_P""._[)NC^ O%TO@[XV?M;>*=$\%7/C#3X/(FTR"65H M;S5[<+CRGD587!3;L6Z9HRA5"-#4I?VBO^#E/Q?#IECI^N_#']AG1-:62YO; MA7M-;^,,]M+D+&O#6VFK(G4\EES\THVVO3?\%Q?!GA7X&?'_ /X)Z>,]#T&T MT/P)X%_:-TOPZL-K"(K/2H;A+:.U0 ?+'&D=H^.P6,^E 'GO_!1+_@G;;?\ M!$W]FJ#_ (*:?\$^OCK\4(_%7PNUS2KKXC:+XL\>W>J6/Q TNXO(+2ZCOH9B M4$I:99-\:J$&\JH<1LGTE_P4!^"W[97_ 4F^)GP'^%GP/\ ''B;P5^S'XHT MB7Q'\8?&W@WQ/;Z=K&H1/;>;8:6G[P7"Q2\"0QJRD7 +?ZO%2?\ !R_XQT3P M=_P1,^-S:Q=(CZI8:5IMA"Q^:>XFU>S540?Q$#<^!V1CVKKOBS^W'\'O^"1W M_!-SX7ZY^T:FH7GB.U\$:'X;\->!=&A\W5_$FM1V$$0L;:+J6WCYW/RH",Y9 MD5@#XT_;0_9CT#_@AA^TG^S3\9/^"?7QE\?65M\3_C5IO@7QO\'-?\:WFL6' MB>PO"1)>1Q73NR7$1VJ) 3M>XA("C<)-_P#X+5:YX)_:&_X*S_ []C#XR_MC M>(O@S\,?"_PD\0>./B3XE\.?$%/#C"*XF%G9"2ZE/E _:K2, 2*QVRN% +YK MU7]@W]@#]J3]J#]J+3/^"M'_ 5HM;>S\"+"+7/ M 7BM)+S3M*TYQ&]M=?8IXOL\K8N%(.9 IGR5#$$ '+?\$M_^"?/[ 7A;XL6_ M[57[&O\ P4]^*_QM70(;BSNM-U7XX6OB/28FN(6CQG]N7Q1XR\.?LQ>"]#TVU^%'@ MOP9X]73X/&%_-$6O;[4!93?: 89 R*DHC.V2+8<"8/\ H?7QO_P4Y_X*KO\ ML@^)- _9,_99^%DWQ7_:1^(W[JSB.Y?[3U.0$"WLT*NQRREQ&_ MS1HKRH ?.'[*&@>)O^"9G_!=;2O^":/P$^.'B_Q=\&_B/\';CQ7<>!_&'B&; M5G\#W\$TZI);SS%I(H91!MV,?F-P"VXK&U<_^RE^SAI?_!?SX[_'C]JW]L3X MJ^/)OA=X'^*M_P" O@Q\._"WC&[TC3[*#3UC,NK2+;.K2W,WG1,')^4^8IW* ML83ZL_X)7?\ !+_Q-^R'J_BS]K7]K3XG#XD?M(?%<)+\1/'!7%O8P JR:3IR ME1Y5I%LC'"KO\F/Y46.-%\:_X->$'A+]E+XW? _6F$/B'P)^T]XKTS7K&3B6 M*0"UPS+U )#J#W,;#M0!/_P2G^,W[1?[.G[1W[4'_!)CQS\0-<^*VH_ ZULO M$/P7UCQ=J@?4M4T;4+,3P:;=7^*VH?'WQ5J%]>7UOH'Q1EM;+P4AGD2VM],CL)FM558A' M*/\ 6(&?;M^4YV?V*4_X3_\ X.8_VP/B%X:87&E>%/A9X3\.:I=P\QK?36]I M.(R1QN MYE(Z@QL.U5?VJ_VZ/VF_^"JGQF\3?\$W/^"1FM-HOA;1KIM*^.7[ M33(S6.@QG*SZ;HY4C[3>LNY/,1ACDH47_2% /-_V&/\ @JQ\>/V;_P#@CW^U M3\5_C!\2YOBE=_LR?$G7/!/P[^(NMN96\4(DMO;:8]U)DM<$7%U"6?<6:*5 M6)&XYGA__@EY^S7\1/@?HNN?MH?\%6O$.G_MJ>._#4.O:7KU_P#'?^RKW0=9 MNX5GM;.RTM9TQ:Q.T<11(MS!6,1B!14]#_X+0?\ !/[X6?L8_P#!M9\1OV3O MV5O#$\.B>$+/1=0N6E(DN]3:/7+&>\OKEP!YDK!7E8X"JJ!5"HBJ.H_9^_X( M(_C;JS^?KT^I7MBEU+JBZ@ M[&1 LDAD6/=Y050K*PW9 /M7]A[PW^U9X-_9/\#^$?VWO%7A_7?BGI>C_9/% MVM^&+B26SU"6.1TCN TD,+&1X1$TO[M5$K2!OH*B@#\T?"G_!O7\9O GAC3O!/@G_@ MN1^UEI&C:18Q66E:5IGC406UG;1($CABC3"QHJJ%55 KZ6\;_P#!+_X4 M?';_ ()[0_\ !/;]K+XH>,_BCIRVQ$WC[Q/JV_Q"UVMS)/!?+!_A[ MXNMK6VL%O8!B"?46A!?4WC'(:3:3E@Q9'='Z#_@I/_P1'T/_ (*-_M/^"OVJ M-1_;/^)WPYUOX>Z*++PC!X'FMX5TVO@;_ ((<_M!^#_&NC^+K[_@N/^UEK$&E:I;WDVD:GX[9[:^2*17,$JY^ M:-PNUAW#&OT*HHH \!_X)U?\$_? 7_!./X0>(_@]\//'6K^(+/Q)\0-3\67- MWK4<2R17%[Y6^%1$H&Q?*&">>3DU[]110 4444 %%%% !1110 4444 %%%% M!1110 4444 %?F]\9?\ @WB/Q,_;2\??MT^!_P#@IK\=?A]XT^(-RPU*Y\$: MI!9-;V(\L1:>DJ*)#;QI#"JH2<^4I.2,U^D-% 'QA^QW_P $GOC-^RQ\?-*^ M-7C#_@K%^T5\5+#3;>ZBE\%?$+Q<;O2KPS0/$KRQ$_,T9<2+Z,@-9_[0_P#P M1FO_ !-^TYXG_:]_8B_;>\??L\>,_B!;PQ?$>+PE86NH:7XB>(;4NI+.Y 6. MZ"EAYRGJS,%#/(S_ &_10!\K_LQ?\$HOA+^R1^R'\0OV:?A)\5_&(\2_%.'4 MY_'/Q@U6^2Y\1ZEJM[ \3ZDTS+M$D>\M$N,*5"%7>V!EL9.!Z5^IE% 'PY M>_\ !&7Q7XL_86^(_P"PU\6_^"D_QP\<67Q(U&TEO_%_B[6H[[5+"TA>)WL; M=I0P2"8Q 2+_ !!V'1C7E?P^_P"#=3XH_";P3IGPV^%__!;;]JOP[X>T6S2U MTC0]$\8K:VEE HPL<44>%11Z 5^F]% 'EW['/[.OBC]E;X":7\%O&/[17C; MXJW^G7-U++XT^(6I&[U6[$LSR*DDIZK&&"*.RJ!7J-%% !1110 4444 %%%% M !1110 4444 %%%% !1110!\^_\ !37]@'0?^"F7[*M_^R9XP^,7B/P7HFKZ MM:7>L7OAE83->PV[F1;5Q*K*8S*(I#QG,*^]?*?A3_@WK^,W@3PQIW@GP3_P M7(_:RTC1M(L8K+2M*TSQJ(+:SMHD"1PQ1IA8T55"JJ@ 5^EU% 'S/XW_X M)?\ PH^.W_!/:'_@GM^UE\4/&?Q1TY;8B;Q]XGU;?XA:[6YDG@OEN2&VW$)< M(C$,I1-C*R,RGQ+P;_P0DU[Q7\1_!&N_MT?\%&?BI\??!_PSU>'5/ _P]\76 MUK;6"WL Q!/J+0@OJ;QCD-)M)RP8LCNC_H+10!\-?\%)_P#@B/H?_!1O]I_P M5^U1J/[9_P 3OASK?P]T467A&#P/-;PKILYFDEDO89&4R1W$F^-6=2/E@CQ] MVN:\#?\ !#G]H/P?XUT?Q=??\%Q_VLM8@TK5+>\FTC4_';/;7R12*Y@E7/S1 MN%VL.X8U^A5% 'R)^W'_ ,$D/"/[5'Q]T+]LOX'?M$>,?@?\;/#^D-I$/Q"\ M#"&4:EIQ)86E_:3#R[N-225R5/0-N"($@_8O_P""0?A']G']HV^_;9_:'_:0 M\:?'?XUW6D'2;'QWXZ$,46B6!SOM].LH!Y=H'W.&(+'#N%V"23?]A44 %%%% M !1110 4444 %%%% !1110 4444 %%%% !1110!^;WQE_P"#>(_$S]M+Q]^W M3X'_ ."FOQU^'WC3X@W+#4KGP1JD%DUO8CRQ%IZ2HHD-O&D,*JA)SY2DY(S7 MJ7['?_!)[XS?LL?'S2OC5XP_X*Q?M%?%2PTVWNHI?!7Q"\7&[TJ\,T#Q*\L1 M/S-&7$B^C(#7V?10!\0?M#_\$9K_ ,3?M.>)_P!KW]B+]M[Q]^SQXS^(%O#% M\1XO"5A:ZAI?B)XAM2ZDL[D!8[H*6'G*>K,P4,\C/V_[,7_!*+X2_LD?LA_$ M+]FGX2?%?QB/$OQ3AU.?QS\8-5ODN?$>I:K>P/$^I-,R[1)'O+1+C"G+'<[. M[?5%% 'Y9_!3_@V:U[]FWP.GPS_9\_X+&?M-^"/#L=U)5"%7>V!EL9.!Z5]H_L#_L6^/?V*_!6O>$?'O[:7Q2^-4^LZHEY!J_Q3ULW MUSIR+&$,$#'[L9(W$>IKWNB@#P'_ (*1_P#!/WP%_P %*OV=H?V<_B/XZU?P M[IT/BG3M<74-$CB:8RVCLZ1XE4KM8MSQGTKWZBB@ HHHH **** "BBB@ HHH MH **** "BBB@ HHHH *^??\ @IK^P#H/_!3+]E6__9,\8?&+Q'X+T35]6M+O M6+WPRL)FO8;=S(MJXE5E,9E$4AXSF%?>OH*B@#\T?"G_ ;U_&;P)X8T[P3X M)_X+D?M9:1HVD6,5EI6E:9XU$%M9VT2!(X8HTPL:*JA550 *^EO&__!+_ M .%'QV_X)[0_\$]OVLOBAXS^*.G+;$3>/O$^K;_$+7:W,D\%\MR0VVXA+A$8 MAE*)L961F4_3%% 'Y]>#?^"$FO>*_B/X(UW]NC_@HS\5/C[X/^&>KPZIX'^' MOBZVM;:P6]@&()]1:$%]3>,Z*++PC!X'FMX5TVO@;_@AS^T'X/\ &NC^+K[_ (+C_M9:Q!I6J6]Y-I&I^.V>VODBD5S! M*N?FC<+M8=PQKTS]N+_@D5X._:G_ &@]#_;/^!W[1/C/X'_&S0=(.D1_$'P- MY,HU/3B21:W]I,/+NT4GY^,O\ P;Q'XF?MI>/O MVZ? _P#P4U^.OP^\:?$&Y8:E<^"-4@LFM[$>6(M/25%$AMXTAA54).?*4G)& M:_2&B@#XP_8[_P""3WQF_98^/FE?&KQA_P %8OVBOBI8:;;W44O@KXA>+C=Z M5>&:!XE>6(GYFC+B1?1D!K/_ &A_^",U_P")OVG/$_[7O[$7[;WC[]GCQG\0 M+>&+XCQ>$K"UU#2_$3Q#:EU)9W("QW04L/.4]69@H9Y&?[?HH ^5_P!F+_@E M%\)?V2/V0_B%^S3\)/BOXQ'B7XIPZG/XY^,&JWR7/B/4M5O8'B?4FF9=HDCW MEHEQA3ECN=G=OEOX*?\ !LUKW[-O@=/AG^SY_P %C/VF_!'AV.ZDN4T/PIXE MBL+432$%Y/*A"KO; RV,G ]*_4RB@#YN_9#_ .">5Y^SY\$O&WP'_:!_:O\ MB1^T%H_CDR0ZF?C#J_\ :+QV4MN8)K),](9%+%E[EC7S4_\ P;S^)]!\!7W[ M+7PK_P""JOQR\+_L]ZG)-'=_"*UDLYWAL9G+2Z?;:G*AF@M6W.IB*N&5V#[R MS%OTFHH Y'X!_ GX5_LQ?!GPW^S_ /!'PE!H?A/PEI46G:'I<#%A#"@ZLS$L M[L279V)9V9F8DDFNNHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "B MBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *** M* "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH M **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ MHHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "B MBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *** M* "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH M **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ MHHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "O MY0?V'_V'_P!N3_@KK^W)\=_A1\*/V[O$'@C_ (0CQ!J%^[ZMX@U.6*6)]3FA M6*-891MVX^F.*_J^K\ ?^#3;_E*9^UW_ -O'_I\GH /^(3;_ (*F?])=O_*A MKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_Q MZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B M$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X M*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?] M)=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ M "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H: MY_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ M'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_? MZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@# M\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^ M(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ M (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F M?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])= MO_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*A MKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_Q MZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B M$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X M*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?] M)=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ M "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H: MY_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ M'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_? MZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@# M\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^ M(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ M (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F M?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])= MO_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*A MKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_Q MZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B M$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X M*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?] M)=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ M "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H: MY_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ M'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_? MZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@# M\ ?^(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^ M(3;_ (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ M (*F?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F M?])=O_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])= MO_*AKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*A MKG_QZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_Q MZC_B$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^(3;_ (*F?])=O_*AKG_QZC_B M$V_X*F?])=O_ "H:Y_\ 'J_?ZB@#\ ?^#0KQ9\:/^&Y/VBOA1\5_C%X@\5?\ M(KX?BL$?5M:N;F+S8=3DA:6-9G;9NV?7!Q7[_5^ /_!IM_RE,_:[_P"WC_T^ M3U^_U !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 M4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1 M110 4444 %%%% !1110 4444 %%%% !1110 5^ /_!IM_P I3/VN_P#MX_\ M3Y/7[_5^ /\ P:;?\I3/VN_^WC_T^3T ?O\ 445R?B_X\_ WX?:RWASQ[\9_ M">AZ@L:R-8:OXBMK:8(WW6*2.&P>QQS0!UE%?\''7_ )O["U!9_[ M/OX_OPOC\<,,JV#M)P<>@5_$'_P3<_X*1_M'?\$OOVCK#]H7]GK7O[MOXF\, MWDK?8/$%ANRUK<*/Q*2#YHVPR]P?ZV?V%/\ @L+^PG^WI^SWI/QW\!?'/PWX M?GNHQ'KOA/Q1XAM;34=%O /GMYHY'4L +]+US3VD:-;_1]0CN82Z_>4/&Q7([ MC/% 'G'[;7[;_P"SG_P3W^ &I_M)?M/>-?['\/:?*EO;Q6\/G7>I7CAC%9VL M((,TS[6(7( 56=BJ(S#XSD_X+9_\%%K[PTWQH\-_\&_OQBN?AF(/M::W=^-; M*WUY[/!82C1/L[3L2GS; YSZX(-]T2\N)+2_L-0@$-]I%]&%,MG=1 MYG_AI+44\0VD MOQ&^&WQ2\1Z=+9W^CM_Q]-'!%";K2I5P"J; PW_>^4AP#]#/BI^V]\#?A#^U MI\+?V*?$UWJ&;.ST\M!#;:?9S75Q/<3,0J+B$QJJ[G+NORA%_VU_'GA2?QSX4\57'AO4-'L[!I/!D= MKHLHF@L1+"P=+DQ.9/.#D><^TKQCV#X^?%_]M3]OO_@J/XE_X):_LR_M7:S\ M'_A_\$O VEZG\7?B#X9T^"3Q!KNI7T,4MO9V\TBE;5?*E1RZ $,DP.X;% !^ MF=%? 'P3T'_@I#_P3.^,/Q$G_:.^/.M_'3]E_0_A5?>++7XA>,;JP3Q)X_8G^!_\ P5"_X*Z?L\6?_!0;XN?\ M%0/'OP3'CN:ZO?AC\-_A5I]I'IF@Z:DTD5NU[YJ[]19RAD*NP)4J=XW;(P#] M8**^'O\ @BQ^W)^T;^T=IWQ@_9._;2N=-U#XP?L[^//^$9\5>)=&M%M[;Q%: M2"4V6I")0JQ/*()LJJJN%1MJEBJ_<- !1110 4453\0>(= \)Z-<>(_%.N6> MF:?:1^9=W^H7*0PPI_>=W(51[DT 7**S]4\6>%=#\-R>,=;\3:?9Z1%;B>75 M;J]2.V2(@$2&5B%"G(^;..11JGBSPKH?AN3QCK?B;3[/2(K<3RZK=7J1VR1$ M B0RL0H4Y'S9QR* -"HK^_L=*L9M3U.]BMK:VB:6XN)Y B1(H)9V8\*H ))/ M JIJGBSPKH?AN3QCK?B;3[/2(K<3RZK=7J1VR1$ B0RL0H4Y'S9QR*_//\ MX+,>)HOVI?VF?V??^"7FJ?%'_A&OA=\3(]7\9?&K6[35Q:?;_#>E11R1:=]H M# )!=3N%D8$8"H02,J0#M_B)_P '%_\ P2M\&>-+[P#X+^,>O_$;4-+DV:K) M\+_ ^HZY:VI]3=6\)@D7 )W1NXPI[\5ZU^Q=_P %8OV ?V_]4N_"G[,G[0NG MZIXET^-GU+P=JUG<:7K%L$QO)L[R..5U0D!GC#HI(!;FO5?AIX$_9[_9B^#- MEX8^%7AWPKX'\!Z)8JUG#I<<%EIUM!@8DW#:GS#!,A.6)R22:];U3Q9X5T/PW)XQUOQ-I]GI$5N)Y=5NKU( M[9(B 1(96(4*_M%:+X(UR71O$'CV#Q3:^'M#DOXB/-AM M+FXBE%UMR.0%)!5@"CH[?HNP#*5/<=C7XW_LX^$_^"P__!O_ *#KO[-?PL_8 M*M_VF_@#%XIOM6\(Z_X&UT6OB2Q@N7#F&XM=DLD\BX!*I P+%@)L%50 ^S?^ M">__ 6!\$_MH?&?Q)^R/\8/V>?&/P1^-WA+35U+5OAKXY56>YL2RK]JLKE0 MJW,8+QY.Q"0X90Z[F&Q_P4)_X*>C]C7XE_#_ /9C^"O[.6N?&7XU?%$W4G@W MX<:'K%OIBM:6R%Y[N[OK@-':0J V&96SL?. I->(_L'_ /!0W_@F'_P4L_;S ML/'>N_L^^*_AG^U9X#\*7&E67A[XG:?<:;JT>F$2O/#;HLODW*J+B5RLJ+,% M=G"!5+#YX_X+N?'7Q!XC_P""B_PR\7?\$K?#7BOQY^U3^SII][J7C/3O#6AB M]T6S\,S6[23V&J2&1#YTBN5C@BS(XNI$!69H0 #[T_X)R?\ !4&/]M_QS\1O MV>/B[^SIKGP=^,OPEO+2+QW\.-#41;PW49DM[FVO(%5+J%U .]548>-AN M616/+?\ !2K_ (+ ZM^P)^T=\-/V6? '[&GBWXP>+_BAI-_?:#I/A+58H9S] MD^:5!&\;%R(U>3(QA4-?._\ P0Y^.7[(NG?!O7O^"MO[3W[:7A_5?BS^TQXU ML?#OC'4-8CCTFUT'5;:!UM/#%M SL4,<,>5=VS-&D#>A;F/^"W_[3/@']CK_ M (+J_L9?M(_$_1M>U#0O#7A/Q8]_9^&-):^OI!-9SVR>5 I!DP\RDX/"ACVH M ]3\8?\ !P/^T1\$?#T_Q-_:?_X(A_M#^"_ NE@2>(?%4,,%\NF09P9Y(]L0 M"#NS.JCCGD5^@?P"^._PK_:>^"_AK]H+X(^*X=;\)^+M)BU'0]3A5E\Z%QT9 M6 9'4@JR, R,K*P!!%?FG^U!_P '$_P+_:"_9Z\:? ;]DW]B']H'XB>._&OA M>_T/0O#TWPKFBM6EN[=X!)&/"B1M?ZCJ%VLS11 M1*Y =B(7^49). ^^RZ+IU_8I!_9LE_,/F2$,]R[!0681%%^9U%8OC__ M (*6?\%9_P#@F7\8O 5[_P %:?A=\%-?^#?Q&\50>'6^(?P3DU.)O"6H7&3# M]KBU [I8,([?*H.Q';S"P6)P#Z<_X* _\%1O!/[$GCGP9^S]X*^"GBKXM_&+ MXBB:3P;\+_!"QB[GMH03+>W,TIV6ELNUAYK Y*.0-L*_%GAS4IHN&N;":TLX_+?U51;]B']E']DGQI\?OBW8:)'K/BGPUX/O;:QL_ M#EC)M,37U],O MVS?^"@/QDUQ?-UN\_:AU#P[)&1HYH9O%]DKQN#@JP,N001@@T =Y17 ?\ M-8?LL_\ 1ROP_P#_ LK'_X[77ZIXL\*Z'X;D\8ZWXFT^STB*W$\NJW5ZD=L MD1 (D,K$*%.1\V<P^&_Q4\-^(9[6,27,.AZY;W;Q(3@,PB=BH)XR:K^+_ (\_ M WX?:RWASQ[\9_">AZ@L:R-8:OXBMK:8(WW6*2.&P>QQS0!UE%'=%!-%J,/V:48,S*)3$(,29=U% 'Z"_P#!0']NGX-_\$Y? MV7M=_:E^-T6HW6F:3)#:V&CZ/")+W5K^=Q'!:0*Q +NQY)("JK,>%KYV_9Z_ MX+*?%_5?VMO W['_ .WU_P $[/%'[/FN_%C3[JZ^%.I:CXVLM>L]<:WC$LMM M,]M'']BN0A7,+[F5G16VETW$O .FF]UN[UZUD5H)TA#*%MU9Q'*[$'9,PCR^W'RE_P2\^+_Q&_;"_;DU+ MXT_\%N/CE:^$OBC^Q%X2NWTKX6WVCII\5M;O91K?^*[NX$CK>,42-G\D"('[ M/*F$= P!^G?_ 5._P""B'AG_@EU^R)J7[6WBWX:7_BVRTW6+'3WT;3M02VE M=KF7RPXD=6 "GDC'-?-*_P#!;S]O9;4:C+_P;\_M"-;"/S&>VO()7*8SE46# M+G'11R>ENM&US2+I9[:\ MA:[X>-U)##@CZ@UT^G?\'/W["%GX?M[73/V?OVA]3O(K1$AL+#X1RF2XD"@! M$WS*I)/ R0/>@#ZC_P"";W_!3/\ 9Y_X*=_"+4_B9\#[77-&U+PUK+Z1XS\& M>++ 6NK:!?J,F&XB#,,'#;74D':RG:Z.B]+_ ,% ?VP-$_8&_8\\<_M?>(_! M5UXCLO!&G0W=QHME=K!+="2YB@"K(RL%(,H;D'I7QM_P0!^ '[14OQ?_ &G_ M /@H]\??@9JOPL@_:,\?6>H^$OA[KT#0:A::?:&\9;JZB8*4DE-Y_$JLS1R/ MMVR(3ZE_P<;_ /*%#X^_]BU9?^G2SH X/P5_P6@_;Y^(O@+2?B=X'_X(/_%W M4]"U[2+?5-'U"U\=Z25N[2>)98I47&XAD96 QGGIFO5/^">'_!8SX5_MV?&3 MQ;^RMXQ^!/CGX._&/P38+?ZY\-_B)8+#=263,B_:;=U/[Z,&6')*H2)D90RG M*1Y/3/\ @F_^VC\;?C-^T5\;O^"0'C3_ (*":9\4 MKW2/ 2^(_A+^T?X!FTV?4?[,F:*WEBN?(,EJ][:S7$."02V'9\@K@ ^[/V-O MVWO@;^W;X0\5^/\ ]G^[U.ZT7PEX\O\ PG=7^I:>;875[9I"TTD*,=_E9F"A MG5&)1CMQ@GU^OQR_X-BO@U\=?!/[-WQJ^.GA7X^>*/%@TOXG>,M'TOX4ZB]E M;:5JVLQ"SDCU&2?RA)%<3,HB8[O*59"=O%;VN_ 7]L:;X3R_&+_@I=_P<)7W MP ^+=\+B\/@?PUXKT+2_#GAD[W^SVK0,ZM?J(]A),@9MVW.YO%MY/#$UO:6MQ) M%=1.FYW!NO+*C:0T;9]!\)^ _P#@JU^V/\9O^#8+XC_ML:C\54M/B[X(NYM$ M3QYH5I#$;V2#5[.);Q8Q'Y2L]O.$;:@4G+!5W8'2_MS^*-?\$[N*PL/#]K*%:(WU_,KK [I)&X& MPKB1,L"P!^VZ_+7]I#]FC_@J1_P3I_X*0_%3_@HQ_P $[O@'X<^.G@KXW6&E M-\1?AQJ&MKIVLZ;=:?!Y*26./V;/%GQ$NOLGP_U'7-;@UK0]:O,JHM%OX(XE6=F>-50(PW M2(&*%TW?H#7Y/'_@KO\ L!?MV?&#X=_LC?\ !7']@/XC? [QU9>-+36?A[:? M%.QNK;3!KD6Z*W>WU"$V\A.9B%:6);=BR$MN"8Z7_@JM_P %"_B;K7_!0_PC M_P $KOA%^VMX7_9QT-O!#>+_ (L?&/7K^Q@NXK5I3%;Z3ISWSI$ES(0KLP._ M;(&4XBD20 _3ROGCX(?\%!_#7QL_X*$_&[_@G[8?#:^L-2^"NEZ#>W_B2:_1 MX-4&J645VBQQ!0T9C$H4DDY(R,5\!^"/VZO$?_!.S]NOX+?";PM_P5QTK]J[ MX/\ QL\51^$=9TS7/%FDZMXB\'ZO<,D=G?)'?A1_P<"_\ !1'XH^,+AXM)\-?#CP/JNJ2QKEDMK?PY;32,!W(1&.* M/U%HK\2/V8OVI/B)_P %0/AS>?MF?M+?\%^]&_9HE\0ZK?'X=?!GP1XYT'3_ M /A&["&>2&!M52[D$U[+(4\PI)MW(58,HD6./U_]D;_@NCX^\-?\$XOVF_B5 M^T9XK\*?$GX@_LJZM-I$GC'PE-$-(\=).[0Z/J"FW/EQK<3@I)Y7 5=P )*@ M _5BO(?VJ/VW?@=^Q]K_ ,,_"7Q:N]3.J_%KXAZ?X-\&6.EZ>9FGU"[E6,/( MQ*I%%&&WNS-G:,*KM\M?!/PT_84_X+,?'W]D73?VV[O_ (*Z>/='^.'B;PG' MXH\-?#K1])TZ#PA9R3PKV3*E(7G'O#VO^#/"TVGW=AX7U];@B37+&4"4-.^] M&6-Y)(U544@D,2 ?MY17.?"'P5XA^''POT#P%XL^(^J>,-3TC2H;2_\ %.MQ MQ)>:K*BA6N9EA58P[D;B%4#)X KHZ /P!_X--O\ E*9^UW_V\?\ I\GK]_J_ M '_@TV_Y2F?M=_\ ;Q_Z?)Z_?Z@ HHHH **** "BBB@ HHHH **** "BBB@ MHHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "B MBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH *_ M'_@TV_Y2F?M=_P#;Q_Z?)Z_?ZOP!_P"#3;_E*9^UW_V\?^GR>@#]_J^?/VC? M^"4O_!.O]KKXER_&/]I7]DGPGXQ\43V<-I+K6L6\C3-#$"(T)5P,*"<<5]!T M4 ?('_#@C_@C;_TCV^'_ /X!S?\ QRC_ (<$?\$;?^D>WP__ / .;_XY7U_1 M0!\@?\."/^"-O_2/;X?_ /@'-_\ '*_*S_@X/_X-B/#OP\\(WO[:'_!,;X;2 M6VEZ19F7QW\*],,LYAA09;4-.5BSD*!F6W!. -\8P&2OZ$J* /X@_P#@FY_P M3<_:._X*@_M'6'[/7[/6@_W;CQ-XFO(F^P>'[#=AKJX8?B$C'S2-A5[D?U$_ ML]_\&U__ 2&^"'P?T/X:>)?V4-#\=ZIIMFJ:IXO\6>;-?:K<8_>3N!($C!. M=L: *@P!DY)^L_@/^RK^SC^R_P#\)+_PSU\%_#_@_P#X3#Q!+K?B;^PM/6#^ MT+^3[\SX_'"C"KD[0,G/H% 'R!_PX(_X(V_](]OA_P#^ V"MQF0 MK'A5R"4EG"9D9%/'_P#$3M^SC%X3.CWO[#W[2$/Q3^SF,?"5OA?/]O:^^[Y MESM\OS./,V[]O/E;ODK],** /RB^$O\ P3J_X*/_ +;G_!+O]I^V_;L\?:SI M/Q$_:1N9-8\"?"S7/$$UQIO@.&WE^UZ=8HCLRV9EF6-95096..(N/-$BBW^S M3_P7G\._LU_LE^%_V;_VH_V-/CCIW[0?@7PK:^'9OAAIGPVO;E_$=_9P);QS M65U$C0M!.41]^[Y=[;!* K/^J5% 'Y&_LG?!'_@IC_P3-_X(W>)_C+X=_99T M'Q_\6?B3\8KWXA_%?X1:I82WLZZ'J0CAN[*VA@E7S+Q8889/*/F!?,E0QR,H M4_*_[>'AG_@F5^W!H>B1_P#!&?\ 8#^*/@[]JRX\5:9-X?U#P?\ #W4O"MOX M3<7$;W,VIE=EC B1[QYL8)20JWF! V[^AJB@#\I_^"N/C#QS^QS_ ,%4?V-O MV_OBE\*?&OC+P/X%\+>*=%\;ZUX!\+R:A);W]WICV\;-#'@1B22?//\ @I%XT^"GCCQ'^S]^T[\/=!?5?%7A#PQ/ MJ%QX0UBQM88HEO[6(&6**2%6;=M/SS[0"8V _5VB@#\WO"'[4O[1W_!9KXS? M$#X/_ ;P!K_A']DS4?@QK/AKQ!XU\=^"9=/N_$^NZC;3VJ'35GVS>1#','9B M ,Q,K!2Z9\I_X)U?\%4[/_@E1^R1H?\ P3S_ ."D/[-?Q7\.?$CX5+B@#\]O^"$7[.G[1FE M>(_VAO\ @H7^U%\*K[P!XA_:4^(L.M:/X#U=2M_H^B6:W"V*W2$ QSE;J0,C M!6Q&K$*7VK^A-%% !1110 5S?Q>^$/PT^/GPTUGX.?&/P;9^(?"_B&S-IK6B MZ@I,-W"2"4< @D9 []JZ2B@#C_'OP!^#?Q1^"EW^SG\0/A[I^J^![[1X]*N_ M#5TA-M+9(JJD! (.T!%'7M1X]^ /P;^*/P4N_P!G/X@?#W3]5\#WVCQZ5=^& MKI";:6R155(" 0=H"*.O:NPHH X_Q[\ ?@W\4?@I=_LY_$#X>Z?JO@>^T>/2 MKOPU=(3;2V2*JI 0"#M 11U[5^?/_!=S]GGP%\(]4^!'[=VO_!E/%GPF^$,E M]X.^-/@NWM'G5O!&K016KW/E*=SI9211R;%()W@DA58C]-JKZOI&E>(-*NM! MU[3+>]L;VW>WO;*[A62*XB=2KQNC AU9205((()!H \]M?!/[+O[6'[+%GX$ MTW3?#WC7X2^+/#%O;V-I9SBXT[4=+V+Y2*R-\T>U5'7/RX/(-?*O_!=/X[?# M/X0_L&W7[ WPY\&V7B;XE_&_2D\!_"/X8VN'FF:8+!]L,> ?AEXFU/6/V!?VYOCC^SMH^M7CW.I^!? 'BE9O#RRN?WDE MO972.+:1N>5;"_*%50H%>K_L1?\ !(K]F+]BCXB:E^T!%K_C'XG?%K6K8V^K M?%OXL>(6UC7'@(P8(9&54MHNHVQH&*X5F8 ':_ O\ 84^$?P__ ."?G@[_ M ()^?%'P[8^+/"NA_#[3_#7B"SO$;[/JWDP1K-(RY!"R2JTF.,;L5Z#X]^ / MP;^*/P4N_P!G/X@?#W3]5\#WVCQZ5=^&KI";:6R155(" 0=H"*.O:NPHH X_ MQ[\ ?@W\4?@I=_LY_$#X>Z?JO@>^T>/2KOPU=(3;2V2*JI 0"#M 11U[5TGA M[0-&\)Z!8^%O#FG1VFGZ99Q6MA:1#Y(88T"(B^P4 #Z5\%:1XJOM"N]8T6ZL;77-,D*7.G22PM&MQ$P((DC+!U.1@J*_)S]D__ (+% M_M'?\$K_ (?M^QG_ ,%HOV=/C3JWB7PEJ5W!HGQPT'0YO$&F>+K%[AY(9GNV M=6,BK($ &]MB()%C=2I_7RB@#\C/A?XF^(7_ 6>_P""Q?P/_;N^#'[)_CCX M;?"']G_1M8-[\2?B#H(TJ_\ &-S>0-%#86L66:6WC9F;=N9566XW;&=%?%^" M?QRU?_@A)_P4:_:BF_;1^ OCO4OAW\?OB$_C;P)\8/!OA2?5[=_-FN93I-V8 M06C>+[28T0C(*.VW9*CU^QM% '\TWQ5^#7Q/U;_@H"O_ 6^^ __ 2R^*%G M^S#X>^*6D^(]<^'NIHUGJ6OZA&LOF>)+71QDI%',RS#.Y"['+K'),(?TC_;3 M\*_$#XB_\' /["?QFT#X7^)U\/VW@OQ5/J]],%*VTN7"% M'(.[Y>37Z;44 %%%% 'Q/_P5+_:B_;R_8D^,_P )OVE?@Y\-]7^('P"L[F[L M?CKX.\(>&H[_ %NTCD0BVU.W 'FM'&6+NJ%5'D*&($I9?D__ (*"_M*6O_!P M?;?#K_@G_P#L)_!OQ_=>"Y?B'I_B#XN_%?Q3X,N](TK0-+LS)OM8FND1IKQR MYVH .4 &X,[1?L110!^8G[:$GCW_ ()@?\%D(O\ @J?=_!OQ7XN^"_Q5^%L7 M@SXJ7_@O19-1O/"VI6L\;VNHS6\0WM;-%##%N .W][U;RD?(^'7CG7/^"TO_ M 5Z^#G[6?PG^$GC#2/V?_V9]#UF\T[QGXR\/3Z6OBKQ%J<*0B&RAG59'CA6 M."4R$#:865@OF1[_ -4J* /R?\/_ !>NO^"&'_!2W]H?Q+^T?\)?&MW\!_VB M?$-OXW\*?$?PCX8N-5MM&ULI)_:%C?1VRL\322R,R'!RL:$ AG,?9_\ !-'P M]\4/V\/^"J_Q._X+%^+?@UXF\$?#N'X<6OPY^"]CXUTMK+4=9LUN5NKO5#;O M\T41E5Q&3PRW##JC8_2VB@ HHHH **** "ODSQ#_ ,$)_P#@D-XLU^^\4^(_ MV!_ =YJ&IWDMW?WZ?JO@>^T>/2KOPU=(3;2V2*JI M0"#M 11U[5V%% 'QAXL_X(9?\$2O GA74_''C']A#X;Z;I&C:?-?:KJ-W;RI M%:VT*&265V,GRJJ*S$]@#7\DG[:WQ4^#OQJ_:J\5'9:;&?+M]P))\UT59)"2?WDCXXP!_;U\?O@-\+?VG_@UXA_9_P#C M;X?N-6\)>*]/-CK^EVVKW5@UW;,06B,]I+%,BMC#!7&Y2RME6(/QA_Q"X_\ M!"C_ *,9_P#,F^)__EG0!_*I^Q3\5/@[\%?VJO _Q'_:'^$VF^.? 5AKT*^, MO"^J6WFQWNFR'R[C: 0?-1&:2,@C]Y&F>,@_UM^$_P#@AE_P1*\=^%=,\<># MOV$/AOJ6D:SI\-]I6HVEO*\5U;3()(I482?,K(RL#W!%_9_P#@EX?N-)\)>%-/%CH&EW.KW5^U MI;*25B$]W++,ZKG"AG.U0JKA5 !PG[+'_!.3]AW]B37]5\4_LH?LU>&_ NH M:Y9I:ZM=Z' Z/=0H^]4;1IFAB!$:$JX&%!..*^@Z* /D#_AP1_P1M_Z1[?#_ /\ .;_ M ..5]9^'M T;PGH%CX6\.:='::?IEG%:V%I$/DAAC0(B+[!0 /I5RB@#\M/C M!^US^W9_P2"_X*&_%/XB_M(_"OXN?&[]F/XK7%KJG@_Q!X.CEUF;X=W2*_GV M)M&<+;VY>1OXD5DCA*%W$D8\=_X*4_MW6G_!P%\ ;3_@G1_P3U_8Q^)FN7WB MCQ3I=UK7Q0\>>"SIFB>"K>WN%EDN_M#LQ\[8'B*C:6CED5/,9@A_:VB@#\I? M^"F7PV^,W[!__!4_]G__ (*QP?!?Q7\6/A;X'^%LOP^\=Q^&-,;4-7\.9-WM MUA8!R0ZW>'<<8BD1F4RQY^1?^"P6DZS_ ,%^_B7HOC7_ ()._L6?$Z3Q-X.\ M+:E!XW^+^OZ9)X:L-9THP.4T)//VF]G=F=45BI F9"K1NSQ?T*44 ?B;_P % M+?$_B7]L'_@UW\.Z3\%/V-_'W@B^T+5O#_AU?AE>>&[E[ZP;2[A;280QA/-F M@5HF E958[6WA6#"OVF\/(\>@6,'M-U[0M9LN_LP_&>YDU_P"#GB&WTZYO M;7P9JDC'S-,GF56$$;,/))<\G[+*<&6OA_P 7^*Y7>)[J0A6 73LQ$@>6-Q\GYRR2(GZ144 ?B5_P3.^)/[27P4_9 M?_:]_P""7GP[^$'Q%\)_M%2>)_B!XI^'VJW?AJ2VTVZ66&"*T>UOW(07$CJ6 MA;[C?(X$D\/S_:99?[3TF1C;Q*A,\7W]LD>Y"(V MPQVFOIS]J[X7?$S5?VH?^"5.IZ7\.M=N;;PO'??\)-<0:1,Z:1G1=(0?:F"X MM\LC+\^WE2.H-?JS10 5^5/B[]M+]N'_ ((Y?MV?%^\_;&^%'Q@^-/[.?Q/\ M2#Q!\.?'GA"&76W\#&0N9=)EMW<"VMT+A%7D^#K2!F\V:&9V8M< M%&8;!M9EW*@D+?+V_P#P5A_90\+_ +/G_!6'PU_P4Q_: _8=/Q_^ _BGX:+X M/^).F0^"XO$5WX1OX)@]OK'V.1&+1F-(HS*H^53< D,\2/\ KS10!^/7P1\4 M_L3?M7_MQ_"OPA_P2C_X(T_#1_!>AZVNL?%3XU^//@$=%M] A@=)(8M*D9(' M.H[T;:2K;7\M@C*LCIZ3\#OV;?%?Q6_X+8_\%#_"GC+PKK6E^%?B5\+?"6@V M/B.;2I5M;I9O#<%K.8)6 29HR[!@K'!7!Q7Z>44 ?@=^Q+%_P3A_X)U?!$_L M9?\ !8W_ ())6I^*_@34;ZTT_P =6_P$3Q%:_$"S:XEEMKFUOH[=O-DV.(OW MA C391&#LCV*\KA-KKG]:J* /RG^#W_!>7_A27[& M.A_LW?$']C/XV6_[3_A3P7!X;M_A9%\,KZ<:KK5M;+;17,-RB&%K.614E+[B MP1CM$F%+\G_P5$T_]NSPE^R9^PW^UW^V5\,M3\8>,_A1\=]'\6?&RS^&OAS[ M1)I=MYK3[5MX&*DQ1(D#.&\II@,.!(IK]A** ./_ &?OC;X4_:1^"WAKX[>! MM,U>RTCQ3I4=_86FOZ:]G>PQO_!- _,;C!!4UV%%% 'X _\ !IM_RE,_:[_[ M>/\ T^3U^_U?@#_P:;?\I3/VN_\ MX_]/D]?O]0 4444 %%%% !1110 4444 M %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 M4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1110 4444 %%%% !1 M110 4444 %?S6_\ !N[^V[^R?^Q'_P %+?VIO%/[5_QTT/P+I^N7EW:Z3=ZY M*ZI=3)K,[LB[5/(7FOZ4J_-3QO\ \&GO_!(;X@^--7\>^(_!OCQM0US5+C4+ M]H?&\R(9II&DZL+N(_)-#)K,SHZ^Q4@CZU_057R9 M_P $Z?\ @BO^P[_P2W\:>(_'O[*&@^)+/4/%6EQ:?JS:YXA>]1H8Y/,4*K*- MIW=Z^LZ "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB M@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** M"BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH * M*** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HH MHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB M@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** M"BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH * M*** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HHHH **** "BBB@ HH 1HH **** "BBB@ HHHH __]D! end XML 13 R1.htm IDEA: XBRL DOCUMENT v3.26.3
Cover - USD ($)
$ in Billions
12 Months Ended
Aug. 30, 2026
Sep. 29, 2026
Feb. 15, 2026
Cover [Abstract]      
Document Type 10-K    
Document Annual Report true    
Document Period End Date Aug. 30, 2026    
Document Fiscal Year Focus 2026    
Document Transition Report false    
Entity File Number 0-20355    
Entity Registrant Name COSTCO WHOLESALE CORP /NEW    
Entity Incorporation, State or Country Code WA    
Entity Tax Identification Number 91-1223280    
Entity Address, Address Line One 999 Lake Drive    
Entity Address, City or Town Issaquah    
Entity Address, State or Province WA    
Entity Address, Postal Zip Code 98027    
City Area Code 425    
Local Phone Number 313-8100    
Title of 12(b) Security Common Stock, $.005 Par Value    
Trading Symbol COST    
Security Exchange Name NASDAQ    
Entity Well-known Seasoned Issuer Yes    
Entity Voluntary Filers No    
Entity Current Reporting Status Yes    
Entity Interactive Data Current Yes    
Entity Filer Category Large Accelerated Filer    
Entity Small Business false    
Entity Emerging Growth Company false    
ICFR Auditor Attestation Flag true    
Document Financial Statement Error Correction [Flag] false    
Entity Shell Company false    
Entity Public Float     $ 451.6
Entity Common Stock, Shares Outstanding   443,129,349  
Amendment Flag false    
Document Fiscal Period Focus FY    
Entity Central Index Key 0000909832    
Current Fiscal Year End Date --08-30    
Documents Incorporated by Reference
Portions of the registrant's Proxy Statement for the Annual Meeting of Shareholders to be held on January 21, 2027, are incorporated by reference into Part III of this Form 10-K.
   
XML 14 R2.htm IDEA: XBRL DOCUMENT v3.26.3
Audit Information
12 Months Ended
Aug. 30, 2026
Auditor Information [Abstract]  
Auditor Name KPMG LLP
Auditor Location Seattle, WA
Auditor Firm ID 185
XML 15 R3.htm IDEA: XBRL DOCUMENT v3.26.3
Consolidated Statements Of Income - USD ($)
shares in Thousands, $ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
REVENUE      
Total revenue $ 303,154 $ 275,235 $ 254,453
OPERATING EXPENSES      
Merchandise costs 264,279 239,886 222,358
Selling, general and administrative 27,190 24,966 22,810
Operating income 11,685 10,383 9,285
OTHER INCOME (EXPENSE)      
Interest expense (145) (154) (169)
Interest income and other, net 711 589 624
INCOME BEFORE INCOME TAXES 12,251 10,818 9,740
Provision for income taxes 3,025 2,719 2,373
NET INCOME $ 9,226 $ 8,099 $ 7,367
NET INCOME PER COMMON SHARE:      
Basic $ 20.78 $ 18.24 $ 16.59
Diluted $ 20.76 $ 18.21 $ 16.56
Shares used in calculation (000's)      
Basic 443,953 443,985 443,914
Diluted 444,427 444,803 444,759
Net sales      
REVENUE      
Total revenue $ 297,247 $ 269,912 $ 249,625
Membership fees      
REVENUE      
Total revenue $ 5,907 $ 5,323 $ 4,828
XML 16 R4.htm IDEA: XBRL DOCUMENT v3.26.3
Consolidated Statements Of Comprehensive Income - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Statement of Comprehensive Income [Abstract]      
NET INCOME $ 9,226 $ 8,099 $ 7,367
Foreign-currency translation adjustment and other, net 150 58 (23)
COMPREHENSIVE INCOME $ 9,376 $ 8,157 $ 7,344
XML 17 R5.htm IDEA: XBRL DOCUMENT v3.26.3
Consolidated Balance Sheets - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
CURRENT ASSETS    
Cash and cash equivalents $ 20,207 $ 14,161
Short-term investments 1,094 1,123
Receivables, net 3,959 3,203
Merchandise inventories 19,324 18,116
Other current assets 1,998 1,777
Total current assets 46,582 38,380
OTHER ASSETS    
Property and equipment, net 35,633 31,909
Operating lease right-of-use assets 2,697 2,725
Other long-term assets 4,133 4,085
Total assets 89,045 77,099
CURRENT LIABILITIES    
Accounts payable 22,591 19,783
Accrued salaries and benefits 5,641 5,205
Accrued member rewards 3,037 2,677
Deferred membership fees 3,006 2,854
Current portion of long-term debt [1] 2,248 75
Other current liabilities 7,429 6,514
Total current liabilities 43,952 37,108
OTHER LIABILITIES    
Long-term debt, excluding current portion 3,914 5,713
Long-term operating lease liabilities 2,414 2,460
Other long-term liabilities 2,962 2,654
TOTAL LIABILITIES 53,242 47,935
EQUITY    
Preferred stock $.005 par value; 100,000,000 shares authorized; no shares issued and outstanding 0 0
Common Stock $.005 par value; 900,000,000 shares authorized; 443,266,000 and 442,237,000 shares issued and outstanding 2 2
Additional paid-in capital 8,830 8,282
Accumulated other comprehensive loss (1,620) (1,770)
Retained earnings 28,591 22,650
TOTAL EQUITY 35,803 29,164
TOTAL LIABILITIES AND EQUITY $ 89,045 $ 77,099
[1] Net of unamortized debt discounts and issuance costs.
XML 18 R6.htm IDEA: XBRL DOCUMENT v3.26.3
Consolidated Balance Sheets (Parenthetical) - $ / shares
Aug. 30, 2026
Aug. 31, 2025
Statement of Financial Position [Abstract]    
Preferred stock, par value (in dollars per share) $ 0.005 $ 0.005
Preferred stock, shares authorized 100,000,000 100,000,000
Preferred stock, shares issued 0 0
Preferred stock, shares outstanding 0 0
Common stock, par value (in dollars per share) $ 0.005 $ 0.005
Common stock, shares authorized 900,000,000 900,000,000
Common stock, shares issued 443,266,000 443,237,000
Common stock, shares outstanding 443,266,000 443,237,000
XML 19 R7.htm IDEA: XBRL DOCUMENT v3.26.3
Consolidated Statements of Equity - USD ($)
shares in Thousands, $ in Millions
Total
Common Stock
Additional Paid-in Capital
Accumulated Other Comprehensive Income (Loss)
Retained Earnings
Common stock at beginning of period (shares) at Sep. 03, 2023   442,793      
Equity at beginning of period at Sep. 03, 2023 $ 25,058 $ 2 $ 7,340 $ (1,805) $ 19,521
Increase (Decrease) in Stockholders' Equity [Roll Forward]          
NET INCOME 7,367       7,367
Foreign-currency translation adjustment and other, net (23)     (23)  
Stock-based compensation 822   822    
Release of vested RSUs, including tax effects (shares)   1,337      
Release of vested RSUs, including tax effects $ (315)   (315)    
Repurchases of common stock, shares (1,004) (1,004)      
Repurchases of common stock, value $ (698)   (18)   (680)
Cash dividends declared (8,589)       (8,589)
Common stock at end of period (shares) at Sep. 01, 2024   443,126      
Equity at end of period at Sep. 01, 2024 23,622 $ 2 7,829 (1,828) 17,619
Increase (Decrease) in Stockholders' Equity [Roll Forward]          
NET INCOME 8,099       8,099
Foreign-currency translation adjustment and other, net 58     58  
Stock-based compensation 864   864    
Release of vested RSUs, including tax effects (shares)   1,054      
Release of vested RSUs, including tax effects $ (393)   (393)    
Repurchases of common stock, shares (943) (943)      
Repurchases of common stock, value $ (903)   (18)   (885)
Cash dividends declared $ (2,183)       (2,183)
Common stock at end of period (shares) at Aug. 31, 2025 443,237 443,237      
Equity at end of period at Aug. 31, 2025 $ 29,164 $ 2 8,282 (1,770) 22,650
Increase (Decrease) in Stockholders' Equity [Roll Forward]          
NET INCOME 9,226       9,226
Foreign-currency translation adjustment and other, net 150     150  
Stock-based compensation 929   929    
Release of vested RSUs, including tax effects (shares)   920      
Release of vested RSUs, including tax effects $ (361)   (361)    
Repurchases of common stock, shares (891) (891)      
Repurchases of common stock, value $ (847)   (20)   (827)
Cash dividends declared $ (2,458)       (2,458)
Common stock at end of period (shares) at Aug. 30, 2026 443,266 443,266      
Equity at end of period at Aug. 30, 2026 $ 35,803 $ 2 $ 8,830 $ (1,620) $ 28,591
XML 20 R8.htm IDEA: XBRL DOCUMENT v3.26.3
Consolidated Statements Of Cash Flows - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
CASH FLOWS FROM OPERATING ACTIVITIES      
NET INCOME $ 9,226 $ 8,099 $ 7,367
Adjustments to reconcile net income including noncontrolling interests to net cash provided by operating activities:      
Depreciation and amortization 2,674 2,426 2,237
Non-cash lease expense 318 303 315
Stock-based compensation 924 860 818
Deferred income taxes 306 (108) (60)
Other Noncash Income (Expense) 49 (9) 51
Changes in operating assets and liabilities:      
Merchandise inventories (1,153) 559 (2,068)
Accounts payable (2,755) (404) (1,938)
Other operating assets and liabilities, net 718 801 741
Net cash provided by operating activities 15,817 13,335 11,339
CASH FLOWS FROM INVESTING ACTIVITIES      
Additions to property and equipment (6,435) (5,498) (4,710)
Purchases of short-term investments (788) (1,028) (1,470)
Maturities of short-term investments 811 1,141 1,790
Other investing activities, net 34 74 (19)
Net cash used in investing activities (6,378) (5,311) (4,409)
CASH FLOWS FROM FINANCING ACTIVITIES      
Repayments of short-term borrowings (577) (862) (920)
Proceeds from short-term borrowings 553 816 928
Repayments of long-term debt (69) (103) (1,077)
Proceeds from issuance of long-term debt 496 0 498
Tax withholdings on stock-based awards (361) (393) (315)
Repurchases of common stock (848) (903) (700)
Cash dividend payments (2,458) (2,183) (9,041)
Financing lease payments and other financing activities, net (91) (147) (137)
Net cash used in financing activities (3,355) (3,775) (10,764)
EFFECT OF EXCHANGE RATE CHANGES ON CASH AND CASH EQUIVALENTS (38) 6 40
Net change in cash and cash equivalents 6,046 4,255 (3,794)
CASH AND CASH EQUIVALENTS BEGINNING OF YEAR 14,161 9,906 13,700
CASH AND CASH EQUIVALENTS END OF YEAR 20,207 14,161 9,906
SUPPLEMENTAL DISCLOSURE OF CASH FLOW INFORMATION:      
Interest 103 106 129
Income taxes paid, net 2,839 2,917 2,319
SUPPLEMENTAL DISCLOSURE OF NON-CASH ACTIVITIES:      
Capital expenditures included in liabilities $ 220 $ 193 $ 203
XML 21 R9.htm IDEA: XBRL DOCUMENT v3.26.3
Summary of Significant Accounting Policies
12 Months Ended
Aug. 30, 2026
Accounting Policies [Abstract]  
Significant Accounting Policies
Note 1—Summary of Significant Accounting Policies
Description of Business
Costco Wholesale Corporation (Costco or the Company), a Washington corporation, and its subsidiaries operate membership warehouses and e-commerce sites based on the concept that offering members low prices on a limited selection of nationally-branded and private-label products in a wide range of merchandise categories will produce high sales volumes and rapid inventory turnover. At August 30, 2026, Costco operated 939 warehouses worldwide: 647 in the United States (U.S.) located in 47 states, Washington, D.C., and Puerto Rico, 115 in Canada, 43 in Mexico, 37 in Japan, 29 in the U.K., 20 in Korea, 15 in Australia, 14 in Taiwan, seven in China, five in Spain, three in France, two in Sweden, and one each in Iceland and New Zealand. The Company operates e-commerce sites in the U.S., Canada, the U.K., Mexico, Korea, Taiwan, Japan, Australia, and China.
Basis of Presentation
The consolidated financial statements include the accounts of Costco and its wholly-owned subsidiaries. All material inter-company transactions among the Company and its consolidated subsidiaries have been eliminated in consolidation.
Fiscal Year End
The Company operates on a 52/53-week fiscal year basis with the year ending on the Sunday closest to August 31. References to 2026, 2025, and 2024 relate to the 52-week fiscal years ended August 30, 2026, August 31, 2025, and September 1, 2024.
Use of Estimates
The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and the disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. These estimates and assumptions take into account historical and forward-looking factors that the Company believes are reasonable. Actual results could differ from those estimates and assumptions.
Reclassification
Reclassifications were made to the 2025 consolidated balance sheet and the 2025 and 2024 consolidated statements of cash flows to conform with current year presentation.
Cash and Cash Equivalents
The Company considers as cash and cash equivalents all cash on deposit, highly liquid investments with a maturity of three months or less at the date of purchase, and proceeds due from credit and debit card transactions with settlement terms of up to four days. Credit and debit card receivables were $2,842 and $2,670 at the end of 2026 and 2025.
Short-Term Investments
Short-term investments generally consist of debt securities (U.S. government and agency securities), with maturities at the date of purchase of three months to ten years. Investments with maturities beyond five years may be classified, based on the Company’s determination, as short-term based on their highly liquid nature and because they represent the investment of cash that is available for current operations.
Short-term investments classified as available-for-sale are recorded at fair value using the specific identification method with the unrealized gains and losses reflected in accumulated other comprehensive income (loss) until realized. Realized gains and losses from the sale of available-for-sale securities, if any, are determined on a specific identification basis and are recorded in interest income and other, net in the consolidated statements of income. These available-for-sale investments have a low level of inherent credit risk given they are issued by the U.S. government and agencies. Changes in their fair value are primarily attributable to changes in interest rates and market liquidity. Short-term investments classified as held-to-maturity are financial instruments that the Company has the intent and ability to hold to maturity and are reported net of any related amortization and are not remeasured to fair value on a recurring basis.
The Company periodically evaluates unrealized losses in its investment securities for credit impairment, using both qualitative and quantitative criteria. In the event a security is deemed to be impaired as the result of a credit loss, the Company recognizes the loss in interest income and other, net in the consolidated statements of income.
Fair Value of Financial Instruments
The Company accounts for certain assets and liabilities at fair value. The carrying value of the Company’s financial instruments, including cash and cash equivalents, receivables, and accounts payable, approximate fair value due to their short-term nature or variable interest rates. See Notes 2, 3, and 4 for the carrying value and fair value of the Company’s investments, derivative instruments, and fixed-rate debt.
Fair value is defined as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. Fair value is estimated by applying a fair value hierarchy, which requires maximizing the use of observable inputs when measuring fair value. The three levels of inputs are:
Level 1: Quoted market prices in active markets for identical assets or liabilities.
Level 2: Observable market-based inputs or unobservable inputs that are corroborated by market
data.
Level 3: Significant unobservable inputs that are not corroborated by market data.
The Company’s valuation techniques used to measure the fair value of money market mutual funds, which are included in cash and cash equivalents, are based on quoted market prices, such as quoted net asset values published by the fund as supported in an active market. Valuation methodologies used to measure the fair value of all other non-derivative financial instruments are based on independent external valuation information. The pricing process uses data from a variety of independent external valuation information providers, including trades, bid price or spread, two-sided markets, quotes, benchmark curves including but not limited to treasury benchmarks, Secured Overnight Financing Rate and swap curves, discount rates, and market data feeds. All are observable in the market or can be derived principally from or corroborated by observable market data. The Company reports transfers in and out of Levels 1, 2, and 3, as applicable, using the fair value of the individual securities as of the beginning of the reporting period in which the transfer(s) occurred.
Current financial liabilities have fair values that approximate their carrying values. Long-term financial liabilities include the Company's long-term debt, which are recorded on the balance sheet at issuance price and adjusted for unamortized discounts or premiums and debt issuance costs. Discounts, premiums, and debt issuance costs are amortized to interest expense over the term of the loan. The estimated fair value of the Company's long-term debt is based primarily on reported market values, recently completed market transactions, and estimates based upon interest rates, maturities, and credit.
Receivables, Net
Receivables consist primarily of vendor, third-party pharmacy, credit card incentive, reinsurance, and other receivables. Vendor receivables include discounts, volume rebates, and a variety of other programs. Balances are generally presented on a gross basis, separate from any related payable due. In certain circumstances, these receivables may be settled against the related payable to that vendor, in which case the receivables are presented on a net basis. Third-party pharmacy receivables generally relate to amounts due from insurance providers. Credit card incentive receivables primarily represent amounts earned under co-branded credit card arrangements. Reinsurance receivables are held by the Company’s wholly-owned captive insurance subsidiary and primarily represent amounts ceded through reinsurance arrangements gross of the amounts assumed under reinsurance, which are presented within other current liabilities in the consolidated balance sheets. Other receivables primarily consist of amounts due from governmental entities, mostly tax-related items.
The valuation allowance related to receivables was immaterial to the Company's consolidated financial statements at the end of 2026 and 2025.
Merchandise Inventories
Merchandise inventories consist of the following:
20262025
United States $13,707 $12,868 
Canada2,188 1,907 
Other International3,429 3,341 
Merchandise inventories$19,324 $18,116 
Merchandise inventories are stated at the lower of cost or market. U.S. merchandise inventories are valued by the cost method of accounting, using the last-in, first-out (LIFO) basis. The Company believes the LIFO method more fairly presents the results of operations by more closely matching current costs with current revenues. The Company records an adjustment each quarter, if necessary, for the projected annual effect of inflation or deflation, and these estimates are adjusted to actual results determined at year-end, after actual inflation or deflation rates and inventory levels have been determined. Due to higher merchandise costs in 2026, a $206 charge was recorded to merchandise costs to increase the cumulative LIFO valuation on merchandise inventories at August 30, 2026. A charge of $142 was recorded in 2025 and an immaterial LIFO benefit was recorded in 2024. Canadian and Other International merchandise inventories are predominantly valued using the cost and retail inventory methods, respectively, using the first-in, first-out (FIFO) basis.
The Company initially provides for estimated inventory losses between physical inventory counts using estimates based on experience. The provision is adjusted to reflect physical inventory counts, which generally occur in the second and fourth fiscal quarters. Inventory cost where appropriate is reduced by estimates of vendor rebates when earned or as the Company progresses towards earning those rebates, provided that they are probable and reasonably estimable.
Property and Equipment, Net
Property and equipment are stated at cost. Depreciation and amortization expense is computed primarily using the straight-line method over estimated useful lives. Leasehold improvements made after the beginning of the initial lease term are depreciated over the shorter of the estimated useful life of the asset or the remaining term of the initial lease plus any renewals that are reasonably certain at the date of the leasehold improvements.
The Company capitalizes certain computer software and costs incurred in developing or obtaining software for internal use. During development, these costs are included in construction in progress. To the
extent that the assets become ready for their intended use, these costs are included in equipment and fixtures and amortized on a straight-line basis over estimated useful lives.
Repair and maintenance costs are expensed when incurred. Expenditures for remodels, refurbishments, and improvements that add to or change asset function or useful life are capitalized. Assets removed during the remodel, refurbishment, or improvement are retired. Assets classified as held-for-sale at the end of 2026 and 2025 were immaterial.
The following table summarizes the Company's property and equipment balances at the end of 2026 and 2025:
Estimated Useful Lives20262025
LandN/A$11,265 $10,323 
Buildings and improvements
5-50 years
27,775 25,508 
Equipment and fixtures
3-20 years
14,850 13,127 
Construction in progressN/A2,722 1,882 
56,612 50,840 
Accumulated depreciation and amortization(20,979)(18,931)
Property and equipment, net$35,633 $31,909 
The Company evaluates long-lived assets for impairment on an annual basis, when relocating or closing a facility, or when events or changes in circumstances may indicate that the carrying amount of the asset group, generally an individual warehouse, may not be fully recoverable. For asset groups held and used, including warehouses to be relocated, the carrying value of the asset group is considered recoverable when the estimated future undiscounted cash flows generated from the use and eventual disposition of the asset group exceed the respective carrying value. In the event that the carrying value is not considered recoverable, an impairment loss is recognized for the asset group to be held and used equal to the excess of the carrying value above the estimated fair value of the asset group. For asset groups classified as held-for-sale (disposal group), the carrying value is compared to the disposal group’s fair value less costs to sell. The Company estimates fair value by obtaining market appraisals from third party brokers or using other valuation techniques. There were no impairment charges recognized in 2026, and impairment charges in 2025 and 2024 were immaterial.
Leases
The Company leases land, buildings, and/or equipment at warehouses and certain other office and distribution facilities. Leases generally contain one or more of the following options, which the Company can exercise at the end of the initial term: (a) renew the lease for a defined number of years at the then-fair market rental rate or rate stipulated in the lease agreement; (b) purchase the property at the then-fair market value or purchase price stated in the agreement; (c) a right of first refusal in the event of a third-party offer; or (d) a right of first offer if the landlord intends to sell.
Some leases include free-rent periods and step-rent provisions, which are recognized on a straight-line basis over the original term of the lease and any extension options that the Company is reasonably certain to exercise from the date the Company has control of the property. Certain leases provide for periodic rent increases based on price indices or the greater of minimum guaranteed amounts or sales volume, which are recognized as variable lease payments. The Company's leases do not contain any material residual value guarantees or material restrictive covenants.
The Company determines at inception whether a contract is or contains a lease. Non-lease components and the lease components to which they relate are accounted for together as a single lease component for all asset classes. The Company initially records right-of-use (ROU) assets and lease obligations for its finance and operating leases based on the discounted future minimum lease payments over the term.
The lease term is defined as the noncancelable period of the lease plus any options to extend when it is reasonably certain that the Company will exercise the option. As the rate implicit in the Company's leases is not easily determinable, the present value of the sum of the lease payments is calculated using the Company's incremental borrowing rate. The rate is determined using a portfolio approach based on the rate of interest the Company would pay to borrow an amount equal to the lease payments on a collateralized basis over a similar term. The Company uses quoted interest rates from financial institutions to derive the incremental borrowing rate. Impairment of ROU assets is evaluated in a similar manner as described in Property and Equipment, Net above.
The Company's asset retirement obligations (ARO) primarily relate to leasehold improvements that must be removed at the end of a lease. These obligations are recorded as a discounted liability, with an offsetting asset, based upon the estimated fair value of the costs to remove the improvements. These liabilities are accreted over time to the projected future value of the obligation. The ARO assets are depreciated using the same depreciation method as the leasehold improvement assets and are included in buildings and improvements. Estimated ARO liabilities associated with these leases are included in other long-term liabilities in the consolidated balance sheet.
Goodwill and Acquired Intangible Assets
Goodwill represents the excess of acquisition cost over the fair value of the net assets acquired and is not subject to amortization. The Company reviews goodwill annually in the fourth quarter for impairment or when circumstances indicate carrying value may exceed the fair value. This evaluation is performed at the reporting unit level. If a qualitative assessment indicates that it is more likely than not that the fair value is less than carrying value, a quantitative analysis is completed using either the income or market approach, or a combination of both. The income approach estimates fair value based on expected discounted future cash flows, while the market approach uses comparable public companies and transactions to develop metrics to be applied to historical and expected future operating results.
Goodwill is included in other long-term assets in the consolidated balance sheets. At the end of 2026, 2025, and 2024 goodwill balances in the Company's U.S., Canadian, and Other International operations were $953, $26, and $15, respectively. No impairment charges were recorded in 2026, 2025, or 2024.
Definite-lived intangible assets, which are immaterial, are included in other long-term assets on the consolidated balance sheets and are amortized on a straight-line basis over their estimated lives, which approximates the pattern of expected economic benefit.
Insurance/Self-insurance Liabilities
Claims for employee health-care benefits, workers’ compensation, general liability, property damage, directors’ and officers’ liability, vehicle liability, inventory loss, and other exposures are funded predominantly through self-insurance. Insurance coverage is maintained for certain risks to limit exposures to very large losses. The Company uses various risk management mechanisms, including a wholly-owned captive insurance subsidiary and participates in a reinsurance program. Liabilities associated with the risks that are retained by the Company are not discounted and are estimated using historical claims experience, demographic factors, severity factors, and other actuarial assumptions. The estimated accruals for these liabilities could be significantly affected if future occurrences, claims, or expenses differ from these assumptions and historical trends. At the end of 2026 and 2025, these insurance liabilities were $2,157 and $1,878 in the aggregate, and were included in accrued salaries and benefits and other current liabilities in the consolidated balance sheets, classified based on their nature.
The captive receives direct premiums, which are netted against the Company’s premium costs in SG&A expenses in the consolidated statements of income. The captive participates in a reinsurance program that includes third-party participants. The participant agreements and practices of the reinsurance program are designed to limit participating members’ individual risk. Income statement adjustments related to the reinsurance program and related impacts to the consolidated balance sheets are
recognized as information becomes known. In the event the Company leaves the reinsurance program, the Company retains its primary obligation to the participants for prior activity.
Derivatives
The Company is exposed to foreign-currency exchange-rate fluctuations in the normal course of business. It manages these fluctuations, in part, through the use of forward foreign-exchange contracts, seeking to economically hedge the impact of fluctuations of foreign-exchange on known future expenditures denominated in a non-functional foreign-currency. The contracts relate primarily to U.S. dollar merchandise inventory expenditures made by the Company’s international subsidiaries with functional currencies other than the U.S. dollar. These contracts either do not qualify for or the Company has not elected derivative hedge accounting. The Company seeks to mitigate risk with the use of these contracts and does not intend to engage in speculative transactions. Some of these contracts contain credit-risk-related contingent features that require settlement of outstanding contracts upon certain triggering events. The aggregate fair value amounts of derivative instruments in a net liability position and the amount needed to settle the instruments immediately if the credit-risk-related contingent features were triggered were immaterial at the end of 2026 and 2025. The aggregate notional amounts of open, unsettled forward foreign-exchange contracts were $541 and $1,184 at the end of 2026 and 2025. See Note 3 for information on the fair value of unsettled forward foreign-exchange contracts at the end of 2026 and 2025.
The unrealized gains or losses recognized in interest income and other, net in the consolidated statements of income relating to the net changes in the fair value of unsettled forward foreign-exchange contracts were immaterial in 2026, 2025, and 2024.
The Company is exposed to fluctuations in prices for energy, particularly electricity and natural gas, and other commodities used in retail and manufacturing operations, which it seeks to partially mitigate through the use of fixed-price contracts for certain of its warehouses and other facilities, primarily in the U.S. and Canada. The Company also enters into variable-priced contracts for some purchases of natural gas, in addition to fuel for its gas stations, on an index basis. These contracts meet the characteristics of derivative instruments, but generally qualify for the “normal purchases and normal sales” exception under authoritative guidance and require no mark-to-market adjustment.
Foreign-Currency
The functional currencies of the Company’s international subsidiaries are their local currencies. Assets and liabilities recorded in foreign currencies are translated at the exchange rate on the balance sheet date. Translation adjustments are recorded in accumulated other comprehensive loss. Revenues and expenses of the Company’s consolidated foreign operations are translated at average exchange rates prevailing during the year.
The Company recognizes foreign-currency transaction gains and losses related to revaluing or settling monetary assets and liabilities denominated in currencies other than the functional currency in interest income and other, net in the consolidated statements of income. Generally, these include the U.S. dollar cash and cash equivalents and the U.S. dollar payables of consolidated subsidiaries revalued to their functional currency. Also included are realized foreign-currency gains or losses from settlements of forward foreign-exchange contracts. These items were immaterial in 2026, 2025, and 2024.
Revenue Recognition
The Company recognizes sales for the amount of consideration collected from the member, which includes gross shipping fees where applicable, and is net of sales taxes collected and remitted to government agencies and member returns. The Company reserves for estimated returns based on historical trends and reduces sales and merchandise costs accordingly. The Company records on a gross basis a refund liability and an asset for recovery, which are included in other current liabilities and other current assets, respectively, in the consolidated balance sheets.
The Company offers merchandise in the following core merchandise categories: foods and sundries, non-foods, and fresh foods. The Company also provides expanded products and services through warehouse ancillary and other businesses. The Company is the principal for the majority of its transactions and recognizes revenue on a gross basis. The Company is the principal when it has control of the merchandise or service before it is transferred to the member. The majority of revenue from merchandise sales is recognized at the point of sale. Revenue generated through e-commerce or special orders is generally recognized upon shipment to the member. For merchandise shipped directly to the member, shipping and handling costs are expensed as incurred as fulfillment costs and included in merchandise costs in the consolidated statements of income. In certain ancillary businesses, revenue is deferred until the member picks up merchandise at the warehouse. Deferred sales are included in other current liabilities in the consolidated balance sheets.
The Company accounts for membership fee revenue, net of refunds, on a deferred basis, ratably over the one-year membership period. Deferred membership fees at the end of 2026 and 2025 were $3,006 and $2,854.
In most countries, the Company's Executive members qualify for an Executive reward, generally 2% on qualified purchases, subject to an annual maximum value, which does not expire and is redeemable at Costco warehouses. The Company accounts for this reward as a reduction in sales, net of the estimated impact of non-redemptions (breakage), with the corresponding liability classified as accrued member rewards in the consolidated balance sheets. Estimated breakage is computed based on redemption data. For 2026, 2025, and 2024, the net reduction in sales was $3,383, $3,007, and $2,804.
The Company sells and otherwise provides proprietary shop cards that do not expire and are redeemable at the warehouse or online for merchandise or membership. Revenue from shop cards is recognized upon redemption, and estimated breakage is recognized based on redemption data. The Company accounts for outstanding shop card balances as a liability, net of estimated breakage. Shop card liabilities are included in other current liabilities in the consolidated balance sheets.
Citibank, N.A. is the exclusive issuer of co-branded credit cards to U.S. members. The Company receives various forms of consideration from Citibank, including a royalty on purchases made on the card outside of Costco. A portion of the royalty is used to fund the rebate that cardholders receive, after taking into consideration breakage, which is calculated based on rebate redemption data. The rebates are issued in February and expire on December 31. The Company also maintains varying co-branded credit card arrangements in Canada and certain Other International subsidiaries.
Merchandise Costs
Merchandise costs consist of the purchase price or manufacturing costs of inventory sold, inbound and outbound shipping charges, and all costs related to the Company’s depot, fulfillment, and manufacturing operations, and are reduced by vendor consideration. Merchandise costs also include salaries, benefits, depreciation, and utilities in fresh foods departments and certain ancillary businesses.
Vendor Consideration
The Company receives funds from vendors for discounts and a variety of other programs. These programs are evidenced by agreements that are reflected in the carrying value of the inventory when earned or as the Company progresses towards earning the rebate or discount, and as a component of merchandise costs as the merchandise is sold. Other vendor consideration is generally recorded as a reduction of merchandise costs upon completion of contractual milestones, agreement terms, or other systematic approaches.
Selling, General and Administrative Expenses
Selling, general and administrative expenses consist primarily of salaries, benefits and workers’ compensation costs for warehouse employees (other than fresh foods departments and certain ancillary
businesses, which are reflected in merchandise costs), as well as all regional and home office employees, including buying personnel. Selling, general and administrative expenses also include substantially all building and equipment depreciation, stock compensation expense, credit and debit card processing fees, utilities, preopening, as well as other operating costs incurred to support warehouse and e-commerce operations.
Retirement Plans
The Company's 401(k) retirement plan is available to all U.S. employees over the age of 18 who have completed 90 days of employment. The plan allows participants to make wage deferral contributions, a portion of which the Company matches. In addition, the Company provides each eligible participant an annual discretionary contribution. The Company also has a defined contribution plan for employees in Canada and contributes a percentage of each employee's wages. Certain subsidiaries in the Company's Other International operations have defined benefit and defined contribution plans, which are immaterial. Amounts expensed under all plans were $1,174, $1,061, and $963 for 2026, 2025, and 2024, and are predominantly included in SG&A expenses in the consolidated statements of income.
Stock-Based Compensation
The Company grants stock-based compensation, primarily to employees and non-employee directors. Grants to executive officers are generally performance-based. Through a series of shareholder approvals, there have been amended and restated plans and new provisions implemented by the Company. Restricted Stock Units (RSUs) are subject to quarterly vesting in the event of retirement or voluntary termination. Recipients are not entitled to vote or receive dividends on unvested and undelivered shares.
For grants issued prior to October 2025, RSUs generally vest over five years, with accelerated vesting provisions for participants reaching specified long-service milestones (25 years of service for employees; five years for non-employee directors). For grants issued in October 2025 and thereafter, RSUs vest over either a three-year schedule with no accelerated vesting or a five-year schedule with long-service acceleration, based on a one-time election made by eligible participants in 2025. RSUs granted to new participants vest over a three-year term with no such acceleration.
Compensation expense for awards is predominantly recognized using the straight-line method over the requisite service period for the entire award and forfeitures are recognized as they occur. Under accelerated vesting provisions, compensation expense is recognized upon achievement of the long-service term. The cumulative amount of compensation cost recognized at any point in time equals at least the portion of the grant-date fair value of the award that is vested at that date. The fair value of RSUs is calculated as the market value of the common stock on the measurement date less the present value of the expected dividends forgone during the vesting period.
Stock-based compensation expense is predominantly included in SG&A expenses in the consolidated statements of income. Certain stock-based compensation costs are capitalized or included in the cost of merchandise. See Note 7 for additional information.
Income Taxes
The Company accounts for income taxes using the asset and liability method. Deferred tax assets and liabilities are recognized for the future tax consequences attributed to differences between the financial statement carrying amounts of existing assets and liabilities and their tax bases, credits and loss carry-forwards. Deferred tax assets and liabilities are measured using tax rates expected to apply to taxable income in the years in which those temporary differences and carry-forwards are expected to be recovered or settled. The effect on deferred tax assets and liabilities of a change in tax rates is recognized in income in the period that includes the enactment date. A valuation allowance is established when necessary to reduce deferred tax assets to amounts that are more likely than not expected to be realized.
The timing and amounts of deductible and taxable items and the probability of sustaining uncertain tax positions requires significant judgment. The benefits of uncertain tax positions are recorded in the Company’s consolidated financial statements only after determining a more-likely-than-not probability that the uncertain tax positions will withstand challenge from tax authorities. When facts and circumstances change, the Company reassesses these probabilities and records changes as appropriate.
Net Income per Common Share
The computation of basic net income per share uses the weighted average number of shares that were outstanding during the period. The computation of diluted net income per share uses the weighted average number of shares in the basic net income per share calculation plus the number of common shares that would be issued assuming vesting of all potentially dilutive common shares outstanding using the treasury stock method for shares subject to RSUs.
Stock Repurchase Programs
Repurchased shares of common stock are retired, in accordance with the Washington Business Corporation Act. The par value of repurchased shares is deducted from common stock and the excess repurchase price over par value is deducted by allocation to additional paid-in capital and retained earnings. The amount allocated to additional paid-in capital is the current value of additional paid-in capital per share outstanding and is applied to the number of shares repurchased. Any remaining amount is allocated to retained earnings. See Note 6 for additional information.
Recent Accounting Pronouncements Adopted
In December 2023, the FASB issued ASU 2023-09, which requires public business entities on an annual basis to disclose specific categories in the income-tax rate reconciliation, provide information for reconciling items that meet a quantitative threshold, and disclose certain information about income taxes paid. The standard is effective for annual periods beginning after December 15, 2024, with early adoption permitted. The Company adopted the ASU for the fiscal year ended August 30, 2026, on a prospective basis. See Note 8 for additional information.
Recent Accounting Pronouncements Not Yet Adopted
In November 2024, the FASB issued 2024-03, which requires disaggregated disclosures of certain costs and expenses on the income statement on an annual and interim basis. The standard is effective for fiscal years beginning after December 15, 2026, and interim periods within fiscal years beginning after December 15, 2027, with early adoption permitted. The amendments should be applied on a prospective basis. Retrospective application is permitted. The Company is evaluating the standard.
XML 22 R10.htm IDEA: XBRL DOCUMENT v3.26.3
Investments
12 Months Ended
Aug. 30, 2026
Investments, Debt and Equity Securities [Abstract]  
Investments
Note 2—Investments
The Company’s investments were as follows:
2026:Cost
Basis
Unrealized
Losses, Net
Recorded
Basis
Available-for-sale:
Government and agency securities$810 $(14)$796 
Held-to-maturity:
Certificates of deposit298 — 298 
Total short-term investments$1,108 $(14)$1,094 
2025:Cost
Basis
Unrealized
Gains, Net
Recorded
Basis
Available-for-sale:
Government and agency securities$783 $3 $786 
Held-to-maturity:
Certificates of deposit337 — 337 
Total short-term investments$1,120 $3 $1,123 
Gross unrecognized holding gains and losses on available-for-sale securities were not material for the years ended August 30, 2026, and August 31, 2025. At those dates, there were no available-for-sale securities in a material continuous unrealized-loss position. There were no sales of available-for-sale securities during 2026 or 2025.
The maturities of available-for-sale and held-to-maturity securities at the end of 2026 are as follows:
Available-For-SaleHeld-To-Maturity
Cost BasisFair Value
Due in one year or less$126 $126 $298 
Due after one year through five years411 405 — 
Due after five years273 265 — 
Total$810 $796 $298 
XML 23 R11.htm IDEA: XBRL DOCUMENT v3.26.3
Fair Value Measurement
12 Months Ended
Aug. 30, 2026
Fair Value Disclosures [Abstract]  
Fair Value Measurement
Note 3—Fair Value Measurement
Assets and Liabilities Measured at Fair Value on a Recurring Basis
The following table presents information regarding the Company’s financial assets and liabilities that are measured at fair value on a recurring basis and indicates the level within the hierarchy reflecting the valuation techniques utilized to determine such fair value:
Level 2
20262025
Investment in government and agency securities$796 $786 
Forward foreign-exchange contracts, in asset position(1)
1 6 
Forward foreign-exchange contracts, in (liability) position(1)
(3)(14)
Total$794 $778 
 ____________
(1)The asset and liability values are included in other current assets and other current liabilities, respectively, in the consolidated balance sheets.
At August 30, 2026, and August 31, 2025, the Company did not hold any Level 1 or 3 financial assets or liabilities that were measured at fair value on a recurring basis. There were no transfers between levels during 2026 or 2025.
Assets and Liabilities Measured at Fair Value on a Nonrecurring Basis
Assets and liabilities recognized and disclosed at fair value on a nonrecurring basis include items such as financial assets measured at amortized cost and long-lived nonfinancial assets. These assets are measured at fair value if determined to be impaired. There were no material fair value adjustments to these items during 2026 and 2025. Please see Note 1 for additional information.
XML 24 R12.htm IDEA: XBRL DOCUMENT v3.26.3
Debt
12 Months Ended
Aug. 30, 2026
Debt Disclosure [Abstract]  
Debt
Note 4—Debt
Short-Term Borrowings
The Company maintains various short-term bank credit facilities, with a borrowing capacity of $2,118 and $1,220, in 2026 and 2025. This increase was primarily driven by the renewal and expansion of the Company's U.S. revolving credit facility in August 2026, which increased total borrowing capacity from $400 to $1,000 and extended the maturity date to August 2027, as well as credit facility expansions in the Japan and Mexico subsidiaries. There were no short-term borrowings outstanding at the end of 2026, and short-term borrowings were immaterial at the end of 2025.
Long-Term Debt
The Company's long-term debt consists primarily of Senior Notes, described below. The Company at its option may redeem the Senior Notes at any time, in whole or in part, at a redemption price plus accrued interest. The redemption price is equal to the greater of 100% of the principal amount or the sum of the present value of the remaining scheduled payments of principal and interest to maturity. Additionally, upon certain events, a holder has the right to require a repurchase at a price of 101% of the principal amount plus accrued and unpaid interest. Interest on all outstanding long-term debt is payable semi-annually. The estimated fair value of Senior Notes is valued using Level 2 inputs.
Other long-term debt consists of Guaranteed Senior Notes issued by the Company's Japanese subsidiary, valued using Level 3 inputs. In 2026, the Company’s Japan subsidiary issued three series of Guaranteed Senior Notes, totaling approximately $500, at fixed interest rates ranging from 2.620% to 3.680%. Interest is payable semi-annually, and maturity dates range from June 2031 to June 2041. In 2026, 2025, and 2024 the Japanese subsidiary repaid $69, $103, and $77 of its Guaranteed Senior Notes.
In 2024, the Company repaid the $1,000 outstanding principal balance on its 2.750% Senior Notes.
At the end of 2026 and 2025, the fair value of the Company's long-term debt, including the current portion, was $5,689 and $5,370. The carrying value of long-term debt consisted of the following:
20262025
3.000% Senior Notes due May 2027
$1,000 $1,000 
1.375% Senior Notes due June 2027
1,250 1,250 
1.600% Senior Notes due April 2030
1,750 1,750 
1.750% Senior Notes due April 2032
1,000 1,000 
Other long-term debt1,175 805 
Total long-term debt6,175 5,805 
Less unamortized debt discounts and issuance costs13 17 
Less current portion(1)
2,248 75 
Long-term debt, excluding current portion$3,914 $5,713 
_____________
(1)Net of unamortized debt discounts and issuance costs.
Maturities of long-term debt during the next five fiscal years and thereafter are as follows:
2027$2,250 
2028— 
2029136 
20301,750 
2031161 
Thereafter
1,878 
Total
$6,175 
XML 25 R13.htm IDEA: XBRL DOCUMENT v3.26.3
Leases
12 Months Ended
Aug. 30, 2026
Leases [Abstract]  
Lessee, Operating Leases
Note 5—Leases
Information regarding the Company's lease assets and liabilities were as follows:
20262025
Assets
Operating lease right-of-use assets$2,697 $2,725 
Finance lease assets(1)
1,413 1,488 
Total lease assets$4,110 $4,213 
Liabilities
Current
Operating lease liabilities(2)
$192 $208 
Finance lease liabilities(2)
94 78 
Long-term
Operating lease liabilities2,414 2,460 
Finance lease liabilities(3)
1,319 1,401 
Total lease liabilities$4,019 $4,147 
 _______________
(1)Included in other long-term assets in the consolidated balance sheets.
(2)Included in other current liabilities in the consolidated balance sheets.
(3)Included in other long-term liabilities in the consolidated balance sheets.
20262025
Weighted-average remaining lease term (years)
Operating leases
1920
Finance leases
2325
Weighted-average discount rate
Operating leases
3.20 %3.05 %
Finance leases
4.72 %4.63 %
The components of lease expense, excluding short-term lease costs and sublease income (which were immaterial), were as follows:
202620252024
Operating lease costs(1)
$282 $271 $284 
Finance lease costs:
Amortization of lease assets(1)
106 102 97 
Interest on lease liabilities(2)
64 63 58 
Variable lease costs(1)
195 182 163 
Total lease costs$647 $618 $602 
 _______________
(1)Included in selling, general and administrative expenses and merchandise costs in the consolidated statements of income.
(2)Included in interest expense and merchandise costs in the consolidated statements of income.
Supplemental cash flow information related to leases were as follows:
202620252024
Cash paid for amounts included in the measurement of lease liabilities:
Operating cash flows — operating leases$312 $255 $274 
Operating cash flows — finance leases
62 58 58 
Financing cash flows — finance leases
89 147 136 
Operating lease assets obtained in exchange for new or modified leases238 294 125 
Finance lease assets obtained in exchange for new or modified leases122 131 200 
As of August 30, 2026, future minimum payments during the next five fiscal years and thereafter are as follows:
Operating Leases(1)
Finance Leases
2027$252 $146 
2028258 142 
2029226 130 
2030204 118 
2031186 97 
Thereafter2,399 1,657 
Total(2)
3,525 2,290 
Less amount representing interest919 877 
Present value of lease liabilities$2,606 $1,413 
 _______________
(1)Operating lease payments have not been reduced by expected future sublease income of $90.
(2)Excludes $1,667 of lease payments
XML 26 R14.htm IDEA: XBRL DOCUMENT v3.26.3
Stockholders' Equity
12 Months Ended
Aug. 30, 2026
Stockholders' Equity Note [Abstract]  
Stockholders' Equity
Note 6—Equity
Dividends
Cash dividends declared in 2026 totaled $2,458 or $5.54 per share, as compared to $2,183 or $4.92 per share in 2025. Dividends in 2024 included a special dividend of $15 per share, resulting in a payment of $6,655. The Company's current quarterly dividend rate is $1.47 per share.
Stock Repurchase Programs
The Company's stock repurchase program is conducted under a $4,000 authorization by the Board of Directors, which expires in January 2027. As of the end of 2026, the remaining amount available under the authorization was $1,115. The following table summarizes the Company’s stock repurchase activity:
Shares
Repurchased
(000’s)
Average
Price per
Share
Total Cost
2026891 $950.90 $847 
2025943 957.66 903 
20241,004 695.29 698 
These amounts may differ from repurchases of common stock in the consolidated statements of cash flows due to changes in unsettled stock repurchases at the end of each fiscal year. Purchases are made from time to time, as conditions warrant, in the open market or in block purchases and pursuant to plans under SEC Rule 10b5-1.
XML 27 R15.htm IDEA: XBRL DOCUMENT v3.26.3
Stock-Based Compensation Plans
12 Months Ended
Aug. 30, 2026
Share-Based Payment Arrangement [Abstract]  
Stock-Based Compensation Plans
Note 7—Stock-Based Compensation
The 2019 Incentive Plan authorizes the issuance of up to 15,885,000 RSUs. The number of RSUs that may be granted under this Plan is subject to adjustments for changes in capital structure. The Company issues new shares of common stock upon vesting and settlement of RSUs. Shares for vested RSUs are generally delivered to participants annually, net of shares withheld for taxes.
Summary of Restricted Stock Unit Activity
At the end of 2026, 5,280,000 shares were available to be granted as RSUs, and the following awards were outstanding:
•1,877,000 time-based RSUs, which vest upon continued employment or service over specified periods of time; and
•123,000 performance-based RSUs, of which 67,000 were granted to executive officers subject to the determination of the attainment of performance targets for 2026, which occurred in September 2026. At that time, a portion vested as a result of executive officers who met accelerated vesting provisions. The remaining awards vest upon continued employment over specified periods of time. Please refer to Note 1 for accelerated vesting requirements.
The following table summarizes RSU transactions during 2026:
Number of
Units
(in 000’s)
Weighted-Average
Grant Date Fair
Value
Outstanding at the end of 20252,308 $597.00 
Granted1,088 933.56 
Vested and delivered(1,303)669.59 
Forfeited(93)696.05 
Outstanding at the end of 20262,000 $728.17 
The weighted-average grant date fair value of RSUs granted was $933.56, $883.46, and $547.26 in 2026, 2025, and 2024. The remaining unrecognized compensation cost related to non-vested RSUs at the end of 2026 was $922 and the weighted-average period of time over which this cost will be recognized is 1.5 years. Included in the outstanding balance at the end of 2026 were approximately 704,000 RSUs vested but not yet delivered.
Summary of Stock-Based Compensation
The following table summarizes stock-based compensation expense and the related tax benefits:
202620252024
Stock-based compensation expense$924 $860 $818 
Less recognized income tax benefit
212 183 173 
Stock-based compensation expense, net$712 $677 $645 
XML 28 R16.htm IDEA: XBRL DOCUMENT v3.26.3
Income Taxes
12 Months Ended
Aug. 30, 2026
Income Tax Disclosure [Abstract]  
Income Taxes
Note 8—Taxes
Income Taxes
Income before income taxes is comprised of the following:
202620252024
Domestic$9,070 $8,324 $7,255 
Foreign3,181 2,494 2,485 
Total$12,251 $10,818 $9,740 
The provisions for income taxes are as follows:
202620252024
Federal:
Current$1,206 $1,395 $1,245 
Deferred328 (42)48 
Total federal1,534 1,353 1,293 
State:
Current472 449 431 
Deferred21 (18)(77)
Total state493 431 354 
Foreign:
Current1,041 955 798 
Deferred(43)(20)(72)
Total foreign998 935 726 
Total provision for income taxes$3,025 $2,719 $2,373 
The reconciliation between the statutory tax rate and the effective rate for 2026 is as follows:
2026
Federal taxes at statutory rate$2,573 21.0 %
State and local income taxes, net of federal income tax effect(1)
402 3.3 
Foreign tax effects:
Canada - subnational taxes185 1.5 
Canada - other(12)(0.1)
Other foreign jurisdictions117 1.0 
Effect of cross-border tax laws(46)(0.4)
Tax credits:
Research and development(134)(1.1)
Other tax credits(99)(0.8)
Changes in valuation allowance62 0.5 
Nontaxable or nondeductible items(75)(0.6)
Changes in unrecognized tax benefits50 0.4 
Other adjustments2 — 
Total$3,025 24.7 %
 _______________
(1)State taxes in California, New York, New Jersey, and Oregon make up the majority (greater than 50%) of the tax effect in this category.
The reconciliation between the statutory tax rate and the effective rate for 2025 and 2024 is as follows:
20252024
Federal taxes at statutory rate$2,272 21.0 %$2,045 21.0 %
State taxes, net338 3.1 288 3.0 
Foreign taxes, net222 2.1 109 1.1 
Employee stock ownership plan (ESOP)(28)(0.3)(120)(1.2)
Other(85)(0.8)51 0.5 
Total$2,719 25.1 %$2,373 24.4 %
The Company's effective tax rate in 2026, 2025, and 2024 included tax benefits of $72, $100, and $45, related to stock compensation. In 2024, tax benefits also included $94 related to the portion of the special dividend payable through the Company's 401(k) plan and a net non-recurring tax benefit of $63 related to a transfer pricing settlement and certain true-ups of tax reserves.
The following is a supplemental schedule of cash paid for income taxes, net of refunds:
2026
U.S. federal$1,377 
U.S. state and local:
California209 
Other322 
Foreign:
Canada430 
Mexico185 
Other316 
Total$2,839 
The components of the deferred tax assets (liabilities) are as follows:
20262025
Deferred tax assets:
Equity compensation$122 $100 
Deferred income/membership fees398 369 
Foreign tax credit carry forward470 390 
Operating lease liabilities710 699 
Accrued liabilities and reserves1,041 917 
Total deferred tax assets2,741 2,475 
Valuation allowance(641)(554)
Total net deferred tax assets2,100 1,921 
Deferred tax liabilities:
Property and equipment(1,372)(944)
Merchandise inventories(344)(305)
Operating lease right-of-use assets(675)(670)
Foreign branch deferreds(107)(103)
Other(33)(31)
Total deferred tax liabilities(2,531)(2,053)
Net deferred tax liabilities$(431)$(132)
The deferred tax accounts at the end of 2026 and 2025 include deferred income tax assets of $635 and $592, included in other long-term assets; and deferred income tax liabilities of $1,066 and $724, included in other long-term liabilities.
In 2026 and 2025, the Company had valuation allowances of $641 and $554, primarily related to foreign tax credits that the Company believes will not be realized due to carry forward limitations. The foreign tax credit carry forwards are set to expire beginning in fiscal 2030.
The Company generally no longer considers fiscal year earnings of non-U.S. consolidated subsidiaries (other than China) indefinitely reinvested after 2023, in the case of Taiwan, and after 2017, in the case of all other subsidiaries, and has recorded the estimated incremental foreign withholding taxes (net of available foreign tax credits) and state income taxes payable assuming a hypothetical repatriation to the U.S. The Company considers undistributed earnings of certain non-U.S. consolidated subsidiaries, which totaled $3,230, to be indefinitely reinvested and has not provided for withholding or state taxes.
A reconciliation of the beginning and ending amount of gross unrecognized tax benefits for 2026 and 2025 is as follows:
20262025
Gross unrecognized tax benefit at beginning of year$65 $81 
Gross increases—current year tax positions18 9 
Gross increases—tax positions in prior years25 14 
Gross decreases—tax positions in prior years(6)(38)
Gross decreases—settlements(8)(1)
Gross unrecognized tax benefit at end of year$94 $65 
At the end of 2026 and 2025, there were $94 and $65 of unrecognized tax benefits that if recognized would affect the annual effective tax rate.
Accrued interest and penalties related to income tax matters are classified as a component of income tax expense. Accrued interest and penalties recognized during 2026 and 2025, and accrued at the end of each respective period were immaterial.
The Company files income tax returns in the U.S., various state and local jurisdictions, and in several foreign jurisdictions. With few exceptions, the Company is no longer subject to U.S. federal, state or local examination for years before fiscal 2018.
Other Taxes
The Company is subject to multiple examinations for value added, sales-based, payroll, product, import, or other non-income taxes in various jurisdictions. In certain cases, the Company has received assessments from the authorities. Possible losses or range of possible losses associated with these matters are either immaterial or an estimate of the possible loss or range of loss cannot be made at this time. If certain matters or a group of matters were to be decided adversely to the Company, it could result in a charge that might be material to the results of an individual fiscal quarter or year.
XML 29 R17.htm IDEA: XBRL DOCUMENT v3.26.3
Net Income per Common and Common Equivalent Share
12 Months Ended
Aug. 30, 2026
Earnings Per Share [Abstract]  
Net Income Per Common and Common Equivalent Share
Note 9—Net Income per Common and Common Equivalent Share
The following table shows the amounts used in computing net income per share and the weighted average number of shares of basic and of potentially dilutive common shares outstanding (shares in 000’s):
202620252024
Net income
$9,226 $8,099 $7,367 
Weighted average basic shares
443,953 443,985 443,914 
RSUs474 818 845 
Weighted average diluted shares
444,427 444,803 444,759 
Basic earnings per share is calculated by dividing net income by the weighted average number of shares of common stock outstanding during the period. Diluted earnings per share is calculated based on the dilutive effect of RSUs using the treasury stock method.
XML 30 R18.htm IDEA: XBRL DOCUMENT v3.26.3
Commitment and Contingencies
12 Months Ended
Aug. 30, 2026
Commitments and Contingencies Disclosure [Abstract]  
Commitments and Contingencies
Note 10—Commitments and Contingencies
Legal Proceedings
The Company is involved in many claims, proceedings, and litigations arising from its business and property ownership. In accordance with accounting guidance, the Company establishes an accrual for legal proceedings if and when those matters present loss contingencies that are both probable and reasonably estimable. There may be actual losses in excess of amounts accrued. The Company monitors those matters for developments that would affect the likelihood of a loss (considering where applicable indemnification arrangements concerning suppliers and insurers) and the accrued amount, if any, thereof, and adjusts the amount as appropriate. The Company has recorded an immaterial accrual with respect to some matters described below, in addition to other immaterial accruals for matters not described below. If the loss contingency at issue is not both probable and reasonably estimable, the Company does not establish an accrual, but monitors for developments that make the contingency both probable and reasonably estimable. In each case, there is a reasonable possibility that a loss may be incurred, including a loss in excess of the applicable accrual. For matters where no accrual has been recorded, the possible loss or range of loss (including any loss in excess of the accrual) cannot, in the Company's view, be reasonably estimated because, among other things: the remedies or penalties sought are indeterminate or unspecified; the legal and/or factual theories are not well developed; and/or the matters involve complex or novel legal theories or a large number of parties.
In November 2023, a former employee filed a class action against the Company alleging claims under California law for failure to pay minimum wage, failure to pay overtime, failure to provide meal and rest
breaks, failure to provide accurate wage statements, failure to reimburse expenses, failure to pay wages when due, and failure to pay sick pay. Martin Reyes v. Costco Wholesale Corp. (No. 23cv011351; Sacramento County Superior Court), removed to federal court (No. 2:24-cv-00300; E.D. Cal.). A second amended complaint was filed, which the Company has moved to dismiss. In January 2024, the same plaintiff filed a related Private Attorneys General Act (PAGA) representative action, seeking civil penalties and asserting the same alleged underlying Labor Code violations and an additional suitable seating claim. In May 2024, the plaintiff filed an amended PAGA complaint; the Company has denied the material allegations of the complaint and filed a motion to stay the action. The motion was granted on December 18, 2024.
In August 2024, an employee filed an action under PAGA against the Company, alleging claims for penalties for various alleged violations of the California Labor Code. Nader v. Costco (No. CV-24-006198; Stanislaus County Superior Court). An amended complaint was filed in November 2024. In February 2025 the court granted the Company’s motion to strike portions of the complaint. The plaintiff filed a further amended complaint; the Company's motion to strike a portion of this complaint was granted on May 13, 2025. The Company's motion to stay the action was granted on November 13, 2025.
In January 2026, a class action on behalf of Washington employees was filed against the Company alleging failure to provide meal periods and rest breaks and to compensate for violations, wage theft, and failure to furnish accurate wage statements. The complaint seeks compensatory and exemplary damages, interest, and attorneys' fees. Madera v. Costco Wholesale Corp. (No. 26-2-02879-6; King County Superior Court). A similar class action was filed in March 2026. Howell v. Costco Wholesale Corp. (No. 26-2-09459-5; King County Superior Court). Howell was subsequently dismissed. The Company has reached an agreement to resolve Madera for an immaterial amount, subject to court approval.
Beginning in December 2017, the United States Judicial Panel on Multidistrict Litigation consolidated numerous cases concerning the impacts of opioid abuses filed against various defendants by counties, cities, hospitals, Native American tribes, third-party payors, and others. In re National Prescription Opiate Litigation (MDL No. 2804) (N.D. Ohio). Cases filed against the Company by counties and cities in Michigan, New Jersey, Oregon, Virginia, and South Carolina, a hospital in Texas, and class actions and individual actions filed on behalf of individuals seeking to recover alleged increased insurance costs associated with opioid abuse in 43 states and American Samoa have been resolved or dismissed. A claim by a third-party payor in Ohio and actions filed on behalf of infants born with opioid-related medical conditions in 40 states remain in the MDL. A claim against the Company filed in federal court outside the MDL by one county in Georgia is pending, and claims filed by certain cities and counties in New York are pending in state court, as are claims by certain county district attorneys in Pennsylvania. Claims against the Company in state courts in New Jersey, Oklahoma, Utah, and Arizona have been dismissed. Claims against the Company in federal court in Georgia and Florida have been dismissed. The Company is defending all of the pending matters remaining.
In June 2025, a former employee filed a class action alleging that the Company restricted workers earning less than twice the minimum wage from having a second job in violation of the Washington law. Gray, et al., v. Costco Wholesale Corp. (No. 25-2-17717-3; King County Superior Court). In October 2025 the court denied the Company’s motion to dismiss. The court certified a class on December 12, 2025. Trial is set for March 1, 2027.
Between September 25 and October 31, 2023, five class action suits were filed against the Company alleging privacy law violations stemming from pixel trackers on Costco.com: Birdwell v. Costco Wholesale Corp., No. C23-02416, Contra Costa County Superior Court; and Scott v. Costco Wholesale Corp., No. 2:23-cv-08808 (C.D. Cal.), now consolidated with R.S. v. Costco Wholesale Corp., No. 2:23-cv-01628 (W.D. Wash.); Groves, et ano., v. Costco Wholesale Corp., No. 2:23-cv-01662 (W.D. Wash.), and Castillo v. Costco Wholesale Corp., under No. 2:34-cv-01548 (W.D. Wash.). The Castillo plaintiffs filed a consolidated complaint on January 26, 2024, which seeks damages, equitable relief, and attorneys’ fees under various statutes, including the Washington Consumer Protection Act, Washington Privacy Act, Washington Uniform Health Care Information Act, Electronic Communications Privacy Act, California
Invasion of Privacy Act, and California Confidentiality of Medical Information Act. The consolidated complaint also alleges breach of implied contract, invasion of privacy, conversion, and unjust enrichment. The Company filed a motion to dismiss the Castillo complaint on March 11, 2024. In November 2024 the court denied the motion to dismiss in substantial part. On May 16, 2024, the parties stipulated to stay Birdwell pending resolution of Castillo. On January 2, and August 22, 2024, the Company received related civil investigative demands from the Washington Attorney General's Office. On January 3, 2024, the Company received a related pre-litigation letter from the Los Angeles Office of the County Counsel. The Company is in the process of responding to both agencies. The Birdwell case was dismissed with prejudice in March 2026.
In October and November 2025, two class actions were filed against the Company alleging violations of consumer protection and other laws arising from the Company's sale of Kirkland Signature tequila products in the United States: Glazer v. Costco Wholesale Corp., Case No. 1:25-cv-25057 (S.D. Fla.); and Salisbury, et al. v. Costco Wholesale Corp., Case No. 2:25-cv-02277 (W.D. Wash.). Plaintiffs allege that the Company's Kirkland Signature tequilas are labeled “100% de Agave” but contain alcohol derived from non-agave sugars. They seek damages, statutory penalties, punitive and treble damages, and disgorgement. The Glazer action was subsequently dismissed without prejudice. An amended complaint was filed in the Salisbury case on March 9, 2026, adding Glazer as an additional named plaintiff. The Company filed a motion to dismiss Salisbury in April 2026.
In March 2026, four class actions were filed against the Company seeking a refund of tariffs paid by the Company under IEEPA that were passed on to members through higher prices. The complaints allege violations of state consumer protection laws and equitable doctrines: Stockov, et al., v. Costco Wholesale Corp. (Case No. 26-cv-02734; N.D. Ill.); Gower, et al., v. Costco Wholesale Corp. (Case No. 26-2-08898-5SEA; King County Superior Court); Ortiz, et al., v. Costco Wholesale Corp. (Case No. 3:26-cv-01164-CVR; D.P.R.); and Briggs, et al., v. Costco Wholesale Corp. (Case No. 2:26-cv-01064; W.D. Wash.). The Company has filed motions to dismiss in Stockov and Gower. The Gower court denied the motion to dismiss on July 17, 2026. A motion seeking discretionary appellate review of that decision is pending.
In June of 2025, a class action was filed related to promotional emails. Zydel v. Costco Wholesale Corp. (Case No. 25-1-16392-0; King County Superior Court). The complaint alleges the emails include “misleading subject lines that encourage recipients to open e-mails on misleading pretenses” and that the subject lines advertised promotional sales with specific time limitations that were misleading, in violation of the Washington Commercial Electronic Mail Act. The Company filed a motion to dismiss the case in August 2025, which was granted in part and denied in part in October 2025. The Company subsequently agreed to a class-wide settlement for an immaterial amount, which is currently in the process of administration. In July 2026, a class action complaint was filed by plaintiff Tracy Jay, alleging deceptive email marketing practices. Jay v. Costco Wholesale Corp. (Case No. 26-2-22333-5SEA; King County Superior Court). Specifically, that Costco sent commercial emails to consumers utilizing false or misleading “limited-time” subject lines, in violation of the Washington Commercial Electronic Mail Act, as well as Indiana’s Deceptive Commercial Electronic Mail Act and Maryland’s Commercial Electronic Mail Act.
The Company does not believe that any pending claim, proceeding, or litigation, either alone or in the aggregate, will have a material adverse effect on the Company’s financial position, results of operations, or cash flows; it is possible that an unfavorable outcome of some or all of the matters, however unlikely, could result in a charge that might be material to the results of an individual fiscal quarter or year.
XML 31 R19.htm IDEA: XBRL DOCUMENT v3.26.3
Segment Reporting
12 Months Ended
Aug. 30, 2026
Segment Reporting [Abstract]  
Segment Reporting
Note 11—Segment Reporting
The Company is principally engaged in the operation of membership warehouses through wholly owned subsidiaries in the U.S., Canada, Mexico, Japan, the U.K., Korea, Australia, Taiwan, China, Spain, France, Sweden, Iceland, and New Zealand. Reportable segments are largely based on management’s organization of the operating segments for operational decisions and assessments of financial performance, which considers geographic locations. The material accounting policies of the segments are as described in Note 1. Inter-segment net sales and expenses, including royalties, have been eliminated in computing total revenue and operating income.
The chief operating decision maker (CODM) is the Company's Chief Executive Officer, President, and Director. The CODM uses the metrics outlined in the table below, along with internal management reports, to evaluate performance, monitor actual results versus budget and prior year results, and make strategic and operational resource allocation decisions.
The following table provides the revenue, significant expenses, and operating income for the Company's reportable segments:
202620252024
United States
Total revenue$219,823 $200,046 $184,143 
Merchandise costs191,440 174,021 160,573 
Selling, general and administrative expenses20,736 19,147 17,353 
Operating income$7,647 $6,878 $6,217 
Canada
Total revenue$40,561 $36,923 $34,874 
Merchandise costs35,287 32,204 30,543 
Selling, general and administrative expenses3,167 2,870 2,683 
Operating income$2,107 $1,849 $1,648 
Other International
Total revenue$42,770 $38,266 $35,436 
Merchandise costs37,552 33,661 31,242 
Selling, general and administrative expenses3,287 2,949 2,774 
Operating income$1,931 $1,656 $1,420 
Total
Total revenue$303,154 $275,235 $254,453 
Merchandise costs264,279 239,886 222,358 
Selling, general and administrative expenses27,190 24,966 22,810 
Operating income11,685 10,383 9,285 
Other income(1)
566 435 455 
Income before income taxes$12,251 $10,818 $9,740 
 ____________
(1)Other income consists of interest expense and interest income and other, net.
The following table provides depreciation and amortization and other asset related information for the Company's reportable segments:
202620252024
United States
Depreciation and amortization$2,082 $1,895 $1,730 
Additions to property and equipment5,122 4,215 3,725 
Property and equipment, net25,714 22,790 20,638 
Total assets65,090 54,862 48,816 
Canada
Depreciation and amortization$219 $196 $192 
Additions to property and equipment673 580 351 
Property and equipment, net3,395 2,930 2,602 
Total assets8,026 7,304 6,915 
Other International
Depreciation and amortization$373 $335 $315 
Additions to property and equipment640 703 634 
Property and equipment, net6,524 6,189 5,792 
Total assets15,929 14,933 14,100 
Total
Depreciation and amortization$2,674 $2,426 $2,237 
Additions to property and equipment6,435 5,498 4,710 
Property and equipment, net35,633 31,909 29,032 
Total assets89,045 77,099 69,831 
Disaggregated Revenue
The following table summarizes net sales by merchandise category; sales from e-commerce sites and business centers have been allocated to the applicable merchandise categories:
202620252024
Foods and Sundries
$116,788 $109,564 $101,463 
Non-Foods
77,375 71,190 63,973 
Fresh Foods
41,715 37,988 34,220 
Warehouse Ancillary and Other Businesses
61,369 51,170 49,969 
Total net sales
$297,247 $269,912 $249,625 
XML 32 R20.htm IDEA: XBRL DOCUMENT v3.26.3
Insider Trading Arrangements
4 Months Ended
Aug. 30, 2026
Trading Arrangements, by Individual  
Rule 10b5-1 Arrangement Adopted false
Non-Rule 10b5-1 Arrangement Adopted false
Rule 10b5-1 Arrangement Terminated false
Non-Rule 10b5-1 Arrangement Terminated false
XML 33 R21.htm IDEA: XBRL DOCUMENT v3.26.3
Insider Trading Policies and Procedures
12 Months Ended
Aug. 30, 2026
Insider Trading Policies and Procedures [Line Items]  
Insider Trading Policies and Procedures Adopted true
XML 34 R22.htm IDEA: XBRL DOCUMENT v3.26.3
Cybersecurity Risk Management and Strategy Disclosure
12 Months Ended
Aug. 30, 2026
Cybersecurity Risk Management, Strategy, and Governance [Line Items]  
Cybersecurity Risk Management Processes for Assessing, Identifying, and Managing Threats [Text Block]
Risk Management and Global Strategy
We have implemented processes, technologies, and controls to seek to assess, identify, and manage risks associated with cybersecurity threats. Management considers cybersecurity risks within our overall approach to enterprise risk management. We evaluate these risks based on several frameworks, including the National Institute of Standards and Technology (NIST) Cybersecurity Framework (CSF), Center for Internet Security (CIS) 18 Critical Security Controls, and the Payment Card Industry Data Security Standard. Our governance policies, including our Information Security Policy, outline high-level objectives designed to meet compliance and regulatory requirements.
We undertake regular NIST CSF and CIS 18 Critical Security Controls assessments, conducted by a third-party, to measure program maturity. We have implemented a variety of technologies, leveraging third-party security providers for some, and engage in multiple activities to seek to identify and mitigate vulnerabilities and risks. These include, among other activities, scanning for common vulnerabilities and exposures, penetration tests on internal and external networks, code scans on applications, allowed application listing, configuration management tools, employee awareness and training, and internal and external audits. We also review with various frequencies and on a risk-based priority select third parties with whom we do business, in an effort to reduce the likelihood of security incidents or business interruptions. We maintain cybersecurity insurance that would apply to certain losses arising from significant security incidents.
We maintain a security operations center, supported by external providers and our employees, which provides threat detection and incident response capabilities. We maintain cyber incident response plans and related playbooks in coordination with stakeholders (including legal counsel). Significant incidents are prescribed to be escalated to a Cybersecurity Materiality Committee to assess materiality based on qualitative and quantitative factors and evaluate disclosure and corrective action. The Committee is composed of a cross-divisional group of executives representing the core business functions of Information Technology and Security, Operations, Administration, Finance and Accounting, and Legal. We conduct periodic tabletop exercises, including at the executive level, to review our response processes and incident management procedures.
Cybersecurity Risk Management Processes Integrated [Flag] true
Cybersecurity Risk Management Processes Integrated [Text Block]
We have implemented processes, technologies, and controls to seek to assess, identify, and manage risks associated with cybersecurity threats. Management considers cybersecurity risks within our overall approach to enterprise risk management. We evaluate these risks based on several frameworks, including the National Institute of Standards and Technology (NIST) Cybersecurity Framework (CSF), Center for Internet Security (CIS) 18 Critical Security Controls, and the Payment Card Industry Data Security Standard. Our governance policies, including our Information Security Policy, outline high-level objectives designed to meet compliance and regulatory requirements.
Cybersecurity Risk Management Third Party Engaged [Flag] true
Cybersecurity Risk Third Party Oversight and Identification Processes [Flag] true
Cybersecurity Risk Materially Affected or Reasonably Likely to Materially Affect Registrant [Flag] false
Cybersecurity Risk Board of Directors Oversight [Text Block]
Governance
Our Board of Directors has delegated certain responsibilities to the Audit Committee of the Board. The Audit Committee reviews and discusses with management the identification and mitigation of cybersecurity risks, including (among other things) the effectiveness of risk-management policies and practices designed to help safeguard our operations, financial systems, and data. Our Chief Information and Digital Officer (CIDO) and his executive team, including the Vice President of Information Security and Chief Information Security Officer (CISO), present cybersecurity-related topics, including program maturity progress, regularly to the Audit Committee. The Internal Audit team, in its periodic compliance and risk assessment updates to the Audit Committee, also reports on its reviews of certain of our cybersecurity risk exposures, controls, and management actions. The full Board also receives cybersecurity evaluations from time to time.
Our information security organization is led by our CISO, who joined us in December 2025 and brings over 20 years of relevant cybersecurity and leadership experiences across various industries, primarily pharmacy, finance, and consulting. The CISO is responsible for cybersecurity engineering and architecture, cybersecurity operations, incident response, threat intelligence, identity and access management, cybersecurity risk and compliance, and vulnerability management. Our CISO reports to our CIDO, who has more than 30 years of experience in which he has led global digital responsibilities, including leading global cyber teams. Our CIDO reports to the Chief Executive Officer.
Cybersecurity Risk Board Committee or Subcommittee Responsible for Oversight [Text Block] Our Board of Directors has delegated certain responsibilities to the Audit Committee of the Board.
Cybersecurity Risk Process for Informing Board Committee or Subcommittee Responsible for Oversight [Text Block] The Audit Committee reviews and discusses with management the identification and mitigation of cybersecurity risks, including (among other things) the effectiveness of risk-management policies and practices designed to help safeguard our operations, financial systems, and data.
Cybersecurity Risk Role of Management [Text Block] Our Chief Information and Digital Officer (CIDO) and his executive team, including the Vice President of Information Security and Chief Information Security Officer (CISO), present cybersecurity-related topics, including program maturity progress, regularly to the Audit Committee. The Internal Audit team, in its periodic compliance and risk assessment updates to the Audit Committee, also reports on its reviews of certain of our cybersecurity risk exposures, controls, and management actions. The full Board also receives cybersecurity evaluations from time to time.
Our information security organization is led by our CISO, who joined us in December 2025 and brings over 20 years of relevant cybersecurity and leadership experiences across various industries, primarily pharmacy, finance, and consulting. The CISO is responsible for cybersecurity engineering and architecture, cybersecurity operations, incident response, threat intelligence, identity and access management, cybersecurity risk and compliance, and vulnerability management. Our CISO reports to our CIDO, who has more than 30 years of experience in which he has led global digital responsibilities, including leading global cyber teams. Our CIDO reports to the Chief Executive Officer.
Cybersecurity Risk Management Positions or Committees Responsible [Flag] true
Cybersecurity Risk Management Positions or Committees Responsible [Text Block] Our information security organization is led by our CISO, who joined us in December 2025 and brings over 20 years of relevant cybersecurity and leadership experiences across various industries, primarily pharmacy, finance, and consulting. The CISO is responsible for cybersecurity engineering and architecture, cybersecurity operations, incident response, threat intelligence, identity and access management, cybersecurity risk and compliance, and vulnerability management.
Cybersecurity Risk Management Expertise of Management Responsible [Text Block] Our information security organization is led by our CISO, who joined us in December 2025 and brings over 20 years of relevant cybersecurity and leadership experiences across various industries, primarily pharmacy, finance, and consulting
Cybersecurity Risk Process for Informing Management or Committees Responsible [Text Block] CISO reports to our CIDO, who has more than 30 years of experience in which he has led global digital responsibilities, including leading global cyber teams. Our CIDO reports to the Chief Executive Officer.
Cybersecurity Risk Management Positions or Committees Responsible Report to Board [Flag] true
XML 35 R23.htm IDEA: XBRL DOCUMENT v3.26.3
Summary of Significant Accounting Policies (Policies)
12 Months Ended
Aug. 30, 2026
Accounting Policies [Abstract]  
Basis of Presentation
The consolidated financial statements include the accounts of Costco and its wholly-owned subsidiaries. All material inter-company transactions among the Company and its consolidated subsidiaries have been eliminated in consolidation.
Fiscal Year End
Fiscal Year End
The Company operates on a 52/53-week fiscal year basis with the year ending on the Sunday closest to August 31. References to 2026, 2025, and 2024 relate to the 52-week fiscal years ended August 30, 2026, August 31, 2025, and September 1, 2024.
Use of Estimates
Use of Estimates
The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and the disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. These estimates and assumptions take into account historical and forward-looking factors that the Company believes are reasonable. Actual results could differ from those estimates and assumptions.
Reclassification
Reclassification
Reclassifications were made to the 2025 consolidated balance sheet and the 2025 and 2024 consolidated statements of cash flows to conform with current year presentation.
Cash and Cash Equivalents
The Company considers as cash and cash equivalents all cash on deposit, highly liquid investments with a maturity of three months or less at the date of purchase, and proceeds due from credit and debit card transactions with settlement terms of up to four days. Credit and debit card receivables were $2,842 and $2,670 at the end of 2026 and 2025.
Short-Term Investments
Short-term investments generally consist of debt securities (U.S. government and agency securities), with maturities at the date of purchase of three months to ten years. Investments with maturities beyond five years may be classified, based on the Company’s determination, as short-term based on their highly liquid nature and because they represent the investment of cash that is available for current operations.
Short-term investments classified as available-for-sale are recorded at fair value using the specific identification method with the unrealized gains and losses reflected in accumulated other comprehensive income (loss) until realized. Realized gains and losses from the sale of available-for-sale securities, if any, are determined on a specific identification basis and are recorded in interest income and other, net in the consolidated statements of income. These available-for-sale investments have a low level of inherent credit risk given they are issued by the U.S. government and agencies. Changes in their fair value are primarily attributable to changes in interest rates and market liquidity. Short-term investments classified as held-to-maturity are financial instruments that the Company has the intent and ability to hold to maturity and are reported net of any related amortization and are not remeasured to fair value on a recurring basis.
The Company periodically evaluates unrealized losses in its investment securities for credit impairment, using both qualitative and quantitative criteria. In the event a security is deemed to be impaired as the result of a credit loss, the Company recognizes the loss in interest income and other, net in the consolidated statements of income.
Fair Value of Financial Instruments
The Company accounts for certain assets and liabilities at fair value. The carrying value of the Company’s financial instruments, including cash and cash equivalents, receivables, and accounts payable, approximate fair value due to their short-term nature or variable interest rates. See Notes 2, 3, and 4 for the carrying value and fair value of the Company’s investments, derivative instruments, and fixed-rate debt.
Fair value is defined as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. Fair value is estimated by applying a fair value hierarchy, which requires maximizing the use of observable inputs when measuring fair value. The three levels of inputs are:
Level 1: Quoted market prices in active markets for identical assets or liabilities.
Level 2: Observable market-based inputs or unobservable inputs that are corroborated by market
data.
Level 3: Significant unobservable inputs that are not corroborated by market data.
The Company’s valuation techniques used to measure the fair value of money market mutual funds, which are included in cash and cash equivalents, are based on quoted market prices, such as quoted net asset values published by the fund as supported in an active market. Valuation methodologies used to measure the fair value of all other non-derivative financial instruments are based on independent external valuation information. The pricing process uses data from a variety of independent external valuation information providers, including trades, bid price or spread, two-sided markets, quotes, benchmark curves including but not limited to treasury benchmarks, Secured Overnight Financing Rate and swap curves, discount rates, and market data feeds. All are observable in the market or can be derived principally from or corroborated by observable market data. The Company reports transfers in and out of Levels 1, 2, and 3, as applicable, using the fair value of the individual securities as of the beginning of the reporting period in which the transfer(s) occurred.
Current financial liabilities have fair values that approximate their carrying values. Long-term financial liabilities include the Company's long-term debt, which are recorded on the balance sheet at issuance price and adjusted for unamortized discounts or premiums and debt issuance costs. Discounts, premiums, and debt issuance costs are amortized to interest expense over the term of the loan. The estimated fair value of the Company's long-term debt is based primarily on reported market values, recently completed market transactions, and estimates based upon interest rates, maturities, and credit.
Receivables, Net
Receivables, Net
Receivables consist primarily of vendor, third-party pharmacy, credit card incentive, reinsurance, and other receivables. Vendor receivables include discounts, volume rebates, and a variety of other programs. Balances are generally presented on a gross basis, separate from any related payable due. In certain circumstances, these receivables may be settled against the related payable to that vendor, in which case the receivables are presented on a net basis. Third-party pharmacy receivables generally relate to amounts due from insurance providers. Credit card incentive receivables primarily represent amounts earned under co-branded credit card arrangements. Reinsurance receivables are held by the Company’s wholly-owned captive insurance subsidiary and primarily represent amounts ceded through reinsurance arrangements gross of the amounts assumed under reinsurance, which are presented within other current liabilities in the consolidated balance sheets. Other receivables primarily consist of amounts due from governmental entities, mostly tax-related items.
The valuation allowance related to receivables was immaterial to the Company's consolidated financial statements at the end of 2026 and 2025.
Merchandise Inventories
Merchandise inventories consist of the following:
20262025
United States $13,707 $12,868 
Canada2,188 1,907 
Other International3,429 3,341 
Merchandise inventories$19,324 $18,116 
Merchandise inventories are stated at the lower of cost or market. U.S. merchandise inventories are valued by the cost method of accounting, using the last-in, first-out (LIFO) basis. The Company believes the LIFO method more fairly presents the results of operations by more closely matching current costs with current revenues. The Company records an adjustment each quarter, if necessary, for the projected annual effect of inflation or deflation, and these estimates are adjusted to actual results determined at year-end, after actual inflation or deflation rates and inventory levels have been determined. Due to higher merchandise costs in 2026, a $206 charge was recorded to merchandise costs to increase the cumulative LIFO valuation on merchandise inventories at August 30, 2026. A charge of $142 was recorded in 2025 and an immaterial LIFO benefit was recorded in 2024. Canadian and Other International merchandise inventories are predominantly valued using the cost and retail inventory methods, respectively, using the first-in, first-out (FIFO) basis.
The Company initially provides for estimated inventory losses between physical inventory counts using estimates based on experience. The provision is adjusted to reflect physical inventory counts, which generally occur in the second and fourth fiscal quarters. Inventory cost where appropriate is reduced by estimates of vendor rebates when earned or as the Company progresses towards earning those rebates, provided that they are probable and reasonably estimable.
Property and Equipment, Net
Property and equipment are stated at cost. Depreciation and amortization expense is computed primarily using the straight-line method over estimated useful lives. Leasehold improvements made after the beginning of the initial lease term are depreciated over the shorter of the estimated useful life of the asset or the remaining term of the initial lease plus any renewals that are reasonably certain at the date of the leasehold improvements.
The Company capitalizes certain computer software and costs incurred in developing or obtaining software for internal use. During development, these costs are included in construction in progress. To the
extent that the assets become ready for their intended use, these costs are included in equipment and fixtures and amortized on a straight-line basis over estimated useful lives.
Repair and maintenance costs are expensed when incurred. Expenditures for remodels, refurbishments, and improvements that add to or change asset function or useful life are capitalized. Assets removed during the remodel, refurbishment, or improvement are retired. Assets classified as held-for-sale at the end of 2026 and 2025 were immaterial.
The following table summarizes the Company's property and equipment balances at the end of 2026 and 2025:
Estimated Useful Lives20262025
LandN/A$11,265 $10,323 
Buildings and improvements
5-50 years
27,775 25,508 
Equipment and fixtures
3-20 years
14,850 13,127 
Construction in progressN/A2,722 1,882 
56,612 50,840 
Accumulated depreciation and amortization(20,979)(18,931)
Property and equipment, net$35,633 $31,909 
The Company evaluates long-lived assets for impairment on an annual basis, when relocating or closing a facility, or when events or changes in circumstances may indicate that the carrying amount of the asset group, generally an individual warehouse, may not be fully recoverable. For asset groups held and used, including warehouses to be relocated, the carrying value of the asset group is considered recoverable when the estimated future undiscounted cash flows generated from the use and eventual disposition of the asset group exceed the respective carrying value. In the event that the carrying value is not considered recoverable, an impairment loss is recognized for the asset group to be held and used equal to the excess of the carrying value above the estimated fair value of the asset group. For asset groups classified as held-for-sale (disposal group), the carrying value is compared to the disposal group’s fair value less costs to sell. The Company estimates fair value by obtaining market appraisals from third party brokers or using other valuation techniques. There were no impairment charges recognized in 2026, and impairment charges in 2025 and 2024 were immaterial.
Leases
Leases
The Company leases land, buildings, and/or equipment at warehouses and certain other office and distribution facilities. Leases generally contain one or more of the following options, which the Company can exercise at the end of the initial term: (a) renew the lease for a defined number of years at the then-fair market rental rate or rate stipulated in the lease agreement; (b) purchase the property at the then-fair market value or purchase price stated in the agreement; (c) a right of first refusal in the event of a third-party offer; or (d) a right of first offer if the landlord intends to sell.
Some leases include free-rent periods and step-rent provisions, which are recognized on a straight-line basis over the original term of the lease and any extension options that the Company is reasonably certain to exercise from the date the Company has control of the property. Certain leases provide for periodic rent increases based on price indices or the greater of minimum guaranteed amounts or sales volume, which are recognized as variable lease payments. The Company's leases do not contain any material residual value guarantees or material restrictive covenants.
The Company determines at inception whether a contract is or contains a lease. Non-lease components and the lease components to which they relate are accounted for together as a single lease component for all asset classes. The Company initially records right-of-use (ROU) assets and lease obligations for its finance and operating leases based on the discounted future minimum lease payments over the term.
The lease term is defined as the noncancelable period of the lease plus any options to extend when it is reasonably certain that the Company will exercise the option. As the rate implicit in the Company's leases is not easily determinable, the present value of the sum of the lease payments is calculated using the Company's incremental borrowing rate. The rate is determined using a portfolio approach based on the rate of interest the Company would pay to borrow an amount equal to the lease payments on a collateralized basis over a similar term. The Company uses quoted interest rates from financial institutions to derive the incremental borrowing rate. Impairment of ROU assets is evaluated in a similar manner as described in Property and Equipment, Net above.
The Company's asset retirement obligations (ARO) primarily relate to leasehold improvements that must be removed at the end of a lease. These obligations are recorded as a discounted liability, with an offsetting asset, based upon the estimated fair value of the costs to remove the improvements. These liabilities are accreted over time to the projected future value of the obligation. The ARO assets are depreciated using the same depreciation method as the leasehold improvement assets and are included in buildings and improvements. Estimated ARO liabilities associated with these leases are included in other long-term liabilities in the consolidated balance sheet.
Goodwill and Intangible Assets, Goodwill, Policy
Goodwill and Acquired Intangible Assets
Goodwill represents the excess of acquisition cost over the fair value of the net assets acquired and is not subject to amortization. The Company reviews goodwill annually in the fourth quarter for impairment or when circumstances indicate carrying value may exceed the fair value. This evaluation is performed at the reporting unit level. If a qualitative assessment indicates that it is more likely than not that the fair value is less than carrying value, a quantitative analysis is completed using either the income or market approach, or a combination of both. The income approach estimates fair value based on expected discounted future cash flows, while the market approach uses comparable public companies and transactions to develop metrics to be applied to historical and expected future operating results.
Goodwill is included in other long-term assets in the consolidated balance sheets. At the end of 2026, 2025, and 2024 goodwill balances in the Company's U.S., Canadian, and Other International operations were $953, $26, and $15, respectively. No impairment charges were recorded in 2026, 2025, or 2024.
Definite-lived intangible assets, which are immaterial, are included in other long-term assets on the consolidated balance sheets and are amortized on a straight-line basis over their estimated lives, which approximates the pattern of expected economic benefit.
Insurance / Self-Insurance Liabilities
Insurance/Self-insurance Liabilities
Claims for employee health-care benefits, workers’ compensation, general liability, property damage, directors’ and officers’ liability, vehicle liability, inventory loss, and other exposures are funded predominantly through self-insurance. Insurance coverage is maintained for certain risks to limit exposures to very large losses. The Company uses various risk management mechanisms, including a wholly-owned captive insurance subsidiary and participates in a reinsurance program. Liabilities associated with the risks that are retained by the Company are not discounted and are estimated using historical claims experience, demographic factors, severity factors, and other actuarial assumptions. The estimated accruals for these liabilities could be significantly affected if future occurrences, claims, or expenses differ from these assumptions and historical trends. At the end of 2026 and 2025, these insurance liabilities were $2,157 and $1,878 in the aggregate, and were included in accrued salaries and benefits and other current liabilities in the consolidated balance sheets, classified based on their nature.
The captive receives direct premiums, which are netted against the Company’s premium costs in SG&A expenses in the consolidated statements of income. The captive participates in a reinsurance program that includes third-party participants. The participant agreements and practices of the reinsurance program are designed to limit participating members’ individual risk. Income statement adjustments related to the reinsurance program and related impacts to the consolidated balance sheets are
recognized as information becomes known. In the event the Company leaves the reinsurance program, the Company retains its primary obligation to the participants for prior activity.
Derivatives
Derivatives
The Company is exposed to foreign-currency exchange-rate fluctuations in the normal course of business. It manages these fluctuations, in part, through the use of forward foreign-exchange contracts, seeking to economically hedge the impact of fluctuations of foreign-exchange on known future expenditures denominated in a non-functional foreign-currency. The contracts relate primarily to U.S. dollar merchandise inventory expenditures made by the Company’s international subsidiaries with functional currencies other than the U.S. dollar. These contracts either do not qualify for or the Company has not elected derivative hedge accounting. The Company seeks to mitigate risk with the use of these contracts and does not intend to engage in speculative transactions. Some of these contracts contain credit-risk-related contingent features that require settlement of outstanding contracts upon certain triggering events. The aggregate fair value amounts of derivative instruments in a net liability position and the amount needed to settle the instruments immediately if the credit-risk-related contingent features were triggered were immaterial at the end of 2026 and 2025. The aggregate notional amounts of open, unsettled forward foreign-exchange contracts were $541 and $1,184 at the end of 2026 and 2025. See Note 3 for information on the fair value of unsettled forward foreign-exchange contracts at the end of 2026 and 2025.
The unrealized gains or losses recognized in interest income and other, net in the consolidated statements of income relating to the net changes in the fair value of unsettled forward foreign-exchange contracts were immaterial in 2026, 2025, and 2024.
The Company is exposed to fluctuations in prices for energy, particularly electricity and natural gas, and other commodities used in retail and manufacturing operations, which it seeks to partially mitigate through the use of fixed-price contracts for certain of its warehouses and other facilities, primarily in the U.S. and Canada. The Company also enters into variable-priced contracts for some purchases of natural gas, in addition to fuel for its gas stations, on an index basis. These contracts meet the characteristics of derivative instruments, but generally qualify for the “normal purchases and normal sales” exception under authoritative guidance and require no mark-to-market adjustment.
Foreign Currency
Foreign-Currency
The functional currencies of the Company’s international subsidiaries are their local currencies. Assets and liabilities recorded in foreign currencies are translated at the exchange rate on the balance sheet date. Translation adjustments are recorded in accumulated other comprehensive loss. Revenues and expenses of the Company’s consolidated foreign operations are translated at average exchange rates prevailing during the year.
The Company recognizes foreign-currency transaction gains and losses related to revaluing or settling monetary assets and liabilities denominated in currencies other than the functional currency in interest income and other, net in the consolidated statements of income. Generally, these include the U.S. dollar cash and cash equivalents and the U.S. dollar payables of consolidated subsidiaries revalued to their functional currency. Also included are realized foreign-currency gains or losses from settlements of forward foreign-exchange contracts. These items were immaterial in 2026, 2025, and 2024.
Revenue Recognition
Revenue Recognition
The Company recognizes sales for the amount of consideration collected from the member, which includes gross shipping fees where applicable, and is net of sales taxes collected and remitted to government agencies and member returns. The Company reserves for estimated returns based on historical trends and reduces sales and merchandise costs accordingly. The Company records on a gross basis a refund liability and an asset for recovery, which are included in other current liabilities and other current assets, respectively, in the consolidated balance sheets.
The Company offers merchandise in the following core merchandise categories: foods and sundries, non-foods, and fresh foods. The Company also provides expanded products and services through warehouse ancillary and other businesses. The Company is the principal for the majority of its transactions and recognizes revenue on a gross basis. The Company is the principal when it has control of the merchandise or service before it is transferred to the member. The majority of revenue from merchandise sales is recognized at the point of sale. Revenue generated through e-commerce or special orders is generally recognized upon shipment to the member. For merchandise shipped directly to the member, shipping and handling costs are expensed as incurred as fulfillment costs and included in merchandise costs in the consolidated statements of income. In certain ancillary businesses, revenue is deferred until the member picks up merchandise at the warehouse. Deferred sales are included in other current liabilities in the consolidated balance sheets.
The Company accounts for membership fee revenue, net of refunds, on a deferred basis, ratably over the one-year membership period. Deferred membership fees at the end of 2026 and 2025 were $3,006 and $2,854.
In most countries, the Company's Executive members qualify for an Executive reward, generally 2% on qualified purchases, subject to an annual maximum value, which does not expire and is redeemable at Costco warehouses. The Company accounts for this reward as a reduction in sales, net of the estimated impact of non-redemptions (breakage), with the corresponding liability classified as accrued member rewards in the consolidated balance sheets. Estimated breakage is computed based on redemption data. For 2026, 2025, and 2024, the net reduction in sales was $3,383, $3,007, and $2,804.
The Company sells and otherwise provides proprietary shop cards that do not expire and are redeemable at the warehouse or online for merchandise or membership. Revenue from shop cards is recognized upon redemption, and estimated breakage is recognized based on redemption data. The Company accounts for outstanding shop card balances as a liability, net of estimated breakage. Shop card liabilities are included in other current liabilities in the consolidated balance sheets.
Citibank, N.A. is the exclusive issuer of co-branded credit cards to U.S. members. The Company receives various forms of consideration from Citibank, including a royalty on purchases made on the card outside of Costco. A portion of the royalty is used to fund the rebate that cardholders receive, after taking into consideration breakage, which is calculated based on rebate redemption data. The rebates are issued in February and expire on December 31. The Company also maintains varying co-branded credit card arrangements in Canada and certain Other International subsidiaries.
Merchandise Costs
Merchandise Costs
Merchandise costs consist of the purchase price or manufacturing costs of inventory sold, inbound and outbound shipping charges, and all costs related to the Company’s depot, fulfillment, and manufacturing operations, and are reduced by vendor consideration. Merchandise costs also include salaries, benefits, depreciation, and utilities in fresh foods departments and certain ancillary businesses.
Vendor Consideration
The Company receives funds from vendors for discounts and a variety of other programs. These programs are evidenced by agreements that are reflected in the carrying value of the inventory when earned or as the Company progresses towards earning the rebate or discount, and as a component of merchandise costs as the merchandise is sold. Other vendor consideration is generally recorded as a reduction of merchandise costs upon completion of contractual milestones, agreement terms, or other systematic approaches.
Selling, General and Administrative Expenses
Selling, general and administrative expenses consist primarily of salaries, benefits and workers’ compensation costs for warehouse employees (other than fresh foods departments and certain ancillary
businesses, which are reflected in merchandise costs), as well as all regional and home office employees, including buying personnel. Selling, general and administrative expenses also include substantially all building and equipment depreciation, stock compensation expense, credit and debit card processing fees, utilities, preopening, as well as other operating costs incurred to support warehouse and e-commerce operations.
Retirement Plans
Retirement Plans
The Company's 401(k) retirement plan is available to all U.S. employees over the age of 18 who have completed 90 days of employment. The plan allows participants to make wage deferral contributions, a portion of which the Company matches. In addition, the Company provides each eligible participant an annual discretionary contribution. The Company also has a defined contribution plan for employees in Canada and contributes a percentage of each employee's wages. Certain subsidiaries in the Company's Other International operations have defined benefit and defined contribution plans, which are immaterial. Amounts expensed under all plans were $1,174, $1,061, and $963 for 2026, 2025, and 2024, and are predominantly included in SG&A expenses in the consolidated statements of income.
Stock-Based Compensation
The Company grants stock-based compensation, primarily to employees and non-employee directors. Grants to executive officers are generally performance-based. Through a series of shareholder approvals, there have been amended and restated plans and new provisions implemented by the Company. Restricted Stock Units (RSUs) are subject to quarterly vesting in the event of retirement or voluntary termination. Recipients are not entitled to vote or receive dividends on unvested and undelivered shares.
For grants issued prior to October 2025, RSUs generally vest over five years, with accelerated vesting provisions for participants reaching specified long-service milestones (25 years of service for employees; five years for non-employee directors). For grants issued in October 2025 and thereafter, RSUs vest over either a three-year schedule with no accelerated vesting or a five-year schedule with long-service acceleration, based on a one-time election made by eligible participants in 2025. RSUs granted to new participants vest over a three-year term with no such acceleration.
Compensation expense for awards is predominantly recognized using the straight-line method over the requisite service period for the entire award and forfeitures are recognized as they occur. Under accelerated vesting provisions, compensation expense is recognized upon achievement of the long-service term. The cumulative amount of compensation cost recognized at any point in time equals at least the portion of the grant-date fair value of the award that is vested at that date. The fair value of RSUs is calculated as the market value of the common stock on the measurement date less the present value of the expected dividends forgone during the vesting period.
Stock-based compensation expense is predominantly included in SG&A expenses in the consolidated statements of income. Certain stock-based compensation costs are capitalized or included in the cost of merchandise. See Note 7 for additional information.
Income Taxes
Income Taxes
The Company accounts for income taxes using the asset and liability method. Deferred tax assets and liabilities are recognized for the future tax consequences attributed to differences between the financial statement carrying amounts of existing assets and liabilities and their tax bases, credits and loss carry-forwards. Deferred tax assets and liabilities are measured using tax rates expected to apply to taxable income in the years in which those temporary differences and carry-forwards are expected to be recovered or settled. The effect on deferred tax assets and liabilities of a change in tax rates is recognized in income in the period that includes the enactment date. A valuation allowance is established when necessary to reduce deferred tax assets to amounts that are more likely than not expected to be realized.
The timing and amounts of deductible and taxable items and the probability of sustaining uncertain tax positions requires significant judgment. The benefits of uncertain tax positions are recorded in the Company’s consolidated financial statements only after determining a more-likely-than-not probability that the uncertain tax positions will withstand challenge from tax authorities. When facts and circumstances change, the Company reassesses these probabilities and records changes as appropriate.
Net Income per Common Share
The computation of basic net income per share uses the weighted average number of shares that were outstanding during the period. The computation of diluted net income per share uses the weighted average number of shares in the basic net income per share calculation plus the number of common shares that would be issued assuming vesting of all potentially dilutive common shares outstanding using the treasury stock method for shares subject to RSUs.
Stock Repurchase Programs
Repurchased shares of common stock are retired, in accordance with the Washington Business Corporation Act. The par value of repurchased shares is deducted from common stock and the excess repurchase price over par value is deducted by allocation to additional paid-in capital and retained earnings. The amount allocated to additional paid-in capital is the current value of additional paid-in capital per share outstanding and is applied to the number of shares repurchased. Any remaining amount is allocated to retained earnings. See Note 6 for additional information.
Recent Accounting Pronouncements Adopted and Not Yet Adopted
Recent Accounting Pronouncements Adopted
In December 2023, the FASB issued ASU 2023-09, which requires public business entities on an annual basis to disclose specific categories in the income-tax rate reconciliation, provide information for reconciling items that meet a quantitative threshold, and disclose certain information about income taxes paid. The standard is effective for annual periods beginning after December 15, 2024, with early adoption permitted. The Company adopted the ASU for the fiscal year ended August 30, 2026, on a prospective basis. See Note 8 for additional information.
Recent Accounting Pronouncements Not Yet Adopted
In November 2024, the FASB issued 2024-03, which requires disaggregated disclosures of certain costs and expenses on the income statement on an annual and interim basis. The standard is effective for fiscal years beginning after December 15, 2026, and interim periods within fiscal years beginning after December 15, 2027, with early adoption permitted. The amendments should be applied on a prospective basis. Retrospective application is permitted. The Company is evaluating the standard.
XML 36 R24.htm IDEA: XBRL DOCUMENT v3.26.3
Summary of Significant Accounting Policies (Tables)
12 Months Ended
Aug. 30, 2026
Accounting Policies [Abstract]  
Schedule of Merchandise Inventories
Merchandise inventories consist of the following:
20262025
United States $13,707 $12,868 
Canada2,188 1,907 
Other International3,429 3,341 
Merchandise inventories$19,324 $18,116 
Property, Plant, and Equipment
The following table summarizes the Company's property and equipment balances at the end of 2026 and 2025:
Estimated Useful Lives20262025
LandN/A$11,265 $10,323 
Buildings and improvements
5-50 years
27,775 25,508 
Equipment and fixtures
3-20 years
14,850 13,127 
Construction in progressN/A2,722 1,882 
56,612 50,840 
Accumulated depreciation and amortization(20,979)(18,931)
Property and equipment, net$35,633 $31,909 
XML 37 R25.htm IDEA: XBRL DOCUMENT v3.26.3
Investments (Tables)
12 Months Ended
Aug. 30, 2026
Investments, Debt and Equity Securities [Abstract]  
Available for Sale and Held to Maturity Investments
The Company’s investments were as follows:
2026:Cost
Basis
Unrealized
Losses, Net
Recorded
Basis
Available-for-sale:
Government and agency securities$810 $(14)$796 
Held-to-maturity:
Certificates of deposit298 — 298 
Total short-term investments$1,108 $(14)$1,094 
2025:Cost
Basis
Unrealized
Gains, Net
Recorded
Basis
Available-for-sale:
Government and agency securities$783 $3 $786 
Held-to-maturity:
Certificates of deposit337 — 337 
Total short-term investments$1,120 $3 $1,123 
Maturities of Available for Sale and Held to Maturity Securities
The maturities of available-for-sale and held-to-maturity securities at the end of 2026 are as follows:
Available-For-SaleHeld-To-Maturity
Cost BasisFair Value
Due in one year or less$126 $126 $298 
Due after one year through five years411 405 — 
Due after five years273 265 — 
Total$810 $796 $298 
XML 38 R26.htm IDEA: XBRL DOCUMENT v3.26.3
Fair Value Measurement (Tables)
12 Months Ended
Aug. 30, 2026
Fair Value Disclosures [Abstract]  
Fair Value of Financial Assets and Liabilities Measured on Recurring Basis
The following table presents information regarding the Company’s financial assets and liabilities that are measured at fair value on a recurring basis and indicates the level within the hierarchy reflecting the valuation techniques utilized to determine such fair value:
Level 2
20262025
Investment in government and agency securities$796 $786 
Forward foreign-exchange contracts, in asset position(1)
1 6 
Forward foreign-exchange contracts, in (liability) position(1)
(3)(14)
Total$794 $778 
 ____________
(1)The asset and liability values are included in other current assets and other current liabilities, respectively, in the consolidated balance sheets.
XML 39 R27.htm IDEA: XBRL DOCUMENT v3.26.3
Debt (Tables)
12 Months Ended
Aug. 30, 2026
Debt Disclosure [Abstract]  
Carrying Value of Company's Long-Term Debt The carrying value of long-term debt consisted of the following:
20262025
3.000% Senior Notes due May 2027
$1,000 $1,000 
1.375% Senior Notes due June 2027
1,250 1,250 
1.600% Senior Notes due April 2030
1,750 1,750 
1.750% Senior Notes due April 2032
1,000 1,000 
Other long-term debt1,175 805 
Total long-term debt6,175 5,805 
Less unamortized debt discounts and issuance costs13 17 
Less current portion(1)
2,248 75 
Long-term debt, excluding current portion$3,914 $5,713 
_____________
(1)Net of unamortized debt discounts and issuance costs.
Schedule of Maturities of Long-term Debt
Maturities of long-term debt during the next five fiscal years and thereafter are as follows:
2027$2,250 
2028— 
2029136 
20301,750 
2031161 
Thereafter
1,878 
Total
$6,175 
XML 40 R28.htm IDEA: XBRL DOCUMENT v3.26.3
Leases (Tables)
12 Months Ended
Aug. 30, 2026
Leases [Abstract]  
DisclosureofSupplementalBalanceSheetInformationRelatedtoLeases
Information regarding the Company's lease assets and liabilities were as follows:
20262025
Assets
Operating lease right-of-use assets$2,697 $2,725 
Finance lease assets(1)
1,413 1,488 
Total lease assets$4,110 $4,213 
Liabilities
Current
Operating lease liabilities(2)
$192 $208 
Finance lease liabilities(2)
94 78 
Long-term
Operating lease liabilities2,414 2,460 
Finance lease liabilities(3)
1,319 1,401 
Total lease liabilities$4,019 $4,147 
 _______________
(1)Included in other long-term assets in the consolidated balance sheets.
(2)Included in other current liabilities in the consolidated balance sheets.
(3)Included in other long-term liabilities in the consolidated balance sheets.
20262025
Weighted-average remaining lease term (years)
Operating leases
1920
Finance leases
2325
Weighted-average discount rate
Operating leases
3.20 %3.05 %
Finance leases
4.72 %4.63 %
Lease, Cost
The components of lease expense, excluding short-term lease costs and sublease income (which were immaterial), were as follows:
202620252024
Operating lease costs(1)
$282 $271 $284 
Finance lease costs:
Amortization of lease assets(1)
106 102 97 
Interest on lease liabilities(2)
64 63 58 
Variable lease costs(1)
195 182 163 
Total lease costs$647 $618 $602 
 _______________
(1)Included in selling, general and administrative expenses and merchandise costs in the consolidated statements of income.
(2)Included in interest expense and merchandise costs in the consolidated statements of income.
Supplemental cash flow information related to leases were as follows:
202620252024
Cash paid for amounts included in the measurement of lease liabilities:
Operating cash flows — operating leases$312 $255 $274 
Operating cash flows — finance leases
62 58 58 
Financing cash flows — finance leases
89 147 136 
Operating lease assets obtained in exchange for new or modified leases238 294 125 
Finance lease assets obtained in exchange for new or modified leases122 131 200 
Schedule of Future Minimum Payments Under Operating Leases
As of August 30, 2026, future minimum payments during the next five fiscal years and thereafter are as follows:
Operating Leases(1)
Finance Leases
2027$252 $146 
2028258 142 
2029226 130 
2030204 118 
2031186 97 
Thereafter2,399 1,657 
Total(2)
3,525 2,290 
Less amount representing interest919 877 
Present value of lease liabilities$2,606 $1,413 
 _______________
(1)Operating lease payments have not been reduced by expected future sublease income of $90.
(2)Excludes $1,667 of lease payments for leases that have been signed but not commenced.
Schedule of Future Minimum Payments under Financing Leases
As of August 30, 2026, future minimum payments during the next five fiscal years and thereafter are as follows:
Operating Leases(1)
Finance Leases
2027$252 $146 
2028258 142 
2029226 130 
2030204 118 
2031186 97 
Thereafter2,399 1,657 
Total(2)
3,525 2,290 
Less amount representing interest919 877 
Present value of lease liabilities$2,606 $1,413 
 _______________
(1)Operating lease payments have not been reduced by expected future sublease income of $90.
(2)Excludes $1,667 of lease payments for leases that have been signed but not commenced.
XML 41 R29.htm IDEA: XBRL DOCUMENT v3.26.3
Stockholders' Equity (Tables)
12 Months Ended
Aug. 30, 2026
Stockholders' Equity Note [Abstract]  
Stock repurchase activity The following table summarizes the Company’s stock repurchase activity:
Shares
Repurchased
(000’s)
Average
Price per
Share
Total Cost
2026891 $950.90 $847 
2025943 957.66 903 
20241,004 695.29 698 
XML 42 R30.htm IDEA: XBRL DOCUMENT v3.26.3
Stock-Based Compensation Plans (Tables)
12 Months Ended
Aug. 30, 2026
Share-Based Payment Arrangement [Abstract]  
Summary of RSU Transactions
The following table summarizes RSU transactions during 2026:
Number of
Units
(in 000’s)
Weighted-Average
Grant Date Fair
Value
Outstanding at the end of 20252,308 $597.00 
Granted1,088 933.56 
Vested and delivered(1,303)669.59 
Forfeited(93)696.05 
Outstanding at the end of 20262,000 $728.17 
Summary of Stock-Based Compensation Expense and Related Tax Benefits
The following table summarizes stock-based compensation expense and the related tax benefits:
202620252024
Stock-based compensation expense$924 $860 $818 
Less recognized income tax benefit
212 183 173 
Stock-based compensation expense, net$712 $677 $645 
XML 43 R31.htm IDEA: XBRL DOCUMENT v3.26.3
Income Taxes (Tables)
12 Months Ended
Aug. 30, 2026
Income Tax Disclosure [Abstract]  
Schedule of Income before Income Tax, Domestic and Foreign
Income before income taxes is comprised of the following:
202620252024
Domestic$9,070 $8,324 $7,255 
Foreign3,181 2,494 2,485 
Total$12,251 $10,818 $9,740 
Schedule of Components of Income Tax Expense (Benefit)
The provisions for income taxes are as follows:
202620252024
Federal:
Current$1,206 $1,395 $1,245 
Deferred328 (42)48 
Total federal1,534 1,353 1,293 
State:
Current472 449 431 
Deferred21 (18)(77)
Total state493 431 354 
Foreign:
Current1,041 955 798 
Deferred(43)(20)(72)
Total foreign998 935 726 
Total provision for income taxes$3,025 $2,719 $2,373 
Schedule of Effective Income Tax Rate Reconciliation
The reconciliation between the statutory tax rate and the effective rate for 2026 is as follows:
2026
Federal taxes at statutory rate$2,573 21.0 %
State and local income taxes, net of federal income tax effect(1)
402 3.3 
Foreign tax effects:
Canada - subnational taxes185 1.5 
Canada - other(12)(0.1)
Other foreign jurisdictions117 1.0 
Effect of cross-border tax laws(46)(0.4)
Tax credits:
Research and development(134)(1.1)
Other tax credits(99)(0.8)
Changes in valuation allowance62 0.5 
Nontaxable or nondeductible items(75)(0.6)
Changes in unrecognized tax benefits50 0.4 
Other adjustments2 — 
Total$3,025 24.7 %
 _______________
(1)State taxes in California, New York, New Jersey, and Oregon make up the majority (greater than 50%) of the tax effect in this category.
The reconciliation between the statutory tax rate and the effective rate for 2025 and 2024 is as follows:
20252024
Federal taxes at statutory rate$2,272 21.0 %$2,045 21.0 %
State taxes, net338 3.1 288 3.0 
Foreign taxes, net222 2.1 109 1.1 
Employee stock ownership plan (ESOP)(28)(0.3)(120)(1.2)
Other(85)(0.8)51 0.5 
Total$2,719 25.1 %$2,373 24.4 %
Schedule of Cash Flow, Supplemental Disclosures
The following is a supplemental schedule of cash paid for income taxes, net of refunds:
2026
U.S. federal$1,377 
U.S. state and local:
California209 
Other322 
Foreign:
Canada430 
Mexico185 
Other316 
Total$2,839 
Schedule of Deferred Tax Assets and Liabilities
The components of the deferred tax assets (liabilities) are as follows:
20262025
Deferred tax assets:
Equity compensation$122 $100 
Deferred income/membership fees398 369 
Foreign tax credit carry forward470 390 
Operating lease liabilities710 699 
Accrued liabilities and reserves1,041 917 
Total deferred tax assets2,741 2,475 
Valuation allowance(641)(554)
Total net deferred tax assets2,100 1,921 
Deferred tax liabilities:
Property and equipment(1,372)(944)
Merchandise inventories(344)(305)
Operating lease right-of-use assets(675)(670)
Foreign branch deferreds(107)(103)
Other(33)(31)
Total deferred tax liabilities(2,531)(2,053)
Net deferred tax liabilities$(431)$(132)
Schedule Of Gross Unrecognized Tax Benefits Table
A reconciliation of the beginning and ending amount of gross unrecognized tax benefits for 2026 and 2025 is as follows:
20262025
Gross unrecognized tax benefit at beginning of year$65 $81 
Gross increases—current year tax positions18 9 
Gross increases—tax positions in prior years25 14 
Gross decreases—tax positions in prior years(6)(38)
Gross decreases—settlements(8)(1)
Gross unrecognized tax benefit at end of year$94 $65 
XML 44 R32.htm IDEA: XBRL DOCUMENT v3.26.3
Net Income per Common and Common Equivalent Share Net Income per Common and Common Equivalent Share (Tables)
12 Months Ended
Aug. 30, 2026
Earnings Per Share [Abstract]  
Schedule of Earnings Per Share, Basic and Diluted
The following table shows the amounts used in computing net income per share and the weighted average number of shares of basic and of potentially dilutive common shares outstanding (shares in 000’s):
202620252024
Net income
$9,226 $8,099 $7,367 
Weighted average basic shares
443,953 443,985 443,914 
RSUs474 818 845 
Weighted average diluted shares
444,427 444,803 444,759 
XML 45 R33.htm IDEA: XBRL DOCUMENT v3.26.3
Segment Reporting (Tables)
12 Months Ended
Aug. 30, 2026
Segment Reporting [Abstract]  
Segment Reporting Information, by Segment
The following table provides the revenue, significant expenses, and operating income for the Company's reportable segments:
202620252024
United States
Total revenue$219,823 $200,046 $184,143 
Merchandise costs191,440 174,021 160,573 
Selling, general and administrative expenses20,736 19,147 17,353 
Operating income$7,647 $6,878 $6,217 
Canada
Total revenue$40,561 $36,923 $34,874 
Merchandise costs35,287 32,204 30,543 
Selling, general and administrative expenses3,167 2,870 2,683 
Operating income$2,107 $1,849 $1,648 
Other International
Total revenue$42,770 $38,266 $35,436 
Merchandise costs37,552 33,661 31,242 
Selling, general and administrative expenses3,287 2,949 2,774 
Operating income$1,931 $1,656 $1,420 
Total
Total revenue$303,154 $275,235 $254,453 
Merchandise costs264,279 239,886 222,358 
Selling, general and administrative expenses27,190 24,966 22,810 
Operating income11,685 10,383 9,285 
Other income(1)
566 435 455 
Income before income taxes$12,251 $10,818 $9,740 
 ____________
(1)Other income consists of interest expense and interest income and other, net.
The following table provides depreciation and amortization and other asset related information for the Company's reportable segments:
202620252024
United States
Depreciation and amortization$2,082 $1,895 $1,730 
Additions to property and equipment5,122 4,215 3,725 
Property and equipment, net25,714 22,790 20,638 
Total assets65,090 54,862 48,816 
Canada
Depreciation and amortization$219 $196 $192 
Additions to property and equipment673 580 351 
Property and equipment, net3,395 2,930 2,602 
Total assets8,026 7,304 6,915 
Other International
Depreciation and amortization$373 $335 $315 
Additions to property and equipment640 703 634 
Property and equipment, net6,524 6,189 5,792 
Total assets15,929 14,933 14,100 
Total
Depreciation and amortization$2,674 $2,426 $2,237 
Additions to property and equipment6,435 5,498 4,710 
Property and equipment, net35,633 31,909 29,032 
Total assets89,045 77,099 69,831 
Revenue from External Customers by Products and Services
The following table summarizes net sales by merchandise category; sales from e-commerce sites and business centers have been allocated to the applicable merchandise categories:
202620252024
Foods and Sundries
$116,788 $109,564 $101,463 
Non-Foods
77,375 71,190 63,973 
Fresh Foods
41,715 37,988 34,220 
Warehouse Ancillary and Other Businesses
61,369 51,170 49,969 
Total net sales
$297,247 $269,912 $249,625 
XML 46 R34.htm IDEA: XBRL DOCUMENT v3.26.3
Accounting Policies - Additional Information (Details)
Aug. 30, 2026
warehouse
states
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 939
UNITED STATES  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 647
Number of states in country | states 47
CANADA  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 115
MEXICO  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 43
JAPAN  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 37
UNITED KINGDOM  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 29
KOREA  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 20
AUSTRALIA  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 15
TAIWAN  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 14
CHINA  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 7
SPAIN  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 5
FRANCE  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 3
SWEDEN  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 2
ICELAND  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 1
NEW ZEALAND  
Summary Of Significant Accounting Policies [Line Items]  
Number of warehouses operated 1
XML 47 R35.htm IDEA: XBRL DOCUMENT v3.26.3
Accounting Policies - Cash and Cash Equivalents (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Accounting Policies [Abstract]    
Credit and debit card receivables, at carrying value $ 2,842 $ 2,670
XML 48 R36.htm IDEA: XBRL DOCUMENT v3.26.3
Accounting Policies - Merchandise Inventories (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Accounting Policies [Abstract]    
Inventory, LIFO Reserve, Period Charge $ 206 $ 142
Schedule of Inventory [Line Items]    
Merchandise inventories 19,324 18,116
UNITED STATES    
Schedule of Inventory [Line Items]    
LIFO Inventory Amount 13,707 12,868
CANADA    
Schedule of Inventory [Line Items]    
FIFO Inventory Amount 2,188 1,907
Other International    
Schedule of Inventory [Line Items]    
FIFO Inventory Amount $ 3,429 $ 3,341
XML 49 R37.htm IDEA: XBRL DOCUMENT v3.26.3
Accounting Policies - Property and Equipment, Net (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Property and Equipment, Net [Line Items]      
Land $ 11,265 $ 10,323  
Buildings and improvements 27,775 25,508  
Equipment and fixtures 14,850 13,127  
Construction in progress 2,722 1,882  
Gross property and equipment 56,612 50,840  
Accumulated depreciation and amortization (20,979) (18,931)  
Property and equipment, net $ 35,633 $ 31,909 $ 29,032
Building and improvements [Member] | Minimum [Member]      
Property and Equipment, Net [Line Items]      
Property, plant and equipment, useful life 5 years    
Building and improvements [Member] | Maximum [Member]      
Property and Equipment, Net [Line Items]      
Property, plant and equipment, useful life 50 years    
Equipment and Fixtures [Member] | Minimum [Member]      
Property and Equipment, Net [Line Items]      
Property, plant and equipment, useful life 3 years    
Equipment and Fixtures [Member] | Maximum [Member]      
Property and Equipment, Net [Line Items]      
Property, plant and equipment, useful life 20 years    
XML 50 R38.htm IDEA: XBRL DOCUMENT v3.26.3
Accounting Policies - Goodwill and Acquired Intangible Assets (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Goodwill [Line Items]      
Goodwill $ 994 $ 994 $ 994
Operating Segments | UNITED STATES      
Goodwill [Line Items]      
Goodwill 953 953 953
Operating Segments | CANADA      
Goodwill [Line Items]      
Goodwill 26 26 26
Operating Segments | Other International      
Goodwill [Line Items]      
Goodwill $ 15 $ 15 $ 15
XML 51 R39.htm IDEA: XBRL DOCUMENT v3.26.3
Accounting Policies - Insurance/Self-Insurance Liabilities (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Accounting Policies [Abstract]    
Accrued insurance $ 2,157 $ 1,878
XML 52 R40.htm IDEA: XBRL DOCUMENT v3.26.3
Accounting Policies - Derivatives (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Forward foreign exchange contracts    
Derivative [Line Items]    
Derivative, Notional Amount $ 541 $ 1,184
XML 53 R41.htm IDEA: XBRL DOCUMENT v3.26.3
Accounting Policies - Revenue Recognition (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Summary Of Significant Accounting Policies [Line Items]      
Deferred membership fees $ 3,006 $ 2,854  
Reduction in sales $ 3,383 $ 3,007 $ 2,804
XML 54 R42.htm IDEA: XBRL DOCUMENT v3.26.3
Accounting Policies - Retirement Plans (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Accounting Policies [Abstract]      
Minimum number of days of employment to qualify for retirement plan 90 days    
Defined contribution plan, cost recognized $ 1,174 $ 1,061 $ 963
XML 55 R43.htm IDEA: XBRL DOCUMENT v3.26.3
Accounting Policies - Stock-Based Compensation (Details)
12 Months Ended
Aug. 30, 2026
Minimum [Member]  
Summary Of Significant Accounting Policies [Line Items]  
Share-based compensation arrangement by share-based payment award, award vesting period 3 years
Maximum [Member]  
Summary Of Significant Accounting Policies [Line Items]  
Share-based compensation arrangement by share-based payment award, award vesting period 5 years
Employees [Member]  
Summary Of Significant Accounting Policies [Line Items]  
Share-based compensation arrangement by share-based payment number of years of service 25 years
XML 56 R44.htm IDEA: XBRL DOCUMENT v3.26.3
Investments - Available for Sale and Held to Maturity Investments (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Available For Sale And Held To Maturity [Line Items]    
Available-for-sale, cost basis $ 810  
Unrealized Losses, Net (14)  
Unrealized Gains, Net   $ 3
Available-for-sale, recorded basis, total 796  
Held-to-maturity, cost basis 298  
Total short-term investments, cost basis 1,108 1,120
Total investments, recorded basis 1,094 1,123
US Government Agencies Debt Securities [Member]    
Available For Sale And Held To Maturity [Line Items]    
Available-for-sale, cost basis 810 783
Unrealized Losses, Net (14)  
Unrealized Gains, Net   3
Available-for-sale, recorded basis, total 796 786
Certificates of Deposit [Member]    
Available For Sale And Held To Maturity [Line Items]    
Held-to-maturity, cost basis 298 337
Held-to-maturity, recorded basis $ 298 $ 337
XML 57 R45.htm IDEA: XBRL DOCUMENT v3.26.3
Investments - Maturities of Available for Sale and Held to Maturity Securities (Details)
$ in Millions
Aug. 30, 2026
USD ($)
Available-For-Sale, Cost Basis  
Due in one year or less $ 126
Due after one year through five years 411
Due after five years 273
Available-for-sale, cost basis, total 810
Available-For-Sale, Fair Value  
Due in one year or less 126
Due after one year through five years 405
Due after five years 265
Available-for-sale, recorded basis, total 796
Held-To-Maturity  
Due in one year or less 298
Due after one year through five years 0
Due after five years 0
Held-to-maturity, cost basis, total $ 298
XML 58 R46.htm IDEA: XBRL DOCUMENT v3.26.3
Fair Value Measurement - Fair Value of Financial Assets and Financial Liabilities Measured on Recurring Basis (Details) - Fair Value, Recurring [Member] - Fair Value, Inputs, Level 2 [Member] - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair value of assets measured on recurring basis $ 794 $ 778
Government and Agency Securities [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair value of assets measured on recurring basis 796 786
Foreign Exchange Forward [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair value of assets measured on recurring basis [1] 1 6
Fair value of liabilities measured on recurring basis [1] $ (3) $ (14)
[1] The asset and liability values are included in other current assets and other current liabilities, respectively, in the consolidated balance sheets.
XML 59 R47.htm IDEA: XBRL DOCUMENT v3.26.3
Debt, Schedule Of Short-Term Debt (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Line of Credit Facility [Line Items]    
Line of credit facility, current borrowing capacity $ 2,118 $ 1,220
UNITED STATES    
Line of Credit Facility [Line Items]    
Line of credit facility, current borrowing capacity $ 1,000 $ 400
XML 60 R48.htm IDEA: XBRL DOCUMENT v3.26.3
Debt, Schedule of Long-Term Debt (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Debt Instrument [Line Items]      
Debt Instrument, Redemption Price, Percentage 100.00%    
Redemption Price Certain Events 101.00%    
Proceeds from issuance of long-term debt $ 496 $ 0 $ 498
Long-term Debt, Fair Value $ 5,689 5,370  
Minimum [Member]      
Debt Instrument [Line Items]      
Debt instrument, interest rate, stated percentage 2.62%    
Maximum [Member]      
Debt Instrument [Line Items]      
Debt instrument, interest rate, stated percentage 3.68%    
0.630% Senior Notes Due March 2026      
Debt Instrument [Line Items]      
Repayments of Debt $ 69    
0.790% Senior Notes Due May 2025      
Debt Instrument [Line Items]      
Repayments of Debt   $ 103  
0.920% Senior Notes Due July 2024      
Debt Instrument [Line Items]      
Repayments of Debt     77
2.750% Senior Notes due May 2024      
Debt Instrument [Line Items]      
Debt instrument, interest rate, stated percentage   2.75%  
Repayments of Debt     $ 1,000
XML 61 R49.htm IDEA: XBRL DOCUMENT v3.26.3
Debt, Carrying Value of Long-Term Debt (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Debt Instrument [Line Items]    
Long-Term Debt, Gross $ 6,175 $ 5,805
Less unamortized debt discounts and issuance costs 13 17
Current portion of long-term debt [1] 2,248 75
Long-term debt, excluding current portion 3,914 5,713
3.000% Senior Notes due May 2027    
Debt Instrument [Line Items]    
Long-Term Debt, Gross $ 1,000 1,000
Debt instrument, interest rate, stated percentage 3.00%  
1.375% Senior Notes due June 2027    
Debt Instrument [Line Items]    
Long-Term Debt, Gross $ 1,250 1,250
Debt instrument, interest rate, stated percentage 1.375%  
1.600% Senior Notes due April 2030    
Debt Instrument [Line Items]    
Long-Term Debt, Gross $ 1,750 1,750
Debt instrument, interest rate, stated percentage 1.60%  
1.750% Senior Notes due April 2032    
Debt Instrument [Line Items]    
Long-Term Debt, Gross $ 1,000 1,000
Debt instrument, interest rate, stated percentage 1.75%  
Other Long Term Debt    
Debt Instrument [Line Items]    
Long-Term Debt, Gross $ 1,175 $ 805
[1] Net of unamortized debt discounts and issuance costs.
XML 62 R50.htm IDEA: XBRL DOCUMENT v3.26.3
Debt, Schedule Of Long-Term Debt Maturities (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Debt Disclosure [Abstract]    
2027 $ 2,250  
2028 0  
2029 136  
2030 1,750  
2031 161  
Thereafter 1,878  
Long-Term Debt, Gross $ 6,175 $ 5,805
XML 63 R51.htm IDEA: XBRL DOCUMENT v3.26.3
Leases, Supplemental Balance Sheet Information (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Operating Lease and Finance Lease Right-of-Use-Assets [Abstract]    
Operating lease right-of-use assets $ 2,697 $ 2,725
Finance lease assets $ 1,413 $ 1,488
Finance lease assets Other long-term assets Other long-term assets
OperatingLeaseandFinanceLeaserightofuseassets $ 4,110 $ 4,213
Current Operating and Finance Lease Liabilities [Abstract]    
Current operating lease liabilities 192 208
Current finance lease liabilities $ 94 $ 78
Operating lease liabilities Other current liabilities Other current liabilities
Finance lease liabilities Other current liabilities Other current liabilities
Long-Term Operating and Finance Lease Liabilities [Abstract]    
Long-term operating lease liabilities $ 2,414 $ 2,460
Long-term finance lease liabilities $ 1,319 $ 1,401
Long-term finance lease liabilities Other long-term liabilities Other long-term liabilities
OperatingLeaseandFinanceLeaseLiabilities $ 4,019 $ 4,147
Other Supplemental Balance Sheet Information [Abstract]    
Operating Lease, Weighted Average Remaining Lease Term 19 years 20 years
Finance Lease, Weighted Average Remaining Lease Term 23 years 25 years
Operating Lease, Weighted Average Discount Rate, Percent 3.20% 3.05%
Finance Lease, Weighted Average Discount Rate, Percent 4.72% 4.63%
XML 64 R52.htm IDEA: XBRL DOCUMENT v3.26.3
Leases, Components of Lease Expense (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Lease, Cost [Abstract]      
Operating Lease, Cost $ 282 $ 271 $ 284
Finance Lease, Right-of-Use Asset, Amortization 106 102 97
Finance Lease, Interest Expense 64 63 58
Variable Lease, Cost 195 182 163
Total lease costs $ 647 $ 618 $ 602
XML 65 R53.htm IDEA: XBRL DOCUMENT v3.26.3
Leases, Supplemental Cash Flow Information (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Leases [Abstract]      
Operating cash flows - operating leases $ 312 $ 255 $ 274
Operating cash flows - finance leases 62 58 58
Financing cash flows - finance leases 89 147 136
Operating lease assets obtained in exchange for new or modified leases 238 294 125
Finance lease assets obtained in exchange for new or modified leases $ 122 $ 131 $ 200
XML 66 R54.htm IDEA: XBRL DOCUMENT v3.26.3
Leases, Future Minimum Payments (Details)
$ in Millions
Aug. 30, 2026
USD ($)
Lessee, Operating Lease, Liability, to be Paid, Fiscal Year Maturity [Abstract]  
2027 $ 252
2028 258
2029 226
2030 204
2031 186
Thereafter 2,399
Total 3,525
Less amount representing interest (919)
Present value of lease liabilities 2,606
Finance Lease, Liability, Payment, Due, Rolling Maturity [Abstract]  
2027 146
2028 142
2029 130
2030 118
2031 97
Thereafter 1,657
Total 2,290
Less amount representing interest (877)
Present value of lease liabilities 1,413
Lessor, Operating Lease, Payments to be Received 90
LesseeOperatingandFinancingLeasesNotYetCommenced $ 1,667
XML 67 R55.htm IDEA: XBRL DOCUMENT v3.26.3
Stockholders' Equity - Additional Information (Details) - USD ($)
$ / shares in Units, $ in Millions
4 Months Ended 12 Months Ended
Aug. 30, 2026
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Dividends Payable [Line Items]        
Common Stock, Dividends, Per Share, Declared $ 1.47 $ 5.54 $ 4.92  
Dividends, Common Stock, Cash   $ 2,458 $ 2,183  
Special Dividend [Member]        
Dividends Payable [Line Items]        
Common Stock, Dividends, Per Share, Declared       $ 15
Special Dividend [Member] | Common Stock        
Dividends Payable [Line Items]        
Dividends       $ 6,655
XML 68 R56.htm IDEA: XBRL DOCUMENT v3.26.3
Equity - Additional Information - Stock Repurchase Programs (Details)
$ in Millions
Aug. 30, 2026
USD ($)
Equity [Abstract]  
Stock Repurchase Program, Authorized Amount $ 4,000
Stock Repurchase Program, Remaining Authorized Repurchase Amount $ 1,115
XML 69 R57.htm IDEA: XBRL DOCUMENT v3.26.3
Stockholders' Equity (Stock Repurchased During Period) (Details) - USD ($)
$ / shares in Units, shares in Thousands, $ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Stockholders' Equity Note [Abstract]      
Repurchases of common stock, shares 891 943 1,004
Average price per share $ 950.90 $ 957.66 $ 695.29
Repurchases of common stock, value $ 847 $ 903 $ 698
XML 70 R58.htm IDEA: XBRL DOCUMENT v3.26.3
Stock-Based Compensation Plans - Additional Information (Details) - USD ($)
$ / shares in Units, shares in Thousands, $ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Weighted-average grant date fair value $ 933.56 $ 883.46 $ 547.26
RSUs vested, but not yet delivered (shares) 1,303    
Granted 1,088    
Restricted Stock Units (RSUs)      
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Number of shares available to be granted as RSUs 5,280    
Share-Based Compensation Arrangement by Share-Based Payment Award, Non-Option Equity Instruments, Outstanding, Number 1,877    
Unrecognized compensation cost $ 922    
Weighted-average recognition period 1 year 6 months    
RSUs vested, but not yet delivered (shares) 704    
Performance Shares [Member]      
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Share-Based Compensation Arrangement by Share-Based Payment Award, Non-Option Equity Instruments, Outstanding, Number 123    
Granted 67    
Maximum [Member] | Restricted Stock Units (RSUs)      
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Number of shares available to be granted as RSUs 15,885    
XML 71 R59.htm IDEA: XBRL DOCUMENT v3.26.3
Stock-Based Compensation Plans - Summary of RSU Transactions (Details) - $ / shares
shares in Thousands
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Number of units      
Outstanding at the end of 2025 2,308    
Granted 1,088    
Vested and delivered (1,303)    
Forfeited (93)    
Outstanding at the end of 2026 2,000 2,308  
Weighted average grant date fair value      
Outstanding at the end of 2025 $ 597.00    
Granted 933.56 $ 883.46 $ 547.26
Vested and delivered 669.59    
Forfeited 696.05    
Outstanding at the end of 2026 $ 728.17 $ 597.00  
XML 72 R60.htm IDEA: XBRL DOCUMENT v3.26.3
Stock-Based Compensation Plans - Summary of Stock-Based Compensation Expense (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Share-Based Payment Arrangement [Abstract]      
Total stock-based compensation expense before income taxes $ 924 $ 860 $ 818
Less income tax benefit 212 183 173
Stock-based compensation expense, net $ 712 $ 677 $ 645
XML 73 R61.htm IDEA: XBRL DOCUMENT v3.26.3
Income Taxes (Income Before Income Taxes) (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Income Tax Disclosure [Abstract]      
Domestic $ 9,070 $ 8,324 $ 7,255
Foreign 3,181 2,494 2,485
INCOME BEFORE INCOME TAXES $ 12,251 $ 10,818 $ 9,740
XML 74 R62.htm IDEA: XBRL DOCUMENT v3.26.3
Income Taxes (Schedule of Foreign And Domestic Income Taxes) (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Federal [Abstract]      
Current $ 1,206 $ 1,395 $ 1,245
Deferred 328 (42) 48
Total federal 1,534 1,353 1,293
State [Abstract]      
Current 472 449 431
Deferred 21 (18) (77)
Total state 493 431 354
Foreign [Abstract]      
Current 1,041 955 798
Deferred (43) (20) (72)
Total foreign 998 935 726
Total provision for income taxes $ 3,025 $ 2,719 $ 2,373
XML 75 R63.htm IDEA: XBRL DOCUMENT v3.26.3
Income Taxes (Reconciliation Between Statutory And Effective Rates) (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Income Tax Expense (Benefit), Effective Income Tax Rate Reconciliation, Amount [Abstract]      
Federal taxes at statutory rate $ 2,573 $ 2,272 $ 2,045
State taxes, net 402 338 288
Foreign taxes, net   222 109
Effect of cross-border tax laws 46    
Tax credits:      
Tax credits - Research and development (134)    
Tax credits - Other tax credits (99)    
Changes in valuation allowance 62    
Nontaxable or nondeductible 75    
Changes in unrecognized tax benefits (50)    
Other 2 (85) 51
Total provision for income taxes $ 3,025 $ 2,719 $ 2,373
Effective Income Tax Rate Reconciliation, Percent [Abstract]      
Federal taxes at statutory rate 21.00% 21.00% 21.00%
State taxes, net 3.30% 3.10% 3.00%
Foreign taxes, net   2.10% 1.10%
Effect of cross-border tax laws 0.40%    
Tax credits:      
Tax credits - Research and development (1.10%)    
Tax credits - Other tax credits (0.80%)    
Changes in valuation allowance 0.50%    
Changes in valuation allowance 0.60%    
Changes in unrecognized tax benefits 0.40%    
Other 0.00% (0.80%) 0.50%
Total 24.70% 25.10% 24.40%
Tax Jurisdiction of Domicile [Extensible Enumeration] UNITED STATES    
CANADA      
Income Tax Expense (Benefit), Effective Income Tax Rate Reconciliation, Amount [Abstract]      
Foreign taxes, net $ 185    
Effective Income Tax Rate Reconciliation, Percent [Abstract]      
Foreign taxes, net 1.50%    
Canada Other      
Income Tax Expense (Benefit), Effective Income Tax Rate Reconciliation, Amount [Abstract]      
Foreign taxes, net $ (12)    
Effective Income Tax Rate Reconciliation, Percent [Abstract]      
Foreign taxes, net (0.10%)    
Foreign, Other      
Income Tax Expense (Benefit), Effective Income Tax Rate Reconciliation, Amount [Abstract]      
Foreign taxes, net $ 117    
Effective Income Tax Rate Reconciliation, Percent [Abstract]      
Foreign taxes, net 1.00%    
XML 76 R64.htm IDEA: XBRL DOCUMENT v3.26.3
Income Taxes (Reconciliation Between Statutory and Effective Rates FY25 and FY24) (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Income Tax Expense (Benefit), Effective Income Tax Rate Reconciliation, Amount [Abstract]      
Federal taxes at statutory rate $ 2,573 $ 2,272 $ 2,045
State taxes, net 402 338 288
Foreign taxes, net   222 109
Employee stock ownership plan (ESOP)   (28) (120)
Other 2 (85) 51
Total provision for income taxes $ 3,025 $ 2,719 $ 2,373
Effective Income Tax Rate Reconciliation, Percent [Abstract]      
Federal taxes at statutory rate 21.00% 21.00% 21.00%
State taxes, net 3.30% 3.10% 3.00%
Foreign taxes, net   2.10% 1.10%
Employee stock ownership plan (ESOP) (percent)   (0.30%) (1.20%)
Other 0.00% (0.80%) 0.50%
Total 24.70% 25.10% 24.40%
XML 77 R65.htm IDEA: XBRL DOCUMENT v3.26.3
Income Taxes (Reconciliation Between Statutory and Effective Rates Narrative) (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Effective Income Tax Rate Reconciliation [Line Items]      
Transfer pricing settlement and certain true-ups of tax reserves tax benefit     $ (63)
Special Dividend [Member]      
Effective Income Tax Rate Reconciliation [Line Items]      
Stock compensation tax benefits     94
Restricted Stock Units (RSUs)      
Effective Income Tax Rate Reconciliation [Line Items]      
Stock compensation tax benefits $ 72 $ 100 $ 45
XML 78 R66.htm IDEA: XBRL DOCUMENT v3.26.3
Income Taxes Cash Paid for Income Taxes (Details)
$ in Millions
12 Months Ended
Aug. 30, 2026
USD ($)
Income Tax Paid, by Individual Jurisdiction [Line Items]  
Income Tax Paid, Federal, after Refund Received $ 1,377
Income Tax Paid, after Refund Received, Total 2,839
CALIFORNIA  
Income Tax Paid, by Individual Jurisdiction [Line Items]  
Income Tax Paid, State and Local, after Refund Received 209
U.S. state and local, Other  
Income Tax Paid, by Individual Jurisdiction [Line Items]  
Income Tax Paid, State and Local, after Refund Received 322
CANADA  
Income Tax Paid, by Individual Jurisdiction [Line Items]  
Income Tax Paid, Foreign, after Refund Received 430
MEXICO  
Income Tax Paid, by Individual Jurisdiction [Line Items]  
Income Tax Paid, Foreign, after Refund Received 185
Foreign, Other  
Income Tax Paid, by Individual Jurisdiction [Line Items]  
Income Tax Paid, Foreign, after Refund Received $ 316
XML 79 R67.htm IDEA: XBRL DOCUMENT v3.26.3
Income Taxes (Components of Deferred Tax Assets And Liabilities) (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Deferred Tax Assets:    
Equity compensation $ 122 $ 100
Deferred Income/membership fees 398 369
Foreign tax credit carry forward 470 390
Operating lease liabilities 710 699
Accrued liabilities and reserves 1,041 917
Total deferred tax assets 2,741 2,475
Valuation allowance (641) (554)
Total net deferred tax assets 2,100 1,921
Deferred Tax Liabilities:    
Property and equipment (1,372) (944)
Merchandise inventories (344) (305)
Operating lease right-of-use assets (675) (670)
Foreign branch deferreds (107) (103)
Other (33) (31)
Total deferred tax liabilities 2,531 2,053
Net deferred tax liabilities $ 431 $ 132
XML 80 R68.htm IDEA: XBRL DOCUMENT v3.26.3
Income Taxes (Deferred Tax Assets and Liabilities Narrative) (Details) - USD ($)
$ in Millions
Aug. 30, 2026
Aug. 31, 2025
Tax Credit Carryforward [Line Items]    
Valuation Allowances $ 641 $ 554
Undistributed Earnings of Foreign Subsidiaries 3,230  
Balance Sheet Location [Axis]: us-gaap:OtherAssetsNoncurrent    
Tax Credit Carryforward [Line Items]    
Deferred Tax Assets, Net 635 592
Balance Sheet Location [Axis]: us-gaap:OtherLiabilitiesNoncurrent    
Tax Credit Carryforward [Line Items]    
Deferred Tax Liabilities $ 1,066 $ 724
XML 81 R69.htm IDEA: XBRL DOCUMENT v3.26.3
Income Taxes (Gross Unrecognized Tax Benefits) (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Reconciliation of Unrecognized Tax Benefits, Excluding Amounts Pertaining to Examined Tax Returns [Roll Forward]    
Gross unrecognized tax benefit at beginning of year $ 65 $ 81
Gross increases—current year tax positions 18 9
Gross increases—tax positions in prior years 25 14
Gross decreases—tax positions in prior years (6) (38)
Gross decreases—settlements 8 1
Gross unrecognized tax benefit at end of year 94 65
Unrecognized tax benefits that would impact effective tax rate $ 94 $ 65
XML 82 R70.htm IDEA: XBRL DOCUMENT v3.26.3
Net Income per Common and Common Equivalent Share - Schedule of Earnings per Share Effect on Net Income and Weighted Averegae Number of Dilutive Potential Common Stock (Details) - USD ($)
shares in Thousands, $ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Earnings Per Share [Abstract]      
NET INCOME $ 9,226 $ 8,099 $ 7,367
Weighted average basic shares 443,953 443,985 443,914
RSUs and other 474 818 845
Weighted average diluted shares 444,427 444,803 444,759
XML 83 R71.htm IDEA: XBRL DOCUMENT v3.26.3
Segment Reporting - Narrative (Details)
12 Months Ended
Aug. 30, 2026
Reportable_segment
Segment Reporting, Descriptive Information [Abstract]  
Number of Reportable Segments 3
XML 84 R72.htm IDEA: XBRL DOCUMENT v3.26.3
Segment Reporting Information by Segment (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Segment Reporting [Line Items]      
Total Revenue $ 303,154 $ 275,235 $ 254,453
Merchandise costs 264,279 239,886 222,358
Selling, general and administrative 27,190 24,966 22,810
Operating income 11,685 10,383 9,285
Other Income [1] 566 435 455
Income before Income Taxes 12,251 10,818 9,740
Operating Segments | United States      
Segment Reporting [Line Items]      
Total Revenue 219,823 200,046 184,143
Merchandise costs 191,440 174,021 160,573
Selling, general and administrative 20,736 19,147 17,353
Operating income 7,647 6,878 6,217
Operating Segments | Canada      
Segment Reporting [Line Items]      
Total Revenue 40,561 36,923 34,874
Merchandise costs 35,287 32,204 30,543
Selling, general and administrative 3,167 2,870 2,683
Operating income 2,107 1,849 1,648
Operating Segments | Other International      
Segment Reporting [Line Items]      
Total Revenue 42,770 38,266 35,436
Merchandise costs 37,552 33,661 31,242
Selling, general and administrative 3,287 2,949 2,774
Operating income $ 1,931 $ 1,656 $ 1,420
[1] Other income consists of interest expense and interest income and other, net.
XML 85 R73.htm IDEA: XBRL DOCUMENT v3.26.3
Segment Reporting Information by Segment (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Segment Reporting [Line Items]      
Depreciation and amortization $ 2,674 $ 2,426 $ 2,237
Additions to property and equipment 6,435 5,498 4,710
Property and equipment, net 35,633 31,909 29,032
Total assets 89,045 77,099 69,831
Operating Segments | United States      
Segment Reporting [Line Items]      
Depreciation and amortization 2,082 1,895 1,730
Additions to property and equipment 5,122 4,215 3,725
Property and equipment, net 25,714 22,790 20,638
Total assets 65,090 54,862 48,816
Operating Segments | Canada      
Segment Reporting [Line Items]      
Depreciation and amortization 219 196 192
Additions to property and equipment 673 580 351
Property and equipment, net 3,395 2,930 2,602
Total assets 8,026 7,304 6,915
Operating Segments | Other International      
Segment Reporting [Line Items]      
Depreciation and amortization 373 335 315
Additions to property and equipment 640 703 634
Property and equipment, net 6,524 6,189 5,792
Total assets $ 15,929 $ 14,933 $ 14,100
XML 86 R74.htm IDEA: XBRL DOCUMENT v3.26.3
Segment Reporting Information by Item Category (Details) - USD ($)
$ in Millions
12 Months Ended
Aug. 30, 2026
Aug. 31, 2025
Sep. 01, 2024
Revenue from External Customer      
Total Revenue $ 303,154 $ 275,235 $ 254,453
Food and Sundries [Member]      
Revenue from External Customer      
Total Revenue 116,788 109,564 101,463
Non-Foods [Member]      
Revenue from External Customer      
Total Revenue 77,375 71,190 63,973
Fresh Foods [Member]      
Revenue from External Customer      
Total Revenue 41,715 37,988 34,220
Warehouse ancillary and other businesses      
Revenue from External Customer      
Total Revenue 61,369 51,170 49,969
Net Sales      
Revenue from External Customer      
Total Revenue $ 297,247 $ 269,912 $ 249,625
XML 87 report.css IDEA: XBRL DOCUMENT /* Updated 2009-11-04 */ /* v2.2.0.24 */ /* DefRef Styles */ .report table.authRefData{ background-color: #def; border: 2px solid #2F4497; font-size: 1em; position: absolute; } .report table.authRefData a { display: block; font-weight: bold; } .report table.authRefData p { margin-top: 0px; } .report table.authRefData .hide { background-color: #2F4497; padding: 1px 3px 0px 0px; text-align: right; } .report table.authRefData .hide a:hover { background-color: #2F4497; } .report table.authRefData .body { height: 150px; overflow: auto; width: 400px; } .report table.authRefData table{ font-size: 1em; } /* Report Styles */ .pl a, .pl a:visited { color: black; text-decoration: none; } /* table */ .report { background-color: white; border: 2px solid #acf; clear: both; color: black; font: normal 8pt Helvetica, Arial, san-serif; margin-bottom: 2em; } .report hr { border: 1px solid #acf; } /* Top labels */ .report th { background-color: #acf; color: black; font-weight: bold; text-align: center; } .report th.void { background-color: transparent; color: #000000; font: bold 10pt Helvetica, Arial, san-serif; text-align: left; } .report .pl { text-align: left; vertical-align: top; white-space: normal; width: 200px; white-space: normal; /* word-wrap: break-word; */ } .report td.pl a.a { cursor: pointer; display: block; width: 200px; overflow: hidden; } .report td.pl div.a { width: 200px; } .report td.pl a:hover { background-color: #ffc; } /* Header rows... */ .report tr.rh { background-color: #acf; color: black; font-weight: bold; } /* Calendars... */ .report .rc { background-color: #f0f0f0; } /* Even rows... */ .report .re, .report .reu { background-color: #def; } .report .reu td { border-bottom: 1px solid black; } /* Odd rows... */ .report .ro, .report .rou { background-color: white; } .report .rou td { border-bottom: 1px solid black; } .report .rou table td, .report .reu table td { border-bottom: 0px solid black; } /* styles for footnote marker */ .report .fn { white-space: nowrap; } /* styles for numeric types */ .report .num, .report .nump { text-align: right; white-space: nowrap; } .report .nump { padding-left: 2em; } .report .nump { padding: 0px 0.4em 0px 2em; } /* styles for text types */ .report .text { text-align: left; white-space: normal; } .report .text .big { margin-bottom: 1em; width: 17em; } .report .text .more { display: none; } .report .text .note { font-style: italic; font-weight: bold; } .report .text .small { width: 10em; } .report sup { font-style: italic; } .report .outerFootnotes { font-size: 1em; } XML 88 Show.js IDEA: XBRL DOCUMENT // Edgar(tm) Renderer was created by staff of the U.S. Securities and Exchange Commission. Data and content created by government employees within the scope of their employment are not subject to domestic copyright protection. 17 U.S.C. 105. var Show={};Show.LastAR=null,Show.showAR=function(a,r,w){if(Show.LastAR)Show.hideAR();var e=a;while(e&&e.nodeName!='TABLE')e=e.nextSibling;if(!e||e.nodeName!='TABLE'){var ref=((window)?w.document:document).getElementById(r);if(ref){e=ref.cloneNode(!0); e.removeAttribute('id');a.parentNode.appendChild(e)}} if(e)e.style.display='block';Show.LastAR=e};Show.hideAR=function(){Show.LastAR.style.display='none'};Show.toggleNext=function(a){var e=a;while(e.nodeName!='DIV')e=e.nextSibling;if(!e.style){}else if(!e.style.display){}else{var d,p_;if(e.style.display=='none'){d='block';p='-'}else{d='none';p='+'} e.style.display=d;if(a.textContent){a.textContent=p+a.textContent.substring(1)}else{a.innerText=p+a.innerText.substring(1)}}} XML 90 FilingSummary.xml IDEA: XBRL DOCUMENT 3.26.3 html 156 390 1 true 60 0 false 7 false false R1.htm 0000001 - Document - Cover Sheet http://www.costco.com/role/Cover Cover Cover 1 false false R2.htm 0000002 - Document - Audit Information Sheet http://www.costco.com/role/AuditInformation Audit Information Cover 2 false false R3.htm 9952151 - Statement - Consolidated Statements Of Income Sheet http://www.costco.com/role/ConsolidatedStatementsOfIncome Consolidated Statements Of Income Statements 3 false false R4.htm 9952152 - Statement - Consolidated Statements Of Comprehensive Income Sheet http://www.costco.com/role/ConsolidatedStatementsOfComprehensiveIncome Consolidated Statements Of Comprehensive Income Statements 4 false false R5.htm 9952153 - Statement - Consolidated Balance Sheets Sheet http://www.costco.com/role/ConsolidatedBalanceSheets Consolidated Balance Sheets Statements 5 false false R6.htm 9952154 - Statement - Consolidated Balance Sheets (Parenthetical) Sheet http://www.costco.com/role/ConsolidatedBalanceSheetsParenthetical Consolidated Balance Sheets (Parenthetical) Statements 6 false false R7.htm 9952155 - Statement - Consolidated Statements of Equity Sheet http://www.costco.com/role/ConsolidatedStatementsofEquity Consolidated Statements of Equity Statements 7 false false R8.htm 9952156 - Statement - Consolidated Statements Of Cash Flows Sheet http://www.costco.com/role/ConsolidatedStatementsOfCashFlows Consolidated Statements Of Cash Flows Statements 8 false false R9.htm 9952157 - Disclosure - Summary of Significant Accounting Policies Sheet http://www.costco.com/role/SummaryofSignificantAccountingPolicies Summary of Significant Accounting Policies Notes 9 false false R10.htm 9952158 - Disclosure - Investments Sheet http://www.costco.com/role/Investments Investments Notes 10 false false R11.htm 9952159 - Disclosure - Fair Value Measurement Sheet http://www.costco.com/role/FairValueMeasurement Fair Value Measurement Notes 11 false false R12.htm 9952160 - Disclosure - Debt Sheet http://www.costco.com/role/Debt Debt Notes 12 false false R13.htm 9952161 - Disclosure - Leases Sheet http://www.costco.com/role/Leases Leases Notes 13 false false R14.htm 9952162 - Disclosure - Stockholders' Equity Sheet http://www.costco.com/role/StockholdersEquity Stockholders' Equity Notes 14 false false R15.htm 9952163 - Disclosure - Stock-Based Compensation Plans Sheet http://www.costco.com/role/StockBasedCompensationPlans Stock-Based Compensation Plans Notes 15 false false R16.htm 9952164 - Disclosure - Income Taxes Sheet http://www.costco.com/role/IncomeTaxes Income Taxes Notes 16 false false R17.htm 9952165 - Disclosure - Net Income per Common and Common Equivalent Share Sheet http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShare Net Income per Common and Common Equivalent Share Notes 17 false false R18.htm 9952166 - Disclosure - Commitment and Contingencies Sheet http://www.costco.com/role/CommitmentandContingencies Commitment and Contingencies Notes 18 false false R19.htm 9952167 - Disclosure - Segment Reporting Sheet http://www.costco.com/role/SegmentReporting Segment Reporting Notes 19 false false R20.htm 995445 - Disclosure - Insider Trading Arrangements Sheet http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements Insider Trading Arrangements Notes 20 false false R21.htm 995447 - Disclosure - Insider Trading Policies and Procedures Sheet http://xbrl.sec.gov/ecd/role/InsiderTradingPoliciesProc Insider Trading Policies and Procedures Notes 21 false false R22.htm 995550 - Disclosure - Cybersecurity Risk Management and Strategy Disclosure Sheet http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure Cybersecurity Risk Management and Strategy Disclosure Notes 22 false false R23.htm 9955511 - Disclosure - Summary of Significant Accounting Policies (Policies) Sheet http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies Summary of Significant Accounting Policies (Policies) Policies http://www.costco.com/role/SummaryofSignificantAccountingPolicies 23 false false R24.htm 9955512 - Disclosure - Summary of Significant Accounting Policies (Tables) Sheet http://www.costco.com/role/SummaryofSignificantAccountingPoliciesTables Summary of Significant Accounting Policies (Tables) Tables http://www.costco.com/role/SummaryofSignificantAccountingPolicies 24 false false R25.htm 9955513 - Disclosure - Investments (Tables) Sheet http://www.costco.com/role/InvestmentsTables Investments (Tables) Tables http://www.costco.com/role/Investments 25 false false R26.htm 9955514 - Disclosure - Fair Value Measurement (Tables) Sheet http://www.costco.com/role/FairValueMeasurementTables Fair Value Measurement (Tables) Tables http://www.costco.com/role/FairValueMeasurement 26 false false R27.htm 9955515 - Disclosure - Debt (Tables) Sheet http://www.costco.com/role/DebtTables Debt (Tables) Tables http://www.costco.com/role/Debt 27 false false R28.htm 9955516 - Disclosure - Leases (Tables) Sheet http://www.costco.com/role/LeasesTables Leases (Tables) Tables http://www.costco.com/role/Leases 28 false false R29.htm 9955517 - Disclosure - Stockholders' Equity (Tables) Sheet http://www.costco.com/role/StockholdersEquityTables Stockholders' Equity (Tables) Tables http://www.costco.com/role/StockholdersEquity 29 false false R30.htm 9955518 - Disclosure - Stock-Based Compensation Plans (Tables) Sheet http://www.costco.com/role/StockBasedCompensationPlansTables Stock-Based Compensation Plans (Tables) Tables http://www.costco.com/role/StockBasedCompensationPlans 30 false false R31.htm 9955519 - Disclosure - Income Taxes (Tables) Sheet http://www.costco.com/role/IncomeTaxesTables Income Taxes (Tables) Tables http://www.costco.com/role/IncomeTaxes 31 false false R32.htm 9955520 - Disclosure - Net Income per Common and Common Equivalent Share Net Income per Common and Common Equivalent Share (Tables) Sheet http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareNetIncomeperCommonandCommonEquivalentShareTables Net Income per Common and Common Equivalent Share Net Income per Common and Common Equivalent Share (Tables) Tables 32 false false R33.htm 9955522 - Disclosure - Segment Reporting (Tables) Sheet http://www.costco.com/role/SegmentReportingTables Segment Reporting (Tables) Tables http://www.costco.com/role/SegmentReporting 33 false false R34.htm 9955523 - Disclosure - Accounting Policies - Additional Information (Details) Sheet http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails Accounting Policies - Additional Information (Details) Details 34 false false R35.htm 9955525 - Disclosure - Accounting Policies - Cash and Cash Equivalents (Details) Sheet http://www.costco.com/role/AccountingPoliciesCashandCashEquivalentsDetails Accounting Policies - Cash and Cash Equivalents (Details) Details 35 false false R36.htm 9955526 - Disclosure - Accounting Policies - Merchandise Inventories (Details) Sheet http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails Accounting Policies - Merchandise Inventories (Details) Details 36 false false R37.htm 9955527 - Disclosure - Accounting Policies - Property and Equipment, Net (Details) Sheet http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails Accounting Policies - Property and Equipment, Net (Details) Details 37 false false R38.htm 9955529 - Disclosure - Accounting Policies - Goodwill and Acquired Intangible Assets (Details) Sheet http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails Accounting Policies - Goodwill and Acquired Intangible Assets (Details) Details 38 false false R39.htm 9955530 - Disclosure - Accounting Policies - Insurance/Self-Insurance Liabilities (Details) Sheet http://www.costco.com/role/AccountingPoliciesInsuranceSelfInsuranceLiabilitiesDetails Accounting Policies - Insurance/Self-Insurance Liabilities (Details) Details 39 false false R40.htm 9955531 - Disclosure - Accounting Policies - Derivatives (Details) Sheet http://www.costco.com/role/AccountingPoliciesDerivativesDetails Accounting Policies - Derivatives (Details) Details 40 false false R41.htm 9955533 - Disclosure - Accounting Policies - Revenue Recognition (Details) Sheet http://www.costco.com/role/AccountingPoliciesRevenueRecognitionDetails Accounting Policies - Revenue Recognition (Details) Details 41 false false R42.htm 9955534 - Disclosure - Accounting Policies - Retirement Plans (Details) Sheet http://www.costco.com/role/AccountingPoliciesRetirementPlansDetails Accounting Policies - Retirement Plans (Details) Details 42 false false R43.htm 9955535 - Disclosure - Accounting Policies - Stock-Based Compensation (Details) Sheet http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails Accounting Policies - Stock-Based Compensation (Details) Details 43 false false R44.htm 9955536 - Disclosure - Investments - Available for Sale and Held to Maturity Investments (Details) Sheet http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails Investments - Available for Sale and Held to Maturity Investments (Details) Details 44 false false R45.htm 9955537 - Disclosure - Investments - Maturities of Available for Sale and Held to Maturity Securities (Details) Sheet http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails Investments - Maturities of Available for Sale and Held to Maturity Securities (Details) Details 45 false false R46.htm 9955538 - Disclosure - Fair Value Measurement - Fair Value of Financial Assets and Financial Liabilities Measured on Recurring Basis (Details) Sheet http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails Fair Value Measurement - Fair Value of Financial Assets and Financial Liabilities Measured on Recurring Basis (Details) Details 46 false false R47.htm 9955539 - Disclosure - Debt, Schedule Of Short-Term Debt (Details) Sheet http://www.costco.com/role/DebtScheduleOfShortTermDebtDetails Debt, Schedule Of Short-Term Debt (Details) Details 47 false false R48.htm 9955540 - Disclosure - Debt, Schedule of Long-Term Debt (Details) Sheet http://www.costco.com/role/DebtScheduleofLongTermDebtDetails Debt, Schedule of Long-Term Debt (Details) Details 48 false false R49.htm 9955541 - Disclosure - Debt, Carrying Value of Long-Term Debt (Details) Sheet http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails Debt, Carrying Value of Long-Term Debt (Details) Details 49 false false R50.htm 9955542 - Disclosure - Debt, Schedule Of Long-Term Debt Maturities (Details) Sheet http://www.costco.com/role/DebtScheduleOfLongTermDebtMaturitiesDetails Debt, Schedule Of Long-Term Debt Maturities (Details) Details 50 false false R51.htm 9955543 - Disclosure - Leases, Supplemental Balance Sheet Information (Details) Sheet http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails Leases, Supplemental Balance Sheet Information (Details) Details 51 false false R52.htm 9955544 - Disclosure - Leases, Components of Lease Expense (Details) Sheet http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails Leases, Components of Lease Expense (Details) Details 52 false false R53.htm 9955545 - Disclosure - Leases, Supplemental Cash Flow Information (Details) Sheet http://www.costco.com/role/LeasesSupplementalCashFlowInformationDetails Leases, Supplemental Cash Flow Information (Details) Details 53 false false R54.htm 9955546 - Disclosure - Leases, Future Minimum Payments (Details) Sheet http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails Leases, Future Minimum Payments (Details) Details 54 false false R55.htm 9955547 - Disclosure - Stockholders' Equity - Additional Information (Details) Sheet http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails Stockholders' Equity - Additional Information (Details) Details 55 false false R56.htm 9955548 - Disclosure - Equity - Additional Information - Stock Repurchase Programs (Details) Sheet http://www.costco.com/role/EquityAdditionalInformationStockRepurchaseProgramsDetails Equity - Additional Information - Stock Repurchase Programs (Details) Details 56 false false R57.htm 9955549 - Disclosure - Stockholders' Equity (Stock Repurchased During Period) (Details) Sheet http://www.costco.com/role/StockholdersEquityStockRepurchasedDuringPeriodDetails Stockholders' Equity (Stock Repurchased During Period) (Details) Details http://www.costco.com/role/StockholdersEquityTables 57 false false R58.htm 9955550 - Disclosure - Stock-Based Compensation Plans - Additional Information (Details) Sheet http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails Stock-Based Compensation Plans - Additional Information (Details) Details 58 false false R59.htm 9955551 - Disclosure - Stock-Based Compensation Plans - Summary of RSU Transactions (Details) Sheet http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails Stock-Based Compensation Plans - Summary of RSU Transactions (Details) Details 59 false false R60.htm 9955552 - Disclosure - Stock-Based Compensation Plans - Summary of Stock-Based Compensation Expense (Details) Sheet http://www.costco.com/role/StockBasedCompensationPlansSummaryofStockBasedCompensationExpenseDetails Stock-Based Compensation Plans - Summary of Stock-Based Compensation Expense (Details) Details 60 false false R61.htm 9955553 - Disclosure - Income Taxes (Income Before Income Taxes) (Details) Sheet http://www.costco.com/role/IncomeTaxesIncomeBeforeIncomeTaxesDetails Income Taxes (Income Before Income Taxes) (Details) Details http://www.costco.com/role/IncomeTaxesTables 61 false false R62.htm 9955554 - Disclosure - Income Taxes (Schedule of Foreign And Domestic Income Taxes) (Details) Sheet http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails Income Taxes (Schedule of Foreign And Domestic Income Taxes) (Details) Details http://www.costco.com/role/IncomeTaxesTables 62 false false R63.htm 9955555 - Disclosure - Income Taxes (Reconciliation Between Statutory And Effective Rates) (Details) Sheet http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails Income Taxes (Reconciliation Between Statutory And Effective Rates) (Details) Details http://www.costco.com/role/IncomeTaxesTables 63 false false R64.htm 9955556 - Disclosure - Income Taxes (Reconciliation Between Statutory and Effective Rates FY25 and FY24) (Details) Sheet http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details Income Taxes (Reconciliation Between Statutory and Effective Rates FY25 and FY24) (Details) Details http://www.costco.com/role/IncomeTaxesTables 64 false false R65.htm 9955557 - Disclosure - Income Taxes (Reconciliation Between Statutory and Effective Rates Narrative) (Details) Sheet http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails Income Taxes (Reconciliation Between Statutory and Effective Rates Narrative) (Details) Details http://www.costco.com/role/IncomeTaxesTables 65 false false R66.htm 9955558 - Disclosure - Income Taxes Cash Paid for Income Taxes (Details) Sheet http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails Income Taxes Cash Paid for Income Taxes (Details) Details 66 false false R67.htm 9955559 - Disclosure - Income Taxes (Components of Deferred Tax Assets And Liabilities) (Details) Sheet http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails Income Taxes (Components of Deferred Tax Assets And Liabilities) (Details) Details http://www.costco.com/role/IncomeTaxesTables 67 false false R68.htm 9955560 - Disclosure - Income Taxes (Deferred Tax Assets and Liabilities Narrative) (Details) Sheet http://www.costco.com/role/IncomeTaxesDeferredTaxAssetsandLiabilitiesNarrativeDetails Income Taxes (Deferred Tax Assets and Liabilities Narrative) (Details) Details http://www.costco.com/role/IncomeTaxesTables 68 false false R69.htm 9955561 - Disclosure - Income Taxes (Gross Unrecognized Tax Benefits) (Details) Sheet http://www.costco.com/role/IncomeTaxesGrossUnrecognizedTaxBenefitsDetails Income Taxes (Gross Unrecognized Tax Benefits) (Details) Details http://www.costco.com/role/IncomeTaxesTables 69 false false R70.htm 9955562 - Disclosure - Net Income per Common and Common Equivalent Share - Schedule of Earnings per Share Effect on Net Income and Weighted Averegae Number of Dilutive Potential Common Stock (Details) Sheet http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareScheduleofEarningsperShareEffectonNetIncomeandWeightedAveregaeNumberofDilutivePotentialCommonStockDetails Net Income per Common and Common Equivalent Share - Schedule of Earnings per Share Effect on Net Income and Weighted Averegae Number of Dilutive Potential Common Stock (Details) Details 70 false false R71.htm 9955564 - Disclosure - Segment Reporting - Narrative (Details) Sheet http://www.costco.com/role/SegmentReportingNarrativeDetails Segment Reporting - Narrative (Details) Details 71 false false R72.htm 9955565 - Disclosure - Segment Reporting Information by Segment (Details) Sheet http://www.costco.com/role/SegmentReportingInformationbySegmentDetails Segment Reporting Information by Segment (Details) Details 72 false false R73.htm 9955566 - Disclosure - Segment Reporting Information by Segment (Details) Sheet http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1 Segment Reporting Information by Segment (Details) Details 73 false false R74.htm 9955567 - Disclosure - Segment Reporting Information by Item Category (Details) Sheet http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails Segment Reporting Information by Item Category (Details) Details 74 false false All Reports Book All Reports cost-20260830.htm cost-20260830.xsd cost-20260830_cal.xml cost-20260830_def.xml cost-20260830_lab.xml cost-20260830_pre.xml cost-20260830_g1.jpg http://fasb.org/srt/2026 http://fasb.org/us-gaap/2026 http://xbrl.sec.gov/cyd/2026 http://xbrl.sec.gov/dei/2026 http://xbrl.sec.gov/ecd/2026 true true JSON 93 MetaLinks.json IDEA: XBRL DOCUMENT { "version": "2.2", "instance": { "cost-20260830.htm": { "nsprefix": "cost", "nsuri": "http://www.costco.com/20260830", "dts": { "inline": { "local": [ "cost-20260830.htm" ] }, "schema": { "local": [ "cost-20260830.xsd" ], "remote": [ "http://www.xbrl.org/2003/xbrl-instance-2003-12-31.xsd", "http://www.xbrl.org/2003/xbrl-linkbase-2003-12-31.xsd", "http://www.xbrl.org/2003/xl-2003-12-31.xsd", "http://www.xbrl.org/2003/xlink-2003-12-31.xsd", "http://www.xbrl.org/2005/xbrldt-2005.xsd", "http://www.xbrl.org/2006/ref-2006-02-27.xsd", "http://www.xbrl.org/lrr/role/negated-2009-12-16.xsd", "http://www.xbrl.org/lrr/role/net-2009-12-16.xsd", "http://www.xbrl.org/lrr/role/reference-2009-12-16.xsd", "https://www.xbrl.org/2020/extensible-enumerations-2.0.xsd", "https://www.xbrl.org/2023/calculation-1.1.xsd", "https://www.xbrl.org/dtr/type/2020-01-21/types.xsd", "https://www.xbrl.org/dtr/type/2024-01-31/types.xsd", "https://xbrl.fasb.org/srt/2026/elts/srt-2026.xsd", "https://xbrl.fasb.org/srt/2026/elts/srt-roles-2026.xsd", "https://xbrl.fasb.org/srt/2026/elts/srt-types-2026.xsd", "https://xbrl.fasb.org/us-gaap/2026/elts/us-gaap-2026.xsd", "https://xbrl.fasb.org/us-gaap/2026/elts/us-roles-2026.xsd", "https://xbrl.fasb.org/us-gaap/2026/elts/us-types-2026.xsd", "https://xbrl.sec.gov/country/2026/country-2026.xsd", "https://xbrl.sec.gov/cyd/2026/cyd-2026.xsd", "https://xbrl.sec.gov/cyd/2026/cyd-af-2026.xsd", "https://xbrl.sec.gov/cyd/2026/cyd-af-sub-2026.xsd", "https://xbrl.sec.gov/dei/2026/dei-2026.xsd", "https://xbrl.sec.gov/ecd/2026/ecd-2026.xsd", "https://xbrl.sec.gov/stpr/2026/stpr-2026.xsd" ] }, "calculationLink": { "local": [ "cost-20260830_cal.xml" ] }, "definitionLink": { "local": [ "cost-20260830_def.xml" ] }, "labelLink": { "local": [ "cost-20260830_lab.xml" ] }, "presentationLink": { "local": [ "cost-20260830_pre.xml" ] } }, "keyStandard": 378, "keyCustom": 12, "axisStandard": 18, "axisCustom": 0, "memberStandard": 36, "memberCustom": 19, "hidden": { "total": 50, "http://fasb.org/us-gaap/2026": 43, "http://xbrl.sec.gov/dei/2026": 7 }, "contextCount": 156, "entityCount": 1, "segmentCount": 60, "elementCount": 687, "unitCount": 7, "baseTaxonomies": { "http://fasb.org/us-gaap/2026": 903, "http://xbrl.sec.gov/dei/2026": 38, "http://xbrl.sec.gov/cyd/2026": 15, "http://xbrl.sec.gov/ecd/2026": 5, "http://fasb.org/srt/2026": 1 }, "report": { "R1": { "role": "http://www.costco.com/role/Cover", "longName": "0000001 - Document - Cover", "shortName": "Cover", "isDefault": "true", "groupType": "document", "subGroupType": "", "menuCat": "Cover", "order": "1", "firstAnchor": { "contextRef": "c-1", "name": "dei:DocumentType", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "dei:DocumentType", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R2": { "role": "http://www.costco.com/role/AuditInformation", "longName": "0000002 - Document - Audit Information", "shortName": "Audit Information", "isDefault": "false", "groupType": "document", "subGroupType": "", "menuCat": "Cover", "order": "2", "firstAnchor": { "contextRef": "c-1", "name": "dei:AuditorName", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "dei:AuditorName", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R3": { "role": "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "longName": "9952151 - Statement - Consolidated Statements Of Income", "shortName": "Consolidated Statements Of Income", "isDefault": "false", "groupType": "statement", "subGroupType": "", "menuCat": "Statements", "order": "3", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:RevenueFromContractWithCustomerExcludingAssessedTax", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfSegmentReportingInformationBySegmentTextBlock", "us-gaap:SegmentReportingDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:InterestExpense", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R4": { "role": "http://www.costco.com/role/ConsolidatedStatementsOfComprehensiveIncome", "longName": "9952152 - Statement - Consolidated Statements Of Comprehensive Income", "shortName": "Consolidated Statements Of Comprehensive Income", "isDefault": "false", "groupType": "statement", "subGroupType": "", "menuCat": "Statements", "order": "4", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:NetIncomeLoss", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:ComprehensiveIncomeNetOfTax", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R5": { "role": "http://www.costco.com/role/ConsolidatedBalanceSheets", "longName": "9952153 - Statement - Consolidated Balance Sheets", "shortName": "Consolidated Balance Sheets", "isDefault": "false", "groupType": "statement", "subGroupType": "", "menuCat": "Statements", "order": "5", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:CashAndCashEquivalentsAtCarryingValue", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:CashAndCashEquivalentsAtCarryingValue", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R6": { "role": "http://www.costco.com/role/ConsolidatedBalanceSheetsParenthetical", "longName": "9952154 - Statement - Consolidated Balance Sheets (Parenthetical)", "shortName": "Consolidated Balance Sheets (Parenthetical)", "isDefault": "false", "groupType": "statement", "subGroupType": "parenthetical", "menuCat": "Statements", "order": "6", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:PreferredStockParOrStatedValuePerShare", "unitRef": "usdPerShare", "xsiNil": "false", "lang": "en-US", "decimals": "INF", "ancestors": [ "span", "div", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:PreferredStockParOrStatedValuePerShare", "unitRef": "usdPerShare", "xsiNil": "false", "lang": "en-US", "decimals": "INF", "ancestors": [ "span", "div", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R7": { "role": "http://www.costco.com/role/ConsolidatedStatementsofEquity", "longName": "9952155 - Statement - Consolidated Statements of Equity", "shortName": "Consolidated Statements of Equity", "isDefault": "false", "groupType": "statement", "subGroupType": "", "menuCat": "Statements", "order": "7", "firstAnchor": { "contextRef": "c-14", "name": "us-gaap:CommonStockSharesOutstanding", "unitRef": "shares", "xsiNil": "false", "lang": "en-US", "decimals": "-3", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-14", "name": "us-gaap:CommonStockSharesOutstanding", "unitRef": "shares", "xsiNil": "false", "lang": "en-US", "decimals": "-3", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R8": { "role": "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows", "longName": "9952156 - Statement - Consolidated Statements Of Cash Flows", "shortName": "Consolidated Statements Of Cash Flows", "isDefault": "false", "groupType": "statement", "subGroupType": "", "menuCat": "Statements", "order": "8", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:NetIncomeLoss", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "cost:OperatingandFinancingLeaseRightofUseAssetAmortization", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R9": { "role": "http://www.costco.com/role/SummaryofSignificantAccountingPolicies", "longName": "9952157 - Disclosure - Summary of Significant Accounting Policies", "shortName": "Summary of Significant Accounting Policies", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "9", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:SignificantAccountingPoliciesTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:SignificantAccountingPoliciesTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R10": { "role": "http://www.costco.com/role/Investments", "longName": "9952158 - Disclosure - Investments", "shortName": "Investments", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "10", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:InvestmentsInDebtAndMarketableEquitySecuritiesAndCertainTradingAssetsDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:InvestmentsInDebtAndMarketableEquitySecuritiesAndCertainTradingAssetsDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R11": { "role": "http://www.costco.com/role/FairValueMeasurement", "longName": "9952159 - Disclosure - Fair Value Measurement", "shortName": "Fair Value Measurement", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "11", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:FairValueDisclosuresTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:FairValueDisclosuresTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R12": { "role": "http://www.costco.com/role/Debt", "longName": "9952160 - Disclosure - Debt", "shortName": "Debt", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "12", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:DebtDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:DebtDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R13": { "role": "http://www.costco.com/role/Leases", "longName": "9952161 - Disclosure - Leases", "shortName": "Leases", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "13", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:LesseeOperatingLeasesTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:LesseeOperatingLeasesTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R14": { "role": "http://www.costco.com/role/StockholdersEquity", "longName": "9952162 - Disclosure - Stockholders' Equity", "shortName": "Stockholders' Equity", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "14", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:StockholdersEquityNoteDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:StockholdersEquityNoteDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R15": { "role": "http://www.costco.com/role/StockBasedCompensationPlans", "longName": "9952163 - Disclosure - Stock-Based Compensation Plans", "shortName": "Stock-Based Compensation Plans", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "15", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:DisclosureOfCompensationRelatedCostsShareBasedPaymentsTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:DisclosureOfCompensationRelatedCostsShareBasedPaymentsTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R16": { "role": "http://www.costco.com/role/IncomeTaxes", "longName": "9952164 - Disclosure - Income Taxes", "shortName": "Income Taxes", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "16", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:IncomeTaxDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:IncomeTaxDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R17": { "role": "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShare", "longName": "9952165 - Disclosure - Net Income per Common and Common Equivalent Share", "shortName": "Net Income per Common and Common Equivalent Share", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "17", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:EarningsPerShareTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:EarningsPerShareTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R18": { "role": "http://www.costco.com/role/CommitmentandContingencies", "longName": "9952166 - Disclosure - Commitment and Contingencies", "shortName": "Commitment and Contingencies", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "18", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:CommitmentsAndContingenciesDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:CommitmentsAndContingenciesDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R19": { "role": "http://www.costco.com/role/SegmentReporting", "longName": "9952167 - Disclosure - Segment Reporting", "shortName": "Segment Reporting", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "19", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:SegmentReportingDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:SegmentReportingDisclosureTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R20": { "role": "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements", "longName": "995445 - Disclosure - Insider Trading Arrangements", "shortName": "Insider Trading Arrangements", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "20", "firstAnchor": { "contextRef": "c-109", "name": "ecd:Rule10b51ArrAdoptedFlag", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "ecd:NonRule10b51ArrAdoptedFlag", "span", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-109", "name": "ecd:Rule10b51ArrAdoptedFlag", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "ecd:NonRule10b51ArrAdoptedFlag", "span", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R21": { "role": "http://xbrl.sec.gov/ecd/role/InsiderTradingPoliciesProc", "longName": "995447 - Disclosure - Insider Trading Policies and Procedures", "shortName": "Insider Trading Policies and Procedures", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "21", "firstAnchor": { "contextRef": "c-1", "name": "ecd:InsiderTrdPoliciesProcAdoptedFlag", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "ecd:InsiderTrdPoliciesProcAdoptedFlag", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R22": { "role": "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure", "longName": "995550 - Disclosure - Cybersecurity Risk Management and Strategy Disclosure", "shortName": "Cybersecurity Risk Management and Strategy Disclosure", "isDefault": "false", "groupType": "disclosure", "subGroupType": "", "menuCat": "Notes", "order": "22", "firstAnchor": { "contextRef": "c-1", "name": "cyd:CybersecurityRiskManagementProcessesForAssessingIdentifyingAndManagingThreatsTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "cyd:CybersecurityRiskManagementProcessesForAssessingIdentifyingAndManagingThreatsTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R23": { "role": "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies", "longName": "9955511 - Disclosure - Summary of Significant Accounting Policies (Policies)", "shortName": "Summary of Significant Accounting Policies (Policies)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "policies", "menuCat": "Policies", "order": "23", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:BasisOfAccountingPolicyPolicyTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:SignificantAccountingPoliciesTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:BasisOfAccountingPolicyPolicyTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:SignificantAccountingPoliciesTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R24": { "role": "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesTables", "longName": "9955512 - Disclosure - Summary of Significant Accounting Policies (Tables)", "shortName": "Summary of Significant Accounting Policies (Tables)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "tables", "menuCat": "Tables", "order": "24", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfInventoryCurrentTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:InventoryPolicyTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfInventoryCurrentTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:InventoryPolicyTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R25": { "role": "http://www.costco.com/role/InvestmentsTables", "longName": "9955513 - Disclosure - Investments (Tables)", "shortName": "Investments (Tables)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "tables", "menuCat": "Tables", "order": "25", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:UnrealizedGainLossOnInvestmentsTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:InvestmentsInDebtAndMarketableEquitySecuritiesAndCertainTradingAssetsDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:UnrealizedGainLossOnInvestmentsTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:InvestmentsInDebtAndMarketableEquitySecuritiesAndCertainTradingAssetsDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R26": { "role": "http://www.costco.com/role/FairValueMeasurementTables", "longName": "9955514 - Disclosure - Fair Value Measurement (Tables)", "shortName": "Fair Value Measurement (Tables)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "tables", "menuCat": "Tables", "order": "26", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfFairValueAssetsAndLiabilitiesMeasuredOnRecurringBasisTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:FairValueDisclosuresTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfFairValueAssetsAndLiabilitiesMeasuredOnRecurringBasisTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:FairValueDisclosuresTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R27": { "role": "http://www.costco.com/role/DebtTables", "longName": "9955515 - Disclosure - Debt (Tables)", "shortName": "Debt (Tables)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "tables", "menuCat": "Tables", "order": "27", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfCarryingValuesAndEstimatedFairValuesOfDebtInstrumentsTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "us-gaap:DebtDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfCarryingValuesAndEstimatedFairValuesOfDebtInstrumentsTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "us-gaap:DebtDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R28": { "role": "http://www.costco.com/role/LeasesTables", "longName": "9955516 - Disclosure - Leases (Tables)", "shortName": "Leases (Tables)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "tables", "menuCat": "Tables", "order": "28", "firstAnchor": { "contextRef": "c-1", "name": "cost:DisclosureofSupplementalBalanceSheetInformationRelatedtoLeasesTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:LesseeOperatingLeasesTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "cost:DisclosureofSupplementalBalanceSheetInformationRelatedtoLeasesTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:LesseeOperatingLeasesTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R29": { "role": "http://www.costco.com/role/StockholdersEquityTables", "longName": "9955517 - Disclosure - Stockholders' Equity (Tables)", "shortName": "Stockholders' Equity (Tables)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "tables", "menuCat": "Tables", "order": "29", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfTreasuryStockByClassTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "us-gaap:StockholdersEquityNoteDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfTreasuryStockByClassTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "us-gaap:StockholdersEquityNoteDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R30": { "role": "http://www.costco.com/role/StockBasedCompensationPlansTables", "longName": "9955518 - Disclosure - Stock-Based Compensation Plans (Tables)", "shortName": "Stock-Based Compensation Plans (Tables)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "tables", "menuCat": "Tables", "order": "30", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfShareBasedCompensationArrangementByShareBasedPaymentAwardRestrictedStockUnitsVestedAndExpectedToVestTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfShareBasedCompensationArrangementByShareBasedPaymentAwardRestrictedStockUnitsVestedAndExpectedToVestTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R31": { "role": "http://www.costco.com/role/IncomeTaxesTables", "longName": "9955519 - Disclosure - Income Taxes (Tables)", "shortName": "Income Taxes (Tables)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "tables", "menuCat": "Tables", "order": "31", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfIncomeBeforeIncomeTaxDomesticAndForeignTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:IncomeTaxDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfIncomeBeforeIncomeTaxDomesticAndForeignTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:IncomeTaxDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R32": { "role": "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareNetIncomeperCommonandCommonEquivalentShareTables", "longName": "9955520 - Disclosure - Net Income per Common and Common Equivalent Share Net Income per Common and Common Equivalent Share (Tables)", "shortName": "Net Income per Common and Common Equivalent Share Net Income per Common and Common Equivalent Share (Tables)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "tables", "menuCat": "Tables", "order": "32", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfEarningsPerShareBasicAndDilutedTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:EarningsPerShareTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfEarningsPerShareBasicAndDilutedTableTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:EarningsPerShareTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R33": { "role": "http://www.costco.com/role/SegmentReportingTables", "longName": "9955522 - Disclosure - Segment Reporting (Tables)", "shortName": "Segment Reporting (Tables)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "tables", "menuCat": "Tables", "order": "33", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfSegmentReportingInformationBySegmentTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:SegmentReportingDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:ScheduleOfSegmentReportingInformationBySegmentTextBlock", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "us-gaap:SegmentReportingDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R34": { "role": "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails", "longName": "9955523 - Disclosure - Accounting Policies - Additional Information (Details)", "shortName": "Accounting Policies - Additional Information (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "34", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:NumberOfStores", "unitRef": "warehouse", "xsiNil": "false", "lang": "en-US", "decimals": "INF", "ancestors": [ "span", "div", "us-gaap:SignificantAccountingPoliciesTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:NumberOfStores", "unitRef": "warehouse", "xsiNil": "false", "lang": "en-US", "decimals": "INF", "ancestors": [ "span", "div", "us-gaap:SignificantAccountingPoliciesTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R35": { "role": "http://www.costco.com/role/AccountingPoliciesCashandCashEquivalentsDetails", "longName": "9955525 - Disclosure - Accounting Policies - Cash and Cash Equivalents (Details)", "shortName": "Accounting Policies - Cash and Cash Equivalents (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "35", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:CreditAndDebitCardReceivablesAtCarryingValue", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:CashAndCashEquivalentsPolicyTextBlock", "us-gaap:SignificantAccountingPoliciesTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:CreditAndDebitCardReceivablesAtCarryingValue", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:CashAndCashEquivalentsPolicyTextBlock", "us-gaap:SignificantAccountingPoliciesTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R36": { "role": "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails", "longName": "9955526 - Disclosure - Accounting Policies - Merchandise Inventories (Details)", "shortName": "Accounting Policies - Merchandise Inventories (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "36", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:InventoryLIFOReservePeriodCharge", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:InventoryPolicyTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:InventoryLIFOReservePeriodCharge", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:InventoryPolicyTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R37": { "role": "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails", "longName": "9955527 - Disclosure - Accounting Policies - Property and Equipment, Net (Details)", "shortName": "Accounting Policies - Property and Equipment, Net (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "37", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:Land", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:PropertyPlantAndEquipmentTextBlock", "ix:continuation", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:Land", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:PropertyPlantAndEquipmentTextBlock", "ix:continuation", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R38": { "role": "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails", "longName": "9955529 - Disclosure - Accounting Policies - Goodwill and Acquired Intangible Assets (Details)", "shortName": "Accounting Policies - Goodwill and Acquired Intangible Assets (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "38", "firstAnchor": null, "uniqueAnchor": null }, "R39": { "role": "http://www.costco.com/role/AccountingPoliciesInsuranceSelfInsuranceLiabilitiesDetails", "longName": "9955530 - Disclosure - Accounting Policies - Insurance/Self-Insurance Liabilities (Details)", "shortName": "Accounting Policies - Insurance/Self-Insurance Liabilities (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "39", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:AccruedInsuranceCurrentAndNoncurrent", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:SelfInsuranceReservePolicyTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:AccruedInsuranceCurrentAndNoncurrent", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:SelfInsuranceReservePolicyTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R40": { "role": "http://www.costco.com/role/AccountingPoliciesDerivativesDetails", "longName": "9955531 - Disclosure - Accounting Policies - Derivatives (Details)", "shortName": "Accounting Policies - Derivatives (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "40", "firstAnchor": { "contextRef": "c-68", "name": "us-gaap:DerivativeNotionalAmount", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:DerivativesPolicyTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-68", "name": "us-gaap:DerivativeNotionalAmount", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:DerivativesPolicyTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R41": { "role": "http://www.costco.com/role/AccountingPoliciesRevenueRecognitionDetails", "longName": "9955533 - Disclosure - Accounting Policies - Revenue Recognition (Details)", "shortName": "Accounting Policies - Revenue Recognition (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "41", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:DeferredRevenueCurrent", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "cost:ReductionInSales", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "ix:continuation", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R42": { "role": "http://www.costco.com/role/AccountingPoliciesRetirementPlansDetails", "longName": "9955534 - Disclosure - Accounting Policies - Retirement Plans (Details)", "shortName": "Accounting Policies - Retirement Plans (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "42", "firstAnchor": { "contextRef": "c-1", "name": "cost:MinimumNumberOfDaysOfEmploymentToQualifyForRetirementPlan", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "us-gaap:PensionAndOtherPostretirementPlansNonpensionBenefitsPolicy", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "cost:MinimumNumberOfDaysOfEmploymentToQualifyForRetirementPlan", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "us-gaap:PensionAndOtherPostretirementPlansNonpensionBenefitsPolicy", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R43": { "role": "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails", "longName": "9955535 - Disclosure - Accounting Policies - Stock-Based Compensation (Details)", "shortName": "Accounting Policies - Stock-Based Compensation (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "43", "firstAnchor": { "contextRef": "c-71", "name": "cost:ShareBasedCompensationArrangementByShareBasedPaymentNumberOfYearsOfService", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "us-gaap:ShareBasedCompensationOptionAndIncentivePlansPolicy", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-71", "name": "cost:ShareBasedCompensationArrangementByShareBasedPaymentNumberOfYearsOfService", "unitRef": null, "xsiNil": "false", "lang": "en-US", "decimals": null, "ancestors": [ "span", "div", "us-gaap:ShareBasedCompensationOptionAndIncentivePlansPolicy", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R44": { "role": "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails", "longName": "9955536 - Disclosure - Investments - Available for Sale and Held to Maturity Investments (Details)", "shortName": "Investments - Available for Sale and Held to Maturity Investments (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "44", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:AvailableForSaleDebtSecuritiesAmortizedCostBasis", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:InvestmentsClassifiedByContractualMaturityDateTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:AvailableForSaleDebtSecuritiesAccumulatedGrossUnrealizedLossBeforeTax", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:UnrealizedGainLossOnInvestmentsTableTextBlock", "us-gaap:InvestmentsInDebtAndMarketableEquitySecuritiesAndCertainTradingAssetsDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R45": { "role": "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails", "longName": "9955537 - Disclosure - Investments - Maturities of Available for Sale and Held to Maturity Securities (Details)", "shortName": "Investments - Maturities of Available for Sale and Held to Maturity Securities (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "45", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:AvailableForSaleSecuritiesDebtMaturitiesWithinOneYearAmortizedCost", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:InvestmentsClassifiedByContractualMaturityDateTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:AvailableForSaleSecuritiesDebtMaturitiesWithinOneYearAmortizedCost", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:InvestmentsClassifiedByContractualMaturityDateTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R46": { "role": "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails", "longName": "9955538 - Disclosure - Fair Value Measurement - Fair Value of Financial Assets and Financial Liabilities Measured on Recurring Basis (Details)", "shortName": "Fair Value Measurement - Fair Value of Financial Assets and Financial Liabilities Measured on Recurring Basis (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "46", "firstAnchor": { "contextRef": "c-88", "name": "us-gaap:AssetsFairValueDisclosure", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfFairValueAssetsAndLiabilitiesMeasuredOnRecurringBasisTableTextBlock", "us-gaap:FairValueDisclosuresTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-88", "name": "us-gaap:AssetsFairValueDisclosure", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfFairValueAssetsAndLiabilitiesMeasuredOnRecurringBasisTableTextBlock", "us-gaap:FairValueDisclosuresTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R47": { "role": "http://www.costco.com/role/DebtScheduleOfShortTermDebtDetails", "longName": "9955539 - Disclosure - Debt, Schedule Of Short-Term Debt (Details)", "shortName": "Debt, Schedule Of Short-Term Debt (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "47", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:LineOfCreditFacilityCurrentBorrowingCapacity", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:DebtDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:LineOfCreditFacilityCurrentBorrowingCapacity", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:DebtDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R48": { "role": "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails", "longName": "9955540 - Disclosure - Debt, Schedule of Long-Term Debt (Details)", "shortName": "Debt, Schedule of Long-Term Debt (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "48", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:DebtInstrumentRedemptionPricePercentage", "unitRef": "number", "xsiNil": "false", "lang": "en-US", "decimals": "INF", "ancestors": [ "span", "div", "us-gaap:DebtDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:DebtInstrumentRedemptionPricePercentage", "unitRef": "number", "xsiNil": "false", "lang": "en-US", "decimals": "INF", "ancestors": [ "span", "div", "us-gaap:DebtDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R49": { "role": "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails", "longName": "9955541 - Disclosure - Debt, Carrying Value of Long-Term Debt (Details)", "shortName": "Debt, Carrying Value of Long-Term Debt (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "49", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:DebtInstrumentCarryingAmount", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "ix:continuation", "us-gaap:DebtDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:DeferredFinanceCostsNet", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "ix:continuation", "us-gaap:DebtDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R50": { "role": "http://www.costco.com/role/DebtScheduleOfLongTermDebtMaturitiesDetails", "longName": "9955542 - Disclosure - Debt, Schedule Of Long-Term Debt Maturities (Details)", "shortName": "Debt, Schedule Of Long-Term Debt Maturities (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "50", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:LongTermDebtMaturitiesRepaymentsOfPrincipalInNextTwelveMonths", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "ix:continuation", "us-gaap:ScheduleOfMaturitiesOfLongTermDebtTableTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:LongTermDebtMaturitiesRepaymentsOfPrincipalInNextTwelveMonths", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "ix:continuation", "us-gaap:ScheduleOfMaturitiesOfLongTermDebtTableTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R51": { "role": "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails", "longName": "9955543 - Disclosure - Leases, Supplemental Balance Sheet Information (Details)", "shortName": "Leases, Supplemental Balance Sheet Information (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "51", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:OperatingLeaseRightOfUseAsset", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "cost:DisclosureofSupplementalBalanceSheetInformationRelatedtoLeasesTableTextBlock", "us-gaap:LesseeOperatingLeasesTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:FinanceLeaseRightOfUseAsset", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "cost:DisclosureofSupplementalBalanceSheetInformationRelatedtoLeasesTableTextBlock", "us-gaap:LesseeOperatingLeasesTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R52": { "role": "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails", "longName": "9955544 - Disclosure - Leases, Components of Lease Expense (Details)", "shortName": "Leases, Components of Lease Expense (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "52", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:OperatingLeaseCost", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:LeaseCostTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:OperatingLeaseCost", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:LeaseCostTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R53": { "role": "http://www.costco.com/role/LeasesSupplementalCashFlowInformationDetails", "longName": "9955545 - Disclosure - Leases, Supplemental Cash Flow Information (Details)", "shortName": "Leases, Supplemental Cash Flow Information (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "53", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:OperatingLeasePayments", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:LeaseCostTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:OperatingLeasePayments", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:LeaseCostTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R54": { "role": "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails", "longName": "9955546 - Disclosure - Leases, Future Minimum Payments (Details)", "shortName": "Leases, Future Minimum Payments (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "54", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:LesseeOperatingLeaseLiabilityPaymentsDueNextTwelveMonths", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:LesseeOperatingLeaseLiabilityMaturityTableTextBlock", "us-gaap:FinanceLeaseLiabilityMaturityTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:LesseeOperatingLeaseLiabilityPaymentsDueNextTwelveMonths", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:LesseeOperatingLeaseLiabilityMaturityTableTextBlock", "us-gaap:FinanceLeaseLiabilityMaturityTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R55": { "role": "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails", "longName": "9955547 - Disclosure - Stockholders' Equity - Additional Information (Details)", "shortName": "Stockholders' Equity - Additional Information (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "55", "firstAnchor": { "contextRef": "c-109", "name": "us-gaap:CommonStockDividendsPerShareDeclared", "unitRef": "usdPerShare", "xsiNil": "false", "lang": "en-US", "decimals": "INF", "ancestors": [ "span", "div", "us-gaap:StockholdersEquityNoteDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-109", "name": "us-gaap:CommonStockDividendsPerShareDeclared", "unitRef": "usdPerShare", "xsiNil": "false", "lang": "en-US", "decimals": "INF", "ancestors": [ "span", "div", "us-gaap:StockholdersEquityNoteDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R56": { "role": "http://www.costco.com/role/EquityAdditionalInformationStockRepurchaseProgramsDetails", "longName": "9955548 - Disclosure - Equity - Additional Information - Stock Repurchase Programs (Details)", "shortName": "Equity - Additional Information - Stock Repurchase Programs (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "56", "firstAnchor": { "contextRef": "c-12", "name": "srt:StockRepurchaseProgramAuthorizedAmount1", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:StockholdersEquityNoteDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "srt:StockRepurchaseProgramAuthorizedAmount1", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "us-gaap:StockholdersEquityNoteDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R57": { "role": "http://www.costco.com/role/StockholdersEquityStockRepurchasedDuringPeriodDetails", "longName": "9955549 - Disclosure - Stockholders' Equity (Stock Repurchased During Period) (Details)", "shortName": "Stockholders' Equity (Stock Repurchased During Period) (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "57", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:StockRepurchasedAndRetiredDuringPeriodShares", "unitRef": "shares", "xsiNil": "false", "lang": "en-US", "decimals": "-3", "ancestors": [ "span", "td", "tr", "table", "div", "ix:continuation", "us-gaap:StockholdersEquityNoteDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:TreasuryStockAcquiredAverageCostPerShare", "unitRef": "usdPerShare", "xsiNil": "false", "lang": "en-US", "decimals": "2", "ancestors": [ "span", "td", "tr", "table", "div", "ix:continuation", "us-gaap:StockholdersEquityNoteDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R58": { "role": "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails", "longName": "9955550 - Disclosure - Stock-Based Compensation Plans - Additional Information (Details)", "shortName": "Stock-Based Compensation Plans - Additional Information (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "58", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsGrantsInPeriodWeightedAverageGrantDateFairValue", "unitRef": "usdPerShare", "xsiNil": "false", "lang": "en-US", "decimals": "2", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfShareBasedCompensationArrangementByShareBasedPaymentAwardRestrictedStockUnitsVestedAndExpectedToVestTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-111", "name": "us-gaap:ShareBasedCompensationArrangementByShareBasedPaymentAwardNumberOfSharesAvailableForGrant", "unitRef": "shares", "xsiNil": "false", "lang": "en-US", "decimals": "-3", "ancestors": [ "span", "div", "us-gaap:DisclosureOfCompensationRelatedCostsShareBasedPaymentsTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R59": { "role": "http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails", "longName": "9955551 - Disclosure - Stock-Based Compensation Plans - Summary of RSU Transactions (Details)", "shortName": "Stock-Based Compensation Plans - Summary of RSU Transactions (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "59", "firstAnchor": { "contextRef": "c-13", "name": "us-gaap:ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsNonvestedNumber", "unitRef": "shares", "xsiNil": "false", "lang": "en-US", "decimals": "-3", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfShareBasedCompensationArrangementByShareBasedPaymentAwardRestrictedStockUnitsVestedAndExpectedToVestTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsForfeitedInPeriod", "unitRef": "shares", "xsiNil": "false", "lang": "en-US", "decimals": "-3", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfShareBasedCompensationArrangementByShareBasedPaymentAwardRestrictedStockUnitsVestedAndExpectedToVestTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R60": { "role": "http://www.costco.com/role/StockBasedCompensationPlansSummaryofStockBasedCompensationExpenseDetails", "longName": "9955552 - Disclosure - Stock-Based Compensation Plans - Summary of Stock-Based Compensation Expense (Details)", "shortName": "Stock-Based Compensation Plans - Summary of Stock-Based Compensation Expense (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "60", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:ShareBasedCompensation", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:EmployeeServiceShareBasedCompensationTaxBenefitFromCompensationExpense", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfCompensationCostForShareBasedPaymentArrangementsAllocationOfShareBasedCompensationCostsByPlanTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R61": { "role": "http://www.costco.com/role/IncomeTaxesIncomeBeforeIncomeTaxesDetails", "longName": "9955553 - Disclosure - Income Taxes (Income Before Income Taxes) (Details)", "shortName": "Income Taxes (Income Before Income Taxes) (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "61", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:IncomeLossFromContinuingOperationsBeforeIncomeTaxesDomestic", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfIncomeBeforeIncomeTaxDomesticAndForeignTableTextBlock", "us-gaap:IncomeTaxDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:IncomeLossFromContinuingOperationsBeforeIncomeTaxesDomestic", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfIncomeBeforeIncomeTaxDomesticAndForeignTableTextBlock", "us-gaap:IncomeTaxDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R62": { "role": "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails", "longName": "9955554 - Disclosure - Income Taxes (Schedule of Foreign And Domestic Income Taxes) (Details)", "shortName": "Income Taxes (Schedule of Foreign And Domestic Income Taxes) (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "62", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:CurrentFederalTaxExpenseBenefit", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfComponentsOfIncomeTaxExpenseBenefitTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:CurrentFederalTaxExpenseBenefit", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfComponentsOfIncomeTaxExpenseBenefitTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R63": { "role": "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "longName": "9955555 - Disclosure - Income Taxes (Reconciliation Between Statutory And Effective Rates) (Details)", "shortName": "Income Taxes (Reconciliation Between Statutory And Effective Rates) (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "63", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:IncomeTaxReconciliationIncomeTaxExpenseBenefitAtFederalStatutoryIncomeTaxRate", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfEffectiveIncomeTaxRateReconciliationTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:EffectiveIncomeTaxRateReconciliationCrossBorderTaxEffectAmount", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfEffectiveIncomeTaxRateReconciliationTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R64": { "role": "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details", "longName": "9955556 - Disclosure - Income Taxes (Reconciliation Between Statutory and Effective Rates FY25 and FY24) (Details)", "shortName": "Income Taxes (Reconciliation Between Statutory and Effective Rates FY25 and FY24) (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "64", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:IncomeTaxReconciliationIncomeTaxExpenseBenefitAtFederalStatutoryIncomeTaxRate", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfEffectiveIncomeTaxRateReconciliationTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-10", "name": "us-gaap:IncomeTaxRateReconciliationDeductionsEmployeeStockOwnershipPlanDividends", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "ix:continuation", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R65": { "role": "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails", "longName": "9955557 - Disclosure - Income Taxes (Reconciliation Between Statutory and Effective Rates Narrative) (Details)", "shortName": "Income Taxes (Reconciliation Between Statutory and Effective Rates Narrative) (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "65", "firstAnchor": { "contextRef": "c-11", "name": "us-gaap:IncomeTaxReconciliationTaxSettlements", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-11", "name": "us-gaap:IncomeTaxReconciliationTaxSettlements", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R66": { "role": "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails", "longName": "9955558 - Disclosure - Income Taxes Cash Paid for Income Taxes (Details)", "shortName": "Income Taxes Cash Paid for Income Taxes (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "66", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:IncomeTaxPaidFederalAfterRefundReceived", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfCashFlowSupplementalDisclosuresTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:IncomeTaxPaidFederalAfterRefundReceived", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfCashFlowSupplementalDisclosuresTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R67": { "role": "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails", "longName": "9955559 - Disclosure - Income Taxes (Components of Deferred Tax Assets And Liabilities) (Details)", "shortName": "Income Taxes (Components of Deferred Tax Assets And Liabilities) (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "67", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:DeferredTaxAssetsTaxDeferredExpenseCompensationAndBenefits", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfDeferredTaxAssetsAndLiabilitiesTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:DeferredTaxAssetsTaxDeferredExpenseCompensationAndBenefits", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfDeferredTaxAssetsAndLiabilitiesTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true, "unique": true } }, "R68": { "role": "http://www.costco.com/role/IncomeTaxesDeferredTaxAssetsandLiabilitiesNarrativeDetails", "longName": "9955560 - Disclosure - Income Taxes (Deferred Tax Assets and Liabilities Narrative) (Details)", "shortName": "Income Taxes (Deferred Tax Assets and Liabilities Narrative) (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "68", "firstAnchor": { "contextRef": "c-12", "name": "us-gaap:TaxCreditCarryforwardValuationAllowance", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-12", "name": "us-gaap:UndistributedEarningsOfForeignSubsidiaries", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "div", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R69": { "role": "http://www.costco.com/role/IncomeTaxesGrossUnrecognizedTaxBenefitsDetails", "longName": "9955561 - Disclosure - Income Taxes (Gross Unrecognized Tax Benefits) (Details)", "shortName": "Income Taxes (Gross Unrecognized Tax Benefits) (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "69", "firstAnchor": { "contextRef": "c-13", "name": "us-gaap:UnrecognizedTaxBenefits", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfUnrecognizedTaxBenefitsRollForwardTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-27", "name": "us-gaap:UnrecognizedTaxBenefits", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfUnrecognizedTaxBenefitsRollForwardTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R70": { "role": "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareScheduleofEarningsperShareEffectonNetIncomeandWeightedAveregaeNumberofDilutivePotentialCommonStockDetails", "longName": "9955562 - Disclosure - Net Income per Common and Common Equivalent Share - Schedule of Earnings per Share Effect on Net Income and Weighted Averegae Number of Dilutive Potential Common Stock (Details)", "shortName": "Net Income per Common and Common Equivalent Share - Schedule of Earnings per Share Effect on Net Income and Weighted Averegae Number of Dilutive Potential Common Stock (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "70", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:NetIncomeLoss", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:IncrementalCommonSharesAttributableToShareBasedPaymentArrangements", "unitRef": "shares", "xsiNil": "false", "lang": "en-US", "decimals": "-3", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfEarningsPerShareBasicAndDilutedTableTextBlock", "us-gaap:EarningsPerShareTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R71": { "role": "http://www.costco.com/role/SegmentReportingNarrativeDetails", "longName": "9955564 - Disclosure - Segment Reporting - Narrative (Details)", "shortName": "Segment Reporting - Narrative (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "71", "firstAnchor": null, "uniqueAnchor": null }, "R72": { "role": "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails", "longName": "9955565 - Disclosure - Segment Reporting Information by Segment (Details)", "shortName": "Segment Reporting Information by Segment (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "72", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:RevenueFromContractWithCustomerExcludingAssessedTax", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfSegmentReportingInformationBySegmentTextBlock", "us-gaap:SegmentReportingDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:OtherIncome", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfSegmentReportingInformationBySegmentTextBlock", "us-gaap:SegmentReportingDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R73": { "role": "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1", "longName": "9955566 - Disclosure - Segment Reporting Information by Segment (Details)", "shortName": "Segment Reporting Information by Segment (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "73", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:DepreciationDepletionAndAmortization", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-1", "name": "us-gaap:SegmentExpenditureAdditionToLongLivedAssets", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "ix:continuation", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } }, "R74": { "role": "http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails", "longName": "9955567 - Disclosure - Segment Reporting Information by Item Category (Details)", "shortName": "Segment Reporting Information by Item Category (Details)", "isDefault": "false", "groupType": "disclosure", "subGroupType": "details", "menuCat": "Details", "order": "74", "firstAnchor": { "contextRef": "c-1", "name": "us-gaap:RevenueFromContractWithCustomerExcludingAssessedTax", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:ScheduleOfSegmentReportingInformationBySegmentTextBlock", "us-gaap:SegmentReportingDisclosureTextBlock", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "first": true }, "uniqueAnchor": { "contextRef": "c-145", "name": "us-gaap:RevenueFromContractWithCustomerExcludingAssessedTax", "unitRef": "usd", "xsiNil": "false", "lang": "en-US", "decimals": "-6", "ancestors": [ "span", "td", "tr", "table", "div", "us-gaap:DisaggregationOfRevenueTableTextBlock", "ix:continuation", "body", "html" ], "reportCount": 1, "baseRef": "cost-20260830.htm", "unique": true } } }, "tag": { "country_AU": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "AU", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "AUSTRALIA", "label": "AUSTRALIA" } } }, "auth_ref": [] }, "us-gaap_AccountingPoliciesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AccountingPoliciesAbstract", "lang": { "en-us": { "role": { "terseLabel": "Accounting Policies [Abstract]", "label": "Accounting Policies [Abstract]" } } }, "auth_ref": [] }, "us-gaap_AccountsPayableCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AccountsPayableCurrent", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_LiabilitiesCurrent", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Accounts payable", "label": "Accounts Payable, Current", "documentation": "Carrying value as of the balance sheet date of liabilities incurred (and for which invoices have typically been received) and payable to vendors for goods and services received that are used in an entity's business. Used to reflect the current portion of the liabilities (due within one year or within the normal operating cycle if longer)." } } }, "auth_ref": [ "r1118", "r1282", "r1287" ] }, "us-gaap_AccruedInsuranceCurrentAndNoncurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AccruedInsuranceCurrentAndNoncurrent", "crdr": "credit", "presentation": [ "http://www.costco.com/role/AccountingPoliciesInsuranceSelfInsuranceLiabilitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Accrued insurance", "label": "Accrued Insurance", "documentation": "Carrying value as of the balance sheet date of obligations incurred through that date and payable to insurance entities to mitigate potential loss from various risks or to satisfy a promise to provide certain coverage's to employees." } } }, "auth_ref": [ "r1291", "r1555", "r1556", "r1557" ] }, "us-gaap_AccruedLiabilitiesCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AccruedLiabilitiesCurrent", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_LiabilitiesCurrent", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Accrued member rewards", "label": "Accrued Liabilities, Current", "documentation": "Carrying value as of the balance sheet date of obligations incurred and payable, pertaining to costs that are statutory in nature, are incurred on contractual obligations, or accumulate over time and for which invoices have not yet been received or will not be rendered. Examples include taxes, interest, rent and utilities. Used to reflect the current portion of the liabilities (due within one year or within the normal operating cycle if longer)." } } }, "auth_ref": [ "r1288" ] }, "us-gaap_AccumulatedDepreciationDepletionAndAmortizationPropertyPlantAndEquipment": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AccumulatedDepreciationDepletionAndAmortizationPropertyPlantAndEquipment", "crdr": "credit", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Accumulated depreciation and amortization", "label": "Property, Plant, and Equipment, Accumulated Depreciation, Depletion, and Amortization", "documentation": "Amount of accumulated depreciation, depletion, and amortization of property, plant, and equipment. Includes, but is not limited to, land and land improvement; building; machinery and equipment; furniture and fixture; and work of art, historical treasure, or similar asset classified as collection." } } }, "auth_ref": [ "r119", "r346", "r351", "r830", "r831", "r845", "r1419" ] }, "us-gaap_AccumulatedOtherComprehensiveIncomeLossNetOfTax": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AccumulatedOtherComprehensiveIncomeLossNetOfTax", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_StockholdersEquity", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "verboseLabel": "Accumulated other comprehensive loss", "label": "Accumulated Other Comprehensive Income (Loss), Net of Tax", "documentation": "Amount, after tax, of accumulated increase (decrease) in equity from transaction and other event and circumstance from nonowner source." } } }, "auth_ref": [ "r7", "r8", "r19", "r146", "r446", "r790", "r791", "r801", "r841", "r881", "r882", "r1520" ] }, "us-gaap_AccumulatedOtherComprehensiveIncomeMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AccumulatedOtherComprehensiveIncomeMember", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "verboseLabel": "Accumulated Other Comprehensive Income (Loss)", "label": "AOCI Attributable to Parent [Member]", "documentation": "Accumulated increase (decrease) in equity from transactions and other events and circumstances from non-owner sources, attributable to the parent. Excludes net income (loss), and accumulated changes in equity from transactions resulting from investments by owners and distributions to owners." } } }, "auth_ref": [ "r1", "r6", "r8", "r634", "r638", "r641", "r712", "r877", "r878", "r1307", "r1308", "r1309", "r1368", "r1369", "r1370", "r1371", "r1447", "r1449" ] }, "ecd_Additional402vDisclosureTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "Additional402vDisclosureTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Additional 402(v) Disclosure", "label": "Additional 402(v) Disclosure [Text Block]" } } }, "auth_ref": [ "r1199" ] }, "us-gaap_AdditionalPaidInCapitalCommonStock": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AdditionalPaidInCapitalCommonStock", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_StockholdersEquity", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Additional paid-in capital", "label": "Additional Paid in Capital, Common Stock", "documentation": "Value received from shareholders in common stock-related transactions that are in excess of par value or stated value and amounts received from other stock-related transactions. Includes only common stock transactions (excludes preferred stock transactions). May be called contributed capital, capital in excess of par, capital surplus, or paid-in capital." } } }, "auth_ref": [ "r1294", "r1446" ] }, "us-gaap_AdditionalPaidInCapitalMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AdditionalPaidInCapitalMember", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Additional Paid-in Capital", "label": "Additional Paid-in Capital [Member]", "documentation": "Excess of issue price over par or stated value of the entity's capital stock and amounts received from other transactions involving the entity's stock or stockholders." } } }, "auth_ref": [ "r832", "r897", "r1368", "r1369", "r1370", "r1371", "r1521", "r1619" ] }, "ecd_AdjToCompAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AdjToCompAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Adjustment to Compensation, Amount", "label": "Adjustment to Compensation Amount" } } }, "auth_ref": [ "r1212" ] }, "ecd_AdjToCompAxis": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AdjToCompAxis", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Adjustment to Compensation:", "label": "Adjustment to Compensation [Axis]" } } }, "auth_ref": [ "r1212" ] }, "ecd_AdjToNonPeoNeoCompFnTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AdjToNonPeoNeoCompFnTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Adjustment to Non-PEO NEO Compensation Footnote", "label": "Adjustment to Non-PEO NEO Compensation Footnote [Text Block]" } } }, "auth_ref": [ "r1212" ] }, "ecd_AdjToPeoCompFnTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AdjToPeoCompFnTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Adjustment To PEO Compensation, Footnote", "label": "Adjustment To PEO Compensation, Footnote [Text Block]" } } }, "auth_ref": [ "r1212" ] }, "us-gaap_AdjustmentsToAdditionalPaidInCapitalSharebasedCompensationRequisiteServicePeriodRecognitionValue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AdjustmentsToAdditionalPaidInCapitalSharebasedCompensationRequisiteServicePeriodRecognitionValue", "crdr": "credit", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Stock-based compensation", "label": "APIC, Share-Based Payment Arrangement, Increase for Cost Recognition", "documentation": "Amount of increase to additional paid-in capital (APIC) for recognition of cost for award under share-based payment arrangement." } } }, "auth_ref": [ "r486" ] }, "us-gaap_AdjustmentsToReconcileNetIncomeLossToCashProvidedByUsedInOperatingActivitiesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AdjustmentsToReconcileNetIncomeLossToCashProvidedByUsedInOperatingActivitiesAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "Adjustments to reconcile net income including noncontrolling interests to net cash provided by operating activities:", "label": "Adjustment to Reconcile Net Income to Cash Provided by (Used in) Operating Activity [Abstract]" } } }, "auth_ref": [] }, "ecd_AggtChngPnsnValInSummryCompstnTblForAplblYrMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AggtChngPnsnValInSummryCompstnTblForAplblYrMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Aggregate Change in Present Value of Accumulated Benefit for All Pension Plans Reported in Summary Compensation Table", "label": "Aggregate Change in Present Value of Accumulated Benefit for All Pension Plans Reported in Summary Compensation Table [Member]" } } }, "auth_ref": [ "r1257" ] }, "ecd_AggtErrCompAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AggtErrCompAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Aggregate Erroneous Compensation Amount", "label": "Aggregate Erroneous Compensation Amount" } } }, "auth_ref": [ "r1170", "r1181", "r1191", "r1224" ] }, "ecd_AggtErrCompNotYetDeterminedTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AggtErrCompNotYetDeterminedTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Aggregate Erroneous Compensation Not Yet Determined", "label": "Aggregate Erroneous Compensation Not Yet Determined [Text Block]" } } }, "auth_ref": [ "r1173", "r1184", "r1194", "r1227" ] }, "ecd_AggtPnsnAdjsSvcCstMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AggtPnsnAdjsSvcCstMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Aggregate Pension Adjustments Service Cost", "label": "Aggregate Pension Adjustments Service Cost [Member]" } } }, "auth_ref": [ "r1258" ] }, "ecd_AllAdjToCompMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AllAdjToCompMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "All Adjustments to Compensation", "label": "All Adjustments to Compensation [Member]" } } }, "auth_ref": [ "r1212" ] }, "ecd_AllExecutiveCategoriesMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AllExecutiveCategoriesMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "All Executive Categories", "label": "All Executive Categories [Member]" } } }, "auth_ref": [ "r1219" ] }, "ecd_AllIndividualsMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AllIndividualsMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure", "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure", "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements", "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "All Individuals", "label": "All Individuals [Member]" } } }, "auth_ref": [ "r1174", "r1185", "r1195", "r1219", "r1228", "r1232", "r1240" ] }, "ecd_AllTradingArrangementsMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AllTradingArrangementsMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "All Trading Arrangements", "label": "All Trading Arrangements [Member]" } } }, "auth_ref": [ "r1238" ] }, "us-gaap_AllocatedShareBasedCompensationExpenseNetOfTax": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AllocatedShareBasedCompensationExpenseNetOfTax", "crdr": "debit", "calculation": { "http://www.costco.com/role/StockBasedCompensationPlansSummaryofStockBasedCompensationExpenseDetails": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansSummaryofStockBasedCompensationExpenseDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Stock-based compensation expense, net", "label": "Share-Based Payment Arrangement, Expense, after Tax", "documentation": "Amount, after tax, of expense for award under share-based payment arrangement." } } }, "auth_ref": [ "r1483" ] }, "dei_AmendmentFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "AmendmentFlag", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Amendment Flag", "label": "Amendment Flag", "documentation": "Boolean flag that is true when the XBRL content amends previously-filed or accepted submission." } } }, "auth_ref": [] }, "us-gaap_Assets": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "Assets", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "totalLabel": "Total assets", "label": "Assets", "documentation": "Amount of asset recognized for present right to economic benefit." } } }, "auth_ref": [ "r103", "r104", "r122", "r178", "r181", "r182", "r224", "r237", "r256", "r260", "r305", "r368", "r369", "r371", "r372", "r373", "r374", "r375", "r377", "r378", "r449", "r590", "r592", "r679", "r790", "r791", "r793", "r807", "r808", "r836", "r941", "r1053", "r1054", "r1070", "r1118", "r1136", "r1137", "r1148", "r1436", "r1437", "r1550" ] }, "us-gaap_AssetsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AssetsAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "ASSETS", "label": "Assets [Abstract]" } } }, "auth_ref": [] }, "us-gaap_AssetsCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AssetsCurrent", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_Assets", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "totalLabel": "Total current assets", "label": "Assets, Current", "documentation": "Amount of asset recognized for present right to economic benefit, classified as current." } } }, "auth_ref": [ "r103", "r104", "r153", "r178", "r181", "r182", "r305", "r368", "r369", "r371", "r372", "r373", "r374", "r375", "r377", "r378", "r449", "r590", "r592", "r679", "r1118", "r1279", "r1436", "r1437", "r1550" ] }, "us-gaap_AssetsCurrentAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AssetsCurrentAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "CURRENT ASSETS", "label": "Assets, Current [Abstract]" } } }, "auth_ref": [] }, "us-gaap_AssetsFairValueDisclosure": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AssetsFairValueDisclosure", "crdr": "debit", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Fair value of assets measured on recurring basis", "label": "Assets, Fair Value Disclosure", "documentation": "Fair value portion of asset recognized for present right to economic benefit." } } }, "auth_ref": [ "r655", "r656", "r1104" ] }, "dei_AuditorFirmId": { "xbrltype": "nonemptySequenceNumberItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "AuditorFirmId", "presentation": [ "http://www.costco.com/role/AuditInformation" ], "lang": { "en-us": { "role": { "terseLabel": "Auditor Firm ID", "label": "Auditor Firm ID", "documentation": "PCAOB issued Audit Firm Identifier" } } }, "auth_ref": [ "r1153", "r1154", "r1177" ] }, "cost_AuditorInformationAbstract": { "xbrltype": "stringItemType", "nsuri": "http://www.costco.com/20260830", "localname": "AuditorInformationAbstract", "lang": { "en-us": { "role": { "terseLabel": "Auditor Information [Abstract]", "label": "Auditor Information [Abstract]", "documentation": "Auditor Information" } } }, "auth_ref": [] }, "dei_AuditorLocation": { "xbrltype": "internationalNameItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "AuditorLocation", "presentation": [ "http://www.costco.com/role/AuditInformation" ], "lang": { "en-us": { "role": { "terseLabel": "Auditor Location", "label": "Auditor Location" } } }, "auth_ref": [ "r1153", "r1154", "r1177" ] }, "dei_AuditorName": { "xbrltype": "internationalNameItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "AuditorName", "presentation": [ "http://www.costco.com/role/AuditInformation" ], "lang": { "en-us": { "role": { "terseLabel": "Auditor Name", "label": "Auditor Name" } } }, "auth_ref": [ "r1153", "r1154", "r1177" ] }, "cost_AvailableForSaleAndHeldToMaturityLineItems": { "xbrltype": "stringItemType", "nsuri": "http://www.costco.com/20260830", "localname": "AvailableForSaleAndHeldToMaturityLineItems", "presentation": [ "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Available For Sale And Held To Maturity [Line Items]", "label": "Available For Sale And Held To Maturity [Line Items]", "documentation": "Available For Sale And Held To Maturity [Line Items]" } } }, "auth_ref": [] }, "cost_AvailableForSaleAndHeldToMaturityTable": { "xbrltype": "stringItemType", "nsuri": "http://www.costco.com/20260830", "localname": "AvailableForSaleAndHeldToMaturityTable", "presentation": [ "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Available For Sale And Held To Maturity [Table]", "label": "Available For Sale And Held To Maturity [Table]", "documentation": "Available For Sale And Held To Maturity [Table]" } } }, "auth_ref": [] }, "us-gaap_AvailableForSaleDebtSecuritiesAccumulatedGrossUnrealizedGainBeforeTax": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleDebtSecuritiesAccumulatedGrossUnrealizedGainBeforeTax", "crdr": "credit", "presentation": [ "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Unrealized Gains, Net", "label": "Debt Securities, Available-for-Sale, Accumulated Gross Unrealized Gain, before Tax", "documentation": "Amount, before tax, of unrealized gain in accumulated other comprehensive income (AOCI) on investment in debt security measured at fair value with change in fair value recognized in other comprehensive income (available-for-sale)." } } }, "auth_ref": [ "r279" ] }, "us-gaap_AvailableForSaleDebtSecuritiesAccumulatedGrossUnrealizedLossBeforeTax": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleDebtSecuritiesAccumulatedGrossUnrealizedLossBeforeTax", "crdr": "debit", "presentation": [ "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Unrealized Losses, Net", "label": "Debt Securities, Available-for-Sale, Accumulated Gross Unrealized Loss, before Tax", "documentation": "Amount, before tax, of unrealized loss in accumulated other comprehensive income (AOCI) on investment in debt security measured at fair value with change in fair value recognized in other comprehensive income (available-for-sale)." } } }, "auth_ref": [ "r280" ] }, "us-gaap_AvailableForSaleDebtSecuritiesAmortizedCostBasis": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleDebtSecuritiesAmortizedCostBasis", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails": { "parentTag": "us-gaap_DebtSecuritiesAvailableForSaleAndHeldToMaturityAmortizedCostBeforeAllowanceForCreditLoss", "weight": 1.0, "order": 1.0 }, "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails", "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Available-for-sale, cost basis", "totalLabel": "Available-for-sale, cost basis, total", "label": "Debt Securities, Available-for-Sale, Amortized Cost", "documentation": "Amortized cost of investment in debt security measured at fair value with change in fair value recognized in other comprehensive income (available-for-sale)." } } }, "auth_ref": [ "r276", "r321", "r812", "r813", "r814", "r815", "r816", "r817", "r818", "r819", "r835", "r1564" ] }, "us-gaap_AvailableForSaleSecuritiesDebtMaturitiesAfterFiveThroughTenYearsAmortizedCost": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleSecuritiesDebtMaturitiesAfterFiveThroughTenYearsAmortizedCost", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": "us-gaap_AvailableForSaleDebtSecuritiesAmortizedCostBasis", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Due after five years", "label": "Debt Securities, Available-for-Sale, Amortized Cost, Maturity, Allocated and Single Maturity Date, after Year 5 Through 10", "documentation": "Amortized cost of investment in debt security measured at fair value with change in fair value recognized in other comprehensive income (available-for-sale), with single maturity date and allocated without single maturity date, maturing in sixth through tenth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r1397", "r1567" ] }, "us-gaap_AvailableForSaleSecuritiesDebtMaturitiesAfterFiveThroughTenYearsFairValue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleSecuritiesDebtMaturitiesAfterFiveThroughTenYearsFairValue", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": "us-gaap_AvailableForSaleSecuritiesDebtSecurities", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Due after five years", "label": "Debt Securities, Available-for-Sale, Fair Value, Maturity, Allocated and Single Maturity Date, after Year 5 Through 10", "documentation": "Fair value of investment in debt security measured at fair value with change in fair value recognized in other comprehensive income (available-for-sale), with single maturity date and allocated without single maturity date, maturing in sixth through tenth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r285", "r828" ] }, "us-gaap_AvailableForSaleSecuritiesDebtMaturitiesAfterOneThroughFiveYearsAmortizedCost": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleSecuritiesDebtMaturitiesAfterOneThroughFiveYearsAmortizedCost", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": "us-gaap_AvailableForSaleDebtSecuritiesAmortizedCostBasis", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Due after one year through five years", "label": "Debt Securities, Available-for-Sale, Amortized Cost, Maturity, Allocated and Single Maturity Date, after Year One Through Five", "documentation": "Amortized cost of investment in debt security measured at fair value with change in fair value recognized in other comprehensive income (available-for-sale), with single maturity date and allocated without single maturity date, maturing in second through fifth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r1396", "r1566" ] }, "us-gaap_AvailableForSaleSecuritiesDebtMaturitiesAfterOneThroughFiveYearsFairValue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleSecuritiesDebtMaturitiesAfterOneThroughFiveYearsFairValue", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": "us-gaap_AvailableForSaleSecuritiesDebtSecurities", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Due after one year through five years", "label": "Debt Securities, Available-for-Sale, Fair Value, Maturity, Allocated and Single Maturity Date, after Year One Through Five", "documentation": "Fair value of investment in debt security measured at fair value with change in fair value recognized in other comprehensive income (available-for-sale), with single maturity date and allocated without single maturity date, maturing in second through fifth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r284", "r827" ] }, "us-gaap_AvailableForSaleSecuritiesDebtMaturitiesAmortizedCostAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleSecuritiesDebtMaturitiesAmortizedCostAbstract", "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Available-For-Sale, Cost Basis", "label": "Debt Securities, Available-for-Sale, Amortized Cost, Fiscal Year Maturity [Abstract]" } } }, "auth_ref": [] }, "us-gaap_AvailableForSaleSecuritiesDebtMaturitiesFairValueAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleSecuritiesDebtMaturitiesFairValueAbstract", "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Available-For-Sale, Fair Value", "label": "Debt Securities, Available-for-Sale, Fair Value, Fiscal Year Maturity [Abstract]" } } }, "auth_ref": [] }, "us-gaap_AvailableForSaleSecuritiesDebtMaturitiesWithinOneYearAmortizedCost": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleSecuritiesDebtMaturitiesWithinOneYearAmortizedCost", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": "us-gaap_AvailableForSaleDebtSecuritiesAmortizedCostBasis", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Due in one year or less", "label": "Debt Securities, Available-for-Sale, Amortized Cost, Maturity, Allocated and Single Maturity Date, Year One", "documentation": "Amortized cost of investment in debt security measured at fair value with change in fair value recognized in other comprehensive income (available-for-sale), with single maturity date and allocated without single maturity date, maturing in next fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r1395", "r1565" ] }, "us-gaap_AvailableForSaleSecuritiesDebtMaturitiesWithinOneYearFairValue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleSecuritiesDebtMaturitiesWithinOneYearFairValue", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": "us-gaap_AvailableForSaleSecuritiesDebtSecurities", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Due in one year or less", "label": "Debt Securities, Available-for-Sale, Fair Value, Maturity, Allocated and Single Maturity Date, Year One", "documentation": "Fair value of investment in debt security measured at fair value with change in fair value recognized in other comprehensive income (available-for-sale), with single maturity date and allocated without single maturity date, maturing in next fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r283", "r826" ] }, "us-gaap_AvailableForSaleSecuritiesDebtSecurities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AvailableForSaleSecuritiesDebtSecurities", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails", "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Available-for-sale, recorded basis, total", "totalLabel": "Available-for-sale, recorded basis, total", "label": "Debt Securities, Available-for-Sale", "documentation": "Amount of investment in debt security measured at fair value with change in fair value recognized in other comprehensive income (available-for-sale)." } } }, "auth_ref": [ "r277", "r321", "r655", "r673", "r674", "r675", "r676", "r790", "r791", "r803", "r812", "r813", "r814", "r815", "r816", "r817", "r818", "r819", "r1104", "r1107", "r1114", "r1115", "r1392", "r1525", "r1526", "r1527", "r1552", "r1569" ] }, "ecd_AwardExrcPrice": { "xbrltype": "perShareItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardExrcPrice", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Exercise Price", "label": "Award Exercise Price" } } }, "auth_ref": [ "r1235" ] }, "ecd_AwardGrantDateFairValue": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardGrantDateFairValue", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Fair Value as of Grant Date", "label": "Award Grant Date Fair Value" } } }, "auth_ref": [ "r1236" ] }, "ecd_AwardTmgDiscLineItems": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardTmgDiscLineItems", "lang": { "en-us": { "role": { "label": "Award Timing Disclosures [Line Items]" } } }, "auth_ref": [ "r1231" ] }, "ecd_AwardTmgHowMnpiCnsdrdTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardTmgHowMnpiCnsdrdTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Award Timing, How MNPI Considered", "label": "Award Timing, How MNPI Considered [Text Block]" } } }, "auth_ref": [ "r1231" ] }, "ecd_AwardTmgMethodTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardTmgMethodTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Award Timing Method", "label": "Award Timing Method [Text Block]" } } }, "auth_ref": [ "r1231" ] }, "ecd_AwardTmgMnpiCnsdrdFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardTmgMnpiCnsdrdFlag", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Award Timing MNPI Considered", "label": "Award Timing MNPI Considered [Flag]" } } }, "auth_ref": [ "r1231" ] }, "ecd_AwardTmgMnpiDiscTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardTmgMnpiDiscTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Award Timing MNPI Disclosure", "label": "Award Timing MNPI Disclosure [Text Block]" } } }, "auth_ref": [ "r1231" ] }, "ecd_AwardTmgPredtrmndFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardTmgPredtrmndFlag", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Award Timing Predetermined", "label": "Award Timing Predetermined [Flag]" } } }, "auth_ref": [ "r1231" ] }, "us-gaap_AwardTypeAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "AwardTypeAxis", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails", "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails", "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Award Type [Axis]", "label": "Award Type [Axis]", "documentation": "Information by type of award under share-based payment arrangement." } } }, "auth_ref": [ "r490", "r491", "r492", "r494", "r495", "r496", "r497", "r498", "r499", "r500", "r501", "r502", "r503", "r504", "r505", "r506", "r507", "r508", "r509", "r510", "r511", "r514", "r515", "r516", "r517", "r518" ] }, "ecd_AwardUndrlygSecuritiesAmt": { "xbrltype": "decimalItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardUndrlygSecuritiesAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Underlying Securities", "label": "Award Underlying Securities Amount" } } }, "auth_ref": [ "r1234" ] }, "ecd_AwardsCloseToMnpiDiscIndName": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardsCloseToMnpiDiscIndName", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Name", "label": "Awards Close in Time to MNPI Disclosures, Individual Name" } } }, "auth_ref": [ "r1233" ] }, "ecd_AwardsCloseToMnpiDiscTable": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardsCloseToMnpiDiscTable", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Awards Close in Time to MNPI Disclosures", "label": "Awards Close in Time to MNPI Disclosures [Table]" } } }, "auth_ref": [ "r1232" ] }, "ecd_AwardsCloseToMnpiDiscTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "AwardsCloseToMnpiDiscTableTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Awards Close in Time to MNPI Disclosures, Table", "label": "Awards Close in Time to MNPI Disclosures [Table Text Block]" } } }, "auth_ref": [ "r1232" ] }, "cost_BalanceSheetLocationTable": { "xbrltype": "stringItemType", "nsuri": "http://www.costco.com/20260830", "localname": "BalanceSheetLocationTable", "presentation": [ "http://www.costco.com/role/IncomeTaxesDeferredTaxAssetsandLiabilitiesNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Balance Sheet Location[Table]", "label": "Balance Sheet Location [Table]", "documentation": "Balance Sheet Location" } } }, "auth_ref": [] }, "us-gaap_BasisOfAccountingPolicyPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "BasisOfAccountingPolicyPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Basis of Presentation", "label": "Basis of Accounting, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for basis of accounting, or basis of presentation, used to prepare the financial statements (for example, US Generally Accepted Accounting Principles, Other Comprehensive Basis of Accounting, IFRS)." } } }, "auth_ref": [ "r1358" ] }, "us-gaap_BuildingAndBuildingImprovementsMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "BuildingAndBuildingImprovementsMember", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Building and improvements [Member]", "label": "Building and Building Improvements [Member]", "documentation": "Facility held for productive use including, but not limited to, office, production, storage and distribution facilities and any addition, improvement, or renovation to the structure, for example, but not limited to, interior masonry, interior flooring, electrical, and plumbing." } } }, "auth_ref": [ "r1424", "r1425" ] }, "us-gaap_BuildingsAndImprovementsGross": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "BuildingsAndImprovementsGross", "crdr": "debit", "calculation": { "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails": { "parentTag": "us-gaap_PropertyPlantAndEquipmentGross", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Buildings and improvements", "label": "Buildings and Improvements, Gross", "documentation": "Amount before accumulated depreciation of building structures held for productive use including addition, improvement, or renovation to the structure, including, but not limited to, interior masonry, interior flooring, electrical, and plumbing." } } }, "auth_ref": [ "r1285" ] }, "stpr_CA": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/stpr/2026", "localname": "CA", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "CALIFORNIA", "label": "CALIFORNIA" } } }, "auth_ref": [] }, "country_CA": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "CA", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails", "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails", "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails", "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "CANADA", "label": "CANADA" } } }, "auth_ref": [] }, "country_CN": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "CN", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "CHINA", "label": "CHINA" } } }, "auth_ref": [] }, "cost_CanadaMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "CanadaMember", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Canada", "label": "Canada [Member]", "documentation": "Canada" } } }, "auth_ref": [] }, "cost_CanadaOtherMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "CanadaOtherMember", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Canada Other", "label": "Canada Other [Member]", "documentation": "Canada Other" } } }, "auth_ref": [] }, "us-gaap_CapitalExpendituresIncurredButNotYetPaid": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CapitalExpendituresIncurredButNotYetPaid", "crdr": "credit", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "Capital expenditures included in liabilities", "label": "Capital Expenditures Incurred but Not yet Paid", "documentation": "Future cash outflow to pay for purchases of fixed assets that have occurred." } } }, "auth_ref": [ "r1357" ] }, "us-gaap_CashAndCashEquivalentsAtCarryingValue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CashAndCashEquivalentsAtCarryingValue", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_AssetsCurrent", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Cash and cash equivalents", "label": "Cash and Cash Equivalent", "documentation": "Amount of cash and cash equivalent. Cash includes, but is not limited to, currency on hand, demand deposit with financial institution, and account with general characteristic of demand deposit. Cash equivalent includes, but is not limited to, short-term, highly liquid investment that is both readily convertible to known amount of cash and so near maturity that it presents insignificant risk of change in value because of change in interest rate." } } }, "auth_ref": [ "r117", "r170", "r174", "r1026", "r1552" ] }, "us-gaap_CashAndCashEquivalentsPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CashAndCashEquivalentsPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Cash and Cash Equivalents", "label": "Cash and Cash Equivalents, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for cash and cash equivalents, including the policy for determining which items are treated as cash equivalents. Other information that may be disclosed includes (1) the nature of any restrictions on the entity's use of its cash and cash equivalents, (2) whether the entity's cash and cash equivalents are insured or expose the entity to credit risk, (3) the classification of any negative balance accounts (overdrafts), and (4) the carrying basis of cash equivalents (for example, at cost) and whether the carrying amount of cash equivalents approximates fair value." } } }, "auth_ref": [ "r171" ] }, "us-gaap_CashCashEquivalentsRestrictedCashAndRestrictedCashEquivalents": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CashCashEquivalentsRestrictedCashAndRestrictedCashEquivalents", "crdr": "debit", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "periodStartLabel": "CASH AND CASH EQUIVALENTS BEGINNING OF YEAR", "periodEndLabel": "CASH AND CASH EQUIVALENTS END OF YEAR", "label": "Cash, Cash Equivalent, Restricted Cash, and Restricted Cash Equivalent, Continuing Operation", "documentation": "Amount of cash and cash equivalent, and cash and cash equivalent restricted to withdrawal or usage; attributable to continuing operation. Cash includes, but is not limited to, currency on hand, demand deposit with financial institution, and account with general characteristic of demand deposit. Cash equivalent includes, but is not limited to, short-term, highly liquid investment that is both readily convertible to known amount of cash and so near maturity that it presents insignificant risk of change in value because of change in interest rate." } } }, "auth_ref": [ "r29", "r170", "r174" ] }, "us-gaap_CashCashEquivalentsRestrictedCashAndRestrictedCashEquivalentsPeriodIncreaseDecreaseIncludingExchangeRateEffect": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CashCashEquivalentsRestrictedCashAndRestrictedCashEquivalentsPeriodIncreaseDecreaseIncludingExchangeRateEffect", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "totalLabel": "Net change in cash and cash equivalents", "label": "Cash, Cash Equivalent, Restricted Cash, and Restricted Cash Equivalent, Period Increase (Decrease), Including Exchange Rate Effect and Discontinued Operation", "documentation": "Amount of increase (decrease) in cash and cash equivalent, and cash and cash equivalent restricted to withdrawal or usage; including effect from exchange rate change and including, but not limited to, discontinued operation. Cash includes, but is not limited to, currency on hand, demand deposit with financial institution, and account with general characteristic of demand deposit. Cash equivalent includes, but is not limited to, short-term, highly liquid investment that is both readily convertible to known amount of cash and so near maturity that it presents insignificant risk of change in value because of change in interest rate." } } }, "auth_ref": [ "r0", "r29" ] }, "us-gaap_CashFlowNoncashInvestingAndFinancingActivitiesDisclosureAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CashFlowNoncashInvestingAndFinancingActivitiesDisclosureAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "SUPPLEMENTAL DISCLOSURE OF NON-CASH ACTIVITIES:", "label": "Cash Flow, Noncash Investing and Financing Activities Disclosure [Abstract]" } } }, "auth_ref": [] }, "us-gaap_CertificatesOfDepositMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CertificatesOfDepositMember", "presentation": [ "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Certificates of Deposit [Member]", "label": "Certificates of Deposit [Member]", "documentation": "Short to medium-term investment available at banks and savings and loan institutions where a customer agrees to lend money to the institution for a certain amount of time and is paid a predetermined rate of interest. Certificates of deposit (CD) are typically Federal Deposit Insurance Corporation (FDIC) insured." } } }, "auth_ref": [ "r1143", "r1144", "r1145", "r1146" ] }, "ecd_ChangedPeerGroupFnTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "ChangedPeerGroupFnTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Changed Peer Group, Footnote", "label": "Changed Peer Group, Footnote [Text Block]" } } }, "auth_ref": [ "r1210" ] }, "ecd_ChngInFrValAsOfVstngDtOfPrrYrEqtyAwrdsVstdInCvrdYrMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "ChngInFrValAsOfVstngDtOfPrrYrEqtyAwrdsVstdInCvrdYrMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Change in Fair Value as of Vesting Date of Prior Year Equity Awards Vested in Covered Year", "label": "Change in Fair Value as of Vesting Date of Prior Year Equity Awards Vested in Covered Year [Member]" } } }, "auth_ref": [ "r1207" ] }, "ecd_ChngInFrValOfOutsdngAndUnvstdEqtyAwrdsGrntdInPrrYrsMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "ChngInFrValOfOutsdngAndUnvstdEqtyAwrdsGrntdInPrrYrsMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Year-over-Year Change in Fair Value of Equity Awards Granted in Prior Years That are Outstanding and Unvested", "label": "Year-over-Year Change in Fair Value of Equity Awards Granted in Prior Years That are Outstanding and Unvested [Member]" } } }, "auth_ref": [ "r1205" ] }, "dei_CityAreaCode": { "xbrltype": "normalizedStringItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "CityAreaCode", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "City Area Code", "label": "City Area Code", "documentation": "Area code of city" } } }, "auth_ref": [] }, "us-gaap_ClassOfStockDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ClassOfStockDomain", "presentation": [ "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Class of Stock [Domain]", "label": "Class of Stock [Domain]", "documentation": "Share of stock differentiated by the voting rights the holder receives. Examples include, but are not limited to, common stock, redeemable preferred stock, nonredeemable preferred stock, and convertible stock." } } }, "auth_ref": [ "r56", "r109", "r110", "r139", "r140", "r141", "r142", "r143", "r144", "r178", "r182", "r209", "r213", "r215", "r217", "r226", "r227", "r305", "r368", "r371", "r372", "r373", "r377", "r378", "r409", "r410", "r412", "r413", "r415", "r418", "r421", "r422", "r424", "r425", "r426", "r427", "r428", "r429", "r431", "r434", "r438", "r439", "r440", "r441", "r442", "r444", "r445", "r448", "r449", "r450", "r679", "r790", "r791", "r798", "r799", "r800", "r832", "r891", "r892", "r893", "r894", "r897", "r899", "r900", "r901", "r902", "r903", "r904", "r905", "r906", "r907", "r908", "r909", "r929", "r949", "r967", "r1000", "r1001", "r1002", "r1003", "r1004", "r1263", "r1361", "r1363", "r1372", "r1448", "r1450" ] }, "ecd_CoSelectedMeasureAmt": { "xbrltype": "decimalItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "CoSelectedMeasureAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Company Selected Measure Amount", "label": "Company Selected Measure Amount" } } }, "auth_ref": [ "r1211" ] }, "ecd_CoSelectedMeasureName": { "xbrltype": "normalizedStringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "CoSelectedMeasureName", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Company Selected Measure Name", "label": "Company Selected Measure Name" } } }, "auth_ref": [ "r1211" ] }, "us-gaap_CommitmentsAndContingencies": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CommitmentsAndContingencies", "crdr": "credit", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "COMMITMENTS AND CONTINGENCIES", "label": "Commitments and Contingencies", "documentation": "Represents the caption on the face of the balance sheet to indicate that the entity has entered into (1) purchase or supply arrangements that will require expending a portion of its resources to meet the terms thereof, and (2) is exposed to potential losses or, less frequently, gains, arising from (a) possible claims against a company's resources due to future performance under contract terms, and (b) possible losses or likely gains from uncertainties that will ultimately be resolved when one or more future events that are deemed likely to occur do occur or fail to occur." } } }, "auth_ref": [ "r137", "r790", "r791", "r797", "r838", "r928" ] }, "us-gaap_CommitmentsAndContingenciesDisclosureAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CommitmentsAndContingenciesDisclosureAbstract", "lang": { "en-us": { "role": { "terseLabel": "Commitments and Contingencies Disclosure [Abstract]", "label": "Commitments and Contingencies Disclosure [Abstract]" } } }, "auth_ref": [] }, "us-gaap_CommitmentsAndContingenciesDisclosureTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CommitmentsAndContingenciesDisclosureTextBlock", "presentation": [ "http://www.costco.com/role/CommitmentandContingencies" ], "lang": { "en-us": { "role": { "terseLabel": "Commitments and Contingencies", "label": "Commitments and Contingencies Disclosure [Text Block]", "documentation": "The entire disclosure for commitments and contingencies." } } }, "auth_ref": [ "r360", "r361", "r1011", "r1426", "r1431", "r1432" ] }, "us-gaap_CommonStockDividendsPerShareDeclared": { "xbrltype": "perShareItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CommonStockDividendsPerShareDeclared", "presentation": [ "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Common Stock, Dividends, Per Share, Declared", "label": "Common Stock, Dividends, Per Share, Declared", "documentation": "Aggregate dividends declared during the period for each share of common stock outstanding." } } }, "auth_ref": [ "r448", "r450" ] }, "us-gaap_CommonStockMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CommonStockMember", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity", "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Common Stock", "label": "Common Stock [Member]", "documentation": "Stock that is subordinate to all other stock of the issuer." } } }, "auth_ref": [ "r144", "r445", "r790", "r791", "r800", "r1139", "r1140", "r1141", "r1143", "r1144", "r1145", "r1146", "r1368", "r1369", "r1371", "r1521", "r1616", "r1619" ] }, "us-gaap_CommonStockParOrStatedValuePerShare": { "xbrltype": "perShareItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CommonStockParOrStatedValuePerShare", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheetsParenthetical" ], "lang": { "en-us": { "role": { "terseLabel": "Common stock, par value (in dollars per share)", "label": "Common Stock, Par or Stated Value Per Share", "documentation": "Face amount or stated value per share of common stock." } } }, "auth_ref": [ "r1293", "r1445", "r1555", "r1556", "r1560" ] }, "us-gaap_CommonStockSharesAuthorized": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CommonStockSharesAuthorized", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheetsParenthetical" ], "lang": { "en-us": { "role": { "terseLabel": "Common stock, shares authorized", "label": "Common Stock, Shares Authorized", "documentation": "The maximum number of common shares permitted to be issued by an entity's charter and bylaws." } } }, "auth_ref": [ "r144", "r445", "r790", "r791", "r800", "r929" ] }, "us-gaap_CommonStockSharesIssued": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CommonStockSharesIssued", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheetsParenthetical" ], "lang": { "en-us": { "role": { "terseLabel": "Common stock, shares issued", "label": "Common Stock, Shares, Issued", "documentation": "Total number of common shares of an entity that have been sold or granted to shareholders (includes common shares that were issued, repurchased and remain in the treasury). These shares represent capital invested by the firm's shareholders and owners, and may be all or only a portion of the number of shares authorized. Shares issued include shares outstanding and shares held in the treasury." } } }, "auth_ref": [ "r144", "r445", "r790", "r791", "r800" ] }, "us-gaap_CommonStockSharesOutstanding": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CommonStockSharesOutstanding", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheetsParenthetical", "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Common stock, shares outstanding", "periodStartLabel": "Common stock at beginning of period (shares)", "periodEndLabel": "Common stock at end of period (shares)", "label": "Common Stock, Shares, Outstanding", "documentation": "Number of shares of common stock outstanding. Common stock represent the ownership interest in a corporation." } } }, "auth_ref": [ "r144", "r445", "r790", "r791", "r800", "r929", "r947", "r1443", "r1619", "r1620" ] }, "us-gaap_CommonStockValue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CommonStockValue", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_StockholdersEquity", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Common Stock $.005 par value; 900,000,000 shares authorized; 443,266,000 and 442,237,000 shares issued and outstanding", "label": "Common Stock, Value, Issued", "documentation": "Aggregate par or stated value of issued nonredeemable common stock (or common stock redeemable solely at the option of the issuer). This item includes treasury stock repurchased by the entity. Note: elements for number of nonredeemable common shares, par value and other disclosure concepts are in another section within stockholders' equity." } } }, "auth_ref": [ "r144", "r410", "r417", "r445", "r790", "r791", "r800", "r840", "r1118" ] }, "ecd_CompActuallyPaidVsCoSelectedMeasureTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "CompActuallyPaidVsCoSelectedMeasureTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Compensation Actually Paid vs. Company Selected Measure", "label": "Compensation Actually Paid vs. Company Selected Measure [Text Block]" } } }, "auth_ref": [ "r1216" ] }, "ecd_CompActuallyPaidVsNetIncomeTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "CompActuallyPaidVsNetIncomeTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Compensation Actually Paid vs. Net Income", "label": "Compensation Actually Paid vs. Net Income [Text Block]" } } }, "auth_ref": [ "r1215" ] }, "ecd_CompActuallyPaidVsOtherMeasureTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "CompActuallyPaidVsOtherMeasureTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Compensation Actually Paid vs. Other Measure", "label": "Compensation Actually Paid vs. Other Measure [Text Block]" } } }, "auth_ref": [ "r1217" ] }, "ecd_CompActuallyPaidVsTotalShareholderRtnTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "CompActuallyPaidVsTotalShareholderRtnTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Compensation Actually Paid vs. Total Shareholder Return", "label": "Compensation Actually Paid vs. Total Shareholder Return [Text Block]" } } }, "auth_ref": [ "r1214" ] }, "us-gaap_ComponentsOfDeferredTaxAssetsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ComponentsOfDeferredTaxAssetsAbstract", "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Deferred Tax Assets:", "label": "Components of Deferred Tax Assets [Abstract]" } } }, "auth_ref": [] }, "us-gaap_ComponentsOfDeferredTaxLiabilitiesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ComponentsOfDeferredTaxLiabilitiesAbstract", "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Deferred Tax Liabilities:", "label": "Components of Deferred Tax Liabilities [Abstract]" } } }, "auth_ref": [] }, "us-gaap_ComprehensiveIncomeNetOfTax": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ComprehensiveIncomeNetOfTax", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfComprehensiveIncome": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfComprehensiveIncome" ], "lang": { "en-us": { "role": { "totalLabel": "COMPREHENSIVE INCOME", "label": "Comprehensive Income (Loss), Net of Tax, Attributable to Parent", "documentation": "Amount after tax of increase (decrease) in equity from transactions and other events and circumstances from net income and other comprehensive income, attributable to parent entity. Excludes changes in equity resulting from investments by owners and distributions to owners." } } }, "auth_ref": [ "r9", "r155", "r157", "r162", "r805", "r851", "r852" ] }, "srt_ConsolidationItemsAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "ConsolidationItemsAxis", "presentation": [ "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Consolidation Items [Axis]", "label": "Consolidation Items [Axis]", "documentation": "Information by components, eliminations, non-segment corporate-level activity and reconciling items used in consolidating a parent entity and its subsidiaries or its operating segments." } } }, "auth_ref": [ "r58", "r87", "r88", "r89", "r90", "r91", "r92", "r93", "r94", "r95", "r178", "r179", "r186", "r188", "r224", "r239", "r254", "r255", "r256", "r257", "r258", "r260", "r261", "r262", "r368", "r369", "r370", "r371", "r373", "r374", "r375", "r376", "r377", "r449", "r811", "r1053", "r1054", "r1273", "r1274", "r1436", "r1437" ] }, "srt_ConsolidationItemsDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "ConsolidationItemsDomain", "presentation": [ "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Consolidation Items [Domain]", "label": "Consolidation Items [Domain]", "documentation": "Components, elimination, non-segment corporate-level activity and reconciling items used in consolidating a parent entity and its subsidiaries or its operating segments." } } }, "auth_ref": [ "r58", "r87", "r88", "r89", "r90", "r91", "r92", "r93", "r94", "r95", "r178", "r179", "r186", "r188", "r224", "r239", "r254", "r255", "r256", "r257", "r258", "r260", "r261", "r262", "r368", "r369", "r370", "r371", "r373", "r374", "r375", "r376", "r377", "r449", "r811", "r1053", "r1054", "r1273", "r1274", "r1436", "r1437" ] }, "us-gaap_ConstructionInProgressGross": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ConstructionInProgressGross", "crdr": "debit", "calculation": { "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails": { "parentTag": "us-gaap_PropertyPlantAndEquipmentGross", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Construction in progress", "label": "Construction in Progress, Gross", "documentation": "Amount of structure or a modification to a structure under construction. Includes recently completed structures or modifications to structures that have not been placed into service." } } }, "auth_ref": [ "r1285" ] }, "us-gaap_CostOfGoodsAndServicesSold": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CostOfGoodsAndServicesSold", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfIncome": { "parentTag": "us-gaap_OperatingIncomeLoss", "weight": -1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Merchandise costs", "label": "Cost of Product and Service Sold", "documentation": "The aggregate costs related to goods produced and sold and services rendered by an entity during the reporting period. This excludes costs incurred during the reporting period related to financial services rendered and other revenue generating activities." } } }, "auth_ref": [ "r21", "r22", "r754", "r1036", "r1040", "r1095", "r1348" ] }, "us-gaap_CostOfSalesPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CostOfSalesPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Merchandise Costs", "label": "Cost of Goods and Service [Policy Text Block]", "documentation": "Disclosure of accounting policy for cost of product sold and service rendered." } } }, "auth_ref": [ "r1265" ] }, "us-gaap_CostOfSalesVendorAllowancesPolicy": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CostOfSalesVendorAllowancesPolicy", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Vendor Consideration", "label": "Cost of Sales, Vendor Allowances, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for allowances received from a vendor. The disclosure differentiates between those allowances that are recorded as a reduction in the price of the vendors' products or services (that is, the entity's inventory) and which ultimately will be recorded as a reduction in the entity's cost of sales and those that are not." } } }, "auth_ref": [ "r1453", "r1454", "r1455", "r1456" ] }, "dei_CoverAbstract": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "CoverAbstract", "lang": { "en-us": { "role": { "label": "Cover [Abstract]", "documentation": "Cover page." } } }, "auth_ref": [] }, "us-gaap_CreditAndDebitCardReceivablesAtCarryingValue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CreditAndDebitCardReceivablesAtCarryingValue", "crdr": "debit", "presentation": [ "http://www.costco.com/role/AccountingPoliciesCashandCashEquivalentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Credit and debit card receivables, at carrying value", "label": "Cash Equivalent, Credit and Debit Card Receivables, Carrying Value", "documentation": "Amount due the Entity as a result of customers utilizing point of sale debit or credit cards in exchange transactions with the entity which are short-term, highly liquid investments that are both readily convertible to known amounts of cash and so near their maturity that they present insignificant risk of changes in value because of changes in interest rates. Generally, only investments with original maturities of three months or less qualify under that definition." } } }, "auth_ref": [ "r1284" ] }, "us-gaap_CurrentFederalTaxExpenseBenefit": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CurrentFederalTaxExpenseBenefit", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails": { "parentTag": "us-gaap_FederalIncomeTaxExpenseBenefitContinuingOperations", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Current", "label": "Current Federal Tax Expense (Benefit)", "documentation": "Amount of current federal tax expense (benefit) attributable to income (loss) from continuing operations. Includes, but is not limited to, current national tax expense (benefit) for non-US (United States of America) jurisdiction." } } }, "auth_ref": [ "r1264", "r1359", "r1365", "r1498" ] }, "dei_CurrentFiscalYearEndDate": { "xbrltype": "gMonthDayItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "CurrentFiscalYearEndDate", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Current Fiscal Year End Date", "label": "Current Fiscal Year End Date", "documentation": "End date of current fiscal year in the format --MM-DD." } } }, "auth_ref": [] }, "us-gaap_CurrentForeignTaxExpenseBenefit": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CurrentForeignTaxExpenseBenefit", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails": { "parentTag": "us-gaap_ForeignIncomeTaxExpenseBenefitContinuingOperations", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Current", "label": "Current Foreign Tax Expense (Benefit)", "documentation": "Amount of current foreign income tax expense (benefit) pertaining to income (loss) from continuing operations." } } }, "auth_ref": [ "r1264", "r1359", "r1365" ] }, "cost_CurrentOperatingAndFinanceLeaseLiabilitiesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://www.costco.com/20260830", "localname": "CurrentOperatingAndFinanceLeaseLiabilitiesAbstract", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Current Operating and Finance Lease Liabilities [Abstract]", "label": "Current Operating and Finance Lease Liabilities [Abstract]", "documentation": "Current Operating and Finance Lease Liabilities" } } }, "auth_ref": [] }, "us-gaap_CurrentStateAndLocalTaxExpenseBenefit": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "CurrentStateAndLocalTaxExpenseBenefit", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails": { "parentTag": "us-gaap_StateAndLocalIncomeTaxExpenseBenefitContinuingOperations", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Current", "label": "Current State and Local Tax Expense (Benefit)", "documentation": "Amount of current state and local tax expense (benefit) attributable to income (loss) from continuing operations. Includes, but is not limited to, current regional, territorial, and provincial tax expense (benefit) for non-US (United States of America) jurisdiction." } } }, "auth_ref": [ "r1264", "r1359", "r1365", "r1498" ] }, "cyd_CybersecurityRiskBoardCommitteeOrSubcommitteeResponsibleForOversightTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskBoardCommitteeOrSubcommitteeResponsibleForOversightTextBlock", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Board Committee or Subcommittee Responsible for Oversight [Text Block]" } } }, "auth_ref": [ "r1162", "r1251" ] }, "cyd_CybersecurityRiskBoardOfDirectorsOversightTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskBoardOfDirectorsOversightTextBlock", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Board of Directors Oversight [Text Block]" } } }, "auth_ref": [ "r1162", "r1251" ] }, "cyd_CybersecurityRiskManagementExpertiseOfManagementResponsibleTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskManagementExpertiseOfManagementResponsibleTextBlock", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Management Expertise of Management Responsible [Text Block]" } } }, "auth_ref": [ "r1164", "r1253" ] }, "cyd_CybersecurityRiskManagementPositionsOrCommitteesResponsibleFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskManagementPositionsOrCommitteesResponsibleFlag", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Management Positions or Committees Responsible [Flag]" } } }, "auth_ref": [ "r1164", "r1253" ] }, "cyd_CybersecurityRiskManagementPositionsOrCommitteesResponsibleReportToBoardFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskManagementPositionsOrCommitteesResponsibleReportToBoardFlag", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Management Positions or Committees Responsible Report to Board [Flag]" } } }, "auth_ref": [ "r1166", "r1255" ] }, "cyd_CybersecurityRiskManagementPositionsOrCommitteesResponsibleTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskManagementPositionsOrCommitteesResponsibleTextBlock", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Management Positions or Committees Responsible [Text Block]" } } }, "auth_ref": [ "r1164", "r1253" ] }, "cyd_CybersecurityRiskManagementProcessesForAssessingIdentifyingAndManagingThreatsTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskManagementProcessesForAssessingIdentifyingAndManagingThreatsTextBlock", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Management Processes for Assessing, Identifying, and Managing Threats [Text Block]" } } }, "auth_ref": [ "r1157", "r1246" ] }, "cyd_CybersecurityRiskManagementProcessesIntegratedFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskManagementProcessesIntegratedFlag", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Management Processes Integrated [Flag]" } } }, "auth_ref": [ "r1158", "r1247" ] }, "cyd_CybersecurityRiskManagementProcessesIntegratedTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskManagementProcessesIntegratedTextBlock", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Management Processes Integrated [Text Block]" } } }, "auth_ref": [ "r1158", "r1247" ] }, "cyd_CybersecurityRiskManagementStrategyAndGovernanceAbstract": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskManagementStrategyAndGovernanceAbstract", "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Management, Strategy, and Governance [Abstract]" } } }, "auth_ref": [ "r1156", "r1245" ] }, "cyd_CybersecurityRiskManagementStrategyAndGovernanceLineItems": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskManagementStrategyAndGovernanceLineItems", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Management, Strategy, and Governance [Line Items]" } } }, "auth_ref": [ "r1156", "r1245" ] }, "cyd_CybersecurityRiskManagementStrategyAndGovernanceTable": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskManagementStrategyAndGovernanceTable", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Management, Strategy, and Governance [Table]" } } }, "auth_ref": [ "r1156", "r1245" ] }, "cyd_CybersecurityRiskManagementThirdPartyEngagedFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskManagementThirdPartyEngagedFlag", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Management Third Party Engaged [Flag]" } } }, "auth_ref": [ "r1159", "r1248" ] }, "cyd_CybersecurityRiskMateriallyAffectedOrReasonablyLikelyToMateriallyAffectRegistrantFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskMateriallyAffectedOrReasonablyLikelyToMateriallyAffectRegistrantFlag", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Materially Affected or Reasonably Likely to Materially Affect Registrant [Flag]" } } }, "auth_ref": [ "r1161", "r1250" ] }, "cyd_CybersecurityRiskMateriallyAffectedOrReasonablyLikelyToMateriallyAffectRegistrantTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskMateriallyAffectedOrReasonablyLikelyToMateriallyAffectRegistrantTextBlock", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Materially Affected or Reasonably Likely to Materially Affect Registrant [Text Block]" } } }, "auth_ref": [ "r1161", "r1250" ] }, "cyd_CybersecurityRiskProcessForInformingBoardCommitteeOrSubcommitteeResponsibleForOversightTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskProcessForInformingBoardCommitteeOrSubcommitteeResponsibleForOversightTextBlock", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Process for Informing Board Committee or Subcommittee Responsible for Oversight [Text Block]" } } }, "auth_ref": [ "r1162", "r1251" ] }, "cyd_CybersecurityRiskProcessForInformingManagementOrCommitteesResponsibleTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskProcessForInformingManagementOrCommitteesResponsibleTextBlock", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Process for Informing Management or Committees Responsible [Text Block]" } } }, "auth_ref": [ "r1165", "r1254" ] }, "cyd_CybersecurityRiskRoleOfManagementTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskRoleOfManagementTextBlock", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Role of Management [Text Block]" } } }, "auth_ref": [ "r1163", "r1252" ] }, "cyd_CybersecurityRiskThirdPartyOversightAndIdentificationProcessesFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/cyd/2026", "localname": "CybersecurityRiskThirdPartyOversightAndIdentificationProcessesFlag", "presentation": [ "http://xbrl.sec.gov/cyd/role/CybersecurityRiskManagementAndStrategyDisclosure" ], "lang": { "en-us": { "role": { "label": "Cybersecurity Risk Third Party Oversight and Identification Processes [Flag]" } } }, "auth_ref": [ "r1160", "r1249" ] }, "us-gaap_DebtDisclosureAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DebtDisclosureAbstract", "lang": { "en-us": { "role": { "terseLabel": "Debt Disclosure [Abstract]", "label": "Debt Disclosure [Abstract]" } } }, "auth_ref": [] }, "us-gaap_DebtDisclosureTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DebtDisclosureTextBlock", "presentation": [ "http://www.costco.com/role/Debt" ], "lang": { "en-us": { "role": { "terseLabel": "Debt", "label": "Debt Disclosure [Text Block]", "documentation": "The entire disclosure for information about short-term and long-term debt arrangements, which includes amounts of borrowings under each line of credit, note payable, commercial paper issue, bonds indenture, debenture issue, own-share lending arrangements and any other contractual agreement to repay funds, and about the underlying arrangements, rationale for a classification as long-term, including repayment terms, interest rates, collateral provided, restrictions on use of assets and activities, whether or not in compliance with debt covenants, and other matters important to users of the financial statements, such as the effects of refinancing and noncompliance with debt covenants." } } }, "auth_ref": [ "r35", "r115", "r116", "r124", "r125", "r128", "r130", "r131", "r133", "r134", "r178", "r180", "r352", "r353", "r354", "r355", "r356", "r366", "r367", "r379", "r385", "r386", "r387", "r388", "r389", "r390", "r395", "r402", "r403", "r405", "r631", "r690", "r790", "r791", "r796" ] }, "us-gaap_DebtInstrumentCarryingAmount": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DebtInstrumentCarryingAmount", "crdr": "credit", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails", "http://www.costco.com/role/DebtScheduleOfLongTermDebtMaturitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Long-Term Debt, Gross", "label": "Long-Term Debt, Gross", "documentation": "Amount, before unamortized (discount) premium and debt issuance costs, of long-term debt. Includes, but is not limited to, notes payable, bonds payable, commercial loans, mortgage loans, convertible debt, subordinated debt and other types of debt." } } }, "auth_ref": [ "r406", "r1555", "r1556", "r1558" ] }, "us-gaap_DebtInstrumentInterestRateStatedPercentage": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DebtInstrumentInterestRateStatedPercentage", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails", "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Debt instrument, interest rate, stated percentage", "label": "Debt Instrument, Interest Rate, Stated Percentage", "documentation": "Contractual interest rate for funds borrowed, under the debt agreement." } } }, "auth_ref": [ "r116", "r128", "r381", "r790", "r791", "r796" ] }, "us-gaap_DebtInstrumentLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DebtInstrumentLineItems", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails", "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Debt Instrument [Line Items]", "label": "Debt Instrument [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r116", "r128", "r129", "r130", "r131", "r132", "r134", "r380", "r381", "r382", "r383", "r384", "r386", "r391", "r392", "r393", "r394", "r396", "r397", "r398", "r399", "r400", "r401", "r404", "r439", "r631", "r790", "r791", "r796", "r811", "r1065", "r1066", "r1067", "r1068", "r1069", "r1116", "r1359", "r1360", "r1362", "r1367", "r1545", "r1546" ] }, "us-gaap_DebtInstrumentRedemptionPricePercentage": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DebtInstrumentRedemptionPricePercentage", "presentation": [ "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Debt Instrument, Redemption Price, Percentage", "label": "Debt Instrument, Redemption Price, Percentage", "documentation": "Percentage price of original principal amount of debt at which debt can be redeemed by the issuer." } } }, "auth_ref": [ "r41" ] }, "us-gaap_DebtInstrumentTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DebtInstrumentTable", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails", "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Long-term Debt Instruments [Table]", "label": "Schedule of Long-Term Debt Instruments [Table]", "documentation": "Disclosure of information about long-term debt instrument or arrangement." } } }, "auth_ref": [ "r18", "r45", "r46", "r47", "r116", "r128", "r129", "r130", "r131", "r132", "r134", "r380", "r381", "r382", "r383", "r384", "r386", "r391", "r392", "r393", "r394", "r396", "r397", "r398", "r399", "r400", "r401", "r404", "r439", "r631", "r790", "r791", "r796", "r811", "r1065", "r1066", "r1067", "r1068", "r1069", "r1116", "r1359", "r1360", "r1362", "r1367", "r1545", "r1546" ] }, "us-gaap_DebtSecuritiesAvailableForSaleAndHeldToMaturityAmortizedCostBeforeAllowanceForCreditLoss": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DebtSecuritiesAvailableForSaleAndHeldToMaturityAmortizedCostBeforeAllowanceForCreditLoss", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Total short-term investments, cost basis", "label": "Debt Securities, Available-for-Sale and Held-to-Maturity, Amortized Cost, before Allowance for Credit Loss", "documentation": "Amortized cost, before allowance for credit loss, of investment in debt security measured at amortized cost (held-to-maturity) and investment in debt security measured at fair value with change in fair value recognized in other comprehensive income (available-for-sale)." } } }, "auth_ref": [ "r1393", "r1398" ] }, "us-gaap_DeferredFederalIncomeTaxExpenseBenefit": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredFederalIncomeTaxExpenseBenefit", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails": { "parentTag": "us-gaap_FederalIncomeTaxExpenseBenefitContinuingOperations", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Deferred", "label": "Deferred Federal Income Tax Expense (Benefit)", "documentation": "Amount of deferred federal tax expense (benefit) attributable to income (loss) from continuing operations. Includes, but is not limited to, deferred national tax expense (benefit) for non-US (United States of America) jurisdiction." } } }, "auth_ref": [ "r1359", "r1365", "r1497", "r1498" ] }, "us-gaap_DeferredFinanceCostsNet": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredFinanceCostsNet", "crdr": "debit", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Less unamortized debt discounts and issuance costs", "label": "Debt Issuance Costs, Net", "documentation": "Amount, after accumulated amortization, of debt issuance costs. Includes, but is not limited to, legal, accounting, underwriting, printing, and registration costs." } } }, "auth_ref": [ "r1439", "r1544", "r1545", "r1546" ] }, "us-gaap_DeferredForeignIncomeTaxExpenseBenefit": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredForeignIncomeTaxExpenseBenefit", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails": { "parentTag": "us-gaap_ForeignIncomeTaxExpenseBenefitContinuingOperations", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Deferred", "label": "Deferred Foreign Income Tax Expense (Benefit)", "documentation": "Amount of deferred foreign income tax expense (benefit) pertaining to income (loss) from continuing operations." } } }, "auth_ref": [ "r1359", "r1365", "r1497" ] }, "us-gaap_DeferredIncomeTaxLiabilities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredIncomeTaxLiabilities", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredTaxLiabilities", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Total deferred tax liabilities", "label": "Deferred Tax Liabilities, Gross", "documentation": "Amount of deferred tax liability attributable to taxable temporary differences." } } }, "auth_ref": [ "r565" ] }, "us-gaap_DeferredIncomeTaxLiabilitiesNet": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredIncomeTaxLiabilitiesNet", "crdr": "credit", "presentation": [ "http://www.costco.com/role/IncomeTaxesDeferredTaxAssetsandLiabilitiesNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Deferred Tax Liabilities", "label": "Deferred Income Tax Liabilities, Net", "documentation": "Amount, after deferred tax asset, of deferred tax liability attributable to taxable differences with jurisdictional netting." } } }, "auth_ref": [ "r138", "r539", "r540", "r790", "r791", "r795", "r837" ] }, "us-gaap_DeferredRevenueCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredRevenueCurrent", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_LiabilitiesCurrent", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/AccountingPoliciesRevenueRecognitionDetails", "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Deferred membership fees", "label": "Deferred Revenue, Current", "documentation": "Amount of deferred income and obligation to transfer product and service to customer for which consideration has been received or is receivable, classified as current." } } }, "auth_ref": [ "r1288" ] }, "us-gaap_DeferredStateAndLocalIncomeTaxExpenseBenefit": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredStateAndLocalIncomeTaxExpenseBenefit", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails": { "parentTag": "us-gaap_StateAndLocalIncomeTaxExpenseBenefitContinuingOperations", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Deferred", "label": "Deferred State and Local Income Tax Expense (Benefit)", "documentation": "Amount of deferred state and local tax expense (benefit) attributable to income (loss) from continuing operations. Includes, but is not limited to, deferred regional, territorial, and provincial tax expense (benefit) for non-US (United States of America) jurisdiction." } } }, "auth_ref": [ "r1359", "r1365", "r1497", "r1498" ] }, "us-gaap_DeferredTaxAssetsDeferredIncome": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxAssetsDeferredIncome", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredTaxAssetsGross", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Deferred Income/membership fees", "label": "Deferred Tax Assets, Deferred Income", "documentation": "Amount before allocation of valuation allowances of deferred tax asset attributable to deductible temporary differences from deferred income." } } }, "auth_ref": [ "r1495" ] }, "us-gaap_DeferredTaxAssetsGross": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxAssetsGross", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredTaxAssetsNet", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Total deferred tax assets", "label": "Deferred Tax Assets, Gross", "documentation": "Amount before allocation of valuation allowances of deferred tax asset attributable to deductible temporary differences and carryforwards." } } }, "auth_ref": [ "r566" ] }, "us-gaap_DeferredTaxAssetsLiabilitiesNet": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxAssetsLiabilitiesNet", "crdr": "debit", "presentation": [ "http://www.costco.com/role/IncomeTaxesDeferredTaxAssetsandLiabilitiesNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Deferred Tax Assets, Net", "label": "Deferred Tax Assets, Net", "documentation": "Amount, after allocation of valuation allowances and deferred tax liability, of deferred tax asset attributable to deductible differences and carryforwards, without jurisdictional netting." } } }, "auth_ref": [ "r1490" ] }, "us-gaap_DeferredTaxAssetsNet": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxAssetsNet", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredTaxLiabilities", "weight": -1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Total net deferred tax assets", "label": "Deferred Tax Assets, Net of Valuation Allowance", "documentation": "Amount after allocation of valuation allowances of deferred tax asset attributable to deductible temporary differences and carryforwards." } } }, "auth_ref": [ "r1490" ] }, "cost_DeferredTaxAssetsOperatingLeaseLiabilities": { "xbrltype": "monetaryItemType", "nsuri": "http://www.costco.com/20260830", "localname": "DeferredTaxAssetsOperatingLeaseLiabilities", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredTaxAssetsGross", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Operating lease liabilities", "label": "DeferredTaxAssetsOperatingLeaseLiabilities", "documentation": "DeferredTaxAssetsOperatingLeaseLiabilities" } } }, "auth_ref": [] }, "us-gaap_DeferredTaxAssetsTaxCreditCarryforwardsForeign": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxAssetsTaxCreditCarryforwardsForeign", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredTaxAssetsGross", "weight": 1.0, "order": 5.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Foreign tax credit carry forward", "label": "Deferred Tax Assets, Tax Credit Carryforwards, Foreign", "documentation": "Amount before allocation of valuation allowances of deferred tax asset attributable to deductible foreign tax credit carryforwards." } } }, "auth_ref": [ "r1495" ] }, "us-gaap_DeferredTaxAssetsTaxDeferredExpenseCompensationAndBenefits": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxAssetsTaxDeferredExpenseCompensationAndBenefits", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredTaxAssetsGross", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Equity compensation", "label": "Deferred Tax Assets, Tax Deferred Expense, Compensation and Benefits", "documentation": "Amount before allocation of valuation allowances of deferred tax asset attributable to deductible temporary differences from compensation and benefits costs." } } }, "auth_ref": [ "r1495" ] }, "us-gaap_DeferredTaxAssetsTaxDeferredExpenseReservesAndAccrualsAccruedLiabilities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxAssetsTaxDeferredExpenseReservesAndAccrualsAccruedLiabilities", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredTaxAssetsGross", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Accrued liabilities and reserves", "label": "Deferred Tax Assets, Tax Deferred Expense, Reserves and Accruals, Accrued Liabilities", "documentation": "Amount before allocation of valuation allowances of deferred tax asset attributable to deductible temporary differences from accrued liabilities." } } }, "auth_ref": [ "r1495" ] }, "us-gaap_DeferredTaxLiabilities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxLiabilities", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Net deferred tax liabilities", "label": "Deferred Tax Liabilities, Net", "documentation": "Amount, after deferred tax asset, of deferred tax liability attributable to taxable differences without jurisdictional netting." } } }, "auth_ref": [ "r1490" ] }, "us-gaap_DeferredTaxLiabilitiesDeferredExpenseCapitalizedInventoryCosts": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxLiabilitiesDeferredExpenseCapitalizedInventoryCosts", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredIncomeTaxLiabilities", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Merchandise inventories", "label": "Deferred Tax Liabilities, Inventory", "documentation": "Amount of deferred tax consequences attributable to taxable temporary differences derived from inventory." } } }, "auth_ref": [ "r1495" ] }, "us-gaap_DeferredTaxLiabilitiesOther": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxLiabilitiesOther", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredIncomeTaxLiabilities", "weight": 1.0, "order": 5.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Other", "label": "Deferred Tax Liabilities, Other", "documentation": "Amount of deferred tax liability attributable to taxable temporary differences classified as other." } } }, "auth_ref": [ "r1495" ] }, "us-gaap_DeferredTaxLiabilitiesPropertyPlantAndEquipment": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxLiabilitiesPropertyPlantAndEquipment", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredIncomeTaxLiabilities", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Property and equipment", "label": "Deferred Tax Liabilities, Property, Plant and Equipment", "documentation": "Amount of deferred tax liability attributable to taxable temporary differences from property, plant, and equipment." } } }, "auth_ref": [ "r1495" ] }, "cost_DeferredTaxLiabilitiesRightOfUseAssets": { "xbrltype": "monetaryItemType", "nsuri": "http://www.costco.com/20260830", "localname": "DeferredTaxLiabilitiesRightOfUseAssets", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredIncomeTaxLiabilities", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Operating lease right-of-use assets", "label": "DeferredTaxLiabilitiesRightOfUseAssets", "documentation": "DeferredTaxLiabilitiesRightOfUseAssets" } } }, "auth_ref": [] }, "us-gaap_DeferredTaxLiabilitiesUndistributedForeignEarnings": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DeferredTaxLiabilitiesUndistributedForeignEarnings", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredIncomeTaxLiabilities", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Foreign branch deferreds", "label": "Deferred Tax Liabilities, Undistributed Foreign Earnings", "documentation": "Amount of deferred tax liability attributable to taxable temporary differences from undistributed earnings of subsidiary and other recognized entity not within country of domicile. Includes, but is not limited to, other basis differences." } } }, "auth_ref": [ "r1495" ] }, "us-gaap_DefinedContributionPlanCostRecognized": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DefinedContributionPlanCostRecognized", "crdr": "debit", "presentation": [ "http://www.costco.com/role/AccountingPoliciesRetirementPlansDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Defined contribution plan, cost recognized", "label": "Defined Contribution Plan, Cost", "documentation": "Amount of cost for defined contribution plan." } } }, "auth_ref": [ "r482" ] }, "us-gaap_DepreciationDepletionAndAmortization": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DepreciationDepletionAndAmortization", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInOperatingActivities", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Depreciation and amortization", "label": "Depreciation, Depletion and Amortization", "documentation": "The aggregate expense recognized in the current period that allocates the cost of tangible assets, intangible assets, or depleting assets to periods that benefit from use of the assets." } } }, "auth_ref": [ "r4", "r165", "r224", "r242", "r260", "r1035", "r1053", "r1054", "r1418", "r1419", "r1423", "r1425" ] }, "us-gaap_DerivativeContractTypeDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DerivativeContractTypeDomain", "presentation": [ "http://www.costco.com/role/AccountingPoliciesDerivativesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Derivative, Name [Domain]", "label": "Derivative Contract [Domain]", "documentation": "Financial instrument or contract with one or more underlyings, notional amount or payment provision or both, and the contract can be net settled by means outside the contract or delivery of an asset." } } }, "auth_ref": [ "r164", "r595", "r596", "r597", "r598", "r599", "r600", "r601", "r602", "r603", "r604", "r605", "r606", "r607", "r608", "r609", "r610", "r611", "r612", "r613", "r614", "r615", "r616", "r617", "r618", "r732", "r917", "r920", "r934", "r935", "r936", "r937", "r938", "r939", "r940", "r942", "r943", "r944", "r945", "r955", "r956", "r957", "r958", "r961", "r962", "r963", "r964", "r984", "r985", "r988", "r989", "r1032", "r1033", "r1034", "r1102", "r1103", "r1120", "r1139", "r1141", "r1298", "r1299", "r1300", "r1301", "r1302", "r1303", "r1304", "r1305", "r1306", "r1515", "r1516", "r1517", "r1518", "r1528", "r1529", "r1530", "r1531", "r1532", "r1533", "r1535", "r1536" ] }, "us-gaap_DerivativeInstrumentRiskAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DerivativeInstrumentRiskAxis", "presentation": [ "http://www.costco.com/role/AccountingPoliciesDerivativesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Derivative, by Nature", "label": "Derivative Instrument [Axis]", "documentation": "Information by type of derivative contract." } } }, "auth_ref": [ "r164", "r595", "r596", "r597", "r598", "r599", "r600", "r601", "r602", "r603", "r604", "r605", "r606", "r607", "r608", "r609", "r610", "r611", "r612", "r613", "r614", "r615", "r616", "r617", "r618", "r732", "r917", "r920", "r934", "r935", "r936", "r937", "r938", "r939", "r940", "r942", "r943", "r944", "r945", "r955", "r956", "r957", "r958", "r961", "r962", "r963", "r964", "r984", "r985", "r988", "r989", "r1032", "r1033", "r1034", "r1102", "r1103", "r1120", "r1139", "r1141", "r1298", "r1299", "r1300", "r1301", "r1302", "r1303", "r1304", "r1305", "r1306", "r1515", "r1516", "r1517", "r1518", "r1528", "r1529", "r1530", "r1531", "r1532", "r1533", "r1535", "r1536" ] }, "us-gaap_DerivativeLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DerivativeLineItems", "presentation": [ "http://www.costco.com/role/AccountingPoliciesDerivativesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Derivative [Line Items]", "label": "Derivative [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r437", "r1514", "r1519" ] }, "us-gaap_DerivativeNotionalAmount": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DerivativeNotionalAmount", "presentation": [ "http://www.costco.com/role/AccountingPoliciesDerivativesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Derivative, Notional Amount", "label": "Derivative, Notional Amount", "documentation": "Nominal or face amount used to calculate payment on derivative." } } }, "auth_ref": [ "r1102", "r1500", "r1501" ] }, "us-gaap_DerivativeTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DerivativeTable", "presentation": [ "http://www.costco.com/role/AccountingPoliciesDerivativesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Derivative [Table]", "label": "Derivative [Table]", "documentation": "Disclosure of information about derivative instrument or group of derivative instruments, including, but not limited to, type of derivative instrument, risk being hedged, notional amount, hedge designation, related hedged item, inception date, and maturity date." } } }, "auth_ref": [ "r437", "r1514", "r1519" ] }, "us-gaap_DerivativesPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DerivativesPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Derivatives", "label": "Derivatives, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for its derivative instruments and hedging activities." } } }, "auth_ref": [ "r175", "r178", "r187", "r594", "r626", "r627", "r628", "r629", "r630", "r632", "r636" ] }, "us-gaap_DisaggregationOfRevenueTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DisaggregationOfRevenueTable", "presentation": [ "http://www.costco.com/role/AccountingPoliciesRevenueRecognitionDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Disaggregation of Revenue [Table]", "label": "Disaggregation of Revenue [Table]", "documentation": "Disclosure of information about disaggregation of revenue into categories depicting how nature, amount, timing, and uncertainty of revenue and cash flows are affected by economic factor." } } }, "auth_ref": [ "r465", "r466", "r1072", "r1073", "r1074", "r1075", "r1076", "r1077", "r1078" ] }, "us-gaap_DisaggregationOfRevenueTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DisaggregationOfRevenueTableTextBlock", "presentation": [ "http://www.costco.com/role/SegmentReportingTables" ], "lang": { "en-us": { "role": { "terseLabel": "Revenue from External Customers by Products and Services", "label": "Disaggregation of Revenue [Table Text Block]", "documentation": "Tabular disclosure of disaggregation of revenue into categories depicting how nature, amount, timing, and uncertainty of revenue and cash flows are affected by economic factor." } } }, "auth_ref": [ "r1451" ] }, "us-gaap_DisclosureOfCompensationRelatedCostsShareBasedPaymentsTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DisclosureOfCompensationRelatedCostsShareBasedPaymentsTextBlock", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlans" ], "lang": { "en-us": { "role": { "terseLabel": "Stock-Based Compensation Plans", "label": "Share-Based Payment Arrangement [Text Block]", "documentation": "The entire disclosure for share-based payment arrangement." } } }, "auth_ref": [ "r484", "r489", "r520", "r521", "r523", "r1085" ] }, "us-gaap_DisclosureOfCompensationRelatedCostsSharebasedPaymentsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DisclosureOfCompensationRelatedCostsSharebasedPaymentsAbstract", "lang": { "en-us": { "role": { "terseLabel": "Share-based Payment Arrangement [Abstract]", "label": "Share-Based Payment Arrangement [Abstract]" } } }, "auth_ref": [] }, "cost_DisclosureofSupplementalBalanceSheetInformationRelatedtoLeasesTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://www.costco.com/20260830", "localname": "DisclosureofSupplementalBalanceSheetInformationRelatedtoLeasesTableTextBlock", "presentation": [ "http://www.costco.com/role/LeasesTables" ], "lang": { "en-us": { "role": { "terseLabel": "DisclosureofSupplementalBalanceSheetInformationRelatedtoLeases", "label": "DisclosureofSupplementalBalanceSheetInformationRelatedtoLeases [Table Text Block]", "documentation": "DisclosureofSupplementalBalanceSheetInformationRelatedtoLeases" } } }, "auth_ref": [] }, "us-gaap_Dividends": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "Dividends", "crdr": "debit", "presentation": [ "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Dividends", "label": "Dividends", "documentation": "Amount of paid and unpaid cash, stock, and paid-in-kind (PIK) dividends declared, for example, but not limited to, common and preferred stock." } } }, "auth_ref": [ "r1447", "r1449" ] }, "us-gaap_DividendsAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DividendsAxis", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails", "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Dividends [Axis]", "label": "Dividends [Axis]", "documentation": "Information by event wherein earnings are distributed to shareholder." } } }, "auth_ref": [ "r1442", "r1447", "r1449" ] }, "us-gaap_DividendsCash": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DividendsCash", "crdr": "debit", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Cash dividends declared", "label": "Dividends, Cash", "documentation": "Amount of paid and unpaid cash dividends declared for classes of stock, for example, but not limited to, common and preferred." } } }, "auth_ref": [ "r1447", "r1449" ] }, "us-gaap_DividendsCommonStockCash": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DividendsCommonStockCash", "crdr": "debit", "presentation": [ "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Dividends, Common Stock, Cash", "label": "Dividends, Common Stock, Cash", "documentation": "Amount of paid and unpaid common stock dividends declared with the form of settlement in cash." } } }, "auth_ref": [ "r1447", "r1449" ] }, "us-gaap_DividendsDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DividendsDomain", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails", "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Dividends [Domain]", "label": "Dividends [Domain]", "documentation": "Event wherein earnings are distributed to shareholder." } } }, "auth_ref": [ "r1442", "r1447", "r1449" ] }, "us-gaap_DividendsPayableLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DividendsPayableLineItems", "presentation": [ "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Dividends Payable [Line Items]", "label": "Dividends Payable [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r1357", "r1442" ] }, "us-gaap_DividendsPayableTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "DividendsPayableTable", "presentation": [ "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Dividends Payable [Table]", "label": "Dividends Payable [Table]", "documentation": "Disclosure of information about distribution of earnings to shareholder declared but not yet paid. Includes, but is not limited to, total amount and amount per share of distribution, declaration date, and date to be paid." } } }, "auth_ref": [ "r1357", "r1442" ] }, "dei_DocumentAnnualReport": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "DocumentAnnualReport", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Document Annual Report", "label": "Document Annual Report", "documentation": "Boolean flag that is true only for a form used as an annual report." } } }, "auth_ref": [ "r1153", "r1154", "r1177" ] }, "dei_DocumentFinStmtErrorCorrectionFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "DocumentFinStmtErrorCorrectionFlag", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Document Financial Statement Error Correction [Flag]", "label": "Document Financial Statement Error Correction [Flag]", "documentation": "Indicates whether any of the financial statement period in the filing include a restatement due to error correction." } } }, "auth_ref": [ "r1153", "r1154", "r1177", "r1220" ] }, "dei_DocumentFiscalPeriodFocus": { "xbrltype": "fiscalPeriodItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "DocumentFiscalPeriodFocus", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Document Fiscal Period Focus", "label": "Document Fiscal Period Focus", "documentation": "Fiscal period values are FY, Q1, Q2, and Q3. 1st, 2nd and 3rd quarter 10-Q or 10-QT statements have value Q1, Q2, and Q3 respectively, with 10-K, 10-KT or other fiscal year statements having FY." } } }, "auth_ref": [] }, "dei_DocumentFiscalYearFocus": { "xbrltype": "gYearItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "DocumentFiscalYearFocus", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Document Fiscal Year Focus", "label": "Document Fiscal Year Focus", "documentation": "This is focus fiscal year of the document report in YYYY format. For a 2006 annual report, which may also provide financial information from prior periods, fiscal 2006 should be given as the fiscal year focus. Example: 2006." } } }, "auth_ref": [] }, "dei_DocumentPeriodEndDate": { "xbrltype": "dateItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "DocumentPeriodEndDate", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Document Period End Date", "label": "Document Period End Date", "documentation": "For the EDGAR submission types of Form 8-K: the date of the report, the date of the earliest event reported; for the EDGAR submission types of Form N-1A: the filing date; for all other submission types: the end of the reporting or transition period. The format of the date is YYYY-MM-DD." } } }, "auth_ref": [] }, "dei_DocumentTransitionReport": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "DocumentTransitionReport", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Document Transition Report", "label": "Document Transition Report", "documentation": "Boolean flag that is true only for a form used as a transition report." } } }, "auth_ref": [ "r1198" ] }, "dei_DocumentType": { "xbrltype": "submissionTypeItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "DocumentType", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Document Type", "label": "Document Type", "documentation": "The type of document being provided (such as 10-K, 10-Q, 485BPOS, etc). The document type is limited to the same value as the supporting SEC submission type, or the word 'Other'." } } }, "auth_ref": [] }, "dei_DocumentsIncorporatedByReferenceTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "DocumentsIncorporatedByReferenceTextBlock", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Documents Incorporated by Reference", "label": "Documents Incorporated by Reference [Text Block]", "documentation": "Documents incorporated by reference." } } }, "auth_ref": [ "r1151" ] }, "ecd_DvddsOrOthrErngsPdOnEqtyAwrdsNtOthrwsRflctdInTtlCompForCvrdYrMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "DvddsOrOthrErngsPdOnEqtyAwrdsNtOthrwsRflctdInTtlCompForCvrdYrMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Dividends or Other Earnings Paid on Equity Awards not Otherwise Reflected in Total Compensation for Covered Year", "label": "Dividends or Other Earnings Paid on Equity Awards not Otherwise Reflected in Total Compensation for Covered Year [Member]" } } }, "auth_ref": [ "r1209" ] }, "country_ES": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "ES", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "SPAIN", "label": "SPAIN" } } }, "auth_ref": [] }, "us-gaap_EarningsPerShareAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EarningsPerShareAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome" ], "lang": { "en-us": { "role": { "terseLabel": "NET INCOME PER COMMON SHARE:", "label": "Earnings Per Share [Abstract]" } } }, "auth_ref": [] }, "us-gaap_EarningsPerShareBasic": { "xbrltype": "perShareItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EarningsPerShareBasic", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome" ], "lang": { "en-us": { "role": { "terseLabel": "Basic", "label": "Earnings Per Share, Basic", "documentation": "The amount of net income (loss) for the period per each share of common stock or unit outstanding during the reporting period." } } }, "auth_ref": [ "r100", "r163", "r192", "r194", "r195", "r196", "r197", "r198", "r199", "r200", "r201", "r207", "r209", "r215", "r216", "r217", "r223", "r343", "r408", "r469", "r524", "r584", "r589", "r651", "r652", "r806", "r853", "r1044" ] }, "us-gaap_EarningsPerShareDiluted": { "xbrltype": "perShareItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EarningsPerShareDiluted", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome" ], "lang": { "en-us": { "role": { "terseLabel": "Diluted", "label": "Earnings Per Share, Diluted", "documentation": "The amount of net income (loss) for the period available to each share of common stock or common unit outstanding during the reporting period and to each share or unit that would have been outstanding assuming the issuance of common shares or units for all dilutive potential common shares or units outstanding during the reporting period." } } }, "auth_ref": [ "r100", "r163", "r192", "r194", "r195", "r196", "r197", "r198", "r199", "r200", "r201", "r209", "r215", "r216", "r217", "r223", "r343", "r408", "r469", "r524", "r584", "r589", "r651", "r652", "r806", "r853", "r1044" ] }, "us-gaap_EarningsPerSharePolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EarningsPerSharePolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Net Income per Common Share", "label": "Earnings Per Share, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for computing basic and diluted earnings or loss per share for each class of common stock and participating security. Addresses all significant policy factors, including any antidilutive items that have been excluded from the computation and takes into account stock dividends, splits and reverse splits that occur after the balance sheet date of the latest reporting period but before the issuance of the financial statements." } } }, "auth_ref": [ "r219" ] }, "us-gaap_EarningsPerShareTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EarningsPerShareTextBlock", "presentation": [ "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShare" ], "lang": { "en-us": { "role": { "terseLabel": "Net Income Per Common and Common Equivalent Share", "label": "Earnings Per Share [Text Block]", "documentation": "The entire disclosure for earnings per share." } } }, "auth_ref": [ "r206", "r218", "r220", "r221", "r222", "r454" ] }, "us-gaap_EffectOfExchangeRateOnCashCashEquivalentsRestrictedCashAndRestrictedCashEquivalents": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectOfExchangeRateOnCashCashEquivalentsRestrictedCashAndRestrictedCashEquivalents", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_CashCashEquivalentsRestrictedCashAndRestrictedCashEquivalentsPeriodIncreaseDecreaseIncludingExchangeRateEffect", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "EFFECT OF EXCHANGE RATE CHANGES ON CASH AND CASH EQUIVALENTS", "label": "Effect of Exchange Rate on Cash, Cash Equivalent, Restricted Cash, and Restricted Cash Equivalent, Continuing Operation", "documentation": "Amount of increase (decrease) from effect of exchange rate change on cash and cash equivalent, and cash and cash equivalent restricted to withdrawal or usage; held in foreign currency; attributable to continuing operation. Cash includes, but is not limited to, currency on hand, demand deposit with financial institution, and account with general characteristic of demand deposit. Cash equivalent includes, but is not limited to, short-term, highly liquid investment that is both readily convertible to known amount of cash and so near maturity that it presents insignificant risk of change in value because of change in interest rate." } } }, "auth_ref": [ "r682" ] }, "us-gaap_EffectiveIncomeTaxRateContinuingOperations": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateContinuingOperations", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": null, "weight": null, "order": null, "root": true }, "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "totalLabel": "Total", "label": "Effective Income Tax Rate Reconciliation, Percent", "documentation": "Percentage of current income tax expense (benefit) and deferred income tax expense (benefit) pertaining to continuing operations." } } }, "auth_ref": [ "r544", "r1087" ] }, "us-gaap_EffectiveIncomeTaxRateContinuingOperationsTaxRateReconciliationAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateContinuingOperationsTaxRateReconciliationAbstract", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "terseLabel": "Effective Income Tax Rate Reconciliation, Percent [Abstract]", "label": "Effective Income Tax Rate Reconciliation, Percent [Abstract]" } } }, "auth_ref": [] }, "us-gaap_EffectiveIncomeTaxRateReconciliationAtFederalStatutoryIncomeTaxRate": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationAtFederalStatutoryIncomeTaxRate", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 1.0 }, "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "terseLabel": "Federal taxes at statutory rate", "label": "Effective Income Tax Rate Reconciliation, at Federal Statutory Income Tax Rate, Percent", "documentation": "Percentage of domestic federal statutory tax rate applicable to pretax income (loss)." } } }, "auth_ref": [ "r178", "r185", "r544", "r575", "r1087" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationChangeInDeferredTaxAssetsValuationAllowance": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationChangeInDeferredTaxAssetsValuationAllowance", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 7.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Changes in valuation allowance", "label": "Effective Income Tax Rate Reconciliation, Change in Deferred Tax Assets Valuation Allowance, Percent", "documentation": "Percentage of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to changes in the valuation allowance for deferred tax assets." } } }, "auth_ref": [ "r549", "r1087", "r1359", "r1366", "r1487" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationCrossBorderTaxEffectAmount": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationCrossBorderTaxEffectAmount", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Effect of cross-border tax laws", "label": "Effective Income Tax Rate Reconciliation, Cross-Border Tax Effect, Amount", "documentation": "Amount of reported income tax expense (benefit) from difference to expected income tax expense (benefit) computed by applying statutory federal (national) income tax rate to pretax income (loss) from continuing operation, attributable to cross-border tax law." } } }, "auth_ref": [ "r548", "r552" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationCrossBorderTaxEffectPercent": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationCrossBorderTaxEffectPercent", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Effect of cross-border tax laws", "label": "Effective Income Tax Rate Reconciliation, Cross-Border Tax Effect, Percent", "documentation": "Percentage of reported income tax expense (benefit) from difference to expected income tax expense (benefit) computed by applying statutory federal (national) income tax rate to pretax income (loss) from continuing operation, attributable to cross-border tax law." } } }, "auth_ref": [ "r548", "r552" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationDeductionsEmployeeStockOwnershipPlanDividends": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationDeductionsEmployeeStockOwnershipPlanDividends", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": -1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Employee stock ownership plan (ESOP) (percent)", "label": "Effective Income Tax Rate Reconciliation, Deduction, Employee Stock Ownership Plan Dividend, Percent", "documentation": "Percentage of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to deduction for dividend paid to employee stock ownership plan." } } }, "auth_ref": [ "r1359", "r1366", "r1487", "r1489" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationForeignIncomeTaxRateDifferential": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationForeignIncomeTaxRateDifferential", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 3.0 }, "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "terseLabel": "Foreign taxes, net", "label": "Effective Income Tax Rate Reconciliation, Foreign Income Tax Rate Differential, Percent", "documentation": "Percentage of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations applicable to statutory income tax expense (benefit) outside of the country of domicile." } } }, "auth_ref": [ "r547", "r553", "r1087", "r1359", "r1366", "r1487" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationLineItems", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Effective Income Tax Rate Reconciliation [Line Items]", "label": "Effective Income Tax Rate Reconciliation [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r544", "r553", "r1087" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationNondeductibleExpense": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationNondeductibleExpense", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 8.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Changes in valuation allowance", "label": "Effective Income Tax Rate Reconciliation, Nondeductible Expense, Percent", "documentation": "Percentage of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to nondeductible expenses." } } }, "auth_ref": [ "r550", "r552", "r1359", "r1366", "r1487" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationOtherAdjustments": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationOtherAdjustments", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 5.0 }, "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 10.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "terseLabel": "Other", "label": "Effective Income Tax Rate Reconciliation, Other Adjustments, Percent", "documentation": "Percentage of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to other adjustments." } } }, "auth_ref": [ "r1087", "r1359", "r1366", "r1487", "r1489" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationShareBasedCompensationExcessTaxBenefitAmount": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationShareBasedCompensationExcessTaxBenefitAmount", "crdr": "debit", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Stock compensation tax benefits", "label": "Effective Income Tax Rate Reconciliation, Tax Expense (Benefit), Share-Based Payment Arrangement, Amount", "documentation": "Amount of difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying domestic federal statutory income tax rate to pretax income (loss) from continuing operation, attributable to expense for award under share-based payment arrangement. Excludes expense determined to be nondeductible upon grant or after for award under share-based payment arrangement." } } }, "auth_ref": [ "r1484", "r1487", "r1489" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationStateAndLocalIncomeTaxes": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationStateAndLocalIncomeTaxes", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 2.0 }, "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "terseLabel": "State taxes, net", "label": "Effective Income Tax Rate Reconciliation, State and Local Income Taxes, Percent", "documentation": "Percentage of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations applicable to state and local income tax expense (benefit), net of federal tax expense (benefit)." } } }, "auth_ref": [ "r546", "r1087", "r1359", "r1366", "r1487" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationTable", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Effective Income Tax Rate Reconciliation [Table]", "label": "Effective Income Tax Rate Reconciliation [Table]", "documentation": "Disclosure of information about income tax rate reconciliation between amount of reported income tax expense (benefit) attributable to continuing operation to amount of income tax expense(benefit) that would result from applying statutory federal (national) tax rate to pretax income (loss) from continuing operation." } } }, "auth_ref": [ "r544", "r553", "r1087" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationTaxContingencies": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationTaxContingencies", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": 1.0, "order": 9.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Changes in unrecognized tax benefits", "label": "Effective Income Tax Rate Reconciliation, Tax Contingency, Percent", "documentation": "Percentage of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to income tax contingencies. Includes, but not limited to, domestic tax contingency, foreign tax contingency, state and local tax contingency, and other contingencies." } } }, "auth_ref": [ "r551", "r1087", "r1359", "r1366", "r1487" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationTaxCreditsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationTaxCreditsAbstract", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Tax credits:", "label": "Effective Income Tax Rate Reconciliation, Tax Credit, Percent [Abstract]" } } }, "auth_ref": [] }, "us-gaap_EffectiveIncomeTaxRateReconciliationTaxCreditsOther": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationTaxCreditsOther", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": -1.0, "order": 6.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Tax credits - Other tax credits", "label": "Effective Income Tax Rate Reconciliation, Tax Credit, Other, Percent", "documentation": "Percentage of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to other tax credits." } } }, "auth_ref": [ "r1087", "r1359", "r1366", "r1487", "r1488" ] }, "us-gaap_EffectiveIncomeTaxRateReconciliationTaxCreditsResearch": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EffectiveIncomeTaxRateReconciliationTaxCreditsResearch", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_EffectiveIncomeTaxRateContinuingOperations", "weight": -1.0, "order": 5.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Tax credits - Research and development", "label": "Effective Income Tax Rate Reconciliation, Tax Credit, Research, Percent", "documentation": "Percentage of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to research tax credit." } } }, "auth_ref": [ "r1087", "r1359", "r1366", "r1487", "r1488" ] }, "us-gaap_EmployeeRelatedLiabilitiesCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EmployeeRelatedLiabilitiesCurrent", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_LiabilitiesCurrent", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Accrued salaries and benefits", "label": "Employee-related Liabilities, Current", "documentation": "Total of the carrying values as of the balance sheet date of obligations incurred through that date and payable for obligations related to services received from employees, such as accrued salaries and bonuses, payroll taxes and fringe benefits. Used to reflect the current portion of the liabilities (due within one year or within the normal operating cycle if longer)." } } }, "auth_ref": [ "r1288" ] }, "us-gaap_EmployeeServiceShareBasedCompensationNonvestedAwardsTotalCompensationCostNotYetRecognized": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EmployeeServiceShareBasedCompensationNonvestedAwardsTotalCompensationCostNotYetRecognized", "crdr": "debit", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Unrecognized compensation cost", "label": "Share-Based Payment Arrangement, Nonvested Award, Cost Not yet Recognized, Amount", "documentation": "Amount of cost not yet recognized for nonvested award under share-based payment arrangement." } } }, "auth_ref": [ "r522" ] }, "us-gaap_EmployeeServiceShareBasedCompensationNonvestedAwardsTotalCompensationCostNotYetRecognizedPeriodForRecognition1": { "xbrltype": "durationItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EmployeeServiceShareBasedCompensationNonvestedAwardsTotalCompensationCostNotYetRecognizedPeriodForRecognition1", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Weighted-average recognition period", "label": "Share-Based Payment Arrangement, Nonvested Award, Cost Not yet Recognized, Period for Recognition", "documentation": "Weighted-average period over which cost not yet recognized is expected to be recognized for award under share-based payment arrangement, in 'PnYnMnDTnHnMnS' format, for example, 'P1Y5M13D' represents reported fact of one year, five months, and thirteen days." } } }, "auth_ref": [ "r522" ] }, "us-gaap_EmployeeServiceShareBasedCompensationTaxBenefitFromCompensationExpense": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EmployeeServiceShareBasedCompensationTaxBenefitFromCompensationExpense", "crdr": "credit", "calculation": { "http://www.costco.com/role/StockBasedCompensationPlansSummaryofStockBasedCompensationExpenseDetails": { "parentTag": "us-gaap_AllocatedShareBasedCompensationExpenseNetOfTax", "weight": -1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansSummaryofStockBasedCompensationExpenseDetails" ], "lang": { "en-us": { "role": { "verboseLabel": "Less income tax benefit", "label": "Share-Based Payment Arrangement, Expense, Tax Benefit", "documentation": "Amount of tax benefit for recognition of expense of award under share-based payment arrangement." } } }, "auth_ref": [ "r519" ] }, "us-gaap_EmployeeStockOptionMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EmployeeStockOptionMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Employee Stock Option", "label": "Share-Based Payment Arrangement, Option [Member]", "documentation": "Share-based payment arrangement granting right, subject to vesting and other restrictions, to purchase or sell certain number of shares at predetermined price for specified period of time." } } }, "auth_ref": [ "r1457", "r1458", "r1459", "r1460", "r1461", "r1462", "r1463", "r1464", "r1465", "r1466", "r1467", "r1468", "r1469", "r1470", "r1471", "r1472", "r1473", "r1474", "r1475", "r1476", "r1477", "r1478", "r1479", "r1480", "r1481", "r1482" ] }, "cost_EmployeesMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "EmployeesMember", "presentation": [ "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Employees [Member]", "label": "Employees [Member]", "documentation": "Employees [Member]" } } }, "auth_ref": [] }, "dei_EntityAddressAddressLine1": { "xbrltype": "normalizedStringItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityAddressAddressLine1", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Address, Address Line One", "label": "Entity Address, Address Line One", "documentation": "Address Line 1 such as Attn, Building Name, Street Name" } } }, "auth_ref": [] }, "dei_EntityAddressCityOrTown": { "xbrltype": "normalizedStringItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityAddressCityOrTown", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Address, City or Town", "label": "Entity Address, City or Town", "documentation": "Name of the City or Town" } } }, "auth_ref": [] }, "dei_EntityAddressPostalZipCode": { "xbrltype": "normalizedStringItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityAddressPostalZipCode", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Address, Postal Zip Code", "label": "Entity Address, Postal Zip Code", "documentation": "Code for the postal or zip code" } } }, "auth_ref": [] }, "dei_EntityAddressStateOrProvince": { "xbrltype": "stateOrProvinceItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityAddressStateOrProvince", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Address, State or Province", "label": "Entity Address, State or Province", "documentation": "Name of the state or province." } } }, "auth_ref": [] }, "dei_EntityCentralIndexKey": { "xbrltype": "centralIndexKeyItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityCentralIndexKey", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Central Index Key", "label": "Entity Central Index Key", "documentation": "A unique 10-digit SEC-issued value to identify entities that have filed disclosures with the SEC. It is commonly abbreviated as CIK." } } }, "auth_ref": [ "r1150" ] }, "dei_EntityCommonStockSharesOutstanding": { "xbrltype": "sharesItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityCommonStockSharesOutstanding", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Common Stock, Shares Outstanding", "label": "Entity Common Stock, Shares Outstanding", "documentation": "Indicate number of shares or other units outstanding of each of registrant's classes of capital or common stock or other ownership interests, if and as stated on cover of related periodic report. Where multiple classes or units exist define each class/interest by adding class of stock items such as Common Class A [Member], Common Class B [Member] or Partnership Interest [Member] onto the Instrument [Domain] of the Entity Listings, Instrument." } } }, "auth_ref": [] }, "dei_EntityCurrentReportingStatus": { "xbrltype": "yesNoItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityCurrentReportingStatus", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Current Reporting Status", "label": "Entity Current Reporting Status", "documentation": "Indicate 'Yes' or 'No' whether registrants (1) have filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that registrants were required to file such reports), and (2) have been subject to such filing requirements for the past 90 days. This information should be based on the registrant's current or most recent filing containing the related disclosure." } } }, "auth_ref": [] }, "dei_EntityEmergingGrowthCompany": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityEmergingGrowthCompany", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Emerging Growth Company", "label": "Entity Emerging Growth Company", "documentation": "Indicate if registrant meets the emerging growth company criteria." } } }, "auth_ref": [ "r1150" ] }, "dei_EntityFileNumber": { "xbrltype": "fileNumberItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityFileNumber", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity File Number", "label": "Entity File Number", "documentation": "Commission file number. The field allows up to 17 characters. The prefix may contain 1-3 digits, the sequence number may contain 1-8 digits, the optional suffix may contain 1-4 characters, and the fields are separated with a hyphen." } } }, "auth_ref": [] }, "dei_EntityFilerCategory": { "xbrltype": "filerCategoryItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityFilerCategory", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Filer Category", "label": "Entity Filer Category", "documentation": "Indicate whether the registrant is one of the following: Large Accelerated Filer, Accelerated Filer, Non-accelerated Filer. Definitions of these categories are stated in Rule 12b-2 of the Exchange Act. This information should be based on the registrant's current or most recent filing containing the related disclosure." } } }, "auth_ref": [ "r1150" ] }, "dei_EntityIncorporationStateCountryCode": { "xbrltype": "edgarStateCountryItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityIncorporationStateCountryCode", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Incorporation, State or Country Code", "label": "Entity Incorporation, State or Country Code", "documentation": "Two-character EDGAR code representing the state or country of incorporation." } } }, "auth_ref": [] }, "dei_EntityInteractiveDataCurrent": { "xbrltype": "yesNoItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityInteractiveDataCurrent", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Interactive Data Current", "label": "Entity Interactive Data Current", "documentation": "Boolean flag that is true when the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit such files)." } } }, "auth_ref": [ "r1260" ] }, "dei_EntityLocationTable": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityLocationTable", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Location [Table]", "label": "Entity Location [Table]", "documentation": "The Entity location table associates entities with primary and other locations. The domain members may be countries, states, provinces and groupings of these and other geographic codes." } } }, "auth_ref": [] }, "dei_EntityPublicFloat": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityPublicFloat", "crdr": "credit", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Public Float", "label": "Entity Public Float", "documentation": "The aggregate market value of the voting and non-voting common equity held by non-affiliates computed by reference to the price at which the common equity was last sold, or the average bid and asked price of such common equity, as of the last business day of the registrant's most recently completed second fiscal quarter." } } }, "auth_ref": [] }, "dei_EntityRegistrantName": { "xbrltype": "normalizedStringItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityRegistrantName", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Registrant Name", "label": "Entity Registrant Name", "documentation": "The exact name of the entity filing the report as specified in its charter, which is required by forms filed with the SEC." } } }, "auth_ref": [ "r1150" ] }, "dei_EntityShellCompany": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityShellCompany", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Shell Company", "label": "Entity Shell Company", "documentation": "Boolean flag that is true when the registrant is a shell company as defined in Rule 12b-2 of the Exchange Act." } } }, "auth_ref": [ "r1150" ] }, "dei_EntitySmallBusiness": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntitySmallBusiness", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Small Business", "label": "Entity Small Business", "documentation": "Indicates that the company is a Smaller Reporting Company (SRC)." } } }, "auth_ref": [ "r1150" ] }, "dei_EntityTaxIdentificationNumber": { "xbrltype": "employerIdItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityTaxIdentificationNumber", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Tax Identification Number", "label": "Entity Tax Identification Number", "documentation": "The Tax Identification Number (TIN), also known as an Employer Identification Number (EIN), is a unique 9-digit value assigned by the IRS." } } }, "auth_ref": [ "r1150" ] }, "dei_EntityVoluntaryFilers": { "xbrltype": "yesNoItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityVoluntaryFilers", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Voluntary Filers", "label": "Entity Voluntary Filers", "documentation": "Indicate 'Yes' or 'No' if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act." } } }, "auth_ref": [] }, "dei_EntityWellKnownSeasonedIssuer": { "xbrltype": "yesNoItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "EntityWellKnownSeasonedIssuer", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Entity Well-known Seasoned Issuer", "label": "Entity Well-known Seasoned Issuer", "documentation": "Indicate 'Yes' or 'No' if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Is used on Form Type: 10-K, 10-Q, 8-K, 20-F, 6-K, 10-K/A, 10-Q/A, 20-F/A, 6-K/A, N-CSR, N-Q, N-1A." } } }, "auth_ref": [ "r1261" ] }, "us-gaap_EntityWideInformationRevenueFromExternalCustomerLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EntityWideInformationRevenueFromExternalCustomerLineItems", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Revenue from External Customer", "label": "Segment Reporting, Entity-Wide Information Not Provided as Part of Reportable Segment, Product and Service, Revenue [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r263" ] }, "ecd_EqtyAwrdsAdjFnTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "EqtyAwrdsAdjFnTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Equity Awards Adjustments, Footnote", "label": "Equity Awards Adjustments, Footnote [Text Block]" } } }, "auth_ref": [ "r1203" ] }, "ecd_EqtyAwrdsAdjsExclgValRprtdInSummryCompstnTblMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "EqtyAwrdsAdjsExclgValRprtdInSummryCompstnTblMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Equity Awards Adjustments, Excluding Value Reported in Compensation Table", "label": "Equity Awards Adjustments, Excluding Value Reported in the Compensation Table [Member]" } } }, "auth_ref": [ "r1256" ] }, "ecd_EqtyAwrdsAdjsMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "EqtyAwrdsAdjsMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Equity Awards Adjustments", "label": "Equity Awards Adjustments [Member]" } } }, "auth_ref": [ "r1256" ] }, "ecd_EqtyAwrdsInSummryCompstnTblForAplblYrMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "EqtyAwrdsInSummryCompstnTblForAplblYrMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Aggregate Grant Date Fair Value of Equity Award Amounts Reported in Summary Compensation Table", "label": "Aggregate Grant Date Fair Value of Equity Award Amounts Reported in Summary Compensation Table [Member]" } } }, "auth_ref": [ "r1256" ] }, "us-gaap_EquityAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EquityAbstract", "lang": { "en-us": { "role": { "label": "Equity [Abstract]" } } }, "auth_ref": [] }, "us-gaap_EquityComponentDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "EquityComponentDomain", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Equity Component [Domain]", "label": "Equity Component [Domain]", "documentation": "Components of equity are the parts of the total Equity balance including that which is allocated to common, preferred, treasury stock, retained earnings, etc." } } }, "auth_ref": [ "r99", "r100", "r109", "r143", "r144", "r159", "r160", "r161", "r189", "r190", "r191", "r193", "r200", "r202", "r204", "r225", "r306", "r307", "r342", "r343", "r344", "r407", "r438", "r443", "r444", "r445", "r448", "r450", "r453", "r467", "r468", "r470", "r471", "r524", "r573", "r574", "r581", "r582", "r583", "r585", "r588", "r589", "r633", "r634", "r635", "r637", "r638", "r639", "r640", "r641", "r642", "r643", "r644", "r645", "r646", "r650", "r683", "r684", "r685", "r686", "r687", "r688", "r692", "r712", "r751", "r790", "r791", "r799", "r800", "r832", "r849", "r877", "r878", "r879", "r897", "r967", "r1450" ] }, "ecd_EquityValuationAssumptionDifferenceFnTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "EquityValuationAssumptionDifferenceFnTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Equity Valuation Assumption Difference, Footnote", "label": "Equity Valuation Assumption Difference, Footnote [Text Block]" } } }, "auth_ref": [ "r1213" ] }, "ecd_ErrCompAnalysisTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "ErrCompAnalysisTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Erroneous Compensation Analysis", "label": "Erroneous Compensation Analysis [Text Block]" } } }, "auth_ref": [ "r1170", "r1181", "r1191", "r1224" ] }, "ecd_ErrCompRecoveryTable": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "ErrCompRecoveryTable", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Erroneously Awarded Compensation Recovery", "label": "Erroneously Awarded Compensation Recovery [Table]" } } }, "auth_ref": [ "r1167", "r1178", "r1188", "r1221" ] }, "ecd_ExecutiveCategoryAxis": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "ExecutiveCategoryAxis", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Executive Category:", "label": "Executive Category [Axis]" } } }, "auth_ref": [ "r1219" ] }, "us-gaap_FIFOInventoryAmount": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FIFOInventoryAmount", "crdr": "debit", "presentation": [ "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "FIFO Inventory Amount", "label": "FIFO Inventory Amount", "documentation": "The amount of FIFO (first in first out) inventory present at the reporting date when inventory is also valued using different valuation methods." } } }, "auth_ref": [ "r1295" ] }, "country_FR": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "FR", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "FRANCE", "label": "FRANCE" } } }, "auth_ref": [] }, "us-gaap_FairValueAssetsAndLiabilitiesMeasuredOnRecurringAndNonrecurringBasisLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FairValueAssetsAndLiabilitiesMeasuredOnRecurringAndNonrecurringBasisLineItems", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]", "label": "Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r653", "r655", "r656", "r664", "r1104" ] }, "us-gaap_FairValueAssetsAndLiabilitiesMeasuredOnRecurringAndNonrecurringBasisTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FairValueAssetsAndLiabilitiesMeasuredOnRecurringAndNonrecurringBasisTable", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Fair Value, Recurring and Nonrecurring [Table]", "label": "Fair Value, Recurring and Nonrecurring [Table]", "documentation": "Disclosure of information about asset and liability measured at fair value on recurring and nonrecurring basis." } } }, "auth_ref": [ "r653", "r655", "r656", "r664", "r1104" ] }, "us-gaap_FairValueByFairValueHierarchyLevelAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FairValueByFairValueHierarchyLevelAxis", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Fair Value Hierarchy and NAV [Axis]", "label": "Fair Value Hierarchy and NAV [Axis]", "documentation": "Information by level within fair value hierarchy and fair value measured at net asset value per share as practical expedient." } } }, "auth_ref": [ "r393", "r473", "r474", "r475", "r476", "r477", "r478", "r479", "r480", "r653", "r654", "r656", "r657", "r658", "r659", "r663", "r664", "r665", "r674", "r717", "r718", "r719", "r724", "r1066", "r1067", "r1079", "r1080", "r1081", "r1082", "r1083", "r1104", "r1107", "r1114", "r1115" ] }, "us-gaap_FairValueByMeasurementFrequencyAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FairValueByMeasurementFrequencyAxis", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Measurement Frequency [Axis]", "label": "Measurement Frequency [Axis]", "documentation": "Information by measurement frequency." } } }, "auth_ref": [ "r655", "r656", "r657", "r659", "r1104", "r1526", "r1537" ] }, "us-gaap_FairValueDisclosuresAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FairValueDisclosuresAbstract", "lang": { "en-us": { "role": { "terseLabel": "Fair Value Disclosures [Abstract]", "label": "Fair Value Disclosures [Abstract]" } } }, "auth_ref": [] }, "us-gaap_FairValueDisclosuresTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FairValueDisclosuresTextBlock", "presentation": [ "http://www.costco.com/role/FairValueMeasurement" ], "lang": { "en-us": { "role": { "terseLabel": "Fair Value Measurement", "label": "Fair Value Disclosures [Text Block]", "documentation": "The entire disclosure for the fair value of financial instruments (as defined), including financial assets and financial liabilities (collectively, as defined), and the measurements of those instruments as well as disclosures related to the fair value of non-financial assets and liabilities. Such disclosures about the financial instruments, assets, and liabilities would include: (1) the fair value of the required items together with their carrying amounts (as appropriate); (2) for items for which it is not practicable to estimate fair value, disclosure would include: (a) information pertinent to estimating fair value (including, carrying amount, effective interest rate, and maturity, and (b) the reasons why it is not practicable to estimate fair value; (3) significant concentrations of credit risk including: (a) information about the activity, region, or economic characteristics identifying a concentration, (b) the maximum amount of loss the entity is exposed to based on the gross fair value of the related item, (c) policy for requiring collateral or other security and information as to accessing such collateral or security, and (d) the nature and brief description of such collateral or security; (4) quantitative information about market risks and how such risks are managed; (5) for items measured on both a recurring and nonrecurring basis information regarding the inputs used to develop the fair value measurement; and (6) for items presented in the financial statement for which fair value measurement is elected: (a) information necessary to understand the reasons for the election, (b) discussion of the effect of fair value changes on earnings, (c) a description of [similar groups] items for which the election is made and the relation thereof to the balance sheet, the aggregate carrying value of items included in the balance sheet that are not eligible for the election; (7) all other required (as defined) and desired information." } } }, "auth_ref": [ "r657", "r660", "r661", "r662", "r663", "r665", "r666", "r667", "r668", "r669", "r789", "r1104", "r1108" ] }, "us-gaap_FairValueInputsLevel2Member": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FairValueInputsLevel2Member", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Fair Value, Inputs, Level 2 [Member]", "label": "Fair Value, Inputs, Level 2 [Member]", "documentation": "Inputs other than quoted prices included within level 1 that are observable for an asset or liability, either directly or indirectly, including, but not limited to, quoted prices for similar assets or liabilities in active markets, or quoted prices for identical or similar assets or liabilities in inactive markets." } } }, "auth_ref": [ "r393", "r473", "r478", "r479", "r481", "r656", "r657", "r664", "r674", "r718", "r1066", "r1067", "r1079", "r1080", "r1081", "r1082", "r1083", "r1104", "r1114", "r1115" ] }, "us-gaap_FairValueMeasurementFrequencyDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FairValueMeasurementFrequencyDomain", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Measurement Frequency [Domain]", "label": "Measurement Frequency [Domain]", "documentation": "Measurement frequency." } } }, "auth_ref": [ "r655", "r656", "r657", "r659", "r1104", "r1526", "r1537" ] }, "us-gaap_FairValueMeasurementsFairValueHierarchyDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FairValueMeasurementsFairValueHierarchyDomain", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Fair Value, Measurements, Fair Value Hierarchy [Domain]", "label": "Fair Value Hierarchy and NAV [Domain]", "documentation": "Categories used to prioritize the inputs to valuation techniques to measure fair value." } } }, "auth_ref": [ "r393", "r473", "r474", "r475", "r476", "r477", "r478", "r479", "r480", "r653", "r654", "r656", "r657", "r658", "r659", "r663", "r664", "r665", "r674", "r717", "r718", "r719", "r724", "r1066", "r1067", "r1079", "r1080", "r1081", "r1082", "r1083", "r1104", "r1107", "r1114", "r1115" ] }, "us-gaap_FairValueMeasurementsRecurringMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FairValueMeasurementsRecurringMember", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Fair Value, Recurring [Member]", "label": "Fair Value, Recurring [Member]", "documentation": "Frequent fair value measurement. Includes, but is not limited to, fair value adjustment for impairment of asset, liability or equity, frequently measured at fair value." } } }, "auth_ref": [ "r1104", "r1523", "r1524", "r1525", "r1526", "r1527", "r1537" ] }, "us-gaap_FairValueOfFinancialInstrumentsPolicy": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FairValueOfFinancialInstrumentsPolicy", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Fair Value of Financial Instruments", "label": "Fair Value of Financial Instruments, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for determining the fair value of financial instruments." } } }, "auth_ref": [ "r1538" ] }, "us-gaap_FederalIncomeTaxExpenseBenefitContinuingOperations": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FederalIncomeTaxExpenseBenefitContinuingOperations", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Total federal", "label": "Federal Income Tax Expense (Benefit), Continuing Operations", "documentation": "Amount of current and deferred federal tax expense (benefit) attributable to income (loss) from continuing operations. Includes, but is not limited to, current and deferred national tax expense (benefit) for non-US (United States of America) jurisdiction." } } }, "auth_ref": [ "r178", "r183", "r541", "r543" ] }, "us-gaap_FederalIncomeTaxExpenseBenefitContinuingOperationsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FederalIncomeTaxExpenseBenefitContinuingOperationsAbstract", "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Federal [Abstract]", "label": "Federal Income Tax Expense (Benefit), Continuing Operations [Abstract]" } } }, "auth_ref": [] }, "us-gaap_FinanceLeaseInterestExpense": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseInterestExpense", "crdr": "debit", "calculation": { "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails": { "parentTag": "us-gaap_LeaseCost", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Finance Lease, Interest Expense", "label": "Finance Lease, Interest Expense", "documentation": "Amount of interest expense on finance lease liability." } } }, "auth_ref": [ "r696", "r702", "r1117" ] }, "us-gaap_FinanceLeaseInterestPaymentOnLiability": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseInterestPaymentOnLiability", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesSupplementalCashFlowInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Operating cash flows - finance leases", "label": "Finance Lease, Interest Payment on Liability", "documentation": "Amount of interest paid on finance lease liability." } } }, "auth_ref": [ "r698", "r705" ] }, "us-gaap_FinanceLeaseLiabilitiesPaymentsRollingMaturityAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilitiesPaymentsRollingMaturityAbstract", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Finance Lease, Liability, Payment, Due, Rolling Maturity [Abstract]", "label": "Finance Lease, Liability, to be Paid, Rolling Maturity [Abstract]" } } }, "auth_ref": [] }, "us-gaap_FinanceLeaseLiability": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiability", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Present value of lease liabilities", "label": "Finance Lease, Liability", "documentation": "Present value of lessee's discounted obligation for lease payments from finance lease." } } }, "auth_ref": [ "r694", "r709" ] }, "us-gaap_FinanceLeaseLiabilityCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityCurrent", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Current finance lease liabilities", "label": "Finance Lease, Liability, Current", "documentation": "Present value of lessee's discounted obligation for lease payments from finance lease, classified as current." } } }, "auth_ref": [ "r694" ] }, "us-gaap_FinanceLeaseLiabilityCurrentStatementOfFinancialPositionExtensibleList": { "xbrltype": "enumerationSetItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityCurrentStatementOfFinancialPositionExtensibleList", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Finance lease liabilities", "label": "Finance Lease, Liability, Current, Statement of Financial Position [Extensible Enumeration]", "documentation": "Indicates line item in statement of financial position that includes current finance lease liability." } } }, "auth_ref": [ "r695" ] }, "us-gaap_FinanceLeaseLiabilityMaturityTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityMaturityTableTextBlock", "presentation": [ "http://www.costco.com/role/LeasesTables" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Future Minimum Payments under Financing Leases", "label": "Finance Lease, Liability, to be Paid, Maturity [Table Text Block]", "documentation": "Tabular disclosure of undiscounted cash flows of finance lease liability. Includes, but is not limited to, reconciliation of undiscounted cash flows to finance lease liability recognized in statement of financial position." } } }, "auth_ref": [ "r1548" ] }, "us-gaap_FinanceLeaseLiabilityNoncurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityNoncurrent", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Long-term finance lease liabilities", "label": "Finance Lease, Liability, Noncurrent", "documentation": "Present value of lessee's discounted obligation for lease payments from finance lease, classified as noncurrent." } } }, "auth_ref": [ "r694" ] }, "us-gaap_FinanceLeaseLiabilityNoncurrentStatementOfFinancialPositionExtensibleList": { "xbrltype": "enumerationSetItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityNoncurrentStatementOfFinancialPositionExtensibleList", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Long-term finance lease liabilities", "label": "Finance Lease, Liability, Noncurrent, Statement of Financial Position [Extensible Enumeration]", "documentation": "Indicates line item in statement of financial position that includes noncurrent finance lease liability." } } }, "auth_ref": [ "r695" ] }, "us-gaap_FinanceLeaseLiabilityPaymentsDue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityPaymentsDue", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Total", "label": "Finance Lease, Liability, to be Paid", "documentation": "Amount of lessee's undiscounted obligation for lease payments for finance lease." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_FinanceLeaseLiabilityPaymentsDueAfterYearFive": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityPaymentsDueAfterYearFive", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Thereafter", "label": "Finance Lease, Liability, to be Paid, after Year Five", "documentation": "Amount of lessee's undiscounted obligation for lease payment for finance lease to be paid after fifth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_FinanceLeaseLiabilityPaymentsDueNextTwelveMonths": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityPaymentsDueNextTwelveMonths", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2027", "label": "Finance Lease, Liability, to be Paid, Year One", "documentation": "Amount of lessee's undiscounted obligation for lease payment for finance lease to be paid in next fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_FinanceLeaseLiabilityPaymentsDueYearFive": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityPaymentsDueYearFive", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2031", "label": "Finance Lease, Liability, to be Paid, Year Five", "documentation": "Amount of lessee's undiscounted obligation for lease payment for finance lease to be paid in fifth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_FinanceLeaseLiabilityPaymentsDueYearFour": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityPaymentsDueYearFour", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2030", "label": "Finance Lease, Liability, to be Paid, Year Four", "documentation": "Amount of lessee's undiscounted obligation for lease payment for finance lease to be paid in fourth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_FinanceLeaseLiabilityPaymentsDueYearThree": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityPaymentsDueYearThree", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2029", "label": "Finance Lease, Liability, to be Paid, Year Three", "documentation": "Amount of lessee's undiscounted obligation for lease payment for finance lease to be paid in third fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_FinanceLeaseLiabilityPaymentsDueYearTwo": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityPaymentsDueYearTwo", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2028", "label": "Finance Lease, Liability, to be Paid, Year Two", "documentation": "Amount of lessee's undiscounted obligation for lease payment for finance lease to be paid in second fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_FinanceLeaseLiabilityUndiscountedExcessAmount": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseLiabilityUndiscountedExcessAmount", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Less amount representing interest", "label": "Finance Lease, Liability, Undiscounted Excess Amount", "documentation": "Amount of lessee's undiscounted obligation for lease payments in excess of discounted obligation for lease payments for finance lease." } } }, "auth_ref": [ "r709" ] }, "us-gaap_FinanceLeasePrincipalPayments": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeasePrincipalPayments", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesSupplementalCashFlowInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Financing cash flows - finance leases", "label": "Finance Lease, Principal Payments", "documentation": "Amount of cash outflow for principal payment on finance lease." } } }, "auth_ref": [ "r697", "r705" ] }, "us-gaap_FinanceLeaseRightOfUseAsset": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseRightOfUseAsset", "crdr": "debit", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Finance lease assets", "label": "Finance Lease, Right-of-Use Asset, after Accumulated Amortization", "documentation": "Amount, after accumulated amortization, of right-of-use asset from finance lease." } } }, "auth_ref": [ "r693" ] }, "us-gaap_FinanceLeaseRightOfUseAssetAmortization": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseRightOfUseAssetAmortization", "crdr": "debit", "calculation": { "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails": { "parentTag": "us-gaap_LeaseCost", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Finance Lease, Right-of-Use Asset, Amortization", "label": "Finance Lease, Right-of-Use Asset, Amortization", "documentation": "Amount of amortization expense attributable to right-of-use asset from finance lease." } } }, "auth_ref": [ "r696", "r702", "r1117" ] }, "us-gaap_FinanceLeaseRightOfUseAssetStatementOfFinancialPositionExtensibleList": { "xbrltype": "enumerationSetItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseRightOfUseAssetStatementOfFinancialPositionExtensibleList", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Finance lease assets", "label": "Finance Lease, Right-of-Use Asset, Statement of Financial Position [Extensible Enumeration]", "documentation": "Indicates line item in statement of financial position that includes finance lease right-of-use asset." } } }, "auth_ref": [ "r695" ] }, "us-gaap_FinanceLeaseWeightedAverageDiscountRatePercent": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseWeightedAverageDiscountRatePercent", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Finance Lease, Weighted Average Discount Rate, Percent", "label": "Finance Lease, Weighted Average Discount Rate, Percent", "documentation": "Weighted average discount rate for finance lease calculated at point in time." } } }, "auth_ref": [ "r708", "r1117" ] }, "us-gaap_FinanceLeaseWeightedAverageRemainingLeaseTerm1": { "xbrltype": "durationItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinanceLeaseWeightedAverageRemainingLeaseTerm1", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Finance Lease, Weighted Average Remaining Lease Term", "label": "Finance Lease, Weighted Average Remaining Lease Term", "documentation": "Weighted average remaining lease term for finance lease, in 'PnYnMnDTnHnMnS' format, for example, 'P1Y5M13D' represents reported fact of one year, five months, and thirteen days." } } }, "auth_ref": [ "r707", "r1117" ] }, "us-gaap_FinancialInstrumentAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FinancialInstrumentAxis", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails", "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Major Types of Debt and Equity Securities", "label": "Financial Instrument [Axis]", "documentation": "Information by type of financial instrument." } } }, "auth_ref": [ "r275", "r276", "r277", "r278", "r279", "r280", "r281", "r282", "r283", "r284", "r285", "r286", "r287", "r288", "r289", "r290", "r291", "r292", "r293", "r294", "r295", "r296", "r297", "r298", "r299", "r300", "r301", "r302", "r303", "r304", "r308", "r309", "r310", "r311", "r312", "r313", "r314", "r315", "r316", "r317", "r318", "r319", "r320", "r322", "r323", "r324", "r404", "r437", "r631", "r670", "r678", "r680", "r714", "r715", "r716", "r717", "r718", "r719", "r721", "r722", "r723", "r724", "r726", "r727", "r728", "r729", "r730", "r731", "r733", "r734", "r736", "r737", "r738", "r739", "r740", "r741", "r742", "r743", "r744", "r745", "r746", "r747", "r748", "r749", "r750", "r812", "r813", "r814", "r815", "r816", "r817", "r818", "r819", "r820", "r821", "r822", "r823", "r824", "r825", "r826", "r827", "r828", "r829", "r834", "r850", "r1059", "r1104", "r1106", "r1107", "r1108", "r1109", "r1110", "r1111", "r1112", "r1113", "r1266", "r1267", "r1268", "r1269", "r1270", "r1271", "r1272", "r1400", "r1401", "r1402", "r1403", "r1522", "r1525", "r1526", "r1527", "r1534", "r1537", "r1539", "r1540" ] }, "cost_FinancingLeasePaymentsAndOtherFinancingActivitiesNet": { "xbrltype": "monetaryItemType", "nsuri": "http://www.costco.com/20260830", "localname": "FinancingLeasePaymentsAndOtherFinancingActivitiesNet", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInFinancingActivities", "weight": -1.0, "order": 8.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Financing lease payments and other financing activities, net", "label": "Financing lease payments and other financing activities, net", "documentation": "Financing lease payments and other financing activities, net" } } }, "auth_ref": [] }, "us-gaap_FiscalPeriod": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FiscalPeriod", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Fiscal Year End", "label": "Fiscal Period, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for determining an entity's fiscal year or other fiscal period. This disclosure may include identification of the fiscal period end-date, the length of the fiscal period, any reporting period lag between the entity and its subsidiaries, or equity investees. If a reporting lag exists, the closing date of the entity having a different period end is generally noted, along with an explanation of the necessity for using different closing dates. Any intervening events that materially affect the entity's financial position or results of operations are generally also disclosed." } } }, "auth_ref": [ "r17" ] }, "us-gaap_FixturesAndEquipmentGross": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FixturesAndEquipmentGross", "crdr": "debit", "calculation": { "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails": { "parentTag": "us-gaap_PropertyPlantAndEquipmentGross", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Equipment and fixtures", "label": "Fixtures and Equipment, Gross", "documentation": "Amount before accumulated depreciation of fixtures and equipment. Includes, but is not limited to, machinery, equipment, and engines." } } }, "auth_ref": [ "r1285" ] }, "cost_FoodandSundriesMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "FoodandSundriesMember", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Food and Sundries [Member]", "label": "Food and Sundries [Member]", "documentation": "Food and Sundries [Member]" } } }, "auth_ref": [] }, "us-gaap_ForeignCurrencyTransactionsAndTranslationsPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ForeignCurrencyTransactionsAndTranslationsPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Foreign Currency", "label": "Foreign Currency Transactions and Translations Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for (1) transactions denominated in a currency other than the reporting enterprise's functional currency, (2) translating foreign currency financial statements that are incorporated into the financial statements of the reporting enterprise by consolidation, combination, or the equity method of accounting, and (3) remeasurement of the financial statements of a foreign reporting enterprise in a hyperinflationary economy." } } }, "auth_ref": [ "r681" ] }, "us-gaap_ForeignExchangeForwardMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ForeignExchangeForwardMember", "presentation": [ "http://www.costco.com/role/AccountingPoliciesDerivativesDetails", "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "verboseLabel": "Forward foreign exchange contracts", "terseLabel": "Foreign Exchange Forward [Member]", "label": "Foreign Exchange Forward [Member]", "documentation": "Foreign exchange forward traded on an exchange (examples include but are not limited to the International Securities Exchange, Philadelphia Stock Exchange, or the Chicago Mercantile Exchange) for options or future contracts to buy or sell a certain currency, at a specified date, at a fixed exercise exchange rate." } } }, "auth_ref": [ "r935", "r939", "r944", "r957", "r963", "r986", "r987", "r988", "r1094", "r1096", "r1097", "r1098", "r1099", "r1100", "r1101", "r1141", "r1502", "r1503", "r1504", "r1505", "r1506", "r1507", "r1508", "r1509", "r1510", "r1511", "r1512", "r1513" ] }, "us-gaap_ForeignIncomeTaxExpenseBenefitContinuingOperations": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ForeignIncomeTaxExpenseBenefitContinuingOperations", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Total foreign", "label": "Foreign Income Tax Expense (Benefit), Continuing Operations", "documentation": "Amount of current and deferred foreign income tax expense (benefit) attributable to income (loss) from continuing operations." } } }, "auth_ref": [ "r178", "r183", "r543" ] }, "us-gaap_ForeignIncomeTaxExpenseBenefitContinuingOperationsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ForeignIncomeTaxExpenseBenefitContinuingOperationsAbstract", "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Foreign [Abstract]", "label": "Foreign Income Tax Expense (Benefit), Continuing Operations [Abstract]" } } }, "auth_ref": [] }, "us-gaap_ForeignTaxJurisdictionOtherMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ForeignTaxJurisdictionOtherMember", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Foreign, Other", "label": "Income Tax Jurisdiction, Foreign, Other [Member]", "documentation": "Designated foreign jurisdiction entitled to levy and collect income tax outside country of domicile, classified as other." } } }, "auth_ref": [ "r1087", "r1356", "r1493" ] }, "ecd_ForgoneRecoveryDueToDisqualificationOfTaxBenefitsAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "ForgoneRecoveryDueToDisqualificationOfTaxBenefitsAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Forgone Recovery due to Disqualification of Tax Benefits, Amount", "label": "Forgone Recovery due to Disqualification of Tax Benefits, Amount" } } }, "auth_ref": [ "r1174", "r1185", "r1195", "r1228" ] }, "ecd_ForgoneRecoveryDueToExpenseOfEnforcementAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "ForgoneRecoveryDueToExpenseOfEnforcementAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Forgone Recovery due to Expense of Enforcement, Amount", "label": "Forgone Recovery due to Expense of Enforcement, Amount" } } }, "auth_ref": [ "r1174", "r1185", "r1195", "r1228" ] }, "ecd_ForgoneRecoveryDueToViolationOfHomeCountryLawAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "ForgoneRecoveryDueToViolationOfHomeCountryLawAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Forgone Recovery due to Violation of Home Country Law, Amount", "label": "Forgone Recovery due to Violation of Home Country Law, Amount" } } }, "auth_ref": [ "r1174", "r1185", "r1195", "r1228" ] }, "ecd_ForgoneRecoveryExplanationOfImpracticabilityTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "ForgoneRecoveryExplanationOfImpracticabilityTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Forgone Recovery, Explanation of Impracticability", "label": "Forgone Recovery, Explanation of Impracticability [Text Block]" } } }, "auth_ref": [ "r1174", "r1185", "r1195", "r1228" ] }, "ecd_ForgoneRecoveryIndName": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "ForgoneRecoveryIndName", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Name", "label": "Forgone Recovery, Individual Name" } } }, "auth_ref": [ "r1174", "r1185", "r1195", "r1228" ] }, "ecd_FrValAsOfPrrYrEndOfEqtyAwrdsGrntdInPrrYrsFldVstngCondsDrngCvrdYrMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "FrValAsOfPrrYrEndOfEqtyAwrdsGrntdInPrrYrsFldVstngCondsDrngCvrdYrMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Prior Year End Fair Value of Equity Awards Granted in Any Prior Year that Fail to Meet Applicable Vesting Conditions During Covered Year", "label": "Prior Year End Fair Value of Equity Awards Granted in Any Prior Year that Fail to Meet Applicable Vesting Conditions During Covered Year [Member]" } } }, "auth_ref": [ "r1208" ] }, "cost_FreshFoodMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "FreshFoodMember", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Fresh Foods [Member]", "label": "Fresh Food [Member]", "documentation": "Fresh Food [Member]" } } }, "auth_ref": [] }, "us-gaap_FurnitureAndFixturesMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "FurnitureAndFixturesMember", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Equipment and Fixtures [Member]", "label": "Furniture and Fixtures [Member]", "documentation": "Equipment commonly used in offices and stores that have no permanent connection to the structure of a building or utilities. Examples include, but are not limited to, desks, chairs, tables, and bookcases." } } }, "auth_ref": [ "r1064", "r1424", "r1425" ] }, "country_GB": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "GB", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "UNITED KINGDOM", "label": "UNITED KINGDOM" } } }, "auth_ref": [] }, "us-gaap_Goodwill": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "Goodwill", "crdr": "debit", "presentation": [ "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Goodwill", "label": "Goodwill", "documentation": "Amount, after accumulated impairment loss, of asset representing future economic benefit arising from other asset acquired in business combination or from joint venture formation or both, that is not individually identified and separately recognized." } } }, "auth_ref": [ "r113", "r120", "r329", "r790", "r791", "r792", "r1054", "r1060", "r1088", "r1089", "r1090", "r1093", "r1105", "r1118", "r1416", "r1417", "r1499" ] }, "us-gaap_GoodwillAndIntangibleAssetsGoodwillPolicy": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "GoodwillAndIntangibleAssetsGoodwillPolicy", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Goodwill and Intangible Assets, Goodwill, Policy", "label": "Goodwill and Intangible Assets, Goodwill, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for goodwill. This accounting policy also may address how an entity assesses and measures impairment of goodwill, how reporting units are determined, how goodwill is allocated to such units, and how the fair values of the reporting units are determined." } } }, "auth_ref": [ "r328", "r340", "r1060" ] }, "us-gaap_GoodwillLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "GoodwillLineItems", "presentation": [ "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Goodwill [Line Items]", "label": "Goodwill [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r330", "r331", "r332", "r333", "r334", "r335", "r336", "r337", "r338", "r339", "r340", "r1060" ] }, "us-gaap_HeldToMaturitySecurities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "HeldToMaturitySecurities", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails": { "parentTag": "us-gaap_DebtSecuritiesAvailableForSaleAndHeldToMaturityAmortizedCostBeforeAllowanceForCreditLoss", "weight": 1.0, "order": 2.0 }, "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails", "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Held-to-maturity, cost basis", "totalLabel": "Held-to-maturity, cost basis, total", "label": "Debt Securities, Held-to-Maturity, Amortized Cost, before Allowance for Credit Loss", "documentation": "Amount, before allowance for credit loss, of investment in debt security measured at amortized cost (held-to-maturity)." } } }, "auth_ref": [ "r43", "r288", "r311", "r673", "r1405" ] }, "us-gaap_HeldToMaturitySecuritiesDebtMaturitiesAfterFiveThroughTenYearsNetCarryingAmount": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "HeldToMaturitySecuritiesDebtMaturitiesAfterFiveThroughTenYearsNetCarryingAmount", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": "us-gaap_HeldToMaturitySecurities", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Due after five years", "label": "Debt Securities, Held-to-Maturity, Amortized Cost, after Allowance for Credit Loss, Maturity, Allocated and Single Maturity Date, after Year 5 through 10", "documentation": "Amount, after allowance for credit loss, of investment in debt security measured at amortized cost (held-to-maturity) with single maturity date and allocated without single maturity date, maturing in sixth through tenth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r295", "r823" ] }, "us-gaap_HeldToMaturitySecuritiesDebtMaturitiesAfterOneThroughFiveYearsNetCarryingAmount": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "HeldToMaturitySecuritiesDebtMaturitiesAfterOneThroughFiveYearsNetCarryingAmount", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": "us-gaap_HeldToMaturitySecurities", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Due after one year through five years", "label": "Debt Securities, Held-to-Maturity, Amortized Cost, after Allowance for Credit Loss, Maturity, Allocated and Single Maturity Date, after Year One through Five", "documentation": "Amount, after allowance for credit loss, of investment in debt security measured at amortized cost (held-to-maturity) with single maturity date and allocated without single maturity date, maturing in second through fifth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r294", "r822" ] }, "us-gaap_HeldToMaturitySecuritiesDebtMaturitiesNetCarryingAmountAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "HeldToMaturitySecuritiesDebtMaturitiesNetCarryingAmountAbstract", "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Held-To-Maturity", "label": "Debt Securities, Held-to-Maturity, Amortized Cost, after Allowance for Credit Loss, Maturity [Abstract]" } } }, "auth_ref": [] }, "us-gaap_HeldToMaturitySecuritiesDebtMaturitiesWithinOneYearNetCarryingAmount": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "HeldToMaturitySecuritiesDebtMaturitiesWithinOneYearNetCarryingAmount", "crdr": "debit", "calculation": { "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails": { "parentTag": "us-gaap_HeldToMaturitySecurities", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/InvestmentsMaturitiesofAvailableforSaleandHeldtoMaturitySecuritiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Due in one year or less", "label": "Debt Securities, Held-to-Maturity, Amortized Cost, after Allowance for Credit Loss, Maturity, Allocated and Single Maturity Date, Year One", "documentation": "Amount, after allowance for credit loss, of investment in debt security measured at amortized cost (held-to-maturity) with single maturity date and allocated without single maturity date, maturing in next fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r293", "r821" ] }, "us-gaap_HeldToMaturitySecuritiesFairValue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "HeldToMaturitySecuritiesFairValue", "crdr": "debit", "presentation": [ "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Held-to-maturity, recorded basis", "label": "Debt Securities, Held-to-Maturity, Fair Value", "documentation": "Fair value of investment in debt security measured at amortized cost (held-to-maturity)." } } }, "auth_ref": [ "r44", "r297", "r656", "r663", "r675", "r676", "r677", "r790", "r791", "r803", "r835" ] }, "country_IS": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "IS", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "ICELAND", "label": "ICELAND" } } }, "auth_ref": [] }, "dei_IcfrAuditorAttestationFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "IcfrAuditorAttestationFlag", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "ICFR Auditor Attestation Flag", "label": "ICFR Auditor Attestation Flag" } } }, "auth_ref": [ "r1153", "r1154", "r1177" ] }, "us-gaap_IncomeLossAttributableToParent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeLossAttributableToParent", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfIncome": { "parentTag": "us-gaap_NetIncomeLoss", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails" ], "lang": { "en-us": { "role": { "totalLabel": "INCOME BEFORE INCOME TAXES", "terseLabel": "Income before Income Taxes", "label": "Income (Loss) Attributable to Parent, before Tax", "documentation": "Amount, before tax, of income (loss) attributable to parent. Includes, but is not limited to, income (loss) from continuing operations, discontinued operations and equity method investments." } } }, "auth_ref": [ "r23", "r161" ] }, "us-gaap_IncomeLossFromContinuingOperationsBeforeIncomeTaxesDomestic": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeLossFromContinuingOperationsBeforeIncomeTaxesDomestic", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesIncomeBeforeIncomeTaxesDetails": { "parentTag": "us-gaap_IncomeLossFromContinuingOperationsBeforeIncomeTaxesExtraordinaryItemsNoncontrollingInterest", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesIncomeBeforeIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Domestic", "label": "Income (Loss) from Continuing Operations before Income Taxes, Domestic", "documentation": "The portion of earnings or loss from continuing operations before income taxes that is attributable to domestic operations." } } }, "auth_ref": [ "r178", "r184", "r542" ] }, "us-gaap_IncomeLossFromContinuingOperationsBeforeIncomeTaxesExtraordinaryItemsNoncontrollingInterest": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeLossFromContinuingOperationsBeforeIncomeTaxesExtraordinaryItemsNoncontrollingInterest", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesIncomeBeforeIncomeTaxesDetails": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesIncomeBeforeIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "totalLabel": "INCOME BEFORE INCOME TAXES", "label": "Income (Loss) from Continuing Operations before Income Taxes, Noncontrolling Interest", "documentation": "Amount of income (loss) from continuing operations, including income (loss) from equity method investments, before deduction of income tax expense (benefit), and income (loss) attributable to noncontrolling interest." } } }, "auth_ref": [ "r20", "r39", "r807", "r809", "r847", "r1025", "r1037", "r1039", "r1040", "r1048", "r1053", "r1374", "r1378", "r1384", "r1387", "r1388" ] }, "us-gaap_IncomeLossFromContinuingOperationsBeforeIncomeTaxesForeign": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeLossFromContinuingOperationsBeforeIncomeTaxesForeign", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesIncomeBeforeIncomeTaxesDetails": { "parentTag": "us-gaap_IncomeLossFromContinuingOperationsBeforeIncomeTaxesExtraordinaryItemsNoncontrollingInterest", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesIncomeBeforeIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Foreign", "label": "Income (Loss) from Continuing Operations before Income Taxes, Foreign", "documentation": "The portion of earnings or loss from continuing operations before income taxes that is attributable to foreign operations, which is defined as Income or Loss generated from operations located outside the entity's country of domicile." } } }, "auth_ref": [ "r178", "r184", "r542" ] }, "us-gaap_IncomeStatementAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeStatementAbstract", "lang": { "en-us": { "role": { "terseLabel": "Income Statement [Abstract]", "label": "Income Statement [Abstract]" } } }, "auth_ref": [] }, "us-gaap_IncomeTaxAuthorityAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxAuthorityAxis", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Income Tax Jurisdiction [Axis]", "label": "Income Tax Jurisdiction [Axis]", "documentation": "Information by income tax jurisdiction." } } }, "auth_ref": [ "r173", "r544", "r553", "r557", "r570", "r1087", "r1494" ] }, "us-gaap_IncomeTaxAuthorityDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxAuthorityDomain", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Income Tax Jurisdiction [Domain]", "label": "Income Tax Jurisdiction [Domain]", "documentation": "Income tax jurisdiction." } } }, "auth_ref": [ "r173", "r544", "r553", "r557", "r570", "r1087", "r1494" ] }, "us-gaap_IncomeTaxDisclosureAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxDisclosureAbstract", "lang": { "en-us": { "role": { "terseLabel": "Income Tax Disclosure [Abstract]", "label": "Income Tax Disclosure [Abstract]" } } }, "auth_ref": [] }, "us-gaap_IncomeTaxDisclosureTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxDisclosureTextBlock", "presentation": [ "http://www.costco.com/role/IncomeTaxes" ], "lang": { "en-us": { "role": { "terseLabel": "Income Taxes", "label": "Income Tax Disclosure [Text Block]", "documentation": "The entire disclosure for income tax." } } }, "auth_ref": [ "r178", "r185", "r534", "r544", "r554", "r555", "r556", "r563", "r568", "r576", "r578", "r579", "r580", "r833", "r884", "r896", "r1087" ] }, "us-gaap_IncomeTaxExpenseBenefit": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxExpenseBenefit", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfIncome": { "parentTag": "us-gaap_NetIncomeLoss", "weight": -1.0, "order": 2.0 }, "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails": { "parentTag": null, "weight": null, "order": null, "root": true }, "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": null, "weight": null, "order": null, "root": true }, "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details", "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Provision for income taxes", "totalLabel": "Total provision for income taxes", "label": "Income Tax Expense (Benefit)", "documentation": "Amount of current income tax expense (benefit) and deferred income tax expense (benefit) pertaining to continuing operations." } } }, "auth_ref": [ "r49", "r55", "r178", "r203", "r204", "r224", "r245", "r260", "r541", "r544", "r577", "r856", "r1025", "r1037", "r1039", "r1040", "r1087" ] }, "us-gaap_IncomeTaxExpenseBenefitContinuingOperationsIncomeTaxReconciliationAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxExpenseBenefitContinuingOperationsIncomeTaxReconciliationAbstract", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "terseLabel": "Income Tax Expense (Benefit), Effective Income Tax Rate Reconciliation, Amount [Abstract]", "label": "Income Tax Expense (Benefit), Effective Income Tax Rate Reconciliation, Amount [Abstract]" } } }, "auth_ref": [] }, "us-gaap_IncomeTaxPaidByIndividualJurisdictionAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxPaidByIndividualJurisdictionAbstract", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Income Tax Paid, by Individual Jurisdiction [Abstract]", "label": "Income Tax Paid, by Individual Jurisdiction [Abstract]" } } }, "auth_ref": [] }, "us-gaap_IncomeTaxPaidByIndividualJurisdictionLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxPaidByIndividualJurisdictionLineItems", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Income Tax Paid, by Individual Jurisdiction [Line Items]", "label": "Income Tax Paid, by Individual Jurisdiction [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r173", "r570" ] }, "us-gaap_IncomeTaxPaidByIndividualJurisdictionTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxPaidByIndividualJurisdictionTable", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Income Tax Paid, by Individual Jurisdiction [Table]", "label": "Income Tax Paid, by Individual Jurisdiction [Table]", "documentation": "Disclosure of information about income tax paid by jurisdiction." } } }, "auth_ref": [ "r173", "r570" ] }, "us-gaap_IncomeTaxPaidFederalAfterRefundReceived": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxPaidFederalAfterRefundReceived", "crdr": "credit", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Income Tax Paid, Federal, after Refund Received", "label": "Income Tax Paid, Federal, after Refund Received", "documentation": "Amount, after income tax refund received, of cash paid to federal (national) tax jurisdiction for tax on income." } } }, "auth_ref": [ "r173", "r569" ] }, "us-gaap_IncomeTaxPaidForeignAfterRefundReceived": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxPaidForeignAfterRefundReceived", "crdr": "credit", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Income Tax Paid, Foreign, after Refund Received", "label": "Income Tax Paid, Foreign, after Refund Received", "documentation": "Amount, after income tax refund received, of cash paid to foreign tax jurisdiction for tax on income." } } }, "auth_ref": [ "r173", "r569" ] }, "us-gaap_IncomeTaxPaidStateAndLocalAfterRefundReceived": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxPaidStateAndLocalAfterRefundReceived", "crdr": "credit", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Income Tax Paid, State and Local, after Refund Received", "label": "Income Tax Paid, State and Local, after Refund Received", "documentation": "Amount, after income tax refund received, of cash paid to state and local tax jurisdictions for tax on income." } } }, "auth_ref": [ "r173", "r569" ] }, "us-gaap_IncomeTaxPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Income Taxes", "label": "Income Tax, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for income taxes, which may include its accounting policies for recognizing and measuring deferred tax assets and liabilities and related valuation allowances, recognizing investment tax credits, operating loss carryforwards, tax credit carryforwards, and other carryforwards, methodologies for determining its effective income tax rate and the characterization of interest and penalties in the financial statements." } } }, "auth_ref": [ "r158", "r537", "r538", "r563", "r564", "r567", "r572", "r890" ] }, "us-gaap_IncomeTaxRateReconciliationDeductionsEmployeeStockOwnershipPlanDividends": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxRateReconciliationDeductionsEmployeeStockOwnershipPlanDividends", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": -1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Employee stock ownership plan (ESOP)", "label": "Effective Income Tax Rate Reconciliation, Deduction, Employee Stock Ownership Plan Dividend, Amount", "documentation": "Amount of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to deduction for dividend paid to employee stock ownership plan." } } }, "auth_ref": [ "r1487", "r1489" ] }, "us-gaap_IncomeTaxReconciliationChangeInDeferredTaxAssetsValuationAllowance": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxReconciliationChangeInDeferredTaxAssetsValuationAllowance", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 7.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Changes in valuation allowance", "label": "Effective Income Tax Rate Reconciliation, Change in Deferred Tax Assets Valuation Allowance, Amount", "documentation": "Amount of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to increase (decrease) in the valuation allowance for deferred tax assets." } } }, "auth_ref": [ "r549", "r1087", "r1487" ] }, "us-gaap_IncomeTaxReconciliationForeignIncomeTaxRateDifferential": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxReconciliationForeignIncomeTaxRateDifferential", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 3.0 }, "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "verboseLabel": "Foreign taxes, net", "label": "Effective Income Tax Rate Reconciliation, Foreign Income Tax Rate Differential, Amount", "documentation": "Amount of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to foreign income tax expense (benefit)." } } }, "auth_ref": [ "r547", "r553", "r1087", "r1487" ] }, "us-gaap_IncomeTaxReconciliationIncomeTaxExpenseBenefitAtFederalStatutoryIncomeTaxRate": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxReconciliationIncomeTaxExpenseBenefitAtFederalStatutoryIncomeTaxRate", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 1.0 }, "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "terseLabel": "Federal taxes at statutory rate", "label": "Effective Income Tax Rate Reconciliation at Federal Statutory Income Tax Rate, Amount", "documentation": "The amount of income tax expense or benefit for the period computed by applying the domestic federal statutory tax rates to pretax income from continuing operations." } } }, "auth_ref": [ "r544", "r1087" ] }, "us-gaap_IncomeTaxReconciliationNondeductibleExpense": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxReconciliationNondeductibleExpense", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 8.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Nontaxable or nondeductible", "label": "Effective Income Tax Rate Reconciliation, Nondeductible Expense, Amount", "documentation": "Amount of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to nondeductible expenses." } } }, "auth_ref": [ "r550", "r552", "r1487" ] }, "us-gaap_IncomeTaxReconciliationOtherAdjustments": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxReconciliationOtherAdjustments", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 5.0 }, "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 10.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "terseLabel": "Other", "label": "Effective Income Tax Rate Reconciliation, Other Adjustments, Amount", "documentation": "Amount of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to other adjustments." } } }, "auth_ref": [ "r1087", "r1487", "r1489" ] }, "us-gaap_IncomeTaxReconciliationStateAndLocalIncomeTaxes": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxReconciliationStateAndLocalIncomeTaxes", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 2.0 }, "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails", "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesFY25andFY24Details" ], "lang": { "en-us": { "role": { "terseLabel": "State taxes, net", "label": "Effective Income Tax Rate Reconciliation, State and Local Income Taxes, Amount", "documentation": "Amount of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to state and local income tax expense (benefit)." } } }, "auth_ref": [ "r546", "r1087", "r1487" ] }, "us-gaap_IncomeTaxReconciliationTaxContingencies": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxReconciliationTaxContingencies", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 9.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Changes in unrecognized tax benefits", "label": "Effective Income Tax Rate Reconciliation, Tax Contingency, Amount", "documentation": "Amount of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to increase (decrease) in income tax contingencies. Including, but not limited to, domestic tax contingency, foreign tax contingency, state and local tax contingency, and other contingencies." } } }, "auth_ref": [ "r551", "r1087", "r1487" ] }, "us-gaap_IncomeTaxReconciliationTaxCreditsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxReconciliationTaxCreditsAbstract", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Tax credits:", "label": "Effective Income Tax Rate Reconciliation, Tax Credit, Amount [Abstract]" } } }, "auth_ref": [] }, "us-gaap_IncomeTaxReconciliationTaxCreditsOther": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxReconciliationTaxCreditsOther", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": -1.0, "order": 6.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Tax credits - Other tax credits", "label": "Effective Income Tax Rate Reconciliation, Tax Credit, Other, Amount", "documentation": "Amount of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to other tax credits." } } }, "auth_ref": [ "r1087", "r1487", "r1488" ] }, "us-gaap_IncomeTaxReconciliationTaxCreditsResearch": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxReconciliationTaxCreditsResearch", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": -1.0, "order": 5.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Tax credits - Research and development", "label": "Effective Income Tax Rate Reconciliation, Tax Credit, Research, Amount", "documentation": "Amount of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to research tax credit." } } }, "auth_ref": [ "r1087", "r1487", "r1488" ] }, "us-gaap_IncomeTaxReconciliationTaxSettlements": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxReconciliationTaxSettlements", "crdr": "debit", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Transfer pricing settlement and certain true-ups of tax reserves tax benefit", "label": "Effective Income Tax Rate Reconciliation, Tax Settlement, Amount", "documentation": "Amount of the difference between reported income tax expense (benefit) and expected income tax expense (benefit) computed by applying the domestic federal statutory income tax rates to pretax income (loss) from continuing operations attributable to income tax settlements. Including, but not limited to, domestic tax settlement, foreign tax settlement, state and local tax settlement, and other tax settlements." } } }, "auth_ref": [ "r1487", "r1489" ] }, "us-gaap_IncomeTaxesPaid": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxesPaid", "crdr": "credit", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "Income taxes paid, net", "label": "Income Tax Paid, before Refund Received", "documentation": "Amount, before refund, of cash paid to foreign, federal, state, and local jurisdictions as income tax." } } }, "auth_ref": [ "r31", "r1356", "r1492", "r1493" ] }, "us-gaap_IncomeTaxesPaidNet": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncomeTaxesPaidNet", "crdr": "credit", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Income Tax Paid, after Refund Received, Total", "label": "Income Tax Paid, after Refund Received", "documentation": "Amount, after refund, of cash paid to foreign, federal, state, and local jurisdictions as income tax." } } }, "auth_ref": [ "r42", "r173", "r569", "r570" ] }, "us-gaap_IncreaseDecreaseInAccountsPayable": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncreaseDecreaseInAccountsPayable", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInOperatingActivities", "weight": 1.0, "order": 8.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedLabel": "Accounts payable", "label": "Increase (Decrease) in Accounts Payable", "documentation": "The increase (decrease) during the reporting period in the aggregate amount of liabilities incurred (and for which invoices have typically been received) and payable to vendors for goods and services received that are used in an entity's business." } } }, "auth_ref": [ "r3" ] }, "us-gaap_IncreaseDecreaseInDeferredIncomeTaxes": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncreaseDecreaseInDeferredIncomeTaxes", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInOperatingActivities", "weight": -1.0, "order": 5.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Deferred income taxes", "label": "Increase (Decrease) in Deferred Income Taxes", "documentation": "The increase (decrease) during the reporting period in the account that represents the temporary difference that results from Income or Loss that is recognized for accounting purposes but not for tax purposes and vice versa." } } }, "auth_ref": [ "r3" ] }, "us-gaap_IncreaseDecreaseInInventories": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncreaseDecreaseInInventories", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInOperatingActivities", "weight": -1.0, "order": 7.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedLabel": "Merchandise inventories", "label": "Increase (Decrease) in Inventories", "documentation": "The increase (decrease) during the reporting period in the aggregate value of all inventory held by the reporting entity, associated with underlying transactions that are classified as operating activities." } } }, "auth_ref": [ "r3" ] }, "us-gaap_IncreaseDecreaseInOperatingCapitalAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncreaseDecreaseInOperatingCapitalAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "Changes in operating assets and liabilities:", "label": "Adjustment to Reconcile Net Income to Cash Provided by (Used in) Operating Activity, Increase (Decrease) in Operating Capital [Abstract]" } } }, "auth_ref": [] }, "us-gaap_IncreaseDecreaseInOtherOperatingCapitalNet": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncreaseDecreaseInOtherOperatingCapitalNet", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInOperatingActivities", "weight": -1.0, "order": 9.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedLabel": "Other operating assets and liabilities, net", "label": "Increase (Decrease) in Other Operating Assets and Liabilities, Net", "documentation": "Amount of increase (decrease) in operating assets after deduction of operating liabilities classified as other." } } }, "auth_ref": [ "r3" ] }, "us-gaap_IncreaseDecreaseInStockholdersEquityRollForward": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncreaseDecreaseInStockholdersEquityRollForward", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Increase (Decrease) in Stockholders' Equity [Roll Forward]", "label": "Increase (Decrease) in Stockholders' Equity [Roll Forward]", "documentation": "A roll forward is a reconciliation of a concept from the beginning of a period to the end of a period." } } }, "auth_ref": [] }, "us-gaap_IncrementalCommonSharesAttributableToShareBasedPaymentArrangements": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "IncrementalCommonSharesAttributableToShareBasedPaymentArrangements", "calculation": { "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareScheduleofEarningsperShareEffectonNetIncomeandWeightedAveregaeNumberofDilutivePotentialCommonStockDetails": { "parentTag": "us-gaap_WeightedAverageNumberOfDilutedSharesOutstanding", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareScheduleofEarningsperShareEffectonNetIncomeandWeightedAveregaeNumberofDilutivePotentialCommonStockDetails" ], "lang": { "en-us": { "role": { "terseLabel": "RSUs and other", "label": "Incremental Common Shares Attributable to Dilutive Effect of Share-Based Payment Arrangements", "documentation": "Additional shares included in the calculation of diluted EPS as a result of the potentially dilutive effect of share based payment arrangements using the treasury stock method." } } }, "auth_ref": [ "r210", "r211", "r212", "r217", "r488" ] }, "ecd_IndividualAxis": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "IndividualAxis", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure", "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure", "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements", "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Individual:", "label": "Individual [Axis]" } } }, "auth_ref": [ "r1174", "r1185", "r1195", "r1219", "r1228", "r1232", "r1240" ] }, "ecd_InsiderTradingArrLineItems": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "InsiderTradingArrLineItems", "lang": { "en-us": { "role": { "label": "Insider Trading Arrangements [Line Items]" } } }, "auth_ref": [ "r1238" ] }, "ecd_InsiderTradingPoliciesProcLineItems": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "InsiderTradingPoliciesProcLineItems", "lang": { "en-us": { "role": { "label": "Insider Trading Policies and Procedures [Line Items]" } } }, "auth_ref": [ "r1155", "r1244" ] }, "ecd_InsiderTrdPoliciesProcAdoptedFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "InsiderTrdPoliciesProcAdoptedFlag", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingPoliciesProc" ], "lang": { "en-us": { "role": { "terseLabel": "Insider Trading Policies and Procedures Adopted", "label": "Insider Trading Policies and Procedures Adopted [Flag]" } } }, "auth_ref": [ "r1155", "r1244" ] }, "ecd_InsiderTrdPoliciesProcNotAdoptedTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "InsiderTrdPoliciesProcNotAdoptedTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingPoliciesProc" ], "lang": { "en-us": { "role": { "terseLabel": "Insider Trading Policies and Procedures Not Adopted", "label": "Insider Trading Policies and Procedures Not Adopted [Text Block]" } } }, "auth_ref": [ "r1155", "r1244" ] }, "us-gaap_InterestAndOtherIncome": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InterestAndOtherIncome", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfIncome": { "parentTag": "us-gaap_IncomeLossAttributableToParent", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome" ], "lang": { "en-us": { "role": { "terseLabel": "Interest income and other, net", "label": "Interest and Other Income", "documentation": "The amount of interest income and other income recognized during the period. Included in this element is interest derived from investments in debt securities, cash and cash equivalents, and other investments which reflect the time value of money or transactions in which the payments are for the use or forbearance of money and other income from ancillary business-related activities (that is, excluding major activities considered part of the normal operations of the business)." } } }, "auth_ref": [] }, "us-gaap_InterestExpense": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InterestExpense", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfIncome": { "parentTag": "us-gaap_IncomeLossAttributableToParent", "weight": -1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome" ], "lang": { "en-us": { "role": { "negatedLabel": "Interest expense", "label": "Interest Expense, Operating and Nonoperating", "documentation": "Amount of interest expense classified as operating and nonoperating. Includes, but is not limited to, cost of borrowing accounted for as interest expense." } } }, "auth_ref": [ "r224", "r237", "r241", "r247", "r260", "r689", "r1053", "r1054", "r1618" ] }, "us-gaap_InterestPaidNet": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InterestPaidNet", "crdr": "credit", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "Interest", "label": "Interest Paid, Excluding Capitalized Interest, Operating Activity", "documentation": "Amount of cash paid for interest, excluding capitalized interest, classified as operating activity. Includes, but is not limited to, payment to settle zero-coupon bond for accreted interest of debt discount and debt instrument with insignificant coupon interest rate in relation to effective interest rate of borrowing attributable to accreted interest of debt discount." } } }, "auth_ref": [ "r167", "r169", "r172" ] }, "us-gaap_InventoryCurrentTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InventoryCurrentTable", "presentation": [ "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Inventory, Current [Table]", "label": "Inventory, Current [Table]", "documentation": "Disclosure of information about inventory expected to be sold or consumed within one year or operating cycle, if longer." } } }, "auth_ref": [] }, "us-gaap_InventoryLIFOReservePeriodCharge": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InventoryLIFOReservePeriodCharge", "crdr": "debit", "presentation": [ "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Inventory, LIFO Reserve, Period Charge", "label": "Inventory, LIFO Reserve, Period Charge", "documentation": "The change in the inventory reserve representing the cumulative difference in cost between the first in, first out and the last in, first out inventory valuation methods, which change has been reflected in the statement of income during the period." } } }, "auth_ref": [ "r34" ] }, "us-gaap_InventoryLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InventoryLineItems", "presentation": [ "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Inventory [Line Items]", "label": "Inventory [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [] }, "us-gaap_InventoryNet": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InventoryNet", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_AssetsCurrent", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails", "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Merchandise inventories", "label": "Inventory, Net", "documentation": "Amount after valuation and LIFO reserves of inventory expected to be sold, or consumed within one year or operating cycle, if longer." } } }, "auth_ref": [ "r111", "r151", "r1027", "r1118" ] }, "us-gaap_InventoryPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InventoryPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Merchandise Inventories", "label": "Inventory, Policy [Policy Text Block]", "documentation": "Disclosure of inventory accounting policy for inventory classes, including, but not limited to, basis for determining inventory amounts, methods by which amounts are added and removed from inventory classes, loss recognition on impairment of inventories, and situations in which inventories are stated above cost." } } }, "auth_ref": [ "r50", "r108", "r111", "r150", "r325", "r326", "r327", "r753", "r1041" ] }, "us-gaap_InvestmentPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InvestmentPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Short-Term Investments", "label": "Investment, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for investment in financial asset." } } }, "auth_ref": [ "r854", "r886", "r887", "r888", "r889", "r976", "r977" ] }, "us-gaap_InvestmentTypeAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InvestmentTypeAxis", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Investment Type [Axis]", "label": "Investment Type [Axis]", "documentation": "Information by type of investments." } } }, "auth_ref": [ "r910", "r912", "r913", "r915", "r918", "r973", "r975", "r979", "r982", "r983", "r990", "r995", "r996", "r997", "r998", "r999", "r1141" ] }, "us-gaap_InvestmentTypeCategorizationMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InvestmentTypeCategorizationMember", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Investments [Domain]", "label": "Investments [Domain]", "documentation": "Asset obtained to generate income or appreciate in value." } } }, "auth_ref": [ "r910", "r912", "r913", "r915", "r918", "r973", "r975", "r979", "r982", "r983", "r990", "r995", "r996", "r997", "r998", "r999", "r1141" ] }, "us-gaap_InvestmentsClassifiedByContractualMaturityDateTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InvestmentsClassifiedByContractualMaturityDateTableTextBlock", "presentation": [ "http://www.costco.com/role/InvestmentsTables" ], "lang": { "en-us": { "role": { "terseLabel": "Maturities of Available for Sale and Held to Maturity Securities", "label": "Investments Classified by Contractual Maturity Date [Table Text Block]", "documentation": "Tabular disclosure of maturities of an entity's investments as well as any other information pertinent to the investments." } } }, "auth_ref": [ "r1394", "r1399" ] }, "us-gaap_InvestmentsDebtAndEquitySecuritiesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InvestmentsDebtAndEquitySecuritiesAbstract", "lang": { "en-us": { "role": { "terseLabel": "Investments, Debt and Equity Securities [Abstract]", "label": "Investments, Debt and Equity Securities [Abstract]" } } }, "auth_ref": [] }, "us-gaap_InvestmentsInDebtAndMarketableEquitySecuritiesAndCertainTradingAssetsDisclosureTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "InvestmentsInDebtAndMarketableEquitySecuritiesAndCertainTradingAssetsDisclosureTextBlock", "presentation": [ "http://www.costco.com/role/Investments" ], "lang": { "en-us": { "role": { "terseLabel": "Investments", "label": "Investment in Debt and Equity Securities and Other Trading Assets [Text Block]", "documentation": "The entire disclosure for investment in debt and equity securities and other assets at fair value and held for trading." } } }, "auth_ref": [ "r57", "r273", "r274", "r671", "r672", "r1554", "r1562" ] }, "country_JP": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "JP", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "JAPAN", "label": "JAPAN" } } }, "auth_ref": [] }, "country_KR": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "KR", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "KOREA", "label": "KOREA, REPUBLIC OF" } } }, "auth_ref": [] }, "us-gaap_LIFOInventoryAmount": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LIFOInventoryAmount", "crdr": "debit", "presentation": [ "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "LIFO Inventory Amount", "label": "LIFO Inventory Amount", "documentation": "The amount of LIFO (last in first out) inventory present at the reporting date when inventory is also valued using different valuation methods." } } }, "auth_ref": [ "r1295" ] }, "us-gaap_Land": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "Land", "crdr": "debit", "calculation": { "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails": { "parentTag": "us-gaap_PropertyPlantAndEquipmentGross", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Land", "label": "Land", "documentation": "Amount before accumulated depletion of real estate held for productive use, excluding land held for sale." } } }, "auth_ref": [ "r1281", "r1285" ] }, "us-gaap_LeaseCost": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LeaseCost", "crdr": "debit", "calculation": { "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Total lease costs", "label": "Lease, Cost", "documentation": "Amount of lease cost recognized by lessee for lease contract." } } }, "auth_ref": [ "r701", "r1117" ] }, "us-gaap_LeaseCostAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LeaseCostAbstract", "presentation": [ "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Lease, Cost [Abstract]", "label": "Lease, Cost [Abstract]" } } }, "auth_ref": [] }, "us-gaap_LeaseCostTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LeaseCostTableTextBlock", "presentation": [ "http://www.costco.com/role/LeasesTables" ], "lang": { "en-us": { "role": { "terseLabel": "Lease, Cost", "label": "Lease, Cost [Table Text Block]", "documentation": "Tabular disclosure of lessee's lease cost. Includes, but is not limited to, interest expense for finance lease, amortization of right-of-use asset for finance lease, operating lease cost, short-term lease cost, variable lease cost and sublease income." } } }, "auth_ref": [ "r1547" ] }, "us-gaap_LeasesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LeasesAbstract", "lang": { "en-us": { "role": { "terseLabel": "Leases [Abstract]", "label": "Leases [Abstract]" } } }, "auth_ref": [] }, "us-gaap_LesseeLeasesPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LesseeLeasesPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Leases", "label": "Lessee, Leases [Policy Text Block]", "documentation": "Disclosure of accounting policy for leasing arrangement entered into by lessee." } } }, "auth_ref": [ "r700" ] }, "us-gaap_LesseeOperatingLeaseLiabilityMaturityTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LesseeOperatingLeaseLiabilityMaturityTableTextBlock", "presentation": [ "http://www.costco.com/role/LeasesTables" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Future Minimum Payments Under Operating Leases", "label": "Lessee, Operating Lease, Liability, to be Paid, Maturity [Table Text Block]", "documentation": "Tabular disclosure of undiscounted cash flows of lessee's operating lease liability. Includes, but is not limited to, reconciliation of undiscounted cash flows to operating lease liability recognized in statement of financial position." } } }, "auth_ref": [ "r1548" ] }, "us-gaap_LesseeOperatingLeaseLiabilityPaymentsDue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LesseeOperatingLeaseLiabilityPaymentsDue", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Total", "label": "Lessee, Operating Lease, Liability, to be Paid", "documentation": "Amount of lessee's undiscounted obligation for lease payment for operating lease." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_LesseeOperatingLeaseLiabilityPaymentsDueAfterYearFive": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LesseeOperatingLeaseLiabilityPaymentsDueAfterYearFive", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Thereafter", "label": "Lessee, Operating Lease, Liability, to be Paid, after Year Five", "documentation": "Amount of lessee's undiscounted obligation for lease payment for operating lease due after fifth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_LesseeOperatingLeaseLiabilityPaymentsDueNextTwelveMonths": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LesseeOperatingLeaseLiabilityPaymentsDueNextTwelveMonths", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2027", "label": "Lessee, Operating Lease, Liability, to be Paid, Year One", "documentation": "Amount of lessee's undiscounted obligation for lease payment for operating lease to be paid in next fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_LesseeOperatingLeaseLiabilityPaymentsDueYearFive": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LesseeOperatingLeaseLiabilityPaymentsDueYearFive", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2031", "label": "Lessee, Operating Lease, Liability, to be Paid, Year Five", "documentation": "Amount of lessee's undiscounted obligation for lease payment for operating lease to be paid in fifth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_LesseeOperatingLeaseLiabilityPaymentsDueYearFour": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LesseeOperatingLeaseLiabilityPaymentsDueYearFour", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2030", "label": "Lessee, Operating Lease, Liability, to be Paid, Year Four", "documentation": "Amount of lessee's undiscounted obligation for lease payment for operating lease to be paid in fourth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_LesseeOperatingLeaseLiabilityPaymentsDueYearThree": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LesseeOperatingLeaseLiabilityPaymentsDueYearThree", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2029", "label": "Lessee, Operating Lease, Liability, to be Paid, Year Three", "documentation": "Amount of lessee's undiscounted obligation for lease payment for operating lease to be paid in third fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_LesseeOperatingLeaseLiabilityPaymentsDueYearTwo": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LesseeOperatingLeaseLiabilityPaymentsDueYearTwo", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2028", "label": "Lessee, Operating Lease, Liability, to be Paid, Year Two", "documentation": "Amount of lessee's undiscounted obligation for lease payment for operating lease to be paid in second fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r709", "r1360", "r1367", "r1561" ] }, "us-gaap_LesseeOperatingLeaseLiabilityUndiscountedExcessAmount": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LesseeOperatingLeaseLiabilityUndiscountedExcessAmount", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Less amount representing interest", "label": "Lessee, Operating Lease, Liability, Undiscounted Excess Amount", "documentation": "Amount of lessee's undiscounted obligation for lease payments in excess of discounted obligation for lease payments for operating lease." } } }, "auth_ref": [ "r709" ] }, "us-gaap_LesseeOperatingLeasesTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LesseeOperatingLeasesTextBlock", "presentation": [ "http://www.costco.com/role/Leases" ], "lang": { "en-us": { "role": { "terseLabel": "Lessee, Operating Leases", "label": "Lessee, Operating Leases [Text Block]", "documentation": "The entire disclosure for operating leases of lessee. Includes, but is not limited to, description of operating lease and maturity analysis of operating lease liability." } } }, "auth_ref": [ "r691" ] }, "cost_LesseeOperatingandFinancingLeasesNotYetCommenced": { "xbrltype": "monetaryItemType", "nsuri": "http://www.costco.com/20260830", "localname": "LesseeOperatingandFinancingLeasesNotYetCommenced", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "LesseeOperatingandFinancingLeasesNotYetCommenced", "label": "LesseeOperatingandFinancingLeasesNotYetCommenced", "documentation": "LesseeOperatingandFinancingLeasesNotYetCommenced" } } }, "auth_ref": [] }, "us-gaap_LessorOperatingLeasePaymentsToBeReceived": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LessorOperatingLeasePaymentsToBeReceived", "crdr": "debit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Lessor, Operating Lease, Payments to be Received", "label": "Lessor, Operating Lease, Payment to be Received", "documentation": "Amount of lease payments to be received by lessor for operating lease." } } }, "auth_ref": [ "r711" ] }, "us-gaap_Liabilities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "Liabilities", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_LiabilitiesAndStockholdersEquity", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "totalLabel": "TOTAL LIABILITIES", "label": "Liabilities", "documentation": "Amount of liability recognized for present obligation requiring transfer or otherwise providing economic benefit to others." } } }, "auth_ref": [ "r103", "r104", "r178", "r181", "r182", "r305", "r368", "r369", "r371", "r372", "r373", "r374", "r375", "r377", "r378", "r449", "r591", "r592", "r593", "r679", "r927", "r1047", "r1070", "r1148", "r1297", "r1436", "r1550", "r1551" ] }, "us-gaap_LiabilitiesAndStockholdersEquity": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LiabilitiesAndStockholdersEquity", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "totalLabel": "TOTAL LIABILITIES AND EQUITY", "label": "Liabilities and Equity", "documentation": "Amount of liabilities and equity items, including the portion of equity attributable to noncontrolling interests, if any." } } }, "auth_ref": [ "r149", "r790", "r791", "r802", "r843", "r1118", "r1136", "r1137", "r1359", "r1364", "r1404", "r1543" ] }, "us-gaap_LiabilitiesAndStockholdersEquityAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LiabilitiesAndStockholdersEquityAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "LIABILITIES AND EQUITY", "label": "Liabilities and Equity [Abstract]" } } }, "auth_ref": [] }, "us-gaap_LiabilitiesCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LiabilitiesCurrent", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_Liabilities", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "totalLabel": "Total current liabilities", "label": "Liabilities, Current", "documentation": "Total obligations incurred as part of normal operations that are expected to be paid during the following twelve months or within one business cycle, if longer." } } }, "auth_ref": [ "r103", "r104", "r107", "r127", "r178", "r181", "r182", "r305", "r368", "r369", "r371", "r372", "r373", "r374", "r375", "r377", "r378", "r449", "r591", "r592", "r593", "r679", "r1118", "r1436", "r1550", "r1551" ] }, "us-gaap_LiabilitiesCurrentAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LiabilitiesCurrentAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "CURRENT LIABILITIES", "label": "Liabilities, Current [Abstract]" } } }, "auth_ref": [] }, "us-gaap_LiabilitiesFairValueDisclosure": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LiabilitiesFairValueDisclosure", "crdr": "credit", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails" ], "lang": { "en-us": { "role": { "negatedLabel": "Fair value of liabilities measured on recurring basis", "label": "Liabilities, Fair Value Disclosure", "documentation": "Fair value of financial and nonfinancial obligations." } } }, "auth_ref": [ "r656", "r1523" ] }, "us-gaap_LineOfCreditFacilityCurrentBorrowingCapacity": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LineOfCreditFacilityCurrentBorrowingCapacity", "crdr": "credit", "presentation": [ "http://www.costco.com/role/DebtScheduleOfShortTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Line of credit facility, current borrowing capacity", "label": "Line of Credit Facility, Current Borrowing Capacity", "documentation": "Amount of current borrowing capacity under the credit facility considering any current restrictions on the amount that could be borrowed (for example, borrowings may be limited by the amount of current assets), but without considering any amounts currently outstanding under the facility." } } }, "auth_ref": [ "r1282", "r1286" ] }, "us-gaap_LineOfCreditFacilityLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LineOfCreditFacilityLineItems", "presentation": [ "http://www.costco.com/role/DebtScheduleOfShortTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Line of Credit Facility [Line Items]", "label": "Line of Credit Facility [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r115", "r124", "r367", "r790", "r791", "r794", "r1359", "r1362", "r1435" ] }, "us-gaap_LineOfCreditFacilityTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LineOfCreditFacilityTable", "presentation": [ "http://www.costco.com/role/DebtScheduleOfShortTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Line of Credit Facility [Table]", "label": "Line of Credit Facility [Table]", "documentation": "Disclosure of information about short-term and long-term contractual arrangements with lender under which borrowing can occur up to maximum amount. Includes, but is not limited to, letter of credit, standby letter of credit, and revolving credit arrangement." } } }, "auth_ref": [ "r115", "r124", "r367", "r790", "r791", "r794", "r1359", "r1362", "r1435" ] }, "dei_LocalPhoneNumber": { "xbrltype": "normalizedStringItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "LocalPhoneNumber", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Local Phone Number", "label": "Local Phone Number", "documentation": "Local phone number for entity." } } }, "auth_ref": [] }, "us-gaap_LongTermDebtCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LongTermDebtCurrent", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_LiabilitiesCurrent", "weight": 1.0, "order": 5.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets", "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Current portion of long-term debt", "label": "Long-Term Debt, Current Maturities", "documentation": "Amount, after deduction of unamortized premium (discount) and debt issuance cost, of long-term debt classified as current. Excludes lease obligation." } } }, "auth_ref": [ "r1030", "r1031" ] }, "us-gaap_LongTermDebtFairValue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LongTermDebtFairValue", "crdr": "credit", "presentation": [ "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Long-term Debt, Fair Value", "label": "Long-Term Debt, Fair Value", "documentation": "The fair value amount of long-term debt whether such amount is presented as a separate caption or as a parenthetical disclosure. Additionally, this element may be used in connection with the fair value disclosures required in the footnote disclosures to the financial statements. The element may be used in both the balance sheet and disclosure in the same submission." } } }, "auth_ref": [ "r1114", "r1115", "r1523", "r1525", "r1526", "r1527", "r1539", "r1540", "r1541", "r1542" ] }, "us-gaap_LongTermDebtMaturitiesRepaymentsOfPrincipalAfterYearFive": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LongTermDebtMaturitiesRepaymentsOfPrincipalAfterYearFive", "crdr": "credit", "presentation": [ "http://www.costco.com/role/DebtScheduleOfLongTermDebtMaturitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Thereafter", "label": "Long-Term Debt, Maturity, after Year Five", "documentation": "Amount of long-term debt payable, sinking fund requirement, and other securities issued that are redeemable by holder at fixed or determinable price and date, maturing after fifth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r5", "r1360", "r1367", "r1440", "r1561" ] }, "us-gaap_LongTermDebtMaturitiesRepaymentsOfPrincipalInNextTwelveMonths": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LongTermDebtMaturitiesRepaymentsOfPrincipalInNextTwelveMonths", "crdr": "credit", "presentation": [ "http://www.costco.com/role/DebtScheduleOfLongTermDebtMaturitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2027", "label": "Long-Term Debt, Maturity, Year One", "documentation": "Amount of long-term debt payable, sinking fund requirement, and other securities issued that are redeemable by holder at fixed or determinable price and date, maturing in next fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r5", "r179", "r188", "r397", "r811" ] }, "us-gaap_LongTermDebtMaturitiesRepaymentsOfPrincipalInYearFive": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LongTermDebtMaturitiesRepaymentsOfPrincipalInYearFive", "crdr": "credit", "presentation": [ "http://www.costco.com/role/DebtScheduleOfLongTermDebtMaturitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2031", "label": "Long-Term Debt, Maturity, Year Five", "documentation": "Amount of long-term debt payable, sinking fund requirement, and other securities issued that are redeemable by holder at fixed or determinable price and date, maturing in fifth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r5", "r179", "r188", "r397", "r811" ] }, "us-gaap_LongTermDebtMaturitiesRepaymentsOfPrincipalInYearFour": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LongTermDebtMaturitiesRepaymentsOfPrincipalInYearFour", "crdr": "credit", "presentation": [ "http://www.costco.com/role/DebtScheduleOfLongTermDebtMaturitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2030", "label": "Long-Term Debt, Maturity, Year Four", "documentation": "Amount of long-term debt payable, sinking fund requirement, and other securities issued that are redeemable by holder at fixed or determinable price and date, maturing in fourth fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r5", "r179", "r188", "r397", "r811" ] }, "us-gaap_LongTermDebtMaturitiesRepaymentsOfPrincipalInYearThree": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LongTermDebtMaturitiesRepaymentsOfPrincipalInYearThree", "crdr": "credit", "presentation": [ "http://www.costco.com/role/DebtScheduleOfLongTermDebtMaturitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2029", "label": "Long-Term Debt, Maturity, Year Three", "documentation": "Amount of long-term debt payable, sinking fund requirement, and other securities issued that are redeemable by holder at fixed or determinable price and date, maturing in third fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r5", "r179", "r188", "r397", "r811" ] }, "us-gaap_LongTermDebtMaturitiesRepaymentsOfPrincipalInYearTwo": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LongTermDebtMaturitiesRepaymentsOfPrincipalInYearTwo", "crdr": "credit", "presentation": [ "http://www.costco.com/role/DebtScheduleOfLongTermDebtMaturitiesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2028", "label": "Long-Term Debt, Maturity, Year Two", "documentation": "Amount of long-term debt payable, sinking fund requirement, and other securities issued that are redeemable by holder at fixed or determinable price and date, maturing in second fiscal year following current fiscal year. Excludes interim and annual periods when interim periods are reported from current statement of financial position date (rolling approach)." } } }, "auth_ref": [ "r5", "r179", "r188", "r397", "r811" ] }, "us-gaap_LongTermDebtNoncurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LongTermDebtNoncurrent", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_Liabilities", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets", "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Long-term debt, excluding current portion", "label": "Long-Term Debt, Excluding Current Maturities", "documentation": "Amount, after deduction of unamortized premium (discount) and debt issuance cost, of long-term debt classified as noncurrent. Excludes lease obligation." } } }, "auth_ref": [ "r1283", "r1289" ] }, "cost_LongTermOperatingAndFinanceLeaseLiabilitiesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://www.costco.com/20260830", "localname": "LongTermOperatingAndFinanceLeaseLiabilitiesAbstract", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Long-Term Operating and Finance Lease Liabilities [Abstract]", "label": "Long-Term Operating and Finance Lease Liabilities [Abstract]", "documentation": "Long-Term Operating and Finance Lease Liabilities" } } }, "auth_ref": [] }, "us-gaap_LongtermDebtTypeAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LongtermDebtTypeAxis", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails", "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Long-term Debt, Type [Axis]", "label": "Long-Term Debt, Type [Axis]", "documentation": "Information by type of long-term debt." } } }, "auth_ref": [ "r116", "r128", "r129", "r130", "r131", "r132", "r790", "r791", "r796", "r1427", "r1428", "r1429" ] }, "us-gaap_LongtermDebtTypeDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "LongtermDebtTypeDomain", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails", "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Long-term Debt, Type [Domain]", "label": "Long-Term Debt, Type [Domain]", "documentation": "Type of long-term debt arrangement, such as notes, line of credit, commercial paper, asset-based financing, project financing, letter of credit financing. These are debt arrangements that originally required repayment more than twelve months after issuance or greater than the normal operating cycle of the company, if longer." } } }, "auth_ref": [ "r11", "r116", "r128", "r129", "r130", "r131", "r132", "r790", "r791", "r796", "r1427", "r1428", "r1429" ] }, "country_MX": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "MX", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails", "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "MEXICO", "label": "MEXICO" } } }, "auth_ref": [] }, "srt_MaximumMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "MaximumMember", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails", "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails", "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails", "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Maximum [Member]", "label": "Maximum [Member]", "documentation": "Upper limit of the provided range." } } }, "auth_ref": [ "r59", "r61", "r63", "r64", "r66", "r83", "r85", "r86", "r97", "r98", "r105", "r106", "r232", "r362", "r363", "r364", "r365", "r483", "r515", "r516", "r517", "r533", "r659", "r720", "r721", "r722", "r723", "r725", "r726", "r727", "r728", "r752", "r875", "r876", "r883", "r919", "r920", "r974", "r978", "r980", "r981", "r991", "r1006", "r1007", "r1009", "r1010", "r1021", "r1022", "r1058", "r1084", "r1088", "r1091", "r1092", "r1107", "r1108", "r1112", "r1113", "r1131", "r1438", "r1441" ] }, "ecd_MeasureAxis": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "MeasureAxis", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Measure:", "label": "Measure [Axis]" } } }, "auth_ref": [ "r1211" ] }, "ecd_MeasureName": { "xbrltype": "normalizedStringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "MeasureName", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Name", "label": "Measure Name" } } }, "auth_ref": [ "r1211" ] }, "us-gaap_MembershipMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "MembershipMember", "presentation": [ "http://www.costco.com/role/AccountingPoliciesRevenueRecognitionDetails", "http://www.costco.com/role/ConsolidatedStatementsOfIncome" ], "lang": { "en-us": { "role": { "terseLabel": "Membership fees", "verboseLabel": "Membership [Member]", "label": "Membership [Member]", "documentation": "Conveyance of right to use facility or service by organization, association, or club." } } }, "auth_ref": [ "r1451", "r1452" ] }, "srt_MinimumMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "MinimumMember", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails", "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails", "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Minimum [Member]", "label": "Minimum [Member]", "documentation": "Lower limit of the provided range." } } }, "auth_ref": [ "r59", "r61", "r63", "r64", "r66", "r83", "r85", "r86", "r97", "r98", "r105", "r106", "r232", "r362", "r363", "r364", "r365", "r483", "r515", "r516", "r517", "r533", "r659", "r720", "r721", "r722", "r723", "r725", "r726", "r727", "r728", "r752", "r875", "r876", "r883", "r919", "r920", "r974", "r978", "r980", "r981", "r991", "r1006", "r1007", "r1009", "r1010", "r1021", "r1022", "r1058", "r1084", "r1088", "r1091", "r1092", "r1107", "r1108", "r1112", "r1131", "r1438", "r1441" ] }, "cost_MinimumNumberOfDaysOfEmploymentToQualifyForRetirementPlan": { "xbrltype": "durationItemType", "nsuri": "http://www.costco.com/20260830", "localname": "MinimumNumberOfDaysOfEmploymentToQualifyForRetirementPlan", "presentation": [ "http://www.costco.com/role/AccountingPoliciesRetirementPlansDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Minimum number of days of employment to qualify for retirement plan", "label": "Minimum Number Of Days Of Employment To Qualify For Retirement Plan", "documentation": "Minimum number of days of employment to qualify for 401(k) Retirement Plan" } } }, "auth_ref": [] }, "ecd_MnpiDiscTimedForCompValFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "MnpiDiscTimedForCompValFlag", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "MNPI Disclosure Timed for Compensation Value", "label": "MNPI Disclosure Timed for Compensation Value [Flag]" } } }, "auth_ref": [ "r1231" ] }, "ecd_MtrlTermsOfTrdArrTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "MtrlTermsOfTrdArrTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Material Terms of Trading Arrangement", "label": "Material Terms of Trading Arrangement [Text Block]" } } }, "auth_ref": [ "r1239" ] }, "country_NZ": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "NZ", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "NEW ZEALAND", "label": "NEW ZEALAND" } } }, "auth_ref": [] }, "ecd_NamedExecutiveOfficersFnTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "NamedExecutiveOfficersFnTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Named Executive Officers, Footnote", "label": "Named Executive Officers, Footnote [Text Block]" } } }, "auth_ref": [ "r1212" ] }, "us-gaap_NetCashProvidedByUsedInFinancingActivities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "NetCashProvidedByUsedInFinancingActivities", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_CashCashEquivalentsRestrictedCashAndRestrictedCashEquivalentsPeriodIncreaseDecreaseIncludingExchangeRateEffect", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "totalLabel": "Net cash used in financing activities", "label": "Cash Provided by (Used in) Financing Activity, Including Discontinued Operation", "documentation": "Amount of cash inflow (outflow) from financing activity, including, but not limited to, discontinued operation. Financing activity includes, but is not limited to, obtaining resource from owner and providing return on, and return of, their investment; borrowing money and repaying amount borrowed, or settling obligation; and obtaining and paying for other resource obtained from creditor on long-term credit." } } }, "auth_ref": [ "r168" ] }, "us-gaap_NetCashProvidedByUsedInFinancingActivitiesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "NetCashProvidedByUsedInFinancingActivitiesAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "CASH FLOWS FROM FINANCING ACTIVITIES", "label": "Cash Provided by (Used in) Financing Activity, Including Discontinued Operation [Abstract]" } } }, "auth_ref": [] }, "us-gaap_NetCashProvidedByUsedInInvestingActivities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "NetCashProvidedByUsedInInvestingActivities", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_CashCashEquivalentsRestrictedCashAndRestrictedCashEquivalentsPeriodIncreaseDecreaseIncludingExchangeRateEffect", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "totalLabel": "Net cash used in investing activities", "label": "Cash Provided by (Used in) Investing Activity, Including Discontinued Operation", "documentation": "Amount of cash inflow (outflow) from investing activity, including, but not limited to, discontinued operation. Investing activity includes, but is not limited to, making and collecting loan, acquiring and disposing of debt and equity instruments, property, plant, and equipment, and other productive assets." } } }, "auth_ref": [ "r168" ] }, "us-gaap_NetCashProvidedByUsedInInvestingActivitiesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "NetCashProvidedByUsedInInvestingActivitiesAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "CASH FLOWS FROM INVESTING ACTIVITIES", "label": "Cash Provided by (Used in) Investing Activity, Including Discontinued Operation [Abstract]" } } }, "auth_ref": [] }, "us-gaap_NetCashProvidedByUsedInOperatingActivities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "NetCashProvidedByUsedInOperatingActivities", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_CashCashEquivalentsRestrictedCashAndRestrictedCashEquivalentsPeriodIncreaseDecreaseIncludingExchangeRateEffect", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "totalLabel": "Net cash provided by operating activities", "label": "Cash Provided by (Used in) Operating Activity, Including Discontinued Operation", "documentation": "Amount of cash inflow (outflow) from operating activity, including, but not limited to, discontinued operation. Operating activity includes, but is not limited to, transaction, adjustment, and change in value not defined as investing or financing activity." } } }, "auth_ref": [ "r29", "r30", "r32" ] }, "us-gaap_NetCashProvidedByUsedInOperatingActivitiesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "NetCashProvidedByUsedInOperatingActivitiesAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "CASH FLOWS FROM OPERATING ACTIVITIES", "label": "Cash Provided by (Used in) Operating Activity, Including Discontinued Operation [Abstract]" } } }, "auth_ref": [] }, "us-gaap_NetIncomeLoss": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "NetIncomeLoss", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfComprehensiveIncome": { "parentTag": "us-gaap_ComprehensiveIncomeNetOfTax", "weight": 1.0, "order": 1.0 }, "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInOperatingActivities", "weight": 1.0, "order": 1.0 }, "http://www.costco.com/role/ConsolidatedStatementsOfIncome": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows", "http://www.costco.com/role/ConsolidatedStatementsOfComprehensiveIncome", "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/ConsolidatedStatementsofEquity", "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareScheduleofEarningsperShareEffectonNetIncomeandWeightedAveregaeNumberofDilutivePotentialCommonStockDetails" ], "lang": { "en-us": { "role": { "totalLabel": "NET INCOME", "terseLabel": "NET INCOME", "label": "Net Income (Loss) Attributable to Parent", "documentation": "The portion of profit or loss for the period, net of income taxes, which is attributable to the parent." } } }, "auth_ref": [ "r23", "r32", "r40", "r100", "r103", "r104", "r154", "r156", "r161", "r178", "r181", "r182", "r186", "r192", "r196", "r197", "r198", "r199", "r200", "r203", "r204", "r214", "r305", "r343", "r368", "r369", "r371", "r372", "r373", "r374", "r375", "r377", "r378", "r408", "r411", "r414", "r419", "r449", "r469", "r524", "r584", "r589", "r652", "r679", "r848", "r948", "r965", "r966", "r1037", "r1039", "r1040", "r1147", "r1436" ] }, "us-gaap_NewAccountingPronouncementsPolicyPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "NewAccountingPronouncementsPolicyPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Recent Accounting Pronouncements Adopted and Not Yet Adopted", "label": "New Accounting Pronouncements, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy pertaining to new accounting pronouncements that may impact the entity's financial reporting. Includes, but is not limited to, quantification of the expected or actual impact." } } }, "auth_ref": [ "r205" ] }, "cost_NonFoodsMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "NonFoodsMember", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Non-Foods [Member]", "label": "Non-Foods [Member]", "documentation": "Non-Foods [Member]" } } }, "auth_ref": [] }, "ecd_NonGaapMeasureDescriptionTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "NonGaapMeasureDescriptionTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Non-GAAP Measure Description", "label": "Non-GAAP Measure Description [Text Block]" } } }, "auth_ref": [ "r1211" ] }, "ecd_NonNeosMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "NonNeosMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Non-NEOs", "label": "Non-NEOs [Member]" } } }, "auth_ref": [ "r1174", "r1185", "r1195", "r1219", "r1228" ] }, "ecd_NonPeoNeoAvgCompActuallyPaidAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "NonPeoNeoAvgCompActuallyPaidAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Non-PEO NEO Average Compensation Actually Paid Amount", "label": "Non-PEO NEO Average Compensation Actually Paid Amount" } } }, "auth_ref": [ "r1202" ] }, "ecd_NonPeoNeoAvgTotalCompAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "NonPeoNeoAvgTotalCompAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Non-PEO NEO Average Total Compensation Amount", "label": "Non-PEO NEO Average Total Compensation Amount" } } }, "auth_ref": [ "r1201" ] }, "ecd_NonPeoNeoMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "NonPeoNeoMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Non-PEO NEO", "label": "Non-PEO NEO [Member]" } } }, "auth_ref": [ "r1219" ] }, "ecd_NonRule10b51ArrAdoptedFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "NonRule10b51ArrAdoptedFlag", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Non-Rule 10b5-1 Arrangement Adopted", "label": "Non-Rule 10b5-1 Arrangement Adopted [Flag]" } } }, "auth_ref": [ "r1239" ] }, "ecd_NonRule10b51ArrTrmntdFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "NonRule10b51ArrTrmntdFlag", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Non-Rule 10b5-1 Arrangement Terminated", "label": "Non-Rule 10b5-1 Arrangement Terminated [Flag]" } } }, "auth_ref": [ "r1239" ] }, "us-gaap_NumberOfReportableSegments": { "xbrltype": "integerItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "NumberOfReportableSegments", "presentation": [ "http://www.costco.com/role/SegmentReportingNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Number of Reportable Segments", "label": "Number of Reportable Segments", "documentation": "Number of segments reported by the entity. A reportable segment is a component of an entity for which there is an accounting requirement to report separate financial information on that component in the entity's financial statements." } } }, "auth_ref": [ "r1049", "r1057", "r1377" ] }, "us-gaap_NumberOfStatesInWhichEntityOperates": { "xbrltype": "integerItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "NumberOfStatesInWhichEntityOperates", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Number of states in country", "label": "Number of States in which Entity Operates", "documentation": "The number of states the entity operates in as of the balance sheet date." } } }, "auth_ref": [ "r1375" ] }, "us-gaap_NumberOfStores": { "xbrltype": "integerItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "NumberOfStores", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Number of warehouses operated", "label": "Number of Stores", "documentation": "Represents the number of stores." } } }, "auth_ref": [ "r1375" ] }, "us-gaap_OperatingExpensesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingExpensesAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome" ], "lang": { "en-us": { "role": { "terseLabel": "OPERATING EXPENSES", "label": "Operating Expenses [Abstract]" } } }, "auth_ref": [] }, "us-gaap_OperatingIncomeLoss": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingIncomeLoss", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfIncome": { "parentTag": "us-gaap_IncomeLossAttributableToParent", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Operating income", "verboseLabel": "Operating income", "label": "Operating Income (Loss)", "documentation": "The net result for the period of deducting operating expenses from operating revenues." } } }, "auth_ref": [ "r1037", "r1040", "r1048", "r1277", "r1278", "r1374", "r1378", "r1384", "r1387", "r1388", "r1404" ] }, "cost_OperatingLeaseAndFinanceLeaseLiabilitiesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://www.costco.com/20260830", "localname": "OperatingLeaseAndFinanceLeaseLiabilitiesAbstract", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Operating Lease and Finance Lease Liabilities [Abstract]", "label": "Operating Lease and Finance Lease Liabilities [Abstract]", "documentation": "Operating Lease and Finance Lease Liabilities" } } }, "auth_ref": [] }, "cost_OperatingLeaseAnfFinanceLeaseRightOfUseAssetsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://www.costco.com/20260830", "localname": "OperatingLeaseAnfFinanceLeaseRightOfUseAssetsAbstract", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Operating Lease and Finance Lease Right-of-Use-Assets [Abstract]", "label": "Operating Lease anf Finance Lease Right-of-Use-Assets [Abstract]", "documentation": "Operating Lease and Finance Lease Right-of-Use-Assets" } } }, "auth_ref": [] }, "us-gaap_OperatingLeaseCost": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingLeaseCost", "crdr": "debit", "calculation": { "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails": { "parentTag": "us-gaap_LeaseCost", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Operating Lease, Cost", "label": "Operating Lease, Cost", "documentation": "Amount of single lease cost, calculated by allocation of remaining cost of lease over remaining lease term. Includes, but is not limited to, single lease cost, after impairment of right-of-use asset, calculated by amortization of remaining right-of-use asset and accretion of lease liability." } } }, "auth_ref": [ "r703", "r1117" ] }, "us-gaap_OperatingLeaseLiabilitiesPaymentsDueAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingLeaseLiabilitiesPaymentsDueAbstract", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Lessee, Operating Lease, Liability, to be Paid, Fiscal Year Maturity [Abstract]", "label": "Lessee, Operating Lease, Liability, to be Paid, Fiscal Year Maturity [Abstract]" } } }, "auth_ref": [] }, "us-gaap_OperatingLeaseLiability": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingLeaseLiability", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesFutureMinimumPaymentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Present value of lease liabilities", "label": "Operating Lease, Liability", "documentation": "Present value of lessee's discounted obligation for lease payments from operating lease." } } }, "auth_ref": [ "r694" ] }, "us-gaap_OperatingLeaseLiabilityCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingLeaseLiabilityCurrent", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Current operating lease liabilities", "label": "Operating Lease, Liability, Current", "documentation": "Present value of lessee's discounted obligation for lease payments from operating lease, classified as current." } } }, "auth_ref": [ "r694", "r1029" ] }, "us-gaap_OperatingLeaseLiabilityCurrentStatementOfFinancialPositionExtensibleList": { "xbrltype": "enumerationSetItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingLeaseLiabilityCurrentStatementOfFinancialPositionExtensibleList", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Operating lease liabilities", "label": "Operating Lease, Liability, Current, Statement of Financial Position [Extensible Enumeration]", "documentation": "Indicates line item in statement of financial position that includes current operating lease liability." } } }, "auth_ref": [ "r695" ] }, "us-gaap_OperatingLeaseLiabilityNoncurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingLeaseLiabilityNoncurrent", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_Liabilities", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets", "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Long-term operating lease liabilities", "label": "Operating Lease, Liability, Noncurrent", "documentation": "Present value of lessee's discounted obligation for lease payments from operating lease, classified as noncurrent." } } }, "auth_ref": [ "r694" ] }, "us-gaap_OperatingLeasePayments": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingLeasePayments", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesSupplementalCashFlowInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Operating cash flows - operating leases", "label": "Operating Lease, Payments", "documentation": "Amount of cash outflow from operating lease, excluding payments to bring another asset to condition and location necessary for its intended use." } } }, "auth_ref": [ "r699", "r705" ] }, "us-gaap_OperatingLeaseRightOfUseAsset": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingLeaseRightOfUseAsset", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_Assets", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets", "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Operating lease right-of-use assets", "label": "Operating Lease, Right-of-Use Asset", "documentation": "Amount of lessee's right to use underlying asset under operating lease." } } }, "auth_ref": [ "r693" ] }, "us-gaap_OperatingLeaseWeightedAverageDiscountRatePercent": { "xbrltype": "percentItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingLeaseWeightedAverageDiscountRatePercent", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Operating Lease, Weighted Average Discount Rate, Percent", "label": "Operating Lease, Weighted Average Discount Rate, Percent", "documentation": "Weighted average discount rate for operating lease calculated at point in time." } } }, "auth_ref": [ "r708", "r1117" ] }, "us-gaap_OperatingLeaseWeightedAverageRemainingLeaseTerm1": { "xbrltype": "durationItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingLeaseWeightedAverageRemainingLeaseTerm1", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Operating Lease, Weighted Average Remaining Lease Term", "label": "Operating Lease, Weighted Average Remaining Lease Term", "documentation": "Weighted average remaining lease term for operating lease, in 'PnYnMnDTnHnMnS' format, for example, 'P1Y5M13D' represents reported fact of one year, five months, and thirteen days." } } }, "auth_ref": [ "r707", "r1117" ] }, "cost_OperatingLeaseandFinanceLeaseLiabilities": { "xbrltype": "monetaryItemType", "nsuri": "http://www.costco.com/20260830", "localname": "OperatingLeaseandFinanceLeaseLiabilities", "crdr": "credit", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "OperatingLeaseandFinanceLeaseLiabilities", "label": "OperatingLeaseandFinanceLeaseLiabilities", "documentation": "OperatingLeaseandFinanceLeaseLiabilities" } } }, "auth_ref": [] }, "cost_OperatingLeaseandFinanceLeaserightofuseassets": { "xbrltype": "monetaryItemType", "nsuri": "http://www.costco.com/20260830", "localname": "OperatingLeaseandFinanceLeaserightofuseassets", "crdr": "debit", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "OperatingLeaseandFinanceLeaserightofuseassets", "label": "OperatingLeaseandFinanceLeaserightofuseassets", "documentation": "OperatingLeaseandFinanceLeaserightofuseassets" } } }, "auth_ref": [] }, "us-gaap_OperatingSegmentsMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OperatingSegmentsMember", "presentation": [ "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Operating Segments", "label": "Operating Segments [Member]", "documentation": "Identifies components of an entity that engage in business activities from which they may earn revenue and incur expenses, including transactions with other components of the same entity." } } }, "auth_ref": [ "r254", "r255", "r256", "r257", "r258", "r261", "r1053", "r1054" ] }, "cost_OperatingandFinancingLeaseRightofUseAssetAmortization": { "xbrltype": "monetaryItemType", "nsuri": "http://www.costco.com/20260830", "localname": "OperatingandFinancingLeaseRightofUseAssetAmortization", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInOperatingActivities", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "Non-cash lease expense", "label": "OperatingandFinancingLeaseRightofUseAssetAmortization", "documentation": "Amount of Amortization expense attributable to right-of-use asset from operating and finance lease." } } }, "auth_ref": [] }, "us-gaap_OtherAssetsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OtherAssetsAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "OTHER ASSETS", "label": "Other Assets [Abstract]" } } }, "auth_ref": [] }, "us-gaap_OtherAssetsCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OtherAssetsCurrent", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_AssetsCurrent", "weight": 1.0, "order": 5.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Other current assets", "label": "Other Assets, Current", "documentation": "Amount of current assets classified as other." } } }, "auth_ref": [ "r152", "r1118" ] }, "us-gaap_OtherAssetsNoncurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OtherAssetsNoncurrent", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_Assets", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Other long-term assets", "label": "Other Assets, Noncurrent", "documentation": "Amount of noncurrent assets classified as other." } } }, "auth_ref": [ "r114", "r121" ] }, "us-gaap_OtherComprehensiveIncomeLossForeignCurrencyTransactionAndTranslationAdjustmentNetOfTax": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OtherComprehensiveIncomeLossForeignCurrencyTransactionAndTranslationAdjustmentNetOfTax", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfComprehensiveIncome": { "parentTag": "us-gaap_ComprehensiveIncomeNetOfTax", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfComprehensiveIncome", "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Foreign-currency translation adjustment and other, net", "label": "Other Comprehensive Income (Loss), Foreign Currency Transaction and Translation Adjustment, Net of Tax", "documentation": "Amount after tax and reclassification adjustments of gain (loss) on foreign currency translation adjustments, foreign currency transactions designated and effective as economic hedges of a net investment in a foreign entity and intra-entity foreign currency transactions that are of a long-term-investment nature." } } }, "auth_ref": [ "r2", "r849" ] }, "us-gaap_OtherIncome": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OtherIncome", "crdr": "credit", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Other Income", "label": "Other Income", "documentation": "Amount of revenue and income classified as other." } } }, "auth_ref": [ "r855", "r950", "r992", "r993", "r994", "r1136", "r1137" ] }, "cost_OtherInternationalMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "OtherInternationalMember", "presentation": [ "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails", "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Other International", "label": "Other International [Member]", "documentation": "Other International [Member]" } } }, "auth_ref": [] }, "us-gaap_OtherLiabilitiesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OtherLiabilitiesAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "OTHER LIABILITIES", "label": "Other Liabilities [Abstract]" } } }, "auth_ref": [] }, "us-gaap_OtherLiabilitiesCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OtherLiabilitiesCurrent", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_LiabilitiesCurrent", "weight": 1.0, "order": 6.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Other current liabilities", "label": "Other Liabilities, Current", "documentation": "Amount of liabilities classified as other, due within one year or the normal operating cycle, if longer." } } }, "auth_ref": [ "r115", "r123", "r126", "r1118" ] }, "us-gaap_OtherLiabilitiesNoncurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OtherLiabilitiesNoncurrent", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_Liabilities", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Other long-term liabilities", "label": "Other Liabilities, Noncurrent", "documentation": "Amount of liabilities classified as other, due after one year or the normal operating cycle, if longer." } } }, "auth_ref": [ "r136", "r1290" ] }, "cost_OtherLongTermDebtMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "OtherLongTermDebtMember", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Other Long Term Debt", "label": "Other Long Term Debt [Member]", "documentation": "Other Long Term Debt [Member]" } } }, "auth_ref": [] }, "cost_OtherMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "OtherMember", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Warehouse ancillary and other businesses", "label": "Other [Member]", "documentation": "Other [Member]" } } }, "auth_ref": [] }, "us-gaap_OtherNoncashIncomeExpense": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OtherNoncashIncomeExpense", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInOperatingActivities", "weight": -1.0, "order": 6.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Other Noncash Income (Expense)", "label": "Other Noncash Income (Expense)", "documentation": "Amount of income (expense) included in net income that results in no cash inflow (outflow), classified as other." } } }, "auth_ref": [ "r32" ] }, "us-gaap_OtherNonoperatingIncomeExpenseAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "OtherNonoperatingIncomeExpenseAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome" ], "lang": { "en-us": { "role": { "terseLabel": "OTHER INCOME (EXPENSE)", "label": "Other Nonoperating Income (Expense) [Abstract]" } } }, "auth_ref": [] }, "ecd_OtherPerfMeasureAmt": { "xbrltype": "decimalItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "OtherPerfMeasureAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Other Performance Measure, Amount", "label": "Other Performance Measure, Amount" } } }, "auth_ref": [ "r1211" ] }, "cost_OtherSupplementalBalanceSheetInformationAbstract": { "xbrltype": "stringItemType", "nsuri": "http://www.costco.com/20260830", "localname": "OtherSupplementalBalanceSheetInformationAbstract", "presentation": [ "http://www.costco.com/role/LeasesSupplementalBalanceSheetInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Other Supplemental Balance Sheet Information [Abstract]", "label": "Other Supplemental Balance Sheet Information [Abstract]", "documentation": "Other Supplemental Balance Sheet Information" } } }, "auth_ref": [] }, "ecd_OutstandingAggtErrCompAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "OutstandingAggtErrCompAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Outstanding Aggregate Erroneous Compensation Amount", "label": "Outstanding Aggregate Erroneous Compensation Amount" } } }, "auth_ref": [ "r1172", "r1183", "r1193", "r1226" ] }, "ecd_OutstandingRecoveryCompAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "OutstandingRecoveryCompAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Compensation Amount", "label": "Outstanding Recovery Compensation Amount" } } }, "auth_ref": [ "r1175", "r1186", "r1196", "r1229" ] }, "ecd_OutstandingRecoveryIndName": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "OutstandingRecoveryIndName", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Name", "label": "Outstanding Recovery, Individual Name" } } }, "auth_ref": [ "r1175", "r1186", "r1196", "r1229" ] }, "ecd_PayVsPerformanceDisclosureLineItems": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PayVsPerformanceDisclosureLineItems", "lang": { "en-us": { "role": { "label": "Pay vs Performance Disclosure [Line Items]" } } }, "auth_ref": [ "r1200" ] }, "us-gaap_PaymentsForProceedsFromOtherInvestingActivities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PaymentsForProceedsFromOtherInvestingActivities", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInInvestingActivities", "weight": -1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedLabel": "Other investing activities, net", "label": "Payment for (Proceeds from) Other Investing Activity", "documentation": "Amount of cash (inflow) outflow from investing activity, classified as other." } } }, "auth_ref": [ "r1353", "r1354" ] }, "us-gaap_PaymentsForRepurchaseOfCommonStock": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PaymentsForRepurchaseOfCommonStock", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInFinancingActivities", "weight": -1.0, "order": 6.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedLabel": "Repurchases of common stock", "label": "Payments for Repurchase of Common Stock", "documentation": "The cash outflow to reacquire common stock during the period." } } }, "auth_ref": [ "r27" ] }, "us-gaap_PaymentsOfDividendsCommonStock": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PaymentsOfDividendsCommonStock", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInFinancingActivities", "weight": -1.0, "order": 7.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Cash dividend payments", "label": "Payments of Ordinary Dividends, Common Stock", "documentation": "Amount of cash outflow in the form of ordinary dividends to common shareholders of the parent entity." } } }, "auth_ref": [ "r27" ] }, "us-gaap_PaymentsRelatedToTaxWithholdingForShareBasedCompensation": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PaymentsRelatedToTaxWithholdingForShareBasedCompensation", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInFinancingActivities", "weight": -1.0, "order": 5.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedLabel": "Tax withholdings on stock-based awards", "label": "Payment, Tax Withholding, Share-Based Payment Arrangement", "documentation": "Amount of cash outflow to satisfy grantee's tax withholding obligation for award under share-based payment arrangement." } } }, "auth_ref": [ "r166" ] }, "us-gaap_PaymentsToAcquirePropertyPlantAndEquipment": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PaymentsToAcquirePropertyPlantAndEquipment", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInInvestingActivities", "weight": -1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedLabel": "Additions to property and equipment", "label": "Payments to Acquire Property, Plant, and Equipment", "documentation": "The cash outflow associated with the acquisition of long-lived, physical assets that are used in the normal conduct of business to produce goods and services and not intended for resale; includes cash outflows to pay for construction of self-constructed assets." } } }, "auth_ref": [ "r26" ] }, "us-gaap_PaymentsToAcquireShortTermInvestments": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PaymentsToAcquireShortTermInvestments", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInInvestingActivities", "weight": -1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedLabel": "Purchases of short-term investments", "label": "Payments to Acquire Short-Term Investments", "documentation": "The cash outflow for securities or other assets acquired, which qualify for treatment as an investing activity and are to be liquidated, if necessary, within the current operating cycle. Includes cash flows from securities classified as trading securities that were acquired for reasons other than sale in the short-term." } } }, "auth_ref": [ "r25" ] }, "ecd_PeerGroupIssuersFnTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PeerGroupIssuersFnTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Peer Group Issuers, Footnote", "label": "Peer Group Issuers, Footnote [Text Block]" } } }, "auth_ref": [ "r1210" ] }, "ecd_PeerGroupTotalShareholderRtnAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PeerGroupTotalShareholderRtnAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Peer Group Total Shareholder Return Amount", "label": "Peer Group Total Shareholder Return Amount" } } }, "auth_ref": [ "r1210" ] }, "us-gaap_PensionAndOtherPostretirementPlansNonpensionBenefitsPolicy": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PensionAndOtherPostretirementPlansNonpensionBenefitsPolicy", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Retirement Plans", "label": "Pension and Other Postretirement Plans, Nonpension Benefits, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for plans, other than pension plans, that provide postretirement benefits (including both defined benefit and defined contribution plans). This accounting policy may address (1) the types of plans sponsored by the entity, and the benefits provided by each plan (2) groups that participate in (or are covered by) each plan (3) how plan assets, liabilities and expenses are measured, including the use of any actuaries and (4) significant assumptions used by the entity to value plan assets and liabilities and how such assumptions are derived." } } }, "auth_ref": [ "r12", "r13", "r14" ] }, "ecd_PeoActuallyPaidCompAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PeoActuallyPaidCompAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "PEO Actually Paid Compensation Amount", "label": "PEO Actually Paid Compensation Amount" } } }, "auth_ref": [ "r1202" ] }, "ecd_PeoMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PeoMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "PEO", "label": "PEO [Member]" } } }, "auth_ref": [ "r1219" ] }, "ecd_PeoName": { "xbrltype": "normalizedStringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PeoName", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "PEO Name", "label": "PEO Name" } } }, "auth_ref": [ "r1212" ] }, "ecd_PeoTotalCompAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PeoTotalCompAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "PEO Total Compensation Amount", "label": "PEO Total Compensation Amount" } } }, "auth_ref": [ "r1201" ] }, "us-gaap_PerformanceSharesMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PerformanceSharesMember", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Performance Shares [Member]", "label": "Performance Shares [Member]", "documentation": "Share-based payment arrangement awarded for meeting performance target." } } }, "auth_ref": [ "r1457", "r1458", "r1459", "r1460", "r1461", "r1462", "r1463", "r1464", "r1465", "r1466", "r1467", "r1468", "r1469", "r1470", "r1471", "r1472", "r1473", "r1474", "r1475", "r1476", "r1477", "r1478", "r1479", "r1480", "r1481", "r1482" ] }, "us-gaap_PlanNameAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PlanNameAxis", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Plan Name [Axis]", "label": "Plan Name [Axis]", "documentation": "Information by plan name for share-based payment arrangement." } } }, "auth_ref": [ "r1457", "r1458", "r1459", "r1460", "r1461", "r1462", "r1463", "r1464", "r1465", "r1466", "r1467", "r1468", "r1469", "r1470", "r1471", "r1472", "r1473", "r1474", "r1475", "r1476", "r1477", "r1478", "r1479", "r1480", "r1481", "r1482" ] }, "us-gaap_PlanNameDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PlanNameDomain", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Plan Name [Domain]", "label": "Plan Name [Domain]", "documentation": "Plan name for share-based payment arrangement." } } }, "auth_ref": [ "r1457", "r1458", "r1459", "r1460", "r1461", "r1462", "r1463", "r1464", "r1465", "r1466", "r1467", "r1468", "r1469", "r1470", "r1471", "r1472", "r1473", "r1474", "r1475", "r1476", "r1477", "r1478", "r1479", "r1480", "r1481", "r1482" ] }, "ecd_PnsnAdjsPrrSvcCstMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PnsnAdjsPrrSvcCstMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Pension Adjustments Prior Service Cost", "label": "Pension Adjustments Prior Service Cost [Member]" } } }, "auth_ref": [ "r1203" ] }, "ecd_PnsnAdjsSvcCstMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PnsnAdjsSvcCstMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Pension Adjustments Service Cost", "label": "Pension Adjustments Service Cost [Member]" } } }, "auth_ref": [ "r1259" ] }, "ecd_PnsnBnftsAdjFnTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PnsnBnftsAdjFnTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Pension Benefits Adjustments, Footnote", "label": "Pension Benefits Adjustments, Footnote [Text Block]" } } }, "auth_ref": [ "r1202" ] }, "us-gaap_PreferredStockParOrStatedValuePerShare": { "xbrltype": "perShareItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PreferredStockParOrStatedValuePerShare", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheetsParenthetical" ], "lang": { "en-us": { "role": { "terseLabel": "Preferred stock, par value (in dollars per share)", "label": "Preferred Stock, Par or Stated Value Per Share", "documentation": "Face amount or stated value per share of preferred stock nonredeemable or redeemable solely at the option of the issuer." } } }, "auth_ref": [ "r424", "r1280", "r1292", "r1444", "r1555", "r1556", "r1559" ] }, "us-gaap_PreferredStockSharesAuthorized": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PreferredStockSharesAuthorized", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheetsParenthetical" ], "lang": { "en-us": { "role": { "terseLabel": "Preferred stock, shares authorized", "label": "Preferred Stock, Shares Authorized", "documentation": "The maximum number of nonredeemable preferred shares (or preferred stock redeemable solely at the option of the issuer) permitted to be issued by an entity's charter and bylaws." } } }, "auth_ref": [ "r109", "r143", "r444", "r790", "r791", "r799", "r929" ] }, "us-gaap_PreferredStockSharesIssued": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PreferredStockSharesIssued", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheetsParenthetical" ], "lang": { "en-us": { "role": { "terseLabel": "Preferred stock, shares issued", "label": "Preferred Stock, Shares Issued", "documentation": "Number of shares issued for nonredeemable preferred shares and preferred shares redeemable solely at option of issuer. Includes, but is not limited to, preferred shares issued, repurchased, and held as treasury shares. Excludes preferred shares classified as debt." } } }, "auth_ref": [ "r109", "r143", "r424", "r444", "r790", "r791", "r799" ] }, "us-gaap_PreferredStockSharesOutstanding": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PreferredStockSharesOutstanding", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheetsParenthetical" ], "lang": { "en-us": { "role": { "terseLabel": "Preferred stock, shares outstanding", "label": "Preferred Stock, Shares Outstanding", "documentation": "Aggregate share number for all nonredeemable preferred stock (or preferred stock redeemable solely at the option of the issuer) held by stockholders. Does not include preferred shares that have been repurchased." } } }, "auth_ref": [ "r109", "r143", "r444", "r790", "r791", "r799", "r929", "r947", "r1443", "r1619", "r1620" ] }, "us-gaap_PreferredStockValue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PreferredStockValue", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_StockholdersEquity", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Preferred stock $.005 par value; 100,000,000 shares authorized; no shares issued and outstanding", "label": "Preferred Stock, Value, Issued", "documentation": "Aggregate par or stated value of issued nonredeemable preferred stock (or preferred stock redeemable solely at the option of the issuer). This item includes treasury stock repurchased by the entity. Note: elements for number of nonredeemable preferred shares, par value and other disclosure concepts are in another section within stockholders' equity." } } }, "auth_ref": [ "r109", "r143", "r410", "r416", "r444", "r790", "r791", "r799", "r839", "r1118" ] }, "us-gaap_PriorPeriodReclassificationAdjustmentDescription": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PriorPeriodReclassificationAdjustmentDescription", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Reclassification", "label": "Reclassification, Comparability Adjustment [Policy Text Block]", "documentation": "Disclosure of accounting policy for reclassification affecting comparability of financial statement. Excludes amendment to accounting standards, other change in accounting principle, and correction of error." } } }, "auth_ref": [ "r1276" ] }, "us-gaap_ProceedsFromIssuanceOfLongTermDebt": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ProceedsFromIssuanceOfLongTermDebt", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInFinancingActivities", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows", "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Proceeds from issuance of long-term debt", "label": "Proceeds from Issuance of Long-Term Debt", "documentation": "The cash inflow from a debt initially having maturity due after one year or beyond the operating cycle, if longer." } } }, "auth_ref": [ "r10", "r891" ] }, "us-gaap_ProceedsFromSaleAndMaturityOfMarketableSecurities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ProceedsFromSaleAndMaturityOfMarketableSecurities", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInInvestingActivities", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "Maturities of short-term investments", "label": "Proceeds from Sale and Maturity of Marketable Securities", "documentation": "The cash inflow associated with the aggregate amount received by the entity through sale or maturity of marketable securities (held-to-maturity or available-for-sale) during the period." } } }, "auth_ref": [] }, "us-gaap_ProceedsFromShortTermDebt": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ProceedsFromShortTermDebt", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInFinancingActivities", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "Proceeds from short-term borrowings", "label": "Proceeds from Short-Term Debt", "documentation": "The cash inflow from a borrowing having initial term of repayment within one year or the normal operating cycle, if longer." } } }, "auth_ref": [ "r10" ] }, "us-gaap_ProductMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ProductMember", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Net sales", "verboseLabel": "Net Sales", "label": "Product [Member]", "documentation": "Article or substance produced by nature, labor or machinery." } } }, "auth_ref": [ "r1036", "r1040", "r1071", "r1072" ] }, "srt_ProductOrServiceAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "ProductOrServiceAxis", "presentation": [ "http://www.costco.com/role/AccountingPoliciesRevenueRecognitionDetails", "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Product and Service [Axis]", "label": "Product and Service [Axis]", "documentation": "Information by product and service, or group of similar products and similar services." } } }, "auth_ref": [ "r68", "r69", "r70", "r71", "r72", "r73", "r96", "r263", "r754", "r868", "r869", "r870", "r871", "r872", "r873", "r874", "r1023", "r1036", "r1039", "r1040", "r1071", "r1072", "r1130", "r1131", "r1132", "r1135", "r1138", "r1275", "r1310", "r1311", "r1312", "r1313", "r1314", "r1315", "r1316", "r1317", "r1318", "r1319", "r1320", "r1321", "r1322", "r1323", "r1324", "r1325", "r1326", "r1327", "r1328", "r1329", "r1330", "r1331", "r1332", "r1333", "r1334", "r1335", "r1336", "r1337", "r1338", "r1339", "r1340", "r1341", "r1342", "r1343", "r1344", "r1345", "r1346", "r1347", "r1349", "r1350", "r1351", "r1352", "r1433", "r1434", "r1574", "r1577", "r1578", "r1579", "r1580", "r1581", "r1582", "r1583", "r1584", "r1585", "r1586", "r1587", "r1588", "r1589", "r1590", "r1591", "r1592", "r1593", "r1594", "r1595", "r1596", "r1597", "r1598", "r1599", "r1600", "r1601", "r1602", "r1603", "r1604", "r1605", "r1606", "r1607", "r1608", "r1609", "r1610", "r1611", "r1612", "r1613", "r1614", "r1615" ] }, "srt_ProductsAndServicesDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "ProductsAndServicesDomain", "presentation": [ "http://www.costco.com/role/AccountingPoliciesRevenueRecognitionDetails", "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Product and Service [Domain]", "label": "Product and Service [Domain]", "documentation": "Product or service, or a group of similar products or similar services." } } }, "auth_ref": [ "r68", "r69", "r70", "r71", "r72", "r73", "r96", "r263", "r754", "r868", "r869", "r870", "r871", "r872", "r873", "r874", "r1023", "r1036", "r1039", "r1040", "r1071", "r1072", "r1130", "r1131", "r1132", "r1135", "r1138", "r1275", "r1310", "r1311", "r1312", "r1313", "r1314", "r1315", "r1316", "r1317", "r1318", "r1319", "r1320", "r1321", "r1322", "r1323", "r1324", "r1325", "r1326", "r1327", "r1328", "r1329", "r1330", "r1331", "r1332", "r1333", "r1334", "r1335", "r1336", "r1337", "r1338", "r1339", "r1340", "r1341", "r1342", "r1343", "r1344", "r1345", "r1346", "r1347", "r1349", "r1350", "r1351", "r1352", "r1433", "r1434", "r1574", "r1577", "r1578", "r1579", "r1580", "r1581", "r1582", "r1583", "r1584", "r1585", "r1586", "r1587", "r1588", "r1589", "r1590", "r1591", "r1592", "r1593", "r1594", "r1595", "r1596", "r1597", "r1598", "r1599", "r1600", "r1601", "r1602", "r1603", "r1604", "r1605", "r1606", "r1607", "r1608", "r1609", "r1610", "r1611", "r1612", "r1613", "r1614", "r1615" ] }, "us-gaap_PropertyPlantAndEquipmentByTypeAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PropertyPlantAndEquipmentByTypeAxis", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Property, Plant and Equipment, Type [Axis]", "label": "Long-Lived Asset, Class [Axis]", "documentation": "Information by class of long-lived asset. Includes, but is not limited to, property, plant, and equipment; right-of-use asset from finance lease; long-lived asset of lessor subject to operating lease; proved oil and gas property accounted for under successful efforts method; and long-term prepaid asset." } } }, "auth_ref": [ "r345", "r346", "r710", "r1061", "r1062", "r1063", "r1064", "r1419", "r1420", "r1553" ] }, "us-gaap_PropertyPlantAndEquipmentGross": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PropertyPlantAndEquipmentGross", "crdr": "debit", "calculation": { "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Gross property and equipment", "label": "Property, Plant, and Equipment, before Accumulated Depreciation, Depletion, and Amortization", "documentation": "Amount, before accumulated depreciation, depletion, and amortization, of property, plant, and equipment. Includes, but is not limited to, land and land improvement; building; machinery and equipment; furniture and fixture; and work of art, historical treasure, or similar asset classified as collection." } } }, "auth_ref": [ "r112", "r118", "r345", "r846", "r1419" ] }, "us-gaap_PropertyPlantAndEquipmentLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PropertyPlantAndEquipmentLineItems", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Property and Equipment, Net [Line Items]", "label": "Property, Plant, and Equipment [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r345", "r346", "r710", "r1061", "r1062", "r1063", "r1064", "r1419", "r1420", "r1553" ] }, "us-gaap_PropertyPlantAndEquipmentNet": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PropertyPlantAndEquipmentNet", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_Assets", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails", "http://www.costco.com/role/ConsolidatedBalanceSheets", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Property and equipment, net", "label": "Property, Plant, and Equipment, after Accumulated Depreciation, Depletion, and Amortization", "documentation": "Amount, after accumulated depreciation, depletion, and amortization, of property, plant, and equipment. Includes, but is not limited to, land and land improvement; building; machinery and equipment; furniture and fixture; and work of art, historical treasure, or similar asset classified as collection." } } }, "auth_ref": [ "r710", "r790", "r791", "r804", "r830", "r831", "r846", "r1118", "r1424" ] }, "us-gaap_PropertyPlantAndEquipmentPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PropertyPlantAndEquipmentPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Property and Equipment, Net", "label": "Property, Plant, and Equipment [Policy Text Block]", "documentation": "Disclosure of accounting policy for property, plant, and equipment. Includes, but is not limited to, land and land improvement; building; machinery and equipment; furniture and fixture; and work of art, historical treasure, or similar asset classified as collection." } } }, "auth_ref": [ "r53", "r54", "r347", "r348", "r844", "r1419" ] }, "us-gaap_PropertyPlantAndEquipmentTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PropertyPlantAndEquipmentTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesTables" ], "lang": { "en-us": { "role": { "terseLabel": "Property, Plant, and Equipment", "label": "Property, Plant, and Equipment [Table Text Block]", "documentation": "Tabular disclosure of property, plant, and equipment. Includes, but is not limited to, land and land improvement; building; machinery and equipment; furniture and fixture; and work of art, historical treasure, or similar asset classified as collection." } } }, "auth_ref": [ "r1422" ] }, "us-gaap_PropertyPlantAndEquipmentTypeDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PropertyPlantAndEquipmentTypeDomain", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Property, Plant and Equipment, Type [Domain]", "label": "Long-Lived Asset, Class [Domain]", "documentation": "Class of long-lived asset. Includes, but is not limited to, property, plant, and equipment; right-of-use asset from finance lease; long-lived asset of lessor subject to operating lease; proved oil and gas property accounted for under successful efforts method; and long-term prepaid asset." } } }, "auth_ref": [ "r345", "r346", "r710", "r1061", "r1062", "r1063", "r1064", "r1419", "r1420", "r1553" ] }, "us-gaap_PropertyPlantAndEquipmentUsefulLife": { "xbrltype": "durationItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "PropertyPlantAndEquipmentUsefulLife", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Property, plant and equipment, useful life", "label": "Property, Plant, and Equipment, Useful Life", "documentation": "Useful life of property, plant, and equipment, in 'PnYnMnDTnHnMnS' format, for example, 'P1Y5M13D' represents reported fact of one year, five months, and thirteen days. Includes, but is not limited to, land and land improvement; building; machinery and equipment; furniture and fixture; and work of art, historical treasure, or similar asset classified as collection." } } }, "auth_ref": [ "r1421" ] }, "ecd_PvpTable": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PvpTable", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Pay vs Performance Disclosure", "label": "Pay vs Performance Disclosure [Table]" } } }, "auth_ref": [ "r1200" ] }, "ecd_PvpTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "PvpTableTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Pay vs Performance Disclosure, Table", "label": "Pay vs Performance [Table Text Block]" } } }, "auth_ref": [ "r1200" ] }, "srt_RangeAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "RangeAxis", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails", "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails", "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails", "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Statistical Measurement [Axis]", "label": "Statistical Measurement [Axis]", "documentation": "Information by statistical measurement. Includes, but is not limited to, minimum, maximum, weighted average, arithmetic average, and median." } } }, "auth_ref": [ "r59", "r61", "r63", "r64", "r66", "r83", "r85", "r86", "r97", "r98", "r105", "r106", "r232", "r362", "r363", "r364", "r365", "r472", "r483", "r515", "r516", "r517", "r523", "r533", "r659", "r720", "r721", "r722", "r723", "r725", "r726", "r727", "r728", "r735", "r752", "r875", "r876", "r883", "r919", "r920", "r974", "r978", "r980", "r981", "r991", "r1006", "r1007", "r1009", "r1010", "r1021", "r1022", "r1058", "r1084", "r1088", "r1091", "r1092", "r1107", "r1108", "r1112", "r1113", "r1131", "r1141", "r1430", "r1438", "r1441", "r1526" ] }, "srt_RangeMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "RangeMember", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails", "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails", "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails", "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Statistical Measurement [Domain]", "label": "Statistical Measurement [Domain]", "documentation": "Statistical measurement. Includes, but is not limited to, minimum, maximum, weighted average, arithmetic average, and median." } } }, "auth_ref": [ "r59", "r61", "r63", "r64", "r66", "r83", "r85", "r86", "r97", "r98", "r105", "r106", "r232", "r362", "r363", "r364", "r365", "r472", "r483", "r515", "r516", "r517", "r523", "r533", "r659", "r720", "r721", "r722", "r723", "r725", "r726", "r727", "r728", "r735", "r752", "r875", "r876", "r883", "r919", "r920", "r974", "r978", "r980", "r981", "r991", "r1006", "r1007", "r1009", "r1010", "r1021", "r1022", "r1058", "r1084", "r1088", "r1091", "r1092", "r1107", "r1108", "r1112", "r1113", "r1131", "r1141", "r1430", "r1438", "r1441", "r1526" ] }, "us-gaap_ReceivablesNetCurrent": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ReceivablesNetCurrent", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_AssetsCurrent", "weight": 1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Receivables, net", "label": "Receivables, Net, Current", "documentation": "The total amount due to the entity within one year of the balance sheet date (or one operating cycle, if longer) from outside sources, including trade accounts receivable, notes and loans receivable, as well as any other types of receivables, net of allowances established for the purpose of reducing such receivables to an amount that approximates their net realizable value." } } }, "auth_ref": [ "r1118" ] }, "us-gaap_ReceivablesPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ReceivablesPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Receivables, Net", "label": "Receivable [Policy Text Block]", "documentation": "Disclosure of accounting policy for receivable. Includes, but is not limited to, accounts receivable and financing receivable." } } }, "auth_ref": [ "r269", "r270", "r271", "r272", "r1391" ] }, "us-gaap_ReconciliationOfUnrecognizedTaxBenefitsExcludingAmountsPertainingToExaminedTaxReturnsRollForward": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ReconciliationOfUnrecognizedTaxBenefitsExcludingAmountsPertainingToExaminedTaxReturnsRollForward", "presentation": [ "http://www.costco.com/role/IncomeTaxesGrossUnrecognizedTaxBenefitsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Reconciliation of Unrecognized Tax Benefits, Excluding Amounts Pertaining to Examined Tax Returns [Roll Forward]", "label": "Unrecognized Tax Benefits [Roll Forward]", "documentation": "A roll forward is a reconciliation of a concept from the beginning of a period to the end of a period." } } }, "auth_ref": [] }, "ecd_RecoveryOfErrCompDisclosureLineItems": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "RecoveryOfErrCompDisclosureLineItems", "lang": { "en-us": { "role": { "label": "Recovery of Erroneously Awarded Compensation Disclosure [Line Items]" } } }, "auth_ref": [ "r1167", "r1178", "r1188", "r1221" ] }, "cost_RedemptionPriceCertainEvents": { "xbrltype": "percentItemType", "nsuri": "http://www.costco.com/20260830", "localname": "RedemptionPriceCertainEvents", "presentation": [ "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Redemption Price Certain Events", "label": "Redemption Price Certain Events", "documentation": "The redemption price, as a percentage of the principal amount, that the Company, upon certain events defined by the terms of the outstanding notes, will be required to make a purchase offer to redeem notes outstanding." } } }, "auth_ref": [] }, "cost_ReductionInSales": { "xbrltype": "monetaryItemType", "nsuri": "http://www.costco.com/20260830", "localname": "ReductionInSales", "crdr": "debit", "presentation": [ "http://www.costco.com/role/AccountingPoliciesRevenueRecognitionDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Reduction in sales", "label": "Reduction In Sales", "documentation": "The entity's rewards members receive a cash back reward. These rewards are accounted for as a reduction to sales revenue for this revenue stream." } } }, "auth_ref": [] }, "us-gaap_RepaymentsOfDebt": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "RepaymentsOfDebt", "crdr": "credit", "presentation": [ "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Repayments of Debt", "label": "Repayments of Debt", "documentation": "Amount of cash outflow for short-term and long-term debt. Excludes payment of lease obligation." } } }, "auth_ref": [ "r1355" ] }, "us-gaap_RepaymentsOfLongTermDebt": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "RepaymentsOfLongTermDebt", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInFinancingActivities", "weight": -1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedLabel": "Repayments of long-term debt", "label": "Repayments of Long-Term Debt", "documentation": "The cash outflow for debt initially having maturity due after one year or beyond the normal operating cycle, if longer." } } }, "auth_ref": [ "r28", "r894" ] }, "us-gaap_RepaymentsOfShortTermDebt": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "RepaymentsOfShortTermDebt", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInFinancingActivities", "weight": -1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Repayments of short-term borrowings", "label": "Repayments of Short-Term Debt", "documentation": "The cash outflow for a borrowing having initial term of repayment within one year or the normal operating cycle, if longer." } } }, "auth_ref": [ "r28" ] }, "ecd_RestatementDateAxis": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "RestatementDateAxis", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Restatement Determination Date:", "label": "Restatement Determination Date [Axis]" } } }, "auth_ref": [ "r1168", "r1179", "r1189", "r1222" ] }, "ecd_RestatementDeterminationDate": { "xbrltype": "dateItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "RestatementDeterminationDate", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Restatement Determination Date", "label": "Restatement Determination Date" } } }, "auth_ref": [ "r1169", "r1180", "r1190", "r1223" ] }, "ecd_RestatementDoesNotRequireRecoveryTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "RestatementDoesNotRequireRecoveryTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Restatement does not require Recovery", "label": "Restatement Does Not Require Recovery [Text Block]" } } }, "auth_ref": [ "r1176", "r1187", "r1197", "r1230" ] }, "us-gaap_RestrictedStockUnitsRSUMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "RestrictedStockUnitsRSUMember", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails", "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Restricted Stock Units (RSUs)", "label": "Restricted Stock Units (RSUs) [Member]", "documentation": "Share instrument which is convertible to stock or an equivalent amount of cash, after a specified period of time or when specified performance conditions are met." } } }, "auth_ref": [ "r1457", "r1458", "r1459", "r1460", "r1461", "r1462", "r1463", "r1464", "r1465", "r1466", "r1467", "r1468", "r1469", "r1470", "r1471", "r1472", "r1473", "r1474", "r1475", "r1476", "r1477", "r1478", "r1479", "r1480", "r1481", "r1482" ] }, "us-gaap_RetainedEarningsAccumulatedDeficit": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "RetainedEarningsAccumulatedDeficit", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_StockholdersEquity", "weight": 1.0, "order": 5.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "Retained earnings", "label": "Retained Earnings (Accumulated Deficit)", "documentation": "Amount of accumulated undistributed earnings (deficit)." } } }, "auth_ref": [ "r145", "r147", "r446", "r790", "r791", "r801", "r842", "r880", "r882", "r895", "r930", "r1118" ] }, "us-gaap_RetainedEarningsMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "RetainedEarningsMember", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Retained Earnings", "label": "Retained Earnings [Member]", "documentation": "Accumulated undistributed earnings (deficit)." } } }, "auth_ref": [ "r99", "r100", "r189", "r190", "r191", "r193", "r200", "r202", "r204", "r306", "r307", "r342", "r343", "r344", "r407", "r443", "r453", "r467", "r468", "r470", "r471", "r524", "r573", "r574", "r581", "r582", "r583", "r585", "r588", "r589", "r633", "r634", "r635", "r637", "r639", "r640", "r642", "r650", "r692", "r751", "r832", "r877", "r879", "r897", "r1447", "r1449", "r1619" ] }, "us-gaap_RevenueFromContractWithCustomerExcludingAssessedTax": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "RevenueFromContractWithCustomerExcludingAssessedTax", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfIncome": { "parentTag": "us-gaap_OperatingIncomeLoss", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails" ], "lang": { "en-us": { "role": { "verboseLabel": "Total revenue", "terseLabel": "Total Revenue", "label": "Revenue from Contract with Customer, Excluding Assessed Tax", "documentation": "Amount, excluding tax collected from customer, of revenue from satisfaction of performance obligation by transferring promised good or service to customer. Tax collected from customer is tax assessed by governmental authority that is both imposed on and concurrent with specific revenue-producing transaction, including, but not limited to, sales, use, value added and excise." } } }, "auth_ref": [ "r224", "r238", "r239", "r254", "r260", "r263", "r265", "r267", "r464", "r465", "r466", "r754", "r1037", "r1040" ] }, "us-gaap_RevenueRecognitionPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "RevenueRecognitionPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Revenue Recognition", "label": "Revenue [Policy Text Block]", "documentation": "Disclosure of accounting policy for revenue. Includes revenue from contract with customer and from other sources." } } }, "auth_ref": [ "r951" ] }, "us-gaap_RevenuesAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "RevenuesAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome" ], "lang": { "en-us": { "role": { "terseLabel": "REVENUE", "label": "Revenues [Abstract]" } } }, "auth_ref": [] }, "us-gaap_RightOfUseAssetObtainedInExchangeForFinanceLeaseLiability": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "RightOfUseAssetObtainedInExchangeForFinanceLeaseLiability", "crdr": "debit", "presentation": [ "http://www.costco.com/role/LeasesSupplementalCashFlowInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Finance lease assets obtained in exchange for new or modified leases", "label": "Right-of-Use Asset Obtained in Exchange for Finance Lease Liability", "documentation": "Amount of increase in right-of-use asset obtained in exchange for finance lease liability." } } }, "auth_ref": [ "r706", "r1117", "r1357" ] }, "us-gaap_RightOfUseAssetObtainedInExchangeForOperatingLeaseLiability": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "RightOfUseAssetObtainedInExchangeForOperatingLeaseLiability", "crdr": "debit", "presentation": [ "http://www.costco.com/role/LeasesSupplementalCashFlowInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Operating lease assets obtained in exchange for new or modified leases", "label": "Right-of-Use Asset Obtained in Exchange for Operating Lease Liability", "documentation": "Amount of increase in right-of-use asset obtained in exchange for operating lease liability." } } }, "auth_ref": [ "r706", "r1117", "r1357" ] }, "ecd_Rule10b51ArrAdoptedFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "Rule10b51ArrAdoptedFlag", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Rule 10b5-1 Arrangement Adopted", "label": "Rule 10b5-1 Arrangement Adopted [Flag]" } } }, "auth_ref": [ "r1239" ] }, "ecd_Rule10b51ArrTrmntdFlag": { "xbrltype": "booleanItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "Rule10b51ArrTrmntdFlag", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Rule 10b5-1 Arrangement Terminated", "label": "Rule 10b5-1 Arrangement Terminated [Flag]" } } }, "auth_ref": [ "r1239" ] }, "cost_S2024Q2DividendsMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "S2024Q2DividendsMember", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails", "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Special Dividend [Member]", "label": "S2024Q2Dividends [Member]", "documentation": "Special Dividend [Member]" } } }, "auth_ref": [] }, "country_SE": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "SE", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "SWEDEN", "label": "SWEDEN" } } }, "auth_ref": [] }, "us-gaap_ScheduleOfCarryingValuesAndEstimatedFairValuesOfDebtInstrumentsTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfCarryingValuesAndEstimatedFairValuesOfDebtInstrumentsTableTextBlock", "presentation": [ "http://www.costco.com/role/DebtTables" ], "lang": { "en-us": { "role": { "terseLabel": "Carrying Value of Company's Long-Term Debt", "label": "Schedule of Carrying Values and Estimated Fair Values of Debt Instruments [Table Text Block]", "documentation": "Tabular disclosure of information pertaining to carrying amount and estimated fair value of short-term and long-term debt instruments or arrangements, including but not limited to, identification of terms, features, and collateral requirements." } } }, "auth_ref": [] }, "us-gaap_ScheduleOfCashFlowSupplementalDisclosuresTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfCashFlowSupplementalDisclosuresTableTextBlock", "presentation": [ "http://www.costco.com/role/IncomeTaxesTables" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Cash Flow, Supplemental Disclosures", "label": "Schedule of Cash Flow, Supplemental Disclosures [Table Text Block]", "documentation": "Tabular disclosure of supplemental cash flow information for the periods presented." } } }, "auth_ref": [ "r1262" ] }, "us-gaap_ScheduleOfCompensationCostForShareBasedPaymentArrangementsAllocationOfShareBasedCompensationCostsByPlanTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfCompensationCostForShareBasedPaymentArrangementsAllocationOfShareBasedCompensationCostsByPlanTableTextBlock", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansTables" ], "lang": { "en-us": { "role": { "terseLabel": "Summary of Stock-Based Compensation Expense and Related Tax Benefits", "label": "Share-Based Payment Arrangement, Cost by Plan [Table Text Block]", "documentation": "Tabular disclosure of cost recognized for award under share-based payment arrangement by plan. Includes, but is not limited to, related tax benefit." } } }, "auth_ref": [ "r16" ] }, "us-gaap_ScheduleOfComponentsOfIncomeTaxExpenseBenefitTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfComponentsOfIncomeTaxExpenseBenefitTableTextBlock", "presentation": [ "http://www.costco.com/role/IncomeTaxesTables" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Components of Income Tax Expense (Benefit)", "label": "Schedule of Components of Income Tax Expense (Benefit) [Table Text Block]", "documentation": "Tabular disclosure of the components of income tax expense attributable to continuing operations for each year presented including, but not limited to: current tax expense (benefit), deferred tax expense (benefit), investment tax credits, government grants, the benefits of operating loss carryforwards, tax expense that results from allocating certain tax benefits either directly to contributed capital or to reduce goodwill or other noncurrent intangible assets of an acquired entity, adjustments of a deferred tax liability or asset for enacted changes in tax laws or rates or a change in the tax status of the entity, and adjustments of the beginning-of-the-year balances of a valuation allowance because of a change in circumstances that causes a change in judgment about the realizability of the related deferred tax asset in future years." } } }, "auth_ref": [ "r1496" ] }, "us-gaap_ScheduleOfDeferredTaxAssetsAndLiabilitiesTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfDeferredTaxAssetsAndLiabilitiesTableTextBlock", "presentation": [ "http://www.costco.com/role/IncomeTaxesTables" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Deferred Tax Assets and Liabilities", "label": "Schedule of Deferred Tax Assets and Liabilities [Table Text Block]", "documentation": "Tabular disclosure of the components of net deferred tax asset or liability recognized in an entity's statement of financial position, including the following: the total of all deferred tax liabilities, the total of all deferred tax assets, the total valuation allowance recognized for deferred tax assets." } } }, "auth_ref": [ "r1490" ] }, "us-gaap_ScheduleOfEarningsPerShareBasicAndDilutedTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfEarningsPerShareBasicAndDilutedTableTextBlock", "presentation": [ "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareNetIncomeperCommonandCommonEquivalentShareTables" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Earnings Per Share, Basic and Diluted", "label": "Schedule of Earnings Per Share, Basic and Diluted [Table Text Block]", "documentation": "Tabular disclosure of an entity's basic and diluted earnings per share calculations, including a reconciliation of numerators and denominators of the basic and diluted per-share computations for income from continuing operations." } } }, "auth_ref": [ "r1373" ] }, "us-gaap_ScheduleOfEffectiveIncomeTaxRateReconciliationTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfEffectiveIncomeTaxRateReconciliationTableTextBlock", "presentation": [ "http://www.costco.com/role/IncomeTaxesTables" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Effective Income Tax Rate Reconciliation", "label": "Schedule of Effective Income Tax Rate Reconciliation [Table Text Block]", "documentation": "Tabular disclosure of the reconciliation using percentage or dollar amounts of the reported amount of income tax expense attributable to continuing operations for the year to the amount of income tax expense that would result from applying domestic federal statutory tax rates to pretax income from continuing operations." } } }, "auth_ref": [ "r545", "r1087", "r1487" ] }, "us-gaap_ScheduleOfEntityWideInformationRevenueFromExternalCustomersByProductsAndServicesTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfEntityWideInformationRevenueFromExternalCustomersByProductsAndServicesTable", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbyItemCategoryDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Revenue from External Customers by Products and Services [Table]", "label": "Segment Reporting, Entity-Wide Information Not Provided as Part of Reportable Segment, Product and Service, Revenue [Table]", "documentation": "Disclosure of information about revenue by product and service if it is not provided as part of reportable segment information." } } }, "auth_ref": [ "r263" ] }, "us-gaap_ScheduleOfFairValueAssetsAndLiabilitiesMeasuredOnRecurringBasisTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfFairValueAssetsAndLiabilitiesMeasuredOnRecurringBasisTableTextBlock", "presentation": [ "http://www.costco.com/role/FairValueMeasurementTables" ], "lang": { "en-us": { "role": { "terseLabel": "Fair Value of Financial Assets and Liabilities Measured on Recurring Basis", "label": "Schedule of Fair Value, Assets and Liabilities Measured on Recurring Basis [Table Text Block]", "documentation": "Tabular disclosure of assets and liabilities, including [financial] instruments measured at fair value that are classified in stockholders' equity, if any, that are measured at fair value on a recurring basis. The disclosures contemplated herein include the fair value measurements at the reporting date by the level within the fair value hierarchy in which the fair value measurements in their entirety fall, segregating fair value measurements using quoted prices in active markets for identical assets (Level 1), significant other observable inputs (Level 2), and significant unobservable inputs (Level 3)." } } }, "auth_ref": [ "r1523", "r1524" ] }, "us-gaap_ScheduleOfGoodwillTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfGoodwillTable", "presentation": [ "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Goodwill [Table]", "label": "Goodwill [Table]", "documentation": "Disclosure of information about goodwill, including, but not limited to, change from acquisition, sale, impairment, and other reason." } } }, "auth_ref": [ "r330", "r331", "r332", "r333", "r334", "r335", "r336", "r337", "r338", "r339", "r340", "r1060" ] }, "us-gaap_ScheduleOfIncomeBeforeIncomeTaxDomesticAndForeignTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfIncomeBeforeIncomeTaxDomesticAndForeignTableTextBlock", "presentation": [ "http://www.costco.com/role/IncomeTaxesTables" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Income before Income Tax, Domestic and Foreign", "label": "Schedule of Income before Income Tax, Domestic and Foreign [Table Text Block]", "documentation": "Tabular disclosure of income before income tax between domestic and foreign jurisdictions." } } }, "auth_ref": [ "r1359", "r1365" ] }, "us-gaap_ScheduleOfInventoryCurrentTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfInventoryCurrentTableTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesTables" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Merchandise Inventories", "label": "Schedule of Inventory, Current [Table Text Block]", "documentation": "Tabular disclosure of the carrying amount as of the balance sheet date of merchandise, goods, commodities, or supplies held for future sale or to be used in manufacturing, servicing or production process." } } }, "auth_ref": [ "r1295" ] }, "us-gaap_ScheduleOfMaturitiesOfLongTermDebtTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfMaturitiesOfLongTermDebtTableTextBlock", "presentation": [ "http://www.costco.com/role/DebtTables" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Maturities of Long-term Debt", "label": "Schedule of Maturities of Long-Term Debt [Table Text Block]", "documentation": "Tabular disclosure of maturity and sinking fund requirement for long-term debt." } } }, "auth_ref": [ "r5" ] }, "us-gaap_ScheduleOfPropertyPlantAndEquipmentTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfPropertyPlantAndEquipmentTable", "presentation": [ "http://www.costco.com/role/AccountingPoliciesPropertyandEquipmentNetDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Property and Equipment, Net [Table]", "label": "Property, Plant, and Equipment [Table]", "documentation": "Disclosure of information about property, plant, and equipment. Includes, but is not limited to, land and land improvement; building; machinery and equipment; furniture and fixture; and work of art, historical treasure, or similar asset classified as collection." } } }, "auth_ref": [ "r345", "r346", "r710", "r1061", "r1062", "r1063", "r1064", "r1419", "r1420", "r1553" ] }, "us-gaap_ScheduleOfSegmentReportingInformationBySegmentTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfSegmentReportingInformationBySegmentTable", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Segment Reporting [Table]", "label": "Segment Reporting [Table]", "documentation": "Disclosure of information about segment reporting. Includes, but is not limited to, reconciliation of reportable segment amount to corresponding consolidated total." } } }, "auth_ref": [ "r234", "r237", "r238", "r239", "r240", "r241", "r242", "r243", "r244", "r245", "r246", "r248", "r249", "r251", "r252", "r253", "r254", "r255", "r256", "r257", "r258", "r260", "r261", "r262" ] }, "us-gaap_ScheduleOfSegmentReportingInformationBySegmentTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfSegmentReportingInformationBySegmentTextBlock", "presentation": [ "http://www.costco.com/role/SegmentReportingTables" ], "lang": { "en-us": { "role": { "terseLabel": "Segment Reporting Information, by Segment", "label": "Segment Reporting [Table Text Block]", "documentation": "Tabular disclosure of segment reporting. Includes, but is not limited to, reconciliation of reportable segment amount to corresponding consolidated total." } } }, "auth_ref": [ "r1376", "r1378", "r1379", "r1380", "r1381", "r1382", "r1383", "r1385", "r1386", "r1389" ] }, "us-gaap_ScheduleOfShareBasedCompensationArrangementByShareBasedPaymentAwardRestrictedStockUnitsVestedAndExpectedToVestTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfShareBasedCompensationArrangementByShareBasedPaymentAwardRestrictedStockUnitsVestedAndExpectedToVestTableTextBlock", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansTables" ], "lang": { "en-us": { "role": { "terseLabel": "Summary of RSU Transactions", "label": "Share-Based Compensation Arrangements by Share-Based Payment Award, Restricted Stock Units, Vested and Expected to Vest [Table Text Block]", "documentation": "Tabular disclosure of number, weighted-average exercise price or conversion ratio, aggregate intrinsic value, and weighted-average remaining contractual term for outstanding restricted stock units that are fully vested and expected to vest. Includes, but is not limited to, unvested restricted stock units for which requisite service period has not been rendered but that are expected to vest based on achievement of performance condition, if forfeitures are recognized when they occur." } } }, "auth_ref": [ "r38" ] }, "us-gaap_ScheduleOfShareBasedCompensationArrangementsByShareBasedPaymentAwardTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfShareBasedCompensationArrangementsByShareBasedPaymentAwardTable", "presentation": [ "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails", "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule of Share-based Compensation Arrangements by Share-based Payment Award [Table]", "label": "Schedule of Share-Based Compensation Arrangements by Share-Based Payment Award [Table]", "documentation": "Disclosure of information about share-based payment arrangement." } } }, "auth_ref": [ "r485", "r487", "r490", "r491", "r492", "r494", "r495", "r496", "r497", "r498", "r499", "r500", "r501", "r502", "r503", "r504", "r505", "r506", "r507", "r508", "r509", "r510", "r511", "r513", "r514", "r515", "r516", "r517", "r518", "r523" ] }, "us-gaap_ScheduleOfTreasuryStockByClassTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfTreasuryStockByClassTextBlock", "presentation": [ "http://www.costco.com/role/StockholdersEquityTables" ], "lang": { "en-us": { "role": { "terseLabel": "Stock repurchase activity", "label": "Class of Treasury Stock [Table Text Block]", "documentation": "Tabular disclosure of treasury stock, including, but not limited to, average cost per share, description of share repurchase program, shares repurchased, shares held for each class of treasury stock." } } }, "auth_ref": [ "r1450" ] }, "us-gaap_ScheduleOfUnrecognizedTaxBenefitsRollForwardTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ScheduleOfUnrecognizedTaxBenefitsRollForwardTableTextBlock", "presentation": [ "http://www.costco.com/role/IncomeTaxesTables" ], "lang": { "en-us": { "role": { "terseLabel": "Schedule Of Gross Unrecognized Tax Benefits Table", "label": "Schedule of Unrecognized Tax Benefits Roll Forward [Table Text Block]", "documentation": "Tabular disclosure of the change in unrecognized tax benefits." } } }, "auth_ref": [ "r558", "r1086" ] }, "dei_Security12bTitle": { "xbrltype": "securityTitleItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "Security12bTitle", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Title of 12(b) Security", "label": "Title of 12(b) Security", "documentation": "Title of a 12(b) registered security." } } }, "auth_ref": [ "r1149" ] }, "dei_SecurityExchangeName": { "xbrltype": "edgarExchangeCodeItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "SecurityExchangeName", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Security Exchange Name", "label": "Security Exchange Name", "documentation": "Name of the Exchange on which a security is registered." } } }, "auth_ref": [ "r1152" ] }, "us-gaap_SegmentDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "SegmentDomain", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Segments [Domain]", "label": "Segments [Domain]", "documentation": "Components of an entity that engage in business activities from which they may earn revenue and incur expenses, including transactions with other components of the same entity." } } }, "auth_ref": [ "r102", "r224", "r234", "r237", "r238", "r239", "r240", "r241", "r242", "r243", "r244", "r245", "r246", "r248", "r249", "r251", "r252", "r253", "r254", "r255", "r256", "r257", "r258", "r260", "r261", "r262", "r267", "r330", "r331", "r332", "r333", "r334", "r335", "r336", "r337", "r338", "r341", "r349", "r350", "r358", "r359", "r586", "r587", "r857", "r858", "r859", "r860", "r861", "r862", "r863", "r864", "r865", "r866", "r867", "r1050", "r1053", "r1054", "r1060", "r1134", "r1574", "r1577", "r1578", "r1579", "r1580", "r1581", "r1582", "r1583", "r1584", "r1585", "r1586", "r1587", "r1588", "r1589", "r1590", "r1591", "r1592", "r1593", "r1594", "r1595", "r1596", "r1597", "r1598", "r1599", "r1600", "r1601", "r1602", "r1614", "r1615" ] }, "us-gaap_SegmentExpenditureAdditionToLongLivedAssets": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "SegmentExpenditureAdditionToLongLivedAssets", "crdr": "debit", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Additions to property and equipment", "label": "Segment Reporting, Long-Lived Asset, Expenditure for Addition", "documentation": "Amount of expenditure for addition to long-lived asset included in determination of segment asset by chief operating decision maker (CODM) or otherwise regularly provided to CODM. Long-lived asset excludes financial instrument, long-term customer relationship of financial institution, mortgage and other servicing rights, deferred policy acquisition cost, and deferred tax asset." } } }, "auth_ref": [ "r224", "r249", "r260", "r1053", "r1054" ] }, "srt_SegmentGeographicalDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "SegmentGeographicalDomain", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails", "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails", "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails", "http://www.costco.com/role/DebtScheduleOfShortTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Segment, Geographical [Domain]", "label": "Geographical [Domain]", "documentation": "Geographical area." } } }, "auth_ref": [ "r60", "r62", "r65", "r67", "r74", "r75", "r76", "r77", "r78", "r79", "r80", "r81", "r82", "r84", "r85", "r86", "r229", "r265", "r266", "r755", "r756", "r757", "r758", "r759", "r760", "r761", "r762", "r763", "r764", "r765", "r766", "r767", "r768", "r769", "r770", "r771", "r772", "r773", "r774", "r775", "r776", "r777", "r778", "r779", "r780", "r781", "r782", "r783", "r784", "r785", "r786", "r787", "r788", "r807", "r808", "r809", "r810", "r911", "r914", "r916", "r975", "r979", "r983", "r995", "r1006", "r1008", "r1009", "r1010", "r1012", "r1013", "r1014", "r1015", "r1016", "r1017", "r1018", "r1019", "r1020", "r1024", "r1045", "r1071", "r1073", "r1122", "r1123", "r1124", "r1125", "r1126", "r1127", "r1128", "r1129", "r1133", "r1141", "r1574", "r1577", "r1578", "r1580", "r1581", "r1582", "r1583", "r1584", "r1585", "r1586", "r1587", "r1588", "r1589", "r1590", "r1591", "r1592", "r1593", "r1594", "r1595", "r1596", "r1597", "r1598", "r1599", "r1600", "r1601", "r1602", "r1614", "r1615" ] }, "us-gaap_SegmentReportingAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "SegmentReportingAbstract", "lang": { "en-us": { "role": { "terseLabel": "Segment Reporting [Abstract]", "label": "Segment Reporting [Abstract]" } } }, "auth_ref": [] }, "us-gaap_SegmentReportingDisclosureOfEntitysReportableSegmentsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "SegmentReportingDisclosureOfEntitysReportableSegmentsAbstract", "presentation": [ "http://www.costco.com/role/SegmentReportingNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Segment Reporting, Descriptive Information [Abstract]", "label": "Segment Reporting, Descriptive Information [Abstract]" } } }, "auth_ref": [] }, "us-gaap_SegmentReportingDisclosureTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "SegmentReportingDisclosureTextBlock", "presentation": [ "http://www.costco.com/role/SegmentReporting" ], "lang": { "en-us": { "role": { "terseLabel": "Segment Reporting", "label": "Segment Reporting [Text Block]", "documentation": "The entire disclosure for segment reporting." } } }, "auth_ref": [ "r224", "r233", "r234", "r235", "r236", "r237", "r250", "r252", "r253", "r258", "r259", "r260", "r261", "r262", "r263", "r264", "r267", "r1049", "r1051", "r1052", "r1053", "r1055", "r1056", "r1057" ] }, "us-gaap_SegmentReportingInformationLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "SegmentReportingInformationLineItems", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Segment Reporting [Line Items]", "label": "Segment Reporting [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r234", "r237", "r238", "r239", "r240", "r241", "r242", "r243", "r244", "r245", "r246", "r248", "r249", "r251", "r252", "r253", "r254", "r255", "r256", "r257", "r258", "r260", "r261", "r262" ] }, "us-gaap_SelfInsuranceReservePolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "SelfInsuranceReservePolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Insurance / Self-Insurance Liabilities", "label": "Self Insurance Reserve [Policy Text Block]", "documentation": "Disclosure of accounting policy for self-insurance reserves, including, but not limited to incurred but not reported reserves (IBNR)." } } }, "auth_ref": [] }, "us-gaap_SellingGeneralAndAdministrativeExpense": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "SellingGeneralAndAdministrativeExpense", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedStatementsOfIncome": { "parentTag": "us-gaap_OperatingIncomeLoss", "weight": -1.0, "order": 3.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Selling, general and administrative", "label": "Selling, General and Administrative Expense", "documentation": "The aggregate total costs related to selling a firm's product and services, as well as all other general and administrative expenses. Direct selling expenses (for example, credit, warranty, and advertising) are expenses that can be directly linked to the sale of specific products. Indirect selling expenses are expenses that cannot be directly linked to the sale of specific products, for example telephone expenses, Internet, and postal charges. General and administrative expenses include salaries of non-sales personnel, rent, utilities, communication, etc." } } }, "auth_ref": [ "r24", "r1036", "r1037", "r1038", "r1040", "r1348" ] }, "us-gaap_SellingGeneralAndAdministrativeExpensesPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "SellingGeneralAndAdministrativeExpensesPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Selling, General and Administrative Expenses", "label": "Selling, General and Administrative Expenses, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for inclusion of significant items in the selling, general and administrative (or similar) expense report caption." } } }, "auth_ref": [ "r1485" ] }, "cost_SeniorNotesOnePointSevenFivePercentDueAprilTwentyThirtyTwoMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "SeniorNotesOnePointSevenFivePercentDueAprilTwentyThirtyTwoMember", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "1.750% Senior Notes due April 2032", "label": "SeniorNotesOnePointSevenFivePercentDueAprilTwentyThirtyTwo [Member]", "documentation": "SeniorNotesOnePointSevenFivePercentDueAprilTwentyThirtyTwo" } } }, "auth_ref": [] }, "cost_SeniorNotesOnePointSixZeroPercentDueAprilTwentyThirtyMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "SeniorNotesOnePointSixZeroPercentDueAprilTwentyThirtyMember", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "1.600% Senior Notes due April 2030", "label": "SeniorNotesOnePointSixZeroPercentDueAprilTwentyThirty [Member]", "documentation": "SeniorNotesOnePointSixZeroPercentDueAprilTwentyThirty" } } }, "auth_ref": [] }, "cost_SeniorNotesOnePointThreeSevenFivePercentDueJuneTwentyTwentySevenMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "SeniorNotesOnePointThreeSevenFivePercentDueJuneTwentyTwentySevenMember", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "1.375% Senior Notes due June 2027", "label": "SeniorNotesOnePointThreeSevenFivePercentDueJuneTwentyTwentySeven [Member]", "documentation": "SeniorNotesOnePointThreeSevenFivePercentDueJuneTwentyTwentySeven" } } }, "auth_ref": [] }, "cost_SeniorNotesThreePercentDueMayEighteenTwentyTwentySevenMemberMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "SeniorNotesThreePercentDueMayEighteenTwentyTwentySevenMemberMember", "presentation": [ "http://www.costco.com/role/DebtCarryingValueofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "3.000% Senior Notes due May 2027", "label": "SeniorNotesThreePercentDueMayEighteenTwentyTwentySeven[Member] [Member]", "documentation": "SeniorNotesThreePercentDueMayEighteenTwentyTwentySeven[Member]" } } }, "auth_ref": [] }, "cost_SeniorNotesTwoPointSevenFivePercentDueMayEighteenTwentyTwentyFourMemberMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "SeniorNotesTwoPointSevenFivePercentDueMayEighteenTwentyTwentyFourMemberMember", "presentation": [ "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "2.750% Senior Notes due May 2024", "label": "SeniorNotesTwoPointSevenFivePercentDueMayEighteenTwentyTwentyFour [Member] [Member]", "documentation": "SeniorNotesTwoPointSevenFivePercentDueMayEighteenTwentyTwentyFour [Member] [Member]" } } }, "auth_ref": [] }, "cost_SeniorNotesZeroPointNineTwoPercentDueJulyTwentyTwentyFourMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "SeniorNotesZeroPointNineTwoPercentDueJulyTwentyTwentyFourMember", "presentation": [ "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "0.920% Senior Notes Due July 2024", "label": "Senior Notes Zero Point Nine Two Percent Due July Twenty Twenty Four [Member]", "documentation": "Senior Notes Zero Point Nine Two Percent Due July Twenty Twenty Four" } } }, "auth_ref": [] }, "cost_SeniorNotesZeroPointSevenNineZeroPercentDueMayTwentyTwentyFiveMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "SeniorNotesZeroPointSevenNineZeroPercentDueMayTwentyTwentyFiveMember", "presentation": [ "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "0.790% Senior Notes Due May 2025", "label": "SeniorNotesZeroPointSevenNineZeroPercentDueMayTwentyTwentyFive [Member]", "documentation": "SeniorNotesZeroPointSevenNineZeroPercentDueMayTwentyTwentyFive" } } }, "auth_ref": [] }, "cost_SeniorNotesZeroPointSixThreePercentDueMarchTwentyTwentySixMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "SeniorNotesZeroPointSixThreePercentDueMarchTwentyTwentySixMember", "presentation": [ "http://www.costco.com/role/DebtScheduleofLongTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "0.630% Senior Notes Due March 2026", "label": "Senior Notes Zero Point Six Three Percent Due March Twenty Twenty Six [Member]", "documentation": "Senior Notes Zero Point Six Three Percent Due March Twenty Twenty Six" } } }, "auth_ref": [] }, "us-gaap_ShareBasedCompensation": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensation", "crdr": "debit", "calculation": { "http://www.costco.com/role/StockBasedCompensationPlansSummaryofStockBasedCompensationExpenseDetails": { "parentTag": "us-gaap_AllocatedShareBasedCompensationExpenseNetOfTax", "weight": 1.0, "order": 1.0 }, "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows": { "parentTag": "us-gaap_NetCashProvidedByUsedInOperatingActivities", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows", "http://www.costco.com/role/StockBasedCompensationPlansSummaryofStockBasedCompensationExpenseDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Stock-based compensation", "verboseLabel": "Total stock-based compensation expense before income taxes", "label": "Share-Based Payment Arrangement, Noncash Expense", "documentation": "Amount of noncash expense for share-based payment arrangement." } } }, "auth_ref": [ "r3" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardAwardVestingPeriod1": { "xbrltype": "durationItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardAwardVestingPeriod1", "presentation": [ "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Share-based compensation arrangement by share-based payment award, award vesting period", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Award Vesting Period", "documentation": "Period over which grantee's right to exercise award under share-based payment arrangement is no longer contingent on satisfaction of service or performance condition, in 'PnYnMnDTnHnMnS' format, for example, 'P1Y5M13D' represents reported fact of one year, five months, and thirteen days. Includes, but is not limited to, combination of market, performance or service condition." } } }, "auth_ref": [ "r1085" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsAdditionalDisclosuresAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsAdditionalDisclosuresAbstract", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Weighted average grant date fair value", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Additional Disclosures [Abstract]" } } }, "auth_ref": [] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsForfeitedInPeriod": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsForfeitedInPeriod", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails" ], "lang": { "en-us": { "role": { "negatedLabel": "Forfeited", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Forfeited in Period", "documentation": "The number of equity-based payment instruments, excluding stock (or unit) options, that were forfeited during the reporting period." } } }, "auth_ref": [ "r507" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsForfeituresWeightedAverageGrantDateFairValue": { "xbrltype": "perShareItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsForfeituresWeightedAverageGrantDateFairValue", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Forfeited", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Forfeitures, Weighted Average Grant Date Fair Value", "documentation": "Weighted average fair value as of the grant date of equity-based award plans other than stock (unit) option plans that were not exercised or put into effect as a result of the occurrence of a terminating event." } } }, "auth_ref": [ "r507" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsGrantsInPeriod": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsGrantsInPeriod", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails", "http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Granted", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Grants in Period", "documentation": "The number of grants made during the period on other than stock (or unit) option plans (for example, phantom stock or unit plan, stock or unit appreciation rights plan, performance target plan)." } } }, "auth_ref": [ "r505" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsGrantsInPeriodWeightedAverageGrantDateFairValue": { "xbrltype": "perShareItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsGrantsInPeriodWeightedAverageGrantDateFairValue", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails", "http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails" ], "lang": { "en-us": { "role": { "verboseLabel": "Weighted-average grant date fair value", "terseLabel": "Granted", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Grants in Period, Weighted Average Grant Date Fair Value", "documentation": "The weighted average fair value at grant date for nonvested equity-based awards issued during the period on other than stock (or unit) option plans (for example, phantom stock or unit plan, stock or unit appreciation rights plan, performance target plan)." } } }, "auth_ref": [ "r505" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsNonvestedNumber": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsNonvestedNumber", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails" ], "lang": { "en-us": { "role": { "periodStartLabel": "Outstanding at the end of 2025", "periodEndLabel": "Outstanding at the end of 2026", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Nonvested, Number", "documentation": "The number of non-vested equity-based payment instruments, excluding stock (or unit) options, that validly exist and are outstanding as of the balance sheet date." } } }, "auth_ref": [ "r502", "r503" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsNonvestedRollForward": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsNonvestedRollForward", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Number of units", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Nonvested, Number of Shares [Roll Forward]", "documentation": "A roll forward is a reconciliation of a concept from the beginning of a period to the end of a period." } } }, "auth_ref": [] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsNonvestedWeightedAverageGrantDateFairValue": { "xbrltype": "perShareItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsNonvestedWeightedAverageGrantDateFairValue", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails" ], "lang": { "en-us": { "role": { "periodStartLabel": "Outstanding at the end of 2025", "periodEndLabel": "Outstanding at the end of 2026", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Nonvested, Weighted Average Grant Date Fair Value", "documentation": "Per share or unit weighted-average fair value of nonvested award under share-based payment arrangement. Excludes share and unit options." } } }, "auth_ref": [ "r502", "r503" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsVestedInPeriod": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsVestedInPeriod", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails", "http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "RSUs vested, but not yet delivered (shares)", "negatedLabel": "Vested and delivered", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Vested in Period", "documentation": "The number of equity-based payment instruments, excluding stock (or unit) options, that vested during the reporting period." } } }, "auth_ref": [ "r506" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsVestedInPeriodWeightedAverageGrantDateFairValue": { "xbrltype": "perShareItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardEquityInstrumentsOtherThanOptionsVestedInPeriodWeightedAverageGrantDateFairValue", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansSummaryofRSUTransactionsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Vested and delivered", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Equity Instruments Other than Options, Vested in Period, Weighted Average Grant Date Fair Value", "documentation": "The weighted average fair value as of grant date pertaining to an equity-based award plan other than a stock (or unit) option plan for which the grantee gained the right during the reporting period, by satisfying service and performance requirements, to receive or retain shares or units, other instruments, or cash in accordance with the terms of the arrangement." } } }, "auth_ref": [ "r506" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardLineItems", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Share-based Compensation Arrangement by Share-based Payment Award [Line Items]", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r485", "r487", "r490", "r491", "r492", "r494", "r495", "r496", "r497", "r498", "r499", "r500", "r501", "r502", "r503", "r504", "r505", "r506", "r507", "r508", "r509", "r510", "r511", "r513", "r514", "r515", "r516", "r517", "r518", "r523" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardNonOptionEquityInstrumentsOutstandingNumber": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardNonOptionEquityInstrumentsOutstandingNumber", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Share-Based Compensation Arrangement by Share-Based Payment Award, Non-Option Equity Instruments, Outstanding, Number", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Non-Option Equity Instruments, Outstanding, Number", "documentation": "Number of equity instruments other than options outstanding, including both vested and non-vested instruments." } } }, "auth_ref": [ "r36", "r37" ] }, "us-gaap_ShareBasedCompensationArrangementByShareBasedPaymentAwardNumberOfSharesAvailableForGrant": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentAwardNumberOfSharesAvailableForGrant", "presentation": [ "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Number of shares available to be granted as RSUs", "label": "Share-Based Compensation Arrangement by Share-Based Payment Award, Number of Shares Available for Grant", "documentation": "The difference between the maximum number of shares (or other type of equity) authorized for issuance under the plan (including the effects of amendments and adjustments), and the sum of: 1) the number of shares (or other type of equity) already issued upon exercise of options or other equity-based awards under the plan; and 2) shares (or other type of equity) reserved for issuance on granting of outstanding awards, net of cancellations and forfeitures, if applicable." } } }, "auth_ref": [ "r15" ] }, "cost_ShareBasedCompensationArrangementByShareBasedPaymentNumberOfYearsOfService": { "xbrltype": "durationItemType", "nsuri": "http://www.costco.com/20260830", "localname": "ShareBasedCompensationArrangementByShareBasedPaymentNumberOfYearsOfService", "presentation": [ "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Share-based compensation arrangement by share-based payment number of years of service", "label": "Share Based Compensation Arrangement By Share Based Payment Number Of Years Of Service", "documentation": "The number of years of service completed by an employee with the Company at which accelerated vesting occurs." } } }, "auth_ref": [] }, "us-gaap_ShareBasedCompensationArrangementsByShareBasedPaymentAwardAwardTypeAndPlanNameDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationArrangementsByShareBasedPaymentAwardAwardTypeAndPlanNameDomain", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryandEffectiveRatesNarrativeDetails", "http://www.costco.com/role/StockBasedCompensationPlansAdditionalInformationDetails", "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Award Type [Domain]", "label": "Award Type [Domain]", "documentation": "Award under share-based payment arrangement." } } }, "auth_ref": [ "r490", "r491", "r492", "r494", "r495", "r496", "r497", "r498", "r499", "r500", "r501", "r502", "r503", "r504", "r505", "r506", "r507", "r508", "r509", "r510", "r511", "r514", "r515", "r516", "r517", "r518" ] }, "us-gaap_ShareBasedCompensationOptionAndIncentivePlansPolicy": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShareBasedCompensationOptionAndIncentivePlansPolicy", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Stock-Based Compensation", "label": "Share-Based Payment Arrangement [Policy Text Block]", "documentation": "Disclosure of accounting policy for award under share-based payment arrangement. Includes, but is not limited to, methodology and assumption used in measuring cost." } } }, "auth_ref": [ "r484", "r493", "r512", "r513", "r514", "r515", "r518", "r525", "r526", "r527", "r528", "r529", "r530", "r531", "r532" ] }, "us-gaap_ShortTermInvestments": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "ShortTermInvestments", "crdr": "debit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_AssetsCurrent", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets", "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Short-term investments", "verboseLabel": "Total investments, recorded basis", "label": "Short-Term Investments", "documentation": "Amount of investments including trading securities, available-for-sale securities, held-to-maturity securities, and short-term investments classified as other and current." } } }, "auth_ref": [ "r1296" ] }, "us-gaap_SignificantAccountingPoliciesTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "SignificantAccountingPoliciesTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Significant Accounting Policies", "label": "Significant Accounting Policies [Text Block]", "documentation": "The entire disclosure for all significant accounting policies of the reporting entity." } } }, "auth_ref": [ "r176", "r177" ] }, "us-gaap_StateAndLocalIncomeTaxExpenseBenefitContinuingOperations": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StateAndLocalIncomeTaxExpenseBenefitContinuingOperations", "crdr": "debit", "calculation": { "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails": { "parentTag": "us-gaap_IncomeTaxExpenseBenefit", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "totalLabel": "Total state", "label": "State and Local Income Tax Expense (Benefit), Continuing Operations", "documentation": "Amount of current and deferred state and local tax expense (benefit) attributable to income (loss) from continuing operations. Includes, but is not limited to, current and deferred regional, territorial, and provincial tax expense (benefit) for non-US (United States of America) jurisdiction." } } }, "auth_ref": [ "r543", "r1359", "r1365", "r1486", "r1498" ] }, "us-gaap_StateAndLocalIncomeTaxExpenseBenefitContinuingOperationsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StateAndLocalIncomeTaxExpenseBenefitContinuingOperationsAbstract", "presentation": [ "http://www.costco.com/role/IncomeTaxesScheduleofForeignAndDomesticIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "State [Abstract]", "label": "State and Local Income Tax Expense (Benefit), Continuing Operations [Abstract]" } } }, "auth_ref": [] }, "us-gaap_StateAndLocalTaxJurisdictionOtherMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StateAndLocalTaxJurisdictionOtherMember", "presentation": [ "http://www.costco.com/role/IncomeTaxesCashPaidforIncomeTaxesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "U.S. state and local, Other", "label": "Income Tax Jurisdiction, Domestic State and Local, Other [Member]", "documentation": "Designated state and local jurisdiction entitled to levy and collect income tax in country of domicile, classified as other." } } }, "auth_ref": [ "r1356", "r1493" ] }, "us-gaap_StatementBusinessSegmentsAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StatementBusinessSegmentsAxis", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "Segments [Axis]", "label": "Segments [Axis]", "documentation": "Information by business segments." } } }, "auth_ref": [ "r102", "r224", "r234", "r237", "r238", "r239", "r240", "r241", "r242", "r243", "r244", "r245", "r246", "r248", "r249", "r251", "r252", "r253", "r254", "r255", "r256", "r257", "r258", "r260", "r261", "r262", "r267", "r330", "r331", "r332", "r333", "r334", "r335", "r336", "r337", "r338", "r341", "r349", "r350", "r358", "r359", "r586", "r587", "r857", "r858", "r859", "r860", "r861", "r862", "r863", "r864", "r865", "r866", "r867", "r1050", "r1053", "r1054", "r1060", "r1134", "r1574", "r1577", "r1578", "r1579", "r1580", "r1581", "r1582", "r1583", "r1584", "r1585", "r1586", "r1587", "r1588", "r1589", "r1590", "r1591", "r1592", "r1593", "r1594", "r1595", "r1596", "r1597", "r1598", "r1599", "r1600", "r1601", "r1602", "r1614", "r1615" ] }, "us-gaap_StatementClassOfStockAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StatementClassOfStockAxis", "presentation": [ "http://www.costco.com/role/StockholdersEquityAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Class of Stock [Axis]", "label": "Class of Stock [Axis]", "documentation": "Information by the different classes of stock of the entity." } } }, "auth_ref": [ "r56", "r109", "r110", "r139", "r140", "r141", "r142", "r143", "r144", "r178", "r182", "r209", "r213", "r215", "r217", "r226", "r227", "r305", "r368", "r371", "r372", "r373", "r377", "r378", "r409", "r410", "r412", "r413", "r415", "r418", "r421", "r422", "r424", "r425", "r426", "r427", "r428", "r429", "r431", "r434", "r438", "r439", "r440", "r441", "r442", "r444", "r445", "r448", "r449", "r450", "r679", "r790", "r791", "r798", "r799", "r800", "r832", "r891", "r892", "r893", "r894", "r897", "r899", "r900", "r901", "r902", "r903", "r904", "r905", "r906", "r907", "r908", "r909", "r929", "r949", "r967", "r1000", "r1001", "r1002", "r1003", "r1004", "r1263", "r1361", "r1363", "r1372", "r1448", "r1450" ] }, "us-gaap_StatementEquityComponentsAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StatementEquityComponentsAxis", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Equity Components [Axis]", "label": "Equity Components [Axis]", "documentation": "Information by component of equity." } } }, "auth_ref": [ "r99", "r100", "r109", "r143", "r144", "r159", "r160", "r161", "r189", "r190", "r191", "r193", "r200", "r202", "r204", "r225", "r306", "r307", "r342", "r343", "r344", "r407", "r438", "r443", "r444", "r445", "r448", "r450", "r453", "r467", "r468", "r470", "r471", "r524", "r573", "r574", "r581", "r582", "r583", "r585", "r588", "r589", "r633", "r634", "r635", "r637", "r638", "r639", "r640", "r641", "r642", "r643", "r644", "r645", "r646", "r650", "r683", "r684", "r685", "r686", "r687", "r688", "r692", "r712", "r751", "r790", "r791", "r799", "r800", "r832", "r849", "r877", "r878", "r879", "r897", "r967", "r1450" ] }, "srt_StatementGeographicalAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "StatementGeographicalAxis", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails", "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails", "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails", "http://www.costco.com/role/DebtScheduleOfShortTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Geographical [Axis]", "label": "Geographical [Axis]", "documentation": "Information by geographical components." } } }, "auth_ref": [ "r60", "r62", "r65", "r67", "r74", "r75", "r76", "r77", "r78", "r79", "r80", "r81", "r82", "r84", "r85", "r86", "r229", "r265", "r266", "r755", "r756", "r757", "r758", "r759", "r760", "r761", "r762", "r763", "r764", "r765", "r766", "r767", "r768", "r769", "r770", "r771", "r772", "r773", "r774", "r775", "r776", "r777", "r778", "r779", "r780", "r781", "r782", "r783", "r784", "r785", "r786", "r787", "r788", "r807", "r808", "r809", "r810", "r911", "r914", "r916", "r975", "r979", "r983", "r995", "r1006", "r1008", "r1009", "r1010", "r1012", "r1013", "r1014", "r1015", "r1016", "r1017", "r1018", "r1019", "r1020", "r1024", "r1045", "r1071", "r1073", "r1122", "r1123", "r1124", "r1125", "r1126", "r1127", "r1128", "r1129", "r1133", "r1141", "r1574", "r1577", "r1578", "r1580", "r1581", "r1582", "r1583", "r1584", "r1585", "r1586", "r1587", "r1588", "r1589", "r1590", "r1591", "r1592", "r1593", "r1594", "r1595", "r1596", "r1597", "r1598", "r1599", "r1600", "r1601", "r1602", "r1614", "r1615" ] }, "us-gaap_StatementLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StatementLineItems", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Statement [Line Items]", "label": "Statement [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r109", "r110", "r115", "r116", "r123", "r133", "r135", "r139", "r142", "r143", "r144", "r147", "r189", "r190", "r191", "r225", "r409", "r410", "r412", "r415", "r421", "r438", "r440", "r441", "r442", "r443", "r444", "r445", "r446", "r447", "r448", "r450", "r452", "r453", "r463", "r692", "r754", "r790", "r791", "r798", "r799", "r800", "r886", "r898", "r909", "r921", "r922", "r923", "r924", "r925", "r926", "r929", "r932", "r933", "r934", "r935", "r936", "r937", "r938", "r939", "r940", "r942", "r943", "r944", "r945", "r946", "r951", "r952", "r953", "r954", "r955", "r956", "r957", "r958", "r959", "r960", "r961", "r962", "r963", "r964", "r967", "r1028", "r1039", "r1040", "r1142", "r1617" ] }, "us-gaap_StatementOfCashFlowsAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StatementOfCashFlowsAbstract", "lang": { "en-us": { "role": { "terseLabel": "Statement of Cash Flows [Abstract]", "label": "Statement of Cash Flows [Abstract]" } } }, "auth_ref": [] }, "us-gaap_StatementOfFinancialPositionAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StatementOfFinancialPositionAbstract", "lang": { "en-us": { "role": { "terseLabel": "Statement of Financial Position [Abstract]", "label": "Statement of Financial Position [Abstract]" } } }, "auth_ref": [] }, "us-gaap_StatementOfFinancialPositionLocationBalanceAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StatementOfFinancialPositionLocationBalanceAxis", "presentation": [ "http://www.costco.com/role/IncomeTaxesDeferredTaxAssetsandLiabilitiesNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Balance Sheet Location [Axis]", "label": "Location, Statement of Financial Position, Balance [Axis]", "documentation": "Information by location in statement of financial position line item where disaggregated cumulative balance is reported." } } }, "auth_ref": [ "r357", "r595", "r598", "r599", "r600", "r601", "r619", "r620", "r621", "r622", "r623", "r624", "r625", "r678", "r1102", "r1103", "r1575", "r1576" ] }, "us-gaap_StatementOfIncomeAndComprehensiveIncomeAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StatementOfIncomeAndComprehensiveIncomeAbstract", "lang": { "en-us": { "role": { "terseLabel": "Statement of Comprehensive Income [Abstract]", "label": "Statement of Comprehensive Income [Abstract]" } } }, "auth_ref": [] }, "us-gaap_StatementOfStockholdersEquityAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StatementOfStockholdersEquityAbstract", "lang": { "en-us": { "role": { "terseLabel": "Statement of Stockholders' Equity [Abstract]", "label": "Statement of Stockholders' Equity [Abstract]" } } }, "auth_ref": [] }, "us-gaap_StatementTable": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StatementTable", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Statement [Table]", "label": "Statement [Table]", "documentation": "Presentation of information about comprehensive income, income, other comprehensive income, financial position, cash flows, and shareholders' equity." } } }, "auth_ref": [ "r101", "r109", "r110", "r115", "r116", "r123", "r133", "r135", "r139", "r142", "r143", "r144", "r147", "r189", "r190", "r191", "r225", "r268", "r409", "r410", "r412", "r415", "r421", "r438", "r440", "r441", "r442", "r443", "r444", "r445", "r446", "r447", "r448", "r450", "r452", "r453", "r463", "r692", "r754", "r790", "r791", "r798", "r799", "r800", "r832", "r886", "r898", "r909", "r921", "r922", "r923", "r924", "r925", "r926", "r929", "r932", "r933", "r934", "r935", "r936", "r937", "r938", "r939", "r940", "r942", "r943", "r944", "r945", "r946", "r951", "r952", "r953", "r954", "r955", "r956", "r957", "r958", "r959", "r960", "r961", "r962", "r963", "r964", "r967", "r1028", "r1039", "r1040", "r1142", "r1617" ] }, "ecd_StkPrcOrTsrEstimationMethodTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "StkPrcOrTsrEstimationMethodTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/ErrCompDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Stock Price or TSR Estimation Method", "label": "Stock Price or TSR Estimation Method [Text Block]" } } }, "auth_ref": [ "r1171", "r1182", "r1192", "r1225" ] }, "us-gaap_StockAppreciationRightsSARSMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StockAppreciationRightsSARSMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Stock Appreciation Rights (SARs)", "label": "Stock Appreciation Rights (SARs) [Member]", "documentation": "Right to receive cash or shares equal to appreciation of predetermined number of grantor's shares during predetermined time period." } } }, "auth_ref": [ "r1457", "r1458", "r1459", "r1460", "r1461", "r1462", "r1463", "r1464", "r1465", "r1466", "r1467", "r1468", "r1469", "r1470", "r1471", "r1472", "r1473", "r1474", "r1475", "r1476", "r1477", "r1478", "r1479", "r1480", "r1481", "r1482" ] }, "us-gaap_StockIssuedDuringPeriodSharesRestrictedStockAwardGross": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StockIssuedDuringPeriodSharesRestrictedStockAwardGross", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Release of vested RSUs, including tax effects (shares)", "label": "Stock Issued During Period, Shares, Restricted Stock Award, Gross", "documentation": "Total number of shares issued during the period, including shares forfeited, as a result of Restricted Stock Awards." } } }, "auth_ref": [ "r1280", "r1292", "r1293", "r1443", "r1444", "r1445", "r1447", "r1449" ] }, "us-gaap_StockIssuedDuringPeriodValueRestrictedStockAwardGross": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StockIssuedDuringPeriodValueRestrictedStockAwardGross", "crdr": "credit", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Release of vested RSUs, including tax effects", "label": "Stock Issued During Period, Value, Restricted Stock Award, Gross", "documentation": "Aggregate value of stock related to Restricted Stock Awards issued during the period." } } }, "auth_ref": [ "r1280", "r1292", "r1293", "r1443", "r1444", "r1445", "r1447", "r1449", "r1555", "r1556", "r1559", "r1560" ] }, "srt_StockRepurchaseProgramAuthorizedAmount1": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "StockRepurchaseProgramAuthorizedAmount1", "crdr": "credit", "presentation": [ "http://www.costco.com/role/EquityAdditionalInformationStockRepurchaseProgramsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Stock Repurchase Program, Authorized Amount", "label": "Share Repurchase Program, Authorized, Amount", "documentation": "Amount authorized for purchase of share under share repurchase plan. Includes, but is not limited to, repurchase of stock and unit of ownership." } } }, "auth_ref": [ "r1450" ] }, "us-gaap_StockRepurchaseProgramRemainingAuthorizedRepurchaseAmount1": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StockRepurchaseProgramRemainingAuthorizedRepurchaseAmount1", "crdr": "credit", "presentation": [ "http://www.costco.com/role/EquityAdditionalInformationStockRepurchaseProgramsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Stock Repurchase Program, Remaining Authorized Repurchase Amount", "label": "Share Repurchase Program, Remaining Authorized, Amount", "documentation": "Amount remaining authorized for purchase of share under share repurchase plan. Includes, but is not limited to, repurchase of stock and unit of ownership." } } }, "auth_ref": [ "r1450" ] }, "us-gaap_StockRepurchasedAndRetiredDuringPeriodShares": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StockRepurchasedAndRetiredDuringPeriodShares", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity", "http://www.costco.com/role/StockholdersEquityStockRepurchasedDuringPeriodDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Repurchases of common stock, shares", "terseLabel": "Repurchases of common stock, shares", "label": "Stock Repurchased and Retired During Period, Shares", "documentation": "Number of shares that have been repurchased and retired during the period." } } }, "auth_ref": [ "r1280", "r1292", "r1293", "r1443", "r1444", "r1445", "r1447", "r1449", "r1555", "r1556", "r1559", "r1560" ] }, "us-gaap_StockRepurchasedAndRetiredDuringPeriodValue": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StockRepurchasedAndRetiredDuringPeriodValue", "crdr": "debit", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsofEquity", "http://www.costco.com/role/StockholdersEquityStockRepurchasedDuringPeriodDetails" ], "lang": { "en-us": { "role": { "negatedLabel": "Repurchases of common stock, value", "terseLabel": "Repurchases of common stock, value", "label": "Stock Repurchased and Retired During Period, Value", "documentation": "Equity impact of the value of stock that has been repurchased and retired during the period. The excess of the purchase price over par value can be charged against retained earnings (once the excess is fully allocated to additional paid in capital)." } } }, "auth_ref": [ "r1280", "r1292", "r1293", "r1443", "r1444", "r1445", "r1447", "r1449", "r1555", "r1556", "r1559", "r1560" ] }, "us-gaap_StockholdersEquity": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StockholdersEquity", "crdr": "credit", "calculation": { "http://www.costco.com/role/ConsolidatedBalanceSheets": { "parentTag": "us-gaap_LiabilitiesAndStockholdersEquity", "weight": 1.0, "order": 2.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets", "http://www.costco.com/role/ConsolidatedStatementsofEquity" ], "lang": { "en-us": { "role": { "totalLabel": "TOTAL EQUITY", "periodStartLabel": "Equity at beginning of period", "periodEndLabel": "Equity at end of period", "label": "Equity, Attributable to Parent", "documentation": "Amount of equity (deficit) attributable to parent. Excludes temporary equity and equity attributable to noncontrolling interest." } } }, "auth_ref": [ "r33", "r931", "r947", "r968", "r969", "r1118", "r1148", "r1297", "r1359", "r1363", "r1364", "r1404", "r1543", "r1619" ] }, "us-gaap_StockholdersEquityIncludingPortionAttributableToNoncontrollingInterestAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StockholdersEquityIncludingPortionAttributableToNoncontrollingInterestAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedBalanceSheets" ], "lang": { "en-us": { "role": { "terseLabel": "EQUITY", "label": "Equity, Including Portion Attributable to Noncontrolling Interest [Abstract]" } } }, "auth_ref": [] }, "us-gaap_StockholdersEquityNoteAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StockholdersEquityNoteAbstract", "lang": { "en-us": { "role": { "terseLabel": "Stockholders' Equity Note [Abstract]", "label": "Stockholders' Equity Note [Abstract]" } } }, "auth_ref": [] }, "us-gaap_StockholdersEquityNoteDisclosureTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StockholdersEquityNoteDisclosureTextBlock", "presentation": [ "http://www.costco.com/role/StockholdersEquity" ], "lang": { "en-us": { "role": { "terseLabel": "Stockholders' Equity", "label": "Equity [Text Block]", "documentation": "The entire disclosure for equity." } } }, "auth_ref": [ "r109", "r143", "r144", "r148", "r420", "r423", "r425", "r430", "r431", "r432", "r433", "r434", "r435", "r436", "r439", "r444", "r445", "r448", "r450", "r451", "r455", "r456", "r457", "r458", "r459", "r460", "r461", "r462", "r631", "r648", "r649", "r713", "r970", "r972", "r1005" ] }, "us-gaap_StockholdersEquityPolicyTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "StockholdersEquityPolicyTextBlock", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Stock Repurchase Programs", "label": "Stockholders' Equity, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for its capital stock transactions, including dividends and accumulated other comprehensive income." } } }, "auth_ref": [ "r647", "r971" ] }, "cost_SummaryOfSignificantAccountingPoliciesLineItems": { "xbrltype": "stringItemType", "nsuri": "http://www.costco.com/20260830", "localname": "SummaryOfSignificantAccountingPoliciesLineItems", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails", "http://www.costco.com/role/AccountingPoliciesRevenueRecognitionDetails", "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Summary Of Significant Accounting Policies [Line Items]", "label": "Summary Of Significant Accounting Policies [Line Items]", "documentation": "Summary Of Significant Accounting Policies [Line Items]" } } }, "auth_ref": [] }, "us-gaap_SupplementalCashFlowInformationAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "SupplementalCashFlowInformationAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfCashFlows" ], "lang": { "en-us": { "role": { "terseLabel": "SUPPLEMENTAL DISCLOSURE OF CASH FLOW INFORMATION:", "label": "Supplemental Cash Flow Information [Abstract]" } } }, "auth_ref": [] }, "country_TW": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "TW", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "TAIWAN", "label": "TAIWAN" } } }, "auth_ref": [] }, "ecd_TabularListTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TabularListTableTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Tabular List, Table", "label": "Tabular List [Table Text Block]" } } }, "auth_ref": [ "r1218" ] }, "us-gaap_TaxCreditCarryforwardLineItems": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "TaxCreditCarryforwardLineItems", "presentation": [ "http://www.costco.com/role/IncomeTaxesDeferredTaxAssetsandLiabilitiesNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Tax Credit Carryforward [Line Items]", "label": "Tax Credit Carryforward [Line Items]", "documentation": "Line items represent financial concepts included in a table. These concepts are used to disclose reportable information associated with domain members defined in one or many axes to the table." } } }, "auth_ref": [ "r571" ] }, "us-gaap_TaxCreditCarryforwardValuationAllowance": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "TaxCreditCarryforwardValuationAllowance", "crdr": "credit", "calculation": { "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails": { "parentTag": "us-gaap_DeferredTaxAssetsNet", "weight": -1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/IncomeTaxesComponentsofDeferredTaxAssetsAndLiabilitiesDetails", "http://www.costco.com/role/IncomeTaxesDeferredTaxAssetsandLiabilitiesNarrativeDetails" ], "lang": { "en-us": { "role": { "negatedLabel": "Valuation allowance", "terseLabel": "Valuation Allowances", "label": "Tax Credit Carryforward, Valuation Allowance", "documentation": "Amount of valuation allowance pertaining to the deferred tax asset representing potential future taxable deductions from tax credit carryforwards for which it is more likely than not that a tax benefit will not be realized." } } }, "auth_ref": [ "r1491" ] }, "us-gaap_TaxJurisdictionOfDomicileExtensibleEnumeration": { "xbrltype": "enumerationSetItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "TaxJurisdictionOfDomicileExtensibleEnumeration", "presentation": [ "http://www.costco.com/role/IncomeTaxesReconciliationBetweenStatutoryAndEffectiveRatesDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Tax Jurisdiction of Domicile [Extensible Enumeration]", "label": "Tax Jurisdiction of Domicile [Extensible Enumeration]", "documentation": "Indicates tax jurisdiction of domicile." } } }, "auth_ref": [ "r544", "r1087" ] }, "srt_TitleOfIndividualAxis": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "TitleOfIndividualAxis", "presentation": [ "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Title of Individual [Axis]", "label": "Title and Position [Axis]", "documentation": "Information by title and position of individual or group within organization." } } }, "auth_ref": [ "r1390", "r1549" ] }, "srt_TitleOfIndividualWithRelationshipToEntityDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/srt/2026", "localname": "TitleOfIndividualWithRelationshipToEntityDomain", "presentation": [ "http://www.costco.com/role/AccountingPoliciesStockBasedCompensationDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Title of Individual [Domain]", "label": "Title and Position [Domain]", "documentation": "Title and position of individual or group within organization." } } }, "auth_ref": [] }, "ecd_TotalShareholderRtnAmt": { "xbrltype": "monetaryItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TotalShareholderRtnAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Total Shareholder Return Amount", "label": "Total Shareholder Return Amount" } } }, "auth_ref": [ "r1210" ] }, "ecd_TotalShareholderRtnVsPeerGroupTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TotalShareholderRtnVsPeerGroupTextBlock", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Total Shareholder Return Vs Peer Group", "label": "Total Shareholder Return Vs Peer Group [Text Block]" } } }, "auth_ref": [ "r1217" ] }, "ecd_TradingArrAxis": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TradingArrAxis", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Trading Arrangement:", "label": "Trading Arrangement [Axis]" } } }, "auth_ref": [ "r1238" ] }, "ecd_TradingArrByIndTable": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TradingArrByIndTable", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Trading Arrangements, by Individual", "label": "Trading Arrangements, by Individual [Table]" } } }, "auth_ref": [ "r1240" ] }, "dei_TradingSymbol": { "xbrltype": "tradingSymbolItemType", "nsuri": "http://xbrl.sec.gov/dei/2026", "localname": "TradingSymbol", "presentation": [ "http://www.costco.com/role/Cover" ], "lang": { "en-us": { "role": { "terseLabel": "Trading Symbol", "label": "Trading Symbol", "documentation": "Trading symbol of an instrument as listed on an exchange." } } }, "auth_ref": [] }, "us-gaap_TransfersAndServicingOfFinancialInstrumentsTypesOfFinancialInstrumentsDomain": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "TransfersAndServicingOfFinancialInstrumentsTypesOfFinancialInstrumentsDomain", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails", "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Financial Instruments [Domain]", "label": "Financial Instruments [Domain]", "documentation": "Instrument or contract that imposes a contractual obligation to deliver cash or another financial instrument or to exchange other financial instruments on potentially unfavorable terms and conveys a contractual right to receive cash or another financial instrument or to exchange other financial instruments on potentially favorable terms." } } }, "auth_ref": [ "r275", "r276", "r277", "r278", "r279", "r280", "r281", "r282", "r283", "r284", "r285", "r286", "r287", "r288", "r289", "r290", "r291", "r292", "r293", "r294", "r295", "r296", "r297", "r298", "r299", "r300", "r301", "r302", "r303", "r304", "r309", "r310", "r311", "r312", "r313", "r314", "r315", "r316", "r317", "r318", "r319", "r320", "r404", "r437", "r631", "r670", "r678", "r680", "r714", "r715", "r716", "r717", "r718", "r719", "r721", "r722", "r723", "r724", "r726", "r727", "r728", "r729", "r730", "r731", "r733", "r734", "r736", "r737", "r738", "r739", "r740", "r741", "r742", "r743", "r744", "r745", "r746", "r747", "r748", "r749", "r750", "r812", "r813", "r814", "r815", "r816", "r817", "r818", "r819", "r820", "r821", "r822", "r823", "r824", "r825", "r826", "r827", "r828", "r829", "r834", "r850", "r1104", "r1106", "r1107", "r1108", "r1109", "r1110", "r1111", "r1112", "r1113", "r1121", "r1266", "r1267", "r1268", "r1269", "r1270", "r1271", "r1272", "r1400", "r1401", "r1402", "r1403", "r1522", "r1525", "r1526", "r1527", "r1534", "r1537", "r1539", "r1540" ] }, "ecd_TrdArrAdoptionDate": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TrdArrAdoptionDate", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Adoption Date", "label": "Trading Arrangement Adoption Date" } } }, "auth_ref": [ "r1241" ] }, "ecd_TrdArrDuration": { "xbrltype": "durationItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TrdArrDuration", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Arrangement Duration", "label": "Trading Arrangement Duration" } } }, "auth_ref": [ "r1242" ] }, "ecd_TrdArrExpirationDate": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TrdArrExpirationDate", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Expiration Date", "label": "Trading Arrangement Expiration Date" } } }, "auth_ref": [ "r1242" ] }, "ecd_TrdArrIndName": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TrdArrIndName", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Name", "label": "Trading Arrangement, Individual Name" } } }, "auth_ref": [ "r1240" ] }, "ecd_TrdArrIndTitle": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TrdArrIndTitle", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Title", "label": "Trading Arrangement, Individual Title" } } }, "auth_ref": [ "r1240" ] }, "ecd_TrdArrSecuritiesAggAvailAmt": { "xbrltype": "sharesItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TrdArrSecuritiesAggAvailAmt", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Aggregate Available", "label": "Trading Arrangement, Securities Aggregate Available Amount" } } }, "auth_ref": [ "r1243" ] }, "ecd_TrdArrTerminationDate": { "xbrltype": "stringItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "TrdArrTerminationDate", "presentation": [ "http://xbrl.sec.gov/ecd/role/InsiderTradingArrangements" ], "lang": { "en-us": { "role": { "terseLabel": "Termination Date", "label": "Trading Arrangement Termination Date" } } }, "auth_ref": [ "r1241" ] }, "us-gaap_TreasuryStockAcquiredAverageCostPerShare": { "xbrltype": "perShareItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "TreasuryStockAcquiredAverageCostPerShare", "presentation": [ "http://www.costco.com/role/StockholdersEquityStockRepurchasedDuringPeriodDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Average price per share", "label": "Shares Acquired, Average Cost Per Share", "documentation": "Total cost of shares repurchased divided by the total number of shares repurchased." } } }, "auth_ref": [] }, "country_US": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/country/2026", "localname": "US", "presentation": [ "http://www.costco.com/role/AccountingPoliciesAdditionalInformationDetails", "http://www.costco.com/role/AccountingPoliciesGoodwillandAcquiredIntangibleAssetsDetails", "http://www.costco.com/role/AccountingPoliciesMerchandiseInventoriesDetails", "http://www.costco.com/role/DebtScheduleOfShortTermDebtDetails" ], "lang": { "en-us": { "role": { "terseLabel": "UNITED STATES", "label": "UNITED STATES" } } }, "auth_ref": [] }, "us-gaap_USGovernmentAgenciesDebtSecuritiesMember": { "xbrltype": "domainItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "USGovernmentAgenciesDebtSecuritiesMember", "presentation": [ "http://www.costco.com/role/FairValueMeasurementFairValueofFinancialAssetsandFinancialLiabilitiesMeasuredonRecurringBasisDetails", "http://www.costco.com/role/InvestmentsAvailableforSaleandHeldtoMaturityInvestmentsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "US Government Agencies Debt Securities [Member]", "verboseLabel": "Government and Agency Securities [Member]", "label": "US Government Agencies Debt Securities [Member]", "documentation": "Debentures, notes, and other debt securities issued by US government agencies, for example, but not limited to, Government National Mortgage Association (GNMA or Ginnie Mae). Excludes US treasury securities and debt issued by government-sponsored Enterprises (GSEs), for example, but is not limited to, Federal Home Loan Mortgage Corporation (FHLMC or Freddie Mac), Federal National Mortgage Association (FNMA or Fannie Mae), and the Federal Home Loan Bank (FHLB)." } } }, "auth_ref": [ "r1042", "r1043", "r1079", "r1081", "r1119", "r1406", "r1407", "r1408", "r1409", "r1410", "r1411", "r1412", "r1413", "r1414", "r1415", "r1563", "r1564", "r1565", "r1566", "r1567", "r1568", "r1569", "r1570", "r1571", "r1572", "r1573" ] }, "us-gaap_UndistributedEarningsOfForeignSubsidiaries": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "UndistributedEarningsOfForeignSubsidiaries", "crdr": "credit", "presentation": [ "http://www.costco.com/role/IncomeTaxesDeferredTaxAssetsandLiabilitiesNarrativeDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Undistributed Earnings of Foreign Subsidiaries", "label": "Undistributed Earnings of Foreign Subsidiaries", "documentation": "Amount of undistributed earnings of foreign subsidiaries intended to be permanently reinvested outside the country of domicile." } } }, "auth_ref": [ "r48", "r535", "r885" ] }, "ecd_UndrlygSecurityMktPriceChngPct": { "xbrltype": "pureItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "UndrlygSecurityMktPriceChngPct", "presentation": [ "http://xbrl.sec.gov/ecd/role/AwardTimingDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Underlying Security Market Price Change", "label": "Underlying Security Market Price Change, Percent" } } }, "auth_ref": [ "r1237" ] }, "cost_UnitedStatesMember": { "xbrltype": "domainItemType", "nsuri": "http://www.costco.com/20260830", "localname": "UnitedStatesMember", "presentation": [ "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails", "http://www.costco.com/role/SegmentReportingInformationbySegmentDetails_1" ], "lang": { "en-us": { "role": { "terseLabel": "United States", "label": "United States [Member]", "documentation": "United States" } } }, "auth_ref": [] }, "us-gaap_UnrealizedGainLossOnInvestmentsTableTextBlock": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "UnrealizedGainLossOnInvestmentsTableTextBlock", "presentation": [ "http://www.costco.com/role/InvestmentsTables" ], "lang": { "en-us": { "role": { "terseLabel": "Available for Sale and Held to Maturity Investments", "label": "Unrealized Gain (Loss) on Investments [Table Text Block]", "documentation": "Tabular disclosure of unrealized gains and losses on investments." } } }, "auth_ref": [] }, "us-gaap_UnrecognizedTaxBenefits": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "UnrecognizedTaxBenefits", "crdr": "credit", "presentation": [ "http://www.costco.com/role/IncomeTaxesGrossUnrecognizedTaxBenefitsDetails" ], "lang": { "en-us": { "role": { "periodStartLabel": "Gross unrecognized tax benefit at beginning of year", "periodEndLabel": "Gross unrecognized tax benefit at end of year", "label": "Unrecognized Tax Benefits", "documentation": "Amount of unrecognized tax benefits." } } }, "auth_ref": [ "r536", "r558", "r1086" ] }, "us-gaap_UnrecognizedTaxBenefitsDecreasesResultingFromPriorPeriodTaxPositions": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "UnrecognizedTaxBenefitsDecreasesResultingFromPriorPeriodTaxPositions", "crdr": "debit", "presentation": [ "http://www.costco.com/role/IncomeTaxesGrossUnrecognizedTaxBenefitsDetails" ], "lang": { "en-us": { "role": { "negatedTerseLabel": "Gross decreases\u2014tax positions in prior years", "label": "Unrecognized Tax Benefits, Decrease Resulting from Prior Period Tax Positions", "documentation": "Amount of decrease in unrecognized tax benefits resulting from tax positions taken in prior period tax returns." } } }, "auth_ref": [ "r559", "r1086" ] }, "us-gaap_UnrecognizedTaxBenefitsDecreasesResultingFromSettlementsWithTaxingAuthorities": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "UnrecognizedTaxBenefitsDecreasesResultingFromSettlementsWithTaxingAuthorities", "crdr": "debit", "presentation": [ "http://www.costco.com/role/IncomeTaxesGrossUnrecognizedTaxBenefitsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Gross decreases\u2014settlements", "label": "Unrecognized Tax Benefits, Decrease Resulting from Settlements with Taxing Authorities", "documentation": "Amount of decrease in unrecognized tax benefits resulting from settlements with taxing authorities." } } }, "auth_ref": [ "r561", "r1086" ] }, "us-gaap_UnrecognizedTaxBenefitsIncreasesResultingFromCurrentPeriodTaxPositions": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "UnrecognizedTaxBenefitsIncreasesResultingFromCurrentPeriodTaxPositions", "crdr": "credit", "presentation": [ "http://www.costco.com/role/IncomeTaxesGrossUnrecognizedTaxBenefitsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Gross increases\u2014current year tax positions", "label": "Unrecognized Tax Benefits, Increase Resulting from Current Period Tax Positions", "documentation": "Amount of increase in unrecognized tax benefits resulting from tax positions that have been or will be taken in current period tax return." } } }, "auth_ref": [ "r560", "r1086" ] }, "us-gaap_UnrecognizedTaxBenefitsIncreasesResultingFromPriorPeriodTaxPositions": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "UnrecognizedTaxBenefitsIncreasesResultingFromPriorPeriodTaxPositions", "crdr": "credit", "presentation": [ "http://www.costco.com/role/IncomeTaxesGrossUnrecognizedTaxBenefitsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Gross increases\u2014tax positions in prior years", "label": "Unrecognized Tax Benefits, Increase Resulting from Prior Period Tax Positions", "documentation": "Amount of increase in unrecognized tax benefits resulting from tax positions taken in prior period tax returns." } } }, "auth_ref": [ "r559", "r1086" ] }, "us-gaap_UnrecognizedTaxBenefitsThatWouldImpactEffectiveTaxRate": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "UnrecognizedTaxBenefitsThatWouldImpactEffectiveTaxRate", "crdr": "credit", "presentation": [ "http://www.costco.com/role/IncomeTaxesGrossUnrecognizedTaxBenefitsDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Unrecognized tax benefits that would impact effective tax rate", "label": "Unrecognized Tax Benefits that Would Impact Effective Tax Rate", "documentation": "The total amount of unrecognized tax benefits that, if recognized, would affect the effective tax rate." } } }, "auth_ref": [ "r562", "r1086" ] }, "us-gaap_UseOfEstimates": { "xbrltype": "textBlockItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "UseOfEstimates", "presentation": [ "http://www.costco.com/role/SummaryofSignificantAccountingPoliciesPolicies" ], "lang": { "en-us": { "role": { "terseLabel": "Use of Estimates", "label": "Use of Estimates, Policy [Policy Text Block]", "documentation": "Disclosure of accounting policy for the use of estimates in the preparation of financial statements in conformity with generally accepted accounting principles." } } }, "auth_ref": [ "r51", "r52", "r228", "r230", "r231", "r232", "r807", "r809", "r1046" ] }, "us-gaap_VariableLeaseCost": { "xbrltype": "monetaryItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "VariableLeaseCost", "crdr": "debit", "calculation": { "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails": { "parentTag": "us-gaap_LeaseCost", "weight": 1.0, "order": 4.0 } }, "presentation": [ "http://www.costco.com/role/LeasesComponentsofLeaseExpenseDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Variable Lease, Cost", "label": "Variable Lease, Cost", "documentation": "Amount of variable lease cost, excluded from lease liability, recognized when obligation for payment is incurred for finance and operating leases." } } }, "auth_ref": [ "r704", "r1117" ] }, "ecd_VstngDtFrValOfEqtyAwrdsGrntdAndVstdInCvrdYrMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "VstngDtFrValOfEqtyAwrdsGrntdAndVstdInCvrdYrMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Vesting Date Fair Value of Equity Awards Granted and Vested in Covered Year", "label": "Vesting Date Fair Value of Equity Awards Granted and Vested in Covered Year [Member]" } } }, "auth_ref": [ "r1206" ] }, "us-gaap_WeightedAverageNumberOfDilutedSharesOutstanding": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "WeightedAverageNumberOfDilutedSharesOutstanding", "calculation": { "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareScheduleofEarningsperShareEffectonNetIncomeandWeightedAveregaeNumberofDilutivePotentialCommonStockDetails": { "parentTag": null, "weight": null, "order": null, "root": true } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareScheduleofEarningsperShareEffectonNetIncomeandWeightedAveregaeNumberofDilutivePotentialCommonStockDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Diluted", "totalLabel": "Weighted average diluted shares", "label": "Weighted Average Number of Shares Outstanding, Diluted", "documentation": "The average number of shares or units issued and outstanding that are used in calculating diluted EPS or earnings per unit (EPU), determined based on the timing of issuance of shares or units in the period." } } }, "auth_ref": [ "r208", "r217" ] }, "us-gaap_WeightedAverageNumberOfSharesOutstandingAbstract": { "xbrltype": "stringItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "WeightedAverageNumberOfSharesOutstandingAbstract", "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome" ], "lang": { "en-us": { "role": { "verboseLabel": "Shares used in calculation (000's)", "label": "Weighted Average Number of Shares Outstanding, Diluted [Abstract]" } } }, "auth_ref": [] }, "us-gaap_WeightedAverageNumberOfSharesOutstandingBasic": { "xbrltype": "sharesItemType", "nsuri": "http://fasb.org/us-gaap/2026", "localname": "WeightedAverageNumberOfSharesOutstandingBasic", "calculation": { "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareScheduleofEarningsperShareEffectonNetIncomeandWeightedAveregaeNumberofDilutivePotentialCommonStockDetails": { "parentTag": "us-gaap_WeightedAverageNumberOfDilutedSharesOutstanding", "weight": 1.0, "order": 1.0 } }, "presentation": [ "http://www.costco.com/role/ConsolidatedStatementsOfIncome", "http://www.costco.com/role/NetIncomeperCommonandCommonEquivalentShareScheduleofEarningsperShareEffectonNetIncomeandWeightedAveregaeNumberofDilutivePotentialCommonStockDetails" ], "lang": { "en-us": { "role": { "terseLabel": "Basic", "verboseLabel": "Weighted average basic shares", "label": "Weighted Average Number of Shares Outstanding, Basic", "documentation": "Number of [basic] shares or units, after adjustment for contingently issuable shares or units and other shares or units not deemed outstanding, determined by relating the portion of time within a reporting period that common shares or units have been outstanding to the total time in that period." } } }, "auth_ref": [ "r207", "r217" ] }, "ecd_YrEndFrValOfEqtyAwrdsGrntdInCvrdYrOutsdngAndUnvstdMember": { "xbrltype": "domainItemType", "nsuri": "http://xbrl.sec.gov/ecd/2026", "localname": "YrEndFrValOfEqtyAwrdsGrntdInCvrdYrOutsdngAndUnvstdMember", "presentation": [ "http://xbrl.sec.gov/ecd/role/PvpDisclosure" ], "lang": { "en-us": { "role": { "terseLabel": "Year-end Fair Value of Equity Awards Granted in Covered Year that are Outstanding and Unvested", "label": "Year-end Fair Value of Equity Awards Granted in Covered Year that are Outstanding and Unvested [Member]" } } }, "auth_ref": [ "r1204" ] } } } }, "std_ref": { "r0": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "SubTopic": "230", "Topic": "830", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477401/830-230-45-1" }, "r1": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "10A", "SubTopic": "10", "Topic": "220", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482790/220-10-45-10A" }, "r2": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "10A", "Subparagraph": "(a)", "SubTopic": "10", "Topic": "220", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482790/220-10-45-10A" }, "r3": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "28", "Subparagraph": "(a)", "SubTopic": "10", "Topic": "230", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-28" }, "r4": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "28", "Subparagraph": "(b)", "SubTopic": "10", "Topic": "230", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-28" }, "r5": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "SubTopic": "10", "Topic": "470", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481544/470-10-50-1" }, "r6": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1A", "Subparagraph": "(c)(3)", "SubTopic": "10", "Topic": "810", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481203/810-10-50-1A" }, "r7": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "220", "SubTopic": "10", "Section": "45", "Paragraph": "14", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482790/220-10-45-14" }, "r8": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "220", "SubTopic": "10", "Section": "45", "Paragraph": "14A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482790/220-10-45-14A" }, "r9": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "220", "SubTopic": "10", "Section": "45", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482790/220-10-45-5" }, "r10": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "230", "SubTopic": "10", "Section": "45", "Paragraph": "14", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-14" }, "r11": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "470", "SubTopic": "10", "Section": "50", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481544/470-10-50-5" }, "r12": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "715", "SubTopic": "60", "Publisher": "FASB", "URI": "https://asc.fasb.org/715-60/tableOfContent" }, "r13": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "715", "SubTopic": "70", "Publisher": "FASB", "URI": "https://asc.fasb.org/715-70/tableOfContent" }, "r14": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "715", "SubTopic": "80", "Publisher": "FASB", "URI": "https://asc.fasb.org/715-80/tableOfContent" }, "r15": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "718", "SubTopic": "10", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r16": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "718", "SubTopic": "10", "Section": "50", "Paragraph": "2", "Subparagraph": "(h)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r17": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "810", "SubTopic": "10", "Section": "45", "Paragraph": "12", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481231/810-10-45-12" }, "r18": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Name": "Accounting Standards Codification", "Topic": "942", "SubTopic": "470", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477734/942-470-50-3" }, "r19": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "11", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482790/220-10-45-11" }, "r20": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.5-03(10))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483621/220-10-S99-2" }, "r21": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.5-03(2)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483621/220-10-S99-2" }, "r22": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.5-03(2)(d))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483621/220-10-S99-2" }, "r23": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.5-03(20))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483621/220-10-S99-2" }, "r24": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.5-03(4))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483621/220-10-S99-2" }, "r25": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "13", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-13" }, "r26": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "13", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-13" }, "r27": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "15", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-15" }, "r28": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "15", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-15" }, "r29": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "24", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-24" }, "r30": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "25", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-25" }, "r31": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "25", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-25" }, "r32": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "28", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-28" }, "r33": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "310", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SAB Topic 4.E)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480418/310-10-S99-2" }, "r34": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "330", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 5.L)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480581/330-10-S99-1" }, "r35": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "470", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/470/tableOfContent" }, "r36": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r37": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r38": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "718", "SubTopic": "10", "Subparagraph": "(e)(1)", "Name": "Accounting Standards Codification", "Paragraph": "2", "Section": "50", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r39": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "942", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-04(15))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478524/942-220-S99-1" }, "r40": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "942", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-04(22))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478524/942-220-S99-1" }, "r41": { "role": "http://fasb.org/us-gaap/role/ref/legacyRef", "Topic": "942", "SubTopic": "470", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477734/942-470-50-3" }, "r42": { "role": "http://fasb.org/us-gaap/role/ref/otherTransitionRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482913/230-10-50-2" }, "r43": { "role": "http://fasb.org/us-gaap/role/ref/otherTransitionRef", "Topic": "310", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481962/310-10-50-7A" }, "r44": { "role": "http://fasb.org/us-gaap/role/ref/otherTransitionRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(aa)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r45": { "role": "http://fasb.org/us-gaap/role/ref/otherTransitionRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-6" }, "r46": { "role": "http://fasb.org/us-gaap/role/ref/otherTransitionRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-7" }, "r47": { "role": "http://fasb.org/us-gaap/role/ref/otherTransitionRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-8" }, "r48": { "role": "http://fasb.org/us-gaap/role/ref/otherTransitionRef", "Topic": "740", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482603/740-30-50-2" }, "r49": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "2", "Subparagraph": "(a)", "SubTopic": "20", "Topic": "740", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482659/740-20-45-2" }, "r50": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "6", "Subparagraph": "(a)", "SubTopic": "10", "Topic": "270", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482989/270-10-45-6" }, "r51": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)", "SubTopic": "10", "Topic": "275", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482861/275-10-50-1" }, "r52": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)", "SubTopic": "10", "Topic": "275", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482861/275-10-50-1" }, "r53": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)", "SubTopic": "360", "Topic": "958", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477798/958-360-50-1" }, "r54": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "SubTopic": "360", "Topic": "958", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477798/958-360-50-6" }, "r55": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(h))", "SubTopic": "10", "Topic": "235", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r56": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-K (SK)", "Number": "229", "Section": "1402", "Paragraph": "a", "Publisher": "SEC" }, "r57": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-K (SK)", "Number": "229", "Section": "1403", "Paragraph": "b", "Publisher": "SEC" }, "r58": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "04", "Paragraph": "a", "Publisher": "SEC" }, "r59": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "12", "Paragraph": "Column A", "Footnote": "2", "Publisher": "SEC" }, "r60": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "12", "Paragraph": "Column C", "Footnote": "5", "Publisher": "SEC" }, "r61": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "12A", "Paragraph": "Column A", "Footnote": "2", "Publisher": "SEC" }, "r62": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "12A", "Paragraph": "Column C", "Footnote": "4", "Publisher": "SEC" }, "r63": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "12B", "Paragraph": "Column A", "Subparagraph": "(a)", "Footnote": "4", "Publisher": "SEC" }, "r64": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "12B", "Paragraph": "Column A", "Subparagraph": "(b)", "Footnote": "4", "Publisher": "SEC" }, "r65": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "12B", "Paragraph": "Column C", "Footnote": "2", "Publisher": "SEC" }, "r66": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "14", "Paragraph": "Column A", "Footnote": "2", "Publisher": "SEC" }, "r67": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "14", "Paragraph": "Column F", "Footnote": "7", "Publisher": "SEC" }, "r68": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "17", "Paragraph": "Column A", "Publisher": "SEC" }, "r69": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "17", "Paragraph": "Column B", "Publisher": "SEC" }, "r70": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "17", "Paragraph": "Column C", "Publisher": "SEC" }, "r71": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "17", "Paragraph": "Column D", "Publisher": "SEC" }, "r72": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "17", "Paragraph": "Column E", "Publisher": "SEC" }, "r73": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "17", "Paragraph": "Column F", "Publisher": "SEC" }, "r74": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "28", "Paragraph": "Column A", "Footnote": "2", "Publisher": "SEC" }, "r75": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "28", "Paragraph": "Column B", "Publisher": "SEC" }, "r76": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "28", "Paragraph": "Column C", "Publisher": "SEC" }, "r77": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "28", "Paragraph": "Column D", "Publisher": "SEC" }, "r78": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "28", "Paragraph": "Column E", "Publisher": "SEC" }, "r79": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "28", "Paragraph": "Column F", "Publisher": "SEC" }, "r80": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "28", "Paragraph": "Column G", "Publisher": "SEC" }, "r81": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "28", "Paragraph": "Column H", "Publisher": "SEC" }, "r82": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "28", "Paragraph": "Column I", "Publisher": "SEC" }, "r83": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "29", "Paragraph": "Column A", "Footnote": "3", "Publisher": "SEC" }, "r84": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "29", "Paragraph": "Column A", "Footnote": "4", "Publisher": "SEC" }, "r85": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "29", "Paragraph": "Column B", "Publisher": "SEC" }, "r86": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "12", "Subsection": "29", "Paragraph": "Column C", "Publisher": "SEC" }, "r87": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "13", "Subsection": "01", "Paragraph": "a", "Subparagraph": "(4)(i)", "Publisher": "SEC" }, "r88": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "13", "Subsection": "01", "Paragraph": "a", "Subparagraph": "(4)(iii)(A)", "Publisher": "SEC" }, "r89": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "13", "Subsection": "01", "Paragraph": "a", "Subparagraph": "(4)(iii)(B)", "Publisher": "SEC" }, "r90": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "13", "Subsection": "01", "Paragraph": "a", "Subparagraph": "(4)(iv)", "Publisher": "SEC" }, "r91": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "13", "Subsection": "02", "Paragraph": "a", "Subparagraph": "(4)(i)", "Publisher": "SEC" }, "r92": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "13", "Subsection": "02", "Paragraph": "a", "Subparagraph": "(4)(iii)(A)", "Publisher": "SEC" }, "r93": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "13", "Subsection": "02", "Paragraph": "a", "Subparagraph": "(4)(iii)(B)", "Publisher": "SEC" }, "r94": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "13", "Subsection": "02", "Paragraph": "a", "Subparagraph": "(4)(iii)(C)", "Publisher": "SEC" }, "r95": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "13", "Subsection": "02", "Paragraph": "a", "Subparagraph": "(4)(iv)", "Publisher": "SEC" }, "r96": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Staff Accounting Bulletin (SAB)", "Number": "Topic 11", "Section": "L", "Publisher": "SEC" }, "r97": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Staff Accounting Bulletin (SAB)", "Number": "Topic 5", "Section": "Y", "Paragraph": "Question 2", "Publisher": "SEC" }, "r98": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Name": "Staff Accounting Bulletin (SAB)", "Number": "Topic 5", "Section": "Y", "Paragraph": "Question 4", "Publisher": "SEC" }, "r99": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "105", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "9", "Subparagraph": "(d)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479343/105-10-65-9" }, "r100": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "105", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "9", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479343/105-10-65-9" }, "r101": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "205", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "10", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483475/205-20-45-10" }, "r102": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "205", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483499/205-20-50-1" }, "r103": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "205", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483499/205-20-50-5A" }, "r104": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "205", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483499/205-20-50-7" }, "r105": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "205", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480868/205-20-S45-2" }, "r106": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "205", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SAB Topic 5.Z.5.Q2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480781/205-20-S99-2" }, "r107": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483467/210-10-45-5" }, "r108": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483489/210-10-50-1" }, "r109": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "11", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-11" }, "r110": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "13", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-13" }, "r111": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-3" }, "r112": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-5" }, "r113": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-6" }, "r114": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "7", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-7" }, "r115": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "8", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-8" }, "r116": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "9", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-9" }, "r117": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r118": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(13))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r119": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(14))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r120": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(15))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r121": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(17))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r122": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(18))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r123": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(19)(a)(5))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r124": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(19)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r125": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(19))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r126": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(20))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r127": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(21))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r128": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(22)(a)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r129": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(22)(a)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r130": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(22)(a)(3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r131": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(22)(a)(4))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r132": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(22)(a)(5))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r133": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(22)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r134": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(22)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r135": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(23))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r136": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(24))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r137": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(25))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r138": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(26)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r139": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(27)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r140": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(27)(c)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r141": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(27)(c)(3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r142": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(27))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r143": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(28))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r144": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(29))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r145": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(30)(a)(3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r146": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(30)(a)(4))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r147": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(30)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r148": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(31))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r149": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(32))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r150": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(6)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r151": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(6))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r152": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(8))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r153": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(9))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r154": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1A", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482790/220-10-45-1A" }, "r155": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1A", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482790/220-10-45-1A" }, "r156": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1B", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482790/220-10-45-1B" }, "r157": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1B", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482790/220-10-45-1B" }, "r158": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482765/220-10-50-1" }, "r159": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482765/220-10-50-4" }, "r160": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482765/220-10-50-5" }, "r161": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482765/220-10-50-6" }, "r162": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.5-03(24))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483621/220-10-S99-2" }, "r163": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.5-03(25))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483621/220-10-S99-2" }, "r164": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r165": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-6" }, "r166": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "15", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-15" }, "r167": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "17", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-17" }, "r168": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "24", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-24" }, "r169": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "25", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-25" }, "r170": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-4" }, "r171": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482913/230-10-50-1" }, "r172": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482913/230-10-50-2" }, "r173": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482913/230-10-50-2A" }, "r174": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482913/230-10-50-8" }, "r175": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "9", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482913/230-10-50-9" }, "r176": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/235/tableOfContent" }, "r177": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483426/235-10-50-1" }, "r178": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480738/235-10-S50-1" }, "r179": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480738/235-10-S50-4" }, "r180": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(c))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r181": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(g)(1)(i))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r182": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(g)(1)(ii))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r183": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(h)(1)(Note 1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r184": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(h)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r185": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(h)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r186": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(k)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r187": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(n))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r188": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.12-04(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-3" }, "r189": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "23", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483421/250-10-45-23" }, "r190": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "24", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483421/250-10-45-24" }, "r191": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "5", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483421/250-10-45-5" }, "r192": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-1" }, "r193": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-1" }, "r194": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-1" }, "r195": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-1" }, "r196": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "11", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-11" }, "r197": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "11", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-11" }, "r198": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-3" }, "r199": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-4" }, "r200": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-6" }, "r201": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-7" }, "r202": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-7" }, "r203": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-8" }, "r204": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "9", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-9" }, "r205": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "5", "Subparagraph": "(SAB Topic 11.M.Q2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480530/250-10-S99-5" }, "r206": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/260/tableOfContent" }, "r207": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "10", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482689/260-10-45-10" }, "r208": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "16", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482689/260-10-45-16" }, "r209": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482689/260-10-45-2" }, "r210": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "22", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482689/260-10-45-22" }, "r211": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "23", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482689/260-10-45-23" }, "r212": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "28A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482689/260-10-45-28A" }, "r213": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482689/260-10-45-3" }, "r214": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "60B", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482689/260-10-45-60B" }, "r215": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "60B", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482689/260-10-45-60B" }, "r216": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "7", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482689/260-10-45-7" }, "r217": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482662/260-10-50-1" }, "r218": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482662/260-10-50-1" }, "r219": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482662/260-10-50-1" }, "r220": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482662/260-10-50-2" }, "r221": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482662/260-10-50-3" }, "r222": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "12", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482635/260-10-55-12" }, "r223": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "15", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482635/260-10-55-15" }, "r224": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "270", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482964/270-10-50-1" }, "r225": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "272", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483014/272-10-45-1" }, "r226": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "272", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482987/272-10-50-1" }, "r227": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "272", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482987/272-10-50-3" }, "r228": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "275", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482861/275-10-50-12" }, "r229": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "275", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "20", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482861/275-10-50-20" }, "r230": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "275", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482861/275-10-50-4" }, "r231": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "275", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482861/275-10-50-6" }, "r232": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "275", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "9", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482861/275-10-50-9" }, "r233": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/280/tableOfContent" }, "r234": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "15", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-15" }, "r235": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-21" }, "r236": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-21" }, "r237": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-22" }, "r238": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-22" }, "r239": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-22" }, "r240": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-22" }, "r241": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-22" }, "r242": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-22" }, "r243": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-22" }, "r244": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-22" }, "r245": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(h)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-22" }, "r246": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(j)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-22" }, "r247": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "24", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-24" }, "r248": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "25", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-25" }, "r249": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "25", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-25" }, "r250": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "26", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-26" }, "r251": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "26A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-26A" }, "r252": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "26B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-26B" }, "r253": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "26C", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-26C" }, "r254": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "30", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-30" }, "r255": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "30", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-30" }, "r256": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "30", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-30" }, "r257": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "30", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-30" }, "r258": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "31", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-31" }, "r259": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "32", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-32" }, "r260": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "32", "Subparagraph": "(ee)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-32" }, "r261": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "32", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-32" }, "r262": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "34", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-34" }, "r263": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "40", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-40" }, "r264": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "41", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-41" }, "r265": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "41", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-41" }, "r266": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "41", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-41" }, "r267": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "42", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-42" }, "r268": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "310", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "13", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481990/310-10-45-13" }, "r269": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "310", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481962/310-10-50-2" }, "r270": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "310", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481962/310-10-50-2" }, "r271": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "310", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481962/310-10-50-2" }, "r272": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "310", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481569/310-20-50-1" }, "r273": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/320/tableOfContent" }, "r274": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "10", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-10" }, "r275": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-2" }, "r276": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-2" }, "r277": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(aa)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-2" }, "r278": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(aaa)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-2" }, "r279": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-2" }, "r280": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-2" }, "r281": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-2" }, "r282": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-3" }, "r283": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-3" }, "r284": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-3" }, "r285": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-3" }, "r286": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-3" }, "r287": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r288": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r289": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(aaa)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r290": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r291": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r292": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r293": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(f)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r294": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(f)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r295": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(f)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r296": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(f)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r297": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5A", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5A" }, "r298": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5A", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5A" }, "r299": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5A", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5A" }, "r300": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5B" }, "r301": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5B", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5B" }, "r302": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5B", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5B" }, "r303": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5B", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5B" }, "r304": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5B", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5B" }, "r305": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "323", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481687/323-10-50-3" }, "r306": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "4", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479654/326-10-65-4" }, "r307": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "5", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479654/326-10-65-5" }, "r308": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "11", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-11" }, "r309": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-13" }, "r310": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-13" }, "r311": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "14", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-14" }, "r312": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "16", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-16" }, "r313": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "16", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-16" }, "r314": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "16", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-16" }, "r315": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "16", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-16" }, "r316": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "20", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-20" }, "r317": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3C", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-3C" }, "r318": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3D", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-3D" }, "r319": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-5" }, "r320": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-5" }, "r321": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479130/326-30-45-1" }, "r322": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479106/326-30-50-4" }, "r323": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479106/326-30-50-7" }, "r324": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "326", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "9", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479106/326-30-50-9" }, "r325": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "330", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/330/tableOfContent" }, "r326": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "330", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483080/330-10-50-1" }, "r327": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "330", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483080/330-10-50-4" }, "r328": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/350-20/tableOfContent" }, "r329": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482598/350-20-45-1" }, "r330": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1" }, "r331": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1" }, "r332": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1" }, "r333": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1" }, "r334": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1" }, "r335": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1" }, "r336": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1" }, "r337": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1" }, "r338": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(h)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1" }, "r339": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1A" }, "r340": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-2" }, "r341": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482665/350-30-50-3" }, "r342": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "4", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482705/350-40-65-4" }, "r343": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "4", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482705/350-40-65-4" }, "r344": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "350", "SubTopic": "60", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "1", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476166/350-60-65-1" }, "r345": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482099/360-10-50-1" }, "r346": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482099/360-10-50-1" }, "r347": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482099/360-10-50-1" }, "r348": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482099/360-10-50-2" }, "r349": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482099/360-10-50-2" }, "r350": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482099/360-10-50-3" }, "r351": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480204/360-10-S45-2" }, "r352": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "405", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477092/405-40-50-1" }, "r353": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "405", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477092/405-40-50-1" }, "r354": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "405", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477092/405-40-50-1" }, "r355": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "405", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477092/405-40-50-1" }, "r356": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "405", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477092/405-40-50-1" }, "r357": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "405", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(e)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477092/405-40-50-1" }, "r358": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "420", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482017/420-10-50-1" }, "r359": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "420", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SAB Topic 5.P.4.d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479823/420-10-S99-2" }, "r360": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "440", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482648/440-10-50-4" }, "r361": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "440", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482648/440-10-50-4" }, "r362": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "450", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483076/450-20-50-4" }, "r363": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "450", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "9", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483076/450-20-50-9" }, "r364": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "450", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 5.Y.Q2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480102/450-20-S99-1" }, "r365": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "450", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 5.Y.Q4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480102/450-20-S99-1" }, "r366": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481544/470-10-50-6" }, "r367": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481544/470-10-50-6" }, "r368": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1A", "Subparagraph": "(SX 210.13-01(a)(4)(i))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1A" }, "r369": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1A", "Subparagraph": "(SX 210.13-01(a)(4)(iii)(A))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1A" }, "r370": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1A", "Subparagraph": "(SX 210.13-01(a)(4)(iii)(B))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1A" }, "r371": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1A", "Subparagraph": "(SX 210.13-01(a)(4)(iv))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1A" }, "r372": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1A", "Subparagraph": "(SX 210.13-01(a)(5))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1A" }, "r373": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1B", "Subparagraph": "(SX 210.13-02(a)(4)(i))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1B" }, "r374": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1B", "Subparagraph": "(SX 210.13-02(a)(4)(iii)(A))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1B" }, "r375": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1B", "Subparagraph": "(SX 210.13-02(a)(4)(iii)(B))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1B" }, "r376": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1B", "Subparagraph": "(SX 210.13-02(a)(4)(iii)(C))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1B" }, "r377": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1B", "Subparagraph": "(SX 210.13-02(a)(4)(iv))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1B" }, "r378": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1B", "Subparagraph": "(SX 210.13-02(a)(5))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1B" }, "r379": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1B" }, "r380": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1B" }, "r381": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1B" }, "r382": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1B" }, "r383": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1B" }, "r384": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1B" }, "r385": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1B" }, "r386": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Subparagraph": "(h)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1B" }, "r387": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Subparagraph": "(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1B" }, "r388": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1C", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1C" }, "r389": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1C", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1C" }, "r390": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1C", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1C" }, "r391": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1D", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1D" }, "r392": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1D", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1D" }, "r393": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1D", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1D" }, "r394": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1E", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1E" }, "r395": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1E", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1E" }, "r396": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1E", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1E" }, "r397": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1E", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1E" }, "r398": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1F", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1F" }, "r399": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1F", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1F" }, "r400": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1F", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1F" }, "r401": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1F", "Subparagraph": "(b)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1F" }, "r402": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1I", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1I" }, "r403": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1I", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1I" }, "r404": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1I", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1I" }, "r405": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1I", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1I" }, "r406": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-4" }, "r407": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "4", "Subparagraph": "(f)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481538/470-20-65-4" }, "r408": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "4", "Subparagraph": "(f)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481538/470-20-65-4" }, "r409": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479887/480-10-S45-1" }, "r410": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479887/480-10-S45-2" }, "r411": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479887/480-10-S45-3" }, "r412": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479857/480-10-S50-1" }, "r413": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479857/480-10-S50-2" }, "r414": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479857/480-10-S50-3" }, "r415": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(01)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480244/480-10-S99-1" }, "r416": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(01)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480244/480-10-S99-1" }, "r417": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(01)(iii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480244/480-10-S99-1" }, "r418": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(04)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480244/480-10-S99-1" }, "r419": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3A", "Subparagraph": "(24)(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480244/480-10-S99-3A" }, "r420": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/505/tableOfContent" }, "r421": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481142/505-10-45-2" }, "r422": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "11", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-11" }, "r423": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-13" }, "r424": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-13" }, "r425": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-13" }, "r426": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-13" }, "r427": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-13" }, "r428": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-13" }, "r429": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-13" }, "r430": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-13" }, "r431": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(h)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-13" }, "r432": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-13" }, "r433": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "14", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-14" }, "r434": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "14", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-14" }, "r435": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "14", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-14" }, "r436": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "16", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-16" }, "r437": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "18", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-18" }, "r438": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-2" }, "r439": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-3" }, "r440": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-4" }, "r441": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-5" }, "r442": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-5" }, "r443": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S35", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480125/505-10-S35-1" }, "r444": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480100/505-10-S45-2" }, "r445": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480100/505-10-S45-3" }, "r446": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480100/505-10-S45-4" }, "r447": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "8", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480100/505-10-S45-8" }, "r448": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480070/505-10-S50-1" }, "r449": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480070/505-10-S50-6" }, "r450": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.3-04)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480008/505-10-S99-1" }, "r451": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "4", "Subparagraph": "(SAB Topic 4.C)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480008/505-10-S99-4" }, "r452": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "5", "Subparagraph": "(SAB Topic 4.F)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480008/505-10-S99-5" }, "r453": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "7", "Subparagraph": "(SAB Topic 5.Q.Q2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480008/505-10-S99-7" }, "r454": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "05", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481468/505-20-05-5" }, "r455": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S25", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479982/505-20-S25-1" }, "r456": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S25", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479982/505-20-S25-2" }, "r457": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S25", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479982/505-20-S25-3" }, "r458": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479951/505-20-S50-1" }, "r459": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479951/505-20-S50-2" }, "r460": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479951/505-20-S50-3" }, "r461": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 1.D.2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479921/505-20-S99-1" }, "r462": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481520/505-30-50-2" }, "r463": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "505", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481520/505-30-50-4" }, "r464": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479806/606-10-50-4" }, "r465": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479806/606-10-50-5" }, "r466": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479806/606-10-50-7" }, "r467": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(d)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479719/606-10-65-2" }, "r468": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(e)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479719/606-10-65-2" }, "r469": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(e)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479719/606-10-65-2" }, "r470": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "3", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479719/606-10-65-3" }, "r471": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "3", "Subparagraph": "(e)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479719/606-10-65-3" }, "r472": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-1" }, "r473": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)(iv)(01)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-1" }, "r474": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)(iv)(02)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-1" }, "r475": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)(iv)(02)(A)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-1" }, "r476": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)(iv)(02)(B)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-1" }, "r477": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)(iv)(02)(C)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-1" }, "r478": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)(iv)(03)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-1" }, "r479": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(c)(iv)(01)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-5" }, "r480": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(c)(iv)(02)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-5" }, "r481": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(c)(iv)(03)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-5" }, "r482": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "70", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480794/715-70-50-1" }, "r483": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "715", "SubTopic": "80", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480576/715-80-50-5" }, "r484": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/718/tableOfContent" }, "r485": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "35", "Paragraph": "1D", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480483/718-10-35-1D" }, "r486": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "35", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480483/718-10-35-2" }, "r487": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "35", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480483/718-10-35-3" }, "r488": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480454/718-10-45-1" }, "r489": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r490": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r491": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r492": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r493": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r494": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r495": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r496": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r497": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iv)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r498": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iv)(01)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r499": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iv)(02)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r500": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iv)(03)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r501": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iv)(04)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r502": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r503": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r504": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(iii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r505": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(iii)(01)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r506": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(iii)(02)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r507": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(iii)(03)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r508": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r509": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r510": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(e)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r511": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(e)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r512": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r513": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r514": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(2)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r515": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(2)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r516": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(2)(iii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r517": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(2)(iv)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r518": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(2)(v)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r519": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(h)(1)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r520": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(h)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r521": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(h)(2)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r522": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r523": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(l)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r524": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "17", "Subparagraph": "(d)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480336/718-10-65-17" }, "r525": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479953/718-10-S50-2" }, "r526": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479953/718-10-S50-3" }, "r527": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479953/718-10-S50-4" }, "r528": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479953/718-10-S50-5" }, "r529": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 14.C.Q3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479830/718-10-S99-1" }, "r530": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 14.D.1.Q5)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479830/718-10-S99-1" }, "r531": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 14.D.2.Q6)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479830/718-10-S99-1" }, "r532": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 14.D.3.Q2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479830/718-10-S99-1" }, "r533": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "720", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483359/720-20-50-1" }, "r534": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/740/tableOfContent" }, "r535": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "25", "Paragraph": "3", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482620/740-10-25-3" }, "r536": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "10B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482525/740-10-45-10B" }, "r537": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "25", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482525/740-10-45-25" }, "r538": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "28", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482525/740-10-45-28" }, "r539": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482525/740-10-45-4" }, "r540": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482525/740-10-45-6" }, "r541": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "10", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-10" }, "r542": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "10A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-10A" }, "r543": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "10B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-10B" }, "r544": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12" }, "r545": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12A" }, "r546": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12A", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12A" }, "r547": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12A", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12A" }, "r548": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12A", "Subparagraph": "(a)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12A" }, "r549": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12A", "Subparagraph": "(a)(6)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12A" }, "r550": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12A", "Subparagraph": "(a)(7)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12A" }, "r551": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12A", "Subparagraph": "(a)(8)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12A" }, "r552": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12A", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12A" }, "r553": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12A", "Subparagraph": "(b)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12A" }, "r554": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12B" }, "r555": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12C", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12C" }, "r556": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "14", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-14" }, "r557": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "15", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-15" }, "r558": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "15A", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-15A" }, "r559": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "15A", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-15A" }, "r560": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "15A", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-15A" }, "r561": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "15A", "Subparagraph": "(a)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-15A" }, "r562": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "15A", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-15A" }, "r563": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "17", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-17" }, "r564": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "19", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-19" }, "r565": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-2" }, "r566": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-2" }, "r567": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "20", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-20" }, "r568": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-21" }, "r569": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-22" }, "r570": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "23", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-23" }, "r571": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-3" }, "r572": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "9", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-9" }, "r573": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "8", "Subparagraph": "(d)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482615/740-10-65-8" }, "r574": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "8", "Subparagraph": "(d)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482615/740-10-65-8" }, "r575": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 6.I.1.Q1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479360/740-10-S99-1" }, "r576": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 6.I.5.Q1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479360/740-10-S99-1" }, "r577": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 6.I.7)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479360/740-10-S99-1" }, "r578": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SAB Topic 11.C)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479360/740-10-S99-2" }, "r579": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "270", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477891/740-270-50-1" }, "r580": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482603/740-30-50-2" }, "r581": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "323", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(d)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478666/740-323-65-2" }, "r582": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "323", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(d)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478666/740-323-65-2" }, "r583": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "323", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478666/740-323-65-2" }, "r584": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "323", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(g)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478666/740-323-65-2" }, "r585": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "740", "SubTopic": "323", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(g)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478666/740-323-65-2" }, "r586": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "805", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479581/805-30-50-1" }, "r587": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "805", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479581/805-30-50-2" }, "r588": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "805", "SubTopic": "60", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "1", "Subparagraph": "(d)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476176/805-60-65-1" }, "r589": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "805", "SubTopic": "60", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "1", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476176/805-60-65-1" }, "r590": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "810", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "25", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481231/810-10-45-25" }, "r591": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "810", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "25", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481231/810-10-45-25" }, "r592": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "810", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(bb)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481203/810-10-50-3" }, "r593": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "810", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481203/810-10-50-3" }, "r594": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/815/tableOfContent" }, "r595": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4A", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4A" }, "r596": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4A", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4A" }, "r597": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4A", "Subparagraph": "(b)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4A" }, "r598": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4B", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4B" }, "r599": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4B", "Subparagraph": "(c)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4B" }, "r600": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4B", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4B" }, "r601": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4B", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4B" }, "r602": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r603": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r604": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(bb)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r605": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r606": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r607": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r608": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r609": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4CC", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4CC" }, "r610": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4CCC", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4CCC" }, "r611": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4CCC", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4CCC" }, "r612": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4CCC", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4CCC" }, "r613": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4D", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4D" }, "r614": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4D", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4D" }, "r615": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4D", "Subparagraph": "(a)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4D" }, "r616": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4D", "Subparagraph": "(a)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4D" }, "r617": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4D", "Subparagraph": "(a)(5)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4D" }, "r618": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4D", "Subparagraph": "(a)(6)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4D" }, "r619": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4EE", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4EE" }, "r620": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4EE", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4EE" }, "r621": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4EE", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4EE" }, "r622": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4EE", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4EE" }, "r623": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4EEE", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4EEE" }, "r624": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4EEE", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4EEE" }, "r625": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4EEE", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4EEE" }, "r626": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4F", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4F" }, "r627": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-7" }, "r628": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-8" }, "r629": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-8" }, "r630": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-8" }, "r631": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-8A" }, "r632": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8C", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-8C" }, "r633": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "8", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480339/815-10-65-8" }, "r634": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "8", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480339/815-10-65-8" }, "r635": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "8", "Subparagraph": "(f)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480339/815-10-65-8" }, "r636": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479693/815-10-S50-1" }, "r637": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "6", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480528/815-20-65-6" }, "r638": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "6", "Subparagraph": "(h)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480528/815-20-65-6" }, "r639": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "6", "Subparagraph": "(h)(1)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480528/815-20-65-6" }, "r640": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "6", "Subparagraph": "(h)(1)(iii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480528/815-20-65-6" }, "r641": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "6", "Subparagraph": "(h)(1)(iv)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480528/815-20-65-6" }, "r642": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "6", "Subparagraph": "(i)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480528/815-20-65-6" }, "r643": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480870/815-30-50-2" }, "r644": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480870/815-30-50-2" }, "r645": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480870/815-30-50-2" }, "r646": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480870/815-30-50-2" }, "r647": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480237/815-40-50-4" }, "r648": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480237/815-40-50-5" }, "r649": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480237/815-40-50-6" }, "r650": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "1", "Subparagraph": "(e)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480175/815-40-65-1" }, "r651": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "1", "Subparagraph": "(e)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480175/815-40-65-1" }, "r652": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "1", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480175/815-40-65-1" }, "r653": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "815", "SubTopic": "45", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480865/815-45-50-1" }, "r654": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "35", "Paragraph": "54B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482134/820-10-35-54B" }, "r655": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r656": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r657": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(bbb)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r658": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(bbb)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r659": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(bbb)(2)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r660": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r661": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r662": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(h)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r663": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2E", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2E" }, "r664": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-3" }, "r665": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6A", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-6A" }, "r666": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6A", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-6A" }, "r667": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6A", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-6A" }, "r668": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6A", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-6A" }, "r669": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6A", "Subparagraph": "(h)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-6A" }, "r670": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6B", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-6B" }, "r671": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6B", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-6B" }, "r672": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6B", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-6B" }, "r673": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482736/825-10-45-1A" }, "r674": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "10", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-10" }, "r675": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "11", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-11" }, "r676": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "11", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-11" }, "r677": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "28", "Subparagraph": "(c)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-28" }, "r678": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "28", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-28" }, "r679": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "28", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-28" }, "r680": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "32", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-32" }, "r681": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "830", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/830/tableOfContent" }, "r682": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "830", "SubTopic": "230", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477401/830-230-45-1" }, "r683": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "830", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "17", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481694/830-30-45-17" }, "r684": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "830", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "20", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481694/830-30-45-20" }, "r685": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "830", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "20", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481694/830-30-45-20" }, "r686": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "830", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "20", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481694/830-30-45-20" }, "r687": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "830", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "20", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481694/830-30-45-20" }, "r688": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "830", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481674/830-30-50-1" }, "r689": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "835", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483013/835-20-50-1" }, "r690": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "835", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482925/835-30-45-2" }, "r691": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/842-20/tableOfContent" }, "r692": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "35", "Paragraph": "12A", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479165/842-20-35-12A" }, "r693": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479041/842-20-45-1" }, "r694": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479041/842-20-45-1" }, "r695": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479041/842-20-45-2" }, "r696": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "4", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479041/842-20-45-4" }, "r697": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "5", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479041/842-20-45-5" }, "r698": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "5", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479041/842-20-45-5" }, "r699": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "5", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479041/842-20-45-5" }, "r700": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-1" }, "r701": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-4" }, "r702": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-4" }, "r703": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-4" }, "r704": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-4" }, "r705": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(g)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-4" }, "r706": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(g)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-4" }, "r707": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(g)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-4" }, "r708": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(g)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-4" }, "r709": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-6" }, "r710": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7A", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-7A" }, "r711": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "842", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479773/842-30-50-12" }, "r712": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "848", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(a)(3)(iii)(03)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483550/848-10-65-2" }, "r713": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "855", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 1.B.3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480148/855-10-S99-1" }, "r714": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(b)(2)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-3" }, "r715": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(b)(2)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-3" }, "r716": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(b)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-3" }, "r717": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(bb)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-3" }, "r718": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(bb)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-3" }, "r719": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(bb)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-3" }, "r720": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-3" }, "r721": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-3" }, "r722": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-3" }, "r723": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-3" }, "r724": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(cc)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-3" }, "r725": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-4" }, "r726": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-4" }, "r727": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(b)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-4" }, "r728": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(b)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-4" }, "r729": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-4" }, "r730": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(e)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-4" }, "r731": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(e)(5)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-4" }, "r732": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4D", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481326/860-20-50-4D" }, "r733": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1A", "Subparagraph": "(c)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481420/860-30-50-1A" }, "r734": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1A", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481420/860-30-50-1A" }, "r735": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481420/860-30-50-7" }, "r736": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-3" }, "r737": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-3" }, "r738": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-3" }, "r739": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)(4)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-3" }, "r740": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-4" }, "r741": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-4" }, "r742": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(a)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-4" }, "r743": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(a)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-4" }, "r744": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(a)(5)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-4" }, "r745": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(a)(6)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-4" }, "r746": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(a)(7)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-4" }, "r747": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-4" }, "r748": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(e)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-4" }, "r749": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(e)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-4" }, "r750": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(e)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-4" }, "r751": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "860", "SubTopic": "50", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481229/860-50-50-5" }, "r752": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "910", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482546/910-10-50-6" }, "r753": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "912", "SubTopic": "330", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478411/912-330-50-1" }, "r754": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "924", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 11.L)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479941/924-10-S99-1" }, "r755": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478934/932-220-50-1" }, "r756": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "18", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-18" }, "r757": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "18", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-18" }, "r758": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "18", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-18" }, "r759": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "19", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-19" }, "r760": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "20", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-20" }, "r761": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "20", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-20" }, "r762": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "23", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-23" }, "r763": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "23", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-23" }, "r764": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "23", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-23" }, "r765": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "23", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-23" }, "r766": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "23", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-23" }, "r767": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "23", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-23" }, "r768": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "28", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-28" }, "r769": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "28", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-28" }, "r770": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "31", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-31" }, "r771": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "31", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-31" }, "r772": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "31", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-31" }, "r773": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "31", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-31" }, "r774": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "31", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-31" }, "r775": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "31", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-31" }, "r776": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-5" }, "r777": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-5" }, "r778": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-5" }, "r779": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-5" }, "r780": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-5" }, "r781": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-5" }, "r782": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-6" }, "r783": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-7" }, "r784": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-8" }, "r785": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Subparagraph": "(c)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-8" }, "r786": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-8" }, "r787": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "280", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478657/932-280-50-1" }, "r788": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "932", "SubTopic": "323", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478988/932-323-50-1" }, "r789": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "940", "SubTopic": "820", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478119/940-820-50-1" }, "r790": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477657/942-210-S45-1" }, "r791": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478478/942-210-S50-1" }, "r792": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(10)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r793": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(11))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r794": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(13)(3)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r795": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(15)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r796": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(16))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r797": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(17))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r798": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(18))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r799": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(19))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r800": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(20))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r801": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(21))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r802": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(23))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r803": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(6))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r804": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(8))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r805": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-04(26))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478524/942-220-S99-1" }, "r806": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-04(27))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478524/942-220-S99-1" }, "r807": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478671/942-235-S50-1" }, "r808": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-05(b)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477314/942-235-S99-1" }, "r809": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-05(b)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477314/942-235-S99-1" }, "r810": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-05(b)(3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477314/942-235-S99-1" }, "r811": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.9-06)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477314/942-235-S99-2" }, "r812": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-2" }, "r813": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-2" }, "r814": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-2" }, "r815": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-2" }, "r816": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-2" }, "r817": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(ff)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-2" }, "r818": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(fff)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-2" }, "r819": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-2" }, "r820": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3" }, "r821": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3" }, "r822": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3" }, "r823": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3" }, "r824": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3" }, "r825": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3A" }, "r826": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3A", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3A" }, "r827": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3A", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3A" }, "r828": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3A", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3A" }, "r829": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3A", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3A" }, "r830": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478443/942-360-45-1" }, "r831": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478451/942-360-50-1" }, "r832": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "405", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477787/942-405-45-2" }, "r833": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "740", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477617/942-740-50-1" }, "r834": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "942", "SubTopic": "825", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478898/942-825-50-1" }, "r835": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r836": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(12))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r837": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(15)(b)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r838": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(19))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r839": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(21))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r840": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(22))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r841": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(23)(a)(3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r842": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(23)(a)(4))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r843": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(25))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r844": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(8)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r845": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(8)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r846": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-03(a)(8))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478777/944-210-S99-1" }, "r847": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-04(11))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477250/944-220-S99-1" }, "r848": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-04(18))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477250/944-220-S99-1" }, "r849": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-04(19))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477250/944-220-S99-1" }, "r850": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-04(2)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477250/944-220-S99-1" }, "r851": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-04(20))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477250/944-220-S99-1" }, "r852": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-04(22))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477250/944-220-S99-1" }, "r853": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-04(23))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477250/944-220-S99-1" }, "r854": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-04(3)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477250/944-220-S99-1" }, "r855": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-04(4))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477250/944-220-S99-1" }, "r856": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.7-04(9))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477250/944-220-S99-1" }, "r857": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-16(Column A))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-1" }, "r858": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-16(Column B))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-1" }, "r859": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-16(Column C))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-1" }, "r860": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-16(Column D))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-1" }, "r861": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-16(Column E))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-1" }, "r862": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-16(Column F))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-1" }, "r863": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-16(Column G))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-1" }, "r864": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-16(Column H))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-1" }, "r865": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-16(Column I))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-1" }, "r866": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-16(Column J))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-1" }, "r867": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-16(Column K))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-1" }, "r868": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.12-17(Column A))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-2" }, "r869": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.12-17(Column B))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-2" }, "r870": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.12-17(Column C))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-2" }, "r871": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.12-17(Column D))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-2" }, "r872": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.12-17(Column E))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-2" }, "r873": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.12-17(Column F))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477965/944-235-S99-2" }, "r874": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4E", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-4E" }, "r875": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-5" }, "r876": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7A", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-7A" }, "r877": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480016/944-40-65-2" }, "r878": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(f)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480016/944-40-65-2" }, "r879": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(f)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480016/944-40-65-2" }, "r880": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(g)(2)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480016/944-40-65-2" }, "r881": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(g)(2)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480016/944-40-65-2" }, "r882": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "2", "Subparagraph": "(h)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480016/944-40-65-2" }, "r883": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 5.W.Q2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479583/944-40-S99-1" }, "r884": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "740", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478822/944-740-50-1" }, "r885": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "944", "SubTopic": "740", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478822/944-740-50-1" }, "r886": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-03(d))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479886/946-10-S99-3" }, "r887": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-03(f)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479886/946-10-S99-3" }, "r888": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-03(f)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479886/946-10-S99-3" }, "r889": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-03(f)(3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479886/946-10-S99-3" }, "r890": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-03(h)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479886/946-10-S99-3" }, "r891": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-03(i)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479886/946-10-S99-3" }, "r892": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-03(i)(2)(i))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479886/946-10-S99-3" }, "r893": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-03(i)(2)(ii))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479886/946-10-S99-3" }, "r894": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-03(i)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479886/946-10-S99-3" }, "r895": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "11", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480990/946-20-50-11" }, "r896": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480990/946-20-50-13" }, "r897": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "4", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478009/946-205-45-4" }, "r898": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478009/946-205-45-6" }, "r899": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478494/946-205-50-2" }, "r900": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "27", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478494/946-205-50-27" }, "r901": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478494/946-205-50-7" }, "r902": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478494/946-205-50-7" }, "r903": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478494/946-205-50-7" }, "r904": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478494/946-205-50-7" }, "r905": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478494/946-205-50-7" }, "r906": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478494/946-205-50-7" }, "r907": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478494/946-205-50-7" }, "r908": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(h)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478494/946-205-50-7" }, "r909": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477796/946-210-45-4" }, "r910": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-1" }, "r911": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-1" }, "r912": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-1" }, "r913": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-1" }, "r914": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-2" }, "r915": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-6" }, "r916": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-6" }, "r917": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(a)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-6" }, "r918": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-6" }, "r919": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-6" }, "r920": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-6" }, "r921": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r922": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(12)(b)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r923": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(12)(b)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r924": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(12)(b)(3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r925": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(13)(a)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r926": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(13)(a)(3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r927": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(14))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r928": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(15))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r929": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(16)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r930": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(17))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r931": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(19))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r932": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(2)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r933": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(2)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r934": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(3)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r935": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(3)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r936": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(3)(c))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r937": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(6)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r938": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(6)(c))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r939": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(6)(d))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r940": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(6)(e))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r941": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(8))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r942": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(9)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r943": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(9)(c))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r944": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(9)(d))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r945": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-04(9)(e))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-1" }, "r946": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.6-05(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-2" }, "r947": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.6-05(4))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479170/946-210-S99-2" }, "r948": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "7", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479105/946-220-45-7" }, "r949": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478297/946-220-50-3" }, "r950": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(1)(c))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r951": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r952": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(2)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r953": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(a)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r954": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(a)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r955": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(a)(3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r956": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(a)(5))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r957": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(a)(6))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r958": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(a)(7))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r959": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(c)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r960": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(c)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r961": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(c)(3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r962": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(c)(5))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r963": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(c)(6))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r964": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(7)(c)(7))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r965": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.6-07(9))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-1" }, "r966": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-09(1)(d))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-3" }, "r967": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-09(4)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-3" }, "r968": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-09(6))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-3" }, "r969": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-09(7))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-3" }, "r970": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477968/946-235-50-2" }, "r971": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477968/946-235-50-2" }, "r972": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477968/946-235-50-2" }, "r973": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-12(Column A)(Footnote 1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-1" }, "r974": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-12(Column A)(Footnote 2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-1" }, "r975": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-12(Column C)(Footnote 5))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-1" }, "r976": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "12", "Subparagraph": "(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-12" }, "r977": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "19", "Subparagraph": "(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-19" }, "r978": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.12-12A(Column A)(Footnote 2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-2" }, "r979": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.12-12A(Column C)(Footnote 4))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-2" }, "r980": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.12-12B(Column A)(Footnote 4)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-3" }, "r981": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.12-12B(Column A)(Footnote 4)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-3" }, "r982": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.12-12B(Column A)(Footnote 7))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-3" }, "r983": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.12-12B(Column C)(Footnote 2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-3" }, "r984": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "5", "Subparagraph": "(SX 210.12-13(Column A)(Footnote 3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-5" }, "r985": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "5", "Subparagraph": "(SX 210.12-13(Column G)(Footnote 8))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-5" }, "r986": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "5B", "Subparagraph": "(SX 210.12-13B(Column A))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-5B" }, "r987": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "5B", "Subparagraph": "(SX 210.12-13B(Column B))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-5B" }, "r988": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "5B", "Subparagraph": "(SX 210.12-13B(Column E)(Footnote 4))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-5B" }, "r989": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "5C", "Subparagraph": "(SX 210.12-13C(Column H)(Footnote 7))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-5C" }, "r990": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "5D", "Subparagraph": "(SX 210.12-13D(Column A)(Footnote 2)(i))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-5D" }, "r991": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "6", "Subparagraph": "(SX 210.12-14(Column A)(Footnote 2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-6" }, "r992": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "6", "Subparagraph": "(SX 210.12-14(Column E)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-6" }, "r993": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "6", "Subparagraph": "(SX 210.12-14(Column E)(Footnote 4))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-6" }, "r994": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "6", "Subparagraph": "(SX 210.12-14(Column E)(Footnote 6)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-6" }, "r995": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "6", "Subparagraph": "(SX 210.12-14(Column F)(Footnote 7))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-6" }, "r996": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "7", "Subparagraph": "(SX 210.12-15(Column A))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-7" }, "r997": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "7", "Subparagraph": "(SX 210.12-15(Column B))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-7" }, "r998": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "7", "Subparagraph": "(SX 210.12-15(Column C))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-7" }, "r999": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "7", "Subparagraph": "(SX 210.12-15(Column D))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-7" }, "r1000": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "505", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478448/946-505-50-1" }, "r1001": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "505", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478448/946-505-50-2" }, "r1002": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "505", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478448/946-505-50-2" }, "r1003": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "505", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478448/946-505-50-2" }, "r1004": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "505", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478448/946-505-50-2" }, "r1005": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "946", "SubTopic": "505", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478448/946-505-50-6" }, "r1006": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "948", "SubTopic": "310", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478322/948-310-S50-2" }, "r1007": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "948", "SubTopic": "310", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-29(Column A)(Footnote 3))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479628/948-310-S99-1" }, "r1008": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "948", "SubTopic": "310", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-29(Column A)(Footnote 4))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479628/948-310-S99-1" }, "r1009": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "948", "SubTopic": "310", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-29(Column B))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479628/948-310-S99-1" }, "r1010": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "948", "SubTopic": "310", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-29(Column C))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479628/948-310-S99-1" }, "r1011": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "954", "SubTopic": "440", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478522/954-440-50-1" }, "r1012": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "970", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-28(Column A)(Footnote 2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478979/970-360-S99-1" }, "r1013": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "970", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-28(Column B))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478979/970-360-S99-1" }, "r1014": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "970", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-28(Column C))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478979/970-360-S99-1" }, "r1015": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "970", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-28(Column D))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478979/970-360-S99-1" }, "r1016": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "970", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-28(Column E))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478979/970-360-S99-1" }, "r1017": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "970", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-28(Column F))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478979/970-360-S99-1" }, "r1018": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "970", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-28(Column G))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478979/970-360-S99-1" }, "r1019": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "970", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-28(Column H))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478979/970-360-S99-1" }, "r1020": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "970", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-28(Column I))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478979/970-360-S99-1" }, "r1021": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "976", "SubTopic": "310", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477332/976-310-50-1" }, "r1022": { "role": "http://www.xbrl.org/2003/role/disclosureRef", "Topic": "978", "SubTopic": "310", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479230/978-310-50-1" }, "r1023": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "13H", "Subparagraph": "(a)", "SubTopic": "40", "Topic": "944", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480046/944-40-55-13H" }, "r1024": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "13H", "Subparagraph": "(b)", "SubTopic": "40", "Topic": "944", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480046/944-40-55-13H" }, "r1025": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "205", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "3A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483475/205-20-45-3A" }, "r1026": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483467/210-10-45-1" }, "r1027": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483467/210-10-45-1" }, "r1028": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483467/210-10-45-1" }, "r1029": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "8", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483467/210-10-45-8" }, "r1030": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "9", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483467/210-10-45-9" }, "r1031": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(20))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1032": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "15", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483444/210-20-55-15" }, "r1033": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "16", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483444/210-20-55-16" }, "r1034": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "22", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483444/210-20-55-22" }, "r1035": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-12" }, "r1036": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "11", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476153/220-40-55-11" }, "r1037": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "14", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476153/220-40-55-14" }, "r1038": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "18", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476153/220-40-55-18" }, "r1039": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "21", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476153/220-40-55-21" }, "r1040": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476153/220-40-55-4" }, "r1041": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483426/235-10-50-4" }, "r1042": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480738/235-10-S50-1" }, "r1043": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(m)(1)(ii)(A))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r1044": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "52", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482635/260-10-55-52" }, "r1045": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "275", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "18", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482836/275-10-55-18" }, "r1046": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "275", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482836/275-10-55-6" }, "r1047": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "30", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-30" }, "r1048": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "31", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-31" }, "r1049": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "47", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482785/280-10-55-47" }, "r1050": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "47", "Subparagraph": "(bb)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482785/280-10-55-47" }, "r1051": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "47", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482785/280-10-55-47" }, "r1052": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "47", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482785/280-10-55-47" }, "r1053": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "48", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482785/280-10-55-48" }, "r1054": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "49", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482785/280-10-55-49" }, "r1055": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "54", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482785/280-10-55-54" }, "r1056": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "54", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482785/280-10-55-54" }, "r1057": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "54", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482785/280-10-55-54" }, "r1058": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "310", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "12A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481933/310-10-55-12A" }, "r1059": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "326", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "8", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479081/326-30-55-8" }, "r1060": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "24", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482548/350-20-55-24" }, "r1061": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "05", "Paragraph": "3", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482338/360-10-05-3" }, "r1062": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "05", "Paragraph": "3", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482338/360-10-05-3" }, "r1063": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "05", "Paragraph": "3", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482338/360-10-05-3" }, "r1064": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "05", "Paragraph": "3", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482338/360-10-05-3" }, "r1065": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1B" }, "r1066": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "69B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481568/470-20-55-69B" }, "r1067": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "69C", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481568/470-20-55-69C" }, "r1068": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "69E", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481568/470-20-55-69E" }, "r1069": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "69F", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481568/470-20-55-69F" }, "r1070": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "480", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "64", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481620/480-10-55-64" }, "r1071": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479806/606-10-50-5" }, "r1072": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "91", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479777/606-10-55-91" }, "r1073": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "91", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479777/606-10-55-91" }, "r1074": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "91", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479777/606-10-55-91" }, "r1075": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "91", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479777/606-10-55-91" }, "r1076": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "91", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479777/606-10-55-91" }, "r1077": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "91", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479777/606-10-55-91" }, "r1078": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "91", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479777/606-10-55-91" }, "r1079": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-1" }, "r1080": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)(iv)(01)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-1" }, "r1081": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(c)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-5" }, "r1082": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(c)(iv)(01)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480506/715-20-50-5" }, "r1083": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "715", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "17", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480482/715-20-55-17" }, "r1084": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "715", "SubTopic": "80", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "8", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480547/715-80-55-8" }, "r1085": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1086": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "217", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482663/740-10-55-217" }, "r1087": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "231", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482663/740-10-55-231" }, "r1088": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "805", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479328/805-10-50-8" }, "r1089": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "805", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "39", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479303/805-10-55-39" }, "r1090": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "805", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "41", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479303/805-10-55-41" }, "r1091": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "805", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "43", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479303/805-10-55-43" }, "r1092": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "805", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "47", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479303/805-10-55-47" }, "r1093": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "805", "SubTopic": "740", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "13", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478064/805-740-55-13" }, "r1094": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4A", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4A" }, "r1095": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4A", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4A" }, "r1096": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4B", "Subparagraph": "(c)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4B" }, "r1097": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4B", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4B" }, "r1098": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4B", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4B" }, "r1099": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r1100": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r1101": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4CC", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4CC" }, "r1102": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "181", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480401/815-10-55-181" }, "r1103": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "182", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480401/815-10-55-182" }, "r1104": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "100", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482078/820-10-55-100" }, "r1105": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "100", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482078/820-10-55-100" }, "r1106": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "101", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482078/820-10-55-101" }, "r1107": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "103", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482078/820-10-55-103" }, "r1108": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "107", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482078/820-10-55-107" }, "r1109": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "107", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482078/820-10-55-107" }, "r1110": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "107", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482078/820-10-55-107" }, "r1111": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "107", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482078/820-10-55-107" }, "r1112": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "107", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482078/820-10-55-107" }, "r1113": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "107", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482078/820-10-55-107" }, "r1114": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "10", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482881/825-10-55-10" }, "r1115": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "12", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482881/825-10-55-12" }, "r1116": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "835", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "8", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482949/835-30-55-8" }, "r1117": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "53", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479589/842-20-55-53" }, "r1118": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "852", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "10", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481372/852-10-55-10" }, "r1119": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "860", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480088/860-10-S50-1" }, "r1120": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "860", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "108", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481296/860-20-55-108" }, "r1121": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "860", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481395/860-30-55-4" }, "r1122": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "17", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-17" }, "r1123": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-21" }, "r1124": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "29", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-29" }, "r1125": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477215/932-235-50-3" }, "r1126": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477916/932-235-55-2" }, "r1127": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477916/932-235-55-4" }, "r1128": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477916/932-235-55-5" }, "r1129": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "932", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477916/932-235-55-6" }, "r1130": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "944", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479401/944-30-55-2" }, "r1131": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "29F", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480046/944-40-55-29F" }, "r1132": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "9C", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480046/944-40-55-9C" }, "r1133": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "9C", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480046/944-40-55-9C" }, "r1134": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "9C", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480046/944-40-55-9C" }, "r1135": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "9E", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480046/944-40-55-9E" }, "r1136": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "11", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477548/944-605-55-11" }, "r1137": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "14", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477548/944-605-55-14" }, "r1138": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "944", "SubTopic": "80", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "18", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480078/944-80-55-18" }, "r1139": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-1" }, "r1140": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478795/946-210-50-6" }, "r1141": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "946", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477439/946-210-55-1" }, "r1142": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "946", "SubTopic": "310", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477802/946-310-45-1" }, "r1143": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.12-12(Column A)(Footnote 2)(i))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-1" }, "r1144": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.12-12A(Column A)(Footnote 2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-2" }, "r1145": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.12-12B(Column A)(Footnote 1)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-3" }, "r1146": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "946", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "6", "Subparagraph": "(SX 210.12-14(Column A)(Footnote 2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477271/946-320-S99-6" }, "r1147": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "946", "SubTopic": "830", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "10", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479168/946-830-55-10" }, "r1148": { "role": "http://www.xbrl.org/2003/role/exampleRef", "Topic": "946", "SubTopic": "830", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "12", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479168/946-830-55-12" }, "r1149": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Exchange Act", "Number": "240", "Section": "12", "Subsection": "b" }, "r1150": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Exchange Act", "Number": "240", "Section": "12", "Subsection": "b-2" }, "r1151": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Exchange Act", "Number": "240", "Section": "12", "Subsection": "b-23" }, "r1152": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Exchange Act", "Number": "240", "Section": "12", "Subsection": "d1-1" }, "r1153": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 10-K", "Number": "249", "Section": "310" }, "r1154": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Number": "249", "Section": "220", "Subsection": "f" }, "r1155": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16", "Subsection": "J", "Paragraph": "a" }, "r1156": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16K" }, "r1157": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16K", "Subsection": "b", "Paragraph": "1" }, "r1158": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16K", "Subsection": "b", "Paragraph": "1", "Subparagraph": "i" }, "r1159": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16K", "Subsection": "b", "Paragraph": "1", "Subparagraph": "ii" }, "r1160": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16K", "Subsection": "b", "Paragraph": "1", "Subparagraph": "iii" }, "r1161": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16K", "Subsection": "b", "Paragraph": "2" }, "r1162": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16K", "Subsection": "c", "Paragraph": "1" }, "r1163": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16K", "Subsection": "c", "Paragraph": "2" }, "r1164": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16K", "Subsection": "c", "Paragraph": "2", "Subparagraph": "i" }, "r1165": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16K", "Subsection": "c", "Paragraph": "2", "Subparagraph": "ii" }, "r1166": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "16K", "Subsection": "c", "Paragraph": "2", "Subparagraph": "iii" }, "r1167": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "6", "Subsection": "F", "Paragraph": "1" }, "r1168": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "6", "Subsection": "F", "Paragraph": "1", "Subparagraph": "i" }, "r1169": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "6", "Subsection": "F", "Paragraph": "1", "Subparagraph": "i", "Sentence": "A" }, "r1170": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "6", "Subsection": "F", "Paragraph": "1", "Subparagraph": "i", "Sentence": "B" }, "r1171": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "6", "Subsection": "F", "Paragraph": "1", "Subparagraph": "i", "Sentence": "C" }, "r1172": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "6", "Subsection": "F", "Paragraph": "1", "Subparagraph": "i", "Sentence": "D" }, "r1173": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "6", "Subsection": "F", "Paragraph": "1", "Subparagraph": "i", "Sentence": "E" }, "r1174": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "6", "Subsection": "F", "Paragraph": "1", "Subparagraph": "ii" }, "r1175": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "6", "Subsection": "F", "Paragraph": "1", "Subparagraph": "iii" }, "r1176": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 20-F", "Section": "6", "Subsection": "F", "Paragraph": "2" }, "r1177": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 40-F", "Number": "249", "Section": "240", "Subsection": "f" }, "r1178": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 40-F", "Section": "19", "Paragraph": "a" }, "r1179": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 40-F", "Section": "19", "Paragraph": "a", "Subparagraph": "1" }, "r1180": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 40-F", "Section": "19", "Paragraph": "a", "Subparagraph": "1", "Sentence": "i" }, "r1181": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 40-F", "Section": "19", "Paragraph": "a", "Subparagraph": "1", "Sentence": "ii" }, "r1182": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 40-F", "Section": "19", "Paragraph": "a", "Subparagraph": "1", "Sentence": "iii" }, "r1183": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 40-F", "Section": "19", "Paragraph": "a", "Subparagraph": "1", "Sentence": "iv" }, "r1184": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 40-F", "Section": "19", "Paragraph": "a", "Subparagraph": "1", "Sentence": "v" }, "r1185": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 40-F", "Section": "19", "Paragraph": "a", "Subparagraph": "2" }, "r1186": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 40-F", "Section": "19", "Paragraph": "a", "Subparagraph": "3" }, "r1187": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form 40-F", "Section": "19", "Paragraph": "b" }, "r1188": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form N-CSR", "Section": "18", "Paragraph": "a" }, "r1189": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form N-CSR", "Section": "18", "Paragraph": "a", "Subparagraph": "1" }, "r1190": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form N-CSR", "Section": "18", "Paragraph": "a", "Subparagraph": "1", "Sentence": "i" }, "r1191": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form N-CSR", "Section": "18", "Paragraph": "a", "Subparagraph": "1", "Sentence": "ii" }, "r1192": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form N-CSR", "Section": "18", "Paragraph": "a", "Subparagraph": "1", "Sentence": "iii" }, "r1193": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form N-CSR", "Section": "18", "Paragraph": "a", "Subparagraph": "1", "Sentence": "iv" }, "r1194": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form N-CSR", "Section": "18", "Paragraph": "a", "Subparagraph": "1", "Sentence": "v" }, "r1195": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form N-CSR", "Section": "18", "Paragraph": "a", "Subparagraph": "2" }, "r1196": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form N-CSR", "Section": "18", "Paragraph": "a", "Subparagraph": "3" }, "r1197": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Form N-CSR", "Section": "18", "Paragraph": "b" }, "r1198": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Forms 10-K, 10-Q, 20-F", "Number": "240", "Section": "13", "Subsection": "a-1" }, "r1199": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v" }, "r1200": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "1" }, "r1201": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "ii" }, "r1202": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii" }, "r1203": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii", "Sentence": "B", "Clause": "1", "Subclause": "ii" }, "r1204": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii", "Sentence": "C", "Clause": "1", "Subclause": "i" }, "r1205": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii", "Sentence": "C", "Clause": "1", "Subclause": "ii" }, "r1206": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii", "Sentence": "C", "Clause": "1", "Subclause": "iii" }, "r1207": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii", "Sentence": "C", "Clause": "1", "Subclause": "iv" }, "r1208": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii", "Sentence": "C", "Clause": "1", "Subclause": "v" }, "r1209": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii", "Sentence": "C", "Clause": "1", "Subclause": "vi" }, "r1210": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iv" }, "r1211": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "vi" }, "r1212": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "3" }, "r1213": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "4" }, "r1214": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "5", "Subparagraph": "i" }, "r1215": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "5", "Subparagraph": "ii" }, "r1216": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "5", "Subparagraph": "iii" }, "r1217": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "5", "Subparagraph": "iv" }, "r1218": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "6" }, "r1219": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "v", "Paragraph": "6", "Subparagraph": "i" }, "r1220": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "w" }, "r1221": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "w", "Paragraph": "1" }, "r1222": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "w", "Paragraph": "1", "Subparagraph": "i" }, "r1223": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "w", "Paragraph": "1", "Subparagraph": "i", "Sentence": "A" }, "r1224": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "w", "Paragraph": "1", "Subparagraph": "i", "Sentence": "B" }, "r1225": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "w", "Paragraph": "1", "Subparagraph": "i", "Sentence": "C" }, "r1226": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "w", "Paragraph": "1", "Subparagraph": "i", "Sentence": "D" }, "r1227": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "w", "Paragraph": "1", "Subparagraph": "i", "Sentence": "E" }, "r1228": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "w", "Paragraph": "1", "Subparagraph": "ii" }, "r1229": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "w", "Paragraph": "1", "Subparagraph": "iii" }, "r1230": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "w", "Paragraph": "2" }, "r1231": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "x", "Paragraph": "1" }, "r1232": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "x", "Paragraph": "2" }, "r1233": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "x", "Paragraph": "2", "Subparagraph": "ii", "Sentence": "A" }, "r1234": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "x", "Paragraph": "2", "Subparagraph": "ii", "Sentence": "C" }, "r1235": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "x", "Paragraph": "2", "Subparagraph": "ii", "Sentence": "D" }, "r1236": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "x", "Paragraph": "2", "Subparagraph": "ii", "Sentence": "E" }, "r1237": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "402", "Subsection": "x", "Paragraph": "2", "Subparagraph": "ii", "Sentence": "F" }, "r1238": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "408", "Subsection": "a" }, "r1239": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "408", "Subsection": "a", "Paragraph": "1" }, "r1240": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "408", "Subsection": "a", "Paragraph": "2", "Subparagraph": "A" }, "r1241": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "408", "Subsection": "a", "Paragraph": "2", "Subparagraph": "B" }, "r1242": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "408", "Subsection": "a", "Paragraph": "2", "Subparagraph": "C" }, "r1243": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "408", "Subsection": "a", "Paragraph": "2", "Subparagraph": "D" }, "r1244": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Number": "229", "Section": "408", "Subsection": "b", "Paragraph": "1" }, "r1245": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "106" }, "r1246": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "106", "Subsection": "b", "Paragraph": "1" }, "r1247": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "106", "Subsection": "b", "Paragraph": "1", "Subparagraph": "i" }, "r1248": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "106", "Subsection": "b", "Paragraph": "1", "Subparagraph": "ii" }, "r1249": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "106", "Subsection": "b", "Paragraph": "1", "Subparagraph": "iii" }, "r1250": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "106", "Subsection": "b", "Paragraph": "2" }, "r1251": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "106", "Subsection": "c", "Paragraph": "1" }, "r1252": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "106", "Subsection": "c", "Paragraph": "2" }, "r1253": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "106", "Subsection": "c", "Paragraph": "2", "Subparagraph": "i" }, "r1254": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "106", "Subsection": "c", "Paragraph": "2", "Subparagraph": "ii" }, "r1255": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "106", "Subsection": "c", "Paragraph": "2", "Subparagraph": "iii" }, "r1256": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "402", "Number": "229", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii", "Sentence": "C", "Clause": "1" }, "r1257": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii", "Sentence": "A", "Number": "229" }, "r1258": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii", "Sentence": "B", "Clause": "1", "Number": "229" }, "r1259": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-K", "Section": "402", "Subsection": "v", "Paragraph": "2", "Subparagraph": "iii", "Sentence": "B", "Clause": "1", "Subclause": "i", "Number": "229" }, "r1260": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Regulation S-T", "Number": "232", "Section": "405" }, "r1261": { "role": "http://www.xbrl.org/2003/role/presentationRef", "Publisher": "SEC", "Name": "Securities Act", "Number": "230", "Section": "405" }, "r1262": { "role": "http://www.xbrl.org/2003/role/recommendedDisclosureRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482913/230-10-50-3" }, "r1263": { "role": "http://www.xbrl.org/2003/role/recommendedDisclosureRef", "Topic": "272", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483014/272-10-45-3" }, "r1264": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "9", "Subparagraph": "(a)", "SubTopic": "10", "Topic": "740", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-9" }, "r1265": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Accounting Standards Codification", "Topic": "705", "Publisher": "FASB", "URI": "https://asc.fasb.org/705/tableOfContent" }, "r1266": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Regulation S-K (SK)", "Number": "229", "Section": "1402", "Paragraph": "a", "Publisher": "SEC" }, "r1267": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Regulation S-K (SK)", "Number": "229", "Section": "1402", "Paragraph": "b", "Subparagraph": "(1)", "Publisher": "SEC" }, "r1268": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Regulation S-K (SK)", "Number": "229", "Section": "1402", "Paragraph": "b", "Subparagraph": "(2)", "Publisher": "SEC" }, "r1269": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Regulation S-K (SK)", "Number": "229", "Section": "1402", "Paragraph": "b", "Subparagraph": "(3)", "Publisher": "SEC" }, "r1270": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Regulation S-K (SK)", "Number": "229", "Section": "1402", "Paragraph": "c", "Subparagraph": "(2)(i)", "Publisher": "SEC" }, "r1271": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Regulation S-K (SK)", "Number": "229", "Section": "1402", "Paragraph": "c", "Subparagraph": "(2)(ii)", "Publisher": "SEC" }, "r1272": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Regulation S-K (SK)", "Number": "229", "Section": "1402", "Paragraph": "c", "Subparagraph": "(2)(iii)", "Publisher": "SEC" }, "r1273": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "13", "Subsection": "01", "Paragraph": "a", "Subparagraph": "(4)(ii)", "Publisher": "SEC" }, "r1274": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Regulation S-X (SX)", "Number": "210", "Section": "13", "Subsection": "01", "Paragraph": "a", "Subparagraph": "(4)(iii)", "Publisher": "SEC" }, "r1275": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Name": "Staff Accounting Bulletin (SAB)", "Number": "Topic 5", "Section": "Y", "Paragraph": "Question 2", "Publisher": "SEC" }, "r1276": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "205", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483504/205-10-50-1" }, "r1277": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "205", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483499/205-20-50-5A" }, "r1278": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "205", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483499/205-20-50-7" }, "r1279": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483467/210-10-45-1" }, "r1280": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "11", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-11" }, "r1281": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-5" }, "r1282": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "8", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-8" }, "r1283": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "9", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480657/210-10-S50-9" }, "r1284": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1285": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(13))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1286": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(19)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1287": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(19))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1288": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(20))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1289": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(22))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1290": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(23))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1291": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(24))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1292": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(28))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1293": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(29))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1294": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(30)(a)(1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1295": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(6)(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1296": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02(8))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1297": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.5-02)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480566/210-10-S99-1" }, "r1298": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483466/210-20-50-3" }, "r1299": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483466/210-20-50-3" }, "r1300": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483466/210-20-50-3" }, "r1301": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(d)(1)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483466/210-20-50-3" }, "r1302": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(d)(1)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483466/210-20-50-3" }, "r1303": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(d)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483466/210-20-50-3" }, "r1304": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483466/210-20-50-3" }, "r1305": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "10", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483444/210-20-55-10" }, "r1306": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "210", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "12", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483444/210-20-55-12" }, "r1307": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482765/220-10-50-4" }, "r1308": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482765/220-10-50-5" }, "r1309": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482765/220-10-50-6" }, "r1310": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1311": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1312": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1313": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1314": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1315": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1316": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1317": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(h)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1318": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1319": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(j)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1320": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(k)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1321": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(l)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1322": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "21", "Subparagraph": "(m)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-21" }, "r1323": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1324": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1325": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1326": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1327": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1328": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1329": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(g)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1330": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(h)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1331": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1332": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(j)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1333": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(k)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1334": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(l)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1335": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(m)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1336": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(n)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1337": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(o)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1338": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(p)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1339": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(q)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1340": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(r)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1341": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(s)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1342": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(t)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1343": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Subparagraph": "(u)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-22" }, "r1344": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "30", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-30" }, "r1345": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "31", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-31" }, "r1346": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "32", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-32" }, "r1347": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "33", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-33" }, "r1348": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-6" }, "r1349": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-6" }, "r1350": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-6" }, "r1351": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-6" }, "r1352": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "220", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147476148/220-40-50-6" }, "r1353": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "12", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-12" }, "r1354": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "13", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-13" }, "r1355": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "15", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482740/230-10-45-15" }, "r1356": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482913/230-10-50-2A" }, "r1357": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "230", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482913/230-10-50-3" }, "r1358": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483426/235-10-50-4" }, "r1359": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480738/235-10-S50-1" }, "r1360": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480738/235-10-S50-4" }, "r1361": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(d))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r1362": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(f))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r1363": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(g)(1)(i))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r1364": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(g)(1)(ii))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r1365": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(h)(1)(Note 1))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r1366": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.4-08(h)(2))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-1" }, "r1367": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "235", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.12-04(a))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480678/235-10-S99-3" }, "r1368": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "23", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483421/250-10-45-23" }, "r1369": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "24", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483421/250-10-45-24" }, "r1370": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "5", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483421/250-10-45-5" }, "r1371": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "250", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483443/250-10-50-6" }, "r1372": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "55", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482689/260-10-45-55" }, "r1373": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "260", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482662/260-10-50-1" }, "r1374": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "270", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482964/270-10-50-1" }, "r1375": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "275", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482861/275-10-50-2" }, "r1376": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "15", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-15" }, "r1377": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "18", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-18" }, "r1378": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-22" }, "r1379": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "25", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-25" }, "r1380": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "26A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-26A" }, "r1381": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "26B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-26B" }, "r1382": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "26C", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-26C" }, "r1383": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "30", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-30" }, "r1384": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "30", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-30" }, "r1385": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "31", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-31" }, "r1386": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "32", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-32" }, "r1387": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "32", "Subparagraph": "(ee)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-32" }, "r1388": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "32", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-32" }, "r1389": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "280", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "34", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482810/280-10-50-34" }, "r1390": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "310", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "13", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481990/310-10-45-13" }, "r1391": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "310", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481962/310-10-50-2" }, "r1392": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481830/320-10-45-1" }, "r1393": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-2" }, "r1394": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-3" }, "r1395": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-3" }, "r1396": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-3" }, "r1397": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-3" }, "r1398": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5" }, "r1399": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-5B" }, "r1400": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "320", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "9", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481800/320-10-50-9" }, "r1401": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "321", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479536/321-10-50-3" }, "r1402": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "321", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479536/321-10-50-3" }, "r1403": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "321", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479536/321-10-50-3" }, "r1404": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "323", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481687/323-10-50-3" }, "r1405": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479344/326-20-45-1" }, "r1406": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "14", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-14" }, "r1407": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "16", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-16" }, "r1408": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "16", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-16" }, "r1409": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "16", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-16" }, "r1410": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "16", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-16" }, "r1411": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "20", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-20" }, "r1412": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3C", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-3C" }, "r1413": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3D", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-3D" }, "r1414": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-5" }, "r1415": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "326", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479319/326-20-50-5" }, "r1416": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1" }, "r1417": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "350", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(h)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482573/350-20-50-1" }, "r1418": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "350", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482665/350-30-50-2" }, "r1419": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "350", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482558/350-40-50-1" }, "r1420": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "30", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482222/360-10-30-2" }, "r1421": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "35", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482190/360-10-35-3" }, "r1422": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482099/360-10-50-1" }, "r1423": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482099/360-10-50-1" }, "r1424": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482099/360-10-50-1" }, "r1425": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "360", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482099/360-10-50-1" }, "r1426": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "405", "SubTopic": "30", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/405-30/tableOfContent" }, "r1427": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "405", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477092/405-40-50-1" }, "r1428": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "405", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477092/405-40-50-1" }, "r1429": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "405", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(e)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477092/405-40-50-1" }, "r1430": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "410", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "10", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481931/410-30-50-10" }, "r1431": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "440", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/440/tableOfContent" }, "r1432": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "450", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/450/tableOfContent" }, "r1433": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "450", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "9", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483076/450-20-50-9" }, "r1434": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "450", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 5.Y.Q2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480102/450-20-S99-1" }, "r1435": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481544/470-10-50-6" }, "r1436": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1A", "Subparagraph": "(SX 210.13-01(a)(4)(ii))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1A" }, "r1437": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "470", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1A", "Subparagraph": "(SX 210.13-01(a)(4)(iii))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480097/470-10-S99-1A" }, "r1438": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1B" }, "r1439": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1D", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1D" }, "r1440": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "470", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1E", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481139/470-20-50-1E" }, "r1441": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "13", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-13" }, "r1442": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "15", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-15" }, "r1443": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481112/505-10-50-2" }, "r1444": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480100/505-10-S45-2" }, "r1445": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480100/505-10-S45-3" }, "r1446": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480100/505-10-S45-4" }, "r1447": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480070/505-10-S50-1" }, "r1448": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480070/505-10-S50-2" }, "r1449": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "505", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.3-04)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480008/505-10-S99-1" }, "r1450": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "505", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481520/505-30-50-4" }, "r1451": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479806/606-10-50-5" }, "r1452": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "606", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "55", "Paragraph": "91", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479777/606-10-55-91" }, "r1453": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "705", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "25", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479608/705-20-25-1" }, "r1454": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "705", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "25", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479608/705-20-25-2" }, "r1455": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "705", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "25", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479608/705-20-25-3" }, "r1456": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "705", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "25", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479608/705-20-25-4" }, "r1457": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1458": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1459": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1460": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1461": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1462": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1463": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iv)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1464": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iv)(01)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1465": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iv)(02)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1466": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iv)(03)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1467": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)(iv)(04)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1468": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1469": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1470": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(iii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1471": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(iii)(01)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1472": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(iii)(02)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1473": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)(iii)(03)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1474": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1475": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1476": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(e)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1477": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(e)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1478": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(2)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1479": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(2)(ii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1480": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(2)(iii)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1481": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(2)(iv)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1482": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(f)(2)(v)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1483": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(h)(1)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480429/718-10-50-2" }, "r1484": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "718", "SubTopic": "740", "Name": "Accounting Standards Codification", "Section": "35", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479176/718-740-35-2" }, "r1485": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "720", "SubTopic": "35", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483406/720-35-50-1" }, "r1486": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "10", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-10" }, "r1487": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12" }, "r1488": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12A", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12A" }, "r1489": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "12A", "Subparagraph": "(b)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-12A" }, "r1490": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-2" }, "r1491": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-2" }, "r1492": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "22", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-22" }, "r1493": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "23", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-23" }, "r1494": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-3" }, "r1495": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-6" }, "r1496": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "9", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-9" }, "r1497": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "9", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482685/740-10-50-9" }, "r1498": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "740", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SAB Topic 6.I.7)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479360/740-10-S99-1" }, "r1499": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "805", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479581/805-30-50-4" }, "r1500": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1A", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-1A" }, "r1501": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-1B" }, "r1502": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4A", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4A" }, "r1503": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4A", "Subparagraph": "(b)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4A" }, "r1504": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4B", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4B" }, "r1505": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r1506": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r1507": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(bb)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r1508": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r1509": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4C" }, "r1510": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4CCC", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4CCC" }, "r1511": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4CCC", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4CCC" }, "r1512": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4CCC", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4CCC" }, "r1513": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4D", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-4D" }, "r1514": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-5A" }, "r1515": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-7A" }, "r1516": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-8" }, "r1517": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-8" }, "r1518": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "8", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480434/815-10-50-8" }, "r1519": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "25", "Paragraph": "6A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480682/815-20-25-6A" }, "r1520": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480870/815-30-50-2" }, "r1521": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "815", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "65", "Paragraph": "1", "Subparagraph": "(e)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480175/815-40-65-1" }, "r1522": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "35", "Paragraph": "54B", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482134/820-10-35-54B" }, "r1523": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r1524": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r1525": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(bbb)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r1526": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(bbb)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r1527": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(bbb)(2)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r1528": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r1529": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r1530": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(1a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r1531": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r1532": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r1533": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2" }, "r1534": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2E", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-2E" }, "r1535": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-3" }, "r1536": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-3" }, "r1537": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "820", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6A", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482106/820-10-50-6A" }, "r1538": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-1" }, "r1539": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "10", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-10" }, "r1540": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "11", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-11" }, "r1541": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "11", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-11" }, "r1542": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "28", "Subparagraph": "(c)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-28" }, "r1543": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "825", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "28", "Subparagraph": "(f)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482907/825-10-50-28" }, "r1544": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "835", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "1A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482925/835-30-45-1A" }, "r1545": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "835", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482925/835-30-45-2" }, "r1546": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "835", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147482900/835-30-50-1" }, "r1547": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-4" }, "r1548": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "842", "SubTopic": "20", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478964/842-20-50-6" }, "r1549": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "850", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147483326/850-10-50-2" }, "r1550": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "852", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481404/852-10-50-7" }, "r1551": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "852", "SubTopic": "10", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481404/852-10-50-7" }, "r1552": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "860", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1A", "Subparagraph": "(b)(1)(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147481420/860-30-50-1A" }, "r1553": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "905", "SubTopic": "360", "Name": "Accounting Standards Codification", "Section": "25", "Paragraph": "4", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478704/905-360-25-4" }, "r1554": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "940", "SubTopic": "320", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/940-320/tableOfContent" }, "r1555": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S45", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477657/942-210-S45-1" }, "r1556": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S50", "Paragraph": "1", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478478/942-210-S50-1" }, "r1557": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(15)(5))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r1558": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(16))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r1559": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(19))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r1560": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "210", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "1", "Subparagraph": "(SX 210.9-03(20))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478546/942-210-S99-1" }, "r1561": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "235", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "2", "Subparagraph": "(SX 210.9-06)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477314/942-235-S99-2" }, "r1562": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Publisher": "FASB", "URI": "https://asc.fasb.org/942-320/tableOfContent" }, "r1563": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-2" }, "r1564": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3" }, "r1565": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3" }, "r1566": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3" }, "r1567": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3" }, "r1568": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3" }, "r1569": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3A", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3A" }, "r1570": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3A", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3A" }, "r1571": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3A", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3A" }, "r1572": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3A", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3A" }, "r1573": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "942", "SubTopic": "320", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3A", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477268/942-320-50-3A" }, "r1574": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "30", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2B", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479432/944-30-50-2B" }, "r1575": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "310", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477363/944-310-50-3" }, "r1576": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "310", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "3", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147477363/944-310-50-3" }, "r1577": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4B", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-4B" }, "r1578": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4B", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-4B" }, "r1579": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4C", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-4C" }, "r1580": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4D", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-4D" }, "r1581": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "4G", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-4G" }, "r1582": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-5" }, "r1583": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-5" }, "r1584": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-5" }, "r1585": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "5", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-5" }, "r1586": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-6" }, "r1587": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-6" }, "r1588": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(b)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-6" }, "r1589": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(b)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-6" }, "r1590": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(b)(4)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-6" }, "r1591": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(b)(5)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-6" }, "r1592": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(b)(6)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-6" }, "r1593": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "6", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-6" }, "r1594": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7A", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-7A" }, "r1595": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7A", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-7A" }, "r1596": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7A", "Subparagraph": "(b)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-7A" }, "r1597": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7A", "Subparagraph": "(b)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-7A" }, "r1598": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7A", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-7A" }, "r1599": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7A", "Subparagraph": "(d)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-7A" }, "r1600": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7B", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-7B" }, "r1601": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7B", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-7B" }, "r1602": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "40", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "7B", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480081/944-40-50-7B" }, "r1603": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(a)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479032/944-605-50-1" }, "r1604": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479032/944-605-50-1" }, "r1605": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479032/944-605-50-1" }, "r1606": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(b)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479032/944-605-50-1" }, "r1607": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479032/944-605-50-1" }, "r1608": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479032/944-605-50-1" }, "r1609": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(c)(3)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479032/944-605-50-1" }, "r1610": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)(1)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479032/944-605-50-1" }, "r1611": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(d)(2)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479032/944-605-50-1" }, "r1612": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "605", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "1", "Subparagraph": "(e)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479032/944-605-50-1" }, "r1613": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "80", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480109/944-80-50-2" }, "r1614": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "80", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480109/944-80-50-2" }, "r1615": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "944", "SubTopic": "80", "Name": "Accounting Standards Codification", "Section": "50", "Paragraph": "2", "Subparagraph": "(c)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147480109/944-80-50-2" }, "r1616": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "946", "SubTopic": "205", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "4", "Subparagraph": "(a)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147478009/946-205-45-4" }, "r1617": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "3", "Subparagraph": "(b)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479105/946-220-45-3" }, "r1618": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "45", "Paragraph": "3", "Subparagraph": "(i)", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479105/946-220-45-3" }, "r1619": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-09(4)(b))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-3" }, "r1620": { "role": "http://www.xbrl.org/2009/role/commonPracticeRef", "Topic": "946", "SubTopic": "220", "Name": "Accounting Standards Codification", "Section": "S99", "Paragraph": "3", "Subparagraph": "(SX 210.6-09(7))", "Publisher": "FASB", "URI": "https://asc.fasb.org/1943274/2147479134/946-220-S99-3" } } } ZIP 94 0000909832-26-000093-xbrl.zip IDEA: XBRL DOCUMENT begin 644 0000909832-26-000093-xbrl.zip M4$L#!!0 ( *,)1UW3+7GG>=4! &,Y%@ 1 8V]S="TR,#(V,#@S,"YH M=&WLO6E7XTB6,/Q]?H5>>KHK\QS;Z0V#R:I\#DE"-5690 /9.3U?YH2EL*U" MEEQ: ->O?^\2$0IY834@@^>A0XES)._"C\Y:=&K?Z3 M(T,W\OQP\,M/NV=[AX<__;]/__7S_U>M_L_GTZ_.E\C-1C),G;U8BE1ZSI6? M#IUT*)T?47SA7PKG)!!I/XI'U2I_MA>-)[$_&*9.L][LZ-?TTWBGWNC*AB>Z MUM=MN M=JINJ]?U.NU&N]W?KG@[0FYO];N];J=>[[8[?:_7V):-=JLCO8YTNW67YAVF ML&?8=YC\LC%,T_'.AP]75U>UJU8MB@V*S6MZNM1CY.88CK7AS0C/!FRQK( MFG;^^S?-V:Q7Z\UJHZD'N4[\>9MLUNN-#__S[>N9.Y0C4?7#)!6A*_57GLR_ MHFGU=N$!3M+1+V9)=2#$V+S<%TF/)E /"B\G<3K[(OQ8>,F-LC"-)_.G5P^+ MHZ;C>/[;^*3P*C[U%\&@CC H'H.?1.UF8^NF+_@-L_B)MV#A$V]F)=[4&:M! M.Q_XH7Y5N@O&A =3)Y<4$09_<"/XSXC>JV^WZOI=0*"+&[:%CWLB,0=Q/?-^ MX;+@4WIU)Q! -S9D6/U^MO'IYZ$4WJ>?1S(5#GY:E7]F_N4O&WM1F (-J9Y/ MQC"#RW_]LI'*Z_0#W;L/G_[KO_[KY]1/ _D)-U'5R__Y __X\P<>NA=YDT\_ M>_ZEDZ230/ZRX?G).!"3G3 *)2S O][!%V7,__0]3X;T3WA^!(0L]EV>_SH] ME?U?-MPJ7-90C' DZ>_L JGSD-P=!&*PX?@ B'ZUV=WXU!=!(G_^4!CH'N-J M*GH"+T;>?NA] 5JZX? ]_F4#+OZ.![]41S#$$#^K>F)2G4@15V6HUP' _+2; M#;(D=5KU"E'7QZ_HP$]<$?P'9CJ 7Q(S5V/CTS(GX(T7IVAN?#KXS\,GV \! M-2:GI:/W. M22S[$A;KG:61>W$BXN/X+$4IX=\BR&0^+&X$/JOK538Z6[#,6KV^J9>IU_6P M=;:>;)W;]UYG@D,ECSQ*6D^RFZ7#*/;_DEX1]&$VJGI16E4#SELWD*Q&O5ZI M\_\_>O7W.^#'KGZKOMS5/^3L#Y,DFUYYW[^67O4O&4?S%@T4\Q]_VVXVFA]? MY+COO^#F\A;\D!,^SE(4OE#QN,^J6R][S ]<=?L!JWX,9=Z+1L ;[DONMC:? ME2P_<)&=YZ+)UOH>3=* X76?D2 O<^G;RUUZX=2KK5M7/H^PW6'5P ';[5:E MV>DL_\"?;-7;=;7JUM:+G/5"ZC:S=+W@QLL>\]T7/'O6S3N=]7R!'424J:71 M>CZ#"NW!(L3TD"OOXL2X/C.VG= >#;N?BL6KF3K-H)_^TJZ]UH)\/69-;0+E[,SO81?H\B[ M\H/\KG7,Y&W X^YFZW'3;SY\>K1F=!XW>^?AL\--:=Q/I)J>O;GU\-GA,G2[ M[<=M_A'3MY< ^>V'3[_Y>,AW'SY[Y]&0G^*(]YI]Z_&0[SSBTFT_'O*=1]RZ M[J,AWWDXVF_6'P_YYL-G;]P(^04VR!EIZ\ /T3GR50+S/46/WG'_>R)WDT2F MI*HA,S[N\UN^"$ZBQ,=I]J]38.1^+Y!?_235B]KGZ 1F@>_"&[:-QE%WHB M7R9[2P'%\O?1?)%]V"BUC%VTGF,7-][M9>RB71Y8Y#?O(1O9O.=&EG;/GV O MG6?:R_16SL7U;UGL)YY/?.>X_R4:^:X?R'RA^R$.1=J>7N]6,S_[A4$ ?_M^ M=F>]+I;C*$X%S/9_B1S@VR'@QNVB.G"/D?"BZG\F2+ &\ MR1RO.7K3=Q(*S(!U.>1=WTDG8UA(XH_& 7KEZ;=A3,NV'>2U:Y *_Q;(.R?NCYE[XG[5>/&'NB^(';F/D>?_PB0\#3<-ZP=]U.88@/Q=7? MM.M<\9^>&:&]8Q[?#S1(,F9!0R/RLWL-%])E6 #I,?SS7J/-N9QS%WHZ\]Y= MIE'7G&;":ZY_E^3 UW\!6.#OOB]CAZZ?G!OQM7?X>]&Q/_VQ64%Q]#&9I?1? M<.!QBFY\C*O8K-:[U7I#?Y<_,\OT]*L="BFKYU/P$_VWGN1#8=_SCZ%9@F/@ MB*M4[:Q9126I^.0A.VN5;F?=:K.[C)VUGWIG"@/Y:O&?'DQV/0Z 8Z??)-YY MQ_-'R+>C$(A*G.ZEQ?";C2]^5N]<^D)G<;4I/^=.?/\P=T6S>3+P: M5VAS#8[YX&@3.)IW 8<*DET&.#IK<,P'1XO T;X+.-K%B_08<&RM'CCXFV3H MCU\EO=I>0Z1D)*N[ADC)J%:C7@+IL028V2B=FO1"^% ^/_YNVXVR@(,^R5?!+X7RR&.=BD/ M0S<:R96!1>F4GWO"XE2FP@^EMR_BT \'R(Q4N ^">7.%Y+>)+&8#UY%K9*LOW90#0D^N6JPP@2T"8.O/'" C-55=Z M7T(!6^;YK[P"_,(*V#)AL>K*\+,J8,L\^"?7?%]N:Z7SGY4.ITK@N&BNNIK\ M\@K8RP"NM?*:\XLH8"\$K%77EI]/ 7LA *TUY&?W.K967>E]"05LF>>_\@KP M"RM@RX3%JBO#SZJ +?/@UYKOO=CSRX1BME;=0?SR6LH+ 6[5C0 OHZ6\$+!6 MW1;P?%K*RP"HO>HZ_W-I*4L,^VRONNK^$EK*,L]_U37SE]92E@F+5=?8GU5+ M6>;!ETY5Q\P7<^B_RF@0B_'0=T7 !Z[*3NQ@Q8G2'V[I=.\['N[>[@H<;NGT MZSL>[K?_68'#+9U:?,?#_>UD!0ZW=*KK'0_WU\\K<+BE4S7O>+B_GY;_<#=+ MIR;>\7!WOZ_ X99.'[SCX9[_6('#+9VR=U=1[&@%#K=TVML=#W=_!92(S575 MT Y6@:&MJH9VMK\"A[NJ&MKA*I"%5=70GLQPLT3?_>:J:FA/9KA9YN&NGH:6 MI#MD83^$?<2A8*?'JIAX.ZNGM#W_>2\1OSNEU.-.L78+MA8N^DL^9'V!O*'A/__-P-(ZC2\*' ME7&==$JI4D[#65ROX?Q(.)=2NRW1?3[(XM!/LUC"BP?^-?YK=8!;2NVZ1)=X MI8&[JMK]#3K2G:;8B\(D"GR/)*=#F&TJ6L%T?=&-$U8&HJMJ4KA!,7OC$%T] M.\9#M),W#N32V5/TD7Z!75S"F6+ 7)+&&7Y^ZB<74TPPBJ4_"/>OW2%R9O@3 M&YVNS.F7SN!2^M-?HCE@JY3FEP=)F \XTQ+$MF^5TAYS[J>!/.X?AM2(*"MP ME_W1.(@F\BD$[3+ 8R7L)G?2IU<4 *4T:-Q!B#[ZW_(SVZU2&A3>G,ZYQ')# M6ZMJ17A=.NC*0\*Y,OLA>>B;=+*;FW*MB ]PN MG1'DSD#8DS'.X<*E3([[7^08^ZNOS+F7SMBQ*LB_3 I4.H-'B9%_F>=>.EO( M\R'_W9'S.\+$_Q=>>95!6-W2VB3O"T,@\>&1'TKZQ0+D MQ ;C@7_Y.KLE=4MKX[PG'!&$YU<6!'_+@B((HRQ^8A"^3(_4;FDM@'<#(4+- MW$2\:(5;N.\/AJF4X7Q0ODZ EM9:MHH ?2)9N[2&HSO":%INF0L7@N S &:9 MPF5I#2>K")AEWIC2VBWN!ICC4!)5(P#-(6V_92B S 51^6]-HUXZV\&J0V>) M5Z=1+YT5XF'0 6VXJ&;MCF,_4' 9^G$Z69T+L^)&C)* 9*FW9,5M$@8DL^1K M!B@@8Z_.55EQ&T.9X++4^[**A@.*7L?GY^KYZER#553KG_>XEXK=I=70OV#* MO R]Q"8W:$+Z5],\>I6&K4:]M,JY29K9"T22'/>I%=]#>_2M,>%V3'AR:\!] M#P)(_6:U\=Q^M$:CM(KW+L:3S5;4.Y5)&OMN*CVZ"M]#/TU.S[X_]DJLOEN[ MT2BMEKY44);HP$NK@R\X<% <^E$\$J$KSX9BA4I1-AJEU:U?[JA+$(;1:)16 MMWYIFE,*Z)16P^;^NN?B>C=+AU$,2WO*3@RE@$5IU>_%L !U8$^$PA.DAK_2 M.U):/7T17*8R,."%W[+83SR@:O#]:P95:=7W4C&;EXGD:S1*ZV O%71>R.#1 M+*V>OXC,)>DX?H5R0+.T6OIM_(9LE+NA]S5R1?!VN$ZSM%K^;4+T'>PWA_W3=[L"98:@;?PMN!_/XL C0$,H9_UE_\Z$B-9\Z*1\,.\ M5A5>IMTDD6ER%(68D@9#__QA[C<&PM82RV2X:;Z0@>!M06R9CLOF"QD-7@!B M7WW1\P,J];'Z%^V%[ MO$&Q+O6VE-3\8R'W.$C^42:(K)UK6(=294'W"^EK+ M\,"5H(IC*<2#&S3JNT9IV[( 4[%UXC.KP0XVB5 MUKCTMM'AA5A&J[2FJ[>-#B_%+$H;1',7='BU=>-+P3A*&\>S1HV79B*E#2): MH\9+,Y32QC2]497TB6S+K;61LK1P7J8QNK6V.Y86SDOL[=9HK;0I\57IA4]$ ML=MKNV )(;Q,6MU>F_I*".%E4NGV2EOO7JWB]504>VV<*SFTETJ]U_:VDD-[ MJ92\="8T/.^3./(R-SV.SV1\Z;MVV96#*/)$Z)UEH1<_2:?",MB\VZ6S7I4* M*B]D;FZ7SM94*JB\D*6W73K+T"U0.8I"!,QK)5VE,^"4 QPO1+,V2V=M*0"DZM6H*^G/ XNEIE'^]$\N K'#)T!\[(G;C*"B>,7Y2B^+! MAV:]WOJ@WOC0%VY:[4=1&D:IW'#Z<30ZE?WDEXU^M;V]Y>#_;M/_=O%_N_4- M)_##B].;!Z>1\;T-)XW4<&&UL>%$L2?C7S8:&Q^>:,V;35SG9NLQZVR:=3:? M;)W=>L?!_]VB_]U^Q&I;9K4M7.T'6FX29;$K$_YS*(5':.SYEY]^AO^AR^H+ MN;W5[_:Z';AM[4[?ZS6V9:/=ZDBO(]UNW?T_%,GS;Y)T@JL;^6%U*+&_S$ZG M-4X_7OE>.MQIU.M_WZ#W/OVISX?TD8#D:F/Z]XJG:]_A%V+O74C6;][Q\1]:N>=*.8 M@+.3A;!-? M6(EYX! MY#P(B'@ 0.A%:1J-=KKC=(//_-//O?C#U&>+/DZC\0Y"CS8@ G\0[F!Y>AEO M+(0?[/_NI]>9.KVM.:>W\>G[T>'Y_A?G['SW?/]LX7Y?=HUG^WO?3P_/#_?/ MG-VC+\[^_^S]<_?HUWUG[_C;M\.SL\/CH[L#ZJ-U^LTG//UIW)V_LQ\"R%DX M2*.PXGRI[=6<9GVSW=6[>8IUS+M#&Y_^\;=&I_YQN:>8THU2(_2(/E9A%X$8 M)W)'_^.CYR?C0$QV_)!611]]+,ZW"1-V27<>/H*=X*DAZ9_: MK%I^8YPZY*!S$'H?Q\+S .0[=0<>F D^T,;+A,!WNYH'QZ??'&3/810>92,8 MQ'641'2*Q-=%B2,4*&IZTM_Y$KD9RF]856R#6& ?7OC4J%=_)S:9CW(/VKM& MQCL@(Q[."V#B\YY[N[-=J]?Y,.8?/&]T^D&K56MNSG^T\)N%#]JM>FWKMM'F M [+9O@&0&ER-&@R.(+,//)#]V?.)QD_$S&:8"(N>]R8#NV&8B>!4CJ,X!=D< M"S^G(!7#KD 9W>E%4= 301"EO>A:4XLF,JON5KOS<89@%$2OU%O:.3**/9=< M0$>Y>W3T??>K<[I_D@BIUT*)V^GP!8G(D4L0-J MN?2QM,TU:2TI:9VOTW6,-CB%5BWZ MOQ*0W?,8IJ-24OMNSI+>H\*XV[3T_W3TZ.R0B^_;H[WSU$'LH^0G: MP#?'M&G&J7:&Y_JU6:]M;GY"/'_Y8EC">7])U ^ MG]!8U6S>B87N14GJ1LZ/813(1 " ]Z)XK Q_CT28Y[M,[_:OA9O2Y4![8RP' M?I("14X=D3C)6+KH9/$_7]^&9]=_G/3%@/2!>U>][9.W- M6KMS\Y'==:C-VM;VEYO> MBSPY*X E^,8XCBYQ'!EJ?KEIFXP7LLSERU\?WA"DSL7UH?)UULYJS/QH'T01.MHATSE%4>_]@E>$I_8IW,]G<]];M M>EXLDT3]YRN,U] W;@MN7+?K?!47TOD2^Y=R^M95[JV)J&GVX)_'\7ET90CL M]L:GPR01?V9BN+19Z 8=QR= S>&F&+]'%VCY[O0D#YWC!"1C$?RO/V9VHCPK M=3BY[7IS:SF^E>=$J@6BL]HMRLWC& [3'XO D=?2S5+ "_@9KH],WCOOX"0< M/(K%ET!%< -,J1CCHBE %SPY([S ME,[A^5?YW=UQ$B_4+JRU@(6-C4_MYHR"_U[YG.\\-O5/.<$#*C)D;"?::K2J MVT!7GQ;17[42U2J#0_OE^=89T)*8:N0KS5S&H(R/LSC)4$5/(P?>0 ;-Z-MH MONN]1W*$[HE=-]UYL(W_V?'K@2IG:[O6WF[=2U%<_'NG?K\O%BVJT:EMM[=+ MMJA6%R[PUC/KP2]A,/=3#IV3PATZ;B"2Y!XROR$;*WT$L2 ^?389]:+@K>W^ M2)DR"?[RVAUB0W@G"DDYO!KZ\&M.2^^C(B^TW=E\I\0ZWMV%&\5V)HUFCZZ3 M$6Y:['T!A9"Z+5:<_P:BO>F;CW=@Y?W5Z^O.;DVW#RQV?G MZP->'G;O*]J !&/6YHF4HVCNQ$;V>?=G]E_-K$/5 WSL#1 M.+"^"\?G<[6\)XLN^'[+P[S4 H M:@.I5A"RH O JMW;T/,#9OX=)SY3\Q[2M.:J=#8^_4!@:,BYO0?^?\> M147H/4O4BL(:%4GR!M FC%+XY<_,Q_L,UYAB*&(*O4ENN-\M-*47?Z)PD_S* MUQP >4D@^-P$Q_[?^]ZE?T=!%J8BIHB4.#%W: MDV>@.5^BU8>W54))S9PIU MWS64D6X(I V1UG-$$!C,M5&Z)]4+,/ <+";$Y1]FR:&6"A"C$;DQ6,KQX"DH M5/CJ.):N)/6JT71 $DZ'B?,.!@7YP4DR4"Z2880Q$@YG9L(W(IW>RI5(9J\@ M?:QV\Q[H=^@Y[YK6EGL@BL!+O3]0W("/Z'WX$I>B!J.":K026JE(4J=;=SPQ M2>Y/X?>X(R/'Y*$\FHHTRY%S^W41^)6Z"8@-@ @C/TT!?TC^C*,09>]@XDB0 MPR<.U?43+ODAOHA4. =,Y0MW)!_#)ONVJ' J!QDGNCIGU7/G'8)O2P&SV6K6 MC$3A4VS0&&.#GOJR\*H-^LOD?6UE*>"];Z4%5P2KNJ3F5G;GWDKGA@MYDP=G M+6PMX;*2H![ !J0C7!SOT5A+2P.O=!,H);#K/$FBX#SHQ@ MZY,*-C_JU M6U]8O#[](C(V]?*"M>HWM=[2:/:J32UHVOSYX1=_5?P;[W#'!E$\F6.9HI?H]KGJI=Q(U:QO?/HZ M_R[/1G>4(#WMW!^!T'TDKYS3:"1"..B'G;%)PWOY+2T!8W:G85<*6"UA8].\ M_[&1B279UM$\=ET*F"WU?K5?R_TZ6R2EE )F+\!RZ$!TL?@"R]GI^]?2@[4% MB?$#-ANW)]_=XV;?T>W\&.]T2<"R/U_@?:-(IT_C5SJ,/3Z+VY&O>0_D>YB[ M[46TROX-VAM&7][1PH_&(3() 1M"4W\:.5G"FA]LD//44Y-RJPTO:)#!N8() M3G[EP]1(#4/@&Q&2R4L_(;86BM"%K:)PB0DC^#*V5/!$["4.9HCXWGPOH=-H MO1/OYRIQ:Q/$,]@+E<%<<3P' ()ZN$A3BUZVPI;/!-Q M3\"PU>/K0$[("O^NL>E\KYUA1:JM9@=C'-_CQO-=*M=T+P"J8V%FWX]';%(< MP]P"7P)D)@>I1RL6F>>G:EWWL9 ?NOUX%[^-XMW\! \",9A'O=(XRXE7:W'% MD)5%QKZ3Y/X3..9; @:VR:[7JM4?]2;<#%6_/;9S'Y)T,9!$:M?#G(EXH@..5$DM= G_M\*2 W*' M D'-0I]Q)$N\C2FD:6[ [7/]$2#"+QO5[5D4.B'A\2"(1 HJ-VC1\+1K4*:S M\:F]V:AU--;H.3\Y/3\(X!^KZX%&^*D".G#>R1 X'9Q\EI)6AW"; 8U1"UR. M!&? ,KS.Y#BE$NDJ1*#+ *L0Q!8"C&>=AEG+AMGAT<&<$!5: $6BG]$0Q_FZ MBW0 =ECU(JK,C ,:$-<-B+< Q.U6I0%+;F'-VRE /Q# G1+1W?'IR?+J+%98__\@F:2%Y.0WN<)O J"/T@^ MY_#=YP!@8\X8[IV$@Q]CO WJ1'>L0_T2U^($-57E(9\1RT[BZ'KBF!Z;)N"* M"T@ZWZ1,UB&P?=$ 4$[/]-A#EE:S;HHFQ52-+TK0-%8AGK(T45 M.\)LB]0Y/#PTD3<'@.D.5JV=PM)IV=TZ;;M@^SAB6Y J:G\I9TJXYUYR0O)Z M_HGH)5&0I;.?W%:!_+ZEY[=,Z?FAR14=BP&(UK$4%\!+X&+MB.!*3!(T$<^O M3[^%!'==GWZEZM._+/G$G)N]8^?'/X^_[I_M?L4J[TQ#;RKS_K)++E9K/3YR MJ"HVD@?\%]4&/#@\VX-7_K._>^KL'WT!?K#[_=?O9^=WK5QZAWJ@S[??\]W/ M )?C P#-T3ERNIEE/TE9U<>DGZQ8DG6C5=NNWR_)>M%06ULUT'>65"*LL7ES M:G1YW(]/GQR[?:?[&L:W>GI-][,];G7,'=&2NFUY[LGBHR?#C+ M4Y\IR[-8.V.U(W.P!;W3J#VIA_WYA,B'X/ISKN >N-[9^*3C31Z$Z \"TQP) M+<9]+4;)-?P6PZ^U '"OAFSLKNE&Z?"NN_'IU$\NG /AIE&\IATK"L/N:Z<= MG]>THVQXAY&#WT/LA1F@X_TL%7VT8(U&\RU8:T*R"@!MO'I*LK>F)*5#O,V- M3WN3GHQ5X-MD33U6$XBOGGHTU\2C='BWO?'I)([&>*1R+7>L* 2;]5=..5IK MRE$VO&LU-CY]E0,18 B**ZFRRIJ K"@@7ST!::\)2.GPKKWQZ1M\XIR)ODPG MSA<_<8,HR>*U'+*JX+R-C$Q%_-W8G>YI(B*>WIV\#C9X .YL%8(-GB3:X,DQ MX+F+3!-?VWQROC8U2!7?IP T_0/1RSQKW0^Q6]=.M;NHV?.:B"Z^".TZ\$3. M6\% [CF]D%3)^_T_,S^=5."-@"*S*?& @[N=;YA)'2>45,VED)V3+':'(N'L M%O[6JC.Z9K>KB2G-QBN7VCMKJ;UT>-?!%FTP_R4V+%G3C56$7[/Y3'3C142B MK;5(]*H0MHLBT4P=&+069$GBJ^(QNU:I@P-3)V,O"CTN+83O -G* B[4<3R6 MO*2U[+.B*-%\[0&?6^N S](AWA8PSW]A-1,_I>14(BOP0Z#_MFR8SFXORG0O M)@?#1->D9C4AWGKM:M;VFM*4#N^ Q>5RS%E>[ DISEDV'@?TMX@GU%)C35I6 M$\2MYY)B7D03ZZXUL=>$L(TV1II2K50LL$FD" 0>,8BE(DY4JW67BUX*JHD8 MZC^Q" E^D!.U7%9:4Z\518;.YBN7C+IK):R$F+>-G9^IK"_+0Q2 YJT#1U88 MGJ^?DJQS\,J'>9N-C4_'5#7U,.02?3#4FH:L*"0[G==.0];9=R7$O/;&IUR5 MP9 =$5.QTH,HAKE"Y[B)TJHCBI./NF9<2Q;AF! MZOJ>+BCL_(JM(M >N#8!KBJX7[W0W5@7["LAYK4V/N749<_J9;,F)"L*SFV+M2_T65&VL_%)9=!,G..K$(2;H3^F,O0 (N&'SF<92I!ZT-7) MSTGXR4-954SJPOR=-25;4;1X_2+1NAQ'"3&ON_%)DQZB*FA5!)*4%.C,.7;; MY3Y"H*!Q! ?K:\XAS#K&GKQK=6QU,>#UTYYU)8_R8=Y6$ZN(^:'KCT':L2*^ M#J14(:LROO3==8#&RH)W[>98NSD>ACR;!3?'O]=>COMPNZ>O[[$FA_?&Z&TT M/@[]GI^"##TG2\,YMZ/:?*WOIM+AVA[X],9'*-(UXD&*PS"K1M+5'Z@=J;Z]]D> MU=2T^4EZ5,\!\Y/VKYW?,K:YC/;8C?J&_FC='_M)5E#6_M@S'W]\+G2>WX[Y M\ C[35.#;.=T_RO\X^A7Y_P8>T__V#W]XGP]/OX=?SH[WSW?_S:W7_/BK5G] MDZ=V^D>6I'Y_\JPW5[M^DKQ4@ L?P4_2PV3==.@GCA>Y&2FH\ B6F (APCJ3 M5R+VJD$47:#)UAH TWGI4^F,I CQ*: 1_GD2^Y<8P)?7D'2^PG\&A*C.J<1D M&F?73?']1K>[6<-H>/PRD8] ]O8BE7-!HG<(&1F+B1"[L MQU%[[F?(ZLE\C<^(VDLGC9PD@(X !'3 . M(8=1!C#2L]+F=44;7/G83T7@).@GA.<5.B?9[TL&M?"B,6W#5=@H^'F$SNAYB-PLDF<)6SL?*2QA* M@2M%5(%GPV@\QEWU8_EG)D,7I@O,!*YT5W$\XQ 0("?^J7!I$(U#KPO#TYPG]B@=@(L'4<1U[F MJM(@B?*SU)Q#H 71"/8C;KMK@(].3P)SA[_\O@_K[$E7(!K ;!--1IRK"(#' MN \XCX78FO6/^06JT"^-C_I)3P8^7,/IGW$T/\SF_)X%WO2/ %E_-&=LOL'3 MO_K(WF;&"/P+&4RF?X4+/?,34M/I'\>!"&=^BY"- M[./ 8^[/K @#],6>Y MB907,[\-YQU#"A=!SGQ_Y0-EH;KRQ N(Y"+-9#0"@IT!UFM:'7,= MO@JNSZ):2%D]'VA)C+15(DL,)G#!HI%:G \TQZ4H!J"-A(?YDJPK5R&^A;6W M MA\JFXD$71NTPJ7A,HKIT--Z1.F#@ZPQ "&5X>I^NY6[1:OZFCY,D:4.JI' M#:-4L]H;1]RJYC%@/RVOD*$&.KZ@%H%<'INJTYGEU#8I5A.*56@(KI]H**Z2 MO37;C!FPFE.BT,3&%R$%, 5Q 40:@"82+2AXQ#*1C"!''PE/\M%=P:,(IW1( MJDW%!<$_&^L/$EF KKQV)>C.,# 27#]F) C$56U68KNCEM+:>*28]P("+3K2 MG,,';[GSD"T_K\1N<*]!I3Z;'_/&['>6S%]:%(^2U(V<'\,(Q#T0^4S"B[Z_ M/MZ6K)?XGB]BI)?OU"] M=E9[S_4V,KBQD7/JNU'%V0-BYHF*\PUD6/S[-P%KK]@#_ Z+\X"*PPB_U]Y7 MG-^C6,('NQD*:" *59QSX5_A1WNP#_CS; R,I.(*O#?IULZ+B6,8IG9E"4GK6KCGGEGZAEI$XLNIB0]\8>%OB MI];!PDG.'AP_^;UF#DB?BCI1Z[PHBPK/JN8<@P3H,>35'D)!SS: M/?NR^R_GUR#JH8=2!BBI9E>342\*-)O:.SX[KRE^LCK7#E"?]0C< MNW VFQ\V6_"%O #6E[BP^PEH1:0I)DK98N86IU*&( ]D,;\-T/,CCWDCJSGZ M,,_@P 2J98!,">N4$L6 OD(81H.^']/#&)2)/S,1DY:H9N4I\8F>10IWF(OV MN H02]1G^BOBIGV2]=57[_J8]X++-4BE=P*?\UM4HLO19X";?\\+U-(5""DB MB4#><'Q 7, +^ GL>D-#N\"-J+2F*NY=#1:Q?2R&,\(UW"%(GCL#$GHF*CQ M:V@/D#&&E2;(X_F*Y5<*+Y"E7.,XF\T9P"5XU+"(95W8>QO GH?__HX09*MH9+$1*> M(INK]H!;((+@?&,V3U4# 5IHKB#3A2#*'Z..CP.@/C&(B FC/J7>EGID<*-">!:WA?U(3('UX1;@ M7'#I43DF(9;'1[,8MF@A!4:_FX)"!$3?[V5&=@#)%];G.4/X(U!$#$\6__9) M20*INMJ/83-HIT#K@[()6.8=4%G0LD 6-):U[4WJ3<&-([-51M=60QE.J.^C MFV2"_!.-)#XL5H0I_ P@\\&<90DVGKCO,O)1H#6.WNQ+O#MY#T"/G1&$9)' MTJAB"9ID *A$\DS4!W4;=Q)8!]]#$R-20!)WC$X ZQP#X4'3B)^R=="Y&L)8 M#F@85(+0NX2E"@8^D!58-'PP4D=-QJIDCDI1XMO7RR;J[/I$O>WS9;N7UJ(3 M+!OKZT2D.$+KKY_BF;D(L:H'X@,9[XS:B$@WCGS4[MYYP%L16&A>U<,B6L"4 M^6UG>81?!:BX$ME4@.8+!^D"*XIS%@/@U*VWM2GM) M4D-\G9G%($(9%"Z_??'/T4PTQDJ,0.119$0^WX]I",WC\*H;QF4SQ JS#J8^ M*/"*)(EQ/JZ@!>H*69%(S'=>'(VK-&IN%/1D (0I1K,7 MR1I6?5R(U>*("]H3,,QH&0E.M;R@N$SXUL47,^*_<'>7F(1:$;, 4<=!$A M;>,*R&\XSI_4 V(R+8PQ&FDYMC+%+&E8-($"&^M10128>H)N*Y^XJUITK1$4#&4@V!4<6%3.LH'RD_# T=RX_!<#PT:B3#&$S%P#2][0: M0FWX M;,-G?45R=C#$U24IEU&58,=W-1'(Y? 14@3(HV2Z!DO"E*H(PJ7D:J M*3\K"/)^.$35-E6ZA;D6;I#U\J,J (* KM&E9,L22?Y]NM%TE'X"%WO"+^,=DGFD M JE])"S^R4U6B#.0QL./\."TK$\GHE:@2,NE $PQWG,2YN/)[*US2=O4+FH7 MG7;P)[NF<\>MLBFZD=$LU2N>[.7ONR(9LI-\*&'CE9GSAO6BPX2F(T6)_,=Z M5!I&I?W'LLBF"3-)'>'6C,?WS_8I=1.67GR *H<(6 M1Y>HD[/RPCA*X!1.+XZ$EROKJ)17-:DMT-E4FPJL>X9W2QG0I*6=TE4'$4%> MX_?0:/"&(V<R:,18D6C%-\F3PC>-X$,&,XJ1;H(#XPX!WS[PKKYY$I< M(=0^)U0>1<82YF!\3=(7KF$!.<%41(@C6Y(IN0&DU]#0)S)WQ5'HNXR4-!!1 M9^%TZU6/(I,H/F8,Y!RD(C: T9VJH #.=JXATM4*Q\<0.T<1%(WE.F*D(-KB M%=&T_XI$V!3DHEW/R.!H;?8 8C'<1/T"H('",KC8P%N(Q"_:A@JK^@/9 LK" M)-BL$+1_: X\+>_I\S119"#!15>DV1A;X\X]]EDHY]/JS-UYL:!/8_N9C=;_ M^%NWTVH:5]%S35P\FD:CUNW@QO>0Z=+0S=+^/);S>;G9<^ M^7:-LKT/(NTV0T=93(W%GVY=\Z^E\\X*O5.K )$-^/( 31,H#@+G]/ _403< MD2GD7_B/P/\SBV*E&T8]#%U\O\:7)\27HRBL$LZ\+)JP\(*ZE&%1R P-4P*1 M: 0\6SVFAT,I@I3E_IX4&; ^X:,V $S6NZ)@VT! :, MV*>(VC2:Z,!-]L7"S%F*4@0(C1C"*D9C>MN]D"DO"\8/,(8V!ADRP[D\D-C( M4%5Q2"K#%>"JQY+"O:(8M8L+/THN&+G_D,#FX\D:N9^4& (,ADX)T'LDT1"D M_)H5,DPR&O3$A;P[%I1.%)F_\W*)(C^,_K8;NGX04#;O2R$#IB(\(>)P4QH= M^OB2@E0AC*UB[! ..T>1-<6@BP960/1]$..EE3AS/X6^GU:<@P_KA9E4&E3% M"6&Q9 :.*01LRA12<62(UT@,V%*$7@].#DF-;9;CK\*,K -H8[&B$M'B!?>3 MHI[)A'G)L:%%>T]NU^38"!WQN+75+GXM"O%I&"7%/C%C]360C"6F!B X/:?1 M^#N9_"/,\LD#-T"5I1'>NGN^O7;/K]WSY21EY.%B$[#A&APT-3<_C(/MR-E" MGL:1:BA=)&JVLX^HQS3Y5S9O92T7?A!I3I;E?T ADDDBB5P1BX=/)!NXD$Z'D(X'@^&>;@^2@U70\FI M4EG0!S9;>-="MG@JF(/ 6[!+%PZWLA365;J;_$.9]SG*3CF&=2U?$A/(4:TT MNIB: M9L>8%PI>62'&G*/)'.UZ)J/I2B24[^QD8YT,G;N"W]'YP4' Z\G[Q6[)>>IN MRK5$M J-UGT 8A"(<2)W]#\^JCBK'9_".JKTTJAGJ#S(>/J494ZW[U"[>N,37LI[5#A])5O>?'M;;A>V? N&]T#_ M'H#J"=J26I?K2@D"8 FKPL^OWGLB?*V3+-,MT"&?[FW3SS'N8I6(:JLVAYE@ MDB=+W8U;2F4V;X>/8G0X&P#'(7G4T;LL @_P>AX0J6IF"FKFDY&U!E4)IUU!]75#=ZE2:I87JO5E=G_[O_JSN MN3MF_K.@(28+19J;4''N7DN.;9U.I75O;%L$U"ZH3%$MV+4796C8PM4O MYIVKA9B-S7JE_4CYX9$GM$H"XRM'AO;FHX7)-3*\%F1H=2K;JX@,\]MD/*<; MYO^*__?0,.1FN[;UO&D,TQ;-^=M[UWB_1+/>7>8LGLMVK=G&'9]3J1>KI@07 MQ]+N/)W77/ TYH$Z]L\4*J3J"8RI3!#29ZF2ODJK2-Q%0LEI+:C5^V0GN4L#P?R0857AY@W5#\)ZQQIFB$ MJBF"ST2>!)R[B35 M$<:BT,6!^(R"!4K!;KY=\P/ID@;*CJOHW4P=2GK8<5T MM1HUS4A<^Z-LQ $W5!9"2LXY!_12@6%V9OILY0L[7*S=1%V[XK2V*UOX7\2" MUB9*:WD4V=@Z11U(-NWGY9#N,>PJSH7>4P MMCQ H= \@?SBW6:M]7<[AH KVE*,HBK96]O^>[%2[TPT.Q6 !6'O0H6^S:5RE#P/A(F7 M0 7-=55X_WKNN&I?&)^13Z%61C?U6H77J&KX?F+O$N\"IAE2+0BJW,#1EIBG M$*5;\/2J M^'[%]*58T,.$*S,HLL7]8VZH+?%&TADVU^D,S[R"=3K#'4/R_IF!2 8<@;K\ MK [34P74SU$&W>,*.!10MS\:!]%$@FRCVW00S[J0G'L1A:KQ#U?^\;@Z+5!/ M5X70)4X?:X^/*%] !QMCY)Y/K8_PET53*QZEZ[E3E7K3^HDSV$/9QW)$5%U/ M+Q3GQ$DH101HONZ;Q-29HT*YZ.QT 11B3H#F&0IY0/A]*EU5+LF%QME!W/+= M.X!5@\_Y#/)IJ39RX[)WYT0I7DD-8Y1W-ZG^4PYT(W&!>% 03KN;?V=)1'^K M(O07U_Q>4)=SEPP:CAK.EH:!M6/ZG@&S2/2T,HH(#=:Y:/+' =O3/B/$97?1*QKZS%RW"H$/B]) M_GL;R-!^"(5:(\/K1(;6([2(\D7!KU!$PZ]Q=*4Z&.R' \$-*E?'I_XC;_/% M7<-G&RN*4:1"/"F^4=<'O#3!F*J?H1]Z6 43^\1=F09TW-N8HUQ,D W5R\J[ M3ZIPG3PDP6XEIIN:44 Y1F&.9"Q5+6GU"8W9RZB5G*0^7=1+"_M,8M@$UUB, M"D57HU ]X]5AB X%2L.N.)J2RD[;%1Y5M/X.A1E);*QU*?G?\T* /CIB*JI( M[PY+>)7[DD\#D.J11N%I=K$K4$X=XN7,Z%Z)E)/UZ_+45Z$_"LUWJ1FZH1\*2 R MAE!=C /AJM:"@+*74N=.R/#2CZ.0HWVHT"@UEC$(U),9%> MS4)5DK6RF!1@?T[UCFXJ!V>I2KJJ(JKY1%:N3Q0/1.C_I;Y5TZ78U_4[PQJT^3 UYRNMDL+XHR(AIM#%4.JJ>QBMK/-#4H VAR=2R]^4(MXN #H( M+M/Q$RA$F.$X6'>Y#T]32N90^P9R145DU:':/4/M3M*P9JP)G6"YVY"R$VBQ M[\X.S]\C*@UB,4H6T!V+,&%+/6<;*P91$U:@._D^N6PWEUZFY *X \!^L M! M(E>:POS -++/R!Q*M8O;9!)UVZ>:FEH, EF"S8FOL!:X:N?LPIY))%#,F)#@ MFXC=81ZZ":B&%785Q$&XY2X2 YC:I3RAWL3Y[T8-D 6;B@ZYY_,\#*LX/4R! MH=0+JZ\W48O99!NB7S/H9X^,F5H%[OC?K18L@_NBJ@M%%U5U+0:H$/$TP<>% MP8;4T)5/<#R<)-R41NH,CHK#@=!,'/*"M)A\6%4]Q14A*C)H5;/9IS[ODA(\ MJ3XJ]KNF<.9I4E)S?@VB'LH4W$:86FSJPJ9C[ =.Q?0+3X#U M92,Z/^I7ZQ7J3>?GI!HB$]6LH)BM&?@,OU8,!C\X@PT!W14]GZIY[^6\[QV> M:Q>C%W^4%^NUE%@LEHGP]>IN5^_LW\]D/#C9_: M"_B65VV =:=QA.)9*D+=AF)*\M6MR)4!:DYXA4'6A.TXNC6]/@*4UW _96UD M@)L)\.:AV' 2(U:ED]6A2%-67>R..]W5B,7P%&M5X#7E_H-8*4&,N,W4>$*F M^X1:GHXQ3UQP=QB76F+I]Q,)BE1J_O3@)B;421<11 U&U]6'W0DDE-;)CM7) M8BV,PB4J]((Q9EO=-L8?H1PG0J-F #'%5=%-(GSS@4 F*"P6F_XI1)YC@DWS M7E0L@(("% ,KAZ__0ID3VP)-62BDMG/D%RL_3B9&)&K;'7)H'" H?GP14']O M6)Y (P@MO6")GWW':D"F>^+NYEPRS$=W]R26=3/RGAV=>LO MX*=&+5X=-$=1F,0$K<&C3'EU57.)4L)_1D0'J+24Z7)FK+UX_P^)<#9;WZ\+'B=.J.&WZ4Q4S(M\CO.3QB^1@C!)= M\R:A-GQ)A#(D%HFA?.Q>,-'V+:[#1+4!^ER&AS0%- 8B>/2MCKEO?3(T;WB1 MFUDS2N=,NED,ZH>ZZ_O72+<'DHTP";D0WIWM[RE+3;$Y&6:63]EB ))H8"G8 M5<@9,U&4A_>'JU:%R*Q5LC6/5K6_ITQ#^WOF/B8DI:>*\R%OH!_-B8WI]-G] MD2\S;YM566!.RJU>L.%,VN5MF'^/X&9,*CPM+MPA=2N.T%D3:"^S6C;R5L1E M0,?:(+I<+>;#]92F2V*@438M.L=K2Z< MB;@G0#JK'E\'0()WW13]/V.?O>[L^/?8DI=?^.+=1=YPA9C*+J@SXGT"G,@,21^QVN\Y7I"1?8M*Q#Y-$@$ TK#@_=IWN=KVY57,.^S:DB? DB'%V:VV<71MG7YJ-+#** MY)Q5]**,M8494I6L#F-$.42:]6O&Q^!%SE-13DY-/)2 -U">RL G&P-&EUS5 MG&]6O5 /VHU9F& MW*=836.[UNS>KVC+PKHWFS400)8RU':MM;FYE)%:MJ>Z> M_E/@L=]JSK^%.XS]Q9E1C]VI+M3^LIL]B65"9DV.JYJO 0&#C7%82K.J00E;Y\,'[ $X\6H\'B[V0#@B2-NTHAZ>!9;%@SYJ_)7 M?A.A("_G$2A[PRLL57E*+E\U. Q4YU&QY#A,47LRK)Q/;)X9*?'@7O<..XW' MD=(7[X)WMVW^BK?JFX_6#]?N3'\?F-YEJ^6@I0M)4$[C9FQ(3"7S([*))&HL MZ%=,YM./FX9%JH<:%H=/@*I34V1J'/L!DI NTA.;M)(=O6*7=$?G-*9PMG CDLRI0P M],6_],EIIJ0AE@-MZG6SG/4UPCCD@<3PAFG!BL2U;T+)K*];ZL MONX=;FZ_ M";GJ-W_D[-6VO8A8@!MU:BJ?,*4ZKJ'(VMHL[00*Q<@YS3!Z(;R(7KFL]1"ZM"^2 MU"9+3"+,B1&]6ZP4SMB52)2BW/UI\:?%81_CU)C4&BQ*S9J_5 Y"+O7I\4VI M J:F,],TNEVBICC=ZY>P&J][AYWFVY"PHF'HG&5!X%^*NSBJ7J.$E1NH]V!C MB0RN8M@>@"V#)'=G:Q7LR/EK[P!N]'#:,7*[+#3 M>1/BS!Y([AZFT.UZ8O1VI9E=*TZ3)!;LE(4G\F#M;([?3AM_[)H2MVEEE:)2 M5W HSA=VYGS:4A+,]NN78%Z[C>B15&E%))@37\:Q=$Y]N;CB]FN77Q;:EHL9 MLU-:%IS88@6K0K(,IIL;[4I7H]&DHEL@4,T;3=-:T5.UVJ;4LWI#49WNZY>% M'D9U5F:'G=:;D(5^$Y=8X^P$D]C?K"3$9*<0LPT4X(L_P-IA1<\_'=1\I__L M*"8N"@C)MRCT9"#_FB)E[_!MRK3[/1;]U"$IYGU1=D*'-3KGF%IMJ9^ 3@TY ME.KFB3&LX"2.7$R38WWP5S'J!7D\-3RU8@B<. HD#9WO[%> ^/@.T^Q%KJCN M18$PMF]-%]6B&UNO7QIKO>X=OA%[TKD$\B"'Q 2LCH[R! M2*:M-R&%_4 MQJ4Z3C_\P(VNW[@H=J?H(A;(^+QNHC53WC6@7F<"/75R$"G] MS1 .BB[77GKL7OSZQ96[-&A>X1UVZF]"7#D3L1@"ID?QX"[Y2V]-7"D8IEE$ MX;.ZB6X4K=E5)X\8.H.#BWV92QS-UK2-^P83T@'\<^A,F:N[2F1YH,-]91@Z MGL[KWN'F(RG.BH@LZ"D"# _Z:U%E6E29"5)4WG8XK'O(*969\!Q#;>I3L8[+ MBP JNL\,0:O7G-/V2B>- M[L:ZZLRZZLQTO9$R%*%)Y4)]KIP8[^G MB\A@BU(-RHT5D.(K)PXOD*O(CL?%@+61Z7; MG-D(X21#VFA/4J,B;(Z&K2,N?55)%$?[(PNYN"15Y&%) C/J?TI T$G\[E4(3K/6[XLY*D'](49 8$,PUQ MJ-8OW(H=]X?H7!0 MMYU%Q;D:^B[W? (2 A=BN_-W>GF[19T00YFJVM'6[$2:X!,J"TS)2U!X<*BP]]<>-JFAU:!6TA7XJ9];@X$C=&H&:)JN9QA<*5!3?- MC!W5+D%P=P)52?L2Q,Z1++3GY-9E(N;ZJKA>IK(>[!FPP%4S81!D.'%,M4HD M,P%WZ<2Z*=RD!\: *TEM&/B L,)W3L5F6=--;&FJH93B136LFX(ST-',(D@>7=&!B^[ZQG],O[CP#] 6D43@H\RZ,1 %^0BO)&S00YPOEE858'X%U^GUN)L8['?G7,.,5.G.X0#R<%4"9 M"9$I3/_1X1K#Q+V!LW*?""I!#&\!O0^C$2!EWE_+4?VE3*>0_%@4T@=8Y88X M:A9:[5ZI]KA$R0$/;HA7G'H&)-PYU3JDO \C%5GF7FAV\7Q55SB,+AEN>!1Z M0Z4DP0NYD*J5GH6J'P)VT<1"LR1.Z-Y?"LGS3C'YD5,W.=,DS%QE!)U&&P4H M.C,\* ,X/D0846&Z:?N *A6OH[4/EVC(":C&O5$#P MDYSA$#<84]\9=12ZSCX*WGB:W %"-LN8!CQJ-#YXJ:I MF6O@9X!FFFW,6W1!=>"^?7E?4^'R7-%X'"5Y;7&]U#D#$TWGN(Z46P?U@1!A MO6/3S! 0,AKKSP.UU:OBAHC#YKR%J;-I13O=6Q#OH\;N(CP!M[TY1ZP[O.;M M,%PN*FJM%,MFFR/%IK8(?>ZE:\L]BS&!]#Y<&EU$[/"!;!76!9PKPD8?Q!YP M!71LXPP]1@CNO+,$0I+:Z'+Y?AF/$I:L3%\/SZ!XJ+1![*-+I!D;25*5=:Q_ MS9A\A5(%DB1%;G2#(>XYE9"0-F_%"96X)VX6#JJX#B=+^9"IY+5P%6/$NT'7 M!7DB5[AV$2*YNDO1CH)ZB^IA*F;A?\"R M$L]WK19(,A2D95.][HCQEO!+M:HP%XBU7B*5&)*I2FEK+.1^O_D5,CU X8\Q M7$VBBWH9)$U.W?,;.DIEL)T#>!7+>6/+0+_FL0\CB!HV(M6T3#M5:V&%A*K)3Q_O&ZUHA=@% M=L/%9L0($.+/<_DQ\HB48"Y@TY+N$U8?1HN-ZFJ:# 7V&=HM'C2!S(L%L'+* MOH:#OQ(JQI4ZN.J9ID S(_USI>1I@=@6[2MJ"FS[@E>XLNIP07F'J]@7.O.. ML6=]?EK8!RN7E 21*Y/AEUV!BF^I#GA$W)RP!0Z@F"8%:P4?0)]43W F\Z M;<@'[295S2HRY)RS'R)'Y(9RII<"7O^\7QXW4 E0 (AG1V5VJ, W-NU7=6\O M[F(2F'915I=>WG;-V:=T%6K7:IT&BZPQ$Q]^ZN8M('/5Q.Z4AXYU A_$GF]528%>L2*1I] M R9FBNX4D%H1KAXV'@O$A'D 0>/*IPNX4*6^J4_1&W%G==?]$-:>J=)R &YN MB8T/=:\RFQ-0FRMN19@;]&W%F+K?C= HH9K?C:7T*BA;9T# 63:6R!2PU^M$ MJS74SFV"IA8_U')2@(U6Z+NMAG*\;&G@D:=B]];@)I)&$,=])H05HL6NA)&]-(TH_< M3#6/)A-G1=G9J &D&D?U%5']28CYH3KM7RHCJ(>G"-*-#VM!(-6<+V)$"ITZ M>M4%-);C+%7MM:(<3Y&P:;MV8&P:T[(^M@NEZ@O#PO9T^V@O<^74P5*U7^Q9 M14W:T%]<=.-8H.U+_!A(&1[ S%JT;6;5;PTI>Z2RA9.\W2OQ9MK?G*:P!#IL MXX'0BVXG1=B0/\$I,[04$0F.[ME(_R(:(;S;XZ^ ZM:$+,$VBG,;=KM]O"N9E).P9Y^V.FJJ MF0Z[1>ZBNZDB9DZ;?:D'<3;./[P11O-!!)(+M/F.4;NLY)\B.R*Z!YL#WC=B M(P9?=KP9I.0;^X=U @5)G6A+#F(TZB@WQ W^D:(E](9;PIVT\RNBAU(,E0,2 M+)N&=;X*/RU9)8BPCS(>GQ+VT5H$=VI(@D@L]O=,:B@J3VP&V[^Q.RV%N&=< ; MN([:B)AD(Q2;L!Y+HJRCEJW-!O[,V2KY1WD14&0R_;\5U*F;G>V&41)LSE4U M7')-I6 [+N/YSZ>SAR3J&H/J3!P "_S:24Z! :3[VE>V>"0Y+=(F5>ZB2JHM MWRY$.()F\X UPM( N"L%48H3EF)#(#@3& M=(9R9B;[[O9TT ,'W<*N7#K:HB=0]=AT Q_U3Q59LTIWL*]CZY ,6B$I(M77 M3:MMS+@4[K-WB5:L'FL7=%+4%6VGL+QVV7>,K#S"WM'V@>?,V?+X(F"]Z K= MRP@?'BS7 F#FM!KU01^/W O3 73*WL:\?M%D2JDAU[+BF( BRIRAWB6MV!)Q M\*KE+C-4GOS$F1\XDWL\C=9<*6H@\T(AW[Q'H5%?NQ36+H67IIGSY<9=VPA# M\M]L9.SAN9-,$E2:B+A>4CVO&1.J)1<4!!UN=RQQ%&!\?TC-^(BXV$/S2@(Y M/;2B7+GR844XK:3-S=HT-D@&UN[&&42)>EG.K@IT:8X$M:%#XT5\D M#LT+-*YHO1MF(09"UF85V(V:/PH_*KJMHN<%V8N#7HM/T<=_0; CLS MS>)_ MN(,9!C"KL&H03;C[,=-\,H'Y*;,:".HR.UETYY MJ^!-$+\S%7*NM'4*&E/_YA"Z%*,PI'"'.LB0C203/ 7] H@/I&' 2#*.,=@" M9%<.R98X_(S9A92663L+YR)XDA"#)1/M6E,4SJ!I?C4KC@3*D38@F]=RS2(/^-?1G8# ;#C/#4(ZBEW1<.UFU0WDIQ%5Y2#E MF7+J=MM:RM0Q@!XV#(&R#IC36 S!WH=MV.=PUR%&92M2Z*ERDCE"5PHK)^&]FXALLV5,T M485E8Y%RK9B@:D/>]"Q%=1>Q3SDJ8+6[ASI=$MU"_I\9*89!($.B"H4D&5 E M1:PV[<=>%1].\NM":@ABN@[ ]#%L;6(E9Q;L)^JDB>G%E,!H?F2 MBSRB-QD+4L\4U:'HW"@@FRLR,0]N+9]COM !.G!"#AR,8DNMRD*89QC%Q&<% MVUS0(P4$0I&) ,1V,MI2^%84HJ$3^ I)41PAAFS&)?&&/B"+-%!C#,B=9NL4 MTXIXISF2'W* 1DHZ(E#AA(*P/>5K!;!07* L)L'-8:_D1B--LB".&=85F @0 M@W33*B:'O3.IX:12R[VG%+*I>$U+7KMGZO!AF&2&K<**70$CY0%N=$C6Z.8Q M%>8@FQ3SK0 3$3@61IUC,7<0(6;GCI%CC]@FT78RF@"D2BECWI@B:C9@QY"P MR9'QCR42Q7#A],>ZJZV=H8%!"'E1WY'O 6$<8=CH.)CP;<< 8,K32 &4J<5 M.-.W0#$B]F7D"U W0AOJ"L'I.K.[B,2@8T0*"3R.*RAZAG+RRR8Z'63 RS#& M.2/],=KGH@7SXHSCI2AROV!]FXKB5]*!I,1/>/$/"D\&.0O>&@@+R6E;("P[ M*^='/#0BA,$6AKJ27TBB0:$+_39DGB59SAGYB5$JT'BK23CS6R-KA3)%[Y>1 MPJ?D=>+'N2O1UAHI7%9_G$0L+#.K$11(@FD$=(&!)F#- Z:91/>9>Q63(VV% M )Z&]"\0([TH-@(\2T3&-S7-2[& 0!1@QDF%4CBDT8U*S5Z\ MN"(N&VRU\#,7F0L;J5D)[,P@%QR5O:!Y$164Y$_7DMQB!'.I%1N2^[3$/*VL M3R4KZ:R_FG,J1Q&F@Z&3DU*/2;*B! . #R!'XE-,8JHI\K2/=1\HE>/(Z8FT5JSEY!T^%-*[\N6MU9(<,P$?B/L$[ C<@< M33>,MD+)N/@'#U% Y>)]U/H;@&Z4YU0@<2:KCP[@4=>ZYIS QT-"#K4ZW$-! MW@,$&@'4.950SPJ@O92J"9P?:H2>RIXQ!PYW M?^AC*C1Y:I0N9*X"*:HB3DVHJCY2D&'0 E%1TF*L(Y4X +\GC5P06+U%.1 P M%F/?*\KL( 43SH*X.3)GC[@7D"2K_-^N8#MB48U5!PKT)$HYG(E$9:!R6CU M484.BQF.)Y$1JK!7XB R_[9 -&9590H[*AP$O!\+SMZCX#[@HC3+A91C#,10 MK)GQ%3=]F;-T-B\PGT6!D\5R'(6A0XEBLVB&:)%((R+.N9FHIM'%G%97%N0\ MJB"//)2E N5:OLP"C%7MJ?BWBF4Y&:"V#PS,1Z:-'$.H M[\E$#&R$Z5$0#3C: A3B?!A5K7+>0U78R1:)B6.CC(;\4D5X&UV:3L"R&GB< M\8O!U04R;F>@9QS.CB9!YFE(*@EI*0)=L5 @_)1^;OBX,N&R$$!:?E%T"CU; MS51LWV2P&@9*L*3T1Y+-8JDS44(0*S,!8DHJI3$MF81_%0=#MB.*+E!!&@4# MU[1"H$0;70A#BPNQ+!;'T!E]EHV##:^IMML9SEG &!,8J(LSK) >B?*5)-3:<4P$VRRG!FH8QYQ>.S+*@L+EA)#V?!44R4Q1B.^;:B2UC'NN><^UR M+)_/M^15C&;(19,"RMM2VS)*XBCR9%"9CGFWI;N#+&:?#IZ-C^FR=+U=BK$? M2(Z>4?8L/A-/CMC_PDN)28]BWX,2<&W2KBK7P":,)3CBT8':"W]$#B]CV@'B M8BBEK:@O\%=-U6@@/?H6HX"?V(8C >@0^Y)%35.ES"_TO)I;RN&=9EEX;/L9 MT@>XV=]#/!)=&?D++N7_D\J%46&68;(";H= MK?B!7=?%T#3]$WV$O^^!*BE^2IP3;6"T6V!9JX$/WE=R/23. G)M4, :_K![ M:%L_;"MB$1C&L$Z58UB%P\P/ B%EP5MQA$SQK1Q(S)^RI'U**V3+N\[KH!!J M9 K:44;>F1@!:&MH1;>9HR( +4L.QG_WM0I""K@J D)DA&ZI"B%%1:G4+B@3',F$F;@P$##N??RATM3%GA[">]$T!X-E+: M5'$D@3D7/:T)5?D!!@1L3Q=LZR'.B]@CFW["IB5W*,D,Y495SL3"%X91X%%A MJ9Z@N.3IO$UX0L7H,*6$V8P=LYL,HS$-@]4VD-9'6)>"*[NI6)IH;#*P"P'" M5Z:,FLT K+*X&859%NH\60*O71N(UZ."0/NQR#QBL12UC2YKG0VC5F2.$,-) MR&6>$6P[DU'/'\02+A$C1:-E46 M,BM66*%Y?IM):C+L7#W.;Q_[3*9QG\4%U@6HP"#5_8I"WP7]$V.]":OZY+0Y MH*@D@1J9*M$K7\/UW\8>K!18"4D/)WI59VAXLK410=DLTAJ7=!!YJ// M/=3Y#?H3/BX.F3#^,#TP2%?4($%;B,?#24+N%O)3YIM2%<(JU@U1B0VXSY'/ MU:11@H&Q +]03K"H'5LP#[72H2.TK/!"%:3E.2KDA4V[GDVV4%(*V'Y-L(YE M%3/:E+Q.,K1]#+D,M+C MIF(7T5C"GG*@DNS]0S3Z(XLG,VP.(ZWTCW;2/R?RD?F>O1^Y4E_*$UJ8>L*[ M-?%T-BGK1Y&GI52NG4R_F(/$J\.Y29P>-59Z8YQA *\[] ,/1-N?$O,%FC-2 MZR]B@!E71AAP2RR/#7=4L3=BGRW5>/8ON;:[*>=K128EHD_25>Q0HBRQ6T.N ME.JB /H3):ZXJ2E/K6N+6/DL 9I"599(,00Q*=INHKBHB2"NL.Z6*(^:JB-# M9,D/D<6H?%]R^"!]NP4!:\X9:L;J-9F_F$?.J1@G(B@IL 5)(;]PN0N6H"F5 M2I<[>/->GN;:R[/V\I23.)-0-O)#4\ T&4=^0&)3,4Q7E^JC.H=1#&/ ZST5 MH:P"P,C !+1",4QM-^0D@2#D0S*8:,@9U$]PI3C-XDVZSE4[9"9XA1&DD/^ M$13E. KM9T5HR-$E$8HG5)$6A9!!J/.!33A;+.V*)ZHT;:9"#_*80%MRUZ1, M<0$TH/$:E&P\W6>"V+E=R;"0RDP9")/"!&K@7+4TS,6*\9B2PG.S/OG-L)#R M=#R=,4F31I%O"BW#5-E&U6W%=&0*=YT.R)UG266.9H)%\DU:')J4PL08[?.M MHU\'/UPD&UF=9LR[1?U?6]]P:9FO,,MR<>1N-)]+8.Z0H^/K*:"3 MC$/^R 1VJQ@9FL92($PMZ%(*K NZ6E&NM!(2"_EZJLY2(200(VM ZT3-Q3A< M8SG$0$;2:C@GPQ+]^D5IL;*X5M8\/4SGJI?R/&\VA4Q%59FZ!\J(: O-RA!R MI4^<]5FE3%HE9IFV&U0MA"9B1"R9Q491#PGH>!B%%'V(A"VULK8*,:,PH398 MD8G,/"$W)MD!,*1>E?ZHFX.[#K* MPCSLGS" ;**F$Y.%*G;X0W);=Q63SZ3^G.JRHD28/'R:W+M(T M>TCQC%<-3 M8BL='.F^:8M!<5 \P@]JW;GWD>Q,F.FA,A<08K:221U'H< C/CSF=00]! M%Y.[E)O?K $N):!I(.V?3)$$@H(MB9'E&[/F231"%Y4D*[&'B16"PCYT=45@ MSOUJ#BLK!,<$1?F)(88J/-3TM>$FJ&A='P&QLZ?UV3^+5D\J$,$D7/N-T0B; M3G1*'Y>=2MBAI*='_+L4L6KA0;D,JOT*E4?V]&4T^:C:\T7J.(6AH!$7R %R ML=E?2W6#DK9A%7T7OL=6BAC68XA73)PAW10;3S M:G.;4+(Y\6IWJ5RQ^C1J_F6U"VV:PS(ML?01*8^^7;[!W$7&1K+)P/*)HPB, M?2X&]IABO+9C0-$](I!(]*CII3+U8]@IECW6SE5/EZ@VL=*>S%N)1?T*O6X7 M]-#]@HIE0M"=PYF(2"6L4J8ZY#$W0?)5*M10L;)N@;FIT%'EOU"[F6F-64B" M3H9./XBN;K+,O'EW16OMKEB[*UZ:7-ZW5?4WK@R)U_J8Q(=]K8K9D MEY,M;T$JODEV5KJIJ3LUY5Z!_V#:!@43ZO:6%=5?45?=T/Y^TR(L3G)S0F!7 M?>;VV:&/AH&S5+=RH,1LY:>CJ/-X*IE?=2#3F%.=QIPD@W^;CK+TERGX%(74 MF=I:BRZUBGXKG56"H0K WB5'N%!X(:V$/O PVB,UAA\2>4@KHP0 .S )LZ4Q MN(;#7,FRB^ZG5 XB]A>%(HZCJ_P\[2U>W4A. MYY^0O44EWBA7V^VVYO/IBDM\',H)IN!J?:U[&%&*MS)'J^7D*0 NW&J0Z>)$ MFY91<\(4[&$TSC/:$U6N2B5"*Z(VK]@2Z#/Q0#N;=P]5,@'%K',$KJF4C#-0 M^?=V[+5:F#'E+6&0UIUA+ASA55'2,%0-4\@UQP'VT<<^$:[%..4_9Z2 MO''%'"6K50J%QQ%&Y,U1=.L^KJ1+ 9U&_^NA#]*/,%&(>H3[(\Y4DNPC+2Q2 MVH<=Q59M>$K6F6[]<48E&*S^?*1RZ0:5E@.AF!I9C /H8VWJN-">%R%D%=NJ M*!LG#ZL[_5F=?ZB?"'G8V ;IVP9Z71C;KK-D-R*\Y%"$A,OIZ0[GB@HJ,J_[ M&5+3'$;-HG=ING 316/9M:65_VE>36N[%A(QQE*RPOFRA4YS,LW?C9G6@T-* M=&[:3$(57DRZ,?>6("JO0H3X)X?CXNFI GV&WRDC/+:B4I0\0$<=[34+67 8 M41D0RWZM/C)DS).]5'U7T5R[RN4#7:P2J\B>L8XG,DT#:2<:&D9]!1J9LFFC M 3G*3 T;N) !->%,9?XZU[RVZMG;[73T[>)D9&4ORQ/].$S&BKSH^PE),J,( M+KO0.GLJKIUQA'$)TBY8;UU=PC4TLZL-XA?JGU[&1 B&\_O]Q$KPM1.JL+H1 MVFU1V*&S=-&4E=C-1G*[HC9JJ5*\Q.1OXU M9[>Q:<+N+1X5?#*FW[>Q@\SPRUAXLIHGHC"!\T,24M _8X0_96&;<>6:Z0EG M=9FHJ9!=EAP\B6W'C9M/64JINX,= /5NMM;N>R[F,N$,=A6'RWW'4$RFL'E" M%DS^'6A#E8*ZBDP!%#*F2UZ//C\.9RVV*RO47O>I3ALWBR,ACNKBF.!TR[6H M8I%9 E 5FE0+8&9-W!\FCY,AP)GDE9JC:(5>^@TNY#+SC_ET\"2FV BK>Q 6 MNHV\&4G!D$>.B$':D@=@.YFJ:32GOY%=%%BS<]L5C-03*^K\_^R]>7/;2)(^ M_%40'O>L_ N(S5,2[9V.4,NR5[MMRVNIU^_^M0$211)M$.#@D,3Y]&\>=0$$ M)5(G*6)BMVV31*&.K#R?S 0%B645Z++PG6SX6P+(P8$CL$\B2FQOOL5\E.2K M2".6O3TYA6I*&=R:SZ-3WU)$"A%92^ETM5H!ZH=.);9X9@%7!XQ/L215^L+J M8*0:'32<[U2%B?B-[?(WBU+',F<]T:"X['1DSM'@M,@TE;!%&5$IY>:66LF; M6\8]%U6K.%5YJ,1 *9E5:>4EQB(Y#_/.D,&=*O14$>1'-2XJ\FT"YE1J)DO3 M\M7- >,+5"6V*>441B6&32X9;.U2V<;2TM#P_M>Q@6X=&ZAC R_-L*J-VPN- M\)?)EP9-*<&0*CU6.H]*_D:6.-):%#E_?%\ O9((4G="%*3[EK ME1?!-^DB^L9^N=+R29N2V6%&RFZ3IFAZ:UJ]"TL@5&W<5)T#AL%-[2?X192Q M6*T\("HM@&S>^N&U+@"@\8IDKR;Q-47+R1RR@5FI+&$DH8VL_;GH0$UB>$W) M-6CJEU$E@T*^(8;"5<()>3YMAZEJ^<;: V+C9=42=I3"AW-.)J6<>=GV0Z] M><)E0CUW]I;BB2E?%3!9TC(+$R_8E:Y*#)6UN2VC,TRE(:5>0Q(+*KT*@A3K M67-L1G??++@@O:'L6I$'A!4O!A0B5>V!> N=GBX>Q_N)\%7SMF7]\?*E.HV% M]-;=\R3'0E*SJC#+,Y.9LK@'7B@-F"NL.4TP19>R3"+IPAL(KBA&?4X2??60 MP6',@?5K"H;]+CA'1UG[LGI<@?TAZ]M78YA\6--CSW0NDL:43HR?8L"JU"3! MAF51&G# E;UH=PE[Q4U?Z')+-XRU@<6NDNK-LK^JF;ZLV"PG5*SZ@X93( '\ MA-.DB(?LAUK(QI$NYW2"O7"W8C2N0IB"P,<3#$@ M*L(1M]HR7QE3(@S@[OK<7+W0J]'EOAV(9 I2BF&D"UUR+.NOW"H3/5^>K\I2 M4IJ5PD-$8NPD-!0< N47LL_E7P\)U'0O,!A=(W.A45.:!ZEP7E1UU^B1XO]*^F M:EDV\%#Z2<)(,AZ(%!F$* .Q3 G#19'*&3/4^5 !7HL%Q$S:82EC@?&=V%U:;!R M\Y3'AC+MK"H!=NV]*O]'58+")C*D:B7^D^VR,Q"&_6(,9+E[8=LC31_9%]IN MM@]_X0B-2J095OTQ7["7X MAJRN&]EM "R$:55C-ZRBA4DV,LV$--GBRU MSR9PF6)5"40FK$3H2?9I58;- M4Q1+UC:ZEFV*0]G[J?)GIGKHDA62]D1('-FW2X:K8,949-*/0^#"JMR:;.U5 M"LUA:4XN)%^BXA+UZIY.>33RKN)$*7[Y$L(N+JJB"R410.!%%OSM;-E"*96& M,T2H*".%VTD(5Z:)+/'&<24WVZ[B=A6+<>-"I*CLE+_]ABN6MT7W][B,M;:3 M_DTT#QLS!'R/"%&D8[TJ9N:I;E(60<[5F!S2HT1/;3/*T I)RSCT&\Z)>JBP MX?:VWN**MY1JC UPH@)5Q3%)X=ED&;UN%R.N%D1?U],6=5BZHL?B4A-P1] 3 M:VZE48 K]K((1XIUGHALWEY2^56T0KT.>\7@!G+,;@(W!"-GA"^8SR8QVQ(A M!Z<%&*83T&Y_4G)%$/JC@)[R*4"6I1\6HSM(!6B6,'K":OLR9'LR[)FB740'A'-\MM(=FE8K= KG<"6A0M@\%:+624*28$Y+8$J0652/TP- M33"Z,C(NAG%L2L$D8@3&A)R6*:,U#13BB_:*#!N]*1)>B8X0T[/E*D@#KC2@ M6!TZ*M5T%5Q3NB20G$!Z8T)5R/*-$*%WI,"XM^7 %(>E?HR4B6,2J*B2"Q5Q MMZNUZ]JI=D'TXF $$)0NBKHF5Z\.9-6!K,V4EU8/!N5D9*\2]J L>'L)K,4Z M(BH@I(9YJ>TA+K* Q9%U#2T-RR)&DLA<$SFB:Z%0./7/^%;,0P6[CTN6,/LS M#TN N:UTJK'* 8BU M@GVM!(=NKE60; 0382CE4G0@-WG'0HU6*U_& *K^?EP^F9S3ZC$=(Q@4&Y:F M>4J^64L6JR9[:)N'H3(-+9%5UPBH0+3=!1!5)_Q@!(L$O,UU,M!&[M+R%"J= ME('Y*T LY&,'[2T";=87ILZJ,GZY.2T7LQAKW(MGH5ZLK+W^VH87=CD4GC4-4A8/Z8:I_JTR_Q'NK)-'-A26%488$)) M\M:\RB%P7J0LXV$KT&[!:6)7A%6.X4J]VW46L;<-Z1)2J+Q%.+?L).3":MDQ MA;:_#-'!Z]_+GH%\Z@LGK4'6'TR%\ZDW3.(%0+4%$"W'0\R$YFX!.*^0X'RQ M9,F> OKR@XU\Y%B38N"FXU9NE;Y7XO$#O.AG%%]S;6'NJ2D6(!H%AQN[N. T M2!\&40L":ZIAI2RK34$%JU>1[$%FAW=T'1DIB329*Z#Q!_DQ._J &K)]ZS=4 M'&#^0?J)E*Q3[O]1<<@%AFX!\17&;2! *@1Q(LU22VKB/R70%@D HTBJ_DRA M5[CL.2!W?R,9W)*P@U6R @L_EQ,KJM*'*MVT*MV)LK-*VZ9B:LAQ-G)OED,L M0$<35X52IH'Q/C,+E2YQ*J(Z"@GK1,"HJ@U4;%FRO84"],#THWFACH@LU=K'!.:?(R1K>U &!(@V*K5BI>MB%(D&]+B]X;Q!S(5/I$&V] MG\]4)BY\@V!B'LC.-R#O$9:%2LW?D(UP!"09XG&N06L;DLS_![59PDW^;HK6;%D>_XF127&A M88)=]K>R4=E.5QU<[-DDT^4]JW >=K C?CH2/JH1KG*$RE3ZQ52.RHVV2P-7 MY2R9$O:L2\:^K-.LLCHXK[>JZ;3,(L(&;*Y)"L<&;::\GIT59EDG4 G+.RGU!>U.&\U"+5J6F M*++%*[8RK+DM*>?Y8'G%&RGJY(MTM3L\5=N"E2]$C16S%:6&AU!'[&]2[ C. M^!;B;:@RD;Z%;U()]61D,&@/*Q!RZ5UV@UJ1&7DA+=Q,*56<,_"*>G^AF*2\ MNF5WMMV_HZIFA*RSIAP9G"I.MH$)'%%I"2N71Y7:PG)LZ6A>.D_30\AT!I[Z36"ZOC6US,K235T5BQ@WFQ[K@GH4_\ZCS)5J^. M_7J9F)6;B)!B17BQ/@%9_EZ= >H#7%.^D ZFTQX#B=JPN[?.J!@$E]SG;KUY M),U)1CWR!<>[O/1N6$@0XI*Z+MQ %(UQ73C57>7.F.37 DE[,UT*&P^;@W + M8JX0-+?*=^C.<:J3@+Q\RG-E:I\SPJ&JI8ZJM:RK./!]YO&H[( *LX063EO: ME56%\(ODO$I@3#GSUBFIO"LQF8,Z)E/'9%Z:HZ_:2I31N:IY'^@TLI.R0-AK MD/+E=)V_P(A$'N J^!QI4#8DUJ" B<67?6:Z&*3R$H4><4,*^9NX1%WJ"]%7 M,M<3Q=I(@BC-%OE.N]\NA*CR+$730CK+".>WUVD19!)#*,9$UU&4=\OQC*PQ M*[?#,J"AQ@@N=MTK0>=,^?T%& :C70J%J'2&+L48EH+&5;DP6*JK/>B(6N!L M#2H//(\CU?*#,-WEK&[5=WX)X=I8'KOFK V)UXBV@C0MEGBPD4#*F%BD^BB^ M9K"(50Z[[/ FA920;ZQB+ 6!JI6IG"$JKN'L69 CJR %?PGD.E24H>J>2.F/ MQ5"T_F;J>%6:7#8)VEE+1M?&$92NS9G_?,0RC<(XO^RU8347>+]N 5K)L]#K M2R[[O\A1H< H7!A)TKVNXG6%%"*B8A$&PM"D,B5*81=I+>2T@9'PW*C*UO+- M5V4".!)AF>,RC&W0B5HU#3AGC^KU,Y9Y&5A::8E86L9V]KO% ^\+H6.I(8E7G17"Y9G9O(<^_TF4B MS^S$+ %2"V8*XJ^V#>@VBC&\)KF(MN7896!Z\%I^LQF67I$7GTL(SBU7G*FT M:/MXV,$CF]-(TZLJWE0LUF[WU5+E771A3CIJFA.UM;R;CMQ%0B*GC":FAF/1 M*W=$CI/2FLF587[%VO*<_(Y+7@H/W/+.2M*48'=IGV(N*KG\.9(AEAF/%GA? M0S>*A=+O3)C82-J^5>GF%KB^4;IMOZU ;YH1HE)E28VK$8[C0E;B[#:[2M!> M>,D D;_[YS>AF#O'0ZO_#"94;>0N57. U59'^G"SK?8E+73>(0>LSI,QY5)D MK5$NQ"[+*:LV,51BTBZIHP2AY<;-$V%.1"8K#X6/GI]E;:]D"7S]_C5>+#/E M;W_O @0# ^F)K[N$*Z !8>+,6VPGOZK!*4M#929CJ3+S2$;+C>\;80!AXB&]BV6@)484VH/V0[;H1QJ)C;;KMAJRPM(C^YA?% M=I5 A;ZKSLUBP'E%($O";C!LV7#^+(!1/.KN+MMB4":\#6&'-P]E WM]PAA. MQK8^E=2(6J5L.$[<8R-O]IVJ53'053 1=+5$1CTJYP,7%5[J#'BM^E!5_- R MDZG"&E];L@1"NTIS(J9!EG%BG:7-6_IG.=YHGP,VS$Y]&35I.,<9E0&9@5Y/ M=@]>>U=Q/--_EK0+N'2F"2]2,X>(/-]'-D"PA7WJ%X/IU7/L!J9#DRIT:*4@ MX57@K$Y>KL:0(JL#'>1?PDZHP'V0=]XM=5HM_:J@J1';&>:Z>1)Q%15#PKJ= MHL*!7HYOE%)13$3#J+)N03JAUX/[C6?!,H75.BZ8=2%A"&\*Z7Q6?V"]7$%37\% -NH>NU"V-*+"@FHYGV4Y'-%!.H45EXN/EHJ MO[RX'1CIEI9WG&>XE?QC^($'9U+*Y\)P]P@+8\LJ.Z9BQ#J@Y4?B;+L2=#FL M@RYUT.6E9?GMJ$PLZX'=)P+L/;" "L3\\F(!$0EUT6W!2:+OG5Y\?@S&OT1T4I.PH5:TU[3CY$IP,N0HG%'0)?>H5>R54:2U56PGN M00J"A*JJX;')H\JP.I1V#S.&B%6#R$!.)=R4BV3C*7H)>Z1@]SQ= DRU[<3% MJ;+6C' QX2(K.F)5"RU9EIH\B>AL28(4 P7EGY; \>L-*"8[G!G@;):"0,+E!:@ZSCX-LIA8U: MO#'*Q.K$[4IW>TC0.QY>!FN#Q.=D:U&LQD:96CKEELP%KJ5D-_B.=7]D[@YO MN@M;=<,9_H9]^>R.%MYP0H!J3D>PJ4^7BP6AA@DH]%F4J!7?<2FN$LP&M MN%M!7R9((O42L8)&4HLFY''NF4XK?"Y,U4ADWI#J0B._"](T+U;\QE\K@TE! M_I!5DBV"[IT;(Z,LFH0VPE=50MTC: MG1<+'RB &^?0"L]TLD*C)4Z]D&L! )NZ1G.%>SI-Y=_)+39. N[5+1DCX8OE M$7%#[#13)0$0@\!P7!)IJO9/L>R!SON/X@"-^=B/$Y671_UME#.0Q]2KX0II MJ/Q0V0AK"KC(&3]A'(36+G"%1 NH6TC08Y-0:V9,#X72>20Z"%%=!;,E'JTJ M+=$.L? I:7L+8UG!Q[)"M@A_K215N!GL]T8' !C6.G>GI*R8)KMX!7.L'&%Y M'XB9R:&$&AT:]D37,E7:;3;0RQ?8BKWB'*,.@H!G4C-V+K6[H*E M9L0&^&6'Q2BG?#L=GB*9)'QV@N*!D?.0 M>;YL6,29@-K+N-,XR',[?5E'? TS8M%*2,$J-%I!&"M3Q7JZ,B*I!*"Y,.5# M4[JP+/KD7?-='C'VQ-84.1:CLUJ(.Y)])AO1,X:>(ASWH9M"IZ*$$2.)LNU4 MV*?0I8<5-D(LEG_%MB6G4+N%G*Z,PC)Y1%H"*U:R93N%0LQ&F6@NQQ] I,69 MK@W :I!*CE4US12ZL]7^/*8@FXT]LA-Y9"=SC)G('//B0H.; M]U$!;?\1H,]UMOG,B;XH3G_OO"& C/_Z)9_S?E'_P4)\>$N@!A MASY7R34_I*+J%W"2WX/X^'/-[3+H_W.P1M'I&"2(+-.LMQ.YPO%C 2Q-]GKF-UP2[]I]QU+-D]ID2EQ6T]W(YMK;Z73[5-GT)O_,9A M8"9<\9OL_2BX$?X^[9#:N2,R,?PB%E!92=^0A-92)R@ G8,"/158L*!4:EDX7U7XX@P4T" CA-0(18>5 MZ'%IHI-[7\\N+M\YA1-U/JG1G;V3BT_O7.>$)DW16:Y8+S*$:_.O]T[.+MXY MK2/G))&)9OJK$WE")JWJFX2TGL!D8"QT>8--]]'+//.4FBQW.[# 29+JU@\ MZ,R"_>I1OE&:&H:Q,ZIF24V0J'NW$ZO\A)2ZJXXC]A%1^,@RH"U[NUREH22_ M2K2RT5Z'1[GFEQB3_>:!(7C*<;Z5+GF?+KD.),K-31RD00V!*W*=)H^3S9G51R5&2K[0H1SE8>(D56(4Y._J-)1JU(%"YVD4G2D4*T8+HL" M/ZL<515:9">4R&14+!,IQV%T!@+_6/X#?BC9Y##&/%!X&?T:DZ4"77,5>'1\ MC?MK/G7"(%4ES*-1,%:5%"VP?A83:U/1)G*5<2:&3#P-(EWZO'IV[%]AGQD7 MI[T*L.@8BB6%&)5%SW5X&"=/6\Q88P0+Q'3"*85FBG )'NIZ$D^I%UM<2/5" M7 I'\3GV385Q"<<3_!1A,,%()Y6>D22$8%]?82JTXY)6INJ;+UXK@FO(=)&B MM#3)90P?8%>P2F)3[G8%7+;[@MN^DL79;9$'V-X;<&VR9:F,/EDU6K7"9F4U ML7::)"H+8W2\F@D$[.LG\ @U>QQB;<)]!/BD@>JVE,_P.W$#:V&%)1&X M>!&INHKX'H/:R45'6=R3!(2Q@DB3E0:R+1%;K,@XC_R%CU 8L!B&3/&G<1]57I2X*:V0. ;?R4;:E4]Z6 MRXI5\1TW&."<[K8*=6K=:F*:/0Y-S&MJ952.JJQOF]%4%8NL3ILE=/JL]^GNCS3BWJ^4[YGIQAD8SPMITI.X-_K5;N8/A1R^>R MCP/=4,:H=O*9K]#D%>]UE:G"I5!C'EO=:KR5IEX10;T7+JEMR@T+'B([VUVE M^EU2P: PE/Q5OIR P67_FUUE@(/+F,0M6^PN[-?*+IQ=B9OVZQRS70Z!P@60 M@H*9G)(?P/Z7?MFB+U^IJKBZ8%N4NHN1H,>8Q^D-==Y+"R+_UGDL!/JX@7!% M+6P[V01MTY!]#4,I:N^G,!78+)HR^+(E4E"@*$"=[#R P)PFX_XA'YKIVTP4< MRU#Y.W / FSJCDDD5%V<%4)A(=%"M*47A=*BS5IU\6C5+-+LKUD)P-V@S#ZS MN^Q=+4I+Q.8*D:A<&2\93@)T#N68Q%3\;:FC==$#Y"K?$A=B"V3_(5;?Y2;* MO#@[NZ%",?!4P;7 [)7M"[8+CBWJ/^*@9 MIAQAP]G8,T2ECW7>4ZU"2T5W!26J0(X5GVR,XX.+'I*>J#R$)<>AA$]LCU_D MA]".X&(0B(IS+^0S&/W["W+I6<_^_=#T8Q/M2D(>[O:J /Y&0Q^4GE^T;A3AHEQ93>\!1&$Y17D@>R1=BX-H#++-:YVXU:)40N!4PUT5V>D;9X:;M MH>PJE BKOBB6R,]365]6N6S#W*\>?2HV-4BR7UOR2=84%8RDX'MA^, M,,C(W7%;V$U1U* XP*2Y/KV"U2Z M,(70+$E0ZS-*#L3DS4$AEYLSO#,%9M;>(8LTK2)!"F[=<"Y@[H@O:S<_$/[I M$X<@Z*/6!]P71*(YK>-%^B793T+&IG]5B;#24[&L!M>*(+VC6T!Z2_%/SP[; M<]H2L/=-=[3>R!Y,P-=UB>O[3/6EI=)QYASG8W@QXR0[3;>BZ'>_T[>[?)GZ MW^_O6BB23X\.A"LN:?]+ C=UGPH*S%+Q7OWE Z;^AM[\?4!=;O?IH0_%38/A M/ESA-@^]4&X<[2%_;;P9C29[-+($_M]7;Y9?-^"K7Q<_/V@WVLU6Y5?-1O7G MRX9J-1N]_M%:0RW__."53^JNH7ZE0^2#!%I!FOO'F\X;X_?R4=:^;SHMH+5? M[_I9JP$TA#_]L.#4*U,6$]7CW,BCN]@)T>OY=<17\0^06N0/@C_YD]_S(/3) M+I67+O.?-'+SI)F-BO<;*9 - M?XZI$.R^G-AP*,1H]&'M2P_'\EPZ"2WUSXA*.EUDNB3KMQQF%#O?@V&\E/FU M[UZY5#N0S #E7Y=M0JBML")%.U/52/ZRF)8<4MZG4.F.F5M^,1MP"_EYNQ MZA8LO6)W$F/E%=VI(VVU6O61OJXC/>@>;NB1KBT[1O2_S9<=)U[D^=Z]A$3E M$C>2ZM?G\M&GDNK]W('\VH5=NX5=V:7UGR( MFKY=%-7NW$_&;Z%FME4'T^O6Y[*)Y](ZO*=2_ PL6(4?HC@2R\]Q6WY5+W:3 M)E@OMEYLO=AZL1L[P7JQ]6+KQ=:+?;!/6-D?_*GK?KNLM,/>/1UEC[9!6^'\W!5R:!VMZTVIR>$5DT._<\_XQ@N3 M XFX7PE5:N&PGA-O^W_%_ZT!%);KWTR]_NMH\=" M0Y=12M7+L]!9S_3.XKX<-=I=7'&KZ+I*G/AAO8YZ%)G6>::"&^<$R@)[ M3%&RW;2JCR(K,VY M<)CW(\ODR%-=6 P2_!TA !5[C[>YV*_="UPRN/JRFO^!>O\7G!W MN8^Z&M\67?:OF&#*-4A!?=SY3A[MYF-T\N@HIK&'E.J.@=YS^L^Z39>:X+>J=X7%A. [7-_48OAY??#S^;]V\@PM8RVT@]L*]C.?3 M01RJ[/>3\XO+ADI[/\=:?+.,\H:9JMI]*[MXXH$1VG0/FQV>@>Y8CP5_@)'Y M6V1YJ\X),'=?4D2*.ZH:_&'+/C$,/5FG?# WQ4,+14D;JG2 H]I8L$J)A:&Q MZ U:Y-8+6.E<['2I:K)S 0O5W9(:RS><"S,G;F-!U915)<^4SD:62L16X30* MMQ3FVDZJB9N9!U4]1\L]H^[B R\--K/0]Q*N][ALZ:5ID6HRQE@TG\II01ZV<3,Z>C^G["=FZTNN"I?=O MAG#[L;"EDT[0JX/U5=^]MHH!K6ZC?=1]G#SX3N.@V]FTY/Q.HWNT<9-J-XZZ M[0V;5+O9:+?6HX1GV*E>X[!3_=6:M176+Q'P""ROOU)J]#>JG;M"581B]&EY M9MV*^>*;G5:^VMZQW_VK;OI[@:PZU<)PE5U]3=MQ3(UZL)0/E:#V@#A0@-&N M[$;9C<%,/C*(ISJF#WC4MK/Z)'M]EC1B=:.59U8 M[9R_>#?!-)\Z'TG#<_['"W-AG3<5;/L"QL#_"JPB9YV_L1!+9[V\=,7!HZ:& M/[.D6A$X@7N%>?[D7/G//!+.(9O$JTBO.N'^SH3[I@O#;FC._2.'HKG]FS NS<9@LT\GOFDFX#[=8:LV17B]':O>/-I1PU]8?[UN^ MY@7VG;3"(ZTB@MW4>X"*N(M%/@ZZ]^"Y=0&6YT&.'[0:+UF#I3Z;^MYLX]F M-.ZL6S?CJ4L7K>"PV0Z!"S+V0 I<+H;NM%_>*[-5Y'G0N[^9LR&6S*L]FWZG MW[AO;='Z;.I[LZMGTW);A_>LLES;N+=OK92RG:+05#OZ!]W&07N'+T?--6NNN2H4??7G M7T_IH\.Z[M'2ND>8ULG95E8>UXP1N)B0B"VE;;&N&[!@GCSFP,YG2()QA/LV9 3D9UR6; M4 DUJFB0B"Q/(BQ/ED_Q^40$T95(L\4$<*H1X!2_?0LWC@JD<;DY._76=2[^ M[DUG'[XY/?C-&9#D#5<=PRFIK[Z+S MT.C[]R %.+?-S<<9S@:FXHR2>%CI[ MR]S[E@N_!(5A/*GL^]UP+N]X&6Y4$F":-$TZ577@U#/L5]#E$O 1RA)!F30, M8=>"4Y,#$@E)BV7WWT>Q)[/IZD_N0$YI%C%C*] MUSG%*29Q% RM7T1P1)B]E7FS$";\1:! C'R8O?[1QR0?ZW]\BF-?_D,D*6\^ M5ZN[F DL^93-U9ZD^0"5C1QKTHF5L]T/EA%_,!T[:3)$RD^S?3R)YE&G^7_C M5N.OV?B- V_^QYO>0>M-26IV>LW9S7VRG0_:[=G-&Y8Z^RW2#]<41:V#=F51 MJ@V\VZC+!#XI)2;W'32AH4BHHH(GD_Y2#ZD$\_UTQ42^6Y[3:N[CO<(O@WCE MRA2]U:K:;$>B>[/1[:S7.OX9ACIH]/KK)8+7(]4C/==(!ZLDWI=9.M>^L*U] M*_S S(%,OE)Y9/E5PKRP\KM;BBH7W00+U0 >/(-[)+M. ]\/Q7/IM(7L[PL2 M!*#A.C^4(/A_*[1>W_9=.EQID_9X=\XBYXNL]?)NA;U996MN7?Z3NR'+JZ_V M0OXO:@'G,Q&M51IADU?T-S1+?DQ2J\;1H^6VUS];[V>K,(<[6/7V7;1J-K,B M$&PKEM);O3;-;<>UB12[;3^K))L7"A&OQI^718A?,I2[VLQ;1W=DK*RC"CU! MO^VM9Y"K\)6M6$JW9I UYWM-G*]_.X#EL0$%[277_:4@':OM4KMU1Q>I6CX\ M3#ZLPE:W8BG]6C[4C'\K&/_A[0"UFO'7XG%U\5B;3T\J'CNO13RNLI#=$X^U MW'M&CMZ[OO=XG=AO4NK: =-&OC^4FU@W:M'6RE=E"+_><4 M^[6YN\HNW5Y'M=XE=IW<+M#J76+!5"O:*^Q2^X["3;5R]##EJ/5:E*/F*U&. M:JWG&255M]9Z:JWGL;2>.A3R<"19O4L<,*KYT@J[U.G6NN%3ZH:KJ%3;L)36 MQCO.:J7O&450IQ;4JRA]]2ZMHL[<+H+J76*4T.WE<^M=8J7O]FJI]2YQAD&M M&J^P2P=W-'RK5>,'J<:M57#,V[&4%U.-:YWW&25PNP[)K6(9U([.VM'Y6.'= MFI96T7EKA.##@^#U+K%E4/.E52R#.RJRUY;!PRR#H]=B&:R"#%G3,JA5_F=4 MTVK1NM(NU8;1*CB9&JM8&T:/91C5N[2*850'EE9!@-1\:17#J XLK6(8U6BB M)S6,#F6!_]_%*$[$*[&2#KL+9M*Z!U;;/T^CC1W4H(-5=-;:3;T*S*>6H*O M?&J/PRK._)HOK;!+O=K^645GK6EIA5TZK&EIA5VJB[6LL$N=YD;D(ZO7R;D= M+;::>?Z\AFU(KGV=/ZN;3>C[24T+U^E_LLF+Z7<68*:U/ES M>D*>1?^IC_0YW3;/$FJLC_35%9RNCW1SJF/71[I]1_H\$>?Z2)_3(5LSWM=V MI ?/DDI;'^ESNKKK6_K:CO0.C7?S<4F/ZN2\I?7Y)KOR$/^T>C[%]BYRE>R7 MK5_D&DW,MG:1ZQ0&V-Y%KI'CM+V+7*7_P=8O.+H<-0?] ^:S7[W8.0/ M6D>BU>T<"/] #/O-X?]U#][8#\F]L?;SKSS-@M'\<3:OU;R+U[5Q]\XR,74. M_OZWHW:K_>&[@%&NA*_77)ZL?/2P#6/#?@59$ /7%J&7!5?BPW7@9Q-Y*O93 MDB*;YA%O #269\L?66!=3[0I"R359GQP<0?L_ZYQWGU]WI/$^]\-J;I\CSK>5/@VC?WNOR-BW=C-'HD3>#[[LOAG'BT='E$3 +_!7, MQ'OA&3B31(S^\>9O=Y_%X9O?+O'6XOT^@1<"3:7__JOWVP*E\\[^]N^#Y-=' M^W+A&DV]9 PG+.]%'S9!?H(*4[_(9%^,*1Q*IO#%BX!FI[!C_Y8Z'X&CYFD* MQT L]SCRPGD:$-O\%$1>-(1WXP;[=,_I-\!4\C"CGYS/!)]AZJ@=>KY+O>=- MXQR.W0DB!P8-<1JN(VZ& B0;3,Q))UXB7/4'?(*TC*NX=-)G*<"Y ,, MX_A>YKU;9)2KL89>NTH4;#I9G/_/Z??_.3O]L50\;,X"JDG@:4AY[\M'RJH\ M?N<$2%W 7'Q0*[+8F27Q-,Z$0QPKS6 (T*7PZ6PBG,0,%IO!\#4C_?JA>GW# M42_!=\"X5P&^PX,'G#2?S4):%;S3I1%2H-30!TT'WN+Y2/$PTE]Y-*2E7 ?9 MQ(GS!#\D7<_+A/U6F&E&X_%T<++>D+2B:(X+^ IK2G%]9I\NS"-[W[PD<\[. M7(?8R!&O%V;]"50NI]7<_Z]W#><2/T@%SV:;19&_@&-02.2XH)?W_[A@\G7H3W'/:I8N_5&WOE-W9AR!$P#OA7<F-Y:U[F>!,,)<"O8J""$J=)AX_(OQ#!/X 62GYW>\*KA MO=-IP).#_SL?9O$ UG3D\IZN<==?^'+_0,T^# 1H^-G$RVC-TQA,JV ZBQ.X M?,"S$U!3$R( V$6X1:,@DWH^7]TA7)<423P2&5MC( @\-'#RT$N 0)5M )H$ M?=UPOJI?XN-A[J,-05<+[) IR) )WGJ4&D"*XSC![=\;Q;'/IY ":\#/7#!( MHGWZG&_P"*AUXM '[UQ+^""QA#"7N;,W]O#R1BBK0&1-O>'H$;/ IA=$,%%#T,BK7?\>0R;EH"E!'L@Z!KNB7U8,JX#7J,^ M=U@EA[&R! RJT'H6KO:I?H(^+CVD;%QX/[P['MH7U)O!DG,8<)\&WC+D*O08>8#:&#^S=QTD2Y^,)B"R?AX(?7P5(6=<3 M06L?Y2%PK;#P6[TH%P\[2P(PY)%9,3T!F2>P2VDVC)U+28UWK;UB6Z<"!AXR M76H)CDO0LA5F&T0C]!IH'HT_CN*,1/ &%X&%BV]TAS+#*XQSI-D, K1Q(=# M%\R5_VQ<-"SA!U^#*HKO'9**B0N VP T,L.A]NCGGX^/O[U;D/%7@;@6U7)> M2;U$(!>\92(XYJSL;BES"9V8QV/!'_S$4TG#-%1N): MTA$<'7ZOKIU6+$@IQ[_.G70F\!9$<&?AW"D"4A28%G#GR*#*\'W MGDDO2%$J#N%LO3"-<2\*W!H.+,3)\/T?"I "*.(]D'%)RE("SW @YC&^F#6B M+(G#]PX\.,QR(W9!=B:T+*'D)EYU.!6UR3-09I!3X"A(04E$#P/9&&6##PYG MQ42$ZHI0_Y"L;8@B"R24XNY,:6D:#_D2X<(%T!KR,*VBI,S\)B .4;[10DKG M"/,.@;-<":E_ OL)0%=!)DZ"$O;A6M!6AD)N.8Z3"K"4HK&KZ)2GXT_A5L-= M)+^/LW?Q62G P"]$E IB)!JJL\.Z(M@(.)T;U H<+XVB\#T0P;8"VQWR= M> 1H(:CK,0GBD1M681:$ X#,#E%+9UM!P$G'4RD I88G'#_6PL)FY_3 : 3T M2.IC-;F!Y8LD&Q#GP2?^!#8-*R!%OJ#6R'GA0<%?09"SYJ=D.%P[4+!@/?*2 M*?+$5_!,8457 0@_X.%L28/IDL[0,(&-'M*0'GT(5RIBVAB'\0 U%W6'6!@E M8LPWZGH2P\Q@=I*1) (N=D@:B;T-<2KYFU%BK,O8<'Y,X"%)]7'?0)! M& #1S)&!^P'<;$7^\B2&^H 2VWHHKKZDD"KB(?]SF@.W3U,0>*"?P54"W6"( M9^$2?_:]&5$]WD"M0+$:@LH$O]#%029XM;2P]%'Q9C-,LB*D:+H&L$TVV4^# M&WNS+%:.Q "76&2)IZZ2'.@*2&,?[I((%>M@+LXOCR-B5S%0'FJ;Z1:9#N>X M/B"&.(UG$S(%V'A'(YL6KZ064=,_,3H#%L/8:/$B03TF169B\V=F)T!H=%>1 MQ$8Q:*N*U8/03#+B$BCTIMY-, W^):4^C@:'E8R%[U+H K5UM.53#&S ]*8@ MRDB<79=X5*!9[8PU%>!/X\(JY(FB?Z_=_* I)(<; P;BG#YO?:#O6_ G>@F M0H&JZ#[@KB@Z(;9KK_C* X$+*\8=+6K4-N^0:I86SO )RFVEI!LZ592KYLA\ M=BP9(4I=F)O [2"Q*:E8D#C$VV_]'B6;M-!X0Y7V%L*NLY8/5S9.2&AH#PGI M?P%N&KR#/(-T/P=IG Q8+-FO==':P)_OH[ZYGZ= *1A:@M7HI<#CXP2%1^)< MQ6$^I7L,KQKR-90Z .A$B;+4F>VEJ"0G4FC3Y$$_0 X*7X",QC]GH"8L3@II M2S(#20!\/$%T)12S0)>HQ1S4=D^]N=HS(\\E<<;%1^ -9%W+$T>]6XC,9HBT M%F#F%A;<3*7N$:FQO\3O'1"!VDK(5_MG]* MWIV2XHI(4L%75[5*C/:/I$%(3PAMIJO@(3'=5^(]"85R(G!VT6OAV- MX"S(6-'6+RDH:BN+^H!@.]<7($+UUV!SQFF>"/8^H0\!9P&R84^J/F1^91-4 M2M_16[+YC,T,]K>R)8]NXA2U+7:03JU0C9QHP_D/-K#UQ!-I.8?!3Y0XL";/ MAWU(C?C!P?GUJ'],47UBE5+Z9;;HB"T'.RY .RBT@<)V/ 9O$CA2L)&"$FFG M'T!]L3Q>$Q*]U@59O,MT&OP+Y6503@9'R5VE!* +?6%6J P>*\](R:[1/V9^ M.CO7%!FTMNF0UHMR!:E'.6+6Y96*3MZ:KA1\#Q-']74TE(F7BKU+R)QZ6/8 M+@(FMB\=F8MG@F( ]HD#0-<6W<+.I"4NC2=$S[&2;MQ,^"]0: /IK HRHH(A M\C/B%7Z =P/N/ID4&)1#T $8E0DZCV,Z%34?>@Q/3+J_)#&$>-ML?Q)^'4?$ M]D;R873A,/7 F<^4,X@\!LK3)#5[IG-VTX>6\[P8'[,OF_;F6@$'BJ-Z410, M$%:GKY@T +/*9\"BB=2.P_2&0S)++&>QE_P4F;17D$O3B)5;I>,OQ%?X*J%5 MXT5S)2>*7EDY-HCU7*@(3SJ%QS$$@V=+.@0:D?J7Y+P2=)=(7'D96Y[HJL_% M%ET$E*'28IH$,X>C&@J\,$8WE^2HFK6S$5YPSE((WSR*)#^..%J6" J5#-5; M@,3F7IC-U3#D5Y'[1D$#04$,@;M( AZVA^$,QMFI+JTF7MONPU4PRU3&894; M:R'X!X_)8TWA%-"9@I0#4X';#YO >L$4;77VDVJ71;H80)9$:CVJ_)_D><>X M, K%,*!!83:_J[W5MBMY;F"^04A6O!=B'(,F3[0V]&89,(M4O03V/$^,QPXT M+?0.D3B!*XK'C8Y&4(&R"0:B@C@Q2 B,!>&C"/W@F<^\P-^WME/N,]TZ] ,, MQ()N@^@"O,$%U?6.NXP"R(91()\M7//K. E]]@9;>TE[L_AZ8-B+4T8_K SU M5%YYYM=+5 *+,LC!(MV:1<Z5[G$=9I0N M99">VR@3/'K@FM<3&? X 3:B/&")QE=C"3HI=L6Y.P4]AH'"U"? M4/A"J2C":[^3Q; 8/^"-46$!C#"AHY&\QX._$$IUQ8Q%>^K4O!Q@&Q':9YH] M2O$.OX.G8-%N*0ZGG\2%IB.VZ!P,[08)L43V/:O G-X0#!V&ANO1K<0,:;0@7$HTM\L/*\Z>7 MLJTGIY_ \Q364YN/7D1]??E ^N=L/>_"WY;0?BQ2L3^1I@W76 5!7,=Q$Z@ M%]Q$@935RZY:[=.UL'86PHXB=*CFE*6S>5*@8(AX9 AET0$_:_2)AZP'DXK60?A\YXGX)6'2-(D^&-M'APOY10](VFOD6R!'#L!#5 M%]ISAI_']D13*6_EFH-4FQ^H98,]1;@LG(%91F$5/':FHK684D<6R;^E)<04 M&WB5>UMV.,4V/.91IZ34#WH1)7^,$>X9-33N&N1K@LJG+\TW'7Q4@G6D#V[G M@X7=.EBXL:)YQX.%FO=0U+_$7YX?[(L8VZ<#[VZ/@#XO);&0TT!R\PL@<[3Z M0LS')MOY.!_#'+D"5Z>%/%H+4D[$.>!D%5>E@7=EZH^2R+UV13XX'WMA[*8K M1RN^T1[] B':J&?QE_Q=UZB,=MJ@H03:0P?F*26*;=%Y M8ER4O%M6>I94M-^ON(H."DFN-L!5"MIMK#E0L3+^** P[_O]UI%F4<^S5H+' M'7QX;ANGN#FM+FX.A;30YPHTU3XJQ:Q*+DMRL5O9'7A.'I ;\CJ0#>T>,;+B M$.^=UI&R?-BT'J&>*WWORLQ6!I",G%_'Z@>W&$MN,9?N<+VYP_AX(S_4I/6$ MI%5(;*.8BN^TFK_@>;UM]P_==O?09DAR]6X-?$7>U+WN)+WG/[S<(5IU@=!W0Q_+*?8_1T M6AS.PD)34&4V3CR?%;6J\&M]U$]YU)^7 (442,B7PK5P^1"B97/\PK>5WI " ME(I=*CKIJ#[@ISS@]?!=UKF7CK5TZ)@H:WU='_I&'?JESN\CI[-W(Q$2$=M= M6/H!+-+#7THZ=J\!?+W6G)])<^:(J\U(NRQ5^VX;/0QOV\W&X0&YGOT G;N^ M*CQD']K;([?9[\.O6T>-=FOQU_H\4=BNX2ZHSW3=,SV+G&/@8\T' MX( ?*?2&V>14O )A*QZHR[\4;"%\ F-_8 =C"1$O1>P08N B?R-]/-75GRX) M].Z<<0!D$^==34:_"YA/)+/K/HE!DF/U%/;H+20^JRP #?$GGSO]KNC'.)V* M9$P% 4Y51O W#.2FSC'(QKVST]-OQ^\(_R0=@S+70*$)I7XL03BI+%)#'EX5 M1BPF9/\0!-&CK\96L@62W4V PP)MO>TUFQ38QM>;M(6SXL(/7!.GO,AGB9AB M%: \R9PDY]H;,BF^, R7ULRCT+L>Y2$66PK#^)J5 M 4X%&J$U":7^CET7!" MUP(F"L; E+,DN( NH?H'8D8P4YO4XSY!]6K"0,AC\1C_SV&E(DL"+/B5CGL MCTUYCPNL"0:L)(7]]PG.1K[_O>.+DW=.M]?<1Y>TS-/]C&\XT6_ 4C(J4Q=X M4#R..'<8_PZ[+U-D%^+>1>21%2>.(\QJ2KD2!QTU\"^N0NM\9)PIDP[!TL8> MELH*58T5>7PR774H F2$(+2Z2/ ^4,T,W_:V==CEO%WZM4MS370=,\*M,=PU M7H0_\7UY"XJK_12%O46J$4[.L4/05@;G<;J\FMPU_1Z37CF04LYH)2R:RI"] MR I^IS!0YRY)M-N%:1)1LACG_G"7#RM/<7Y5N;@G#\ M?!!9:@,E5-/4,@W:YD)G'L/52\I^E@!-JPPLSAB&W4J$_,2CG>02/A%<<(9O+K_&NA,1[RT/B:U2)[-4%9.LX M>E4AS6=5_+Z?7OSYQ^6%<_[).?]V^OWX\NS\Z\6]*Y\>W:?RZ6.OE\9YC^C] M8+C"#NAR=MIENQJ&/0F7V(4*M9JEXK_[R <3;#'CN^X"2#/;IH0_%S4#3 MK%1CG>B9OS87N]'DRRT+Q,LWRZ\;\-6OBY\?M!OM9JORJV:C^O-E0[6:C5[_ M:*VAEG]^\,HG===0=_2;6+.IQ LUA#BZ7Z^-G5CR*OU57MF2BWUS[NJHX@U_ MC@D'LR_G-1P* 9K!_?M16,RZX."QW6'< D,;E\KS]70"M[JCQ1)Q4VXZN&R/ MEC;?:2XT]'BA?I$K[L-"PTA-*>V[*66-73A5[[O'I04F+6E^8C^MQO2_,RJ9V=B\>^K9?M] M=N^NIKT[\_RC*96*#_7OIDBXT<]*31BT>0@C6HGC;@JO:35O;[N][H%N)$/] MY;$E\JLEAWY-#34UZ)WJ[APU/)J:M<'RC9)*O'M)N,K5;C@1KRWA[CC2+:#B MQ]027QLY'-344%/##E/#+EAP%5F1NV/0M7=.::M5^.4[=5130TT-.VS>[X)! M=TD5!DZX>W!MU[U>W:W6Y!]/T-74\)JIH;=SU%##O58-$)?KICQB]N,!I7G> M-9^*M Q$+>QW&A5(9"S#R%#^O=:[9TW4I)U[2!!]%0U[%Y_?!9WTWD'T;90V MM>Y1ZQZ[[%.NJ>'Q8NC;3PV[$&%X0 Q]&_V&M1>Y]B+?W[BNJ>$U4\/ASE'# M+MAOCQ5"WT:5K8XLU!K\3ON2:VJH?3V[9<\]/(2^C:I;;=;5BOS]_98U-;QF M:M@](_\..:<*245Q))9' ;?E5W4^^7WA DM+M2\VZ]B7S3KF5;W1:MC!$\$. M5K%*=O'Y7=#C=RIW?_<\K[7"5E-#30VU^KZK49D=2]U?EZ5MOZ^U]KS7GO>: M&FIJV-4XS"YG[M?^]UJ!KV-S-374U+ KYMQN)N[75EVMQ^^R'E]3P^/IP-M/ M#;N'.OB5>G ]9Z_ _RO^;VF+L0(N 1M\]XJWY(F;-I<;_50OYG'C\:N\\T-A M7XX:[2ZN^*2,B\ .FMB%B%N;PA4;YB$U1,U3!$M8.(I$9%X0PN_$SUL:62[M M/EO5WV^3^]A^51T)K*:C;]N';J?3^PT6]4Z(2] %?!KK#MMMOM'>++CGYI. LG1P?&Z) K M['',F!:8Y6"NQZ:!>M3>W@,>BKU0@8_^A*4AMH7:<3OI))[-\ MF$1,O4#VAS8SU8T::(%^ N^.\(W\F>R/W.[1[R)Q#;]*Q"3.:2HS$6&GW0 [ M_N+/L TLS _[?FU1@^./P1@;)(;S?1'AH=>BV.@=,VDS_B2BV-@8>-(ZQ6[.KGF-*=+"U MK_FVX:BQ#:7!E@Z#,,2FWKBY,7DG!\C/1)J6YM%T6_V^ZQ 3_,5U0KX^&O1% MK<@G7C+UX%9LSW[_!_P=UES"KE4R"W.?8=UO.VZOV:+M:'6:S@ V'9\*(FPS M33VZ/:?5_J7 $)!B%6^A]V#C97AU&,81,Y*K.,RGU"!63PC^\*US.(2M7Y@< MGG=Q=BVWW^K0[ Y;AVQ%[V-7U&2%TVN!<&K3_G3[ MI<,KRQ_L?U[AMB>"IWAU !MBNJ!7;/!J;6T/6EO8UO8+-SN?!#/GD[B[N>UM MRZC;W=XY5-WN=ME0=;O;5[[DNMWM<]4_?.X@@25"1K8(J5O5[F1SR)[;;]:- M:FLB>B 1==J=FHAJ(GI093OWJ'VT*(.5>W_S#>BB9 6+^4I$N;"<":T6N938 MW68J;7MM;WOTUZ-^X^@7YSI.0A], ;'< MKR&WY+"->9@+&8+:&OREF,(I3[%I'O$&0,MYMOR1!2WR60_;,@HXI=#Z[R0Q MNN]8[ _@Y'[N>R.8XGLOO/;F*7(XFY*!C.UM*Z]XZ;I&HT=>%U\A7PQC=J^\ M!X8C$D[<_'?OA6?@3!(Q^L>;O]WMVSE\\]LEN3> \D_@A4 >H.AZ:\1X;@D- M;3XC.L;XCK@*XCP-Y]J?[\)-MYB1%T4Y\( BGTF7L #7 5DCAL1E+L0L8S[2 MOXV<5.V*K%V1N[;D'7%%:B!+[83<;=._W3]TV]W:#5F3T;X0N%8LDDB M1#'GSCE=DK5:3#MT@F@4$L@(H2DZ8!R>?DE.OJA.A6,2%NG7Q1UTKCKDP,=6%JHQ06-L !8.[VJ_0>WI'FREB; MJ?<7_"N;XV)I4ZU$RY7S6_%#?'C%-W,B=ZYS#CGIF#+#*;-P&MQ@PO+*K^>G MQHFXQG1PSQEY:89P2'@AC._=L0LGMTT4,91>F,9 1F.OXI0QJW$8[P\2>!;S MLA/A!QF,D,!A)?$X\::X$L])1)J'1*LP2_R6W+'P71H/ ZI^0,FNDU(:+:VL MX9R=GGX[=C*@B!$., +.!42"E T#!M&52#.J (!D33< II$/*8_2!FY5I+S" MBPNW I94=?&V)]L5:;JPHKM(<2(B1]S,$B0EGP_+8@U\*X+$B:^CA53[5F^! M.8@B;_"&-)5R!OGGT@17IO3U9VL8:JM;RM U3$;>Q6U/0G_<3.?RO7C;ZAR^ M8%KSX1:F-5^($#X4> AA>?_^Y-9Q^.424J"I$Z+KFKL8!6OUE'E&HJ>AA0S.T?U'') MFHH>" YRCUK-W8A++@CB*M=$M"PMX-6&(OJ-UKH-UK8_$E''IFXCB'9-$#5! M%#A$=^<(8MU8Y;.G4-]>6G8M66<[X(NQ1%G$%T.=,:>B.VL.O:R([])P*(8D M@ 4=+,8YXZ@0\FDX]_>EF_C(XG+(C8X52Q[J1E]WJ\RD8$'X,CTHOJ'JS:D8 M8TR-@YL4!\1=5(_3@N5/%@_RODY^X /]+73ST\:)-%.^_(=&C&IW_F9XSC=R M4K4[OW;G[]J2=\2=K^6(*,F1G??F/^;*-]$^:'7OV8A^C87?PT1:(X&Q=OSN M(MGVUC7>:[*MR?;%%]PZ6#>'YKG(=LM0[&6%Q0GL#ESD)&&OP(6(@CAQOL:9 M1$N/@@BAGM'8":G\:\/YA#A=!*H&T2A.IAJ_CMX&7PPRQTL2=,F04P+K*XZP MFJ($4,<1G06]3@Z-+HP,/F G1A"AJXC='V?PH7/$8%&8\'>J(UD7?CTL[D"Y M*.BJ'IS6@?;@U/5B7W.]V*HZ7T56 WFWW\FVD9.J M/7^UYV_7EKQKGC\NV%T[_G;%% 6>OJ&F:.U!JT'$B?P[ XE>FW$^%MSQ_L5(=P*( M>O12,-3Z7.XH8_QRY_)JS4WIK+POWZU>=M:&Z*2O]EPZZ][O^ER> M1T^Y)R!IHY1AM<7]S6/!)8^?*7=4R9;O6KFT3V3PIP-K]N,<0TEJ^CMHLS[% MUFSB33ULK2O:GF!G7DSQK6]&?3.6NGN.[FELUS>COAFO^F8#! MY[M#3POS70W8>MA\'>W.OR7Q59#B3<=K)@&,E][- PJ0UDG,FXP:W,A)U5#& M&LJX:TO>$2AC4MFID8TVX M6TBXG<,:V_C,JL[I:(3>I2O2;\C[M@*<9JM0 .UNX_!6JMKB*HQ/@[K;KN/M M-6Z/'=?'^SI!E=U&775UXSRY=\:1Q(*\(1M;QX]&WE6

,*:? MV7T@09?H-3)BDK:V;^52"\F8)F!A;-X_?S?#DL+8A&'=PRG3#Q T(4O6\40P MI6U4W)1YA1:J M&/;RK[#UHG2>Y2J(" (HH )B#0141$04*(B'8Q*54."(+U$0,!*4%14!*0K M J%'143I!"$%%6DR40@C*=QPOGON6[[O/?>>>^]I__MGK5EK6&OVY)EY=OG] MGF?VWK+)=IP;"&0@KK*^!39:TKD*J'!-9AN49P-:?,0*Q2+Z:FK#XK]S?X1_ M(1[4UEYUCP[T1=GBJL8J^>-]>[V00:/*+:BU=-_>/=E3-0NHJ<,9E M))FIQEB8EZ#SW, ':YV.FVR=Q^2@%52RSTDO"X_&EUI^#;HB/X["&MXJ5#D\ MF8.#+DAH"Z&5 &TAM95YDW 2$1*X=O/E1-/I&D,U2*R3J3[L 0X]D:?4O4S7 MJ= ZKK)30;4\*_T'BJTTCY?EOL4I-^\."9F*22?A:A;2EO0OK1STRS_@15-L MN";FT!)E;%9F..>F$2/&E?3E/$>H\9X([LA K27[XH]6)Z>0N3V%F=V M'#_0L:1MM^<;_V+7/USF'(,26"X8@!?]=H(%'2YIMWRRGVANU?,9&)PV%8@SIW.S',P7D;:E!?F@-^;PKXE9O5];A1('E M5>!/%. XOMU0/B88F32AEKETP\8@.5!8Y]Z/(_5(FA%(X@@6K0+-C_GWI_$0 MVU52.WQ1*8&[4LR5AHOC/@3#6#-Q)H^?4: #&![LM'Z,7'CZ?T/J#X ^&/V[ MZ[J'&YV*/LU<.O,A.-NX/<++7>A[9I,S$#'@CF9K(Q1X!'8 OCP(!V] OMR$ M0SC*4;Z'MCR2W.9+PZ](6*\"L3S'*8)/0GXS%>(L62D=_7]3[-COO[1SQ?UV M!W?45=[['9G.L8E^:JNL_.28GEKG"Q.^_L.>Q-_D?W?](<$\V=N_^U7[W_TB M$/3_G-1ZQ)^^?SS^OHE^0G#*M5\[X6AJOO+]ON?(B+"9$-=_6_/Y+R;U#)Z* MJX&UPA(0(D0HEX&FUR70"+#I\Q<;DFK+9PZ3Q[PK2ATWB^[X(/ZY4,B$KV]V MY?D'$[WQR)K95ZU^09I?^]KXM_V<.S*F8;T\7IGH\_D*BI3,EH=QQ>19/#;1 MZHH+?-5CV-6 **7V)D^(#Y[5Q^B ?.=L<:OS<:\\KM;M MV&^Y/U[+->04>IWA:(FME8;!%[^N/HUMHG%8-6XWLM:,Y#+2/ODH@67'?>]C MV0 NI+$M(K2JFNIW.QX"P0/)7VXIRNLRZMRN7PM9B5[KO$&DU,'F75G(&%\Z MH1T&J0=TH65\@ALN<"H\^BK"0B.4NZ]K:>6\G9E+REGW]ESGP?[KGSK%X-UP MR(P7TR6^#JX"H6BU3I8S=@*AT@Q2VO"2P7C5DJM+#F=JFQE^&K(^6&I7 M<29PU/:0S!8 'C8]ANG&4=]I6:\"T2R-R0< -D2W*>K0!>J)BOC FSO!^_V MK]H6\8'(#43JUPHE/%2"#,"/"K5N7L&U>=/'<4<"N<13AT06YU'1N+_P M&VOCQ?Z$[,:054##;/X+RPS2P4WPU,N,%LM\^&6JG%+_XKU%0,4E)(W,0PMX M>39%>JW^Z)Y+NP@+GI %$_LA@F@XZB^UHWX@X^>_^%,$:',O#S?)A3/"N6+1 MK-,SUL2A3AHNA;FBP]N&452#F'/#5_F;N?0H*3Y4E?B$,$ M!?;9@4<_8:47M0W.=\:._Y5OP;C24-#."JYP 6TK=S2,)3%=ORQ0[XAX29\/ M9K^>>&9@>,*E7Z'B*!C-WEC/%4%2K0@@S]VT[FZ6V&$G^,84GCPD7]Y,*U>/ MZFT.1UG_U;.HE"3@_%"C.-I'&Y#%1(-R5WUWVQ3'(-X.!S%_T(][1,LYWMOT[NRZ2T-4S^_>3FFH,* Y2 M(J18[K[\),A]6#IHI=CEU#90K[;FD7S&&T6-+9V:$9^V1[V2O)I&_-V[\+RT MG!JA?-?EP"V)(]K'SJ;O;^%\K']2)'GKOY@7_0^3*OW#;L33/Z UL(#W;E6- M'H9:_6=;DG6JIV _C_SQ*Q5 #PO M-$]BS+IQBMB&/&KZ#2QI[\V\%=!:RC'7MYDD9"%@D%*LO?M@F+:DJVWEM;E$ MV8\>[R^P4]OR_+(<'BW!(9T%MBR)*0&YA($_F?*.F%FNZ%H3+CP:THTB@+A.'RD>CR30,,V2D.?CF%[;W(.O M&.XET29ED8_;T5LDZ[IE^FU?+'6<4.YQ6 5< HM@K_&CWLSLRE4@?ATF$EI@ MZ7)'<,*8R_)MOMMR'6\/J9G8K;AQOU#SQ#^ M/Q7FW5,)(TAJ)D&4NX,=P7F."R1 >E-=/-=-7HC3;S8Y$>1EV+8@$O/TW5CP MM9APY_IC[C^^\N>*O#1JH8G,JF28:73-KQC^K0R6W\R$,.C3%!,I$=ZF=&*^ M]="CRTV(W2I7/ISUTY']3*RKC[,4>L!]B]T]$%&Q?EIN>&/@V=.%%.=45M_LFJ'Y/^:W%#"C"*L 8OLJ0+EG_[MS MU\-6&U:!@*!5X.E9+.IK_1V1SQ1\G:XP:DZG)^A M9N8^_X?D'R (]U_H>?X#I1+I%GHF@Q%Y3@YQ(6T*PB2-H#+/'ED<.GRC;*R,'54DV;5Z[UVQ:^, (]V@CR2^N(6JM,%3N&^1X$.E#CS MDGD]QKKW+AJN#,E,Y*BE/&W8$MTT!-_H=.6G,'6;)E_>&8E._Q@;KG KXS*3 MR-B#[T)!^@7S%N<942MDVMG%BOAFB8LU%7S?CF2Y8=\_]!^X"W,,T'70.NY0 M _0J\Q"E/R:,Y0;5\: RGKW1E7DL=]*_.NA0E>N(F%>-"390M-O#]U_B%D3J?, M(83 N61(W^0&6+ >=JW['.Q6D7SZN9[8,2I^':1#*[CZS)(?G&Q=024OZNM^ MLGX42#8@J)8]?&#SX+RMU%.[XH]6LJ56,B9H40C5?LNY[@IM06+DV#%/J^>C MHYZC#PZU2F7HJF\1?0JL_;D1_C"MVQOE_0(,\C2<@J3A=?N-/R9TS0S_-KUZ M9G_ZKN4_J:[]!XCH:71$N0<]G=;-SP:&KV[?F&77[UV+_WTU+RLEU"@9QX;: M5P%L(ORW4V=;P.:W('KXM].C X?6(_^_+W(<-0]G]+=2JF%SJ\ DFKR#+H9D MZEQIU,>5SP2)K'/<7'OE:V"_I7S8[:/1_OQ-@ VC?W)YCL+:#NUB6W.*$0:0 M30M9^Z=2,%9O2/_9YIP# =UV-PO>73!7_X(_Y7/XG_H+[U]KA(&L8;[ JF'$ M.15<98C0<63"B1DFV-T1M0JYQJ*U#PRGG6K"KB;5=HY]>+ M^BH5V]*.6T1=<]1L7F+T:!XEO,<(7L"TJ$'S+VD.>]D!%P/Y&X#LS+1 M#T/,+9_BHDW+OC1L2WG=>DSC;,;U0Z];3L!(:O F^*H65N"X]?_S72OE?4USV3QG7?U@D_M?=Z:]3L(D(?B@R MHG628L>5U:!*$CMO$ MT62NR!AXVYM3@C5L9[UMVW*-7(A MGT]!-<=8Q6-L%:CNG>MA(;%OB!)EB W8'IS0(EP@YFSWC9HR?A>'C11 \^ MRK\4E\VC$U5C-%JR1YPF\0K37L8S#0^4_//)Y<6R+QJ;;M:UA\C?:']W:Z_P ML>%MI#@)(/BC#XZQP+P-V;!,ZA.DZ4.5L?X8W.0KF! 4,'=I3^<(P:WQI_C& MUZ?L-MC7;55\>.U9L,R79$54%DX&JX\Q'6## L!7S,L#EA>%4BW#@HJA6U_; MO>NKU13[_3R"(H/V46;IZ2<%-1&^\H=>:L=9K.CU0GT>2 M^VO2T7*VAAV!&*=3EOT3@??-*++I^Z)(%U#^2E8>BI\WOF&D4]T?,D*ZN.L8 M>04DF#)T$+D^)F.FWMP^T32RKH:AI' +61F\Y77;Y=!K8X+]UX1/7BR2[#_, MD+Q23/$,NE3W,B D_,F!CT%#RV9;3.0K2=E>Y%CSJ:]5@DC= M[V=U>SOPHY/4BLX%M9@==%P'(;G.JYD(_G2]?0CT>7+AN..#3SWR>9J5\R>- MW_RXVY+A<>9#VX]G"Z(%5GMW'\X34@28[X6^6*G .O 9B-V@?5=O,D$,@P3E M.WPT/C8&&#QJ6 4R3=ZHRR%DO+W]\N5>B=O4DS5/R9SB:Q4_"*R5":8^1U8O MS]]CN7+?%6[E$(@! J!)\T:&?3M*Q@MZ/^S%.CU;KQ3WG%)L_;-H6?CH.TDKNT(./Y3+].7=QP<0D5(U92H03#(B10HEC]D(> MI[[HWYUX*7MG9[C-8[ONKYU:SRH;*PW?>OJGOB;;88F@D^ZWGSNV SX'''5* M>E JV ]$T)X@9-#=Z$+G#>6KNY7'F05143]?\QZG@ (>19.GVJO99IP&(K5,JA,IC%/U4@>8H=AM?W MMGOFS]*Z5@$8>Q>()9Z-MJXX/NW^G9S9<0#AJ>[X(%/*]E-YN;#E1M1]V=<8 M?D@(Q#%](&01>STD0K6 BT/V[3O5^^T^UBRI[])X<]KQM.?XC>K&#*=7U3ND M.G*'/_PO6_':\7?AYU+3WZV+C/\Y,:+MS_DU-7\7ZOZ47OGG=$L@]*]BY#\Z MW/\EM_6ONA7?OQ0JO?^!",J8^PD%NB^,M#/%!O0;!1@Z7<.%VE#Z4UD7&$8+ M%+@RR'9Z^G;2Z+YG6[C<*D"[F!$\8N%HZ=&+ I\@J55$T VU2" +D>3AEQ,N R:KYDK9,Z)QMW!J94 MTA(F&1M )W993&V?A@MA98^I>GOGAYZK%Y,[TF,OD/&N?$/^T7-ZG4@:S^VN M-9H[6@'=PK7N19@0YZ; K.6OJ"M((=-L@Z8G8X1??L]"3IZR5O1(^A0:&6K< MU6ZZ1)CS7&N>S,E"4@D(,9P@]BUA?011LI8,F\^,O/YIIJ%Z2NO[@I^^R>=8>$\KEO*)4NR M7J9J".4(F_"MF-EB<"QY7*MW!!Q/4?G*R2 &5XR.=5 K(7UR>$A"@SC&RD[ M6/GJ1&%.KY6K)2!X1GK&5A\OSENAF"-%<7 MZC\ +B2;6.QL&#+M\5_2GP\M0C5IYNP63=OC6"31H!/ M>4NR:5)"S.5#KD==%;CS1J0>Y\AH6Y6R@UMRX;OR9T4;LWNL&>ET9-=CI'_W M*I &K]9I'6$?GG1<]+Y,$8=V=)H7,,W(FM>[,+=O:KHR _9%;7NVX^7.

M MA.X?]HEFS+8A:PP[X:/]KF!%"S&]CB*&4 ^^%5G/C$[[\N'DT.1' \O7A>C% MH)2TJ<]2768;$"?'$PWGX:S=,>',)Q#?4VXO4;KQ%%W?O/MXTF#D'M_62QT- MME!@0-J%4[?4?62CTD.VZ!B]NJ';TO$9.*D( MP@:?:7=RYMWKUV(";&X?;C#^]$FK<9^-\#8/3/K+ABV[35\R;&A";<0LM74O M(4]&!6TH=1(F0;&$X8H@POZDE??3]_*T4[K%W[[1'O7-[+)NW[2GM'BZ+\YR M%6#F0@F,,5I)^^-&>Y8%M[>48=@!*QLA=].Z&&[-^"^C3L8/.T<*:?N-DHS[ M+J*VYI[]8*V.)UNTPVM0Z9:*CW@J6FW8J0IK\_KLH_7\Q<"2*LZ&^R$I5E^K M9[R*]"(LQX'KEHO<^K5I71I 10;B1E=(S#20F4";72NXOQM,^Z9FV,^V5AV^ M8KF/'#K<&_AEZ/UT_//"]WOM;_*+(P8_GW0OZ<1=(0IQSA+V:FXY.XGFA[\<=K;8=/#COV5AJ'\Z_A1*:F>6_E0: MZX-0Y)\R,T/$_IQF\_._JON)/@O![W? ^R8X?F;_]3- M%D^D$KC\\ W(X%4@2\D^\=X+=VYWW^=KO4^"LW;]F-]&ES!M#P"N'RF]=NSQ MU^9]JT B3R$$,M;Z9?+FA-N-D@S@Y"#$)D"L%MNAKV^V:V6PDFLAH1==4)+D MVI&[5Q?OFP^:5Y![ZU)/# <[JCSO="^DT M$\+#60BVKAT#\4@!2J;+IYZ5?$A7];?;G?W=\*$ -^I7QODY?/1FOHI[C_^E M!)'_C8RUHFM%U1L E5PK 5D7%X;$(1>Q' 7K[MFS' M+[(L*&>K=-:,+1 YX%'([:74%,0C>=H^NN#(>8#8&$C^W+#SE>_Y\ S.$6II\6]2T!VO& M4I.O8$X8QU:XW/79EZ:7E)*GS-1@OVQ[;9$&+.KJ]6)%@W$UA'1B@+/986B9 M1H#%V-##ON?N&C297[=4*V'AW*BOWN&;W;)C"TH_98_C*?LV&#_[8BWG3L0J M /#@LGSH$@'^YKY+2$5,;QOY4#_]PV9L74@?18B M"%>U"EQ=]$XG"$Z;2P>"TRM?V/4+IK?U]$@FU=66]_)&5#O \WUQ"$$H<1*? M0*SM9C17"8/Y28FTCQJ[Z)KIFO3676P9R5Y36?7[[R& MWU9TH8A59-MQ"(LN9"*U>\9G%UCV_8I9BHD,^/[.PL4R;_WJ MM]GD5K/\'I,K49KHYP4G2]#H#!S:,,Y\BBTMS^.H:]^X6G&N(0-R2S$F(+Y] M%*O"1D.GJ+%;UW^(L9\7G*$( MMIKJX21#S-Q%V[X*&R2-W:#=77YV9/)2D;N&YG KJMYCWII&A S@&:%$:AX< M=.&<9WN#7R<[W.6)-D1%]K0]#(F-RBE2L"G_)&O M_,R>Q,3\/%_)@D=DDD!MC9YLX\8M;IDRP%/@&P#P6:GA2MD 7(KHY\^YB45" M/P\S7&7;9/7OZQ_AA'SE,YHLAN)/.VZ#F!,!Z$%\ J M!N$$MR$#NBFBWB%J&YZ#0_USF: M#AZVDEV\J[/_@TEIF-C>?OVY9Z%E?6(6%@[NNXI2973M4HH$W X!AP T.W\ M]PPB_S\M\Y9-H)>RA#'V]X+Z?=H*I,<=0*L^X(?NXT]NEZZ9&3A,O[@TM 3( M>,@S%ICID#1+'V/6R$/%MFRO#QA%6BD?-_M93,)AIYCZD]E*9W?GV+6**0E& M66[128.\<-!6 EN&GRMZV +RY@HOL,QP;494O62C'I83.[1?J[I?S9+:73P= MVAS[JVN_D_JO4P6AV>7A5O @[, J4&XX(H M9$K7RO*\,N/Q_$6$.MOM5*1<(?6[V*/ICMJFJ\&?BO@F=BRKVLLRRP!,.DN1 MQR/D5X$SO:-.I&3F5<:[AJDN9,9R:-4,3@&Q#:7JX?XS^;)MKM'(_<]7-VZ) MM'G^NL5C^.C_!,-A;K)\>??U)?H;CIK1/Z.J=9(LX9.$#*3\5)T\'"Q%P&+" M:C/=^[2!9_5GC#L#;^B2WL72%!!M#Z1GD. A//D@B[F'DXS0X_:3;1]X*"7' M6XH\GKEU0+K<-V=I$[I:+^N;OU$24[OQ,EVZ^\*[7L1,TLJJR. MA"S"VA &8 F>K5\2,]G2K/5\*.*$SWN+)CWWON]]ET.Z+\H8.\FD[&\POF:S MSEHH[6=%/%$&&4 @DUK4S$!\8F23=%?#SDQZDT_=JWTF"U.^'!TR7%[ MW?D+I<;)1T2O05.W(%^NL!G#QAYR8GES!^'@ 4/ EGX,H<+>QG@:@A2-6)#U M=!;HRO6--NWP6,'L/>WYC-Z4F-D8]SQ;*TBD^X/0]+SL%(\[4#IQJ:N 7 U> MBL(^PB$LH9*KOS6;#$3$JO>[#U ;POS;QO-.#9[>O@J4IF$JCZ+OK)]Z7,R, MX6EMT%U7J^'/G,>-.V@2AJ[IG2M7?13QK12$; M=M:)9U=*6SH([U"1U\DFZ6WFF@[>%YWR!*M"M"U7L]_?&&.QMJ.D>/D6L)BP5FJ1Y). M7\1=IPX/\I:7:'EK.R@]7_8Y[Y9H7KMSYK'XMG:VK=YE6T&:8B!)H1)I= MY<+8IA\P>@\_!4M3/@5-J/9MKDKR?OFI<5@\6S!+8##XM@2,Y-S&7& MVCS1LMR^TC D50 /T->D'C M)9A'3"L:RA&+>!%1?_U$R].L,UU7]7U56&#L74;+2;%1X;/+W^ MAS.\6GYNGK8P&D ]FPW*MQ=:,J+3(CBJY1F7AO&1S,%()T+-\>YSW-CNN#[: M([_C^+QU%;:RWV0."3!%?>-R 2 [;A M99_?NFB@U9IW\_VT7_9[QR\]$3X2H$L"0@7R'V[%P3 :#[^9FZ95C4R;FUZ- MJANBW7BU/DWKJ)7GS2S@S>E+M_K_!.1_79XDL*5LN")X1B[=#=^!3$4^+VA7 M=?)J'O!RMC^,D*Y/E//SU_[[49J?:VZG3NX1B+7Y.QJ)HN';<(G$]6S% M('"*.MP>*]2&57N^WC,0J]2WN;*ZOE?GS/:G]Z>:A4P__(=LLOTGKS;M'IW: MB*(A!8)(QQCX-)-Y[8_8I:&2RRH;\9#TM2W\=FD@+&5MUYD(:7NTN1@C4U#U MRZT<1$SU5T]<6UO_EY=P9M=N+Q=V5#,.XK%=H9VXULV6L(?!&]B[.46U\%2$ M1EU-S@ED6^$ZT/])]/G'^XOFTW;?&@T;J#YY-@A0[ %B-_,BL O L>O?3/C MC!KM/LIY@ R"R8AYBQTZ^;$FQ-V]>=@P+5?U[K,SF3]VBFC2#MM8Y+EI-[9S MA=;&FN&%>PZ MI"S@8.]NS7Z*:SW,DRE!U1#8LH;,W"9HC,'DS(4^\_%&"4,&9/^=/BI5X]S[ MIJ%G\YZ+5V^7T)#<^_2^#C]+ 3NZ"O#@N C+^ANAIGZN?S+(!+WQ6]^ICU7, MALS2C5]'QVVO:<=; 6=V;4KTTYUY5@0?WR/[JPQ$M?-4[)]#>RJ!]'7'GSL6 4N*@[X*1X[L\'%;16 M\=Y0_*@/=M9^%4B(7K*_?J%MF4D QQO"F/Y7XR^=7UHL@A&_5<0A:*!Z2C=7=LGN(,^\+PW7-"H-2.*Y",!!T>1X#FWJ>XPW@#.0)?]S[ R MHUG[1APV]RZS7V!#H\>&:X'85< 6P\?#1F:\^91%L?,)X %DO+O 1<-8QN.W MRB/"]-=(+R0M!M?ZQHQ K.,D$?UO:UH*&R*T9Z1V+8\K^?5DD85;2 !8W#>)G27,EDQLY'%(F\=3MG>@F@4>WZ=,;+3#/IG2& M"[_B(72_W8 K@V2K).-^CG,G*-69 M5WQDMV'E)M["/]W4?(W[8*7RSK=@6D3XQ_=C1\RA/;<^MXN%GQ#.K@.3^9\C& [F?U4:F6_YYBL@XT+.TV10-[0KH,-!^S!# $VAR M]B1NJ:W?J_(*GO5LD\7N54#TO[\9%30C>#DSA"N6P IPD.>@1K ZK:'VY?-U M)='HDDE[]J[]W-EE<@E;KIJY?/'VPFT46=Q:<;%-3%U(8:7P\@[ *O!I$4A_#ZVH7=1:\3W _A"N,]6_RYF^=J@C^A>**MJ\" M@D^]V?X<0@FC=ZZ$Y<(^P:CHZ!6SU5S9FT+3!,Y_33 MP]T70[MKVY*D[/B@898W#Q*?0Z)A9 +S1]\J@([!;IF G'S 1)99^UUYVP;M MWG;WR\3)T8U)H^Q.>E2V"]G8QJ"GLF+>98YG'D)R6#(2=*L0"216%["E%YC. MX*.[C')#6#HA5J,&G0! )8=!9);E[MCB6?,]BW67RO.>>-7(RT5OK'14SS?CRQZ\(N"P?H,M M%L*UEB-!JU4@M1G&B$[FO1-*[?&&X43RA.!+Z 1U[/*3T.\5OK>T7>;%YA,] MPR;,$"=>K@+'E3$)W>2J.&PRFY]G\DILXR8H.X!U$-?JA#6:1=4L=]X._TH. M5K.XXMK>()VC0'KT[C6)T%]J.8\5;9^I$R(9G[W%F-U*:O3+U^O3TB8MY(^?#PZ MB1AHF*!F!/72<:.3[? -B M*&O3PG.DL@596"0TR\0ETY!9$6\:Q8(>N1BF1^(E;T3HH^>?U]S?@_AY4=[8 M2F;;:[?].QXK5SGPX*A>+YMO$D46\H(8#/Y6GLL7&?E6N.ZC;Q^1AHIY2^FH M''>AV^6/%ZX"[VO<8'Z?G:NT/GGW*-_9L'TK5@4*8*;W-9NQ;1A"'934!KE2 MJK[S(A%R;U;K7W05^)Y2.69,X91/:AZ_6;(Y%[@8>.-S;IPDMZA^8''LU#/>RVD.'OG6>\(B$V)9.& MO2*&N-(,N3H#$[RXF+>OF/9-P9:A60NC_).>";N."XR]XSE8I']O/%RH60N: MG82UHP#O:1]-J. QF0)-NB9]]3]T3= 3<2K>3A?? MN@J0!7LG85GL6*H%^NK$;O G)-0A\J"G-*:T_=%[T@G_%"?F7>.P.0.J(OG] MSKQ3\4**@N MA=(!/A[O$;0,8EE!I9T3EOU8$[;,<[ PNQBZ5V8I\,0S)L>"R9#,USABZ)^@PU1.8:(AP#TIW'FA$F0['Z4?$;B [%G_K MW& ;<(Z%)VNY2W8=%_]..I7%30-^#=/KV=(_^NG)<^T,%O,\PY"TH +E4"9S M9W/;#3--LV/E$]561FQERV]=D6GU._LM1^OE-G[T[E\I%3>)5 HR@U+- UE7 M+PVOI0RB6'633L8/8N;:WIW0U_3P][)"]BC-=SVA'=J3LIPVM>B: M>OUF]YVIA,6L1AASK0'U*6P['#QT^;(B,K@W3BD@Q=19:]VW">W:PA );Q>^ M]"UIS,')&YM.'[,[1GJ5\^"#D/4D*I-2C9SS!ET[D$K-.V/&VGWXP*;FDFC< MLYGZ1Q9'7[Z\X#FBFSDL;[RQ[7'0F5! @>K130#M<.)L1TYQ\T[,6LF>1LP1 M<&AU(M"&T!3U'Y,4C.K2/((\+ MPBMV^Q?\K"U)8B,?DDV'2BHF$M^2/<&% 9[B&">Y'05IWY MM>HB< +S"L-E7I]*@/:A6HDR29DT"K]S2$\(5R23-X#W#/152PED.U[4*X2@@-6/ M>;77O)YYM#ZM(N#1Z.CWC6]V=$SKF=S9<&Q=DL;7$&PKLAX^GTI#CE5THL#] MO=!62Z[T8"/N%'6$[0M2Z,B$FN7*:D94DO_V_5JUI_?)']ZO('M@ZT:G+@TI M![[E6-E?3]"L$[A6%R3UT2I0B^RD)!-!9V(&EA^R!XNIR6F$-H^)/0SD560] MNM&#KB!XEIJD?4IF9Z6* >/G-<:+;9IC\I6XUBTX-"6+4$-(X6[#OH;755R- MD)">+&E!;Q@+:C9>!:Z>>*#D_](W4MK)]RGY04%/!H13I*&+N]FX<2.\QQ";T=>Y!M^O2*5((40GW"Q$^MT=9-O)D"8CJ((#G#-DR8D<[;FB!0SUV98H\NLK MC>@';,L^_1OV+[82D_=M40\L>#KV1O>-NH%G<<"6(OC0N.PO(HM'!EN/X (K M1##^4"1K!W=BPAATZ8!+L /["Z>HL'D]\.LG[[)Q J/M[=4#AC=44\\ ML@HTB#5*HQZLK:=>@&]$!AK&$80W/H"J&<0V-?FCBE$,^=2PT'@\SMRV$XA< M]'A+V,A#@B\HH ,J$7N2X<&6L:&%SLM%ER2SG=2>M62-5/[,BFT8SN?15"%] M7.OV1AN],8SP '8+V^WFL:?MX )-L#KB1++RT=[UF^XPAM46^9:79']Q>(RB MFG._,98TM\S347/.TR4>@YK19@PGZ5L:BC=GJ'V]N+VD>F/_'1Y)DN"IL=!Z MC-,D;15@;YRE#;>/?%X%7",9\,G!\F*2?V#-2((AJ\GV;S9 2N0U*^&J80? M.[@?4571[0IG6$0P*<;):^CL:1236*-@]V[/BV*NZD6>E?E!B3\QT3S/QHJ9 MOI^[,(K9!=D6QUQ^"Q_WG P(YS(4BV ?E%H9I$YD$E*CZ M:$)Y,$C6WA.]_ZT12A+7L0$$Q]>67RTE+G*>$2OM[I917IU]TYZ=KXN]D;9B02.Q MI7VY(I-@0CHQ1-WL0BGQ$VJWQ\KI-$_ZEYG#EM)==WKUCI(?? M;ODUW:VQV>CMU5;9E?!!-TX P$CPYFZ(T9M%C&3M62L=MPJ$4&2^KP*''X?@ M)#0^S&DOZIT//Q>SK,LC+&8$MCR*;M\-UG.%<<4Q!WG4=2"8N)&+G$Y&+ 0% MP6_=6.SAS9H5G$ 918'AZ(Y>B,- S>' KKD2(8?3.0MFS[V<03]7B- [B-77MF%]>E 6PN M[W*!H E3SL*\&&^JO3G/,=%$#O;V>4;*2%#O;'I(H/S9V,(:#(\4"_;S'D1Y M,=8AA*O+*3#$^/+8C]J321>U6:^,'%PC/OH+@45O!N_'(;#0>9Z^$G@:XXO1 M_/$9PO'^X[UZY"G+8S\6O&G?"::O5X&ZOHX^W.3@/%<>Y/G>C242\%:L;']$ MNFV7?L0KA?E)A57 ?[M T&$K>#H./-_+5LX,8KF20Y#UR7-PZFLJ='L].GJ2 MP!_T(=%%[GY&TWB5I& 1T+V)1]0*BY_>!VGHE V@EV,^V[95&JXB/S3&A(@P'<4 M *C_RX'Q)XP\R7S+N;76BRVAGJ"Z"@2CT_+59,$OS]+%P\<%^X85[R.6 F_MR$KOH3P\>$\^8 M?!3R$TD[2A'FL2,49$CLF,:=[^5"[C.\K(LC;WTGI;SE%.$I%ZGUB% MYUE8RS#7@'.+?5&K9R+Q@KZE*VU/<.><*0'VZ8=E>O?NR*+V3(S&S8SW Z6_XR$J_%6!\,((]^*^<_SB"26$BRTUY0,!4T?_N3 M5CN5=+9\J3=%GQZ8$XMT=5S7?KI. /-&MM_ W[VM4%AU?W"A,J?8C_/(A"@[ MC92*$,;*MM.VSM?B1+J+=P1[*'4?5-*K:7@O)9LB8S29T[%R2*CHJ,[A_N%# M)[0J[LF[B-P,RRA^9Q0O\\+GE?5)D>FB:VEQKC?" %GC5[/%R:=\O=-V/W7+CW,RNN!O]:8(.\X[CY)Z>([F&(]@4;O9L>C1,.SF MZ2FZ%.3$E4H"'WUE'?K([=/'CF7X=O_L+;@S%15#'11#D47;9IE%#9Q\4AM! M16NP)%Z#8<1X5JB*ANPU,[]G/J_T!L>P8R]," &ZL/R'/Z^<2 &)2?:I^$RA MY%!DG7-*E7G]J/2\]LCN\T*W,[G'+GC[1WW.S1A< 7YR++HH-0*D>=,G&,1 ML["G-]NX'L28D=$=)@P3E_,72VM;'4V8S\F:J4A[,4=49@-UQHZQS"Y[.9+$B)4X&P! M7D!*;EY/"436X%*(@9X(,^CK"@4%+A7FP>,,(XNX\'XO(7^S_*%7.U3?W21_ MAXL+Z=W9B$PB^A/CU22A)3J:?)D'ZNMK&)2,FMOZ.SHF-CO=S"A@UL6EQY"- MOQH]-^++LU'[/!QN"QRN 4E)STS'B#+'H$M=J@>YN_I8A],^REW.L[[JJ&RMAP!K\; M6-?(\%U62KQS[\SA>!L-/8WB+%55AR+8R?]927RQ#HHX0AGJ[VB 9[!]J1+* M[H-L(\MJ".TZ4/.ZA+ _WU9,,__[C)>\'Y_3YO59.^)#?G9SA7D^4L>5A<.- MCH6@5G9>XNA6\- ,-1_YG$*"CPI-%LQ[,(3H/Z;Y7:!VQNQA1G3"*E"UQ&]Q MUSPZ.[?W2.D7QR1%G_.S5FIK!04BW>'@L5YHR^@0[K/.*B"RD,#X&LN[/C;W MR(_S!-IH_2J@RGS J;"!0^9B3$=S^Q4&&-"9[#$Z/$?T'[ LH\S]&M\S^XSS MA'BZ8HS$Y.&9^-00%.B*@[1128VJDT'-&I![_SZH'2SH,A\+0I'[1I\^+"P. MN%A#4GDCI;G/,0XXS7_3I> )BY_;CJHS2T>>[97%M;KAJ \WQ+@Z,'BH+L$7 MC&[')W$E!Y16>MO,%6[T;LV?CI,>=]I\VM.XR,EP5[9ORMJV$G5(()*3R-VZ M"@3B7KMRE;P["6.7FU+ N M@N616W+1FTC^48T/+H2/\M 6[X6M?\MYTFS 7JL'&H;1 F&=O5=7 66,AV%Z M!1<.E70F[VT&ZU-*@!.]Z]\]VAKV<).1]4\@NTCDRT+!")*:2P%=5H$L8K5' M*F(;=X3'-M(75<,G2TB\\!'L8ZPF+QG1(]DUM#.-Y%1[T6[YF._I9U/E(\.& M7U)5^.<:>&'1DDBO)Q%24;#&XUP5D#C73);!JLN4D[YGGCPHWP.UE+ MDX1:LWE9AD<7LIJ4SC:MP+[A&GS0-U@,DHOU/?0BKCU44/*K:'B\E4JT>G/U M/Z JYL@DK,:@*XV8_!&C%=,2&!6WW:^5\S;A.L MM>@J\. 9Q=YE[HH7DJ8UN I\.\2##\WY=6LUN2''2-R*C"%NX6$Q5^H$BILH M1F%-AYQ.^]\7Y.XG4FE[PIE5'Y'4(D*M?+(.X7 E>+"2(=;NX6,4K[CS=J>Y M>5U2@<[N_(E=.;/=AV\,'8J.XQY$[M1;X2'>A+M(:C8./ R#MN#G;])Z4XB5 M!7.VG-KB0!^!!)=A3'"AV<=0E/=+Z1[=?6'E%<77TB.N/7W],S-8$ "1ID.EYVFB,XW[PJZM)!4.PC>N957F$X?$Y 2 MF5.X)SBO/R7E&*+,;RQC4/+E% O)0K)M.0]Y^ &[\P-&!_186\>V9I])"@O2 M1VA^8NN!@G>I(I8;T>H.OB]?)ATSNWY1/:8E0^WH':K';5SK2R1HRQLL<:Z$ M%0/9\[Q!+4M^UAT!]-?H'V&U%0QS=_9Y&4J&%+A_M*O_&?0D9E@M9*R+.?(C MNOB-]':4GAY'R#O02RN_-+Q\]!NS$N6CKO7EL_M,U?LGKTZ_NI(O]O*YR.1Y MDJL5/!\N@Z-F$JKMDAFPUD( HM%Q8Z[,>(3AL+?SX))^R*3J4'$ C6TS)99Y M8$PY/.SLY!?WSSE6_'>& Y[B6C<1J6G$JA(\6X!J@88TYQ=2%BPOECL^&IDQ M/C:CIE';_]DAHPQQ3W]^H#1,A)]O9,,QJBBSETSB"E]A\6%'D,JFAF0TR4>* M$9V,U0[^Z$VZ/$E9!_$H7%_%^,FD79OY?&^T[+27"8;E$:X':#>.<57Y69RX1.WE8EB;44J$"P6C(CM+4FC T'5%AD$T]83AWX76DWN/[/WUDC#0TO7T5 MWR7*J\[:4P7368XQ,&9DWR*!;-/58(9': 8QY74\!MD6CR2,^]WN..E95;:1 M-GS=(25UT$SP+%\%7IOGDEYSAX@BJK#Y)SQ'M8/WU#1B59W? %6,)YXV% =L'NJ0V[["F]:J0 M9[;H(5-!P>8U,$O2(A M)4TD0MS!LMF)&)3K8$V,P5F3RP4VRCTAFFE>$W9[CS;Z.;K&G[>2B:2DWY)/ M7#JQ8R]C>\+!YJ'O7A2[ZN:!>TG>O_*B%6CV)_U.-N8=>S' UM$OKSB/EC&3MOG\VB_-3.3<*_-M5^(LXR3@ M6.-NQAR$<),5XIA+#*'$B%ZAF6&S2\M) M$3?NAZ!E2)H(+^_QZOBWV?4+@N^DQF.*)'_GS /_,*(O7#V,&30V"4M=RTCS M!ON9*05M:FK@1&GD^4F_XOKR54_/G.F;F[81HF@'F&[ M@R7SL'+V(0A7QM:$JA\$(F3Z(IV>8-4#HU>$&UX,ARE)/+=!&VG,/ :W,JY07=>[SH&ZL/_WU\/4[L=)'%?E32Z71) M)LNWH1*5$"]I^MY'&O%T@Z;'(??)L:*#F\;16HT*VM,/"C[K&M6$VWN1W.]X\$8#ZU[]A'(.(D!6![0+'@,H]*\JUU MSPW"&@V@PY869(/".^H*9;,4UE?V1*E\]\NK5II[\VDWO=F"%V*OX8)[4W%\ MR).7"0EP$;8./64)EZF4H2:!4IW>J;Q($6N-C P1:/?I>:&@=/GBUR25"\_8C,%+OJO'NKY$&EPU:JWF^<(V+!E5&?;,G,26U>&*/'P28TA;ZBK^ M/,[V@7SIC]GV#Z:E'#=9H>>S!3H?;$Y1.Z^?\_9IQN!20?LOQ#H>&$28&,83 MGA>T4:Y.:"7O&YPO-T&*]M(6)&L[DPI#RZ[^<'YR7%M.Z+8!-R3>__IKEW<' MT>R]4"6U1QD%$N;&)GNO^&QC)-UF!"][]J'/+A)%,^WW]8?1ZXSW-S0FUHVU M&ANEBNF)*.3MFK527;Z*W3K=C 3+;T\2^$=6@9!OY)ZK'@T'2TM.D$R;OM0\ M5MM=G.WH8>"(J RR1!004(858;(#$%)2$04&2J@L325Y"WZO#^Z^W3W MZ7[/^;[3?:[SH[@28.]:M?<:[GO7WFMAKQQJU ,OO(I^7-QJIMK-)IS^"#;L M]TNLR;+S/O!CG-C:OET^4/SLZ_] =5L[YQGGF!RSED[/:[YJ<:9$<8>>AXX; M_+\.>V]XZMML.U!S>,B:5?IJ\]&FVJ'/TW'8@^O 5BLLEIP"HX MAH5FK/=<27!NL0C%)ML^!G.3%W+& MVUQ;TYY/J?]-2?1(/>,:T%UNQP2SH\R[O=&HKA+/']+FXCCD%BK#O:-QY:5Y#=C0MA)4+7]9 MV*6WQ_9V%6/\IO(!XX,_;SS>LZ=<+:O^\*=8J_/8%-OUU]D.9C3&6^>0DJ^D M:)[I[?./6[01JIIU[]."[DDYT]:?]T[9N1@LJX(]^2Y$.]"[E2P+:W$O5 85 M017MG1?'Y<'9N4+EZ-RFZB2/J/"'!E$/#5]',U8-KLGMXR8V9<0U8J%"Q-VG M-5I"T46A 2:@)"\17GM1,*!9'@74;7_F_U,.UCF]^_'XT\V^+X=;Z"C"S;:7 M9AD-.UGA.B*4/SB"\(UKT;ZO^G6SY]WYVZ7F'+LM-A#L![Q<1G9]1UD[Y:]2 MZ@ H4\WX!$"S09*_!?K$NXQMIRK=_ V_[/,YO]VS)7*V'R+P%UXG!7IN5/5V M##3=]C-:9T.CG:"DP0YM4G6;)?( MRA&S-Z=WVUY#I\TV?7JUR]W=)T*O/IMAG;VF>8./V G)2-?3??IDU5C-Y=;OU M_3GU$\3-@D^6;(2?:K \FHA0I-HJN@Z-M2')4"F5<O>4]<')W& M@94/AU0_?Z6?G33C ;S(7:0>O479NPT3]:?\$_6'2WJ==#PY?CA&V&\(*F.1 MU2"]]DTA #JJ7MO-/I+%3UNV88[RYN/U0V]=(SI74.0;IXZ*+:Z0U#[%+8YK MM"!D\*Z WFT &M[/794R@9<;"=U'2)SXWG@O?%UQTN3SM$/C(<&!G[:'CU@\ MWJM>YV T9)B/-N#F--_'MV-K,'&.CA49CNM"-K ^V.VOP2\_-:[K&B47/7OV MJ?1YS>V)L^;;ZJ*,-2Y8*"U&%;1CEMNOY60PE&C4FA[*1(:2V75[V:)I:UO] M"R\_9OK8>S]^8D,^73;9TV3(Z)%V?EUQ&.'']6W8Y8W*A&%.73P00E:"%;/G M.P*D^_&E]F9LU?K,$\]J&_;5;;[FK?#\3+[V=&M@JO=43JO)P0E/6+%"*!O" M]F0P>0^@G<6^1'/!P],SB=<:C:<9ITWM)=BOPW?>_W KY[1T5=R^NAV9A<9/ MNY)7*6[PP7J7D*%"L& BIP.-"@5D&C?#V%[XX$392>;KP2B32WO3I_NF[>,2 MDYV\GCFMX:R)W26U(G9KM_,^,"?5*F,5T;,&3$N;>;>+7A!66:IDX?!PPJZ M;GZI]2A6"].6-I6_,YD76*@7J^RWQ"8Y6 M?;#58V8UCJ"W!RHHVUG0_5SQ[3'^WLD#[F?*5VA=2=_,(\],\3<)Z>0JLQ9- MSSAL-;993I86H%%]G!OBJY+5FN7J)&=*.Z=L5A!$)A_^NI_?_\ MAIFC^]WK4?DGL@C+8K?B9+[FII7?US\#17PZ$W'B^.?.6/EO>WC[6 M(O-]X[_.:#P-$:YY=S[LR4Q-643?=%@X]53"^*3_PP_WZV/UR\^+X/[ M8XSA NN_I IDU*@_^H9EN<&\CX)DTC)".HU_G9O@LO:@72IB@U< UA-5B@M.W$$&58$\>TD*;O75?#P MR1,-B!\*WF3T!/) *[R+/K0#M>+>12!!,$ MOS?JCA(JFFU;FZR$K2 O;FG*UU[;X%,VH>3_EW2R]'F4ORKAN)S?\6F)N)$*$D)>.L@!)U' M[/J5@&+O@X"&S]AJN"OML[O[N3O:6SLT*A"!0W (9Y=WE"4N'VHT@8T@R7)X M]_"WS^%D#W!]W%F55[Q'?>]W*FUL8.K&A.CM'J,FK)]WTOZC8>W]XP>G@!VP M?;50UHR]UQ$#T!IUUIX ZK'7J:< ])=[8L+UN]+N<#;N3B>!L_X_9JC\70 M MR'$='/6N!F#@A=(TEED"#FVZF@7%^=1"M!64)[YBX49.N@E2@_HFV*RTD0T7 MM!^+3Y/_"-F^Q4.FDK#6,B;HB1VK8'DV8:5'[AI'W8_ RA-#*/NJ.@4I9S+" M5)YRMMS2ZXZIFPQ_Y[M8NTOR*Q,RHG;,CW%XOI"XS2R:K_U5A%I64R%'L',> M/(^[GIO83J#$K'/5=?5X=/'TQ4C#K!A-^O:L&QH,B8-981!/\ 09.'(*MM9E M5H[-9%SBY-5IBU#)#<$EKX0EE@JWDLV=#D]<=UNGFVSEFNFV[H"5QI9N%!#I MJ .EJ*5$R6)4"(&[LD4HCX$9=GU_19F!2_(G:7G[4_\+3_9_6C*KCIM%*XUII\-/*-*^?JZM9O@9_G;=G%;-!=&;,^UC;CKVCV M342?"8(Z?,^':*'L&[[SZ[3%+?TSWSH/UH^4!B.P^N1-H58FEP?/#2.XY06. M\CX>(O/MVGFUL16>MTQ>C)Q]'_TIUG'J;RUN,%)8:K"59-/]2)8/-,@5GYCB M38U2V960/]MS)BW:*%,)#\T-&1@)\#?UO-6D\\T>395\>F4^-Q?<6R3&:-XH50;B.'MA[X^$+[+ M4Q44.6()9-]WI/Z/H] \>W#HR;&H8$KV:"JOY\$ZQDT+T[.40KOH^MZT(,LQ$Z%(S5VY%. M!Y[-1P?_]0%H5!>AD@*1T;N1HQ6&6T$,>F+(OWZ9&XP[FC@0WJ U_ [SK -6 M7.1I+[W>R%"VF0D#3^*D.SFX2HPRW2;9RL'M^XJ:13@!&_'BSB[OV8,B5(EL M?=?/:LH9L2^,X7:R+"%TVMU,P=]GQ$,Q(EOSPR&INVH:;U8V74F//*PF0B&: MW>1AAN>1V[ R?O@>.K9M:$.]]MF[,=-8VX4,AIY0ZAZB G6"4I)U&+8&-ZO MU_T\;L@M3M(9I=P_]\-[0*'?MI2K;E)5U]TC@9I]\T8_C]0BE/N. MB&P>,B:D(SW\ NWP[43N>3-/CT6M\[-.F+T$=W9/"D>$6D5##&69RZJZ1Q_P M?.LGCT(WO1_SJ&38C.F?]JI]6?6[CH:K?5R VV,D''A167D,.]>7=;/%X,6! MUA>WCL ^O0>/MI^+/I)ZMOLBO8E^!2,)G 3B?;V;1*A88-4WN@S!Q=DGQ^V= M99)]_:7]QGV>IH-3FH79+HZE'W]4:/936>EDT$U@O*N6"7HPKYI,UGK/8E=^ M&ZWNB5E<:]>8:"FV??X/!R>6TZHRC^7P>-#&&1$J^C5$*7 7H?*/_.Y=!I\1 M%#6N)G7C5EJ9I6$Q5F& -.3ILBGM(&ZHO$\S#&=[XJK)'$&S,,M2IY0576[; M(93&+[VTZAN\N0<9H"A8NN[0UF.2S28J8H[%JH,S 1:@RU6A'A0Z12/+PVL+ MOS(Y!;[+)T5B6X@F&WF^N=^OW; M\W ]Y_[P\KKW26NRV4?LFBNO5CKKW3BL9?:<7O^%694X0RGX&>PFR&T0"_LH M0CWEV\2=/AC/2J&,RICI&R M3Z/5LYL$@A?,]C-G64B0E$3"U=KY+>](FP@EOYET&17#%L.'NZCC_D/.>EJ+ MZ4;?L*'9JWX[L5(\V1<%WT$>/P6@=0+57CFP4@4[NA4]*GN0:T^RNN,+!3;G M^,XG1'PK2A:A]J=/J9VY7&09XM@M0>DJO*7BHRIQ.J:$W&D&67D*9?S.\S5( MXQV\B]Q/I5,TG.:>U3N>6$+N_C$^U.HY\_?B>F[K*MMM-)/>;$GU1G1"T@F@ MN5(G&JBLAPQR"WW95V8H!("1=' XT?YNM',T21_#\"X9F;^OJG+4]=2L[K$? M::2S7W[%"S.!%26% =WAY\/,.\,C\6O==#-=-TZWW#[JM"9]F[*88/ZOK^/@ M-OU;I=B'AS#@03/((">.Y##MFVI.:/%(Y$NRM6L(*TQ.#LJ[K]W?7/JY]\AC M+8GGLH,>E_%.B)OY*UAMJ$U9+..O(ZK3^_\KV_IR*PF#HS)9^;<=7"@F_\Q) M, ,)]1/T%F;2L@'"CZ:+UK7&$8KLUZ&_CGAC@^^JF[_..WX_57V9^M&K8N6R MO-<"1+F"Y\?Z61"DR7>%(@\,1*E_/V7E[M5'W!9=1,?'2)U5[C0IS:SWA6S;^N3CE29C"5GC0Z9(1I]DRN8P3/EO"#B%NA%RRQ![M?1A07PO:VJQH8 M.??1M_I;S9SDI+4W%CR,=?034 #$\3",>,Y01= #@K=0.I,; MQIZ_M:J. Y M%UAI-=,[L5F$JEE%Y2JQRNNV,G+-VN835A?E;(J8IFL=W'YGSM?)X>M\:"'; M3(X0V?9KQSB&&XQX$7?9*]=GSFONR-.0+-"[6LQ5%NN$Q04%C6+" 1$*S8'* M^#;P<7 JW7[KNLXQN> 6VQKO&_J?E1M,>V]6[5SUJ.!8;)#^.2-*^:4)Q1<.*&YV* M95T+4.NW]WL*;Q=D ZR'B/##S2;>7@/!U.?],);KZ/Y!8VY=YJ,+ES1KSG N M*:H1Q/7W28[_YCW%$MQ&#&TBXXI+-(T*;>AHQJ1F/UL,+R*&0GL8=J>U]2[= MUV"XH<-GKT8R&JF"!R13HBLDQ[>;IJK:6X%8'RB'[;_Z[2#]*JQ2:?K=+>#4 MPSM^TO?4G>9-U3^6GCAW2KS7L((^ K XY!%ZTT&3G-E$4!:)ATT:+B:\#9C*0''@>"=H1H9[\]D+-\HY$%QBSVT>_'8QV&_E M#BV4N<17&0-H MV['',I(P5;]?9(?8%B=9OIX">ZHF8_N_A_D4O*RZ4W7U[55"X"KO3PNC31^' M&_<[861(- SHBXD;M^W3%2#NEI4_;MCO*$/JS9.[ZH#M(,EQO\_X'K$M[ I5 MX[MX/+]3:G/H!TIC?^"YM^HL7CM9L9=N9K3'X)NH&_['W;;BZ,['W*;';1Q>W:'@T4N MZA."!;"5'6WT40O>\2%[3[['^S%/+L!!IY\W2\(J"]MI#VL&SZ\XR%,?4;3> M)K-31_G6*OV1W3<\AZ+^_EQ7ZG^>DRK@$M> $]Q<(44\#:)I:$5HO)W>1C*W M31M.L'3[V,I(/;2_?=A#?7ZRM+=2^XR;!N/LY]_^O:N[_X;77/MLL)Q5VXU+%YWR 9NV(D=2Q0C['PJK] M)[;=E!AN%6P(PKK"@@Y066SNEG=^%X^SQL3-#BN%#:-+^]S7$,, M!G^D4MS#(P\)N_M/PTH31O<#IMTS-DS2TE&[Y9(Z(H^>39U2%INU_$-E9NS7 M[5S,W%)58IH!-ARK.B="><4$@IOSJ[?R"XMR)R_$C=S^DLNCCF3P)@7YV#", M9MAJ3!L:,C!H12B1K4G"+=.:V4MLK:'K@@M0 M\L^#O%8(>2*)2#"C79Q%'TGDZ4-G$>@IK6TJ[=V>9PW=Y*WTWXPW5PI>K7&A M2'E.4HZ:GM!0,HL%(YEI6Q,]!,FPRFF8S<8K37MG\HG/$3?]Z]7GI3K5"\P1 M?@M F8\GK2K*X>.)NT$@&3YW?L/'G-] ZPR3M%B*'?'QT%:W\,[%H(PCR3\S MVK&@.P 9SK?BU*9?=J0 K'I Q3CJWH?=,:66>$G8H??;S<"(!0O]9:=^6,QL M?ZP5N_=]YDTG3/1^'!F)IBPN>S^5S815%GD#7.OY[[4N'/S(#%,XTA*Z"6!Y M(:B[S7,TD25"=7B.-O,1CM/],(!PDW:Q]HIJ6NDH+K2ZPT'P=.-*M[/B'887 M1F1MJRJW;M7(E\.JPP"D ,X\AZYPJYMM%5+9GK-D15_&[*^?6:9&BX'"5:L1 MG6 *NZG+$/O/:S2$@OCK2 ..4EQ\*SGI08-5L.35!ESPX_>?LP\6R'9^V5E3 M^NXX"FSO"(NIUC,EUG:\"Y!?.CT,L)+'ESDQ7&8D)S0.6?$9@P)A0<>1F]&1 MZTE%U!P ,@[NP(S>0\CK=XX['S@BD*)$O/& MA\+=%;_WOPW*]&_$&S8GSNV3'".#8<&P:@>+#BMU'N).S=#Y0; '?A71G*L5 M& #RJJWBN]]?C*A6=RU*Z:Q-=UOVWDE^3L8I;*=6S+7A&7& UH,#75YYI))0 MT!KS.FAR#L:ZJ/3_@-$ ?(TM:!]%9':U4-.P/198ZDBN@0)_: MP2B_CZ@[IOFW@]) PAKSU#B:EHX<$$$&]S+'[)H <)_G2$<3EE+<\CU!W=[[ MH7YNWCVE.6'70.!ZHWH+YH^#CY*DVR=E/JCODW3@HP&:1Z,DB?F21WT :T(A M7#L73[0/[>S9QX2O33:^#I2^MUT/PL>![Z4RVDUBZ>B+D]0P/+2AKJUBM)[C M-4\#$@'0O8*AQ"X>F9F=TC$&/1/"QW8\-V_'=*9/NR5,>=X]$JYY./#W.)PO MXM=1&&CCT@GT5LR")Y;%I%[/VMM=$QXI+J+\S*'U?X<'K@Z&W:FDN# M. CAQV D/AG[T8Z_C=21I\K\09W0 (N3\+5 /:]=H_W2+_1!'-#KI -PF4T MQE&71+]8$=LH0[P4-S'<*BNPE:J9Q[1-$*P(W^IO<.^>]-/,TOW=O#19X;4X MP6$G\0I"-9>.I5= *>2E? )G/%LURYA?@0D-R.+!J9_?QR8M9J='OKT5H2[\ M6[WF+8)[ .LV4Y,D#4>\<[0FNB*-:X2]9 7JLZDL'WL]-D9A;.?#T)T3A-KW MC#;TO,*>^($(]1/.Y!RRI^#YDHV0I:CX#S8MN=@V)G)'A1I-G)QGI$F#(XI+ M:4\U6\G>U'GNV*<@G&'X\K3Z>]IAXX9+U;39&F:0_LDR$6J=TH19&HPC+]4@ M,VLK(_DC06/C@NTO-9[1TA% 83,5W#M*&2,C-B)7?/4$U]*:&]8W]M7F1QKA MAL;*M6GO%\BW.M=OSF@,&W^%9P3Y<[ JH?M; MM(6OV$SQP]/>%J7[I0I6#BLX;F]_6O#.\)M*P01UQ(ZG!4:@KV$#L?&K#S'K M!?? ^3UQVL +U'?LW>\5W@]C-WS6T09%J'C+Q]_,9#\?NAB>NG7A](S) ?6; M^C>O.:'>Z/^^JJC\CY UZ2+BXULQSS)@94VAC ??FA#).RA(/>\I^:51^]4P MMD:XUI] ;E7R><4>F[6^D%1),X7@OG['V>>$->TQ%>UV3,B"*I2A'SN+#\1 M5-Z?LJZ3*X(XNZNX]WLO.^]XOC8BT,OZJ%V1(F'@QLIG+EDKPGY)/$Q&&?X] MUQJ%J^;H?:<>QMKO1.;_+A7T^'GDC0&LM,A*L="JMFE.T\JZ#' 85?9+V1=Z MD5D\>R3DG$/'TEE0UJU4TTD4M?F^UN\K6)'AN.U#?Y96TXS&'*7S+@GNS^!K MJ*-( Y$J\!717>UWR=)>=\.+]BFAW*5J'(R4!G]GY C1"Y7 M/6+MI4M)V:X?#Y2GOUB)7BY_,7GQOB9OBR#+?BLWM),SE;"4IR;Q%S[=YF"TJ:SG@"001$YUU(,"^6ZD#ER-9WR-OZ17]A#ZNO.$!\*U*%MN<&;E M_?WLZM?2L-.+J3K?>:_,/WT:[QEWKW_19_AP^T*GGL1O^\S=#&)1\TZ8%"IX MA EM$:%X)MP<6.E@*W85P"*3:RY7)#>$<#=G)*Y7];T\>7LHI?!M*KY509HCQD*,I.-"SPY>7&"W+F/:-^CTC^Y);48K!7,[*K4B<&5/Y M,9O"U_URS.^@X(E0RR_1X!BY0U6Z7N?NO5Q_35Z+(!-V*?4E7&IA4FQ:[@FV M"S_97=+4--,<<;=J[:$=V-)[TGBNRTE&3/^&!'$,]!-*C2'/:0>U@%1D'E<[ M*I.:,2N_XU<1ZG90!FL\=GPQV?C>UU.Q4REV[D)6N?F6->!%[TLL -+#P(HE M$Q5I44#2^#)!'$DKQ';NRE._:5_3DJ#\IQ[!TLNIV>!9:)\DA;A)\!1[$I/6N":G&;<">TJ$$B/4>R7TEA?U MVV_FR!KQDUB'O$)\MZP[*:71ZZX0Z[\K1GD^&4O!S'2"6/^X9F3L@%,5RPC. M!U_4J!UB1"?;^P<5TXTE[BXOT5HH,5=UV=<4:-BR=<4+W.BB4/H#7T;X1FA- M9KO,]/+7$V2;7@J&2Z4?BS'Y,'A"6G?S]G/B3]JE M*I27RAU: K3U45#7/H!F(Y3==/*-!6S;/XF]U^KZR[L"7B'(72I:&]:<$[!< MD"N4A XV^9KP\H=_Y'I>LU2WY,?,Y5JF%1-87H=N/-K_Y+C%M?WO9%"3#0>7 MSO<)8F$Y=K@SC60M>"Y$?_[5<_.225[)HVFJDF7)I7M&22./;G0JYXAQ,@^K MG#@JM>:JF$K*):0=TO;JT9#JR^3]R(<,6.*JQXM1FW8YE;T.9R*>-%HCOSR$ M1&)+1WVHPPN*YTKRQ"%LV5?&IP=6PNK2:2K:\LL4+@-5$'WC.AYRA,'H\9JSW]LSH][#5V8@8' MNIO]<@N>$:%$J,2;SDCH>_H=3IRY8E]1_1-;OW!A9G2!H^5] V@I!EC9N&]IV-&ECE:.(SKRND;,+!'+ M>HK$_7D-0J<'%,-B0H8&M+3@(T/GI8PMTXQ&7[%+ MYAH?@Z"#:UT?'"UP9%AC @,9H&&EC@EA73&4TX1[%DQ+4]K?AP]LZ*/( MZ4U)&3Y9O6BZ_,YJIYBA)5%G:)WZG08W+06)2 M? ,2TB_6W0A!?*"@MC!KVK9LC[6/EB(02-3DB]" M/#P["! MX"80!,0R^J$,%GZF%P%]M-P4AE4!$_*DU=I&=8N;U^\(&-<_'I^I7GYF]Y-V MI_Q5T7\PTVN(F59Y(V:*$?8#E.@K]M+EN"\ECWU" @RYRJJ1]%-];JN[GN@M MV]=PP'3N[B[MDJN(%@PAW>N)4%_T<)*(?WI>(T*QOXXZ&@H[R=4V'7(7T,K$ M$,%]HC1;L)?QSG[?B!T)(O$G=3,K\-;/&-:0NS&K8@?-*R6.0O*=QD&CU MN*Q+?ES_[-MW.0$VR[.M.=5QXPW%;#2LZBF4#@*+.R[26Y;RDM7A6\HT6W6T M!PWZSW?KBE !O^6]G9->O?58YMF%E[95F2-Q ;/@\ 2F.2/.5A;R0R:T!8,F M'-R3S:*OOS]1IBJKKG/@:9&SEM13O]"-<^UG\B^H=']E5DG.Y+#O1\RW-AH( MI^#C=/TL^YWW1Z^ONXZ89#Y:!1FNS\AP8:A? M=)?F&7SH"5;D'X>^@^N6LRK'?ALP2+="Z:ZK+ZR*;Q]ZF98SMQH%NR.R/D1$ M"B?I$6.0S]VCI'%R=T$8OSMIM66-S MT[:=>8X*.*( VFL W$UG>+8*I:!(L)[-3/J.48$8/_;T<]Z9D#!A\WZ^;MH%B(4ZN4.S+=O[;'84]AP3\8X?H0^X9_1.H8?36'3V^Z>UR:9;,3( M$;7 I*'S6WQ=@V\=Z9;.QIJ.$N^GF>X=RMZ<<4]ON?SLWL7;D62#J(#=\*L*IM,"JE-160 M05K%S <\J^C=L7E#KKZ^A&Q[?+5+L6.D;/=>U?6W$6_J;DS=T4!6/$:)' M1[!J, ;:,M;^.^&>4,8%5*/Y08&L^;C^4#^'X=F%E7GOAP?(E4 SFE'!JFB^ M5"%+&L%1?A'#N/X]+ZP^.AJE-%F3M-S]K)-5W%4H-1=&/U#?6@L5Q0N.BFT5?P&Z+ MU]F9'=K5FQ/6'4V6#99Z886X GD&0'.DS/\T(CE"DQP!\ZM+*LERNCKFQ;3F MFRS35[^\/TLHB[5V\[?"Z@V"/#W!+0H@3GL,B=FOPR3@6E[^OO#>Q?I6-GO$ M[_7"YJQMDX8'NMHR#KAMK=@(1L.*2D)I?Y9N%2%,*#T(^FZ5_V274I'PZWS7 MT\L[;FZ?P8KC=O8Z:04CO"H8,SHU<:O2$QQC8>/L[4'Y8Y?1S;SL!'/;\,V[ MGG=0+OR%-5T52IFF&UA(5V(*TL?747O M"YLB0Y$=L&*<,//%'UQG^ET1JCWL\R]#\4GJ4M*.-0#KMLW%(UF(*FP12KLV MSWFM1.+4M^8SFE>$1:\Z6+B9+R":=PR,HJY"Q#2+,<^./=#R'/'5>; M!^?\]^L$*F\L>95M*5&9I7#9"/]WI:S_)TZ8\^?70L886>B!Z:#RQ "!7-C@ MUS]/YI*_ZNN?5W\84OOSHLO+EEYX_/%5"?])3=D_^7I*_/B?__M?NU[,I^!D M83UNW0201%H%"65?U)@I?QZV/50MEUY@]:B/0=?1IR@E@C56Q"*@;L'-(8^ M[5A.=!E.%'MF&S#\1>Y/DV6?(U=19RA@(,\,TG@H[&96C\==*B1@6QX&]49U MSH9."\H.^.0%[\R==M/?T.BRUET^GW449?3N\]\Y\* GHT,H#? E2.^%YOU( M2!PB5U_(X*3A7/NQU=\Z7_G.?;Z<.]85(J/KLO%Q9[WBV9OM;JC \<_YZ$2K M>6.*X:(/IOO&1\R;EF M[?-7F)7TQ 8+-GW5!T'QSF'+L:^#N4/;2Z^5!Z^Y6OKVMZL:AZ]*Z7OWCO_9 M&Y-_J+:(^E_/M^[U#_3TGT]R^K^54_[_K9SR]W3VWU_E\'\K!/PW%V[[6UW] M\^>Y^'\?J'^2/3;_[(5F_V)'?]V#'_K[N_JG&R32#M);7'5"C@@E 4/S7 ZO M3%#IN!%:P,>/2T(E ,LL#K,*-N%HOM+SK(KS/-SULB;E]'3?^^ZI';0W/SWO M%)\K/>:0(I1BPHVO;B-&0"T5!"&3U39TNPPVY>*3*^1ZBK&) M5D;G[YZ>"]YBH1FH+Z65OB=+C**@@**TF']'W9A&1VJN0OC+;J 9$*$D-PM',/(-ELVE2J3)0K4^ MRX/+EE<-UA@\O^,JV=-&TU)ZYYT+!PK((A2^(EF$DOU.3?2FZL#+>T-Y)N)& M4,0IVIOE0;>R5K@<<]+A_WFDY6@;L3"P:N*.OMF:,^2C_:KPI7-$8O.) MV1W[GIJ'5Q'$;Q["3B!31PL#/B\XJ@(3>B+4^P$QGI4*EPYO " 3O$#'I9D. MZP/\W SH $+L?9F_[#/BR9"K"/7#"G4Y;2<1L5<9G%#63X1RR02K12AIC/!3 M@5"9"JO6"3/T)H*%BEA!MQ,F<#\.09_-.4M5AQ&O_I&((+%F%Q'JQ6,1*MYL M:1U4A"IX#?F(4->0T!6Y3W)DP+L#"Q:*4"P*]5L,1A8+9HI0X&% C$"G!:P>!L(\$VW4' V&5W?LR1YN=J_2V!'4Z?;RO?9S M=8Z!I=B/V7^U$?A?>?]Q>0?_Q'4M9/RY0,\S8B]B854,>RK.%':?P#+Z)[H+ M*8TO8@+UO86*_I\.GS"Z39-;\BSW]O]IL_??*ZTWXXYA-E.!Z M(L)>;8%DVTDRX% ]WY>X]?D+KN/S(=L3M8V*_C?>ZIGZ>@RQ9ILZ-+:6,__U MG_]_Y?U_D=?_3[ 13HPHWKM43-GT=I)!CLO[KF0NLP-3?W_UOW/D?+N^?"^'(;9=]Y6OBJ#QH.GM\5'EX+2JS%XAWGUMS8?F^ M%?%_MLZ)D2>]0^3?%29"*9'Z\PP$%:(Z\O,FB@@5N+]WK^/_O1;0(\5-C:;0 M99!\H-<^))]>[-_-D3LPO<44M?+=FZTG2.CM6U6^?OM'%K4E9S$LG!JAFMW1 M[(%OR5WYXT(N)E7_Y6#QM66US^YH.-U7U%]^BX* -;WY7X.M^\X=B8SM$]5\4DQTLT MV9A6,W%X';B^DHME!R>71F'1!, C5X3R';(RNJ+RZGZ-:X#;B/ D16"]!4_3F=W"1XNE2^H-6OWA/2H,_<*(-FV/LB.$SP;SKZO M1/-VW-3/6EC?OR;[4,*B=YULQH:/7O$TCWK5+[GF\?O2Y';C&$;"50>Y1-N@ M='(YO%F0$.41-4/"3?1PT^WM#5:UN54&!]\$T;L-Q\+Z =I9HL8$ M[@H9L[0U.L_BW3=-#W13GH2@((JZJM3Z65+IM\<1B@R[WU#$RO9,AJ.=1.JO M?9)YB(/;067=KV6".YBC3]'0AF)8Z2NGHDT*]@+KC_25-^J=:C3FSHX_">2* MNS]ON-HW;??YY+KEA44^-NU/Y?$;'[2>)KL!-">2+&D4!Q[ 7R>+"56):&[' M]085_F:HP#6G%5 GAK.82F-?&.T/E,9B:E?[DL CQ@= _QJ9-W56(=+04UV),.XD*I8WPW83=6 \LBXS2(EX/"N5C.H7LLG":L-0R' MQ90>)N0U@YGK/I[UMZLZLN/"XQM*E+FU:PS?Z_/CA#*>_#VD<6#5.G!J9A%1 MD*^"6^7VP5SQCMH<$B[C^\\=.NK@CLTUI_!F']?\K!*"-8_+\AO%S M 3YFIMM]8JHF?[:XO:KL&/]L]*V6:@6PAN9_;IY/)O,B=4Q%J#%;P<:_[<>H M]HZ(VM.V8D/12]OXE-T[BGF37)?4AJW\S00SY_YPDC+!C);GX.^(5L=U*X2- MS3KY>/!BC]TPW[A;S^Y$RK&F.]C/EXE+%;BW(G-40IV)8WN(\_8(LDFJ'EP< M+Q-*%$/"F-)$8Q[S9772'&[68:^34UWU]O(.X\)6_.*NY(5\R1Y,5<(5-AY: M'PRK^>U&NCD%+X %3ENTCB0W,>GD(+GI!^AA^RA[L*H6[^3F$/N29Z=AOR M]0Z7WBH7R:XM &V'.ENQ$M\SU$*O?#HI_=*^V'TCB! MT=7=N,BLQL#R0!N9XDW[(LQ+@#G]QFC'$2I @]H?'0/ MNVQN)YT[Z'5_MV^OZ_1A[]?3//I>-N96>CTCL)7@J0D5D,/!"F2?<>ZW,I7S ^B=K&&;Q M-6%%?8U;2?U[4H=L5P8;.=XKN*TW:U-:?[-KE_K'!SM%*-=]J\*$TI?Y7@!M MUU)R:IH9-00?CUUN[V_0CDT&)(0&84RT$G],-HLR=Z% MFXM+L6GVT#R4OL]?%P*( M-2JZK+C"JI (B?2?SNU!?,_BLX,F0P67MC(*QU;.384^C7VJHO ;"8"W07>7 MLKQTY)DT0FI\ZX PG-Q24^.X;1M:H Y.O4?)&7W.G2(I$ R@:-)A(N (&3QC$FT29K23@W.(\WM6D MK-.U\SMU0W=-CQOK7&MV8):;?N[GQW\SR3H-8!6K ;4#F$K)]%+$ZY-44KP@ M&A"HDG-M*'Q7W_#,29],@Y?>#9EK%W5CWW(33\=<,9=:CHG'AC"AM5@:=13@ MJ7!S9@\>XY\BAO0)[0F2339YZ^NAP1CNP7TA%59^[MXOSAJ;&>3P0H*<=9IL M9L[8U)^HFPYNQ28%2$+N+(] -M!*5SG\F:0#"N]9"2FEH=[+C"[9G;K1D/5Z M*MYKGUM%YS\<^D+%R/P= ,V#>AJ72@9=@%$;%U MI1",;J*"^=]L>!>\?PD"Y^9E 25NX7 M2G_G#K.OD39"_N4AWCB%&IPJ@3?_6R5TI?!]P+:0\]K?+!2O'N@WOL?QDK*Y MO8]M[;D=\15LR**9*NZ(1?3:P3[XP6?K7,P5>UG^KB\D['-0;3B/1AGY5S"#!2.(= MUP56LN&=1$()50M6J8]]X6'+F/\+S MF#R,-B+5[PBL@)4SA#+K./W\X"6X$Z#VH,OM509>S467:><+)EJ]BF) M,LO+-R[B.VUZK:&R3N%^U J2YK:T"4TA M&RZ&-=N1/&>/YJ#ENTNP5^99N>?=3*;NU&0Z&\9%M&,W/Y>H4TDK0?@YM($. MJ_B+4"V*[43V7= M$J$TJ*>HH_V\=,%C+.NFSE;H2CGQT !)TG>4D,AJK&3/[G,L?'J*$7\G3\YZ M>FZ[N/J)+,9:HZ/BQG$?=^P\_/_=N]65^-$,H12636>4L/C"=QCP<$8*4X6" MSFC<.&!685;V#9ULSA@E;%BYL([2>%?[6G?HTTJI28O9L87??ZG!FA7\ MW?!Y:)AO#WM##MQJ]N!\:Y)0AA@QU" [@;O^\EJ"&^Q2R(@YJ7'R5M;)&Y(? M/BD>?E2YS$WB7NI_(M8'%/.8$):+$THO'<8[F\([CLSO#A)]W(R+3IIZF=@R M%#VNTELX:'4/4ZM?<9DM'7@ETJI'[VC9@JZ[Y19&9FF4&)<,:WGS+Q(!0='1 M05B-OPZJG7>#-H V[(B4!T07;GI.C#X6O DULHERZ\==7R^NK4RR\^BQ_R*O M8A<8R'^%ZU&#E FL MFEY8^"0) JUEF)G59<^3MU]U23S;O$7SUM2-;?GH?7^KT$G%4A7LW_V%8_M( MK3JV54M+)M A$V^.A"#U4("2#T73'5=Y]^2.O"\!"SL2NY+%C=JU*S\M?[U& M_O)T9>-:>#N(;<8M"\,H"=<3GG8X@S\2OXU6?"\+//!'N/:.[31791?G] :&UV MQ3GVX0!/LYF^MPD.L?@1%O["F]-TAIY0)IQ_'#Z!R&@G?/,2&]O@;Q;7:$T: M&M_0:Z\2R9%S1.N&FTL'G<);73KS?"%OY^$CRF.5$7<+#+VDW@T4"AY269-8 MM9:BPU]^S;=@1H)W#&6[WQN+O^2!YZSD]7TT#FOQ"RG1/6^??03N2ZM]90.K MJ='R5" -K@@EE/["<4!OJWD'2[-P#!MW<+HE3"J9OCMAPJ2 XB39J16B7B(J91QB*4'ILJ=:UAR W'Q$V%Z Y-MK"^S+:<+*4[HU?V=8I;+K.A^EL MK+QE?;;SFPLB2K;A;Q>Q+KH;L@9B*X M2832(MRCX:HQR9;7$4U+;!^7XSHTWB\-57"HNW>LL'A>HKG-;)GSZJK,,[) M29L;8LYF4,<.,!I6L.!$AJFY9CP]'.(;?LV8%#*W?G!F<+\D5][&4?)$(./E M? JV#D.;A_2C8:7("=(+_JZB!S%L.]SR4R1-::?>W,)J.1T#!UB*@FM0AHEN%1: M-]!>E]N6>'W&3%HQP$6EOWY=JTOH=3&[ +;BLK1FCZ5SEH=>L,@,3:$,';3C M;8(Z^8&$%!:]!2,+ZW,ETQWUH9P6LOS!EE3=YW=\1J5-"QWW84-K4L5T*\>, MXE&-88/ 4>:(..\1XB1#32R$,KW(H)VBU%5S>^Z'Z!)5H77!9G>+B5LJ;P'E M9'N/)[8W?#(,22=_#FV9K<=KD=JQH M]3%(H4\W&*<-^O=_(24P=>VE6BA2% M+D8HTV_HKRG;VHH//\_;P.;;EZ7$K_GD5$2\O7(;2JL.5F0*I1?Y8@0_=AMU MUHN_&@%$GB0C.-Q_F6:*79F-%S01QG98O_YY?$%;=X/\$[=E6:^UGBP7C\,] M\/JIPO<2]B"3A&7E(8$"&$6WX9X%7ZFA+ALGAGDJG,*IV,NQ^#NJ^RG:I@PI M??>ZZFO&9V\$91]X^U1V5.^[M\'WH;^]*@6#T#RBA!^78LRVG3 M,0>G9MI8K] >%&@_B[J"\#T*LC\&6.ZLP%/$@FP88@E.KY\8ILYFF20N.RI" M/?C.I<+*4T(9)!16H:];HD#Z0CTT;P'!A:TD*Y3T3?ETB3??HO0!JOF\5 M6S;>+5.O596C0.U>;?0V%K.%]':UY'4JZRX9] \W$DH7@$JXK M21I,.AZ__[;RVJ]JH?32(58JUV8FL02JYE$$98X&Z.N8FL2V,UGP#B[MB-]( MDTQ5B.VYVSI>C_STM#;.+P3^W!^8IM9._;LCJ!@65B1S;&;5^+:D7B:">Q0# M.[#R5O1D1D;35S\S>5AMR-[_J>0 Q4-S7[42K>B#_VNGP)59?CO6G48%W2 F M)97025T B'!M5=(@3I+)BT4<1RLQ "I[3+S,/?3@J!6?%J@K5.]DS>TK)Z*9&P MM..?E0%0/-N 5(SB)Z@PFF].=!NV5P+GV::UGPYQM^O7\AB!']RRAI3??A+9:,H9 7J MB?E1OQ:EEH>$[?2= Z:^!_3K!Q@.Y]HO=7[-0<5D/?.^G;[L:;Z73-)3VXQ1 MOE!JJ;!C-32%_&P!O_]HPUQ[B;E^_O^T]]Y!37WQOF@4$:48.DJ+-$%I*B"* M2%!$0-2H2!>B(@(B1$4E:LR6WHV@@( 2"PI(B70%3*0KJ$A1FI!F12([EK E M.\G;^9T[[]V9<^XI<^Y]\]Z,?VR="7OMM=;GVU?Y?F=3L4I1)%<.-JNY[L_\ MK_E<7GJ0YT.KVS-'G6O=C_K-G=]ZP-Q<:0PE]!7H@TR>/XLYAGTF5A$UM7JS M1;&OC3C\V?5O!FH4V MW./V=*/',>(E/+"EFZ%C5S3IZSW$]!JHLJO:MN,\;>;$[(.FIG/G/O;NB-?K MN?;A:,[IR%GM_](Z_?_\F']F0JMI,S*(/6K;Q0@-E*#&;+HQRUO=6$_5?-]6 M6?W.8"I6KHH,0U.%\M!%SG? M(@,C99]>/K+TMV:BUO#4NN<1&Z[E*?KK#VF$F ML)S8CEL$]O=TBU8CN;A/34EGQEX.>IK,K%]?8/08L;ZO2TB/W"@M^-,#2 Q# M7RR]O2%^0T;SJRF<;[.0%9876KGU_O&\N6L1VM0K8SQ:SFJ-EZK5Y/#W5N_T M.K1%\@C0( 8R]875YIXA\3LV4=\(V@+^[ E@I%K 'GP9+W[HJZD&74]C7RVZ M#W1@^^T3>+-#Q>I3VOFY3;M$_==+/F2.?%527\!/F8E%*% , MO1):D$B#=#MBAUB^2^A*.O!H*.K[W?PVO'+KP>A?%1VV:-76&K6?MJ&=&5^> M*X6)_SO;N2(*[=]V;(]>]92E2M_NB>FKH74!'J)E0I'&,>8,J4=V+&?8H45 MPMV044?-I,?I0DR2HZ=&4EGA-H47'[=IQ/Z3 DX_=[[ %47:=!&9;2@?GX$] M3$B5H!Z-=#$0CNA!Z_J3W(>C3!A\(*.A;+;!4\$]V/2BSKGK:]U7K5M@*$$I MG]-;/I(+.R%@GW4R@U>!>PK "38 :TX(*L#9E/I VX9!VRUJW>:1$:$+,RU. MN>IKJ%] R9*+!ISU@X2ZXM=T,U$N?6$$(-L:(G0E3G"JQ+=BSEK0;:&D-L_+C4L?=B\WO-)[V[=LX-_?%21):[W:B2Z?P4"K\VTHJ9>,@>QK7/LYQ72G1 MM T+'J2,][D/U&VQZ6(0*K,1^$=-C/ M!:2I4]HI5Y@@+AQ@%3,;\KO0*^!]0WFC::V7.)<"@=0 7O318H6/3PP:WV\[ M:+A.\;Y:B+G1>JHJ2("5KP7S\9W HDA&DQNL'L8I[6'*P39OV6\=T>!\4+J(ZU:8MEUB7MX9<'8PRM5A>N_F>.![A$R6@#7%:6:GS&%B=(*""OKQ] M9=*T!VITW6\ ^LR^4/9R1[1=J_F#U\=R_*T/9U]_H==9Q/4Y:_0QWO'2^*=6 M)83BFT2W80PW"-,UP@0/ N-]?@D[WUK.KAJTP^K53>"-]YO?,#D(#SP.JMR< M;#>O@>=(3?!*=$] B.*.HX17.67]@!9L0%; M!T^08KEW%/>%Y\EMYOWZ9B:7'XZ)25Y9T_$X*-[#7I3TGSB=_=^1^')R#P!Z MS&8R:WMZ7IES?3.QK$I\O6^7I]*&J>G5) V^0E?W[,Y6&V>^>9\*UF;'07=Z MYN61L5][Y3HQ]8C>+)2@.IGUG].DI9Y',P13_+D9/A>;J@EV\?6ME_H%3&OC M4XL-&JQ*ZIXL"&F6]SO?>Z%N[=Y^(RQ!N YH,Z.KBE]@:C&=UF.E;-,N8#E% M%?9*\:+V8)?;!7YXPM>__W#J&=^I9&@]3]6MM=XS/X]7I=KC*Z;3SBVE\7*#]B,-IB\.*RNN$-3GV M*M.1TNMK"Q#292.$QY*0^%=VC>C6'=%-L1'TS1?\?@N=?H9WZJR2ZL;"$,M[ M=27$W)V\(^_YU)UST__!CCO]DC3:$S]S0,/J?0)OANB:XV%^1B=98<#N4L#@ MK-]3L+?]V-/DR9<9QSG>H>L*MN_7M[GA.T6/OWL9:TM:+4$M_@T? TV3;6<7 M0:9BA6RA?X3VANP0C;S<^Q'%=LJ!_A/;XXR2S884M->4>7LC(KN0GH>XYZH2 M%-NMAP"9UF-!'&&\CY.2*3;[VG=B^Y03WZF*T6EYKFD]3O;'^ZL3T096*LN3 M]Z?5Y&87X(;4]\I]'DD 6(F%<^G(W(V"$'>0=0^KX>0$8=G%M&7E+""%;M78 MT/@H<'3Q2NJ^\*V7=G-UDZ]%;#K4E3V)D8:VUQ (57YA(3,F#\NBC=_;)ZH3 MFY(VO1/K?[G;U[Z6J!])]-U]\Y5Q;7"'T>J)W 9W:/N6$\QNRRR%>\?@?P^R#;6L^?\IJYQU^ MOXZV2_28P M?>[L1*FT3*$7_@H#W1K!7_PQ^7X,*VN_PJJF&GV_#)S'ONW)4[;)&@>,/_?N M/[TC\E=R.@KJ$&Q&(,"1CHGRG)PB\-JMAQ'F/"*Z2U_C%]$XM\^314L-MK*_ MX,TNE$L+]DO[4[B>X_KKZ.(Z:5%5R,A.@DIC1/2KB4<8-5J\I]S9,6XWH&S) MSN X!JL^:ABV9:@XNAP/\@@[O;#GC/JCG]=_'SMTIW@'T(3(0ZX$=YO+13 M29M"GHQ-T@,A*?.^BF36$>*&V-29/_^2V!9688]^+WFR&]U>;)+>/KS;0/;# MCSOR+1,REIDWT3M%NQ!Z1(NN2L\&^%+K/K=9ZY#D1+>!X\@T,/6:%.XU8X<" MJ*,"F5SKN?T3-U;5[OJ5[&KA?S'/[J>7%&>QZ1N2["6A)4F:'.TA?!IDS,R5 MO["-!994':V[Q:XIZ/,LG3A^^DZA@L_[Z2-KV+FC3C]>!OXJ3$=]("^ ET*^ MPG6D%2!S!J&26_O><+(:F)>K>>O.UY/K#BN:.=2ML_C>F1]VQ'^LX$:.1W7S MOU\L^._S_])#^R@GP(A2)*AH'&1.X[W@,]EN[92)ED[])1)4HE&G=I*07L51 MVN-W/^WWICM^]_Q"='/R3= MSSIV;JPE;$1.0RC"7\:"$4WP?1M!BP351!$YX?",X?_2N>/_'8\O"PUK1TE0 MJW>)JB4H'E>"PET;F?U-1B%^[P/FC^O]X[/B*>RO/UM09 G2X#39&OH)VK,% MM5.Z_-EN8.F7"_'=M7;)-(YY9$2\_>21G(TG]'MTW\CYNY[$@.\PM?TB75J' M! 5;5 (0[U__@HK]Y8M$R$J'A182U$ OC)6@VGM[)*@K(^S/L.Y9"4K.+ _ M'HE_A('5BCBV,6V.A#"^%B-NZ544/7J8L4M[9=SKEK1'V?)G,G (+ MR_,6;A0/8\ <":IC"RD@DQC(4N/P.Q8I#/%,Y M_3A\)T::CD[>3>@&M%DSPK^AQ[4$%T88+00.07%J)_,07S9YIJ&JG=)9DO I MZU'?>\RW,(&ZM.2PN!UH*IV9*X%C0:T>K!)$OEC6>6$V$=['T0G<[>;:*O.Y MJ7"3GB?J]'YO'>.#ZXMOHRZY_7=Q\66C=2!KSK),NA&HE?'K:0PN0MN.,?![ MR??#5HSS+MU=IS=G\IWU3PFCR!/2>G6P&I.UN%3H01Z:LA/W@ +JFL")+@+Z M5FQY\,80C5N5*Q-L^QM2#U[6\!]]:+06>HV#+*FP>H"P8S?_7@< $F:[S:G) M1] -#YIBN8'FE\[/@'X[;7%U]3,[21,R-^=9"0?S80W?/0F". DJ(5Z".@R, M>7%L/6-850XCG?HV#J'/7FH5WJJJ>M4I^P:N5;_DH"MS<^E!0$7N]_[+CI&" M9:)61A@!,OL\,_M /,BLSI@;654M$$;!BI!!Y/WWTTIG.4RUB,;Y6R]2 M D>.7>U9[..A9YGCF9&XS>" MP^;O-?\$_,R\(@BS7!?)[I1;SUAP]&"-8UZ MBN6@.BX![<)!Z&C>X:!QG:SZ)N>3R>/Z1T_JPD??)^W(.IJ=%FH2IZ9AN5)N M>K<&])/+@*RT>-D<&K22(EV_PBE"Y_H[\"M@!;XE68>T;V3&]O#Y2'9+6;6! M9]61S5Y/ N>\)MC+U?U+-\H>D&D"93JP];/I#=C%TA/#\;Z(P%T V"4-ZGRE M$H8*78>TGZ]_R_*6^ J3_VN@37W5MYVY)^4?/.L IOZXGT2_Z4^G-LX]8R9B M&TK;F:.EG2,7;M(=H2?+*DZQBS9O<:Q7GH@0Q 0=Q)VR42Y[G-C]L.5F"ZU7 MRV(+F:ϣ*ST9TXU(QX*G2F8$2(EXPPO^<9,KO3W+T/L5^ZN)6]RC"<85> M=899H8**A86>U:X]1W\F9']V&FP-&75R(N%%#5@" UJ#30-8>8PZ:UY0)8R! M -#SV7AP*3^6@TX^ QGS%[>4XUW4&P7G?KK?C_+MS=5M1KD8/_NNHXXB%PS@ M422U-P"K! ONFLW$JIB*[M$=OP%ZV% 1FNT]EV%)-B!V3[K!?[>C=M*H( M=RW$N*GFQ2*KJ4I]82= 7I4G34;3M9;"JJ75="-?J<#[#&C(]C$4] M5SXU/X5"0";;AQJA7W#[:[EM=F##;&'+;\W3R=NJG^6NB_@W:5C7U4"TSZ^C:;MWWPT]?+V M9!^#;3?4/ MI+$>P\NV:\R%0KTUW5$XKZ?IX^/CJ_(XG/,+C=UOYYT+:2]#Y>!0\N7_N4\Q M'"4H5IW^J@S!?=$#((P)F7PJY[N)56A)3#6CMW HOR*P_FU7Z01L?]]5-SN" M&:ZX<.O9S4G9<!ZSJ(@:ZX^@Z^S=_##V,,7 M(./9_)4GD<0NET MLP3(?5*S4_/?5EE\9APQAC&:Q7 M^9 MB?AZ]$P533PRM9 Q!&/X5+93@G6&DQ9\<.#CE?'Y\>G71J]G78[D:V\ MY&IOIYE7]L\PW?0G$;$10*2&*.DE8@@CC6VVL7.V&QE2,1XKW<:=&1[C #)>-A2RPL(X$=?L;HP[?WC^ZABDH M@F2TT@D-A"7?Q(M'7&EI%H>>G/RDDQ&4\\(QX_+.$D4%S84G- Z@A/;BI;,( M5>- '.\.G]I)K<5VH\<^=V,7D>V)GKN#/'V@2&ZNS\4BU5[&\=HG>RMBEEOK M[^DTWABZK.7&":!M&\ JO2>P@_(1RRT(@_RG@=?;&GY=GE@?-OM#2MRZVI^7BX9295>Q@/W,J%5&%B]3O#S$7^J1>@$ MT1""^;.P\@RYDW$''OWA MBA6>\!&[922M^@:OY\?"JDT=P>;\SSPOH4/$7'-^YJ]9I? CSEQ--I?@V(IW2= ^G\V MS7QDRM,#AP3^H-Q,!(>9J6\-W2EA,L,=<(D-?G=NBJY]REU$T-$RM#N_?EV2 M"UYZ>649>1/Y>7-LV].+8OD)(8X\'HQY2[80#^G;U8"SF6>5CFS\510DY]T8 M]VZH0_.-38V+[KJ/01,V.Z[:WXD.$2L PEV0G$!:!6I:W(VOIW2*=(*';:V5 MB+@N"A#&SC*AT4K4_/M/%!^0WWH-O?Y:0GOREC*98?@P(OPRX@',(M(6;"=S M'! O21&Z0-;/FOU4B2E=>SMD?WR]&K;XO-&$\I+-=0YEW&)7 MX-?FR6?Z*9)NY^$KI%M^S)JY3N;H9O'2LR!5< 1Z.4U?,V#;TO?JW."FSHR0 M4Y> &-*[.]=S0]#CVW<=R+7(/'!UZ^UEU\3RH0A1-$!36,V>997-;^EF*+:Z MWNG #T0KA^LO!NSM&YJ_<.5=GNV][M?,Y0ZT_.SPVHG1'DF #:;$C^!)T MCQ_6+D$I_@8@0X#GQ;Z(4R&F]^UJYMNG.BX;\(M0>;\GV^YC'_=#_,I/;M&] MF9%Y2+M?L+;H"7DC3!+EU,^.?A-$X3$=+$9Z'=03<,V7+K3**,6/EF#&:O$O MG8XFVKQOD96]L7T?.6R?'QWQ%^/S@#9_::4(8'FKK#1C=P04!'KA(7N^3M=> MXEFZ :QVS2NMU:3LX-$.P>,&F6:_M5>8:Q)J]%K;VXZ<1)=B6;>QX '"(G%G M\28P;$;$HL47KX&:^!D7T-*X;,/]ZYN MZ#%:A9O!2M7Z /8XFC+^>2:*/R>(X%.>,;.T-5.;F?#*8+L\A<2W9[H/)7]O M_R'S3<" M'&[-[^N??$DS-1+R1%PW6*-K@CT+:]X3+_W,QR/X?IFGEW,8FL28_856VI_: M(STWPDV_O;5LKJ)1SW$!* %U?$XL_PW3AAT_SSB"&7,3>/!+>V8SSFD;7^A/ M)]FQA!.1.MAE?B_J.T=&1DS[DCTT!G(<=2ON&!.<)TMAM1ZQ?!B(_+- +I.D MA^[ J\&;H%QPX@ %!V6 '=V""LW2NWUKZES,S':^(ICYK%[#W7SZP,+[=$0\ MXN7CN-83]F)Y&?ZU@WC[P%91V5GTLA!35J:\YTUKN97OM>,;8^C&'CH*:'(-P;^ M[V#N9"S08#W3<_BL9=8<;P5K8UCRCBOAQ_B7<<2VP53^P[* MP78I,W42E)LY*,UCKF".$6\.^D]:(-2;2@E*DTCK("\"JTNYE.7??.:CL^]% M_,0?;\YZ'V?8T)BDF-,[0YY^:+YNRV6[YT"''[D/^^LT XUHYMH:"8K;\&#[45I5=@0PE@?9RJCBGB-,]./3HLF;:KL."NBLJ$5N[[P%#9T M/[E:LA+S5/5].DJ4"E+387LN0_YK\4;P7 .A/$+[-55)D%LV[JYO7A%QU4.] MK&/6W,A) MTS_!*GP*6ZMSXLF,DPY\ &2FAC5D>L0L2ZD.G&QUWR.S-FVTS#2SD,:1H"A8 M&3(FTI+=KP^'@<4I91:11G['Q8:-C3>,+KU;;93<-G/J%>KL]?]%G!?[[]EZ MS K$8P7];F$%QT4E)R2H(]9C&0(I^CL09L- M]0V,$EXO,]NAIZ#QTXC93C)!V'&&R)066\0D,,+0T&H 5J/U8.N.E?*U]@?9 M/Q,;OR5M)51_<4@2*IG4T:^KTYPA8RB%\]-*NY& MV8F8YX[Y?U:<1VL!;4>PA]$3GEUD95$FP*IG@'MFT[ R=I$TC?'I8/4,3M3] MX8"5;]F3ZFJN91V"B!V*+^]Z*2>HADZZHLCQTAM!0#0U 0#WX,DX&B&-5VB(6UJ!::C[D+'Q8IZ])/R,3 MSY@(._)^2U"+9OAN,W^J8;^A[]5T]>D 2E9EP[)2QBB=S$=O1!0GDW[.)5\.I;-JOR9DPK9&?7TP%]@R M4G74)_Y,XOJD)I]3NM6=>M?64JR;,*N!-FLG:WB'Z!$C>KY?R-VJ6X C)?$"1W+$\\H+IB/1;3J M'H1VJ<0PQ( )#8_C&YHRR-IXJ+%O]SN+,W,#];RMEO?// MNY\[$: (6$)H@W8F R3T\Y:\:\>N*Q[_L?3@ YM&7X-:RQ-:D:(DYZ*&XTFE8Z,Q\+ MZXJ$2_PA\M3(+A&5$7YISP_S[>XG+)Q4>H\^OFJV0(W46W+MV0N9J7-V)E@;9P+(&:2E\X2#8E8L1+L/Q8KS<-/$/F@8'?"GB]KR;1/-.TT/0# M!Z,-LG,O=Y__6O@;!YFFP)HV;#QOC'^MBU';E$E>!'UFS2*>\*BE^ G(Y)C$ M=YPUN;;>>CQJ$C=[;['?Z9UW#(^&*I:>A*0EF&!=<^Q,DG !O.XQ1$/8]*:H MW!*V8>.2YI4RQ8Z$!24!)KTNI1/M31[G?B3ZF;371W=&^RY:]G84:+,1:Y.' MJ. ^++3&@@$>I&4PY$Z05Y V89<.M5.7DAR+C1J':;^%_B9A#DDO\TKNEOVT M.W +T 9>O!I9"'7Y_%C.F%MH(W&CX$#W6WIAX-7Z^.D%:@)XG&L#MF& M/(#78;"NZMLB/\5'4-5I9R@+K%/%JN(!\8*BW=1]XI<%=YORS*DK7QR?:ZP[ MZ!*_U3(E[+GY970+8APF+K((O DV6EJY0@"T#'^OQR\E_D 49:SO?%YQ5-); M7N&V(0_Y='06J!NO5YP>F38:]5B_.&HB M=I/.J,RO(@$=FN4PQ_(%)_FX'MQ"DAS?OI,7V/$N>WM0"QP/>.^A,;RGZ%9;\X_>K!+;*.I6D'H9X94*?".VFP!M4.!@>35EL+9ZI>!G8E29^LU'WI-Q@^+W8K,1^)0P M4EH6LS6"\W2/YZ277\M;PEGS%\Y*6SJ;-V0;Y^BBUK_LO*D8XXRI_,TWY5$1 M3D!S7NVH_\-*]< M]M4X>G'[X^SUSQ[)\9KA!E$)]A@%6N,&JY6*Y5WX7F+Y=0AK?X?DV/U7BN6A MR G'^U8!U]LY MT]X]+EUK-_.VW1]'@%4M03W20@0S@LX>]^==)#D69:*B$[%\_1,T5E,[00%H.WB&-M["DJ"Z^S7< MV'IANT8<_4NFIPQ!,NWD"[U;/PZ.;IAKS/'7T#NZ-_7A:-_Z1[.,4&L,,9:- M:!D%9"8JT#VN0DJ&!SC209&9;BZIJ?:WK((W1=EFRIU669(+XISJ"\/Q.ARH^=!8,:]/?].8,HG)WS!@4NQ^*\K;Z MH!;<9X!;6U(4:^"C>-?U"A8ORF:PFIV#U 26C'H_-]0Y.MQ^\_W.JJI-54NR[P/VS.\CK2F",E$368[< M,RY!=6"7D@):AE]7\",Y^E06<['?UPOG"TJ'K3[Z=3SO?.BJ?KBIQ28LO+VB MJ0^_"+85)6%9=1@,<#3(7C#1@NBB9N*<&\3F$);V<"A*)(>!7[<5 M$(TSE]*ZA0;9M ]%S)W3UQIYQTJSZUOA?-UV]NF*D//&6=[[W(W7K<0T7??= M!*:T!1M IT"&,ZB5X60T7;QV^%?6&AU/"4K]VZG._,+*LCL!GT*3?-9^W\'1 M<'[!DO_RY9_]I0T2U/4'Y!% P)>@2E]\FYMGH #6$.'/SC >XA<0,/.D8@;P M[UZ!_S]S3.9?'7:A,:=AQ*=-V,WXN)K:P!2U E]_7$")Q#0J-IP)F5@CKJ:@ M&"5!]9A)4"F+@#8=X*L^4QI6+".(-^'Q \Z8E4!'/):5Q?A% M(:0@3"AG+T'ITGK[H8U8L5(J.-O1OV1*>IUZ%R%Y,##B@FM!?@\@_ZO#XM/R MO:$-2IO\ZJ[>/A9X<@^*N?S94=J7G>DH\4I$M191P=W]XYO%\@E"-S]R/[[N M78)H@J)&+/RQ2BB7,F-_N+IZ.=G "&.;E13\ =B'K6/".GA$'R1#!B#@ D5P M\&,N+ORI\@=C#X\76_/#BNP$%:_)/-CN_Z+_]OP.= MV](Z(&,9+/1,!CAHG4"MP[>_LFZ;THK_$5E6'Z2_P<\GPGW]1D6//F6;5['7 M]\I)BREK*0@L$-8WBL3+85EW\8]ZDNZ,B->27P>;%AVH!3-ZC0AJ7YH6R/+B MFU9Q-D9]% ;?.I(ZTW. 8090 MAX.UJ!V,.OQ,/AL88PCNB;*<-GYEUF/B2.:1[#'Z\@BJ$BT:WQDK.&G2&N,? MM#U+8>NF[9>$]"#>HYT+Z\3E^YPQV8S:V#8,M)H"J]F+ETQR@$RZGBCO# 8# M^T/7^.ES'$P7D!AP/[&IKCJE? F[I;8Q>:GORU:_P\DXLS]QI!=[>XS,O'XP M>&PV%5KERVN[\T5Z*GB%!'4(F^ZT3%1AY>C]8#=;Y-(F0:'/6LM/0+N[.@DQ M&Q[XAF8NR9[5/W'H^M6*\W$RT>+DLMOH7@ RIV0B[K N\HT# .(C"3GY[51M MJ.^96!9L2C^#U_D6O !L+4S,FYN[$#+1_4J1J))F3#V=;)[KL>'[ZL:[B!+I MM%9#6ELAMG#*47I(F3C$*KWBZ";$DH<8Z#-:;TG>;+0BKNP@T<6OIB'9+$_\ M;F5H^FH#GZ@)7+_3FZ59ET5!"(7L6PV$^\4#3-"?ELE4=D+#B\'%#,0LV^R# MUE5"D9WZ=GQF?.C0=QA7/;UA:/S.D,^ENO/*/6O/'4&]W%6IWAS6"[!NX4'O MS5C(Q&TF^PXR).E61 FV#M\%+".Y0P>:'*P2Q MNHG=?9C7O4^<8Q?Z&XEBD9%L04(7?%TI;\5](D60C,PH23R,EZ>U+N!@QKTX M%@[O**PM03N97^9-"M];ID\:H'HV!9;+&,F>V%&Y+7^<<N+5@X:[T_*[[$_F+'5#Q>]PGAUOWFDF0^'//L,D M .ID^2#Q:T#92?_K/"UNMI[XJX*A%&2P87#,\&')HH7+WJBX!0\3YUCH-D8Z M5M8*$3ML*@9]1N3[;&[<\8(W,[GZ:E'$B6SO_0L7R(4ON4<[/F-V>QFVAX$B M*\'[H-6QPDVP,W2Q=)HN1Q_@#E;#=F<2)SR/IC^\JKQDL[.KWD7?S_VP5HS@ M/*C5OL6+Y<:;I,$K<)JD59"+R5P"W1:RFAKX[ /NJ%KD0XOYN/K]UU#C?2]J MW$V)QDD^1K_&*Z;G=^1RE-9\VSI2WW=Q0FOX> MLNXKX[?>1F]I '$S+4(_='0&2::.,*VSG!<1R"$1(1M?#S4H&=]Y(][ M9=9/MX8#9_O[$I[;_:#!6CAN4P<3Q5H:OJ&N4I7J+!PB0'KQK^31G5$GR"N,+- MX?-ON>^GR;*@7+H/ 6U1#9PW>9H[N+$Q^\G'0(4?2=[RLA<8,ZZ( DX7W6 < MH:06YO,6:#*XF#2F9D-%"*&"% C5<#3?V?5_ 3D.P'4=AA;GIJETKEX/H/ MRK4[JU9M[)[QO0W]'Z2L!YLGLP,LC@MA$Y9%#(Q'S(?>]&G4S$;G+ ]Q3LV8 M446YG3WR,$AX]4QI1X6EMKOMS^+ M-\Y\=';3\C7F/V($.&1V75+!W8E8#)X0T41MX8PP7)9#4QK)I#RH[2[IY)LS MFUJW/B V=WW7=S]VL?%LB&%E'$IGXLC*[)"S:P"\V6WT\_XD\2HH"7$)BZ6? M@]&B%KHB^85X(Q0%I@B @8:$BWQ3SK)XVPH):OG[*>%G[Q*)F]L#9^RKK\QL.2Y&:_I:-EOH8XK"K!E:I"52+BW#-9M MK$WY11$,@;1.="H#/(F>,>47.4-XSEE0U!0/>SO1+L7LN)7T3U=^TSU MJOHG)Y-T$UH^?ACYVO O%3WX6%C#6G!7U,HX@LN4H)8R(O )5*7?0"H&5?D] M>H;L &UNU]>^(D$%UE_9;CCAU80Z7Z4;FM%\QUM_6_+*G?YD*3GBQ8-Y2/>7 MFCIHD*D$-6,*$GKF@A7R$=^6@\Y@:,!>K+ZG1CO?V+;8K!+Z%7Y5>=!Z^O-Q MU";GQ:S7 ^1.Q$K=H#8F%F^1EN8$VHX:(O^73L(Z?'P&70'VA@*U$IS6X"%K MUVO[6L'&^Y&.A,BR5P3EJ7>OU-=V/99IFGL:V.OV'#K+O14C5D#\4=D+T":A M/VP*>7"5C 2 J.#7EF,_]_"IF:U;G/+H:_B:I?+;#&J3S_KK;_39:+)>><,- M?S_K GT)ZNT:,YD?0(<$I57-8"5CP/W,<4PGHQYHQVM/PG*BNR07 A>0)[F! ME&0KN\ HG<#5IH*DK%_G>OO5/"PRGY\\77,'E1R#"9/F8@'GNM 3'6)Y&G^S M6$&+PTP(7@6Z=3PFZP; FR#K$&Z0966#WK%7T3[3LP[X;ZSYSYC-?AOV=^A#2%[I1=K: ;P?5 MHBQSUCQT=E[)6Z!^EA>4)+T.F8%E)>/![;2%1%\O?D\FU]F/X2=T@),*8V-G7A$AC:C.,T79*;J-A)+8*^&-00/UT/V;?/ M!S7EZN45K?C!FUOH\3-(X^C5'."\$3=S@>@IB0PI@4T"*F3'P8Q)4%Q"RG<[ MPE(B#;?!09P?53'I9S=9IQQ@M*6D9E?Z:(?LJ2>>YJ%^"?P4>!L7@1KQ'.\A M6N!E$0<0^[^1^U$N5(Q4"MV?&\UE/R ^Q[YC)B(@_S-C/0&1&0 M=;^5IO&V_KEQ^H'#IB\K,RO1)UU/25!\!0JL?$^E1S%UOLFP0EED7D1D1="7DPY;ALV$;W5B]&5B M_"2H>@*LFB]>.B(,(GGF-QMNK(U(Z".ZDJVJK5B]75 MKIA_<3"3^8"&3KK!*DWB;-X_^R>H3PC2N;^I*?5*.NT79"E)K9M*W2)*O^:= M"A@-V.[D?CAKH:'UH[VH>>]>1"J&N'*\&.$YH&TE@W6'H2XV% ]BY<56I&C1 M#;'YP8#I8C1?+N%>OG\1>W+0_(]@USK$GES@4]:^Q 2-=:'VBQ=="T_@JWG=-?ROQFYF> MUZ/ZAO[T\M@2(#$<<2#RT.K^#D,E\!, :6 & :(J:-A#QN#2=-"$, M^P0#W1J+2;;M'K8#EAV=Y+W37/!B61,Q5O?(:I6"736?/^ A"\UKE8A D<4F M7^AV2/,]XBZJ6@G?/J'5LGPK%\B8%Q>8)E?:W3)[]M'6^*>@:&RRX*U&^M55 M1]<,M#CBW]Q77P 5(2K&DH]- TY@(#MF1S.N#3?*[)E:0G_30$!#9\DK@HG1 M'V2PN8-5"'^^0AJ:D0^V,B%9'BGYUX.F19X)ZK4H8WS':FUO2=#;U+>I9O)@$@\\HPR M6B%>ZB+<0SH!26V7=*\P:ASBMNE;0=D AYF(T9U@34-WIZ(B!\4OP8:;!QG(CC?.9Y\G4$:2(J5IK1"4V7(:G4#80,T'6@ MUT#2-T2':4'5OL3BZ6T:EX,VKU.5R[/'F'ZVR#$D9R.6(PT/[II-P];GM^'& M ,%3Y)O!I,W05KY6.U!_H-@4BN-04\:KF,DEC4/1>7Z'T@=XA/>)6JH.>4ET M+NF*[I6;]K#:M4X,Z,Y,9-;YICB:<#"0";H3G0XTO-0^A=>$7+JIK3AU?9W$0Y0LTA8L7 F43,\4./F_J,K/N; MM0@=#FV(7CD\J)'J_IUK(?S&QFJ8^'-XKQP%@]3#I6=[4-+H^A!,L M%L5ACV+2K@4&$6?WO"7A^$4]9+1#\#76-_<5K6-W"L8R#JH?TUG\+O1]F;'E M#P$2JOM@QES:):BZS[!&2@<>],*,RPCTL!BQ#%3*O@MA.7L*T/$(]BDDK$CQ/W>^K(_!]XO='%TEZ!HMGOEN"-M&'5Q)[,!X/6 M'8,N!,+ M&>$ZW,#@E*KJ&KX7%T]Q6J"GR71.EO,PR-B9G2/G<.575$E%%& 9O[[R2O$U M<+,@BH_O(D"6%%@=VUZ\'JQNN _YW,C8K.(RBU16Z*]UFP M*KSOT:'*D[YR&O/G75%D.7)G#="V41K3+<+-2$]-9"&H>@10T\6+A@E5MA*4 M7B"\"*<2 #O71::%-CYIH%^9;!W;L#%C+A%EM/MEU5.C>0PB2#.6?#?!O+0I M>; 8-"X_E6K7*:/@'AZHDU&Y) M__%X=_43T7$D'%PM3=5W'F![D+L=,#.3?#F!#31&$.(@K[:3Q&@F^RA>D5:J M7=T0=:)QX&#'Z=3#D9N.'KA.Y[0MYZD>]OP!@ =V8P4S8/Y,@5!)/ (T^G98 MXKKU;:!]?*8;/ZR[#YM,UQ5N+PQJ*ASB!1*7EZ_;GB:SD;#Z@F1 M5T M%&)3PV:SZ.JB$K(",9+;%%?_*KC/G;\G5T^4](#QX.FMF74,<+?,3YU,Y0,C MAQ$?$I*1H!87 ;U>V$B&D"A!#7WX_?^98^(_ Y&Q?1=/,&J!&3>IWA:5MWH) M?>$S;V"%TF_Y^>>:=T\],7\8M*OPY??G+0=^:!6*KU?\].I&V#IB%E;5X:"S M[ !]B-)&=XQR.?C6RDY!D-+]TW#%@^R2TQ5U<4^NR!U'"?HAH$=J67/4_K&L M"Z66]0S0(?YGV>HJ5;ILI64O0>G0D#^FNC"DOYJ0G"6H]N\$L2$%2MPL7C(A M06WS[43#5DA;CID,4X)"I!H#[F#.N^.DIZL5$*.3-8!H1PCAK0T2U. VLC1G M]$$F'-TJ(S98]B^_OLGE([10>,* TK$S<8R_VG>X^ETA,#<3$ OQE$_QMC^C>&?AGQV,48/N*#14E0 M)8G24P#/D+XG,0@,_WB@QJ92#U06\4"[OSW[UR.Z]V\-'#6'P/47S[]X_L7S M+YY_\?R+YU\\_^+Y%\^_>/[%\R^>?_'\B^?_;CRA?K&2QL@O@B;0Y@D<9ZI# M,?NNS.*&9Z:FV[\;_=BM6/CR]15ZE[O1-_P;;U(!TOE7Y!OFX@X&Z EH$RD] MC-KD!([G%I>N@(,!Y,KQSZG!O[67?_BIOJ8VJS3VPOSK_W[YK+_/?^G!2L;^ M+U!+ P04 " "C"4==!.*WG1 , 0 J*@L %0 &-OW/D.)(G^/]^"ESO[4Z56:"+[T?/SJQ%ZE&MNTQ))RFKIB?M M+ TD08E=(5)-,I2I^?0'D(P(QH,D' 2I[#.;Z5)*)-S]%^$.A\,?_^M_?W]> MH5>:%TF6_MN?]#]K?T(T#;,H21__[4^?'RZQ]Z?__>__[;_]K_\#X__X]6BJR3]XR_\?P)24,3$2XOJG__VIZ>R M?/G++[]\^_;MS]^#?/7G+'_\Q= T\Y?-TW]J'O]^]/PWLWI:]WW_E^JOVT>+ MY-2#;%G]E__X]/$^?*+/!"=I49(TY 2*Y"]%]/,8 MYK_"NH%-_<_?B^A/__[?$*KAR+,5O:,QXO_]?'?52=+_A3_Q2TH?^6=[2_,D MB^Y+DIME5GN^MRKGT.9>ZP[G\ M[UW$?AG!OB)^RV->%3!7B7NMBL<^3*^5L?O + 2=GN$6F=$LUU^HBS2:Z[N[ M)36:]>DY5O6UR$JRFN%KL2/38GG%?_&1_=20X0OU&-.*3F.Z6ZS2[R5-(UI; MR[VE41+]VY_83U]I&'U]R G?$Y=Y_N'M*HT>2+"B7\OMU_4K3?'G^\W*U>O] M[_X)P'39H7PY+;)U'M;;%B/*M^R:CW]O2")&D_V:\AV[6*#@#3'ZR6L2KM17?H;/\4+PL'!1O]XTOF'R5; 4- M__R8O?["7OV%.T+\!\Q_J+[HG0O^21WJ] M?@YH?A/?/Q'V>=^L2^X[532#HLQ)6'[=N8R>:6'7CW7LA1;!IN=KAAD;AF&9 M7]EB03:DGK(L0+[';4:$O\XU9;0NF(N=I"@DJW"]JOQ%]).F:?]2_"RFO](8 M]^OW'+C!]'_#"6I8034O*(M1@V6+G04Z3U9K_O27#6<*K,)84$Y8C9@4005+ MLW9C.E9EL?G-SH9(DY_%QHP%9V.#1J\#LU'[)F_Y/2G@NSY_:_[]_B\R&WPE M(&1KA\HV>E-G&LM(*M_#VW*,W+VKI=YAWVZ+<'K'WGL"I@=%7G[]1+XGS^OG M3Y2KVN$F;-LQ)IX78M>S#%,GGJ/%AHBN'*T\L:HTM-"7FEKW-VE _GXM&245 M3$F$!1)6C4[F^W8H]E)K=V+_VNG'\7JSJ$>G&!OMZ'X KAQWW$ =J8;K,H4( M- L'>N1BSS"(9VG$84*(JD9KW8D5X[YD_F51)LS71)\H*=9Y8W#/LV>2I !% M:6,QK":2$L*41%HXD-*<$&6$RK17FTUA3HC05I=3?X8I2T23K_(*(QIQ:?VO7B-/@Q0S=^"GY&&^IBVG(2 MC'Z5&2LBT ,#2B>L+GUB]#A@[+5:9=@/.VTYN=@L*M,GQD9O>I^!*\_F"NXR M*9@U^QLE^27[37&H0X[KXR!V8ZQYFA6:AF\:GB:J0QTT)E:E[>5B319QNJ@B M+*Y-7>@,*Y4"F6&Z)2$N2+T&!)+2LJXU9U.V :':.C?TJ%RT"0?*#8Y"EAI"*3>PO-%I<\Q7X[*GGR[W([\F62DC1,R.HJ+EQ.<4_OE"V'Z,/;[I'&7UI^(WE4?_=WO!0WY1/-'YY(>O/"ERBNL_25%FPS MOLM6J\LLYR\=V@/"#*7OV!:.'$>S+=W7-3N"V(-YV9_8S.RNR]=I4@*-R-Z)"\G]+'RBT7I%;^+/:4[#[#%- M_HM&[+3W@:8T9E:U1:I*G'N@W\L/#/0_#O>F6+?8WA0'V+(#MC%%D49<';0W M2;,R]2UCPQBZB=&O>584J,T@CWB@#8NH8@RX$\E_!(*[RBS G>(#:;,7'>C MV3;@32HLXLRABCN5)GTT1*K,LSPC\YK:T8 =FT=?A[>NQ"S)P'82F-E\U6;2E*Y)!"D-*T XID!]H961$ MAQN/ ;E4F88N,O,J_H"P1VH]]+RNC__+.FV>B%Y.B5D_Y7Y&O:0JO_'Q7UX8:L MRZ9B:C\& M29BZMT%7<(=:W?F=K>LVV_(=O=/5*/V5I^504,74 FW96O"[KX"B M6Y)$BSISY2;M/JN!#<-83!09$&DV9C4T8\$Z-$BCUY,S7)N5[^BJKOIEYY7? MD_+I*5OQ_94=5TY'@P[/%F9@8M\/76P%KFM&NN,$4?RU7?D\J)*RK BIY&"Q M=U\^)CO1?]LQ4B"V11>M+!S"3W3 Z+TT[F+F;5(LI)JF!J6 M1DQ;=US=A)FM PJ36Z,-O4V^'\SN'.(A9DYD9)2R$EOAMDEY.W>('_VNLS3; M_$*=8>@03Y&^'ZX^JQIWB':HG5V/C;V3N4A+YK[\GD3T*N4-JBJ5OJ.O-%W3 M2\;LQ7=&-R6KLS7;4)_9N>+#VVV>1>NP+)9I=$_SUR2D1=W]XD!U?9UBG_H6 M]K7 \YGNN@:QY*YK%'(Y\3FJ80KQ#QIMV$);OOB5](:S2E\VO VVX9CQ M^;S3IS,R4+M -=^8,XY:G#,;5O(/Z97]GOF.!?-Y\I+?(M6O5E=$S6J+S8?9 M_BP7:/,E4-9:91;,E=\OJ>3QG:Z>)H"Y^U9J"F)R^\/%\\LJ>Z.T\04WQ]R$ M%F?K/&=?_*,*#NIC+]8U'+O4LJEGNR85*G07ICBQW5Z&8<[#UP59D3RAM7$. MFGM!F%$>!D_,P"J%!&8L-Z1Q7M-&+>(+U)!79]:$)55DHH;IS6INA,4_-!WB M+\J9@8YK\G,:YCSZQ8Z*Q7K%]U)NG>YI6:[J%F/\V,B>YW=Q]1T29^G0/32H MB8D>4VR:1-<JS0!M6T9;5VDUO,5MW[JW912U^U=FZ26!49!?5\C:K#9T$UD-[ M.PT121+%-H/(=>7\/REQ#WE5YM7WNV!2; MQ, D#G1L4MW5/,<+#0=TJ3F&F:ESDSA95')*$H6WHU 6=/-FP@[H 6ZX0C6Y MRI1RQM ^9PM4 \S=Y8J[UO,<\5O*UE?J*RJ 2Y4;.8:5>3U,!: =.9\JUH07 M^C(;RQ?E=O6<,GOPG*05J7/V2]'"W[XU)H\/;DFC/=J($Q[86ABGT8.-B,]L,+0UPP/5,P! M(S^Q6O/=LV:F) XQB3T2.@2 M2F)-Z"3636)B:\=IUA?V#55@V^L>;/HMEQJ)899H0F&CII5@[7!.*_0>K2F% M%[:>PW+5UI _5YDXS3.URLSUO#F+V1KF?&.&!)X^3NZ3XXZ C7N7/$)/R9K0^CN(@#,Q0T_58 MR)\1(3:Q&=F1KJ:\79-RG0./;[U0B=D050# [,6.ZI3=\$1D4V0)>DG-JO4B M0A]JN- [H[/7!>Z@!GH*.00'FNUBRS-#P]8-SXY!5?QCF)GZZKO5 42ATE] CB=6WY-R4,52?*J5\*' MM]8TG\N<_F--T_#ME+,3ACH.=-?"D6%Y%N,W)#:H1D> YL16KCVX:$MW:-^7 MQD_P%*46%9AMD@($?DP2%U'5R4B XKR'(7$(CLX_@%?APW"6;+&H6G!%'@]5 M/M#8^<9B/P6$ZI;M::[A"(_ V5MY8L7>TD*:;7#-20':XVI./R"W/_Z:9=&W9+7ZF*3TJJ3/1U%%&E/L>Y;/ M#@-Q:#I:$.I6"-D-CRA,K"(;>N@+IX@JDL!-[Q@4L2UNE*@PS8%)"=[).B51 MM&\=KS_K+M4IWN&>U/V@9,NMHW*DSKZ7KHL]RXIP$(>^85I\()0':JK526KJ MQ(G/=W<7UP_HX]7RP]7'JX>KBWM@%ZUND,3T4(WH,(4\50TX2=_+8>%4M;3J M)C1OTZI!@8_:4@V_(9G>F5>.Z5O5@F\9_F.=Y-O!\F=94=[2NB',H7^IQQ[V M=$_#>AC8CA'[AJ['H,1.0<)3NY\U1?22)R'[7YK7C2Z!29NB((HI^Q30 -? M=;//#>T%VL#$R?-JC[I;E,+43*#(JI(R1I&'R0E:;J_RC MHG_"G0.78)-0TW4TU_<\D*??2VUB56_F?:6/*"3%$XI7V;<"810WB2JKJ@98 M/HOG&#S!8+,J2&!J?I"?LZ6\:1&IL&9>2,()\F^.:;U;LDVGV'V9-=TO35AS MWC'H-:1%L:N9KU/8CSK&138.B!/B@%JF9AL6,2U8%R'%#$Y]05_UXM^;$5V2 M[[)MAU1_.&+6YSTA!_HEPC49_ ]-HT7T4\/=SX-]<-479DR%[9SU[Q#V?KR: M> EPI>KD9>A,.PAAR6>M\^S:2\;ZX9$M8FZ<;WLZ)E9D4)T:=J"!+DJDN)C8 M&C\\478\Y@2G&82PCZA@='=JG("!7^ (A K-.D>;,S;_)(23N,P\!F&?AQ]R M!L))F&0'()Q>3*7'>9:Q0VVZ9DPTW&1I<=*NMBZ9\ZJ/><(KZFCDT)>SQ-FQ[IN6VJ/JDZ$_E:@* 5^0^2L,T MJ=<(Y^H'67ES.VRU>2K'A"*I_U0%;TG ;E/0W7=;^Z91BNG]=5 MH]&JFR5OAD=6O!7>1_:O#S3.P8%XI9Y6;8G4F5BETB@RL&IYF-:]*83PTKFH7 MEVU*P\>J($GF]$O"81UG1FB.3$ MWN>.@0)].<^>20)M>26 FIB%4XL%S'R!8)#HW2(JF;+>+(,$9^Z](@K <6\5 MX3=EJXZWW5E:65HWY=.QM@<.P;X>&9@ZGN-04XL"PY'PDGI(SN/[5*2@%:"XT&1C^N-AU^9[M:3_?*, M$4_*8B_D%-K$PG%@.=AU8Q=[CJYC0KTH-!S#\,3*;L:Q,77,G'WWPYKB7]1? M5YY 5=VEY#BLIKQZK-EZC]B0*$(S7B">8.('B/R( B5S&=BSFNR5'T],ZBJ^ MT#P3$\/6<&S9=N1YKD_] ':7UUY^8H-3$Y..4Q] (7H))RL@]'9-5#:)^[)3 M(BB["-M;?.8;KE."'5]=G7Q*:8/9RRRGR6.ZI]CG"=-W7I.1D-6AR^_8 0ZT M(,"Q&VF>8T6FXQA?7VD>9"/[R@YQ OD&M_D13PVL&9">NB&+L&@P8'+4IO(. M-L >/M?F<[;^L** 3=L4=I"+'Z$3K"A4@NU?A9>3-G#5/*/-7*-=G]G]&4+L M?&/I'M8+4H,&Q-,E(AA"Q.>)96Q/^$FM;I4Y ULR 2B% M[98B9"3CF,WTM)\V#/R\U[6Z/?='J>T1%UJ=I1&@.;==$8?AA!4!O#S2*>*) M7Q_>KM(H>4VB-5FU&_]_W&N\8!A$P[YO\@)PY@8%/K,@EN4;5-<<@_J@FE$8 M^AX,"PWD4FMB:,]KJ^IN*I MM8P)?'MQ@Z[9_[=SQ=G1("O3##)"K!^9?GNA%!28:0#B@;XH[;B&B9XD]_FV6NRF=+3BF,2Q\>>$<28Z)9' M/>([)A7R(88(3:S?3;ET0WLS3S/+T88^M'2\ ZY^A58) C#Z(2V_1*%XOW C M2L0[%IZY.+Q?O..R\('GX;LM,P /64E6W 0LGTO1_?7@M8DUCN\7%;G]'6,@ M;#8HZ_"..4),F$[)20C:!#MDD=KV#M>:;:/K$**]M74]HO3NH#M]P,0D9G"Y M%M6Q[]$ 4XN:D1LZ+C%!C7J%*?^P&0/BV(VZ!_CQ\P)J-9[DGA",R;3!_?>^ M_ ?#(1C 5W[%W^KOTF&;P\Y8=YC%8U;IE'UKU5=<[8-PUS3\B:N*[_V9PMH!/N.SWT] MS[%LU_!H! KJ3\/FQ#:I80R'#6>HW#&#R"YVQ:<29EQ B?R(B3X_,7/V_I\* MS )6_*(]AC?>UD^J#:K&.=KQ797U\ HS2DK)I\55D;R=B MRJU4CMP]OND::OS/(;R:,+IHWEVVZ<8%W= M\_!$TIN72G^OLZJDCT;7ZX.2VGK, (FP;U*"P\"(3#/BD37C*]/V)(N8DYV7 M@H9K+OXAFGPHA;A[M&L$BTB)&$>(R[FF=[ MGN.8<=Q\LA=I]$__N6YD4/.I.C_JIRJX%_Z(GQ-P)VUUDMR_H=E)P5.>3G:< MY**P?;82IC7JMJCK3MEG35+4"+1 6Y'8CY50"O?AN3\'5;OX;'S/ZP/,_7$< M>1"S,R#G?_ .'V'VF/(>'[OFFL4F2[:XH\5ZQ=W;2X;Q+3._^6UEA'FR6E;4 M)X6C8'HX9N_&M)OJ.7 M#0<\(?R%,X?>*,F!N?)*/A>Q+61NM&&[0YN[ZN)OP]\";9/PMQPB;@E0Q2.J MF:RS9C=LJK/W*D%39,J5L#2KE58)XJ$!5KJV;,N3S=3WZXRO1U9'G=[KZ!$O M?@P='3M>$$54#Z@.2_CO(C2Q#=R1Y:Y531B4.#0(E)@!4R$^S"C)2"[1ZJ1? M+&5]3CK(S-SDI%_8XPXG \_+J>SO-'E\*K=CH&H7ZR8^&A/#W+8D/)KG8O,[ M/LO&%C6(Y]N&%CHN1(]!U"=6[HH&3(U'@1?2&/N1%F,MUB-JN$[@!S&L GPR M^*3JOC?<(-(,A0LXV3K] N@,PH 5,YJ3@06SI%N4-J/S:D9X<.9X2M8"]7\K MP296"@1%=A=&>U9C+ 7+H8666T2R66\8YFM>P5FL8H\E5ZEM1 MBHFMN"OE -%W:5 I!D17KTK!M^%E6"U?8_GX6%[D.; @JW.!B56[?6_)".=5 M[Q;$R&M-T13$U"^N.XV,WM&TDT88V;-ON@4MLJU8# DQUY>0';\?#HBG:@GL(S;KM#@M\N-4*O"'9 M5'779/KLZ+1=.=NVY6/"CMC8-AS3".W(HH;^M>3%I&+J>TP"I+9;0L)?V[ID MN#F@H-6./+#)ZC$T8JHZ3F"8BNYU;&^H*>RWVBF)JIZKQP3F[;O:*>!1[]7N M)\?44/.\^659YDFPKM3Z(;LE)V->E.# ]EP75] M=O/I GVXN+RYNT#-OQZ6_W%Q+U,[+8J98? YW#;!D1]:- @-1X?=ZBC$3+K] M6C/N2:@MH0QF8B9-'1(P\[97X83:M'F10TU]FI%88A(KK1OO)/8.Q>)#@I^N M$!]\:]IAS]6T5O95.C0$5(^Q'WLFMDW+-JAG^@'L! )E8&+38&BF-LUPYRV" M@I[.A+@ _2#@2.=ZF#-;;?YASH=@S#S'>4O^AQSA? B.[/3FHW4DBWQXT?HR MC3ZR3W_%]I=V6\^KF8X\6Z")Y_G^8F4FWF> M?/H\GSS_\)1GZ\>G!YIRDU9F@<^CB>;V+BNP0;H>Y%)"*FH86@I A5 MG$U];;IFBL5Y0#'O@2"1H:_N,Q"S5^^"+,RB"0TGYGS4W786J.&:>57+566E M>+H<,W?W;%-FA[/-G]$Y^\NB^;PJG\M&C71([_9A1P\P'@WQ1$.,Y?EZUT'& MH^$<&F8\GH!L$(ZMS[9L9O#16>JA[U@C.):X=KYJDRNA0GTC*HD(GBH3 M]#@*U/LT3$?#K"B_?DX3MK54OEEQ>L*X%?B8>(Z#=J57VHNNU60S% ,\;"S'TF.SV_7-'"YJ_TKH8 M\.R)Y(\G-G(7!Y%O8$/7+#<,'".BH+C,$,')M_2&_ )Q!E##P6)3,ELS =W: M!S 4W>35(0/=[D>!(K'WBTFJS L8(#>S/R F_+%G(/C>B-G 9\S&=(T'=@T# M^X'E8YV&7N 3HHJTS0E;HO0U(3+F)P:=$ M43DT>&_]^><&GQ+OY.C@DP^.'&=SQGZ\R1^R;^GA9NMI-E,Y7<>>X;A.X 2^ M[PMMMCTT)E:ZBX,A+IPP[S3-24O.KVGATZ]\BJ2&J9^4P/(#:XY%&C^KIK7F M^XRI.1:JZIY3C8V(UWG#%,YCEW?QF[HQ3CP31/; MQ ^U./;-T/8D9GN/9$M(5T=/_:Y)K6*181*4_,5@:7()H[E9E;;J BZ0QNI:MD?K1WUKVP) MWGZM#M<'$8P5J@S<7XQ#YG10Q:S#_;AR;H?/Z 'P70 M6YVM(W$M$>\46LOTS]"0^/2G\,/W(SY@^_\G[8A/?QCS=2/NH#]Q6N,S'[GQ M7UR:D['ZNN(TH-BS=0<3&NE:X,9QI(/*-49Q,_$^L4NLN]PFUE71;]Y-:ZI$ MQI.HB^T)LV$),_1""8M;GBJ$%^B2G5/)JLY#W&8H3G'KH 2TN5,03_+R8Z8= M]L$FG6K8N^C,3OG')*57)7T^ZM >AGQ>E1YBDT0ZU9C['>C&+.[VEJ6I@[>5 M:Q8(NG#!L0N'OG!64<4K\,)4P>KPR_#KZ*HSSY3I*V+=G69:TJ'/X+E?D\=!X:IJ/B1_J.(@TS_"SE.2W"/'EI;A[8N>:Y5@#9?+!Q'X:@ M9S,7Q$"G1BFZLL,^QZ&B=ORG)"_O,1!T'&P=(T)'+CJBGP!?\":^3%*2A@E9 M;8;6=(7#')]B+PP-'+J&%7L!^[ MDVA-5K\GY=,=K8>H%T_)RT-6VZOS[)DDZ6%RGV_YF)UQ=.S$<6R;3NA8NE!A MG 3MB+WKSF(,X2-L+T9(VFK(HD/R3/OY?7I^O:JE64JWBN]6_Q^Y58F.4R-^X1&7Y3FU I)*-4AO7O5 MV3JD#PK6[I ^_/"/EI'U6S5%N"LCRR4&]DA$+_%@?;.AB/S9"K =!Z!*+ M^IZF;?*7_PD_VOT<9]B'6Y.K/)[MQ_F#?HH3WPA.J'0SWQL*Y]XU'_X_5>[= MZ4_AO6\BH6S_<]Q72GX8\^7>== ?&5,\6Y&BN(GO2^:[++\GQ6% P(I"3%S# MQ.Q7=F18U LUV/5)%Z6)=_**7#58E!-$7SA)V4#A$4C Z. 8T6'V%":U?/2O M2R+5(;\C.N\3Y^L2MS.XU_F"G+I6>9XW\3(,^:@K=M"[S59)^%;_[ZE*WW8HDVW)9@B"\(GIM7J08&I M^!:/'0<+5%-'7YK_3E))"Q->U>B<%.O0MIQ^ M2**%YG667F99U-$^,[!"')BAC8GN:I8144)#H6CAB;6G-A]9BBMJ,LTE#U#H M5Z"1LL'41Z58@'Z9\N+)]OS-TTR.QZ!7_W= M4IK_FF?KEVH>8A6I>,I6[-V[,@7,4!Y89F*=Y]1111[58QU;#* [6JYS^ #E M(6"&KP858@+<:L?# ;HA%!14ZIYP:.W9;@L%A6S?&8J^ MVNV0>7OWV]_L_# MT)WN,S>?FB9/?]:#*/1#/Q!R\W=+3KTY7_R._O-B^7%Y?2ZZ?6V%'=J,940 M[L$"W -VI4.&>_2C>;C6D>8?.SUI+373)G7(^FYO.OJ+W'%V.[KA*GU9E\5' M^DI7QI%O6GWK'<_''C4T3 S#B2*71((9; *T)E:']JR4FO@"5>21 73S1' 3 M.PXJ0@.F6:. !\8!414='SLHS3K85) Y,.CI<@K<'_SQ%;X6[';**&)9X++ M3:S'G5[6;P7:.6/BOJ' 78T-]0#RS(#(K2K#U*: MV!;4M!$GCO_@U-&&/*KI0UM$=P'6K_Q*88"IO#P"$CVC!Z0;T3FZ:^69^T?9VE=^L5U;7 UI=Y_I _IV54U80+[M*="\P0"^:$$:>,];T< MLP>:/R[&UP_$\$ZL! -XS'A8?/2%R0F0Q(Z^(T6'*2'D!(5Y9YQTBW@TY:3G4;E0[.?[PPO3V'(P,6T/1ZX=DC#PG3AV(:'8 MW1\GTKK/UU70XEBTU:SAV MQ_IA.+;U%[F-YYQ7(-(T*DX7$8>\#:=.*38M)R:Z;5E$ _7B/%A_XJ_^EAJP M/+@+#;'=982,,,T B ?>23J$4+2+'*X^ZP[2(=KA[M'UF&Q:?A;^41W0HG.V M[:>/=;)_%8'/YB&C\] MJC##4)<(U RAFJ.F-FI11V@9N#NVFHJ"INBJ8DUE7<$8:)05'4@Q,7-%PAB@ MCLL51JTFZ3PP/WM7YE3-_CDT8*8?LU-K%&"7.+;._JEI :@:^02-B:U3>^35 MQ^UQM>HXW:Y,K"==01V,$X@).AGC< #:DT,('J0@@#LAW4*JD6 M\<@AZ7E43F&OZ;=6L4*>I>S'L H;%D)E2#0@S!V)8DSLT(D,W:*.(]1!59:! MR1V1L"H_WK*$]GE"RRA[V12:7V3&K,"6>P) T_=:-XSQ5 M3;)@*#(M8/*SVAU9< Z-DO0ZDC, 29XR0@5S9RI?9L! !4: @SC0L6_:CF\' M--!L4#W4 +VIK[5HN9DQ]T)SWD;A.4MK#QXXL6\ -C'KHA ,F#'9$.:'F%K\ M>2R(H,"JIN8-4)MW*IZ8Z$=3[P1?D]/^,_*2E&1U\?V%IE%2\@FC3#UX9#_Z ML"[9ALSVXUN21$?YTC:S *X58]LP3.H3-W8T4-A$E/#4%V@U&XBV^&BB)'4# ME%5"@F35?ZDT#EDQ2S$%7C"3L8&JS0+:\%#U?[IN^C]Q/M29#*CDBFR',-E9 MC0@4C$-K GY_[/CTPV;0K4;@']Z:/W:.3W=M$Q,G"''D>)8>>S'1@+,OY?B8 M.OYQV"N]W1Y]4;5PJI^0'9P. UTP(CL]E, 0RA&*\XQ&EQ)?^6AT&!?O-!I= M"JKNT>ARRTE4=-_3-,ER9@UI<9,RCRM)R_OD^W_2/&MF"9^OZ?(E3U8/W]@_ MWAZ>DKQ\.UUB$]DNOU\RL.=:$779'P.Q\.Q81B:V8?J?'4W['ZAF$%4H?%X!,+VU M]F/6GZ\P7P$*>U7\*M:3\VT_%WR.25$F;.>A1ST '@#N+S]U)EN=([ E!W,X#Y 0\R/EY8/9UT/1YHEOG99.D?=WL/BL3MUIP0Y] MM8ZG)%RPJJ-G.]WTM'ME.[P-M^GBT"&Q9;F^JP5"M4Y]1"96NKKC+B>+MK>^ M@/V\"QD!1TB!O# E/"6JC _3)3/ /U$@NYSO(8KI/K SREO%\:["U\\OZRR-TJK M7)^;;RDS 4_)RRW[U+<9CH=VR@M=3'S'P230J!-')+*B8--:_@%P>Z::4:'O M_WXC^0>)RLZ&$514B7'9AA7TPAY#/UWH\;<5WA%.!:RJ M6T7E_,U[#SD5O$2K'B$^#++>8/0>QHVY6+5/K(M'EO&S*EC MA\J'ISQ;/SY=,@G^1DE>;+MZ'!IWS;.P;T4F]@,[T*W ]8D-2L%4QMG$GBL[ M4R/">4!92M$;(XW*FA44<^O"?P,\0ZK[4,2L]KM #;/6E8.XXVN!MCSC.,LQ MYWJ!VFU_&J[?V).KRKPV^73W2?JXHML_HW/VET7S 7)A$),/-0(B+J$Z&ZX< M9D6V6QU?L]ILY7 >VFKU!"3+M&E14'K#/$'";W@^\BJ6CTT*QMOFBUQ=\W6G MT!(-$]X#)0X=@_W:"FSJ@\JXX3Q,?6'_0I29/G]?-FP$^!/J>\ M0]"6:U2Q#33&,NB+F=V),849V)J9Q2%8"[3E:('*# 6TRF39V==)+YA'(*2J M$%V"@WD+U>4A.BID'[&4;*9=\72YRKY=,UG9CUKAZN+^[] D_-&?AAB5F].B&$FD'.& M.&L+U#"'MMQ5ON.6/[1C<&]8Z@3STE7!I2P#<"0[,V<&J@'O.&-0T;KPKG?G M3;R]KK2\2"-^@#EJ%Q*Z.- \RL=WFA;5(C]PA-R]3@I3'Z(;FDW],&)4JY.9 M>'.[T[CTFR0ET@+/L5!!03WL>H61ZEUW>L79>M;U"M3N5=?_H.Q=Z^GI);IM MX,",+6QXEF7KL6DZME![DL.%)U:JWZOFF^N"(FZ15BN2OU7;6%9=O@7K(DFY MQR=X'CI"1?1N=9[[5-D+5,E+TWDO2J>X&87>AK[/#>C0K:>2F\ZK-,SY8>>< MUO^]2K>'H*8VX,2!HXIR$\W&?DPI9C;!"R+3USW=@APXQ$E/;"S.GG@O1U[G M@[)M"( P\U 6E=%HU?P SQ4 =,5.$--@!C,ZR^COZZ*L=O(RV]X84M2JI62_ MKTX4MWG&[VHB7L/PT^>B*J'ZN15G:1S%-]ZJOA8(_;01[6?^>>P>W90;37'0 M@*.JZ$@!(#SKX0$.R.$Q06(%V0X+)?^J;;YI'][XU^PJW9U+MF>1HXB)9F)B MZ '6O$AS3",@U R_EKQYMY@!$R<-,F!;!H0UDFM>=69?URK&_F][=M_R &V? M( RKF.6:!BR)*,=IF[2+=NS9I*8[%C_&9KP G[=[:K[(/8-T)1HI0,%1UD)! MF/#,S1.@@!RW30"O &_G??&/\FWY+8\*MB<6%]_#U>-O9'7WDI>,TOWZ^3E_ MXY/LBS)]"%:-MRW8YQN^\L1.TL4_UOS*HVIEQ=NT;'R 8H$X>[6>5%=^305> M;8DXES0M*GU!50!=O$>X!+K]MFAZ8&'V2!)3YOR?P%7A26D<3E)]R27(S=:P M7!Z*=B?S$:M(%J:D.?/-']/DOVCT0+Y_H"F-D_+(#?)L'WN>[G,WR#5T2AQB MT*\O=3>[DN2EF#/400VB/(=\,?F7. MTY* E2UB4+J>CHD=>=C4#8=&9AQ[(6F@O$BCF8'<4%0((^4A-)4 BOF."B"! M&>8VP2HY=D-28650OTRJ2H0ZJ,Q;*]0OZE'1T,#C5^+*J&T;M-Y MLRZ+DJ1\FSU494(H]G1J8=LQ(D/70^K:H,9[ _0F]M:VU.L,^P6J6_JB;,O&QI0?E_/,B-&$=2S'XOZ MC,\;$^QR83H;7.F^AP,&$]9B/W+LP(\=$^1U"%.>.ENOQ<>_H)H3B7$"0AB* MF9M)D)$*]Z@=T"HMG\K._T)TYV_V#X'C9']_T +PA+:FJN+MXGM874%?D^>C M?#9'"['GNQ$V]<"QV/\3&@J-O^HB,+7F-R31AB;B1,63V4YBTJ_B*B2%:3)0 M2% B6Y\D4GEL)Q><+8VM3YQV%EOO]/5C28#C12;09!S=%@ZI1@BCR[O:5G==Y."77HGYU\1FZ?N+\X MRFV,(YX:%&+;]B+=-^R ZAIDG[B_F-K-^OWB_ *X3S YQ?8)&/= UZF?-U]#[!EIIUG]BQ?KA/M/XBG=9;M]C@(:M+REXDJZI6^X[&ZS3B8WB25UIO M(8;A4ZQ'D8U=ZCF8A%3#AD\"="=6CE97FSIDUW"R:790,X,V MW(!S>H6@%=N8)@ ,IH^JL)))NH5(KB[C5HCJW.FV$"A.Y-J"7I=U/7EU'ZU" MI[_3Y/&II-'RE=%ZI'>4SV_=Q%5Y)S;]J"S/L3$Q(X+MT&';:6R';@ :$ (C M/[G[6C&SN2C8\(,:AM"6H_J)JM$?U,<%H2WJ!4^%(=1/5@B?A,LL@X(RIQI$ M?&:W6P:88\=<:A7)J]U=:R+0\/ V3Z]51F@6MPN3T#.#=,T3'+(4Y3R65LTD#DB10)N^]$,J M9FD4P"1WE[NCV^Z)U>I4H/#65DA&59>T_<3FO9,5$OSH"E;L+?F&X?EZO MN$)5M9$\E3:G3S0MMOT&/V9%<4W+FY@Y2D>)FZ&' \NPL&\8<4A#TPTM_RLS M6D$FW+,/Q@%$!=I\"&M"BY^FZCELZQL M2AM_XMS\O*BJ'9D)9BPI[)(GAX6J7GA ZO-VO).#YJBOG>0R\+O=B[1,RK?[ M)[I:<2(D?3OR1F(#^YJI82-VC="+'!J$PIU*CI>?^,A3$T051=20%+_5/8%& MOWD8+R-,^T'B@>YSNZ60NLT]L=QL=[G=HK1O@JE1D9=?S[*TR%9)5!4Z M797TN3C/^"'B:*Y63' 0NP3[>DA".XKTP"8BRM1'9&*5VB.+*KKH2TU9L)=' M+T+]"J9*;IB:28DLK&XB,O5MENS]UD;)_K53O=ZE9U% $>$V:BCTK)RG_5>Z MBAZR34M$:%_8JBHWS]]X >XSO^PXU.-8BS!Q-8IMRW1Y^VSJT0 2)U3,W\0F M8((.VJH_(#$W_AUAAUF@HV[:G'-<9KC5-?N9SY/DI5]G65%N+D)X+^UO5=@R MSMC9(*=14B+N+(YLN%U.TG![HL]#T5%#-7>S'D4F@O;PJ#(5&8F&<,LU^ZYG M>6N^:E=3J- SL6<:%,<&(5I 0L\3F] \0&=B,]P0;L]=%FDT!$*JWXXJE!\8 M]IA!=$"'.340R#6<.P&%HJYSPU+U-J'K>7V^GG3#,NRUJ!-X?&1JR_[DF"J< MTVJAT:2V:#IV--?&S*5T'A5'<7=:ZM2[X43)+&(H:$ZB66 ZOLDL8A!T9G$(OBZG/'HJ \ M6^5*-;BBV MI*OP1$CSDO!^8OF:XO5+P>\S><,?MB3-7VG1[OZCQ.4XP'R4PR&/Y%3N!O_# MCJ79?(W30$SK:1S0_!'\C-,P"'H9'2^/3Y2]X_EO-_'G@BYY/^G#<(D94>P9 MCH6UR&6_H*[N4*%Z1 %:$QN730YG[5/4W;+E4UP/<1(S#8JDAQF$@^35BB[. M8LPHHXKT-F#<2BAI0LJ*V\8*R#]!VNHAI7?+4>T0N2\AM>L5V9YBW+(G9@C4H@*S!_V 3#HC4%QL9;W&!@G.W&Y,%(#CCF/";\KV &*& MGR]X$]=.!R-R(MNLZR+%)BF,ZL!&!3W4-6' M7X /GF@U1^61C%>:OUVE4=4K2W# 1/<*4VNJ<#NP 4'[-4^=C,![AAU-M"'* M1\E$R6L2KEC[@AY1&Q25C[IYM'FR3 MWB1DW<2?2/X'+?GI;I><=>C&V[Z+ RMVL1;%KL/V5,W4@&W$@1Q,K+V[S#/N MD!9/65YBMLQS,W*JBI^"@P! C(5C M,A!PX15*P@_B5'G)G*,]GFA3(D=PRU MDE.51@KDP% 7. #2GSN.( ?/B;""Y$)J'/NN<$) 0ASHU,!>8,>AZ1F46D)Y MF4.$IG86+A[0U?79S:<+='MQA]@/GVZNT?U?EW<7P%&\3 M'/6'!)O(>7^?P_N0L$.N^\CC./=5JF%?#\^/?\V^?4I?DK.TB-B_M\=)0>^] M?Y6)E;(BCAZ29P;- C$6T*?KVRO$"XX2!H)H0RT!-(9=?'5 P+1S$ /%AVUQ M6:5\_H&E9_/[Q41L^_Z";\AMK^?;L22DY'OY1_;YK+8Y!!??^0@^V@PH.MQR M:6!CW]%TWG'&CSUBVY8#&AL"(3ZQQF]8@6VY(/3$MN&I,($I__ENF!!/!.*^ M?,5(.T6HX07]U'#SL[HM6P8$1=LXB/2L6[L,*(?;O=0:\-80YTUU2KN%[27[ MW5'TP P,3")=P[;E^T% L>UA3HZ]U*9VE8T=-%>-V14D19O&-&-4;^A4"8Y MT"+(" UJ(S$HE%0WB>Y59VLJ,2A8N[?$\,.2Y^BJ9\7OS'5K%2S=T5>:KBD_ MRU]\9YJ0DM79NBB9-<@_)BFM:NH/5=:)F%B? T.8@;BGCY5]J.&FDO,V=RKOKS.RMV0 M>L+._R2O;O_K5YL0X6.=8\R>B]9AGK5^NBF+-;,=E"HY8]"PQL>7BE%%% M&C6T%VQCSLHT*P$7D7T0#("+^3!S0PJ-@+QW%YU-_YRY6^:((3YKGYP!EG[ YCAB(,IU MQ!%<>W2_\AYN' MY4?T\6KYX>KCUMV>^7W:M_=I6FG'H'' M.1]RPE.R[M^>@VQUU%LA))B8E&#;B"P:4]-S0J'DQ:.5)W8<&EJH)B8>P=R7 M?CAJ*2T33$L$Q0'%)D^R+A6/W%]IMACD20':<& EW$RL>MJ?'5/['ZCF$E5L(N['5PPA_L4! M]"<;C7R_"L^.)S3^V,*0\X8JYIAS_1U5[*&&OQ; -7.;__ GO]1L0MK"C88= MT#QN3OCE6LPI^1@4-:53A59OZ[K11.9K<*<*C[TV>,H6G3):='1*.I%&6CEM MH4ZQ'P8^IJY&*?4=RS- Y6$C^9EXOZF"& ^[(,84P:%NK%7&A90@^..$A";) M?%6$Y*RAGFYN?L HSR!T<@&>X67A8R::"]5?:?:8DY>G)"2KTW,F?#/ 2$N MUDF@F<0VJ"$^9Z*3RL1V;7M=W*8L,6JB&Z5^VZ5,=IA%@DD+FC(Q*,V(,1/= M:\\V9V)0O/:@B>&')8OOR%M53O:0+<-_K).<=O;L.')3>.,^QZ18"PPOM!P] MC@,+-N=1G+C0]W?,S,=EQ#9$=L@H4)FAEX:-ZF:$2K;=$0=6S"=1#);<97?# M P>IX0))]BJ"5]>!Y5=55B=.>-YZ.C @1X5T\!7DK,Q!N^'X4[2ZO$[RKR4M+C+5JO++.>E"4<3 M$F(?>UKL8BORW$BWS=#W0)5X4S,\>1YAFWV>U]86H$J=WXBP0%LAFF::53%< M(P97](T@=5/.6A3TA0N#&FF W80F_S:(&=0?Z3.&F>'.#U/T8P$;W[FP4F2R M)V=W5D,_%_B'V\-L=.&YDI=\M/&RN(EO\_QO^44:W<07_RC?EM_RJ/@U3\OH M*JW^4ERNHM^*,GT\R]*H.,_9#Z]Y]+>\"7L+IE6JH39U!F;.@]Y5Q@[CL#V7 MFYE_OI$S?[:JXRO0KSG;WIGI2%*T3-]0Z\WRB93\U14W_)\H+='RY67%3AL\ M(?HW6E2]W;ETC;-\OL[KW[Q6Y9A\#?%L3T4?8K^U?Y_/#^A6_R ?W?#5$RA7 M52WL4FFMBEB8+0-6+63M9%G%*TNDMZ=%NHS^7C J]Z_A65'";'#'ZU,;5=XG MD'G0K>$HC=?'EBE6O&6:,-9=20[N_I)BCWL)Z- M%AFF97+2@G2J5R(IC3J]XFSZU"M06YOZ'QPYZ>8\*<)5QE?MZ@?E610'>N1B MRPL,:MF>H4E.PSNF-;$2MGHL[&A+MX_NPTPL5J,("9AN2H,@/W6F6SS5LV9. M4'J?"3/=(G?.E>EY1?7XJCI3HJ@FY-5IH;8783NR+.S:48 #V]9Q&&J>30W= M)&&PN0%[4#'&JDU=X@KL02(1FWW9PYHJPLUPQW+W.U43JO9@!9J \2C-,*.J MYJD9CSGGF*I38$P^IVJ/Z \RJ.H4$.*3JDZ^+=O?*BBO4F:GJE36_B+1R..M MX7V"-3?6 AJ%EJV#\G6 M7$N@%9!"6LPZ3(W?I"[%EBF>:U.GM2OL.#,"&57-9F18F+?/S B0CEK,C%E+ MSH152;W%TZ;OT8>WSP6-KM+M9. EYZ=*_^T*:=BNA@-7T[ 7Q'9D6+RLU($8 M,#@+4YNOY?U?T>7'F]_OT>7=S2=TKGZ3J-R60%G,>$V+ M'3!NR1C9-= *WM!/G!FV"?R,=D/ &X:JT1R;'"-^=J^^TFOV>/-HEDX259'' M2Y%!DV!@5G,F#]"A,1NQTIB(#2]@X>VX:B.Y9H2VWZCB XVS?&=<:7')_ID\ MIH=YS#1DULSV**:!Y4>N:8:FK<&CM#*L3&S:&BHR,1LI8"%QG*GADHKT_L2Y M^KGNOKAC;&>E"N;0 M).AFNQW3]X534I0Z=)I]*A[H6F%X9V& @USI>D/[&2-61A MWO)(""/B8B\*"/9\VW"#2,T.BFH^4%$Q,BVT8J>/ M"0<$M5@TGJ&:%9WS77* 6&PLT].T$GS$D@5!TL(!2G_4T(0G-X1%"=AEX M#\"Z6_G%,\T?V4*_YMFW\JE)+#RT.+X9X\"P-1P1TS(,3Z>V*S0K=8#.Q,:Y MIHPVI%%-&S7$Q?L%]B'5;T 4R@^\))(3'=1;4$ PJ4Z#?>O.UG=00+AV%T*1 MQ^&GC+J*AQ?U5.?#95&LGU_X3^=)'-.<,BDD^OW#5IU:1^M"I2TW:,<.VO$C M,Q8 "-[P46>$\[+=F6:!UQ0=: M,4; D]$'T10[6BC&"&9)^KNP+%#- _K8AX_,P'-1B=6-.!^D./=01$J9M3;?QMTW3E_-UU;S_X5MVU&0_-#'A26LZ,4)*?=8/9@ !9A-:!A %0<+M.5AP2O$ XIN21(U,SX8 M'^K, E!P1:9!E.JLY@$(Q:&)@+XNFZ">)Z^$IZ(5M]DJ"=]VKO3A/(' QYY% M/,Q^2TE@QF:H@7(ENDE-'=W=$8:FI'>"(V8&U(@,T_P63>805%31E^:_2D\0 MXD(J2T_O)#1SIZ8-OR([+2>E-7!>L7)*PLA$/O.M'5:]&8TW#NF7Q ML:GL?[P@)MBTG<#3=<>B!N@4T$EI8N7E='E@O&E;O"'-3L.<.+ 8M1LN,7U6 M @),G67EEQC$,R";LK$\771F'M(S(.[QR)ZA%^"1P<]IE*_>'IM&S&^?_BAO M\R2D9T_IXVTHG/C3O\K$^LF(4T:]FGC3,,#'*OQ!^8S=JE-(52,B'O ;P&0X MP*<.#IBF"B*AL'Y#7%JIF-W TK/%Z,1$;,?D!-^0=)EY%@9-HZ/1Y'%D8>)& M'@YMSS7LP+"!PQNV*T^>[M#0 ;K#6\$%O5\9<8#.[J D<'?VD&M5WNMVW7F= MU4-QCGS3HP>F"SA=LL_Q*.)$#1P0.\#4CSV=^C2F$:A3BBCAR4-.IJ8^Y%0A MIB[F!,5ALJ 39V3>J%-;]!G#3A79'R[NU 9#)O"T][[DT946!:7;*J%]28U(R^$N$C*.)O8A]KPN,QH?LCS/OK&=XXR\L+^41\G43F3C MP+)M[!F4G5PU/;1-H3EU,L1GNF.I&_VAN.%F@<*:'Q1L&$)AP]'X>Y=.H.6O M8E3 I^1V9H$:5M"6%W0VA)R2&YLA"":\Q.DD_>[W.D.@B%SU#*ZA,&HF49'5-CXR0IK/#J1.Z MF!K$"FS'] //A\T"%2IQM(T:D*"@[S_",ZE7S$52SMU,*M$ M@,7,CV+09'OG5+313QLN?N:](&L06[W =B!^;(-XW0.B3.,<(![J&N6($IZ[ M,0X0D!.-<* KR%F?_3C=YJ[A:+*GZ6%B.3;6+-^V#-?Q'!/4=. TF8D/5SLU M"'G?O'B5?>/MU7\@,JM2 M]PMZJ, #3\LI*X_49"E?Z"8^IS%EYR(^X[$V\B>:A]:W_*Z#V0\!]G2+AD'L MF9X/"I<(49TZ;Z:A6[7DK2D+-N6!82>FQLH1@6GUCCP/@)R 9I*^GB"A%>F] M&,U9S0 (AD.K 'L9GM5:QV>?'V_9NF7^G$:7*_(HFLQZ\N6)];J^EGA(GOD> MQ0E3MD@UNU8\;?6TT/V:K$1>F-9VBXJ^<,J**LM[I9)*1CV]XFPYJ+T"M5-/ M^Q^4+=*JE?22?5PY66W[3EY\YUN] M($ 3:(Z'J8Q(V,IVLUW:$ M_[DR#IIG:I6!.'YA%AO0R>=&S;L?D'"HCM>G=IZW,Z+1 M0X9N+V[VTH)D6CYUP2#@3(]' .A."PH_0?.F 5GEG.R.->=SL_N%VG.T!QZ5 M<[5;$\\?LF44)?QS)"M>N7"5-O'N*B$I.$Q:NN,=B8JDI,V(]%N:)UET5P_% MX@_P%E%'J9V$F#@P+?8YQ#;OI4L(C4%=%:9F>&+K<5^RSZQ)W@Q;S,'<_)TRN8N%Z\:Y5/?]\59SBQ=4:(6B^I.'G/AJ.C,,CF[ MLYYVY@+_\)PT&UW)Y'[F*--E&GUDW]ZN0]RI42%'[?@""V=J*HSH9@O/4&\U9G)Y% MI#!U?B0\JC+E9=F8-S%^)%A'>?!CUU,YS5;$>'F1A3W;U;'G6Y85:8[G.R'$ M>(F3GL-KL#,8&0/@'F# +,2@2*TQ0O-VJ%3\: MN&AZ.(AB'X>&'X06)7H4QZ"J&4'"$Q];)M?W8:9R MZA.2SU%!W2;[XQ1-GP #5"=]ZGV)^ZE6CDDK_?>.3TBYB3\7M$X\.;RYTGP; M^XYE8,>*;(]Y&WJ@QX#B%@!I(1T97=*RTY,JXQ/EG N3;>^N#_BJ M9%D@2?(J:G43UU5 "3\@%F5>?6F:)K*'SI5E^]CW>&C)#S4_]F-BNP&HDY8( MU8D]*\Y#-12EJJO=LH%:? !+_X2@%'.ZE ,$LY0"V,S3\AF$@ZIJ/R&:\U;Y M06 XJNX#O3RBJJ_:9E9GV?-SEM:3YY9EF2?!NN0M%!ZRX_X*K?8+1^%KYI % MAFMB8IE4HY9MF3;H #>>I8D-T-W]Y[I4+>.U3A)%?N/P%C-$\Z((LU(MWE#- MW&:J99L]?C2LQB'RV%,=MSAL+W/B"E)AY%L=A"KK",:>AA8RXQ7!9,/3R2]J6:"%==9^DH+=H \F!#Z*UNZ/&UGFO&4\S<:C'@:,[<1 9\=>7ZJ[SOB1Y*7A]^ .(!K$]AP**'[=WXU41 M*1%C%E%NU6/$-,\&WE'^ * =?A\\GV+"ME]L6:[/-F?-(J'6?!\N4L'*^Q]! M,/BW82.>FN^"\T_X71"\^_X!6)WP'EV@$UUO([H%:F9PM@1M>A>43%34R+I M6VD7Z&AT=R4QXB*CW?%,X?W\#_01JKKK_Q%$FC=OX$>0N"L'X4?B3?:4^\KH M9_FF1]?)'JH>I=C3 QM'86BX5/<-:MNP@^L)*A.?1;Y4S1F/J#UB'E\YNI[6**69;6Z^$[#ZGQ_QI3],PP[>L2>[B@#5:[(B"<7 %+ MW\+S5;$(B+=7RB+RO-S>>+WFB]S$5:IA<97^_I2$3Q=IR;;N^CZ:'K=9TFWL M:YZ-J>?J) KLT/9 (X %:$ZLO34'_'Q7)207O"E9U3,O!S:N%8%/;!M5# I, MK7=XW&_Q^,890#4':,."NCT6(*^B'5>$XJS[+P""P]T8\JIL/4,6_G%'7]@W MYHF[]LLTNJ-EDM/H?)TGZ6-=1'&R9LWW*"86M;#CZIX1&KIC$Q?6\1% 72(Y M!WCALV6CZF04UE<6!>=P@5Y[C_.JD:6NB0/?U7%,:>Q%-&#_ ,W"4HWKB&NT M=T15,#HV#5; (!9G K6XJ*X>&SY0S0BJ.5DHCRW! 5!6[B%.>>8*#S DQT4= M\"7@QZO;M$B7T=^+^]?PK"AAQZI3[TYL#6YI6E2AV5V1'VJJ]:HZ4O%CU4G! MAX]38V6&:?60N(J/4WW"21VC3BXXV_&I3YSVL:GW.3FOZ#9OLOLJ+;XE^4U> MN6"UOC+5K6*AAR*(C.,0SL -;<4(SNUCFZ8V.S2+R2O=VKT M$SLO1-EJ1?(",?<3%9R=[E938Z 5V[O5 P94\"U6]S56C 7V1:N/5U&3H\?8 MJ"^?U&W9,+D5[=:"1&?=J&% '.[1P+ T,>\;B3C5A%P[S6W/6_;#YG=-\?7>76@:-;781]FPQ+0Q M,3P/:[81Q'X0$A*#+A7E69E8Q9O,"/F6/"- %C, \T 'LQ(GNF OJI^W?V@X M6^QGK/ S_X8[]0T\Y1%2W-13@I%W:?0I#UA7\\\1*TH>9-CW\IH\T_/LF23I MH=?ANRX.?-_'ND,,,PQTVW)!=FM_^:D/)NQ?B%-#7VIZP.R' RP$3QC2$@)/ M$N+"P4\+)V50=2K87WQ>[_^D8$=>_NFG)"J8#ZJDF;EN2G::BNGB.BO_1DN> MK$Z9 -&AOL5>@(E&/(;X M@8 #%#]/":!<&;0R(&$%T;) ])9&@Q>=KTA:5MZ]Z9AJSH]L]5.=$"<6D0DTIA8V5E@*IJ MG3R>H7F;(RL#\*C]L;J5)1,"PR<:K5?T)KX@>\"U3Q M5NERPQTPNTT2?#$[.@.D,.,)1K.I 9JFF\U(>%3EQ$ER,6]^W#BHCG+E1BXW MLKG6>5*$JZQ8\]X2'7-KF1N(_=!VL.'[=A"[D6['()>PC]C$-JO5+JI%7&0L M*QPV,4.D"@R8M9''0;XQ5H^ JOMAG2+U/FVP>H3N['[5]X[L]7Y0[E8]H=AU M^PPKP$',SGI,Q2.7.2J:%GJPJ_M39*8^O_%3QXZJM"YW8"2FQ>,EESAJP826 MN"OODTG9/?A)(C/?GQ_W?NTY$F#/O*8_QU]X:>7]'%'H/-48?@$!ZX; M8,T,_""@Q*>1"3I5#-.<^@117UU<0B._'+ J_(].YK*B*N46QGFZW\B^1^TZNY69Y_M0B#LCV&KSF:1PUHVX\I&)W8VK38AK<*F>2#$3-. M/P+<,(NVXYA'UBM?A0^W=J.D@IDG88&$#4PG\WT6@;W4L@;L7SM+<+S>+*K;*<9&U[H? M&.OR/+ %EM^3H\XKQ+$Q<4(-1Z$=AJ9OZ9X!.N42A@]]YV]*1D+GQ=C:9TC =-5:F M/"/SEA6,!NRH!&'\BI(VKQG==A.?)Z])1-.H:%KIEZ>B)(Z%F5L>85TW R^( M8\(L'6#6FAA5(54&(Z ]ZT=/T&:-!T/.+C5T>7+%3R1_0UL6%MN9')P+A<9&2%I5!J6?V+Q&0TCP(\,@]A:\,=!#'BWS_.+[2U)/ M>N6IA**-@4Z].['?L2-6)3V*]P$Z*6>_8JH0$::*VT!?JR.]J,2@#D!]8DEU M #JYX&P=@/K$:7< ZGU.;N-LVA]?9CE-'M.C<>R'.Z=NQ9AX),2F&]BQ'WBF MYH%:_PS0FUC]&NJPW7$((K'M4:'@,*7 8Q;8,=QP6LR\&Z$]N+AE+5O4+,;AS*W6\)1D@#TVTA0825N(/M M'C>V$4LC]XH:W!>FZ)4)T\W%[11!QXYGRR%5(^+75=E-DS6XV/ M+;O-LV@=EG7>2-,\%AC&$L-7;#M6CAI,1??)\]#6!L(I*X- 0JM*$A:B.6_. M, 2&HQ1BT,NC#NU5#\]E&GUD'^RJ[^A>&1([C/D8 Q>'.HGTV PMPPLDCN[] M5'_@ _P 7*!CO#H0Y [S%?W*5%8E529^/I]S'S,<(+!=K-K$-UXB(Z0IE#0/I3NV@ M;QCAL2[$64&,%\2900_9KMW %\X0JC@2S-V!XMMO2R9$#7@0^&$ _3GF@8X MN>"P]#;EPNPW'P=N> R[O7BDGA=SA^[B&,:EC?QQ??PB5]\W3$3 M?Y/RFWG^_SP]^9613\OBCA9EGH0EC?@?JE$I[5^TGCPTT:$=XL!@=MJ,(CO6 MW<"*8*V7)^!QZKO2R\N+LP=T]M'H:<8/=V G15N3T3L'A MK"[RA! ?.M13DH(GHEQGZ=UZ174ML/5EGB^C[(6M?[DBCZ+I*-TK3&QH&6', M*2-.&NM[Z1L-%^*)*CTX])M$=1# K)J ].@+9T'1]*IA&:4R6'J6G2V/95BT M=C:+P--R[MBO619]2U8KINE7S*-/'Q/F ]8U8)L_G M%[JZI4&<+&'*$VOTAEBUW^XXV4IV MW5&!;:!)BK@(/#5[;Q),=2TB[EQ 0![V-B;"%QB#FQ1:Q9,W)1"3]I^GU3\_)B1(5E6FS_%L+Q-[AN_C4#,]+[!]3Z-" M)>L@JA/;*5$V $%L83P%8OY3H 2S-N\)$"#&/P50<^YK^7IR:SBQ[RNMZ?[42WJ>MG#*R;'DN; M_,MJC(/XZ:P3BN&CF H49,]=0P H/D,-B2IU8.I<=+;3T9!8[:/0X+.RG9#S MY)4Y"*]UMN7A%JW%-@X<+< FM5V#^#1P(V +Y+WU)];0';4FYQ?<\W@?#;%M M=H2,,/T#B"?1W?BD$,K:&N^O/G,_XY.B'3,@CBULVX[C$VJZD0_R@WMH3:QP3:.(@I->H*(BCLB6.C#GN )("+8C68[M("W[:!!>94695[%4(K^FB4[]+!'=8H#RW;L MV*4^]4&E!DJYF]IL-!SNXO4\L$O2MW\IT'X5K>R,)!6?D)C->3?<85:J/4]I M'_ZZ?&S+:^LBI>H/5+4K;C$\TYPEA6 JG[ZD@K=WFLFD$-;N24TJB4A$%_B= MW\7W/+S-V7%4.*:P]];$]N_B.\W#I&#G:$X,$"W8%TT@1B M%3 R4-VS"HH% M._J?E$#NP+^_U'S'_),B[!WN3S\AYZ9\:%GUX^US0Z"JM>Z;R MJ%[(SCAUT^^.P4>Z%6(2FAZFL>L;U/0=&H(F(L!9F-KAX+GNEQ]O?K]'EW;7BN^8837G'^$V<& M)>G/:,L/:AAZ6[#?A:MU%>3G?>/KM'3V^#8K?9*Q3/)X*?(+)!B8=?.7!^AP MAQ^Q$KSYR07[^I1OOV6K=5J2_.TR63&U/XQ/FKZ+B><2'(51:/B^Y1!=* .C MD\+4.W]%$VV)HIJJ>&^4T[#TFQ8EPL(L!U1.4.N47EFDFJB<7G&V=BJ] K4; MJ_0_.'+6Z2=*^*2/Y[K^(USG.=/ICJM[.\2^ITQJRV"YMHX\*F/XRBV?9M0HL6P,*8 T8D-PXD!A!^AQ?P@ M# 4#C8J1 <8/Y4 9/96Q3\J)QC*>)/FN/VZ7HV.=QA2#2 A)XL>_90F5B )I3FP7.!=JQ@1H^ M%JW+OJ;40'PDF"B<_29B(I" %H+?M@W@LQ@""#1B#"CRB.%CHI1F&TL&%+T] ML SZJF1_C^>75?9&:9,55GTY/C!R4;O@YCJK0@>,)@^ %@]925;MO_-4LNNL M_!MEYBS,'M.#[(FZ""-P,'%T%YOL#.+:NA-0!S1P:3).)[9'G]-\2PJ%[3*F M4#@%Y';5A4 M9Q-G0U-5YX[)^)RW?\?4]Z4"ETFZ7WY7%[D>9:?93DS49Q8 MUE\(""P^)22T6*!9:?+6PL+FH[A@QX"YY\7_-TS*Z2F_S_&]Y :O]D"8PL3W@[?YQ]DIS M7 U[.*M[?25I3UUZ49>OU_7HMWG"=(*_6Z"')U(B?ICB\I4DW191?6Y,NGC& MB/SGT6]?9OLH8&9GUD]!<9'+:#BEDF+DJ+]"7FIQ<1+P! A3ZAHLG%>,6D$PV MK+TO@=KX=;/V>P2J]\7JB$@?/"0YM#;/7FA>OO'!N"7/+&66_*6:E%LU(^H> M"6)JV#==%].(ZK[A.=2U?=!8;D'"$RO?AHTZ9WO#PP)=4V#$1QA(,0V= AZ8 M\FXX6%1#M2;$B#_X^[MVV.&U?21/\*(F[,W>X(X03?7^9^*LMRMV9M22/)?>9,?W" M)"AQID3JD%5N:W[]!4A6%:M8))$@0'EW8O>T;9'(%RH3B43FDSATO '=NB' MCAFG:20T@4N6 Y=!WL^>I-J&6*U2SA3I\B51SJM'\N M:0I\P5_03JQ( M**19I7+80F#5*@(9FJ&,4;PAF767@QZ:(?41"M&<=61Q#:(-+T)?%[PXZEQ8 M6.>@TR#%81S8V#4IB5P2V[8'FQ1WGH[NY#.X,W)('V+1G0(I@>ECWG1XH(C^ MU#.[;5PL9=@'YZDLC($P*FH?"V'\<3FC[$Y*['?W -AGFA<\^UJP[>K!&RR@]H2L]E9 M&I RVF/1!?NXP48[)93S\ONIBDM2[K;L_G5<75#-WT\ M5 M'3I(P"TY3TXE=S_0);#<]2T?WR8=6%=KFY(473/)B&FZK*.$M;#5L<(WL M5U7;.L#D\0QTQNJ ]D3WWMDZD=A[KW?RUO3&\TL2^^ZH2,KVW?-4%MYW1T7M M[[OCCTMVPU>7;".GC\67_#7CV_H)T 6D17Y\*=)]CU+MF3];]LRJY*L+O(X8/U95IBR8W#H-EHRXX<3B! R6*;O![5 MP1R(2JV!0P*X A1%"0#"BP8.<(6O6Q$ _WS;^NN;+BZ13NJ]09T M/)H'TE@WHH'I('Z^\#"+FR_V!_;__V4?:?G@35< M:N.0L$B MCBH;E"XL=_Q:?2?9FA_C/A7E UG3!PX"4]=2\$S^%[)I_[9'C!FJ:#/8WD., M*,:VXYBV:T6F8X- G:0YT9TVWO&%&6.87DM2UVWEM$AQ(70@<^ M+M!!G^D9?;(_9U5,UG4;#6HY?M."_3A;68J.F_)\+'HDG:VNTV/K_ 7GC9OC MV-+=R52_E475@Z1*DP 3AU!,S"CR$L=C?P'-L!FEIMEU[6GWYLO)C94[KS$Q MUZ1,#S#WBR355FN MDN*5A]]\M+-HVJK_INZXHB55#Z 63TV=D7 Z+35/.)C%/9:D;G;MP)D@,5E! MZ:AAD:1246>66RP--2Q*-P4U\I3<;I&6Z>#(3&)LI(D1$M\QV7$/LD7*,J+90!^?:4D))PC;+:7U*K:1+J$M MF,4?%VM>[*/V"U1KKPGEU>0I5"E!T38LS<:B._1<99UNWK/7DQR*5](DXSU] MC&ZVN21E=S M1YE<""?A$943>B#D%YV9)^$4GHS_&36D*V7^\Y^C8KR M;1A H Z1_-#!81(&V(FIX=M61&@$2HX.$=+L:KY0#O.9)WPLTXZ%L;9(F)+$ M/(<*T6%>8D_Q K5]_UK[_Z<$5%:K-D!FX"8V/(3SPQM-W(I"#061%VSB8,*-X&-YG+:%G4+FG0(]15*U:>G M]%73Q06,]L]7 #MU02&WB.0_TY(\T8]M+]D]V=#V0O@T MOJ"$'6]T*93SGRFEW2$1S#!=KQ@UJ&T(XCQ%EB>W3#%'#F M#DS?8CY)GQ9A3DFQ N'S>:3TH&I2#XSXLC-[I!33F]XCMXID]R[W>31/JLYH M='Z,/LVP6%Z 210[V$L,*TI\$J8AZ(@S1$BSL]F3Y1#KG#"J*?-S?_4,;-4= M4I68]U"A )B?D),=WK$[(9BJEMTA,LOV[$X(VVO:G7I>'L+F,!_[.F>60:O: M+=1(VDGK')C+Z,4288*#T*#8=>/$, S'M],8BFHC1EJW:?/2HVS/R07[<\,+ M*NM]KZK90:][?N"H.((J%G0 6A0'= EU_WY'9SLVVEBAX03=3>M,"E ')KY" MC!U!PHO#[L 4<@Z)![B")$ Q=UO/Q9J]437M2*?Q 8E9?!"$'-[##USB!5[H M>-\V?+"$F%OIDP"YCSTA\?O?V\?59W3U[U^O'_\!1"D^KPW+HBF.7#]B.G!] M'$5)@"UB^$[L1;:5.-^8)\J*A'V:U(D:)F M/06J(@8AGH'M-.+[D1'A,+$M'/M!:KBNXP7F3E57N2"BDPI%[8A)J(GM[PH5 M)+:;S!,9MFLTZU^@U6939M%V4V-$; IT1TJE!\MAF52A8?<)+ N)/2A@#Q=[ M^,EY,$V/Y,>JJNBF8G]HKM+J&[.T*&OXB4]%R8Z[5^Q,T%:OE1#P<%TX-BE"A!XN\"'@53S!"F%' 5R6:DFL)@AY'!#J:Q MX^" '503/S$M(P75&1XOK]F%K!X>KAX?@.U!Q_*+.0)YJ6"&WM#1TXES5@15 M[37'BR_;,W-6L%XCS/FG9*O?K_/D,=NL@97ON[V])^ VP':BIR*G?"SE=UJ^ M?=S2Q^)C5OV3?90LS>*Z+?LV9;O8!YK3-&-V)PYM(K.V_DB5LX1V/*%D6Y^\ M3MGBQT\>E>TXFYP;JT:QTP:K6ZH M7E*SB@6/+!H5!\U>"* 3[!FJ\:SU 1"(JD$3[L D^7>%&Q!5SA3*@/ ZD@X_ MKNMOV-&@+E@^/P*LF6 >FYBD#L$D2),P\FUB&@G(M0^2TNW$]X31CK)T:?"( MO@1]B1(M %,A<@J .XA)V52Y@F%"RQK]I, ]\YY^ WZ&O*?5;MS\QX)6-\7F MGOYSFY7[T!&,?B^^HF;;[3""$L8)RHL-*AM>]J<>\4,A0%/31T$]2H*9=E<_ MG D.,HCN3_2C>**4G.Q2!ST F<6.=W#1NXDP)3.[^;K1"&.UHMVW)W^FZJ,>N2C8*3>I8+#A0JS*YTH@TI?&&@V5V6H5X M!18ZYJE[:7JQ5Z>ZO)*T2E0W"TW2?9]&(5%U##8)"2\@YW[VTR^/9E[VRNR, ME..5^1ZFMF-8#@U,WP2=*@;H: Y+[MC/^)9;@Q74L^_J4:QK@5&L(&V)N0T% M.H YB<,XVK9E9T]3G>%/"*7(S(>H+&K4$Z*>FO#4X_ #Q'5>9>S)]I)P=S*Y M*XOX[B\[]09=O\)P'FC0#H3@OJ&9&42@,$%LJ M!A99?['@%R!L-^J%O#:_(75PMS&M$ >AF;+=QO5C8L?$-SS9OM/_4_>:\YH2 MVVEFRP\SZI/&4 V[S*A &CH\WVF'&15SK%]S[NZR6_-WNDX>BQW2VB&AO0?+ M[)BRW-BCZ:6D?B@%O%)BIK-EM/'FP*_[-'E2A9Q,Y4E,I>'T_H3 M,V"E6IEY=[73T %_3P"G'&SAPA(KLO9I>HM:OK#XIUY _,49\6;2#05JK%": M?%J3)]$\]>1"FHU<-.IL.1)/5$]K"!"/JU".GFB\90;]R=E1'8]/B3TO&A]< M??E8?$K0LY'XY$MR&_T=+=.B?.$!Q,,S8=_X_.@G8A$! M "X'Z.B.Q0]444,6.%-H2DUBN[@"X6'V+",W>*>>D$K1_CQ$9=%=>4+4T[UX MZG'))FBZ9C]]^HWFM"3K59ZLDI.=HYY M0"T3"IME04*K:J 5([IL4RU($;U&6]C;3@P7 O'AAU$ MGN4:OA5!G,0I >UE)CMR/,'&"<*LOZ7K)-O1XSXD\3#.. M/>RDGIU:@6M3%X3X"B.OV3@[S-0;T1$[0*1XF%K%K%B?LF V/JHG=&!%<3G8 M/#6H@HB'$5\6)%Y*,3V8>+E5X,FY>EAT9WCT']4-W;1E(] Z4I&U]'N/SH#Q MH]GCWZN_(<9/6^DDGIP3TM!T?DZU0DPO&JI'(9)+9>F$""R6J(.(V\W5 M@=Z3C3-JN+4:&OHZORN+)_8KH'CN/%%BRH&*2EW0<< M**,L1Z\M;6CP,*PKT4A!B0:@AGXL_(ZL\H&2 M(IV^V'*2V\M4^*W-_'IU^1 M/92SA;-X0Y,:;.MKSJLY'[[V$O#U$2%P QQ2CNB7T" T'9O_%'9"'Z&F_;B^ MH]T@ *.:.OJ%T:]^A9[HQ7I KHF7Y$"QKR\T)B*COTC]%:. ,@('8_ M'2#R$LS.$YI]6VV3C'VEST73_G]JU;89X"BA-K8B-PPBD^DU<46L^LS:FFVX MI89VY,3,]IP.QHUTIF0PDQ062MCX1M@?B8S96XV5L3\P1N)E?L=+QYNV2'Y9*LK_.$_OC?M%<-&H.FH8C]>4WK@4-YTJ(6U/_. MY76F[>[M@'YT,/.19L MW7G7NV<.+';<=)B)FH;)<]B,>B#1AJB*/Z'?]ME=BAUN4=)AM[F?[O )ABU0 M\Y'$ N)%=2Y7T-*2O$ UT8M:OWNZ%ZC[';HB7*"]$,T[*Y%O(H.DH%2!ZG 7 MU+"U-$J#4F6>P710N[ZD(TY8],36)VN>*[S.+\EKMB'KSIR6TXQ>2 Q,8I+@ M*""A%7HABX"$3@OB)'4?(O8,H%?& 8 V]_I53VA MH0;ZJA_\*ZLX^$RZIO55!XMJ'CDRZ+'S3-FREQP_B3WQ#TI*\7U#Q6>:WF@6 M_D(P9[+TQU&\U2G4K=3>J(+^8INI0F5U=U^5RTINUSO@J@/"$3N1'Z,<7?); M]@_UJNSGS1L-8%4[\"X-,$T"%_N^[^ @\0V<& %U8]MRW<"3R#[.XVJ9G&-# MD=>%QYP3'-6LU,.DUN0O8)',S,\@&&7IUZIF\+2:.]RP5S_5O*H>/TV-JE1% M?_.8639:5**X7G2I9M69D)!UZ^_;N?:!IGLG=#"QO03[)"&NZU'/-T#M T.$ M- >9!Z.#]@4,:D;,'ZF0%^9I#J)>-,WU["S8_E=+L-W?#)ZG=EPR7]$!L+%EY(U/_XK7VQJ=@_>/U/TD6_9X^ZC*VTRX M M2!O/P('%G%42I;'O$!+9J2T5:*C@3G-TTM+FYRH.A+-!U8X+Q+X9$&Y [66@7!LV<2D00\;488 M#]!N^D.W;"?8[^?5:86=F[HX)+:%T]@+T]2GL9%02)0(9T%SM-CDGM.)F=VJ MU"GF-?4J">8:=W/B.TZN90?]TC+TZP4Z\'0(!A6VB*YR!9<%:I174 M0W*57VE.M/BPFW R-$LLBEQ,K,#"B>T2$B1.F'H@>)@!.LODE_9DI:>(#:D) M$H?-$EXJV0226S(N&I1*:833I_(.LCCN''X>TQ'XMXRY=Z+$E>U65H M]_2U*'LU^$Y*,4GM"%L!BPT<)_$H%4H$CQ'176G0DD4'NJ@A+-XF,ZB?<0-5 M)37P]AXN,*A=9DHBJ8Z9P447:YJ9$JO;-S/YK&0(OX-2_O"V_^/O&=N*R_CY M[3,?2K7ZT9\#'$4$AZ;GXL ):6PRBR0Q"!E=C*SN;,@>ZAOM:=<-%3>K/]C^ MPA@ [JF"RA0,VI6K"!BHS] ./" '":LJ"!0_">9OA..1U#WLLZ!U'Q>RY ^,69];C3M1P#U6I'&6/+LGR. M&,ICH33$@9_:?,27:SM.2MPXEBK&G"N;KEOXU\!:\R-:HNWYW/V/O4[BI3Z&#AKCH*,/<=%]7FV]7+Z[IXHV=F MHM:'4<-/<62S__%<.PSB.+(#4Z@J[MSBFEWHGAIP_NE9/8Q[K[G2P?R/4L&2 MMFZDP:G6)> 1%1V""GO(,4D:'\>?J!V7$=A&[;S.OK.(^QGC=N= 1I^1B^ ^ MTI26)4WNZ7>:;^EE[Q:P=@96;&!B612;)" ^B9/0I* JG_-D=!??M4312ZVI MZCE[12F%WO@-:$@LR)DO-\QA[$5N"5Z@2]67>N,B*0H>!H@L&@B,"WJZJ4\\ M#2^+O>3 7R4EET72:U6T$Q,3@[@X#-/8=BT[2#Q/M!2VN[!F"[RL49H8+<2) MB9>\'LD^;FES)(+9EJ PH'+6+;18V>HY]KNEJF=_KK!NY:Z=G M; H4T1K^37-URADY=9:G=,F]?WW*&>&%"E3.O3=[?D.-Z,=O+DKZS*]K=RA% MO>-J S)BQ3B@,:]'\4@:F]0T@^#;=UI&A<1LAG':$ /HPF+/0HC28UUC=7EZCU6939M%V4U]J,F]Q1\JZ-TSY5018 M8/73#B;HOM MEW/AA,_PVYJ-AI,0MY0! :=M9;YLP)"XH8=V!"\ZMH-&90:9S;A84H8S ML.1BIC,N4M=X)IZ41 !NT[0/M/R>Q?3AF04D'UC0G'3!J&^*_#NMV-;7(%G7 M9[[NSR^+:G-3;/Y!-YRYISS['YKM/&H6N[V(L]GSB6 MXY$ =/I=EGW-ON'OE)<]T 03]GW)$T7E@39ZK1D"X@HO^W'%0O&?]Y/!7%[- M.*XY1^W)$JW*DCU"FW%H>QD: 'B.$5-MV+]NT!O=H /?%ZCAO(9\[_"N$,_X M752N"O]X6>:7Q4M^EP_3PU=^'RXDB@'.L]:QN@]OAT=:H[S9\BCS-N5#%*K; MM!6R-]']_PD@-J-]_DT_-J0UW33XP21'M/6GZ*]L M\XPV[&4N(LG?.'KF7\]9_(Q('-,UKYYB+W&WROO8BSC>EM7?%%64J-?O:#&* M0G++U;&HU]%1"8R&Y>$Y$K9O_\8V^2^45-N2?J157&:OG(]#5Y%@OF1Z)=VY MDR+'OZU6=ZAE 75X$,^I""AD.K^B5A>P#6-,#>A/I9U2,%&E\B\"RR^6BQ$7 MM9N7 ;PEVZ?4-HE^SG)ZS?[8GUW@62Q8(Q8.+9H87D3]$(8-V2>A.Q ]X")R MDJBF">P%.*,7L13$/&F!X1U,4(F>HR%9E#49]0@LW%4T)&"_C6CP23G#^YHG M6=5J(:J>4T)T4,$T=.Z&,[--.(I)%O$1#6?+,LR$'(XL?+8,VT4HN9-EP6 MF-FNQ@6 %^ <\:NJNJ99=-G2F2-!>G4QQS^="=!X5*_'S*I3L7?2@4L=3*D7 M8=^S(TQ"T\5)3*@1)X'G!T0*LU& N.:]]C-EVJ07G?_Q'$;%:7:F&6O916Y;$E >I1#3J4FRJA?,$>A7*#"1 -/E0LA)4LI1CIH$X^*=$).D5#6,EB2W MG+XY\8%KTS2BCI^ D#=!U#5[-.%!>?)I39BR MQ;R9-A7"?)A:[6F9ZZXKC0JC_=--;9],OLHM(AET25RLUF5+5__A M7UT&4-6]'(_/)+^M;VRJ59+454IDS>?[K@M^HW-N7$ =M$6.C4.#&-@P#,_T MD\CQ0M DUG>28Z$R5K0K8WUB\FQ0PLT\Y3,ZOO,I#\!8[YV^N&"L^/-_1V"L MV:EM':Q)BMJ:I-,:V*;8M1$-=61K>P0W3#K4BG>!#@*BCH1:CMOO_)54!;WO M),6R0?/[?JI>T/W.[,CMDG=E>T*HX15K!JOKJMK2Y/2VTF 1>N@:,39L.TZ] MB":QXT,VLF%2FO>:/6%4<%JA;*:.&R/&=&7V#:@1@LP3WU0P$.C@(8L MNAY7 -AY3LNFR+^-$%K4!4T+?.HE!-Z84?_#3_?L*ZT!J'Q#8ZZ"P,!!Q([F M06IZ1I@8)B4!N%IH!D-+U!9)WX/,UK9@S+B@#H'!7ZV^.IW(>9,9?*TG?E.D M,95U47/86;Z*2H'RSM98R&*GL.[UCOPK57;'.XK?^P!D?DYB=43S'3:! Z-^XB1HR8E]W-(OY.VJ3FG3 M_/$O]D]OS?]^8K^OC8L\#TT>^PD.7=?"5N@;B>GR.1%"->#J6=/LS:R_^:[Q M+ZAA&=4\HV1+$>,.L5]G!]*,JO2+C#N[]]4ST ?.97,?2LE@M*O]*I NX??Z M.G*-PDM^)6 [L Y%CG<$*Z6X8%.P#DT=]P5KH2#9>?"=9&M>*O2I*!_(FGZD M$6,FYD6O&:TZJ(>_E455?9-[T 5<;+5!;JAP_CU&I4O%M$OKE+8_L;9 M00=^+M">7\QH8\XQ^[<.X&S-)CKY"!J$T0)3\LVDJA4 M8Z\/1>GBDD-*]E>XS2S+W?'EGM:4.4)2U;LGK@9KPJW(QB2.0FRFMA&&CN?% M'FR:R3Q^WBD%@NJS'7#XR4S-B[G0!?6I.$&B)3.B2!VJ1K',Y&;9F2UJ5-<; M[J)H67U%XFWK[-$3'S/V(H=!S\BZ=W$34AP:OH-Y78IM.2X!7MRH8$JS(]RU MA6_(#Q[XY- H4HG>Q3S@TMJ$N4'Q09<[E9\^U^6SAN7D9[%EZ\]%U;=@6?HD M2S]=M;JH$F6*V(77ELA'[Z_@2)XT(TQV38SU1.0B_5K1NMEG]5*4F^Q_F@S: MB<],/!\'@6WA($I,V[:(G;A"UV7R+&CVD!SQ*B;5,UIS/A!MJ@L ^4LYO0ID MC[5K2_(&'<*.=CT"\KW:]2F7UVT'(Q2\XB+%6_Y#SB[B M?@P5^P('7EV5MF.DZE]J5;"/LQ0XFL^56WFYO.TLR8_RL_-6FC?@E&THG2;. M4]?NN#$.7=_"GDFI[T>N'U$#@@ASG@S(?<,18F[8[W^R*U-F42Y:R[9\#VA) M\/@^6W9H2K/3I-VA.)XHEAYT>EXLQ8-.3XB\RZ#3\X(.#3H=>!H.I'I'"]A( MIOT+FJ.CNZM;W:9W9<;VNU=>S,L1P&%8 VXJD-"FV4>G6#\Q$.3>8LX,X/Q=[2*2+ M!B&)T5:WE\V17-%.)\7"HOO@'"6=[I*SUI+M9BKB_V84V*_;,T]#K_+DGFXR MME5_9.3SIV9H2-,^=7HE%D81#IR(M]VSP#>PC"B*XF\Y?>+I[4=( Y,X#T*6 M%3:6U>-$V,H.S-10H7'Q\L(.F$=-C= V)GDU)R93,[%\[!)BDY IW(R!<-** M]2OOV=]7L6(.7Y>Z@+>(G O48:/.4K2,H(:3=E35KLU497,77 7*&KD I!=N MVH(KI=^@);&&9#,6;V[O'+9NF)3;DJ?%3QV,9W@X3!,7^X:=4!JGA,(*Q(9) M:78G#8;%FL=$&QX32:]TR6V#B(J(5]TW)-PXL\T[<@)KM;6+.![LC MK'$OM9CMR<@"L[1),O9_/'B[]<4L?BS^R8MUT M)*6_%R_TDM\*E6^?R5^KEXWDV.G)=?57GQQ-;JX;=S8%VK/$HV;.%&JY0HRM M"]3EM/%<;W" V!0:.J)]BVZ2!$YM62F$Y6"&JFET/ M)UZ?,>L_=-B [=UB"A3;V)6K!>9(!C5R@=H>9ZV]SB#I%<4/8C07#2Y :CB- M/& OR[F,M@3MD?SX-W:&KY(LKET3/Q)T6I$MRPNQD20)AYXEO M1"[/FP+.UEM=YTUB< ?FNVJP?.L??B0;^HEDY1\< MQ[=W=Q!0'$:6B1/?"5,CL"GQPV_L[:AX?UADH&P0@^Y**&S7.P[P_Q%0R3-_ M,QPCP5'B.-@)8M-+*#$CX)#2GT4RW2DL3A"*7OK3*.?=,;,U?DS@A=IB*-J- MR"C+]_=S>Q#V5N[F$<0E1UQT],>H9_F)P+4E/^=/#[<-E>LG@'1ZQ\^Y'"2W M+(.SCG(*4'TMU\&AE?B8'?:,T#8#QS4-B3/>SX?GN^O6DT7TG:%CT,GPIT+Q M/=/B^*[HO?-UI/:$^=,C]LY7V,"9='F4WJ:)AAY-8WSKSF),F5?@U84< >GT MV$!#!TC8 **NV94]LKV&$DX0Z,) &A3T6KKT G14;1O< M^%#66F=-Q3%G1Z%?DM&"*E<$HKVL]Y%12\_A2"TBYV,._=A'W=KL'QK']D39 M/]+=<,(TQ([O)-CW/ ,'!@UP$(2!$1J!DP:11$6Q(/EEBHDOGWD47)\'MWG) M&'K*:X@LWGL7-=X>>,U#*&:(]1A"7QVDU/WN/O1KD28$_H)]0=! M:M"H1SF0!H@^5:$M2"IA'&@!NNB"& N2\A[#*\@NH@;A]H *>=ST]O=L\YSE MMSFM ]*A2RSBLE#1)AZVG,CW0]MT# M4!CV/'.0L7B%2(H-<&_9'?G1BM?I;W#5:[-8OMIMHP?\]O M8'(^$> "\;X5GO@LZ3^W=>OMID OY+\IYZGMXF1OI[P(H*B9IR_-J]W%5.&) MB7R>T6AV=('E(E<1.8ZB5*$7Y"+2>\J7HLD5*7/VJ09F%KJ1@4//CG 2DBCQ M2>CX5&A\T#@9[0ZV(8IV5&&QXX!JQ&+"^0)#G>F)K!KJ;\=E4A1V#1!9-)P: M%_0T3)IX>N8PT>,+B^$V=C--<$0C&P>>$5,W\L,PD1LK.D11L[5^WO>Q'Z I M&XQ5^;[V226*&;-2U0 3CCI(+WW&5,Z)?[@P-+)%U5B M$IO$=E*)VT4X)\M<-.Z*C**2 MY/'S'N13":KGJ)[%?(@FM2E& SWB9P]-/QD_*0(*%=&&5A#1409^ H!1$06) M@8\*K?2SM0,Q/E.:;;;L5QO<\6'9%HY($&'?\R.33V^V7- $HY]#+/WEK9R5 MGZ?A _3)Q3SQS\&L/N^^7*M'1][_F[H\9#[C3]_B 1+J_Y+^#ID/N5QSAQ1W M,W!.GXLU>Z-J^)K ]/#B!!,KC7 :N;;O! ;U4Q"FQR1%S1O9*8 DNBN+IY*\ MR !LCBI.<,]1J0[@=M A_;]:S[X,A(>PT"K!,T?I+8^8*2+^69A,H1?U#!3^'?U,_%>]4X6)^19?^EJADKGEJT4+>:<#=@&H6G&=WRL%/-[YN0$4R MT^J&EH+C(5Z5)8_&=K!HC[Q(113S\-R[FH,11K+(:;&MUF_-">OT9+9C1AS# M\*P&QGV&"N&!#D%4;O1GS8FBL2MC0DIA#)Y=<#$YWW8Y/[8KUF1QG^>7LH*Y:+(\..<&@Y#O72Q(AL&W** -+7;,8[;M O M.WY^Y16JYP)L]"=G"[5\ 7O$H5H7"Q4TZA+F%32H4:;32489ZCJ>0-27[GR2 M4!$[P,1AXKEN&),P!>&5CA#3 M[((NSXP,Z9;: =%* 5I+' L3RW2P'3JIY5B.07S_VVLSL6%#RLVRNCLE+*5! M1#8HHD]9SJ^]>!5DLRKZI5'LK_JT:<81CI*0 ^LBC]G.;W>T)>I*I#!]_3]1M;DT&/VPGT;I[DN*G[7 M@/[DQ%%-7=&!:U0RJ1/7^147.W*-"M0];4]?^:CU M_(E%GYMMK\[2HBQ0MDF*@]CQXL"*/#\02DY.$=*=I*Q)HY8VVA-'#74Q@YU4 MUKC%JE0!T&0EI1KPL_+[:$W=,.G M'MR5Q?X97E*-VQ@,B>!]@^#%"KV-:L1UG MHQO7T8X#7ACWR]=&8;^B/1^H9>3M@M]MKK?)+JAN@ K9XWN@0G4[/%PYBC9] M .%%XP"X0DY# XD5X ?$1VZK=>319#OO-SE@)MOYMS5O_C51U*'*9^UNRQP\ M6VU ]NG3\7RQ858O*S'H8#PNE-3)>&#)Q8[&XR)US\833\IM[/R0?9LV902? M2%PW61V2,+Q*B::&@4W'87MY;$8L%'==[(74B.,5$E+17CM.:]'M54CLTQU5["559?W/ZTE#S$]H3LW=U.H$9 M_"QU**A4/B>EMC+E(V+O7*-\3O#I N6S;\EV.D>; ]+4*0;5*D]^I^ODL=B! MD;%PK=QP1.'+HMI\H&E14@Y>]A='\6/O-([I0$V8]-BP8%C 6LOP[K39UB\H%XG@S*")5!NZ; MUO35Q-S4S_ M8 Y. )ROQM[CC.--@3O8?#OF$>?^ D4U_V@O &)_W05*7 :5 M7=MZM:RLMUL3FPMW@.M5=K]/7#,]2WDO;\G;"LY<,L_QYY==%/C3-=?DOW[2)K[ #*T2W-KB;)U:E45Z*L.%I>% M@M6HY!Y K$Y:DOG!(G]Z9%'M,4+M/7UM)[W5'$ZV*IW!P*=ATH_"4 LNM1P@-4RV(VAJX*N2*>%]]?IMVNT? MOJ=K#N_ ,Q!5?=$<=4!X!H<3ITF*29P8.*:6'QI!'$8&*+B;QX[N>Z0:U2LZ M1O7J '_)WB;-_ :":=S%- N\C3H'E093*CS9JD07JE*J\YA9-G&J1'&]]*B: M5767LPXZOT7 M].GZ9G5S>7WS&UI=/E[_[MAOY89%B[Q^X)7[2L9)#[,W-'%HLW M(F84AL2V M31H^1(0^ M=11"[\C.(/I.V:[RB?')IR-S)\-'REUNJTWQ0LNK'^T6M*HJROX?1S(_]121 M33G(D('=Q @-P_#-)'2_?:=E5(B/* )S ;&=+B_ 6IVRX0PZO6BV4@E3:N1Y M%-/4CP(K2*CE>K"I3UI5*MWG<+^40L7![L)FEN1']S?S5M*'/UXC!'?JBT[]OQU13$S7PAXA-/4LST])#$*_ MD6!"]P[ R:E'%N^I4BPJU:T@F"L7QQ9OL-H[3+T3MOB0;A8$%^^Q\-.ABP\I M209>?' ME1,7!],@O0#5"#$QDH2Y*L]UXS1PD\A3-FYQD TA"YP]'>%\(&M0E^(9BR=YT>.TJ.X1BY.:T#I?<9CZ3S!<<5(U8I,5IY>1QF)O M/-\=R3CP[8;7VGQFOP;K%4^DW]-TFR?,(U+F)1NP0,LB+#YR#>:-0I[*LZF/ M(]^+_= D<>#[0"1V<>J:XZ1.!,"YN:@QNIJC1\W1[FJA80KMN *#L /4+>:< MM"D1YII4ZT\&?1VN!W78ZP#:2R.OP]5R!G==8A$YE_18DKQB/K!B)!YH^3WC M-\:W[1$RXQ74^^%WCXQ"=?Y''XL7DN6G\5-HL_C)3 ULQ%X46+816!$(S4$E M6#?S?EWZV/&*W+RI/I"7Z)Z M]Q09_OX0FD!UP;SI9:[%X!_:UCN M?URNT>3^P*O+9>_'>3]*ST\\*A>VU8FR)D[LS?U-/!RF)L6)YR21';L$B)C7 M67N);'F;#8:%2%WYQ2(<2:F MY4B H'#D3.L*XHFNBLO&@R<$>ET+S_WB&1# M^?6GV^O\.W. 1?G68(/VBL\\MA53-\ D-H+(C3S?,D!W46=H:#8>3A'M28)0 M7L<4(V9-,\6%615,4G@;][ LJGJTSU!8M@%[6,1>=_7(HQ)37O^Y>5O]52;5 M*OFO3_EAY+KHH-?SKVNVK!:JL!X,4QU?0WXJBDU>; 1WJS$-C-N9(N%A=B8@ M-_I3Z9AY 3'EIKT.K+GE.NWIPX "F@V/ MD:2,9CVS8T]6W-2&Y9XV-B4BP\RMF>YU5F:E".:3HLF/]SJ[ZK(COL8$ZXWY M&GU8LAFJ;1-]+%8Q\Y\E?>"PG!R?Y/H RGEZ1O.)BZ/ =;!#0S-Q8B]-[7A7 M62 6< K1E2@E@%GL'?OW9U+Q":;I " IL%5*2)UB0:HZ%I M2%WU\!VV--7!BVH!5 (_N>C[5;^+RCM:^"Z\B%RD-[#Z;KNX;X!U]^#* \[; M(18.J65@V_<]SR,),2,;DFF48V.1\H?6/B[V!L(+)!N^+M#'+?M!RUT'X4L2 MRTCR8X@%COI5#'/QP]IEH65$VQ(P&=V" \QYJE$4<4HRL6@(.D]1IS'IS-4D M9_?$SS39KNEMVES#-!#Q^^JTC^P_U2:+N>-E_YX]Y350W"'%>8J'&? "UM3$ M2>#0Q/4#E]B@B\F9_.@NC6BYXR?AMCRS'>MP*-9D7K!ELHDJ&C:!,X%F?A4Q M%[B@KF&^4%[-+9HD4IK!5JPO5?.)9G*S[ C-:KK33A2M*QD72WYT5-7B]-<628$8X=+[93/W9=XLO="@ARH/U^H"F(RG:4.Y-D M9@.J%W1*H5-F<^X)Z]MN"?,\ MH_2T^YDOE-]#YDE6T=K;M'3!_8(C*A/S)O/5(-L/6)-#O^P(_\KT@*X%5"'3 M^C?6)BDM(0.U'L1W9@^Y8-RD1#&5CV)O$"[3A"+4MHQU.-.C*-*:)& MZV)^0ZJBN*AY)>MG)=43J^\7G:=F= 'QX O1]W-^V?. M'(UB$T>.1[##_L\,G30,[4@*_$",ONY<<=VMO^&4),Y!4%T*1RZZ- 1S0.(X M42>@!YWGZVG,BOL$)!6D&O1 D/K[P![ 5#,(? !<9N[UU@-]XB>S>_K*\SBU,;ZIDGS@0[WI *W3]\!>:,M'T]06?X$WP3H,?L MS&'K\GPTC"UZ0V?GM7'.+]#ABS;7+.R M>^Y>-[VYH>EAP/%MVAU\/%YJ%7DA)BP@Q=2V@\A*C= (7+FX5(R!!6NK#@SQ MO]43OS>[B=^R,:J@EJ$!JGK= 7WMN-KV@](7JHR"J4-Y\"I(_ITB5YARAL-6 MX#KJ2N'?+K=ER=QC?5KG?K(#KG575!EWK%<_-LS'9HR3SUG5NY!(C @'Q/6Q ME5@T#$TW]6+0@$LU;&GV9;MB[G5]7[<6:"71^0G$7-KRBH4YNN$"^9;)-E=8 M1Y'%;H((![?:<8K^//"*KO+M2SL<4W/IO+P2-9;22S#U[J7U\HH4*;6?L3K, MP5;EYMMCMFFJ5A,.&;8EZ]6/K#KUE6%"V&G>2G!*2!(Y=I"$B5#F<9""[B)1 M3K,IVMY117]RNH*)Q6'-C+LP)?+"O%$C*K^6.'B7<4F%?@73;SJ]J-N%\Z37!@^P%.4RNFAFT3-P3A]_5)Z*Y6JBMZXX86(N-#U42U M(F:7\V2%F60[RJDFMH_&%4-CGA5%)4+F,8'E@3+/"G@6+_/\DW)6=UF\O&0- MVLDJ3_A8T2Q_HBSFI16O#UH7U;:D9]K;CZ52)4F-8?('Q0JA69D*++P*[P[Y>6AU^U M.!.8W"KCCVFBR\(ORT!?[I>/Y:DGG9^N,?=S5T014 =64.SO3/2 MJ*7=K8F X*".*6#4@407$.T)%%7D>9H() MS;ZMMDG&OL&GK'RY3GK7?)1@8KDVMM*0;<]>X+IB1X/>RKHML:&%.#%T_5', M /OBCUO<+*& )B8HC[!!#?(^8D'LG<:"V!\.%M1?:1&3&11@9R/##\#WI7KC MNZ-E^H62.C86!^0^\^HBZ2E.DA>]\KO5EO1D7X60W-.[T$R194)*&6E!F\^( M3%)[SKGU%MMJ1H3I[C!CCTE"VS^^/'W)7[/+O$K*Y-.:/(%P[7MOZ]Y%:O"7 MQ^REQN:[N;OF*9 J8_**SK,=$5P@FILM,W"3&1$7_RST75*SM(2(*CV/2Q:[N!&9BAXYODVZ;8D+5@2J5/ M V1_>TKBOGV?)!.>CFM=&F] MHUX$TT?S9 5N[+T4$:I%NV0_J2Z]>A50<>O6 MJS1)HW]7?4ECX"O4VTP _%GZFP. +Z@" /K]U(KO!7TO*.D([KWH"O L7EM& M\"FK8K+^!R7E59Y\))M>%WQH6#@*0PLGADG#@% [CH43>D-$=%_IMX4W#5W$ M"2-&&7'2XHF^00U-Y_Q4R USBU(B@W*!4S))I04'%UTL0S@E5C=9./GL3/@< M#O7?XA6O4O9[?T_3;9[;(-$K@R<&(0G!L6M1[%.'>90@8G^RJ1W9 M-$U(D,YNU#M/6[-KZ;;(?MIN>"':ERS/7K8O:#^_;\M'=.YZQG:X>"K:]0:T M+>9I-.D0YFW$)M,<)M)H+,J7T(?.'KH!RN_?*#>N$J%NN(DEY/S1[W2=/!:[ MI0\C6D_S.J:1XL"V0CY*BQ(_3+T@2B#.9XB09D_#R>)-@5]:PA>('^901*H, MZ$M$-15;/HZ(Z6,[\)S N&P5/]3H^A4FXO=$)S5>EW\5;MD#H73CJ'@>5AUCG9* M'8J\ZB"915WHE+"G_G+R>?B=]TV1W]'BAA:K[T^/_)>?0]4 BD>&WM?L[QA9 M?'=UBV[8_]\A!]?D3V"?@-4D@]H8MV55BH#9L1H=@*[%IX24NA@?7'2QJ_$I ML;J7XY//R@4H'VF9?2<UR9\^;F[3N[+\1WGUS\W;ZJ\RJ=@_)]?YY?6;P&:249>%VS;7"JB)/% MYA%>>LN!>$0_)/UTP*Y <)C93,BLM*=D0CBIB'EHS<4"X@FANO'NU*.RQ4M\ MN&E]EWZY)E65I1E-/KQQR!#>ZK\EZUV^G!^LQA'XDMC#D4<]]M?(]3PS3@([ MA%4TR3.CV;J/(;J/AQH\D!92DE\P\,OU_9WZX8X!6OE8$V)2(3&/$GT=IM> ME26_JCC )XEFTT67T;A+M]2YYV+TBYP6VVK=)L1.1[UT4;^4YN&A>I#;T$4( M++>[ \0]VNHA[\U.8S5C4JZK:GLFB"V7!&YB)WYJ@R[-!N@LDZRJ MFDQ,.ULJJRE+YZ:.U 1.1\D*/R<#U="\0-?C@L_).)T32WV2Z8C*>^65SHDZ MDDHZ^SA\ ]HA,W P=<'C;^<5W4%Q0^E?Q<^V77&FMTU)26 VTQ)1!@,_P+C4 M=M9=9[%=ZPSSW[8S-;:%F?M %]PRFH.9]$YIG7Z;EBWT M2\O8KQ?HP!LZ,*<%G7*^CE15P\LSLFQQ_&R%]6KEYZ\(!4G8LJ/IV[>KAUY, M[2@'[J>$)C8%KD-=+TF5%( M)K5Q%!DNMMAO>4SL*/!P N # M*$4$4S5M@D^T^RN+))M7"/%/]#R>Q;3ZF/Q0K*\-Z6< MF#ATTA2')/#M@-* BE50CU+1;,0MW?I^IB6,_FPH Z:;#>MHW("520XS7"FA M08/.)H6:,>QL>.W%!IY-BM<=>C;]\$Q@"5KQ7MT;NFDQ)*(4FVZ28)^D'HY< M+\$F.P*;7II8;B!4.S1,0K,Y]B 0SB(?7#2=.))@$0=UB>VN\Y0 LTPQ^34@ M/_1D4PWR<"#P/G@./0$'H1OZ3P(WSURM0-TL7!,@Q3[-'%Q9(0.CFS3 M3@R;!I8KU/S;WW[^I\[VU*ZPS$9TS.Y^RSGY9\F.N:PB3T\E?:JS';?I/?U.\VUS^\$A.XUX8F\(UMQ?ITS:R$Q;_'[2#9D8#AG' 8X M#(T0L]W+C]S$X?\#JSX_3TAW;J8IV.[0YL5@9'**)4Q9XP:M4@7 Q(RD]!*U MZ^.BS:AC'UAXX9KVT3SRN$^^H;;)U1] MRQCM#N4R;9&IUIP'M&Z9 %?)CJI-;"]6I0R8^0XCA!SH:2.HL\+X$B&SQ9?%&K.R_8J9T- M/"4+^Y)29J')/K7S^;"7-.E28J26[^$TH!'V;=_ 860:V'&B-&1FYB4V:.^< MH*?[*-M2K[.'GV5WS2F="1YBU6D">([=*:&32>W0OD",NDK0&"$QE0'(C%-; M&$Q&2/0^L(S8:Q(@,QPIJF[U6+_Q!.X?53V_K*U'//0_B6+*B"VG.R0^PAIK MV:FO!M#WZF^H&7[7\@0 A1%4U;BM:](2,/\+4!#Z4VD3F(3\O[$3NT<[*?: M W1R?,Y>,3%A 7G$0H74CR+'C#SJ) 8D2E#*G>Z8@@,HU5>014[1&T="VC3L ML%/Z]^9?@ &&VH\C%HZ\F\JAP;YP6)>:<]]%C.[BRZ]I9L9_4A1U9 M_K2FQ\VPN_OD&M**R8E:01&75%U8I$7=BH(HM;PM&G)I4>MI@*:'B/3Y+,0E# 1HJK_+,=Y M0'&'"?3*'FD!MUBC@+2@]YXG*J.^H) MT%SZP">NAC/'/L#+LG>:#R\LKORPK1BIJI=(M5T?!Z[E8<^G;D@=TS%MH2:P M@?67N<&L2:(=3>B]Y;%"QLU:@9@P X9)*'$W>5:.&5>2Q^LM?!-Y5IC^!>3Y MQR0&N#[0/"O*FV)#J_^D97%79/GFAJWZ^%=Q1]D'S3?L;/!OV_7;XU_LS^W_ M?F+?NL6//=F5B17C*+1]'*61EUB1E5B.T#@S%.8!!I7/5/F[C2RL3YA".%,A90S5OB#.'&'>H9>^@W(:WW7\XC]- MO>IU#A@7NZ#NY0;(JO@&BN;**M+5Z*39N326FSVK2!M'TVA5K2F-,?-:TF>: M5^SLV-P'W-#-;?I(?O2J6E*+G>F, )/$":A'(\>-;<@XI!%:H,T!/A'I\O;+ MW?W5[UQ$YJBJ2'9^;W1'?7<;_P>4:_UK=P_/*< M,7"!5IOF3%##M&V8AR%J:UP$I%>'23-(:6E-_/P M3.GF,_]4;#/:%9$3@T0&,VS#LK#O)@23@/>^6[;E>7YBI:E0K](X&#9ES5;58=:7;4A M7MAW7M1Q.=77*SV;E2@;J7=^(-R MF]A=R5LYV/[(ON9FE2<<:>B5?[W/0U-5'6KBP/%]G+BQ%3F&8Y$ 5"PW35*S M,>X8J&NJ]M2;#);\U%4!38IM@FKU S/C'>V+NNR"Z>1(19KFM(H+K&CC%""X MZ#XJKH#3;17PIIQ_N$I36O>^[JO[[YG3X04>>H:IT6HK:1(+G-[WG= M:LFB3/; 39&7N[]^(%56G86Q26.*HXCYI-@WTM2)_#2D(!@;99SI/K7OAR-? MH#TS]>;=94?.1:G[.H))@/?0.3!UH$;=\)R":M6HRD0HXVO9_(5J=?:R'LH) MZ(OB5IL6,9VCSFYYFN;HX5/7:GDF#M.(XC@)DC0FD4LC5W5\-\&3;J?:#A78 M< !!1#:HVG&!2N$6O&9_V^)B]T.1344]_9#$C9/SYR!*:W<67F[OK[@#1FH-Z1/*1.=0Q,&!F MW(A*IAV"(FW K!^B"*5#T@6DE1M$-[+NTT#-W(_I9SJ&::/$H,V)AF0>AW.VQ^MWN,"/^> M,\H;\J-NQ6#;4=[E0W+M:XTIR2.^-H-F+Q07CDFH175HST$*+_/ MS ]QE0P. P$L,2-8:#*^;/7X/*IS8ODX=&T36QX)S)1:3N2!\J=GJ2P2**R+ M_ FSMU\0J"][2 , MN^XF$+#P.B':W[_I ZP.(?!VA4T>''[E8]L^^,A>[?D%&N'0]B-L!8YEI"$- MS=01A1[J+JS9['>D$*<\1"&:]8K* 4(7.,2X%)W2TT&(X0N?8 M[P((G?WY^]5H?1ZJ*6=';CYN+,8T]BC;9L,T(:":HR,?JBVJV9Y2LJ_VF@E' >WTI8*3P'A_I7>K!>LK\B6K"/K]//;X6M>JH M#>L3D437CN-R2Y-^.O8T:^&9"2:):V.7^#&EB>=X8L/C)BEI=KHM7?12PQRA MDOY%R@0*<(@0Q/$=*=JW_\_>H>?;Y>?;C^?/UX??4P[S)_KQY IGZF MT#+)^FZ _N>.J,*(>THN33?Z>S+O>J5_*NS4G7[O>7AUW(K':;^5)-_P9O=] MS"Q:&3?P^F(G?$0J#HI8

A,QT=M'F;V51L3UFQ]C_ M^_\$EFG]?QOR [WN&$%9CEXYCS(C^Y1\);&CX&)*E]J/NMS5E9\[_B[0CD.T MYQ!Q^T4UCZAALGYESZ:Z//5*5Z@=XM#S$^SXE+B1$:2F&<&FZ0G1U5W9PB=K M'MC@0!P[1E#-R;XYG/$"':DGIE@Q_Z=!73 7IT93$D/V0'(K&[,G1G7A07L@ M5?1'[<%>EW,G#QGS9FD6C(/L4!25S,?$B,C81: M3APG-') $,=B9#4[DPX3Z, %VK$!J[<1R;I@>[AUYR_$M[6RLW M_V1()>.FKD!0F$U#992XE1Z9;2)U+_T.TTXFA.G?3:N<;_(0/]-DNZ:WZ6]% MD?R5K==G 0YI/6PI\'#L1J85)*9+8 "' W1T;[."YJ;Q.<>!Q^*7WW_;5> @SUU'M1LYW=D3?T MO>*GN[0H7^K6IP-&R06J>1&_D>Z+/6YELR6&V=8981LK0\H1E@:EDKJ)[J^V MV!WTH"#=V^?AAR3WM@U;XYZ^LN_X3"IZ5Q9/)7FYIR\DRWFA\W;S7)0\KW9X MIFFQ-T^W/]_P,/$,$X=>:! C]X?DC*$#5=2RQI,W+7/HP%WW M09F)/3.^B.!&NXB>@2=;#N4EK&+U, _S=:)J4Y=G9-E]?[;">J'!_!5EAQ=] MW)9-30%H:M'N+ISO%9T<2.K)H+^!TD" O&\SBSPTIFA1/8CC1J20SIA+M MEUIX'-&I"/TY1+TGYAYT:W_\@9E8TH7,ZWRK#V^'1]I6[[HP[IY6FS*+-S2I M[?EKGFVJ/]B_T81/1/GQ2OF/'@O^3R?QZVDX$;)((J8&=GS3L\,@C 5KV'X& M870')-N7%U*^\1/[_<-7Q$R)R12/WWK_?!\D/=!UN94"T4CXQV8J$F0JT%NT"-:,VTJ%8X#JG!_UG+(>QG^E+*4ROO(,H[ MY6_>[Z,-)XG>D2?9XS39U(PQWCGA!IVXXJ/ -F]#74V.&^+(B"CVB&=9AAN' MI@]JY!6BJOV0W/+ =Z4N%_\+-7R(M #-T*GHV5>QIH!N7X62) ZW *&5G6-% M:"Y\9 6HH7\ZA;PL/?^3]_%7O$KMNJJV/&UZFWXN\B<^9Y07GIP&R881X\@W M4YP&- K\U(WL( #._YP@J3LKWC+05'-F+0O&?@@HX,_Q3]$UX90>_S%[? M/1]'O5 81AQ9A8?HH-WW1BFSJ!8X:B91VGBVLV^)HJ-(3&ZI1N#ST![*K?YIGS[=KGJ1=J6 M@4GBF.ROINV&U+<]*Q9KC-PMJ=D\+ES7?X)Q0&_: M*:\CO^CMP\TO>_N7PR]\9ZF%VLA.63_T@O5^(MMFD-*RI,D>0+O3X=_[92<. M#E,[QH%/B&\[[+<_2K]M^.0!PC!C(#/8DQ6\'Z@E-2U[FLZ0HVJ.])4=@=,BZ>L)6"$U,)] --"]XO_!=Z!6795;KY= M%GE5K+.DSF[5&'*K'UG?GIT41Z&38,_V0C]Q#9O:0IO7, G=FUF7: .XB/[D M= 4S0".Z&;=;-1(#-T"XL,*&.BW/F'FRMSNFR?YV,,N1A1Z*BFTZ_YF]7A9)K[C7B"),F,%AXB>^YX0I20SA(]8P&*(4X<6TI]5U/093(WX,&N4E5RBO'Y,L!E5]F>77;C8?DRT?LW] MZ-.RQGE/GS*>7VQ/-U,:1S4):YEN,U&ET MD-2U<1!0$[/3IT5)&I'4 MU(J&%+LQDWB"!9?HP(LAO:R"% T!$\B!(\$.B7 M$3O:+J]OF#,9P039\7B*"=)R^3ZH()**TXL+ F7J9T &D52D(#:([.IS1F%^ M9DZCIE+PWM\MHWG[2IO"S>H#38N2[O,*M+KZP1P]HY'EI'RKSSI\ !=[DZF6 M47JZSIG?HE6OF,2U/!Q::<(B(H/8H6/YD44A63^-O&I.&E[?7-Y^N4(?KC[= MWE^A]F^/J_^ PNWJ_%IB3ODG^08P3]U.[/R%L_UKZXGWG*,#ZRBJ>>],^*3M M1+\#MVC'KNI)GEIUJG3RIQY.WV%2J%:5GY\LJIP 'WB] MP$VQ627%:PU*!VQ>%5Y0?5S71"1;]CJ':44M:^*]*^): M&_>JVA0&]8]@72E&=)%2A%3#C#B5Q7IIP()WVVS@+\O 0#=M';?I*%3,YS.# MVYK[(8[^9(8V]@V'4L>,:1 4)]AQ#7[E5V'RVV*)D&//D-'KDDI>]S%Z%8A MS-/\?-J#0#?KTZ(D4K-B;0)AFN74,8[*#%QS01!F.6F/,9+X16KIO\F^_?+E^_')U M\_B 5C7MS>/US6]7-Y?@839C"A,['2M2 \RG=HC6 =L1676G5 '9%)TR MQR@M>DH4$/GTE"?RBN1HW7.SK/EYL,D,=MI FB'S AUUF^UYW=^%H#\/[**KG$5&389$Y4Q'%SE!*0[X5YIN7F[6_/8+4]XF]TK)UQ?O/9@CTF 21S$ MF!J)$P5F&-BQ![GR&">G^=:BN4M^;5FH8PNZHP_N>AO3FICW4Z<+F$O;T;U M->6+!K]@1_QB=VG OGMRW;-)WF@C_2UI.QWD/_Z\0D1KVO:_)&_NGHIRDWV M/XKP9&#:4=<=-T9LZ8:, M; .'H>]AVXY"SXJIY5 ;EIX;H*1Y(]D3JT\]:JE1A"D:0@""#U#0[.MWC[^?G6/5@\/5X_ 2[-S^A"SS9E2PJRR)H8::EJ@ MS$:D462)YR@L:H,C(IY:W]BC\)S*)\9QD=-[&A??:?G&]N7'@D,EYA6]3:_R MM&#?O 98?-F(YE@ 2VHVO983M&.E/FQM"M1RPV](.OQ, LS/4MYT=D:3WH!; MK%J5@5(W$@J02N5 Z"R6VI$0OIOJD7D=[BVN?M!XNV%A_"79T*>B?*MA&03] MPMF7=0?*.YIH1_1?Q M1OF&@Y/="/S6"X*3W2P,3G9S^OM]YB?S:Z?NLZ?GS6WZM:)U?-J]C>W5K4*7<<)A++]0+JZ(\SCFIR:$5RD^"N? \5YN1"[DYZE6M%\C7*% M0;,W:G0UJR!)0'(-Y49C5-^MF$A %6.E0B*O2^+IRPX J/^'P_OSDN^ZG;LW ML"[UF-\)?1:11'X:Q0:Q8RJ$':.#./_X!9M[ .Q6Q=AV9@EM_A8'\IKVF@$51819Y MF.RB?@&JC%,O 7Y?+MNY^GIZ_C(=I^F(\U(_H<1G_Q<)M<,>EM1LYZNO#X_W M*V;ML(PG$U4LXPD3 &:.T[R#LYX'=F=G/=E2BV8]#ZR?9CT[/YD[-/<3R7M5"RN9D%W5DU,P;4H#B*7,ANQW.&Q;:>A&\JW4UFQS-B!^4]UZAF6W8*KHHO*)B8>*_O M LQ,M&S6'V3_>2XD/LE"HV<5:E/Y+%D5O+W3<%B%:AV>]JJ2B"Q.YW=V>"_* MMQO:G]*:>#AT;!,;;A($AAV&1@ ZO'07U^Q)O] R?F;&F54492U9<-_]D3+$ MO)JLB#"GM*=R@1@=E0B1?>Z503IVEEX8@[$O5!\T\ M]XMRB/./Q0O)\M.@R"8F)L0/<&K[5NJE*4E-7^G%C023NH\B=7Z?4T9_-@2A M4Y1U?!A%ES":U0T\. $TK?XB988JEKI0D6'QY[I8F:%D\ 7+'%KPJLR;(K^C MQ0TM5M^?.$.K>+,EZ_7;'Q6AHJ^,K^D;H=# MW=9RGT9%-(AQZ$8F#BS+\#W?MBP7U \U0FO9TKD=\5VG@7RIW*G*!.]-U2@" M>'$JJ8-9)7 #TFDH>SNE]&ZE;@,BCY6W#;TB:=*[+,?'K(K7!4]J5(/Y7].G M.$K#%">1;]J^GQ G%*H(%Z*V7#ZWS=[ ,:W&M25HSZIT +3H@_@=PHIQ;D R MJK+K45K+6K:(V#W;%GI)V4E2\IWJ[# @KN*/=&N:.\_*VH&K%7*X.=<&\KZI?1/A<.*#H MJB:_B9)==K8;4!F]Z6W0]R6SUMO7UW4=G9#U):F>/ZV+OZYYI^Q+D\X9J&?S M^6G+=4.<&F[J4HN&Q*>@1+087"?;-0Y0HFD]6K#.98N@P@S@'B+* . M#UIJWH!RJTH&"U)=-K\+4T4O90M\'9Z%Y0DA/IA9,-O:/J[9RNN\H?"PZ:X8 MTPE1"0E@1C?)/"B7><*N5,YRM\9BN-VH4Q@ MF*5 9!4V&B%9QK80>#N#$WM8LK&"5E51MK,J\Z&5:/Q0>.Z4*S[S0YM@,9NM3ZA+5%KP! RBZJ@8,4;++-F ME=%KP("^+UO;N)]XR^\F>^6-L8^)02UL.#1UC- ($P=T?7BROF9/T0Z/WG!R MZ)71NT#Y2"V@D$;$S'Z&G##K/LS'KF_S]R,P[FFZS1,-5CT@F=*IUH?5WV$2 M=4^T\].C^X\IGF+SX:VN^SD37KO4QI%#7&R[J96R?Z)F;$*L4("F[G/F\2"7 M4X#>IK .$(-#M"EFP8IU!-RS^7BTS]QP=T@WEVM257V/N>>G2DX:&,>9^MFJ!'[Q\N2)MFFNJ<5922> MF;\@1NP&/-+W;>Q;KH&#) RQ$[J19:?,85CAMYP^D7HHM;#;D.-&R$K"QDIZ M/ E;#-\ XX8PPFA'N_8K"?U.UX7$J"Q)[8OY%XW*E$.%W/&#.B$%9PD=\W11 M_Z!AZV*OZ O4 O6K\TWS%*3(74DRL:@'FZ>H4Z>'179C%E*D"/_W]UW]8<.8Z<^^Y?P8=S MXLQ$"&O>+W:$(]1J]5B[W9(L:<:>F(<)D EVB66EJ0TH_WU!DA6%:MX0X( MU6=BMW4#D1=6)H!$YI?W=\:!%:/A13RZ+J2<^="[:KT +\,$5**ALQ=$:*GH MOA"!U4+_$'&[]P*@YV#F36CV^V5>9=4[\QA7A"T/=:=U3N#Z=:BGEQ^D"+NN MA^R4I%Y,$P];0B>;64J:K;ZA72^-Q]2-AKR8Q<_K:]K4E6H!N'V058"P20L+ M-V'+;([&EMDW!UN>GWD5(Q86<&>]X@](GCZ>7S;;=]Z,J7ACOGNXBHF1_D1S MFF;5%R9)]R\C)0A)Z",GAC&(,4AEX?&8K9'M8Y!& MW+ #/(2H>0F"AY+5%0O<20QA6Q[*Z,YVA1#-(>73C+[A1Q*EZE%U1%'#U+I' M%J6*[!UAU,XNYSSO>'NZU_K@])C7S<]OMYLL>1^JXJCO5CC2, [- !$2!ZYI MF832&!+5G:6H>0_4TCM[^J-? M'CUPL64'N_R59^ZT^1\JFUTH49ZBA689+ZLN0DK4=KI J9E4.O.GX$E%GVGS M]2H_3VKXRY(=M#A\6GVK&+-_D)M&-@ILFJ (APFR79-2ZCE)XIF[6T4Q?SA+ M4^+N$.;Q=O1X'PM.$)P;-*,S,0>F1@^R^4,U2>.''?$?C8Q#A+1ZN9W1BTS^ MD)BLZC**9NBMG6,D)OY UI'@@[(Q>G[A5[QLFP6F3EZ^:.!O+[:D%\7#"44X M)2YRB&>2R+7CD)JP2/TDO77B]4)"+Z0M(NB.M/S[]R=%](V'Z,7^PQ^/W[^>-C=5D4/ )VO:U^I=5GR@SJ M.9T^UH>HU\QQ@S&F7%@3?PZ7DA7TR:N0TTP M&Y?0D(;;>8@.I&[GA0BL=CL/$;=[.P]Z#F[\WZIB\\#F*V_2AX*<%P78Y,=G MT&SHW]@GN.#([S5UCCW^4&#"3\F=&R%QTY[0Q+Q!JU$"S(R%Y-=@N/.R2IGK MQ+2K&>F\:%W3%!@MA",*$]T6:-R9I:6#V MLQ-$(;K+*/>R@)>=F=:$M^P+< )F.3 _E'_I:SRQ\_5%PZS=9->_KUZ/_^C M(.5/15Z1\YRP/Y.K_.*M(+\6,', 3ZS99'8--S_S/==Q_Y*V_U4-\UL:/S&_ MS4/ /"+,'V+?9CG;F[U1WB[C5XH%\\CDM#MOF5H5"[->A3I5[ "DE23E).#4 M5G,DTHKH.AOY2>0ZD%W=GT:Z7"M <>#ZB,8.(4$:Q:$KU-+C,*5F_W)UA3SEVB[,^8)9T;+.;_/V5M&:$Y*GD!S:M$D#5%HA1YR4S^DJ>4Y$4XE M:N6/B$BDL4B4P->)8V1'UR TV3#M >&OCI4C9J9P6:6L.Y5S6U0;%.+6QXD"PP';/4BVU9G1J5;7DH2G&"/)\X[#AA!TEB_E[Q)4C, MFO8S@_8.^_F!J^*F3HA*&#G@8G=0@)CA2(D%,YH6ZXT348GL=L*W,NBVW;PK M8[.=B-,'7SL=(&D@..^A,B:VBV)JLGUD$I' =9TX-H4:W'.$+U/>O=OT @J\WN'9BG;M NA_0EO M>*>D^R=*JPZ,]AW=\,U.M:TM;+S-?5V"04.*XB!)D>FZV&'_N:$G!)^MG#/- MYK:,5=$PL.JW-1=-_L!W -UG+N$2TL)>\QLAV^2U?KP^*,S0,=L["=4$5[K:T*2GPPV)+@*2<=7DB9+7#;U)]]W2+UZ+ M@GTWNK0UFT 2HI#:(4HRDD/* M-4QEX/"AJ$(% XH:U 0,,78TM.>!G<\:+B"+!SS&"!1>5=11E.RZ<4B@,GJ1 M2>CS\EC_E![#?H\W O7863*R/8J(ZT1)D% [B&!GR4ERND^9-?$>4#TX!C.I M,=' C"H]0*,UPRK0U ]43$R%N/P3Q%9'XY\7? B#7^ I24O?YH\\FY@WKON& MJ[9QW1U]:4'^;]+;(LN3[ 5OKO)K1O3A#[IYH]^V>?740P@G QEL: 'H4CB7.^ZJ:69T;+&MMRU*F/ M-[G"2TPE*E#E;1;QLJXS4J&VGJ]2,JF\*ZM:VAP(O9=AUO3%Q!A%IITR1V6[ MH>?YIAL+51!/D]&]2>'V5!WLJ>E4()53-J(F<7>S3/AE?D1,;BD7,BZ60M\P M0&1UHQ\7=,B:)T;+F>GY&\XV_+#R95OE$@[GJMP$6NF_ 6;;;M.PG$]0Y2T>Q":QI M9.1!98CYOL4BPGS8CASODF+4!,^,:8GAV,13$JF"&AZDL2YR\)28/2#@R<&2 M_=K: Q3S!NPT]3 %FWS"A2S845*D6LUOFLUR[8@QH$ZUTQ#W[B? MU R\4YNPL*H:MFW:Q)^4V2>"5Q[S I[ZOIEO M0/_@%]&]2U_71V%$,+),&D5QXA./'9% ?D&0LG;GL"=IX!U-F%.05*%E8A2' M 44!C1,;$^QX80C9ZJA4X * @+WZ]A2!YT=1_8EY5@U:@;G70XLYH\O"F3&@ M*74^%BBV(DRB.L8WB@-AVXN+0 M25U(S<'1[" '(%MWD+1)(+BF# P@'>E", D*R',F!LR^QP7A5&5(?Y5146. MYEXWJC$D5B\J,3@(9D=E4?U^QXL;3YI,UZ<6$ODHMMGNA,8T-M,TM7TJU(KM M:%;=^68\<;2LLH193[>V'=(Z^E@+TY8C+1O,8B3%$C:@03&F#(<]T#$:]M/! M8([G6L50!MG?&>5%\S7)Z5='GN<_(],/Z/C0MS2$4 MP-+XC3-@U!PH@CF:%U$*SVABVM6 B^9%ZR(4"8Q>GA'$"\^']SDF3E'D6#Y* M_3"PG(":V 4!M0R36>T:G=37R?3/9/-:?VQWFZ 7'C6'HC:,J$QL.[1<$3"# M/;U2O]SK8)<-?+A(J9Q_R MO#[UX$V+LW>:J^<0% 6.@QS'PB'VTM@WA0QXDHIF^ZW)&D=T 55.HZJ9-E1E M L/L=$#6>%5_IFFE'DYP@8UI\F1>*MM MFP$*_!0S7^6QS482$>1$%B%I0'%L@?**%?.GVOL;;T@BWZC4:/AM&[@RWDUCID],QIV^3O9,5R/;5@>"A"?\5OW1&GD29-:55W3 M*^9NW0M^/:KMI09H(B,9R>;Q<9[8>1*):S:(-$0X)A19"4E=&Q/;H4*X!X.S M:W:9-:TV.Q@0A!M6A& 86U8\8!A;6#)X('M( E6![*.YUPUD#XG5"V0/#H*9 M$6^2]+G=UI[G^2O>W%$>/SBUI#2.41C9-B(Q=JCGXL"SA6+:8P0T&]..I-'0 M-!JBX@W)!G4R;50J)(79%5!(4'>Q*4FDVHD-3KA:_[ I<;H-PR;'2?0DP<^4 M7/Y)DU>^8-ZD:9:PS_*7'-PK:'8BS?94TS?V#!@[#LZ,+]MME6\KP3V]F%+F MKPF4Z@-F=?.JT- Z2%A>N7XIL[.OUT-%5-"COBK"#\D ,?-@3($GTE+#2Z/X%FPF=HD15%J6R@(4HHB&GLH2<+0C%W'Q#$H>BI( M5WO2#:-A%(>D=\P#*5GU+@OM-*U$L2" !M7 _&A-I^G"V-!O*@!60G02$EHY MH-,TU0_":WAZ)CORI*L%[%P4A]% M(0F0YP>^$_M!9'I"S:?$26KV%CL&#-IR /,2 BH3U(HQ#7ZBF98R 9@-O23;E]0U5-UM7=B2X MICT,$RMF^W4W39"/TR# 3A@EQ 'T@I%F1.@SO+A?S)YV&Q'904/5'_!MG>^3 M[H?@/7]G1DX%[R#DWX1 \$2;8J6L3$"(1;=2Y8(M6I0+"[\L4[N7Y^?BW?>1JRL\H=X\V5; MG+]LX@VTN3AX8MT)%X^/1;T$=!*C;MEX?J.Z;XG=/6U\HCG;QU8U$.-Y&-,4$E*:I:C9XS5$F5TTA5<2S5WG=2864U*J M"6"XF9'FOJ4F?F:T.CG0/S,:#HS?VJ]: M#""E 49IJGMVJ425C\TR"3^(,2 M.Q^>4%=>;+8E?=A^RU\RWA^E7C>$MSBC,^C>R]2$C9HR7P(?,MYT>&M\N[Z] M,@YM7@1#R#/*$-AG*-$#<$,AJ(+V7DG5%F!64KFU?GS:]1;U6=&.5N_YT;++ M]!YMJE<&6 >;? # M< JWV[.2*%LG3^=?>5T<$:^_#HX-U %I??CIU/A2$J P,BV$?8K3U+'3U";J MT*H//^E>0(^@D(X M2BC')@!@,.E0*QR>Z:/5*N8>=2@+YC4%H+K7PM3NB[L*7':'['>$A-U7!@SD M>N!YB2NY>YIGV^)Z6]'R@;T,VE9E?GZEW_#[9?;X5%&:/_S!?O7>_'M/WVC> MK O#T E)D*+0CR*$/>('Q*<13<4[ B_G1[,W=_YBFN;_-1H^C9I1@[QR]/IW M0[P)DBK=3SNA#] HS#?)\;;;^LD /BC0.>#F;EW=R]WC+7L'BF[RU"EJ\EY/ M 9GU;OG4Z>3HSD_AM/K@,*ZW.=O&O;)A;/F[_)/?M>QP+]((.1;U>4Y6B**$ MK3N1Y00XM4,[=3U )LA2?M9)"%D;[F)0\V)[7:V*U Q@<<27T3+V02 54SI: M$8UBD(WO#G9B2EDR^!*3\\DYO..*EZ'&7($9H"AR3>;/3"^BQ,7$!W6'Z9/0 MO T^:89[5K=X@GFC ;6(^9EEPL(\"$Q.L#L8%T61H0\06-6$QP4\-TPVS?DI:\%YPH3QD3OUA_D/ZR8XG@S-EO)5_ MJ;-3A_E,RZ3(7NHPT6D) MH8E1F-H$Q1BG26JZEDM ?9:A#&A>D$YY '8?@VI3;)^H4T!$Q9\"!E._&'H1>]K7A7OO__TJ=^G M(D$X]7R46I;M)I&96E@H[G284K.-_WQ]]7#YV?C;U?5/GV^^B5[T[>6=NQ^5 MD0)FB((" *[+3GF>L*%V<&-'[0\'6^I,M=*MUBGKAXNIWE_D]N6?V;+[AGF( M]V*;UQM]CF+Z>?N,L[S73,OQ4(B#$%EN;*?8#!S/ 4'X3A'3O?3M29\9'*+. M^*TA"T3VG527V"9;E1* R]N>JK$C.Z\"\'991#9%6^-)4JMN@T6$/MWR"CTC M"\^34#9WO-E588SN:6.VCH5.8"'3\TV?>)[I64) PO.D])^>=X29.8O6G@MH M2,R$U<@-/A&W-/6>>.=E4P:V,TIH99"=.8'[X#JS3\ O8"[_7KV?_U&0DAUY M2U@Q]\"CFNWO\N^O=12F*?,Y'-(!-4U#\L[?BRP4%69RHU(J+EV>$$KJ#F-H MOM6N*B:$Z=Y(3 V36_KAZO+>.+_^;%S^Q\]7#[\"^PW. M:4YL552I#YBA=BC78"H-/87=!@4E4]5W<([*>AW9)$Z9 MDRPS>'[9;-\IK9?JF_JF5?P<.CN)[A-I2[&"T8G7%>%+P @G]_UNI!0^W_K+"J\NY'Z:R;6#\G;B]S?O8!R:8- M%:[J=_OIM"B)B]SHI"#TD 6M%2-8TRG9- M^^V A 3.K9^=2+-U'N@;C($?WG[LP#H!@*UFU3$?$E:J"9BI3BE!0Q*\L*1R M,%>SLZ^'=B4JZ!'HE?!#DAG,[-7SS(&A;@=Q$+$#KQ,@US.)E:9>3%.A;@=# MDVNV7$ZJ38&06%B/M""VCLK*!K-%8;'@.< #_*O*[^U.O6[N[H!0O;S7.3]8;H'\.2\HWF3_H.0G9K!?MV5YDU_E;[3-.#GY%/:RTDT4 M6E&"/-/S+3L)21" KCI!U'6?+'<@;G5W 0[C5M_I_SO=D!I"&%<W=Z/ ' M6UUAJA9;.G3N'$H. M\4[]VDAX&GLY2?WOGQ M8M2O-??(H8GB,(A1&*:FZY+8,U,LUVIX12ETQ\7;CBJ\;0*_7&BO?XZP&EH8 MGMIQWM&F9PO?G+=]6X .\V,^"X)!^N_]#2N^T*L[9L3O=:>=E;HR?X!BE?=X M7E.&#^H8_0&O:;S_]$-!K49N1=@[-*P$GL;")R$Y8@6L617(" M;U@$&XFEG<4.1%:74^1W<0?VU7D1+S9OB*GXV7S&D[S M@Z_R9/-*LOSQ=EO44!!5563Q:U4;__::2<BNWKX],#S7^EN."YIQ>X*-YYY]MGCDS0.\BG"8I,=IHG MF'B)EUANZ(+@6A7SI]D!?WYE1V_.BY'R@OMWS@/,':M^'V+^^ .U#'/(O18M MG'-4;=&.]S.#L<",Z!]U9(3? #7O8]^AL XN7Q249)7!(VEG1N?1YC#"'N7Q MDWLFSX8>XLZ?V5]VTW&Y#<^H&D48EJG.NVMZ%XK'M3T5>D:O\XJT@OQ8WKU5)&*6<_)R_E16!%:#+SJ_9 M#7,](LI,^ O.BD,CZ^.R[I\*G+>]JFN\2_9M;=75$ZX,7%"#LUXQ1\#W<]P? M_%Q'W"D1/WE+JW_^5+Z&YF&N6:_2%5?>+U6?U-E?FNAJ<8&E:NG&#!;/)1E/ M& PB=D*.G][[ 4G^X=QMQ=FVNL&8NZF>:/'PA/.FBJ/\LBU2FK'/XE7>8%;V M^GG9 8I-]@\U:6PG892&+MZU61$,-ZS'O9 G.&[* O/">XK @,2*+U P6O&= MO93%%TS'\.X'.?C]TN!%%!?F;.?*._(8M4#<>^=MQ1G;3^^%XEZ^$4MA[&/] M=Z$J,+(BY^M&3=9_);V0R@>P( N'OGVA155?9U5LY>,,O'#*X^B+[).$,"$6 MQQ\U?9N0-,*@&+8 3 FC:OB6D; M7BH?S%@/HJF0#- D=8&$]0M=&R,[#ZA MA?RH;XOJS4O9%G?\@Y)3QQ!A!T5!$K*#:.0$-K&], !-$^3T[X[V$'.E)SZ MF5'6] V\9P"Z)YC4G>AV0)5&8,[EH(S[1AD-:>-\7AD2>P$1&95M R:)K;P# M$!&\O_@+/;6P4++?:/-STV63G4:.P47^R)FM/64O?#/RF>= T9ST*I2CT$8A M=6SV8XI-WW?CQ \E>O^JXD\B["31"WB/"E1[%&.[8\5XX>FS/US>W]S^*%F: MN?3]B+F?5=6MN6/PGN$SXQ2M:?]>ZK3F'=?U)>ZKRF;"JM6INMIT*5L?4YVJ M2)FCU:RJYI=K O/E[M27>GZ"8B<(D4E3-\$!]9FK@C2!^7*G^]1U=WY]<0EK M_L+DG#M=R7 //%--,PYN^G+@=7'3%S;5JDU?#JR?-GWI_&5QBPB>9O#*-C-' M.5OU-5;@FRBTO02%?AI&?F E/@'E; U2T?S!/VH,D2]H#-'1B]A*O5A:F*&< M=L X,UJ26CI!]"52WP2B0^.C^C_TQ9QH_3 P>&FIY7A8D5/LW3.S?[!KQ\AV MW93:7AJ$8LL0E/!*MP*GUP%,P6V%&Q3\3U2A8I:M0TW08,#1OC-D/ZC"3DP9XT5Q@L^KB!36>5=]6&X?X\*@H)V'-%MFIP-WM3U*)?H7"/YG5\II4UHD(,R QF53!BXX*HTD M=F=WIA5Q.@<$.,;D'!H@M\#Q,HZ;E.,!S?4U-,T817X8(M\Q*4T<.[$CT#78 M."G-1O6-%LD37YE*6I>M *N&)E0DMDRI$1QF;#6BQ38U?JIS!.J*&UJ\98GF M/H?SHBI:PR8(K;J4S0M\NJ()/"'93F87FKW%[W6;FBRG5Q5][@'8IU:$,,4! MLD,KL$B:) DU08UDQBAI-N0]7:,E;/S&21LU;6C/X5%MB1FU$AW ;%I2?'@+ MF3G15#6/&:6S;MN8.7%[#6-F'Y!$2+UXA=<1MAVE\Z,HX&9&='@R/U=R];JAEQIYU7A0/Q7->D2\;_"@:M!E^ M6O<]*2-J<*K(.JK\>J#% MD2E7"_A,B]2-_,R,E B(/CY6ET51!Y.>*^&(Z-%3ND.BCX]%G:IH,)+;G&Y? MRY,:R^ETMCF9!>*CTN(" Z0+)86%20>%DHN3'D^U7J!T4(2C2.GP"+D]XA?F MS1A/=???'5!46^YXD^]ZAKZ?!EMB[*$HB-@_461::1*X=NA#-HUB9#4;XEF^T=I("-M>#,VG#E@6%50G6);3/5*@IEN2W_7?WN/4+6 3A!3+-=[DGS0"0G;M3419!2X7H3,U]5 MVH#9\@)%R+< GI!0=0?@(5(?TP!X0NC1_K]3ST@:.*T!7'^B.7/*F_.FYLV6R2 MT8=M0;/'G&U*GWB(E?W((9:&H4R2.$6QA4UD$9M0TP\)DBM6ZX14#H M7I!%Y!G9T,H;VU-NB_>O QEOC5%C%V''(B@*XB"($S/P/="^KD]"]YZMK6_A MQY<]\07I;@,Z$HV^+)$<&H !"2H151F315E@I4=@Y=C*F(#]\,KH2(EVU@4Y M+XH#%OOYXV/=;Q9PI3@QQ6KWB_L>N8"6UA.23]N70J%A1O90X#JH>=0 \<"# M,: /I1>/ D++];R>F'>]KM?SPAWUO188+K+KVNF#DW=^NAF,<*N M92),/3<,(LO')BBI;922[LTN1\)_VR'AXYH+XYEB3IKP"[>"J[7@'_48EQGP MR#"N/[%E4XE68(;=D#SKM@@XD%6WB,Y*IF@M':>SZI(Z*^[IRCK_@/PNMRF? M&P]BUO<7EFTAG'@$^6%@^AZ-3 ^#DL1'*>G>\SYMBPKQO#'Y-O3C6A+?[BZ6 M';[K;4BN$S6<%5'A9GB8SNI[XDEQA[;&TP\L!"%L80VK][H^]\1Z'8I>ZO;"]3DBP1*>R%Z$G4?I=*#S5>*<'E,?8& MY5*-F'=,Y&/P[P8%'46S&QZ]/-%OG_[3)@25GU\I;ZK$>XOUZBI3%X5ID*(T MLFS7([YK$E#B@"AAS<9LFXXEG\LWJ3'!J+$&/0 CR,?Y?'LFSCAT04S;#*&Z MNQ9G1$]*GXCH&I+Z)LE^6%J?B#*F$ON$GH>'OKXU!TY(;_O.(YH-&=;*OBO* M?.Q*4@J8&;9$%/:>'V!;*MK4G6>UZ-( \]UHTM"?%VY5#Z?7T>-F:M4!I #Y M?HHM.P@MQQ3JFR%";+5M*S3S95)#P*WJ0KFE-ZP'NL9OFDZ:\Q*JWKH.D?J8 M#>R$T*/;V*EG)%K>?,OR[/GU^?J5W[+>I)_Q>WF3-N#.-4+>]C]>\29+W[]L MBSM:945]&\"!]$Z-G/*,$M_%R+4#+_ =VP],2[@YCC0;FLV_Y.;_C^WK!7=[ WC3R+V/:GZRG8N#BW6JWX&*O".<%@S8KN_Y?+"O/%>U):@!FCS:9%470L.$UGW3G!2 MT-Z%X/1H>,R!3?1+>4L+YL*?>7SCL&G\*IC<)3B+OD\C(VZ\E4:'_-%IY*O* M["^@L%+A )'Y5PL3 (3MA@\@CTD&UG>7XFVDHH[#[7_Y[QDMV)1/[\/89W52 MNTLQ"F,OL#V2!,!K;1#U-9)76@#I+CM'V1M[EB1ATV#J%@S-ZU(B,#X_I"5> MCW-]_HL&Z#4IJ56%YD&TUXW/RZBE%Z27FD3. =4-R*^9<+A\:F(N;;$.8YEJI#R$I+B@]W#K&B*7,$XG57-?E;<4Q.??T#.G+_2LJ1TC\, MN;!O6LXY 8I2VT&8NI[I4&(2:D.V%% &OKN+>[ &Q6Q=IUY@+J#AI O6L?J5 MOJPR%#D-,/E5?8FL)$PS#FY?>>!UWZH))I M<=*:361'O+X>[Y 7;+XCH4JQ]52/@F!6>."!7RJ-:4H+P Y)B2(:F0$IP.,[ZM%BJD-9'J*R+M3XM:@]M?6:XQ*W2VTL# MZB^8QKH;K]G")F^*Q)-;]]()7(Q)"*;T]DM5MX(A8>1NMW:3K'>%=<+VT3W5 MZ=^6Y+A^W9;E%T;Z8INS<^,K.SJV9\AM7GZB'(!HGYM'R\_LF[+*DM/%RZ0$ M83.P$/78VI6F#DTM%YX"*\6+[@6N)2.3'2NG6[$%;R6-P>QZ%V'F;/UH\$^T M<>#,.+!FQ#5O1C?]^,R85;5D_NTB)2E-SY7CY .R=Q>I;#BY=]F4DJE;A&2< M -[PX.95WN(8#P.?A0D[Q2>ICZ+4]4P[,"VV*0=E<$U1TYW(M:==QW%1EN] MFX$I79,:$W--RO0 R8DHZJ,KTE:ZR9^B8C=R_\2>@AFX81FOU\R M1U*]?\DVM+C %7W<%N^G-NT3'X6>9:&8D#2EU#-#L9R9D?DU6W%#T:A)&CN: M8@8\II!IDU4@)LQ(81(*F^6,'!.;?O9D8X/LFX/IC>D+('GCTU%@YGW5'7]H+[IMT/ST/$)YN M!ZS$1;&;$N2&-K4M/TX<$DIDM8T2%/J<+LYJ.Y#G-U'EP;/%VZ+8_L&.5D!K M'5>@F,DNTX=+I M>.Z/Z28\!>@T/$@6DO@J)Q!DEJ.'--L%#)OE6)QI.U@D"?N2)"G8VRKKKY1TQ MB5<7%2UOT-0.16]#7SS-AQVC1;:GD],W8O MJ,.NRJP3M0I4EJ:BB*V5\UK4*K.?"*-X?LGL65P^L?GYE\N_OV9O>,,/!>?5 M!2Z*=[9$UL5LI^XT"@*>,XZ1[WD^3DQJF0XHD"A$5;.OK)LKM-A^M1 M6@B(3CO,!JDRPYO;;5E?%E[^63'7E<4;]E39"^2YE*#8]#%*L1?XQ(NP2T @ MT:H8T^Q;#E5;=8?Y[GX,6+RJZD6(.:"/4"_,1TW5P[5LGAE'373WK!H[7HW? M#MP:E_GK)EHH,W!=)2@L*%$V))!4O&IQP MM;#1E#C=Z-'D. GDT N<8X+KPOU]NB V*6':\:.$%^PX#HI]]F- 3-<+W8B8 MIM#997AZ[8<43L^H"0) )?M:F+:IY;)!3QH'L8!-7D?D X!A+I)3#N12Z#7" M8"I'I9B$G^P_M1ZLY"C'1W"1XZ-D$Z-P03^Q=9UP-\Y6Z_K-=0+_G]X/0]J" M^W/>XO5ZF]^\U(L\.V55[X>BI?+FM2HK=DYF.X8&U;)%X8D(LDC*/(L?12BV M+1N9:1"Z84+O[^V%P]SY]_6N)7*]UE.^LMRQ%5A> M.1=MO9?0SVU;D?;2+HHE3],YSTE#LM.#M8]R40?K8]-!H>^&*#(3FCA.2&,/ M%*P7)ZUY2;GJ9KG6A=P\6-VZBTXG8 $HAZ4Z%O/J>C0'\\T*E;:@8Z.H_,I; M.,X2_J">CJ(*&6_R*#R#;"K&2T&3K/:$[/L-K5UB3LZ?MT65_:,Y9YVXFA#; M*+2C$*4)\5W'=%R?@O:](D1UY_UU6*A-!7=H0_,G!%0HYDE4*P;F0[K4N1-I MZ3>Y#2+JD4AE$)=769J" ,F54Q#$E=!/+P \*XF*3=E8O-F7_[99"Y]H3M.L M&JH7[O6,-2D*TPBCF)V833^RS# )?Z]X28N8OX"S /(>>T;$$POK@U7IYCOT*LDF"=I>>D@".Q2IHP?6H9^/!L&'U"(BBVM$%70V' &UL7'EE90 M#R1;?B:)X/\=):]U&^.K_!YOCM) Z_0#VTY02'",+$(LCIKK^H$O'/L_G5WS M1F1/SLARH^0$ 0'RGB8$XO]+Y(-Y@8-H5[EQOU0T0.A_B8ARD?^')VK0NMKW M_Y5&07G0H#2>Z\ V_SFAV1LU<).#%N/D?]HQ?S'8@\PI[I[ !1O5]&.AI.Z! MA=DOV9]WBJRVS6>$_>J-YJ^T'E,]98=?L%,!Q<]_473],*;)R=N'WD/K73Z, M\7MT]S Z2+*^,7M\JF[2GTM:9WC>Q!7.6OJR+09;_9[NDQ+3 M0[&-3918- Y-C[H!!N%]2W.BV=A:"),PAA1BJ,@"5-";5 O)3DV-'O! M+E-&Q8Y$<)),K.KNEBGJU-[PL45.OT;$_W]U=7C\8Y_?WEP_W M0*S,0:V(>8W%LL*\PJ[&N"6HY9)^4B154)B#--:%P)P2LP=].3E814W=?U)^ M$*/D_(W]]I'>4=XELTSV!0U(4!V&*'">P3-.,PM07"E[+,J#9A'N5 M7#N.C)8E8\]3&X[@7"TIGQ/0N9@7T*E)F(-0K,2%=6[BFM!2SR9 _@/KUL25 M,UV?!I@'7H=VOWEC7%\*=H4;DFS:TA<* M!3/BCCP*(:\G1)"J)SN=:[52LA$ANE5D8T,D$UNV!;.QO%G^D_>' N.FN:R^W6XR-H#^67UBW/Y/#R6'J0LZQDMSHOO> MIN'+V#$&S'21UJ_8\KR*UF F?JHPH\M4G4?79%,RK:=I#Z1,>IAWD19< JA_0K % MS'Q(U#*TDC[ EAB2K@9;6@ MP?>5,C+V9L0V+"OI&^94(&DC)V&(CTHTR+;D)+SR$YN_^HPK^@5GQ2D88KU5"BA& MS,G:R#6=Q"&NG9HP3+/O1C+-OKOAIC[L$+K)&!>4K%2PK_PS(.;7OQM^]:T2 M"DK_^_7^+3!,Q>0U6H'/C/;CPY:>1NB!6''RXHF85NU\T MY$ZC,EZ:H#BU4A1@TW$(\4QLAHMZ4!S3T^SF]BT.&FK_W-:P/64O1DH7=Y8X M49V8'2M4",R>!_M G"A(8UN'83%U=6LXH?:Q31B&19_MK3#RF&3+A&U9W:0_ M;;>$7]3UT.YI^ 9S?5AZ.'Y\=OM'K:DD-:@6"6T\CCFDVQIFH\9,\\O-Z0 M%L]Z&I-XV@H5"0LSOP$YC=^49CX(B"65&34VYVH94C-"=3.EYH;*=Q$Z:4AR M1\NJR#BP=]NPY/@7G9%-$((MS06_+_A,FZ_LY\TKAT_CFS'#U+,^XJ*'XG795_S2?N:5D9[-9?E#;"$FBY'*[Y@P4W"=_O: M@!L/QMG9:=.ENH5271P\T(AD[F8P?=E+]R)M;MH(=+FZY:&W9 M:SWUYZQ,&D >-OD>D$=M\Z?U7Y?"+E(K,K]Z.ZKU7\Q07ZL/X *^B_S"]+S- MZ1U-MF^T>+_\\X594FEQ_MB_GR=@Q=69TV.(G MIE/&Q/>G4!L529HJ6' %QEK3U&B7 M1S+ILLR&R,?:YI&@L]9Y/%JF6UQ3X;_/6&5'C"'PL^'N&DW2"F9KK!7$;+7U M2>(&7A0[XI"R/# RC LJTVI#5^K0O6$&7P(C.=ZI&2)<\ MK>J4;*,'4ZNJ3GO2FIANQ0>?=L5>?=(R'S?SDY\&ZLU?\ZIX__UO=Z>'(#,D M*+1]#R6.16F:^E% A" C#U-J]KE_N[F[/!>U^[V8(Z#K:#)&:??\@1XFAVW9=4EP_&U?7%S;=+V%%A4@.I[Z(8 MVRZ*$M>WO=0FKNM"TFWD-2 !8J)$ V)G)&FY8 Z!ARS:5-) \:&G5@A,^L"G._\QZ MS7HBWV'^Q>/8RRG%II6&II5 ,4E/B6@VLAI5LSJ@:G*R;+/-" -; PXJ2,SX MEHH-L\%3'%$1B:7P0\=$4@@/VB.Q.OKGF)!#X)ZC8^$WC)=%P2M^SG.\>2^S M$GR)./:\9FMC9+T^;DZL[I7;[%C)(O,*5W5EW4W:G%,SO+G=EAE_HU_Y.V%?/^$-/\ .+9&8 M+Y%VG"( !829OKAL\B9] M)()JBVTF_QB#/!)LU-Z.1\&WTSQKL)V*E[77"XS@3GK@4E^Q*\0YEO MXUK:\]C,8)V)+66*- &S36DEP.L"YL53E<0_06G=C/MYD7OI\0*/R.XTV<'Y MJBQ?*?G\6F3Y8Y-,7R._'!+NZU%U]=AI EO3HC2)4!Q[+DH3VW>!Y/3 M1\8O>8#L2R68$;*"J+&"'DN U:K!G&3&\-9@4=W=_UR><1B3MK2&)\ U#?J M&7!RKT!T(ZQ+HY+[94;(:/@Q&H;V@%XU3T>%3\WH%BA,<9;=(L4HVX7+\+#R M9GV!FOI[^B632?HWNDFO\O*UX"=S1H06;W0+]H^0&!5 MKD6 XKJ.1%P%/;'1QFG['/':_;7&C+O!+5N$-[R=ZE;^Q8]6V>.= %?V+ M@,A!H1,3%.(T\.,0!ZX32.R&EG&USK:H"Q63M?3!GF6A^L65P2&"S(0C]1/J4$I\?E_Z1HMXNX8ZNH1D%"(7>>XI1GY[?@TKKV%B3IN*'/,PXYCF&UQ15%B2)@IG2L@YKH(4=>W8HS*YFBI6>< MSJIKT*RXIXO1_ .2K?,H.Q._#M;HUVN40RV$(QHC.[5=]C\G28D-ZH=W0D!W M"M#E+Y?7/P/KPGI*$+/&):+!C'!'2:38'=X=;D0,52W?3J=?MX_;B'"]YFQC MXR23?9KB[2^4/8(W4XU)FD)K)T81/W3B.$S8KRV2.#$HX6>:GNZDGX8Z,+=G M1D5B-JA0<)A)[O 46LJZ&Y0(RJDJV6>&VKH)/V*B]Y)^!!^#Y\3>YF7^*4^K M\IS\]Y<<7&$V\KCNO2R3G6>'MN*7!J/^6E9UBZLSX\MV6^7;2K#-\Y02ILU6 MD?S +:R0Z!J*S68DE4J>'9MSM03:&:&Z2;1S0\=,KZO]K^R[?_NGW6_8/S$N MZ;_]T_\"4$L#!!0 ( *,)1UTL0M"HKY .#F!P 5 8V]S="TR,#(V M,#@S,%]P&UL[+U9EQLY=B[Z[E]1M^_K11?FP9C'20J5+VK[\ F2.#$0PR$ QD^7JU5/Z_E/ MWWV]G%6+?_X3^C/\TT]^82LW6US^\Y]^N_@ Y)_^U[_\PS_\T_\%P'^\.?_T MT[O*WE[[Q>JGM[77*^]^^GVVNOII=>5_^DM5_VWV7?_T=:Y7H:JO ?B7]3][ M6]W4&@,4!1S8(E1CE-$:9#K#YW/%G_[Q_2'T4O_4V1OL5Q_^<]_ MNEJM;O[QYY]___WW/_\P]?S/57WY,X:0_/SPVW^Z__4?C=__G:Q_&RFE?E[_ M]/%7E[-=OQ@_%OW\'[]^^F:O_+4&L\5RI1-R_'CY_7MD7OS1/$JT> M_^5<&S]??_>OSL_^NO[4,[-!DI7BM@Z>V?+ZOO/\ZCA\$ M[-5L[A[^=:BKZQRZ6E49)+=12R3W3S]%KH.O:^\^;;32RMR:LU4TI'[]FSDT M?K98W.KYN;^IZH80")? &$Z!M8Q"&((DVF;1_/-5>R$ EX^ HR59"!*^^GI6 MN?<+]RZ>N=L,8.B \<9&5J0TD' .H^V M<9I"H(W%P"M&I:*1*8+SW!.V5NX%"E8^* 9)=&)4O%^L9JN[#[.Y_WQ[;7R] M33MT.OI.\=@CD ?,),31S1J$ANT5>Z& EXN"01(L0OOG_G*6A+!8?=;7C6-. M0 B42G^C5FG"K;989T# RU5[H4"4CH(!DBP""1\7MJJC"5L+_EN4OW];W2Y6 M]=W;RC7O/\P (XT&)$C(+28*RF&7AQY$],*)+!TG^>1 9MR "0'4OWBU?!TM$Q5*@E(>-M_.N7^J+Z?;'- K7I M AT(D%@80KW"C.6X@C06[H>*@L.8.01:$B;69^.7^FM=?9\M;.-H#%""*)9X M/@I.?)!6.0;S 6-K]7[H*#C$F4VT)4'D:[5#1\%1STQBG1@J=U5[OHAM" Z2(?^-""HO<^I5XV-/=L]7Z M :#@*.?1HIM8Y>EY?/[UJEJTA& T%Q1+0,U&DJNQ"#=OUBNG^(+CEL>+[Q"-OW[ M'_9*+R[]KH"K=2*>62Q!%P7#N)?;U\MXCKF/R^5M\R!3EB375P-DDR43E!$_S"!T+M\/',5'(7,(MPB4_'LU MOXT*J->Z%Y!G1L+=LO5ZKXZ.,081:!AK>W=9+7 MYMD^'8-1"!9::V!T?DW($438O7H_;!0?@\P@VB(@\G$1/RV* M8_;=O],K?<_6-A]<$F"L"L!SH02#TE,ZS,7H6KT?1(H/1&80;1$065N_MWKE M+ZOZKG%Q@A9H)B# RB'IK?+:#')7(*=&!\?;:C/;MTL_L;9 M:N67&QU\F.O+9LXH!8I9&F6$+8DP%PP/2X5H7[L?.@J.7F82:R$)VA]FBV^K MZ]7[NJ[JMU4DPK9Q [4$RD13&#TK%8(+%OL\A3WM-/0#2\$1S\QB+N+$^7;E MY_,6>Q@@ M)X#9B%)"ACG+0Y#IKG:_8#1<$AT(%B+ ($7V_-?&8_S"O=]*'B MW5D1&<]$:@FB6D)M608,/%NR'P2*#W0>*\0B$!"A>YWRB2O[MV]746S++[>K M5$R>7G@::8&( ^,, \3K$*S1UM(@VY]%.XX M])1P0$GM@2-.$4.THP,OH"^6ZP>%@J. M:R1MD$9YFNEVN;5T/S04'-#,(]0R#I'(1JWG'Q?.__@WW[@'245!>LL!B$'J MN-*$L2SGQLME^R&B^(CF$&%.G4>Y"<<_53RWE,$S)))WQ ,A&,F>7!ZF'_1 MMG(_3!0&]2^@&GX/#G.$+/AJ1_^KDAV$_Q&\?UE%H'\CXN4ENP]2>]I+9? M>ZG&9V3H--5-U\"F4VFQO]Z',)^MT0H<+(!);04<-@(SIJ34#\N>V5IPFL93(X/@*&F6 80/L_KZHVL$T4D VGL.E/7Q M%!(H<#+,FWRQW#0=IT8&P1&2+/-,?ULMEM5\YM*U95UWN+[,? GI.G/MCSGA M]WQBELZ2_6D>>/K?+L&EUC=_W7STXV)M,(*,11AA!Q1T3!%I.+1=:>U!+\U: MV_?K;/:3GZ^6#]]YVEA[2#G6/#Q\[.,'7FC3K#)1S@,9+ZKQWHI0H-QK2;K* M>8]A["4%TUP@R7OWU:UVY6[OZ4G_S]?>9]6<_9HWPF?4! M2!;/0 Q%0$1J[%U7)X!'A,0%GJ$C?O6$C+:UI\7&$#U6&85:!BB69PMWS\'R M776M9XV+D5,<&,8#,"XH22U5"G6%%PY$1I. :>"11Z=-@ P4\(0H>=@P]XS\ MZG>5KZ;NO89A#S2UA%@>]P_L93<..%E>$# Y.H8JM,HEW0*@L:%Z>36[V4V_ M51!HK@AP-OV=">1#5UN 8]"Q3<,T7NMX !DDXP(P\GC>1A_!?XQ_;39WA108 M)#4(U&$$/5>P,]MNT.WTD8II<)+Q%I))P 5 Y-Q_]XM;OVR[IP?J4U>4 #AE M3D6$APCRS #9IJ&02^J1.JTR"K@<@'R(/_W(7^T9"7L]'7\P8HBPB4#&/-N[HO#\#0(61."[-AN-@-LM&4 M=#0.O_O:5)F0^.7&I^:BB\OW/V[\8MDN.BD5D%H[ #FB(2#CJ>YZGCD&;ZW$ M%'*VY3%>>41>@!5[6RU77\(O5>6>7Q&_5?-&)-H1":2S$'AD1,!.88URWXC: MJ9G6)F52=S6*[ M T3<_GZ=2+;^([CKQ]ET]JF<= U@DX*0-JCK#;A]$]5LV94HGA6!RFK*U]_KA;52U;N<=^VQ:S!0&D1 M114H5LIRSE!NF]2/LFFFZ(R%I_S**, 8K7M:^.6JQ9:RU#,580:PAXHQ"*W3 M75D0QSW=OB!AXFO2"%JN\HG\<,2H#6(6_C(E!F3%3#R0U^+:B*CAY"H()'<4 M!!D,0=P9G3U(O9N2B:]"IT/0 4487H>SN6SU:J>F=M5BME>5%_UKK8Z@7B@ M!': &RH=XQARGA].711-,_YKI-,LH_ +N"AMN+G0/^YWV9OH,819LR+6I^)& MH0&D0FDF21"JUYO[P1AJD#+-U+!1P3-,W 48H,]^U>X;N!!] R4X4%A:@0,2 M"':E 1^#E1<$3#-1;"2$'"_: JS)>UTOXKF]_.KK=;UTVYE-(Q^&,@@\<9(Q$PB]0+L"K;?+S1RYEMEM5JH!FQ OFJ?..$I'[-K.3 MD&F]JSPZW@.(&K>S>:WT5]K7,0D^^QX]SLO[@1A?0J/71YO,HHR A)@"2@W4DJ/H@N8& MU:$T3AN*'@5MHZJIB%?\OASNM-#&T7@A5!Y(9;3!R$#;.;EY3!06<%2.BY8C MH7FXXLHUC_?&?F]')&X=T A%+Q8Z*)3'/G)Y&ERVD3CM45P",K,H[W75'J8^ M?[6_\HOE[+O/7XBXZ^-'K$KO%4J^;TT9IKK^:;Q3J_L_MS(4XT& M&B@*(=!08D,0QAYVM?T\.G,A.R>%9(:> ,8%(*& _;!# &VL$,>!)-("PE)9 MDA'0F_Q)IZWD%)+3=0)DYM))MA>(T:Z%;_1<+ZS_=N7]:CGT$OCRPS)?^3HH MS7_!^S!;Q,5F>OZU6LZZ^II([X&1-DUQTL[S 'G0(][J6ND::H52R<>J-=66 M*P&,\ %X%#!1 4+5.4O\&"Y?4E#,92X/$K8-S !Q%W!D;:B_;^G8QH1F-%4* M"8!98"QH%)C,G7B\DY!IH3-$LSM!,D3,!6#EK5Y>I9,Z_N?]?]_.ONMY\MK/ M5F]U7=_-%I?_KN>WC7PSQ A0F I@$>=0,:Z5S/TOKCXOO?N,,-//S0_(" @<4*<2T9S"(W(VC=M$QK3>7'T"#95T M7LZ]]1'Z9NZ7\5;?,GN1008D=@I(AK 26BMF46; ["1D6B\K/V*&2[L R"2T M+^*OW$46&F=Z=/ZD\0IX;K"'(1[IG5T^CTL%?5I_VE*8_ Y6K8%X&(=PGHA MDF8;Z@ TU 0$XZ32BD*4/=F\2<6T">;Y,3)0S@4@I9-X#"/,G0P@8$^8"9Q8 MFCN;_'!\C)9#GA\?QTNW@"3A9^!N?>A.C6\U"X#@>)V2Z:\Z=^1W!QDEW%ZS MN-)#15R ?E:IS*PU=W7N5ZD#V#G@;,XD]SWVMV M$C*M$YT=.(-E70!@-O0W[F8X *6E7-H]"7Z3A=W;6)AJ47-6\4<,(&QZ&T,OO38U_:BDG- M&>=1CH EFTXL0"+S A)I7%A-S)K'N)FO;P&PE0>551 M +;B#JEO^S""+0.:2@^XI20R@[T)N5,L6HF9]BX^GG'*(/H",/3N?MG[=M%M M5A9B(*E*YSXD*# '-VF9-H'T)'0DT'H!4#G4[6X3-DA[[QY]M2OH=:> M19II ,(Y#Q0+#G"*'"2>*V6RW[&;9$S[(CH2:(:*NP#$K&-;^VVF-!H8)UUZ M%Y0D8*,IRYV.TT+*M&^E(R$GA]@+0,]^#DC@0'ND #%:-YTB1%P"( M1X8D9/$PI@XYPJ-A5;G3U_<25XN1> *P,-\@A)E/M&W4%.,2'# M\7"42QD%V)^FA#XN[D<3?JWJM=9>=)I/EC;-,ZS6,YX>1QJT2-7$OVE#&/!. M8<<=E\1G+P7,RD$QL'===BV%F$JPB)+%@&I(6$6!9]&IA[ M%-,.,J;NPS =*AI)X,-45 #*T@E1+=KIY]8"S1&.7G-$1KRDWU[3JQIZO57%MG+R,XD!XK !E&B+OX4YL[ M;GL@B5-/02P'K".JMHC^Y^=^I6<+[Q[:QS]C^)T/,]L8WH?3<6D!YTD1#U<+:^L)^IF MBN657\VLGK_D86"#U)>?/&:WU X>)FR=R@D'2@4+L!$>:\15-'?93XOQ6Z>^ MC Q%67^IU\NZM1__,/>G$2R2&A@8-Z!E\9\;0XB6N1,:^U$V=8@O,W*Z W=9 MU%/ 9>PE5YOA)6>WJZNJGOV].78L @/H>.0#%J!!$/E@R+C!XVV*IH[SG11D M@]11*+@^+I>W34ZT4D!J+0 T.& N*>4BM]/93LW4L;L)0'6$&@H%5,>H)20D MT,%I(*SVWD&I/,O=5'T/25-'VB: UK$**0!?SX+4?0]XQG5D*1@076#N9""" MB=S1W1YD31TO&QEGN153%M;VG?-4<&"LI,#&+8."(TB;,9*>6LB9.C!V.FP- M4D2)F-I]S#/C@8)11BRDR<$<(P9'Q],!5ZW1"II.CZ4C%% BCCK.=&UAO#.J MZ(FH@"BF&G*3VR?LHJ<7HN0?!U''JN(UC1:MPGU,?&"<=,.B M_6/SPAN@B44 0D-,D,1IF-NI[D78\!?#^T4NTMM7XS$**Q"Y4\ +$\VIMDZ[ MW,TA7U)03*0S$Q::#X!'R[N P^N1^HU$4DI'M5BGL_^8-5/8)4K3F!704!"A ME,1AO,>#7005@J4C--T&FL%B+P!#6SR\JZ[U;-$XQW6(MSC)@46,D("XL2AW MXN%.0@K!S'!%;W?1&BSU J#S[,+VJT^CX1NF.-[\)+4^>I(,"1]E K./%&X0 M,2UD,BBV_5I\A)0+@$E+FFP+,\@"(U4TQ-XI9B2.]_KCR\$X M3I< H;AC#AJ:&5V[*9GVT2T_E#+(NP S]7AO_!1Y^1C_VK@L,D72T!,+F(7! MB!'2?@ B 2S6*=&JB\\YO_?EPT(QSGU7S^H:I_UW4C MK(YY&M!E.= N2".UIQSE?N\_D,1"7+4C$=&8L#B>>@I WR&A=J(9, (RX)CE M)/H6Q(@1G;CC7CU&P]6H0!CP -*IE:,1=N/K694B_?5JS (8C+T$(<0_XNG- M@ K$ :T1"88(TC+WU7%LGJ9--SWE'BD*'07LEK6D-UEM[V[K5)V\ MN=.LK^;G?KFJ9W9UGP]^EJ3_2_UP1CYW.Z4!TJ@ O ],(DDU=;FGQAQ'Z;3) MKB>_!(^KR7+QNMY[O9E,CS^2<0>"(5QX9)GQ^;-$CB!TVG3: M":48^'@U5M MP+KPE^F5YR(O9L_]S6UMK]*I$F]O1#E$4:!"BA)=);S$?I M2MF3OFG38VCDD H,>&!64V.H=[E? P\@KQ+/#9JYV-# MFJW'(2#!T.CS0PH,LP9@J8WU4#J-_"K("Z03E4U]"LLH? MYM7ORYOZAHQ51M5*>OX[J<:'6F7:( 8D=!8Y82JV6@;H1^THUZ,GP M.)@^\VM=I:/:O;G[+=[^/BX>1Q6=V54\Q+O&UK@TI,@Q I TPM/X(2)[6[S# MJ2PDI68H@G:\*8ZIK@)"<^AE% :\H!@8(2; Q1;/K7ZM%@-+:V]SY8 M]Q5] ;AY\023WD\6=C;W+UBZJ 9*TZ:.IMK%.P7'J8NS3\TGQWR4R\3'M#D[ M)T;QY$ H8#.\\W%E.UNK./Y][N^?Y,^N4Y?@OZ^_WQ!R<-$?9QY Q"0,EMAX M\,349 M20,TLA8H)(FCWC%V HP^(ZBTVL$\*-@+MF-54D2B2Y.=,VNKVT4:RG*WJW+< MH-1@P% R-2$:88S)UAO9>HTBH*3X2T(:HI%&WK*\:V^.)9TI"<0,D1\\ [ M+0T2UC.9NQML?^I*JT@\$?ZR**L((/9_8&C,1HDW$TF0!L02*"/]#)+< 9S^ MU$T+Q-,_-HZAM +F"K9PEFX6RWZ"5% #Q7"\,&/,$!',,Y2[)^_A5!;2 N=$ M*16YU%6 XQ%O& ^EB?:_;V>UC[S&;;:Z^SK7B]79PJ5LMYOT*XW.0@X!$P@$ MB$B+F;)$D-Q>2'_JBDS&R(:3[:$YXRBMB .[P=NWJZI>7?CZ>B/-]0\;;#&4 M8J,6.,OCN>*IYCC[6+D^A!6937$R& Y651D(K"OKO5M^B/+]IN<^[J=?]>JV MGJWNOH1?=?TWOYZ@_,W;]+T=EQ!,+-#0($"<,EQBY)C*/S7L0"*+O$".ALQ1 M55C0L?VAJI_SNO;;=@BUL0DC>Q(A#BS%W#BB**6YBU$.)'':)\*)+.<8ZBO" MAO:79Z/9BU# &$:!"$0)2TE ,O>S8'_JIGTG/#$J1U):N6[W8XK2?D'2]/") MA ;(22294Q.W.I:X"SN]S?W-_!'P)C[?F=]XTWT<52:%^ M!^*V(H3*8.,6RXR[5F**=*JSH:#1(SN'2LK)@7AQ!^[BQT$.) PX;DWDB#"2 M!94[T-U*3)$.\U@0RZ.2PLS7IVIQVU4[*=J MVN36B>"824E% >]+>&KFU,$/\T!ZK@&WQAICO='9$Q>Z*9JVU^5$@,N@G.E] MVG5QXU?%HG9]/\I$>B[GF\NP@\]CM,/UDT\GW_CV6\VKL T M;!")6]=>$(;$SKD8_V.#*UP@MPU@[N5^,?!J,%&\J$^$%*+&9D75Z6@P7&JE1^S (B,+5MS?UV,#YN1XM9 MO!+<=BFQE![.MSU;Y.=P )H@@T($"&.*24$YJXI M'$KSM''346]D)U-E$=!=-S58][ERLU7D9!DW8QI6Z][WV^MK7=]5X=OL9T]/SD#,,ZCN$AT\2.YC)M S$ N4)!$)I M)35!WF:?,-=.S6 /LTNR%U&8;^8['OZ]I4!#Z^.F<(B0X'B0N6]U_2B;N+=W M'I0TO,O\2BG32#VO@3_"$C5*Z(>9FU9J,MF49Y^?DEWO.RZL[IX*BEL+\I1/ M#1@W=Z?NN$NX^-*J8?M>JVG\NK&J@OWUMU>OA MJ+]ZG7A;=ZLYPD3N_)P,MG(_?9F,YN-"3WIN!1_"'$@&!5"$J*"XUISDWO!= M] PUC+L^NQ74VG.@(IX!H\$H;2W6*K=+V4G0M"8J&RZVC5(^)91I6=9E1T=8 MDJ=RI6&6H[E^)DN1/GA_O,!0"Z0( G /!:'<^(!S)Y3OIF3X"*;GG]H*2:LP M,,@'P(-P3'-D&,D_=6DG*=-:A SZ;XY*&B[R,JW .N/Z**?K_E]FL 2[:,AD M"S8?O0,#0J00-P] 6ZX!-IP9S861*/>#P4L*AN[]3S[>=?UC*]/-A^_"XYH_ MZ3"04#"@-8&(4Q1L]MK6;HJFM00#M+]M 3(*ODQ#L&- ]S$QX98QWP/COWMH MRS:=>7N9S]5JUP%RKV,'M.11T=3$ZR3'&)+I# M;2Z/YE'GZYK?QQ7OJ]/?1O*6ZWITDVAZK)]K :% ,#T-<. IY4B%X%GVULO# M*![L(?5=_6*/ZW3X;'AF)U1UF:;S M^:#$H][.MN8L#GT[:Z$FV]O9_>=W>OAK72)N@&*" (B-X(ZGV6#Y'\M:R AV" 9JYK0)UI+<;4^[Z)GZE2H/)EK3*X=JH$S#\3B*+SJUF^8. M>N$V?WDJEUC;SF/LR@&?GL'L',M+)JOT7M>+V>(RE?VM%]D)/PLBXN+]WWL$ MJ+$:*F\IE+ESA-IH&5PJOO6YN[="9-(X"11%*?>8(Q9XY-'D]@Y;B9G6$F7! M0:-D.XO@R[1!:8O.UB__Z_VZ3G#RBV,S$CL^+8.-Z4MK)IORM-PZX^'Y>GO. MN0B%H"/ (#3 AC3+BE C:>ZNK <1.#CANL]BK3LC%5(;A3SPD@MIC'>49"_4 M/(C"B9.O1\-6(]-Z/+V5:=&^^K$ZU'AJ^W/R!&SZJ0K5P1]:Y$V M"$'J@>$6@E1QJY3P.-C<.2MMM R.FF]];@\80\.!5EZ#H"3V%@D>&1Z9W>)L M3A9L-&+DF951J$WI5?\P?BW'Z6LZ"JGMT (!K0T&R#B&&82<9.\^.5YMQQN] MG"V_A*T%[C9_MB:S4&>!\5Q$2JED1%).9&Z>^U'V6FH[.E&R;;E&4$H!=9$? MHOW5\TWWHT:%GC-1/#H J8WF"A/J7/9$U6?K3UO_/1)LCA9P >#X+?4L?K]< MS:[UJMDJ40D&I.4!>$W>SJM^XXCPYCW >!,I6N-Y;H[+W)#Z1QVDZ2 M(\%L5$45 ,3[+E+;;?VZ3V>%(5":"J $P5P)'ECV4HQ>A$W;DG$DR.5720$X M>RI]V\-(X"A:;D,!P\AR[)2S28\S_W\U$[-M+T&1T)4)N$7 *-D=Q?Q5_;%.D2( M9M<0#R@TCAICA>%CG'B[:)FV3=>(!]Y@P1< H*]U=>/KU5U*N'[H27#3XQQG M! .E4G>4@#U!,MK8[&4+?6GK%].$KPQAHVBF ,1MJK\V15_[(K0! Q,H!-@2 M2H660N+\-86MY/3#U6L+EN>2?P%0^J6JW.^S^3SNCH\ID^AR%H_T30>3AQ_M MOAVFC'B-B $8JWC&,TM<]K2ZWL3U@]EK"ZZ/HYL"0/?-ST-T/V[K-&KU/"JK M_N[W.;TR)30S#9QT, BM8'"YVP?T(*L?T%Y;D#ZW/@J V#M?1_=D-?N^UT(; M*( QC(%XTCLCE.4H^,S(:J>F'Z!>6S@^D_0+P-&'JO:SR\7;U(QU$?F(6V09 MI1/UDQ((UU_.U^K:QVC0%F@J%, (.Z:#$!QE;P)U++']4/C:(O2GT5T!(#WW MT9.^C9;;5I>+V;KXMYLA!].MU$J@"/;<4LJYSQUMW4M4/]"]MC!^7ET4 *Y4 ML_HE?-/[(WTT.*")M$!9[9S 4.+L%8[MU/2#TVN+W&>2?EDX^G>_<%5]-I]7 MOZ<;Y]/[@X8!>PUXBO8)S%-G/*> 5E(2J(.T(7<5Z5ZB^J'JM47O\^JB '!% M#R;^Z/(7O_"U3@[SF;N>+69)5.D6NNZLOS]8@X5.Z8P8$$*TLA0''O(GQA]# M:3\8OK87@!-HK0!L?HU,)$7=SP__&O=>[5>S37/:=9>6S]7B9O-+;Z(HPJSM M118A#Y22J4^8)IS'ZP*$N0>H'4]MOP375_>&NUO3UDD7P!"-KN5K#/B=(^.E&$1$,-.3+: M,&O&[HAQ%)Y>VQ-#3CT4 *MF,\0]#&D!@4R6-GI2FB&*#,E>3K*7J'[0>FV/ M#7EU40"X/OO?GXFJKA;QK]8_R]3R5=[=S_R4\)GYN7N96:^&VE\P8#V3WU?/9W M[W[1L\6G:KG\LMC60#ONTY1"!*-9%51"@CPWV45Q$(%3=],=!5.-/@6CJ:R MD_ 9(V_O:^.]>W.7VM\EP=WJ^:]ZE:1Y]TZO?#>OE& 0'>CHMSBKL4&01KL_ MWDX]F-YI3\\3H?5D"BWSG-TUY?/X [?CTT::2#KB$7S(_$D!4;18" (NH*,2 M(TU,[I9:8\XE?7)<'E?95$?$;?=IILULOMYQ]X)W7Q;G:1?6\6J[[G;5O2U8 M8,!H1E-/9,8=LH'J[$^9.1EX/7-/.W'7[IV>6LEEVKYTK!QOZY[]ZTPS4T>T M9?TF9P9&@)(4I_DL$@7BC6.YG^S&F9SZ!.VWNJ[O(F37\$[(?NB8Y1Y!O_P2 M$A7/NC9T0]LP!0R*+GJ*+&-"H?)T//N5@8'7,*6U$VOMENO4ZBW Y7AB_OXF M.DLL?JH6EQ>^OGXT'*W\2>Z QIH CP/T$C,2CXK1X-N/QFE=BU$1.H*2RCP^ M[R>E'GV OOCWV88-CWB(=@^=39,_HJ\9@-?8A\",U-E;@><9.9P$]VR\6A6^ MW=Y$?:WG7\S?Z'E*7O]VY=/@G5#5U\^GKJVJ9U)N'9G$(07:1T3+( *TBD6E MAWUPR$Y5R1.*.\'R8%NFU5,!)]^:AU1@L8>-=2(PL\ 2:(.CU'B9NP2OA91I MS[$,&,LIZB(0TQSF_>#:WCT$\KI99)K&_0 ]X 1+Q93A&N8N8C^"S&E;&F=% MVK@J*@"%F\: OB=K&FKM-+ ,^]0]UP)%$ 40026#T9KYW'4I!Y W;8?CC*@; M2R5E7LV;>9P#LLC:/BO7N.V]=.8:87300'AW2O=M,-[];OW.]A'O +@ 5, *"^)0LHB#PB!&?>FQ9-UZTJY.TB<<: MY<-+>[0@GVH*MD2-RJIU'=5 D]3YH;EL4W_*7:Y_YS5UC7/S9[[IVYSZ2,K.1UK7*?UO,5LM_ MC]_S+H67?]SX]*.+*GVK^UIJO .&! >PU]X(+#D)V6??3:Z M<) 5X/L\>ZIY)J&DG0]5W93-D^26J7'&9LY(FYS7.GZS3GSM%I*,#J(QR +, M:/#,>*;A>$\>)V1TXG>3$K9@J; J\_[U6'P\Y*6F^2%9\J@[*%:I%,]@/KD=W[QD7W M[6#VL.H5T,&F%AS<2VXY=72\^_?!Y$Z=3CTV7,?57U%0?1]"O+#/OC]MR_-X M 4J-*A=V-I^ME=K-:U (1!%3( 3&"!'OI,[]RC2$WFF?F\8'Z\@:+ JM::[> MAWGU^_/T@6>YQ3O83,WN@>4F,J>E!B9%'P-$U"#&%,S>W_9(4J=]G#J!01U- M;T7!\]T] 5&4N]+1NW>A#B'MPK@5%39!<1,$'^^:>A"ITX[J'!^>X^FM*'BF M8GO=G%*F@>9& TA\T$%A&K\]&D(/I7;:^9_C M@W14[949\OF<$@*37&]\'>_DU]5"+]SF+T_3==>1L/Z_>7SL:$1J,@2A3B6K M3-&L[=9O.S>+30E2:6J190!"'NTJ4XZ0W"-^VFC)Z&5MK9"JT%+ M2]HW;A0!]1A(1S@(3BKBD95,YTZD.I+4:>-663#4X5B-IK0RK6TR ;-U_?C: M'JS;O?C%L,9=>S\S@^4[C.Y,]NMIT719?+'JGAM B1/'7:- S:ZWM8B2:*/ MDWE''T3@&.DR_C(M?NYOJCHM/2!'9OYGV[::,F8P;*UPK.RCC=W]S]L-9W*17]?"064<8KJH)'//D3R2%(G M3N/+@:&.C)#1E%: %QQMGKZ\K/WE_?OY_42F[D-:O:T3K/N?4(,#U_ML/>^96>S8\Z'P]<(<.Y.82GDS=( M54$"B3@!W/" L(&4HMS5K/D;I#H_^^O[^(FKNT_W.3_KG='HFN(\4,QAP%7P M#$GM*.IZ*%YZ^^?+ZOO/\>,W?,6_/+'3LNAK:7#:J>D'^Y-#L!.>9\MZ]==O M4?CK1Y1??'59ZYNKF=7SLQ^S97/D,P.&.1>MIQ1,66-DZ-4U,*[R#/;QJR>, M=!(P#5*RJ+3*+=^I0;(YM)^S\*ZZUK-%HVF(@B"*@@.!"5-8>(U9+V=T'TC: M")@&)!D56^66\H106=O6^NZOOWUK]*_T4084TZA5R!!E\I56#)%B SM^>-::1!0(DC!1S+Q -)GBMNZ+MA^G\[=DT M?LQX.C]0@@7H_-?_: YKPL!@' #%RC.*#/6=]^/#=/[K?TR3?S6>S@^48 $Z M_]>OC?:N1D>*A0,$FH 9(09JF4WG__IUFGRF\71^H 0+T/DO;QH46YY*;A7 M6 MDK*>0=\TQ.$SGO[R9)DEH/)T?*,$"=/YOYXTIN)@ C1$#@2HDTWQ1UIF; M>YC._^U\FIR;\71^H 0+T/G9;PTWE\"(4@8!5=@1RXTFIJM2^C"=G_W62^?B M]>C\0 D6H/.+OS3;M0>@N*1 $LFMX2&@D._>?O&77CK//N]^/)T?*,$"=/[V M!E$11(I4)@633^=O/O72>?;C\B+[:81(L0.?O&Q$%:U/JJ## M&!BY)T:@SEC=83I_WS,FDWU:^WA*/U"$!2C]0_,* BW0VF* ,,<."X$ESG=Q M_]#O$H=>423N0!$6H/1O[QM#0+4%RJY?++#T4CDF.GOP'J;T;^_[*?T5A>(. M%&$!2O_8L$T:IO0&[0'15#BM!:,TWS7N8T_S_HIB<0>*L "E?_ZO;8I)B P; MZX"6Z0XBH)"N*[W[,*5__J]^2G]%P;@#13BITI=1")M9PE^Z9PE_FBW\QY6_ M;CQ%6H2!"DX#1Y#"$G&)]%8#H)8.Y X^?;:^/KR%W\ M-=^@GBD!C(_[R&L9$)4ZB.S=HEY2,,TK[OB:WI[I?KS8BP*-7OGEQ\5?HBF^ MVNRZ3??J)DN46&!DW'70.,0%80QG;QK;@ZQIC-*$\,JCH->2"KN>QE:%K\\^ M/FLB;,?GCY(&VY>?DR?!8A. %$P#CSQ$1'OH8.[MO"\)=F0LI1X3J0 L_N>I MC'69%4[=2XR"J .X.CFH:,I[$)H YW"\E@4(#= M-[/5VW5G4^NCA%,-V-GJQ7BVAL-!$5!4QE,_VMX@K%;$Y>Y&? A]KR5#NQ,Q MVX?B: IZ+:?CK[ZV:?//EC[-=EY$/*?JS9P6K7N)42S: 5R=W*+!%(<0G@", MH1&*BB!1;O]I/(OV(,Z[3Q\_?#F/^JJ_^Z^^GE7N[96N+QN;Q$:/15)H@&-. M:JRH$SAW&?(^FEZ+Y>I$QJY)[-D448#_^,C/V]LZB75GB&;M\' >KYA1/@QY M$:#.W1UH)R'3%D>.#:&C13YU_4G?6HM(>JJU,( %#2V+4L*P5WN3UU6DE%&Q MQY0J=4IY:JCT?2; /HK%1+%8CA4+C!'=;WSU'[A4J5NQQY0J=4JY@">T9J&- MT@AHD^8*>>6EE=HPW=4TXP]8JM2MM+VE2IT2+$#GS4(;+QG0,J19=O$;@B&N M4==UXP]8JG20S@^4X-2OIE]65[[^N(B?MM";Q@*_^A0C;]1;(92:PAM@!2.I M%Z> 8JM%1\OS:-L*KZ!>J:?B*.8"D/)A/PLP7HND(!)X3X-6'&J?O?7F#C(*L2IYD#)4S 4@Y9'\S[Y! MNX4:*&0EL(Q;:ZB@@HP6]HKK3SW.(BLVCA;L:WG"^5I7-[Y>W>F%2\^W-^E^ M%WG-^H:S9XU1'G$.X>ODKS@BC5-G4() )8*:>$7DJ9,=7WD$? M);WSGA>/6F XML +JB62+OKTX\WAZ:;MM;SJ="*EO5-F1L44<+JU L=@K0=9$[=C'04/U;C**1EOB:'= 0^D.%#" M,$"C/V&()D2ZW,Y]#[*FQ5MV*/2%VI%Z*0!J;VZC1%/'VH5[^.O'ZYNZ^KX9 MJ+L[%J80C?M3$\"H%%AZ3TQG%=8Q8.M%6*%P.Q8.U=BZ*0!P'V[KQ6R5.NLO MW(?9C_2W%DZ"TO'JH2EP01)A@J(HY$XU:J=FV@C#V-#*I(6)G\7/T^#O758] MX3_-P />: \##%3TFQ&PYQG\<<&)VXV/>:\Z7K EH*$%Q#B"V <.A&24!FL, MTSG:_#Y;UXO6/=L(U-L!(H8$A\4RD$ FC>L6V]BG^^:+3Y3YD M4?S1\BO@ MEZY+4&W+V*/IXD$B LI(U44VERQ_WV4S7ML\2TH9CC5%,RV'Y; M^G [_S0+#8D9RH&).P=H(8QDF&%#;"/#)Y\J"L#50ZCGN9AV,F)%-)1,ZY0][WQ0 M7 37U3KSJ-A;&S'3]$8_$9[RJ* ++VM%LM5?6N37CXNHM0N(U>[MP7R%DC" M&4!:"NZ1P"[D3C?H(&>:ONLGPE,N-12 J%9)[>0FLA#/\,@-PT)HJG7PLFM" M0]9[=G]<9>_M/O45^W!E' ^M:J7G6:!U9NWM]>UN9F[M<* M6[BSZS2[\^_K[[^N3!*0TS"" T^LM ^35OZ$\%U$@4?#FRU M ?8B#77U[F)\T[DC;51Q#91$!&!NA:#,"\)S^PM=]$S3*G]JLWFH(EY+_NXG MKY>96ZZ\_,A1LG,[J#YY,JZ5%!@/.?"(2.-(_#^9.W5KXLYCOU25^WTVCWO" MG=FX(R*6/\9E%IQ_)X<>QY'$V1L );X>#HQ) MG:9ZBD3P!X'O?,- & %IH8\&'',CG0P*YZY1:B'EM:1Y=^*@/+%/_(*< MO.8H$K=6Q?K4WY5 X;D'VI@T#@-[HBU'R/9R,?<\)>]>O91<[0%*K;)*N#B, M[$Z\DQ!%%\$[8*CR1B+!7);QT&WK3Y=TDD.GG1 Y0L %Q*TV#8BCE;UO3]"2 M2>F5!JHS;].D-J:YQC*(^>IP=*W[8E>9^MH#AQUT")G#!;_T]M_=2OVF/9? MG5(NH!54LWF5LQIH#S%@@E&%XN[!G2&&/V#[KVZE[6W_U2G! G3>;%YE-(D, M2PL\C*QZZSSC73GO?\#V7P?I_$ )OIKV7XP '9@%G'%.@O-2HRT8_/':?_54 M?"XQ%N"#/-R66E\Q J= I7,'8&/:2-= U78 HB#Y/E:'O<^+I:WM5Y8_\W/P^,7 MGV;:S.:S5>Y1"[U7&^7-YCA>3S^ P2*@'%$@,*:9-HAZ^7H&,,1/KF_38]B] M>._;,IXMW.=J83=?-$)#+/7+BMPX\$48BB*QGV5LU=]!3"IR&:GV[H"N7"HZ&TW=?FRJ[?6H- MCRCA@68A,N$EHHPSP;*/4-]!QK3OTN.<9\?)N "[\\3"YVH3-M_=MUPB 904 M-AIFZ 2UG!J6.ZK81DLI]N9();>"9H#$7XMS?F]3-\$(>Y?506_Y[%&<]#Y\ MG'[2N75 8:0!-8I[28,S+'<>VL3U!N?^NU_5BUCID_E@(M7_\*"CJ MRZ-(HS3IE[=OM];6N[[Z$;]&UF(69397FS0KG M-J\SM>I02&C "6:*8\&\V'L'/F;AB0,VN<^AT65?@/5Y=[_LO;#>[G[_IT8# M::D%2(G@I [0BMS-P793,HTE&E_SC5C/8#5,G9Y\[MU#3ZIO>NX;\L J &." M <$;BJ@RF--^5FC[DZIU24]JGI(W*Z?ELT<*U^SG MX_1-1HP$6J0[#9?(1=L!!CX+=Q^J^J7HMV4@XA\260BT%2%XAZR#II?-.9J$UQ*XZ83'"U-T M&FV4<1>*AMNM7XMGYG;=-2RR\38*X3X2^W??:"P,O0*&.QGOE"H(C2WE-G^> M6 _"IKU\9P;>>"IY+6?CMU5E__9&+Q/SUS=^L=39'S6ZEQCEI#R JY,?F(I9 MH#C2@#!&:(!2R9 [Y'^*SDC?KN*.;<*;NZ??^:K75OPLI;#L M=)6Y2\52! (K/2;*&8MD;M\O&_&OY?3MQ%I[]Z53JG;B /K%;)4X_KAPL^\S M=[N[TE_B "0V#C ((1/261]Z);CM"9[O7+R4;DTG!4&54R.E0>HOL]75N9^O MY9>"PQ?5^[A[5WQG7\,D2B'?;. M])OQ]!JGF1Z@LHYIIOWE-[7BMZ9QWA/NJ!:1<.F UM'(42HY#,$HRG-,LBYR MFNF1BC]:?E-?#(>^'UH"#,(>:(2TEPXZA4*OB^,8F1PG:.,SQ05B=$45\-2Q M5ZYM8EW_\>]^N9:"KV>50]N\$Z6!W%]]IU]U[-Y.N="5:E=\L8QY&/RTNOOF;2*CX^V'QDM(\F0!X00:KAQ2 M*O?YV)^Z0:;U41D?-LHXVRCCXE$9K M91%H[HXJ.>F?UA1F 515B'8+0/9OWWZIOOMZL1;DI5]LN@*:U=/1LON1S#@3 M#8!SP&#));*(D6T_93!J^](V+2*G0T]U E46 -&WOEZM7<%5$MX[?U,M9ZO= MK% 2XG5'2(!H]/^"P":>5IE1V4'.M&^DQ0 QE\*FCO+LO1^UQB&((4!*O!D< MPXT,/&P72ASKCAP63Q\G2C/BQ7%,P1=@R[8Y>VF?[X>+IYC4Y$XH/I+%D#^9(H&SWMQY3:^6CTMK;Z]MYFC7_2UTME[\M M:J_GB>%/\:LW*6KF+_2/]:.IU8H#IQB/$N8XE1/&>[C1"*IX;F!]8JCV([QD M0WH2_(Z@W\-!K3:@7J1:>^\N)L?V+_$6M,V[M2#R8J/,<=S+J3\>IL$1)KC' MV;N@9B%\FD?WUX#MX_5;H,%^8O@E^XW45JZ \8X!SX*%0LB ?/9ZI)ZT]8(F M_2-!,XN6"D#?2UFU\T&< -*F-"SO-=2$(NE]9K2UT=(+7>PUHRN+%@I&TP<] MJ_]=SV\;?J15%"B4AF(QI"R%!%J7^[%S+U&]\,7_B/@Z3B\% &WK9K!/BB_= MNO5-X6P^KWY/ X[BOWD;&9BMT@WYX6),02#Q#V%EO!-39X#'(CI\V$#+<\^P M&8N77K 6KQG61:#@^-U0K?0\4[IF9"RZ6=?/D@L:W34@ X;R$ 4K)%.$*[4] M]C5#VF63CEXHE*\9A8.EG[&#X%BI9/<2B[NL"GM3K)[?C7-DE0UOGHSTI[L4YT-J"P4$@J1' 88JPA<'A MD+TI_A""7VL:6R?F#G.[^&50R+WH3^".Y.^7Q'"ST)<,S)\<557MY=7'V;?U[PO.YGW M(C7MU0:8(#DUDGMMS2TH>!:0M)7\D6R(J" K? H2D8G% @#;4 IW;\1E@EMQO6EYDX MD_T%K#P@9]5E :&UOI)]C*2W3L76"!@A&0B.0TLD9\9.99H;Q$Y[$RG,EQRF MR@+M:R^_HO4I2% %)+0*0,&8=I8++K(/=1M$\>OP'P?"*H?O>)R.7Q&BVSR& M5L8I\T B@X$(TO! J NX5^>L$_J,A^%\(AWY%C!W'T(8@!2&.CO.206GY21$^= M"5DR8(_46P&^7UO6U$M9?O:KM[JN[V:+R\T ]M8QVZE_75 &6"@QDD1P1'*7 MV0XD>5IS>R(_\)1J+<"J]F/WA9_0X+WA+W"=2D@94)Q9%*S25.1.B\M!][2> MX4F!=A3(,VK]U2"]S5/8R[YA!FAA(. A"!6PUMCE#H1D9F%:C[%\_(^#A=>U M%79X$'O91XP 0SA/8[BADH1B&'+?N#.S,.W5YI5LA>Q8*'@K-'-^*9 "P2A8 MSR$A"&FB2ZIP&LUK+!&OE[6;NY>/WJJ>&+6?+I5\M M]<(]?N?33)O9?"V'^W_KJL5YDDT=I;]^1QV067T2NC(D79]>?IGRL1^)?#=; MVGF5UF_U7+5BP%@M@9:&A6A'(3>Y"^"ZZ!G28#"H7:\G''[K;G4A&@C$( 8DTI9AP*G+OXIP]=A8 M%QAZ@&V0 M9@I VU-Z4;J=[-J/@HA4C*0 C3<&&)SQ!.5^UFQ2,>W+9!GGZ$#=%(>NMWKE M+ZMZ]O>U'G?O%Z@\D-@C8#DF0GL45'8O=S]5I;01.4[OG3 :K(0"8/7L5O'X MU_\]\W4DZNKND__NY[N$YJ $)AIYP (,QALG&1GMD.RD;-J7[3*,VP@Z+ F9 MSZ\(3?[:+R-&Q;W') XT.N4A]!M?/_06UT9@(=>YC CI 0^136Z=) M+ R0+/VAI-&$22'M:'#,P< TS;@+/=!/CH@"ML.&YQTY)XUR0VZBO: 22,&# MY )2F+_C11LQA=C9TP-DNS8OB[8*@-TS ?;@AF .)%0HC5T0EFAM",E=U]]- MT>M_'$4M=Z9?$"6N\@PW\:LGS'02,"U> M,BFWRBWIJ>'B+[=9>/3?7S#A+0$Z" RD$PBQ@#6RO>Y$^^#21L T<,FHV"JW ME">=@GR[6-5W?_WMVQ/%'!D$1! :&"8LX%Y#:RVC&G9EL2^]_?-E]?WG^T_< M0./^BR=D/*TW(0SR**T:),$B?*>FY7Q^NW\A"QD/7&.PBVP1KR#DS&4/D'82 M-*WGE/>4R:^!0N'T-CJ.4;IOJKJN?H\>Y%M]$W^RNFON- RTXP%XA:2#$!M& M5>:(V'1 W!9=)0-?Z.YX%7X5"TN,WO@NS\TLP/>@_*3^M^***"5 MAT!*:BT/(17XOPK_.WWJ4\[YSHB_,1P8'NVW121P+BD1+G>RUPXR7H//W:GW M74/XAHBZA ,M[KK5_:YKRT-B' &I& /844(5]2':X]P'UPXZIL?+(.5N'TM# M)5T@6G:_ELOXA_9Q#ZD@C4Y#QXFD(^.EA%26X1K> YDCQ#VIV[U,?NAB5M6? MJY5?_I>OJZ_5;+'Z-OMQ$6'@O_K:1K&^N_6_IMR+B]_C%W>;/^.O/&9,I'FD M- H,,1TO:!I'/C4'%!+IN=4$>[WO-I.%DK*P=0P4JJGT4B0(_7>_^!Q=A?5W MGG%\]YS?U!5J=^J.-@Q(&Q10TF$,K434P..!>" U$P<*3@'&,?53(B 3KQ>_ M/V/U7V_G+WFM;NO=O&)B@4R]ISP56G+NXMY#1V/Q $*FK=\X!0S'TDI!"$SL M/>ZXM*%>[+;WL\NKE?>+W3RW5+Y3#Q0.,,H *A^/ XG:]H$_!'1 M>6*-3?S*=YX*W7?=I95-8H,8&&>\3(/&G>U5>[OG5>]QP6E/V5P.Z/$R+$'Q M+;9U?=V$! 1CD;$>4:1[5?GT4?V4]_T!RMI6]Q&2FUCAO\X6L^O;Z]V$4^* M@90"1F% E%ON=:\HU!Z5OUAT8J4?H[(JA_RF5KS^T4ZX3+W76;Q,8U MD#*MFY,[$)U#WL7!YMP[?WV35/*UGMF'"[&^;(@*20>4IM$U4M+M[Z>A7]N/??4_U@8Q@/DD"EO*CH0 E-G&-D M.\6CQ?'M6J4D-V083O(*M C]+6NK/=N^2&*[>-R>:L7UG]YD0H7=_3B&F-:3S.HY@(S-U';S]5)9UH>4Q/9DT4@*V74OJXB)_LEZMSO?+K M'%_7;D])2N=$\<9'5#",!$\YSXVQ_M1-&X8;_YC+IID",'?N;_3=NC3^2[C? M,R^?KWUJ=.4\0") [(17F.9.B]JF8=JRZS'P,TC*!:#DN55M';DJ!0I"#J5]V7&C,ED[Q3UU'/!Y_L5VEN3.G(MU=D97TH6%#AAE M!8"!" $#9FP[3[I'FLQQM)2%KV/@T)8;(UY#-.@B HVBC1-0U]UB# MTXO?J]W,&D2 1-H!90@)E'%.Y<&)_4=1\AKR58?A;S2]3 W"+ZLK7S^/^[1L M)$2CFX404,X:B+RP&S(YI%B ;]DW!(PU,$$88+ 2TB#F M;?9N(T,2FJ9,;#XH'I%#WL7!YN7 ^49>!&7Q"F@E0,Q@8ACS#H];P?^2GI(" M6D.%33MK00@.,P:)#?W:+QZ)F"=*7D?NT;&@.5+B!>#F^ PJI2'0 M4%* J.*4F <1(! &Y AW&L]ANLR0F?SG1)]GLSWM9XM[.PF#?W^'(5Z M\;N??_>_5HO556-3$A?O@-)JH#"D7C'%&!GC:?EH@J=W\09BJ>OD'%=]!1RP M!S'[GU[7%[]7S086'!BJ,&#,& ^#AR1[&ODQ=$[O/$Z)S&.4]2H!F5Y+&UQB M Z17$A!)",.(64;&2. ZG-+IW=/)07FPPEXC+%,GE68\4 C9 #>*T)MH,'K M['W#CR%T>O=W:E >K*Y7BJR2 MGK_1\_3"]^W*^\AXJ.KK]1(#XH0'KY$A6#B,KTP1PPT1.V"X1@NT%&AH"; & M.\@DQ!1E'Q#X@H)A.6 WOHX26URN/_-L$>Z?@M=?GJNL(4=KNP\_QRT]1, M$P>>"&.YU%(VPAZG5WZYE^A,S[]6RUE2ZOMTYUC.S-Q_FBT;3.N4*8-U -(Q M']WG$/UG?3HL]B=\FD!Q>:@=2=635P*\D+%>N.3LTTR;-/=PUGZ[#HIO"EP) M)?$V@KWBIE^UYZ$K3US7.9*/D57>4X/I/OOTDZT==-CA MO7&/(]VI7EF]B*,P-HY+>V*, M9=-* 0CKWB_'.SI4TC3JPP'KE/,,:>F].:G->Q5N;5'6<21M%X#RKAU[/-=> M,""A2HD/!%I+K0TT=SU''LHG])H+LLTC:7IJ#^@A56* B"'&P!CH03RCE!26 M*J;Z36$\8O&"8M_C^4!C*Z4 H]IRF.RL[-M(3XNXAQD!VE,J*";$\1/="0XL MJQS'%1H=$_U.^R,55 #B=AKW=G8@BXZ=D HHZH4,(G66[C5I;^CY?"#:QK%U MIT9;3N64C[7C[Q*2!2"94D 83*4,3."0VPIF(WY"UZ@P_(ZD\*DOCYVO3,]$ MW(AK> @TI?'+8$3P&CK.^@7-^ZXXH<]R*NB-IX')897:H?7(T&P57S! 08X! M9=)HRP+C*O2#UX$K3]PY,]<3WYCR+N T?KE)_N+7?9'=V??XW4M_[E/OOH#.Z),:BP7MQ]$U#MC;7"Y MTRD.HW#*I,1"+.90O95<0?>VNKZI%JGJM KK[[S_<1/]?3^X;&[?!V>KE3N( M@Y,4R$5G-;HV3@ H'74"84%5[FR5/ 5R+SXM]49MWTH(:$T9L)IJ2JA1E*LQ M6'I.1,E5<)TZ;A1\#Q)O 8?:RT,[<=+(DD $*$L50,A8:./A'+;SEC-?J1(5 M!2#D>+5V7HP.EG$!*.FH&3B[KNK5[.]KU32]#1J/:0^!")1A9PCB]H0E0L]) M*R G/AN>QM#&_]?>ES5'?7+Y!,'GG'@4@@V5*;M>J@$.[^?0 <#G='821[;H.ZVO&WKGR1!(I1 M# 1#EE!.&=I\R"TIL3;$*2#Z.@B9^EB] +]H::C^+;%WF4VVD1H:P%U#B'" M4$5%ZJOU+2$R/S*4E"S]+%P 1?;OP*P"&E<$> .](C*X?C3YX^FM*#'<(T)) M*='-HMVI4,_5^'2M9SZJV?V79W9(4<&KJAO;A(U,G M0Q>PV^SRK5:Z7$Y>LG6V#,4(T!1K@#1QSCJ-$4]]X&XF60&'IC1T&@"(PNCU MTE=PWUQAA@5[406@(48[3["D0]X_; E4P*$I/9GZF;T #FW$#RYU< 8FSGZ= M?/YI[M7DSGVIIWLRLK>,B!T0@G!@C&5$&J:53+V=]Q"W@'-8&OZ="K(S8>?. M#-BM;%:.@#2" G+FSL 4PG.1URB(%2G ; Q"45M"+U!4'0YX.WR1!OQASL:L# M\"KS.C!>,@@@<]@HSR"I4K?I;B-?R2?)@\QH5DZ6 )0"ML=?75AFW9Z]_HU^ M!]Y6>NH2#0E088T%2"**O @&M:G;2G:5-2\1AV//5ACU!%">$66W'UUZ"BH3 M!H2J% C'*,&@1AI7R1_9:"=BWB!)<03M MRY\7+CW:6E@EC"6(6,@=':>(Z@ M)2)][_260N:-N93)S=;@G1D[-QY@6NT**.:O$L"E<<&L0I(J]1.@;67,&X\I MDINMH3LW:NYXZH8[#U3%"/#40@NEUVJS)/>TU,S^8E:9U&P+W1E1\^!33,9: M((700#E4024H)29UI5LG0?,^GE4<2;N#>$9,W=_9*HZ/K: JG8*_3^RJ4LK9SS]-^-'=SXW%>F=1!3\ZS#+G& U^"SLI M'_<)VHB="F *& !W-/ YME:U_4X_)=WJU<]'_=9CGH,E*T]MQ24M.YFIUHW,"H JE8YN+ (8)4()3(#C'3G@,O4D=*6\K8]Z[G%/PIDEW MME0@G@%)]UP&Q*H 91P!R%/J.('!B$/6!19[>U,@);M =BY,W!7ZUYX J:$& MEBGIK$04)X\_-A8N[WU-J6QL#=N9\'%GN!]5,5(%@26JHHIC1D^^;9=Q0U,H M&UN#=BYDW!$V9;&SMI0>$$Z-Q$YI6J$<9,Q^)U,J&=N"=@9D/!C(UPZ&95\* M( C$SBO'*C;D \B%W\(42,ON\)T!-[?RU&TXFCE/@;0,$DTQD8*-@O67!%>Y6:CX;+3;^H.[=L8%%\)N^1"4 ,6# M(Q'6<6D=]=;2U#1K*EO)-@ MI]E63L0.-N$?("'''BFJS>;Q=]_[#6_O,JL^;^:U^>=]/0X MS3[_:Q$7>&N7K^NH<9J>02V_D* :M(].B2I#MT4(U-F;K> @ 0)B YBRSEN. MM%2I0_B')>J[%WX:_1C98+CH-<3^:K?Q_[;6VC 1A:TX0(HX6E688)PZDV6G M('FO;1-R87/7ZV_V ORH%R4N?HZV+I"A%D 8@@"26EH.G9!J,,Y$ ?)R)0&@ M^RC2VKHE4>-3'5\&V=YO8Y<%@X!&RF&NM7+*#D6.)Q$*H4=[,/?1HH-E<[O% M-P$D^E_X187?W(-V6W=:D/C@C!D%7$61J[RG%C5[*F_W^(4@WP6O.JWQ"E@8 M7IZ%_#A6L]FE7^ZQNR8%Q10HYPUPB#%%%!20I-X_]@J3-SM M_+LG%(V/*%@B@87<4EDIZFSJ=KK;4N1V5)/ 6R>U=0EL">?]>K)48/=JZ:0& M2G@/($%"6P@%3]X'=DN(O%SIB^HF27J9N ".;"ZVOXXF[FN83=L9L?'E)XX) M\$PP)BJCE$O]7,U>8?*&>P<\W/2R>@'T>N0ASC?A38OQZEP:, CKTHLG711F.[?$Y!V,V% M#8Y^)7GJ\./+Q\ORB=.PI9ME2Z+$&[['#OM;B[(20 1,054QS;&R!N/4WO ^ M6JN@H',2 8Y4%?8F1X%T+/#*>,2M#=L32=T$9%V"KDO3;#K_QV[S72SF M]_5T]#_./J4B;;T-'3=@67$(#():2BFT4(TA3%_ 1K=;K9?WQE_U>_V9/9I6D !MC%D>< 7TA#.1NJ2@N[1YO:L$'#PQ M8&7NH=LWQAOFL)\6TV"%<"(9U39I;D:3#PV2HM%:PRR9&LAR(#6IEB]X$U]Y MS38OE0K/U-BT\\4D3*'Y:+IN\>5!=_LX(S40U@A@424(DTQ0EKK'=QOYKYL7Z(CQ4OQ[L:J\ELD 3<#I]*Y>;UU3*1H_=I-#/C M.BQN[M*_E>;:C6.M45S=9LNU34=YGVL']E$;4P.T9[&U<3A05,H)C5,_[M)/ MXMY+IKEW=C$.WUY^8PO%B^DTOHBT_.:'Q]>?6:VMTW?-0"13D'BFD, M@W]BI4Q^@DXE?.[+K9-Q=FLYS@)_1E>!3$I=VIDTA* MH"JE@35:413^"MG4.8+K$N1U/[HCN8<2'YD7XX5UV8- #02$!3"KM ME=46\]3/4K/C7$!/+]VL_ET9.;.+L.-OT]&\]GUS>][G$R$@,". 4HL MY&%'00ZF+M4X*%#F@WYVOFR^N)X,O *8>.6FRU#VQ+BGN]G=:A!%@"!, 0,Q MT<)KP4UJ#NX1)?.YH33VI0"L -X=M>L^L_ZZ+YL940H41AA(HR260GE(4^>+ M]IA,ES4$V-_SFS_MHB3>P77[.*'&HVC^;_4TU_"?[MU71(T!UI9! @V M@F.A%?>IBQZ&TJ5P+R,Q)U--B90$.>N)4D\NO\>??4KQ^#H)/MIBN8Y=+N:S MN9K8T>3NR5C/2;X6(.MM3/E@0$L:'V"+?6H15!@7LW&TT*MP1ZG4"300<RCN[RJ!( 3O=8(9X6EV"-[WZH_AS6^5:DB"@B'& A5]Q M++$CR1W(TVJ8]^&?]SJK^I.I@*DVW([^Q]*>SSOZ]F.(%$AI+<"6$\(0#^M0 M\C*V$^F6]P&C=^L2]B#0NYY8ZZ[R\RG6 6]CB3$A#DAH-""5P*J" G*2O%CH M1+KE?9?IW4ZL'@0ZNU*FF\7#@YH^UO[ZYO?;H/=,F:4-AJEF.O:U80N:6NE: M9$V3L 8$RD&@H58:>X893OTP3>::IL%F]8L+>UV/Q\$KC?_1IGV]]4 P[@$B ME$,HJ>#)8P.GU? ]54<=9/_IMH?>1'K7WM>+=5XN$38"D0)(2A5@E@FO+/2\ MG+2%MLJ=Z1WN"1A^^LG8@6Z=Y^'WI^8>M87 $M106,0%6E M!':(-:J9+&(R=C@+E7<=_)[F8@^RO>LM\7"@1A(;EBAN0+"-5)(IYOCY[(@= M(GWE7?Z^ITG8@VQ]'P,N?!H&W+P;'3".$ Q(XRO@:#"-=(J(*G76]PG5.].[ MXOES\;77UVO(;F\5#7WVQ?O,%R:CEKO^I#X MLCRUSNV4D /E8[8:T5@;5WDBSF1;6T^I2S0 M&,4H&I?68NZE3/Y::BG*O]>8[CG.^"%Y^ZXW]O6 7'O#53(8CE9 80N9@\H8 MDOH%]6*4?Z_QXW.<\$/R]EU/^%70+T+"$PPD$A#QHQR!J9.I2DQ M/7[3#APJ($BL]M=:&\(1J=QI>GZ^IW3S@VQJMG"W N9\VC#_HRSNS5> MZ?7-S2]]T'Z[RI8#K3$%G%5,4\J@JD1B8K>3,&\(+2.!!P2R^S$V]DD8RL'] M.@F_=$$7-WOZY0?GZZE[\\<]/-CF@R=P43MJDL@'??G,*WGW$M+'UK4< N4T ME)(++%FC]^M;3/<#XO1=ZYZ&_K6>S9Z6[\E\-%F,)G>7X3"V!&VV;?CPB]E\ M9+;#N\&3P9(#R*V5PFF/4>HR^A[BYO5#4S%J?W-@HC:!;WSY.GGG\' =G11$T?EWTPOM7A M;R?S(%KXS-W721 O3-JM*6LLT!75 "HDF! 049/Z;FA =?(ZI@4Q?1#\BW=1 MGWNQUWXUTR\F]GES2NZRMOQ86A>VCZ:G=VFQI('ME '&J!4,5$2DOXT[% MC'HXF I@W:?59P];<^O"UQL@=? V)''(6^@00ZE7PF:2Y3T=9>+@ * 50,7V MQMSR?Q$'.CY'P"FJO-&5@BRUI])>RKS'FDP4'1C,9(>9'A?M 5ZRGPVL:A6/N9)D2Q@H5VY,&MJ']T]\%-+$ X0 M@VD%K;KDN MC@%-N05(4<@PM1JIU%?NS23+' G-P\$!0"N BNV-N?7\N*B =I4$EDK*7& 4 M0JF#2>VES!P)S4/1@<$LP*]L..MDV T<19(3Z7C01#%4G.RS]HX6"GY4!YA M"KL7GQ44GP:<*F.\3MTB>;OGPC&G<=BENEQ]OO)TL+ M@HN+ ;<(2FX$5%7R1X.;"GR_Z7"SF]_5T-'^\^#G: M=@-D.#N12H3%W%;:YEQ*RP MS^;_^*@FRJIE*YC?W*KKN8+.&@LJ:6CL>DZ!LE("9RHG1+ #8_Z8*[U[Z$*R M1]*@W=MV!>P6KZ';_[N8CF9VM'SM=%VA)94E@-;:L*-"%G942H#US'/B!,$^ M=77K4:$*N=Y)0:-A@"B 64U\ME_7'GG&V!J 7%@U.84<:"\D0"SLOA53S+O4 M%SJM!,R[<)W&_QT.L0+HV"+X^JK^FNK[#K#(!$<1)6,@I MJDA.)X&U7-9N7B7'"?EI%';5B-Q(C;<:RWH(E*;! :R00K(*YM6#.2?M1"WD M$%W\=I/9M]6"(?@5G^%Q 8$0 L&FFDN)"-6I2UD:"Y>W+7LA_!T&RG*]BU?%K@/>0<+[)\44=T!C M@\+V8F68@RAJQQ"VR$!&4G>-;BQ<(6>[M.1H2\%.2)W1:KD,@:],*#"P?AE: M9Q60"E- !$-,:H,@'2S%Z*!DA9S%\G*P/4;%$_#C?7Q-X^OD.;T\7O?,9FX^ MB\]?/.$['M=_JHEQJS@EK(!5H@)MSW'R6MKYSX0]7\;V@'0+$.AI[P@H@*A$.BV'7PYH0S>2) MR+HI6B.BBG]/HO:"L7B2+OVB"_O?B]E\^8;!\V:!0 5YF()202"X#RZ[-9PI MY1A,WKRBH6B-2"K_/4G:"\:2]OS#54(.54!7B@/K@B=/A+/&#[9D=JF>AO\N M].N!4P'%@+NCOKN,N3,@O'9D54I[(!P+1U;KJ_"KV-_:&VYT)2I(4M=9)Q*] M_&RQ-$DV.9 N8#UM8N"6210(A=V#> V,UA65C@J/3T/N5F*7F#TV,-TZ7&FE MQ/Y,Z-XT[<)( V1L(PJE)LY[JBA/G3[>1]X25^[R")X$[3-A=MM4#!P?HX'0 M 4J%=E(;X;G/P/"RTV_.A>E)T3\3QN_*R+AR4^/>IF2H*O9EK@2+;]5J8#5W M CF*"$Y]9.PI2K,RPG)-:N9V7=/2H'7M IG;4J"C2D"0DE!A5+* MD1R)9J4EZ)P+KWLB?"8K]KYLD'@97\4<$*XP!D)(#K!%UF-E9$7R]"8I*XGG M%!SJ1=M.@)[K*KR61T( 02RF?58T=B^'H$*F$@)IJ74.A[JHQ)_B>=L>RO,B M;8<4$1Y\)Q^G;C@0*X0\0,I*KP,24.:(@9Q-LM"Y.!M#<>),O)#]22=!(H P M08!3+H'&F@&.N%'2,:Y-ZAOOKK+F32@Z%Y+W1OF\UOG]"2K6!=/RRGF@F37 M<\6U@-QQ6F7R3LI).CH7,O="]TR6Y7W9*Q!HI\+6(\.,E17WP L&*VX1MLG3 M/KK(F35>L^56 S@BH5-A",,!,8:6.HD M(X03#5/7X+>3L)"BI<3-@0=$*=E"F:='NMKL%/[E[YB%/PS_HJ=HE][D^Z?L MG-[:'B=IHJX@9& M5C!6T$)QHM: 96=WELWBI# 7T5SM0'SPT]-=3;#TYW"DJQ^=NYG7YI^7?T[" M;+H??;\:J\FGT8^1#>>;YWE,8#@)&Q/FL?) *"Z!=@J>%$<,!5P9Y'V M1LA(0'$5=H)@0:",8Z#RPB%,E>[BJU( U%\ MPQG';-0*.**Q#/:G4.3(B2\ZR):%;H/47#?'_DSH?BP:XP'T+NQ^PH2CJ[8F M'&(5LA#S2JO488J_:JZ')G@2M,^$V,[16<0@-9'M74XA2"! >&R(LPQXG#JIMS)E7A/==G#S87A M>%%.U*YCFFM\9U53H'A< VQ%PJ\4 >$N;"\%[K%KO![ M,E]7423E8V3*6$C^Z#5=G@))8 <=199A#SM,SRAQM\];Q MLE:! H,5#!.0,2##U@"01)(:Y8Q$.;S@I7"%9,;U9$NWDKJVV!2P@5_\J:;V M-OSPQ<_12T1% X6- !PR!(1 %D@J#%)(0\]3EWBN"5!BQ+8^4J!AF1J3O"#J%'7O+VH%5=&,8%\/S:A4UC9,)I M?QEU^'T2&Q+=_/Z;>]"KYBY+ZUI1+9M]!K5LY0&L5,61-5+YU%DT!P7*R[S\ M?*F' J\ )K[$N%;S>JU*T%H(! SSFF)+K4$(P2IU2=": "7>6*7>H+M;O"2Z MO,RC]<>_O06*N"KXP$%Z2ZEAR0/F&R+D79QZ@+F/%ATLFY$8\;C_CYL $OTO M_*+"RU*XI@*L.) (2H"9EH111BS:""5O!S,.C%\(\EWPJM,:KX"%H>W;&,M- M,AZ3J]C6*$P4K:P"D$NH--8>4YEXV6@E8(GWR:GWH>$0.Q,Z[G8L/_\T;A8# MX<]UA<]/IBOHL0C3TEVP\H\ M:5B:'J7B>ZE\5+/[*S6ROIZ^^=,T-UV'QTY[C]5"CY/<4L6^9(( 2# %G%<> M"!/)XJ@GDBKC1.J@^BGZFT0#?WC\.K'1+UZH\=L.1!NZQT=WF0VZ,ZV I(2# M,"=%F"?0)3'Q8C&_KZ>C^>-+D G'XYZ4)+H$ MO@+*0@D@55)27&'!4X?<=DMR!@SK@/L^>G4'H4@JO8E:O=$#5G'F00&8\8J$ M*0DY'6P)VY"E$#KUP/DH=3H8/2-Y9O/OTW]\O'@6%X/@$X0Y5!$"-($JK--& M590+:\DA)VOFS'_K#Y3&OQ=L*J[&ZZ 16*M$.IVH^=G M3"1^$YG&6%/@E8N7_T("Z: -%A+,*RR)3?[R0$/1"BE,3L&A(4')>EVTF,RG MCV]F!P16(18ORQ 0,&S-2"&#C4&&>=Y@65F-^,2BU6]>"?3ZO4(:-Z7@1D)8*BQQ.'A*!+0(BZ)3&B&EJ:OTH;AC.]A_^W^%="]*"7M+(Q:P MLZP*#X\N7V&KQ%K)>)&%@63:@;!N44ME3*1-[8<>%:J0ED$I=Y.T0!3 K$:G MP+N!-K "3%-3>2BA9H.U86LD82$>S(G.U.E!*XV2J]X9%SZ,?^W\ M8F*OG7&C'\X^6S#LU39&OL($ R)6/1$#!7(24<\'ZY5V6+1"CF(#L.,0$1-! M51H#UPX0^Y4+*[ZTG@(N4#@YP,H#1#R*K6>IQZF;][02\ R6Q '8F!2VTCBY M3V+:3NVW M7JJ-2_E(Z=%X-!\ERWEI_\'$B3 ]-3Y1=LR;-&I$*J"EQ@ 2RR!EEE3#I;FE MSXYY-?CE#H/OT5DA#A2Q!! KM3>2$852UZTW$JR0!.[2IG=*H*1<;/0C@"(K4 :&V1E\AJRSM+FI>0 U-FL*CH- MCB4R]OD/GN;]ICI<:2 \JH(Z*/S+$>$/WCLDH>6Z2'D/MAFXUP.1$@D6?O$Q M_'XT_ZBFTT=?3V.Y\6QU8-K4C@@,1"4(8)X+S"577*1.36TG8=[S;)ZE+Q%> MN>LMMU1;=<^:W/WJ5/C J]N]Y=EX I23&NA*<6DIQX328T>.EM_,>Z =CEA# MFK[0]6W#5;@.4$Y_N'BTNS!FNE#CV?+?SA[0NQ(F. [: ND<$E)*(53JBXU4 MLN>]\BW"'4R/<8G<_F5:S[:U0 @()R$PWC#%N?':IBY#WBU)WOZ0&7C7WOX% MO/RRTX'X0XT73TB-Q_6?:F*V'%L)?7SF3@ NK!.T0I8G;Z+>4+1&/./GR[,A M$.K;SWF8!>PY>KYV0J= -^*"3D1CDL2 T^PIM8RZ6WJ)_M:BEADQ+@W4_8O>W=W/+_WO,_?DM&QJQH@-/J^ P&LMI?4$ M&;W1)^)X)/# ]XH,+Z:G>A$^MHJ9MCJ_6@4$C26^G$IMN=/8I&XUN5N2(J/%IUFS6H%0_"-4 M6Q%,M9:;F_C1J;9?2YN3W$O7$R@ M#VH<;U-N[IV;QSJE]>K0MTJR<.9AQ(-*4$T9)++:;!&RYZRY]Q/GD4M\#."U M\V0:Q6V_Q8T>XHD(R&WR+J M>.4E\CYU&4Y+$?.P+24K=K65&0BB ABX\Q[XU[4JIC?:8,J @L0"A&U%A(%: M5JF/AH8R&%9.<270X!EOZR+E MW1Y3HG_L,KX'% 4Q:]=Q]DF=V/^;5\ +IX*I<' F%%$ 662I(9"$67G"$$-3 M9@UVB70"9J6 H@!F=4F%"B837 &E1'!7.7&5#]ZXQJF3B%(FJPUV@S0@TX: MI@#&K=TO/%\L!/_RZ:;A9J%G(SM2T\WH2M0,QY?$?7 M6#@>2<60T:D]_N;2 MG4>.4=.CY<#H%%^5O\PT_GTR=::^F\0+_]N7YUT2E>$W^4+:&%=KG4X?UV+Q M-5A<*0 5DY2)RF%S!G&MYZ'7'V6Y]'N,_?FG&2]LF$E/+P7-KMPT6#].K=OZ M\T_U$+:+^./7;KZ83F;7]7C\Y6FUW_)3J]BJE7! (!(.&H(X3ETE/;1.9Q.2 M.\C-[==>"V)"$;O\3OVWU* TG+DX!$)R2+EES'.5?$O?*4I>'I;%ERTGH#]X MG3GXW4U'=6QL-IT/R<2P$$QC*>;LVLT6XUB9^26 ]'$QC>A=+64(/_T<[-P. M;6H+-%$0$..-]B[>)J8.WJ21/*^?>HX\'Y(:Y2[-N[6^"MI.C^N,XY.BQE& M!*%$4^Y@\@S\%'+G#1:\G\F0@A;E3H5/KH?.T(1S,#,<"$2HME Y*DXT%5K) MG3?%]1RGPG"T*">3L97J;YX@_=MH?A]^/B*U:D2_(T3D8%@.?.6!IK[,ZR9IWM3BV<78U?[YXNL\)\L_^;)+/7D9:PPQ-]<+,ES]N*'FP:ORGU;Q)=N M:O]I-%Y$"U[5\S#P2(V?OG4SK\T_>]P,E:A&@NNG$M4:XH[K6>:KE7%_K]N=F&*M\K( H5)<-$XT@I2R"1*[=NL M"9 W7I\$[\TUO+N!"_"!W\Y(=;>:D)=^:9W9Y6(^FX=I&TSV0OU&/\X8OI5$WNGHZBFSI7.KXKH12(=8#8:&:)2'T9V5_J MO"'L09AZ8BC+73R7WHRS6U-TRVVG879JA@'DQDCFK-4J=9OHEB+F#2>?<@%- M E*9Q:!Q]HWFRYD8O?9)C-^Y< 3N]13-\4$3G#M:2I[H%/#ZU=@(=_VS1_.+ ME.! *2R =!)KJK37+'4GJ%8"#D"H&W<7/W[MOM?3^.D4-<1'QTQ IW9R)V+3 MYD?7B(,)) I8@$W4@+MK +26"&-T4*PU+T6]\G2N^AS8]Q7%E[ZSX&=\\?9 MT]_%37_UP[-M0QC$".#2!T-P@P&N.'2\0AI6J0_7O03.>V9-PJ>MDM"3 5B MF_:\Y6]K]*P)!:BJ9#@OA7U>P(H"2ZH*:DPIJW!B*NZ7IBR>#4B)S0!*&GS* M#'1OFO7KQ-?3A^6@^G'UEPFWT4/##["C-M;F%)OKV[ ;)4 +9($5RE>86;S.'@;*$@8I0C3W!3MK48=T.8I:UP'7BSM9& M.C!8&;?/V70>3AZ363T>V:4:RV+(71TB'/% (2:!(:J2//RE@8TR@L(GWE M M_.Z59ON_GIE%0P->)[5^I$@' Q?@H[^\K/7L^OWFHE.X%?GC.OB5F *L#4928B5)ZN#^'E%* MHDP7C.OT!B^ -R^]C3XL9J.)F\U>3B8[9A4C-.SL%0.8LV"HBE9&I:Y3/2A0 MWOO)4VU=Z;$I@6BKP\W.F2?#2BVEE:$R"S#Y0.V-UQJ0Y6 MSOU,Y^^34;Q.BI;9LY12B( V%01,$:EXQ5C3YSBWQR[B)-4%I3J=R7(C_E%- ME%6[!6?( >V= 4X;):R "&]V^MR#]=M1,V\7:5#N;*;<^"Y;F7^=A-$F2YNK M\6XEA$) :62 I1@SB 5!$C;">M\7\B:'),(]B?G*V?AW^4J_[NT0Y:,G[ARH MF(360(>%'#K\N$NNS$0ZM;^9&JD"V'?M?KC)PBU+U^O),EX9:Z\^+F;S^L%- M7ZL69K/@ARV+")8J*A/F*&5$ .Z9 0+Q"CC!6'SM4D&2OMU,:S&+<&$2VU9--H= M<4T"): 2D'*.TK<0;R19$7[;<$0; )X"2/<2"-U?Q(&I#UZ(LP#' :6)';$ M'BKJW+)69K!DW,'IU-?P1=0OK$XY48'M7A$"J$I482/GW$EL8EUF:M:\?CYO MEX/AV=+1T 6L,*_\7J^%N%I:=NO((QD0R];[5A -93CT#%&_1)9^$#ITT[V]3HQ(EG2%(@),6@0L@:M[R$3>TJ%)QXIF&8 M+94C07VOG?/&N\W'G_Y*/.O$G0$2SPZ"55SBT*Z[1>TY$,*%7QGF/+(4<_97 MXEE'P%LGGAVT?G'\V7V?H3D!DE0"$(DJ(JUFE#0J/GFGB6>',>V0>';0P 4X MYPWSH(CC0*O* 8V91M1AR=U@(8!S2SP[C'&WQ+.#!B^ -ZUR8(3R0#G, ?+< M>&VT52QU;Z[WG7C6:.M*CTT)1#MT'2^P!EHC!PS73AI&+>?),QK/-/'L,+!M M$L\.6CEWFLKQ+*J*0""9C:U@A',\_ TB&T]>OH?$L\,HM4L\.VBRW(@?RJ@2 M7@*)'04L=IV26'-MCL9SSBGQK#G*G#0O13>9>)9.W\S-5(%L.^3"U\V M3TUSPZ_';@G>Q%X\1!W_9_GGFSIY6\7@006TM$S&$GWFT[]8>URN(IR4A&S8 M>KPV,30%T&UEM&4.B1W-8S\C:Y=O,-S6O]:3NU]'/YQ]>@1Z:V> " C*-7"N MDHQ"%-;RU!V86HA7A.\T'/F& JH #EY-Z^]N.G^\&JO)/,RGV.KX>U1VQUOC MT(>I1)D&4CLO@OO 494ZN>.0/$5X:L.Q+!D4!=!J]V1P'@=_UC/@!>=(6RXL M29T2VV)!*BN-K U5.IBWS+:-!Y,/0[4+VO6-H9,WCNIUXOP- M6$$@B1+ 8&X9Y9Y1G7I='SY_X_.R7]??1M:],?:;BH3//Y>GX_%S-<+LPV-8 M<>W"S-^FD.\\&%7Q87KG$:!."RPXXXXG3W 90I&R#@6=^+<_!R07X)EO^5 ?(E!/3'=)L@/0V<.UC_I:ZM"AHL)G8ZVG>= MY+D'DG(.$/+0$(*D@N-!#H/4R6&^TOP?+W4?@]+2VT#DR-2;R04>$LK&S#+B\; M ^>)\ PUR7L8+3?@R_O$/6D"W@"UO"H2C@E/G;>H&=AO!LT3GQD(Z*[&*B!. MM[+&;N%UY8&*#:U)$)P[%)P:FCJ#;TV /.5\Z5G1W[I%U'FV/5'MC6TZY("2 MR@$"G2..:,MLZM>S.PM;2IIH[O/K:5$O8.WKVJWDK8O.%-"<.Z"-AY6V,IHZ M,;'/KLW,B0B4J/=,4S3SE[TNQYXY\Q]W]8__=,8^#7\1WV.^'3VLO5YQ_)ID MC99O!WUB9#B'O!!Q]Q=:7I)T%K[G74CXU#^>OO*P_,3KLM_5'/M'[+@>O1WP MM\GW41ST-JC](?SE/Y.(N3UJE@7B*!;/<[J113+N(&ORN?E];1/CM3%F%@^E M&UJ[K5$(5E?AL_/IP\1^&:N[)$BMCY@E>M$)IYV6* 2E..,_3F9VF@ZFC2&S M!!\ZKW[;MB@$J/]3__DJ7]H5<,_06>(#G8 [;)O, +[LJ:,'9[_4TX_UP_<_ MU+CW=#LT;I;^.JV@:V"5$B;>[&-PD]UM_2+NLI-/NMEW9/PF./+\4["9E8K% MVWLO(?E1K/HH%$* .OF/BC[ M0-9K86,?P33VX50)76LP' M$3%KV'PW&3:S7P=$I@#B?7[X/JX?G;N9!R?M\GO4[>A2WNFR<.]W\B:S#HGN MYC7?,5,70(>E;!??7RL_KT=W]_/9S<7US2"T./Z]O'?%)Z1'8]/G]OMV;;K! M$8H:IC]$/0_!&P \T]J[KZHT?0/ M-5XD@&;'F(TP*N >3NRO3;]D[,G0CZ/)>338S M3JEI.)^GR_N"@5)PMD=/DGYS1.@$J3?7SM0_W/3QTF]]:XL,G7C?Z ,]INQJ MU.?/] _.[QPP6URQ#3YO)^LALV1>9*_=[+EC9MP#>@?I=XV7#:^#=J\;&>'? M^OID$.^D*2A_79S\=7'2"IMO]>2;JU. LCY2OHO&0[:NCRA>T+[BPI /HZ=6 MFW%]3;;!; V<;5'KZADT,5/N)>_N;KY2JG>T:7VH; F@7=':;8K,^#P+-%'C MQ]EHEB:W:>^@V9)!>_K>>\V3&;V;^3^OIN9R>CN;?I[-1T_E/RFSY!M](%NF M:%=4VY@M,\*7BWE8XR?+:JIT2^G^4;.ECG;%\JB!RMD O]7SO[N7G=JE2N-N M\H%LF:0)-LNC9LN,\).OZL\A ML#_XL7P7YRD9T,2>!=(@:/ROA1J/_,BLI+]5/S^XB?.C>>]DB4X?S'=5GY(. M3>U:%B7",C96DY7 7Q^^QS8'00$]&H_FCVE\MVY?S)<;D(@4[2Q;S@DLI8MW M8-A\"00)#F%E^GH[!$Q\CMXUSWTA]-.9Q7STPSV_FM$[=63WB/E@ MVK1WW5#YW('D\7A3O->&W;T"R(<&SI=]=1"*NIU=,D-WY>H$.+V.DC.GY+BM MZP.*YT_R"2)]2P+'YECY:J%;@K+'"'_E*IYRI_DK/_&O_,1VV-C_OJV7Y_&^ MTV-]I&QI5(=FQTYEZZB>ZY0;F[FR^KEB:SR1\J M3-Z;QGKQ?:S'?Y^FP*SUUW)Z:OL0JQ.8KP#8H\Q!Q=G- M#_-Q-D^$[LY!/EZ[#<:-D[8()2P!G8'6GSG7QQO ,P M[4+S;'R0-<7BDQ=WP8.Z_CZ=VVT54L_09I_+5Z39$O/6%LP,_=^GGR?V2VQW M<>E?E/AE.HF"?_PQM7^?QKMT.[F[F-C?)S]F] C_/4+ M[1/0I/W7LCF%:>C1V;SEK"(7LTN_4N/2+QG\HD9B=G3^:+8RS^1K2"=CYTYC M?A;\2=Z)W=XWGQ:^+V.[U.UC/;&S3]/PBU3,221"ML+2-#Q*"T1F5GWZ8>WL M%2>[1\QW_]\-KX-VR9U>%D2Q+[E8E]Z/3!CWRR3-7#L^>KXE ML!N6C>V5>\UT;OK+M%Y\_SJ;+1(B>FC<;+YOUW7TN(URKZCWL7>_?1$T%8J' MQLWF<79=78_;*/M/UZID4T$ MU*XAL_5#Z8[7 *NL?.U%TF Y0%CE;"4OHB:?$'=.W*^ MQB!]UM5CALJ>Y[,8S1_CTR9/I@S'FX?E$VZ?1CX(XX*VJ=!M^:E\?4(ZPMW- ME+F/C1O+S!^SY2:R?/SMOAX'*U_/4YTDVWTJ7XN1SK&[+J8L#O]O;OYU8NJ' M1#'T1A_(UVDD&=;[S58-6] M?]1&<)84SCIJH-P ;J\L?2,A>X9LE*U04C#KL&FR1_Z?%__T !X;NQ&2)86R M&AHK^[:YX<+UQ7'G@(W *RF2<<@LN5N=QITY:I0(L%WC-<*KI,C# :.4$"M. M\CS6VX$: 512N&"7&;+O9G7OG+OG,1KA4=)A?D/Y,O*%>\/1-O$1EW3>+C#? ML9[\HM3WE6"?W,Q,1\MX?J*$Q^/#-P*QI)-T.4VL;^ZV0V"L:\G:KE$X;3:4S C>WY-PJ&>O:T/_"9) WN MFZJ1H-O]UJ>V:-&Q:^S>8?N$,E^&^Q"?1.G?YW[G@!E;JA[#8BUX>< 8N4/. M+Z+U+DK<&"H;-@>MO1.5@LH4+\;C'6M)FKZK^PNUH;)55'<$9#[;AABE@ EW+%:@HU3[$(K@V7 MK32ZRT*XRQ %+8:WTX?)/.U:^&;(;$71W9?";8.4M1(F FS_J-GJH7NM@\7! M]GQ@F#Z,GEX73[02;HZ8KP2ZRVJXQQY%8/7YY_?1-"54&P/F*W#N@M1N:Q0! MU*?%DV )('H9*E^YR@;<[C.OBJ'H],4.!J6IL!KX/7/C/ =?!^-9)?![_]U!9'$MP+[QZ_UZ7) M:GC[=NA49^_CHQ=R=7P0M_6;EH;VRGX9MDO.;_5\)6J:>'_SKQ02_N^)\P'[ M#;^BK_XB_I]6,_>__]?_!U!+ P04 " "C"4==?U[#(Q,3$P:S@S,#(V+FAT;>V;7U/;.!# W^]3Z')STY?$L4-2( 1F MTI1.4UI@"AQS3S>R+3M[*%)&D@GFT]]:CH_0D$*@ 4*78;K7">&20+A;@8;K1;['PD;+ MBYI1,]CRFLWM9L-['[2VW ;U__$J*(K=12M?]P[6\;BN>MP]VS^3;2!*%W2=)IW3N=TP$@D.9?CS,U!$THX M:$-D1'3B:PB!*F ZNS;8M2>'(RI20NTOW21&D\F&6[5Q4"5R",9DBF[)C@<0 M#*HDD )_8PJ#"H351N-8L1C#K$K&,N$A$=+8;A@SB<%VHI$+1!#0C$>A,W7N M(&VHSUG!S)<*!ZHA.DY'FK6++SLAZ!&G:1N$16&%=FX'00NY73)E<% ^61B[ M1GGS)-:VMYU-MY&%F\&U-6$Q\"02'1N)=1/.MFTTG=:F-[?9=1[;MM5L/DKR M9\8V6LZ&M[DBQB+9S<;#U-;MJJFB0Q$1N/05*XC^HM'/=RM>JU)T&M$P1-=N MN\2SW193M/%S/:O4=3+G^V0\!REDJ' M*OE+V3V8@Y&CYX=@,/L2J<@1YF-%OB0*= B! 2FR!-\7@50CJ6C^ W93,15P M;:_7%MHA'3*2"*PPY#PK;>1_5TIQ_X@%[T.V:63Z+K>Z)WA\&ES$2J+RVF0* M0%3(OD'!H]R MN]7BF&$#*L@GAD%">>$CZV^JT'C\)Q\9^0KX$TX"U]'YE\-<*CB M6HI74BQ7 ]E]OK86M:\O=**H"!CIQDP$Z9.WL6N7P,\I[J!$;!:XFRRI+>Q^ M;[OL'2L(LI/I"1/#E+#G$Y2_IMO*U6!YR"YQ_U026ZKWK45MO-F3'TC%YF_) MRR0_AZ/%5@);FN.][:(X ^,+Q0D^.0K7+KU;;"6PI3G>6M3",#LNOH) 5LF) MTW6RZY[S5UD-%R"9\RN)+='WUJP@GAV41Z6+8SP3&3%R@):&#\] L0(ZDA.W1M*\:I@4LV\TK$S9/A]B%O M]T:$^EKRQ,R*W/,6Q>1O_D)'W;Y(\A]02P,$% @ HPE'74UR"*+O @ M^ @ !4 !C;W-T97@R,S$Q,&LX,S R-BYH=&W-5EMOTS 4?N=7F$XPD)HN MB9,XS;I)TV (,6!B#WU$CN,T9JD=V6ZW\NLYSH6ML,)>J,A#=)QS^\[G<^S, M*KNL3V<5I\7IL]ESST-O%%LMN;2(:4XM+]#*"+E \X*;&^1YO=6Y:C9:+"J+ M0C],T%SI&[&FG=X*6_/3(<[LJ%O/CMHDLUP5F]-9(=9(%"LCS'/HMP MA*52(7P#:>!-O(=V+V)^$V:@:[P?5>89\K:5POJ1*]EP5O M.+Q@^84OA $LT%U7J[P6#)TQIE;2NDZ[$'KYQ!(=BMU[^@=F@FUFOJV,%>7F M'U$3/4K-G"/6LV,5LA5'0C*E&Z6I%4JB?(,T+X$CR9RJM= M;[V!L3">;L(, M>O5)F0G"&'MI2-)PW(J0)@[Q($\#,GS',2AZ.?;](!KD@$1I+R=Q'/N]G/I! M,L1)213T-F[P"1[DB.!I+PQGX8#S9Q@*?)&%%9=&N2)&'T&D$I%THO MT;67MKK=A;HZNS+#:1(EZ4-?['I,K32X H7 2=$>7I^953G7"/(ZO&-T*VP% M-J;A["?Q;A]4+3J/4D@J&6SO0X(A]KDREBDTKU3-#:TY?+C?K $W+TN(*]9< M^7!Q$Y-NT;?;CZ^ Y=7E[] M#:P[IQ\4N!^@UW#-P04U1G-J*M@)J^1_2^HO[?Q$G G$;FA10'%>S4N;A62" MXT>/P.Z3:(_IS(,KA#RQW7J8Q-TYC3+"C46F>4W=-.R\GP4\LMR96L^^OO&7+UL"6E2I/*,K &+&N7KR'G\,P, M.?!%ZH;J\B(5/+[\U\6_ZW7VG8Z*H<@L7B]K7>M\ M8N0@=:S=;!^SC]K+0S_(15_'D\N+6(Z8C-_LR=.H MTQ;'2=*.NL='[>[I*8_[<;<;)]U(G"3=Y(_6'IJB>FACW42)-WM#F=530>/W MCMJ-DV[NSLK7EXD.G,8SZ!]^!JZ6>K,B0=7YTH.LIZ?TEYH M.BV.M-*F]ZKI?\ZII)[PH523WK=71G+U;ET0.,(*"[-5B:]O M[C[+12PML:N],9^[G!?N-1:J2ML4@8)Y,)NK/5N;4.II)O:\S'2] ^:;1: M-.=;EO*18$:,I!B#)EPJ+;O*LH(K=B=R;1R##MYJ,V2M9OU'IA.0AG619A]3 MK83E2N"%047N)&KNOWYUVFXWSUU*G0ZD=89GSK]LG1] 9V/9A!69,X6 X# (WC9 F9P- M\42"LH1'>&68'H+(G [UEBID(A+6M:GQ;L8PF!(Y0T+QJ * MD30P)*B6H3DDB85AXU1&*;,%?Q62B760(."1PA MLT@5,?H$2!:T50/ I%$3ED/'!$^"K5)S_)6JMT^&!L1C21W7J$:A4 &@TT"& M'\YZ>2)N4Y8H/;931,[9B7%Z&>2&E+4%8-FI,$O2OFAL'>T*MCXLF8G6R;DM MT5-:>]KZ.DDD'O?M@=?2+>-&>#Q O[(/&P2],0$0]I6T*;6@:D,P'[$?/ @%@!64/;-0Y3R;"#8%>CFKH"Q8ZT.K[>Z M^R)(T>K&X2D\2O+AL@!(ZI\1)RW@-."&9-EXH.310 D&HGD^12]JD!'_^P[1 M2?O9$IU C%/:1*B+E! M1HM@WA>]$GSK"ZH(4D5[$?]]$MT!R/9W$[(;T] 2-2QM(X\Q#Y^P QY577 CO4%X*">4 M%XA0+'8>N111I$WL!? .Y4!D\!044(P2D=/VH"IPE@-2L8UD#DY^T5B-GANK MIXUVA^9\,^*J\!Q$BA1) H=.CJ "N\(QF_D#&W!J>%SMJWEHHB'XT :/L*\+ MMUZ"35B?SVH+3OXY&6'_J2/O=)L)*0!Z/+!K@I:(K?FYTS9@P*&X9 !3^ MEDZ6+UF)LL_@/S+(.HH*0VI>L'XK>AUJZ_">COC0EXW0T9\%C">ZWE_3) %> MP4Q/:I>"(Y(1/G*GH-Z?TP2Y#H)4*;-;Q)[L_7J41#Q!?'XO5!G& M/ZE?^^(E^C),[T"(U'WQ(9(_V(NG.Z(VIQ]BPT54SIF(R#^R"6BU1-_Z2^SO=<.+/0D)\ MO[F*+/(!_T$5"7T-,KU2<*C@X$G@BN),BE@C*8""TMS.(I*QX/=D/X.#Y2VH M=PW]:>+T'.:SL%4&#R'*7\%8/$9#*V:$M1:'I4.))@ 3_+Y:,.(6%MP60T ! MJ^0G4QJ*E2=6+]Y [TRH<@4[G!B000T:%I["@!%_SEN"J1;,F,Q&6HT$V;*, M#\KC:E.RGACF2D\$2L>I#CS''T$5T/HJAKZQI/"U]Y&[<6?V'H39QUR.:_Y& M=XWX&\CR00ZQO._$F-UIJ !2/1'H;"-Y7K]J'3=G5.Q\ %@.WL=N%*8.&13/ MK>A-OYS#9.6*3WHR\_WY1N?EFO:U13;0FTSH.0(V])_LKNOR%2G&XW^_MU6R=&/Z6^UMS[3J^L?[FZ?W/5/H?@) ME#69=T0W0F:YJXG[")7^R)%-I[,I;$L,+FUQG6\5EH^S#V;+]G47;/?6Q/?3 MDPX#1!NLTB\&OA[Y-=Z-NDZE2-C-@X@*.E5A[T-4\D6+=^A-P&<:X2=Y1;FV M_HZP%T[,1V(ITVB.8&]BFO,FO \8%VY]DW69/&O3EL)G:N9S'XAZ'Y[N?9TG M:-_C:LPG=F\KV5)5\M'JY*/O*;N^H?;7ZKTHPV5]"3_H,H_6KU,LURCP/:_(0P)WU8D)H6"MU-3&QZK M%*7U*4J'X?\\'?K_+_5_4$L#!!0 ( *,)1UTP0Z2BC 4 /8G 5 M8V]S=&5X,S(Q,3!K.#,P,C8N:'1M[5KK;]I($/]^?\4>T;6)A(UMWH]&X@AI MT;4E MI>/YW6]AKOU7A]N^LDW%]_L[M R(,*M2E)3T9*9'8\[_'X-R-ZL5PD MI[V8X/#TE]ZOEH7.6) O2"I1P F6)$2YH.DQ1)[C M-= GQK_02VSHDLJ$G*[E]"KF>Z^BE?1\%BY/>R&]1#1\5:)5^-3:M6;H.^U: MN^GY]2!TO: 5NFW2<%K!7VX)6.%VPR/D,B&O2@N:6C%1^CLUSV[6,]F]HJ&, M.Z[C_%;2MY[V(I9*T,>!WUP:,?>$27(M+9S0>=K1+I4,ZYHE@5.A24(IY$A"_HO 4O */WURAC:!.Z$IF1MN.LI4X?7 M,?6I1%7/=F_;N>TNYG/P6+*LTP:I6P8'$&'"#VKQ8#B9C,+Y#K6'^@B'$M<$DP1R0-H9?U\SDXBJJ0?M6WR@@+%-$$ M*!OU4Q+DG$I*!,)IB(;708S3N=:QH$)L=!K[3LIH5$83.'QGHX\XB#D5973! MB:"A:J)*Q""F) )!(%C22X+&440#PI5K6\:7$9RI')11EG.18^"6#&U5KPG4 MBR.WX71-"8/U.&29ZM+;/+?N5!6STC3%W,%7%E(&.Y8NC M>JN[3_$T(+\9#D-X,5@)B2#!]0?+R1S15(6B8WG-[$?UUH<+[-@]67MS**6W MP^+6[&9+.3W;% R*\B190N$OLD35V*;N./DGIYRH5Z90:;F3[F,,U4_YH"@UE8;H.]"V)@36$4R2W MDHLIA^QF\/RK/)85&2<) C:B3(,LBPP2*\J:*Z(I3@-U#@)#JD6KC@%WY8DI M Y81T^G$G7YAKT,CL0\]<14;G_&0< M"E.!,D,[ZHAM2D25XV:&I=EDS=5?Y M]YF4;-%1";]4/2C R>HYUODWY!7 :KNVTW(5QI( K&2X5KR"7[:&7Q49WJ>!(?<>SHTLGYQ5&MVA?Z/)H_X<+;VT@X MZ* -02M5+_:#>]H?O)F,IG<&EU4E_J@B>P3YIB)W:CACTJCP5+:(C6%G]?2$#F0>-Q&Z'>"L+35-3.V&X"ZRA5 MC]QD#Y8,+:=#)2@(]DC/7@/#,\C:[MQ4-*)X]C-G'PE0#;B-<0IF ?+2J(H" M$ ,CS%8J/U<4()VO(/L*!/K+KP^IBBG* M>4I%;*3L.6@"X*< \&D*$)Y!B=J2B!"VCLA_9VM6,:$AI4=3A*LBNG>GNSF M@=0@T+EAP3X\E;GBM)!=GW% MZJQ8G16KLZ=>G;W&?(G>04,E/(AI5MYZ[7V$E]Z#J[3SS=A'7S!-/C_%+NW@?H[>OAU.!F]&%\4NK=BE/4X\[D#69["6 M*99IV_G93! &\*DQPES=FB7,D1XHS.5FJC!?BZ5;L73['RW=*N9W=Q7]>[__ M %!+ 0(4 Q0 ( *,)1UW3+7GG>=4! &,Y%@ 1 " 0 M !C;W-T+3(P,C8P.#,P+FAT;5!+ 0(4 Q0 ( *,)1UUW%=P'CQ ,*\ M 1 " :C5 0!C;W-T+3(P,C8P.#,P+GAS9%!+ 0(4 Q0 M ( *,)1UW.6E2001\ '=\ 0 5 " 6;F 0!C;W-T+3(P M,C8P.#,P7V-A;"YX;6Q02P$"% ,4 " "C"4==>;3/4]<\ L#@, %0 M @ ':!0( 8V]S="TR,#(V,#@S,%]D968N>&UL4$L! A0#% M @ HPE'7>2RAY8[ $ -WX! !0 ( !Y$(" &-O#(S,3$P M:S@S,#(V+FAT;5!+ 0(4 Q0 ( *,)1UT]+@1PEP@ &9* 5 M " 5[H! !C;W-T97@S,3$Q,&LX,S R-BYH=&U02P$"% ,4 " "C M"4==,$.DHHP% #V)P %0 @ $H\00 8V]S=&5X,S(Q,3!K ?.#,P,C8N:'1M4$L%!@ + L V ( .?V! $! end XML 95 cost-20260830_htm.xml IDEA: XBRL DOCUMENT 0000909832 2025-09-01 2026-08-30 0000909832 2026-02-15 0000909832 2026-09-29 0000909832 us-gaap:ProductMember 2025-09-01 2026-08-30 0000909832 us-gaap:ProductMember 2024-09-02 2025-08-31 0000909832 us-gaap:ProductMember 2023-09-04 2024-09-01 0000909832 us-gaap:MembershipMember 2025-09-01 2026-08-30 0000909832 us-gaap:MembershipMember 2024-09-02 2025-08-31 0000909832 us-gaap:MembershipMember 2023-09-04 2024-09-01 0000909832 2024-09-02 2025-08-31 0000909832 2023-09-04 2024-09-01 0000909832 2026-08-30 0000909832 2025-08-31 0000909832 us-gaap:CommonStockMember 2023-09-03 0000909832 us-gaap:AdditionalPaidInCapitalMember 2023-09-03 0000909832 us-gaap:AccumulatedOtherComprehensiveIncomeMember 2023-09-03 0000909832 us-gaap:RetainedEarningsMember 2023-09-03 0000909832 2023-09-03 0000909832 us-gaap:RetainedEarningsMember 2023-09-04 2024-09-01 0000909832 us-gaap:AccumulatedOtherComprehensiveIncomeMember 2023-09-04 2024-09-01 0000909832 us-gaap:AdditionalPaidInCapitalMember 2023-09-04 2024-09-01 0000909832 us-gaap:CommonStockMember 2023-09-04 2024-09-01 0000909832 us-gaap:CommonStockMember 2024-09-01 0000909832 us-gaap:AdditionalPaidInCapitalMember 2024-09-01 0000909832 us-gaap:AccumulatedOtherComprehensiveIncomeMember 2024-09-01 0000909832 us-gaap:RetainedEarningsMember 2024-09-01 0000909832 2024-09-01 0000909832 us-gaap:RetainedEarningsMember 2024-09-02 2025-08-31 0000909832 us-gaap:AccumulatedOtherComprehensiveIncomeMember 2024-09-02 2025-08-31 0000909832 us-gaap:AdditionalPaidInCapitalMember 2024-09-02 2025-08-31 0000909832 us-gaap:CommonStockMember 2024-09-02 2025-08-31 0000909832 us-gaap:CommonStockMember 2025-08-31 0000909832 us-gaap:AdditionalPaidInCapitalMember 2025-08-31 0000909832 us-gaap:AccumulatedOtherComprehensiveIncomeMember 2025-08-31 0000909832 us-gaap:RetainedEarningsMember 2025-08-31 0000909832 us-gaap:RetainedEarningsMember 2025-09-01 2026-08-30 0000909832 us-gaap:AccumulatedOtherComprehensiveIncomeMember 2025-09-01 2026-08-30 0000909832 us-gaap:AdditionalPaidInCapitalMember 2025-09-01 2026-08-30 0000909832 us-gaap:CommonStockMember 2025-09-01 2026-08-30 0000909832 us-gaap:CommonStockMember 2026-08-30 0000909832 us-gaap:AdditionalPaidInCapitalMember 2026-08-30 0000909832 us-gaap:AccumulatedOtherComprehensiveIncomeMember 2026-08-30 0000909832 us-gaap:RetainedEarningsMember 2026-08-30 0000909832 country:US 2026-08-30 0000909832 country:CA 2026-08-30 0000909832 country:MX 2026-08-30 0000909832 country:JP 2026-08-30 0000909832 country:GB 2026-08-30 0000909832 country:KR 2026-08-30 0000909832 country:AU 2026-08-30 0000909832 country:TW 2026-08-30 0000909832 country:CN 2026-08-30 0000909832 country:ES 2026-08-30 0000909832 country:FR 2026-08-30 0000909832 country:SE 2026-08-30 0000909832 country:IS 2026-08-30 0000909832 country:US 2025-08-31 0000909832 country:CA 2025-08-31 0000909832 cost:OtherInternationalMember 2026-08-30 0000909832 cost:OtherInternationalMember 2025-08-31 0000909832 srt:MinimumMember us-gaap:BuildingAndBuildingImprovementsMember 2026-08-30 0000909832 srt:MaximumMember us-gaap:BuildingAndBuildingImprovementsMember 2026-08-30 0000909832 srt:MinimumMember us-gaap:FurnitureAndFixturesMember 2026-08-30 0000909832 srt:MaximumMember us-gaap:FurnitureAndFixturesMember 2026-08-30 0000909832 us-gaap:OperatingSegmentsMember country:US 2026-08-30 0000909832 us-gaap:OperatingSegmentsMember country:CA 2026-08-30 0000909832 us-gaap:OperatingSegmentsMember cost:OtherInternationalMember 2026-08-30 0000909832 us-gaap:ForeignExchangeForwardMember 2026-08-30 0000909832 us-gaap:ForeignExchangeForwardMember 2025-08-31 0000909832 srt:MaximumMember 2025-09-01 2026-08-30 0000909832 cost:EmployeesMember 2025-09-01 2026-08-30 0000909832 srt:MinimumMember 2025-09-01 2026-08-30 0000909832 country:NZ 2026-08-30 0000909832 us-gaap:OperatingSegmentsMember country:US 2024-09-01 0000909832 us-gaap:OperatingSegmentsMember country:CA 2024-09-01 0000909832 us-gaap:OperatingSegmentsMember cost:OtherInternationalMember 2024-09-01 0000909832 us-gaap:OperatingSegmentsMember country:US 2025-08-31 0000909832 us-gaap:OperatingSegmentsMember country:CA 2025-08-31 0000909832 us-gaap:OperatingSegmentsMember cost:OtherInternationalMember 2025-08-31 0000909832 us-gaap:USGovernmentAgenciesDebtSecuritiesMember 2026-08-30 0000909832 us-gaap:CertificatesOfDepositMember 2026-08-30 0000909832 us-gaap:USGovernmentAgenciesDebtSecuritiesMember 2025-08-31 0000909832 us-gaap:CertificatesOfDepositMember 2025-08-31 0000909832 us-gaap:FairValueInputsLevel2Member us-gaap:FairValueMeasurementsRecurringMember us-gaap:USGovernmentAgenciesDebtSecuritiesMember 2026-08-30 0000909832 us-gaap:FairValueInputsLevel2Member us-gaap:FairValueMeasurementsRecurringMember us-gaap:USGovernmentAgenciesDebtSecuritiesMember 2025-08-31 0000909832 us-gaap:FairValueInputsLevel2Member us-gaap:FairValueMeasurementsRecurringMember us-gaap:ForeignExchangeForwardMember 2026-08-30 0000909832 us-gaap:FairValueInputsLevel2Member us-gaap:FairValueMeasurementsRecurringMember us-gaap:ForeignExchangeForwardMember 2025-08-31 0000909832 us-gaap:FairValueInputsLevel2Member us-gaap:FairValueMeasurementsRecurringMember 2026-08-30 0000909832 us-gaap:FairValueInputsLevel2Member us-gaap:FairValueMeasurementsRecurringMember 2025-08-31 0000909832 srt:MinimumMember 2026-08-30 0000909832 srt:MaximumMember 2026-08-30 0000909832 cost:SeniorNotesZeroPointSixThreePercentDueMarchTwentyTwentySixMember 2025-09-01 2026-08-30 0000909832 cost:SeniorNotesZeroPointSevenNineZeroPercentDueMayTwentyTwentyFiveMember 2024-09-02 2025-08-31 0000909832 cost:SeniorNotesZeroPointNineTwoPercentDueJulyTwentyTwentyFourMember 2023-09-04 2024-09-01 0000909832 cost:SeniorNotesTwoPointSevenFivePercentDueMayEighteenTwentyTwentyFourMemberMember 2023-09-04 2024-09-01 0000909832 cost:SeniorNotesTwoPointSevenFivePercentDueMayEighteenTwentyTwentyFourMemberMember 2025-08-31 0000909832 cost:SeniorNotesThreePercentDueMayEighteenTwentyTwentySevenMemberMember 2026-08-30 0000909832 cost:SeniorNotesThreePercentDueMayEighteenTwentyTwentySevenMemberMember 2025-08-31 0000909832 cost:SeniorNotesOnePointThreeSevenFivePercentDueJuneTwentyTwentySevenMember 2026-08-30 0000909832 cost:SeniorNotesOnePointThreeSevenFivePercentDueJuneTwentyTwentySevenMember 2025-08-31 0000909832 cost:SeniorNotesOnePointSixZeroPercentDueAprilTwentyThirtyMember 2026-08-30 0000909832 cost:SeniorNotesOnePointSixZeroPercentDueAprilTwentyThirtyMember 2025-08-31 0000909832 cost:SeniorNotesOnePointSevenFivePercentDueAprilTwentyThirtyTwoMember 2026-08-30 0000909832 cost:SeniorNotesOnePointSevenFivePercentDueAprilTwentyThirtyTwoMember 2025-08-31 0000909832 cost:OtherLongTermDebtMember 2026-08-30 0000909832 cost:OtherLongTermDebtMember 2025-08-31 0000909832 cost:S2024Q2DividendsMember 2023-09-04 2024-09-01 0000909832 cost:S2024Q2DividendsMember us-gaap:CommonStockMember 2023-09-04 2024-09-01 0000909832 2026-05-11 2026-08-30 0000909832 srt:MaximumMember us-gaap:RestrictedStockUnitsRSUMember 2026-08-30 0000909832 us-gaap:RestrictedStockUnitsRSUMember 2026-08-30 0000909832 us-gaap:PerformanceSharesMember 2026-08-30 0000909832 us-gaap:PerformanceSharesMember 2025-09-01 2026-08-30 0000909832 us-gaap:RestrictedStockUnitsRSUMember 2025-09-01 2026-08-30 0000909832 country:CA 2025-09-01 2026-08-30 0000909832 cost:CanadaOtherMember 2025-09-01 2026-08-30 0000909832 us-gaap:ForeignTaxJurisdictionOtherMember 2025-09-01 2026-08-30 0000909832 us-gaap:RestrictedStockUnitsRSUMember 2024-09-02 2025-08-31 0000909832 us-gaap:RestrictedStockUnitsRSUMember 2023-09-04 2024-09-01 0000909832 stpr:CA 2025-09-01 2026-08-30 0000909832 us-gaap:StateAndLocalTaxJurisdictionOtherMember 2025-09-01 2026-08-30 0000909832 country:MX 2025-09-01 2026-08-30 0000909832 us-gaap:OtherAssetsNoncurrent 2026-08-30 0000909832 us-gaap:OtherAssetsNoncurrent 2025-08-31 0000909832 us-gaap:OtherLiabilitiesNoncurrent 2026-08-30 0000909832 us-gaap:OtherLiabilitiesNoncurrent 2025-08-31 0000909832 us-gaap:OperatingSegmentsMember cost:UnitedStatesMember 2025-09-01 2026-08-30 0000909832 us-gaap:OperatingSegmentsMember cost:UnitedStatesMember 2024-09-02 2025-08-31 0000909832 us-gaap:OperatingSegmentsMember cost:UnitedStatesMember 2023-09-04 2024-09-01 0000909832 us-gaap:OperatingSegmentsMember cost:CanadaMember 2025-09-01 2026-08-30 0000909832 us-gaap:OperatingSegmentsMember cost:CanadaMember 2024-09-02 2025-08-31 0000909832 us-gaap:OperatingSegmentsMember cost:CanadaMember 2023-09-04 2024-09-01 0000909832 us-gaap:OperatingSegmentsMember cost:OtherInternationalMember 2025-09-01 2026-08-30 0000909832 us-gaap:OperatingSegmentsMember cost:OtherInternationalMember 2024-09-02 2025-08-31 0000909832 us-gaap:OperatingSegmentsMember cost:OtherInternationalMember 2023-09-04 2024-09-01 0000909832 us-gaap:OperatingSegmentsMember cost:UnitedStatesMember 2026-08-30 0000909832 us-gaap:OperatingSegmentsMember cost:UnitedStatesMember 2025-08-31 0000909832 us-gaap:OperatingSegmentsMember cost:UnitedStatesMember 2024-09-01 0000909832 us-gaap:OperatingSegmentsMember cost:CanadaMember 2026-08-30 0000909832 us-gaap:OperatingSegmentsMember cost:CanadaMember 2025-08-31 0000909832 us-gaap:OperatingSegmentsMember cost:CanadaMember 2024-09-01 0000909832 us-gaap:OperatingSegmentsMember cost:OtherInternationalMember 2026-08-30 0000909832 us-gaap:OperatingSegmentsMember cost:OtherInternationalMember 2025-08-31 0000909832 us-gaap:OperatingSegmentsMember cost:OtherInternationalMember 2024-09-01 0000909832 cost:FoodandSundriesMember 2025-09-01 2026-08-30 0000909832 cost:FoodandSundriesMember 2024-09-02 2025-08-31 0000909832 cost:FoodandSundriesMember 2023-09-04 2024-09-01 0000909832 cost:NonFoodsMember 2025-09-01 2026-08-30 0000909832 cost:NonFoodsMember 2024-09-02 2025-08-31 0000909832 cost:NonFoodsMember 2023-09-04 2024-09-01 0000909832 cost:FreshFoodMember 2025-09-01 2026-08-30 0000909832 cost:FreshFoodMember 2024-09-02 2025-08-31 0000909832 cost:FreshFoodMember 2023-09-04 2024-09-01 0000909832 cost:OtherMember 2025-09-01 2026-08-30 0000909832 cost:OtherMember 2024-09-02 2025-08-31 0000909832 cost:OtherMember 2023-09-04 2024-09-01 iso4217:USD shares iso4217:USD shares cost:warehouse cost:states pure cost:Reportable_segment false 2026-08-30 2026 FY COSTCO WHOLESALE CORP /NEW 0000909832 --08-30 0.005 0.005 100000000 100000000 0 0 0 0 0.005 0.005 900000000 900000000 443266000 443237000 443266000 443237000 P5Y P3Y P5Y 1 1 953000000 26000000 15000000 994000000 953000000 26000000 15000000 994000000 953000000 26000000 15000000 994000000 http://fasb.org/us-gaap/2026#OtherAssetsNoncurrent http://fasb.org/us-gaap/2026#OtherAssetsNoncurrent http://fasb.org/us-gaap/2026#OtherLiabilitiesCurrent http://fasb.org/us-gaap/2026#OtherLiabilitiesCurrent http://fasb.org/us-gaap/2026#OtherLiabilitiesCurrent http://fasb.org/us-gaap/2026#OtherLiabilitiesCurrent http://fasb.org/us-gaap/2026#OtherLiabilitiesNoncurrent http://fasb.org/us-gaap/2026#OtherLiabilitiesNoncurrent http://xbrl.sec.gov/country/2026#US 3 10-K true false 0-20355 WA 91-1223280 999 Lake Drive Issaquah WA 98027 425 313-8100 Common Stock, $.005 Par Value COST NASDAQ Yes No Yes Yes Large Accelerated Filer false false true false false 451600000000 443129349 <div style="margin-top:3pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Portions of the registrant's Proxy Statement for the Annual Meeting of Shareholders to be held on January 21, 2027, are incorporated by reference into Part III of this Form 10-K.</span></div> <div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Risk Management and Global Strategy</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">We have implemented processes, technologies, and controls to seek to assess, identify, and manage risks associated with cybersecurity threats. Management considers cybersecurity risks within our overall approach to enterprise risk management. We evaluate these risks based on several frameworks, including the National Institute of Standards and Technology (NIST) Cybersecurity Framework (CSF), Center for Internet Security (CIS) 18 Critical Security Controls, and the Payment Card Industry Data Security Standard. Our governance policies, including our Information Security Policy, outline high-level objectives designed to meet compliance and regulatory requirements.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">We undertake regular NIST CSF and CIS 18 Critical Security Controls assessments, conducted by a third-party, to measure program maturity. We have implemented a variety of technologies, leveraging third-party security providers for some, and engage in multiple activities to seek to identify and mitigate vulnerabilities and risks. These include, among other activities, scanning for common vulnerabilities and exposures, penetration tests on internal and external networks, code scans on applications, allowed application listing, configuration management tools, employee awareness and training, and internal and external audits. We also review with various frequencies and on a risk-based priority select third parties with whom we do business, in an effort to reduce the likelihood of security incidents or business interruptions. We maintain cybersecurity insurance that would apply to certain losses arising from significant security incidents.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">We maintain a security operations center, supported by external providers and our employees, which provides threat detection and incident response capabilities. We maintain cyber incident response plans and related playbooks in coordination with stakeholders (including legal counsel). Significant incidents are prescribed to be escalated to a Cybersecurity Materiality Committee to assess materiality based on qualitative and quantitative factors and evaluate disclosure and corrective action. The Committee is composed of a cross-divisional group of executives representing the core business functions of Information Technology and Security, Operations, Administration, Finance and Accounting, and Legal. We conduct periodic tabletop exercises, including at the executive level, to review our response processes and incident management procedures.</span></div> <div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">We have implemented processes, technologies, and controls to seek to assess, identify, and manage risks associated with cybersecurity threats. Management considers cybersecurity risks within our overall approach to enterprise risk management. We evaluate these risks based on several frameworks, including the National Institute of Standards and Technology (NIST) Cybersecurity Framework (CSF), Center for Internet Security (CIS) 18 Critical Security Controls, and the Payment Card Industry Data Security Standard. Our governance policies, including our Information Security Policy, outline high-level objectives designed to meet compliance and regulatory requirements.</span></div> true true true <div style="margin-bottom:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Governance</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Our Board of Directors has delegated certain responsibilities to the Audit Committee of the Board. The Audit Committee reviews and discusses with management the identification and mitigation of cybersecurity risks, including (among other things) the effectiveness of risk-management policies and practices designed to help safeguard our operations, financial systems, and data. Our Chief Information and Digital Officer (CIDO) and his executive team, including the Vice President of Information Security and Chief Information Security Officer (CISO), present cybersecurity-related topics, including program maturity progress, regularly to the Audit Committee. The Internal Audit team, in its periodic compliance and risk assessment updates to the Audit Committee, also reports on its reviews of certain of our cybersecurity risk exposures, controls, and management actions. The full Board also receives cybersecurity evaluations from time to time.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Our information security organization is led by our CISO, who joined us in December 2025 and brings over 20 years of relevant cybersecurity and leadership experiences across various industries, primarily pharmacy, finance, and consulting. The CISO is responsible for cybersecurity engineering and architecture, cybersecurity operations, incident response, threat intelligence, identity and access management, cybersecurity risk and compliance, and vulnerability management. Our CISO reports to our CIDO, who has more than 30 years of experience in which he has led global digital responsibilities, including leading global cyber teams. Our CIDO reports to the Chief Executive Officer.</span></div> Our Board of Directors has delegated certain responsibilities to the Audit Committee of the Board. The Audit Committee reviews and discusses with management the identification and mitigation of cybersecurity risks, including (among other things) the effectiveness of risk-management policies and practices designed to help safeguard our operations, financial systems, and data. Our Chief Information and Digital Officer (CIDO) and his executive team, including the Vice President of Information Security and Chief Information Security Officer (CISO), present cybersecurity-related topics, including program maturity progress, regularly to the Audit Committee. The Internal Audit team, in its periodic compliance and risk assessment updates to the Audit Committee, also reports on its reviews of certain of our cybersecurity risk exposures, controls, and management actions. The full Board also receives cybersecurity evaluations from time to time.<div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Our information security organization is led by our CISO, who joined us in December 2025 and brings over 20 years of relevant cybersecurity and leadership experiences across various industries, primarily pharmacy, finance, and consulting. The CISO is responsible for cybersecurity engineering and architecture, cybersecurity operations, incident response, threat intelligence, identity and access management, cybersecurity risk and compliance, and vulnerability management. Our CISO reports to our CIDO, who has more than 30 years of experience in which he has led global digital responsibilities, including leading global cyber teams. Our CIDO reports to the Chief Executive Officer.</span></div> true Our information security organization is led by our CISO, who joined us in December 2025 and brings over 20 years of relevant cybersecurity and leadership experiences across various industries, primarily pharmacy, finance, and consulting. The CISO is responsible for cybersecurity engineering and architecture, cybersecurity operations, incident response, threat intelligence, identity and access management, cybersecurity risk and compliance, and vulnerability management. Our information security organization is led by our CISO, who joined us in December 2025 and brings over 20 years of relevant cybersecurity and leadership experiences across various industries, primarily pharmacy, finance, and consulting true CISO reports to our CIDO, who has more than 30 years of experience in which he has led global digital responsibilities, including leading global cyber teams. Our CIDO reports to the Chief Executive Officer. false 297247000000 269912000000 249625000000 5907000000 5323000000 4828000000 303154000000 275235000000 254453000000 264279000000 239886000000 222358000000 27190000000 24966000000 22810000000 11685000000 10383000000 9285000000 145000000 154000000 169000000 711000000 589000000 624000000 12251000000 10818000000 9740000000 3025000000 2719000000 2373000000 9226000000 8099000000 7367000000 20.78 18.24 16.59 20.76 18.21 16.56 443953000 443985000 443914000 444427000 444803000 444759000 9226000000 8099000000 7367000000 150000000 58000000 -23000000 9376000000 8157000000 7344000000 20207000000 14161000000 1094000000 1123000000 3959000000 3203000000 19324000000 18116000000 1998000000 1777000000 46582000000 38380000000 35633000000 31909000000 2697000000 2725000000 4133000000 4085000000 89045000000 77099000000 22591000000 19783000000 5641000000 5205000000 3037000000 2677000000 3006000000 2854000000 2248000000 75000000 7429000000 6514000000 43952000000 37108000000 3914000000 5713000000 2414000000 2460000000 2962000000 2654000000 53242000000 47935000000 0.005 100000000 0 0 0.005 900000000 443266000 443237000 2000000 2000000 8830000000 8282000000 -1620000000 -1770000000 28591000000 22650000000 35803000000 29164000000 89045000000 77099000000 442793000 2000000 7340000000 -1805000000 19521000000 25058000000 7367000000 7367000000 -23000000 -23000000 822000000 822000000 1337000 315000000 315000000 1004000 18000000 680000000 698000000 8589000000 8589000000 443126000 2000000 7829000000 -1828000000 17619000000 23622000000 8099000000 8099000000 58000000 58000000 864000000 864000000 1054000 393000000 393000000 943000 18000000 885000000 903000000 2183000000 2183000000 443237000 2000000 8282000000 -1770000000 22650000000 29164000000 9226000000 9226000000 150000000 150000000 929000000 929000000 920000 361000000 361000000 891000 20000000 827000000 847000000 2458000000 2458000000 443266000 2000000 8830000000 -1620000000 28591000000 35803000000 9226000000 8099000000 7367000000 2674000000 2426000000 2237000000 318000000 303000000 315000000 924000000 860000000 818000000 -306000000 108000000 60000000 -49000000 9000000 -51000000 1153000000 -559000000 2068000000 2755000000 404000000 1938000000 -718000000 -801000000 -741000000 15817000000 13335000000 11339000000 6435000000 5498000000 4710000000 788000000 1028000000 1470000000 811000000 1141000000 1790000000 -34000000 -74000000 19000000 -6378000000 -5311000000 -4409000000 577000000 862000000 920000000 553000000 816000000 928000000 69000000 103000000 1077000000 496000000 0 498000000 361000000 393000000 315000000 848000000 903000000 700000000 2458000000 2183000000 9041000000 91000000 147000000 137000000 -3355000000 -3775000000 -10764000000 -38000000 6000000 40000000 6046000000 4255000000 -3794000000 14161000000 9906000000 13700000000 20207000000 14161000000 9906000000 103000000 106000000 129000000 2839000000 2917000000 2319000000 220000000 193000000 203000000 <div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Note 1—Summary of Significant Accounting Policies</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Description of Business</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Costco Wholesale Corporation (Costco or the Company), a Washington corporation, and its subsidiaries operate membership warehouses and e-commerce sites based on the concept that offering members low prices on a limited selection of nationally-branded and private-label products in a wide range of merchandise categories will produce high sales volumes and rapid inventory turnover. At August 30, 2026, Costco operated 939 warehouses worldwide: 647 in the United States (U.S.) located in 47 states, Washington, D.C., and Puerto Rico, 115 in Canada, 43 in Mexico, 37 in Japan, 29 in the U.K., 20 in Korea, 15 in Australia, 14 in Taiwan, seven in China, five in Spain, three in France, two in Sweden, and one each in Iceland and New Zealand. The Company operates e-commerce sites in the U.S., Canada, the U.K., Mexico, Korea, Taiwan, Japan, Australia, and China. </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Basis of Presentation</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The consolidated financial statements include the accounts of Costco and its wholly-owned subsidiaries. All material inter-company transactions among the Company and its consolidated subsidiaries have been eliminated in consolidation.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Fiscal Year End</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company operates on a 52/53-week fiscal year basis with the year ending on the Sunday closest to August 31. References to 2026, 2025, and 2024 relate to the 52-week fiscal years ended August 30, 2026, August 31, 2025, and September 1, 2024.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Use of Estimates</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and the disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. These estimates and assumptions take into account historical and forward-looking factors that the Company believes are reasonable. Actual results could differ from those estimates and assumptions.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Reclassification</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Reclassifications were made to the 2025 consolidated balance sheet and the 2025 and 2024 consolidated statements of cash flows to conform with current year presentation.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Cash and Cash Equivalents</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company considers as cash and cash equivalents all cash on deposit, highly liquid investments with a maturity of three months or less at the date of purchase, and proceeds due from credit and debit card transactions with settlement terms of up to four days. Credit and debit card receivables were $2,842 and $2,670 at the end of 2026 and 2025.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Short-Term Investments</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Short-term investments generally consist of debt securities (U.S. government and agency securities), with maturities at the date of purchase of three months to ten years. Investments with maturities beyond five years may be classified, based on the Company’s determination, as short-term based on their highly liquid nature and because they represent the investment of cash that is available for current operations. </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Short-term investments classified as available-for-sale are recorded at fair value using the specific identification method with the unrealized gains and losses reflected in accumulated other comprehensive income (loss) until realized. Realized gains and losses from the sale of available-for-sale securities, if any, are determined on a specific identification basis and are recorded in interest income and other, net in the consolidated statements of income. These available-for-sale investments have a low level of inherent credit risk given they are issued by the U.S. government and agencies. Changes in their fair value are primarily attributable to changes in interest rates and market liquidity. Short-term investments classified as held-to-maturity are financial instruments that the Company has the intent and ability to hold to maturity and are reported net of any related amortization and are not remeasured to fair value on a recurring basis.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company periodically evaluates unrealized losses in its investment securities for credit impairment, using both qualitative and quantitative criteria. In the event a security is deemed to be impaired as the result of a credit loss, the Company recognizes the loss in interest income and other, net in the consolidated statements of income. </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Fair Value of Financial Instruments</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company accounts for certain assets and liabilities at fair value. The carrying value of the Company’s financial instruments, including cash and cash equivalents, receivables, and accounts payable, approximate fair value due to their short-term nature or variable interest rates. See </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_115" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Notes 2</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">, </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_118" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">3</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">, and </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_121" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">4</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for the carrying value and fair value of the Company’s investments, derivative instruments, and fixed-rate debt.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Fair value is defined as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. Fair value is estimated by applying a fair value hierarchy, which requires maximizing the use of observable inputs when measuring fair value. The three levels of inputs are:</span></div><div style="margin-bottom:9pt;text-align:justify;text-indent:24.75pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Level 1: Quoted market prices in active markets for identical assets or liabilities.</span></div><div style="padding-left:24.75pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Level 2: Observable market-based inputs or unobservable inputs that are corroborated by market</span></div><div style="margin-bottom:9pt;padding-left:63pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">data.</span></div><div style="margin-bottom:9pt;text-align:justify;text-indent:24.75pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Level 3: Significant unobservable inputs that are not corroborated by market data.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company’s valuation techniques used to measure the fair value of money market mutual funds, which are included in cash and cash equivalents, are based on quoted market prices, such as quoted net asset values published by the fund as supported in an active market. Valuation methodologies used to measure the fair value of all other non-derivative financial instruments are based on independent external valuation information. The pricing process uses data from a variety of independent external valuation information providers, including trades, bid price or spread, two-sided markets, quotes, benchmark curves including but not limited to treasury benchmarks, Secured Overnight Financing Rate and swap curves, discount rates, and market data feeds. All are observable in the market or can be derived principally from or corroborated by observable market data. The Company reports transfers in and out of Levels 1, 2, and 3, as applicable, using the fair value of the individual securities as of the beginning of the reporting period in which the transfer(s) occurred.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Current financial liabilities have fair values that approximate their carrying values. Long-term financial liabilities include the Company's long-term debt, which are recorded on the balance sheet at issuance price and adjusted for unamortized discounts or premiums and debt issuance costs. Discounts, premiums, and debt issuance costs are amortized to interest expense over the term of the loan. The estimated fair value of the Company's long-term debt is based primarily on reported market values, recently completed market transactions, and estimates based upon interest rates, maturities, and credit.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Receivables, Net</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Receivables consist primarily of vendor, third-party pharmacy, credit card incentive, reinsurance, and other receivables. Vendor receivables include discounts, volume rebates, and a variety of other programs. Balances are generally presented on a gross basis, separate from any related payable due. In certain circumstances, these receivables may be settled against the related payable to that vendor, in which case the receivables are presented on a net basis. Third-party pharmacy receivables generally relate to amounts due from insurance providers. Credit card incentive receivables primarily represent amounts earned under co-branded credit card arrangements. Reinsurance receivables are held by the Company’s wholly-owned captive insurance subsidiary and primarily represent amounts ceded through reinsurance arrangements gross of the amounts assumed under reinsurance, which are presented within other current liabilities in the consolidated balance sheets. Other receivables primarily consist of amounts due from governmental entities, mostly tax-related items.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The valuation allowance related to receivables was immaterial to the Company's consolidated financial statements at the end of 2026 and 2025.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Merchandise Inventories</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Merchandise inventories consist of the following:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:justify;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">United States </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">13,707 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">12,868 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Canada</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,188 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,907 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other International</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,429 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,341 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise inventories</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">19,324 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">18,116 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Merchandise inventories are stated at the lower of cost or market. U.S. merchandise inventories are valued by the cost method of accounting, using the last-in, first-out (LIFO) basis. The Company believes the LIFO method more fairly presents the results of operations by more closely matching current costs with current revenues. The Company records an adjustment each quarter, if necessary, for the projected annual effect of inflation or deflation, and these estimates are adjusted to actual results determined at year-end, after actual inflation or deflation rates and inventory levels have been determined. Due to higher merchandise costs in 2026, a $206 charge was recorded to merchandise costs to increase the cumulative LIFO valuation on merchandise inventories at August 30, 2026. A charge of $142 was recorded in 2025 and an immaterial LIFO benefit was recorded in 2024. Canadian and Other International merchandise inventories are predominantly valued using the cost and retail inventory methods, respectively, using the first-in, first-out (FIFO) basis.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company initially provides for estimated inventory losses between physical inventory counts using estimates based on experience. The provision is adjusted to reflect physical inventory counts, which generally occur in the second and fourth fiscal quarters. Inventory cost where appropriate is reduced by estimates of vendor rebates when earned or as the Company progresses towards earning those rebates, provided that they are probable and reasonably estimable.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Property and Equipment, Net</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Property and equipment are stated at cost. Depreciation and amortization expense is computed primarily using the straight-line method over estimated useful lives. Leasehold improvements made after the beginning of the initial lease term are depreciated over the shorter of the estimated useful life of the asset or the remaining term of the initial lease plus any renewals that are reasonably certain at the date of the leasehold improvements.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company capitalizes certain computer software and costs incurred in developing or obtaining software for internal use. During development, these costs are included in construction in progress. To the </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">extent that the assets become ready for their intended use, these costs are included in equipment and fixtures and amortized on a straight-line basis over estimated useful lives.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Repair and maintenance costs are expensed when incurred. Expenditures for remodels, refurbishments, and improvements that add to or change asset function or useful life are capitalized. Assets removed during the remodel, refurbishment, or improvement are retired. Assets classified as held-for-sale at the end of 2026 and 2025 were immaterial.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table summarizes the Company's property and equipment balances at the end of 2026 and 2025:</span></div><div style="margin-bottom:9pt;margin-top:5pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:40.887%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.441%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.810%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.972%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Estimated Useful Lives</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Land</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">N/A</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">11,265 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">10,323 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Buildings and improvements</span></td><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-align:center"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5-50 years</span></div></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">27,775 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">25,508 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Equipment and fixtures</span></td><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-align:center"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3-20 years</span></div></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">14,850 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">13,127 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Construction in progress</span></td><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">N/A</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,722 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,882 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">56,612 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">50,840 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="6" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Accumulated depreciation and amortization</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(20,979)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(18,931)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="6" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 13pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment, net</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">35,633 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">31,909 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company evaluates long-lived assets for impairment on an annual basis, when relocating or closing a facility, or when events or changes in circumstances may indicate that the carrying amount of the asset group, generally an individual warehouse, may not be fully recoverable. For asset groups held and used, including warehouses to be relocated, the carrying value of the asset group is considered recoverable when the estimated future undiscounted cash flows generated from the use and eventual disposition of the asset group exceed the respective carrying value. In the event that the carrying value is not considered recoverable, an impairment loss is recognized for the asset group to be held and used equal to the excess of the carrying value above the estimated fair value of the asset group. For asset groups classified as held-for-sale (disposal group), the carrying value is compared to the disposal group’s fair value less costs to sell. The Company estimates fair value by obtaining market appraisals from third party brokers or using other valuation techniques. There were no impairment charges recognized in 2026, and impairment charges in 2025 and 2024 were immaterial.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Leases</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company leases land, buildings, and/or equipment at warehouses and certain other office and distribution facilities. Leases generally contain one or more of the following options, which the Company can exercise at the end of the initial term: (a) renew the lease for a defined number of years at the then-fair market rental rate or rate stipulated in the lease agreement; (b) purchase the property at the then-fair market value or purchase price stated in the agreement; (c) a right of first refusal in the event of a third-party offer; or (d) a right of first offer if the landlord intends to sell.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Some leases include free-rent periods and step-rent provisions, which are recognized on a straight-line basis over the original term of the lease and any extension options that the Company is reasonably certain to exercise from the date the Company has control of the property. Certain leases provide for periodic rent increases based on price indices or the greater of minimum guaranteed amounts or sales volume, which are recognized as variable lease payments. The Company's leases do not contain any material residual value guarantees or material restrictive covenants.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company determines at inception whether a contract is or contains a lease. Non-lease components and the lease components to which they relate are accounted for together as a single lease component for all asset classes. The Company initially records right-of-use (ROU) assets and lease obligations for its finance and operating leases based on the discounted future minimum lease payments over the term. </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The lease term is defined as the noncancelable period of the lease plus any options to extend when it is reasonably certain that the Company will exercise the option. As the rate implicit in the Company's leases is not easily determinable, the present value of the sum of the lease payments is calculated using the Company's incremental borrowing rate. The rate is determined using a portfolio approach based on the rate of interest the Company would pay to borrow an amount equal to the lease payments on a collateralized basis over a similar term. The Company uses quoted interest rates from financial institutions to derive the incremental borrowing rate. Impairment of ROU assets is evaluated in a similar manner as described in Property and Equipment, Net above.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company's asset retirement obligations (ARO) primarily relate to leasehold improvements that must be removed at the end of a lease. These obligations are recorded as a discounted liability, with an offsetting asset, based upon the estimated fair value of the costs to remove the improvements. These liabilities are accreted over time to the projected future value of the obligation. The ARO assets are depreciated using the same depreciation method as the leasehold improvement assets and are included in buildings and improvements. Estimated ARO liabilities associated with these leases are included in other long-term liabilities in the consolidated balance sheet.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Goodwill and Acquired Intangible Assets</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Goodwill represents the excess of acquisition cost over the fair value of the net assets acquired and is not subject to amortization. The Company reviews goodwill annually in the fourth quarter for impairment or when circumstances indicate carrying value may exceed the fair value. This evaluation is performed at the reporting unit level. If a qualitative assessment indicates that it is more likely than not that the fair value is less than carrying value, a quantitative analysis is completed using either the income or market approach, or a combination of both. The income approach estimates fair value based on expected discounted future cash flows, while the market approach uses comparable public companies and transactions to develop metrics to be applied to historical and expected future operating results.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Goodwill is included in other long-term assets in the consolidated balance sheets. At the end of 2026, 2025, and 2024 goodwill balances in the Company's U.S., Canadian, and Other International operations were $953, $26, and $15, respectively. No impairment charges were recorded in 2026, 2025, or 2024.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Definite-lived intangible assets, which are immaterial, are included in other long-term assets on the consolidated balance sheets and are amortized on a straight-line basis over their estimated lives, which approximates the pattern of expected economic benefit.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Insurance/Self-insurance Liabilities</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Claims for employee health-care benefits, workers’ compensation, general liability, property damage, directors’ and officers’ liability, vehicle liability, inventory loss, and other exposures are funded predominantly through self-insurance. Insurance coverage is maintained for certain risks to limit exposures to very large losses. The Company uses various risk management mechanisms, including a wholly-owned captive insurance subsidiary and participates in a reinsurance program. Liabilities associated with the risks that are retained by the Company are not discounted and are estimated using historical claims experience, demographic factors, severity factors, and other actuarial assumptions. The estimated accruals for these liabilities could be significantly affected if future occurrences, claims, or expenses differ from these assumptions and historical trends. At the end of 2026 and 2025, these insurance liabilities were $2,157 and $1,878 in the aggregate, and were included in accrued salaries and benefits and other current liabilities in the consolidated balance sheets, classified based on their nature.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The captive receives direct premiums, which are netted against the Company’s premium costs in SG&amp;A expenses in the consolidated statements of income. The captive participates in a reinsurance program that includes third-party participants. The participant agreements and practices of the reinsurance program are designed to limit participating members’ individual risk. Income statement adjustments related to the reinsurance program and related impacts to the consolidated balance sheets are </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">recognized as information becomes known. In the event the Company leaves the reinsurance program, the Company retains its primary obligation to the participants for prior activity.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Derivatives</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company is exposed to foreign-currency exchange-rate fluctuations in the normal course of business. It manages these fluctuations, in part, through the use of forward foreign-exchange contracts, seeking to economically hedge the impact of fluctuations of foreign-exchange on known future expenditures denominated in a non-functional foreign-currency. The contracts relate primarily to U.S. dollar merchandise inventory expenditures made by the Company’s international subsidiaries with functional currencies other than the U.S. dollar. These contracts either do not qualify for or the Company has not elected derivative hedge accounting. The Company seeks to mitigate risk with the use of these contracts and does not intend to engage in speculative transactions. Some of these contracts contain credit-risk-related contingent features that require settlement of outstanding contracts upon certain triggering events. The aggregate fair value amounts of derivative instruments in a net liability position and the amount needed to settle the instruments immediately if the credit-risk-related contingent features were triggered were immaterial at the end of 2026 and 2025. The aggregate notional amounts of open, unsettled forward foreign-exchange contracts were $541 and $1,184 at the end of 2026 and 2025. See </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_118" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Note 3</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for information on the fair value of unsettled forward foreign-exchange contracts at the end of 2026 and 2025.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The unrealized gains or losses recognized in interest income and other, net in the consolidated statements of income relating to the net changes in the fair value of unsettled forward foreign-exchange contracts were immaterial in 2026, 2025, and 2024.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company is exposed to fluctuations in prices for energy, particularly electricity and natural gas, and other commodities used in retail and manufacturing operations, which it seeks to partially mitigate through the use of fixed-price contracts for certain of its warehouses and other facilities, primarily in the U.S. and Canada. The Company also enters into variable-priced contracts for some purchases of natural gas, in addition to fuel for its gas stations, on an index basis. These contracts meet the characteristics of derivative instruments, but generally qualify for the “normal purchases and normal sales” exception under authoritative guidance and require no mark-to-market adjustment.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Foreign-Currency</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The functional currencies of the Company’s international subsidiaries are their local currencies. Assets and liabilities recorded in foreign currencies are translated at the exchange rate on the balance sheet date. Translation adjustments are recorded in accumulated other comprehensive loss. Revenues and expenses of the Company’s consolidated foreign operations are translated at average exchange rates prevailing during the year.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company recognizes foreign-currency transaction gains and losses related to revaluing or settling monetary assets and liabilities denominated in currencies other than the functional currency in interest income and other, net in the consolidated statements of income. Generally, these include the U.S. dollar cash and cash equivalents and the U.S. dollar payables of consolidated subsidiaries revalued to their functional currency. Also included are realized foreign-currency gains or losses from settlements of forward foreign-exchange contracts. These items were immaterial in 2026, 2025, and 2024.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Revenue Recognition</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company recognizes sales for the amount of consideration collected from the member, which includes gross shipping fees where applicable, and is net of sales taxes collected and remitted to government agencies and member returns. The Company reserves for estimated returns based on historical trends and reduces sales and merchandise costs accordingly. The Company records on a gross basis a refund liability and an asset for recovery, which are included in other current liabilities and other current assets, respectively, in the consolidated balance sheets.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company offers merchandise in the following core merchandise categories: foods and sundries, non-foods, and fresh foods. The Company also provides expanded products and services through warehouse ancillary and other businesses. The Company is the principal for the majority of its transactions and recognizes revenue on a gross basis. The Company is the principal when it has control of the merchandise or service before it is transferred to the member. The majority of revenue from merchandise sales is recognized at the point of sale. Revenue generated through e-commerce or special orders is generally recognized upon shipment to the member. For merchandise shipped directly to the member, shipping and handling costs are expensed as incurred as fulfillment costs and included in merchandise costs in the consolidated statements of income. In certain ancillary businesses, revenue is deferred until the member picks up merchandise at the warehouse. Deferred sales are included in other current liabilities in the consolidated balance sheets.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company accounts for membership fee revenue, net of refunds, on a deferred basis, ratably over the one-year membership period. Deferred membership fees at the end of 2026 and 2025 were $3,006 and $2,854.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In most countries, the Company's Executive members qualify for an Executive reward, generally 2% on qualified purchases, subject to an annual maximum value, which does not expire and is redeemable at Costco warehouses. The Company accounts for this reward as a reduction in sales, net of the estimated impact of non-redemptions (breakage), with the corresponding liability classified as accrued member rewards in the consolidated balance sheets. Estimated breakage is computed based on redemption data. For 2026, 2025, and 2024, the net reduction in sales was $3,383, $3,007, and $2,804.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company sells and otherwise provides proprietary shop cards that do not expire and are redeemable at the warehouse or online for merchandise or membership. Revenue from shop cards is recognized upon redemption, and estimated breakage is recognized based on redemption data. The Company accounts for outstanding shop card balances as a liability, net of estimated breakage. Shop card liabilities are included in other current liabilities in the consolidated balance sheets.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Citibank, N.A. is the exclusive issuer of co-branded credit cards to U.S. members. The Company receives various forms of consideration from Citibank, including a royalty on purchases made on the card outside of Costco. A portion of the royalty is used to fund the rebate that cardholders receive, after taking into consideration breakage, which is calculated based on rebate redemption data. The rebates are issued in February and expire on December 31. The Company also maintains varying co-branded credit card arrangements in Canada and certain Other International subsidiaries.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Merchandise Costs</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Merchandise costs consist of the purchase price or manufacturing costs of inventory sold, inbound and outbound shipping charges, and all costs related to the Company’s depot, fulfillment, and manufacturing operations, and are reduced by vendor consideration. Merchandise costs also include salaries, benefits, depreciation, and utilities in fresh foods departments and certain ancillary businesses.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Vendor Consideration</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company receives funds from vendors for discounts and a variety of other programs. These programs are evidenced by agreements that are reflected in the carrying value of the inventory when earned or as the Company progresses towards earning the rebate or discount, and as a component of merchandise costs as the merchandise is sold. Other vendor consideration is generally recorded as a reduction of merchandise costs upon completion of contractual milestones, agreement terms, or other systematic approaches.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Selling, General and Administrative Expenses</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Selling, general and administrative expenses consist primarily of salaries, benefits and workers’ compensation costs for warehouse employees (other than fresh foods departments and certain ancillary </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">businesses, which are reflected in merchandise costs), as well as all regional and home office employees, including buying personnel. Selling, general and administrative expenses also include substantially all building and equipment depreciation, stock compensation expense, credit and debit card processing fees, utilities, preopening, as well as other operating costs incurred to support warehouse and e-commerce operations.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Retirement Plans</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company's 401(k) retirement plan is available to all U.S. employees over the age of 18 who have completed 90 days of employment. The plan allows participants to make wage deferral contributions, a portion of which the Company matches. In addition, the Company provides each eligible participant an annual discretionary contribution. The Company also has a defined contribution plan for employees in Canada and contributes a percentage of each employee's wages. Certain subsidiaries in the Company's Other International operations have defined benefit and defined contribution plans, which are immaterial. Amounts expensed under all plans were $1,174, $1,061, and $963 for 2026, 2025, and 2024, and are predominantly included in SG&amp;A expenses in the consolidated statements of income.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Stock-Based Compensation</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company grants stock-based compensation, primarily to employees and non-employee directors. Grants to executive officers are generally performance-based. Through a series of shareholder approvals, there have been amended and restated plans and new provisions implemented by the Company. Restricted Stock Units (RSUs) are subject to quarterly vesting in the event of retirement or voluntary termination. Recipients are not entitled to vote or receive dividends on unvested and undelivered shares. </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">For grants issued prior to October 2025, RSUs generally vest over <span style="-sec-ix-hidden:f-430">five</span> years, with accelerated vesting provisions for participants reaching specified long-service milestones (25 years of service for employees; five years for non-employee directors). For grants issued in October 2025 and thereafter, RSUs vest over either a <span style="-sec-ix-hidden:f-432">three</span>-year schedule with no accelerated vesting or a <span style="-sec-ix-hidden:f-433">five</span>-year schedule with long-service acceleration, based on a one-time election made by eligible participants in 2025. RSUs granted to new participants vest over a three-year term with no such acceleration.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Compensation expense for awards is predominantly recognized using the straight-line method over the requisite service period for the entire award and forfeitures are recognized as they occur. Under accelerated vesting provisions, compensation expense is recognized upon achievement of the long-service term. The cumulative amount of compensation cost recognized at any point in time equals at least the portion of the grant-date fair value of the award that is vested at that date. The fair value of RSUs is calculated as the market value of the common stock on the measurement date less the present value of the expected dividends forgone during the vesting period.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Stock-based compensation expense is predominantly included in SG&amp;A expenses in the consolidated statements of income. Certain stock-based compensation costs are capitalized or included in the cost of merchandise. See </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_130" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Note 7</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for additional information.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Income Taxes</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company accounts for income taxes using the asset and liability method. Deferred tax assets and liabilities are recognized for the future tax consequences attributed to differences between the financial statement carrying amounts of existing assets and liabilities and their tax bases, credits and loss carry-forwards. Deferred tax assets and liabilities are measured using tax rates expected to apply to taxable income in the years in which those temporary differences and carry-forwards are expected to be recovered or settled. The effect on deferred tax assets and liabilities of a change in tax rates is recognized in income in the period that includes the enactment date. A valuation allowance is established when necessary to reduce deferred tax assets to amounts that are more likely than not expected to be realized.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The timing and amounts of deductible and taxable items and the probability of sustaining uncertain tax positions requires significant judgment. The benefits of uncertain tax positions are recorded in the Company’s consolidated financial statements only after determining a more-likely-than-not probability that the uncertain tax positions will withstand challenge from tax authorities. When facts and circumstances change, the Company reassesses these probabilities and records changes as appropriate.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Net Income per Common Share</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The computation of basic net income per share uses the weighted average number of shares that were outstanding during the period. The computation of diluted net income per share uses the weighted average number of shares in the basic net income per share calculation plus the number of common shares that would be issued assuming vesting of all potentially dilutive common shares outstanding using the treasury stock method for shares subject to RSUs.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Stock Repurchase Programs</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Repurchased shares of common stock are retired, in accordance with the Washington Business Corporation Act. The par value of repurchased shares is deducted from common stock and the excess repurchase price over par value is deducted by allocation to additional paid-in capital and retained earnings. The amount allocated to additional paid-in capital is the current value of additional paid-in capital per share outstanding and is applied to the number of shares repurchased. Any remaining amount is allocated to retained earnings. See </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_127" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Note 6</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for additional information.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Recent Accounting Pronouncements Adopted</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In December 2023, the FASB issued ASU 2023-09, which requires public business entities on an annual basis to disclose specific categories in the income-tax rate reconciliation, provide information for reconciling items that meet a quantitative threshold, and disclose certain information about income taxes paid. The standard is effective for annual periods beginning after December 15, 2024, with early adoption permitted. The Company adopted the ASU for the fiscal year ended August 30, 2026, on a prospective basis. See </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_133" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Note 8</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for additional information.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Recent Accounting Pronouncements Not Yet Adopted</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In November 2024, the FASB issued 2024-03, which requires disaggregated disclosures of certain costs and expenses on the income statement on an annual and interim basis. The standard is effective for fiscal years beginning after December 15, 2026, and interim periods within fiscal years beginning after December 15, 2027, with early adoption permitted. The amendments should be applied on a prospective basis. Retrospective application is permitted. The Company is evaluating the standard.</span></div> 939 647 47 115 43 37 29 20 15 14 7 5 3 2 1 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Basis of Presentation</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The consolidated financial statements include the accounts of Costco and its wholly-owned subsidiaries. All material inter-company transactions among the Company and its consolidated subsidiaries have been eliminated in consolidation.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Fiscal Year End</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company operates on a 52/53-week fiscal year basis with the year ending on the Sunday closest to August 31. References to 2026, 2025, and 2024 relate to the 52-week fiscal years ended August 30, 2026, August 31, 2025, and September 1, 2024.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Use of Estimates</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and the disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. These estimates and assumptions take into account historical and forward-looking factors that the Company believes are reasonable. Actual results could differ from those estimates and assumptions.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Reclassification</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Reclassifications were made to the 2025 consolidated balance sheet and the 2025 and 2024 consolidated statements of cash flows to conform with current year presentation.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Cash and Cash Equivalents</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company considers as cash and cash equivalents all cash on deposit, highly liquid investments with a maturity of three months or less at the date of purchase, and proceeds due from credit and debit card transactions with settlement terms of up to four days. Credit and debit card receivables were $2,842 and $2,670 at the end of 2026 and 2025.</span></div> 2842000000 2670000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Short-Term Investments</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Short-term investments generally consist of debt securities (U.S. government and agency securities), with maturities at the date of purchase of three months to ten years. Investments with maturities beyond five years may be classified, based on the Company’s determination, as short-term based on their highly liquid nature and because they represent the investment of cash that is available for current operations. </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Short-term investments classified as available-for-sale are recorded at fair value using the specific identification method with the unrealized gains and losses reflected in accumulated other comprehensive income (loss) until realized. Realized gains and losses from the sale of available-for-sale securities, if any, are determined on a specific identification basis and are recorded in interest income and other, net in the consolidated statements of income. These available-for-sale investments have a low level of inherent credit risk given they are issued by the U.S. government and agencies. Changes in their fair value are primarily attributable to changes in interest rates and market liquidity. Short-term investments classified as held-to-maturity are financial instruments that the Company has the intent and ability to hold to maturity and are reported net of any related amortization and are not remeasured to fair value on a recurring basis.</span></div>The Company periodically evaluates unrealized losses in its investment securities for credit impairment, using both qualitative and quantitative criteria. In the event a security is deemed to be impaired as the result of a credit loss, the Company recognizes the loss in interest income and other, net in the consolidated statements of income. <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Fair Value of Financial Instruments</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company accounts for certain assets and liabilities at fair value. The carrying value of the Company’s financial instruments, including cash and cash equivalents, receivables, and accounts payable, approximate fair value due to their short-term nature or variable interest rates. See </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_115" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Notes 2</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">, </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_118" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">3</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">, and </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_121" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">4</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for the carrying value and fair value of the Company’s investments, derivative instruments, and fixed-rate debt.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Fair value is defined as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. Fair value is estimated by applying a fair value hierarchy, which requires maximizing the use of observable inputs when measuring fair value. The three levels of inputs are:</span></div><div style="margin-bottom:9pt;text-align:justify;text-indent:24.75pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Level 1: Quoted market prices in active markets for identical assets or liabilities.</span></div><div style="padding-left:24.75pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Level 2: Observable market-based inputs or unobservable inputs that are corroborated by market</span></div><div style="margin-bottom:9pt;padding-left:63pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">data.</span></div><div style="margin-bottom:9pt;text-align:justify;text-indent:24.75pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Level 3: Significant unobservable inputs that are not corroborated by market data.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company’s valuation techniques used to measure the fair value of money market mutual funds, which are included in cash and cash equivalents, are based on quoted market prices, such as quoted net asset values published by the fund as supported in an active market. Valuation methodologies used to measure the fair value of all other non-derivative financial instruments are based on independent external valuation information. The pricing process uses data from a variety of independent external valuation information providers, including trades, bid price or spread, two-sided markets, quotes, benchmark curves including but not limited to treasury benchmarks, Secured Overnight Financing Rate and swap curves, discount rates, and market data feeds. All are observable in the market or can be derived principally from or corroborated by observable market data. The Company reports transfers in and out of Levels 1, 2, and 3, as applicable, using the fair value of the individual securities as of the beginning of the reporting period in which the transfer(s) occurred.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Current financial liabilities have fair values that approximate their carrying values. Long-term financial liabilities include the Company's long-term debt, which are recorded on the balance sheet at issuance price and adjusted for unamortized discounts or premiums and debt issuance costs. Discounts, premiums, and debt issuance costs are amortized to interest expense over the term of the loan. The estimated fair value of the Company's long-term debt is based primarily on reported market values, recently completed market transactions, and estimates based upon interest rates, maturities, and credit.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Receivables, Net</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Receivables consist primarily of vendor, third-party pharmacy, credit card incentive, reinsurance, and other receivables. Vendor receivables include discounts, volume rebates, and a variety of other programs. Balances are generally presented on a gross basis, separate from any related payable due. In certain circumstances, these receivables may be settled against the related payable to that vendor, in which case the receivables are presented on a net basis. Third-party pharmacy receivables generally relate to amounts due from insurance providers. Credit card incentive receivables primarily represent amounts earned under co-branded credit card arrangements. Reinsurance receivables are held by the Company’s wholly-owned captive insurance subsidiary and primarily represent amounts ceded through reinsurance arrangements gross of the amounts assumed under reinsurance, which are presented within other current liabilities in the consolidated balance sheets. Other receivables primarily consist of amounts due from governmental entities, mostly tax-related items.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The valuation allowance related to receivables was immaterial to the Company's consolidated financial statements at the end of 2026 and 2025.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Merchandise Inventories</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Merchandise inventories consist of the following:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:justify;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">United States </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">13,707 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">12,868 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Canada</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,188 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,907 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other International</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,429 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,341 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise inventories</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">19,324 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">18,116 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Merchandise inventories are stated at the lower of cost or market. U.S. merchandise inventories are valued by the cost method of accounting, using the last-in, first-out (LIFO) basis. The Company believes the LIFO method more fairly presents the results of operations by more closely matching current costs with current revenues. The Company records an adjustment each quarter, if necessary, for the projected annual effect of inflation or deflation, and these estimates are adjusted to actual results determined at year-end, after actual inflation or deflation rates and inventory levels have been determined. Due to higher merchandise costs in 2026, a $206 charge was recorded to merchandise costs to increase the cumulative LIFO valuation on merchandise inventories at August 30, 2026. A charge of $142 was recorded in 2025 and an immaterial LIFO benefit was recorded in 2024. Canadian and Other International merchandise inventories are predominantly valued using the cost and retail inventory methods, respectively, using the first-in, first-out (FIFO) basis.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company initially provides for estimated inventory losses between physical inventory counts using estimates based on experience. The provision is adjusted to reflect physical inventory counts, which generally occur in the second and fourth fiscal quarters. Inventory cost where appropriate is reduced by estimates of vendor rebates when earned or as the Company progresses towards earning those rebates, provided that they are probable and reasonably estimable.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Merchandise inventories consist of the following:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:justify;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">United States </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">13,707 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">12,868 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Canada</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,188 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,907 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other International</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,429 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,341 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise inventories</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">19,324 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">18,116 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 13707000000 12868000000 2188000000 1907000000 3429000000 3341000000 19324000000 18116000000 206000000 142000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Property and Equipment, Net</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Property and equipment are stated at cost. Depreciation and amortization expense is computed primarily using the straight-line method over estimated useful lives. Leasehold improvements made after the beginning of the initial lease term are depreciated over the shorter of the estimated useful life of the asset or the remaining term of the initial lease plus any renewals that are reasonably certain at the date of the leasehold improvements.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company capitalizes certain computer software and costs incurred in developing or obtaining software for internal use. During development, these costs are included in construction in progress. To the </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">extent that the assets become ready for their intended use, these costs are included in equipment and fixtures and amortized on a straight-line basis over estimated useful lives.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Repair and maintenance costs are expensed when incurred. Expenditures for remodels, refurbishments, and improvements that add to or change asset function or useful life are capitalized. Assets removed during the remodel, refurbishment, or improvement are retired. Assets classified as held-for-sale at the end of 2026 and 2025 were immaterial.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table summarizes the Company's property and equipment balances at the end of 2026 and 2025:</span></div><div style="margin-bottom:9pt;margin-top:5pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:40.887%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.441%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.810%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.972%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Estimated Useful Lives</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Land</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">N/A</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">11,265 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">10,323 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Buildings and improvements</span></td><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-align:center"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5-50 years</span></div></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">27,775 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">25,508 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Equipment and fixtures</span></td><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-align:center"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3-20 years</span></div></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">14,850 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">13,127 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Construction in progress</span></td><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">N/A</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,722 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,882 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">56,612 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">50,840 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="6" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Accumulated depreciation and amortization</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(20,979)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(18,931)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="6" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 13pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment, net</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">35,633 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">31,909 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company evaluates long-lived assets for impairment on an annual basis, when relocating or closing a facility, or when events or changes in circumstances may indicate that the carrying amount of the asset group, generally an individual warehouse, may not be fully recoverable. For asset groups held and used, including warehouses to be relocated, the carrying value of the asset group is considered recoverable when the estimated future undiscounted cash flows generated from the use and eventual disposition of the asset group exceed the respective carrying value. In the event that the carrying value is not considered recoverable, an impairment loss is recognized for the asset group to be held and used equal to the excess of the carrying value above the estimated fair value of the asset group. For asset groups classified as held-for-sale (disposal group), the carrying value is compared to the disposal group’s fair value less costs to sell. The Company estimates fair value by obtaining market appraisals from third party brokers or using other valuation techniques. There were no impairment charges recognized in 2026, and impairment charges in 2025 and 2024 were immaterial.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table summarizes the Company's property and equipment balances at the end of 2026 and 2025:</span></div><div style="margin-bottom:9pt;margin-top:5pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:40.887%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.441%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.810%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.972%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Estimated Useful Lives</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Land</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">N/A</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">11,265 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">10,323 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Buildings and improvements</span></td><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-align:center"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5-50 years</span></div></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">27,775 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">25,508 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Equipment and fixtures</span></td><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-align:center"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3-20 years</span></div></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">14,850 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">13,127 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Construction in progress</span></td><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">N/A</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,722 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,882 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">56,612 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">50,840 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="6" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Accumulated depreciation and amortization</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(20,979)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(18,931)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="6" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 13pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment, net</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">35,633 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">31,909 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 11265000000 10323000000 P5Y P50Y 27775000000 25508000000 P3Y P20Y 14850000000 13127000000 2722000000 1882000000 56612000000 50840000000 20979000000 18931000000 35633000000 31909000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Leases</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company leases land, buildings, and/or equipment at warehouses and certain other office and distribution facilities. Leases generally contain one or more of the following options, which the Company can exercise at the end of the initial term: (a) renew the lease for a defined number of years at the then-fair market rental rate or rate stipulated in the lease agreement; (b) purchase the property at the then-fair market value or purchase price stated in the agreement; (c) a right of first refusal in the event of a third-party offer; or (d) a right of first offer if the landlord intends to sell.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Some leases include free-rent periods and step-rent provisions, which are recognized on a straight-line basis over the original term of the lease and any extension options that the Company is reasonably certain to exercise from the date the Company has control of the property. Certain leases provide for periodic rent increases based on price indices or the greater of minimum guaranteed amounts or sales volume, which are recognized as variable lease payments. The Company's leases do not contain any material residual value guarantees or material restrictive covenants.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company determines at inception whether a contract is or contains a lease. Non-lease components and the lease components to which they relate are accounted for together as a single lease component for all asset classes. The Company initially records right-of-use (ROU) assets and lease obligations for its finance and operating leases based on the discounted future minimum lease payments over the term. </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The lease term is defined as the noncancelable period of the lease plus any options to extend when it is reasonably certain that the Company will exercise the option. As the rate implicit in the Company's leases is not easily determinable, the present value of the sum of the lease payments is calculated using the Company's incremental borrowing rate. The rate is determined using a portfolio approach based on the rate of interest the Company would pay to borrow an amount equal to the lease payments on a collateralized basis over a similar term. The Company uses quoted interest rates from financial institutions to derive the incremental borrowing rate. Impairment of ROU assets is evaluated in a similar manner as described in Property and Equipment, Net above.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company's asset retirement obligations (ARO) primarily relate to leasehold improvements that must be removed at the end of a lease. These obligations are recorded as a discounted liability, with an offsetting asset, based upon the estimated fair value of the costs to remove the improvements. These liabilities are accreted over time to the projected future value of the obligation. The ARO assets are depreciated using the same depreciation method as the leasehold improvement assets and are included in buildings and improvements. Estimated ARO liabilities associated with these leases are included in other long-term liabilities in the consolidated balance sheet.</span></div> <div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Goodwill and Acquired Intangible Assets</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Goodwill represents the excess of acquisition cost over the fair value of the net assets acquired and is not subject to amortization. The Company reviews goodwill annually in the fourth quarter for impairment or when circumstances indicate carrying value may exceed the fair value. This evaluation is performed at the reporting unit level. If a qualitative assessment indicates that it is more likely than not that the fair value is less than carrying value, a quantitative analysis is completed using either the income or market approach, or a combination of both. The income approach estimates fair value based on expected discounted future cash flows, while the market approach uses comparable public companies and transactions to develop metrics to be applied to historical and expected future operating results.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Goodwill is included in other long-term assets in the consolidated balance sheets. At the end of 2026, 2025, and 2024 goodwill balances in the Company's U.S., Canadian, and Other International operations were $953, $26, and $15, respectively. No impairment charges were recorded in 2026, 2025, or 2024.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Definite-lived intangible assets, which are immaterial, are included in other long-term assets on the consolidated balance sheets and are amortized on a straight-line basis over their estimated lives, which approximates the pattern of expected economic benefit.</span></div> 953000000 26000000 15000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Insurance/Self-insurance Liabilities</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Claims for employee health-care benefits, workers’ compensation, general liability, property damage, directors’ and officers’ liability, vehicle liability, inventory loss, and other exposures are funded predominantly through self-insurance. Insurance coverage is maintained for certain risks to limit exposures to very large losses. The Company uses various risk management mechanisms, including a wholly-owned captive insurance subsidiary and participates in a reinsurance program. Liabilities associated with the risks that are retained by the Company are not discounted and are estimated using historical claims experience, demographic factors, severity factors, and other actuarial assumptions. The estimated accruals for these liabilities could be significantly affected if future occurrences, claims, or expenses differ from these assumptions and historical trends. At the end of 2026 and 2025, these insurance liabilities were $2,157 and $1,878 in the aggregate, and were included in accrued salaries and benefits and other current liabilities in the consolidated balance sheets, classified based on their nature.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The captive receives direct premiums, which are netted against the Company’s premium costs in SG&amp;A expenses in the consolidated statements of income. The captive participates in a reinsurance program that includes third-party participants. The participant agreements and practices of the reinsurance program are designed to limit participating members’ individual risk. Income statement adjustments related to the reinsurance program and related impacts to the consolidated balance sheets are </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">recognized as information becomes known. In the event the Company leaves the reinsurance program, the Company retains its primary obligation to the participants for prior activity.</span></div> 2157000000 1878000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Derivatives</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company is exposed to foreign-currency exchange-rate fluctuations in the normal course of business. It manages these fluctuations, in part, through the use of forward foreign-exchange contracts, seeking to economically hedge the impact of fluctuations of foreign-exchange on known future expenditures denominated in a non-functional foreign-currency. The contracts relate primarily to U.S. dollar merchandise inventory expenditures made by the Company’s international subsidiaries with functional currencies other than the U.S. dollar. These contracts either do not qualify for or the Company has not elected derivative hedge accounting. The Company seeks to mitigate risk with the use of these contracts and does not intend to engage in speculative transactions. Some of these contracts contain credit-risk-related contingent features that require settlement of outstanding contracts upon certain triggering events. The aggregate fair value amounts of derivative instruments in a net liability position and the amount needed to settle the instruments immediately if the credit-risk-related contingent features were triggered were immaterial at the end of 2026 and 2025. The aggregate notional amounts of open, unsettled forward foreign-exchange contracts were $541 and $1,184 at the end of 2026 and 2025. See </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_118" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Note 3</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for information on the fair value of unsettled forward foreign-exchange contracts at the end of 2026 and 2025.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The unrealized gains or losses recognized in interest income and other, net in the consolidated statements of income relating to the net changes in the fair value of unsettled forward foreign-exchange contracts were immaterial in 2026, 2025, and 2024.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company is exposed to fluctuations in prices for energy, particularly electricity and natural gas, and other commodities used in retail and manufacturing operations, which it seeks to partially mitigate through the use of fixed-price contracts for certain of its warehouses and other facilities, primarily in the U.S. and Canada. The Company also enters into variable-priced contracts for some purchases of natural gas, in addition to fuel for its gas stations, on an index basis. These contracts meet the characteristics of derivative instruments, but generally qualify for the “normal purchases and normal sales” exception under authoritative guidance and require no mark-to-market adjustment.</span></div> 541000000 1184000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Foreign-Currency</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The functional currencies of the Company’s international subsidiaries are their local currencies. Assets and liabilities recorded in foreign currencies are translated at the exchange rate on the balance sheet date. Translation adjustments are recorded in accumulated other comprehensive loss. Revenues and expenses of the Company’s consolidated foreign operations are translated at average exchange rates prevailing during the year.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company recognizes foreign-currency transaction gains and losses related to revaluing or settling monetary assets and liabilities denominated in currencies other than the functional currency in interest income and other, net in the consolidated statements of income. Generally, these include the U.S. dollar cash and cash equivalents and the U.S. dollar payables of consolidated subsidiaries revalued to their functional currency. Also included are realized foreign-currency gains or losses from settlements of forward foreign-exchange contracts. These items were immaterial in 2026, 2025, and 2024.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Revenue Recognition</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company recognizes sales for the amount of consideration collected from the member, which includes gross shipping fees where applicable, and is net of sales taxes collected and remitted to government agencies and member returns. The Company reserves for estimated returns based on historical trends and reduces sales and merchandise costs accordingly. The Company records on a gross basis a refund liability and an asset for recovery, which are included in other current liabilities and other current assets, respectively, in the consolidated balance sheets.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company offers merchandise in the following core merchandise categories: foods and sundries, non-foods, and fresh foods. The Company also provides expanded products and services through warehouse ancillary and other businesses. The Company is the principal for the majority of its transactions and recognizes revenue on a gross basis. The Company is the principal when it has control of the merchandise or service before it is transferred to the member. The majority of revenue from merchandise sales is recognized at the point of sale. Revenue generated through e-commerce or special orders is generally recognized upon shipment to the member. For merchandise shipped directly to the member, shipping and handling costs are expensed as incurred as fulfillment costs and included in merchandise costs in the consolidated statements of income. In certain ancillary businesses, revenue is deferred until the member picks up merchandise at the warehouse. Deferred sales are included in other current liabilities in the consolidated balance sheets.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company accounts for membership fee revenue, net of refunds, on a deferred basis, ratably over the one-year membership period. Deferred membership fees at the end of 2026 and 2025 were $3,006 and $2,854.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In most countries, the Company's Executive members qualify for an Executive reward, generally 2% on qualified purchases, subject to an annual maximum value, which does not expire and is redeemable at Costco warehouses. The Company accounts for this reward as a reduction in sales, net of the estimated impact of non-redemptions (breakage), with the corresponding liability classified as accrued member rewards in the consolidated balance sheets. Estimated breakage is computed based on redemption data. For 2026, 2025, and 2024, the net reduction in sales was $3,383, $3,007, and $2,804.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company sells and otherwise provides proprietary shop cards that do not expire and are redeemable at the warehouse or online for merchandise or membership. Revenue from shop cards is recognized upon redemption, and estimated breakage is recognized based on redemption data. The Company accounts for outstanding shop card balances as a liability, net of estimated breakage. Shop card liabilities are included in other current liabilities in the consolidated balance sheets.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Citibank, N.A. is the exclusive issuer of co-branded credit cards to U.S. members. The Company receives various forms of consideration from Citibank, including a royalty on purchases made on the card outside of Costco. A portion of the royalty is used to fund the rebate that cardholders receive, after taking into consideration breakage, which is calculated based on rebate redemption data. The rebates are issued in February and expire on December 31. The Company also maintains varying co-branded credit card arrangements in Canada and certain Other International subsidiaries.</span></div> 3006000000 2854000000 3383000000 3007000000 2804000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Merchandise Costs</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Merchandise costs consist of the purchase price or manufacturing costs of inventory sold, inbound and outbound shipping charges, and all costs related to the Company’s depot, fulfillment, and manufacturing operations, and are reduced by vendor consideration. Merchandise costs also include salaries, benefits, depreciation, and utilities in fresh foods departments and certain ancillary businesses.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Vendor Consideration</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company receives funds from vendors for discounts and a variety of other programs. These programs are evidenced by agreements that are reflected in the carrying value of the inventory when earned or as the Company progresses towards earning the rebate or discount, and as a component of merchandise costs as the merchandise is sold. Other vendor consideration is generally recorded as a reduction of merchandise costs upon completion of contractual milestones, agreement terms, or other systematic approaches.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Selling, General and Administrative Expenses</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Selling, general and administrative expenses consist primarily of salaries, benefits and workers’ compensation costs for warehouse employees (other than fresh foods departments and certain ancillary </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">businesses, which are reflected in merchandise costs), as well as all regional and home office employees, including buying personnel. Selling, general and administrative expenses also include substantially all building and equipment depreciation, stock compensation expense, credit and debit card processing fees, utilities, preopening, as well as other operating costs incurred to support warehouse and e-commerce operations.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Retirement Plans</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company's 401(k) retirement plan is available to all U.S. employees over the age of 18 who have completed 90 days of employment. The plan allows participants to make wage deferral contributions, a portion of which the Company matches. In addition, the Company provides each eligible participant an annual discretionary contribution. The Company also has a defined contribution plan for employees in Canada and contributes a percentage of each employee's wages. Certain subsidiaries in the Company's Other International operations have defined benefit and defined contribution plans, which are immaterial. Amounts expensed under all plans were $1,174, $1,061, and $963 for 2026, 2025, and 2024, and are predominantly included in SG&amp;A expenses in the consolidated statements of income.</span></div> P90D 1174000000 1061000000 963000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Stock-Based Compensation</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company grants stock-based compensation, primarily to employees and non-employee directors. Grants to executive officers are generally performance-based. Through a series of shareholder approvals, there have been amended and restated plans and new provisions implemented by the Company. Restricted Stock Units (RSUs) are subject to quarterly vesting in the event of retirement or voluntary termination. Recipients are not entitled to vote or receive dividends on unvested and undelivered shares. </span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">For grants issued prior to October 2025, RSUs generally vest over <span style="-sec-ix-hidden:f-430">five</span> years, with accelerated vesting provisions for participants reaching specified long-service milestones (25 years of service for employees; five years for non-employee directors). For grants issued in October 2025 and thereafter, RSUs vest over either a <span style="-sec-ix-hidden:f-432">three</span>-year schedule with no accelerated vesting or a <span style="-sec-ix-hidden:f-433">five</span>-year schedule with long-service acceleration, based on a one-time election made by eligible participants in 2025. RSUs granted to new participants vest over a three-year term with no such acceleration.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Compensation expense for awards is predominantly recognized using the straight-line method over the requisite service period for the entire award and forfeitures are recognized as they occur. Under accelerated vesting provisions, compensation expense is recognized upon achievement of the long-service term. The cumulative amount of compensation cost recognized at any point in time equals at least the portion of the grant-date fair value of the award that is vested at that date. The fair value of RSUs is calculated as the market value of the common stock on the measurement date less the present value of the expected dividends forgone during the vesting period.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Stock-based compensation expense is predominantly included in SG&amp;A expenses in the consolidated statements of income. Certain stock-based compensation costs are capitalized or included in the cost of merchandise. See </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_130" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Note 7</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for additional information.</span></div> P25Y <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Income Taxes</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company accounts for income taxes using the asset and liability method. Deferred tax assets and liabilities are recognized for the future tax consequences attributed to differences between the financial statement carrying amounts of existing assets and liabilities and their tax bases, credits and loss carry-forwards. Deferred tax assets and liabilities are measured using tax rates expected to apply to taxable income in the years in which those temporary differences and carry-forwards are expected to be recovered or settled. The effect on deferred tax assets and liabilities of a change in tax rates is recognized in income in the period that includes the enactment date. A valuation allowance is established when necessary to reduce deferred tax assets to amounts that are more likely than not expected to be realized.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The timing and amounts of deductible and taxable items and the probability of sustaining uncertain tax positions requires significant judgment. The benefits of uncertain tax positions are recorded in the Company’s consolidated financial statements only after determining a more-likely-than-not probability that the uncertain tax positions will withstand challenge from tax authorities. When facts and circumstances change, the Company reassesses these probabilities and records changes as appropriate.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Net Income per Common Share</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The computation of basic net income per share uses the weighted average number of shares that were outstanding during the period. The computation of diluted net income per share uses the weighted average number of shares in the basic net income per share calculation plus the number of common shares that would be issued assuming vesting of all potentially dilutive common shares outstanding using the treasury stock method for shares subject to RSUs.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Stock Repurchase Programs</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Repurchased shares of common stock are retired, in accordance with the Washington Business Corporation Act. The par value of repurchased shares is deducted from common stock and the excess repurchase price over par value is deducted by allocation to additional paid-in capital and retained earnings. The amount allocated to additional paid-in capital is the current value of additional paid-in capital per share outstanding and is applied to the number of shares repurchased. Any remaining amount is allocated to retained earnings. See </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_127" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Note 6</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for additional information.</span></div> <div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Recent Accounting Pronouncements Adopted</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In December 2023, the FASB issued ASU 2023-09, which requires public business entities on an annual basis to disclose specific categories in the income-tax rate reconciliation, provide information for reconciling items that meet a quantitative threshold, and disclose certain information about income taxes paid. The standard is effective for annual periods beginning after December 15, 2024, with early adoption permitted. The Company adopted the ASU for the fiscal year ended August 30, 2026, on a prospective basis. See </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_133" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Note 8</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for additional information.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Recent Accounting Pronouncements Not Yet Adopted</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In November 2024, the FASB issued 2024-03, which requires disaggregated disclosures of certain costs and expenses on the income statement on an annual and interim basis. The standard is effective for fiscal years beginning after December 15, 2026, and interim periods within fiscal years beginning after December 15, 2027, with early adoption permitted. The amendments should be applied on a prospective basis. Retrospective application is permitted. The Company is evaluating the standard.</span></div> <div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Note 2—Investments</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company’s investments were as follows:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">2026:</span></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Cost<br/>Basis</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Unrealized<br/>Losses, Net</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Recorded<br/>Basis</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Available-for-sale:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Government and agency securities</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">810 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(14)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">796 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Held-to-maturity:</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Certificates of deposit</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">298 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">298 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total short-term investments</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,108 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(14)</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,094 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">2025:</span></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Cost<br/>Basis</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Unrealized<br/>Gains, Net</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Recorded<br/>Basis</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Available-for-sale:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Government and agency securities</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">783 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">786 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Held-to-maturity:</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Certificates of deposit</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">337 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">337 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total short-term investments</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,120 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,123 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Gross unrecognized holding gains and losses on available-for-sale securities were not material for the years ended August 30, 2026, and August 31, 2025. At those dates, there were no available-for-sale securities in a material continuous unrealized-loss position. There were no sales of available-for-sale securities during 2026 or 2025.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The maturities of available-for-sale and held-to-maturity securities at the end of 2026 are as follows:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr style="height:12pt"><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"></td><td colspan="9" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Available-For-Sale</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" rowspan="2" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Held-To-Maturity</span></td></tr><tr style="height:12pt"><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"></td><td colspan="3" style="border-top:1pt solid #000000;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Cost Basis</span></td><td colspan="3" style="border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="border-top:1pt solid #000000;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Fair Value</span></td><td colspan="3" style="padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Due in one year or less</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">126 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">126 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">298 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Due after one year through five years</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">411 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">405 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Due after five years</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">273 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">265 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">810 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">796 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">298 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company’s investments were as follows:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">2026:</span></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Cost<br/>Basis</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Unrealized<br/>Losses, Net</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Recorded<br/>Basis</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Available-for-sale:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Government and agency securities</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">810 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(14)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">796 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Held-to-maturity:</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Certificates of deposit</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">298 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">298 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total short-term investments</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,108 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(14)</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,094 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">2025:</span></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Cost<br/>Basis</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Unrealized<br/>Gains, Net</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Recorded<br/>Basis</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Available-for-sale:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Government and agency securities</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">783 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">786 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Held-to-maturity:</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Certificates of deposit</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">337 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">337 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total short-term investments</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,120 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,123 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 810000000 14000000 796000000 298000000 298000000 1108000000 14000000 1094000000 783000000 3000000 786000000 337000000 337000000 1120000000 3000000 1123000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The maturities of available-for-sale and held-to-maturity securities at the end of 2026 are as follows:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr style="height:12pt"><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"></td><td colspan="9" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Available-For-Sale</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" rowspan="2" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Held-To-Maturity</span></td></tr><tr style="height:12pt"><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"></td><td colspan="3" style="border-top:1pt solid #000000;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Cost Basis</span></td><td colspan="3" style="border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="border-top:1pt solid #000000;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Fair Value</span></td><td colspan="3" style="padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Due in one year or less</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">126 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">126 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">298 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Due after one year through five years</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">411 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">405 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Due after five years</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">273 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">265 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">810 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">796 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">298 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 126000000 126000000 298000000 411000000 405000000 0 273000000 265000000 0 810000000 796000000 298000000 <div style="margin-bottom:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Note 3—Fair Value Measurement</span></div><div style="margin-bottom:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Assets and Liabilities Measured at Fair Value on a Recurring Basis</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table presents information regarding the Company’s financial assets and liabilities that are measured at fair value on a recurring basis and indicates the level within the hierarchy reflecting the valuation techniques utilized to determine such fair value:</span></div><div style="margin-top:9pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="9" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Level 2</span></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="border-top:1pt solid #000;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="border-top:1pt solid #000;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Investment in government and agency securities</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">796 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">786 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Forward foreign-exchange contracts, in asset position</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Forward foreign-exchange contracts, in (liability) position</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(3)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(14)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">794 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">778 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:9pt;font-weight:400;line-height:120%"> </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">____________</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">The asset and liability values are included in other current assets and other current liabilities, respectively, in the consolidated balance sheets. </span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">At August 30, 2026, and August 31, 2025, the Company did not hold any Level 1 or 3 financial assets or liabilities that were measured at fair value on a recurring basis. There were no transfers between levels during 2026 or 2025.</span></div><div style="margin-bottom:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Assets and Liabilities Measured at Fair Value on a Nonrecurring Basis</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Assets and liabilities recognized and disclosed at fair value on a nonrecurring basis include items such as financial assets measured at amortized cost and long-lived nonfinancial assets. These assets are measured at fair value if determined to be impaired. There were no material fair value adjustments to these items during 2026 and 2025. Please see </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_109" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Note 1</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for additional information.</span></div> <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table presents information regarding the Company’s financial assets and liabilities that are measured at fair value on a recurring basis and indicates the level within the hierarchy reflecting the valuation techniques utilized to determine such fair value:</span></div><div style="margin-top:9pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="9" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Level 2</span></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="border-top:1pt solid #000;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="border-top:1pt solid #000;padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Investment in government and agency securities</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">796 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">786 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Forward foreign-exchange contracts, in asset position</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Forward foreign-exchange contracts, in (liability) position</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(3)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(14)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">794 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">778 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:9pt;font-weight:400;line-height:120%"> </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">____________</span></div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span>The asset and liability values are included in other current assets and other current liabilities, respectively, in the consolidated balance sheets. 796000000 786000000 1000000 6000000 3000000 14000000 794000000 778000000 <div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Note 4—Debt</span></div><div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Short-Term Borrowings</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company maintains various short-term bank credit facilities, with a borrowing capacity of $2,118 and $1,220, in 2026 and 2025. This increase was primarily driven by the renewal and expansion of the Company's U.S. revolving credit facility in August 2026, which increased total borrowing capacity from $400 to $1,000 and extended the maturity date to August 2027, as well as credit facility expansions in the Japan and Mexico subsidiaries. There were no short-term borrowings outstanding at the end of 2026, and short-term borrowings were immaterial at the end of 2025.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Long-Term Debt</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company's long-term debt consists primarily of Senior Notes, described below. The Company at its option may redeem the Senior Notes at any time, in whole or in part, at a redemption price plus accrued interest. The redemption price is equal to the greater of 100% of the principal amount or the sum of the present value of the remaining scheduled payments of principal and interest to maturity. Additionally, upon certain events, a holder has the right to require a repurchase at a price of 101% of the principal amount plus accrued and unpaid interest. Interest on all outstanding long-term debt is payable semi-annually. The estimated fair value of Senior Notes is valued using Level 2 inputs.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Other long-term debt consists of Guaranteed Senior Notes issued by the Company's Japanese subsidiary, valued using Level 3 inputs. In 2026, the Company’s Japan subsidiary issued three series of Guaranteed Senior Notes, totaling approximately $500, at fixed interest rates ranging from 2.620% to 3.680%. Interest is payable semi-annually, and maturity dates range from June 2031 to June 2041. In 2026, 2025, and 2024 the Japanese subsidiary repaid $69, $103, and $77 of its Guaranteed Senior Notes.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In 2024, the Company repaid the $1,000 outstanding principal balance on its 2.750% Senior Notes.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">At the end of 2026 and 2025, the fair value of the Company's long-term debt, including the current portion, was $5,689 and $5,370. The carrying value of long-term debt consisted of the following:</span></div><div><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.000% Senior Notes due May 2027</span></div></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,000 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,000 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.375% Senior Notes due June 2027</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,250 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,250 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.600% Senior Notes due April 2030</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,750 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,750 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.750% Senior Notes due April 2032</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,000 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,000 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other long-term debt</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,175 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">805 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total long-term debt</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,175 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5,805 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Less unamortized debt discounts and issuance costs</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">13 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">17 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div style="padding-left:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Less current portion</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,248 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">75 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Long-term debt, excluding current portion</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,914 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5,713 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">_____________</span></div><div style="margin-bottom:9pt;padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Net of unamortized debt discounts and issuance costs.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Maturities of long-term debt during the next five fiscal years and thereafter are as follows:</span></div><div style="margin-bottom:9pt;margin-top:5pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:80.310%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.490%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2027</span></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,250 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2028</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2029</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">136 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2030</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,750 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2031</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">161 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Thereafter</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,878 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:36pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></div></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,175 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 2118000000 1220000000 400000000 1000000000 1 1.01 500000000 0.02620 0.03680 69000000 103000000 77000000 1000000000 0.02750 5689000000 5370000000 The carrying value of long-term debt consisted of the following:<div><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.000% Senior Notes due May 2027</span></div></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,000 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,000 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.375% Senior Notes due June 2027</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,250 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,250 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.600% Senior Notes due April 2030</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,750 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,750 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.750% Senior Notes due April 2032</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,000 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,000 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other long-term debt</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,175 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">805 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total long-term debt</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,175 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5,805 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Less unamortized debt discounts and issuance costs</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">13 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">17 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div style="padding-left:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Less current portion</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,248 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">75 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Long-term debt, excluding current portion</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,914 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5,713 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">_____________</span></div><div style="margin-bottom:9pt;padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Net of unamortized debt discounts and issuance costs.</span></div> 0.03000 1000000000 1000000000 0.01375 1250000000 1250000000 0.01600 1750000000 1750000000 0.01750 1000000000 1000000000 1175000000 805000000 6175000000 5805000000 13000000 17000000 2248000000 75000000 3914000000 5713000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Maturities of long-term debt during the next five fiscal years and thereafter are as follows:</span></div><div style="margin-bottom:9pt;margin-top:5pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:80.310%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.490%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2027</span></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,250 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2028</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2029</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">136 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2030</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,750 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2031</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">161 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Thereafter</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,878 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:36pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></div></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,175 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 2250000000 0 136000000 1750000000 161000000 1878000000 6175000000 <div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Note 5—Leases</span></div><div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Information regarding the Company's lease assets and liabilities were as follows:</span></div><div style="margin-bottom:1pt;margin-top:9pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:99.839%"><tr><td style="width:1.0%"></td><td style="width:60.858%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.519%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.521%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Assets</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease right-of-use assets</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,697 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,725 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance lease assets</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,413 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,488 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total lease assets</span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,110 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,213 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Liabilities</span></td><td colspan="3" style="background-color:#cceeff;border-top:3pt double #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:3pt double #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Current</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease liabilities</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(2)</span></div></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">192 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">208 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance lease liabilities</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(2)</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">94 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">78 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Long-term</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease liabilities</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,414 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,460 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance lease liabilities</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(3)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,319 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,401 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total lease liabilities</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,019 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,147 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:3pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> _______________</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Included in <span style="-sec-ix-hidden:f-559"><span style="-sec-ix-hidden:f-560">other long-term assets</span></span> in the consolidated balance sheets.</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(2)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Included in <span style="-sec-ix-hidden:f-561"><span style="-sec-ix-hidden:f-562"><span style="-sec-ix-hidden:f-563"><span style="-sec-ix-hidden:f-564">other current liabilities</span></span></span></span> in the consolidated balance sheets.</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(3)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Included in <span style="-sec-ix-hidden:f-565"><span style="-sec-ix-hidden:f-566">other long-term liabilities</span></span> in the consolidated balance sheets.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Weighted-average remaining lease term (years)</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating leases</span></div></td><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">19</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">20</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance leases</span></div></td><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">23</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">25</span></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Weighted-average discount rate</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating leases</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.20 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.05 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance leases</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4.72 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4.63 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td></tr></table></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The components of lease expense, excluding short-term lease costs and sublease income (which were immaterial), were as follows:</span></div><div style="margin-bottom:1pt;margin-top:9pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:99.839%"><tr><td style="width:1.0%"></td><td style="width:52.511%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.831%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease costs</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">282 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">271 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">284 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance lease costs:</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Amortization of lease assets</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">106 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">102 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">97 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Interest on lease liabilities</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(2)</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">64 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">63 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">58 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Variable lease costs</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">195 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">182 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">163 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total lease costs</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">647 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">618 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">602 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:3pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> _______________</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Included in selling, general and administrative expenses and merchandise costs in the consolidated statements of income.</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(2)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Included in interest expense and merchandise costs in the consolidated statements of income.</span></div><div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Supplemental cash flow information related to leases were as follows:</span></div><div style="margin-bottom:9pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:99.839%"><tr><td style="width:1.0%"></td><td style="width:52.511%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.831%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Cash paid for amounts included in the measurement of lease liabilities:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating cash flows — operating leases</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">312 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">255 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">274 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating cash flows — finance leases</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">62 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">58 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">58 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Financing cash flows — finance leases</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">89 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">147 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">136 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease assets obtained in exchange for new or modified leases</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">238 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">294 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">125 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance lease assets obtained in exchange for new or modified leases</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">122 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">131 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">200 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">As of August 30, 2026, future minimum payments during the next five fiscal years and thereafter are as follows:</span></div><div style="margin-bottom:1pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-align:center"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Operating Leases</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:5.2pt;font-weight:700;line-height:100%;position:relative;top:-2.8pt;vertical-align:baseline">(1)</span></div></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Finance Leases</span></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2027</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">252 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">146 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2028</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">258 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">142 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2029</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">226 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">130 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2030</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">204 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">118 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2031</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">186 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">97 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Thereafter</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,399 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,657 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(2)</span></div></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,525 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,290 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Less amount representing interest</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">919 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">877 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Present value of lease liabilities</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,606 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,413 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr></table></div><div style="margin-bottom:3pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> _______________</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Operating lease payments have not been reduced by expected future sublease income of $90.</span></div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(2)</span>Excludes $1,667 of lease payments <div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Information regarding the Company's lease assets and liabilities were as follows:</span></div><div style="margin-bottom:1pt;margin-top:9pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:99.839%"><tr><td style="width:1.0%"></td><td style="width:60.858%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.519%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.521%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Assets</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease right-of-use assets</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,697 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,725 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance lease assets</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,413 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,488 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total lease assets</span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,110 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,213 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Liabilities</span></td><td colspan="3" style="background-color:#cceeff;border-top:3pt double #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:3pt double #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Current</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease liabilities</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(2)</span></div></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">192 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">208 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance lease liabilities</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(2)</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">94 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">78 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Long-term</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease liabilities</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,414 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,460 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance lease liabilities</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(3)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,319 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,401 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total lease liabilities</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,019 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,147 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:3pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> _______________</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Included in <span style="-sec-ix-hidden:f-559"><span style="-sec-ix-hidden:f-560">other long-term assets</span></span> in the consolidated balance sheets.</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(2)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Included in <span style="-sec-ix-hidden:f-561"><span style="-sec-ix-hidden:f-562"><span style="-sec-ix-hidden:f-563"><span style="-sec-ix-hidden:f-564">other current liabilities</span></span></span></span> in the consolidated balance sheets.</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(3)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Included in <span style="-sec-ix-hidden:f-565"><span style="-sec-ix-hidden:f-566">other long-term liabilities</span></span> in the consolidated balance sheets.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Weighted-average remaining lease term (years)</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating leases</span></div></td><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">19</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">20</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance leases</span></div></td><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">23</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">25</span></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Weighted-average discount rate</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating leases</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.20 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.05 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance leases</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4.72 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4.63 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td></tr></table></div> 2697000000 2725000000 1413000000 1488000000 4110000000 4213000000 192000000 208000000 94000000 78000000 2414000000 2460000000 1319000000 1401000000 4019000000 4147000000 P19Y P20Y P23Y P25Y 0.0320 0.0305 0.0472 0.0463 <div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The components of lease expense, excluding short-term lease costs and sublease income (which were immaterial), were as follows:</span></div><div style="margin-bottom:1pt;margin-top:9pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:99.839%"><tr><td style="width:1.0%"></td><td style="width:52.511%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.831%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease costs</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">282 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">271 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">284 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance lease costs:</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Amortization of lease assets</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">106 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">102 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">97 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Interest on lease liabilities</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(2)</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">64 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">63 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">58 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Variable lease costs</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">195 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">182 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">163 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total lease costs</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">647 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">618 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">602 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:3pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> _______________</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Included in selling, general and administrative expenses and merchandise costs in the consolidated statements of income.</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(2)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Included in interest expense and merchandise costs in the consolidated statements of income.</span></div><div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Supplemental cash flow information related to leases were as follows:</span></div><div style="margin-bottom:9pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:99.839%"><tr><td style="width:1.0%"></td><td style="width:52.511%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.831%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Cash paid for amounts included in the measurement of lease liabilities:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating cash flows — operating leases</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">312 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">255 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">274 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating cash flows — finance leases</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">62 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">58 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">58 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-indent:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Financing cash flows — finance leases</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">89 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">147 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">136 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease assets obtained in exchange for new or modified leases</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">238 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">294 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">125 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Finance lease assets obtained in exchange for new or modified leases</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">122 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">131 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">200 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 282000000 271000000 284000000 106000000 102000000 97000000 64000000 63000000 58000000 195000000 182000000 163000000 647000000 618000000 602000000 312000000 255000000 274000000 62000000 58000000 58000000 89000000 147000000 136000000 238000000 294000000 125000000 122000000 131000000 200000000 <div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">As of August 30, 2026, future minimum payments during the next five fiscal years and thereafter are as follows:</span></div><div style="margin-bottom:1pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-align:center"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Operating Leases</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:5.2pt;font-weight:700;line-height:100%;position:relative;top:-2.8pt;vertical-align:baseline">(1)</span></div></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Finance Leases</span></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2027</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">252 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">146 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2028</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">258 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">142 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2029</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">226 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">130 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2030</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">204 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">118 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2031</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">186 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">97 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Thereafter</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,399 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,657 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(2)</span></div></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,525 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,290 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Less amount representing interest</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">919 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">877 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Present value of lease liabilities</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,606 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,413 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr></table></div><div style="margin-bottom:3pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> _______________</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Operating lease payments have not been reduced by expected future sublease income of $90.</span></div><div style="margin-bottom:9pt;padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(2)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Excludes $1,667 of lease payments for leases that have been signed but not commenced.</span></div> <div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">As of August 30, 2026, future minimum payments during the next five fiscal years and thereafter are as follows:</span></div><div style="margin-bottom:1pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="text-align:center"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Operating Leases</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:5.2pt;font-weight:700;line-height:100%;position:relative;top:-2.8pt;vertical-align:baseline">(1)</span></div></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Finance Leases</span></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2027</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">252 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">146 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2028</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">258 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">142 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2029</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">226 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">130 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2030</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">204 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">118 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2031</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">186 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">97 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Thereafter</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,399 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,657 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(2)</span></div></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,525 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,290 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Less amount representing interest</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">919 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">877 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Present value of lease liabilities</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,606 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,413 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr></table></div><div style="margin-bottom:3pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> _______________</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Operating lease payments have not been reduced by expected future sublease income of $90.</span></div><div style="margin-bottom:9pt;padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(2)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Excludes $1,667 of lease payments for leases that have been signed but not commenced.</span></div> 252000000 146000000 258000000 142000000 226000000 130000000 204000000 118000000 186000000 97000000 2399000000 1657000000 3525000000 2290000000 919000000 877000000 2606000000 1413000000 90000000 1667000000 <div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Note 6—Equity</span></div><div style="margin-bottom:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Dividends</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Cash dividends declared in 2026 totaled $2,458 or $5.54 per share, as compared to $2,183 or $4.92 per share in 2025. Dividends in 2024 included a special dividend of $15 per share, resulting in a payment of $6,655. The Company's current quarterly dividend rate is $1.47 per share.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Stock Repurchase Programs</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company's stock repurchase program is conducted under a $4,000 authorization by the Board of Directors, which expires in January 2027. As of the end of 2026, the remaining amount available under the authorization was $1,115. The following table summarizes the Company’s stock repurchase activity:</span></div><div style="margin-bottom:9pt;margin-top:5pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Shares<br/>Repurchased<br/>(000’s)</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Average<br/>Price per<br/>Share</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Total Cost</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2026</span></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">891 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">950.90 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">847 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2025</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">943 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">957.66 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">903 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2024</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,004 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">695.29 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">698 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">These amounts may differ from repurchases of common stock in the consolidated statements of cash flows due to changes in unsettled stock repurchases at the end of each fiscal year. Purchases are made from time to time, as conditions warrant, in the open market or in block purchases and pursuant to plans under SEC Rule 10b5-1.</span></div> 2458000000 5.54 2183000000 4.92 15 6655000000 1.47 4000000000 1115000000 The following table summarizes the Company’s stock repurchase activity:<div style="margin-bottom:9pt;margin-top:5pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Shares<br/>Repurchased<br/>(000’s)</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Average<br/>Price per<br/>Share</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Total Cost</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2026</span></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">891 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">950.90 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">847 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2025</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">943 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">957.66 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">903 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2024</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,004 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">695.29 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">698 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 891000 950.90 847000000 943000 957.66 903000000 1004000 695.29 698000000 <div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Note 7—Stock-Based Compensation</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The 2019 Incentive Plan authorizes the issuance of up to 15,885,000 RSUs. The number of RSUs that may be granted under this Plan is subject to adjustments for changes in capital structure. The Company issues new shares of common stock upon vesting and settlement of RSUs. Shares for vested RSUs are generally delivered to participants annually, net of shares withheld for taxes.</span></div><div style="margin-bottom:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Summary of Restricted Stock Unit Activity</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">At the end of 2026, 5,280,000 shares were available to be granted as RSUs, and the following awards were outstanding:</span></div><div style="padding-left:31.5pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">•</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;padding-left:14.5pt">1,877,000 time-based RSUs, which vest upon continued employment or service over specified periods of time; and</span></div><div style="margin-bottom:9pt;padding-left:31.5pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">•</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;padding-left:14.5pt">123,000 performance-based RSUs, of which 67,000 were granted to executive officers subject to the determination of the attainment of performance targets for 2026, which occurred in September 2026. At that time, a portion vested as a result of executive officers who met accelerated vesting provisions. The remaining awards vest upon continued employment over specified periods of time. Please refer to </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_109" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Note 1</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for accelerated vesting requirements.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table summarizes RSU transactions during 2026:</span></div><div style="margin-bottom:9pt;margin-top:5pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Number of<br/>Units<br/>(in 000’s)</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Weighted-Average<br/>Grant Date Fair<br/>Value</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Outstanding at the end of 2025</span></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,308 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">597.00 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Granted</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,088 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">933.56 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Vested and delivered</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(1,303)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">669.59 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Forfeited</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(93)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">696.05 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Outstanding at the end of 2026</span></td><td colspan="2" style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,000 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">728.17 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The weighted-average grant date fair value of RSUs granted was $933.56, $883.46, and $547.26 in 2026, 2025, and 2024. The remaining unrecognized compensation cost related to non-vested RSUs at the end of 2026 was $922 and the weighted-average period of time over which this cost will be recognized is 1.5 years. Included in the outstanding balance at the end of 2026 were approximately 704,000 RSUs vested but not yet delivered.</span></div><div style="margin-bottom:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Summary of Stock-Based Compensation</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table summarizes stock-based compensation expense and the related tax benefits:</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Stock-based compensation expense</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">924 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">860 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">818 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Less recognized income tax benefit</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline"> </span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">212 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">183 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">173 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Stock-based compensation expense, net</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">712 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">677 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">645 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 15885000 5280000 1877000 123000 67000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table summarizes RSU transactions during 2026:</span></div><div style="margin-bottom:9pt;margin-top:5pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Number of<br/>Units<br/>(in 000’s)</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">Weighted-Average<br/>Grant Date Fair<br/>Value</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Outstanding at the end of 2025</span></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,308 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">597.00 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Granted</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,088 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">933.56 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Vested and delivered</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(1,303)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">669.59 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Forfeited</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(93)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">696.05 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Outstanding at the end of 2026</span></td><td colspan="2" style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,000 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">728.17 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 2308000 597.00 1088000 933.56 1303000 669.59 93000 696.05 2000000 728.17 933.56 883.46 547.26 922000000 P1Y6M 704000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table summarizes stock-based compensation expense and the related tax benefits:</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Stock-based compensation expense</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">924 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">860 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">818 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Less recognized income tax benefit</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline"> </span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">212 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">183 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">173 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Stock-based compensation expense, net</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">712 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">677 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">645 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 924000000 860000000 818000000 212000000 183000000 173000000 712000000 677000000 645000000 <div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Note 8—Taxes</span></div><div style="text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Income Taxes</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Income before income taxes is comprised of the following:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Domestic</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9,070 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">8,324 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">7,255 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,181 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,494 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,485 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">12,251 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">10,818 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9,740 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The provisions for income taxes are as follows:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Federal:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Current</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,206 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,395 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,245 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">328 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(42)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">48 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total federal</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,534 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,353 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,293 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">State:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Current</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">472 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">449 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">431 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">21 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(18)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(77)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total state</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">493 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">431 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">354 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Current</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,041 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">955 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">798 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(43)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(20)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(72)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total foreign</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">998 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">935 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">726 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total provision for income taxes</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,025 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,719 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,373 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The reconciliation between the statutory tax rate and the effective rate for 2026 is as follows:</span></div><div style="margin-bottom:1pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:68.291%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.805%"></td><td style="width:0.1%"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"></td><td colspan="9" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Federal taxes at statutory rate</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%"><span style="-sec-ix-hidden:f-725">2,573</span> </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">21.0 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">State and local income taxes, net of federal income tax effect</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">402 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.3 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign tax effects:</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Canada - subnational taxes</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">185 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.5 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Canada - other</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(12)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.1)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other foreign jurisdictions</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">117 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.0 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Effect of cross-border tax laws</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(46)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.4)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Tax credits:</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Research and development</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(134)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(1.1)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other tax credits</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(99)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.8)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Changes in valuation allowance</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">62 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">0.5 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Nontaxable or nondeductible items</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(75)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.6)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Changes in unrecognized tax benefits</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">50 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">0.4 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other adjustments</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,025 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">24.7 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr></table><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> _______________</span></div><div style="margin-bottom:9pt;padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">State taxes in California, New York, New Jersey, and Oregon make up the majority (greater than 50%) of the tax effect in this category.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The reconciliation between the statutory tax rate and the effective rate for 2025 and 2024 is as follows:</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:66.367%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:6.432%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:6.432%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:6.432%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:6.434%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"></td><td colspan="9" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="9" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Federal taxes at statutory rate</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,272 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">21.0 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,045 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">21.0 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">State taxes, net</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">338 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.1 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">288 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.0 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign taxes, net</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">222 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2.1 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">109 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.1 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Employee stock ownership plan (ESOP)</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(28)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.3)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(120)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(1.2)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(85)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.8)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">51 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">0.5 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,719 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">25.1 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,373 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">24.4 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td></tr></table></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company's effective tax rate in 2026, 2025, and 2024 included tax benefits of $72, $100, and $45, related to stock compensation. In 2024, tax benefits also included $94 related to the portion of the special dividend payable through the Company's 401(k) plan and a net non-recurring tax benefit of $63 related to a transfer pricing settlement and certain true-ups of tax reserves.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following is a supplemental schedule of cash paid for income taxes, net of refunds:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:83.996%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.804%"></td><td style="width:0.1%"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">U.S. federal</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,377 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">U.S. state and local:</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">California</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">209 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">322 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign:</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Canada</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">430 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Mexico</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">185 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">316 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,839 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr></table></div><div style="margin-bottom:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The components of the deferred tax assets (liabilities) are as follows:</span></div><div style="margin-top:5pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred tax assets:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Equity compensation</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">122 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">100 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred income/membership fees</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">398 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">369 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign tax credit carry forward</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">470 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">390 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease liabilities</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">710 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">699 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Accrued liabilities and reserves</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,041 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">917 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total deferred tax assets</span></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,741 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,475 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Valuation allowance</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(641)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(554)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total net deferred tax assets</span></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,100 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,921 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred tax liabilities:</span></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(1,372)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(944)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise inventories</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(344)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(305)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease right-of-use assets</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(675)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(670)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign branch deferreds</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(107)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(103)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(33)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(31)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total deferred tax liabilities</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(2,531)</span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(2,053)</span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Net deferred tax liabilities</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(431)</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(132)</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The deferred tax accounts at the end of 2026 and 2025 include deferred income tax assets of $635 and $592, included in other long-term assets; and deferred income tax liabilities of $1,066 and $724, included in other long-term liabilities.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In 2026 and 2025, the Company had valuation allowances of $641 and $554, primarily related to foreign tax credits that the Company believes will not be realized due to carry forward limitations. The foreign tax credit carry forwards are set to expire beginning in fiscal 2030.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company generally no longer considers fiscal year earnings of non-U.S. consolidated subsidiaries (other than China) indefinitely reinvested after 2023, in the case of Taiwan, and after 2017, in the case of all other subsidiaries, and has recorded the estimated incremental foreign withholding taxes (net of available foreign tax credits) and state income taxes payable assuming a hypothetical repatriation to the U.S. The Company considers undistributed earnings of certain non-U.S. consolidated subsidiaries, which totaled $3,230, to be indefinitely reinvested and has not provided for withholding or state taxes.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">A reconciliation of the beginning and ending amount of gross unrecognized tax benefits for 2026 and 2025 is as follows:</span></div><div style="margin-bottom:9pt;margin-top:5pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross unrecognized tax benefit at beginning of year</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">65 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">81 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross increases—current year tax positions</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">18 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross increases—tax positions in prior years</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">25 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">14 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross decreases—tax positions in prior years</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(6)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(38)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross decreases—settlements</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(8)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(1)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross unrecognized tax benefit at end of year</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">94 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">65 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">At the end of 2026 and 2025, there were $94 and $65 of unrecognized tax benefits that if recognized would affect the annual effective tax rate.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Accrued interest and penalties related to income tax matters are classified as a component of income tax expense. Accrued interest and penalties recognized during 2026 and 2025, and accrued at the end of each respective period were immaterial.</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company files income tax returns in the U.S., various state and local jurisdictions, and in several foreign jurisdictions. With few exceptions, the Company is no longer subject to U.S. federal, state or local examination for years before fiscal 2018.</span></div><div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Other Taxes</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company is subject to multiple examinations for value added, sales-based, payroll, product, import, or other non-income taxes in various jurisdictions. In certain cases, the Company has received assessments from the authorities. Possible losses or range of possible losses associated with these matters are either immaterial or an estimate of the possible loss or range of loss cannot be made at this time. If certain matters or a group of matters were to be decided adversely to the Company, it could result in a charge that might be material to the results of an individual fiscal quarter or year.</span></div> <div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Income before income taxes is comprised of the following:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Domestic</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9,070 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">8,324 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">7,255 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,181 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,494 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,485 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">12,251 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">10,818 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9,740 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 9070000000 8324000000 7255000000 3181000000 2494000000 2485000000 12251000000 10818000000 9740000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The provisions for income taxes are as follows:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Federal:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Current</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,206 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,395 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,245 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">328 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(42)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">48 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total federal</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,534 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,353 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,293 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">State:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Current</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">472 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">449 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">431 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">21 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(18)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(77)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total state</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">493 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">431 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">354 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Current</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,041 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">955 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">798 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(43)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(20)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(72)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total foreign</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">998 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">935 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">726 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total provision for income taxes</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,025 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,719 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,373 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 1206000000 1395000000 1245000000 328000000 -42000000 48000000 1534000000 1353000000 1293000000 472000000 449000000 431000000 21000000 -18000000 -77000000 493000000 431000000 354000000 1041000000 955000000 798000000 -43000000 -20000000 -72000000 998000000 935000000 726000000 3025000000 2719000000 2373000000 <div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The reconciliation between the statutory tax rate and the effective rate for 2026 is as follows:</span></div><div style="margin-bottom:1pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:68.291%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.805%"></td><td style="width:0.1%"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"></td><td colspan="9" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Federal taxes at statutory rate</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%"><span style="-sec-ix-hidden:f-725">2,573</span> </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">21.0 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">State and local income taxes, net of federal income tax effect</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">402 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.3 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign tax effects:</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Canada - subnational taxes</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">185 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.5 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Canada - other</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(12)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.1)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other foreign jurisdictions</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">117 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.0 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Effect of cross-border tax laws</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(46)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.4)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Tax credits:</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Research and development</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(134)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(1.1)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other tax credits</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(99)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.8)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Changes in valuation allowance</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">62 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">0.5 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Nontaxable or nondeductible items</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(75)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.6)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Changes in unrecognized tax benefits</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">50 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">0.4 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other adjustments</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">— </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,025 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">24.7 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr></table><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> _______________</span></div><div style="margin-bottom:9pt;padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">State taxes in California, New York, New Jersey, and Oregon make up the majority (greater than 50%) of the tax effect in this category.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The reconciliation between the statutory tax rate and the effective rate for 2025 and 2024 is as follows:</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:66.367%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:6.432%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:6.432%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:6.432%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:6.434%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:1.5pt 1pt;text-align:left;vertical-align:bottom"></td><td colspan="9" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="9" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Federal taxes at statutory rate</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,272 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">21.0 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,045 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">21.0 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">State taxes, net</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">338 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.1 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">288 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3.0 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign taxes, net</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">222 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2.1 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">109 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1.1 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Employee stock ownership plan (ESOP)</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(28)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.3)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(120)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(1.2)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(85)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(0.8)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">51 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">0.5 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,719 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">25.1 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,373 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">24.4 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">%</span></td></tr></table></div> 2573000000 0.210 402000000 0.033 185000000 0.015 -12000000 -0.001 117000000 0.010 -46000000 -0.004 134000000 0.011 99000000 0.008 62000000 0.005 -75000000 -0.006 50000000 0.004 2000000 0 3025000000 0.247 2272000000 0.210 2045000000 0.210 338000000 0.031 288000000 0.030 222000000 0.021 109000000 0.011 28000000 0.003 120000000 0.012 -85000000 -0.008 51000000 0.005 2719000000 0.251 2373000000 0.244 72000000 100000000 45000000 94000000 -63000000 <div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following is a supplemental schedule of cash paid for income taxes, net of refunds:</span></div><div style="margin-bottom:9pt;margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:83.996%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.804%"></td><td style="width:0.1%"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">U.S. federal</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,377 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">U.S. state and local:</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">California</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">209 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">322 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign:</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Canada</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">430 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Mexico</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">185 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">316 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,839 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr></table></div> 1377000000 209000000 322000000 430000000 185000000 316000000 2839000000 <div style="margin-bottom:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The components of the deferred tax assets (liabilities) are as follows:</span></div><div style="margin-top:5pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred tax assets:</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Equity compensation</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">122 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">100 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred income/membership fees</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">398 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">369 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign tax credit carry forward</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">470 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">390 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease liabilities</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">710 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">699 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Accrued liabilities and reserves</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,041 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">917 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total deferred tax assets</span></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,741 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,475 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Valuation allowance</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(641)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(554)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total net deferred tax assets</span></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,100 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,921 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Deferred tax liabilities:</span></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(1,372)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(944)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise inventories</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(344)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(305)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating lease right-of-use assets</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(675)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(670)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foreign branch deferreds</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(107)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(103)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(33)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(31)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total deferred tax liabilities</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(2,531)</span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(2,053)</span></td><td style="background-color:#ffffff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 37pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Net deferred tax liabilities</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(431)</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(132)</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 122000000 100000000 398000000 369000000 470000000 390000000 710000000 699000000 1041000000 917000000 2741000000 2475000000 641000000 554000000 2100000000 1921000000 1372000000 944000000 344000000 305000000 675000000 670000000 107000000 103000000 33000000 31000000 2531000000 2053000000 431000000 132000000 635000000 592000000 1066000000 724000000 641000000 554000000 3230000000 <div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">A reconciliation of the beginning and ending amount of gross unrecognized tax benefits for 2026 and 2025 is as follows:</span></div><div style="margin-bottom:9pt;margin-top:5pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:60.919%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.489%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:17.491%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross unrecognized tax benefit at beginning of year</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">65 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">81 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross increases—current year tax positions</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">18 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross increases—tax positions in prior years</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">25 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">14 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross decreases—tax positions in prior years</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(6)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(38)</span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 19pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross decreases—settlements</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(8)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">(1)</span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td><td colspan="3" style="display:none"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Gross unrecognized tax benefit at end of year</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">94 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">65 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 65000000 81000000 18000000 9000000 25000000 14000000 6000000 38000000 8000000 1000000 94000000 65000000 94000000 65000000 <div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Note 9—Net Income per Common and Common Equivalent Share</span></div><div style="text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table shows the amounts used in computing net income per share and the weighted average number of shares of basic and of potentially dilutive common shares outstanding (shares in 000’s):</span></div><div style="margin-bottom:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Net income</span></div></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9,226 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">8,099 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">7,367 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Weighted average basic shares</span></div></td><td colspan="2" style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">443,953 </span></td><td style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">443,985 </span></td><td style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">443,914 </span></td><td style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">RSUs</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">474 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">818 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">845 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Weighted average diluted shares</span></div></td><td colspan="2" style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">444,427 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">444,803 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">444,759 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Basic earnings per share is calculated by dividing net income by the weighted average number of shares of common stock outstanding during the period. Diluted earnings per share is calculated based on the dilutive effect of RSUs using the treasury stock method.</span></div> <div style="text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table shows the amounts used in computing net income per share and the weighted average number of shares of basic and of potentially dilutive common shares outstanding (shares in 000’s):</span></div><div style="margin-bottom:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Net income</span></div></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9,226 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">8,099 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">7,367 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Weighted average basic shares</span></div></td><td colspan="2" style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">443,953 </span></td><td style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">443,985 </span></td><td style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">443,914 </span></td><td style="background-color:#ffffff;border-top:3pt double #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">RSUs</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">474 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">818 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">845 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Weighted average diluted shares</span></div></td><td colspan="2" style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">444,427 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">444,803 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">444,759 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 9226000000 8099000000 7367000000 443953000 443985000 443914000 474000 818000 845000 444427000 444803000 444759000 <div style="margin-bottom:9pt;margin-top:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Note 10—Commitments and Contingencies</span></div><div style="margin-bottom:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Legal Proceedings</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company is involved in many claims, proceedings, and litigations arising from its business and property ownership. In accordance with accounting guidance, the Company establishes an accrual for legal proceedings if and when those matters present loss contingencies that are both probable and reasonably estimable. There may be actual losses in excess of amounts accrued. The Company monitors those matters for developments that would affect the likelihood of a loss (considering where applicable indemnification arrangements concerning suppliers and insurers) and the accrued amount, if any, thereof, and adjusts the amount as appropriate. The Company has recorded an immaterial accrual with respect to some matters described below, in addition to other immaterial accruals for matters not described below. If the loss contingency at issue is not both probable and reasonably estimable, the Company does not establish an accrual, but monitors for developments that make the contingency both probable and reasonably estimable. In each case, there is a reasonable possibility that a loss may be incurred, including a loss in excess of the applicable accrual. For matters where no accrual has been recorded, the possible loss or range of loss (including any loss in excess of the accrual) cannot, in the Company's view, be reasonably estimated because, among other things: the remedies or penalties sought are indeterminate or unspecified; the legal and/or factual theories are not well developed; and/or the matters involve complex or novel legal theories or a large number of parties.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In November 2023, a former employee filed a class action against the Company alleging claims under California law for failure to pay minimum wage, failure to pay overtime, failure to provide meal and rest </span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">breaks, failure to provide accurate wage statements, failure to reimburse expenses, failure to pay wages when due, and failure to pay sick pay. </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Martin Reyes v. Costco Wholesale Corp.</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> (No. 23cv011351; Sacramento County Superior Court), removed to federal court (No. 2:24-cv-00300; E.D. Cal.). A second amended complaint was filed, which the Company has moved to dismiss. In January 2024, the same plaintiff filed a related Private Attorneys General Act (PAGA) representative action, seeking civil penalties and asserting the same alleged underlying Labor Code violations and an additional suitable seating claim. In May 2024, the plaintiff filed an amended PAGA complaint; the Company has denied the material allegations of the complaint and filed a motion to stay the action. The motion was granted on December 18, 2024.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In August 2024, an employee filed an action under PAGA against the Company, alleging claims for penalties for various alleged violations of the California Labor Code. </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Nader v. Costco</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> (No. CV-24-006198; Stanislaus County Superior Court). An amended complaint was filed in November 2024. In February 2025 the court granted the Company’s motion to strike portions of the complaint. The plaintiff filed a further amended complaint; the Company's motion to strike a portion of this complaint was granted on May 13, 2025. The Company's motion to stay the action was granted on November 13, 2025.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In January 2026, a class action on behalf of Washington employees was filed against the Company alleging failure to provide meal periods and rest breaks and to compensate for violations, wage theft, and failure to furnish accurate wage statements. The complaint seeks compensatory and exemplary damages, interest, and attorneys' fees. </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Madera v. Costco Wholesale Corp. </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">(No. 26-2-02879-6; King County Superior Court). A similar class action was filed in March 2026. </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Howell v. Costco Wholesale Corp. </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">(No. 26-2-09459-5; King County Superior Court). </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Howell</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> was subsequently dismissed. The Company has reached an agreement to resolve </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Madera</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> for an immaterial amount, subject to court approval.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Beginning in December 2017, the United States Judicial Panel on Multidistrict Litigation consolidated numerous cases concerning the impacts of opioid abuses filed against various defendants by counties, cities, hospitals, Native American tribes, third-party payors, and others. In re National Prescription Opiate Litigation (MDL No. 2804) (N.D. Ohio). Cases filed against the Company by counties and cities in Michigan, New Jersey, Oregon, Virginia, and South Carolina, a hospital in Texas, and class actions and individual actions filed on behalf of individuals seeking to recover alleged increased insurance costs associated with opioid abuse in 43 states and American Samoa have been resolved or dismissed. A claim by a third-party payor in Ohio and actions filed on behalf of infants born with opioid-related medical conditions in 40 states remain in the MDL. A claim against the Company filed in federal court outside the MDL by one county in Georgia is pending, and claims filed by certain cities and counties in New York are pending in state court, as are claims by certain county district attorneys in Pennsylvania. Claims against the Company in state courts in New Jersey, Oklahoma, Utah, and Arizona have been dismissed. Claims against the Company in federal court in Georgia and Florida have been dismissed. The Company is defending all of the pending matters remaining.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In June 2025, a former employee filed a class action alleging that the Company restricted workers earning less than twice the minimum wage from having a second job in violation of the Washington law. </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Gray, et al., v. Costco Wholesale Corp.</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> (No. 25-2-17717-3; King County Superior Court). In October 2025 the court denied the Company’s motion to dismiss. The court certified a class on December 12, 2025. Trial is set for March 1, 2027.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Between September 25 and October 31, 2023, five class action suits were filed against the Company alleging privacy law violations stemming from pixel trackers on Costco.com: </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Birdwell v. Costco Wholesale Corp.</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">, No. C23-02416, Contra Costa County Superior Court; and </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Scott v. Costco Wholesale Corp.</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">, No. 2:23-cv-08808 (C.D. Cal.), now consolidated with </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">R.S. v. Costco Wholesale Corp.</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">, No. 2:23-cv-01628 (W.D. Wash.); </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Groves, et ano., v. Costco Wholesale Corp.</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">, No. 2:23-cv-01662 (W.D. Wash.), and </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Castillo v. Costco Wholesale Corp.</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">, under No. 2:34-cv-01548 (W.D. Wash.). The </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Castillo</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> plaintiffs filed a consolidated complaint on January 26, 2024, which seeks damages, equitable relief, and attorneys’ fees under various statutes, including the Washington Consumer Protection Act, Washington Privacy Act, Washington Uniform Health Care Information Act, Electronic Communications Privacy Act, California </span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Invasion of Privacy Act, and California Confidentiality of Medical Information Act. The consolidated complaint also alleges breach of implied contract, invasion of privacy, conversion, and unjust enrichment. The Company filed a motion to dismiss the </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Castillo</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> complaint on March 11, 2024. In November 2024 the court denied the motion to dismiss in substantial part. On May 16, 2024, the parties stipulated to stay </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Birdwell</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> pending resolution of </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Castillo</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">. On January 2, and August 22, 2024, the Company received related civil investigative demands from the Washington Attorney General's Office. On January 3, 2024, the Company received a related pre-litigation letter from the Los Angeles Office of the County Counsel. The Company is in the process of responding to both agencies. The </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Birdwell </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">case was dismissed with prejudice in March 2026.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In October and November 2025, two class actions were filed against the Company alleging violations of consumer protection and other laws arising from the Company's sale of Kirkland Signature tequila products in the United States: </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Glazer v. Costco Wholesale Corp., </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Case No. 1:25-cv-25057 (S.D. Fla.); and </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Salisbury, et al. v. Costco Wholesale Corp., </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Case No. 2:25-cv-02277 (W.D. Wash.). Plaintiffs allege that the Company's Kirkland Signature tequilas are labeled “100% de Agave” but contain alcohol derived from non-agave sugars. They seek damages, statutory penalties, punitive and treble damages, and disgorgement. The </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Glazer</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> action was subsequently dismissed without prejudice. An amended complaint was filed in the </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Salisbury </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">case on March 9, 2026, adding </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Glazer</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> as an additional named plaintiff. The Company filed a motion to dismiss </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Salisbury </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">in April 2026.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In March 2026, four class actions were filed against the Company seeking a refund of tariffs paid by the Company under IEEPA that were passed on to members through higher prices. The complaints allege violations of state consumer protection laws and equitable doctrines: </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Stockov, et al., v. Costco Wholesale Corp. (</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Case No. 26-cv-02734; N.D. Ill.); </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Gower, et al., v. Costco Wholesale Corp. (</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Case No. 26-2-08898-5SEA; King County Superior Court); </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Ortiz, et al., v. Costco Wholesale Corp. (</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Case No. 3:26-cv-01164-CVR; D.P.R.); and </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Briggs, et al., v. Costco Wholesale Corp. (</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">Case No. 2:26-cv-01064; W.D. Wash.). The Company has filed motions to dismiss in </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Stockov </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">and</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%"> Gower.</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> The </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Gower </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">court denied the motion to dismiss on July 17, 2026. A motion seeking discretionary appellate review of that decision is pending.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In June of 2025, a class action was filed related to promotional emails. </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Zydel v. Costco Wholesale Corp.</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> (Case No. 25-1-16392-0; King County Superior Court). The complaint alleges the emails include “misleading subject lines that encourage recipients to open e-mails on misleading pretenses” and that the subject lines advertised promotional sales with specific time limitations that were misleading, in violation of the Washington Commercial Electronic Mail Act. The Company filed a motion to dismiss the case in August 2025, which was granted in part and denied in part in October 2025. The Company subsequently agreed to a class-wide settlement for an immaterial amount, which is currently in the process of administration. </span><span style="color:#212223;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">In July 2026, a class action complaint was filed by plaintiff Tracy Jay, alleging deceptive email marketing practices. </span><span style="color:#212223;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Jay v. Costco Wholesale Corp</span><span style="color:#212223;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">. (Case No. 26-2-22333-5SEA; King County Superior Court). Specifically,</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> </span><span style="background-color:#ffffff;color:#212223;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">that Costco sent commercial emails to consumers utilizing false or misleading </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">“</span><span style="background-color:#ffffff;color:#212223;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">limited-time</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">”</span><span style="background-color:#ffffff;color:#212223;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> subject lines,</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%"> in violation of the Washington Commercial Electronic Mail Act, as well as Indiana’s Deceptive Commercial Electronic Mail Act and Maryland’s Commercial Electronic Mail Act</span><span style="color:#212223;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company does not believe that any pending claim, proceeding, or litigation, either alone or in the aggregate, will have a material adverse effect on the Company’s financial position, results of operations, or cash flows; it is possible that an unfavorable outcome of some or all of the matters, however unlikely, could result in a charge that might be material to the results of an individual fiscal quarter or year.</span></div> <div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:700;line-height:120%">Note 11—Segment Reporting</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The Company is principally engaged in the operation of membership warehouses through wholly owned subsidiaries in the U.S., Canada, Mexico, Japan, the U.K., Korea, Australia, Taiwan, China, Spain, France, Sweden, Iceland, and New Zealand. Reportable segments are largely based on management’s organization of the operating segments for operational decisions and assessments of financial performance, which considers geographic locations. The material accounting policies of the segments are as described in </span><span style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline"><a href="#iae87f9b9600946fdb18e1436ed6ec90c_109" style="color:#0000ff;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%;text-decoration:underline">Note 1</a></span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">. Inter-segment net sales and expenses, including royalties, have been eliminated in computing total revenue and operating income.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The chief operating decision maker (CODM) is the Company's Chief Executive Officer, President, and Director. The CODM uses the metrics outlined in the table below, along with internal management reports, to evaluate performance, monitor actual results versus budget and prior year results, and make strategic and operational resource allocation decisions.</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table provides the revenue, significant expenses, and operating income for the Company's reportable segments:</span></div><div style="margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">United States</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total revenue</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">219,823 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">200,046 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">184,143 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise costs</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">191,440 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">174,021 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">160,573 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Selling, general and administrative expenses</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">20,736 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">19,147 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">17,353 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating income</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">7,647 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,878 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,217 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Canada</span></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total revenue</span></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">40,561 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">36,923 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">34,874 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise costs</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">35,287 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">32,204 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">30,543 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Selling, general and administrative expenses</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,167 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,870 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,683 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating income</span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,107 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,849 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,648 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Other International</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total revenue</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">42,770 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">38,266 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">35,436 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise costs</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">37,552 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">33,661 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">31,242 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Selling, general and administrative expenses</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,287 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,949 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,774 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating income</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,931 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,656 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,420 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Total</span></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total revenue</span></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">303,154 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">275,235 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">254,453 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise costs</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">264,279 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">239,886 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">222,358 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Selling, general and administrative expenses</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">27,190 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">24,966 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">22,810 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating income</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">11,685 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">10,383 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9,285 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div style="padding-left:6.75pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other income</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">566 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">435 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">455 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Income before income taxes</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">12,251 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">10,818 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9,740 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table><span style="color:#000000;font-family:'Arial',sans-serif;font-size:9pt;font-weight:400;line-height:120%"> </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">____________</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Other income consists of interest expense and interest income and other, net.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table provides depreciation and amortization and other asset related information for the Company's reportable segments:</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">United States</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Depreciation and amortization</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,082 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,895 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,730 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Additions to property and equipment</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5,122 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,215 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,725 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment, net</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">25,714 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">22,790 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">20,638 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total assets</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">65,090 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">54,862 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">48,816 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Canada</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Depreciation and amortization</span></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">219 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">196 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">192 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Additions to property and equipment</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">673 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">580 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">351 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment, net</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,395 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,930 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,602 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total assets</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">8,026 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">7,304 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,915 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Other International</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Depreciation and amortization</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">373 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">335 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">315 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Additions to property and equipment</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">640 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">703 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">634 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment, net</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,524 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,189 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5,792 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total assets</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">15,929 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">14,933 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">14,100 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Total</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Depreciation and amortization</span></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,674 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,426 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,237 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Additions to property and equipment</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,435 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5,498 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,710 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment, net</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">35,633 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">31,909 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">29,032 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total assets</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">89,045 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">77,099 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">69,831 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-style:italic;font-weight:400;line-height:120%">Disaggregated Revenue</span></div><div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table summarizes net sales by merchandise category; sales from e-commerce sites and business centers have been allocated to the applicable merchandise categories:</span></div><div style="margin-top:14pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:99.839%"><tr><td style="width:1.0%"></td><td style="width:52.511%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.831%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foods and Sundries</span></div></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">116,788 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">109,564 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">101,463 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Non-Foods</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">77,375 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">71,190 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">63,973 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Fresh Foods</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">41,715 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">37,988 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">34,220 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-right:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Warehouse Ancillary and Other Businesses</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">61,369 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">51,170 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">49,969 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:13.5pt;padding-right:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total net sales</span></div></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">297,247 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">269,912 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">249,625 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> <div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table provides the revenue, significant expenses, and operating income for the Company's reportable segments:</span></div><div style="margin-top:9pt"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">United States</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total revenue</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">219,823 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">200,046 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">184,143 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise costs</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">191,440 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">174,021 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">160,573 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Selling, general and administrative expenses</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">20,736 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">19,147 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">17,353 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating income</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">7,647 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,878 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,217 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Canada</span></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total revenue</span></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">40,561 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">36,923 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">34,874 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise costs</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">35,287 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">32,204 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">30,543 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Selling, general and administrative expenses</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,167 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,870 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,683 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating income</span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,107 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,849 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,648 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Other International</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total revenue</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">42,770 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">38,266 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">35,436 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise costs</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">37,552 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">33,661 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">31,242 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Selling, general and administrative expenses</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,287 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,949 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,774 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating income</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,931 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,656 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,420 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Total</span></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;border-top:1pt solid #000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total revenue</span></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">303,154 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">275,235 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">254,453 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Merchandise costs</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">264,279 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">239,886 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">222,358 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Selling, general and administrative expenses</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">27,190 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">24,966 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">22,810 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Operating income</span></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">11,685 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">10,383 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9,285 </span></td><td style="background-color:#ffffff;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><div style="padding-left:6.75pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Other income</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:6.5pt;font-weight:400;line-height:100%;position:relative;top:-3.5pt;vertical-align:baseline">(1)</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">566 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">435 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">455 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Income before income taxes</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">12,251 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">10,818 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">9,740 </span></td><td style="background-color:#ffffff;border-bottom:3pt double #000;border-top:1pt solid #000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table><span style="color:#000000;font-family:'Arial',sans-serif;font-size:9pt;font-weight:400;line-height:120%"> </span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">____________</span></div><div style="padding-left:24.75pt;text-align:justify;text-indent:-18pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%">(1)</span><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:400;line-height:120%;padding-left:8.24pt">Other income consists of interest expense and interest income and other, net.</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table provides depreciation and amortization and other asset related information for the Company's reportable segments:</span></div><div style="margin-bottom:9pt;margin-top:9pt;text-align:justify"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:100.000%"><tr><td style="width:1.0%"></td><td style="width:52.585%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.803%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.601%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.807%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">United States</span></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;border-top:1pt solid #000000;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Depreciation and amortization</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,082 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,895 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">1,730 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Additions to property and equipment</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5,122 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,215 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,725 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment, net</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">25,714 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">22,790 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">20,638 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total assets</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">65,090 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">54,862 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">48,816 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Canada</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Depreciation and amortization</span></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">219 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">196 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">192 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Additions to property and equipment</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">673 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">580 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">351 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment, net</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">3,395 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,930 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,602 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total assets</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">8,026 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">7,304 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,915 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Other International</span></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Depreciation and amortization</span></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">373 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">335 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#ffffff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">315 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Additions to property and equipment</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">640 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">703 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">634 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment, net</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,524 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,189 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5,792 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total assets</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">15,929 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">14,933 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">14,100 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%;text-decoration:underline">Total</span></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Depreciation and amortization</span></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,674 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,426 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">2,237 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Additions to property and equipment</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">6,435 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">5,498 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">4,710 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Property and equipment, net</span></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">35,633 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">31,909 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">29,032 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 7.75pt;text-align:left;vertical-align:top"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total assets</span></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">89,045 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">77,099 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">69,831 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 219823000000 200046000000 184143000000 191440000000 174021000000 160573000000 20736000000 19147000000 17353000000 7647000000 6878000000 6217000000 40561000000 36923000000 34874000000 35287000000 32204000000 30543000000 3167000000 2870000000 2683000000 2107000000 1849000000 1648000000 42770000000 38266000000 35436000000 37552000000 33661000000 31242000000 3287000000 2949000000 2774000000 1931000000 1656000000 1420000000 303154000000 275235000000 254453000000 264279000000 239886000000 222358000000 27190000000 24966000000 22810000000 11685000000 10383000000 9285000000 566000000 435000000 455000000 12251000000 10818000000 9740000000 2082000000 1895000000 1730000000 5122000000 4215000000 3725000000 25714000000 22790000000 20638000000 65090000000 54862000000 48816000000 219000000 196000000 192000000 673000000 580000000 351000000 3395000000 2930000000 2602000000 8026000000 7304000000 6915000000 373000000 335000000 315000000 640000000 703000000 634000000 6524000000 6189000000 5792000000 15929000000 14933000000 14100000000 2674000000 2426000000 2237000000 6435000000 5498000000 4710000000 35633000000 31909000000 29032000000 89045000000 77099000000 69831000000 <div style="margin-top:9pt;text-align:justify"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:120%">The following table summarizes net sales by merchandise category; sales from e-commerce sites and business centers have been allocated to the applicable merchandise categories:</span></div><div style="margin-top:14pt;text-align:center"><table style="border-collapse:collapse;display:inline-table;margin-bottom:5pt;vertical-align:text-bottom;width:99.839%"><tr><td style="width:1.0%"></td><td style="width:52.511%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.827%"></td><td style="width:0.1%"></td><td style="width:0.1%"></td><td style="width:0.602%"></td><td style="width:0.1%"></td><td style="width:1.0%"></td><td style="width:13.831%"></td><td style="width:0.1%"></td></tr><tr><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2026</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2025</span></td><td colspan="3" style="padding:0 1pt"></td><td colspan="3" style="padding:1.5pt 1pt;text-align:center;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:8pt;font-weight:700;line-height:100%">2024</span></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Foods and Sundries</span></div></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">116,788 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">109,564 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">101,463 </span></td><td style="background-color:#cceeff;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Non-Foods</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">77,375 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">71,190 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">63,973 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:9pt;padding-right:9pt;text-indent:-9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Fresh Foods</span></div></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">41,715 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">37,988 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td colspan="2" style="background-color:#cceeff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">34,220 </span></td><td style="background-color:#cceeff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#ffffff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-right:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Warehouse Ancillary and Other Businesses</span></div></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">61,369 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">51,170 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#ffffff;padding:0 1pt"></td><td colspan="2" style="background-color:#ffffff;padding:1.5pt 0 1.5pt 1pt;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">49,969 </span></td><td style="background-color:#ffffff;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr><tr><td colspan="3" style="background-color:#cceeff;padding:1.5pt 1pt;text-align:left;vertical-align:bottom"><div style="padding-left:13.5pt;padding-right:9pt"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">Total net sales</span></div></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">297,247 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">269,912 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td><td colspan="3" style="background-color:#cceeff;padding:0 1pt"></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0 1.5pt 1pt;text-align:left;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">$</span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 0;text-align:right;vertical-align:bottom"><span style="color:#000000;font-family:'Arial',sans-serif;font-size:10pt;font-weight:400;line-height:100%">249,625 </span></td><td style="background-color:#cceeff;border-bottom:3pt double #000000;border-top:1pt solid #000000;padding:1.5pt 1pt 1.5pt 0;text-align:right;vertical-align:bottom"></td></tr></table></div> 116788000000 109564000000 101463000000 77375000000 71190000000 63973000000 41715000000 37988000000 34220000000 61369000000 51170000000 49969000000 297247000000 269912000000 249625000000 false false false false true KPMG LLP Seattle, WA 185 The asset and liability values are included in other current assets and other current liabilities, respectively, in the consolidated balance sheets. Net of unamortized debt discounts and issuance costs. Other income consists of interest expense and interest income and other, net.

V^)K']ES_;R'>IZ,O2CXEXR^C9S3 M81S%TV#HG,0Z9$;;_=$ZAKWSTY./[S#RE\1^/L16>,XH\:;B.DY^XB;!SLH0 MGN>,PWC@A0YV'9OF4^P&.(NY-R3L-/;X[/WB[%$]%5G#%<[H&W7A<]KO7.=Z M$@ AX,&9@Z40'1P8#,N5>]7OX1A])XHS9^+!SSQG"N_!?=+5>2/9,O*.2,[] MXS2=32@@>VL(YH^S__[S[./9Y?\ZQU\_.B?'W\XNC_]POI]>G/_Y_>3T8JNI M>12'87Q-)9DY_I-/L1K0OT1*YY["W((12(4(#8T\&:-']!? MQ#_SX,H+D1[>UU4UMC_JLY&3JD-1=2AJUY:\(Z&HKR)C03+#F)0O.U:S4@42 M"A%15P1BJB-3N^(G;?7Y+:#<38VJ MOMK@E%9^X+;_:LN32\SR1_3;F.IP6CYPP^&<>^$$V=[Q$L- 9 MA?%UZHR2>&HE8KK+XVTN1_@G<9+M9R*92NN!8[/.R;+';GF*>XB^;8,QV&PQ MYJ#5<]M'7&!L8A@ MTS#YEE_B7 ?9A%K#8G<2;UX5K]Y4HOFB0O(JE3;'[-P!S$>EYR9!BFH)K ^S M+B/LQH*_SA/NE3O(X6N1VJU>,)X?I)0O/ ,RG%!773.DZX1Q-&:2X%XND:\A M'3I]>>;-97,7[@G#!(!#9TD^U#B($/]3]1;."*Z3?.^7Y-MN<9)OZG1?*,L7 MS[4^O7N>7O?-;[VMS\XF7)$W!4T&H5]Y!L]&J, @;*A:1%BX,,U89$>I[>'( MWRJ8F )F D%'E>UA; M'7;14\0^)\-"FCTL*._Q[Y@V1 M6=!!..(FD $1>,J[\H*0-EK9#^-$J&Z#UT$8PE2<-!^-@F& [R3&*WA.EL%% M1M$,RW$ TX)/$V&*VF0$D$3+0]"+1GF6)T+R:;F\/QL7#8RTNF0Z-8>9DSV,=J?BT$%D:9_6Z)61R?C)6[+D^Y.-%[^G&2_QS M1$B!K\&)."/X)$X*VZG&FL/:03GB 8%91/$55HB52W30H$Z9M5D'1J?@ M)7#2]NG&@\R#%6*:!4VKX:P,CX/'X9H*]M@ MYX+HTF>8/V"HN5CIS+R3C\O%#(1K 2S70U\-)SBL?%C\8M#18'?HM1ZFL^0A MJ:,C+\VH9)K:7]Q4WEXX&M@'>--MN[L&_]PPAGFFP__;R#!70C,8.J5H_Q(R MI9"SHE*^+I'&3J13G*ICQ1.C*PVBP)!CG] M%KZ28GVCKL29NO37H,7,< N>WR4&_*?;Z6W0IJ #K8J92?8'XC1] <VAVVLV07/8H&VEBR'S()]__X#,#S=H M,ZJYP).G'(+R9U,T<4?\8"AE.%CM[(Q&ML=. "4O'QX)W:#M?X'=_U$=;7NA M#4"WL;@S@O2D[M,-V 42]DJ\/_]>B((9FTT2(93SGN^9ULG)MP7*"]FF<'1. M/L._=CJ%%13'&V'N><5PAV3S$=8AP@L?80Y[FB=XZ]FUIL0,/;!0 M0UBC;R;%;"3-!^AZ(TN JT_G,U1\\H0B#(FX"F"JH#FS7W)!O,)*A"]M=ZR+ MH#+[1705)'&$+&03M>O5[,E/&K[X*NS)*C2FL2<)K;C$GB3(G/%Z+#KA*H=> M&@U3W@<@*]C P =B2C'.:2PWBJI-IZBN8RD,^E(Y>HIFW"!.$LK&EV7;"R , MIG84B9,XY.N*7C)'C;L_\' !'M9A+S@7;7=1Y=ITG)?\>G@%B&*63RR RTIW M%<%+A4EN5A1W38/T#[V4C["4C5K)[?'HPK&5H#NJ88$^9&;R^"JFS<^Y!XPW M@P&<"Q$%8'\RK(0N$U%*4:\'K=Y%#-@HN+'10-3, /X;C8GSXTS:C0.8'TF) MQL%1\Q>7"$?Z+8$%_Z='6Y0/TL /P(0F/Z)]5T$N:)+4%_9[X?8L6:WQ+/47 M1GW;:G;TSR#D&YAU*48 L^_<8@QA /!^#1) O M7_N]?2+,?\*5 )K"V(L]7Z;JMZU&I\ETU.@>FG?6L(1^#4NH80G;PCPO\,ZB M,%& *)"BX\2;;@\O/8] @D8Y^IY;?0+8=9;R-R_/0)M#H\GQF%U9*BH*65RZ M@ELQHH]JN77=)HI[1FJ!J10D'(Y5+V9C[B.[G(F#HW[(D9IK^QV^<]1OX6#T M@WZW0W^GF51HR!Z&G!T/XZUCG%X NJ9FM#2Q?J_9Z/-@\/?#Q@'R=J6QO#T" MQLQ?-3L*'ZYPBE-O+D/#S,]IQ4,2*M&<@^46,-*"0ZIZ5XS-ER'1H0E1&T2[ MK?W#4LB8C.A$A ?[*#V0<^$E#>>;^66"\#A?R&D%4WH!_BG%'IJI; A[":IL MKCHPLL=E9R8*HCN#$(ONZ5FX^%?4V@'A!269&2 />__,ZWF&*)!)!:58+WH@,$C\MN6V6KW2[B(!;H^%_KL7_71. M&&#Q20=GB&Y/X#:(A/"XWSPD?,F*]14(G+5:V3M5,X#;D,Q6R!#F 9PI?X6PHAPX2IHF1LO>NP M@.,H3TLO0\-QV'S#-WP1-\$P-I8.*W MG4X'$0)C8]?*4SEA'M]@TF$/)&4Y@9U9[>RP,>V:C):1#IV#41-L]J*4YZ7!SUF.,)%\R[\ MQ^1E-:.K7>3L,GWBBYMJG>@+:@&WROSST6C_=WDO+_!>.L>HRHU9Q=R>*WJF M%$]0Y5BR38'5\S*D++XBOAK#@@N,R/&L!?,]H-^B\,9L(M(UO12D U:<#H.? MZ'1$[&&I0+'B@EC9F''97.Y8E2PV&4U:<:;?KE:\^.7W?4E4!^%?:#P<,UH5 MF=0I.!%*!5CR M'+^)E"]2<$3U.M7X55,"U5%$N8)O8_@2K4>?;7#S$/X+M*L@]AL.)F90TA=L MLMD/V'A0L!"%.Y2!4-#<<%\)SATM[M6UE=\1RT@LWU2AI0CO 1O',N)*\^26 MQ4+*$CT):G^L0[0VM@V] 5;Y:<\0_ QH9$A*0"KX"/*4%.RZ9_ .]@QF;7Z% MQL$O[@98)DHE\N'7"Q&.]@/U3^VA[.?A%XP9=->9Y9,A!=FD_TARG:3 M98*6/^AO?__;4;MU^*'0(,+5+@#%.^"Q_!PS Q.&%! MTT-F"8P<,WN4AH]/6YJ7,Q7HCPS2:0&&XX%-$H->OQ]?X^O!H*:F$(;23 B6 M920P;O.E= XW;'I$T1##Q"H@Q?D1@9@.T$ M<)J6+!HR%1F1!*6Z8,BB>LR%>Q3'(5\&_9;$$?Q]N&T^DXNBL0)7 MZ*ZUU0;-+AHT"V5V[M]0XP2/@C5OS]J MATOJ' _B/'.^<-S[.ZK">\I-@NG&01BBRO=N>S@$ALR4!8#T8\A%!O=)WV?M M4Z(]E6:J G,E/"9N'Y:P@!7ML\=TB*$\"8]/V ,#1H4*141C,EO\2FIZY=I J(*$E!KV$_ M)A"!LE]M(J$R%\#H=1I81687(D9'9$/7DK&6C$E60"PLJ6,*SX[1#Q/I@F7 MQY -IL#A9#8]^3!,N\QBGKV)BS)TGJN0T2I J<80ZH)?7V&8#-1 IXG'E*-$ M;'54OCQV3@:]@,J>)E?T-.S.3 6Z,37)UU>0)PAOG@KG6+U% M'N$,2HC^?1K2;)+"T5G;5IET13L^\H+$09>_4$"Y B\IB*W-D@1WY_MC]&'. M_KJT3&E(!!20P@*'Y)_D?Y8HT/XG$2,?6:$$JX7/-*6M^'=#[(&9(5$2HG,P M7^TEQ1*OJST"Q"[F2D:@&U3EH*-_D$ FT4]=U7=%T(^-$U)^VC(Y&AF#JMS" M)&ALQA)@(6PTF3.^K;X@3Y=K75M?1.2UY>JU#J8CJO@QAI&VB/Z.'6RN//!2 MK( 2!]C@F36Y"LTO50%&&[)R3=X&'7#W;*< 8\SP"+3/4E]EN?=THSEDETUB M6<='>QXHG(I9G:&7*G%O(4+V0;O8QW)8C%+.(Y7'Z8R]@)5)=G/;*79E_59- M)$;=-%0EW,IK)]_+*.2D<-A/LWYM1)F%4^!_4X$ M:"7D+*?"5,%KPEFAA(@\7=/.(&ZH1EXQL0I1TU<4("@ZP'5Q:;O\B:N.R6"6 M;<^\=-8WG.,JÐ/DW"N3+;C(# !V[KL ;LAA/.W0OV6?-)A>'@!RSQ* M9*R+4S]"<>H7JTW]R#6.IS%I2 5PPN(EV:RKOZ9)^TEZ"4Z4EV#[K%KIZ"CH M%\2"@#/H@&O!?P'_CN)H'U2*H=1-C%I@9;V@O\+)TRIY5.%+X7BL DU:OZ?D M":SM[.K8,0E"+M,/L\?4;>VNT2/KDLR$=R&T/$Q$52<@#63B !DT1LY.3@X=L)8;SQME+02CM.P/,T#8 M:L^834RL%F$'%SD=FU^4B@9()/J_I:N>>BV)'NCL2%_,VU&W2;C_Z;6.WOS6 MV3858@D@S3EV)O,9:L",X&TU?X%1@)6.X2-50)\TT2II5,A1XC8O57*K[-Q? MWJS'L@3AE%1N4:5J;%CCH,:G=%HU/F5C&<;*^)3E*)1;O]Q\/;A0F\CD8P1,^MAET#05K&6B4!_&/Q&.\E=5^KWJQE*[N'O2V8!%3*[M@J=$:O1%>S0W*JQ,\@+5^IABD.26I%GXI6FD2.Z%&EZW;A_>*ZGY M4T%4?%J+**!:;EA]2S@'[7^H * MA2#PK,SBDZ4D)!YCG >%#L#]+-Z7CD"#4-OY,CF=]G(%8@UH M3__-(V@=!YU:Z]AZ5.RSX[6<(XG4^J3-H8MBZMH%]E_@4%(R=SYZF7=?"-M1 MNPK"]EPW>$D2YOG%Y79^=>[SAPQ=KVB M-O$"*SC[^O'T_W,NSV'F7R_._SC[>'QY^M'Y=/;U^.O)V?$?SL4E?/#E].OE MQ4/6PSD4FD\G<+/V*70]2\5[]9/[^&O#P!I- M9F*R_;%\L_RZ 5_]NOAYO]TXZ%5_U6RT*C]?-E2OT;ICI#N:,]_:)'OQ9Y4] ML'GWG[()]M%=)$:'\ UD4:'_M5Q[2=JW>L3 'K0?DK20%+%G-MDPCEK6PA@K MGD'EYH9BM+R_^/.)SN:+B\[;9["ZZ#SJ(<(?_6.DT9[!$.CJ1P#*=S$.L/D/ MJ.;?\@&8>#9._E.03!=%K.JS_MC'6B%VJ O[\OM4G_?R\^YTEYQ57X?.K+MPU'VNG7EV_S3PH&NE4$NE ?T(D:'$9 /L+W^[>&O^IC7G;,!PH4 MF\5.X3971?3JF[RE1]QMWW:3?Z5(VW(NE\/_U\=G%Y^OWTH_/MS]__.#MQCD]. MSO_\>GGV];/SZ>S[EZ5[]=*YJHQZO["2> EI4M'K:'LPG2=QF@UCYP7'/2A9[)U/ZJ](YZ,G"%RU7=N'B@N"/9#5RAS,$J[-23-USGG%$6NH>@H6X:@J6.UPI M+><=M7Y$S*UL4K#BU*G;JEZN])[U&;(8[O? MJ9E]X%I?>$+XAVF70V4/L&S24QX'UJ>-*8T14<^FW+Y!%P/MBQE5];7JLW.Q MFG"K2FLHA+A]NY=V.Z,V(]AG66VU1*BH,[>0*N=4^PK>(T75WI]1H/TFZ3MG M[]O)\?GO[UR;9F1YBE3EMX8,"(]#!^NS6#1G*OTOIS+7X<;00)G#)" BQNJ@ MH"@%P)96J:3U?"75<*DGJ\>Y)YWYX5 M:#H8R_."FY$)4CDO9LA;*"WB/!E[4? OE7;--'()!H$/=@ _145 9=Y%GLB3 M=)@OG8,B,Q )G^.!9!;B!CD3M?A&*#[#^K'&2EP4MKJ,%97E*#*C]0EKLV[P MFC3U.Q7*0;8H%9*-6LQ=M5G25:05Y@1)08'D%W!E^V7';DK%\V0SF2@9EDH M =35$_<(5!)4-GC[B(H+VPU!8\:.B3, ML[56AR>E?N+J 67M.I$DF+^%#6-A5GQU]$[(Y&\Y==9_XJ'P51<'[ 24IE:' MA&6OM=*M;U_!'?-S[:TLSP=WG&^]S"3'DZ%Y-9R+''1'Z\=Z;>(&2 I3U#EE MS1*L1+Q32LFKU5J::5/;GL32;%S,R&6PGI M-U4IGIRY2/:4U4/(%$57143LKF56*P?E=32Y#W08LLR7];A&LL=49LAETT7,[KC7SSLY+<]7)'JWJ@E,)N: MTA(H=S:/J!BACV<>7Z-,]=378-13IQ/==UHUL9.F&(^U*F%)]DFMH:W7QDE9 M6!:^E@*27S74^BM+*"][[^RUWNE*O\B^^'I1>3[[(NMJ?YJ7K5PP ]^UUWZ' M!7[B\$I*%I+?G#,,\A/,_6A,#$?6%P5]UG6XY2?<[QOGK]P?R^O%98C4$N75 M]):U4JSEQYOT4$1?%PR8[I@^:;'SC(I>Q M9BK,H)J)KF&\'V) M#;F]*&ZJVJK4=>$? AGHME5=^$TO#%]PENKRY]2(N^\>M3NJ]P<1^MMNT^T= MM/1GJ%YAXVY%^KIF2.&*[*&+X)UU4USE8I!!"%5.@USIM_G0I;A5UHMZ*^F M4S$=B"2=!#-G)*A!MU7_D*IPL#XQ]G!#(OD93Z[B%K]C98A,N)0T3799H*4N M"XPM>1+55.-1R6=2BY 5$J=YF*%952AIF(GA) )Z&,^=O;/+=TXZ3^%XUG+Y M;QPK 4L-N6;&CE7RIDI+T!A\Z0K<=LDFDYI8J;DUG-.BR7G[6[2";[1C_@D0 MI=*,E7, 1Y/-#;T<=I[C:ESV&5L@RGH[DFA816226;8.0].DOTMO,A;E@[^$('](#ZCP%TD+NQL(K'N,/"DKEA&'+9$G M4O2##>PYT#7)[L>K[-:FDD8D%9%C2G"_:VUD[!XF7 MREY NA.N7/%?8(CC[@ 1Z4*^JGNXOPH''L@VN[>RXL%<.F9-TW0=:;?H5B^T M3'149P]N&DQ*G6_E'4C1IZKFMD6>_U_37YW_^O;EL_/'']]>KL+?2E @CYJHA9[[QC MJ5<[EC;6WGUIQ](3D68?$R]>$3YX<3VO 2"\ZJH>"2'\Z).^/QYX >>% #D+ M%/Q=0]JVZ)C*J."[4+Z/Z%N[_Z$\)NQOU8VRT[[( YX7Z[GR"3TNV+,:D*Z\V%,P6MEPO0UR;GJ4;A\T^/X$LZ/TLET"\.71 M\W>DWCPX*6-G4VD>'Z8>KX(EWK +\%#P^38IM)>W@LR6)KPG>69M3.R",WWE@5W'[L^TD*[W12]*K_,XBG)MB*QELMP'5/^ MG)]%J'V-M-\XI/T:$K0":K^I2/O[W'!$JAHM=ZF2:R&_U[KHYI[S,IBI<-,2 MVA 9UUJ#KB).WLH H"@4]\ZQ@EL$>"J02CD^)](Q78>M$-\>U.I(\] 01XJ>5?.XT&D_DRU-69I3/Q51#1K6#$']/GG MKE-D[3[U]')Q$7G"[>)(!Z.T=_CA*%3-T@LMDV5"CPK!:0&$3,G867(#/A#. M_];#I944WT!*"$Z:NEM M&#O\70P]"9/D?$ 0LGB4H9$,[AKW?^K-*3U%'AZ= 1U9(540F0S(>DH5^4L, M-2DA'181BT75 KL&RH(1W @O)0KB^TV:SU@F71+,+R@JM)K1Q045!5],2+, HR=K 6@VC$[6 M =3(.3_O!#<3?;+J[&OX207\Y& Y_&2-"G='CU'AKNYOO.V8E1(3W;*^>QNT M"*OCGNFSQT"D]LW:3Z3]=@L=7;E Z+ M_;NN'Q%LK^W\$.)GZIQB%+"JU^)3]57\L!7[PV%1I]-T2=@5-,+E!:SO7O1N M[%I+[UJOWK4[=^T"G4F8R^F8?>NNNU<+WG%M[W^5X;!VSI8.J%Z3_>[!^\<2)O*O"7^V//F[W_SFE^ MGY)X2J$X&/%'D$U.0+3%4Y&2N%MA._1>%W5CHP>MJ-K^#X M$O)'Y^#\T3R[;%5ZM+1!MY1W]:72*J-6?9'2_K72ZV/9&H;5C8YSZP1FGS*-4=+F.+FL')\PN>&J=5D5OY.6I*<(\!L(\O,3L 6&VFI5F*[,A MNR_"/.)LZ/WW:RQ)N_M5N_Z?[]=WC]>/61*CATXO%N[[IY'!_";A0 ]MU]LN M-I4F&EU&R?N^X$40IOOQK[8]U-%F%*5=J]6H/"K"NWO16/OAJ":F*:O]-J9E;:5;+Y*$.HT$T7T MO,-!^7:2(SI>;GF?68+#O:&SO;5=-RUGM,\NZ_5*N[OS,'L9/:@3)+@U^CX' MBNL Q=4JC>[.X^>*XDI!<;N7<=VSRUY%+XF(.^9LS=-OUP^B\U[[(#(V'U7& M1F5L4LH7@O[#.6>,NP.GDK#YD*/MZ)]AX%'%Q&8/%'4S+C1C#*M"YR4BBC7V MW5JJZ-2 *A*JQ115E)DJLLJ*3AVHHAW/V!Z$*DXC01+H0!Y7X2C'B#I$J1Y=MG6,U?<%S$74;R@@P@W?+[^>O]P[0RJQH]U5F791(\5%3X%H5G2<)MBE3 MT:WG5?VE2/ 82'"O4K"#J8M.,W/=PKXH\#1\[^\X%()&8-$4->Z >\9/!6NQ MM=GP9/P4T:7/S&)C,S6G=,\N&Y5:=F 7Y785CGXV4OJ9"0@;^RJ=NO+;CX^ M]B*!NMBY5&ETB@1PLD8=^\#NL%BVFM[*\BFUV>.(V-Q=/RV/9\C?O#TNG, T M&R^[,']?EM\Q;^M"L6Z="L7TO'H&R^#O*Y92++7.P,[$4_K99;=2Z^75S:UX M2O%4*7AJEWJJ<7;9J33:>8&AERUX5BP9]?_-A%%H*=J@9[" M/N[:>:=(Z!E[,.\4M9>.VFNYD#N6K'3/LQ=V*7)7Y+Y3[WQRM\/\B&K;1K+ OM/>C0;]6%?QC.[6^",Q_LQ%P/W"\_U$%??>A8AA$VRG U? MQO=J9Y?-9J/2RSYI0Y7D%I&T:@>DK;J@K>R@8(JVBDA;AY1;NJ"M^E%V>!=: ME:^(C&[$%6G2&27EBJV80IQIC#?2LD4#V:)9:>IYE2T5)#^FB"N+.L^+NIJ< MNKJUO&!E%745BKH.*[M:G+HZQ4MV_D+MY7Z)H%3V.#.<9],B5W])50\9XM2( MR[[\Q\#!9\F%AM)3Q)UU=*R;M%T3MWSAL"F!\7]Z-4?>Q+]0Z5M\C1>U\"O& MP+7Q*E9^15IN77]GO1F)LUY;1YTZC36>,,T8#NT9O/$-[DFS;(^Y&E"1!DLP M83W/.)-F;CB>9H\U;\)H=IQ%I;,&4)PV-BW#&L)"8,'P@QGLP3U?>C0;W+ZLU&FXW:;-BK#?^%/I;XTL0) MBW&?677@,.-'U1C#OBZ,Z:OQYB(YR\0&LS!S\%*S$./ *M(F#TO%OZ^^B R2-<@*)%0>C(C7^XQ=C-=\+@A2,')9$ M)XF+-5]N[)&>8R761,]7]X]/5_?:G[_=WUX_]F^OM:O[A^_W.#CT_F[#$SC\ M)F#1=X_WMS=?^D_77[3')_CCV_7=TZ-V_Q6+QK\_7/]V??=X\\?U_Q'_>;)SW&GKBKVKG M]<2?KWI4O7W>[G93/6KUS]NU=-\HW:)ZR;_R'[4F3K)M1\J2,5]O;?9$3M.' M;\ENZ=J?C/UPM6M0/M'PRGX.3/*>-I^^4,23["^>%ZZG-6H5TJ1Z#;N-UR=# MUVYZ74;P.$ZM'IQ:2YW:VE-[9'/P/, 1UL)S:Z9AWOP:\^ (2]J5E]R#EZ*@ MY$1:?+?8>)G"4OM%HNBU" Q6CN-N%(&5@< R M3H5S8=7PM\.16OWL4H\7^!1QRMSA$6(5M.Z^H'5/)2BZ/LVC!(\7$BHDS^"EY_SM^OKIL=0%^Q6-_1PR MT(L@3+478[I@E"BD9CX-9*D1K^@O2:%^NW;>J_?R*3_OG#>[Z1ZUAYIX6%3O M_4=M6.*]IIBV%"6SVY5G'^,)K"JUWDETO#";?WR4)7&V@1NKG8D"3+388'%' M/&+PZO>'A^N[)RW#?>>$R);[]T\# OO*<"=D80SQ+^ROA0E&![>'TT4'CCF M=60A*'U-" HHH6^-\(_KD![ZWI7A..C]_X%6:>I@5 OAKRMZ+:^80H!*9WC'/%[BZZ5F@=[9)8(\Y]665Q #6]'/>@F:"_W4 M:T@_>G;<1V6)IB2%;\P93A!/T65DBEJ>[9A,F:);2-(;<7QOP >I&: .-D2O MTCBVN9.*;M9+T$QTH^,XJDJ]GKGH61F?*4F &J8TWFGK:8;KLBT]^&,W(-:( M33K'/AW?MM9# QVP7B]S_Z*R/@M'/&MD9P[$TT3BZ72*E!LXC3D/3[9G3/,0 MH&+WV6OIHDMT8F9R.Y-A8]5QK= MO- NBH=&LVVG\?XK;.Z??KM^R%)?DU/)4^[?/XW8SG?'GL,:WJC&!LMKYIC? MV#Y2?NQ^^AI5ZA_G]ZEA>7UK=.V?Z#9^>P?$7*O2;A0I::3B/7O1C[G241?H M"'S?6N%FVAQ__ UQ=P#]4.&CK<)!_K+=XJ@_XEOOQ M[RXCJS(U>_3.+O5*NUI5ZDU\[*94LSQ*68[ MCN*BH^:BC;(BJ;D(<90Z^QAX42R?I(A]Y;/6O_NBW;]W[_? M//TS2]^Q=!D)D%:'[DI.N;HCSH/YG>82!:AT6.E""?WAD$/>S(TWK%?/YFL< MB99.WEO9=?$ZBU90PG=."%N6*NC85JY76KW,_;/%"H8H/C@:/EAGD^;#!VWJ M7>ATBQ04/(T<)%R@LV!PHL;4P+8=JO08,(N-395]W$8S7,_F4_N-L0?$566C M6],8F%/3@Z/=ECDZ9Y>M2KM9)(P%E8' M#6>DLI#;F=YXDCDP [64Y/"% MC1EJ9BQST.(_73RDBI^_J'=A17O%5?>[%US/'O[0_OZ> MG/_.G,>)X;#W38N;NZ]QF&CQED=\R7?#N7<>/6PDI&'?X6.%N*^%XKYS=ED[ MKR6T"6ISP]%>\.N?M)5K=O&Q;L;ETMK<_L*;V X<[&@SE27M 6?JUFJ5&O]_ M?"=\E9H1O.&39MG^3TW7Q6X];(:V%Y[KX7Q#ZSG@/J C%4Y(AWPOWVW"L/FQ M^9.-JO]ACIUD?O3.P,[HZG7]4X'\/Q5$V!/8?1;2:=6*2#K[MU.*HOFN[-G, MMG:J]O@KTNJ\5OT0.D]::U:%U]+/+GLI%5ZF[50;:W=S0VHT]4X:X&TV&Q6] MW4[>":KEM$MO[&?I3;'T1N?=2\C=OCCV1-X:^T*Z/J$AXIH P;8*E)93*=Z] MF ^;4$:[6)1Q&@G;/BP6#]J8@H(U1U73TH;&W/2,JV>3!GBAVP2UX55P]\2P(3\$Z:"AROY?&\L M.&YV"X=\Q[S[\9/Q,S7K]'"\>%N/R^&/RFPM,7G%9/!AR*M=X]/K"T)>IV'[ M/C#/@!^.-&8X%BQ;E2AN8?+ZAW@MSE!BE"]L; [-U%5F;:P$[QX?'K>BIO4V M[PZH22=T]W:K2![4&ODZ,MWYU'C#Q;+5Q+?+3Y5]@4=5]KFFZ"1+&=Y15^*M MT5SD0D_L*9R,B[.[O;?4LJ5!T]^[MGOJ11^PVG2W1H=EP/=81U^KP)_ MEH7NC@U 9\,J_7?FBVU8;\DWD32X*SMO%<,+2SW;)=>3*;NLV;RQH6^-[@,@_FV2E>5KR\U\Z1?'BYG==,TL+P,ID9OW@X!,NOWY%*[L3-='2X MNKGM4G+MPL&I+N8+^_1JCKR)?VW2M\1V:N%7C &L?.&M_LK,<)Y-B^]33QJ" MF@\)UFOK:% GJV3"-&.(^2;#>D, #,OVL +-@1];F@GK>78H_>]X"#GM39C+ MD#3I>BAC-38MPQK"0F#!\(,9[,$]CY9)2;M?M=O+?PPK/19J,V&_9JPW\!!9WYWYHX887H M,ZL.'&;\J!ICV-B%,7TUWERDV(CF 'P" M$H(Y^"E8B7'@%6@3!Z7LW]9?1@) M<-=\N;%'81%S873>V?;X='6O_?G;_>WU8__V6KNZ?_A^_]!_NKF_V_ $BK") MN\?[VYLO_:?K+]KC$_S!6_7NORX[8VOO\L [^6#,^*Q;T]+@H5,@:O?CNM6C MWFFM6#KIQE"UD3Z&+4R-N;NF MJS7M<4UU_;S;;A9L41L=5"$S)H5!!1/S M)WIG-+Z 7QC%PR+7E:QI]-KN-8T44TX5_BKB$?.F/.T#/)K:>3N?WI<8:3:^ M#M"B](?7)U=N&^V==[%+<[^Y@^7C20Z5?^[?]N^NKK7^D_9X_1U<]L_7#UJC MHNDUO7'DM2^;'5#:7MMFRE[;^[ %=K-40B-()72I5UBO='JG5 FS>\HK!F=N MGM7;8N-E8K2DI%TS?;%/+!/7;>;7^JH81S%.*1BGM>LJN2Z-(FPT\T(!5YRE M..M0^TW7U-;>L*DM!QYK8]]:-P&O)W7?FF(OQ5ZE4%R=G2NN#C!5K]+2,S? M'9:U"A<,52RO6'XKEN_NG.6[X &V*K56YK&:9>WH2&P1IW^;UHA9WD6U%Z\X MV3_9W#%/,REA5OYF\NUNAMU-^INU-VHNRF.8=9[WS #;1UB\Z2V MR7H4/VQW"@0<4107:EM'2]'S^_1]H/\5SXOX:COP3ZO*Y_ - MWS3/@8=-J6E%,T;_7K@>-EEQ9&HLW:MH%EM=.E(:!+==:F>%KJ?N1MV-NIMB MWDVJ!)Y>VS"!]QX4I= Q5T+%/*&&X>_N6Z.G4-_T W43@E?&;0?$Y(O7=BGL MTV)164$E0'G\DQ.DF72E!3$'Y>"222^.9#K1G BEOZH#PV4C@C6'^Z;[4QD2 M%4U4=Z/N)H_(F+XF,A;J"O?)7C$Y@]H<2$Q=25+J@?VU,%W38X_,>3&'.)W. MM$HVSRZY>I%D:BM:4'%!WRPG23)Y9E4/HCF;1=,>) M9F(>V)3!K2+8UPMS$>S.@3\<<^@%8^&1M%SMP\/C[^['"A9_31>X8\TS?FIP M FSH'<'HIIVTH.IK)M62X\A'O'Y9.' (G']X.^I#< _TL?ZKX8Q^=3;.>X;- MJ;T6]B@T&IGSGBJ&65QK0-U-X6*%ZURV%=Q/*O,=YH_KTO;99:.>0P>2(A[% MV.INBG0WY7'!3I!F,B:.=J0,.@52!B>:#WI@\X4SG(!;Y:)?->38A>Z[V(5' M%IY8S1L9/*7P7$=]:_3 /--)5P46<51UO)%7<7"R*4=Q9,D7* M>;IIVY-R'4BY5Q#-=*()KRO#G6@C\\6$-8U3JR/QQ5?;J,13MG_K-?WLLEMI=>/3/@N4*"V/)Z%H.9LGD8V6 M&X6BY;SS/.69SU"G^0S-+&F=4YW/H#?V-I]!KS5Q/D.C4M?;^.GPJ0TQ)J)XYL,+]!KK1R&%RBJ.B*JVF(D1DKUCY/K*UT]Y\'UBNR*1G;I MDJJQB1*[@KW7:QV"O==S"&4KVBLH[:4BO=C$A=PI#HMT.I5VO>0RKSP.ON*' M#/RPZQD)>JV'L!^5=FX]=,4#3#^.?&-&P/02ALE4.%[=C;H;=3?J;M3=%,XP M6S/))@O M%ZO85:FULOLHJ@THZ+G#;.,,:34/.FY7CQZ/M&6LCT"II>PQ%=U M$JB[47>C[N:8[B:55;NF;FY?8,1 3&>7V48OCVMR@C23IVNR/Z'4 M*)A0.M%,2*XPZ27TZU4,4=V-NIO=*IW&&J6S?ZA;O8Y0M^TXN(RBM0+2FI(# MZFZ.UF$Y09K)TV$YA.YH%4UWG&C^)0Z3CG#H>:*A'U,T(+GAJU$O !JZ7F\3 MVE\K,U.I*&5QE;ZZF\)UIZSSS'("P-7K"(#;RS(041&/8FQU-P6\F_)X6B=( M,^G ,?:E#+H%4@8GFO;)&PV]A%&(M&CH&WE*&Z.AQUV@WMEEKUF0F=$J>%6V M@*>ZFYWX/ENCRNJUC'#GBF(4-Y_VW:3#V5C30Y21F['IHEN0 3Y%\;!4QNN M?MCVI*R#G5DKB)UYHHFK"-QY-K3S$@8E"AK(4@$C=3?J;M3=J+LYLKO)U8_( MA!"M-\XN]4J]6Y#8=U%-L\L<[U%L> =:ZW M<\ Z5U1U1%2U!8)^2N7?01 BO:O([LC)+EU&-8:QOS.L\4/&=KF=FX"-&K #[U*/;=&N.)A MG1]'LC$CUGD)@V0J&*_N1MV-NAMU-^INBF:8-=8,99VCL4MRUHM'SB?:+[9'J/,2EO>J+@)U-^INU-T;:-U=MG3,\\+5+2FY("ZFP+>37D) MYE]V#W5^3,& %?U>O=U G<>:O1H=Y)HB.?PJHE2V**2ZF]3=)YL@@.4 7]M M^-IVO1@ 2HIX%&.KNSD]3^H$:28=],6>=$&O0+K@1+,Z>4.9ES#(D!K*?!-/ M:'LH\V;M[++;R\(5*IY97"VL[J9PVFXCUV=KQ-AF_>PR(9JAN+E8%*.XN;AW MDXZ;U[0(9>1F'92S'D>A*A [E\<-4Z2:EC[D;=C;J;([N;7-V(3.C/34)_;K8*/>&L/'Z$HN5,?D0V4FX5 MBI3SSN*4!6BJ+0;'__U@%[_Q=1>!A1-T7W.3<8#K,.*;G1PP MXA5+*I94+(DLN4E<.Q.Z;K.+ /O=1N8B/EF=3^9#-V*R5G4TG:/9P M.D$[CZ()Q;B*<8^/<5/Q[4 :R\>\:K>7_Q@X>$?[^=I^SK99BRY, M_B\N$OG,-%BW,^X->NU:K==LCT>#>I?5FXTV&[79L%<;_JM>:YSYWYHX_LKG MQC.K#AQF_*@:8]C8A3%]-=YILF5IS$>YWP:G,Q!V-@. 3E< M@'A@#GX*5F(<> 7:Q$&A^K?UE]$!CD$!@KQPA?+80I "8S4%"FX7[R_O?G2?[K^HCT^P1_?KN^>'K7[K]I5__$W[>OM_9^/I=G-!V,&FM9S051K M\- I$+;[,<7J)6W46K$9TIBAPB,5#9N:&G.77?A_^>2;R*9%BZ0O?8J^KQ6O M\Z3W\5^'PNF\Q@64R!V+-XM?G\.O?HG_O-4Y;[4:B;^JG=<3?[[J4?7Z>4=/ M_M6J1ZU^A=[4CWQ1[Q_ZFB* =^M$ZJW8YQ)=&4ZI^S3?8[Q(!-O2M3\9^^%J MUZ!9HJ7#68Y!#[]Q?/"];! @I3?NT42:39]&J=6#TZMI4YM[:D] MLCGX(@/F:.&Y-=.PY.:E4?N,JO0VVGQHQVA?'^Z_:???K]%(N_M5ZU\]W?QQ M\W1S_;@)#:TZ@HT&7*ZCKZU*!T]K<;GC(+3/.ZT$@MUG-\XR!:<=]9EN[\<5 M_#RR".8.!VZU"CAP:P]) T7\I2'^-;5PV:@?^TDKM5Z1X$X5]2OJ#ZE_I[*_ M>7;9J33:\7[J(P+[+8TE)V$]:YZM.0PH86A.&4Y5%"8>_AS_-<06[+EC8PO, M2!N\:?:<8:S>>M;P E],SV3N11;'Y=#F?^&^OQ>DM8/3X!:=)[P]RD3\Z3ZTK&FEMK4O-;N- LDM15XREYLW9V04YMZ M(8_- 53DM-YXW DY8==116\!Q**"&_%%"7O+ M/?7=9W7>9%F23.!P@97X\WF"N0 MC;(3SPH=G2_U(,AT]G)213V%HYY]R)YV#65/JT#4\ZD/F\T3)A)A*3XO M#S5+HO4Z#EY2OO#Q$<@Z#(2-*031;]MY=54K"BD.A>0F0S +F-U65QYKZFCS MF#D.*$L_NV'\9&J2X2;*6?\0\2?B$!YS$ $UT-S)' M )6[L0_"28>BMT:+;DTQK;/+>JT@^'F*6'(BEC4*=6MB:9]=)AA@1X&U6$S- M>N]-F*-9?D0XJ3R@@I4$RC/=7MG2&=_9%IXPI_]K'G)/XH#.V67SR(K,CI56 MW89IY$"#6E1Y)'90\U#EO3.+EMYP=8H9W53E7HU,:QG1NW#DCK% M:+Q+E5)3TQB84U5Y5_C*NT:GB.3UC>% )&MDN@Q([(59GNV86T9#2BA5\X2& MC[LI-^&!IJUGZ=00UZ_>BN=BE6(N%@EE,]LVCJA%:"E.+G50SBUEZ9>"8G8< M',DB=72LHJNULP38"FSA%5,%]X=#CA S-]X0E$5E(G)0O?ZA?N=GFIH1&L@( MG5:1BEE4N'DO"?X-:"E.+DT$D\M<#:*(I7#$LG?!@PFN2J]1I K>T_"$>>YB M78Q%I2]RKQ6@@P]J4*^,N>D9TSOF)7%'^^RR4ZB*&>7F'-HQ3D,^G;/+;JU( M,6Q%/OM->&0CGRY(GV:1R.WE_NP7!05A.<%-C.((^^- EGLKX4Y1ZBO4\DQY5G?\=UX M(Y2T)[L_A'-TV'=QM-^GAN7UK=&U?[JII;U^=MFN-!.,#]774&9Z6F/.[I"@ M&F>7K4JSIQIECHN@#B>A,,%9Z=2/M)NFJ)K\^P*K,UWFXC@K=V([7M5CSHPJ M-05FYZGDHG:JR1_Q:)_@9&_"@TWB@M;99:=;D.(HE3HXD)9.)I:4\K2-:?Z: MKFCIN&@I'\&3DI8Z2$O-3@XCX(N8DRJJ;OYF> N'@GLY*^<26K%YZF;'AOV/ MW*^./7L$2@>K59STV_WXF^'\8#2Y\)$-Q>DG<407@54R)VJ5!U0XVEFGJ],3 M3TI9VZ.VG.Q% (JV"D=;^0NF=+35HY:O3B\S9)ARM+7#06U>'P4M&G19PXDI&/IGB*A,I#03CSN#*33 M +5<$'R4O'UKO7ZN%U(?!R6?"Y=P&A-5LRKWS!P77R%P5Q0V)3),2B.WB:GN M1B>'S*0JL3L*DMS4"-@A3;8P6]Y("!@IFCQ-FBR G&QCPKU9RV)XJ-+/W$L_ MO][<]>^N5.EGV19W*DFI!S87#L]24@J.R[%?82LGDY/*LV D/-;[<9"R_<(& M25V"O0Y8$YUX7Y.JO"LS?:Q)/*4B$,Q.MG5%($=%('E*D![.%E*EEOLMM131 M06WLV+,<-6<) ["[JN9XG^P;M1IB&&8>/JB"](6CD315&^N(I(ZE/6IH]/$1 M29Z21$<%6B28H-/T/Z>V]V1S/6SC-]XB^<7;9SB%J;$2C1JB4M:)$M4[3)S5==V%80Y:39CUV M>W)S<_)&'.QZ&8I)N9YR/HZ/6%)XJ*NH19:H8_,G&U7_PQP[B8HZ9T Q7;VN M?U*4='24M!.YTT6YH_S9_6O@)^.G]FIZDXD]Q76#5XOOM8<_J@,<\*T9KX8S M4BG5##WX#VQJ>&ST9,-1_QF>]%?;V72.>J/6.[MLM'.HWE*N38'(9\.V_!SH M!UYUV>@IU_BXZ&=_\J>._4GU@H!WG8IO_,#F,CC.T)[-?-U\*N[P+M0QT'UX MLO?C*SK61SS5),+7SRZ[385A;G#)1;N[T>O1]_$Y0,7\U+<,:8MO[%,=5 M!:J9T-QM JT9!Q\Y4=":/-3WT':]B^"P;_&L??[I6R-"BPA^&S9U)HX):]2[ MP"I9^$2Y.L4CFQ4:.U>Z06RY9I82&T4XQ2.B)DD1*XB: M/4/4)#!-6E-7QW1.I='*(:&CX$".@B0S0M3D09,ZTF2GHVA2T60N$#5YT"0" MX]4JG78<5[%X1'G$̉[]>7SUI]U^UZ_^Y^JU_]^NU]M!_NM;XWQ^U^SN- M8&SZ=U_X7Z[_^_>;/_JWUW=/J[%K3MIFWY"UKL=C-O3NQ]<_AQ/#>F8/AL?N M+>0V_#_.6GH!EJ$:$]=SS*''1O@+L.^C/Y ^F<1F31#]*L=>= K+,_Z_)\)J MG5VJ7H;C(ZXU>8$]$1>VRF1&LB]P7**H&0,*2]#%8DR" A28*Z"_L/#*=A*8 M.%Z>>I^E,C'/=UB]#1;YT,$@X!?&_X1_3Q=XEC*; M?[F]Q^.EY37&1\&)&5NA*GI"<$X1\Y$0\V[B( 4GZQ[%]WJ[#*6H.,H&6+]) M01+M\_6O-W=WB/I[_U7[YW7_X53")JDXL;%#O9*6GQJ8$FU6Z@E=@8 ;M/5>[Z M<#;CHK_OL^)"Q87%3DCB@L5 M%Y:("XOEJ;5R\M3V7++D+\2_!7C,6;X^7KII2PW8QLA>#*:LB+.@RK^Z(W:J M'G___OWV^ANX4?U;[/O#]?H3@6#UK2;NZ_W#]_Z3S?W=Q=;C5;; M))ERBM_/NV>R=5[( @C",I@;((Q'"P>[,;P)T]Z8X:"^V(ZB"*P/=:\[P!@7>!P/7X^)S#$7C>YGI1C:NA/6.: M9_Q<@5J22_:Y;$R:O+>R,^DZ'D5*>$)"0#9-'=[K(O*\JE307J\,N:F9TPU]G/.K)'I+5M:A(OP47:G;4S[B%"6,=U*4KRB_")2_0YG?Q/+O(E$^67._ M>,9@RG*YCGIMW7WH>!]:L->1^7+Y#_C/4E5=1X?GS&W7Q/.Y<' FF/G"/KV: M(V_BWZGT+;ZABUKX%6/@VM.%M_HK,\-Y-BU>+JA'V7#(,#V1#WUN>"!/$Z89 M0W"XX8UO6"1CV1[8FX8#/[; VO38LP/&Z-QP/)RNY4V8RY!NJ#'Q!R[?G*8UZUV\M_#!PDB_U\;3]GBQCY\L+D_^(BD3E-@W4[X]Z@UZ[5 M>LWV>#2H=UF]V6BS49L->[7AO^HX;%I\:Q(4@:&)W#X3=S=/UT_:D_WL/B[Q_O;FR_] MI^LOVM>;N_[=U4W_5GM\@A]\BV BKKW4 V_I@S$#->UAF$"#ATZ!NMV*QGX. M&=:CX_3*BC9GCO]7A(%ZA;]-[ 4)<_BJ!K+<^!C?\*8BJA>(*&YAW"UFL)5A MW*F-FC2/<&#F& P$R^L/:2&@@KZ#:AF:S'V"+WZ>TH@2WXQI<9O)M!9LU/?$ MS_"Q#$R>.0I\9\$2U:UT5Y("#OEQ3[0'RE6KBYGOCXL9+.4-18ET#EIX$)I_ M$ML1XK\7KF>.W_+>(#WG BU1<[B!$OP"5^.8<[)^8:>?%RY\Q"W6EM[=P)7M M>D-;^W-B3YD+=C7(?6TR;P,%J>(JN]@)F\DQLS@'7!F.;+R [;6 )<&XL&WR' M 0J&!?'>OMC,=X4%=;+%$\-NR+A$QWQ)FB> %(N'\;A$E M/*+I[FH??C]_//\(]#*D,X7/K%PS&?MNA@7CUV^L/R?F<'(-XLY[N^=7F;@+ M!/M*V 1?1$7BM8KVY?SJG'/9]P5XG[;V8 [MRC:'W\I\^#C()6$>-![LE6$9 M(V.K=;6SKJM5@^.,1P-P6=_8SVV/JY-Y63AO(9E4_S\#Y.I6J^IF7A7&RQ-X MW&>@\_][OM7">ID71CW]B0O[O_"5K6BK5!.')2\:_@'FU5:K3JM#TJT:](OW M:BDSO] QDI3"UQ.3G2_%C5,YN9\- MUW3OQTL.[AO_;]S);:=T9POG\=%^T2'X#I0!!CWY%>7Q]YXF&P2X_8(,HBJ# MWZS+@X+DEOA.WBMXC>!0V:\6NEN2QP>>#;A%P#(,5TR!=JRK MZ4W"+FG,,@+EB0C#X\(:&6_:<&J#5^MIX%=%_/+ZN0:TP1QF890!?LN]=/AO MB\M1^%M3HWP:PU_C(UMZ;"$NOA5H-=GGC[Y1?OHCFWL4[."_Y+]KYDGAO[OL M?GP-5SGC/JI/XXV2TSCL"^56L+-R$?G<87-#Q.)@%RM$-=XM&BBF]\9I'"T# M[==^_SM0Y%\+$ROL9F F/-,WD#QGQ@\&]RK.A$C,<-W%;,YE,H79# )X)DJ& M5=@.RE@_$ ]K@<\S,9]9JMBC?^-71D#TP$L+AXZ?1[6?\>VKOL??A,)>)&*3 M=^L_/VE)#KH2"S^@B'4$&*&2T!'XE_!?8=RHEER.;&\W?+(B>65@YX#/04L/@HT$2J2J#DU0(<#'8H)8U[ 5/2Y M0)M%[:^0!9&?$7MD/+5?21<*\<-E#U7L )^0CIU+)G*>="HPLY;1ZU>Y'*V2 M$^>5/]V&_G*=,-VF\%0JFVQ(6.8(,S>&NWIRCV: !T$_!.4W8E2!5*$,R_0- M5 =\D*=4N% 2UIV!/@<(?.^-:Q&' 2? XB8NYK"FS(UIFOD"TSJNR!O/'7O( MV BU!N/2=^BPD#%K-FPH%RYP9LZ\ ]IMO'.BC+7>ZC@_MH=Q+"S8)0K3PEVDU MR2NE6#=>'=#NIJT.*)QL>YR 259] I;1PC,HD6#CZT>6CT@CL'7!+YU.A;1S MJ;P0>-X#03%$ 67Z^4CM&5/!%DD.,NW@J\,WZ6,?*US"",F68"W[,BPF\U#_ M,XN[GN?R^<:>.&!O-IJSY@L3GNK,0*-5\XT+-JI$<_)"FE.U1^<32$R&AV!: M?AV "\9%<#3R-TUG28I;N Q&FQ^PH8%5._"Q-S37N?U [PM/-[! R,@&Q]YX M,L&")A[K-H;#Q6PQ)>?,AF^"W .![+ ) W7S@N*2 &<^X'<_:IB9 MP1@#?S0&,U>]1(0<&)4Q4: GON-0-U4T$SYAO57H%'P5P$6]L7+3/!Q+RDX^ M.Y-7Y". D;]\_ SMCC!S_,S7.YXI_YX?V$E8NWRUE$G8U<)-P M#6&D#8@!K$C^Q5@("TP,H8F]8)\4P'O#Y4[LZ8C'%OTG!_X9O1 Q^*]X0X-LQ.#ZZ.; @N1OX>3' MH[ 8Z21*\!>"ZZY$: V%PK,%F^+?P0_D*1_B-)(E!?X5]D=^Y_WXJ\]*-R$G M<8\N=.1Z)7?9<+O:'YP;QUJP8TW:.7& M4(0@?$DU3O23$H5M163<\=LK(V(5.5+$XU7!BN?&&_X8?CJ?._9/2A7(8A/C M63P:;#JR8R9\+QL_!XW7=L\O&H2Z-RMK4Q6UU<7K][+)YF(LCQ>'%50%EBB4;-EDS2%9[!4PH MZDSAKIRD)^A1YD\VJE)'#8845[$RX M4-C\;0Y-. ,OB*P*YX-L9S0CS[7HROUL/#F!H'*G=-F&?,D3DSF&,YR ;_R* M72!R+0;H9_,_?FA@P0.W]@#.]$5HX/F"JNMPD;027EH0-3=XI)<<5V':TK? M@[K(1!#\1Z:%/ON%WB0V(Y/J/P9*8@CSG<2AG*]!Z/(Z!Q*:FX8D/S)&P"$#,N7.'&:.*YKW:5:P=\>\'/D &/.,!K2TD'_?5 MF(M75*C,D8*!EPNT^1ENWT"C! M6!\=,GYD20C8R^J!RX-(&PF/OKJ!C<05*(;-%A2#N^7V Y84\^4W*'>+-@V( M)@HIA%F,N T+MVW"'2+W23%&P_5_/V @@2PJM!XGUF#B/];Z"3(8C'(N(A4_E(UH$<)#OH)9T"*-%'])Z.*5U!7(G#/1@$+D#D" M;#HS%S/7+W&2'C6T70_V\L7_>"7X<&75ISE.4_ F8-L@-B7*>S5,NW#*P8T* M&IO:AA!PR+>/D+%G-[.;E3D:HR^)=XC'Q-L=&[.8]3*6)HJ"*&PH9E#EK$H"<6,33. M4N9YI(+#555ZG5K)DSL//A"^*",UB^ZDR3X6'L!J]1V,,]H.J,J MAGW>M/G$ &MT^%;Q4Y%4D0L*%<,)+PS%.UC1"]$A':0;Y4P,&/'TX$@=KZ^2 M1Z&ZXX@P\*E!:"M&+&?^9+ &GAUC!H_]S-4R5X-A0:$HBO.++)X=S(U2'AS< M%-XO)&J7Y4R[2!!A(HA2MWYZ:V@Z0]#!'KVI(A 0Y9V(.D!>WXR5#5@QXO<% M19]-"28P'_R##DR[H<%K^B(/YM4/D;V@6\4S^J"]XY<4^7IX(&';G=\,%%1O M!W<7^AI!%7;TIB//#LDFK$'TG\T,!V.6) .!S@(T(9E^P(##V@T.%JD]A"04 M.P"LQ_!=QF7/.-)="R+%#P:+1P4ML6\^DM'*-0\9KM";./;B>2*3=&2E@I2$ M>>1_EUJ-@@U'V"&T*,-[Q$HFN'=1DB3LX:BQ&L_11PQ0.+'[91Z3=B?5T\:N M.ZS"081Y+%H@*VH&QB3&@(V?59]DP0^"11KI4(M>X'[-PDWS-]M#/0N':S@<,)& MBRF['P>G)QQ/LK 2SK!PG>H;GY@9GIC,^12,L)$+$*DY!1O'T!%YN5W@\M ( M>]C>U)B[[,+_RR=_6H=IT7+I2Y^B3\>\P1(>-)TC_W7H0)S7N!,A9GV(-XM? MG\.O?HG_O%T[[]5[B;^JG=<3?[[J4?7.>;.;[E&K?]ZNI?O&>XOJO?^H-?-1 M-AP^\^[$(>ZR[A-5/7GF$ K;#08)'=F66Y$M[V2DE)\"6F93>[XO^4:;C8(2 MIIVY*F04 :PC_BVJ<2&-2J>6>91B^OLI["QLQ5VGP%VMSNZY"X$B]4JWW2T+ M=^4V@6X=-^Q;WW*(O)46E9YVBRL8OXR,$ 4!CC/"UQP8H86]]?5N9CXHUF J M13XH1[N[)Y\VR-%*+[N14L9YM_N6E#SN>F-1U0['R]]*;";N]YCHOK=[NN^< M738JS01H[NW,AX+8WXI\@'S::X9 YD$^V+U2:>",KL*03]XCCNN]XDG0%;'K MM%I*&/OA5"EM9"\P4.VO^P3]U%T<3=DER3KPKT"*W+'T(@3'>_0J#3T^5& [ MTRO/FROL0%K%N8IS\X"[R\*YW1IP;K=2K[>/AG,C W63ZP[*F-+&VADJNACY M!1=3^Q5<,,),=JDOP.\4(9B9V3O/H8+DH)B(OB[0A;!4)AC/(-?S3PT7>Z$J MVMATX&_8$O !8Y\?PRJL! 1C_"9^RG_\S'9X77M8G"8C?5!%40C&1MU+^ W" M6I]B#X\WG!#P@:@6XK7?$319']IYN;0Z B6LX2'9'!$W"JS1O HK#OV/YS\/@GI)YP;)WH]P_$'X0O.M2\#AD6EU=)ZF)6#FC92XG!O**:2(!X8-*8PC2%]-@ M9DGBJ8\(W+IL0\0B^ M0<5+08L"]4 M[X4Z 8;8PL/+"@44%M;'$6&&E5+46+6"9_S9>YH/P7^N]?TU M "&D.Z4U+MTVQZ3C0*<$:-7(^?!KY;#-.-(Z+/JBDQ@PBXU-+^D[S7,^/,8T M>$-00O#G77D#K#ZR$?"1NA^$] EE"PD@FG[(/,.<2F3,Q0:U3B!"&%[;]"W2 M9D32:$DN?97D4KGJ]GQQ90+]F**$EXI1>>MRV*,B<3H'>3-Y>:F\-/ MB)X;?FC+?25 K-@@ U=E#9G?P@>O=*DLWHW(+($JM_H=?IUG6'!+G5E^(:<+ M5"5F&2'2,0AM,?!"B& !/.H_$8CB%1'6>-_3'$[8HXYZ(*;%D*NO<#=!T;9? M-)%&- E1TG,,?'\5 MUQ)8>M@.%PJ4ACY=N**G MP6*OH&C#%GF)50/#LMRNT1&I+VG"X9+FO@B;,/OD:0&I9HWH:[0_.20$C$-SF#SS##T\*VW_!*N_ M<+.UUMHH06N.)MIK%C.T7WTTW[ /;9YL-0^"SM?5M[%EU\]*>*]2- (U:^?= M;J=XC4#-9FZ-0-UZ\J\.VIW4Z^BJ.XE;B]>!,OR="^Y;5(:GUZ^D6K3V505Y M@$SNK2'-0UY]O^F+]=_?_>[O>L/]W_W2S[+]7#MOCK0H(NVV2U_PL*94"5DN M=:%#Z^RR7J_H[=:NFVR*4C^KN.C$N6A-V=!67(0M%K5*0V^4@HOVUJ=V %+X MO#"GN$@W%D[92AUGWGD18N$RCR1'5]J;AU>XSW)KCJ,S8F%9PXO1PL$:G9 O M.F>7K>7,1/7]E>B[64D75E);7@H?U+D4.)2T1FWG2DF]&E!2J]*J%:GE]IBC!=>)*:8\'.BC MU=B-G>C)7IUF-J72V,W=K$3'B%GN&EMU5F;3V%\%;\K7NIV,1?"<9J4;6F4% M:+!45+0?;9T?%34)@JFNYP7!I/SK-5 P*ZK2=N9=ESZBKRS[;!I'IK@;Z[N@ MM^VD!2'I=/1X2XAR$$M/1FM43IYD1(@ZW6Z1R"BK=[@FP7Z8[V]@0F5,UY22 MTM<(S)7NUW;$CC'<=J5=STSM9ZS;SU2J_0Z M<:"UC\J@+C/!K1'T!R(XV!F!L_0:<6BV@Q!<:IF_)M14;Q12_"?WYU9PY-2! M*AV3T71.O((KZZ$446SMQ3M*#Q/5K&&VK%5I-W*N^\IXAT6OK51\J_@V/[=R M&[[5@6\1$SLO;.!#\FW)@=UD1 ;&8:>8&"@]I3GNHHUYS-M2#=.A.A%R.WWL M,3&[DUIO'3:UAX8GD!D0(@W_:FAC8X@#%-^HOY6#X+PP,72;=]82PE=DFB>- M[L0![4,^6UPT4P;CQ?GXQ"@"G(LN-#.^6 MGLV14BP7IWNRD;P,?E!1()+Q E.W.,U23&:EV9KN1!M/[5=_JBA]$ =*XG=A M:=QHQ /'0\ >4 $AD;0<]A.X:N0#X F JZ5MT A66MA+I.E]:;.P,SSBY-U5 M.-Y70%.(&<61E(;VLT5M[3[L/QX NK<@8P.N7CS0V M6EUZ7P(IO-=^_8$?+JR&/OPQD08$-([A< 0K@GF)?"T8H2HM;8J;"N#C7#:= M1L$$0]0IZ4N#-PD=18QU1^ JPW01?T;0B.G@#%QT+@:._8,Y+F]K)R8F4+40 MC\YCPXEE_N5#&0(E4E.Y9E!ZOBFRX/](-,XH1_!-K)0!#*@5]R2C3U"P+1 MA66,GBR6"4-(( QQ>K;'8W/(I2(PGN>8@P51M]!29H V)8]I1F*@1UB,<$T1 M W1YE*=FSPDDU,><\R* 1PB.Q9PA@A%&@0%DK"C$C[K0/A@?.4Q4"/Q$TM! MB$U"Y 0[:\"1JJ@HSW\B_-^JD@00[.[P:<(T51L!,/!/N,:Y""4+%#S^!N/9 M852X^TG[,/BHS1>(GB@P*D.H@Q4O$A+4";\V=_"4!7R8>)'\BN%';N\9&AE9 MN!<"3"1(#)>@_"0E@RBPD=GG<(O,^81O_##ZJ,4>0K]&_%2.%&N-@$Q' G@E ME*'EX81'Q)$1+."/9Q_#858)879.8)RA#ZAK 9!?F'!D& '>DF89S!)00<$=@K(V[MA=\%6B+F M<^RI_WZ?&,^U*_$H<3 "%Y%XA1\): ,Z"A]P5<*8Y/1)%B9S?20WH$]#0,#- M@"=GBYGVO# <<'O0*O)'=L.'4=^[VHL]!9VSXG1AX2\&W#S:<@(#SG@34]4E MP?9?KK_\D>T;3!P#SB)X88Z'"L88-V(YHP6+D+/0E^;O!Q?J#GVIUM5?G)H\4%HIMF M@W,H9"WV"Z#'0&Z_B=GD'"1YZ-O:9)+:SV(!^":TDZ:QAW%I/9T*TY%LQF7\ MYQ!0U4>")A%6M<=5--H_/-S__M%WP'#-_!7V "Y'8%&36X;NFG8N2Z.F@\!'FI@-=CJ^!6 M!PT'B,8*W,62511(4'3SC>E0&-HA\FWX7K))9MQ ']B.PWT(7"Q7%(X EY: M^!02JG0044QZT1#BC(3TJR)C[T'^X_2F#-P@""&TA&'N:,.,,1! ,6 M8!Q&7=O $GLBC$OY=;ZQ3)C^9$I)QLD4K&81,:9)&@;&*L>P>+)L:!L50?&+ MN1V+DL9">D'DC"^3$Y.,HBP6Z+_7GQ( EA^<5H 1;%VZ4 MPY/*H3D\BMX1(4R!J0)Y <)08OQ7\RZT!,%-J+F3ACS\@WK_6K;(U0% MV(0,$L)Z-D%T<\Q,_U<\VA<&^5)B4TI C(6,[OG;I.ON#T%R88PY/ R!(%H> MZ15LR&&1T3QAD-_ 78IL!I\YY#LN<2%@L9!;_,,AQN"*WUT,D*-I$HY4.K4\ MM.?%9)AI"8\:LV#3-Y_:Q10),3XBECD3Z:]HIBO(5CPAWAFD*U M)L9B@,["3&PH@^'0='Y'$C),OC_G&8 M7:,HSY3KCJ75<.N&9W6XP;L !3#D/[%,$87V'& %GNH6A@VAT:.4!_'F)Q#A MF5.3IX;@CG%B#8XCH12>OTJQM-#5%R.;UMHE^Y- 776 MCT'MTE"D5B7,*04L&^#SQCP!G%)6">8*558.%I+F@5&F*M6PI?::J?7^Z235 M3H#7V&O%"YXJ*5?0WGX%[;-+/3[\BA]5ND5TME\$^//U.-!,="031O^2PV/&1$9/) '.(()WL&XE:,"\MSRM$C MFXYO+'?AX!;]R6>K*[3@L_##A(QBS%(.Z ,-L.5S>&^L>H M::0"UP3G";<>_B2\;9JV21D^6/YBQB.F_+3#-V.P8D&%/3R9N13/&%+8#RQ, M%WC/!"KD5&+0[%"4^N/ L!SRR:5#%,1\^:0:Q9P-%PZ LNM^TM9E\K)HV=+^ M/0=3[DDF6C -P9^!$EZ=O/#T)M8&[5H@B42H1LS\6-U6LB%.B7WDG![O!>@##'.BV9&%97[B!DF!H\PA]@4)\9BYF M$5/-8AYQ^#/FMR/1_*!84'PMG)?[^.O_-F;S3_V0;9,.F>IS1'1_+-QF+EC\ M]6TD8T7 @%.#&RG4";X?%#Y(/PDK@CB%S(GHABRHX$QZ%P^AHACC?C)73>$Z MJ=R188%4H&:E*F 4]J@$*4 0;%^:P>R*T'=0GIFX!AJQ*:JHX":&/+Z\UCIV MU.RX#9+I;95,5\GTI&1Z*S&9WGXGF=XM?#(]6C)F6EQOXQ[X^#A7^V&!/1RK MNH^4QOJC[1-D527R66[+0!+P0:LJ' 7*4U C3Y5*#\;3!7HL MW!\09H>%9#U%-\1Q27@,T%6BH:HWGG -7>$(R-^O$-0=T&,E\&@]T=B"U;ZV M@Z.R@P7YZPB* \FS8C\HR6H'L2)*V4S8Z#G(!6,=(3Y/7CE_?O2YP"/$CKZS MQ.0A@R-FD?\=E!H $U3]<8&P^>5C$Y:6OU0_YQXFX6')&)361EATX21.M'^+ M+H$&(D<=U\!&-"-1[,"7)B<+?6%II6*%^"M;I&,,?H_2>ORT>;@!D;L1E:R4 M9AKSR9>BP%8NZZ5RFZG(O 3\(:Y%%%W"O46C"GB99&J!S8="BWOOH2\OZ,); M6AA5^]N,OY27@1,]6,\4_P"&FC,JUJ%:$RE38L,C(1]2[(R-EMM^WAN@N+Q[N%9.N-+>;6"+"CC: M?-VC#63%-NF<[ON^>BCX[\02^[3")!=/(&ELD5WK;+BIET "!A"OU M;C-AS>_=W2,+W2!E?J-0S7<8A#&C5_D(K54 M9[R898&\E"[U<^LENZ05)NV2S4K]02)39#'G&5,\Y!6!E>" JB/+Q<&28IZ+ MH" D]O :D= ]W-+,'O$H)[4K8U(%?;"IF&AM+3#@ST=#AX4%?O3/]$*+AUY/ MEFM@^R19Q.9/-JKR[J;P)N6<#E(/7FZT29(O-VR"K$AFJ"F9?OA9*I$PHH89 MJ!JTISSL( ;JMH/F)[Z6T=)B7*1>OUF0*#IR@&B@C$:F[Y..%VP:]+O !X@9 M^#EQ- (31.E/GE>.6Z4SQD2'^L3 GP#I .4-WS&0L,/4D]H_94L6'X0FM5[[ M)'R:W$"V;RHRJ MGEWURXV"$&6>*>ZOG/VOA$OR)-F^?6M$_YSRLU[IG!=NQG=*YUP<0=4_@W*) MLQ5>VSBM"XBQ:9Y/00@+^6'!['GJ0Y/2-G(=C5 C\AKHB8* I-IP7\_P+@4N M6B)Q6*G@,"1PS$+IS$&[8E_K"D]/GV@.Z30O!HT%.9,4Q M112OOS.I["N^,T.DTB.[H[3,"\AZ%.XC+N/Q==BT75*E&9@Q;CP()/G-POPA M@O'MGR"IXE#EJH")(7.$4C8V&"^4V4\FMJ7@RNH(19PAWG(TN4/V4GB$%X\2 '^!>4Z[#O2A"I_>FZ\H;JD5T57(7,I/[L@.07/PQ0N)O%V7RU:\*);6LY9E)D@L$?.($2[.4JA15/ M(\#/2E^I)0Y DTZ@]#*&]]D'4$ !Z)./*F2(TO^IB",&0 (\ 1R8T7YF^AF! ML$'+F/,YRIPQ=M"_$I0-%5X/?6PBWA; Z%U\#9[QDZIH_#=Q6PTL<2'4GK&8 MRN*YY&=? :*%3PM!FW_A6.YR.P%5% HO(ZCD$9\-RQQBY33B[:/%,#@C_JXP M/LP+ 3",ZF!<=$[5F?Q4>%6F00 ?2U>?2.RJ,7-I!WT#QZ.S&/WEF=1R?U6!X- M0O _[E*^3#1H^6A-0VQLBDA,D#+/-EI9%_"Q $\'+M>A> @E\_#G7$&,06)- M^ <3(B$"BX9"3(:HSK5!7@OC#^4^Q9?\"$X0C=&P#QH-PC=)6/JYTAB(B"B+ M!\\"L_730%/.C'_;5$TJ@CV1YB.N/ (=ZPB[85D5K'F5WZ:?@- CGRJ9^+19 M;<#0?!1]9;0BN"4)!X^K2OY:>0/^ DFYR\_FFB\*&RB\S+EM6H'V#KP_"2+1 M/WA6Q1 =/)0O=@FEYM"*('V_M'S$#(RL$JT-ZB[# C^> MU95-E, :HVSO/[)A@N*? LJB\3789GA!QR&80<9TU?_7TCF M_ M8"QX$WRN1%NX H'AF_"2$*]&(S!V6H!0$9"L&VX7#!_?'V(RL,J#W*]C$ MT);R)$MJ7N90;T)?IQB)P9VH43BIDZ1:P*Y>I&TCK#U"^P)7X#=2?""C'*SS MCY6PO@6L%O24;%XL$OIH45Q:OQ8_<#YQ89NUTH;($/[K_2;MA2>7WH>(BS 2I6"B2$Z20#Q,*XN@B)F$]JEM40/M>,G$C-@(H;7+ M([GA>Z.6,AFQ(1MS2F&)["]]:[4 6"D2-27X/)S*Z&P^^$I&%:Y&[.1W[S9BB#V=).7*J4/4[R?$JD3P0 MMI4"(:ARS[4^09Q)&/7^DTQ114$U 98/5#\(9@3@ Q$C"8T*L0&@:PQK:9Y! M5\$*>*Y$R%^90-GX7OR@M'A:U]@8:27 M&_6$R('?B4L'_\9=P:3K@WLF9D.\/P^;AM9:'#Q.5+$5PN"[E1,M-)Q]K0 "K MD"YF/"K*K1S1Y!6DW_U_\\@A6J&6X 6IU5:".AB+=*89*.2$@34AO_/I/8:# MK;?<&QR<2'_%H'"BN8P&<>+!@%CW^R!'S*P1+X M[;AOKL>P3GH8@(7ER_2/X'W \8J2%!S[.4)(;X3;P?C)M:AS6JF.$^:*7ZG!$Q,C):/[1E$=N!+MZEG9E1'<5%+;YJCTLXN6YD"7-QJ$<5D/= M"&9 413ZH3YRCJM]D$JOTNE E;U?F[WOJNR]RMXG9>\[B=G[[NKLO5Y\2'DY MLRB/4Y'LDYB._EA!3?[*:- &>18.>Q9M@)A*Y8V;-.TI$%ER@&*P(%,'7 C7 MMBQ$1TTE8J-. WC5'B*<\L&#B#,IX)>C0YN7/ DP(88_HA)7/+_B^_K4NLH& MOM-NG>V->=3@TQP VO@25QB:@Z(DJ*.H1D1I*8QW P2M=Y% M(#AM8KPP"1YX,\JB+,4W/M;FCL:DW8^_@$:\'U_3^W!A3_9_\X3C5]MYB)!; M))T!QS*\&"V2D)4BD_VD4HBA^T;H25\\7*K[X M7RZ=CQM.^HK4PL< ?-> ]1(]^4L6%K 0KRNVL0(P]5SKBS;SH#9']'4!;=/W MMJF)6%M@@&N\DI:(!(M1GX<@.Y,Z&]>F!NY./!N7$E-X579SMZM'(.!*K1UO MF<\QZYER!_%%@EW6:\=SR,0A23T182 SBNR77VH]HN55I]YJ\_5)J;^W9(:U$YFB59[RBB+<1 M3)I0L/.&5ZL:@.D&J+?GVJ^.K^E84,_CX]\2?8>1.3&\ (/5_.VH<7A]IH'E MHZ*CT9V0?3HE48OQM!=@5M)X\#22[@/&<)01HV09KW,5(TBY6*;ULE=I-B9- MAB(NB2&^8B*=#U2$7]%]:[];Y\/#XN_N1]B#5'(FA#U-,.[@>SS5*B%U4 MJ!>.WG%H>J1%I0%BUA17M2!-S+D9=#I2C0!.3IAR4_W%%K-<>>18(V!#Z@DA M 8>O%EM'E81PVE17B2?G+D_R*S)U8A6MH$J14.489' $]T!@F#[EQ&'^Q?):5QHR>LB;T.Y2>Q-\:17.R)+N M]O6]P'O%+Z*0 R7(>/6R)V*99(OQT1C\-P/FO:([2M\.YMN&D/-!K8V$6;=.8Z!E8".CJR@?$H5'DI0;]CO[+!LP'&^ J M0(#7B=DG-+L$]?MH@PW2/%J!6H)K#39GQL'YY T)NV]YP@%:@,;0"\P)+%H. M!S(:?NT=HFE]_$(&$IKI'ZC"R1J$4)]PF'Y@* M'-&!KSPQ]@,[ )N=#Y,-(*E!4/EL[OJXA:X\7TK[]V+T'"9#@Z(SPB%-?LPR MN-MZ=+:X9L50*(VVPK:/$>/15=Z1@M*SRJ5G%:5G%:6GO-E@LNVJ!=(,48RB M4$L3*I3IE*%.X=!#*+P%N",AY_V)\GX<8)!')_]R;;0\H(%/Y W \,/5^0: MC]WC [UB*G;.6\U0$>5:H''-ZW?=[\RA2.-*D[E5"(F38/L MJ/[=#PF/>5+?1N7#B[MH/^8+6WJ>?#"A-^(Y9%._B5B4"#,2 B[_FI1 PAA7 MKOE9?*7HAKL&Z>R]K>3>=LFYEV?G'EC0PO1=]$&4AW?#Q8\"DAI'(YEB.B6. MKJ\(Y%-0!.1F! !?QHN9J(\^-)G45,)PLR9"SM,ZP_]TB1#"J\Z\9<3K@N: M"CZL7G0IPE! 9&/7E;[O-X]A(#U\A?RP =5'VL-@XI 4\9D;YJB*Z)X\\B?4 MG9C'*7I)_-$7/(0M'B5\T]5/$NVQ?E=PL/-WOA(*%IFW!5:$-*@]*F7$\4DG M"JXA*?:9,*'$RDTWNOB$?:I@YO;!3*P.HF!F^ZB#F7?LM1_,R@&I9]EHN9(9 MS*7]2IG?22?S]S[I/'49+88/M/ PM.AI:/V1/0=6*^UP]QNI;XEQ^ZOJ1]+(+\$&'S.H&:+JT\BT$!\^E#Z')3+D=I(M1C#]!I;1 MX-+$**8)=A51DS$5:OJK\GTS^='& ,1T-"J,$IUK"Q+?F'?$>!S%#?'Q'&^( M=LX-6(S:PI5S,4W^8W#D]59%U.>1KF4T!<) FB)S$YU,Q()=JI7E-$?'A;<3 M1)--+!2D8*G&BY7ZBV>@*:U1JXBJ0"H2@"/T85%]4#ZE$S(DN!I")W2+KA.* M)9?R%L5P!]H_@=LW%,G%$"666!%%OX)KZ0 M92&&8SB>0!:T4NHH(K,YZB-6IL]DX,[5$D\2/NOE7;L2>8$O)E$&(O!!FD=U M-A*=5+W)R00DOW#/?6M[E5!\8)[T0X'E[7> KY#->"XB8Q.4!/$CVRIO@F;5 M)O.[6F=2[#E-TAI#$G0N-]87-L!Q[]^H] 7#M]R]?V3@WI!6AU^*.HLGQT"W MA4_P^!)07MP>;.GQI'=+3YOT/A3'=I*#>BCK=0H;ZI[^#T8\?4K MG.ZM[;KWEO1DREMS^-4O\9^W]/-6MY7XJ]IY/?'GJQY5;YQW:XU4 MCUK]\W8MW3?*MZC.NX_ZA2Z17R30"E+A_SD##@RRN2,4B? &( ZM'F6L*1O' M"(;32CZ\UETGN&KOF]NHDD/.\D9;;9(GV@^]3:SD=3U*S7Y&-9YB5S7NH(0UW#PPAC^>'80:O?4-Z67N8VW[_B!:7 MFA[']+\X/6KB;[WBD>:OTC0C+!]YIDEA;N!?+--INKW7M(.HW@WW_O>,FY.W MY.!S"["G-)W0W36]W('8^FH["#>(SJCD>0_V+'F>B3,$YJB6\VSRVZ] M%FN*YKC:V3)^)G%&Z^RR'H=C^*AXXN#T6R;/^=#^9^&^?PHN M+N;'J$_!8Z(O@HK\5]*1GG;[*ZR94JK^->!8R(U/]C?!B^^K>AQQUNL62-7G M8.8>+9&(U*FZG")>SCXX^*MA.G]@K702*W>+QLK*MBO2 @MIR JJ:G2*9Y$\ MV=AUX$YLQZL26).94+&RCINB*0U1!-&8X[RY!994^(O?*.=Q7&&971Q-V?7" M^DF\D;CF4HBG;XVBBB,:_:S6 MLGG'QU-"0 F!7+(=ZZ3 KK(=[5K&;(?B9L7-I\#->3+S(QJ83V!?2F7+:=5Q MNT[0Z[TX[Y95'9.#\0M5$+]7]R__^_30DEHUA9:TYQ64 "V)MXFL_NWZZ5.J MX+] M?6%7-1)%_RW5,'_,=2Y+Q7\8_^8JO=7]?ZJWK_8BSN%8@A5[W_"=9W9 M@G^;U/NW];/+3C<^!*W4=06*!Q0/K N HXWW;@"\<7:IV$*QQ9&P18J2_W83 M58(J^2]F/^A*J:+Y**KD7Y7\JY+_O:G^1FXE_^T6&+F-3H%4O:HJ M5R7_I;RR7_[7;16%G9=D5:8"$-657RK^H#57U@6!^X1B\4I>2_W:&2 M?STS3%!A:@Q5D; 2 B41 CM+>'1S2'@HAE8,K1@Z'4/G4O7/F_#TXV'@%57_ M*Z!$@V>L+PR&@HM)/[$2-*G(AP.XXT14H F&:POF MU? !#_*D&G[CX;@:?$_D-W7Z3>MM61$.N0M7(Z[% M7O =!T/ ! M=!V&&BIP?.7\A5S41CT&_B\#VN>4E6O?P9)EV2M7>7=8Y@R^0Q6=AQSJVQW@ M_:6(?BD.@Y+63W;5E_=)E>X'("G)64EE8A7QB#'NQ&V.39M*[9ATJ.M-?F",XLML)BYZ8LV(=B1VX;D3]J1,,9MBMK3,]E[)0T=7C*8833':IN5# M[[#9'?.N#,=YPWFD,QP-G,1NC5Q 1??%;KF5S1;1 N9C? ,CV)O 3IXGVAAG M[%)$6%7.[E!#]?'T@7.>^+%_A5-')G+76H;-L\MFO5Z@&CU5T5D.RGK7#&H! M5=5:BJI.CJHV4_2K:"I!Y\M)Y['YDXVJ_V&.G41S[: DDL/(*8)IGIBUF8;'&1J=O*HP"N)U*LK: V6]J^%QG$,[LX975%4Z MJDJAX1-H*I.&[^6FX7.DNU/HA:7.D[3FT_8%>T<:%\S]7(Y=U.0 )M6MY3D\ M.K>K*RS@CF):Q;2[M#K?[?WOUO.<[*N853&K8M;<@#FZ>IX#_ [,G!L.<(BW M=N!AK$?7K]?!/=ZF%R!PN;^8[G!JNPN'N?%B?P1K2%'LOR/JC!4*4F7_G>TQ MK2'<--R.1OO1OC$#=X-M#JEG#.2V\ M[T!L980-"-(.L6-&>T 6HO:0:'UI>E)X'$[8:#%E]^. */AZ^M9(6HV_F'LK M>#6]>46?2+=YYG?&L%'?$S_#MY>L>X2W>.!!\T:-.7 *MM!HIL4#"B@:'?9L M.-3?A(TB5_8,EOA&M-GYY&ICTS*L(?8*&>%%3Z6+]B9PP]A2,I-N?(PW_A+> MN!/<^ #/G1YB6B,!'(7OG;(7-M5>J;B!?C QF6,XP\D;?'D\92!'Q0KQL7SE M'AM.+/.O!3QBX9G4NZ1Y-LAR!'Z ]'(X(P*J +%_:X8J?$2C6N#>#:=MR^H#%G]OXN@. M^/RK[;P:S@@K)>#'5I7]'$X,ZYD1BR/SN14"/T$6#L!-?#;,89EM/*"UZTR8 M98L\76V<)T0%!H;+^,C"#_6/T=B%Z@^0Q78[1[&-&(D%JHU5-=DYT4@G1QKI MGEV6:,[*#ISB8LKV#WY<^NWCB4GX,M9;?LA3Q$O)G@UYN)<$F_E1%>66F4C6 MR/C41-*K@3'0+ :5J!+:W*LDCC=PLXNC*:)X2"4=NOE9@#TJPHM+AGW7^>P[ M=GJ0.CS%IB?%IKTU%*QHG14XC*J*#$N].9YIY58]<-_9%HC9GD7U7J7BNV62A[#HC$L$$LH M&]-WD]%//@W9C8S59L(/QK;M65A]2*NV8,E[6]RGR*%WS_7FFN/4>1$;C]C* M96=OO)S+I;(STQI.%XBBC>B"B(2M8:D9I.U64O;/I& M402L,8,5$??B/ 9M8$QQ](KF3A@\[SQ^L)I\Y/X);P&H?.B2P;Z7$HJ\(I<, M:B.0=HAUCG#I&OZ ER?5$>NQ$2\D1 3(Y3I" AE/44BX#$[N.;#],7-<;<"\ M5\8L7E>X"1SY<978WMF6\UZ5;9FH,KGN5,+GQU^-N!V03#66?!J\ E6(#0:R RG?6OXV4:?+ D&TFK;-<5BU2C6L M _@9<)4)'UVF\7"40/A]8X0W0_#X^&V/7LNW)E,^+IF/$/@^A84@8#_3UJCL M\3CG&^7T!":>[9#XO !+BSD\"OH/X\ KT"8.FJ%_VZ!]H=83A?SU?_QB7.[? M\*%1$JA2<0M #E)-]_G&AI!X8D>'5\8#UT$I\O^*%KL+65$+OV(,0%\NO-5? MB54_[E6&M.I+)R+]-T7'BEX/.E8F3FA+/K/JP&'&CRIAO5P8TU?CS45[79:R M(%#EPUX^)\5_*?FO ]8A5>3;8PW'@/ !CR$C;JS5+_\Q<'ZY3**/5*THV+@9 M.J/QII)>(^X=]!IIFTIB$SCVW+34%$U+N-LL@T,.:4[1X*8J3F[2/MN.0PTR M: M-2 _^#6X5+("ZJB\"SY =@2 M(13@A#,FV]\BZ8_N8Q?N?0Z\9XH*:^BRQ!4PPX];@B]3%S3E9 &HJN*XW0)4 MFH3!K-PA]/9&[\H<0A[.)K9;S$,9]>52ZS3VI%B?%%GH!%>E:!OLG&,V42Q. M1TG .[H/XS-XJSW G.ZI'X+M@LJ$B &') [PG=$3K8 MB!>\4#1:"38X9!=]1'-*CC,;JT =0F;TZ+/OH88Y/!"[,T(9YLLT0*4PQ+_/ M[3"6Z1WT\1E[&ZQI3*2Y!]+2'H]!Z4+?(:R=1#%;1.Y>X+GD/PO /69;2T_ M_6@CYXFTE7, ,8_ RLFKC2GO^/CI0Y$6^=&/0!5$8_[K:B%?/P4EPBIA05WI866GHI=U,0=(C4F(JHM$GO%%<$S4 M<0A0G=JL))@&0_ U(0#?Q:%U\+?Y(AQ/4?;14V7'<\0Q:%O. 3T[]QM@?\L6 M^OZ93?@L@#Q.\53R6:/;(;^&? BUA3^WW2P>?DS B XLX--9_KE!;("=;>%*WVF MCOYMW BV_>O"#FV +6QU P(1;I\K3RECHZ(/O6DKD0?X6P K/8$5G!P7:47E M]$R2IN]*OAN#W8O'%_))CUN6*3.%BPK1^3P,?M"C!>Y:3MU=4V"L31[T)0S& M\.'H ZAP'V%Y&/SX/$$YA6(*.51>,^DI2F?8*^ ^E/W2CH4I9PAIU3_L[PDW M0C7%DO0[4$KQT828OL*''V,DAIVLM*>H8%MTS0*=_*_(C\HNMAS3+[U8K3/4 MNV:_8+$9-K*-23#-:TU79$=#V,'\?>$3P&==Q8WS?QAJ!LM9'(A;*$:J+J[3 M#')N9'"E\'2PQ[S\2A(Q]'FR#2WUSM <%&!EN87LL0\/68B!,B*?<2J7MU8' M>PR00U:#I9U6WH@ SH-JUQ;NTR(YP-#36 ]0;84FQX*ABASEPS#L'75*MYA M&LD\\IATLTER$N886PQ\F?ITZG7"901WIEMU210%XZ(GF_T\*SV!MZV6!0]P MP;J5Q\*N=&R/J:0I,UT0MIAZG^C6JV5R#I!2SY8>4SU5R84#X%H^'( J_)A_ M-\6P8@67. GVK1H_W>=;MFTTVRI(OF$+X6$IT?9H[ZO:U/:HMC'';6EP7,I8%E=1_KI+J/JJ(M5J3)K>L^DH/='NTE=<87U_V) M?CZBG\\FON9UI75TW34U8K_*I&K;S!#1\4=0V553V9[2L%JI3&\9E9UY(&O# M]8?!:?4']!)V=2L_,ZI ?^#>V&T*A&C[D3NO$U,VR^0I<'R)]C%MQR-XXHR( M9#8/D805N88-IPWIJ9CFU34/,R,?YJ'K88A.N;$&,N7H5STC_6(FCEP4 1&3 M']N/2'O"+;4BTJ!YB"3,@35LT$\J"#1L0'1 +'5=$&C"(-A!OWNBCW72+]:+ MU6+K"XN@@8BT)PVG5D2JRS7;7HO@?%A0E$.Z-8AXV[K0GL2H6DF ^DW5 M>8 M4*K;CTA[VGON1J0\KAB=85]I$J;<3/?&.OCF>K^M"K&W5M+"&>U+K=<9FG7P MU/(GU@KE]48Q\)P6DHEIFC7PZG-A8&U:;X,9^6\DB@!#TGY'-,D4.RSA$?/I MG;PPB/9"R@TC$UK-09Q\0L*0.!]HVRCR%@'YB13J,Q@/R->.",6W]2BRE]4> MC"(8<\A7]%R!QGNPG[BPN2=OVGEFYKE1U7$;0RBNWN-7HM"&-_PHK0X-L*F- M9M35LKB%.O?UHD^)LJ<5^N0P1%R@.9=I,HF,&0'X4A6F+W-K/$,O\5S:U%<^LM/3!^9YVB7.QTD1596]I< MZ'JNO_66@2^T%W:SV\"D>R_HP<'G+&#W#1^6*4V 6\!_4$)+2V*'C&EA:A&A ME$3'0>#("=JJ([H_KIMVL73IM*1M1U_IZFKQ3T=UR-C]JO./23Z?)KI6!GB4 ME__*;(]KLQY*. !2-I5M3/8EZ1[VT?\$[_WV0KQG\CM\9!J5-C)HZ_4:ZM/: M&&ZZ#''WJR127:]+O4ZJ^%\0TM]>@G5BH)U+[_Y+PJ"(#GHX]I#.P[A&AWPS M*6$@J>@7G/R&^?P@686D]R*JI/%-P_T.I M017<_RS4X#X7,G],,C/S@PYNB?EO.G"Y#__L>6;?5IXDD;)U#L)X0%"GM%%2 M4M!"_GYMH^C;*2FVD(YNGIMTL%"I4M=-$>T7T?[&5'$92DU57,V,^9<)X1XZ MQ]?H'!4&P]QN0C[/"8;V_*??< 9BE ]Z&6J^M[NAMFW4:X^[MM@N,X]'7]8/DZHYK:=;U9^]C#A8-#MZX,CFOOW M>_VZHH2]DG,"=C7WUVI;E%9+<_\KZ5\O6O:WT8ESR%YWI><\4/YWP-&7;X6\ MNRBE:@%CO2N[9G?V2G/B(H^J@7?!Y&ZQDG_5+.%K,:F*-W?M1M&Z8OT5O_)Y M\D=$*&$QMX MW?Z:A7<;Q>"W'G+C)U\+Y=*Y H9H '*-:+1'!-2)1G2J@-&O'(-J8OB6?UNW MFE<\SMOB%4B $S2UNC*%3X2,N!M]716T?2?+&.AN@PD8T0R_2G,&JS,T9%6M M*X^I,67=%>PH07,W07-;Q.\9:*Z/-*=55^I:U_BP33[IW]) 7$V.Z8)P>H.< MTX>L[IH=U+SOTE%G?4C_JTL\?]$\K\OVXMN,-WAY5O%[W%I MS\;I?!/)J<9U3OM"JG7/&0ZSK2I@$PTL\LP M;[L-@3!^:C-^=)'X5;/Q4X&X:?*7K@X:Y-D0R5\7M(\JH!)+ %.NLG]'2Q+ M=FCB!T;X1>N!$X.F]5SEZ#RR3+9#:=Y"4\B4ZF+J!"?:]!PS0=&"HD^4I5:% MHFF"FFK453]W>8HNZ"JRM7V"?N8V$0RF__K786-'VC9DY$S?+)XF\M''86W$ MD5Q?6EL)?&-\Y_ZXF[H.0.@><7ZP :#\+:;2&0;8Q3_3_W\CJY_^@5_#+A] MR123L:N)-&)-3Z0(NYYD1I:T\WRUUIVOJ>X_W\WI-P6WZ/MO,1(L208$%BG^ M!7_< -KH[4.;WOX#-_-L8>N15SKD?=V-&M#FY\AI(*;2'91LSK-K&DB_OCX_ MY9[8.:)$]/D1?7[:W>?G0 /G3_H/XMS9L!;[B4@AF=FNGP:E*8]\14-$]IZ8*3U-:$L^B/V,U;7K'U4 M5^Z=18BTMK+O36Q>/\AUT6Q Y4N+STT_P[GU49#L/+?&=':^;.R]"BLY!"+M M0,D<*\GZ!VM!R $@I%X+(ZDY[:_%IY9C)'6?FH7U$KUZV4B+"CUSVFDR6U@" M=DV:( 6OH_ZS3:KES:2B^(O9B(2[X\8?/WTHIUQDR./.=Y_/5D,O'6,5<_!^9JB+E*74,66HRYM^NK*&5>W$P._)'B M9(=&>RA)ZIVAT;4JE[G7E??>?&$B:C>J"Y,:\-9 O#7K:OW48KS=,NAGS2(M M&//#5\I?;&GPY7RIPRH6^==U"<(CF4KZB#V* F\1;W^D**1ZOMR@GKXA:3+_ MG89I!.R)W(U"8G^_HU,![VWOQ5Y&2-W9Z+'KWV7!MKGCK?N:3&K>UZZV6S_; M%UZ!- V1&_QE_RPIJS.D0XJD8"*]14;B8R:0/3P\?L]Q:?CS*/QI6'32&Y.O MTBE3=\5SIK1]SJ7\6"M@96^#*-XR;LGJ51FW5)"!SP7-B M\4?R8T[\B,CP%\P$03=!- W"F"=OT'LPPY*-9(HP5Q$ON3Z\C$BO7J;N>,JF M,[FS&3!\7.EK6"MDQ?"Z+&T4" OO/*V93.SO[3AG=@,M(U!6>% MNKY?S"<'O\M!W,>NU8/&U,H(6^YLTOT@[,!&U+4%K@5V- @[ZN =V)BDNLK7 M1*.^)4W*UV2Y:$\NFAF?4;O8R1GZZ#*XGH;$HL6XH,JF4.4>M6XG60Z +-6Z MC&]!EH(L!5D>J$_O(LN! F19/9[:&+(4[?MOOGU_1#QXZ$F6GHA/0K!7L#+3 M=F:N[T9Q2/U_25DGJ]JPRSC@G66. M+2(65HG2=VV!W@&R5[!FV8D)](E5! M4+&8@8A=A%0BIUGMF5RUX\HGRM2R-&X>0?L65W=(1ATT$J/3$OB5YAA)_^?QM@I$;Q&B MERKNWH7I&C:XKYR")#!=8'H3*K%W8;J.K0R:E$I_NS6S.Q6V25WMHZ\^C:Q\ M:CBGC\]^,O)Z640I1F=HBKS#*T28(VI.#L.87AUU!0)CFH]1CL455/!":!ZDS158=N< M1Q+7C$ZUVW#;Y[MF2I*7F% MD/C=CAU;D5FP(K-@12V:\/= MJX(>%D_P;89ONB)+F. N2Y,%@(-(6"(V6\RD.?B/=,?H?W3PO"9*:"4WMZ8EZ<(#%!8GL-NY*DA1%HHZYY)QR6:PXQTXHR(7;GX\1-A' M!8QV(#*"3LUHIR$IF)U@JE@IJ8EA;;>'/0>QVFU8@\%GO7+ Y^18([3:/+/% M8Q-:[4F9[8=@$191C8'P;U*MKE!KF\-KMR$-3E.IK<%RZUEMJ_1:3*P1>NUI M6:W[7*B@T"DS0JV]/>0YB-5N01JK80-EA5)[X/R:5::.4&U/R&\?$,(I_; > MQO]?Q_T1W_N+V9T3Q'?\,T7$A0%(61^(ZM_;0[!]/+D:8F'X339[S2\6;HN* MO*W?_=E[.-"Y9*V9*UII?'AM20G7R#\.%5!E68>F=(:ZW*NM[JP-:3$"&T\M MS4IC(=;0RMJ@+G>ZR"!IB%F";(MW(I=",@])1'R:^IP,0Q'62MW"X \<)C-& MB!/G_8\QW/I X5]$=AI8^ZHP1VX/@PH9>!G,T3O#OB7LC?:YY+\P'BP]V]Z" M% Z .%+8BF&.)P;-M?.DK:TR2NJ2&&*63:7F;.06#&2M7@D@:%C05$S(&MO_JSV7-@-]L.KBKYI_8SD?P@ED:$X"Q-9S$FCC1: MTC&C8YRKR7L 1(CS^"B;'XJZW__4;95N-KQ*?$+?@E_(5S(F[C-QBBC>!$,T M[_S9&'&ZV;ZBZ-^\MP,=+$HY6_9"VI;B3NUL_]6DO^YL %$%=8L_VS/4.RW7 MFP*OZA<:G)L'YT4)8 ?< $)@K^*4NZ@>E,9)O)M>%MMW5@VU62GXIR#^7Q*_ M#6: XF/$ZY)BSJ)1.S-O1:=F64+E^<.@?,#U >$ $&(@M8Q)0O MC),%%I#3^OGFKV2(@!^0A1T&\N&A5:.-OZZ3#J<9)7W$'H%\7<3;'SE1V]V(O(Y3J66X#K"8+[$TX;87&9%(S-!C[ @P.0HH/ M]Z!;D9#%^GZV+[P":1HB$?]E_V' 4=!N0$A6;Y'^*4'9P\.G2G,,'/X\"G\: M%N%'J?Y%CW$P_CX-/-A)]/X_"]"0@9.0=VXT]@(';(.EM@ 2HHQ?P#^74XL[E;T5F!"T1?X%)UQ':4%X ]-49!E2LVV]RY MXB\D?)S"1G>N_..G#YM+SZQXM8OD7>\X[%8K558KU140#-U>OFY! NU BO!I M&;MC@:B=4_#'04F([VEX6!?(=1IH5?MYT_IXD"LG@KG6&1K=0;Z<-84YQ_)> M5UJ]F%\RTK''(*? #@)"6Y')7LMG^U:M$^T5B\GR*1A9[ I)M/!XZ!3VQ!7# M\D:5;/YN9A&/EK2AXR^!'5(F]\X-R3@.PDB67J;N>(HN M(;B$3))YZOYN@Z47+I%C6EV)]9'$-W FR5I(XH60S&S71^[#DSGL9]OUJ%+- MH(@WK2_FQ:[)&%]3FW/0_9JL+ 5S>L^Q *>6N5K D;M2255_/"7.PB.?)]_ M[ /E?DEW\%-&=M>*D73Q9-\W%#,@2 !#1T^#4 M0#5QZTT!3>"6GD$]O\\[TK)4O\5+1E=UN!E2[!]K2R?0GM;M]7OU--W4NWU% M;UHGT,8NRMKYJC.T%&U*%TJJHT34 9'R-X?^^Q5\+B'SUUL3ZJX3+ ^P ON) M4#A\ >9%F& #O8Q>HE"[,9#0D@$&AK?!1H;EV3*;@.>?NX..6:72^ ;RO*F= M$NWV]>A[E"[GP0?U*@8ETGE'.XB#]>0&SB-_-=>D]%2?&>"TR\K#%5I47'!Z M1&MY(LU5YLD$H72&@Y[2;7O)A* M M05OU3I@Z3&+]$].?"TQ_ XS:?O6IN^) M4<59NC4[O8D)*1ACIPD(D32S,DSPG.X922'6?3.X@]GF9G?G:E+^F=.#34=@A;;NS.Z&?P M3Y[HZ#LTG3^27NPPM/U83M8=S(D/CX;?28PYA7!UA"D.4F85\'GX5[2 Q_"M ML M?" .\N2(6&YEWD6NIC#7Y])1/-ED=TPEIAD MS+)=,+C1;^.ML&"Z$^1\3\0'CJ_Q-P.L,S8)L1RJ0D_'? MF2Q#&U?,'P\6,:@D/E7S#JOOUJD.>,;R[H-+UON:9JYTW'-]>+W&5340.$?X M*DZ&F('_>8[WL@JNCSZR8LJK/Z,,#QPV^@B#' M150*11]]YCTH#26],S2+R9QIDU24))('Y!#Y0<8+JHH'DPG0\.=.W "]1P.1]ACVCG'>P 2ZU'45IH 5),4 M M8CH ^JXQ,D'%[G8CZR!5S4W)#>80^ #[;+*KAHR/(V M:I@R9NE&I.[H;-B;KVZZF.G\*?"9Q5C&PY"F O5Z=%:84E=,7I1WB/*.!E+M MKD0I?6>BU!DH-Y%17$11Z83""673>B9-QN=E@ADZL+I;?5Z-(]S:2D@2DALT M3[+^RGR,HJ#DN!K@1OF7,S*2MFE1^LV?#"YJ#4Y30'LNS#Q*$O0[PX&N=WM- M*H6IS79J,+/_)P_4@.FTRMZYF6J'5VUA_>R4CF;]=.*M7E NE'.DB"QWP?6/ M0\ICN+ZI=(:F.>CVFE2$<0LJ_H<@G!#WEI3\UK#ZU=&DW#['T$T5M:4*W%SH M\(*;%^/= FCA*%:N85&4V54JS\8^GP)_W$BI5L[.;%1TIH[>MN;'8I5C"ENKL+=FGC4Q4>TD24&QVCBP/7<)R:VD"1YD.R*95@4F6^MZN M]DU3@JL[LLW>5D>V7,?(F'8!P^P,^WV]:Q0! UW.QP&DQ=AAXVBQ]6/@A&0=//LYNH".4DAU*.(=1"EFE/98SP-OOUFIU$_++PAY9 5FQ8>Q$@\4[A'MP9W]'?L$L'F17U=[+6C$86+02"N8 M>9248^;8%BL!22I 6($(*W*AA=<4@B^NYV&19P;,\-/NA&C5.!L<&/*!MLGR]EM&FH$I*RI8"6HJR9=(,I3=.>\EDT26)TQ!;*ZO< M#^MC<63EP";> X;GSS4]]>C!\X(QO7M;U0'M-O++$KLI;"D9L$HV%&F )K:C M9(!V<^!%E&N" 6=;^]A?A[/%E8RP?P"C\\G$C:,C:PJV0J45909B4HV85'/A MU/Z=[M"KW?+V_/RKW;)Q&V49CWN$T"F3N:_2G7F5:>QEIQ04ZG<%%J&%W=BU MNCK"BC(003\MH9]]S<8/)B"],^R;K2G'$ 0D".@\'8,/)B #"$AM32'BF4?B M[&H%<@(,^(U$T9H?UP>5E&3]'C4VJS%IN[-]BRKH*(.G>Z=W"QP=J$:SUB72 MNGOFZM,U:U0>#_+$?[-__,(PXD,8S+*_O&=V2Q&I8]6QF@\_B'JJUF/4'G7J M="AE=H9JOTEC701*G4?!.!U*8=VGU224NH6RNGUN,-H'^WQY3+=BJ]0#FM;S MFMVLAD=.B5/,9#@K^43BSQ-@.$4LI=\96M45GQ,<7=.]"()T!>E6TCRKT^X MVPQ?/K-6T*Z@W6NCW5/+W3Z62QN5"^P:0[L'),87CS$[=(J5?MP4JX_430AG MD(ZSRN>.]=7\B*J^VK8157T^HNH;CM[9F@)V^KRWDDF)[(2D@E4?F7W(7O@+ MF00A28\?_H#=CA]\S+>%[V_+(^QK54[]TFF%')@CNOF,CQS'2T74>@U=M&/Y M (%5!N+Q*8,B/[!!J7B-7)3(#Q3Y@;>UY1O)#TQDJL@#%&D8I3V73%/Y+8@B M%O^@VC=L__.SW_%J5C6'%[6IUC6;U%/SZO('J2- M8$1VH$A3:(>F]/Y''-H 0=>WP^7'F,RP_Q]^- P\6.O31W2R@^U1FOU@SR(- M3(_*NE1C4AY$NI+@ TWA _4KLZ=B! ,%&($BUUY7*1B!8 2"$9S WC@9(\#! M%[)E7+Y9>*W.ROTYD%N:!?,SMS1 BGQA\2KWZ:_K"6E\NTKZB#V"G2WB[8_D MV]V(O(X1R-C?-]>^R8-O< M\=9]328U[XMA"2![P,CH'O"3A*S>^V?[PBN0IB%RA[_L3[.UP%ZER7S!1$+F M@,T9?_[)'I;N<#FD(\R+3GHC"3A-P;TK3L+5.I7:4 8^;1TB1Z]F@M,I&+DKD>HI< MS]O:\HWD>GX@P.EM[_Z ZZ6+; '+8X;+7I;B[N%J9=O%V$(3*!:U.I:/"'% MFVN]+V.W*X-C &=,.4U1.$%05P10>SQ\M=-$08=-3YH M4L: H A!$27:4LQVDT ".TX# M6_R@1:E2A-V5E7*4*IGGK22&';3PFX:*,J[**V+8D*E MW-/KJAIH3)94324%-XJ6>UP$)\=+2U&HUZ!75Y=B@9=7@9>7YI>6HE+;?= : MO+S:4.)C;,=$!!);L+@;#B268>G7R[4/\JY2>G[PG=^"<:&/-<^*-;#W+#%L MY0H1YK (57F,T0%CC(' F.O#F%/Q& ,P1F]2XP81J+EU_^EA[M,U5#_8B6HI M=()9@YRHPNU^J6C-L1A$!Y:)F,UU(4^.ZYP(>:S.L& 4R460YW;"-Q$>E@C> MU#VB_@ 2*'9)YLD"0YOM\3D*7W@#C.0ZT6]0IQ4DT.\JT.]\W \P?:CW6A.A MOMJ("V\9)V(N+5B'Q!/K\LT%HAW%8AW%HXW0"6@KJY% M(L9233E8=6'--6$5(V!$Q_>+C8"I'"?0,)(KTP:?5]*LO08[5Y"P(.'S36^I M3L,J3H #A4'0L*!A04-H:&#QB:3"1GC\)05 M[+_:,?E*X 5CUW.I154\_\'2]-PL"KB&'VO95(AP;;?2B,0OA/A2/"4T=WP1 M!^$2[1,)#$PBV;Y#?R()Y-AE-&6PG[WD1D>,D5#;,S?"['>UP;6/:-@[%Z- MI";G F1(Q%W9NPX<:5%6\&]\?]"ZL0B'#+]H_.FUUQO%^^DD\W_B#+.LG=:BK,F5NUW:YZ!>2)?Q_;45^D-3[ZHM&^J=W"VS9D1T1-C;T ME?IZW<(693*5%9'BVD92%%?7L(.Y(IJ4M1QU#I#V^C&R?B\F985\OS/4NW4U M 3@=*EU>;C7UKNOU$[ 4I(QXC"I5"5^ZUO; YR^/44V]ZR;*CVW?=FSI3HH6 M(Y]R\\13)BJ2"T.;O:.4KMX M=)3:=3!.9=0O'2<2=)N/5)=G_DV]ZQ8J=U="*8BG)!3UN\62R#RPIJX^D:1C MAXR&%-F)VLQC$&F;-#(WI-$65#J96-(Z0Z6;;[S2(,RZ/.=OZEVW8"9]1D&4 ME+M*_UZ$;N2X%$>%G50LG:QSV4DZ#JM7\^UVFZ;2"COI*#O)NHR=A//>JX>B MA9W4'JG4%CR_4*AC M&A=]XF$&X"SJ2Z+W.D,C7Y'<(,56F$Q'F4SU&4Q%^/2%A)C 7"B:3+25\HV$ M&X12E^?^3;WKS,E(YZ,?P%R01\1QCPV:'J(,-^?YRV-24^^Z!?_T5Q(1.QQ/ M:=Z=0YZ)%\QGQS9QOBYI65MZ&EQXR_A) NTB[T_D4AR?>G9]A:L&8:-;2QL?WS< ,4V M:J2GERX,T!_]I*H'D,=3.T*Q<FXGR>8\/K@ NTL^$;A8V'[ Z'6&O;K:P@A3 MZ,I,H:T(E!4V6W)FFH9"E^?L3;WK:NT=%N"Q'>R*BSD$MV/?G%ZV4-@^I* M MDBU69R@:V[0<84XE6O+XD^W".'%_$.?NOR0,"D5.OP-HU-=4[4WCT>OR[+VI M=]U"-AN=UG2^9ODWT2.W!KBTB@-?;!B3,6C*,*8V6I:GIN+&XVU]FL/.$849 MO:"G@,)I="O7JS8 7T4/W+;N,)3^U_K_#AR5@HH2Q] [5 ;N MD6AZA9-DV"77=T!'O[]3^W3(2@V[W!SP4+S)3&_:,WUS'2[]KF;@CEDG8#;D MP/6EMP B$*6^:\O2)_(B_6\0?F=_^SL)([*4:?'"YY \ 3^V0B%^*IVXDC>'.IR!<=C?Z]&Z, M+\)_\V%"-FM'GT$ OD5+PZ//]0E>3;/YZ_JL(8XO2OJ(/0(NMXBW/Y(;$W+6 M640]:P-&F?].PV0-<_N)W(W@!+[?V1-8XKWMO=C+"*DY2S- ,%FP;>YXZ[XF MDYKWQ8@0Q&; A-\]R"H2LO;-/]L77H$T#5&R_\6U2=^:#$8#4U$&ACEQ1FJ? MJ(9N$L%I6PT^6 BH4AG'CE[>#C7XK@T_'D4_C0L.ND-$N"*@=E7 M44O8F+2%5_7.MF?8'*X]3)1?007@"@=Q]>CO\!?CN(E@=8&3MM[O9MV5C;\M5FO8LA M8&((V.F&45]BQ%>/CK#6K+IJ!,1LKYN8[:5<9KA73Q/#O8YV;)YBBKL07=\OP(AD^ESQXSM,#&YMKI>)W"J>7SI.+WN"+YDXI [)=_S4>!0JW#H9/K=47Q) M*VXS?#FAUI9WDL;3>D"N=J+7)7TP?J950^G(.>=-@*A6H-0)U,.JW,K$S7% M*C.VA3/PP*8[-^/_JZ@%ENLD>D#/'=/J#/M5NH@*V[J9_'-3VZO01G0K&F5Y M9;_J? 6!2-?BZ#N$[0PZPUZ3?# "99KDUSN$XUA*T_KFW\(,K'(-JO@&CV^, MNI6/O+22=0B)UR")=\H& MC99!&S16'A;0#+2]<#U8TG,P[0:WM?M;&SI7O0UF\+WEWZ),-ZI5HRK7QSY4 MIDS;4LF9OE3^V%LX&Q-DL+_8_Y3CVL9NMGU0;OK4#LDO=D0QT4LO=<9%O2;D,ONI'_YG6"83R1;=YP:] 9FGG=+ LE6XI#8)@3$DKS MT!WCEJ+5.^FNQR!S;&P!&B[(W6).N1KEAP28[#.)-KJ!KC4#S?=<7M_8XWA* MG(5'/D_>VM'T@Q>\/"[F<_9QVWOG1F,OB!;P)=JO\1N\Z11M3)$L&-K0RG*;!_.DT$'(3X&^ "Z@MJ 31%=BA"9.A>\)203 M4$TJ=$5L2PO$OMX=#,Q:VNBI>K>O[.ZCU^A^S_O[^Q5:)@>V 6Q0"SNS%;W! MKS:9YH_N8U>:L*X:HH^>:$9T_"B0+R##>'N6!^QY_95*+5!L""B,3ED'5!\+ M>63=JGG4PKG]2RWD7&VI%:&<*XJ3+M,>5FS?U^VVOXXC;>%I9B MRMJAD6]DRVM=#0J915*RTDQ+;8:+QH^3CEYI#\TU:?8@O9Z5O;MYWC%)NKYZ=JKXR]R2CC M0$YJ=(:&WJ1^35=#@RTT,'XG/]QQ((R+0IU&.QD-8OEM0?F8,"MN40X*LV*[ M&-P3BJ] @M@^536%&+Q=@T(,C:\_%B2&QA\<*2(1,JU/I'16$[^63/\4HX(U1P'TQ"OC,*VC)*&"]X=F9 P) XPSX4,KV)+I^J22ZLZ?(83HKL!R?)51CBJ;#]TGS$&VZ4^F5EV[T MM62'I,R@8.3I=G994".,>/):LO.E33XF[!M?7^/PLW7JY5;%1SK5R+U5R\N=:;OGL\ MYCD%#OZ27..5NMER&5#O>*%,4?5'?X ]+)N?$E!K@;R@AA91@WY&:A@HQ=6 M5S"&I\'R;:7>L(JEGV8$:[UIK_8)(9&(J]8A))(+S'-:A/MJ9Z@/*H\S$VWQ MFH-Q8&MMAN,3(QXL=.B+Z79,V_98" M]RW"EH,VXK OH@6],S2L)ND,9VY/<[VH=\B5,_3.'*_,<38^RO$N>KNT@-Q+H]6V&Y+K=QDX7S:;$.RXZXQ8DVS@HM2<*IH MV!63@EM)SF5%R*]A$)47" /:D[ZZ0"AY4*W0T6\1Z\H*D6.PKJ_@C';9L.JJ MX#HMUEUM[YM_VAY/.K4Q#]+VQ^1FM/ER _'V\.)"[]\*N@\)<(LH006;MH#[ MBD&BK<:7/5RT KYHG6&OE^]L*V:#UJ_#8M_4<^FQUZU4E%5ERQ=U]14Z:J*& M#)[+=OH[ORY[W9A75IT]!O,,]*D-M).;4$*?+9,LG_%75^KG>)J,^4-4J-H7 M=PLAWB]A,(<5+&F,@OQGX9\ N33C M[+'FO%4FW8L < /1ZG"A>QA:Y3''Q/$>5:P@$00NV>8J'$^!H[H1SCAZAE,) MPF.39J[?^C^*K6Y6+MAS%XQ06*/SD0-\^3:(BFH7^HK5&>J5R$$XD1J(1D>Q MT2IHU ) MJF/3&%Y!&G+5:K\R,;2J/^_Q92I]M8?)'+U*1%+^M%JA>-XJ]AW( M@6O!/A.Q3^G5H)XV+Y=CC^S0K>:Q\D^;>7@[&/F!R35'].H^F+Y:USWL%*!I M/\,YRBHHXB86SHNJ0=VK\WPN9D\(^A3T>4&3K(@^^YVAJM>0@W1Y^CQ@XL*N MSNUO,MW.-UQ8_UY$L3M9GKVW^WKZ_7@,8(\CR8YIFW?B.]CQ'?M?TVP_[ J- MC02]A9-YDG46S+:"AV?^IYPH*)M%G,$XFE"<1SH,->KY4"/=1\G%&74O3E,Z MP]X@3Q%R EP$JA2@=T/R O_I+B;AC /W#=U!$?"S_2/*G\"><8Z[U/\C4KHU ME;9),//CK8XY(+/BVO/+TSI#2\OG^^P^H,P!= ^?7W%I+O#17R=PF9(^]G6U M_:4TM1WI.5_%> R&G:IB"YA'887?$9ATLJHRX"&%566R- _AX2A>7,^3_""&*_ 2EHLD.0N";UIK8@@8.G-C MNMBH*R'[SW]H_8F(#O( OH/O(C_F+OQK1 "!,>Z$-#!Q<:^ .+K2(IS_E@'C M$_%)"(B]!!!28@::!K2(7% EHF1_2V*'$N'A-L1].,2[/[J/77HKZAGTZ*+% M")YS;4S=E%XQ_@#GYDMOIZYOOP: >-V 0,)/6],](SP.3IQ"*E/1PY#3WF, M^4KPH6^V"T@E4V1.;E.MW&VP "ALH1X@3O!0CW\R+/M>G0^2P&"OJ;?BG!R>D8JP=-S>TF? M ?FUF.%+;6FZG.-BJ9(%2YO;,9PI)4] ,UPA!6WVE-(3660#H6MG,@:US0:X M[#\;67J9NN,I? TV3DK+F]U<8BU2FX1H/T]XS/8QLXS24K/7&>JR5C ;64; MC8BA2PU3K!TIP_AC4 8;7?'!2RCMI]8Q/X6[/4.O&6YZP MUP,@7PHS2F$C#C5Z8AO:>%1FS%(QO'IB\-)AKQ*#E\3@)3%XJ29GU*\[>1VZ M(%)F":P1-; 3%OI>IRNSM9[*.JVV+2I(D7YE@25Y\I9)[0L6" *Z:@+2]LRP M+T% _7^[J(RH 86O,9UT9L[A^,+*4>^G9K42S'A+PCKPPA&!9N\+I.@ M(5J_0*>Z67 )?,*ZK'P<4$S8.#T'AM,^+0=NH]92+B7L*))Y1RJ2#,;WFU'( M*/3?NC#I..Y;&96P,"QO4(FBV+,RWHC$L4>S#FY'T[T8GWU,@?VG&T_A?OCA M81%/@W!;PJ[>ZPRK$(G0=AN(4G4RW&-PR@2]MQDX=7V3B]I2,KP_Y,LSSDL% M>]_0.)=N87O4FORHM1W0Q6P:09J"-)N2PZ'W MZ\CA: 9I5BTWNW02[/8J,EID$A+I!?]3<_9U(:9\F]KQG\'"1)(ET#>$L(B-'''\,N[=]5E%S!IZX(UI5O!? MUQ.].38KZ2/V"*AL$6]_))?5>5:D[PTV8)+Y[S1,\=5^32K+WP"M)B'?!2NP+KT":ADAI M?W%MTK*",_P5J&RTW0))XBT1*75#V\/"\ M>8Y+PY]'X4_#HI/>( %.FV9?O3/VE3!0NT@R)8LKIYL2W/5I2FBE/ MRQ2=SNPXQJH<+!,;>W84N1,7ZTW@"K#!V1Q,6E;:D'F&L,[976GO%U\(4-H311_QWK),K''4QR@/N<,:TZ]PTS)Z),H"-"3Q M(F0QK*1X2I:>;=CR(N(E/0@J+\!RJW\#*"/'I;*!%XC!<&FU0)WW#QD&GH>%KH&S&,(Q5+&*]WEK%(.!C@KT;>/C17U7Y8>5CM%FL3)D& 8IW:+E\%%$GI30) M@QG39%(G95?Z$@"[0FG@!7@O+BBT 8&1@ 8TEAQH<2 RL&E6^D#IY$?S O*> MEX2IAS/$#K8DOC7^"O8 +;Z$G;H^H+7KH*K(B?<_"SO$DE5.VP>IBR@P]TMR M%1W*QY0F)@697TCX"%LLJ#PTU"J5AR&)?O W_E?<> /$"H*9+KU6@H\-^'YBQVYXP??>>>BDKZMNM/0=L&X 0R0 M552R$FA:%SD-7B+&0F:L1\HB8ET@4,M9T!D36"7MI@<0(3@H_/$Q]D6D0Q2T M0%G^8C9"TIBP&RD1C1!X]!'*@E _=6EINH/01$5FS(XR>601@TAE5:2O^#58 M$@"%XH3U)GI=HB:T+46@/:W;Z_?JJ;?4NWU%;UH1:&,798G*5%&9>E-;-BY3 MC+O::X9?\Y??4/T;]DH>1J)Z2 MJ-D9&H8N#PI&553**#KH'%M1HW3#B*E<$C,MCIG]FG/=!&9> 69>E&?V.696 M+W,^&V:>WZ]W/MSY^OC'[939U:M;?$R[([,0*J.0AYAU]Z6AS2")>A+GB[W$ MFQ]"&M&GF0=%]#$ ^K":U ) %-F=32OR;]2&VSK#[;Y2L^]-X+; [2,])+7AML%PV^K5U8SS\KC=\F)5 MZNM*QPFE";PNYN1[XP6K?AIA+NZSZVSD^\+E@Y-\DQ3>.!A_7\O@Y45.M$B MUBMU)8YP!ZP+E7LI8 5 JVQA5K&)'T4OD+2(DO?'V-5E$2[Y*F8DGL+G\NGY MFZ=W:'+^X+CD?+1@W)A:)0^^\Y;6!CP1?^R2Z)T;C;T UER03=[K,?IV_060 M;,ROW;4LCU]5>")_!@H\?3\#AT;5$94LA_J-/-F>]"4,P"Y$C"^SF6;-=]JH MD7+]Y\![9O4 ,SJNS+/=642+GI*]LE([' _YQ NG[-"E!$FKD[ 6>X0$2B)V MZO H$'N\E((7GX31U)W3\B>%2W]8+XHB$?)D-YIB M%9//ZB59H9_DT?/(K!$+P?';+U."G"3(E#C-@7MAY0@K4LIB)*L10I8$QS7% MUXW8O#!P4_T,%N(;X99QC"@F)<#Z^S @!BB6'$:HIXJ06O M\5R?" <\U(V#,-I8)^[+(<_$"^:,@NCJ.XT"&BIA9+.O2^8@> MZQB>(06*!RDN\BUVI0\9\#.,]8/5D2-6C B0X%0 ^3& 4]\5"8RH7M>6C@#GL2J M,M.2\"A88"DBU7^ '''L+M:ATIKBA8^X3>O/WS"4H^P-CN\G^'7"^0S\$-#Q MG#:%%; &XGD)8N"3_'Y\00)8SMYIJ9='?N#'_ >X%]8O9+68GJT;C)5_.9V M>-!$X(9(-L#I3[ WNGHVD-2FQ@W\D\#N@R4AM #=P1I1+/B7N,5E/]G Z]9' MU-J>AS.\GK@\E&C/!NDM[ Y>Z;L(K!=*F!,;5%96LCH'PH!#=6>+F?0".K2\ M^6- 39#9Q@]LJ"5HLNS()=I/8+]">UO-24Q%-":0N+/1(HQ(TI DRK$:?#QBVK"S($PS MV[@EZI%>?@JZDZ>-G157UGOI&DA[M<6CCJ02P*-!OE]+C@KH]L'1]$<:O9=0! M@F<^$9VU$,%&!6',WW:O&7?CYSM%T>&;TOONNRZ*EN[KKO0@13A^%W5LXJ-* M3"4WR"<0]S@N%^77:@;TAAJ]^J3C1C/04*F:]W<;2"9MA+='"Y17?Q(Y7[UL'B"#W/(8_>0#9W+EU8.;E2E*/ +-"\YIWI-UO1HUK.%M5A)\">#*?Q, M,HI:BE'-8'2?;-S^BL-=BJ.]_><=,"%%,=5!_XWT&-N^&WE@V&QA:<"9_%T\ M":VHK/9M4%+\0$9APGUZG%B0"R8HGSGWI.W#&N&$[GF.4E.=D$_@$ M&F6YY;[9,/1RG[*3C[%OH:-Z;:L94D4NH^J42GMK'HV-]Z[1_N9+5A!;O:D] M])X1+*:\:5+!_T=D:GL3!.2?=H3F<1RD3"'*8,Y.\VN;H<3"#%%J,#&=BKFJ M GILH!BA'*,,8\4@9*98P;>H1XFK_K$<1=9(EK_!MH!]G-J E_Z'?F2O5WU.LTB=RZ)*4OFG7:G M:'UK<&>^D?Z!2+&518%."Q^WPW5D7&-2H&>"ZH1(VPRP_]^ NG$:"O:!T1O< M]?: O3E@O( P1>2*%J.(_&P^176AIY!0IL+LN8AZ MZ9H 2,8&+@#("6LZE_74\S!#IH\?4Q]H,.'Y@"Z8#9&6OZ LHQ$6-Z/C:XIJ M,1OE#]]%A> 1!4TD_7WAN&/<_Q?;)Q[5-;![(> 5*"D AM]6@3AT?-!T"&JX M^>@=1+68]A?,QG7P&R[MQ4R5J&#N!BY@X6B!]ZT+X42U=L@$E"<;HPVCI<0" M=2C(QB[[,UZ+!H-'^>NL%KM)WS M&\EJ$YD=T!6P35!I '8T? %,UT_D1?H[MAD$"^1S2)[0G/VGBUCDVFS=C\$B MGL*W0H"XC]=60, W?2,_;+[!K/!)0FFK_H+)9;;:-3TIO2M:6=*4.XS1<;RR M=I)YK#Q"1P.JXP!#;INM'K,'C6LT=*;,L$6M#NP1" TV8\,A\IA+Q&+"&'=* MN=D#,\@0FG;^!R\M>V.34X85H$&E%WE7>)_P.#)F/I+?">=<&@HR=)# M,L,NDCQJ UB1KJSH[%>"?]T/@]DKJ$SR=^"F I\P-%GB[;^2 [?QJ@8:'<8 M4UH=+C5*Z6L1L9*FGFZ*7@FNH4T$:/6_0?B=!FWXBVC76MI/EJY%IO%1UH48 M7YU]*5O.BO17BB.^X@OQ_6CI/8/E9@,-L(>+0+#^N=6R5MC^W;.GP0PP^H_8 MGK)= M/[+U!E!BDRB+#[4^MPSD 2W_L!V"RPJ^+W;J0F,!9$@WF@("4]2/FE M),#%L &NM$46H.6T $SC?: /C% EYA"-PV8!CD8%H@9M?A]^1Y#PC"O)PZ G M/ "$\N*.&:IGPU,L>P-.@D5NN=_QW\&(=K%-+*8$\!DCSK-?FJ'T_1K:@+\$ MZ,+#MM&-=Q''#G2=95DG%";O>4K!R^WU;/(0OA M'"(.A@SD%3ZN]46JOJ%Q"_(31[)/.;:58\RG 2J M.MN0+@.!/9-UZD)?,F\\?(!'8H[^\?&2!H SCL<(OCM;Y43-W1^@NL6A/:8D M"1]AJ-D=![/[1M#.+R"_=UN>YR<;F2IX;S4=['U#-64:3 QMNCZ[F'9HUD,C M /HX#N*X>=#4[@&<&&OJ]Y6^].KM*M8D2W[PLFY!4'6L";#\BKWWFPM*U=0 ME'\B*%$L=E^_:034?@6C& TO%(A^T"R)F(.@J:U!4&X,'8,Q&;N>%S0+>BQH MQF"HL^"QVC/6L9")_R;!\ *:URH<%*6J=);'I=[[(!/#,&4>N&21=>;87WGO MR7^2:#,8J2Z9;'CQN4)&??G\H+(C3!8QBP DJ8D;VC3(N @]-YA='A.FD3S@ MM(G,/5^XSK%Y_0\?HYPSZ?\2VV.^"0*J)*OH6;WGO0=O#0/?'=-V^@N?IP%' MZZ_-A$S%;*Q<^IDJTL_.O(*6I)\U.M'LH_]L1]R(7R-V6IR3$CQ ;>(Z;&8# MIGO#[;]S-]P&.TE,S$*.:GM1P-V4$0W( BM%E]\,JPH^-2<$W*<8M>E=/$C+54 MC6)O0QZNZ$=P""I@"(0CLK#8 MQ^:U;,U1_E>>I?-C$D8^:41^%55@/@TXH7]C5)5L9("TQ+N9\0XC;629-\XC M?@DV0HZ'NC+7\R;'B2$R3PV15;P6W9T;=9_KN734/(:W_,,-OWLT7 K0 N,' M,ZO0?O+L9(Y>.NTQ&_9NAE?T5\_^;S8[<]/TER^ U!C=II:_>J_UT/+7>DK/ MDEX]HN7_P;/1_=04Y\DCW!>-%N$J+--04&H MP&O ()^"D-4 -T=T,/*[@%J6R10L3N:B66% M#.0D89CV;6D$="Z'==%&50OV%'%2%^:A!F\3@'A)% -*>YB'KM9_;Z2CNM:9))IE-"/1/,B/GM>8(&0 :-4""&H8$1_T M[WJ/[Q]V)NG MJ.F0U%:05$P@\ER0-UM5P"0$TPJB#7]M$R#.N>H%] + N28 0*(\\1)IB(VQ MZQ E[ ]]@UF*PJK"'Y*Y$P8);QR&A*CI6^,WGQ$/'+ZA=V"F( M.7/MF';EI$&M-&6\1;HH34J&K21YR5LJZ!*?-ZO'9( "PP6SL+V&%#+^OZ5# M&I76*+U*^7KO3KU337T ZL>>E.#U4M,DJHI(S(#-,TI(XF(";/:([; ^;JQ@ M"I?"NX41'VD!L[Y#0-.YR_J(!5( F"J1._9&..G,6^: \[2Y2.*O8FW@N"ML M_1NV0UL;130:DJ(%0CUB+GC>X6HL80,D>&KFQMQH2&V1]./ROAQTS&0A(2V3 MRN2W_ [;2*/4AT6*J7_"S?8OZ"5I0-EJ;;@#HYK,><882G+)74_>7O_XFCN) M5OU1XN$$=O>"12@1B6./50-NKX)C2\*2=&R[1E^7#Q#9#F;X1S'+IMA)CYJJ M:9I^&E;B;2D++W*3@96:EO!_"S%%X>]VM@T$\%4R9TUA$4TE8)W?26/96MG/^@^AFV0[:._ 17=]O[W2E1TZJ< )+^0+LLNB36]M' MGQ:(E#?Q Z5-1,!%M[I?AJ.>')9<-#8(H MY?S$N4,Q<"%XJ$V"Q[H@O02Y59*TM'B11OOASX^@]-J^O2I0>K?BW+M?0H7J M[Z!<8T1M]?3N9R[ 4%NBS&>UCU6;V1$F+C_S4";^DB0BT:+3;+MG&9E6FLXB M2\1EW70\+)!EA;ZTH\T3*#-P#P'5Q/4\5M)I9SIEH4H8I9W7S&?C>I=7F6RC2D.F'+LB,.=HG$O&?[*#ASZL[!W@S)-* - M3Y+@Y@L8:!X;4N!0,]T%[27D?1MH?EKWL8MU,;[MV++T._GAC@,9C-,Y]@MA M-_P#;OA' #Q%EAX6:'9[V"WDF^V^X#UOI[11R.,/+\0A\.^/ M8X+Z#LO'P88,_X_8>*'+CX>WMWSBXS1H4A'((%CR:F3*#-;&^:-L>!@IZAY'7H9UC!RO96SLNT5V<4L3N#259(DY"6 ]"-,(]$,GD@DIY( M\!3:<[@J 14QL:A3#LJT:H>QF+>N2$HXD'(_9/P,HGS0^RIB%U$(M28 M<6TK=LJ8$)^L@1; $_/FTGZ&R#=2#H0]@8%K8>.G0"+/MK? &,D:P^ 3+9+! M*8FZC';" F?(.$\DYA-D7*XC)S>Q+="9%]2[29Z RV0.G#(Q+*I8A&/:6)@S MH)2Q;6!".9T!V[8M//)YLJD]9,JC?EGR'POT"*M C[":J4=LQ\\)R,O@A=(= M&Q#"&G)&W/:A1"A+$2R1>@\!)5("+Z)-*H36<3G,2[[[ RD8P,$?3&P?.C8. MP.+9\XC<)W]YX[C1W+.7]ZY/MTD?>K.N=/;FN7%Q%/[LY]0FZ"K,+N#C??F7 M^<]=^.FG_/6>UNWU>X4_*5VU\/JV5ZEZMZ_HI5ZU_;JIE'NB?8NR=KYJSYSF MG1,M\[<5CIQD!O4I9T[V]QD%%%\Q-K,YIO'ZM]R[O2T;:ULN/8E\VQ3T?9/( M@2.?;Z.[5'568<3FDK(RHP-P8"L<#AI$N@=S]@+YV.>O:'&E\71CZ/#F+%BK M:_7.B+3[-2I*GM^RMDO9H;D'33@NVN4%!AS_3\7-M6IH\R)RDF-B*0!(EF& MK&BJ0*0K1*0]DG<.H0(7XB MG.JA9@A6DB5PZ@IQ:H\\/Q%.F:@DRGI/6-[G%NV?-U)8RBI16P-A5^I_*[OM M]G.$/9K+"H$^4OSY+8BBTN1O=8:6;%:7*"4/YV*VHR"J6R>J/:I;'435[PQ- MN6_U!5$)HKH-HMJCN]9!5 ,D*DUMAZ2JS3G5FO0X5MIT5$H2^932(3FXCSEY/&MS5!ZGV*5WU)9U8 M.M!"3];Z(MAYC7BT1RFI$8\,P"--UI3*/%7@40/Q:(_0KA&/>H!'8.N)%/7K MRX&[^ES1?6+[-+DEE@DD(ZMF72[[AEA] J4.D> G0BFK,]3 0!*E$=>(4GN$ M^8E0"LN99;/?)-_4;=C<1R? '1S\NB['6]EMMY\A[%%;:D@KL+!&6U:5NKP, MS_WA/M/)%A]9,UO61/8D#>*:VX"M32N[#0M+](6[E2X^NG[Q[(6^UAD: MFFQ5=\XU*](FZ.2:Z,2X/)U@9D-?ULPK:PT@Z.2:Z*1W>3HQ: :0T:@6&K<1 M<1=-X6I1NNK+/NEC]HDE]WI:@Z)4(O!Y)J6D1CS"E Q=-J^M8D7@T2%"NT8\ ML@"/5%DSFL2/;L.G(SK"G5ILGR;/I-_';#B1SWZ=*+5'@I\(I6CRPJ"V.*M MJ2:AU!YA?AJ4&BB(4E;U"C1A22ZP35V9;=A4XEN<+?2O>?BV0H#S%90=%GM-:EYCVAR)<@D2R:7 M[YDXZ'6&FM63-;TGZ$3024/II 'RQ 0ZZ1FR47TRBPBQ7R3][>HC5.=*-AE@ MTP_3D#5+!#JO$(W.UE)P@)T^]('<[S?)'J!K)*!@EDEEJP.1-^N*\2H2S07'"@JH)0A#ZI7T0F4:AY*789+ M:2C7Y;[:)"YU&Q;WON2W,AINQ?2"5M++J>/M P7C[:IL]BM[;4N>4BN,JEM$ MN9/WYALH!N"<(NO56W,*G+L.G#L#G^MUA@-9:PF;.W.7+<=]3E[-WW"'-]^; M5* MJ:]7Z .@%(Z)4CH,'CBCZR*R-3O#GC %KQ$M]ND9N_'"Z@R-:\LT$'AQB"ZP M&R_Z@!>])N'%;=CY[$"D$0&MC'#Q+<7VC[RS_D#%B@'P7H<=.\%BY!&F7-U: MB4&]0&D];]C-&E+KX"&.0W>TB&V T;?@BQT2/RYM,0S 2M5DK5>Y:*[60VQL M&SA!N()PCU7VZJ5<5:'^I;Y:Q.ENR2ZSN M0?=W:K\N%^1F[6/Q3C+>/,#!21#$?A 3AJ'^G7Z^I;Q9 U>_JQD(B*R#%&DU MB[V,D"5D=C)S_;LLV#9WO'5?DTG- M^]I5[?NS?>$52-,0Y=!?7)OTKD]HEJZ"9Q3#(>*.-_69WA M-^2U2 I8NP'H$?W\DSWCZ"[K, M)&VT9X)ANOU7B_ZZZ\-O^!441(-"CGA6-/\V)2"V/2]XP;P-*L"D>1@\NPZ) M0!>8AR"^V19ICN8L 'XW_0"92^2'44DEB@/(,B&F!Z ]\#?)+@%#FD&6UK^ M+8*[YO .^IV(/,WPY.X//[:#H,??GC >*OZE7;KYM*N2?:MRAKYZOVN' /K.[?&9METNR4ML$AC1\Z0TW1S .Z M.US9EGNWMV5C;U;W&W$4Q[ MMTO'$M.^MF^N]"+FJGB\$%Z *S]V5+;](TR-NHD7Z Q2*@(RD. MT",WA^4LJ8)(_K-PY^@X$Z71QZA5C\SK2,L+ <2+D"2@_A;\%OA/O[G/Q,&> M/W'IN@.UUQGV9%5KTCP=D:IZ)K7DE'AE=H:&K*E-2G45>'4FL7Y*O,(!8+*E M-0FO;L/K\Z50H-,XO6A35MB-W-Q-)0E OWBV'X/2^SZ!Z2=2/C$)6TSU9$MM MTOP:VAF:/5D1_<:N$F?VB.$C<4;K#'N&W#>%"^8:<6:/P#T2 M9_3.T.C+?;5)G0=N;]C06]NW';O*M*%+3^YIW/.WH9_5DT$C!CRT4![LJ30] M+"*:%P@&V%IJY3;US=(@!.)?$^+O*=0\%O%[G:$Z:)(:)!!?(/X:XFNG07P3 M$;])-N-MA,%.E>1R_:[GO>W:2P2-\^1@=8:F55?#5A&S:!+B[&W*7@EQ^IUA MKR^"7=>(.'LD;T7$&72&>FW-MT1LZU)Y*-?O@MZ3K55GS!>$_%"7]>I%"S2X6A$)Q^S(@^I9_ *1&HA(>S2Z6A&)E@^:BK"46Y>$IVA*0^J M%_@TT0!N308*Z[;X$=OV^/1'VZO2)^;2W58:]_QM:&JBH^-33EGB;B&M>(2'LTN%H124=$4ON5*ZP$(C40 MD?9H=+4BDH']%JWJA1O"4A8]43!]J55:<*G#E$"!^),UC< M9L@#71C"UX@S>^3MD3AC49R!]30(9VZO)PH5LZ(EBFB)(EJBB +Y@\3!^4=$ M&'U:$V UR5LJVD8(JLA212U]@DJ2!;;^E8WJA0."+ 19G(@L+B M>MC'6-9T MJT%D<1NQ-=%KY20JU0G'<_0P"BT;UY8!*;#J )7DE&B%/9)E8]"D3O("KOOIXD::9G=89]P'A#&-)7B#(G MR9GI]3M#RY*5@,'X^^J(3:4C$3CX.;PA#A>DT[;D2D,4#V*0B7;_C/DS"82010WGO^A1<]*$W_/6, M9.Y1:=Q4$O%[[.T"^'_*7^]IW9ZJ%OZD M=(NO;WN5JG?[FE7J5=NOFXIVW8O2=W]\C^EQ8 ;:SAQ#AJ>GE)*')!KB %E, M1]B;37AE6^[=WI:-M2V?K9/;:J\9]LU?H%X5*'BBF 5A1XKB,EB[[JK)@R.V^[Z: :>^K. MN0+Y ;2FM_ DOO-/-YZ^!0TP ,WG_8^QMT" H(T!_W>^V3_*&AJFVAFJJBE; M_T:-GX/^-* _92#WS+I2G@7]"?IK"_WM\9V=@_YT MI#]5-LRZ8NHGI[^S5:ZU40/_%/AW5 LO5KR%RYK27?_R=&?0F(ANB3#:-2+8 MGO$9YT"P'B"8*JN#)J40"@2K"<%Z>S*>SX%@)K9UDP>-:J8MO'.[O',AB:92 M5>W@VM/'U-Z>M.]ST);5&1JJ;%5O6RSR$QN(8'L2L\Z!8-@4VY('M7D]!8(U M"<'VI'&= \%P!K$A:]I-]KS9I1VLE(&SXL^?=DBFP2(BTH,_=CW/#EF%"QO3 M] O//MD6KQ-*-R6K/=VASD!6E@)*MRKKIDBEO$8$NWP\U%([PYXJJY9P&UPC M@ET^X&=I8-H,Y$&C.%ASW :JCJ_*>PXN4%JSRFJME,/#_+4-$PM MNB=R-PJ)_?W.GL#&[FWOQ5Y&>*K96CS7O\L">Q-.6Z$QF=0,C5U=TW^V+[P" M:1HBF_G+_L.PP'*EM8O!1$). T@%MJN]'=77RQ53*[N(0@Y^N&[TS=4E4?3] M&).9-/@_?^EKJO;F[=3VGT@DN:P_.:W##0G!GB:1] *\5GH8CX')Q39> &[. M_XG%K/C !]>W_3&L"1\=>T&T"$EIH)V';#\%/NGFUW8HM?8[A^SHS7KU\=D/ MEHFLP4-RO"@U0=>C9_4E#,;$@0.*+GY"Q1MX_VQ[3!PA':8()57>QJ6KP#\O M0LE)]S/.[F>^VH_TRHY 'YK XPY2Y-<%5GZKNGVG]EZ1UU(02FK/X?^@;(X6 M=3^2\2($R0GW@D9$"1K(-$88J@/=D"5X*ZA5<+_S6K+A\PZ) !"L*ISX=$7Q MU([ADTQWP@,(L8%=R.X9D63Q;%WXT9#,@Q!8 GWPA4@3%[DGR+'%:.;&F=6M M++V8+CY;0XVNP_![TV55-_'X;=-;WY8/ $) M,DZE*[*$Y=#TV&5I9"/@ WJD;BB1%4/@JX 7(Y#I,N 8<2T'?/:%A)DU\U5$ MB_%4,=X130',G!1,P."E4B$1HT;31/U8V:[H)JX/OVW X0,YPF$R$'# M\4$*$#0IX84):*0\NTVX[>3U%A;6E7"9AW_"C=;8+6#EL^L@.=E1X%.5$VAQ M$5)23*F=<5C/M4>NY\9+Q-?"]7-BG\,E.UQ)SO16@%?,E3D*OQ]\V?-%"-86 MU_O&R)#I BAO^*/[V)5^?7CX0E_/N!I!1@\/2',P5L 0>,ZC+!>V@GR0\DO;#>&OH,A[!&4: #\& M:$7,1(]6(,"F(MQ^7'$DUN'MC?1*>[T;\'0U^5>'9"6M$%5\@N(*TU_P($F( MLZLD[1W,ECHB^.P, MR #X [RYX+/V'!O. Z4"E=@+.-&0CP\ (.$[7^E[ )5B*&PB31S MHPR 4(?^-QFOB,7VEQE9BU?6)3SRCLD"46VE@"'&@:Z';TE(/72C[\G)<4&, M"QH!"I3?K@8*7#K3R&U.CZ$8,N] M!.%W$&N*JK]N$6K_DFCWR.L8=C)DS6A]4\"T#2V_'*:^P LV=?TBO&5FE TX M&<4K*OK'E]]_E7[[[8O,/^H0%+*X+I!\8#$1M!/G"]!!QUF!/7'#F##2!CL?KKV M1.E"/95B-?IGX(-,,^;ZX1*TE>^H_5%_R,8#_N[ MCEQ$K6C4JE=+U J'(8FHE8A:-2?6\0O7RE@]RL?4L]L>-^!3?C2G8KN+>J\L<,0U8,9 M]Q'8@$K^W9X;:1B)V&-02.'SS*^Y4DJHZFDH_5<[63"E%]7WK$/00B/^=+?@; CQ^6>%JI8?>&^F8\^QK#H M#R485;.:6W\*8NEAU5*ZPCE;AP77SZ5!%1_^EX>OWZ2/'S\>O4U3:5$.@:JL M$)S)F$C.AQLC%JY]&X1SZF>3?D5-GGK[VR-]/ZX%@Y%OH2SF#=.?;=?+1&'0 M=!L'#E6Y")C98^8"QP8+*8J3Q]-X<'K3?$YLM FE+R#VI8^R ME#F'38.>^BT* ]C4UP8W4FZ,3A0XBB0>G6@*;$5^ *$$+;XE1+!7 _)63H2 M&K&PIA$-OZ!C&D,E#"Y1XCW&&$#LPB^PN<^51Z<3T/DP4PZR'C MIL%L YZQ *@E.6 #)6L"12Y! *[B+?'(7Z5@RZZ)+_YU5_J3NQ$.FZ> R@4( M%A?6^BUTOG#?.&;,[%&QZ!B%E8ZAKC0L@(?$7RA]XTH!?>TRIVH\4=)/]-CY M L<+8* '"\$8FV!9!D61NBA-80%L\&2D"1^&&6]$!MAUED0 MDUS$P.5;2?0;SWZ!5]/R>*D+(A!E"LI!S M9N^G6\:(X W8N;8YF?S[E603##$)9, V=M^Z-8?8 DMRJY^G6ZUN)T38E##_ MF__"JYU^QB6FC)>=_A""FK 1A !%!D*?[R'RX V$A76@?AR+>5K'PP$I'(/4 M IFXW4/=X, LP,UT^BX4=')^EA1SBFI-G]6-->MO"*'V$2',[B6^$5F+22R2 M<5C>,[IY<4Y>93U%HEK@OYGT1\R/^[-$H]*P?>O9#!$&L M2.@JSX/O;"WBC$OEI3>;+N!S25V,RMC2)VSQFSH ML!7=91<6=@.3@_D.^JIY<++];W=X[3(FX(O?9]2T3QG^<8/B9^/U(^(OHDL^ MG/;%V?;/Y-]L#Q=/5#_]@8WZZI,.*.8B.V753@C;;21AB;-#OX.G%=NHU7:R M4:O#\4+8J'T7F7)SH__U<;:1>A*/]<8^9>/B9[?/HN-$SU^+2D'J+UX+X?]A M+'D1[;3P2_;M,1W.7F516KL3]G4I'91:3P6?Y3S21,_X$.:1=9QU].3RM&!5 MT@T^Z O/GL4G(X03UPI$4.V+MSV*01*A3E80EW#=K#QJ??55""5:N%>!I9S? MA"%I8LPILK_91+^2^343G>FT]BD5/&GN*O9&:8L[$>3)3V="0[FYQB$ M$1%W2$23)GN0:JHD0Z+CX[[O!D0GS^/R+[ .BVTC9LR$WL=63T$1=5 41)VS MF3.Q0_WR]FA\64!IA+7B.)'O.L$X!7C?V "+0X_?,U4W>KV\B/F!E"S'LD1, MK6 EO15%D@VS8)W2)54N7.US(AF:"IW:K%-Z^JTMJ\2O9L_2)7U%>:>ECV-J MX?V:X[]3FOR-G'69/_?C@\7UWRG$SI^;817V=A(K&$CTYB"Q56GVI91NFR=M MVUSL,IR1&*:%)ZD[XT$CJQGN/BZ%6T_4^_*RRPR&6TU09'1=T,#VG<>E:)(B M3E/&0G3)>9P0H2NVG'AL57:SLUW^Q")*&&>T&\S71@.M_&3>BHP$T6IM\6@X MF-G=+7+6QU@/,@!-@\R5S3DE,JKV-NG;O1MX5.D>M7<#(,M4R8J$=P>;OU51 M)*,M77G3+=VE[;S8@_0UIV[%^[SC,'P,SFJUIZ^S\38,: M'=Y;?FUHA5;-E$U#(37>R^@C(?PSP37;"]A3%(SE!]D@!B'2.&3SW^!O91(% M;"W,%>X!721NC':.>=P$^CGV6&-K0E^.W0ANNKJ;O#N!VFVS/#CMALN1^Q@S M6H^I&;RS'J]1(^S_,B%5&C26:_77@]Z>S>2ZB*#9NF8EXP=9+4W@!SGR Y5_ M5LPY/R#&Z8.)-:)&].#\F9]2 RZ0,3;N@PID,'N%P%B3 2S'6!4PMHS-2H6Q M:O%M\#V,^M+Q@Q#U9X^/$Q$O8TW$V2Q7Y'@=T/")APB]!3+BD(Q(%7UNN0^H M*R[RLS1!X-E.G+.=8=:=/V.@1D]0%*H3Y6.\MA@N(B(R& MB6X! O);!$179$46#@H-U]@X5!QZQH,4_DH$]""Q1A:D(CLQ%5(& I"I )"% M *C<_LCEO<>'C>(D9O\9H";/7NF&B; P?E^$AAD\-4(45^;.54L]4BW'P(.! M!^=HO]<(]S7)X&LJ9;.2\6#P-948Z3$V%4SJA'V0#5FI#4U9,31M2'^I./(S M"2SE-<,D1:__!^I'*!*UH#KM?6, ML!$EG0=H!6C-=_+J-:PQ:,4Z0&L9FY4,6C6 UDI"J[H,K8HDISJ%$] *^ZT MK0"MT R@=4-HU0%:RPNMZ>?J56/E7'TB=5-T9&XZY05I>2TE@%,X+K\]?8#C M\@#[)6M6*MC'LH2_ /"7%_CG-C51B6&8,K.I#4,V=6938SF.8GYU9G%1P_** M6I-P+"K] ?X#_F\]7K-&N %<-?C'YNM1 _Z7I%G9\)\ _I<8_V/#'QO\,S:$ MX?_(RP #A?8%P U#X=U!8&+PIN>MJHNY72EFQS"I3IU:YS;E7T7.A'M]KI\>Z MZ8!Z?!M*(=3CRVN:H![? 4D8U..#>GP',+,[KL=7#+TO=@9\Q^;V0'3_3]<)4>/)\H>H<>]3 M49_@M#5]G'C/E,(NP6XB]_ZG4E%LN$;4UUOK91\UJ1$% @I*VZQ\1 &B]RI) M%,@.B0(Z15W//165B8 S &< S@"< 9J5F#- &&(E.8.R2^<"9PR+&##L37H61Y_,\?#*ZI3[[/+58 M^]-S*V"\(I5B! L^ 30": 30"* 1T*R$-*(.-*+\-(+4V4>LF2\T0L'ROQF1 M4$@])A("XZLY]K=<+Q6>EHUVJI9VJ= 1)YD6;Q2@>]]R180\O7= U(\EL"; FOB0-<%Y-$9 HL"+ JP*,"B M@&;ELR@@R*$R]H2LOR \-DX?V+_J'.$OG8"]%4YTM$0UA'//G060>!%J"Q8! M5V4&JH"KI6U6-ER%7?\JX*K"/VOU1$(#83EK1(EP=8&ED:])>* 6OB@Z&E%; MW/YNN3/+?T98U/)53]" AD^4NJCGN>@ORQ[[3H L=XA>%2]JQKG21+8K0&DP MTS]@IO.JO42IU*A)3"<4H!-E;%8Z.@$9DBI!*$0M!=U<)10J47^+4-2!4 "A MR/A< ME#H:<"CSHN"D%2BD( H3C\9N4C%)!)J0J$8G5OGZSL[7^04&A *(!0 M0" !!!) ,R 4@E!HP";*RR:PS*@$EDV3?=2QD;AT:IJGT44I_!5&=1)X8; V M>^C4=4;L+?%.+"@%4(!=K#>HW_A[R*HP:]V$% *E;%8V9-7!4"\SM*IJ79'K M6)%EHA+R8JC7L?Q 9!P'$ESP&F@^Y=;U])&Z002J$)JW.Y-Z#[%YQ85 LX9Y M#IUJ;?G+-:R]'C7 ?DF:;0O[FR%]HA)Q_ NGO/&9)MA"UE3 F(ON#IZJ\8EX M'_)>%ROGY=%.%2FE>O+ "F@$TI_W!4E 7(I"7)([##)>CH$D6)MO,#29] PL M]^$$=:6&Q/C+Z;EO\9I_J,GXC!.BYO+Y7+Z%8+%/0_Y7@# *Q[XWNQ\CKK>! MZL#NP9;C)1'J5VOS0.$>#M@[*&NS>! MC6TW<-BCT)UO\?>';KV)8S\#XH-SXX/.C8J%'\HUB#XL;[-2 3[! /B' _@1 M7/-*S?*#H+)'ROYA?_;HO MS VYX7CI^%- ($ @0*##:R9>9"VT!A,Z7[B)_=?XO>J$+8;7NY)/SC K/:NE37CW-&-%GR7^'?N+";VG MIP.?6@^GUHAU\+&J288/9VMV(P^^Q8 MU-!'YL#49-E4M=%P@ V*546C0XW:IFS_2__TQQV7O6?)GOVV,UTHKBX2\KQ& WHV__!U MZ 2/$^OYS''%)(@O?5WN24H0@)B?Z'8L6J8I&8K)I2MFE_\&3F.#54J[+ M$C&UU%NRA+>\KLEDJV^LZY2B2+)A%JQ3NJ3*>L'ZA(ED:"IT:K-.Z>FWYC^U M=\MLK[L@;]A'F3_WXX/%]4*8 L8*1.FIED#;M>-#MSRG^3.SF$;,7')MFK8] ML&XZ8ER(-3T7*\:;G"&:][D@#H'-9J0540,!E]W9=$#]W1E+6T_4^_+RXC_( M>H+^\1EK\M<+&MB^\Q@=V2[P-&4L1)?.A Z%"%VQY?3DA./L9B>^+TC<84H8 M/QJXP7QM--#*3^8M^Y8WC%9KBX=3PLSN;I&S/L9ZD 'H-I!9$$C<-$H0-F*+ MX5;8PD>NK&[$]F;,DL>*A?[QV2 8?T58/;*.49//]?ST=8IO 1SBA?)\@D,< MFI5]2U8A$OX"9YD/#7#(:N0/3PCFN0QSZG*&,%/!9J#&2]*L5&K:_#L"\(+89_Z,*S9U'"PTRFHAAP!!XW4,8'W:QTRKC? MO*JN,KZS?GFN-WU&K5\A,T.X$=*WQW1J@78N]C($[0S-JJ"=FXT.:.>$=FY: M$WLVB=Q%'<=]X!GE0%<7>U&"KH9F5=#5%ZU+T-4)77U!1X[K@*H&50VJ^K"; ME4Y5=QKGH*H3JKIC#>@$M#1H:=#2A]NL=%KZMM<"+9W0TK<^Y>ENP/L!RAJ4 M]8$W*YFRSBK>JB"*NNFQ/J!;ZYZB-E>'5E0#^\(*+<0/ :.CD>=/K9 ?K[<" MY"3T.J]?8;,'6.S*D-U!\<%JQ!#O&'1X(1?K'I;^VBQ6R_ES(LV>R3L1>:2B M8ZW_2OO?J]Q#>SESF]ZM+^C:L9+X-7ELB4YBYM]?QZMB]>!UM-O!(.V$M'K.H)G @60HS2[B9KH[Z[6_= MQMV?O5;_O='&RG)O-&+#]7<[\X,9!_#0BR']WS/'IU$5/?8"XV.[L8I5.+CC M^M'P>)Z\G]V?^4S3T(!9+/:84RS4L$-^&YN*>K+*$S@C80#UC 0/&49TQ:>/ MGB^Z,* H8%/!;G V$W+V,K8FHSGA$.(8-1"_[-.9R[XE?M":A6//9T,?OLLX M"C+W-W;H#:@?S:UV@HA,-+1)WZ,2HMEFXV0*49(CI;A-.DY5D]0MTW&N^RDB MZ>KN$GMN]XTWAJ?5WTZBN:%+)]5<-'?@_MB52;:I#V2'[/A=4T@\\:9_U[S) ME).+QZ*?F8_TZJ;3ZC]!IW[9ON?EP,&X[\J/<"7LM6_7:X!LO,8[S,7X@5R+A[$4OEG^,[IV)A/*$U8\KB74>^^E^)TS M)V3/L#?H=^L7LZ7$AM%?CDW%MK[PH0H7;'/LT!%:N/QN1B/6R%\GC^_M(_"7 MK^9O ;UG?6YH82Y,R!>'=VQ%#NC$>YI;CR-F$WE/3+K1([,B/3?@1F9L8,8/ M2WJTW6'D3Z?,5GVT[*@+_*H771U:(>6;>$.>QVISJ_,P3,Q<*CY\T,94)(*5 M'1F&)C9V8Q@R!5K?]N'IUXF$=V=!*X6;*$52];D MMI>]X=G-@]-*Z*_LZ7OSJM?NIW"(HHHHK-P#6KE7VP[# M7=UFVJ%!NA^P[P<'8HY')N;!*8Y/S9&&9G@AS MZ()9;,S,2+-%=ZCV,_&<[*9'I1;F*_Y3(9-HKO*L*0V6-NGSE5?+\:<\VB^R MY<\]RQ]FX+)_PQ>_VV9@!U6838%S/P_G?E%E%);N 2W=N^Q%^O*RT:W&ZI5R M&.5Y#KKX/''J%6R]PM+CU9^S#.+7_@T\)(=9^ZCN>GBO2\D+$(0?<]OB!7Y;EAV][,#?F&\!L" M#>;B(7#.:D1X]3,G'G_V&WGXTSL2NLA\K*WFCU9O:TB#0,K2+;,?V8M>M]NZ MN\IAH5WDLM"ZUXUNOM9,YM2Q0"+>G[%O(ZYBJ?T0TZ(BL+D/;R25-;:V8'+S M@[HN#<>(ZPSJ3BWW$"0'Z#OPBB(LGGPB8EJ=5K>1AX=40I>9#_;FS\Z/U(@8 M(/ 56VC9V\F-3B>/_9;L@\Y:/UN=#G#WW,)OZ(2Z%N+ZU9M-'@H4?@/LO=B2 MTQ<9O+[3)SJ9'(+0K"'N*A!WX!-9\XD<8/;RLM?*@U'TI1R.W#3:'R'N$'Y5 MX269?3QD.Q=+^CJ?]7A]T[VX 9J?EX1_IZ.13Y\1U\:64PJ:7[S0GRH+V#>' M69'70KJFGCOT#D&^P"( ^E&$M9./17!SE4<@SD\I!V?J7:-[MYKV#1SY55QF MV9\G:/3^F4-ZQ:, -G]E_QN%T\L?_ U!+ P04 M" "C"4===Q7'-D[5UM<]LV M$O[>7X'3E^O-5)'?E,:>.AW%CGON.+'/@2>$T?/.X9N##@(:L)#0\7GG MR\-5]UWGQ_???//#7[K=?W^XOT&7+$BG0 6ZX( %A.B)B D2$T#_8OPW\HC1 M78Q%Q/BTVWVOQ2[8;,[)>"+0T<'1VZ)8<9>?'1R>PF&(3[O]?GC<_?XH#+KO M3H.W73@YZ!\?].6=J/_=^.ST^/N38^B/NH>X#]V3@]&H>WIR]+8;'(].P[GIS=/QV\8'_>.#@X.>__^ M=#/413MYV9C0WTJEGT<\+LH?]]3M$4Z@*!ZP1)2*JPL!DW^F/67LP;OC@Z*L M0B(UV(0F M-@@1T*WA7S&235,O)V3]U6>DZZ!X?=XT-34[BLEZFFW\MN=A 6 M@I-1*N!*4G4)$4YC*9+2WU,L +'9^J9%+89)7O02P2]:VKOKUY M3L).K[G6-.F.,9YY:39E,NWY%9\:U,5"534J1=2W;B'759>ZATI0R&U9A\KX7D>*2U)_3QI6H[J]-'1"(:"L[_LH3"!X,V:/O8"E5/!YDRBL M$BF^^,1?&6P>=G'43=*15Q7F8:Y^(;YQ#4(@/JJ+XNK#QCHA"'UT%L75AXUU M)F+&?90NRNM/%6HQI4QH!'4EOS:;$1JQ[(*\I%KG6=%$[R$JA@QKX,N'ROBM'%RV,>S/.9L %@<0<-#7 A$-TWE$C1+<8&WZ=<7@C:U(4 ML124^QEU6VJ 1(Y.VMZ;I4$%A&KQYYU$4A%#YJ)=MC^$R-=^*4(H^5-8'^.1 MK_52!.+_>\,#'/L:+D6"--XDZI7X@[R/2'C>N6!RSM]!ZMJ7^^MUM,2M: M8!5HR_![?Z#_':+N\N&@B[34#[W5LBLH:0+A+7VO/Z\VZ%PX+U(CN.*2QG+E M%E0IEE\L7%?CT$$:$G%-U8./KDDSWUI23C='#C XF5S%[&F#'J\:QLG26X_12:(B#=LBIH;I=(KYG$5# M,J8DDAT)%8- )[\('=])5P7R(:P970VQG)Q]KZ;F) EBEJ0<%($9L&I*!C1: M8J,"O$7,7=-'2(2.WF;TF ).#MZM&W!ZL>5F(M\N>-C**F'7I>UNG3PU6? M9H(M\NI0L."W"8M#X(G/)+1"SNGM(VMX-$#^VK[)IC;_@PRX4.47@":Z/G?R M4:GIO*4&P,G&<24;70V'3#RD 5O$2Y;?><#/3;L;4\#I]Q-[@J*DD19OD9<_ M@\@LGP&7X39E%-,P^Z!Z@D<<2]N&$\P;Y@8]\)P<]59;!(*B@^ M+E4@K:-%1"H/$#W!U@[7SS5 FS]]U<@[B7J[2M02+&?'@&L1)T,8*Q_<@]J' M(!W0<#Q9E7+ZWW[BS2#0 J--3F^41O@:J8F&*8I^_]":\39/4:!OBT]MRM@V M(^ !C^*7I31'=!)J3ZH]",V4M(E.(QODPYDMYB3&FE\;&&WT?%5>R8>"&GDG M%]:1E?;B2FO ML7F=M),">R9^35A1+S?0'T;:ZGW:S*62!)6'1GF+4EIS6(3D:MA$4UHUJ%RO292O:$:O>H M79%J?))_ED-_LB6G]:!.6JV$2#6M>D.G'@?5!T/1GEKMHD_ T4#24 E5:E@ M7%[=DMIZ4">U5@JFFEI#"S+4[(G-UK&RMR?GTD$JZF=J^B$G]ELRZT!U4FNE M=JJI+=3HEKM0])U^,MG3JYR4926W9+,,XB3/2OI4DUTMA=?$6&SCWWVEN7 MP.6$4Y#'K5FN0'+R:>6&JODTH/>T::=<,0YD3"]2SH$&\RVI6X/FI,_*(E73 ME\.C G_/H?;,/\%R3:6Z/7$ MK9FL1'/2V#"5M(0O5C_W'$K/5"\[;TEE/:B3T899I+6KVVUDUMA\-WB4QJMU MC(CQ(8Y!/@_\'>)0L$]8I)R(N5'6B^@M=3AYMU),YHY"&06%3B25(J55/^HH MO4@P5&@N[T-L=RCD/I'MA45.RH80Y(4WC8HMU3D#Q$I4E0-DJ5XM&30-EV4] M6ADM5=M.%]=8=$6H?(HD.,ZR!]*#BRO&@V4N&S)ZK[S)94^MEVZ\ ND/J8DS MQJQ\VIJMM*4;,MP6E2GR+"K8EA?-I_"BCDB.58M:YFM=;0Q!M6M6G5(=IC'< M1L,)X^(!U)',([_,> ,<)_U6LDU)?X<*6'4N>OY4N MTG3WKKJ(A-OO1C9HK7&[ M=MX]S%*U;3"!.\[&'$_]FN?F\$ZRK6R0B]X\'-!2)RJ4MI)ZN_6M4!)>IBK] M=0>809=I0INYO[66[^B76%^K(-P!W,=ZW4DB. M]V;W?7LSRA<'P=P/OSQP>0$'ZIY?Y[X%OI-X^[ @%_'&X3-2*3*U[ME?PTYU MF4V>AU],FS,RJH_R;!@9:\NV^=G:>(4^^_A!K0R#<=ESU;DIG)/KBH.,S#?U M\V\9?NE>.\=XP\7+I9M\N^. AI?R9B)(\ +$>L([B:X]F53.Z(PEHV+[IM2( M"I5[[DWNU79(&I"8Z"I] /$$0-7O-J2"\;GTV\-'XF?,N7XOX@\*&DN?,V0JMJEM'3*+6K0^7-3R MQATFH9R.O< <0RAO9UCDY MMF[Z(MYV*IQT.P[U*J^G%DK5W6)3H)HV&(I;WY@M8G")F*W[>E]\5P38OU*S MVJIMSG&9\WU7OBD[OQY^;?ZEAGT$_)$1\!-G2?*%\NS=NO]JHCX E=J\WTWQ MPG2R;*6&RRQK'H]!0-<(1:6H<(TE-FFYSVY=6AA7E&!;,VTC4UC_9&27H'J MAG&&C97MKC^:LH5?5BIXS^>F?%X+F%Y@ 6/&_0YR M\49ULNK^B:]55I4:5.CYLW/[0^\Y.<.S&9$^4%>R[Y2RK.[ZDKP"V?9SS;SB M[-=!&A*ADJH+UPU&B> X$!V$\T_G'<%3Z""*IW#>J9.@ZBRU40R%Q/.(Q^1L MIK?:J;J>=\*4:YD.2E(I1D2JOLGGM'1VWLF*$\E;!PE=/+LBX54,R>L*I--; M:\VM5(55+"Q?.Z9CO8/[7DV$6?0ER8YU&TQ5S/PWK\K2T C'R<+2#=%\G)#= M&V5OYL@;,"+"RS5ROB[CFL\;.*=L0K&!?4##6S$!OK@[4.L96=H%Q%K?; :V MA6L"#N'7\\VR9V%1@S>S[D$V;0@%,WX?YP&>Q8=8/CFM]=G+*GGQMA8*WE6? MDC-1:&G@N7Q#U6W]S\C)S@P46+*N5_&&>?6N1L7Y-17 J=:"XT^@'JW7&;B^ M_%)YW&HSE5VJL\@.]7G M87&JCQY,UL[P&DJ_@)VA.)O(DCQ(1[ICW[ S=M;8.?[X(+SVT#,$2AC_S 0D M_P'.[ABA8DB>'R8.P8R3.+=B0KB8>[NG.>2N^L2FUC)!]IK^CO'#W07OZ+Q! MZ> G=YJAJOA.V%(D5'5&:T#SPR)AF5.]7>14$U<>>D.PUYZ\EZN]R"QGU>99 M7CF5-W2UW:GI9B@>P^@?F:)9I;!DA;$3SS<4W#BO'079[PV(1<4WMWT3I->V MONB?7L#\C:!>V_[:UFO4>+/F7P+8O.5_W047/4XU6 1Q-GUOG-5WH49S@6F M.,0Z*.N-J"BX"_6W-N*7>YHF?9,/Q([.2PP3C.JNSBF;>*!6?%>;H]F%WK! MAUSM@D&-P.ZL$7RATBFA>GW3M09657(7&F?69S3I5W:IUE>,A7)L&J8TY,3E M^C6%=\&.SXRJVCD,6"VU"S6_XI!,5*T$ MQ!V*U!8IV=I??P"2DB46*9&L+*KLGIZ0)8HBOLS\"L@+D/CSOWT['S^[@F8V MFD[^\IS]0I\_@TFG]L]?3>'D. MD_FS5PWX.:1G7T?SLV?S,WCVCVGSK]&5?_9Q[.=YVIP3\M?%G[V:7EPWH].S M^3-.N;YYV\UOFU\I<\"2=T2I)(CA*1+KHB8@J1)4E=]D]?].?W7"2 $J$.85 M$$E#($YR3:((+FG)I,QV\:'CT>1?O]8OP<_@61%O,EO\^)?G9_/YQ:\O7GS] M^O67;Z$9_S)M3E]P2L6+FW<_7[W]6^O]7\7BW^4PN7JS>\6)V>7Z^ M0$A&CI>?Q7Y9@/N_ M:Y_^XCO8&Z3W8*X^-TYG\S@M_YR_6&!\-9W,IN-1JE3\/"]?*S=G'_*[PN%S M>!QS_3Q2>4FMH M-* MI&ES\Y=C'V"\>/6?ES-RZOW%/Y!NM+@W60.#3]*%X)\U2 MWI9=/9C,H M_T]?_+=UR;6GQ-MB6J>PY ? ',QBV94\ZP]&WR9#>VI>%=_U M0_[;=)IFY2'^#,W5*,+L\W2P9S=D>ZZ[/Q!3>K ,&FM^@_EV*2$(XI,!$G0T61CGI,1>=^\!Z.Y;[N,RZ9!) MX#(26H03QE(>LW["(@ M&Z)8C8-5T,4#[H4/+2C#62:QF=!-ZVL4^/.+3?D]W 3EJ^GY10-G!7&9F_&S ME9L^OK_4Y:/"(.4Q-XQ3B/0A;_"/N0)BP1LB10S:<252#_[H5CB]+I@1Z++V MH9.FPGL=HV#'6S"?< '!(L#Z)'*XNO$2%#5#LD&^BNCMM"FJG;RZ;,KJ%J^_ M-'XR*S%C-< D+7Y:F2/]=PDAZT.Y32LFE"#!V$P\&&!<,0&.8^I%DS[7K MQ^/@ API'7PI1_78NCG,X#YK.NJ=__#<->X!X BK6@UPS.?+>W:\EF\UB0P M:4F(.@LJ69 1.RUW#T#G=)&?G15"UG_>_,_EZ,J/JW]P,G_EF^:ZQ*;_X<>7 MK0C4NDRL2(S$G%@"+ZQ2V+F!G8 -9I4[G!2M[!&Z0? 226?39OX%FO-WDRM8 MSEGME3<5,96E)#IJA-;:,9>QTT8;< QFK<%C0F=UHQG^$T0H3"SA^JPL4EMD MHU$39[PBVE)AK9*1.>RQI%> M"TFE$=$)]+S(]_%WL;3\L2Q]L'IQHY@'!:(0B;7&D&2"R;2L+]IA.S5M%+L8 M6_U8QNZH:C23OQ_Y,!J/YB/8AH.E3%QFB<@2>3 F8XS)()N\C:*K7"Y)!$124IDYQ1H,BR;48R&'>U(P'6>8V@=S1NORG1Z/0: M2I0[KO'@XY)27Y[@4*9:R P$]UX$CCV[/0IJ,.XK,C-PK8%&DD+8YG(7.,E8 M8D.D1(%TW)09GEGL2N!6,(-Q;/&G"P3MHY'A-60HPZ?5%I\M6%PEII62\,QM MTEZI8+!S'IN1#,;K1:8!@M[Q/*+IY+2&VJ\A; NW'%5%-DB$*FL4E1ET"M@N M41O&8-Q@9.MWU3AN_+-1.$^]!TXBU9D8;AWQF2>BG?,I6RXYNINP!4E9?&".P,QW)D'/S;GJ2ZD)I4-&J"$B(: M#0*[M+YW\'[$Q/Q>9FVY*P=K%HV<'YOI!33SZX]C/ZE[\VMEX&)5,VP[38Q8 MK3P).6MM*61AL+<:/(1G,*$,@NG1]-Y'MNZWZ21N)J7RB3AFH/S( D23 N@> M$W;?@0PF8D&P?7=-XY^$>0]^!I^J\C[DWV>P0->J!7I#O%"*<&&T-4;+K+ K M< \"&DR\@D$"-,WWD;RMQPOFT_BOL^FX:'569Z?Y=6M'BUUU9PR,!V31C\(=6?XP3@VJ#1H!6<'ZAMOJ\&C\AC& M2& 62'0F),<3]1)[6]QC1!Y&GA;?_!VU?T06@"GKK\B.@ 2:2M"H&7KC _SI M[&.S2GTM/GKCCIY8#PLJY4AVD)64 D3&SC9M@#&8Z:VCZ=N.?#>-(Q[//#^? M3K:C8%340P^9^*PSLX+Q\A_VUKHU#(.9U)"-WDG7>(FEE$95=C_^Z$?IW>25 MOQC-_?@.N'8D2>N> DT4"YZ%! HH]M+V.*K!Q'+(K$"V!V9-\O+\^&92XM?9 M'="O(8_BAO-V4I"@<9(I#]P+KU7&/L3_**C!.-58E, U0V^;.K;C$24(M(I3$HTO_].":XF] MPV\[FL&XR&A\P%'\4[1W\+.SM^/IU\['6S=_:(^M'#8#1SKN6L\?E0$^-M.K M4?FTE]>_SZ!$S7Z4DLT4 #NQS/XXOD4N&X=DEF%9PV"EL%.P';TP?MMXU,'WQJ)7S1S86Y MF2<"I%GM)?C9C^%DDO[NYY=-638_Y+_[YE^PZ(ST&6)];8,B$JLP;2)1&$4M M+\Z6P=Z4MC?(P3B[QR)8KU;$(]OZ<[!U2U-K9UMPQ'EA";=6.YYRS ';,=H= MW7": #[5!(9C.'1BO9TV=Q^%5=?@1W5AG^,!RLAU8LBT.>P_2#NZ8O_ M/!3KPX1X!=.BB+5F&)\*LF84BQN\:I9Q_X4[[_P(S6A:-!>;&IV^AN6_Y>=E ML]XWW^*9GYS"I^),O\D98NM9,DZ2D'0DR2IK-(M46NPR_'$E1&ASMHF;MWF M[7QAB1//(I"L*672"V<]=B)N=W2#RJ[U87O,GK4'SIN,&F)!:B*" M93H;[B%B'Y X-%9]RL9I/SPWN]J^;VZ^'4W\)#Z(S_E:3.% ;.;&2,VY\=AE MN-W1#2:#_>-SLZOM\7HF+$3\D.^*_6'22<&M:%=28B7UQ5FD$+4$FO&[+."+ M,9C\_ _$]J=FTP"F[& 4LM]6?*4:6ILDN!8!7%7XG?.WMU-LHY&LKH9GR9B?$Q,UFUP'/L0 MXS8L@T\U]SF1'&R47N:1=[/996WG_#"NS 0)TAGBU5:W\A;IWTZ;SV>^@9?% TYUYS9,9@NMMD*O MZ(@W&8CSWEGM;)81>[_8H5CWW"3]XT]11S%J'[6Q,K=>-B4.FL'BSI5M1TPD MC<1Z:DC1(1<>O*4&.SQ^'-6>C89^'EHA&0J=0!_RZU%5P"3-'L D0BJD]I%( M%W/BV1@NL LK#R/:A3CF9R0.@H$ZDZ;N$_SGK8"+?;@W\&ZN\=T@_H8.-BZ+ MLC0'3G2='7.=(/-:HKF]\_'@T7?AC/T9.',<^_2=]=JAR%>" N)DE"1034WD M'"AZT^A#"[P'Z>&!"Z9\;?L5,XDJ%NG@G,13YK^PIQP$>V#>8[Q6VKUI MKGU[UVY;6LX4\8E;PI0Q*D,NPZ*##0TPB>X;=#W\KF,$GJK 9@V.6'N>;FWNL-@@JK2?!.2!!&16L MUC(!=E^1!P$-/CO5__QRJ'EZ9,S:I4%MI\H3YQ@C3'KM A4@T6_,?A34GCFJ MGY X7:S4(WD6\^&M]*L67LN4F:=1EE4R@ZV%:EK<+\,TD=)*;J0"2/VS:!NZ M7>CD?NZ)",5P/78'6/&]8/LX'8]B4<#-N3M_O_W[Z]K/:7Q0LX"]Q^C>.Z"; M6$BM!+:>8/Q;LR')YW@NZY)R)"D9C84LH^YA5\<#B#KW)RJZ;1W0HY(4R1)) M4AN???(>?6-3'7VK7[0%Z>7E:+'OH!9PWIU?E%ETV8QCHTR< M ;$T6>(B#S)H837Z1I(' 0TF&=PC%_ L@D:2MZ-O\\MFT9_[84%U;;"3=2"0 ME2NX(G"F8PZ=X>R8%C"<0>T)/9O+F,52GO)D7NTX)M,U.5L22PS,J/ MRE%9KQCVZ.>/M\,93$ZW1W)@6:-'I_1.RYJ3J^*>U4@L3YO:=J0L@?\.XS2? MWC0?N?/>#BYJQQ&[.ZR8(B.YKW5+Z_=V+K>HWBY1G2Q1?;E%M:H8U?+ ;/ZR M@H>3\7CZM>Z3+7_SJH$TFF^J;O-8M\D:1TSQ9H+,PH+$SLOW)4OG)MAK2-9P MWH/A9Z/V!)XHL4Q&0D59WVOVTT1L]WI?C(-QQ0=!X%8S[3XMCK9DW]?,]J9. MM:UWX"$2Q0T51HD #+NMS38L@W'S!\DS% L>9XU?@2S@IOG1Q>^[)#C+?V#8AQQWFPCP9*S/]7>3U.,7H\F'"?P7 M^&:13VZ:ZYHZ/J^9QE9>1G'B=-)$V!R]4[H>)#N2/O;!/9C%&H5HNTZ"O5FV M]P7X/O*3/(>F /]RUDPO3\_>CJX6,LP>%8)S4R)&S@@7T0H1DHP!VV]$%F$P MR_T3,K4?>S\%:2OTE11?8+*;$" $L2Y:8IAE*67+(F#OMT<683#9QJZAZAB0<45)R%21K"6GCA4?,Z/?7M8I!.^NDYU6SGLP6KMNP)) 78E=>91" M9 '686],Z(YZ,-Y0KZ1\+"71L[5[>W+WG8 >%$'00+R6F62O:9+2@DK8ATQ1 M!1B,?S1([N)SX&EHO,'Y>U"$P#)QPI5%G>NHN+>1BKY7ITX"#,9C&BZ-43EP M)!IO]SBSC\0GGPC5$;A4X#+%WBZR*[:G7I'>^E&S\>I>P35Q(7!2HC>7A-,, M?T\Y&OC!>E$HE,1>@0ZS^6!6GZWPK5#$%=T1"SI3ZA(+%+LTA 9^L,[3TU,6 MS>9'I^R]>&4K9D?KEG[.B*5,><9Y2/:XZ\]CB ?K$CTI.1&LVV-YOK$ZQ=2A=[O;!W#0F_(=O1M79V2I> M5H8X%@LAH_;&BP1<8-N_!6(P^^!QK-Y-R3UZB8ONB:V>*G73_^QSU5!S/9*$]4";Y""?6HS$9X]*LQ#N_+=)SL8W_$V;LWT^,V MP;M.+GNI*ZZCM$$(J=#O M4T)!OJ]-NN5,MOE[OT[[S<:>_YKA^.L;?\($&05L[O M#4V7]J[]&"Y+J+Z*V:>360O.FV_SQI>'I+CIS?6[PNY9;0)5_K*(4X8YO?'9 MUYD2:2*!N4BDD#(K:1CG/?1VZTLZA+[)DEJQS69 M8PP*_>*Z#G 'L[H/A=P;6M 8Y0_Y\C4W$:G%4X@D1"$)9UYK'8*W OO*X?U1=NZ[<=DT,)FO!FX- MV7;X-7'::9(3%1"=<\IBA^R/0!K,ZMXSI5H].1 MA7@?P+)'[\.Z:#D-PA+O M)"4.4N!"AZ0"=@>7W9 -9L$],IEZL!M>4_>YG]<3\>_+.\<=%"*Y(\Y;22CS M0;!DN;41F66'8D6:MN\-_ZCYE(_$90XD9\.I3DX:]!5L)V"#F<*/0K4M$SFB M[="G\UWTTEIP A 7HB1)!)4=U\I:[,,P^^ ;S-3^)"3KS9+(,?VC8+@L8!3G MA :EO$^.*88]:>W$H -B#B@DZV1REDML[*@@*8HH16!2:NS]T?NC',STC4&A MUNZ/?HTV."\I,DN3H,EVA',2#>;K3.\8F/H0:D ME"B5K0"FB@N#3;2N^9,GW+O6RUS6K]'PR-5YSI4R$:LM$!."#9[J8 1V7JKK M0GEX6,(3H1EXM#XJT-C]M1Z!-!C7H&=*;4O.85@*/SGWH"Y: MCWQ6Q%%C2-*!*Z;ZB3FPG[UE3WWKRN(,M,T4T( MQ%K)N;%*>(&]=P !]F#6X)ZHV-I7>&1+X^V"W0'XYB@16AICP1 /.A#O- @) MFN,?$NN"=S!K^8!(B6+;H[)Q/:"L[W@]*G]8G=^1'[>0"TML#)[DE&+@U&6I ML).W&+@'DP48$#M1;7U4EKZJ]Y2\7)BM>LV+O_@(383)?!TT*$Q+'Q46I87EWW[2[@P@S+HV3I6[DJ4R)@E4!ZD ,)P MIM$/L!R$=#C7D0^(A1T-^D3D6]PVN@Y4JS)YY[J#"$R(4"][4-CYTP-@#N=. M\T'2;G]3'G<=/O.3T_*&FWQ6>=.BM\*L=N%9FO'F3I-U(2A/Q">H?B^-V3!G M93Y.+N)@$?:\4?T/0=6^&'!4&O\VK6FY>AE>&-_T-KJ'UA!C9"*.>B#*"LMC MML8Q[,U/AV(=S(7M R)F9YL>??%>:.D4)G&TEB H2)W+) 3#269!F\ -!?0; MW@[!N>?=[G\(YG6RY5%9M_ N3M)_7ZYNGFHA-;D$_%&3I*5W0:N"]BE8MXYS MI_PW_8/1KI,QC[#G[$\%BXS4:.R&Y#WM^?QN@GOJWS+: MSF6)I5ZR!.*CL41'"]%+E:W&CM)0!1A,*0J#>)O/HCZ%J?&?QWT+$TN0$5*] M""B0:'R0U%AET#<<[0EQ,'6F(S(.Q5Q]O!MW>)78/L[7%Z=D,VG!K-DY!G?^OTS9R#DNY+W#*629-&3E2DM+(^ MA7 DI^M'K+0G4V MTS&6P\UI\R6XH#CQSE,"98U602OPZ*<+=X0VF*K'D=?#@\W3-W>VY[Y7>1'K M2Z@0!8'H0)JLP GLO=,[0AM.[>*(Y.EDGR&<;/+K!WS>_A=7Y<7RCSS&(:== MQC_B>:>]U8':2_@!RD86?*VMZ3(7L4R\MYJ5_].L>LM:_Q#5I:5>K!#$::9) M?8I58O51[JW3RA^KNK0#\8Y47=K!U$]?75J"]+* S$$2,)P:1:,V]$@ICA^_ MNH3'.!1S#:>ZM 0KHB.!.D^R<[G C3&E(U72?Y[J$A['4,W7 ]=:=8C7RV!Y M.IG=WFI1[Q[Z\'4"S>QL=%'O)7H]NAJEXM>TGA3-'?%! U$Y%.W)[!CZ;;)8 MV/>L.#UE=K<3'8]HX:<+=U<3=?EB9:X[OY1,6C$CCU59/R3<53_97-?)/#U7 MSA_>F@A0 G'C+)#@."7)9^6XI)DZ[-GK!VT3L520*+IQM0+$>91*"443>FGN MC]XF8@SBS1^^341/[$2U]5%9>J"'OQ0C8CK#:/!PR(6O+L*C!2C?-FZ%MD=\9M M=0:7E'AC6-T"9HR4(%/$CM0?PH/5O_;^I]Z\NLK4O/(7H[D?C_ZW8K@J]BE! MVZMBQI8VDK;$.6$(=3D::[C+$GMW?S?$@XG(T4BVK;/M$2S:>?&M<\$6P)^J M 3[DWV>P?/Q;.JD7J"3N"##)K' ^L*@>F^OV&&\P43(Z4?I2.GI/[?O8?I^D MT6S>C,+E_/9.M3>^F12WH84SI)I#3H+0LFI3B()9W]>LO#O*P82V1YY[T"S7 M,\,^-M/B?\ZO:S0RKPVE_^=R='&^['=W_X(()XA7RA*1@PY@-*6\K_;M.T(< MS*FU(W,+QV8]$^OF_,K]7O+6$9<9)SX(E:2RU&3L$N$#< 83$QZ9,/O;HF=R MW,,22Z2;-0F>!E*BW!*$!@N>'F?M0I1OZ3[\!O-UZ<"$.5$RL(KKK+N M3[I;''OZ_3VFY1!8\ #3#U,\.L4??9ACO6[3$\\$$ XZBVQ9CK0O*CP>.@_ MP^^!$9WMT,?DMYFC]12=L21PJX@4&4*T-CB'O3OZ\6;YCI/ MFZ^^21L/#=Z_;U8SXK6@I/:MY<[IH!5VNGA':(.<'@_CR?JCT(=Q^GLJ_E:; M+[22,.6+!4Z)D/76<999ECVZBG>0#'&.Q*$%@N:/S *5'+&IB,>B4H9#* M! MCU'G5A8@R%>^64M(UOX0S174+/])C,VE'\\6_T)Z(!R \G@Z86IEJ*Q<@3H M@=W+'0O[X!+/'_ S> "<"Y846)EDJ6(0H?S2 MK#DKCR>@'QESN-/OX:3I4^W]SJ6X!:(%XH7P4.F7C";T5O[/P)I<,GE M/N>7#M;HCR+M2:_6L\N_2S-,TFK#>TL7IEXDH'0@*E#M3/*&I=YS(CNC'5QF M^;@+%X8->^5<.[B9K6HL+6>64>(S9230\BWU,5CT WG[(1Q<$KIG;B'9JL?M M1R6L6DZJ93TNU#^?3OPD+;^II94K/X;)_/.9;^!S/(-T.89IOJGEE3]9_&:Y M_6HZN?VL\A'_6)@0TLD5-'#JX;?+\P#--+\>C2_K3JV/T_ER+^MRK,7VP Z; MFH8H1O>M4D.4JH\-6'?Q^-,5G ]+.) 68LP^7,YG\X*]R+:>T+3E,760,HG: MEP?)>>'1K_C:$V+7B7_+<*UQ7OK9*+8RQTR38&P@(D<7 E/,RB/I8S/ P<3" M?1)M?3WHSX28AUT;J,7SVR=] >YDOMR\X<,8ODP7KQ60D#[ZZ_KFDZ:I??-N M=M'>KSII7G G2W1M3VRLTT([9.IU1SV8,/N8?#RRL7?T65:OUR^A#/O7/_U_ M4$L#!!0 ( *,)1UUYM,]3USP "P. P 5 8V]S="TR,#(V,#@S,%]D M968N>&UL[7U9=QLYDN[[_(JZ=5\OVMB7/M,S1U;9->YQV1[+-=4S+W6P2IRF MF.XDZ;+FUU]DDMJ8BT@FD*1H]^FCDB@Y\2&^2" "$8CXYW_]>CW]X8LOYY-B M]I7']_^\%-AE]=^ MMOCAO/1ZX=T/?TP65S\LKOP/OQ7EWR=?] \?IGH1BO(:@'^I_]EY\?FFG%Q> M+7[ $//;/[O];?EGB)1'3BO F"- 8&>!5)8#3R$CD,7?!/;_+O^LB*#$,P.0 M9AY0: Q0%'-@B5&.4T1ID/5#IY/9W_] M_/'''W_Z:LKIGXKR\@6&D+RX_>L?UW_^M?'W?Y#ZKY%2ZD7]V[L_G4_:_C ^ M%KWXVR]O+^R5O]9@,ILO],S>#Q"'=XN[?_@0#7NQ^F7\T_GDS_/ZW[\MK%[4 M!#TYA1\Z_Z+Z"=S^&:@^ @@#@O[T=>Y^_)=_^N&'E>1T:>IO/[LJ?>A$?SOE"A2K MX/S?ZFDO!F.ZBD!*NS0>Q$_]K%+QA!C;GCX<\]VS@/-!+Z>+A(B;STZ*M[C6 MDY0";CPZ =KZ0>#:7QM?IH3ZZ+D/<-Z"W$18/=(6\X4MXG^N7]3@SHO9O)A. M7+6L7BSBUVJ=G;\/;^)Z?.V?1EL]#U1K+)0$UK">>.(#G%$A)K-)M<:\C3^N M'UNA2H;8?UWXF?.KI>9VV&EA'_W1M%KHBCMFIMKX:?WI[\LYN-3Z\^]WPT2< M_DW\=O[[_0;"XZ8@/*3 (*E!H XCZ+F"WC9YG=_J2=!S4S.['N)%)<(7?KJ8 MWWY2"[46:#>*E3 3S.N3-E._.2?E/)!6"R H0H%RKR/%N>94(W@\GWOU."MO M9[9^IW;:&D)97"?E;>_>7'1;GT M]Q\6LT74ZE?3>L#X3OK+ZIM]-6%>+G[_4!9N:1?ORPM??IE8?_9UTI"']0%( MIFQD4 1$I,;>Z6UT(0[P0 _B3_'TSL]F M;HUH_E.]">2#2;> *-YHA' 7#*G(IP0D24F.=-#./Q MG,E0'R34#"_S&L_K.._HU=:0?ILLKLZ7\T5T90-&+.P/]Y,5^\#S\7A7NX,UX44]?8 M%XD$TED(/#(B8*>P1JG/JKK1C*\!B2@KLL@[@R9<^&G\U>7/?A;G/8W@SMQU M%'(UY\7DBU]+H6'((@L490AH&U3U#FBK4F\DVR$[%0W)P$-36W"R?6-U?OZV MF#<62(GB+L8Q AX:;(VF&B&>:\>XAW$Z>\6>HLW!]N+*E^^*6?$8VEH7N]3> M&@R4%G'J@6*E+.<,I5X;MD/V_'4B/0%--2%#U>3-;.%+/U]TK%$,4: 09@![ MJ!B#T#I-$^O#!H0#; H9F"K2B3F#X7 +)VY5]>17$VXX4@H"R1T%009#$'=& M)S]A:D=RTCHP0.@9]HG['>MLL2@G9KFH8F*?B@^ZC$MA QWQ0 GL #=4.L8Q MY#R]2O0A>O;[0D*!-]6!IE&'3_KK6O-?1ILV3!JPN.? .*$!I$)I)DD0:JL8 MTLYZT(!R(@HP3,1-YME0YM_Y1;?UZD*T7I7@0&%I!0Y((.@2\_T(P+-G>7]Q M-KGEZURJ%QO"B$C_GC(9K BO_K&<+&[2)8/=/3%3,E@[XM&2P9@B0)/HQS,+ M@^7*4*12;X=C)X-YK*(Y(Q7PP@3/=31%7>JE_5B3P7KYW"T9K%>,ATX&:TQA M]1:=%]>?BUGU7K5E3"B)@$9( 0T%$4I)'$SJE()>0,>9+M9/=)?.#!9X!J]P M U-[K+T5U"ZY8SMH0RN@<7/(,A!7Y)+ZH52"ZP 4E!Q8Q @)B!N+4N^"(ZI" M1V+9D6A"K["S1!NOKXO9Q:*P?V_/EQ'! DFM!\8R)'R<(X0L>9!Q \3X[D$" M+/2T URTDHQ4<=OS3C$C,3ZG$UFE_-V5$X;H!G'U?8H%'?,09,Z MJ-2.Y!24(8&,L\01;>GUW/_D5_]]L]K8KHII?/Y\)86/Q73ZNBC_T&4C1.YQ,Y*+ZEI[E7VY MB8UH!HR ##AF.8EF$3$BH\W9P#.^;F0EL]LP'<9$CI2WQJQK1!A["4*(7^)B MQX *Q &M$0G.<4RY2'Y,M8GBM#5BH-0S6!K-\$H$8P *P@*A/0&2:PNXI=H* MAB55\K2B56.RO[^L,Q@:709PA2U.UD\N9^?+LO0S>_.IU+.YMC41,U?_-*T+ MG9RY_UG.%]5.&Z?V/K3D]'.%@;8. JAED(CH^+O4&I1G)J>MBD? ?H:DBWM$ M\T]%QYE O1-7M75<-?TX]WHN'WT4[WRR\.NT] ^^G!3NH[?%Y8KV_]339?.& M.XWOK',N_DB49X@@+5.;3[GG=-IZ?E0:D2'9I);H+3OLA/6WM'(&]SB28 MY#I7OP];@Z[.7R7C#@1#N/#(,N/3!\'W /I-:EQ"[IH*)Y(HW$?_>5G:JVJ9 MCF;(1[^8E&UO3>-RT.H^J08!2FB)]!;SU ;H+OB^ ?7*P513J^0X6M6ZRQM: M5;44&/# K*;&4.]2'[SO .^[3NW#4U.EU%"5^FGR9>+\S,W/]?RJH=]& U75 MQ#)66&N9MM$U2JPTCP"70[0_= M$QT=:Z@UAX $0Z,75"5X,VL EMI8#Z6+GO](1\<)D[O/K"V6L^H2TX=B.K$3 M/[_W(-_,JN+)M:?X4Q5(G,[W2?;><83!R=]#9C0P&;R"\OO%\OI:ES?OP\4D M>M%A8O5LT<34&;:S" ,5G :.((4EXA)MWJ)LRGB?@?=]19R?_/XJ/G)Q\W9= M"[HUU57$E4DQ%_SU\[NV?+HLO+^+C5Z]&_.;^C>@8-''9" M;U?\%$(]=*)X58;K+BS]LR\N2_WY*DIKVI;LZ!R+RV=UB"2D8,H:(P/:9OE\ MHK!@)X"Q$\*3,%JDEFSB.I(7*XUY"*FCZEH;J(151#N!C%]%-!%112XI'TH% M3%4KSU$>;6#"%!9>8Y:B6/#(U/>4$CT@\[W"3N5-[__>M&XVN+CG"BF M=25Z1!FCBO0MZ+?[_?J)*X;7/]P3?#_>N.4D$PF^&"2UA(E3MPC.SS81H$" MA!$!]P+18(+7NJ^>^VZ\G9^= F\[2BW#^_;+WQJ7_34&!N, *%:>462H1R$9 M;[_\[11XVU%J"5./;A'\]4/;L8W!P@$"3<",$ -[LT5VX^VO'TZ!MQVEEC!S MZ!;!SR\;""P'QBL%,-8"&>LI[$T5W(VWGU^> F\[2BUA=LPM@G__V#APQ01H MC!@(5"%).(_X^[+%=^/MWS^> F\[2BUACL-M1:@GS)&X1?/JM\<:3 !27%$@BN34\!!32V9.??CL%WG:4 M6L)T@SN+]ETCX2%4&38. BF)HD0J$T)?*8\=_8!WI\#;CE)+&-"_1?"JX4%: M2X'1P@!C8)P-,0+U'JOLQMNKD_"[=Y1:PJCY+8+7S1T66J"UQ0!ACAT6 DN< MSIY\?1)VR8Y22QGTOH5P\:IY =,"9>MC>RR]5(X)G,[QOGAU"L3M*+46X@:? MF+QIO/,:!J"Y]H!H*IS6@E&:SC)YIM1 W^+;5NV4UZ??A(OY9,_61*1$]DS@;KV5 M5.H@8.I\PL<(QJ-UM#2!!*+.^/F;V6]1J:]6L>]5L?N61%A2U2>) MVP$T#G%!&(N[>39MZ(3U3:A(&E(Z@QI9D]%^\55&[,Q-JD3++W'9+,KX:=)L MM/XA,J2C[3"G1,5);X>YZ50M6'>X)!QH9JPV!')A4U]5::(87DAD_<35/<[V MFHOU6\.Y!MX(Q9 7 >KT9_!^5[BCI*,IC:+WBQ$07GEII39,][4S/)%TM'[!/YF.UBNU M4=+1O&0@>JT40!0_$ QQW5L?^$32T7;B;4>I)7W?HA>[;DBT\.5,KZ[5M)<5 M1 BM;DA9P8C0(0@H-FY(==QDZ1KA>9.72G09*F2]??/Z_9U]>'9=Z5DC]_II2#!N!%(0";RG02L.M4_> M#KH%QK-G>ZAHL_3O6\-YYYL]Z: &"ED)+./6&BJH(-G.1N+XSY[?O879N6AG M/3[]4%8]"AN:J^\.?UX7,DIZ?/C%&A@/476:5Z 3U=L@/T^K(_L&XG6KE MJ_*[,K[F" MI??!4FM15BI]&-?@>O+WR;CGU[T/G6*WG2'$[ X9C"[R@6B+I MHF>1>O;;8AOK'#:QCC1JA.2@XM!'M4_*[N7-I_B(ME.+P*/PM-31897>:D:L M35Z[=PM8!VLTE44=BKRT9#!ONF.E!U.=)YI:':'F]-*106->+B?3JLQ01'?[[9OK MSV7Q9=5IM/U01R$:5UY- *-28.D],;WYA_OHS%; QO?"DE-:Y.8CQ['+LHQR M7I8^HGP]^5I]UX$L*!U=4DV!"Y(($Q1%(76N7#>:TU./1))/'*K\J&>7K:ME MI9,*>@>\T1X&&*B ?;&K;4.3=P.>I,VZOT@3'JC?@6A7KU88"?,.'@P]?J;! MGL+?I&^ Y'*\H!WK!([KA \<",DH#=88IE.4K\I.8$^^0%;^>@66F+=?HJ2N ME]?M0#"#=<5,0+B6)@3HA-ZJ;N,3S#T:=-Q Y=YB+U+(+*&E5 /17[N!:&R MD4(#0Z(%0"$21FV5-OX4>0\'?8;D[2VS,;WI7^<^+*=O)Z&EAC$'1E2=CX4P MDF&U=2W4+6$=D^*8Y,DY-10:GZ*V>-6HD2\6 ICX A"1EV''$DTI_?0!V_ML@"E!2IX [ /6%)H@G"YCD1: 9V<"J03?X8THUO? M^^&T6X%9$1<@IG65FQI)45P$UU>,8J\#D"XP)Z<3:<2>H3_?>3&;+\IEW7?M MS2Q*X3*B;%=5Y"V0A#. M!3<(X%=2'UAL ?.R>E$*M%GZ'#7.?/V1CV"Q_TM MHF-8"$VU#EZF;G[3C^CD=",A 1G:P3UHL&CF?71;F8 M_&_]>>=DFB5AHI,;@H[SX-%%TA"3D+IE12KL)Z=R!R$U0]^X3F M^8**:Z D M(@!S*P1E7A">VOCMPW-R2I1,^)T%U[(F:_Y<%.Z/R32"=VS-;Z-GE MQ$S]V7SN%VDOON\P7H8DSGUGFRBA\W;X3LT+G +-78@*8H3DFDC#4I])-4"D M2]>\?71K/ UA!*2%/KY5<7;2R:!P\EZH[5#&2L8C!W!:))5MXCA8 M$U%[+D4KIH11Z2XH4W#42_D 1^(? E1M)"] X8J;R02S"5IRS(NZ3UA M[0-QWBO7#.?NJZ).TY[WC1U[2'H?N)$TDP M(EOYQ'O-:M0 R%!.-]_Y(9(\=.BC.87Z,-SJ-.303QWZLQ >63U2#. [MZ)-\!JUX791^\9V-=,QM)K*G$GN& MBTSWDWY7K/S=]O*/$@F@I+#Q'8"NZH],#4OM9W9A.:0JI+9"!TCY,)[H1__% MSY;Q ;:X7#T]J4/:_?@,?NF6SV,X*)VTRJ^;*I2&$9:W=>"W\FZ?" FV MC7TP3S89J45"X28. J_Q5'?[UH@Z\EQ:027, ^@$,GX>P'".FH0G$O"AV+>R MNJ3E'4!&<\%(M(RWNR5W7*SWI N69P/%>^SOQJ\KG=ZY&BFF'TL+E# MT=L6$'&7NG3")H9Q0Y6)J"D2RC6+-QE\67JWWK/6+=LV45&C@;34 J1$<%(' M:$7J:_+M2)Y7X]3=;,'AHD^:/A*G_]&[VYO:%WK:;-R*50#&! ."-Q1193"G MVSDYFT\^05Z'2[!S'<]Z7G"Q*.S?7^KH,IP7UY_C#JB3GQGT#Y'AW&"'.1W# MV4$T%PS"'FB$XN;AH%,H;/5:C7QV<)_Q?'&E2]\0\%E95N>E=<;ZRYO[O_F@ M;ZK/SJI3U%:W*.YV<94C$%CI,5'.6"13;S#)P#^+4XD^E>J^=3@FK<=PA/%I MLJBF_6;F)E\F;MF>RRMQB#:9<8!!")F0SOJ0HG-OZ^"'O\PPJ@X4*;E([/0V M /TV65Q]]--:'I4)_ZEX5?>Y[[CPTP8UX4'(CO#&/QY)0&B?>F1@X]@4*%J= M%(;XY@2',>>8)*G]>Q2*TW/"GG1X_/5:1'U0'%H@ W8,V*4 MPBC% >D1U=P_E &QG\RS%N5_&L8I%N7?0?B=1=UWEUS6HOR/X!@F@.$$ ZH, M=-PQ0EB*H.:Q%.5/SE^OP#(7Y=?0>VR!<,3%O:2J.LUU_#%$$ Y[9[:K _Q< MBO+O(/:>HOS;RRQS4?XU$$>UB$"D UK'C8!2R6$(1E&>HEW-T13EWY.\O666 M(6[XY-[?M?777_[3S^O3+5]."H+2L6WH?_\KJ<1W&OHL.-^Z;5FV>KLI((*2J##]AL MK%9=A_K),)V@!AZ2M3'B<(IAW!^+U"L39"L2G.Q"="DP, 5+B5?D/;F3@ M@;BM7OGMQQRTVCTY3&?.HL:! 1U0B.\#A :Q--,:+YZ6B=5'RU(&\1XZ2';? MVF&F9W:BI_>7K]I.95& 0"%+@6=..A:\@C1U]X0.*&.?>V5CO-%48[CD,QCZ MG^)>.P^^O,^/BUO\^]""=EY=RIJW_ZJCYVK;7#)=@TTYC\-?R:^L0-WN>FJ+VD9E#07R]^+K[X.-^P,J4B*<,R MM6GS/M;Q=?>E6)E6I7C",?E&5V1D=A M*L/*] 3>^]9-=7^P7V>EU]-J F_C3R^K,R/_27^M(R!6*PZ<8CQ*C.,JXS[: M%$8CJ.*[A_7(ZK8=\&]2!S-P.OZ2USF)GR,+FY.P%OC@;=4O.U3]LBW -#C" M!/;V6),"_*V8:3C,4&=VL>AC!0N%D 'YU(4=ML7V M;:A7$F::&C2X->[CN7?C(DX ::O$!.\UU(0BZ7UBC>G"-LJRA0J*K&RY"R%!)H7>J\C"=!?5LZLA\73649W"1W8]=\ M2BJ/?8YZ%SV;3HL_H@M=_9OSTKO)XNVJ^6]M\5$02/PBK(S&'G4&>"RB-X(- MM,E[F.::RVFJYE$PW]3HP9UU+ZXBT$^^O'Z0:[ I* %9](EYB((2DBG"E=HL MPY\@$ZV)XS0U:;#$FUJ0OHWNW8K[B]?S95E'U^\^*^Z/ 5<=9?7,W7WR=J+- M9+H^ *[_K2MF'ZLWIYS,+NN#EP'9.Z/@&ISC,[[T$E6LOP.Y0A;?@!9 [^\! MQ3]X5T1?\2&^SK:IE"0,1-7MF'WF6FLUACH0 +05#!$H35& MITYR.7Y-39-A=32*VDOJ$65811<6:$,J"J "(U@FMOG57;%7G9Q>H[JJX=1Z-.R6C*T?CEUC)^>?/P MR*3T_UA&O;]I6]5AA"@18E'5,;:.2ZG$5I5%]O&!NV%]X[Y$8MXRY RTGL7= M FQ_K5HA9G(7MH!W("\@-;5=JI.8EYRKT_90%8% ,>0 (2XNGY)2&E+;[P=3 MG:?,\N/3G%XZ1M*8^=U:W%$+71&@C$( 8DTI9AP*G#KE9!M1K=88R9H3SVJD4R$C)L1+LCAF6?U^V^^_;?)KZ,@US=O/5??&LM6@5E$@=JG0UANR*9STNWMG?:CU*U>EG*J5)O9I^7BWDM =R^:Q.& MXZ*-*"!(!8R8B@BSY;4UX1R'OYZ(R"Z5&!I>&H8RJ,X#@6R!CF .)%2HNB(G+-': M$+)5^>T=]*L1 FY&J.>9IT?\* UP?JJ0?7Q@*S[+9XZ.&=^5^2),MXK M+7D?5O=Q7FM;47WS4',T] %"@"BUU:&P L9@!T0@7D'(F4N^T_<"&K[R-!]^ MZX@^FBD*-BJR5T!XR;!FRC.9^I)C)YBQ,L;3<=]<-5+(^= 9W56Y]8N%7M1/ M^]D7EZ7^?#6Q=QV*'LU$4 P,CC-Q7'A%+4_4:Z 3P*$.?Q)Q6Z26<>+&$A$J"#P$ Z@1 +6".;HD/,R-3W M](LY(/.]PDW:DFTY6Y0WO_]Z<8^ (X/BABR[JC/W]D^7 MQ9<7ZR>N&%[_<$_P_7CC-B%))/ABD-2R>)7-?6G=9?UE49;%']$Q.M>?XV\6 M-\VI8J =#\ K)!V$V#"2^C+6+OC&]SC'M063\-*I0YG\R2*\+6:7B=W)]H?Y^TW7D X0,!BC@,H$/8!QR@MJG+475 25$ Y?ZQK3%,8ZH& M6G$'M(@$SB4EPJ7.4VJ!,9;3F(+CMN(B0Z1Z:$?Q;JF+[]EB_9YUI5 PCH!4 MC 'L**&*^A!7T]1;30N.0[F+@[G=W$Z&RCA#L&P34WODIQ55IF!^.Z+#1.V' M,_:$"@P0]\&40<8OVGL(5)!&5X4CB:3/6 F>"*\?2 =ZI9S4=ZS:E/G9I"C? M%0L__V]?%A^***Z+R==/D4W_(2Z8E_J6+#G_Z(/]RLOL8_>=#,T6H: M!8"8CENHQA&WYH!"(CVWFF"OG[(MDR Y@/N1@,[B4%PD=&:[P?LO?O8N6EOU M)P]F'J - ](&!91T&$,K$35P?V7:$.B042,P$\%5IR[N+[@/;6IQV G*8JY6(BX8723>P5W+NW MH%+R1V_ J\GEU<+[6?L<.B[N5[W'HZ<8YX24YEHPY?"N.C48J\AX,^0_+VEEF&T\#'^_E'[_SUYTI\'\J)O;7%]&5K M8WJE:;3LG8(.6:H139U_N"6T\O7%MU1(YT@" M5>591/M;:.(<(YL9"QV^4M\HSYOKM$+,L!A\* OKO9N_CF)X,Y\OJVX([Q]% MY]?GCL0#&*2-""L[@QH!-*9QO8O3)C!UO;BG43UOM<@D_0RUNA[/^LULX4L_ M7WS4"U_GW[GN=8I4:5HH;FM$!<-(\)3SU'JR/;K3T)=,;&0HBO+1?]8W]2W$ MJGELK<>/(VN^*N;C/$ B.BY.>(5IZBMXFQA.0P<&239#-8&'JU5G5R@I.) A M2("94C(N8,3J'+'E!I#3X'RXC)O$LRR9B>>Z+&\FL\MU7Y6$Z8E;/#E)CN*N M,Q@Y41%K8((PP& EI$',V^3WW0Z7J!@7+Z \]D C8QB77D",L\[N*!,5^SC> M(U&Q5ZK/*5%15-%I31 PQ$NBD-:6I\[2?6:)BOW<[I&HV"OC@^6FM:+ZGJBX M!6-[):EM)>[#9:W" "0G-%H[FDC%@L')=XEGEJB800=ZI9PQ%:B1$->:$E G M#_3E!%CH@%%6 !B($#!@QC:S6;?(W-@/R[&F:_13VI6N,0(?&=,5W\]\G6U2 M3Z,EY>2ORRK-J74BC7!/W&N-J&(^2AD/B=%,B5U5:@">DU*KL7C)N%+=3N%B M\O5QNN79YW(R78._FI2+FW;<02"@7+ MA^=2'Y?W,9[C/5#?_]1L@,0S5(WXR0=?EG[=@=R?1\6= MO_,-6*K23T0Y4)PS$9@+Q*?N9],!Y51T8+B<,YV!W"Y/ZZ(4#8/714=?(AI'?%S+:CLG%7TLY:$(*+WC,D-FQ7TFE/ MUN^1G![Q>THY0Z+$_BD=2D.@H:0 4<4IY89SD7X#>/X)-OO;!9D0!1^QQ$&1^.'S"A55'[R M9>+B@^8?]$T5?FO3,B$J'R08H 0F(##)F.16:Y^ZADHGF,%KT,:#-R.-]0P- MK,JN<0&0)E7V&"8XO>/1!F2TZ'P2KALKRF#9'DN$_FXF&P&H>@;02" M00 I MHYR 7BJ=33L.&I,?SF>7ANPLUQR70V[!-(Y:NN%DBL-O0#E, 'X .5TT#Y#L M^(1+%KU?:Z,_A+3'PACM=?)\LS&(?B+(/AK/O0)-'JR*LJ;_@>\@-8X[5],C M 1AC-?"<(L]#H X]:0SV//\ KL 0F1=I!9;A1/"NU/'Y5,_G[T-M&+?7! H\8TR3Z(Y"DWH4[P9S.CIQ&WAD.BA[B:5?U5D29-N@FFL/LT8GH*K+( M.L.6O04R7O5M)PHX*!Q57%/O4E^W&(O])S;N@Y'?)^(7.G2_^3M-/[' M-6C;/$N/98Z@TP9ZA^_4Q7U5"*"9P5#%E5BIU+4DDH$?*UXULI8V#DD.0O:A@V%= M=?AJY!B:REC0 %''A<.4*)FBZ=K!2X >B.LG"H<^+?-1ZDUVPSCEPJ%;"/_) MPI/;2VX\(BFV0'LG >/82N^LY6JKRZ6')G#'PJ')^.L56.K"H1UU%%>V/]5 MPKB@28Z\HEX;MUUU@.=6>W(+L6]1>_)IF64XM:CL^7?ZNE49+;) N8! P $S M+)T./'7PZN'XW^9F.IB)#&&M6RSMY[FM:#*%M!XC.4PX:W]F.B@>(-8<%2=[ M42&E@.;: &>-IBC^"KG4>91CD/Q$U&HDCGNEF8';U=K4K%&QVFNJ:WH4$L"4 M-D$[X[!(74#X$8!O>X'?GXL,MQSV%\3]-&:N7]E;YY1IG\@QG\/L-@/49/- MZ%@XSK"PC3$W3@20!B/@0ERL86#4PM3KX_/1VREMKW49E#7CWZ^*"=V MX5T=5ODU$C+_>/%KAP^($)#8,T")@R*:',C#U(DCO8#&CR<>GO-&4=]4A.5P MVGU9A]UFUM="ZD0&V>7F-XM*_AK M$WI^]D5/II5)_+HH?X[_=K$Y+R4U,-HA0+"5 DNC14B=#Y%K+D>HO9E#A\>@ M%#GR]/>>5S%[7S<(65USO;^!/'^_7,P7>N8FL\O5Y'^O&D)XKQQ +K@H>,> M432N%)QBHA#4&!]-9L$.\_K^$AQ:68YI]6].K:K<].E*KZ<^K]_W^9M9W/8F MA?O-UR4IW=D77^I+7__R)[WP;;7RU]N@J4C2@''.%3'&$90\H>18)O_]U7H6 M:IZ'7UFF\T_%0D\?_KXJC/2N6/R7 M7WSTMKB<3?ZW)?O9$6 H58 RYPE$AB&8VOS*-IEO[OTX#K7(<,R<;6*K]SW: MF>N/JK]##7.3(*")]8#%[P16V)/DIMBX,_S^9AR/ F6H.YEOG_S/6CZW^V0C M[8A3H)1S #M!"$,BK@VIKZB,-;=O[A4Y2J7I;&]UC"_'8R/RUD?S(%1EY^+< M/%#0&D"XQ)I#"05)W=UBK+E]?SF.06F:+P=/?D7IS2Q^ZS_IKWY>[7 S.YE. MZKF_](L_O)]5U[27\86[.9NY5R%XNYA\\55=O?F RTK#!QU\;2GQO!-=8+H; MZ0Y>->1C@(\5'F-G057+)!KM4 3I *($<P5;#-::;T.4 M QK%5U\X!)6P$FJ>W*O=%MQ8UXKRZ4[#V,["RZ%O"-W.[FY29\O%55%6U2M; M4A5,55X@+MK 1'D9)V3UO\0JUH[D4-EQF5@ODDL_PWEX$U5[Y+<55Z94MBY, MATE'2\';DZHP0.@'5 H!*3"&Q"^:>,(#AP*EKO\]KC(\D>-U0%WHE772*GW+ MV:*\^?W\;+V3QDT40U6YNT$ 20,!5DI%-,>&JKYLFKFW?[HLOKQ8/W%%]OJ' M>Y[OQQO?-4LC^V*0X%(WFCO7,^UT[:O=Y=M$Q\Q9![BR%(C@JG+R2@%ON9\C@F>+5[[.*Z>WAU1/1)UHPX>CO-@#@,6&'0",Q*2]QQ* M.H$#KI$C:U*70H^N!CF=H\>3J:M^GLW$^%TO,U"9<^]_#'=MLSQZ27Z:Q-VJ:B8UT=/&;=X @384 \&11HI' M<9EL&_UN4+]K8D9JI25X5S7:BYWQ/(Q[H/5YU%H6$@,7ZG,NQH'2 MF (B&6+*6 1IZLNNVR'[9A5H=U[&\Q+.KZJ$KS>SVQ[3U<'I?.X7\^I:R&JM MGDZ+/ZK;NNO#*\B!TY(#H4T4%PHB>MA8,N@ILR%;F&]OU-^WQW$([\S=2ZZR M[XHJ\6P9[4XS]6L9KTW)0 SC@&!%0'*&@@(L5@'0Z2UJ;O![0#ONQ(FIK"I M;2+C]EH+[=+'#]>G/1$F L1Y"H13$D@NH],2]P]L"#%,C:1IF]"^:UE"ZIH: M)C-I6&T>G+G_6"K1IV2Q&BV>FL8%I[EKXD_Y;0OFM80NJ: M&J8RA8$;L1'$@>%: .>C44JJHKPAVYKU&,IW#1I 38M3.3@6VWZ$UR:=UM.] M1QZ4UB8 Z5GTH%S@\;OH2YE@A35<V.T,_Y9R!0[";X>AC&X'M&!]& M**[*)!A@C>%4>2H#'D=!=X)]+,J9667VB"NDY/M *KMM1-DJ"Y2 &$!EB ^! M:BI2I_(-P?M=2;,RG*/>RA;8=XTRXS@'#:$'E$KCE;$RB*W:6B36TN/+)G@N MVIJ4\2/**_C@2^L?QILU5U%^7#(@JTI'S@@OD:>(X-1NT$#(WW4U-\\9\@JV MNSC8%8.B(!C*HR=(210614!J):G46GMRB+278\@X>"Y*.9#5#+D'NZ%^'.JN M@I6\"G +C3&04@F '7(!:ZLX.H0;OA19S\\EZTZEQYDR(/89CK=$74,(4"8(""H4,!@PX! PFKEF3 V M>=G'/;%^5]1LS&;(E=AV;VB/OD=VXV;$?0"&.0N"T,)(*+R@J;MH[H/SNR9F M831#/L4VF+LB]! 8K_6JDJGB(H @&>3"(>R2A\+WP?E="[,PFB'G8GNY;1Z? M:NB EL@"[J#A7"-)D_>SVA[==XU+R%YWIL8A2EGJS9*.[W19S>J+'Z.FY=.C MCU?<KWD :0*&@CE9>P#1UH^&CK7)9O]@46*PA M$($QH#!2 "FDJ-7>*I3Z.M2SKW*YO>X,J7*Y/2_'4N5RLP]G+2<#-+82",@0 MD!(YH*BT2",#@TCMBQQ%Q^=,'#_1T7E[63^?CKA/S^E[1^<=.SKOH";CM,;= MG>/GI+_Q[39 ,AE-9N8U,!PA$ S6GC/(B$J=#/E\]';'CLY'J+;;4GN CLYK M:3G)Z[2W"-/Q "#77"!GE0ZI3Z2_C8[..W"^8T?G[0G+4"GNI\F7B8LNV+RM MH*Z+UJV$\5VCV%%G$4*0IRY)_@C :5MM^\LZ0RCW#DQ[]&BU;UY]M7Y>'>/?%O.\+0"F8< RSB? ZHZ.04!K)8%#BJ!@G&3N$'>R=IG# ML81-#G4BF(WO\>H.QP\N_&*Q.G"] M9A.C!Q+#@0/MHLD)J5:*8HZER%:2\BC:P.6B??L^<-N*?^R67T_A^M;[P&W- MVRZ]OW85^@&5 G(-%(42,!LTP=A!0?.WC#S./G"Y=:%7U@EU8+[X7-[W,M,8 M6"_C>L<) 89 #02SFE,AG2-]%[5NF\!5CUO17'UW3^]ZF"-K'[6UO(O]A97! M[7U4A.+34SVL# 5!^RJ4&?UTY:&+,Y8L:*R(2WY=9$MHSUP/"-3JOUI+>V#>"H1J"N*^BD&( M3A"B5%C&LVI4-[1O1Y<2T9.S18F?5T#?^<6M)Q05F55ME1'E59G$^(5QB*&# M7"6O0]1$\6WHQGY"[S2$\X19&]4Z=%P4)]I,IG&,Y/<:=QTM92AVT$P3!6?O MRONXV&ZD.QS.@8;1H$':<2 N-XJE#0_V(!N6HO=33JMC+ MQ97WBVJ??1S6>3!/P1R(+U0 7%)#&22*;YZ+=:2I=0XQ5K0T(:&/TM72R.Y8 M(J&UM54]Z'UX/9G%B4WT]$,Q7[W-Z]FM9]S(TJP<3T_C4DGCCXAZP8-"(:3> MI':$.';L-*52M)VA9B(G1UKSYC+^< WWBTUX"$M@%(WRL!ARKT5582!UFG,_ MI/&MG0RK4@[QY[C>LH9WM^\WX%4);X*#(+V.4\<"*$TT0 XY:@DD\=7)I!T= MD$Y2.U*(/\/:T3KSCO)T#T0@A09:2Q475N*C^2^)P7X,.^P8R@]FU)8<='1Z MT4?A/OV.QG6@?D>'=*$V9_O=B?KN1'UWHKX;OL]RL_IN^'XW?+\;OM\-WV_9 M\+U8[60?_>>BK*K6OIE%[-\"9@LY"CZ5*GD"Z!:[!Y\'VRKOEU+\//:.]O&6AU61C'@/M" .<4(,#P5ZY MU 7F]H YELF<7'L:I\*9*3JT53TO%[^?%[-Y,9VX>BZUR-H.N'WT"S1B"EBB MN1+QEW%QWT;3XA /M"S^]" ;OW/T0UW*RLYWD53N*2]@M")JJ3?1A6F76UD[ MZ\0A;F*EXJB7\@$"/A#Y0E;KIW; "VRH58S)[>H6'!7I'3>N#LAYKUPS.$/K M"N2SR_5BUE8+IMHNA0$FVO4 1Q<>*86U(JF+R7= &<_92<=3D5[(N6YN57A> M+N?13IK/;^&U:3HC%!C)&<""Q8ESRJWNNZ0S*.^@#="I&P/I6S$Q*UJ0*#I9RC4G ?*!6W0.D-!D@Y8PTEP9O4^\,(E#]Q M _M C/<*-W4QO:I"JU]=">C8IBA$P%@. =-$:<%9G.E&!EI'<*WY[ -4R-U? MTD4Z,27V\'7PZ<^6Z;V%DWJ-ZN^ M[_=FMO#EK+89]+0=E-0(:(,L+XMJ7K[[:Z=)%"[$*CL;_5W'2&K*V<=:4$5E= M\;1 (L&!EXPA%Z< 2>K[M7O /)BJY#N]S4U6!L_L/"K_^_!S4;CYV:$]261*+/8H!/XZ\N?_:S^O[O MS)VYZRCOJDU=E6?VL'GKPY1T 8$6AD1:H9:0"H'2WQ?8"MD)*DL&2C+L5G?' M3ZN$C+?%O"5B'X!VW@%]U;6VHOW^^%/D>\]A9NMBD>E<6>+13DQRT5U&/FI^*!+/VLD MY3'%@*SS/)TD!JI L$Q]9-./Z 2U(2$%305AA\QAVB];?[& M$0:T51)017!T++#V,'7^Z3/)9#(POA'<$\!1,-X'&WSZJH GELG4IST9,IEZ M*7H^F4PF"""EC]]9Y@-R% OV/9-I9[YWSF3JE?N!DEE:,7W#F4S]'.V1U;*5 M@ ]%OB! $2X!48@3Y0RC9*O=]ZA('YS)E)[S/KD>+I.)> &,YAX8S RB'BOA MLYUT/(=,IGZ>]LMDZA7RH3.9I Y >RP "L(&8XW3+/5%GE/-9-K*&$C/RMB9 M3*U@OF J8Q"0H;8>R3 M1Y#'GLFT/5-[B^90F4Q:QJE9Z@&B@CI$M>1ZN_?KF60R;<]=$I'EZ(3N/Y?> MKOIAQN^GOI;FS)U=5Y;A_]:?;V(,CE>N(@=&.19=!PY92%\OX6EUY51:D\;Y !"05!GC/%:,0 M10U/W>UV!W@GJ$"YR,E@AG\HB^B\+FX^3/5L$77\U3^6D\\5^)8*,C!$]:;, M &5\D'%A%(BGSE/HPW."FI),_!EVI78%]0''W38P$*00R#@A'4F=ZWBR"\,> M(AVC^GIOQ+Z:]7GT2RZ+\B97*96V,?+F(3PYJT2I"*]FB\GBYK>)\P^&?Y , M_>IK;8U.;Q.A._7,1P-7*^T!@=X33XQC;JM0Z0[OW=Y@TR4M[ IA_O(FKJ%N M:1"(!'XI];QF01CD@JN.KH#'A2;(I1F:])YWB,*3W MRC7U^>[KHG Z(EK.7#GIB@H$$8"B0@"$ K2$(&7A=M? 6Q\_;G)$(KD72866 M.I3RKIA5H#J@"%6=&%H'#!+!!0H19V0K_AX_]]D3-T!,R5^\TL^O*C =U]6- MB=I#,>"04>D=Y&[+R@L;#W[VG T15-+&V+>AG8[(:;! USDSTC,9J \.;4?8 M09H@9R)K7P%EN JWGET[&,,#T,)B0"*0Z$G&39NF3@Q[!. Y,SM!9U&4XS)%,;@8[;:P]S[0?^2^U>"O7Q7MW M_:(24'0GS-2_FBVOZ[S9ZJGSQ1:'V-OZ2-6(\WL%J\;=\1I=@@DD.J]>12C. MS+QF/4M[+.OKK&D1MX\Q^C+0SDKK+>@N@;18R1#UOG7K MCZLO1L_]O_S3_P=02P,$% @ HPE'7>2RAY8[ $ -WX! !0 !C;W-T M+3(P,C8P.#,P7V_M\_>]NWR^/%6I^E:M>;VKOB**!\4L8-$V5W=70$)2 MB/ M_ /$WX"%FPX1@D. $ #9),3#@#,@*3&_S7]*SF_24O.?"Z2EI:1E%LC(_#9D MY>60(2LC(ZD%Z\0,70:I.,ZJX#LDM/JEG'I!?(&6TN9ZA[=8/&-L&G8N45 M-#2UM'5,EBTW7;'2UFZ-_=IUZYVWN+BZ;77?MGN/MX^OGW_ P4,AAX^$'@T[ M?2;B;"3QW/FXB_$)B9>2DC.N7LO,RKY^(Z>PZ/:=N\4E]^Y75%95U]0^>5K7 MW-+:UM[Q_,7+GMZ^=_T#@T-,-F?LXZ?/XU\F)GG??_RH&AE8S*IEVR!TZJ+K6.D5/;G%Y0SI W MLO$"U8-/=2MH&-NR37CSHOTFV7].L-C_)-O56$GL =V,6 MX'[O*TL,0.L2.;4IY$5B@*'6:/LU2*$QI_^'3WFO[;I'!X(5 G!A9VL&MIT< MXG[,,A(#^TRE/D^GT<%(;+-?H^7DJ((8V$\8Q':,5BUHC)VRLUST9;;"+W!; M:%,K#0TWR0P/S@QGNA\X[*\_ M%MQV(^F5RD:GRX7T1?10VG 'K)"(3"0B="J)L[!\GAB0[A85'H L00%;-X@Q MAM$;#OS,G\2OZ^F9/+CR7C;L]+Y%:5'#@7 CE4>@5 MW":60(Y[S.+NLZK$_=9[,W2D%[:Y#6M]DO-7?=.(@GLI8%#710SH3=>C,)0< M'1 V@"I>0GWI"[6S8D"==+1 \2G)(?3,E^JC=KI;KE2NNMOY&GM M&3*\$EHQ";YO:6AXK+?)&(6ZSA,.1S_W6D=0)3,QH'\7TP-6?,?KA>7+!4OA M 7=VJ43GI^J[1643._<%0I;;+_I[VG$?!F_H.H&=6W]\E0VQPW1CQFK4R'TS M<)A/$E6* 5:)& "W4J!5]&@Z*Y<&[L0P[Q+2T*A&ZUS3!CM.U XI?NZYLN*, M_G[BC1_&JRR-OA^J/6I\V94]()W,IT K+6/HK#*Z&OU8E(\^'E8(9V&'5/G' M>JL*29:TEW<.+CQZ*O,)5767EID.]\<)"8J[-A;P,$;X. M ^ZF,+]R*$(U F= J$H;J^6F'.'-,AJUP39^&6LT:5?[HP%/?-01&:BX_9=A MCD-%VZ&C:QR7&(4;UW;A*K!<2\0$/,0MBLG]HU6R4P<%Z\@CX\WGW>(=_2-+ ML)S.8W(A/:NX$8KU^/ U_8%^.BZJ525O3N;5.(]+G=HJ,3EKHD^B9@=$Y.I"<%>#&G)&?:KJA="SP0-QKS&IVQXYJ MO@EY!3Q(JYX5JGGP-R#W9\ ME,=G2P4X_/E'>1S4 N+F44Y3LMEIV:3J=787 MZ@._)I@K//&7WN2Z)B_YZ:\*;#Z%$4AGW1,#5?W/$!$R>6BAZH]VQ!Z[.@/Y M+M FMOZRWBDGZ[="0SM1>VGDALSJYQE':E=8/TQU3'^0I*'5#_@15H5*S38F M"Y\CMS>81(->4KRK[>N/M&*A%4>:ZE;UO_ /LB,.Z<<+>,=QP)*Q0AC#!0 CE"'>(+F-8-\5 M1)%RFDQ M:*AU7/E3C:*^/Y<2M1ZT:.9NQ6LVHP-;Q:<;#\Q%O MCDVD,+9A6'D4T-=S.2SW"R'J G7A>3@7WLQM+Z$3=&F_?*3NCHI<=_LI?Y-D M__TY0V.Y%SI6+S"VNC?:C*?4T(0:-OP4A)" =!KY/ :_I-1(.VF /SHB"0=+ MH#B76#Y*YBC/Y/+WD:&6Q]K'W3OKY+5*!(%Z!8I+ 3*X"Y7HQ>1B-!#ED016JT3B)4U>1&)T2W5=EX1BC%S5MF)/Y MYKWA20U].F:)U1X)&:N71^;[?0XM<#=,/7 YVZ2CLY_,0,()2=4K?*<4$6:. M5"/"K$$<'MMH$T#:^9C7%OL"'.=@KSPXK7;5>556AN9@V2JO!NOAAE.)Q/%= M-4):WQ6;WW*Q.;4.U3C2>L M>4?06&N4W#,9F!7HZWYS:HOW@1]Z:T;?HF+0BTA8WA%6]D6G%5 O^VX1JQ/7 MFJ]3_L[.4BYLRG,D:4.KO-D0]IKSY]:][:S[5UZZ+J!8.TF*KM!9Q754H1Z> M,SU4O 7A/'8X@$2I>-M:5]P>5_3)@@TW5=%>?2/,9570E\/UCS61JVE0"7"]5SX87+1;D45@:E M:F&*8#T)"YEQIC7Q.AT7"P:8%"01W_9Y[''ZI*0K?/K>B&=E#2"X@SV? LO; M(YI0A[LHH,\H$^,KRB6KD21YV?'5^FA&MI-1[BZ>CXH=JL M>E=MK6;[:I*+X!C\!@DK_U$-"J.CT414+@:"T8.O)XN:#?13MH.H%/)2?SMZ MHM>P0/_8M^7^(Z%>_H[##SK3'U2&S*JM?.C61P>1$@B9CW+=>=/\=SRJ4*47 M5C@-VF\!,>U=BH'8D\4?B">L \(VJ[D?BAFSV=YX(-;E25KH;2L/#8[D@>W1 MZ)+*&UF:^-!W'Q5(U9$K[Y0W&4O%3,?]M ,UIS01WP A@B ('@E",EGL26& M*,]N]")%E61A:53;Z^AJ9^#$3/6G6>^R_6H[SW5]GSG!D_R!<3Y MNND@=O023IGDS+:$+&2G#G7=)CE#WB6#F+0[CZGC3ZH2O ,WN%^C/%Q=[K=, MUH'[<>/@UL EZ/W(U+UTUE.*#(5UK=$*1#6;C5X,&&TM,Q!N3*=Y@H0$0E'R MI"YAM;-:YU.]J[8?VU06O+K^D?%K-;D3E*GF4!=#FJX\5&J#H1B0@\NC[C!. MW@_%$ *+BO_G+!+RRS51<<'H5OL;MN#[4:^\;AUL>TJ):G4_,]NV4NWYCK1D#G/_JT4 MS-&%:ME-%-"--IC(3W[;J(1]Z,>XP%/D-#X]J233Y"%=NUDZAY EG=9O:+'G MX55WVY-FMV2)LE/QZM 1P4I$7A=*. %:5BM4O\ NGI(2>"!?.0LW"+R$9M + MOH>^:GM-Y)H?HZ',S+[.<,G*CE451J+;6ZAJ&2\35O1O6H;XR ,6%3(; M;[,<7OB-06'=SI<695 .IV+5YWM1DIO:X:=[@QZRJ^:$=Y';B?N4J MJ[9%RZW7Z$G-!"<+G<5 ' G#NDNO'D7R<;$84$$*=BY=1PR$7\ PT4TYF 1" MM:4/1!4&VRW9W%[@43->OOO"MMI!TUKY+Q_I$3&KG( M/KQ*P#KN#F *)W^=AA72$0*G153N]:4BN+S,?560&A@4H^-> M,CFM97"PY.R>9+7WN9]/27X#9()+HA+YGM %7AS;;:J3A4U$5VFV:3OBQTIU MF_EG1RQY>RZBN>8NP;BJ;<7!&EB;$YM?:I5XC5K901<$![[48;B92,1?)Z+X MD1#OH$89VW+!\$3WT1S7PEB/HRH#+5Y0C%'H\*<(_(N%GY8DH%<\YT1O.#BO ML_8S8D#I:X[K4\$VQ&AFL FDVK3^XZ1MEU;'H]R[3Y.>_EB:P&GO7]&(RY5W M.+%0OFQ #$2+ 7TG-7(O3I;DP)ME$2YS29O8ENI'DR@%D_S<6*SBH5,/I8P> MR+BZ2J2_RXP.67*0_$X,5%";Z,,'61;U CMR=Z,B=1^8?2DXE3"U/<'>)\TE M8]W2]!/=6Q_>>G!/^OP/W&*$F7V.#@>10H)'?%2#^ KQJ=BP]Z,D2ZQ<6)T[ M.%5'+K+[67/X1T!U8&$9J=?JAW3/MQ=&UE9:RZ(Q6TO*WM DR0.XJ@0$,LAT M=@D.XX1^?290/KT2+GID>5EG;6./G1;GYIWV-*Y2!8VF9WW%QB/M@:H\7 M(3-N$VOY7YZ);ML]=3+W(_:8.6!TJY!Z%)8LQ7$P\XHAT2T-MJ?1(HL,A&]E MOWFK"Z=)+E J8O2?\Y_2I[H1WRN?HPG5)L>:YR(3SN#7V78E!NEU^\A7!QK3 MJ3NBMO$_DJ[N?;4"'Z?8SCNVQ**95%[ Z4K#@$&CP[ZP_+KYUB$K!5;0Q(,# MSB#Y\O5D$PKC00V2R7=^D.+LS=>!ZI5%69DE4/&6RH0U.7XDUQQ2MJ*V MLX[M6U.+^P7.6P6;+TO\1,6) 3R-B4%*<=SASZ)*2_*J,!42%CI4_-NZ+N5YN,*Z:I;W)6+/'%FE SCW>\]L%Z3]!97(\RIN(8MHDP MU,+O&'!:P=!LH1A ;MMI6 BO_E0,)!VOW7 Y.UNS<+/UR[==:H8>Z)EU'>MN MH8;HT(HRH5HM$LJQ)\@O='!<'*;IV86.FKF[SP[<[6"+%GX*?GIYWR;;9J\V MO0-;_(ST_4X'#0L<27M3QL1 $TJ*1(QK\5V_DCC,8!YNS-GP]5M.:U" VXDE M5U@AO:^9.V17$M5_:2/*L(60MG3!?*_KBP2J_$^T)O$!_UL]#]UFUI5R_LQ9 MV*'[YV !L7?_K6'@U>LW>UFVZ58(S7M;7%"O,GQCO ME.7.J/_21]*=/$+,Q\D)F"B=4H[;0J['-F%1-G[I#!J8U=;4YLYOH3YYH ME-<[GNHT-EE.5#3.>*';8F1]\<19>&JG[%AV&P5RB"(OQ.'#QS"0B7U;O;F9 M<]^AZB<#EF6-76%G.S\^N&%\#KK:FB8%K:O.= MPM,C8L K:ED5$A5#H[\VC3=1!#)XW%Q47ZC4MY=F/ R_?1Y,(#)Y(K5T%/0E MJ"+[)D@@X/2Y\&*B+SOOV2OB;$=W8-PYVZQ2-=^,&Y)5E]+?=^D_/-&\*^_[ M]+*62S_(B^ /&' /'3+2%*K;L[N$J@)8P4/@[L*CLQ/;M4O-&RS'+M1'U=:H M?-@KRE@G;#<(77&R_'"";^86KU67FCXN0O6A+B$-+W7(ACW+'470P;)/799.'"'VG(WZUI:V8^S%'L\]#$U+(@?>>@N;X1Y* MI:90;7D@DLT*V9 1&ST =0=JIRB 9!/]J6+;20#?( M26;R+9ZLUP,/6Z;B_"XQ7V,JN#/*AW_/\'MBA;Q1O<>%LL?OWR3HQAB_SNBP57CT MP+'<\=01"5[E/AS$9.M7VH:^OJ$]KA6*F-8@QK9_[FJNF JW,QHX.ZSG-&2@1^;!(?)2"FM.B+4O\,K9IQX8)O3NH'JP>/TR@+Z:C-WATN<[QR7FL-^.U\8=[Y5;A#U(@E*B#!< M /<@V(/6-AI+ ;=1!O&<_$P63IOD^OCQ^O'6416L0JKF]JR)A^;#G3?\ERB] MW?O"]I-'X6;'!IM# +G>MXM611"JC?.WBZ[3PS )H^4$JO! Y&F>/2>_""^; MT&!^Q\^VPH7@6+&EME9%I;Q%!KH=Y%>O%EXR&(PQXM)9MW"UD<+%5#X'W@V78'!;X/@LYCG>3NY&WSM'U\+OCS.E7K7Z?O;T^P M#?'%(1@VMI7*Q]I\.1(>\Y,41=,G)[,R1@: MLCXFFH@9RZM,Z,KKXT1C[BJ8\?"PP@L! J$86R@'J,.R?)0HJVJ:.;H[?[RU M.S3'MZW4V;,JQI"WCS-Y5J/6=V'%%G_I@D_LLRQWYC,I>&&;J)Z.IPYB^5&0 M!X<^9#26\( 5Y1;$RYRY6Q9QQT71KF]%J/ZNAKZ3T>]YR8 HI)"N26=]HD(K M<-Q/ F5AL"C[@(@*FX].9$#W>[Z/!X!39\$7!([NI4>VTROE6RRX:2'$YZ[. M2=@EK%3+%(P2G55# SV1*,_F8@0^Y $TZ*7)HZ8< 1L3(UA[0&'^H2 ]>M0. M._HA=^XN(UWC---^PT^9UBK)FW?*3D6I"T5"$SH2U]$4@B5D;$L'O?!(D6G- ME^EI4&2;'_$"9^-_;EC^LL]QW\),DQ<-]8W/+MU]D<<=3S:M<=SB;.!M;T,+ M$^5@6$]P-<7)2%YD4B[AP)V*PWCL8F$0%%GFSL9!6XU[BKY_,C^]/^4^EJ!S MZ56+S"WMZ)V709D(9E TYG!)V6XEPL50'MX@IGB3[56 W^UYOKV'>T5E.+AFQ9)?O@LV8MZ*@:E?]AWRL"SD M@V4&H)6+J6+@,;Y%(ZO*"M,M5GU3F E) M^ZRUMV3)8R]KFQS^>5.I7QP14M9*T. N%&2?RT;P@5"U@_]^ONQ:=;93OY6[*GW3*?-/"=]&W&^?R[SV,+WJS:.+5^Y-8T#72W16 M&0W<28=6HI*01(JNJH,0ZTXS?*O.]#AI[9O,KJD[6^=27E-9Z[&N)JIP[29[ ME2"M/O?5S2?>E,,]NS:BH_,=$,/@"9!]"JSHQHOD?Z#RM_-P;6BD/NH>M].M M?X9C\*DV$_3CSP+YJ3>\L^193WX8[;E>Z*GXS??]PEP ] MG@[N-"?P?7B89EH,6@JWXVE/F1 7QO.\_^K .1.A54&(=_[11T/2*1I?V F8 M&Z\R5RG$R>OGUDU/M- MBWETX\J]UG+O,QZNUA+U?@D%<0Q:"HC$_WB0!=1FWTQ3*;X8 C:X:R8';GZB M@Z\5&F;M"M=T<"PDM:U('26J3UKAJOMVRG*R6RWC<)K?,*P?%$GA@5IH-\<7 MO&R@D;F(26R!$M**D(-W04UJZ,9>&85=/!+WML M3"_'\-W>R M:1J*=%*'3%P1N_Z;9?<['MS_ MMN'[Q&S%I+SVL7.$TW;#;=H)RR@6IK/EDZCKY+=U/E00!2MR>=F<6J'&!3X* M*N9U,)@B^!9-AOWVS(H(#^?0@6US 0PI#S5-JSO75]L&'5C\QJ$H+/9H$EU5B$ IB,HZDN 8"8[M-D"!M_-5\9X8M]I\3VM^ MS]L&*_,&+U&&9)!AU>V"[LQ]VZCSS1:.K$C:!\T_AY4653FZ\8S8F"1'S)$' M4.&R[NGJ3@5.CUD?W/_.[WK0GEVF+88OK[:L^&;&KTL&A AXCGU%TH'H8RAH M'86_%DIG6\8[F;QS="@:(NX/8_+S"O9B0P[M;@V(>Y)SQEGOPJ[,-,YJ+57& M70HCM'$MEDT;?D19\%M19Z7.'6FC#3T_JN+"ZDK!*37815DFE;YK=M+%]Z*+@(#P\BH?&F5KC(E^_$LT 2[X(:='6'4'6:'PD] VOY M!]_^=/A2[>ZTTLC9XG[E1)?"X(I7YAUS>.>UE]WMKSTVJT\P+8YL/CU?#,%P M2Z'Z[C%<.T8-?NZT&LH&%<=,1&V?LI-(VH=[==?F?PNLW]^SP.HV>.Y'$_@Z M^(?L]*Z::-TYI<)HC!SE$ 9)#M5TH:8EK(C(#JV<;NT:2FS%*3@ID9;V<@W! M$EY(94O$_=PU3W)ZM%(*SWT;R/;"&K7?-4TGE4X)/,YB0"P]#J/Y$PTYV/ O M0P\>"5?P3++C9U"*82^*H8SIS4_2FC]=G]#U<4C8I'NU')32XSHET/&AMU!M M:*8SJZM=V0U&*4.>O--8)%+\A2N.LHE>7UO!+[[*Q9M'!]=GA%^XDN^5]_I! M[ >_A;=]N1%J.V5_C(+?!/S2^39['F#K.AE!78@>J:VT:)Q6A/SQG]-J1(L7 M=]>41SW"/]C8$X[(GI+$RI"_["(&^HO"I2+Q @W2-MSU)LG>NR%2\^?N>#SL?@: MTIQNEQ&\=-N5+'I4B'A>G*B"PGI( [UQD(F;4*V^=0!7C6M"+R)YB;*KA_V' MF[)' /"FXK)\X]"/E]S/E L'%F5F?2C(WRIL.V ]+N4TOT))@F0%N^:?'R(I M^8G!.L27QX4'1/DSH_'Y$BG8C-ZF.M\D\WS=4A_G.QVW6\KW[7FAPS3.\%BM MZSB^9S,43'N"Z'*<F' MMK5Y6@7'%C_;-/PVS6P0N==3 PV>?2J=E8$V$*Y@=2W$3<[=$0/1QY>6]YYY M9?_DR9-3/+;*6L81PG[YL@>(I=_0(+M$]C2U48O"0#LBG4026;;?T>&!"^=9 MQ*=>NP_6@1X7?9Z=>G@PTSO:Z,K)YV5)R$U8E$&;=MH".NN1 6*?V'M(BVS5 M1]X@5.D_\\H#FS2RN'>5\5.\_ZVJC-8;7DL";+][-H O!R]WRKN%O/PF^H9X M-Q*7K#P/P5IX& =Z4>7"T(\3A8L\6D84("NV^\.9*%].;2L5%308EK.C(-QL MQ[*:#-U[Y@'[ODHZ'V_$?_/)'-IMZ!C'?]I=-1V# T]@VS"7,:"_Y>!I#A7I M[Q+7#S +H4WA[ \:^[:]#JQZ7).S)/Y.LN+%M \A"5L=7Z_J<:@Z]G[@)]4% MH#@A7N9"31 #&D)=!+WJ$.=S=3)]/TI%* ]&I@FE2J@R1"^LG%U>6CK>Y-DU M_I5UL2:UM3=*N?XCEM<>/OSB.I4\0X/6?&65M74E4D ?W#"N30PL:E2%KF[N MC:"JCM2DWONZ7KWMH>9SYLR/S]K&+OZ;O$HSE\>BG''5/W=*X!#.<71HN2SW M#MC!_P%1D(13-X\&2!A:N\$*,'B(JDMTV%%Y(?=IYZW0GD_F8Z)/?=;,I]4Y M:^G$2\DOY8Z$BH$C);=0X^-\Y,9Q"0@T'P6]<-&^],>S4XC[2;^$\EC3E\@V M?E73B[Z>S=;T]=79:W*M4[_E?V6NE$[$,$#(@!:-DH]QT' M!:VAXD1IC49"9YYF6UG:R= :G9&'LW,-=7D?/K0UEA(HR_*D>S0NQ"E7>2J1 MRK.VPKB9:-2[]0C Z8&6(S*L$-V!5R !H&0W#1D7-UM"RP;:N,X<; )9>Y)I MF=S@?++ =OV:W-O.XUV.4V^D1\/6, H]O&+R#^^\_/&B UD*6L!CHB ;0CM- M;CEDQNGC'1MQ3/8C60RMX$9V2T"*ZS]:3,S MB5KCU49QN'(D--F6366#TL_+EL%.?R[@LPI#,7J4G?V]AE8^IZ:C/Z2PV2IQ9"FJ#9 M6 15J,W@J;*5IQE=ZLZ<5ZG'S]:"#8T&3_>Y[B1YABPQ.[:[\T"YQPGZ&=6W MOE8";W(7I;8=2= R-TF2$ %T9@^D+@U'XY[1.+47;3]8?S;W_%G&5?8NL@E< MH/*L[B7HOC3<4>NC49@&[DMP,@#[4,+W:?*C1"445HZ!%A2!.-C\6LLRTE80 M2307(_17B@%.;9LYKJD07W-C?\;;P<"@A*S/OT*>/E%Y8A#T+EZK6=9*=&[^ M(9=P ?2.-P#+.0B,H3$VI1FK$G:/]4%W,T*FS+.Z>SF^4Q^W::O_HR7RG[>4 M=RY.>F6J,'5K1EWP#DGO\V_8X#!AN$MHT '4@O#=+#MG?T%E:N[-PZ\*%O4OS;_M^.(-4 MN%Q$=UUP"U*;R[BRB"&5NBE'T<,4=G%R52>:CX?"91.%BIHI/Q53,#\3+EP_ M5CKFW[TEA:!7VQ-RNKQ5-G93V6XD3B_/O^QS:1Y<%=,6TEGW-='EHMD.7!SW MCO_$J+JC>K&_QRDP]Z3MJI[;&RM<^=_;NU^EIM@U&J_4MB=/([@Y!O/X(;U2 MDSN_I*,%.N4))"@,X"=:4;CD[?+*O@9O'H9#2;0\(Q#I3,I?[K1KN++O1=@A MW6"__:*/U"46PT;*E;/,9%,I-A9:AV^";2&D(9/VA-ZQNA+S%[VSXP;/PHN[ MRB?66]!,WKT6.+K?>2Y8FN0_'&9FU;36VQA41I(.XVFC$B^Q911:BNRC98F" MYO/YB0^&CC*;&GJJ4^3-'^TW+YU<6,"Y(K/W@9E2S)6FGW;\=VH2D*' F;B< MWX XC3R%<+5XZMX M08QGCF^-E8$B_R\._ [''A*5J@^QA(#7 ^"8#FQDAW9A(JU7Q.96DI\ MTUUP=<^:V=@9CNM*#?_B=,.+'?(1";;6-I]B::-UIE*@%*SP"OI/?.=*/Z/()!?)S]%J3H;PJ_4=T6=R18J, +O,UK@=^#R; M,_VG"JNV9J=/JLB'Q(\LRU2Q,RY1Q'7O4Y,0?A!J@ F5CQ#M-8]6%G-]P2.P M_.DQ3/2H-"%@I*-90Y7D))#-/?XVB*GL.F>V)Y1[*.LS>?M#]\NNGX;\$ @+ M'F$-M DPD.-5CEN;@(Z XY1F7R>-(0(GR=8LOO<. 7*I^L(O?8%=D39SJ(G0 M<#M"71#H JA#"$"1&26I0:_ :5C11! ,M7!DF[&J7P)VE-W#R[J_L\N3X?0S M?]I?"HE8_6KIRA?7#!-Z3JV;P#VYAKB_"'&XDZ(X>A@*,J()U36;,: /!EHF MVYQ'\ '+4F9J"-I$='/ WA^,!6/"V1J;3<Z'RQ//S;I:EH<;OA_G M>F_OE@E\\.#<7C,Y W7S*TVTD1RDSHR+\B,P0YK\'Z+J1C3)'+'"&425#>O- MJ=$^H8>@S#%J"EGG67FX\L67A[*T2X\S%WQ//S28%N#_<:6D6]5X)1*$R440 M0V!&89RA'YZ&5BCAD.]2' ^P+!6(@5L3OE.4)RH\/G\8FF1>K@R0E[R6=E#] M_:J8YZ-/8F;]J",!B!_MAA-%0,5TY<)599*FV0J.3CY MFAMFDSK2='Q%GSF[8>O;JFV?UP5;C*"JZ MK?>FNT@NH>_TCX/Q!&?<^7FGO[2Z-N^=W)RKX] M^.+TZ1,M>RJ#Y[&BX::U "C/Q1U&*NQU-.C1E4!;W&"%^% Y+<' &**43L F M8B#>AJ3/XU!LOM9E.&!_BG MYE>T&\U0,90*%VI2HY$+[Z#WTT1V=IN^Y*3/-+;&!Z;&S>NMN3OS M*GZ%:[U:K2Y(1>#:"DRU+1W$6C)3^*>R&08HQ.BFI&/040'N T.]^DTF.-P\ M4).OHW/EQI:T'%*MR@NU504OA^^41*Q2[33]>\-I3"KI$!2'G(L8[[PZ_.N?8GV7Q:UVH^>T$E5M7\H.:MF[$3S+_ MZ]]$_7O\;C04\8=%Y4XJ,(->B4':DJ/3EPW52SZ$S?;H9_5K MO!*>]ERQ9]?;0Y4'O"\)WR(.H$GLX _QE@LUL/R;5_EGA4 MWN6[KJ8_9^U&"8V?=ZCEML1!EDCA)J M2(VAIE)X1SAE*3_+AL0 /Q3DI^+O00Z,D:6T;3@UB+H[J?A'V>&8++EWAYYIZ= M+EUA,NOJMMKS9^Q5,KC'WK;8UKNO?;TOL#,2$#D4TI=B0BR'6N9?'H!)D1!/ MX ,/TM1)Y^R;IZ6$WG10DT%-)&OP4D?2BX.[ M:2TYF76O:R)M;FJGEF=(+W1;Y@XP+UVZA2ZLVN4"J/T]_E.#O(G"<&[<0.Z9 MZQ)JZ+KWD]=0&#:84$PR1;I1HH500C+O@;4AF4"1/8ZWA]^]C?FA[Y'7.J?G M)J'[4R.GLM9$O?0H.I<]I8\43%W>YWH$02L(3T!4>Z%JY=@[!$ZJG<$N^*)# M320X&F@@Z?VDW$.N&*BJ)LZ*@2+_= %[&?8;?,SWFS<1U4R!ED]'-ZH@5VUL M1,K?9MLR_;#9 #'01ETXH>/ZX-9[MT65%51LK.E!XJ5]GZYO43QN?.CF3MD7 M=-#]#!J%F5_/V#F/-P[(E#T@7FTV,.H]<#7A:7G6&][KE,E[_!*U]";K@Z7+ MN>N+.D;!,XE3W;>@\/BVCNA&*2A[+T^E.3(JIY]+>%A@2:V_L6\M9A2W*X@G M.(&PLZP!(]A%(B-1>HP63:^B72;+"(^^K7+M=J,VJ.K9W'UPUT93(YM_FFK! M54_[]$)K["PW?:H/B0$R,MF/< M/^5Z$2=YS1?VW7BUO=K^[$9MP3EL4!\N/ M(1$Z"2&U5OH3Y/V J,I^]*R,F(OC!=5;U(^-HHF-T+XPV.2=B6#6WIIUPGKS M+:V]Y0YY'P:E1K\4)@/?Q4#RB)KHX0Q%<\,X SF -7ML=TM*5[RK6O[D^E;9 M-VT,/:0IS!7NIXL:G)1)JP><3/$XG0;M"^&%$],G34K+$K2-KZ0!"Y*D,E ; M8LKNFKW$'*?\LJ48B('!!6+@I]VMA96,2"?,@%#_]M?:G _9N1?N;G)\4K7D M./$=57O&KIAOJ2L&WAY_)08DJ% ?3I'^\084"3?YT.9,S,Y&6\%M8Y0YY2$* M"Y%0Q^GW!X.%_]O.%I=TC7DHUGL<[C=WK[M>F%G#.IF/O_V0@H3'_[]WMKBP:\PSJ/O1P7[S/:O>7+]PG+P[[5V/#R9&#'Q<;"DB M=XJ!@IT2?_"C[C\<];>I25#_/O]_ZWSGI W4T_RM9Z@ZQ>OX7=,[X4_TCN0\ M_>,D#NZ7XA\5 M:"+=VA?[$#$0W2$,!3'"6*3S*ANB_UPY>$N)4DX/.XB E2COU=_LUIG^? M^V_']_XC3Y\P0[?2OVMVBX&O/Q'U+HM&_8MR_W_*N7O_D?.>R:2R*+^DD8X% M5TGYL@>(2FE'((1NA1AH.@C;_N'(KMP%."CZ5SIO5Z9U4B?)3X-IOVCMLJQD MP+3P/Q[_@)#*?,M,14^18M8MO" &]FLB4=X?[5 6/_I]N] !^<(,*U+)K/?[ M,S3ZAQ=..GB6POB?E#D19DZ^-/GW1[>4D__*FRL=?\@:#RE2",Q9BIL3Y8J! MS7^-E)40L:5A%!JF8^%8?'#Y'P__TOLT5D*4&%B21/G*)X@4:LS036+@NUPV M3#^,J.O!7R#U+ZBEW\9WZC -]D1WT/D2%)$R_MW7?P327]F1PJN8A<@7"@C@ MW'+G>+]F\_2O962DWWNL7@PG;?MP2S+9](^C_)]8(%0J^,^7_[-1_D\L4/*7 M2"G]"3D/_AE*#_[GN?J-W.]UCQCUCU7O+PCX+ZBKWT9#$7]<#%QUXTV+HG%B MP#E@YOP?_254J@[:)P:,NUKH?,DJ,="](K Z'JR'W6F)E*D%1\5 H5=MZ#\\ M(/L'M?]#2S/X5YZW/?QG=OA+I*3^6&UK_E1]:_[2S>P"]PX$[:8!&?VSL]@QI"\S/ CK2%6?>9>5F91)_OG5KLH,"CFSUU M5*_H7UFQ)-I=)GI#1O)W'+.+SQ51Q< !G.(0L85?*[K5X,#"F^_PI7KL"_Z2 MF_)YH^(O#5Y"5GA]]LDMAI$6)]/S,$-4?H/H!N:8&$CLX-"FRGGU+?"ZMT5/ MULQJUBF#5X:W TY[NF\ZHF)U#R67QBYD6RJVP09>/E+M8&KD)\[B&7@QY M\!^+[CN:LSX(;&R:;V*O9GDPV*EAW)+%KD M$?-/Z-4_H6LQPAP,E3(E*0;F= 8>#%PCOT?\(A3>@* P1234\1OU!_X$RQY: M_BFR-BY0V_7'<1#*AC?/841DFDBZO^WW1V]EVOY\\3\;!R$TO FI2P-3HW/J MQ_[TE.POD=*:7[.]THA8$5_D9-%9F^ASPCLX?A ]=]W M>MY_@=*_B*+0YO [.KAC>FAV#,=-9%$A4U^NW5A@*M89,F>)W 2634SN37L= M]9O<1O_J1%>O[1-:0?71 L=5P"%IH3D8.$:?JA<#"Y#[QR4V:LYGX=A]K^[6 M)I*UA.OZ.=#X6+C-#OAE7.N)?9N,U_AX2#]0JRU5X^IJDRIN23M<2C+[AD+, M .XA)% JJ4(U+ /S&,U5!N/E[A=: MWM=N?7AZYV.GI/2R ]0T#*O4GB))"D28B!$E5]$'<\8W/X%^'.6Y.M!T/A - M"_&7'+7N&I'J)07);OC*8S44*B*P$N9]NT&A/ M//6JU4HHU4NR8U$2SNIT5KQO*2I]K:DR@E78JG"[U*ZAX[74B<#BG2<\G0@* M1%^^X?S?AI"TV;@8LD$5.)U /TJ)#4B!>EN8>Q07Y+VIO?.L\V784C4)C8-* M$HH2+[(.KSNJE45N@]>"N"D,2V4W]&2Q)O%@EVIL-8HWM#HRCH0%S5HU\I>" U.] MH,I]\ M>N#BFK-*H12&F6T4FN^,6'@ 'L2 6&I\P+$ 7,N%9PZ;H"0V5CG XM4^GG$W.&G4?I%DTX&C1YGJ^C1VWP[4R^&O-@[Y5]@GCIF+P98F>M'4@5! M8H"!%P/'+"%3^^;2S1MVLY_=S;M%<@"+DTH#HQY51AP-E\)5-\1]RC3*^B 7 M8>)OL73_UC! Y/@? \MBJ%1@0K*#VCCCO.)D.S&@%OBA05Z>ZL[3ZW_+W11] MUK ]"GN>U\7,Y:^&O,$!/I%'2;-%+X;J\,\PKNFLE)T\QQ_-K6QRZ" [06MF M.AF8"_QS:SN@"78QSN^A*PLQ1GM'0JH<-I\\,R@&O#(17N2$$U&HR;0/_X@; :$[Y15\T'(UPRYR84CB":"-SU_]C, M/R5"6\K_(',8GZ_>6QJAOT9K_.G2"QF/ MA)4@3"-F#RRT,*M.DG]=>O9V*@ MJ:8(7A1E!),)%-!\OAWL$ ,7T5O% "UW5*@8AF'+]F#&/\^* 4DF O;^?S[Q M#]B7^KO+'G8I0+X[^FPGEN5I_\/$^R^9Z8-) MHGRT+$*@W012KCQ_G]G]<\;CSWS=Y^:9L.[;UOR/#[*>!&\<'NZ)7E]GAOY= MG/PA1H#!PG(Q\+M ^7T20MJNOV<"?^I%?Y=R'M@T-ZKW5BNO=[^;_W'QZ:71 MV4I%$B52#_ZUQ7L09+O8M?S>6F_@T(^-BBYJ.R60(9L/]] K(J<&!,'"#1@% M>IAE+-F UQZ]7+6E&(K#^C=VK9:6/T"A*UTW)J1F/M[Z1E[])?D%!MR!&L3Q M%]OWPB\PE9KQ0M7(>ZU+^^P\UW3??O;DTJ+FY74W\@]33\@>B'JJW8X?#KV% M6BYZB#F &Y+ECX//LN=_EH8P]*,E?WU%K\DYVYK^8UVTX#? :6E>9I8^P_>$ MV\YAWW5-[=2I%H$A^36EG-+2"Y;Q?2$CMAB0^F*]5SOQPTM0:XXN M/)3O>(HNG'\TZUM&&JJ5-E;()VV-PA2<4- MA^>&V,^V.FLLRKVD;4*,TUBZ)OA6Y7Y2AU,!B&?1FBV'1MGMN6 Z"LAXO7D)4&FUZO6IUZWEQAGXDK^7.?Y>YOA[F>/O98Z_ MESG^7N;X>YGC[V6._RU:^AMR_$M"CL8=HGHZZ]'HX\0I;=X/=G$3A>DVIM^8 MSD%K3]Y:9;4D:X/&N\Q,RVH969'&T"=)N_28%ZL&OX^EOY7ZJK/2P:/>0^!7 M-F5Q,%]^S-\P1U,IPU!;Z?:)3;)+DC/^%YWL!V68QA\7Y=%9>:.5->4"#W+/ MR.I]-EMZ-5]55"3B1\)F+]]N"SFZV*CS!O^F4KRWTC?OQ=?)YRF,14@[^ID2 M3P%WXBZO[YIB"%R)'A[0R3%S7-!3&OM6\J_\+K^J2'.#_.\O>D2:!T6VX10U2 M+#_EKE3AR:(OW?'O#[V+6%LZ8/ T/5']4[X50O\:A;$>-M# ZL,C-)DSDB M7U$9*VP@7WE+H=X[I*M+>Q>"I\2+ 8T&_-@][YI?08L@;-D.CS--UDQ7E&-$ M&Q E&(M[(X6+K(?B_HV/8,#;Q#+W$'X]&SDN=>"*)&IU$_)9.$\/R2P;GQZIE]R#7Y)/"3H:P"8.UC#5= MLVE%49SP;=]64^H_22PV&HW;B+ZEYHL@.Z'UJ%#/\#$8 MV333UU#YA4ZXSXF+()D$)8@#9E8ML]D2U_-+G_UHE MP-+# !%02,>( 78S,S&)?H%'@!75!6'$2[76_L/"4)VH7!INF6[0AK7'Q_NI M4$(V+)]==I(73EX%"0V,#:R@CH>=GU&NWX^DI/V4X-=>)J\7+H;.[B5MA#K8 M^Q1?&6/X79?"2\^F#S@=?&3VTO$@PFPP(CT. M9#E; "&O3IWZ.-#X%NW/58 M+09J=KWIFO/-A.QA920QQZZ$%BWIQNRW5.AZK$P?7I]?5#)N0,<_O8JA!LQ0 M9"F,%1C6]7S %%X\_X.$0O7*3"?N[*!2SJ*'/OZ1=W)QYMZN1^'/8VL)UC[ -R/.4J#EOE.;1#XDKL"1J>Z>);\L^"SVL2(!R?N+8LI&/;[<+2WQ,G[ MW<-R5R4;5_>538LVK62DWPC\Y3+__P90&*IB %\&+7?C1MZ%.U6(]KMYCVAC MX=CGD#=G@^+V<[))<6OWQ!S/U_/F4!)\@U)U&1%Q)K.<[ MOGU(#Z8-J[; %KSIF'2-4?8'Q.W._"CY&F![0\*6+1^!S_69T+EGO9GLHJSM MG3)3!"\U$V7B/M:(KHB!L'6W'=V4<)*$%(>SN[(FS_O*B@$9Q',9="QPZ'GP0U=&A_G[6E%Y^1 M &6%6^S!Y7#ZK #I/MBQ=6)@K(_2NFE4\9L3DK7D4P5A859G;(;(75C3)V1&J\4 MO.@L77C53>ATE5_T5 3/_Z\K*T7WF!J"U(@"OQ;#F9?:+X)."[_^QC$:(I5Q MXR,$>6:PG(O P[&C\ .CN.GZ=+;U%4PI&H30PV7P%7/!1@IK&,G:G*_3D[]- MNH 5JIVBC PB*I8D6U>9OP['I-D2;U+/+%\9=0_#_HH#=]?3/R "@QM1R533 MCRFC277F=>%BX%R%_$3'0$\CTMI'.R&9)?$VA>%'F< 1+J&AK<3"M2L;Y;F !.!B IV ")^P75#;]L<9#] MA=WI'1:6]#"T\K"I05O!.J<^2DL+4LD1R_U\5 :'=R5@?AG\]ULF?$,T.5O[ MF@YNBI+8]-&,W'=>VVB0HX!AUV)8]&QA (6!O=F0<3I<=+#_N'/PK_M,+8:\6" M?7[['TA*2)^2*YOZ"BLB"4,Z"I) %$* %B2-[7S"WG]6W863H+(5]P_H./= MHG0]1$H&[RXGN37I9\C*266R-R(DAO6.JGL4IQ^!IM+!W4AV/NMDMI!Z5_9OF:;Q!QRK